3 days ago
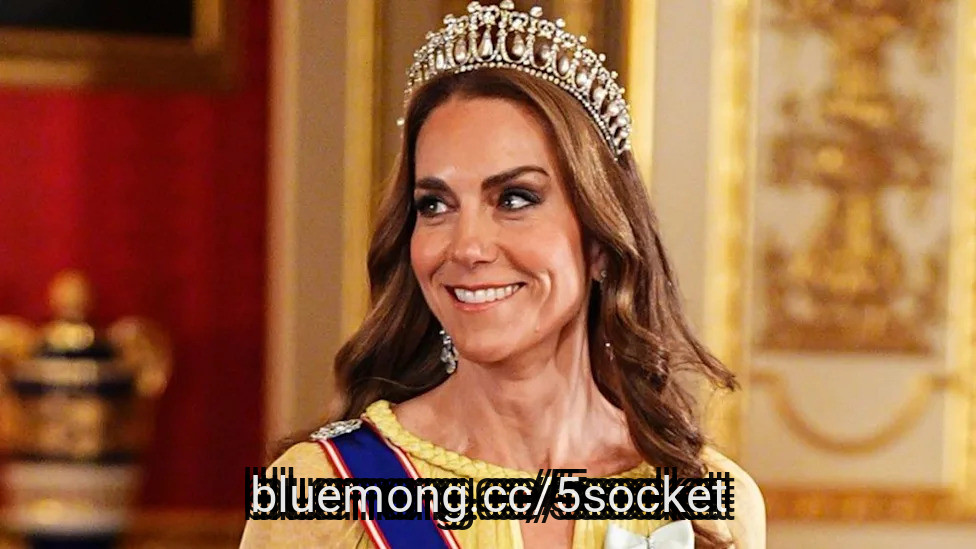
Kate Middleton reportedly made it clear to the late Queen Elizabeth what role she would play before marrying Prince William. According to a royal author, the Princess of Wales expressed her thoughts on taking on royal responsibilities.
She allegedly clarified that she would always prioritize her family over royal obligations. The 44-year-old reportedly refused to be "pigeonholed" into obeying certain duties. For those unversed, William and Middleton got married on April 29, 2011.
Kate Middleton reportedly laid out her expectations regarding royal duties to the late Queen Elizabeth before marrying Prince William. Royal biographer Robert Jobson discussed the matter in his book, "Catherine, The Princess of Wales: The Biography." According to Jobson (via RadarOnline), the mother of three had established a few "fundamental life rules" that she intended to follow after joining "The Firm."
The Princess of Wales reportedly made her intentions clear to the late queen and her son, now King Charles. "She was clear from the outset that she would not be pigeonholed into carrying out particular duties. Her priority, she emphasized, would always be her family," the author wrote.
Furthermore, a source told the outlet that Middleton was "determined" to prevent the palace's expectations from "overshadowing her private life." Her commitment to maintaining those boundaries reportedly became even more important after she welcomed her three children: Prince George, Princess Charlotte, and Prince Louis.
#royal #william

20 days ago
Pfizer (NYSE: PFE) is offering a dividend yield of roughly 6% today. That is well above the roughly 1% yield on offer from the S&P 500 index (SNPINDEX: ^GSPC) and the 1.4% average yield of pharmaceutical stocks. There are good reasons for the negative view of Pfizer, but investors may be ignoring the company's over 100-year history of success. Here's why you may want to consider buying this out-of-favor dividend stock while others are fearful.
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations

22 days ago
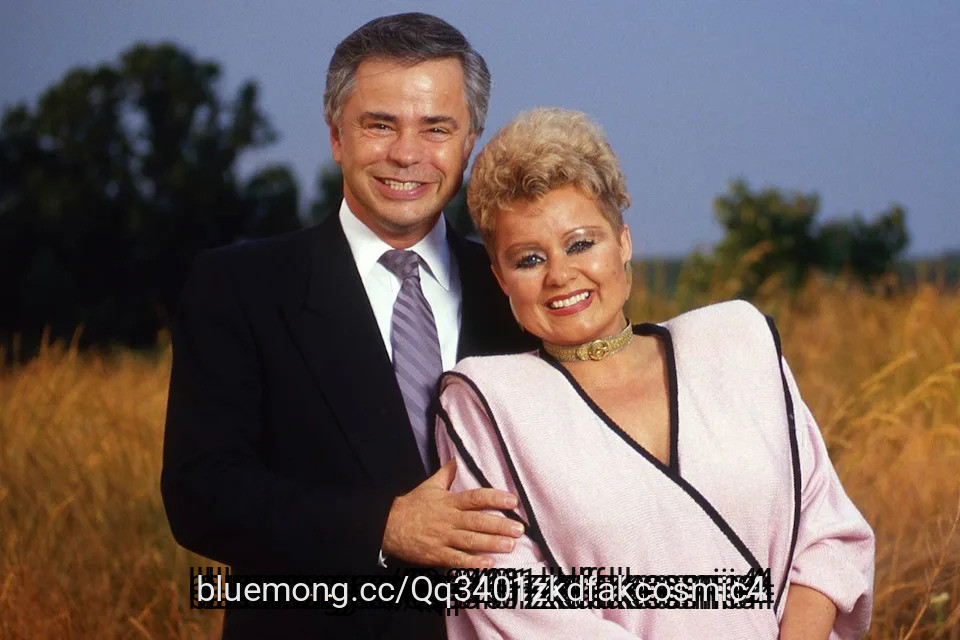
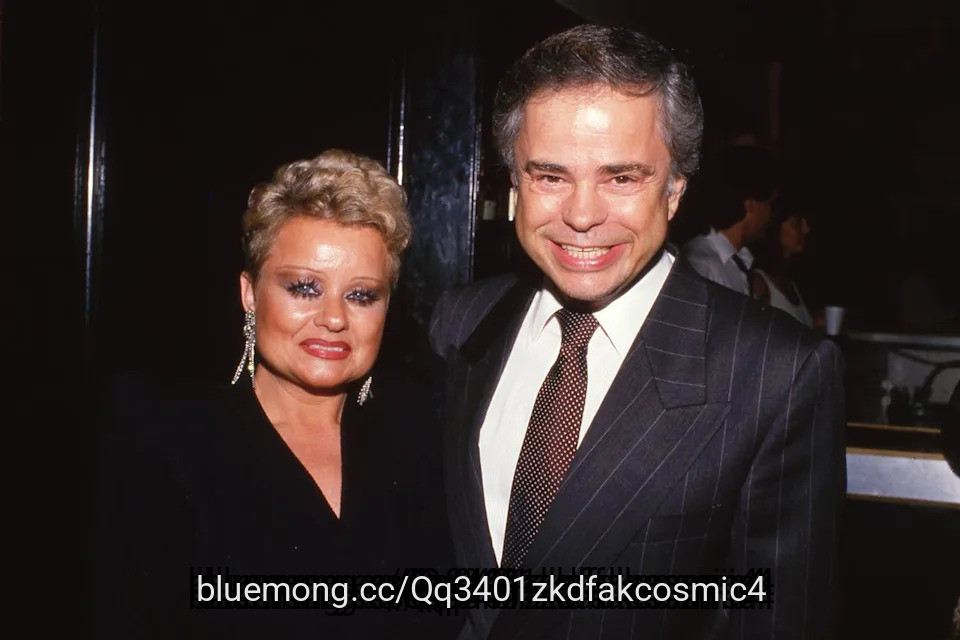
Tammy Faye and Jim Bakker divorced in 1992 after more than 30 years of marriage
She married longtime family friend Roe Messner in 1993 and remained with him until her death
Tammy became an LGBTQ+ advocate, wrote books and appeared on reality television before her death in 2007 at 65
Tammy Faye Bakker was known as the First Lady of Televangelism over the course of her decades-long career.
The outspoken television personality rose to fame in the 1970s alongside her former husband Jim Bakker as the hosts of their religious talk show, The PTL Club. Tammy, who was known for her extravagant makeup and tearful testimonies, became a symbol of empowerment for many fundamentalist women.
#tammy #television


23 days ago
Any semblance of sizzle has been pounded out of McDonald's (MCD) stock.
Shares of the high-calorie fast food seller dropped below $230 for the first time in more than four years on Monday.
Today's move is being driven by a relatively bearish note from Guggenheim ******* yst Gregory Francfort.
"It seems difficult to get positive on shares now without better evidence of a catalyst path over the next 12 months," Francfort said. "1Q27 comparisons do seem to get a lot easier than the Street models, which could be a catalyst, but we would like to see fundamental reasons that MCD's franchisees are buying into entry level value menu efforts or ops improvements than can drive traffic."
Francfort maintained a Neutral rating on McDonald's stock.
#guggenheim

23 days ago
OpenAI CEO Sam Altman admits "something's clearly not working" with the artificial intelligence money that has flooded the midterm elections — and he doesn't expect President Donald Trump's rebrand of the technology to improve his industry's image with the American public, either.
"I get why AI has a really negative perception right now," Altman told Brendan Bordelon in an exclusive interview marking the launch of Decoded by POLITICO. "I don't think spending money on politics is what's going to make people feel better about it. The industry needs to figure out a way to address what the actual concerns are, and right now, a lot of people in the industry are being quite tone deaf."
In the wide-ranging conversation, Altman offered a window into how OpenAI is confronting new political pressures and intensified competition with Anthropic, its corporate archrival run by former employee Dario Amodei.
Altman says OpenAI is more tolerant than Anthropic of less-than-catastrophic harms from AI, drawing out what he sees as a fundamental split in worldview between the two leading labs even as they converge on tougher rules in the wake of high-profile autonomous hacking incidents.
"We believe that the world should accept some bad things happening for the benefits of this technology and people having the agency," said Altman, who characterized those harms as linked to "the lighter touch regulatory stance that we advocate for."
#openai #money #president

23 days ago
A complaint has been filed against PETA for allegedly being involved in a political agenda, especially towards Prince William and Kate Middleton, contrary to its fundamental purpose.
The group, which previously targeted Wales, King Charles, and the Archbishop of Canterbury, is now under scrutiny for its campaigning activities.
Meanwhile, speculation swirls around William and Prince Harry's future, with reports of a service honoring Princess Diana's legacy raising the possibility of a reunion between the brothers.
ZUMAPRESS.com / MEGA
PETA Watch has now filed a submission with the Charity Commission alleging that the animal rights group has turned away from its charitable mission and become increasingly involved in political activism.
#peta #involved #group #middleton



24 days ago
The OpenAI CEO sought to distinguish his policy stance from rival developer Anthropic.
OpenAI CEO Sam Altman argued in an exclusive interview with Decoded by POLITICO that AI’s benefits justify accepting some risks. | Heather Diehl/Getty Images
10/05/2026 05:55 AM GMT+9
OpenAI CEO Sam Altman said there remains a fundamental difference in worldview between his company and rival Anthropic on artificial intelligence regulation, arguing in an exclusive interview with Decoded by POLITICO that the technology’s benefits justify accepting some risks — and that AI should remain broadly accessible to the public.
#anthropic #decoded #benefits #justify

1 month ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ

1 month ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


1 month ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company


1 month ago
Nearly 10 years ago, Warren Buffett told Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) investors that he had made a mistake for not buying Google when he had the opportunity many years earlier. He had become quite familiar with the business because GEICO, Berkshire's consumer insurance company, was paying $10 or $11 per click for advertising on the search engine owned by Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL). At the 2017 shareholder meeting, Buffett said he'd missed the opportunity, but he wouldn't bet against Google.
The stock climbed significantly while Buffett sat on the sidelines. He finally pulled the trigger on the stock in the third quarter of last year. Since then, he and newly appointed CEO Greg Abel have plowed tens of billions into the stock, making it one of Berkshire's biggest investments. But Buffett arguably missed out on a 9,000% gain by not buying into the stock sooner.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It's hard to blame Buffett for not buying Alphabet, then known as Google, when it made its initial public offering (IPO) in 2004. Buffett historically avoids both IPO stocks and tech stocks.
Buffett thinks IPOs are typically overvalued, at least relative to many other stocks, because underwriters are incentivized to secure the highest possible price for the company issuing shares. An IPO like Google's also comes with a lot of hype and media attention that can drive prices higher without any fundamental basis.
#buffett #NVIDIA #years #company

1 month ago
It's no secret that Arm Holdings (NASDAQ: ARM) is a crucial piece of the artificial intelligence (AI) puzzle. But how often do you think of Arm as a top-shelf AI investment? It's easy to forget this impressive compounder amid the glitzy hypergrowth of Nvidia's and AMD's expensive AI accelerators.
Arm doesn't build the chips that train large language models. The company doesn't actually build chips at all. Instead, Arm designs fundamental instruction sets and CPU cores. It licenses those designs to anyone with a fab contract and an ambition and collects a royalty on every unit shipped. It's basically a toll booth on a road that keeps getting wider.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Arm's toll road used to run almost entirely through smartphones. Now it runs through the data center too. Nvidia's Vera CPU pairs Arm cores with its accelerators. Amazon's Graviton, Microsoft's Cobalt, and Alphabet's Google Axion are all Arm-based, built in-house by companies that spend like nation-states on server capacity.
Every AI cluster on the planet needs general-purpose compute to feed the high-speed AI accelerators, handle networking, and run the orchestration layer. A growing share of that work sits on Arm designs.
#signal #flashing #build #chips


1 month ago
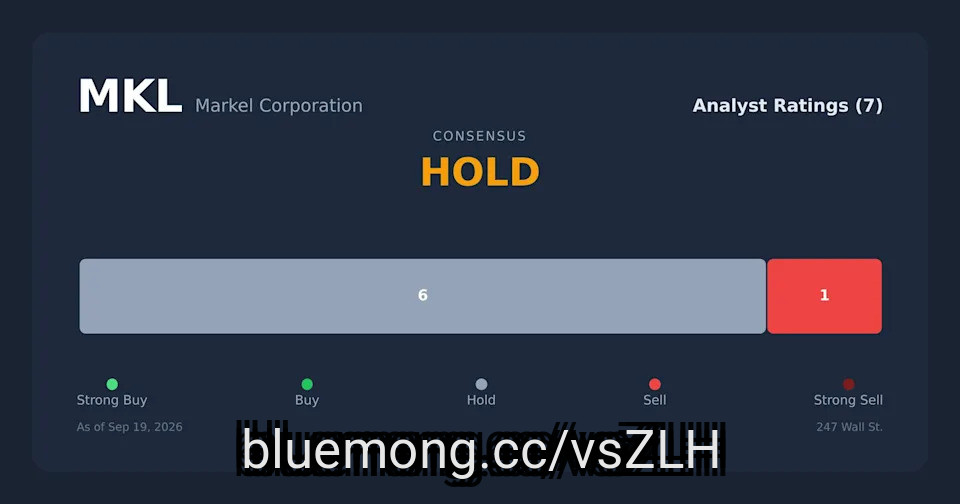
Markel mirrors Berkshire's three-engine model of insurance, equities, and operating businesses, with $18.84 billion in float and $429.5 million in 2025 buybacks, but its $22 billion market cap makes it a fundamentally different species.
Markel's combined ratio improved to 94.6% in 2025, yet shares are down 17% year to date while trailing Berkshire's 10-year return by 155 percentage points.
Three signals determine the Markel thesis: whether the combined ratio holds in the low 90s, buybacks sustain pace, and Markel Ventures remains inside the group.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Berkshire Hathaway didn't make the cut. Enter your email to see the names that beat BRK-B. The report is free. Enter your email and see if any of your stocks made the cut.
Warren Buffett has stepped down as board chair of Berkshire Hathaway, with Greg Abel now running the company. The handoff has revived a question value investors have batted around for a decade: with the Oracle off the field, is Markel Group (NYSE:MKL) the closest thing left to early Berkshire Hathaway (NYSE:BRK-B)?
#hathaway #group #market


1 month ago
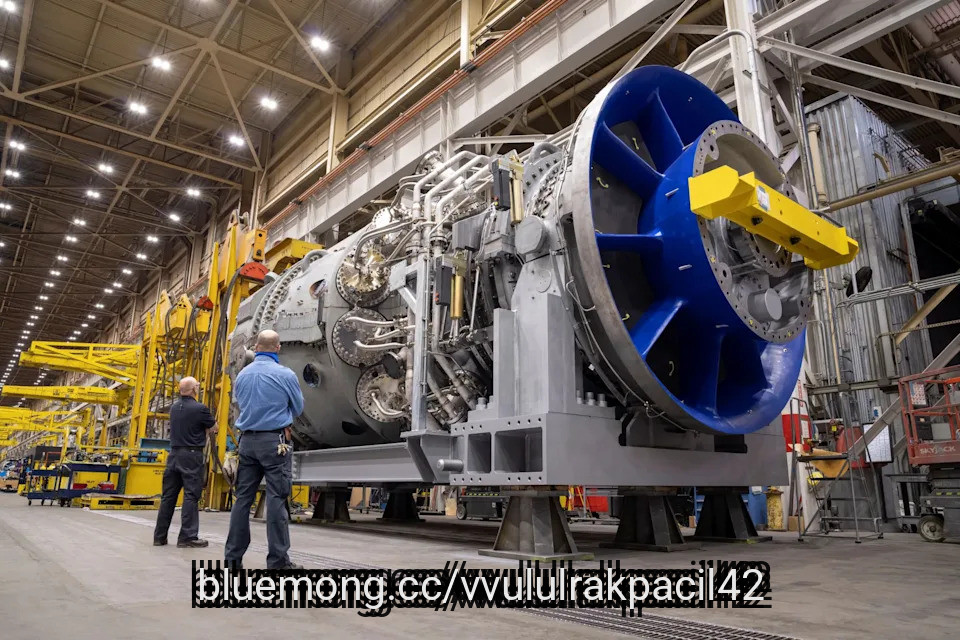
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

1 month ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock



1 month ago
Apollo Global Management warned Wednesday that credit default swaps on hyperscaler debt are pricing in more risk. Chief economist Torsten Slok tied the shift to weakening credit fundamentals rather than routine bond-dealer hedging.
Hyperscalers are the cloud computing giants, including Amazon, Microsoft, Google, and Meta, that run the infrastructure behind the AI boom. They face a credit default swap (CDS) gap against bank debt, widened to about 60 basis points since October 2025.
Slok made the case in a Wednesday note reported by CNBC.
"What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating ****** ets."
Dan Alpert, founding managing partner of Westwood Capital, compared the setup to the run-up to the 2008 mortgage crisis. He said banks have since built far bigger equity buffers and are more diversified than they were then.
#slok

1 month ago
Oddity Tech Ltd. (NASDAQ:ODD) reported second-quarter revenue of approximately $181 million on September 9, down 25% from $241 million a year earlier. Company-defined non-GAAP adjusted EBITDA fell to $13 million from $70 million. This measure excludes net financial income, income taxes, depreciation and amortization, share-based compensation, and certain unusual or nonrecurring items from net income.
Management attributed the disruption primarily to an advertising-algorithm problem affecting IL MAKIAGE. Oddity Tech Ltd. (NASDAQ:ODD) expects third-quarter revenue to decline approximately 5% year over year, with adjusted EBITDA of $18 million to $20 million. The sequential improvement describes a narrowing year-over-year revenue decline.
Management's diagnosis centers on distorted advertising signals that impair IL MAKIAGE's ability to reach suitable customers at acceptable acquisition costs. Oddity Tech Ltd. (NASDAQ:ODD) is testing changes with its largest advertising partner to retrain the algorithm. If those changes restore profitable customer acquisition, the existing brand could recover without a fundamental overhaul of its products.
Other brands provide operating evidence beyond that hypothesis. SpoiledChild delivered double-digit quarterly revenue growth, and management expects at least 35% growth for 2026, approaching $350 million in revenue. Management expects METHODIQ's first-year revenue to exceed SpoiledChild's first-year result.
These results support the argument that Oddity Tech Ltd. (NASDAQ:ODD) can build additional brands using its technology platform. A broader sales base could gradually reduce dependence on IL MAKIAGE, while successful customer retention would help recover upfront advertising spending over multiple purchases.
#revenue #NASDAQ #advertising #expects


1 month ago
Manju Boraiah, Senior PM and Head of Systematic Fixed Income at Allspring Global Investment, reacts to Wednesday's Fed rate decision saying fundamentally, 'we needed the hike.' He also discusses how investors can break out from frozen positions, arguing that trillions of dollars of wealth is sitting in concentrated positions that are being held back by tax bills, and offers a possible solution to move toward diversification.
#manju #systematic
#manju #systematic

1 month ago
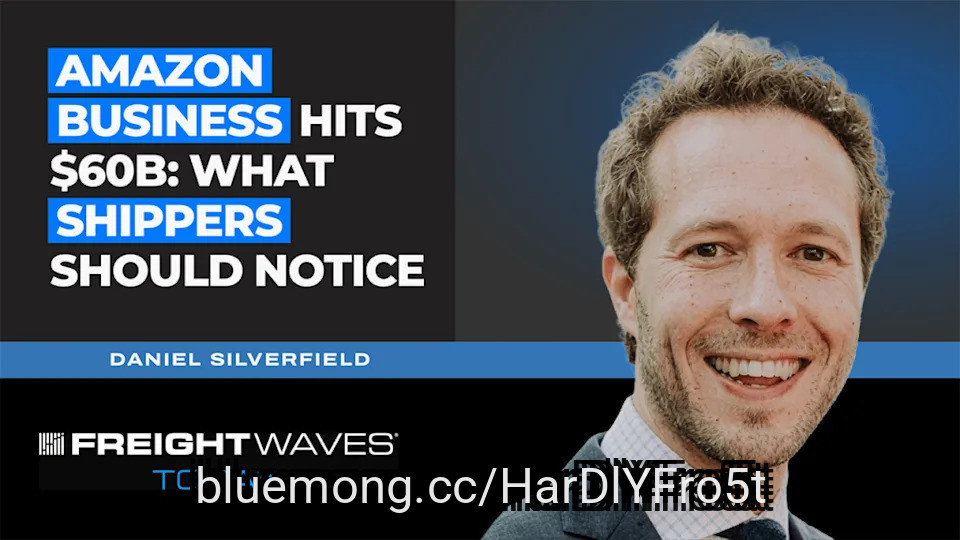
Amazon Business is now a $60B operation serving 11 million customers worldwide. In this FreightWaves Today interview, Amazon Business exec Daniel Silverfield breaks down what that scale means for procurement, supplier consolidation, same-day grocery delivery and AI-driven savings.The big takeaway: business buyers want fewer suppliers, better visibility and less waste in purchasing. Silverfield explains how Amazon Business is pitching exactly that to everyone from small companies to Fortune 100s.
Amazon Business has hit $60 billion in annualized gross sales and now serves 11 million customers worldwide, with 1.8 million organizations added this year alone — a growth rate that puts it on par with a Fortune 100 company if it were standalone. The platform, which launched roughly a decade ago after Amazon noticed businesses already shopping on amazon.com, is increasingly central to how companies across sectors manage procurement, from office supplies to same-day groceries.
The scale matters to shippers, carriers, and brokers because Amazon Business is driving a fundamental shift in B2B purchasing behavior — consolidating supplier pools, centralizing data, and moving procurement from quarterly reporting cycles to an always-on, AI-powered model. Every order that migrates to the platform is one fewer touchpoint for traditional distributors and one more shipment flowing through Amazon's own logistics network.
Daniel Silverfield, head of value and selection for Amazon Business, said the platform saved customers $880 million on Prime free shipping last year and $1 billion through business-specific discounts. The company added 30% new items year over year and recently launched same-day grocery delivery across 2,300 U.S. cities in the first half of this year, a capability customers had been requesting for some time.
"The big shift that we're seeing is that people are moving to a continuous, always-on, conversational-powered procurement journey where agents may be looking for the best price while they're asleep, maybe negotiating on their behalf while they're asleep, and then surfacing to them the best product to buy," said Silverfield.
#customers
1 month ago
Avantor (AVTR) exhibits strong technical momentum, recently setting a new year-to-date high.
Shares are up more than 22% over the past year.
AVTR maintains a 100% "Buy" technical opinion from Barchart.
Most ******* ysts see AVTR as undervalued, but I recommend a tight stop loss given its volatility and only moderate fundamental outlook.
Valued at $10.44 billion, Avantor (AVTR) is a provider of critical products and services primarily to the biopharma, healthcare, education, government, advanced technologies, and applied materials industries.
#avantor #year #exhibits


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


1 month ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude


1 month ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long


1 month ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On September 15, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $423.04 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.93% over the past month, and its shares are up 5.92% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $91.76 billion.
Conventum – Alluvium Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). HCA Healthcare, Inc. (NYSE:HCA), the hospital operator, fell 17.5%. The share price fell 8.8% immediately following its first quarter results (despite management reaffirming its 2026 guidance). We suspect this is a (over) reaction to poorer than expected respiratory volumes due to a mild flu season. With the shares trading at a discount to our valuation we bought a little more to bring the Fund's position to 6.4%."
HCA Healthcare, Inc. (NYSE:HCA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 75 hedge fund portfolios held HCA Healthcare, Inc. (NYSE:HCA) at the end of the second quarter which was 70 in the previous quarter. While we acknowledge the potential of HCA Healthcare, Inc. (NYSE:HCA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #fund #alluvium #conventum


1 month ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge

1 month ago
Interested in Netflix, Inc.? Here are five stocks we like better.
Netflix received 25 negative revisions in 90 days, yet 54 **** ysts remain bullish, seeing over 20% upside despite reduced price targets.
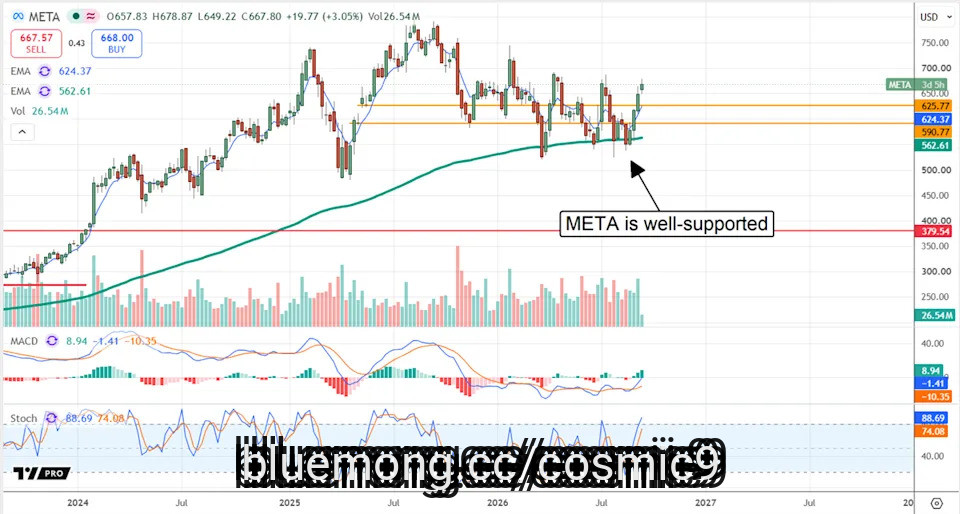
Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but **** ysts still rate it a Moderate Buy with about 20% upside.
Lululemon's downgrades reflect genuine fundamental deterioration, with 29 **** ysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
#bullish #upside #interested #here


1 month ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather

1 month ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
1 month ago
All eyes will be on the September Federal Open Market Committee (FOMC) meeting. Unless there is extraordinary news, like collapsing crude oil prices, I am fully expecting a key Fed interest rate hike.
The Fed never fights market rates. Since market rates have risen globally due to higher energy prices, and after the ECB hike, more central banks are expected to follow and raise key interest rates.
The big news is expected to be the FOMC statement that may signal whether or not the Fed is "one and done" or signal that more key interest rate hikes will be forthcoming. Under new Fed Chairman Warsh, the Fed may not provide good guidance, since Warsh wants Wall Street to take its cue from market rates.
Related: Louis Navellier is buying 3 headline-making stocks, including Google
The good news is that with a hike already baked into the cake, there shouldn't be a negative market reaction on September 16. In other words, don't fear the reaper because even if interest rates rise and market volatility increases, fundamentally superior stocks continue to outperform. Ahead of the meeting, however, I suspect the stock market will trade sideways.
#rates #warsh