4 days ago
Despite the S&P 500's (SNPINDEX: ^GSPC) 13.3% gain thus far in 2026, there's still plenty bubbling beneath the surface that could trigger a sharp and sudden market crash. Stubborn inflation, the U.S. national debt sitting above $40 trillion, and fears of an artificial intelligence bubble are just a few concerns.
As one of the most successful investors of all time, Warren Buffett has some sage advice. It's found in the 1996 Berkshire Hathaway shareholder letter, which offered one of the top strategies for handling a market crash. The good news is that it can be followed before a crash even starts.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
It's easy to feel panicked when the market starts tumbling, and making any kind of move, even if it's a knee-jerk reaction, can initially feel better than making no move at all. While that small voice whispering to "sell" may never go away during the initial waves of a market crash, it can be countered by being prepared in advance.
Buffett shared exactly how to counter it. In Berkshire's 1996 shareholder letter, he said, "If you aren't willing to own a stock for ten years, don't even think about owning it for ten minutes."
#crash #NVIDIA #even #shareholder
5 days ago
Under Warren Buffett, Berkshire Hathaway stock returned 19.7% annually between 1965 and 2025, nearly doubling the 10.5% annual return in the S&P 500 (SNPINDEX:^GSPC). That makes Buffett a great source of inspiration, and he consistently recommended an S&P 500 index throughout his career.
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#source
5 days ago
AGNC's Q2 spread income of 40 cents per share covered its 36-cent dividend, but the payout has been cut three times since 2015.
Annaly raised its quarterly dividend from $0.70 to $0.75, while Dynex rebounded to 6.4% economic return after both posted Q1 losses.
If Q3 spread income falls below 36 cents or book value drops below $8.38, shareholders' own capital funds the dividend and a cut becomes likely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
AGNC Investment (NASDAQ:AGNC) is a mortgage REIT that borrows short-term money in the repo market, buys agency mortgage-backed securities, and keeps the spread between bond yields and borrowing costs. Leverage of 7.4 times tangible equity magnifies both gains and losses.
#times
5 days ago
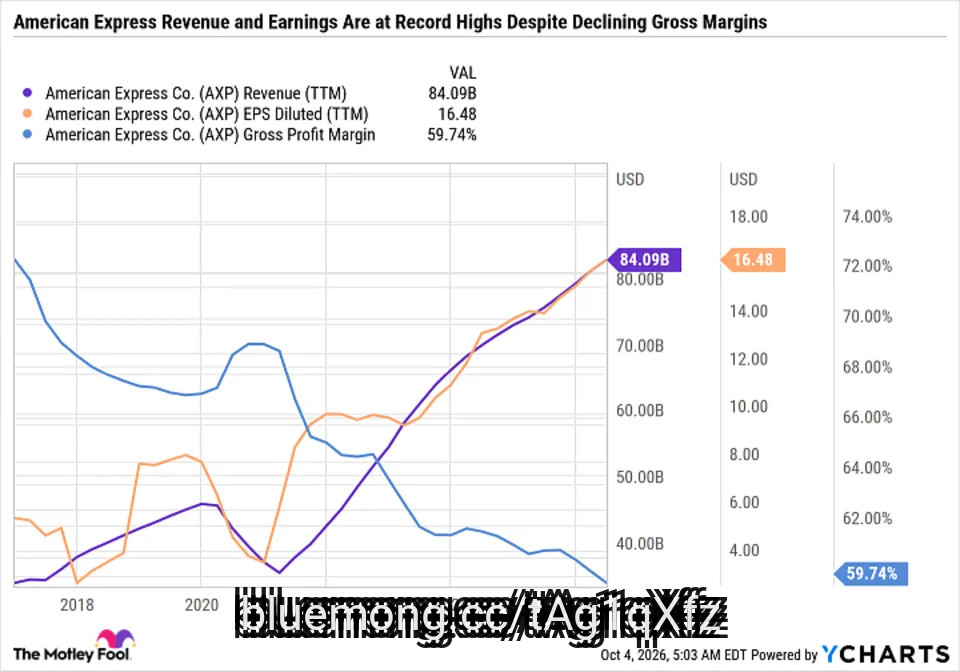
American Express (NYSE: AXP) has been a staple of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) portfolio for decades -- with Warren Buffett essentially completing purchases of the stock by 1995. Buffett's hand-picked successor -- Greg Abel -- expects American Express to remain a long-term compounder and a core Berkshire holding because it's a business Berkshire understands well and trusts its management team.
American Express also features a growing dividend. It doesn't raise it every year, but even during the 2008 financial crisis, when many banks and financial services companies were slashing their payouts, American Express held its quarterly dividend steady at $0.18 per share.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
American Express has substantially increased its dividend since then. The next payment of $0.95 per share is payable on Nov. 10 to shareholders on record as of Oct. 9.
Here's how many shares of American Express you'd need to generate $1,000 in yearly dividends, and the three levers American Express pulls to reward long-term shareholders.
#signal


5 days ago
A 62-year-old retiree can withdraw up to $66,500 annually from a 401(k) at just 12% federal tax, moving roughly $532,000 before RMDs begin.
RMDs force a $1.2 million account holder to withdraw $45,283 in year one, potentially pushing effective tax rates to 41% when Social Security is included.
Leaving $900,000 untouched grows it to roughly $1.7 million by 73, creating a first RMD larger than the current 73-year-old's and repeating the same tax trap.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Picture two retirees. One is 62 with $900,000 in a traditional 401(k). The other is 73 with $1.2 million. Most people would take the bigger account. The smaller one is worth more because the 62-year-old still determines when that money gets taxed and at what rate. The 73-year-old has already gave that decision to the IRS.
#rmds
6 days ago
An XRP holder proposed raising XRP Ledger fees 100x, but even that hike would cost only $0.0015 per transaction, which amounts to a negligible dent across 63 billion circulating tokens.
David Schwartz called higher fees 'truly bizarre,' warning they would drive away payment processors and undermine XRP Ledger's core advantage of cheap, fast settlement.
Higher fees would force active users to subsidize passive holders, and any fee change requires validator approval, which is a threshold this proposal hasn't reached.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Recently, an XRP (CRYPTO:XRP) holder made a bold proposal on X, suggesting that XRP Ledger fees be raised 10 to 100 times to enable a larger XRP burn with each transaction. Burning tokens reduces the total supply, a move many holders support because it could increase the value of their remaining tokens.
#tokens #ledger


6 days ago
A $300,000 investment in SCHD grew to $468,150 over five years versus $573,900 in VOO, leaving a $105,750 gap driven by missing big tech.
SCHD's dividend quality screen kept out the tech giants that led the market, yet that same tilt powered its 23.86% one-year return.
SCHD suits retirees drawing income today, but younger investors should know the yield cost a $300,000 account over $100,000 in five years.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Putting $300,000 into the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) on October 1, 2021 left a holder with $468,150 by October 5, 2026. The same money in the Vanguard S&P 500 ETF (NYSEARCA:VOO) grew to $573,900. That leaves a shortfall of $105,750.
#nysearca #Dividend #income #same
6 days ago
In 2023, a shareholder stood up at a Berkshire Hathaway (BRK.A) (BRK.B) annual meeting in Omaha and asked about the future of value investing. Charlie Munger took it: "I think value investors are going to have a harder time now that there are so many of them competing for a diminished bunch of opportunities," he said. "So, my advice to value investors is to get used to making less."
Warren Buffett, sitting next to him, did not let it stand. "And Charlie has been telling me the same thing the whole time we've known each other," he said in the same session. The two men met in 1959.
Why It's Time to Load Up on Broadcom Stock Before It Touches $523
NVO vs. LLY: Novo's CEO Says Confidence Is Gone. Lilly Is Winning 7 in 10 New Seniors.
Why It's Time to Load Up on HPE Stock Now
#time #charlie #load
6 days ago
President Donald Trump signed an executive order Monday evening temporarily allowing the use of red-dyed diesel on public roads and deferring the federal excise tax on that fuel through the end of the year, a move aimed at lowering costs for truckers and farmers facing record-high diesel prices.
Red-dyed diesel is chemically the same product as standard highway diesel, but carries a red dye to mark it as off-road fuel — meaning it is not subject to the 24.4-cent-per-gallon federal excise tax that applies to diesel sold at the pump for road use, such as for tractors and heavy machinery. Using it in highway vehicles has been illegal, carrying penalties for tax evasion, according to CNBC.
According to the White House, the order instructs the Treasury Secretary to hold off on collecting federal excise taxes on highway use of dyed diesel between October 5 and December 31, 2026, and to do so without charging interest or imposing penalties. The Treasury is also directed to direct the Internal Revenue Service not to impose penalties for on-road use of dyed diesel during that period. The order further instructs officials to explore pathways, including legislation, to eliminate the deferred tax obligations entirely.
The White House projected that a trucker who tops off an 18-wheeler's tank with 250 gallons stands to save over $100 on a single fill-up, provided the trucker's state suspends its own diesel tax as well. On top of the federal levy, each state levies its own diesel excise tax, and those state-level taxes average out to 35.5 cents per gallon, according to CNN.
The order also directs the Secretary of Agriculture to coordinate with agricultural cooperatives and rural fuel distributors to ensure adequate dyed diesel distribution in high-demand areas, and the Secretary of Transportation to engage with state governments and industry stakeholders. The White House Office of Intergovernmental Affairs was directed to encourage states to adopt corresponding policies.
#Diesel #federal #House #according

6 days ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly
6 days ago
Four major corporate splits are upcoming, with MSGS separating the Knicks and Rangers into two distinct public companies by October 2026.
Keurig Dr Pepper's coffee spinoff carries significant execution risk as Russ Torres becomes its third CEO candidate ahead of the early 2027 split.
Textron leans toward selling its $3 billion Industrial segment rather than spinning it off, meaning shareholders would receive no second stock.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Corteva (NYSE:CTVA) has split into two companies, and we walked through what its shareholders own now. Four more large separations are coming. Each has its own timeline, and each leaves shareholders holding something different. They are listed below by expected timing, soonest first.
#split #second #different


6 days ago
Before we get worried about recessions or market crashes, let's put a 10% drop in context. Going back to 1980, the S&P 500 has fallen 10% or more in roughly half of all calendar years, and a correction of that size has historically shown up about once every 12 to 18 months.
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month

6 days ago
Under Warren Buffett, Berkshire Hathaway stock returned 19.7% annually between 1965 and 2025, nearly doubling the 10.5% annual return in the S&P 500 (SNPINDEX:^GSPC). That makes Buffett a great source of inspiration, and he consistently recommended an S&P 500 index throughout his career.
"In my view, for most people, the best thing to do is to own the S&P 500 index fund," Buffett said at Berkshire Hathaway's shareholder meeting in 2021. Investors have several options, but Buffett himself selected the Vanguard S&P 500 ETF (NYSEMKT:VOO) when going head-to-head with a hedge fund in the early 2000s.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Following Buffett's advice could turn $400 per month into $820,000. Here's what investors should know.
Image source: Getty Images.
#buffett #investors #hathaway
6 days ago
At the end of 2025, Warren Buffett stepped down from his longtime position as the CEO of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB). Over the 61 years he ran the company, the stock produced incredible returns for shareholders, rising by more than six million percent. Over the same span, the S&P 500 index (SNPINDEX: ^GSPC) gained 46,000%.
Clearly, Buffett earned the nickname the "Oracle of Omaha." But can you still benefit from his investment wisdom now that the 96-year-old investor is no longer with Berkshire Hathaway? You sure can!
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Buffett's investment approach is deceptively simple to explain. He liked to buy well-run businesses while they were attractively priced. Then he liked to hold for the long term, so he could benefit from the growth of the businesses in which he invested. That's something that any investor can do. And while all investment approaches go in and out of favor over time, this one has clearly proven itself to be a long-term winner.
That said, Buffett was also highly selective. He once described investing as a baseball game where they don't call ******* and strikes. His point was that you don't have to swing at every pitch, even though you should have a diversified portfolio. The Motley Fool recommends 50 stocks as a good portfolio size, but there are thousands of investments you could choose from. Once again, Buffett's advice is very good: Be selective.
#hathaway #once #investor


6 days ago
Pfizer (NYSE:PFE) has been a reliable healthcare company to invest in for decades, also providing shareholders with some terrific dividend income along the way. Nowadays, however, it's struggling to attract any investors at all.
While its shares are up over 10% this year, over the past five years, they're still down 35%. Worries about its future growth and the safety of the payout are keeping investors away. Here's why I think that's a mistake, and why it may just be the most underrated dividend stock out there today.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Many investors may scoff at stocks that have high yields, out of fear that they simply are too good to be true, and that a cut could be due. But that isn't always the case. In fact, there can be low and modest-yielding stocks that can be riskier. Yield is not always indicative of risk.
#down #company
6 days ago
A 62-year-old retiree can withdraw up to $66,500 annually from a 401(k) at just 12% federal tax, moving roughly $532,000 before RMDs begin.
RMDs force a $1.2 million account holder to withdraw $45,283 in year one, potentially pushing effective tax rates to 41% when Social Security is included.
Leaving $900,000 untouched grows it to roughly $1.7 million by 73, creating a first RMD larger than the current 73-year-old's and repeating the same tax trap.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Picture two retirees. One is 62 with $900,000 in a traditional 401(k). The other is 73 with $1.2 million. Most people would take the bigger account. The smaller one is worth more because the 62-year-old still determines when that money gets taxed and at what rate. The 73-year-old has already gave that decision to the IRS.
#year #rmds
6 days ago
Over his career, Warren Buffett established himself as one of the world's best investors. However, after 60 years at Berkshire Hathaway, he finally stepped away for good. After relinquishing the CEO **** le at the start of the year, he also stepped down as Chairman last month.
In a farewell letter to shareholders on Sept. 18, Buffett said his goodbyes. In it were the only four words that investors need to be successful: "Father Time always wins." While Buffett was talking about his age and retirement, these words also hold true for investing and can help investors build a $10 million portfolio.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The most powerful force in investing is time. It's not necessarily about picking the best stocks or timing the market correctly; it's about time in the market. Over time, the stock market, as represented by the S&P 500 (SNPINDEX: ^GSPC), has always gone up in the long term.
The longer you are in the market, the greater your wealth will grow. This is due to compounding, where in later years your gains start generating gains of their own. While early growth may seem slow, it's the late-stage growth that will eventually turn even a small investment into millions of dollars.
#market #years
6 days ago
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing

14 days ago
Vista Gold Corp. (NYSEAMERICAN:VGZ) announced on September 21 that it had agreed to be acquired by Artemis Gold Inc. (TSXV:ARTG). Under the agreement signed September 20, shareholders would receive 0.0966 buyer common shares for each existing common share and own approximately 5% of the combined company. That ownership calculation excludes the buyer's existing 4.95% stake in Vista Gold Corp. (NYSEAMERICAN:VGZ), which it intends to cancel at completion.
For shareholders, the trade-off is a smaller interest in a larger mining business with an operating ***** et and development expertise. The central question is whether that combination can supply the capital and execution needed to bring Australia's Mt Todd gold project into production.
Artemis Gold Inc. (TSXV:ARTG) operates the Blackwater mine in British Columbia and expects its future cash generation to support Mt Todd. That offers Vista Gold a potential funding source alongside a team experienced in building and operating mines.
The financial starting point explains the appeal. Vista Gold Corp. (NYSEAMERICAN:VGZ) ended June 2026 with $49.5 million in cash and no debt. Management described that cash as sufficient for interim development objectives. Joining an operating producer could broaden the resources available for the much larger task of construction.
The acquisition requires no cash consideration or new acquisition debt. Preserving the buyer's financial capacity could leave more room for investment, although the share exchange itself does not raise construction funding.
#cash
22 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
22 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
22 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

22 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited

22 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
22 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
22 days ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management

22 days ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount

22 days ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
22 days ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
22 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital