

21 days ago
HUNTSVILLE, Texas (AP) — A Texas man who fatally shot a convenience store clerk was put to death Wednesday evening, becoming the 30th person executed in the U.S. this year and the first since Tennessee's failed attempt to administer a lethal injection to Christa Pike a week ago.
Jamaal Howard, 46, was **** ounced dead at 8:03 p.m. after receiving a fatal dose of pentobarbital at the state prison in Huntsville. He was convicted of killing of Vickie Swartout, 42, in a 2000 store robbery caught on surveillance video.
Asked by the warden if he had a final statement, Howard apologized profusely to some members of his victim's family, who watched through a window just feet from the death chamber.
"I wish that you accept my apology and I wish for your forgiveness," he said, shortly before the injection got underway. "I'm sorry for what happened. I wish you can learn to forgive me one of these days."
He also thanked his friends and family and said he loved them, adding he was "in a good state of mind to find peace and the Lord, so I thank y'all." He concluded with: "Hey, enjoy life, and peace to y'all."
#howard

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#advertiser


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Visa and Mastercard ATM cash withdrawals spanning roughly 19 years are part of a class-action lawsuit settlement totaling $167.5 million.
The case, known as Burke v. Visa Inc., involves independent ATMs often found in convenience stores, gas stations, grocery stores, hotels, and bars — non-bank locations that often levy surcharges on cash withdrawals.
Here's who is eligible for a cash payment as part of the settlement.
Read more: Just received a settlement? 5 smart ways to use the money.
#Visa #part #stores #mastercard



1 month ago
PepsiCo (PEP) has gone nowhere for a year, down 1.8% over the past twelve months while the S&P 500 returned 16.6%. At about $135 a share it trades at 17.7 times earnings, against an S&P 500 median of 22.5. A big cash generator priced below the market is what value buyers hunt for, so is this discount impatience or a verdict?
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing

1 month ago
XLE has surged 46% year-to-date while XLY dropped 7%, with defensive XLP up 9% as markets rotate away from consumer exposure.
XLF's soft 4% gain signals financial stocks aren't pricing a healthy cycle, with the 10-year/2-year Treasury spread flattened to 0.33%.
Torres pegs $120 WTI as the consumer spending breaking point, still 20% above current prices but reminiscent of 2022's economy-crushing oil surge.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
The national average price of regular gasoline jumped 16 cents in a single week to $4.32 a gallon on September 14, 2026, a move that puts the pump price in the 90th percentile of the past year and caps a 7.8% jump in one month. The proximate cause sits upstream: WTI crude cleared $97.26 a barrel on September 9 after running up 16.1% in a month, and Brent has traded through the $100 line. On Fed decision day, a CNBC Morning Call panel put a number on where this stops being an inconvenience and starts being a recession.
#september #cnbc

1 month ago
XLE has surged 46% year-to-date while XLY dropped 7%, with defensive XLP up 9% as markets rotate away from consumer exposure.
XLF's soft 4% gain signals financial stocks aren't pricing a healthy cycle, with the 10-year/2-year Treasury spread flattened to 0.33%.
Torres pegs $120 WTI as the consumer spending breaking point, still 20% above current prices but reminiscent of 2022's economy-crushing oil surge.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
The national average price of regular gasoline jumped 16 cents in a single week to $4.32 a gallon on September 14, 2026, a move that puts the pump price in the 90th percentile of the past year and caps a 7.8% jump in one month. The proximate cause sits upstream: WTI crude cleared $97.26 a barrel on September 9 after running up 16.1% in a month, and Brent has traded through the $100 line. On Fed decision day, a CNBC Morning Call panel put a number on where this stops being an inconvenience and starts being a recession.
#Consumer #torres

1 month ago
Starbucks Corporation (NASDAQ:SBUX) is betting $1 billion that leather armchairs, rugs, and bookshelves can turn a recovering coffee business into a more profitable one. The company plans to upgrade as many as 9,000 North American stores into warmer, more comfortable **** es designed to bring back customers who stopped treating Starbucks as a place to sit and stay. The strategy arrives as CEO Brian Niccol's turnaround gains traction, but investors still need to see whether higher traffic can translate into stronger margins.
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions


1 month ago
A few weeks ago, I used Uber Eats to deliver me a case of bottled water, a dozen Starbucks iced coffee bottles, and a 12-pack of Gatorade Zero.
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero

2 months ago
Back in the late 70s and early 1980s, my small town had a mom-and-pop convenience store, Paul's Market, as well as one location of a regional chain, Richdale's. It later added a store from a larger chain, White Hen Pantry.
7-Eleven and other large chains existed, but local stores, even one-offs, were common. Now, just over the past few years, a number of bigger players have swallowed up some smaller chains.
The banner retirements are real and named, according to data from NACS Magazine.
GetGo was sold to Circle K, Redwood Markets went to Jacksons (24 stores, California), and Maverick bought the ****** & Go Brand, which included about 400 locations. In all three cases, the name changes were gradual as stores got remodeled, but in the end, the classic names disappeared.
Now, the same thing has happened again as Casey's has begun the process of removing the CEFCO name from the 198 stores it added when it bought the rival chain in 2024.
#store


2 months ago
Casey's General Stores Inc. (NASDAQ:CASY), the third-largest convenience chain and fifth-biggest pizza brand within the U.S., released its first quarter results, showing early traction from the company's recently announced three-year strategic plan. For the recent quarter, inside same-store sales jumped 3.2% year-over-year, and 7.7% on a two-year stacked basis, leading to inside margins of 42.2%. Total inside gross profit stood at $749.8 million, rising 6.3% compared to the same period last year. The company posted net income of $273.7 million, exhibiting a 27.1% increase relative to Q1 last year. This translated into a 27.7% jump in diluted EPS which rose to $7.37.
Foodio/Shutterstock.com
Casey's is building on its three-year roadmap which rests on three core pillars. These include acceleration of growth across food and beverage, scaling up its store footprint, and elevating its operational efficiency.
Food remains a major growth enabler for the broader business, with prepared foods and nonalcoholic beverages currently driving the expansion of inside sales. Wings sales within Des Moines market also posted a 20% year-over-year sales jump. This positions the company to benefit from a larger opportunity of ramping up the offerings across roughly 3,000 stores, and cements Casey's reputation as a food destination.
The retailer also plans to expand its operations with at least 400 stores through a mix of acquisitions, and ground-up development of new stores. The integration of Fikes Wholesale, owner of CEFCO Convenience Stores and Casey's largest acquisition to date, demonstrates its capacity to expand through dealmaking. Management said the integration remains ahead of schedule.
#stores #largest


2 months ago
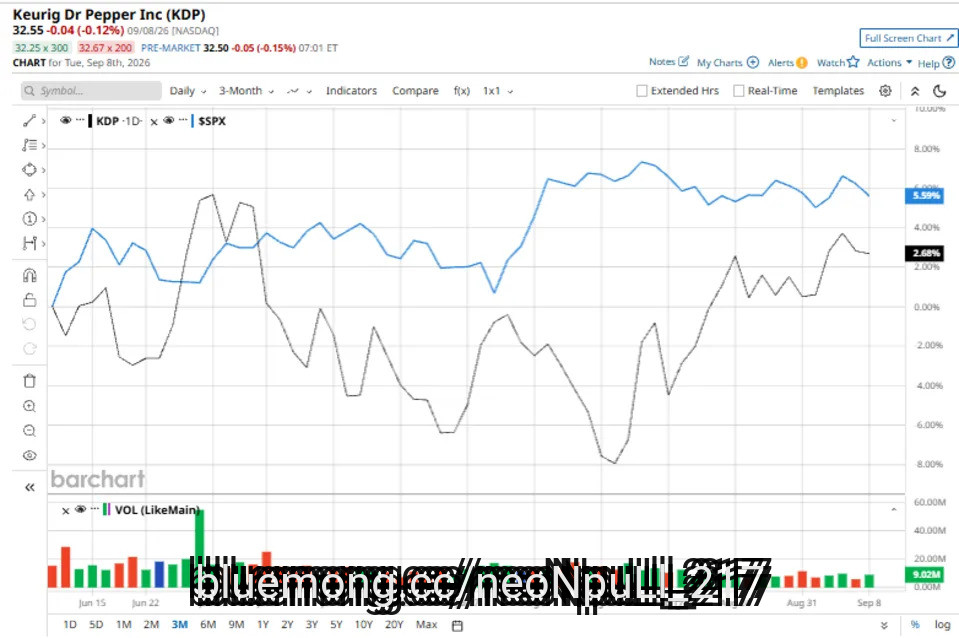
Keurig Dr Pepper Inc. (KDP) is a leading beverage company headquartered in Frisco, Texas, with more than 150 owned, licensed, and partner brands. With a market capitalization of $44.4 billion, the company manufactures, markets, and distributes soft drinks, coffee, water, tea, and other beverages through an extensive distribution network serving consumers across retail, e-commerce, convenience, and foodservice channels worldwide.
Companies valued between $10 billion and $200 billion are generally classified as "large-cap stocks," and Keurig Dr Pepper comfortably fits this category. Its substantial market capitalization reflects its size, influence, and established presence in the non-alcoholic beverages industry.
Dear Nvidia Stock Fans, Mark Your Calendars for September 10
Rocket Lab Keeps Landing Defense Deals. Here's Why ******* ysts Aren't Getting More Bullish.
Why Stifel Just Revamped Its Price Target for Microsoft Stock
#keurig #pepper

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
To say Pittsburgh Steelers quarterback Aaron Rodgers is a little outspoken would be like saying the Chernobyl disaster was a minor inconvenience. The four-time MVP isn't afraid to share his opinions, and he let loose in the most recent episode of Not Just Football with Cam Heyward.
The episode wasted no time getting into Rodgers' thoughts on why he believes he's so polarizing, to which he called out "hypocrisy" in the media.
"Everybody loved hearing my takes on Colin Kaepernick when I said he was one of the top 64 quarterbacks in the league," Rodgers said. "They loved my takes when there was a shooting that occurred years and years ago during Obama's presidency. Somebody yelled out some anti-muslim rhetoric during the moment of silence, which I thought was so disrespectful. And I said after the game, the first thing I said was, 'There's no place for that kind of hate in this world. Regardless of what happened [or] what you think happened.'… I said something about that and President Obama sent me a hand-written note afterward. And everybody loved that part. They enjoyed my takes. Mina Kimes had me to her house for a feature I did. All of these people were my friends in the media. Until I came about against COVID."
It's not exactly disputable that Rodgers gets no benefit of the doubt from the media after being a genuine media favorite for a long time. To tie it back to his vaccination status is probably pretty on point.
Let us know what you think in the comments. Be sure to bookmark Behind the Steel Curtain for all the latest news, breakdowns, and more!
#Media #years #think

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
A.B. Quintanilla, the brother of the late "Queen of Tejano Music" Selena, is responding to the statement released by his mother Marcella Quintanilla and sister Suzette Quintanilla-Arriaga — a statement that said he was making "false accusations" about his family members and damaging their reputations.
"I don't lie," A.B. wrote in his latest statement shared on Wednesday (Sept. 2). "Suzette and her lawyers were notified with the corresponding documents via certified mail and electronic mail. She was notified of a lawsuit related to her fiduciary duties, that is, her legal obligations to act with loyalty, transparency and in the best interests of those she was responsible to."
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
He continued, "She responded, but did not provide what was being requested: contracts, documentation and financial information. Those fundamental requirements were left unanswered. What she did under the excuse of using my mom for convenience. She had no idea what was really happening around her and never had any participation in anything."
A.B. says that his lawyer will speak out on Friday (Sept. 4) where "many things will be made clear."
#notified
2 months ago
On August 5, Murphy USA (NYSE:MUSA) reported second-quarter results that make the case for its unglamorous business model. Net income came in at $209.1 million, or $11.27 per diluted share, up from $145.6 million and $7.36 per share in the same quarter of 2025. Adjusted EBITDA climbed to $377.3 million from $286.0 million. For a company that mostly sells gasoline and convenience store snacks, that is a striking jump, and it did not come from a single lucky quarter.
The engine behind the gain was fuel. Total fuel contribution reached 40.6 cents per gallon in the quarter, up from 32.0 cents a year earlier, while the retail fuel margin alone rose 20.2% to 35.1 cents per gallon. Volume grew at the same time, with total retail gallons up 3.9% and same-store sales volumes up 0.5%, so Murphy USA was not just pricing better; it was also moving more gas through its pumps. Merchandise held up its end too, with contribution dollars up 4.0% to $227.4 million on unit margins of 20.1%, as nicotine contribution rose 6.1% and non-nicotine contribution grew 2.9%.
The company kept returning cash to shareholders through it all, buying back 143.1 thousand shares for $76.8 million and raising its quarterly dividend 28.0% year over year to $0.64 per share. In May, it issued $500 million of notes due 2034 and used the proceeds to retire $300 million of 2027 notes, pushing out its debt maturities while continuing to open new stores, with 6 net additions in the quarter and 36 more under construction.
The quarter's growth came with a heavier expense load. Total store and other operating expenses rose to $308.7 million from $275.2 million, and the company said two-thirds of that increase came from payment processing fees, which climb automatically as retail fuel prices rise. SG&A costs increased to $60.5 million from $50.9 million on higher employee costs and incentive accruals, and the effective tax rate ticked up to 24.7% from 24.4%, with guidance now pointing to the higher end of the company's 23% to 25% full-year range.
Fuel supply contribution, excluding renewable credits, was negative $54.9 million, a wider loss than the negative $25.9 million posted a year earlier. Management's own full-year outlook **** umes some cooling ahead: its projection of roughly $636 million in net income and $1.25 billion in Adjusted EBITDA is built on second-half fuel margins averaging 35 cents per gallon, down from 37.9 cents in the first half. Capital expenditures are also being guided to the higher end of the $475 million to $525 million range, meaning the spending pace is not slowing even as margins are expected to.
#million #fuel #total #same

2 months ago
Few retail chains that filled malls in the 1980s and 1990s still exist today.
Teenage me could have shopped at Chess King for shiny shirts, visited Gadzooks for baggy pants, or gone a little classier and purchased dressier clothes at Structure. All of those chains were fairly, if not very, popular for a minute, and none of them exist now.
Former Tory Burch Chief Client Officer Francesca Danzi told Forbes that it's a major challenge for a brand to remain relevant across decades.
"Enhancing retail experience is key and goes beyond adding omnichannel capabilities that boost convenience. We are witnessing the rise of experiential retail that is reshaping the store of the future," she said.
Danzi does not see the so-called retail apocalypse as a crisis where stores are closing, but as an opportunity to right-size store portfolios.
#danzi #chains #store
2 months ago
On August 5, Murphy USA (NYSE:MUSA) reported second-quarter results that make the case for its unglamorous business model. Net income came in at $209.1 million, or $11.27 per diluted share, up from $145.6 million and $7.36 per share in the same quarter of 2025. Adjusted EBITDA climbed to $377.3 million from $286.0 million. For a company that mostly sells gasoline and convenience store snacks, that is a striking jump, and it did not come from a single lucky quarter.
The engine behind the gain was fuel. Total fuel contribution reached 40.6 cents per gallon in the quarter, up from 32.0 cents a year earlier, while the retail fuel margin alone rose 20.2% to 35.1 cents per gallon. Volume grew at the same time, with total retail gallons up 3.9% and same-store sales volumes up 0.5%, so Murphy USA was not just pricing better; it was also moving more gas through its pumps. Merchandise held up its end too, with contribution dollars up 4.0% to $227.4 million on unit margins of 20.1%, as nicotine contribution rose 6.1% and non-nicotine contribution grew 2.9%.
The company kept returning cash to shareholders through it all, buying back 143.1 thousand shares for $76.8 million and raising its quarterly dividend 28.0% year over year to $0.64 per share. In May, it issued $500 million of notes due 2034 and used the proceeds to retire $300 million of 2027 notes, pushing out its debt maturities while continuing to open new stores, with 6 net additions in the quarter and 36 more under construction.
The quarter's growth came with a heavier expense load. Total store and other operating expenses rose to $308.7 million from $275.2 million, and the company said two-thirds of that increase came from payment processing fees, which climb automatically as retail fuel prices rise. SG&A costs increased to $60.5 million from $50.9 million on higher employee costs and incentive accruals, and the effective tax rate ticked up to 24.7% from 24.4%, with guidance now pointing to the higher end of the company's 23% to 25% full-year range.
Fuel supply contribution, excluding renewable credits, was negative $54.9 million, a wider loss than the negative $25.9 million posted a year earlier. Management's own full-year outlook ***** umes some cooling ahead: its projection of roughly $636 million in net income and $1.25 billion in Adjusted EBITDA is built on second-half fuel margins averaging 35 cents per gallon, down from 37.9 cents in the first half. Capital expenditures are also being guided to the higher end of the $475 million to $525 million range, meaning the spending pace is not slowing even as margins are expected to.
#million #cents #total #Share


2 months ago
There aren't too many dividend stocks that yield more than 5%. Those that do can be separated into high- and low-risk categories, and most investors, especially those who rely on passive income, are looking for low-risk options.
Realty Income (NYSE: O) boasts a 5.3% dividend yield, and it's as reliable as they come. Here's why it's my pick for the top S&P 500 (SNPINDEX: ^GSPC) stock with a yield above 5%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Realty Income is a real estate investment trust (REIT), a structure that pays out 90% of earnings as dividends. REITs often play a big role in a dividend-focused portfolio, although there are all sorts of REITs, some of which are high-risk and some that don't pay high yields.
REITs buy and lease properties, and they typically have an industry focus. Realty Income is a retail REIT, meaning it predominantly leases its properties to retailers. Its tenant roster includes some of the largest and most stable retailers in the U.S., such as Walmart and Home Depot. Grocery and convenience stores make up more than 20% of its total portfolio, and it services other essential retail categories like pharmacy and home improvement, which is why its tenant base is so reliable.
#realty #yield #high

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a place to keep your money, big national banks and online banks aren't your only options. Mutual banks are depositor-owned financial institutions that operate for the benefit of their customers rather than outside shareholders. That structure can translate to competitive rates, lower fees, and a greater focus on the local community — but there are potential drawbacks, too.
Here's how mutual banks work, their pros and cons, and how to decide whether one is right for you.
Mutual savings banks, or mutual banks, offer all the same accounts you can get at other banks, but they have some fundamental differences. These institutions are owned by customers instead of shareholders, and their main focus is on giving you access to savings accounts and mortgages.
Mutual banks, which represent less than 10% of all financial institutions in the U.S., tend to be small. While they may lack some of the conveniences you get with large banks, such as technology-driven services and vast ATM networks, there are some compelling reasons to switch banks and join a mutual institution:
#banks #owned #savings
2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management is prioritizing a return to core fundamentals in the Snacks division, specifically targeting households with kids for Goldfish and launching national brand campaigns for Pepperidge Farm.
The Meals and Beverage segment is leaning into 'semi-scratch' cooking trends, which represent 50% of at-home cooking occasions, by focusing on convenience with 5-ingredient-or-less recipes.
Performance attribution highlights a divergence in the soup portfolio, where cooking-related products (broth and condensed) are performing well while 'eating' soups require further innovation to meet consumer value needs.
The company is implementing a new $500 million enterprise cost-savings program through fiscal 2030, focusing on procurement efficiencies and supply chain network optimization.
#focusing


2 months ago
Ro Khanna is a Democratic congressman known for being one of the most active stock traders in Congress, with hundreds of disclosed transactions. Khanna says the trades sit in family accounts he does not control.
His disclosures show he has been buying NCR Voyix (NYSE:VYX), a small-cap company that sells checkout technology to retailers and restaurants.
The most recent trade was a buy in June. There were about seven purchases of this stock from Khanna in 2026.
NCR Voyix sells the checkout technology that grocery stores, convenience chains and restaurants run on. The business splits into two segments, Retail and Restaurants, with retail accounting for a major chunk of sales.
The company is in the middle of a rebuild. It handed hardware manufacturing to an ODM partner at the end of the first quarter of fiscal 2026, so hardware now shows up as commission instead of full product revenue. Management is pushing customers onto the Voyix Commerce Platform, a cloud system sold on multiyear subscription contracts, and onto Voyix Connect, its payments gateway.
#khanna #retail #checkout

2 months ago
Shell has agreed to take full control of U.S. convenience store operator and fuel distributor Tri Star Energy, in a transaction that will more than double the energy major's company-owned convenience retail footprint in the United States.
Equilon Enterprises, which operates as Shell Oil Products US, will increase its ownership of Nashville-based Tri Star from 33% to 100%. The acquisition includes 320 fuel and convenience retail sites in Tennessee and surrounding states, along with fuel-supply agreements covering another 552 dealer-owned locations. Financial terms were not disclosed.
Shell is acquiring the remaining interest from The Parman Corporation, Kimbro Oil Company and their subsidiaries. The deal is expected to close by the end of 2026, subject to regulatory approval and customary closing conditions.
The transaction represents a substantial expansion of Shell's directly controlled retail operations. While Shell already has around 12,000 branded fuel and convenience sites across 49 U.S. states, the vast majority are operated by wholesalers or dealers rather than owned directly by the company. Shell says its U.S. network serves more than 7 million customers per day.
Following completion, Tri Star will be operated by Texas Petroleum Group, a wholly owned unit of Shell Mobility & Convenience US. Shell expects the combined business to have nearly 550 company-owned convenience retail locations and supply agreements with around 650 dealer-owned sites across the southern United States.
Tri Star, founded in 2000, operates convenience-store brands including Twice Daily, Sudden Service and Little General and also owns the White Bison Coffee brand. Its wholesale fuel operation reaches multiple states, giving Shell additional exposure to both fuel distribution and higher-margin convenience and food-and-beverage sales.
#shell #convenience #retail

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you use a rewards credit card, you're more like a millionaire than you may think. Although most adults have credit cards, millionaires are even more likely to use them. According to the Federal Reserve, almost all adults with incomes over $100,000 have a credit card in their name.
But if millionaires are so wealthy, why do they rely on credit? Credit cards provide plenty of benefits, even for the super-wealthy. However, you don't need a seven-figure net worth to take advantage of those benefits.
Dig deeper: Our top picks for best credit card
Millionaires use credit cards thanks to the convenience and perks they provide. These are some of the key benefits of using a credit card — even for people who can easily afford any purchase in cash:
#even #benefits #adults #wealthy


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Credit cards can offer a range of benefits, including rewards, perks, security, and convenience. However, they can also charge high interest rates, threatening your financial security. The good news is that you don't have to worry about credit card interest if you pay your balance on time and in full every month. However, if you regularly carry a balance or might not be able to afford an upcoming payment, it's a good idea to know what to expect.
Credit card companies typically calculate interest daily, which means that accruing interest is compounding. To get started, you'll need to know the following information:
Days in your billing cycle: Check your monthly statement to determine the number of days in your most recent billing period.
Annual percentage rate: This is the interest rate on your account; it can be found in your original cardholder agreement or on your most recent billing statement.
#security #card #balance


2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
For many renters, their monthly rent payment is the biggest recurring expense. If you have a rewards credit card or are struggling to keep up with your basic needs, you may wonder if you can use your credit card to pay your landlord.
While it's technically possible to pay rent with a credit card, it's important to understand the potential pitfalls and the right way to do it. Here's what you need to know.
Yes, it's possible to pay rent with a credit card. You may have a few different options, depending on your situation.
Some landlords and property managers use a payment system that allows tenants to pay with a credit card. Unfortunately, many of these services charge a convenience fee, which typically ranges from 2% to 3% of the payment amount but can be higher.
#card #possible



2 months ago
Investment management company First Pacific Advisors recently released its "FPA Queens Road Small Cap Value Fund" second-quarter 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned 27.02% in the first half of 2026, outperforming the Russell 2000 Value Index's 22.99% gain and the S&P 600 Index's 23.90% return. Small-cap earnings growth also began accelerating relative to large caps, while the small-cap technology sector surged nearly 100% in 26H1. The fund's technology holdings gained 72.39%, contributing 14.87 percentage points, compared with a 95.27% return and 7.10-point contribution from the benchmark's technology sector. Excluding IT and cash, the Fund contributed 12.73% versus 15.89% for the Russell 2000 Value Index; on a fully invested basis, the figures were 16.62% and 17.59%, respectively. The portfolio continued to trim appreciated technology holdings amid the AI-driven rally, while maintaining a bottom-up approach and avoiding beaten-down SaaS stocks due to the widening range of AI-related outcomes. The fund also eliminated about $62 million in capital gains during Q2 and approximately $140 million year-to-date through July, while ending the quarter with 10.2% in cash. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, FPA Queens Road Small Cap Value Fund highlighted stocks like Vontier (NYSE:VNT). Vontier (NYSE:VNT) provides technology and solutions for mobility, transportation, and industrial markets, including fueling, fleet, and repair applications. The one-month return of Vontier (NYSE:VNT) was -4.76% while its shares traded between $27.25 and $48.20 over the last 52 weeks. On August 31, 2026, Vontier (NYSE:VNT) stock closed at approximately $32.76 per share, with a market capitalization of about $4.35 billion.
FPA Queens Road Small Cap Value Fund stated the following regarding Vontier (NYSE:VNT) in its Q2 2026 investor letter:
"In Q2 we added new position. Vontier (NYSE:VNT) manufactures tanks, pumps and payment systems for gas stations. The company was a 2021 spinoff from Fortive, which itself was the spinoff of Danaher's lower growth industrial ****** ets. Since 2021, Vontier has been dealing with headwinds following a pull forward of sales from changing payment standards (EMV) and reorganizing the disparate collection of businesses that were originally acquired by Danaher. At their November 2025 Investor Day, Vontier made the cogent argument that they benefit from potential sales to the growing convenience store end market. We believe that shares are attractively priced at roughly 9x earnings."
#NYSE #fund #small #technology

2 months ago
McLaren spent the first half of 2026 looking like last year's champion team in name only. The wins dried up, the new car took time to come alive and even as Lando Norris kept putting points on the board, the gap to Kimi Antonelli kept growing. Then Hungary happened, Zandvoort followed, and two weeks was all it took to change the mood of the season.
Norris has now won the last two grands prix and sits fourth in the standings at 159 points, 83 behind Antonelli and 24 behind Lewis Hamilton and George Russell, who are tied at 183. That is still a mountain for Norris and McLaren to climb, but it is no longer out of the question.
Also Read:Ferrari Must Win at Monza or Watch Its ****** le Shot Slip Away
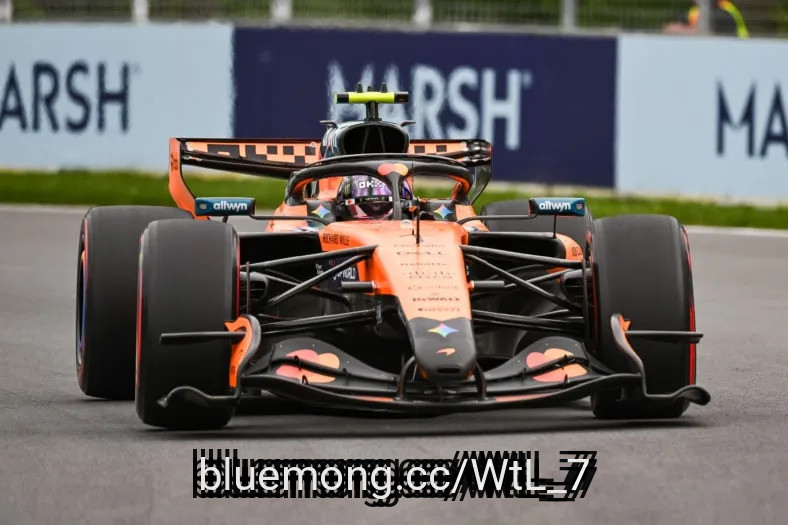
May 23, 2026; Montreal, Quebec, CANADA; McLaren driver Lando Norris (1) during the qualifying session of the Lenovo Grand Prix Du Canada at Circuit Gilles-Villeneuve. Mandatory Credit: David Kirouac-Imagn Images
McLaren is third in the constructors' championship with 263 points, 75 behind Ferrari and 162 behind Mercedes. Another strong weekend at Monza would not crown anyone, but it would force the two teams ahead to treat McLaren as a Sunday problem rather than a midfield inconvenience.
#Ferrari

2 months ago
The broader retail industry is moving beyond physical stores, with channels including e-Commerce, digital advertising, memberships, and convenience-led fulfillment tagged as critical growth drivers. Furthermore, scale and pricing are important, and consumers continue to emphasize value. Such trends are supporting Walmart Inc. (NASDAQ:WMT).
The company has been benefiting from businesses that are beyond its traditional physical-store retail operations. Its Q2 revenue saw an increase of 5.9% to reach $187.9 billion, with global e-Commerce sales increasing by 23% and advertising revenue jumping by 38%. Membership revenue also rose 17%. This gives the company several higher-growth businesses alongside its core stores.
Investors gave more weight to its profitability. The company's adjusted operating income went up by 17.4% in constant currency, and its gross margin expanded 96 bps. Walmart Inc. (NASDAQ:WMT) reported $19.7 billion in operating cash flow. However, its FCF fell to $5.5 billion.
On the positive side, the company increased its FY 2027 outlook to 4%-5% sales growth and 7%-8.5% adjusted operating income growth. This means that earnings might continue to grow faster than its revenue.
Bernstein ***** yst Zhihan Ma kept a "Buy" rating on Walmart Inc. (NASDAQ:WMT)'s stock and a price objective of $142. As per the ***** yst, the quarter ended at the high end of guidance. The ***** yst opines that softer US comparable sales were mainly aided by pharmacy-related factors rather than deterioration in the company's core business. Also, the ***** yst anticipates the combined Q2-Q3 period to result in approximately mid-single-digit sales growth and around 10% EBIT growth.
#walmart #sales #analyst

2 months ago
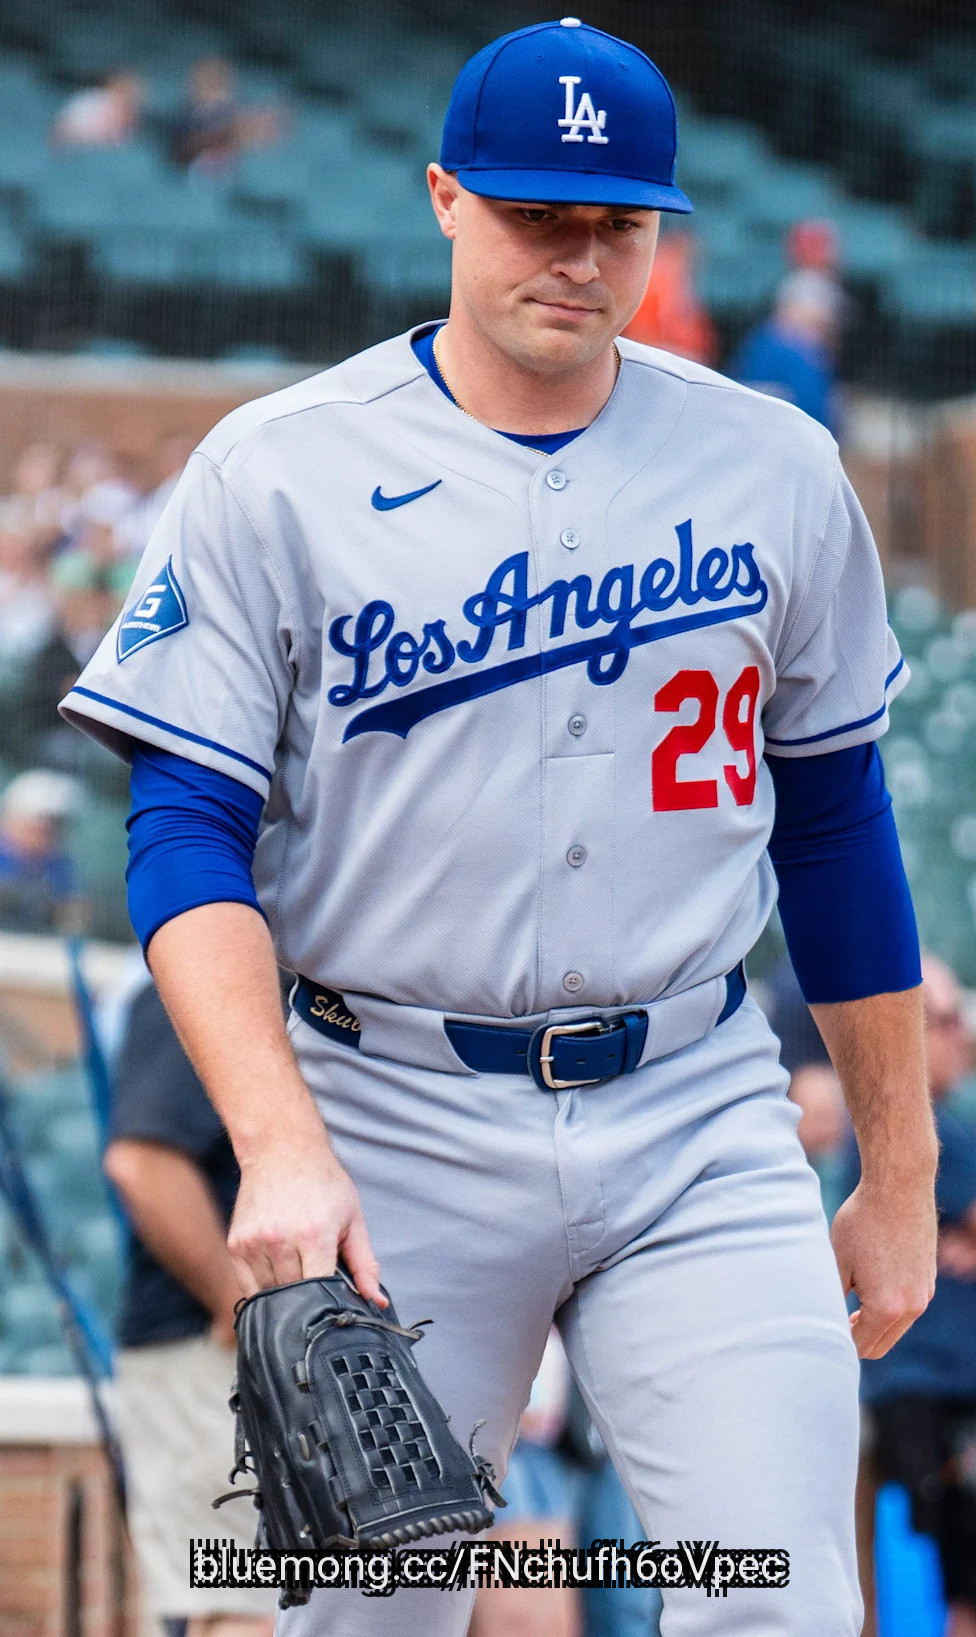
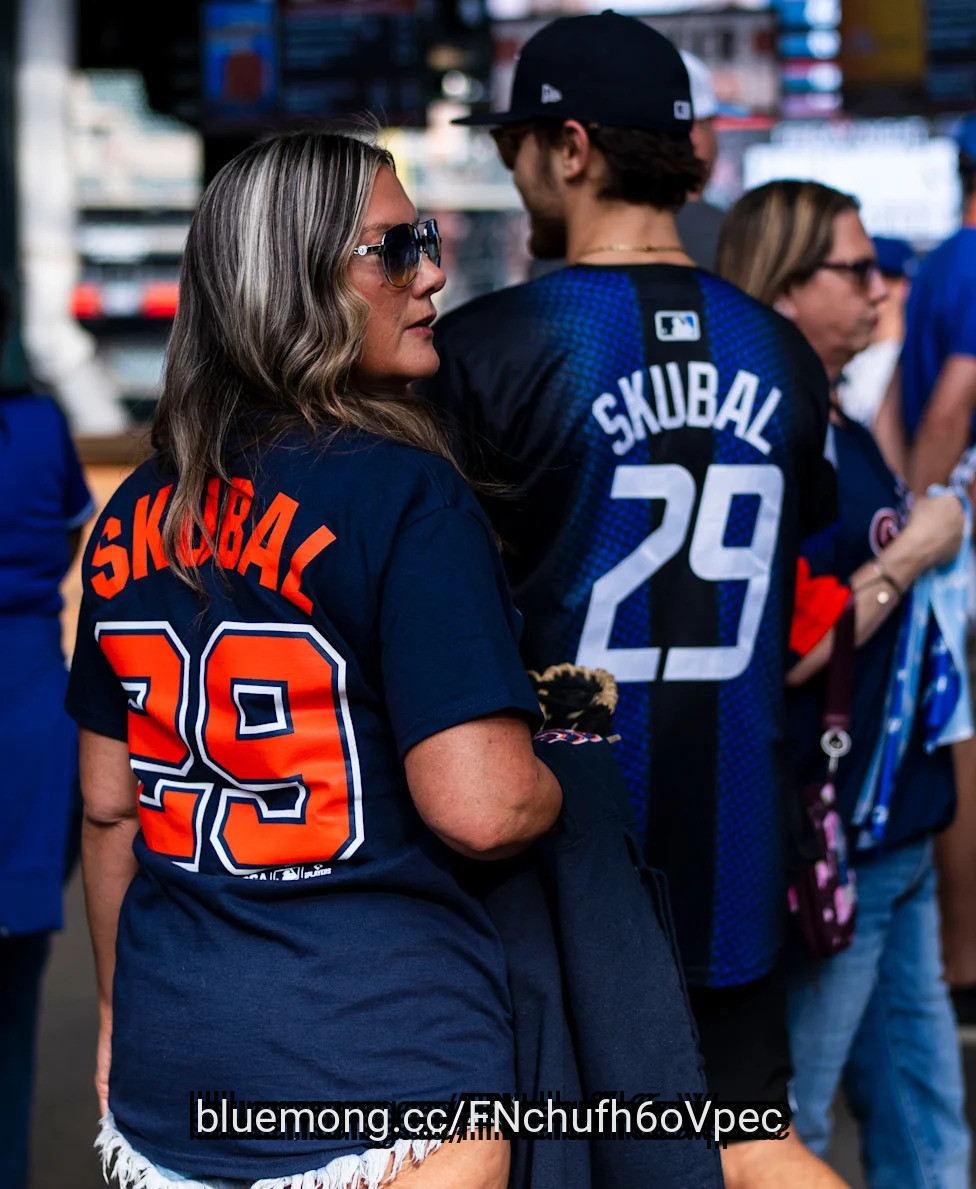
Los Angeles Dodgers pitcher Tarik Skubal looked comfortable sitting in the first-base dugout in the stadium he called home for his first seven MLB seasons – minus a few inconveniences that come from playing for the visiting team.
"I've never been on this side of the clubhouse. So when I first got here, I'm like, 'which way is the field?'" he said. "It's much farther down there. There's a lot more steps going on, but I guess it's good for your health."
The setting was familiar, but the threads were not. Skubal wore his usual headband and sleeveless hoodie, but both were dipped in Dodger blue instead of stamped with the Olde English D. The night before, he pitched six brilliant innings in the Dodgers' 2-1 win over the Detroit Tigers, returning to Comerica Park less than a month after the Tigers traded him to Los Angeles at the deadline for three prospects.
Skubal didn't have a say in where he went. But based on his interaction with the media before Detroit's game with the Dodgers on Saturday, Aug. 29, he looks to have landed in a situation he really likes.
"[The Dodgers] have won the last two World Series for a reason. It's not a mistake," he said. "You watch [first baseman Freddie Freeman's] ground ball routine, he does the same thing every single day. I think those routines matter, and they translate to the field, stuff they do in the cage, the way pitchers prepare ... no little thing is overlooked, and I think that's what makes good teams really good."
#really #thing

2 months ago
The FIBA World Cup is a very big deal in women's basketball, and it only comes around every four years, so you'd like for it to work smoothly. That is hardly the case for the event that begins on Friday in Berlin.
The timing, as it relates to the WNBA, is absurd. Here we have a nine-day tournament that finds the WNBA suddenly going dark near the end of its regular season, then resuming with only four games remaining per team.
The Valkyries' season goes on pause on Sunday (against Portland) and doesn't restart until Sept. 18. That's nearly a three-week break for the league's hottest team - all the while uncertain about their playoff opponent, with the seedings still to be determined.
They'll have four players engaged in the World Cup: Gabby Williams and Janelle Salaün (France), Cecilia Zandalasini (Italy) and Miela Sowah, a development player who has appeared in just five Valkyries games but was recently added to the Australian team.
Conveniently, the WNBA's eight-team playoff group is locked in, so that's one inconvenience out of the way. Certain teams and players could certainly use a break, but the league is understandably worried about injuries and, especially in the Valkyries' case, hard-earned momentum gone stale.
#team #case #season



2 months ago
Olivia Rodrigo wore a frilly micro minidress and styled it with Repetto heels for a Taco Bell ad. The singer is known for wearing dresses with playful and feminine silhouettes. This time, the "deja vu" hitmaker took her fashion game up a notch with a dress covered in delicate frills, pairing it with a classic pair of heels. While the dress exuded a soft and feminine vibe, the heels added a daring edge to the otherwise romantic silhouette.
Olivia Rodrigo paired her frilly micro minidress with Repetto heels for a Taco Bell campaign. The singer's photos were shared on X (formerly Twitter) by JumpTrailers and quickly received widespread attention. Fans were quick to compliment her look, with one calling her a "classy lady." Her outfit certainly lived up to the description, effortlessly blending elegance, sweetness, and a touch of modern edge.
The dress featured a soft white finish and a short silhouette. Its pleated construction created a gentle texture that added movement and dimension. Meanwhile, the short sleeves, accented with ruffle detailing, gave the dress an extra dose of softness and sweetness. The dress flared into a skirt, adding movement and another layer of delicate frilly detailing while giving it an almost doll-like look. A drawstring-style tie at the waist provided comfort and convenience while also adding structure to the silhouette.
The "drivers license" hitmaker paired the dress with black Repetto heels, creating a striking contrast against the white minidress. The pointed shape of the footwear added a sharp edge to the otherwise soft look, while the sleek black color provided the perfect contrast. She paired the black shoes with pink socks, creating an unexpected color combination that made the outfit feel more contemporary.
Rodrigo kept the rest of her styling simple, allowing the dress and footwear to remain the focus. She skipped statement accessories and opted for understated hair and makeup. Soft, flushed cheeks, defined eyes, a smooth lip shade, and sleek hair completed the look, giving her overall appearance a polished and effortlessly refined finish. In the photos, she can be seen holding a beverage with a smile on her face, adding a perfect dose of glamor to the ensemble and the overall look.
#look #rodrigo




