

1 day ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

2 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
According to average rates from the Zillow lender marketplace, mortgage rates are lower headed into the weekend.
The current 30-year fixed rate today, Saturday, September 19, 2026, fell by 1 basis point to 7.04%, the 20-year fixed rate fell 10 basis points to 6.82%, and the 5/1 ARM fell by 10 basis points to 7.04%.
Read more: Weekly survey of mortgage lenders with the lowest rates: Breaking the 7% barrier
Here are the current mortgage rates today, Saturday, September 19, 2026, according to the latest Zillow data:
#mortgage #fell #year
According to average rates from the Zillow lender marketplace, mortgage rates are lower headed into the weekend.
The current 30-year fixed rate today, Saturday, September 19, 2026, fell by 1 basis point to 7.04%, the 20-year fixed rate fell 10 basis points to 6.82%, and the 5/1 ARM fell by 10 basis points to 7.04%.
Read more: Weekly survey of mortgage lenders with the lowest rates: Breaking the 7% barrier
Here are the current mortgage rates today, Saturday, September 19, 2026, according to the latest Zillow data:
#mortgage #fell #year



2 days ago
Choosing the right mortgage lender could save you thousands of dollars. Shopping for one should be one the first steps you take when buying a house.
Comparing lenders and lining up preapprovals early gives you some benchmarks to work from, and when your real estate agent recommends lenders, you'll have a better sense of whether they're offering a good deal. Plus, having preapprovals in hand lets buyers and agents know you're serious.
Real estate agents typically have a roster of recommended lenders, often built on years of repeat business. "Choosing a lender is not just about obtaining financing," says Matthew Martinez, a California real estate broker. "It is about choosing one of the most important members of the transaction team."
Agents vet lenders to add to their networks, and they know what separates a good one from a bad one. Here are the four questions they say you should ask any lender you're considering.
A lender may offer a special program based on your profession, income or location that can make the mortgage more affordable.
#agents #estate #good #know
Comparing lenders and lining up preapprovals early gives you some benchmarks to work from, and when your real estate agent recommends lenders, you'll have a better sense of whether they're offering a good deal. Plus, having preapprovals in hand lets buyers and agents know you're serious.
Real estate agents typically have a roster of recommended lenders, often built on years of repeat business. "Choosing a lender is not just about obtaining financing," says Matthew Martinez, a California real estate broker. "It is about choosing one of the most important members of the transaction team."
Agents vet lenders to add to their networks, and they know what separates a good one from a bad one. Here are the four questions they say you should ask any lender you're considering.
A lender may offer a special program based on your profession, income or location that can make the mortgage more affordable.
#agents #estate #good #know
3 days ago
One of the challenges for nontraditional fintech lenders has been the expense **** ociated with lending.
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest
Because most of them do not have bank charters, they must partner with a traditional third-party bank to fund their loans. However, they must pay a fee or provide a cut of interest income earned on every loan they make using a third party. That eats into their profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
A federal bank charter would allow the fintechs to take deposits, because without one, they cannot. The deposits serve as an internal funding source, as loans can be made from the deposit base. With an internal funding source, these fintechs do not have to get third-party funding for loans, which, in turn, allows them to save on fees and collect all of the interest income.
Since fintechs started popping up more frequently over the past five or six years, federal regulators have been reluctant to grant bank charters to fintechs, imposing stringent requirements. But that has changed over the past couple of years as restrictions have eased. There has been a surge in the number of fintechs applying for, and getting, bank charters.
#Fintechs #missed #interest


3 days ago
Financial services company Enova International (NYSE: ENVA) seemed headed for the investor doghouse late Thursday. The company, which focuses on lending to underserved individuals and small businesses, withdrew its applications for banking licenses.
As investors considered this a defeat for the company, they promptly and vigorously sold the stock. As of Thursday evening, according to data compiled by S&P Global Market Intelligence, its price had fallen by nearly 20% week to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In December 2025, Enova announced it had signed a definitive agreement to acquire Grasshopper Bancorp, the holding company for a Federal Deposit Insurance Corporation (FDIC)-insured online lender Grasshopper Bank. Around that time, Enova submitted a clutch of applications to federal and state authorities for it to provide banking services as Grasshopper's would-be owner.
Enova said the decision was in the best interests of the company and its investors. It cited a lack of clarity in the authorization process as a roadblock for its ambition.
#signal
As investors considered this a defeat for the company, they promptly and vigorously sold the stock. As of Thursday evening, according to data compiled by S&P Global Market Intelligence, its price had fallen by nearly 20% week to date.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In December 2025, Enova announced it had signed a definitive agreement to acquire Grasshopper Bancorp, the holding company for a Federal Deposit Insurance Corporation (FDIC)-insured online lender Grasshopper Bank. Around that time, Enova submitted a clutch of applications to federal and state authorities for it to provide banking services as Grasshopper's would-be owner.
Enova said the decision was in the best interests of the company and its investors. It cited a lack of clarity in the authorization process as a roadblock for its ambition.
#signal


3 days ago
The Hain Celestial Group, Inc. (NASDAQ:HAIN) announced on September 14 that it agreed to sell most international operations to AURELIUS for estimated cash consideration of $323 million. Expected net proceeds of $305 million to $310 million would repay debt and leave a business concentrated in North America.
The immediate hurdle is financing. The agreement, signed September 12, requires a credit-agreement amendment by October 12 extending the December 22, 2026 maturity by at least nine months. AURELIUS can terminate if that amendment is not secured by the deadline.
The Hain Celestial Group, Inc. (NASDAQ:HAIN) expects closing in its fiscal second quarter ending December 31, subject to lender agreement and regulatory approvals. The dollar consideration estimates also depend on exchange rates because the purchase price is denominated in sterling.
The transaction could materially reduce the debt burden. The Hain Celestial Group, Inc. (NASDAQ:HAIN) reported $558 million of total debt as of June 30. Subtracting the estimated net proceeds implies approximately $248 million to $253 million remaining, a calculation using rounded figures before subsequent borrowings, repayments, or other changes.
That reduction could lower interest expense and give management more room to stabilize the retained brands. The remaining portfolio includes Celestial Seasonings tea, The Greek Gods yogurt and Earth's Best baby and kids foods.
#december
The immediate hurdle is financing. The agreement, signed September 12, requires a credit-agreement amendment by October 12 extending the December 22, 2026 maturity by at least nine months. AURELIUS can terminate if that amendment is not secured by the deadline.
The Hain Celestial Group, Inc. (NASDAQ:HAIN) expects closing in its fiscal second quarter ending December 31, subject to lender agreement and regulatory approvals. The dollar consideration estimates also depend on exchange rates because the purchase price is denominated in sterling.
The transaction could materially reduce the debt burden. The Hain Celestial Group, Inc. (NASDAQ:HAIN) reported $558 million of total debt as of June 30. Subtracting the estimated net proceeds implies approximately $248 million to $253 million remaining, a calculation using rounded figures before subsequent borrowings, repayments, or other changes.
That reduction could lower interest expense and give management more room to stabilize the retained brands. The remaining portfolio includes Celestial Seasonings tea, The Greek Gods yogurt and Earth's Best baby and kids foods.
#december


3 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Apollo Global Management (NYSE:APO) is in talks to increase its loan to SoftBank's Vision Fund II from $5.4 billion to as much as $9 billion, potentially giving the ******* anese conglomerate additional financing capacity for its massive investment in OpenAI.
The deal size has not yet been determined, according to Bloomberg.
Apollo has previously extended financing to SoftBank's venture capital arm in 2021. The lender increased the facility by another $900 million last year, bringing its total size to $5.4 billion. NAV financing allows private capital managers to raise liquidity by using investments held with their funds as collateral.
Read Also:KKR Doubles Private Debt Deals to $80 Billion as AI Spending Explodes
#capital #finance #management
Apollo Global Management (NYSE:APO) is in talks to increase its loan to SoftBank's Vision Fund II from $5.4 billion to as much as $9 billion, potentially giving the ******* anese conglomerate additional financing capacity for its massive investment in OpenAI.
The deal size has not yet been determined, according to Bloomberg.
Apollo has previously extended financing to SoftBank's venture capital arm in 2021. The lender increased the facility by another $900 million last year, bringing its total size to $5.4 billion. NAV financing allows private capital managers to raise liquidity by using investments held with their funds as collateral.
Read Also:KKR Doubles Private Debt Deals to $80 Billion as AI Spending Explodes
#capital #finance #management


3 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Prequalification is a rough estimate of how much you may be able to borrow, while preapproval is a vetted, conditional commitment of the amount and interest rate a lender feels comfortable offering you for a mortgage.
Prequalification is based on the information you provide, whereas a preapproval requires a soft credit pull and is a more accurate representation of what you can borrow.
Preapproval vs. prequalification can vary from lender to lender in terms of definition, and it's important to understand the differences as you begin your homebuying journey.
Prequalification
#preapproval #affect
Prequalification is a rough estimate of how much you may be able to borrow, while preapproval is a vetted, conditional commitment of the amount and interest rate a lender feels comfortable offering you for a mortgage.
Prequalification is based on the information you provide, whereas a preapproval requires a soft credit pull and is a more accurate representation of what you can borrow.
Preapproval vs. prequalification can vary from lender to lender in terms of definition, and it's important to understand the differences as you begin your homebuying journey.
Prequalification
#preapproval #affect



4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#next #five
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#next #five


4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans


4 days ago
The best time to refinance is when your credit score or overall financial situation has improved.
Generally, you should aim to either lower your interest rate or your monthly payment — preferably both.
Avoid refinancing when auto loan rates are high or if you won't be able to save money by switching lenders.
It makes sense to consider refinancing your auto loan if you can lower your interest rate and monthly payment. The refinancing process involves swapping your current loan for a new loan with different — and ideally better — terms.
However, refinancing is not always a wise financial move. If interest rates are high, or if you're close to paying off your loan, then it may make more sense to stick with your current lender. Knowing the ins and outs of when to refinance and when to wait will help you make the best decision for refinancing your auto loan.
#financial #lower
Generally, you should aim to either lower your interest rate or your monthly payment — preferably both.
Avoid refinancing when auto loan rates are high or if you won't be able to save money by switching lenders.
It makes sense to consider refinancing your auto loan if you can lower your interest rate and monthly payment. The refinancing process involves swapping your current loan for a new loan with different — and ideally better — terms.
However, refinancing is not always a wise financial move. If interest rates are high, or if you're close to paying off your loan, then it may make more sense to stick with your current lender. Knowing the ins and outs of when to refinance and when to wait will help you make the best decision for refinancing your auto loan.
#financial #lower


4 days ago
Before signing off on an auto loan, crunch the numbers to ensure you can afford your new set of wheels.
To find how much you'll spend on interest, use an auto loan calculator, work it out yourself or talk to a lender.
Factors including car specifics, the economy, your credit history and overall financial health determine your car loan interest rate.
To avoid paying too much in interest, shop around for the right loan and save up ahead of purchase.
With so many online auto calculators available, car buyers may not give that much thought to how to calculate interest on a car loan. You don't need to be a math whiz: You just multiply the loan balance by your interest rate and divide it by the number of months you have left on your loan term.
#numbers
To find how much you'll spend on interest, use an auto loan calculator, work it out yourself or talk to a lender.
Factors including car specifics, the economy, your credit history and overall financial health determine your car loan interest rate.
To avoid paying too much in interest, shop around for the right loan and save up ahead of purchase.
With so many online auto calculators available, car buyers may not give that much thought to how to calculate interest on a car loan. You don't need to be a math whiz: You just multiply the loan balance by your interest rate and divide it by the number of months you have left on your loan term.
#numbers

4 days ago
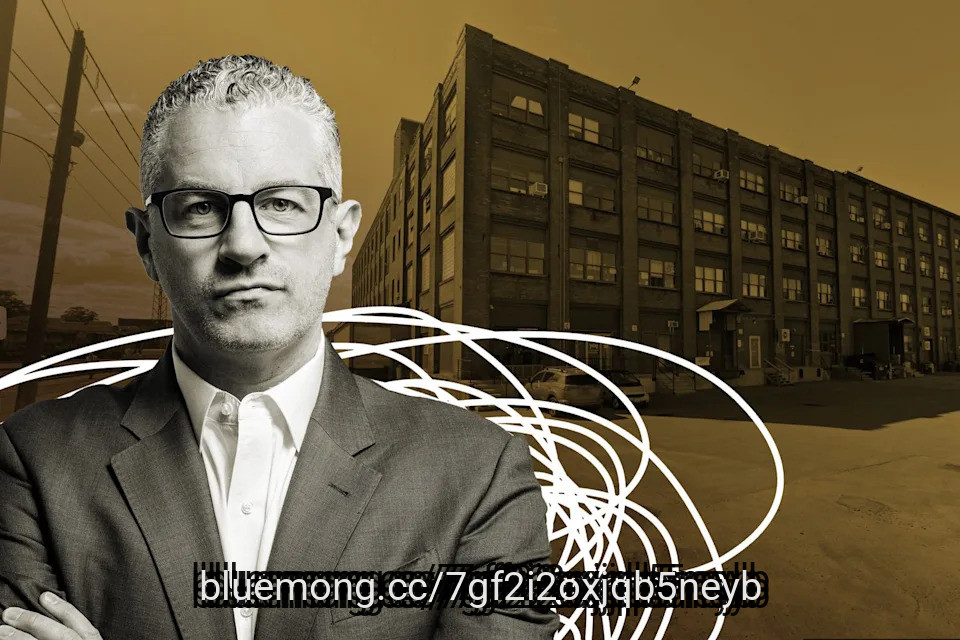
Peter Hungerford has six weeks to save a Rochester investment that shares his name.
An auction for Rochester's "Hungerford Building" — named for a distant relative of the Staten Island real estate investor — has been scheduled for Oct. 29. The lender filed a foreclosure case in September 2025 and has moved to take the building.
Hungerford says the sale won't happen. He said he's working on securing a construction loan to pay off the debt on the building.
Hungerford first made headlines for his bullish take on rent-stabilized properties in New York City and his involvement with the Haruvi real estate family.
A Hungerford affiliate took out an $8.25 million loan on the building in 2022 from a lender ****** ociated with Sheridan Capital. The plan was to add 200 apartments to the four-story former industrial building.
#estate #take #loan
An auction for Rochester's "Hungerford Building" — named for a distant relative of the Staten Island real estate investor — has been scheduled for Oct. 29. The lender filed a foreclosure case in September 2025 and has moved to take the building.
Hungerford says the sale won't happen. He said he's working on securing a construction loan to pay off the debt on the building.
Hungerford first made headlines for his bullish take on rent-stabilized properties in New York City and his involvement with the Haruvi real estate family.
A Hungerford affiliate took out an $8.25 million loan on the building in 2022 from a lender ****** ociated with Sheridan Capital. The plan was to add 200 apartments to the four-story former industrial building.
#estate #take #loan

4 days ago
The financial unraveling of Jon Venetos' Lurin Capital is now the subject of a Federal Bureau of Investigation probe.
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.
#email
An email sent to an investor from the FBI's Dallas Division shared with The Real Deal revealed that the agency has opened an investigation into Venetos, Lurin Capital and **** ociated entities. The note provided an email address through which victims can provide comments and ask questions: LurinVictimsfbi.gov.
The Real Deal also obtained a public link to an FBI form **** led "Lurin Investigation Questionnaire" seeking information from "possible victim" investors. The form asks for details about investors' contributions and any distributions received.
The company's downfall has been punctuated by claims of fraudulent dealings from lenders and former Lurin employees. Keybank accused Venetos of transferring $25,000 from his accounts with the bank to a personal account. Vista Bank accused him of falsifying account statements from the lender in an attempt to take out loans elsewhere.
In addition, a former employee who worked in property management and asked to remain anonymous claimed Lurin lied on reimbursement requests to lenders by inflating costs of repairs and submitting invoices for work that wasn't done.


4 days ago
While the average personal loan interest rate is 12.44%, borrowers with excellent credit may have access to rates as low as 5.96%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing

4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#rates #five #yields
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#rates #five #yields


4 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer

5 days ago
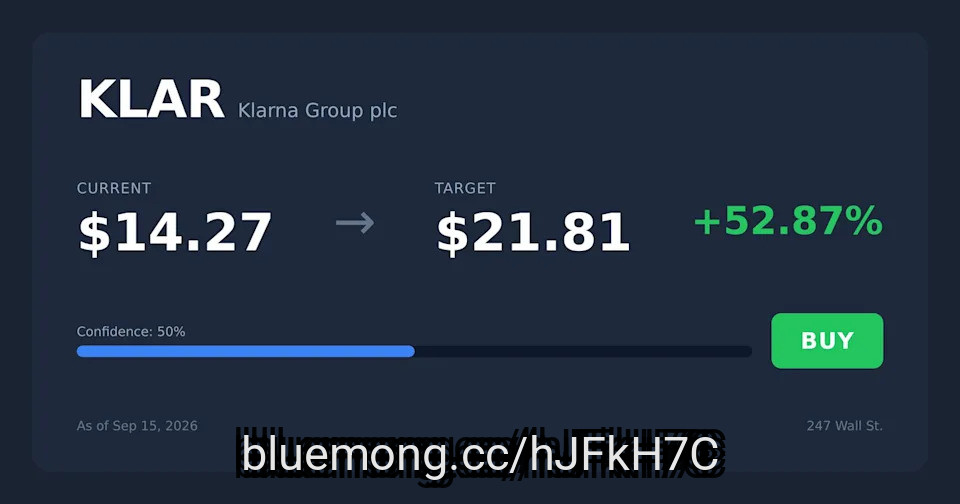
Klarna stock has cratered 51% year to date and 32% in just the past month, trading near its 52-week low of $12.
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month
While KLAR collapsed, Sezzle surged 87% and Affirm slipped just 3%, signaling Klarna's pain is company-specific, not a BNPL sector rout.
Klarna's Q2 showed transaction margin up 42% and a swing to $9M net profit, but a guidance cut and accounting changes cloud the Q3 outlook.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now, and Klarna Group plc didn't make the cut. Enter your email to see the names that beat KLAR. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Klarna (NYSE:KLAR) are trading at $14.23 on Tuesday afternoon, leaving the buy now, pay later (BNPL) lender down 51% year to date. Klarna stock is also down 32% over the past month, meaning much of the damage has landed recently rather than fading out.
#klar #year #month



5 days ago
Sept 15, 2026, 2:38 pm EDT
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana
For months, investors and banking industry executives have privately speculated Wells Fargo could be poised to acquire a smaller lender.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
Insurers like Humana are canceling some Medicare Advantage plans. How to make the best of it.
#sept #wells #reserved #humana


5 days ago
An AI approval in minutes means nothing if you retire before closing. Lenders must re-verify employment within 10 business days of the note date.
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval
Retirement income like Social Security can replace a salary for qualifying purposes, and an SSA award letter alone may be enough to close.
A rate lock protects only the interest rate, so disclose your retirement date early and build the loan file around income that survives closing day.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Mortgage lenders are racing to make refinancing feel almost instantaneous. Better.com says an initial approval can take as little as two minutes. For a borrower nearing retirement, that speed creates a strange new trap.
#approval

5 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Debt settlement is a debt relief strategy where you negotiate with creditors to pay less than the full amount you owe, often through a lump-sum payment. In some cases, a creditor will accept as little as 50% of your balance.
A successful debt settlement has the potential to save you money and get you out of debt, but it comes with serious trade-offs, including potential fees, damage to your credit, and tax liabilities. There's also no guarantee that your lender will agree to settle your debt.
It's important to understand these pros and cons to determine whether debt settlement is a viable path for you.
While you can pursue debt settlement on your own, there are companies that offer debt settlement services and negotiate directly with the lender on your behalf. Here are the steps you'll typically take to settle a debt:
#settlement #lender #disclosure #here
Debt settlement is a debt relief strategy where you negotiate with creditors to pay less than the full amount you owe, often through a lump-sum payment. In some cases, a creditor will accept as little as 50% of your balance.
A successful debt settlement has the potential to save you money and get you out of debt, but it comes with serious trade-offs, including potential fees, damage to your credit, and tax liabilities. There's also no guarantee that your lender will agree to settle your debt.
It's important to understand these pros and cons to determine whether debt settlement is a viable path for you.
While you can pursue debt settlement on your own, there are companies that offer debt settlement services and negotiate directly with the lender on your behalf. Here are the steps you'll typically take to settle a debt:
#settlement #lender #disclosure #here



6 days ago
German lender Deutsche Bank (NYSE: $DB) plans to offer cryptocurrency custody to its institutional clients.
Germany's largest bank said in a news release that its digital **** et custody service is set to go live by the end of this year.
Deutsche Bank said the service will give European institutional and corporate clients regulated custody of cryptocurrencies such as Bitcoin (CRYPTO: $BTC).
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#bank #german #Bitcoin
Germany's largest bank said in a news release that its digital **** et custody service is set to go live by the end of this year.
Deutsche Bank said the service will give European institutional and corporate clients regulated custody of cryptocurrencies such as Bitcoin (CRYPTO: $BTC).
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#bank #german #Bitcoin

7 days ago
Three and a half years of freight recession did two things to the truck financing market at once. It shredded the credit profiles of the carriers who most needed to borrow. It also pushed a large share of the lenders who would have lent to them out of the sector. Both are now rationing the equipment replacement cycle the industry has spent two years waiting on.
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large

8 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates
With mortgage rates pushing 7%, the timing of a "rate sale" couldn't be better. Chase Home Loans is once again hosting a limited-time interest rate discount promotion.
The national lender launched its first weeks-only offer just over a year ago. Apparently, it's been enough of a success that Chase is bringing the rate sale back for its third encore.
The rate discount is available for three weeks only, from Monday, Sept. 14, through Sunday, Oct. 4. Chase Home Loans will offer homebuyers and homeowners discounted rates on all new mortgage purchase and refinance loans. The sale is available for both new and existing customers.
While offers vary by state, Chase says qualified buyers can receive up to 0.25% off their loan interest rate. For example, an offered rate of 6.75% could be cut to 6.50%. That would save a borrower over $23,800 in interest on a $400,000 loan with a fixed-interest 30-year term — and reduce the payment by more than $65 a month.
#offers #rates

9 days ago
If you are looking for yield today, rising interest rates have increased your options. For example, the 30-year Treasury bond's yield is around 5.3% as of this writing. By comparison, the S&P 500 index (SNPINDEX: ^GSPC) is only yielding around 1%. But there are still two big reasons why investors may want to buy a high-yield dividend stock like Coca-Cola (NYSE: KO), even though its 2.4% yield isn't even close to the 30-year Treasury yield.
A bond is an agreement between the lender and the borrower. The lender provides a fixed amount of cash, while the borrower pays interest at a fixed rate until the loan matures. When the loan matures, the borrower repays the bond's principal. Everything is fixed, and both the value of the interest collected and the bond's principal are slowly eroded by inflation. It doesn't matter that 30-year Treasuries are considered safe because they are backed by the U.S. government. The big inflation risk is still the same.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you have a short investment time horizon, inflation may not be a big issue for you. In which case, the 5.3% yield of a 30-year Treasury would probably be more attractive than Coca-Cola's 2.4% yield. However, if you have a long time horizon, Coca-Cola's yield comes with something that a Treasury doesn't: Growth.
Coca-Cola is one of the world's largest consumer staples companies. It has an incredible history of growth, highlighted by 64 annual dividend increases. That makes the company a Dividend King. But think about that for a second, you can collect 30 years of the same income from a bond or 30 years of increasing income from Coca-Cola. Since the start of 1996, roughly 30 years ago, the company's dividend has increased by nearly 750%. That dividend growth was driven by the company's growth, which also led to an over 300% increase in the stock price. If you hold a bond to maturity, all you get back is the principal.
#coca
A bond is an agreement between the lender and the borrower. The lender provides a fixed amount of cash, while the borrower pays interest at a fixed rate until the loan matures. When the loan matures, the borrower repays the bond's principal. Everything is fixed, and both the value of the interest collected and the bond's principal are slowly eroded by inflation. It doesn't matter that 30-year Treasuries are considered safe because they are backed by the U.S. government. The big inflation risk is still the same.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you have a short investment time horizon, inflation may not be a big issue for you. In which case, the 5.3% yield of a 30-year Treasury would probably be more attractive than Coca-Cola's 2.4% yield. However, if you have a long time horizon, Coca-Cola's yield comes with something that a Treasury doesn't: Growth.
Coca-Cola is one of the world's largest consumer staples companies. It has an incredible history of growth, highlighted by 64 annual dividend increases. That makes the company a Dividend King. But think about that for a second, you can collect 30 years of the same income from a bond or 30 years of increasing income from Coca-Cola. Since the start of 1996, roughly 30 years ago, the company's dividend has increased by nearly 750%. That dividend growth was driven by the company's growth, which also led to an over 300% increase in the stock price. If you hold a bond to maturity, all you get back is the principal.
#coca


9 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Mortgage rates have been slowly rising over the past seven months, from just below 6% before the Middle East conflict began in late February to near 7% this week (with some surveys reporting rates already above 7%).
However, it's still possible to lock in a rate below the national average. Borrowers need to shop diligently and deploy one or more of the following strategies to earn the lowest mortgage rate possible in the 2026 housing market.
See the average mortgage rate in your state.
Analysis by Yahoo Finance of nearly 5,000 mortgage lenders reporting 2026 loan information under the Home Mortgage Disclosure Act reveals the surprising truth: the lenders offering the absolute lowest mortgage rates. In 2026, the largest national banks, credit unions, and homebuilders that finance their own construction offered the most favorable home loan rates to the widest variety of borrowers.
#rates #finance #reporting
Mortgage rates have been slowly rising over the past seven months, from just below 6% before the Middle East conflict began in late February to near 7% this week (with some surveys reporting rates already above 7%).
However, it's still possible to lock in a rate below the national average. Borrowers need to shop diligently and deploy one or more of the following strategies to earn the lowest mortgage rate possible in the 2026 housing market.
See the average mortgage rate in your state.
Analysis by Yahoo Finance of nearly 5,000 mortgage lenders reporting 2026 loan information under the Home Mortgage Disclosure Act reveals the surprising truth: the lenders offering the absolute lowest mortgage rates. In 2026, the largest national banks, credit unions, and homebuilders that finance their own construction offered the most favorable home loan rates to the widest variety of borrowers.
#rates #finance #reporting


10 days ago
In 2024, Catalent tapped direct lenders for a $4.2 billion term loan to fund its acquisition by Novo Holdings. Last month, the drug manufacturer refinanced with a $4.1 billion syndicated loan that it says will cut its annual interest expense by about $100 million.
Catalent's move captures a shift under way in the leveraged finance market, according to a new report from DC Advisory. Redemptions from retail investors are contributing to the erosion of private credit's pricing advantage, creating an opening for banks to win refinancing business.
The problems in the retail private credit market show few signs of abating.
All the largest direct lenders, such as Ares, Apollo and KKR, also run business development companies, the most common form of credit fund aimed at individual investors, all under varying degrees of pressure to redeem investors.
PitchBook LCD reported on Wednesday that investors in Cliffwater's direct lending interval fund sought to redeem 16% of shares outstanding in the third quarter, down from 17% in the prior quarter.
#billion #private
Catalent's move captures a shift under way in the leveraged finance market, according to a new report from DC Advisory. Redemptions from retail investors are contributing to the erosion of private credit's pricing advantage, creating an opening for banks to win refinancing business.
The problems in the retail private credit market show few signs of abating.
All the largest direct lenders, such as Ares, Apollo and KKR, also run business development companies, the most common form of credit fund aimed at individual investors, all under varying degrees of pressure to redeem investors.
PitchBook LCD reported on Wednesday that investors in Cliffwater's direct lending interval fund sought to redeem 16% of shares outstanding in the third quarter, down from 17% in the prior quarter.
#billion #private


10 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#rates #treasury #look #predictions
Mortgage rates continue to rise as 2026 nears its fourth quarter. What is the outlook for home loan rates in the next five years? Should you wait for mortgage rates to fall significantly before buying or refinancing? Mortgage interest rates are determined by several factors, all of which can give us clues about the future. Let's take a closer look at mortgage rate predictions over the next five years.
Here are the housing market predictions for 2026.
One of the most useful indicators for predicting mortgage rates is the yield on the 10-year U.S. Treasury note. Mortgage rates and 10-year Treasury yields typically move in the same direction, although mortgage rates are usually higher because lenders factor in additional risks. This difference is known as the spread, and we'll account for it when estimating where mortgage rates could go.
With that in mind, the first step is to look at where economists believe Treasury yields are headed over the next five years. To build a forecast, we'll combine expert economic projections with data compiled using artificial intelligence.
#rates #treasury #look #predictions



10 days ago
Intellia Therapeutics, Inc. (NASDAQ:NTLA) entered a five-year senior secured credit facility with OrbiMed for up to $400 million and drew $75 million at closing. The remaining $325 million depends on milestones or further lender agreement.
The facility bears interest at an annual rate equal to the greater of 3% or the one-month Secured Overnight Financing Rate, plus 6.15%, payable monthly. The formula sets a 9.15% minimum. Applying that floor to the initial borrowing produces approximately $6.9 million of article-calculated annual interest before commitment, administrative, undrawn-amount, and facility fees.
The financing arrives as Intellia Therapeutics, Inc. (NASDAQ:NTLA) prepares for a potential U.S. launch of lonvoguran ziclumeran, or lonvo-z, for hereditary angioedema. Intellia Therapeutics, Inc. (NASDAQ:NTLA) held $628.4 million of cash, cash equivalents, and marketable securities as of June 30, but reported a $106.6 million second-quarter net loss.
The staged structure gives Intellia Therapeutics, Inc. (NASDAQ:NTLA) capital without issuing equity at closing and avoids drawing the full amount before milestones that could support additional debt.
A second $75 million tranche becomes available at the option of Intellia Therapeutics, Inc. (NASDAQ:NTLA) if the FDA approves the biologics license application for lonvo-z before a specified date. Three further $40 million tranches depend on lonvo-z revenue targets, while another $30 million requires an equity-fundraising milestone. This links most committed borrowing capacity to regulatory and commercial progress.
#million #therapeutics #ntla #lonvo
The facility bears interest at an annual rate equal to the greater of 3% or the one-month Secured Overnight Financing Rate, plus 6.15%, payable monthly. The formula sets a 9.15% minimum. Applying that floor to the initial borrowing produces approximately $6.9 million of article-calculated annual interest before commitment, administrative, undrawn-amount, and facility fees.
The financing arrives as Intellia Therapeutics, Inc. (NASDAQ:NTLA) prepares for a potential U.S. launch of lonvoguran ziclumeran, or lonvo-z, for hereditary angioedema. Intellia Therapeutics, Inc. (NASDAQ:NTLA) held $628.4 million of cash, cash equivalents, and marketable securities as of June 30, but reported a $106.6 million second-quarter net loss.
The staged structure gives Intellia Therapeutics, Inc. (NASDAQ:NTLA) capital without issuing equity at closing and avoids drawing the full amount before milestones that could support additional debt.
A second $75 million tranche becomes available at the option of Intellia Therapeutics, Inc. (NASDAQ:NTLA) if the FDA approves the biologics license application for lonvo-z before a specified date. Three further $40 million tranches depend on lonvo-z revenue targets, while another $30 million requires an equity-fundraising milestone. This links most committed borrowing capacity to regulatory and commercial progress.
#million #therapeutics #ntla #lonvo


