

2 months ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services


2 months ago
Walmart Inc. (NASDAQ:WMT) is expanding its restaurant-delivery business through a partnership with Papa John's, allowing customers in select U.S. markets to order pizzas, sides, and desserts through Walmart's app and website. The service is expected to launch this fall before expanding to thousands of participating Papa John's locations nationwide. Customers will be able to order restaurant food either separately or alongside Walmart groceries and household products, with Walmart's delivery network handling fulfillment.
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment


2 months ago
Founded in 1977 and headquartered in South Korea, LX Pantos has grown into a global logistics provider spanning freight forwarding, contract logistics, e-commerce fulfillment, last-mile delivery and installation, and supply chain management consulting. The company now operates more than 380 locations worldwide with a workforce of approximately 8,500 employees, moving more than 1.6 million TEUs of ocean freight and over 120,000 tons of air freight annually. In 2025, LX Pantos recorded revenue of approximately $5.85 billion.
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics



2 months ago
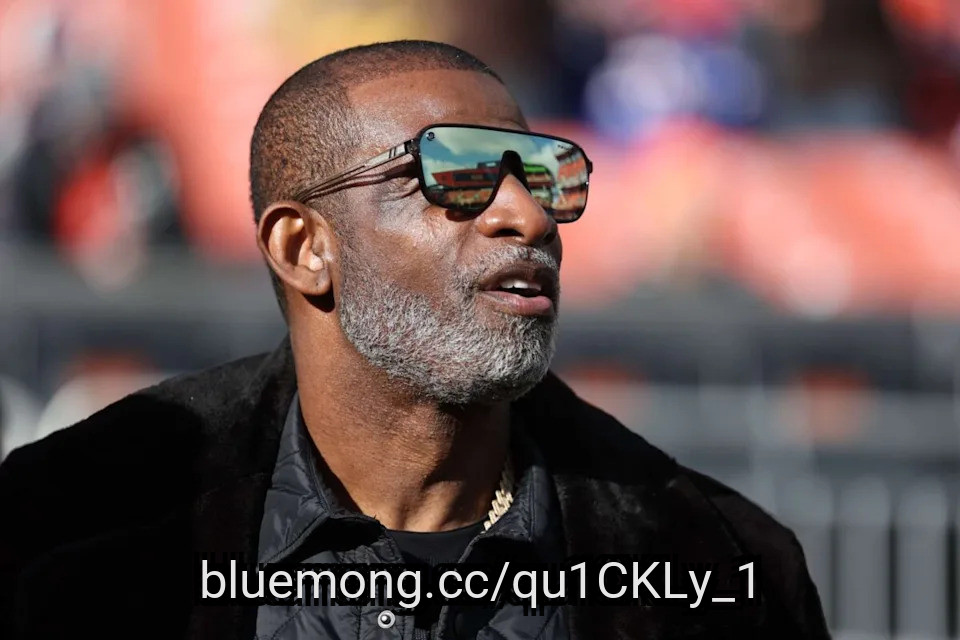
Deion Sanders is still remembered as one of the most iconic players in the NFL's history. His accomplishments while playing for 14 seasons in the league are still remarkable, being an 8-time Pro Bowler, 6-time first-team All-Pro, and the 1994 AP Defensive Player of the Year.
The Pro Football Hall of Famer is also a two-time Super Bowl champion, one with the San Francisco 49ers and the other with the Dallas Cowboys. However, those trophies meant nothing at one point to him.
Sanders won his two Super Bowl trophies back-to-back, with the 49ers in the 1994 season and the following season with the Cowboys. He achieved both of them at the age of 27 and 28, respectively, and became a living icon already at the time. Aside from the Super Bowls, he has also achieved much more and has also played in the Major League Baseball.
Deion Sanders & GF Karrueche Tran Soak Up Golden Hour Caribbean Vibes
(Credit: Scott Galvin-Imagn Images)
He recently admitted that these victories eventually did not provide him with any personal fulfillment and made him feel empty. In a recent interview on Hallow's Coffee with Jeff with Jeff Cavins, Sanders explained, "I thought people, places, and things would give me that, even the accolades. Well, they didn't. I received every darn accolade you could think of. On the journey to go on to the Super Bowl and win, and everybody went out and partied that night. And I couldn't get myself to do it. I didn't have peace."
#time #bowl #league
The Pro Football Hall of Famer is also a two-time Super Bowl champion, one with the San Francisco 49ers and the other with the Dallas Cowboys. However, those trophies meant nothing at one point to him.
Sanders won his two Super Bowl trophies back-to-back, with the 49ers in the 1994 season and the following season with the Cowboys. He achieved both of them at the age of 27 and 28, respectively, and became a living icon already at the time. Aside from the Super Bowls, he has also achieved much more and has also played in the Major League Baseball.
Deion Sanders & GF Karrueche Tran Soak Up Golden Hour Caribbean Vibes
(Credit: Scott Galvin-Imagn Images)
He recently admitted that these victories eventually did not provide him with any personal fulfillment and made him feel empty. In a recent interview on Hallow's Coffee with Jeff with Jeff Cavins, Sanders explained, "I thought people, places, and things would give me that, even the accolades. Well, they didn't. I received every darn accolade you could think of. On the journey to go on to the Super Bowl and win, and everybody went out and partied that night. And I couldn't get myself to do it. I didn't have peace."
#time #bowl #league

2 months ago
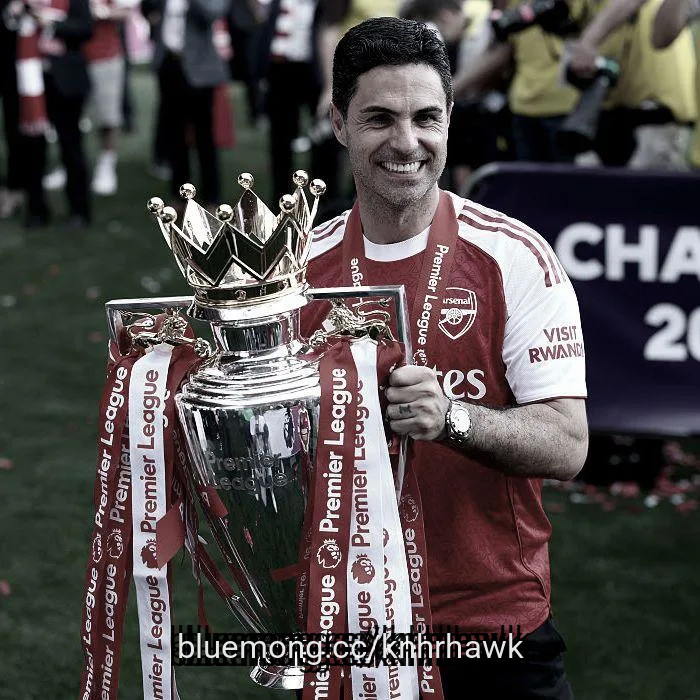
Going into the summer transfer window as Premier League champions, hope sprang eternal for ***** nal.
An opportunity to capitalise, encouraged by a sense at Emirates Stadium that their competitors were in transition because of managerial instability.
If ever there was a moment to strike in recruitment, this was it.
The plans were ambitious: a shortlist with more than 20 players on it. They were targets at Real Madrid and Atletico Madrid, even at Chelsea and Tottenham.
But as the window shut on Tuesday night, you could not escape the sense of unfulfillment - certainly from a section of supporters.
#emirates
An opportunity to capitalise, encouraged by a sense at Emirates Stadium that their competitors were in transition because of managerial instability.
If ever there was a moment to strike in recruitment, this was it.
The plans were ambitious: a shortlist with more than 20 players on it. They were targets at Real Madrid and Atletico Madrid, even at Chelsea and Tottenham.
But as the window shut on Tuesday night, you could not escape the sense of unfulfillment - certainly from a section of supporters.
#emirates


2 months ago
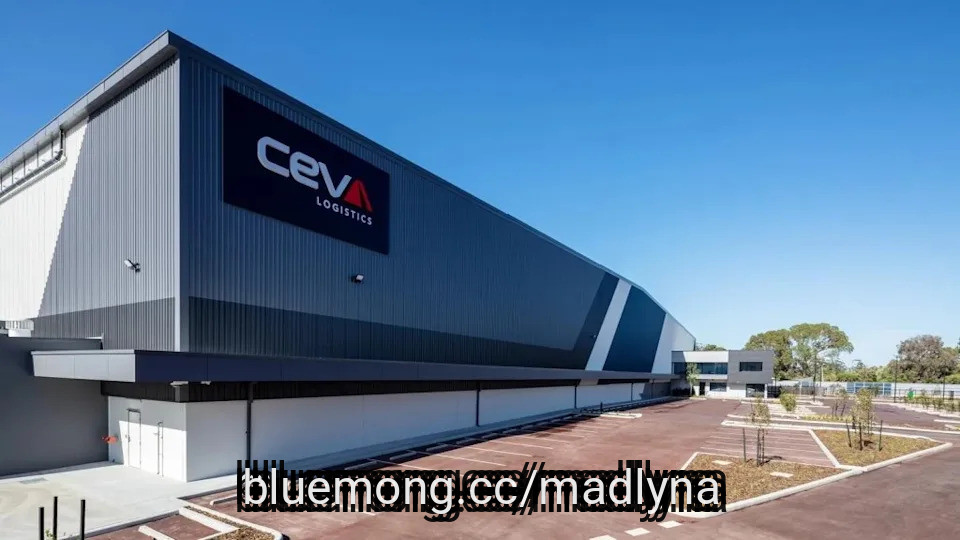
A former employee has filed a class action lawsuit against Ceva Logistics, alleging the freight giant failed to protect highly sensitive personal information stolen during a recent cyberattack that impacted operations in Europe.
Hackers gained access to Ceva Logistics systems and data in late July, which disrupted operations at eight warehouses that provide store replenishment and e-commerce fulfillment for retailers in the Netherlands and other European countries, as FreightWaves reported. The legal action suggests that customers were not the only ones affected by the data breach.
Why It Matters: France-based Ceva is one of the largest third-party logistics providers, with more than 1,000 warehouses worldwide. Last year the company generated $18.3 billion in revenue.
Kevin Krupa, a former employee, sued Ceva Logistics late last month in U.S. District Court for the Southern District of Texas, in Houston, where Ceva's U.S. headquarters is located.
The complaint alleges that the personal information of employees, including bank account details and social security numbers, was stolen during the cyber intrusion, which never would have happened had the company taken appropriate precautions following a similar incident a year earlier.
#ceva
Hackers gained access to Ceva Logistics systems and data in late July, which disrupted operations at eight warehouses that provide store replenishment and e-commerce fulfillment for retailers in the Netherlands and other European countries, as FreightWaves reported. The legal action suggests that customers were not the only ones affected by the data breach.
Why It Matters: France-based Ceva is one of the largest third-party logistics providers, with more than 1,000 warehouses worldwide. Last year the company generated $18.3 billion in revenue.
Kevin Krupa, a former employee, sued Ceva Logistics late last month in U.S. District Court for the Southern District of Texas, in Houston, where Ceva's U.S. headquarters is located.
The complaint alleges that the personal information of employees, including bank account details and social security numbers, was stolen during the cyber intrusion, which never would have happened had the company taken appropriate precautions following a similar incident a year earlier.
#ceva
2 months ago
One problem in the artificial intelligence industry that just doesn't seem to be going away: Companies still aren't saying new AI tools are making them more profitable.
"While it's easy to find anecdotal examples of AI-driven margin gains or cost-cuts, economically meaningful implementation seems uneven at best," Barclays strategist Venu Krishna wrote in a note on Thursday.
"While nearly half of all companies talked about AI [on recent earnings calls], only 12% were willing to quantify AI-related value capture," Krishna added. "Of those, tech, financials, and healthcare companies were over-indexed at 68% of the total. The average reported gain in operational efficiencies seems impressive at first blush at 56%, but these ******* sments have not meaningfully changed over the last three years of LLM advances, calling their precision into question."
Krishna noted that Meta's (META) AI tools delivered an 8.3% increase in Facebook ad clicks and a 15.7% uplift in conversions.
Online pet care retailer Chewy (CHWY) is targeting $50 million in cost savings in fiscal year 2027 through AI deployed across fulfillment and customer service.
#cost #barclays
"While it's easy to find anecdotal examples of AI-driven margin gains or cost-cuts, economically meaningful implementation seems uneven at best," Barclays strategist Venu Krishna wrote in a note on Thursday.
"While nearly half of all companies talked about AI [on recent earnings calls], only 12% were willing to quantify AI-related value capture," Krishna added. "Of those, tech, financials, and healthcare companies were over-indexed at 68% of the total. The average reported gain in operational efficiencies seems impressive at first blush at 56%, but these ******* sments have not meaningfully changed over the last three years of LLM advances, calling their precision into question."
Krishna noted that Meta's (META) AI tools delivered an 8.3% increase in Facebook ad clicks and a 15.7% uplift in conversions.
Online pet care retailer Chewy (CHWY) is targeting $50 million in cost savings in fiscal year 2027 through AI deployed across fulfillment and customer service.
#cost #barclays


2 months ago
Symbotic (NASDAQ: SYM), a developer of autonomous warehouse robots, went public through a merger with a special purpose acquisition company (SPAC) on June 8, 2022. It started trading at $10.51 per share, closed at a record high of $87.30 on Nov. 26, 2025, but now trades at $38.
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue
Symbotic is still a divisive stock. The bulls are impressed by its robust revenue growth, its expanding margins, and its growing backlog -- which reached $22.5 billion in its latest quarter. But the bears will warn you that it's overly dependent on Walmart (NASDAQ: WMT) and that many investors overlook that customer concentration risk.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Walmart is Symbotic's largest customer and one of its top investors. The world's largest retailer accounted for 85% of its revenue in fiscal 2025 (which ended last September), driven by a long-term contract to automate all of its U.S. regional distribution centers through 2037.
Symbotic also acquired Walmart's own robotics division in early 2025, and the two companies have been co-developing automated micro-fulfillment systems for its brick-and-mortar stores. In other words, Symbotic wouldn't exist in its current form without Walmart's support.
#NVIDIA #walmart #flashing #revenue

2 months ago
Descartes Systems Group announced Tuesday that it has acquired Extensiv, a warehouse management and fulfillment tech provider, for $120 million. The deal follows Descartes' $100 million acquisition of Tai last week.
The acquisition was funded with cash on hand.
California-based Extensiv helps 3PLs with inventory management and order fulfillment. It uses AI tools to leverage its omnichannel data and enhance decision making for warehouse operators.
"3PLs are under constant pressure to fulfill faster, scale flexibly, and support the evolving needs of modern brands," said Mikel Richardson, general manager of ecommerce operations at Descartes. … "Extensiv strengthens that position by adding more participants, more contextually rich operational data and fulfillment intelligence to the Descartes Global Logistics Network."
Like the addition of Tai, a TMS provider to freight brokers, the Extensiv deal deepens Descartes' reach into the logistics services provider market. It also builds out its warehousing, inventory management and ecommerce fulfillment offerings.
#management
The acquisition was funded with cash on hand.
California-based Extensiv helps 3PLs with inventory management and order fulfillment. It uses AI tools to leverage its omnichannel data and enhance decision making for warehouse operators.
"3PLs are under constant pressure to fulfill faster, scale flexibly, and support the evolving needs of modern brands," said Mikel Richardson, general manager of ecommerce operations at Descartes. … "Extensiv strengthens that position by adding more participants, more contextually rich operational data and fulfillment intelligence to the Descartes Global Logistics Network."
Like the addition of Tai, a TMS provider to freight brokers, the Extensiv deal deepens Descartes' reach into the logistics services provider market. It also builds out its warehousing, inventory management and ecommerce fulfillment offerings.
#management

2 months ago
ShipStation, a provider of multicarrier parcel shipping software, is offering e-commerce sellers the ability to also select and coordinate with less-than-truckload operators at pre-negotiated rates in one integrated platform, bringing to life promised benefits from ownership's recent acquisition of freight brokerage Worldwide Express Group.
Few, if any, software-as-a-service companies that connect small-and-midsize merchants with parcel carriers offer a pallet-shipping solution.
"Most of those small companies don't have enough volumes to do full truckload so their first need after parcel shipping tends to be LTL, which creates this natural linkage between LTL freight brokerage and parcel," said Chris Wofford, the founder of Wofford Advisors LLC, a strategic advisory firm for the logistics sector.
In early June, private equity firm Thoma Bravo acquired WWEX Group and merged it with portfolio company Auctane, which provides shipping and fulfillment technology through brands like ShipStation, Stamps.com, Metapack and Packlink. The combined valuation of the companies is $12 billion.
WWEX Group companies include Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics.
#group #Logistics
Few, if any, software-as-a-service companies that connect small-and-midsize merchants with parcel carriers offer a pallet-shipping solution.
"Most of those small companies don't have enough volumes to do full truckload so their first need after parcel shipping tends to be LTL, which creates this natural linkage between LTL freight brokerage and parcel," said Chris Wofford, the founder of Wofford Advisors LLC, a strategic advisory firm for the logistics sector.
In early June, private equity firm Thoma Bravo acquired WWEX Group and merged it with portfolio company Auctane, which provides shipping and fulfillment technology through brands like ShipStation, Stamps.com, Metapack and Packlink. The combined valuation of the companies is $12 billion.
WWEX Group companies include Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics.
#group #Logistics


2 months ago
Descartes Systems Group announced Tuesday that it has acquired Extensiv, a warehouse management and fulfillment tech provider, for $120 million. The deal follows Descartes' $100 million acquisition of Tai last week.
The acquisition was funded with cash on hand.
California-based Extensiv helps 3PLs with inventory management and order fulfillment. It uses AI tools to leverage its omnichannel data and enhance decision making for warehouse operators.
"3PLs are under constant pressure to fulfill faster, scale flexibly, and support the evolving needs of modern brands," said Mikel Richardson, general manager of ecommerce operations at Descartes. … "Extensiv strengthens that position by adding more participants, more contextually rich operational data and fulfillment intelligence to the Descartes Global Logistics Network."
Like the addition of Tai, a TMS provider to freight brokers, the Extensiv deal deepens Descartes' reach into the logistics services provider market. It also builds out its warehousing, inventory management and ecommerce fulfillment offerings.
#descartes #extensiv #provider #deal
The acquisition was funded with cash on hand.
California-based Extensiv helps 3PLs with inventory management and order fulfillment. It uses AI tools to leverage its omnichannel data and enhance decision making for warehouse operators.
"3PLs are under constant pressure to fulfill faster, scale flexibly, and support the evolving needs of modern brands," said Mikel Richardson, general manager of ecommerce operations at Descartes. … "Extensiv strengthens that position by adding more participants, more contextually rich operational data and fulfillment intelligence to the Descartes Global Logistics Network."
Like the addition of Tai, a TMS provider to freight brokers, the Extensiv deal deepens Descartes' reach into the logistics services provider market. It also builds out its warehousing, inventory management and ecommerce fulfillment offerings.
#descartes #extensiv #provider #deal


2 months ago
ShipStation, a provider of multicarrier parcel shipping software, is offering e-commerce sellers the ability to also select and coordinate with less-than-truckload operators at pre-negotiated rates in one integrated platform, bringing to life promised benefits from ownership's recent acquisition of freight brokerage Worldwide Express Group.
Few, if any, software-as-a-service companies that connect small-and-midsize merchants with parcel carriers offer a pallet-shipping solution.
"Most of those small companies don't have enough volumes to do full truckload so their first need after parcel shipping tends to be LTL, which creates this natural linkage between LTL freight brokerage and parcel," said Chris Wofford, the founder of Wofford Advisors LLC, a strategic advisory firm for the logistics sector.
In early June, private equity firm Thoma Bravo acquired WWEX Group and merged it with portfolio company Auctane, which provides shipping and fulfillment technology through brands like ShipStation, Stamps.com, Metapack and Packlink. The combined valuation of the companies is $12 billion.
WWEX Group companies include Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics.
#parcel #Companies #wwex
Few, if any, software-as-a-service companies that connect small-and-midsize merchants with parcel carriers offer a pallet-shipping solution.
"Most of those small companies don't have enough volumes to do full truckload so their first need after parcel shipping tends to be LTL, which creates this natural linkage between LTL freight brokerage and parcel," said Chris Wofford, the founder of Wofford Advisors LLC, a strategic advisory firm for the logistics sector.
In early June, private equity firm Thoma Bravo acquired WWEX Group and merged it with portfolio company Auctane, which provides shipping and fulfillment technology through brands like ShipStation, Stamps.com, Metapack and Packlink. The combined valuation of the companies is $12 billion.
WWEX Group companies include Worldwide Express, GlobalTranz, Unishippers, JEAR Logistics and BLX Logistics.
#parcel #Companies #wwex
2 months ago
The broader retail industry is moving beyond physical stores, with channels including e-Commerce, digital advertising, memberships, and convenience-led fulfillment tagged as critical growth drivers. Furthermore, scale and pricing are important, and consumers continue to emphasize value. Such trends are supporting Walmart Inc. (NASDAQ:WMT).
The company has been benefiting from businesses that are beyond its traditional physical-store retail operations. Its Q2 revenue saw an increase of 5.9% to reach $187.9 billion, with global e-Commerce sales increasing by 23% and advertising revenue jumping by 38%. Membership revenue also rose 17%. This gives the company several higher-growth businesses alongside its core stores.
Investors gave more weight to its profitability. The company's adjusted operating income went up by 17.4% in constant currency, and its gross margin expanded 96 bps. Walmart Inc. (NASDAQ:WMT) reported $19.7 billion in operating cash flow. However, its FCF fell to $5.5 billion.
On the positive side, the company increased its FY 2027 outlook to 4%-5% sales growth and 7%-8.5% adjusted operating income growth. This means that earnings might continue to grow faster than its revenue.
Bernstein ***** yst Zhihan Ma kept a "Buy" rating on Walmart Inc. (NASDAQ:WMT)'s stock and a price objective of $142. As per the ***** yst, the quarter ended at the high end of guidance. The ***** yst opines that softer US comparable sales were mainly aided by pharmacy-related factors rather than deterioration in the company's core business. Also, the ***** yst anticipates the combined Q2-Q3 period to result in approximately mid-single-digit sales growth and around 10% EBIT growth.
#walmart #sales #analyst
The company has been benefiting from businesses that are beyond its traditional physical-store retail operations. Its Q2 revenue saw an increase of 5.9% to reach $187.9 billion, with global e-Commerce sales increasing by 23% and advertising revenue jumping by 38%. Membership revenue also rose 17%. This gives the company several higher-growth businesses alongside its core stores.
Investors gave more weight to its profitability. The company's adjusted operating income went up by 17.4% in constant currency, and its gross margin expanded 96 bps. Walmart Inc. (NASDAQ:WMT) reported $19.7 billion in operating cash flow. However, its FCF fell to $5.5 billion.
On the positive side, the company increased its FY 2027 outlook to 4%-5% sales growth and 7%-8.5% adjusted operating income growth. This means that earnings might continue to grow faster than its revenue.
Bernstein ***** yst Zhihan Ma kept a "Buy" rating on Walmart Inc. (NASDAQ:WMT)'s stock and a price objective of $142. As per the ***** yst, the quarter ended at the high end of guidance. The ***** yst opines that softer US comparable sales were mainly aided by pharmacy-related factors rather than deterioration in the company's core business. Also, the ***** yst anticipates the combined Q2-Q3 period to result in approximately mid-single-digit sales growth and around 10% EBIT growth.
#walmart #sales #analyst


2 months ago
Target Corporation (NYSE:TGT) enters its fiscal second-quarter report with its shares up significantly in 2026. Consensus estimates call for revenue to increase 3.5% to $26.09 billion, adjusted earnings to rise 14% to $2.34 per share, and comparable sales to grow 2.4%. That follows a first quarter in which net sales increased 6.7%, comparable sales rose 5.6%, and traffic grew 4.4%. With the stock's recovery already well advanced, another sales beat may not be enough.
The central test is profitability. Target Corporation (NYSE:TGT) improved its adjusted operating margin to 4.5% from 3.7%, but the adjusted SG&A expense rate increased to 21.9% from 21.7%. Gross margin expanded 80 basis points to 29%. Management expects the full-year operating margin to exceed the 2025 adjusted rate of 4.6% by more than 20 basis points.
Target Corporation (NYSE:TGT) reported higher sales across all six core merchandise categories during the first quarter. Digital comparable sales grew 8.9%, led by more than 27% growth in same-day delivery. Non-merchandise sales increased nearly 25% as Roundel advertising, Target Circle 360 membership revenue and the Target+ marketplace expanded.
That breadth matters because Target Corporation (NYSE:TGT) is not relying on one category or sales channel to restore growth. Higher traffic, positive average transaction growth, and gains across stores and digital channels indicate that the retailer is becoming more relevant to shoppers.
Target Corporation (NYSE:TGT) also showed early margin progress. Supply-chain productivity, lower markdowns, and growth in advertising and other non-merchandise revenue helped expand gross margin despite higher product costs. Sustained traffic growth would give the retailer a larger sales base over which to spread its store and fulfillment expenses.
#target #Margin #quarter
The central test is profitability. Target Corporation (NYSE:TGT) improved its adjusted operating margin to 4.5% from 3.7%, but the adjusted SG&A expense rate increased to 21.9% from 21.7%. Gross margin expanded 80 basis points to 29%. Management expects the full-year operating margin to exceed the 2025 adjusted rate of 4.6% by more than 20 basis points.
Target Corporation (NYSE:TGT) reported higher sales across all six core merchandise categories during the first quarter. Digital comparable sales grew 8.9%, led by more than 27% growth in same-day delivery. Non-merchandise sales increased nearly 25% as Roundel advertising, Target Circle 360 membership revenue and the Target+ marketplace expanded.
That breadth matters because Target Corporation (NYSE:TGT) is not relying on one category or sales channel to restore growth. Higher traffic, positive average transaction growth, and gains across stores and digital channels indicate that the retailer is becoming more relevant to shoppers.
Target Corporation (NYSE:TGT) also showed early margin progress. Supply-chain productivity, lower markdowns, and growth in advertising and other non-merchandise revenue helped expand gross margin despite higher product costs. Sustained traffic growth would give the retailer a larger sales base over which to spread its store and fulfillment expenses.
#target #Margin #quarter

2 months ago
On August 20, ATRenew (NYSE:RERE) reported second-quarter results that beat the high end of its own guidance, with revenue climbing 32.4% year over year to RMB 6.6 billion. Net income jumped 78.6% to RMB 129.1 million, and the company kept buying back shares even as it pushed into new markets overseas. For a business built on other people's used phones, that pairing of faster growth and faster profit is the number worth sitting with.
The engine behind that growth is ATRenew's 1P model, where the company buys, refurbishes, and resells devices itself rather than just running a marketplace. Net product revenue rose 35.9% to RMB 6.2 billion, and the company moved 11.6 million consumer products during the quarter, up from 10.3 million a year earlier. Owning more of that chain is also making each device more profitable. Gross margin on the 1P business rose to 15.7% from 13.2% a year ago, and 1P-to-C retail revenue, the curated resale of phones and computers, grew 92.4% and now makes up 48.8% of product revenue, up from 34.4% last year. Revenue from refurbished products alone grew 87.8%.
All of that flowed to the bottom line: non-GAAP operating income rose 70.1% to RMB 206.3 million, with margin expanding 69 basis points to 3.1%. Newer categories are following the same pattern. Luxury recycling revenue grew 77.3% after the company upgraded select stores into specialized formats, and its B2B marketplace, PJT, grew its registered merchant base to 2.2 million while lifting inspection penetration to 84.4%, up 11.5 percentage points from a year ago. Overseas, the company crossed HKD 120 million in monthly export sales in June and is now building out its FoneSquare and ReRe brands toward hubs in Hong Kong, Dubai, and Miami.
Not every part of the business is pulling in the same direction. Net service revenue fell 4.2% to RMB 414.6 million, a decline the company tied to discretionary discounts handed to merchants during its extended June 18 promotional push. Gold recycling revenue fell even harder, down 35%, as gold prices swung lower and the company chose to pass higher payouts to users rather than protect its own take. Costs are climbing too. Fulfillment expenses rose 31.1% to RMB 540 million as the company staffed up its to-door recycling teams during peak demand.
Physical footprint is also shrinking at the edges, with the company trimming its AHS store count to 2,117 locations by closing underperforming sites. And management flagged a timing risk heading into the back half of the year, noting that expectations around Apple's next iPhone lineup could push device volume into the fourth quarter and early next year rather than this one. Guidance itself points to a slower pace ahead. ATRenew expects third-quarter revenue of RMB 6.3 billion to RMB 6.4 billion, growth of 23.1% to 25.1%, a clear step down from the 32.4% posted this quarter.
#billion #business
The engine behind that growth is ATRenew's 1P model, where the company buys, refurbishes, and resells devices itself rather than just running a marketplace. Net product revenue rose 35.9% to RMB 6.2 billion, and the company moved 11.6 million consumer products during the quarter, up from 10.3 million a year earlier. Owning more of that chain is also making each device more profitable. Gross margin on the 1P business rose to 15.7% from 13.2% a year ago, and 1P-to-C retail revenue, the curated resale of phones and computers, grew 92.4% and now makes up 48.8% of product revenue, up from 34.4% last year. Revenue from refurbished products alone grew 87.8%.
All of that flowed to the bottom line: non-GAAP operating income rose 70.1% to RMB 206.3 million, with margin expanding 69 basis points to 3.1%. Newer categories are following the same pattern. Luxury recycling revenue grew 77.3% after the company upgraded select stores into specialized formats, and its B2B marketplace, PJT, grew its registered merchant base to 2.2 million while lifting inspection penetration to 84.4%, up 11.5 percentage points from a year ago. Overseas, the company crossed HKD 120 million in monthly export sales in June and is now building out its FoneSquare and ReRe brands toward hubs in Hong Kong, Dubai, and Miami.
Not every part of the business is pulling in the same direction. Net service revenue fell 4.2% to RMB 414.6 million, a decline the company tied to discretionary discounts handed to merchants during its extended June 18 promotional push. Gold recycling revenue fell even harder, down 35%, as gold prices swung lower and the company chose to pass higher payouts to users rather than protect its own take. Costs are climbing too. Fulfillment expenses rose 31.1% to RMB 540 million as the company staffed up its to-door recycling teams during peak demand.
Physical footprint is also shrinking at the edges, with the company trimming its AHS store count to 2,117 locations by closing underperforming sites. And management flagged a timing risk heading into the back half of the year, noting that expectations around Apple's next iPhone lineup could push device volume into the fourth quarter and early next year rather than this one. Guidance itself points to a slower pace ahead. ATRenew expects third-quarter revenue of RMB 6.3 billion to RMB 6.4 billion, growth of 23.1% to 25.1%, a clear step down from the 32.4% posted this quarter.
#billion #business


2 months ago
Citizens' **** yst Andrew Boone recently reiterated a Market Outperform rating on Amazon.com, Inc. (NASDAQ:AMZN) with a $315 price target. The firm noted that Amazon trades at 23.8x 2027E GAAP EPS and 10.9x 2027E EBITDA. However, it believes that the stock deserves to trade at a higher valuation.
Citizens believes that two factors support a higher valuation for Amazon.com, Inc. (NASDAQ:AMZN), one of which is its cloud computing leadership through Amazon Web Services. AWS is currently the undisputed leader in cloud infrastructure with an estimated 28% of market share.
In the second quarter of 2026, AWS net sales grew 37% year-over-year to $42.2 billion. Operating income for the segment grew to $16.6 billion from $10.2 billion a year ago. This means that AWS accounted for an estimated 60% of Amazon's operating income while contributing one-fifth of revenue.
AWS is now essentially a "$169 billion annualized revenue run rate business," with the company now building a narrative around their custom silicon. The business has a chips revenue run rate "over $25 billion," and an AI-specific revenue run rate also "over $25 billion."
On the retail side, North America segment sales rose 16% to $$116.2 billion. Operating income climbed to $9.1 billion, supported by the company's efficient fulfillment network.
#revenue #year #rate #NASDAQ
Citizens believes that two factors support a higher valuation for Amazon.com, Inc. (NASDAQ:AMZN), one of which is its cloud computing leadership through Amazon Web Services. AWS is currently the undisputed leader in cloud infrastructure with an estimated 28% of market share.
In the second quarter of 2026, AWS net sales grew 37% year-over-year to $42.2 billion. Operating income for the segment grew to $16.6 billion from $10.2 billion a year ago. This means that AWS accounted for an estimated 60% of Amazon's operating income while contributing one-fifth of revenue.
AWS is now essentially a "$169 billion annualized revenue run rate business," with the company now building a narrative around their custom silicon. The business has a chips revenue run rate "over $25 billion," and an AI-specific revenue run rate also "over $25 billion."
On the retail side, North America segment sales rose 16% to $$116.2 billion. Operating income climbed to $9.1 billion, supported by the company's efficient fulfillment network.
#revenue #year #rate #NASDAQ


2 months ago
On August 13, 2026, YETI Holdings (NYSE:YETI) reported second-quarter fiscal 2026 results that showed broad-based top-line expansion and operational progress. Sales climbed 9% year over year to roughly $484 million, with growth spread across every category, channel and region the company reports. CEO Matthew Reintjes told investors the quarter reinforced the company's structural breadth and scalability, even as YETI navigates an uneven consumer backdrop and ongoing macro uncertainty.
Coolers & Equipment led the way, growing 16% to $232 million as newer lines like the Daytrip insulated bags and Camino totes gained traction alongside cases and storage. Management pointed to smaller hard coolers such as the Roadie 15 and the newly launched Roadie 8 as early bright spots, evidence that YETI's product platforms extend well beyond its original hard cooler business. International sales jumped 19% to $93 million, with Europe, Australia and ******* an all posting strong growth. ******* an, in its first full year as a direct business, delivered significant growth in the quarter, and YETI expects to be live in 11 international markets by the end of 2026, up from four at the same time last year. Wholesale sales rose 10% to $218 million, and tracked channel inventory ended the quarter lower, a sign management reads as healthy, demand-driven sell-through rather than a pullback.
Gross margin expanded 170 basis points to 59.5%, with 110 basis points of that coming from pricing discipline and product cost management rather than one-time items. On the back of that performance, YETI raised its full-year gross margin expectation to 57.5%–58.0% (and raised its full-year adjusted EPS guidance range to $2.94–$3.00, up from $2.83–$2.89), while continuing a buyback program that has repurchased more than $600 million in stock since 2024.
Gross margin expansion was offset by operating expense growth during the period. Adjusted SG&A grew 19% to $220 million and deleveraged 410 basis points to 45.4% of sales, driven largely by the brand campaign shifting into the second quarter from the fourth quarter of last year, a higher short-term incentive compensation accrual, and rising distribution and fulfillment costs. That expense growth outpaced the gross margin gains, and adjusted operating income actually fell 7% to $68 million, while adjusted net income dropped 8% to $51 million. Cash on the balance sheet shrank sharply, ending the quarter at approximately $60 million versus $270 million a year earlier, while total debt climbed to $102 million from $76 million.
#quarter
Coolers & Equipment led the way, growing 16% to $232 million as newer lines like the Daytrip insulated bags and Camino totes gained traction alongside cases and storage. Management pointed to smaller hard coolers such as the Roadie 15 and the newly launched Roadie 8 as early bright spots, evidence that YETI's product platforms extend well beyond its original hard cooler business. International sales jumped 19% to $93 million, with Europe, Australia and ******* an all posting strong growth. ******* an, in its first full year as a direct business, delivered significant growth in the quarter, and YETI expects to be live in 11 international markets by the end of 2026, up from four at the same time last year. Wholesale sales rose 10% to $218 million, and tracked channel inventory ended the quarter lower, a sign management reads as healthy, demand-driven sell-through rather than a pullback.
Gross margin expanded 170 basis points to 59.5%, with 110 basis points of that coming from pricing discipline and product cost management rather than one-time items. On the back of that performance, YETI raised its full-year gross margin expectation to 57.5%–58.0% (and raised its full-year adjusted EPS guidance range to $2.94–$3.00, up from $2.83–$2.89), while continuing a buyback program that has repurchased more than $600 million in stock since 2024.
Gross margin expansion was offset by operating expense growth during the period. Adjusted SG&A grew 19% to $220 million and deleveraged 410 basis points to 45.4% of sales, driven largely by the brand campaign shifting into the second quarter from the fourth quarter of last year, a higher short-term incentive compensation accrual, and rising distribution and fulfillment costs. That expense growth outpaced the gross margin gains, and adjusted operating income actually fell 7% to $68 million, while adjusted net income dropped 8% to $51 million. Cash on the balance sheet shrank sharply, ending the quarter at approximately $60 million versus $270 million a year earlier, while total debt climbed to $102 million from $76 million.
#quarter


3 months ago
Layoffs and facility closures are mounting across U.S. freight, distribution and manufacturing networks, with more than 7,000 jobs affected by recently announced workforce reductions involving companies ranging from Tyson Foods and FedEx to Ryder, CJ Logistics America and Daimler Truck.
The largest reduction comes from Tyson Foods, which is reportedly eliminating more than 3,000 jobs as it closes facilities in Joslin, Illinois, and Eagle Mountain, Utah. The food giant said it is shifting beef operations toward Nebraska, Kansas and Texas amid what it described as a historic cattle shortage.
Wholesale distributor Essendant also warned of sweeping cuts affecting more than 1,200 employees across six states as the company attempts to secure additional capital or find a buyer.
WARN notices show approximately 644 jobs affected in Illinois, 192 in Georgia, 150 in Pennsylvania, 136 in Texas, 103 in California and 53 in Arizona. The reductions are scheduled to begin Oct. 3. The company has warned that it could cease operations and liquidate if financing or a sale cannot be secured.
The announcements are part of a broader wave of restructuring hitting transportation, warehousing, fulfillment and manufacturing operations.
#Jobs #operations
The largest reduction comes from Tyson Foods, which is reportedly eliminating more than 3,000 jobs as it closes facilities in Joslin, Illinois, and Eagle Mountain, Utah. The food giant said it is shifting beef operations toward Nebraska, Kansas and Texas amid what it described as a historic cattle shortage.
Wholesale distributor Essendant also warned of sweeping cuts affecting more than 1,200 employees across six states as the company attempts to secure additional capital or find a buyer.
WARN notices show approximately 644 jobs affected in Illinois, 192 in Georgia, 150 in Pennsylvania, 136 in Texas, 103 in California and 53 in Arizona. The reductions are scheduled to begin Oct. 3. The company has warned that it could cease operations and liquidate if financing or a sale cannot be secured.
The announcements are part of a broader wave of restructuring hitting transportation, warehousing, fulfillment and manufacturing operations.
#Jobs #operations


3 months ago
Interested in Full Truck Alliance Co. Ltd. Sponsored ADR? Here are five stocks we like better.
Full Truck Alliance reported solid Q2 growth: Revenue rose 4.4% to RMB 3.38 billion, while net income increased 6.3% to RMB 1.35 billion. Fulfilled orders climbed 12.7% to 68.5 million and shipper monthly active users rose 12.8% to 3.57 million.
Platform efficiency reached record levels: The fulfillment rate increased to 47%, up 6.3 percentage points year over year, while the median order-to-capacity matching time fell to five minutes. The company attributed the gains to improved freight classification, capacity allocation and matching efficiency.
Monetization and cash generation strengthened: Transaction service revenue grew 33.1% to RMB 1.77 billion as commission penetration reached 94.7%. Operating cash flow totaled RMB 2.15 billion, and management plans to continue quarterly dividends while investing in overseas operations, less-than-truckload services, autonomous delivery and AI.
Full Truck Alliance (NYSE:YMM) reported second-quarter 2026 revenue growth of 4.4% as transaction services expanded and platform fulfillment metrics reached record levels, despite what management described as a challenging market environment.
#billion #transaction #five #reported
Full Truck Alliance reported solid Q2 growth: Revenue rose 4.4% to RMB 3.38 billion, while net income increased 6.3% to RMB 1.35 billion. Fulfilled orders climbed 12.7% to 68.5 million and shipper monthly active users rose 12.8% to 3.57 million.
Platform efficiency reached record levels: The fulfillment rate increased to 47%, up 6.3 percentage points year over year, while the median order-to-capacity matching time fell to five minutes. The company attributed the gains to improved freight classification, capacity allocation and matching efficiency.
Monetization and cash generation strengthened: Transaction service revenue grew 33.1% to RMB 1.77 billion as commission penetration reached 94.7%. Operating cash flow totaled RMB 2.15 billion, and management plans to continue quarterly dividends while investing in overseas operations, less-than-truckload services, autonomous delivery and AI.
Full Truck Alliance (NYSE:YMM) reported second-quarter 2026 revenue growth of 4.4% as transaction services expanded and platform fulfillment metrics reached record levels, despite what management described as a challenging market environment.
#billion #transaction #five #reported


3 months ago
Layoffs and facility closures are mounting across U.S. freight, distribution and manufacturing networks, with more than 7,000 jobs affected by recently announced workforce reductions involving companies ranging from Tyson Foods and FedEx to Ryder, CJ Logistics America and Daimler Truck.
The largest reduction comes from Tyson Foods, which is reportedly eliminating more than 3,000 jobs as it closes facilities in Joslin, Illinois, and Eagle Mountain, Utah. The food giant said it is shifting beef operations toward Nebraska, Kansas and Texas amid what it described as a historic cattle shortage.
Wholesale distributor Essendant also warned of sweeping cuts affecting more than 1,200 employees across six states as the company attempts to secure additional capital or find a buyer.
WARN notices show approximately 644 jobs affected in Illinois, 192 in Georgia, 150 in Pennsylvania, 136 in Texas, 103 in California and 53 in Arizona. The reductions are scheduled to begin Oct. 3. The company has warned that it could cease operations and liquidate if financing or a sale cannot be secured.
The announcements are part of a broader wave of restructuring hitting transportation, warehousing, fulfillment and manufacturing operations.
#affected
The largest reduction comes from Tyson Foods, which is reportedly eliminating more than 3,000 jobs as it closes facilities in Joslin, Illinois, and Eagle Mountain, Utah. The food giant said it is shifting beef operations toward Nebraska, Kansas and Texas amid what it described as a historic cattle shortage.
Wholesale distributor Essendant also warned of sweeping cuts affecting more than 1,200 employees across six states as the company attempts to secure additional capital or find a buyer.
WARN notices show approximately 644 jobs affected in Illinois, 192 in Georgia, 150 in Pennsylvania, 136 in Texas, 103 in California and 53 in Arizona. The reductions are scheduled to begin Oct. 3. The company has warned that it could cease operations and liquidate if financing or a sale cannot be secured.
The announcements are part of a broader wave of restructuring hitting transportation, warehousing, fulfillment and manufacturing operations.
#affected

3 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed the revenue decline to significant headwinds in traditional advertising monetization, despite stable audience consumption levels.
The company is executing a 'remodeling the house while living in it' strategy, incurring higher operating expenses to build out digital infrastructure and sales leadership.
A strategic shift toward a 'blended digital strategy'—combining radio with search, SEO, and social—drove a 76.4% increase in blended digital revenue for the first half of the year.
Management emphasized a return to in-house search tools and specialized digital fulfillment teams to improve speed-to-market and campaign optimization.
#revenue #strategy
Management attributed the revenue decline to significant headwinds in traditional advertising monetization, despite stable audience consumption levels.
The company is executing a 'remodeling the house while living in it' strategy, incurring higher operating expenses to build out digital infrastructure and sales leadership.
A strategic shift toward a 'blended digital strategy'—combining radio with search, SEO, and social—drove a 76.4% increase in blended digital revenue for the first half of the year.
Management emphasized a return to in-house search tools and specialized digital fulfillment teams to improve speed-to-market and campaign optimization.
#revenue #strategy


3 months ago
To think back four years ago, when I first decided I wanted to pursue a career in journalism — and sports journalism, for that matter — I could not have predicted the fulfillment and opportunities it has given me.
Naturally, sports have been a big part of my life from the beginning. My first word as a baby was "so" — not just because it was easy to get me to say, but because it was the name of the former St. Louis Cardinals outfielder So Taguchi, who played for a team that I was raised loving (thanks Mom and Dad!). I know that said team probably isn't popular around the Lafayette area, but please give me some grace.
At the start, my love for sports was on the field, playing baseball, soccer and basketball. As I grew up and began high school, I loved it in a different way. I started to keep closer track of sports leagues and debating numerous topics with my friends, which resulted in a couple of moderately successful Instagram accounts that I frequently posted on. But that was just the groundwork for what I ultimately decided to do.
Choosing the Missouri School of Journalism wasn't very difficult. I had always excelled in reading and writing far more than I did in math and science, and I sure wrote a lot. Even in fifth grade, I spent some of my free time typing up mini biographies of a variety of people, from U.S. presidents to Larry Bird to Robert Downey Jr.
I didn't have a whole lot of journalism experience before college, but the stories I wrote for my high school paper showed me I not only could do it, but that I really, really enjoyed it. And with home being only two hours away from one of the most renowned journalism schools in the country, it was a no-brainer for me.
#high
Naturally, sports have been a big part of my life from the beginning. My first word as a baby was "so" — not just because it was easy to get me to say, but because it was the name of the former St. Louis Cardinals outfielder So Taguchi, who played for a team that I was raised loving (thanks Mom and Dad!). I know that said team probably isn't popular around the Lafayette area, but please give me some grace.
At the start, my love for sports was on the field, playing baseball, soccer and basketball. As I grew up and began high school, I loved it in a different way. I started to keep closer track of sports leagues and debating numerous topics with my friends, which resulted in a couple of moderately successful Instagram accounts that I frequently posted on. But that was just the groundwork for what I ultimately decided to do.
Choosing the Missouri School of Journalism wasn't very difficult. I had always excelled in reading and writing far more than I did in math and science, and I sure wrote a lot. Even in fifth grade, I spent some of my free time typing up mini biographies of a variety of people, from U.S. presidents to Larry Bird to Robert Downey Jr.
I didn't have a whole lot of journalism experience before college, but the stories I wrote for my high school paper showed me I not only could do it, but that I really, really enjoyed it. And with home being only two hours away from one of the most renowned journalism schools in the country, it was a no-brainer for me.
#high


3 months ago
Investors often weigh the potential of a retail recovery against the stability of defense contracts. Comparing Advance Auto Parts Inc (NYSE:AAP) and BWX Technologies Inc (NYSE:BWXT) reveals two distinct strategies for long-term growth.
Advance Auto Parts provides essential vehicle components to a wide range of customers, focusing on operational improvements to drive value. BWX Technologies serves critical defense and energy needs through nuclear innovation and government partnerships. While one targets a consumer turnaround, the other capitalizes on specialized industrial demand and expanding government budgets.
Advance Auto Parts sells automotive replacement parts, accessories, and maintenance items to both professional installers and do-it-yourself customers. The company operates thousands of stores across North America and recently expanded an AI-powered delivery partnership with OneRail to improve fulfillment speed. This strategic focus on professional accounts like local garages and service stations is intended to recapture market share in a highly competitive environment.
In FY 2025, revenue reached $8.6 billion, representing a year-over-year decline of approximately 5.4%. Despite the sales dip, the company managed to report a net income of $44 million, resulting in a net margin of approximately 0.5% for the fiscal year. The company is currently implementing a multi-year restructuring plan to optimize its supply chain, reduce costs, and enhance its competitive position in a fragmented market.
As of its January 2026 balance sheet, the debt-to-equity ratio is nearly 2.4x. This metric compares total debt to shareholder equity and indicates a significant reliance on borrowed capital to fund operations. Free cash flow for the year was negative $298 million, defined as cash from operations minus capital expenditures.
#parts #NYSE #technologies #government
Advance Auto Parts provides essential vehicle components to a wide range of customers, focusing on operational improvements to drive value. BWX Technologies serves critical defense and energy needs through nuclear innovation and government partnerships. While one targets a consumer turnaround, the other capitalizes on specialized industrial demand and expanding government budgets.
Advance Auto Parts sells automotive replacement parts, accessories, and maintenance items to both professional installers and do-it-yourself customers. The company operates thousands of stores across North America and recently expanded an AI-powered delivery partnership with OneRail to improve fulfillment speed. This strategic focus on professional accounts like local garages and service stations is intended to recapture market share in a highly competitive environment.
In FY 2025, revenue reached $8.6 billion, representing a year-over-year decline of approximately 5.4%. Despite the sales dip, the company managed to report a net income of $44 million, resulting in a net margin of approximately 0.5% for the fiscal year. The company is currently implementing a multi-year restructuring plan to optimize its supply chain, reduce costs, and enhance its competitive position in a fragmented market.
As of its January 2026 balance sheet, the debt-to-equity ratio is nearly 2.4x. This metric compares total debt to shareholder equity and indicates a significant reliance on borrowed capital to fund operations. Free cash flow for the year was negative $298 million, defined as cash from operations minus capital expenditures.
#parts #NYSE #technologies #government

3 months ago
The Kroger Co. (KR), headquartered in Cincinnati, Ohio, operates supermarkets, multi-department stores, and fulfillment centers. Valued at $35.7 billion by market cap, the company offers meat, seafood, bakery, dairy, frozen, cleaning, kitchen, beverages, health, electronics, toys, vegetables, fruits, beauty, and household products.
Shares of this supermarket chain have underperformed the broader market over the past year. KR has declined 18.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 21.8%. In 2026, KR stock is down 6.8%, compared to the SPX's 11% rise on a YTD basis.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 **** anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#market #cincinnati #valued #index
Shares of this supermarket chain have underperformed the broader market over the past year. KR has declined 18.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 21.8%. In 2026, KR stock is down 6.8%, compared to the SPX's 11% rise on a YTD basis.
General Motors vs. Ford: 1 Auto Giant Is Winning the EV Race
1 **** anese Company Just Waved a Red Flag for Micron Stock. How to Play It Here.
Billionaire Ken Griffin Just Saved Situational Awareness, But Here's What a Rescue Call From Citadel Really Sounds Like — 'I… Heard the Grim Reaper's Scythe'
#market #cincinnati #valued #index


3 months ago
In the cold chain world, every box of frozen food that lands on a doorstep carries a cost decision made days earlier. One example: five pounds of dry ice, or 15? Undershoot and the product arrives thawed. Overshoot and the brand pays to move weight it never needed.
That calculation, repeated across millions of orders, is the business Grip built. The Miami-based cold chain fulfillment company is now handing its national operation to a 40-year veteran of frozen and refrigerated distribution.
Grip said Tuesday that John Hummel will join as president of Grip Fulfillment, leading the company's national fulfillment operations. For the e-commerce brands that rely on Grip to move pet food, prepared meals and grocery orders, the hire brings proven experience. It's a high-stakes industry: a shipping decision that misses by either too few pounds of refrigerant or a single day in transit eats margin or may even destroy the product.
Hummel served as president of Burris Logistics' Custom Distribution division, where he oversaw five frozen and refrigerated distribution centers and eight direct-to-consumer fulfillment facilities. Earlier he was president of United Natural Foods Inc.'s Central/Southeast Region, running eight distribution centers with more than $6 billion in annual sales. Before that he led operations for 31 distribution centers at Reinhart Foodservice as the company grew from $2 billion to $7 billion.
"I've known Juan since his ButcherBox days, and I've followed Grip's journey ever since," Hummel said. "Joining the team to lead its fulfillment operation is an incredible opportunity."
#centers
That calculation, repeated across millions of orders, is the business Grip built. The Miami-based cold chain fulfillment company is now handing its national operation to a 40-year veteran of frozen and refrigerated distribution.
Grip said Tuesday that John Hummel will join as president of Grip Fulfillment, leading the company's national fulfillment operations. For the e-commerce brands that rely on Grip to move pet food, prepared meals and grocery orders, the hire brings proven experience. It's a high-stakes industry: a shipping decision that misses by either too few pounds of refrigerant or a single day in transit eats margin or may even destroy the product.
Hummel served as president of Burris Logistics' Custom Distribution division, where he oversaw five frozen and refrigerated distribution centers and eight direct-to-consumer fulfillment facilities. Earlier he was president of United Natural Foods Inc.'s Central/Southeast Region, running eight distribution centers with more than $6 billion in annual sales. Before that he led operations for 31 distribution centers at Reinhart Foodservice as the company grew from $2 billion to $7 billion.
"I've known Juan since his ButcherBox days, and I've followed Grip's journey ever since," Hummel said. "Joining the team to lead its fulfillment operation is an incredible opportunity."
#centers


3 months ago
GE's numbers were stellar, but ****** ysts on the call wanted to know if the growth was sustainable or a supply-constrained peak.
After a 32% run over the past year, GE Aerospace (GE) just gave bulls everything they wanted, reporting 24% revenue growth and raising its full-year free cash flow guidance to a range of $8.9 billion to $9.2 billion. Yet on its latest call, nearly every sharp question from ****** ysts circled a single, nagging worry: is this as good as it gets? They pressed management to prove that the explosive first-half growth was not just a pull-forward, and that GE's supply chain could actually deliver on its large backlog without margins getting crushed.
The core tension for GE is the gap between its promises and its parts. The company sits on a large commercial services backlog of roughly $170 billion, a powerful signal of future revenue. The problem is that the checks are being written today, but the revenue depends on shipping physical goods in a strained supply chain. The clearest evidence of this operational bottleneck showed up in the company's own metrics: spare parts delinquencies, which track orders delayed by material shortages, grew 20% sequentially in the second quarter. If demand is so resilient, why are the fulfillment issues getting worse, not better?
Management's response was to frame the growth as structural, not a one-time surge. The CEO argued that the aging of the global fleet creates a natural tailwind for higher-value shop visits, and that the company's focus is squarely on execution. The issue, as management put it, is "much more a supply-side challenge than it is demand." That is a confident read on the market, but it also openly confirms that the primary governor on GE's growth is its own ability to get parts out the door.
Even if GE solves its supply issues, the next question is whether that revenue will be profitable. The company is delivering a wave of new engines, particularly the GE9X, which carry lower margins and act as a drag on overall profitability. ****** ysts pushed on when, exactly, the high-margin services business would translate into higher company-wide margins.
#revenue #analysts #parts #call
After a 32% run over the past year, GE Aerospace (GE) just gave bulls everything they wanted, reporting 24% revenue growth and raising its full-year free cash flow guidance to a range of $8.9 billion to $9.2 billion. Yet on its latest call, nearly every sharp question from ****** ysts circled a single, nagging worry: is this as good as it gets? They pressed management to prove that the explosive first-half growth was not just a pull-forward, and that GE's supply chain could actually deliver on its large backlog without margins getting crushed.
The core tension for GE is the gap between its promises and its parts. The company sits on a large commercial services backlog of roughly $170 billion, a powerful signal of future revenue. The problem is that the checks are being written today, but the revenue depends on shipping physical goods in a strained supply chain. The clearest evidence of this operational bottleneck showed up in the company's own metrics: spare parts delinquencies, which track orders delayed by material shortages, grew 20% sequentially in the second quarter. If demand is so resilient, why are the fulfillment issues getting worse, not better?
Management's response was to frame the growth as structural, not a one-time surge. The CEO argued that the aging of the global fleet creates a natural tailwind for higher-value shop visits, and that the company's focus is squarely on execution. The issue, as management put it, is "much more a supply-side challenge than it is demand." That is a confident read on the market, but it also openly confirms that the primary governor on GE's growth is its own ability to get parts out the door.
Even if GE solves its supply issues, the next question is whether that revenue will be profitable. The company is delivering a wave of new engines, particularly the GE9X, which carry lower margins and act as a drag on overall profitability. ****** ysts pushed on when, exactly, the high-margin services business would translate into higher company-wide margins.
#revenue #analysts #parts #call
4 months ago
Amazon is expanding its logistics business, accelerating delivery speeds, and generating stronger profits.
But growth does not mean every Amazon warehouse or job remains safe.
A newly filed Worker Adjustment and Retraining Notification (WARN) notice shows that Amazon plans to shut down another Florida facility, affecting nearly 500 employees.
The closure follows a separate Amazon facility shutdown in the state that affected more than 600 workers.
Together, the two notices show how Amazon is adjusting its enormous fulfillment network even as the company handles more orders, delivers products faster, and opens its logistics infrastructure to outside businesses.
But growth does not mean every Amazon warehouse or job remains safe.
A newly filed Worker Adjustment and Retraining Notification (WARN) notice shows that Amazon plans to shut down another Florida facility, affecting nearly 500 employees.
The closure follows a separate Amazon facility shutdown in the state that affected more than 600 workers.
Together, the two notices show how Amazon is adjusting its enormous fulfillment network even as the company handles more orders, delivers products faster, and opens its logistics infrastructure to outside businesses.

4 months ago
The logistics industry has spent the past few years talking about robots, warehouse automation and artificial intelligence. This year, that talk has turned into real money.
But the way companies are spending it looks different from what it did even two years ago. Instead of chasing fully automated "lights-out" warehouses, most operators are building hybrid systems that mix people, robots and software in ways they can adjust as conditions change.
More from WWD
Maersk, Lululemon Go Big on New Fulfillment Hubs
UPS, FedEx Top List of Logistics Companies Ranked by Market Cap
But the way companies are spending it looks different from what it did even two years ago. Instead of chasing fully automated "lights-out" warehouses, most operators are building hybrid systems that mix people, robots and software in ways they can adjust as conditions change.
More from WWD
Maersk, Lululemon Go Big on New Fulfillment Hubs
UPS, FedEx Top List of Logistics Companies Ranked by Market Cap

4 months ago
Carvana Co. (NYSE:CVNA) is one of the top stocks to buy according to Whale Rock Capital Management. On June 24, Carvana Co. (NYSE:CVNA) announced plans to bring Inspection and Reconditioning Center (IRC) capabilities to its existing ADESA Sarasota wholesale auction site in Bradenton, Florida.
The move adds extra vehicle reconditioning capacity to Carvana's national network, which means it can inspect more used cars, repair, and prepare them for sale. Carvana stated that because of the new IRC, customers along the Florida Gulf Coast could receive their vehicles as soon as the same day once the new inventory pool is running.
Brian Boyd, Senior Vice President of Inventory at Carvana, stated that he expects the IRC integration to create around 100 new jobs in inspection, reconditioning, and vehicle fulfillment. These positions do not require a college degree and come with full benefits, and that hiring for the roles has already started, Boyd said. Boyd added that the expansion strengthens the company's national network and its customer offering.
ADESA Sarasota has operated as a wholesale auto auction facility for 20 years. It sits on roughly 60 acres with over 3,000 parking ***** es, which gives Carvana enough room to run both the IRC and the existing wholesale auction side without disruption. The company detailed that its proprietary software platform, CARLI, will manage the site's shift into an IRC-enabled facility.
Carvana Co. (NYSE:CVNA) is an e-commerce platform company. It operates an online marketplace for buying and selling used cars in the United States, offering vehicle acquisition, inspection, and reconditioning; online search and shopping; financing; complementary products; and logistics network services.
The move adds extra vehicle reconditioning capacity to Carvana's national network, which means it can inspect more used cars, repair, and prepare them for sale. Carvana stated that because of the new IRC, customers along the Florida Gulf Coast could receive their vehicles as soon as the same day once the new inventory pool is running.
Brian Boyd, Senior Vice President of Inventory at Carvana, stated that he expects the IRC integration to create around 100 new jobs in inspection, reconditioning, and vehicle fulfillment. These positions do not require a college degree and come with full benefits, and that hiring for the roles has already started, Boyd said. Boyd added that the expansion strengthens the company's national network and its customer offering.
ADESA Sarasota has operated as a wholesale auto auction facility for 20 years. It sits on roughly 60 acres with over 3,000 parking ***** es, which gives Carvana enough room to run both the IRC and the existing wholesale auction side without disruption. The company detailed that its proprietary software platform, CARLI, will manage the site's shift into an IRC-enabled facility.
Carvana Co. (NYSE:CVNA) is an e-commerce platform company. It operates an online marketplace for buying and selling used cars in the United States, offering vehicle acquisition, inspection, and reconditioning; online search and shopping; financing; complementary products; and logistics network services.


4 months ago
Chewy, Inc. (NYSE:CHWY) is one of the best stocks to invest in according to Two Sigma Advisors with huge upside potential. On June 23, TD Cowen ***** yst William Kerr named Chewy, Inc. (NYSE:CHWY) as the firm's best small- and mid-cap, or Smid-cap, stock idea for 2026, and at the same time reiterated a Buy rating and a $34 price target on the shares.
Kerr said his firm's endorsement was built around several growth and margin levers it believes Chewy has not yet fully monetized. These include its veterinary care partnership through CVC and Modern Animal, an expanding advertising business, ongoing automation of its fulfillment operations, the Chewy+ membership program, and the integration of generative AI into its platform.
Kerr added that at the time of the note, Chewy was trading at just 6.3 times its enterprise value-to-EBITDA. He described this valuation as attractive given the company's expected EBITDA compound annual growth rate of 15% over the next five years. Put simply, the ***** yst believes the stock is too cheap relative to how fast the business is expected to grow.
The ***** yst also pointed out that as online shopping for pet products continues to grow as a share of total industry sales, Chewy is well positioned to pull customers away from physical competitors. The competitors include local pet stores, traditional retailers, and grocery chains.
The Smid-cap designation places Chewy in a curated list of TD Cowen's top investment picks for companies with a market capitalization generally below $10 billion. This is the firm's annual selection that signals its highest-conviction ideas in that size category.
Kerr said his firm's endorsement was built around several growth and margin levers it believes Chewy has not yet fully monetized. These include its veterinary care partnership through CVC and Modern Animal, an expanding advertising business, ongoing automation of its fulfillment operations, the Chewy+ membership program, and the integration of generative AI into its platform.
Kerr added that at the time of the note, Chewy was trading at just 6.3 times its enterprise value-to-EBITDA. He described this valuation as attractive given the company's expected EBITDA compound annual growth rate of 15% over the next five years. Put simply, the ***** yst believes the stock is too cheap relative to how fast the business is expected to grow.
The ***** yst also pointed out that as online shopping for pet products continues to grow as a share of total industry sales, Chewy is well positioned to pull customers away from physical competitors. The competitors include local pet stores, traditional retailers, and grocery chains.
The Smid-cap designation places Chewy in a curated list of TD Cowen's top investment picks for companies with a market capitalization generally below $10 billion. This is the firm's annual selection that signals its highest-conviction ideas in that size category.

