6 days ago
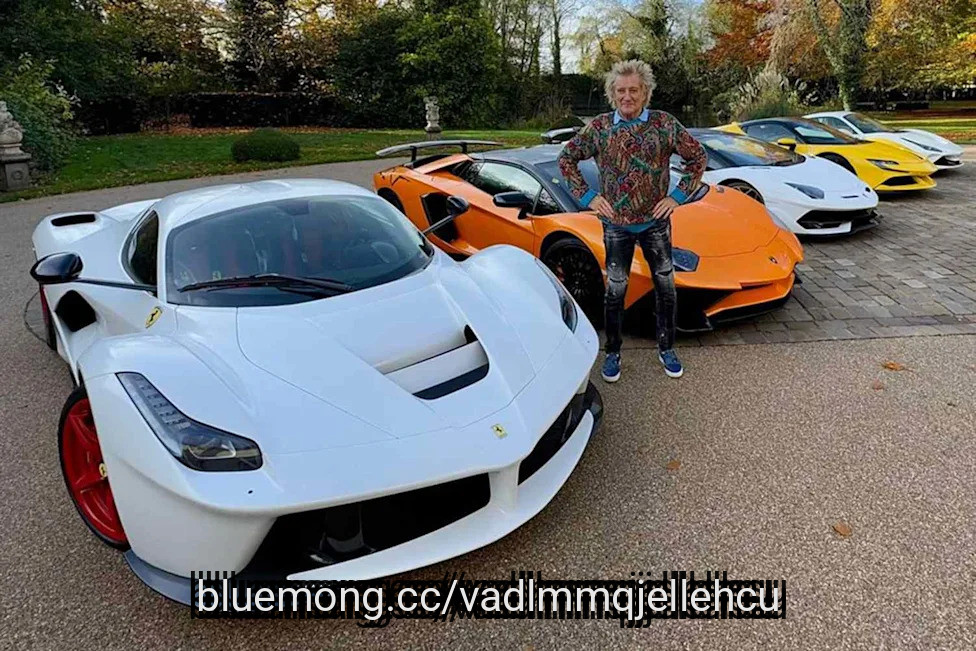
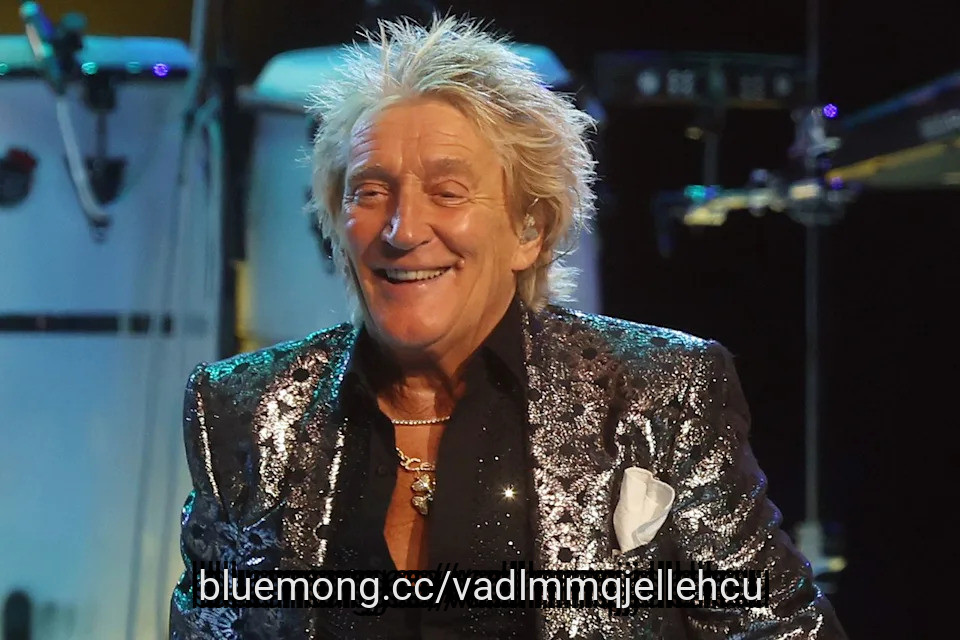
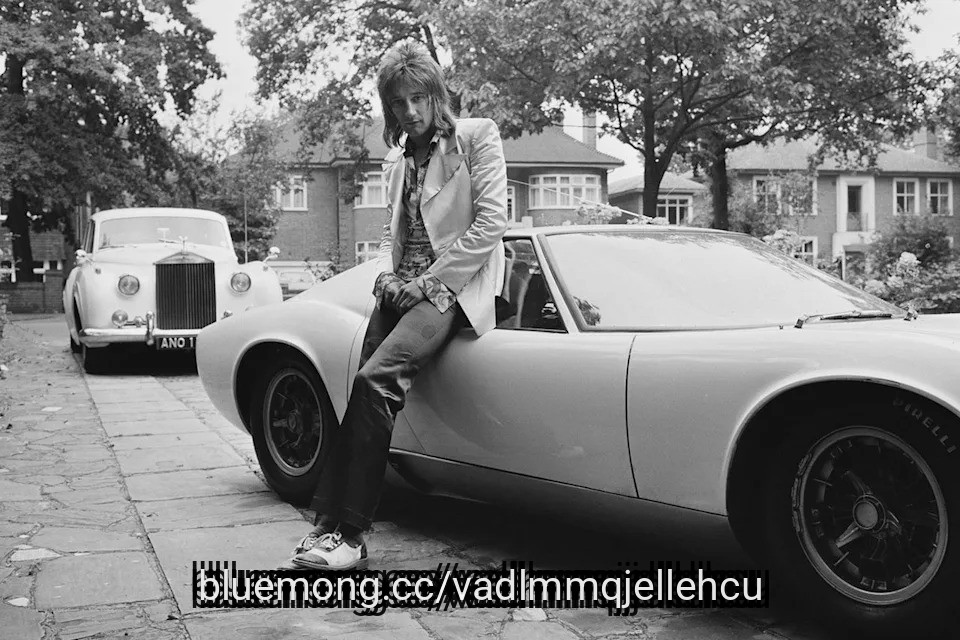
A Lamborghini once owned by Rod Stewart is up for sale with Australian auction house Lloyds
Despite the opening price being less than $1, bids have already climbed above $215,000 USD
Stewart has collected Italian sports cars since the 1970s and calls them works of art
A vintage Lamborghini once owned by legendary rocker Rod Stewart is up for sale, with bids for the classic car starting at less than $1.
The item is being sold via Lloyds Auction House in Australia, and though the price began at just one Australian dollar, which is less than one U.S. dollar, it now stands at over $215,000 (USD) with bidding open through October.
#lloyds #owned
7 days ago
Stocks are doing something that normally should not happen at the same time.
Major indexes keep closing at record highs even as Treasury yields climb to levels not seen in over two decades. That combination has traditionally meant trouble for expensive growth stocks, not fresh records.
Jim Cramer says there is a clear explanation for the disconnect. It comes down to just three companies carrying far more weight than their size alone would suggest.
Also read: Jim Cramer noticed something odd about the stock market
"Mad Money" host Jim Cramer said Nvidia, Microsoft and Meta are propping up the broader market even as surging Treasury yields pressure nearly everything else on Wall Street. "Here, I think there's tremendous distortion caused by some very big winners, namely Nvidia, Microsoft and Meta," he said.
#cramer #meta #market


7 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
A married couple, ages 45 and 43, got spooked during a steep market selloff and sold their entire $600,000 brokerage portfolio. Eight months later, stocks have climbed back, their money is still sitting in a savings account, and each spouse blames the other for pushing the sale.
The argument misses the real problem. They're not stuck because of one bad decision; they're stuck because they never had a plan for what to do when markets fell. Getting back in the right way matters more than figuring out who panicked first.
Don't Miss:
Think Your IRA Can Only Hold Stocks And Funds? Think Again. Here's What A Self-Directed IRA Can Actually Invest In.
#benzinga
7 days ago
WASHINGTON (AP) — Most Federal Reserve officials expect that another interest rate increase will likely be needed this year to combat inflation, according to minutes released Wednesday from the central bank's most recent meeting.
The officials unanimously agreed that inflation was still elevated and had not made much progress toward their 2% target in recent months, the minutes said. The Fed increased its key interest rate at the Sept. 15-16 meeting by a quarter-point to about 3.9%, its first increase in three years.
The increase defied President Donald Trump's repeated calls for the Fed to cut rates and prompted the president to criticize the Fed's rate-setting committee, though he still expressed support for Chairman Kevin Warsh, whom he appointed earlier this year. The rate increase comes as Americans are already struggling with high costs for groceries, gas and housing, and as affordability has taken on a leading role in the upcoming midterm elections, just seven weeks away.
Longer-term interest rates for mortgages and other borrowing have also jumped in the past few months for a range of reasons, including rising government debt, heavy borrowing by tech firms to finance data center construction, climbing oil and gas prices, and signs that growth and inflation remain elevated. The Fed's rate hike has likely played only a limited role in the increase.
Still, key policymakers have said since the meeting that the Fed can take some time to monitor the economy and the impact of last month's rate hike before making another move. Wall Street investors now forecast the Fed will keep its rate unchanged at its next meeting Oct. 28-29, according to futures pricing, and raise it when they meet in December.
#officials



8 days ago
Dividend-paying stocks are taking a beating as surging Treasury yields make bonds a more competitive income source, creating a difficult environment for baby boomers who lean on dividend funds and individual stocks to cover living expenses in retirement.
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury
8 days ago
Jim Cramer has built a career on conviction calls, and few have been more consistent than his faith in Amazon (AMZN). For years, the Mad Money host has treated the retail giant as close to untouchable. A permanent fixture in nearly every portfolio he recommends.
That changed, briefly and publicly, after watching a rival's AI demo live on air. Here is what Cramer actually said, the stock moves that gave his comment real weight, and what it all means for anyone holding either name heading into the rest of the year.
Also read: Jim Cramer noticed something odd about the stock market
Cramer made the comment live on CNBC's Squawk on the Street on September 28, after watching a demonstration of Meta's (META) new AI shopping capability. "I'm an Amazon guy, but maybe I shouldn't be. This seemed impressive," he said, speaking as a shopper describing his own buying habits rather than making a stock call.
The timing gave the remark unusual weight. Meta shares had climbed roughly 24% over the prior month. Amazon fell roughly 8% over the same stretch. Investors were already debating which company was winning the fight for online shoppers before Cramer weighed in.
#cramer #amazon #roughly

8 days ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Social Security is the retirement income lifeline for millions of Americans and garners its share of confusing headlines. From the full retirement age and cost-of-living adjustment to the rules for claiming benefits while still working, here is what's expected to change in 2027.
A common concern among those planning for retirement is an ever-increasing Social Security "full retirement age."
Geoffrey Schmidt, a certified public accountant and founder of Holy Schmidt!, a retirement education resource, told Yahoo Finance that many seniors ****** ume the full retirement age keeps climbing.
"It doesn't. It has finished its long, slow climb to 67. Anyone born in 1960 or later has a full retirement age of exactly 67, and that group reaches it in 2027," Schmidt said. "Under current law, it does not go any higher. So if you've been worried they'll keep moving the goalposts on you, at least on the retirement age, that increase is over."
#Retirement #schmidt #Social #holy


8 days ago
Rising interest rates have the US on a collision course with the need to finally deal with its bloated debt pile, Goldman Sachs warns.
"Persistently higher rates would boost interest expense as a share of GDP — a key gauge of the cash outflows needed to service the debt — and push the debt-to-GDP ratio up to 132% by 2035, 10 percentage points above our baseline, raising the odds that deficit reduction becomes necessary sooner to stabilize the debt," Goldman Sachs strategist Pierfrancesco Mei wrote in a new note on Tuesday.
US Treasury yields have climbed aggressively this year, effectively pushing up the country's debt servicing costs. The benchmark 10-year Treasury yield (^TNX) has surged more than 115 basis points, from around 4.10% late last year to a 24-year high of around 5.28% at present.
Read more: How soaring Treasury yields could hit your finances
This sustained sell-off across the bond market has been fueled by inflation brought on by the US war on Iran, which prompted the Federal Reserve to hike interest rates last month. The economy's resilience in the face of pricing pressures has also contributed to the sell-off.
#points #yields


8 days ago
BarriC's $750 XRP target extrapolates the token's historic 500x rally from 2017, ignoring that it implies a staggering $47 trillion market cap.
At $750, XRP's market cap would dwarf Bitcoin's entire $1.73 trillion valuation 27 times over, requiring capital inflows unprecedented in any market.
XRP must first climb 143% just to reclaim its $3.65 all-time high, making a 500x moonshot an extraordinarily remote possibility.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Crypto ******* yst BarriC recently suggested that XRP (CRYPTO:XRP) could potentially reach $750 if it replicates the extraordinary 500-fold increase seen in 2017 and 2018. This prediction has gained traction in the XRP community on social media platform X, where BarriC has made bold price forecasts for years.
#market #barric #building #definitive


8 days ago
Rising interest rates have the US on a collision course with finally having to deal with its bloated debt pile, warns Goldman Sachs.
"Persistently higher rates would boost interest expense as a share of GDP—a key gauge of the cash outflows needed to service the debt—and push the debt-to-GDP ratio up to 132% by 2035, 10 percentage points above our baseline, raising the odds that deficit reduction becomes necessary sooner to stabilize the debt," said Goldman Sachs strategist Pierfrancesco Mei in a new note on Tuesday.
US Treasury yields have climbed aggressively this year, effectively pushing up the country's debt servicing costs. The benchmark 10-year Treasury yield has surged more than 115 basis points, from around 4.10% late last year to a 24-year high of around 5.28% at present.
This sustained sell-off across the bond market has been fueled by inflation brought on by the US war on Iran, which prompted the Federal Reserve to hike interest rates last month. The economy's resilience in the face of pricing pressures has also contributed to the sell-off.
What's happening in the bond market couldn't come at a worse time for US debt watchers.
#interest


9 days ago
Joe Evermore's 7-year-old son climbed El Capitan in Yosemite National Park, making him the youngest person to ever accomplish such a feat
But in posts celebrating the achievement, many in the comments take issue with the risk involved in taking on such a climb with young children
"There's a lot of bullying that goes on online," Joe tells PEOPLE in an interview
Joe Evermore knows not everyone agrees with his parenting style.
He and his wife, Ann, have made a name for themselves online for sharing their family's impressive climbs — including El Capitan in Yosemite National Park, the largest granite cliff in the world, which their 7-year-old son completed in May, making him the youngest person to ever accomplish such a feat. But in posts celebrating the achievement, many in the comments take issue with the risk involved in taking on such a climb with young children.
#capitan

11 days ago
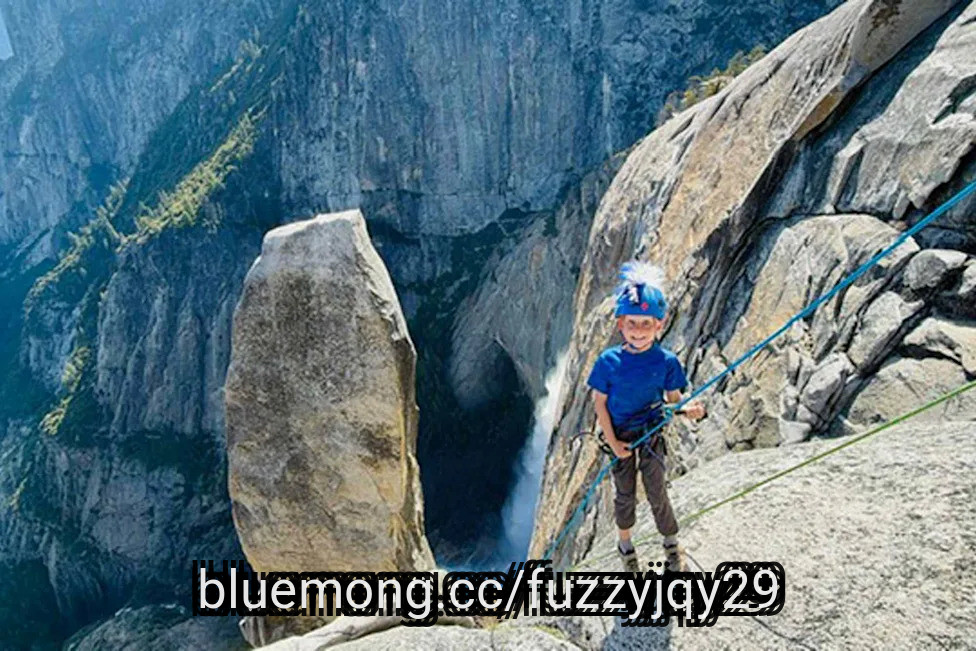
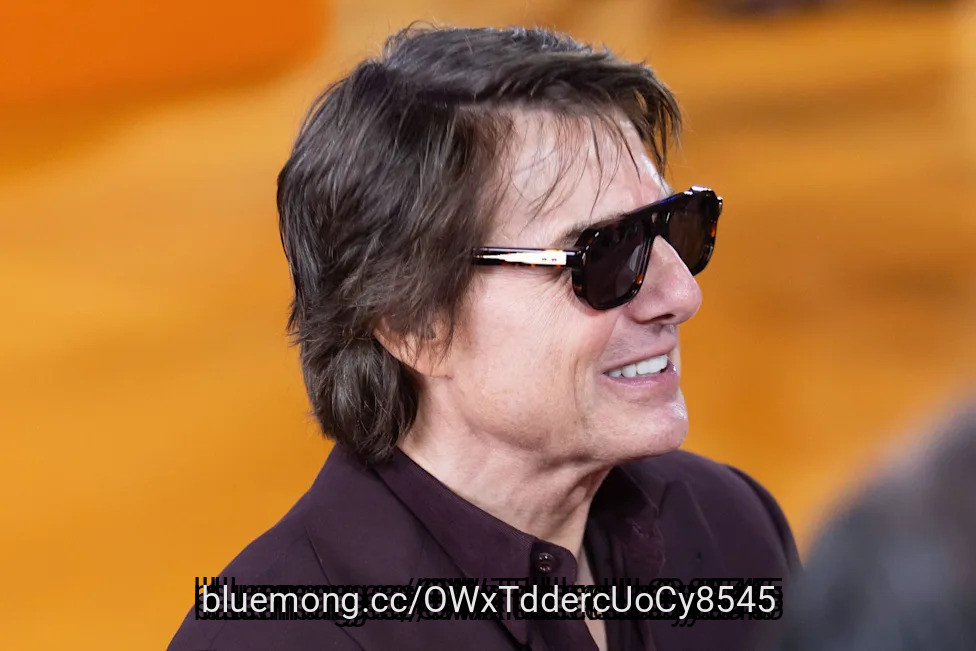
US actor Tom Cruise has surprised a British man who spent a year completing a series of extreme sporting challenges to raise money for charity.
Lloyd Kembrey, a facilities manager at the University of Bristol, took on the challenges to fundraise for children's hospice charity Jessie May.
His connection to the charity was born from his twin cousins, Francesca and Josephine, who were diagnosed with the life-limiting condition Sanfilippo disease type A when they were three-and-a-half years old. Both died in their teens.
Kembrey was inspired to undertake a number of exhilarating challenges in order to honour their memory and support other families facing similar circumstances.
The challenges he faced included a 31-mile ice skating ultramarathon in Finland, climbing the height of Mount Everest on a climbing wall and a 94-mile hike along southern England's Jurassic Coast.
#cruise
11 days ago
Celine Dion stunned fans during her Paris concert in a dazzling Tom Ford gown that brought serious drama to the stage. The singer's shimmering blue dress featured a dramatically high slit that revealed one leg while giving the glamorous look a daring edge. The floor-length gown sparkled under the stage lights, with tiny embellishments scattered across the rich blue fabric. Meanwhile, its long sleeves and structured shoulders added sophistication to the otherwise sultry silhouette.
The Celine Dion dress's high-slit detail became the focal point of the look. The dramatic opening climbed high along one side of the gown, creating plenty of movement as Dion performed.
She kept the rest of her styling sleek. Dion wore her blonde hair pulled back, allowing the statement gown to take center stage. Her polished makeup also complemented the glittering design without distracting from it.
According to the outfit details shared by "Check The Tag," Dion wore a Tom Ford by Haider Ackermann while performing at Paris La Défense Arena. Annie Horth and Patrick Vimbör styled the look.
The Tom Ford creation also joined an impressive lineup of designer looks from Dion's Paris residency. Fashion publications have highlighted her custom Dior, Schiaparelli, Alaïa, and Givenchy ensembles alongside the Tom Ford design.
#Paris #high
11 days ago
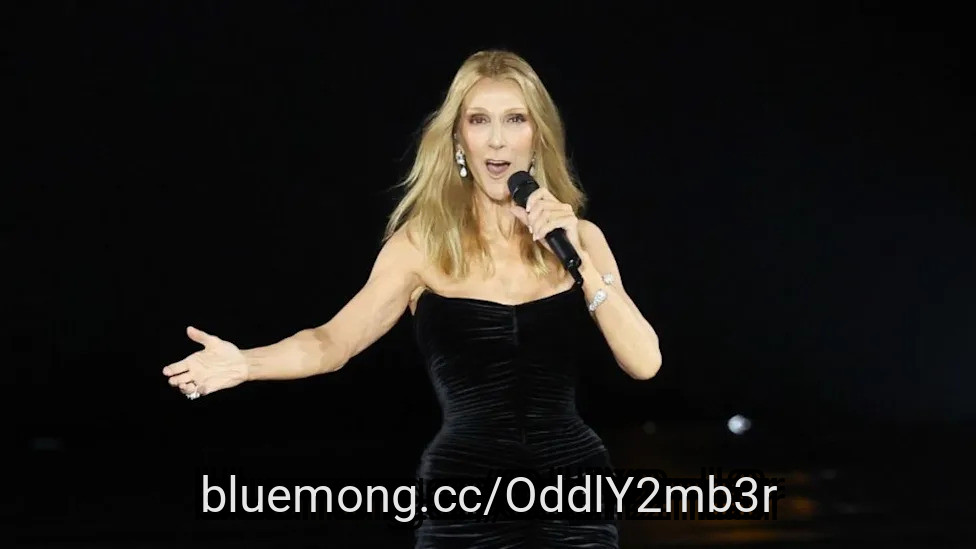
Celine Dion stunned fans during her Paris concert in a dazzling Tom Ford gown that brought serious drama to the stage. The singer's shimmering blue dress featured a dramatically high slit that revealed one leg while giving the glamorous look a daring edge. The floor-length gown sparkled under the stage lights, with tiny embellishments scattered across the rich blue fabric. Meanwhile, its long sleeves and structured shoulders added sophistication to the otherwise sultry silhouette.
The Celine Dion dress's high-slit detail became the focal point of the look. The dramatic opening climbed high along one side of the gown, creating plenty of movement as Dion performed.
She kept the rest of her styling sleek. Dion wore her blonde hair pulled back, allowing the statement gown to take center stage. Her polished makeup also complemented the glittering design without distracting from it.
According to the outfit details shared by "Check The Tag," Dion wore a Tom Ford by Haider Ackermann while performing at Paris La Défense Arena. Annie Horth and Patrick Vimbör styled the look.
The Tom Ford creation also joined an impressive lineup of designer looks from Dion's Paris residency. Fashion publications have highlighted her custom Dior, Schiaparelli, Alaïa, and Givenchy ensembles alongside the Tom Ford design.
#high #look #celine #blue


11 days ago
This summer, we took a family vacation to Oregon to hike in the Pacific Northwest. Not surprisingly, we saw a bunch of people decked out in clothing made by Columbia, the huge sportswear company founded in Portland in 1938, and named for the nearby river.
We also saw a lot of people wearing Patagonia clothes. Named after the vast geographic region at the southern tip of South America, shared by Argentina and Chile, Patagonia was founded by climber Yvon Chouinard in 1973 to provide durable climbing equipment and outdoor wear. The company heavily supports environmental causes and donates profits from the sale of their jackets, fleeces and other gear to ecological protection. The company even sued President Trump in 2017, for shrinking federal lands protections.
In addition to environmental causes, Patagonia has also championed the LGBTQ community by partnering with the Human Rights Campaign to oppose state legislation targeting their rights. This summer, though, the company sued one member of that community.
Wyn Wiley is an activist from Bend, Oregon, who focuses on environmental and LGBTQ+ issues, promoting acceptance of queer identities in the environmentalist and outdoors communities, and promoting awareness of climate change and its effects.
In October of 2018, Wiley created the character Pattie Gonia and produced short-form outdoors activism content on Instagram and TikTok, while dressing in drag. The first posted video garnered more than 100 million views. Pattie Gonia has 1.8 million Instagram followers and claims to have raised $3.7 million for environmental causes, including $1 million raised last year on a 100-mile hike. In 2022, Pattie Gonia partnered with The North Face, another outdoor gear juggernaut, for their 2022 "Summer of Pride" series, which consisted of outdoor community-building events focused on local LGBTQ+ engagement and acceptance.
#lgbtq #summer
12 days ago
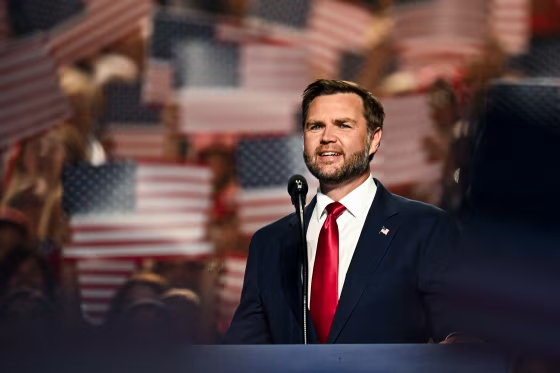
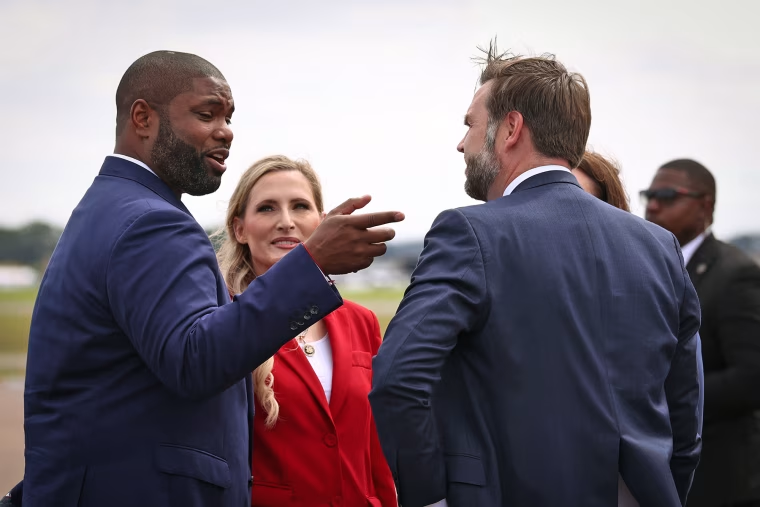
JOINT BASE ANDREWS, Md. — Vice President JD Vance acknowledged Thursday that Republicans face an “uphill climb” in next month’s midterm elections — and that the results may be a data point he reviews as he decides whether to run for president in 2028.
“Historically there’s always a bit of an uphill climb, and I think you definitely sense that,” Vance said in an interview with NBC News. “I also think you can sense a sense of cautious optimism, in the sense that, you know, people feel like the numbers are sort of moving, maybe in our direction.”
He added: “Politically, there’s just a recognition that it’s always going to be hard to win a midterm when you have the White House, the Senate and the House.”
Vance spoke aboard Air Force Two shortly after it landed on a return trip from Lakeland, Florida, where he campaigned for Sen. Ashley Moody and Rep. Byron Donalds, the Republican nominee for governor. It was his latest headlining gig at a rally meant to boost support for the party’s candidates in what is expected to be a challenging year for the GOP.
Aside from the historical trends Vance mentioned, polls have shown President Donald Trump and the war in Iran highly unpopular among voters. A related rise in gas prices has added to a cascade of affordability concerns. And Americans are growing more skeptical of artificial intelligence and the large, power-hungry data centers being built to accommodate the technology. All of those issues could factor into voters’ choices in this fall’s key races for the House, the Senate and governor.
#vance #House #president
13 days ago
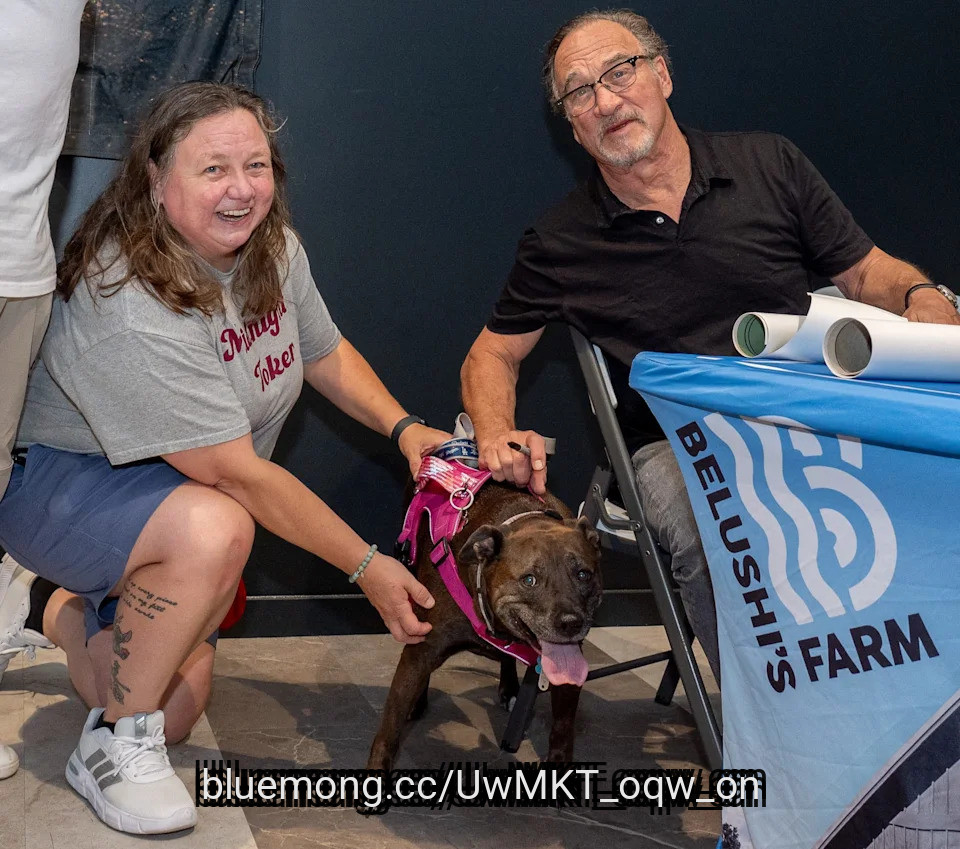
MASSILLON − Fans of actor Jim Belushi exploded into applause when he arrived inside the Bloom Cannabis dispensary.
Admirers chanted his name as he climbed atop a table triumphantly: "Jim! Jim! Jim!" He was welcomed like a conquering hero of cannabis.
While the 72-year-old is known as a funnyman on screen, he's also in the cannabis business as the owner and operator of Belushi's Farm in Oregon.
Belushi was a special guest Oct. 1 of Bloom Cannabis, which also has locations in Akron, Athens, Columbus, Painesville, Seven Mile and Maryland. Founded in 2015 along the Rogue River in Southern Oregon, Belushi's Farm produces cannabis products in Ohio by Wondergrove.
Hundreds showed up at the Massillon dispensary and retail outlet, with a line stretching along the sidewalk in the shopping plaza on Federal Avenue NW.
#massillon #farm #dispensary #along



13 days ago
Pennsylvania has reported its fifth measles-associated death of 2026 as the state's ongoing outbreak climbs to 943 confirmed cases across 39 counties.
The Pennsylvania department of health said on Wednesday that an unvaccinated Lancaster county resident who tested positive for measles had died. Health officials did not release further information about the individual, citing privacy protections.
The death marks the fifth Pennsylvania resident to meet the state's definition of a measles-associated death this year after a fourth death two weeks ago. Due to how the Trump administration has changed its method for reporting measles deaths, the Centers for Disease Control and Prevention (CDC) has not counted the Pennsylvania measles deaths in its national tally.
As of Monday 28 September, Pennsylvania had recorded 40 new positive cases. The outbreak has now reached 39 counties, with 943 ******* ulative confirmed cases, 176 hospitalizations and five confirmed measles-associated deaths.
Only four of those confirmed cases have involved vaccinated individuals, representing less than 1% of the state's total cases.
#associated

24 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
24 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
24 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
24 days ago
Though it's down by 33% over the last five years, Ethereum (CRYPTO: ETH) climbed from about $130 in early 2020 to over $4,800 in early November 2021, which would have been sufficient to turn an investment of $27,000 into about $1 million. It's natural for investors to wonder if another historic run is in the cards for the coin, given that it's more widely known now than it was then.
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even
24 days ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


24 days ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
24 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
24 days ago
On August 10, Simon Property Group (NYSE:SPG) reported results for the three months through June 30 and raised its full-year profit outlook once again. Real estate funds from operations (FFO), a cash-flow measure suited to landlords, hit $3.29 per share. Tenants are earning more from their stores, and management is confident enough to lift its guidance again. Yet the professionals who own the stock are heading the other way.
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate
24 days ago
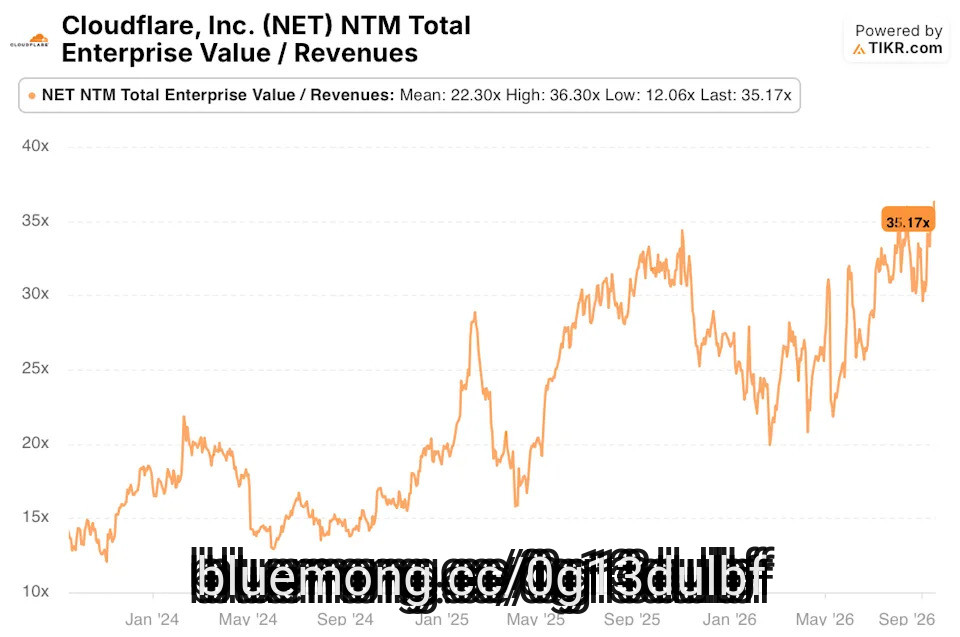
Cloudflare's Q2 beat and reaccelerating growth (36% revenue growth, 120% net dollar retention, record large customer adds) pushed NET stock to new highs, but the market has already paid up: NTM EV/Revenue sits at 35.17x, just below its all-time high of 36.30x and well above its roughly two-year average of 22.30x.
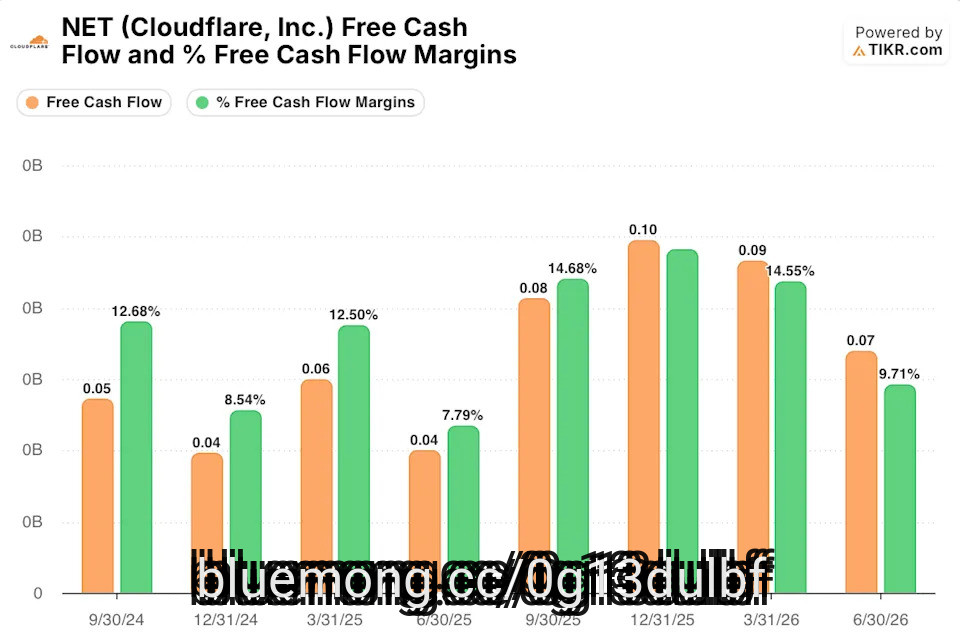
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar
24 days ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
24 days ago
Nvidia (NASDAQ:NVDA) has constructed an artificial intelligence (AI) empire over the past few years. The company sells the world's most powerful AI chips, known as graphics processing units (GPUs), and an entire portfolio of related tools that are generating triple-digit growth and record levels of revenue.
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips

24 days ago
Eli Lilly (LLY) trades near $1,150, up about 52% over the past year, and is now worth more than a trillion dollars. At that size the easy read is that the big money has been made. But Lilly has barely started selling Foundayo, its oral obesity medicine, outside the United States. So how much is left? The scenario below starts from Lilly's own trailing numbers, but the growth, margin, and multiple it ***** umes are ours. It is not a forecast and not a price target.
Almost all of the upside is revenue. The scenario caps growth at 30% a year. That is well below the 49.6% Lilly grew over the past twelve months, though only a little below the roughly 32% pace of its own 2026 guide. Revenue still climbs from $79.7 billion to $175.0 billion by year three.
The engine is incretins. Mounjaro and Zepbound together made $14.9 billion in the second quarter of 2026, $6.3 billion more than a year earlier. Net margin eases to 30.7% in the scenario, so earnings roughly double.
Then the multiple takes its cut. Lilly's P/E of 38.5x already sits below its three-year average of 68.9x, and the scenario trims it further to 33.6x because slower growth will not support even today's multiple. On those ***** umptions the stock would be worth about $2,024 in three years, roughly 76% above today.
LLY
#below #roughly #revenue