2 days ago
Burry is mitigating near-term tax selling in underperforming holdings.
The investor foresees an early end to the artificial intelligence boom, positioning for a 2000–2003 style value equity revival.
Significant capital is being directed into discounted Chinese equities like BYD, while maintaining a cautious stance on Alibaba amidst its infrastructure spending.
Renowned value investor Michael Burry outlined his fourth-quarter portfolio maneuvers in an update on his Cassandra Unchained Substack platform on Monday, revealing how he is positioning around tax-loss harvesting headwinds while building long-term exposure to deeply discounted sectors.
Burry noted that the final quarter routinely brings heightened selling pressure on underperforming equities as investors sell underperforming ***** ets at a loss to offset capital gains.
#burry #positioning #capital #equities

17 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

18 days ago
On September 14, NextEra Energy, Inc. (NYSE:NEE) and Dominion Energy, Inc. (NYSE:D) announced a "transformational" Virginia benefits package to address concerns regarding their proposed $66.8 billion merger. The Virginia supplier program, worth up to $1 billion annually for five years, will direct spending toward contractors, suppliers, and service providers in the state.
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs

18 days ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


18 days ago
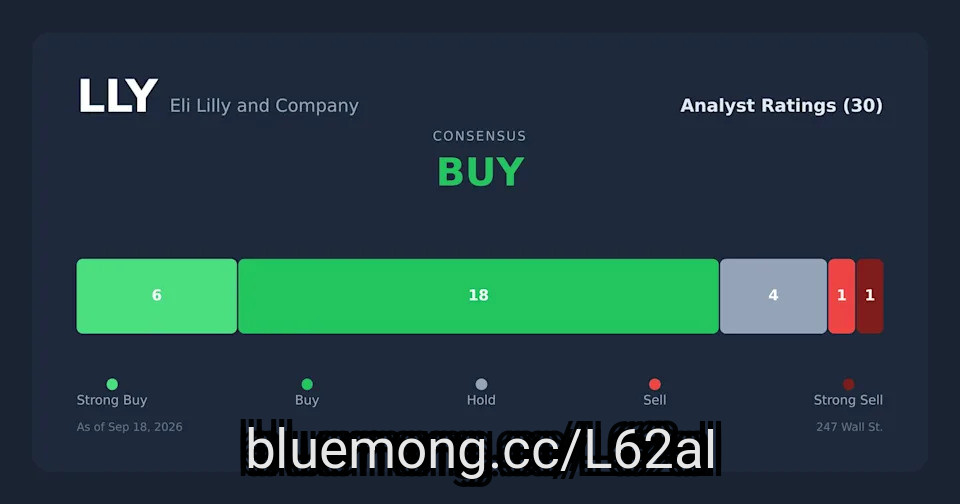
Eli Lilly presents mid-stage eloraTZP data September 30, and LLY stock near $1,152 with a $1 trillion market cap leaves no room for a weak result.
Novo Nordisk's GLP-1 franchise faces headwinds while Viking Therapeutics' VK2735 looms; a convincing eloraTZP win raises the bar for both rivals.
Bearish options positioning shows put/call ratios hitting 4.67 for October 9 expiry, signaling Wall Street is hedging hard against disappointment.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Eli Lilly didn't make the cut. Enter your email to see the names that beat LLY. The report is free. Enter your email and see if any of your stocks made the cut.
Eli Lilly (NYSE:LLY) presents mid-stage data on eloraTZP, a combination of eloralintide and tirzepatide, at a European **** ociation for the Study of Diabetes symposium on September 30.
#eloratzp #september #Stock


18 days ago
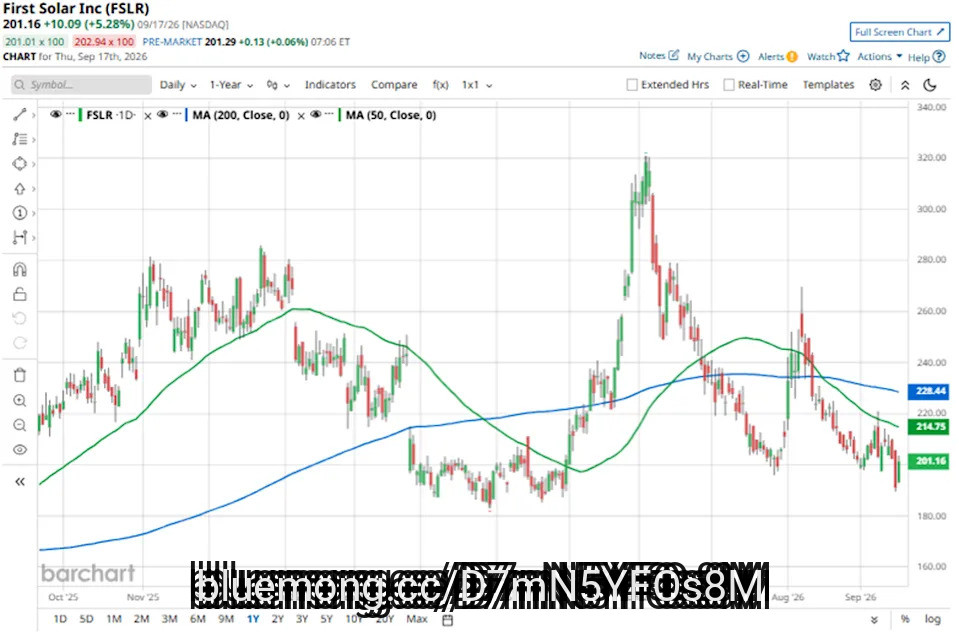
Tempe, Arizona-based First Solar, Inc. (FSLR) is a leading photovoltaic (PV) solar technology and manufacturing company. The company develops and manufactures solar modules using its proprietary thin-film semiconductor technology, offering an alternative to conventional crystalline silicon PV modules. First Solar operates a global manufacturing network spanning the United States, India, Malaysia, and Vietnam. With a market cap of $21.6 billion, the company is one of the largest solar manufacturers.
Companies worth $10 billion or more are generally described as "large-cap stocks," and First Solar fits this description. The company is also one of the few major solar manufacturers with a significant U.S. manufacturing footprint, positioning it to benefit from domestic-content incentives and the broader push to expand U.S. solar manufacturing capacity. First Solar ended the second quarter with a contracted sales backlog of approximately 45.1 GW extending through 2030.
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#Solar #first #billion #tempe
19 days ago
Bitcoin's most violent rally of its two-year drawdown wasn't powered by fresh bullish bets. It was powered by bears getting crushed, according to a new report from ******* ytics firm Glassnode and crypto exchange Bybit.
Over five days in August, Bitcoin climbed 24.6% even as coin-denominated open interest, a measure of active leverage, fell 12.6%, the report found. That combination is the tell: rather than traders piling into new long positions, the move ran on the forced unwinding of existing shorts.
Roughly 64,000 BTC worth of open interest was closed out, and short positions supplied 89% of every liquidated dollar during the stretch.
The options market told the same story. Puts, the contracts traders buy to protect against a fall, had priced richer than calls for 361 straight days. A single session ended that run, flipping roughly a year of downside positioning as the market scrambled to reprice.
Bybit's own volatility index traveled four times its normal daily range in one session, and the front of the futures curve repriced sharply while longer-dated contracts barely moved, a sign the market read the move as a one-off event rather than a lasting regime change.
#interest

19 days ago
Tesla's (NASDAQ: TSLA) business is in an interesting spot. The company saw a significant sales rebound in the second quarter, with revenue rising 26% year over year to reach $22.5 billion. Recent reports also suggest that the company's share of the U.S. electric vehicle (EV) market has risen sharply amid a substantial sales contraction for the overall industry. And while the company's net income fell 5% annually in the second quarter, the business still recorded net income of $1.11 billion in the period.
On the other hand, positive net income doesn't tell the whole story because the metric doesn't include capital expenditures (capex) that are recorded as ****** ets on the balance sheet. With Tesla betting big on its robotaxi project, Optimus humanoid robots, and other potential growth drivers, the company recorded $5.79 billion in capex in Q2. As a result, the business posted -$1.1 billion in free cash flow (FCF) in the period. With FCF coming up negative lately, the company's $43.5 billion cash position provides a valuable cushion.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Tesla posted substantial sales growth in the second quarter as some of the pressures facing the brand eased, higher gas prices encouraged EV purchases, and price cuts helped spur demand. On the other hand, it remains to be seen whether this sales growth momentum is sustainable -- and banking on the core EV business to be an earnings driver that can support the company's highly growth-dependent valuation seems unwise.
While Tesla has seen competitors based in the U.S., ****** an, and South Korea reduce their focus on the EV market, BYD and other China-based rivals are making inroads in the market and continue to bet heavily on long-term growth in the category. CEO Elon Musk appears to have a good grasp on the challenging competitive landscape and has been positioning robotaxis, humanoid robots, and semiconductor projects as the core elements of his company's growth strategy.
#NVIDIA
20 days ago
Coherent jumped 6% and Lumentum climbed 5% with no catalyst, driven by short covering after both stocks fell sharply over the prior month.
SOXX gained only 2% and SPY just 0.3%, making the optics group's surge a positioning-only bounce confined to the sector, not a broad re-rating.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Coherent didn't make the cut. Enter your email to see the names that beat COHR. The report is free. Enter your email and see if any of your stocks made the cut.
Optics stocks are rebounding Wednesday morning without a fresh headline to point to, and the size of the group's move relative to the broader market is the story. The iShares Semiconductor ETF (NASDAQ:SOXX) is at $508.59, up 2%, while the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is at $759.69, up just 0.3%. The three optics names running today are outpacing both benchmarks by a wide margin.
Coherent Corp. (NYSE:COHR) stock is up 6% to $287.21 in Wednesday morning trading. The bounce arrives after a rough stretch. Coherent shares had fallen 12% over the past month heading into today's session, and that drawdown is the part of the setup that hasn't been undone.
#optics

20 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #NASDAQ #fund #parnassus

20 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

20 days ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#elevated #analyst

21 days ago
Hive Digital Technologies Chief Financial Officer Darcy Daubaras joined Steve Darling from Proactive to discuss the appointment of renowned capital markets executive Hubert Marleau as an Independent Director of HIVE's wholly owned subsidiary, BUZZ High Performance Computing (BUZZ HPC), a move designed to strengthen governance and strategic oversight as the company expands its sovereign AI infrastructure platform across Canada.
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
21 days ago
NuScale Power Corporation (SMR) stands out as America's leading developer of small modular reactors (SMRs), building light-water nuclear systems designed to deliver reliable, carbon-free baseload power. Its core product, the NuScale Power Module, targets a wide range of applications, from traditional electricity generation to industrial decarbonization, AI data center power supply, and hydrogen production. Notably, NuScale remains the only SMR developer to secure Standard Design Approval from the U.S. Nuclear Regulatory Commission, a regulatory milestone that continues to anchor its competitive positioning in the emerging advanced nuclear industry.
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude


21 days ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry

21 days ago
CrowdStrike (CRWD) stock is already having a huge 2026, but Nvidia CEO Jensen Huang just offered investors another reason to stay bullish. Speaking at a Goldman Sachs technology conference, Huang said cybersecurity could become the next major growth driver for artificial intelligence and described CrowdStrike as Nvidia's (NVDA) "number one cybersecurity partner."
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#crowdstrike #huang #goldman #become


21 days ago
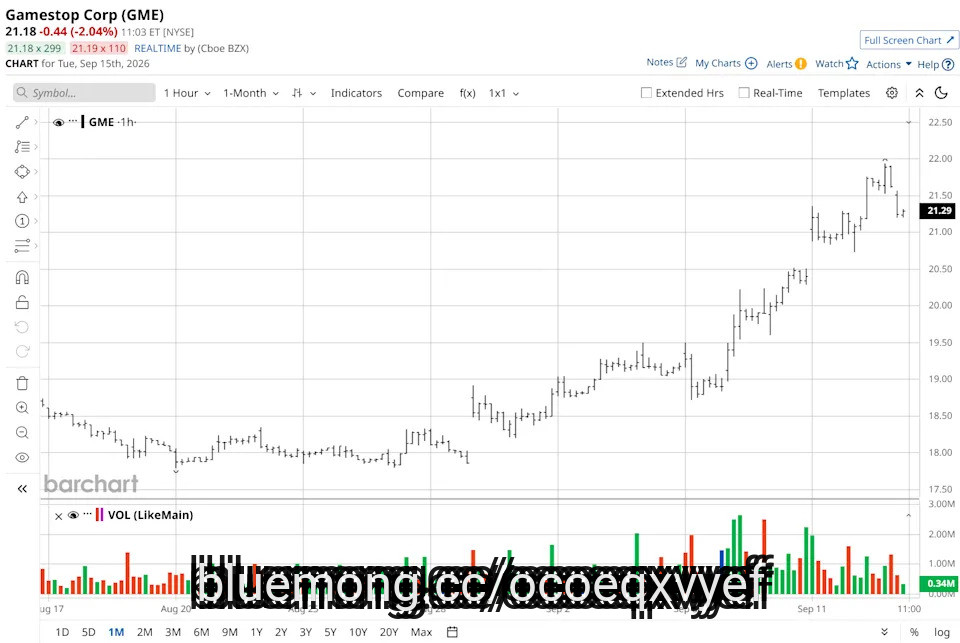
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital ***** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#shares

21 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c

21 days ago
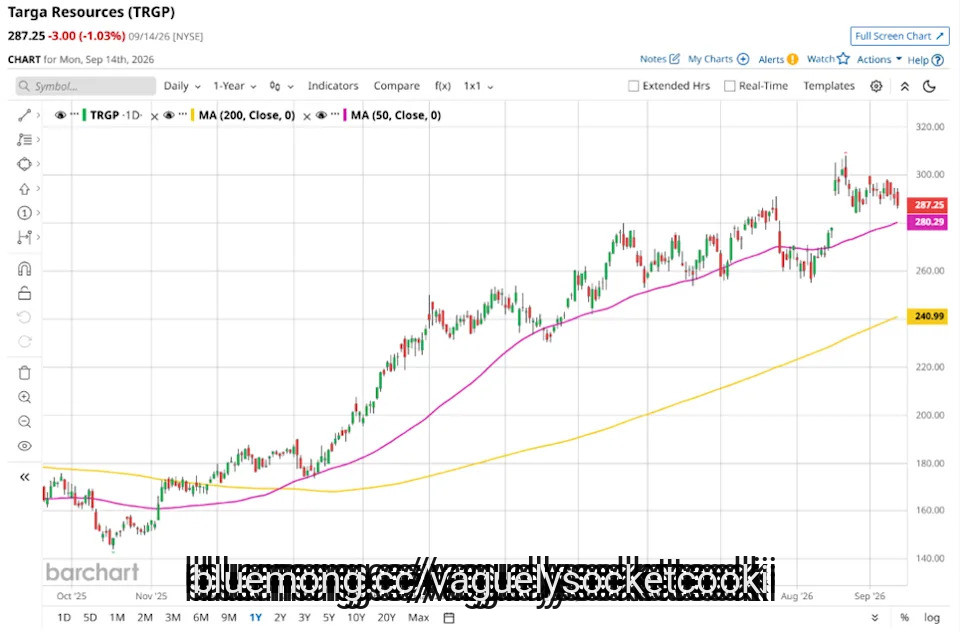
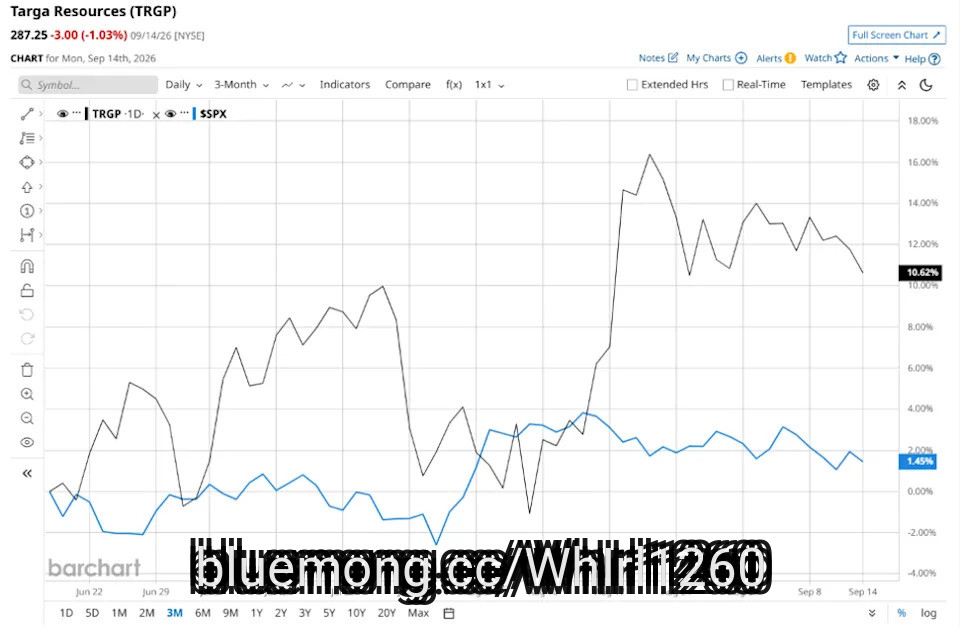
Targa Resources Corp. (TRGP), headquartered in Houston, Texas, owns, operates, acquires, and develops a portfolio of complementary domestic infrastructure ***** ets. Valued at $62.2 billion by market cap, the company's ***** ets connect natural gas and NGLs to domestic and international markets with growing demand for cleaner fuels and feedstocks.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#market


21 days ago
With Agentic AI accelerating CPU server chip demand, Wall Street believes Advanced Micro Devices, Inc. (NASDAQ:AMD) is one of the primary beneficiaries taking share. On September 9, Piper Sandler ******* yst David O'Connor initiated coverage on AMD (NASDAQ: AMD) with an Overweight rating and a $600 price target.
Analyst O'Connor estimates revenue for FY26-30 to grow at a 50% CAGR, while earnings per share compound at 65%.
The server-CPU share gain story for AMD is simple, Agentic AI is expected to increase demand for server CPUs. This is because the workloads require continuous control-plane activity, API calls, database queries and tool execution. AMD will benefit from this use based on its high-frequency and general-purpose processors with its Venice portfolio.
Even AMD executives have highlighted that AMD is now transitioning from merely a semiconductor supplier to a provider of rack-scale systems and software. It is also positioning its server CPU portfolio for increased demand from agentic AI workloads.
The company reported second-quarter revenue of $11.5 billion, beating ******* yst estimates. This includes $6.7 billion from data centers, up 107% year-over-year. The segment performance was attributed to EPYC processors and Instinct GPUs.
#workloads


21 days ago
CrowdStrike (CRWD) stock is already having a huge 2026, but Nvidia CEO Jensen Huang just offered investors another reason to stay bullish. Speaking at a Goldman Sachs technology conference, Huang said cybersecurity could become the next major growth driver for artificial intelligence and described CrowdStrike as Nvidia's (NVDA) "number one cybersecurity partner."
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#become

21 days ago
GameStop (GME) is a Grapevine, Texas-based specialty retailer operating stores and e-commerce platforms under the GameStop, EB Games, and Micromania banners across the U.S., Canada, Australia, and Europe. Once known primarily as a video game and electronics retailer, GameStop has diversified aggressively under Executive Chairman Ryan Cohen, expanding into collectibles, trading cards, pop culture merchandise, and even cryptocurrency and equity investments. The company has become a prominent "meme stock," attracting substantial retail investor attention while pursuing an unconventional capital allocation strategy that includes bitcoin holdings and a sizable equity stake in eBay (EBAY), positioning GameStop as much an investment vehicle as a traditional retailer.
GameStop stock recently traded around $21.15, near the bottom of its 52-week range of $17.79 to $28.10 and below its 200-day moving average. Shares have pulled back significantly from their 2025 meme-stock highs, weighed down by declining video game sales, ongoing store closures, and investor skepticism toward the company's diversification into digital **** ets and equity investments. The stock did see brief bursts of retail-trader enthusiasm this year, including renewed meme-stock speculation tied to its proposed eBay acquisition, though shares have remained volatile and range-bound as GameStop's core retail business continues shrinking alongside its growing collectibles and investment segments.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#Equity
21 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight
21 days ago
Targa Resources Corp. (TRGP), headquartered in Houston, Texas, owns, operates, acquires, and develops a portfolio of complementary domestic infrastructure ****** ets. Valued at $62.2 billion by market cap, the company's ****** ets connect natural gas and NGLs to domestic and international markets with growing demand for cleaner fuels and feedstocks.
Companies worth $10 billion or more are generally described as "large-cap stocks," and TRGP perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the oil & gas midstream industry. TRGP benefits from strategic positioning in key shale plays including Permian, STACK, SCOOP, and Bakken, giving it a competitive edge in midstream. Its diversified service portfolio, including the Grand Prix NGL pipeline and Mont Belvieu fractionation capacity, underpins a strong market presence and stable revenue base.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #market #assets #midstream


21 days ago
Ocean Power Technologies Inc (NYSE-A:OPTT) reported first-quarter fiscal 2027 revenue of $1.7 million, up 44% from a year earlier, as the company expanded its work with US defense and security customers and moved forward with a strategic review process.
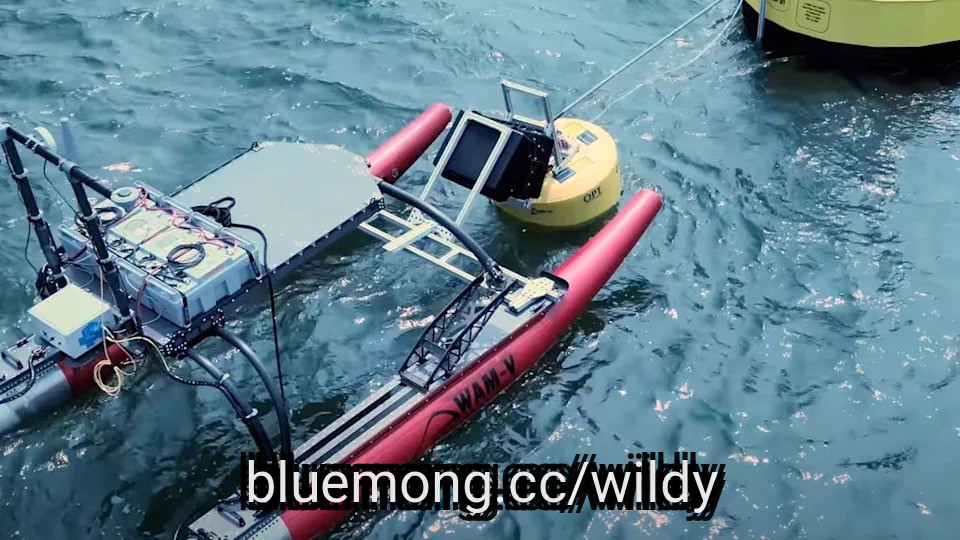
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy
22 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Medline Inc. (NASDAQ:MDLN). Medline Inc. (NASDAQ:MDLN) manufactures med-surg products serving hospitals, surgery centers, physician offices, post-acute facilities, and nursing home sites of care. On September 15, 2026, Medline Inc. (NASDAQ:MDLN) closed at $36.59 per share. Over the past month, Medline Inc. (NASDAQ:MDLN) declined 4.23%, and YTD its shares lost 22.68%. Medline Inc. has a market capitalization of $42.22 billion.
Parnassus Growth Equity Fund stated the following regarding Medline Inc. (NASDAQ:MDLN) in its Q2 2026 investor letter:
"Medline Inc. (NASDAQ:MDLN) shares declined as medical technology stocks broadly came under pressure. The company also faced near term concerns surrounding tariffs and higher transportation costs, though we remain confident in its long-term competitive positioning."
Medline Inc. (NASDAQ:MDLN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 52 hedge fund portfolios held Medline Inc. (NASDAQ:MDLN) at the end of the second quarter which was 65 in the previous quarter. While we acknowledge the potential of Medline Inc. (NASDAQ:MDLN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#medline #fund

22 days ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Twist Bioscience Corporation (NASDAQ:TWST) as a new addition. Twist Bioscience Corporation (NASDAQ:TWST) is a leading biotechnology company specializing in the manufacture and sale of synthetic DNA-based products. On September 15, 2026, Twist Bioscience Corporation (NASDAQ:TWST) closed at $138.10 per share. Over the past month, Twist Bioscience Corporation (NASDAQ:TWST) returned 2.97% while its shares gained 443.64% over the past 52 weeks. Twist Bioscience Corporation (NASDAQ:TWST) has a market capitalization of $9.09 billion and its stock has traded within a 52-week range of $23.30 and $155.44.
Parnassus Growth Equity Fund stated the following regarding Twist Bioscience Corporation (NASDAQ:TWST) in its Q2 2026 investor letter:
"During the quarter, we added Twist Bioscience Corporation (NASDAQ:TWST), a biotechnology company with a proprietary silicon-based DNA synthesis platform. Twist Bioscience provides exposure to two powerful long-term trends in Health Care, AI-supported drug discovery and next-generation sequencing. The company's proprietary silicon-based DNA synthesis platform enables higher throughput and lower costs than traditional methods, creating a durable competitive advantage and positioning Twist to take share in a growing market."
Twist Bioscience Corporation (NASDAQ:TWST) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 42 hedge fund portfolios held Twist Bioscience Corporation (NASDAQ:TWST) at the end of the second quarter which was 30 in the previous quarter. While we acknowledge the potential of Twist Bioscience Corporation (NASDAQ:TWST) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands

22 days ago
On the September 11 episode of Mad Money, Jim Cramer expressed strong optimism for Brinker International, Inc. (NYSE:EAT) ahead of its upcoming **** yst presentation, as he said:
Thursday, we have two important **** yst meetings. Brinker... We have them all the time on the show. Brinker, you know, is Chili's, and the company never fails to wow me. I think this meeting will be no exception.
Brinker International, Inc. (NYSE:EAT) continues to demonstrate operational strength across the casual dining sector, driven by sustained customer traffic and menu innovation at Chili's Grill & Bar. In its fourth quarter of fiscal 2026, the company generated $1.54 billion in total revenue, bringing full-year revenues to $5.81 billion. Adjusted earnings per share for the quarter reached $3.07, representing a 23% year-over-year increase.
Chili's reported a 5.6% increase in comparable store sales, marking its 21st consecutive quarter of positive same-store sales growth. The sustained momentum has been supported by the ongoing success of the $10.99 "3 for Me" everyday value platform as well as targeted menu launches, including the Big Crispy Chicken Sandwich, which helped support traffic as Chili's continued positioning its value proposition against fast-food offerings. According to the company's CEO Kevin Hochman, the Big Crispy Chicken Sandwich "overdelivered" on the management's estimates.
Despite consistent top-line momentum, Brinker International, Inc. (NYSE:EAT) faces ongoing execution risks **** ociated with sticky cost inflation and broader macroeconomic pressures on consumer spending. Elevated wholesale prices for core commodities, especially beef and produce, continue to weigh on restaurant operating costs, while wage growth across regional markets keeps labor expenses elevated.
#NYSE

23 days ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
23 days ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen