

20 days ago
My husband, who is 59 and an only child, recently inherited $3 million from his father. I'm 57, and we've been married since we were in our 20s. We've always kept most of our money separate, although we split the household bills and own our house together.
He grew up wealthy. His family had a big house, belonged to a country club and paid for his college and graduate school. He's always been comfortable spending money on things I think of as luxuries. My parents were middle-class and worked hard, but they never had much saved.
My brother-in-law convinced his parents to sign over their home and life savings to buy a $3 million compound. Do I intervene?
America's favorite index is misleading investors about the state of the stock market
We both still work. He's a partner at a consulting firm and makes $350,000 a year. I work in healthcare administration and earn $145,000. We have $1.6 million in retirement accounts, a little more than half of which belongs to my husband. We owe $280,000 on our $1.1 million house.
#we 've #husband #only



1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august

1 month ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


1 month ago
By Exec-Edge Editorial Staff
Sir Lynton Crosby has spent four decades reading public opinion for people who couldn't afford to get it wrong — prime ministers, presidents, and the boards of some of the world's largest companies. As Executive Chairman of CT Group, the research and strategy firm he co-founded, Crosby has built one of the most quietly influential shops in political and corporate consulting, with offices across eight countries and a client roster that spans government, industry, and advocacy. In recent years, CT Group has turned its research apparatus toward a subject closer to home for the business community it serves: capitalism itself, and why the system's public standing hasn't kept pace with its performance. We spoke with Crosby about what the firm's research found, and what it means for how business leaders talk about the system they operate in.
Exec Edge: CT Group ran a large-scale study on public attitudes toward capitalism. What prompted that?
We had seen a number of signals that some of the trending narratives on how the public felt about the predominant economic system were misleading. But we don't operate on feelings, but instead we respond to data, so we tested it. There's a narrative that's taken hold since the financial crisis — that the public has simply given up on capitalism, that a decade of scandals and populist politics has turned the average voter against the system outright. We fielded a nationally representative survey of 3,000 people, backed by focus groups, to find out if that was actually true or if something more specific was going on. It turned out to be the latter.
Exec Edge: What did the research actually find?
#edge #Research #turned


1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


1 month ago
Listen
(4 min)
The latest Market Talks covering the Health Care sector. Published exclusively on Dow Jones Newswires at 4:20 ET, 12:20 ET and 16:50 ET.
1528 ET – Q/C Technologies shares mostly rebounded from a 67% drop Monday and a 52-week low Tuesday, more than doubling late Wednesday. The optical-computing company late Friday disclosed that consulting agreements with an entity affiliated with Martin Shkreli and with OpenAI scientist Chelsea Voss were mutually terminated. Voss also resigned from the board. Earlier Wednesday, adviser James Altucher posted on X about the company’s AI-powered platform for chip design, which coincided with an intraday peak in the company’s share price. Shares were recently at $1.06, up 139%, amid very volatile trading and still below Friday’s close of $1.71. (josh.beckermanwsj.com)
#voss

1 month ago
Investors continue to ask for more timely information, even as the volume available to them expands. A 2026 CFA Institute survey of 2,500 **** ysts and portfolio managers found that 62% opposed replacing quarterly reporting with semiannual reporting. Nearly 85% expressed concern about comparability if companies and investment managers could determine their own reporting frequency and format. Access remains important, while interpretation requires a separate discipline.
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#investor


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Robert Half Inc. (NYSE:RHI). Robert Half Inc. (NYSE:RHI) is a leading staffing and consulting company. On September 15, 2026, Robert Half Inc. (NYSE:RHI) closed at $38.30 per share. Over the past month, Robert Half Inc. (NYSE:RHI) declined 12.03% and its shares gained 10.28% over the past 52 weeks. Robert Half Inc. (NYSE:RHI) has a market capitalization of $3.92 billion, and its stock has traded within a 52-week range of $21.83 and $46.70.
Conventum – Alluvium Global Fund stated the following regarding Robert Half Inc. (NYSE:RHI) in its Q2 2026 investor letter:
"We last wrote about Robert Half Inc. (NYSE:RHI) (up 23.5%) in our December report, where we mentioned that hindsight suggests our purchasing during price descents in May, August and October were mistakes. This remains the case - but less so. Our expectation that the recruitment / outplacement market will slowly recover, appears, going by Robert Half's recent results, to be bearing fruit. And management remain cautiously optimistic. We did not trade the stock. The Fund's position is now 2.7%."
Robert Half Inc. (NYSE:RHI) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 30 hedge fund portfolios held Robert Half Inc. (NYSE:RHI) at the end of the second quarter which was 36 in the previous quarter. While we acknowledge the potential of Robert Half Inc. (NYSE:RHI) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#half #NYSE

1 month ago
Cardinal Health, Inc. (CAH), headquartered in Dublin, Ohio, operates as a healthcare services and products company. Valued at $54.6 billion by market cap, the company's services include pharmaceutical distribution, health-care product manufacturing, distribution and consulting services, drug delivery systems development, pharmaceutical packaging, automated dispensing systems manufacturing, and retail pharmacy franchising.
Companies worth $10 billion or more are generally described as "large-cap stocks," and CAH perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the medical distribution industry. As one of the top three U.S. pharma wholesalers, CAH holds a commanding market position. Its diversified pharmaceutical and medical distribution portfolio, broadens its customer base, adds resilience to market swings, and creates multiple revenue streams with cross-selling opportunities.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#market #Health #Manufacturing #systems



1 month ago
MiKargo247 is expanding its spot cargo insurance coverage to include strategic cargo theft under a new partnership with Verified Carrier.
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies


1 month ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Creative Planning, the Overland Park, Kan.-based registered investment advisor with $780 billion in **** ets under management, has agreed to acquire an institutional consulting and investment research firm overseeing $4.3 trillion in **** ets for public and private retirement plans, endowments, foundations and insurance companies.
The transaction is expected to close in January 2027.
According to an announcement, Creative Planning is set to acquire Portland, Ore.-based RVK Inc., a 40-year-old consultant with 200 institutional clients.
RVK will continue to be led by its current management team, according to the announcement. The firm's services include investment policy development, **** et allocation, investment manager research and selection, performance measurement, operational diligence and governance consulting.
#wealthmanagement #assets #acquire


1 month ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) provides strategy and consulting, industry X, song, and technology and operation services. On September 14, 2026, Accenture plc (NYSE:ACN) closed at $195.00 per share. Over the past month, Accenture plc (NYSE:ACN) was up 12.35%, and its shares lost 17.96% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $119.33 billion.
Broyhill ******* et Management stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"Accenture plc (NYSE:ACN) fell 38%, and we exited in June. Our case rested on unpriced optionality appearing as revenue per employee, and that measure grew only marginally while bookings declined 3% and the managed services book to-bill fell below one. Management's response was to raise the acquisition guide to $9 billion. An inflection in bookings was a key point in the thesis, and the fact that management fell back on acquisitions when it came in weak does not inspire confidence in the core business. We sold the position following these results."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#management #investor

1 month ago
Weitz Investment Management, an investment management firm, released its second-quarter Q2 2026 investor letter for the "Multi Cap Equity Fund". The letter can be downloaded here. The Multi Cap Equity Fund's Institutional Class returned 7.90% in Q2, underperforming the Bloomberg U.S. 3000 Index's 15.71% gain. Markets rose in the quarter on hopes of de-escalating Middle East tensions and easing oil flow. Investor focus shifted back to artificial intelligence, despite component shortages like processing chips affecting profits and valuations. Valuation-sensitive investors are selective within the AI sector, in contrast to valuation-agnostic indexes that adopt a more relaxed strategy. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Weitz Multi Cap Equity Fund highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) is a leading professional services company that provides consulting, industry X, song, and technology and operation services. On September 15, 2026, Accenture plc (NYSE:ACN) closed at $193.40 per share. Over the past month, Accenture plc (NYSE:ACN) was up 3.11%, and its shares lost 21.71% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $118.33 billion.
Weitz Multi Cap Equity Fund stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"IT services and management consultant Accenture plc (NYSE:ACN) reported results in mid-June that did little to quell investor fears of AI-disintermediation. Accenture has a long history of helping clients navigate technological transformation, and we believe it will again play a role as AI permeates businesses. To date, however, we have maintained a smaller position given the higher-than-usual degree of uncertainty."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#multi #investment

1 month ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Robert Half Inc. (NYSE:RHI). Robert Half Inc. (NYSE:RHI) is a leading staffing and consulting company. On September 15, 2026, Robert Half Inc. (NYSE:RHI) closed at $38.30 per share. Over the past month, Robert Half Inc. (NYSE:RHI) declined 12.03% and its shares gained 10.28% over the past 52 weeks. Robert Half Inc. (NYSE:RHI) has a market capitalization of $3.92 billion, and its stock has traded within a 52-week range of $21.83 and $46.70.
Conventum – Alluvium Global Fund stated the following regarding Robert Half Inc. (NYSE:RHI) in its Q2 2026 investor letter:
"We last wrote about Robert Half Inc. (NYSE:RHI) (up 23.5%) in our December report, where we mentioned that hindsight suggests our purchasing during price descents in May, August and October were mistakes. This remains the case - but less so. Our expectation that the recruitment / outplacement market will slowly recover, appears, going by Robert Half's recent results, to be bearing fruit. And management remain cautiously optimistic. We did not trade the stock. The Fund's position is now 2.7%."
Robert Half Inc. (NYSE:RHI) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 30 hedge fund portfolios held Robert Half Inc. (NYSE:RHI) at the end of the second quarter which was 36 in the previous quarter. While we acknowledge the potential of Robert Half Inc. (NYSE:RHI) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#half #quarter #global #letter

1 month ago
On September 1, Korn Ferry (NYSE:KFY) completed its £850 million acquisition of UK-based AMS, from OMERS Private Equity. The deal combines two well-reputed brands, resulting in a highly well-rounded solutions provider and a leading business within the global talent and organizational consulting **** e. It offers a broader market reach to Korn Ferry, along with more extensive coverage spanning several new industries.
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business


1 month ago
Cowboys news: Dallas praying Malik Hooker's injury isn't as bad as it could be after Week 1 debacle appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
On Sunday evening, the Dallas Cowboys kicked off their season with an ugly 28-20 road loss to the New York Giants. The Cowboys' new-look defense, which had received considerable hype from fans and pundits alike heading into this year, fell flat on its face in this one, finding itself unable to get off the field in the second half against New York.
Things went from bad to worse when Malik Hooker went down with an injury, and on Monday, the team got the latest update on his potential recovery process.
"#Cowboys S Malik Hooker fractured a bone in his forearm and he's consulting with a hand specialist to learn his recovery time, sources say. While some breaks can mean a player is out six weeks, the hope is based on the specific bone and break, it's quicker than that," reported NFL insider Ian Rapoport of the NFL Network on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#cowboys #recovery


1 month ago
Founded in 1977 and headquartered in South Korea, LX Pantos has grown into a global logistics provider spanning freight forwarding, contract logistics, e-commerce fulfillment, last-mile delivery and installation, and supply chain management consulting. The company now operates more than 380 locations worldwide with a workforce of approximately 8,500 employees, moving more than 1.6 million TEUs of ocean freight and over 120,000 tons of air freight annually. In 2025, LX Pantos recorded revenue of approximately $5.85 billion.
For President and CEO Lee Yong-ho, those figures mark a foundation rather than a destination.
"Since **** uming the role of CEO, I have set a clear vision for LX Pantos: to build the company into a 'Korea-born, global logistics company,' and we have been pursuing that goal with unwavering commitment," Lee said.
That vision marks a departure from the model that carried LX Pantos for decades on domestic corporate freight volumes.
"For many years, LX Pantos grew rapidly by leveraging freight volumes from domestic corporate customers. However, we have also recognized that growth driven primarily by the domestic market has its limitations," Lee said. "It is now time for LX Pantos to evolve into a truly global logistics company — one that is not confined to any single country or customer segment, but is capable of delivering comprehensive logistics solutions to customers worldwide."
#pantos #Logistics



2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved a sixth consecutive quarter of top-line growth, driven by broad-based strength across all regions and industry groups despite macroeconomic headwinds.
Completed the acquisition of AMS to create a global leader in talent and organizational consulting, significantly expanding capabilities in contingent workforce solutions and early career recruiting.
Transitioned to a new geographic reporting structure (Americas, EMEA, APAC) to better align with 'We Are Korn Ferry' go-to-market initiatives and holistic client engagement.
Leveraged proprietary data and IP—including 113 million executive ******* sments—to differentiate services in an AI-saturated market where resume quality has become commoditized.
#market #NVIDIA #tell #americas

2 months ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Edelman Financial Engines is extending its retirement plan advisory and fiduciary capabilities to the small and mid-sized business market. While the firm has long served business owners through its workplace and wealth businesses, this service focuses on helping smaller business owners offer and manage retirement plans for their employees.
The firm has partnered with ADP for payroll, human capital management and retirement services. Edelman's will provide investment management, 3(38) investment management, plan consulting and personalized financial advice to plan participants. That includes providing one-on-one discretionary advisory services for individual employees.
Employees also gain unlimited access to Edelman's phone-based licensed advisors, who average 10 years of industry tenure, along with on-demand digital planning tools.
"EFE financial wellness and advisory services have been available to employees in eligible workplace retirement plans through the ADP platform since 2018," said Chris Magno, senior vice president and general manager of ADP Retirement Services, in a statement. "The new service expands that relationship by delivering a more comprehensive retirement solution purpose-built for small and mid-sized businesses, offered in combination with the full-service recordkeeping, payroll integration and plan administration capabilities of ADP."
#Services #management #wealthmanagement

2 months ago
Crowe UK, an audit, tax, advisory and consulting practice, has welcomed 96 trainees as part of its 2026 intake.
The recruits will be based in Cheltenham, Kent, Manchester, London, the Midlands and the Thames Valley.
They will join teams covering tax, corporate audit, business advisory and accounting, social purpose and non-profit audit, and financial reporting.
According to a statement, the trainees will complete an induction programme during their first weeks at the company.
The induction programme is designed to introduce the new employees to Crowe's culture, values and working practices. It will also help the new starters connect with colleagues across the business.
#business #programme #cheltenham

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
On August 13, Legence Corp. (NASDAQ:LGN) reported second-quarter results that more than doubled the company's revenue from a year earlier, a jump big enough to make even seasoned investors do a double take. Strip out the contribution from the company's Bowers acquisition and the underlying business still grew 60%. But dig one line deeper into the same report and a less flattering picture shows up: profitability per dollar of revenue actually shrank, and the bottom line posted a wider loss than it did last year. That contrast, blistering growth paired with thinning margins, is the story investors now have to sort out.
The headline number was revenue of $1.26 billion for the quarter, up 110.7% from $598.9 million a year ago. Adjusted EBITDA climbed even faster in percentage terms, rising 114.1% to $154.6 million, which tells you the company managed to grow its cash-generating profit measure roughly in step with the top line even during a period of heavy acquisition-driven expansion. Backlog and awarded contracts, effectively the pipeline of future work already on the books, reached $5.67 billion, more than double the $2.77 billion Legence held a year earlier.
That backlog is not concentrated in one place either. While data centers and technology remained the biggest driver, management pointed to healthy activity across life sciences and healthcare, state and local government, and education as well, spreading the growth across several end markets rather than resting it on a single customer type. The Installation & Maintenance segment did the heavy lifting, with revenue up 162% to $1.06 billion, and even after removing the Bowers acquisition's impact, that segment still grew 86.6% on its own.
Management also used the quarter to raise its full-year guidance, now targeting $4.7 billion to $4.8 billion in revenue, up from a prior range of $4.1 billion to $4.3 billion, alongside adjusted EBITDA guidance lifted to $565 million to $585 million from $470 million to $490 million.
The same report shows profitability moving in the opposite direction of revenue. Gross margin fell to 17.4% from 21.5% a year ago, and the non-GAAP adjusted version slipped to 18.5% from 21.8%, a shift the company attributed to a revenue mix leaning more heavily toward lower-margin installation and maintenance work. The Engineering & Consulting segment felt this directly, with gross profit down 12.4% to $56.1 million even as its revenue grew, a sign that pricing and cost pressure in that business outpaced its sales growth. Net loss attributable to Legence widened to $27.8 million from $5.3 million a year earlier, and the company's total net loss grew to $34.6 million from $3.9 million.
#year #grew #adjusted


2 months ago
Palantir Technologies' stock jumped approximately 8% on Thursday, recovering from the previous session's nearly 6% decline and trading near $183.
The rebound came even as prominent short-seller Michael Burry, known for his role in "The Big Short," renewed his long-standing bearish critique of the company.
In a detailed post on X early Thursday, Burry reiterated that Palantir is back in the stratosphere and that the facts have not changed. He described the firm as a consultant riding a bubble of AI FOMO demand and warned that its market cap could eventually fall well below $100 billion.
Burry focused on accounts receivable trends, noting that receivables had grown faster than revenue in 9 of the last 12 quarters, with one customer accounting for about 25% of receivables while contributing less than 10% of revenue.
He also highlighted rising days sales outstanding, deferred revenue patterns resembling those of consulting firms like Accenture rather than pure SaaS peers, elevated stock-based compensation, and large net operating losses. Burry disclosed that he remains short the stock and holds put options.
#Stock #revenue


2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ****** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high-quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections in 2026.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted Arthur J. Gallagher & Co. (NYSE:AJG). Arthur J. Gallagher & Co. (NYSE:AJG) provides insurance and reinsurance brokerage, consulting, and third-party property/casualty claims settlement and administration services to entities and individuals. On September 02, 2026, Arthur J. Gallagher & Co. (NYSE:AJG) closed at $264.46 per share. Over the past month, Arthur J. Gallagher & Co. (NYSE:AJG) was up 5.05%, while its shares lost 11.91% over the past 52 weeks. Arthur J. Gallagher & Co. (NYSE:AJG) has a market capitalization of $67.78 billion.
Eagle Capital Management stated the following regarding Arthur J. Gallagher & Co. (NYSE:AJG) in its Q2 2026 investor letter:
"High quality with low volatility (24% of capital): London Stock Exchange, Danaher, S&P Global, Mastercard, A.J. Gallagher: Approximately a quarter of Eagle's portfolio is spread across a handful of superb businesses that exhibit high and stable margins, strong returns on capital, wide competitive advantages, and well above GDP growth. We expect the group to deftly navigate the integration of AI into their markets. Most operate with a combination of oligopoly/monopoly ****** ets, network effects, or regulatory moats. A.J. Gallagher is a commercial insurance broker that continues to gain share in a consolidating industry.
A few years ago, these stocks were priced for perfection. Their attractive characteristics were prized, and the group traded at more than 30x earnings. Over the past five years, the businesses have grown significantly, while the stocks have de rated. Today, the group trades at a high teen multiple. In a market that is growing EPS at nearly 20%, their steady growth isn't scarce. Howev

2 months ago
On August 24, ePlus (NASDAQ:PLUS) announced it had completed the acquisition of the **** ets of Daymark Solutions, a Massachusetts-based IT services provider, with the deal having closed three days earlier on August 21. The announcement landed three weeks after the company posted first-quarter fiscal 2027 results on August 4, showing sales climbing even as profit slipped. Together, the two headlines capture where ePlus stands right now: reaching for new growth in cloud and security while working through pressure on its existing business.
Daymark, founded in 2001, built its business serving highly regulated, data-intensive industries including energy and utilities, healthcare, life sciences, defense, and financial services. Its core capabilities span modern data center infrastructure, cloud, Microsoft 365, Microsoft 365 Copilot, and cybersecurity, and its status as a Microsoft Tier 1 Cloud Solution Provider slots directly alongside ePlus' existing Azure and Microsoft 365 professional and managed services work. The acquisition also gives ePlus a deeper foothold in the New England region, particularly metropolitan Boston. CEO Mark Marron framed it as a way to gain a specialized Microsoft team that could serve as a catalyst for growth across Azure, Microsoft 365, security, and Copilot.
The timing lines up with what was already ePlus' fastest-growing segment. Managed services revenue rose 15.1% to $51.3 million in the first quarter, the segment's first quarter above $50 million, with gross profit up 11.3% on that growth. The balance sheet backs further moves like this one: cash and equivalents reached $448.9 million as of June 30, up from $410.8 million three months earlier, giving ePlus room for additional acquisitions, dividends, and buybacks. Management also pointed to record sales and a significant rise in booked and open orders, positioning the company for what it called a stronger second half.
The first quarter numbers show a company growing on top but shrinking underneath. Net earnings from continuing operations fell 5.4% to $30.3 million, adjusted EBITDA dropped 9.2% to $47.8 million, and operating income declined 9.6% to $38.8 million. Gross margin slipped to 23.3% from 23.9% a year earlier, with margin compression showing up across all three business segments rather than just one.
The professional services segment, the part of the business closest to the consulting and implementation work Daymark specializes in, fell 5.1% to $68.1 million, and its margin dropped to 36.9% from 39.2%. The product segment saw its own margin decline, to 21.0% from 21.3%, as an ongoing memory chip shortage extended lead times and delayed shipments. Terms of the Daymark transaction were not disclosed, leaving no visibility into what ePlus paid or how the deal affects near-term results.
#Microsoft #million #august #first

2 months ago
Nick Kyrgios is eligible to return to tennis after accepting a one-month ban for testing positive for cocaine.
The Australian, 31, was provisionally suspended on 4 August after a sample he submitted during the Mallorca Open in June was found to contain benzoylecgonine, a metabolite of cocaine.
Kyrgios told investigators from the International Tennis Integrity Agency (ITIA) that he used cocaine at a nightclub in Magaluf in the early hours of 20 June.
He played his first-round match at the Mallorca tournament two days later, losing in straight sets to compatriot Adam Walton.
The ITIA accepted he used cocaine outside of competition after consulting with an independent expert.
#june #itia #australian #august
2 months ago
It's not often that we use "high yield" and "tech stocks" in the same sentence. However, some of the legacy software and consulting companies have joined the league, thanks to the drawdown in their stocks amid "AI-pocalypse" fears. With artificial intelligence (AI) looking to automate coding and back-office tasks, the "man-hours" model that IT services firms rely on could be at risk. Accenture (ACN) is among the names that have been in the penalty box amid fears that AI would cause large-scale business disruption for the sector. However, such fears have eased, and legacy tech companies, which were considered net AI losers, have jumped sharply from their lows. Looking at some specific stocks, Adobe (ADBE) and Salesforce (CRM) have respectively risen 54% and 76% from their 2026 lows, while Accenture has soared 60%.
Despite the rally, Accenture still has a dividend yield of 3.4%, which is well ahead of the S&P 500 Index ($SPX) average. The company has a long history of paying dividends and started paying a semi-annual dividend in 2005, eventually transitioning to quarterly dividends beginning in 2019. It has increased its payouts every year since its initiation, with an impressive annualized growth of 11.1%. Last year, the company raised its quarterly dividend by 10.1% to $1.63 per share.
Corning vs. Applied Materials: One Stock Beat the Other by 75 Percentage Points. The Better AI Infrastructure Play Is Clear.
Nvidia Can Clearly Afford a Bigger Dividend. Why Its Payout Hasn't Grown.
Stop Missing Market Moves: Get the FREE Barchart Brief – your midday dose of stock movers, trending sectors, and actionable trade ideas, delivered right to your inbox. Sign Up Now!
#legacy

2 months ago
Dmitry Vinogradov/Getty Images
KKR has made its largest exit from its Strategic Holdings portfolio, representing a significant step towards the firm's ambition of creating a "mini Berkshire Hathaway."
The New York alternatives manager has agreed to sell USI Insurance Services, one of the largest insurance brokerage and consulting firms in the US, to Aon for around $17 billion, the firm announced on Monday.
KKR acquired the Valhalla, New York-based business in 2017 for $4.3 billion. It invested more money in 2020, 2023 and 2025, growing the company through over 90 strategic acquisitions. The exit from Aon represents a 6x return on KKR's original equity and a 3.4x return when accounting for those additional investments.
KKR co-CEO Joseph Bae drew the comparison between Strategic Holdings, which comprises stakes in 18 companies, and Warren Buffett's famous holding company in 2025, at the Bloomberg Invest conference in New York.
#strategic #largest #exit


2 months ago
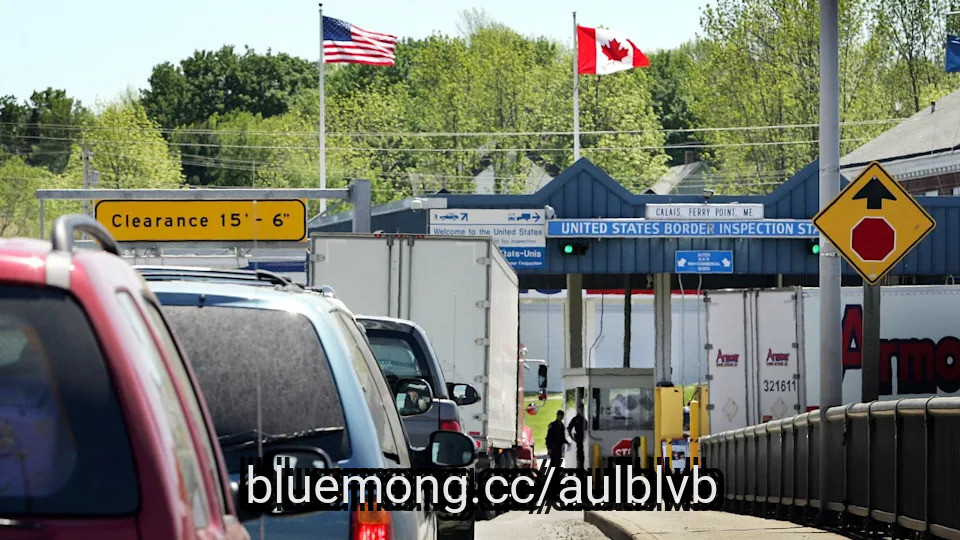
Steel and aluminum stocks surged and then retreated last week as the escalating trade war between the United States and Canada sent investors scrambling to reprice exposure to North American metals supply chains.
SLX gained 1.6% on Monday, Aug. 25, following the breakdown of U.S.-Canada trade talks, and the State Street Materials Select Sector SPDR (XLB) reached a new intraday record that session, topping the peak it had set in February. Shares of Nucor, Steel Dynamics, Cleveland-Cliffs, and Century Aluminum all climbed. The gains proved short-lived, however: by Friday's close, XLB had slipped into the red for the week and SLX was essentially unchanged, according to CNBC. Through Aug. 28, Morningstar data show SLX has gained more than 28% on the year and XLB more than 18%.
The swing reflects the complexity of a trade war between two countries whose metals industries are deeply intertwined. Dan Luttner, who serves as managing partner of the supply chain consulting firm NEOS by Argon & Company, characterized the initial stock move to CNBC as a repricing reflex rather than a durable signal. "The stock pop is a headline reflex, honestly — mills reprice to replacement cost the second a 50% wall goes up, so of course Nucor and Cleveland-Cliffs jumped," Luttner said. "But that's not the interesting question. The interesting question is who controls their feedstock inside the wall versus who's still exposed to it?"
Luttner noted that both Nucor and Cleveland-Cliffs use electric arc furnace technology whose inputs have no dependence on Canadian ore or slab, positioning them to capture tariff-driven pricing benefits without the same exposure. Cleveland-Cliffs stock is nonetheless in negative territory for 2026 because of balance sheet stress. Century Aluminum is a more complicated case: because domestic primary aluminum production is thin, the raw inputs that sustain it — alumina and semi-finished material — largely still flow across the Canadian border, undermining the protection the tariffs were meant to provide.
Atsi Sheth, chief credit officer at Moody's Ratings, said uncertainty will persist. "Expect much more of this uncertainty for some time to come," Sheth said. She added that U.S. steel companies hold a modest edge over their Canadian counterparts because the U.S. market is larger, but said the auto sector has no clear winner given how deeply integrated cross-border production is.
#cliffs #nucor
2 months ago
Dublin, Ireland-based Accenture plc (ACN) provides strategy and consulting, industry X, song, and technology and operation services. Valued at $126.6 billion by market cap, the company delivers a range of specialized capabilities and solutions to clients across all industries and operates a network of businesses providing outsourcing and alliances.
Companies worth $10 billion or more are generally described as "large-cap stocks," and ACN fits right into that category with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the information technology services industry. ACN leads in IT services with a brand known for quality and innovation. Its global reach and large workforce let it deliver broad solutions, while ongoing investment in R&D, AI, and talent development keeps offerings cutting-edge and the company a top employer, fueling long-term growth.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Wu-Tang Clan Member Raekwon Is a Palantir 'OG,' Visiting Headquarters 16 Years After Receiving His Custom PLTR Jacket
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#billion #dear #palantir #market





