3 days ago
On September 17, Lucid Group, Inc. (NASDAQ:LCID) and Bolt, a leading European shared mobility platform, announced a strategic partnership to develop and deploy autonomous mobility services across Europe. This sent shares of Lucid Group, Inc. (NASDAQ:LCID) higher, and the stock ended the trading session with gains of nearly 6%.
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership

4 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual ****** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in ****** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in ****** an also reached 67%.
The company's new ads plan also showed encouraging signs in ****** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#high

4 days ago
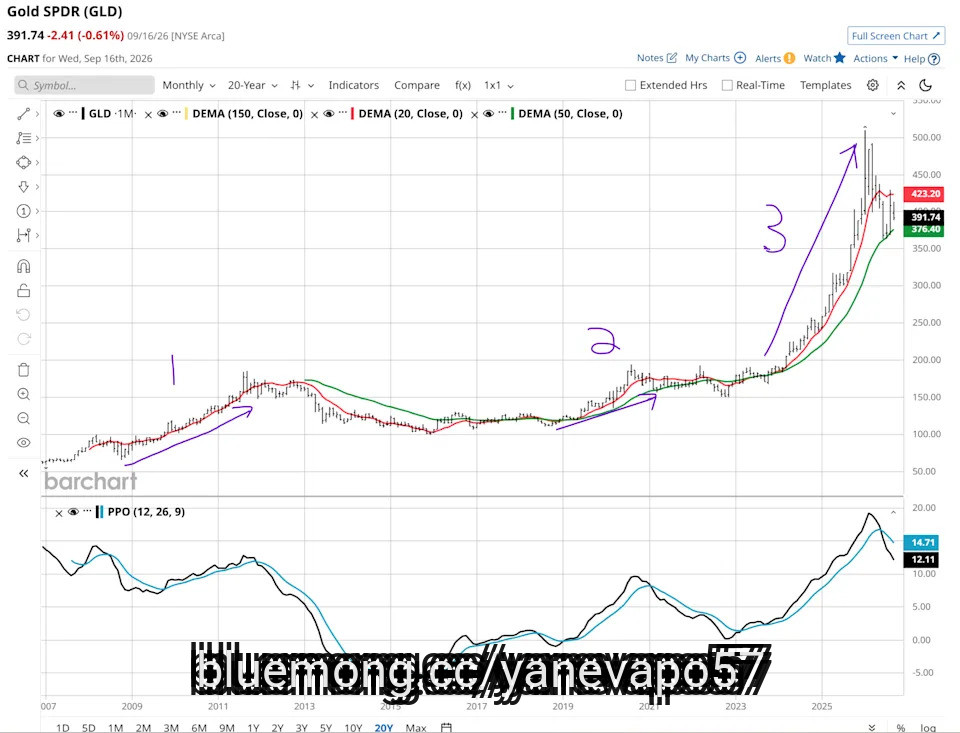
Is there any investment market segment more debated than gold (XAUUSD)? I'm not sure there is. We have "gold bugs," including those who see the yellow metal as the ***** et to own when the world goes haywire.
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief
Then, there are the "we're going back on the gold standard" types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Get exclusive insights with the FREE Barchart Brief newsletter. Subscribe now for quick, incisive midday market ***** ysis you won't find anywhere else.
Of course, there are also plenty of investors who don't really think about gold investing very much, and who will simply trade it when there's a good opportunity. I'm in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You'll need a lot of gold.
#Gold #free #barchart #brief

4 days ago
On September 9, 2026, Apple Inc. (NASDAQ:AAPL) unveiled the iPhone Duo, its first foldable smartphone and the biggest change to the iPhone's design in nearly 20 years, at the first product launch event led by new CEO John Ternus since he succeeded Tim Cook on September 1. The book-style, passport-shaped device opens into a 7.6-inch display, Apple's largest ever, starts at $1,999 for the 256-gigabyte model and rises to $3,199 for 2 terabytes of storage. This makes it the most expensive iPhone Apple has ever sold, with availability set for October 23.
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl

4 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

4 days ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


4 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

4 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer

4 days ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management

4 days ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
4 days ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
4 days ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
4 days ago
Though it's down by 33% over the last five years, Ethereum (CRYPTO: ETH) climbed from about $130 in early 2020 to over $4,800 in early November 2021, which would have been sufficient to turn an investment of $27,000 into about $1 million. It's natural for investors to wonder if another historic run is in the cards for the coin, given that it's more widely known now than it was then.
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even
Today, with a market cap of $292 billion as of Sept. 15, Ethereum can still grow your wealth substantially, but it probably won't be a millionaire maker for those with small positions anytime soon. Let's first look at the math to see why, then examine its upcoming catalysts.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Ethereum isn't going to be a millionaire-maker investment from here, even if you're willing to pony up a lot more capital than most investors have on hand or are willing to allocate to a lottery ticket, and even if it becomes the next cryptocurrency to explode.
Turning $10,000 into $1 million requires a 100x gain, which would boost Ethereum's market cap to $29.2 trillion.
#even

4 days ago
Phillips 66 (NYSE:PSX) has been on a strong rally this year, posting gains of over 110% since the beginning of 2026. The outperformance has been driven by an unusually sharp surge in global refining margins amid the war in the Middle East, which has significantly tightened the world's refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
Given Phillips 66's substantial outperformance compared to the wider market, investors may be questioning whether the stock's record-setting run has reached its peak. However, the ****** ysts over at BMO Capital see further upside ahead. On September 17, the firm raised its price target on PSX from $260 to $310, while maintaining an 'Outperform' rating on the shares. The target boost implies an upside of 13% from the current levels and even exceeds the stock's all-time high of over $274 achieved earlier this month.
BMO Capital highlighted Phillips 66's integrated business model, noting that it has gained momentum and outperformed its individual segments, supported by strong execution across the portfolio. While Refining and Renewables remain the cyclical leaders, BMO also sees a favorable medium-term growth outlook for the company's Midstream business.
BMO Capital's vote of confidence comes amid a broader optimism surrounding Phillips 66, with ****** ysts from Morgan Stanley, Raymon James, UBS, and several others also improving their respective outlooks on PSX. This suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, particularly following the renewed escalations between Iran and the United States.
The supply disruptions now extend beyond the troubled region, as a recent wave of Ukrainian attacks on Russian refineries has further reduced global refining capacity and provided further support to margins.
#further #margins #amid
4 days ago
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
4 days ago
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies

4 days ago
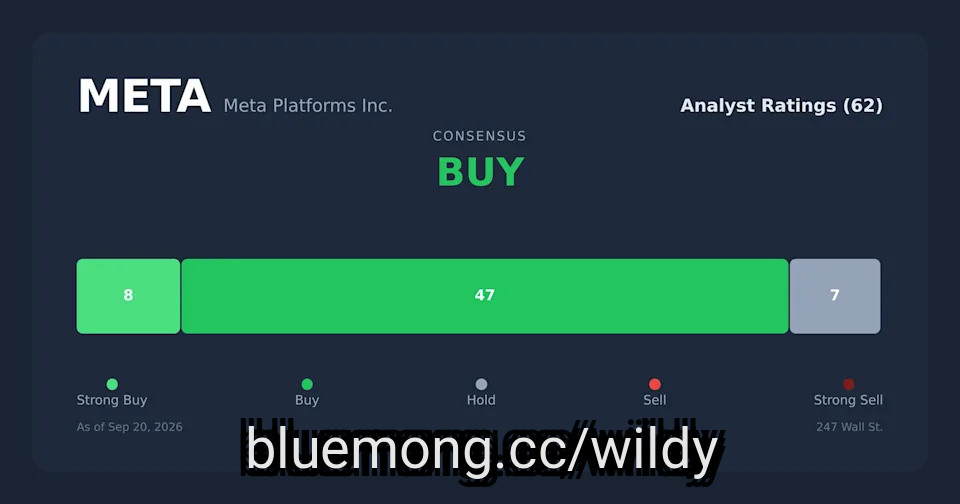
Helfstein estimates META needs 115 million paying Muse subscribers at $20/month to unlock $28 billion in AI revenue, but doubts it happens.
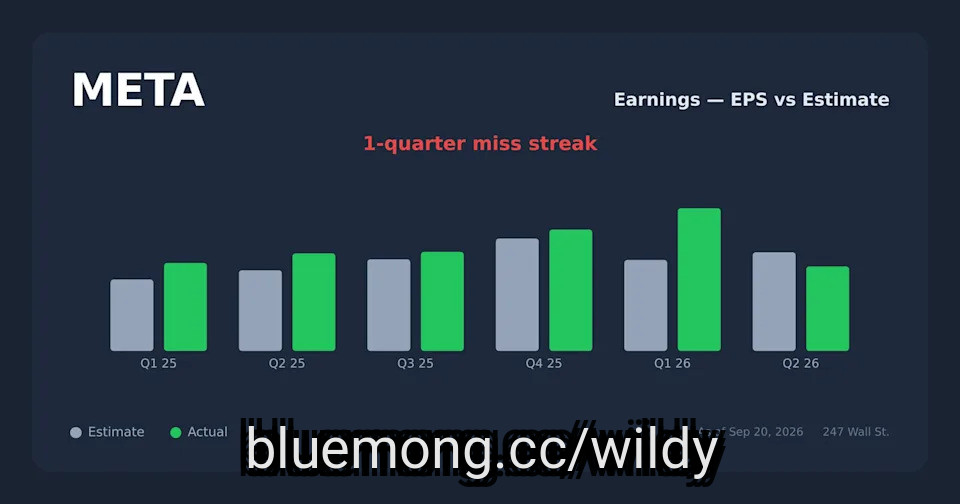
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million

4 days ago
Marathon Petroleum Corporation (NYSE:MPC) has substantially outperformed the wider market this year, supported by an unusually sharp surge in global refining margins as the prolonged Iran crisis has significantly tightened global refining capacity and reduced supplies of gasoline, diesel, and jet fuel.
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle
With Marathon up by over 150% since the beginning of 2026, there are now concerns that the stock may have topped out. However, the ****** ysts over at Morgan Stanley are convinced that the rally still has further room to run. On September 14, Morgan Stanley ****** yst Joe Laetsch significantly raised the firm's price target on MPC from $265 to $453, while reaffirming an 'Overweight' rating on the shares.
The target boost reflects an upside of over 9% from the current price level and even exceeds the stock's record high of just under $411 per share achieved earlier this month. The Morgan Stanley update comes amid broader Wall Street optimism surrounding the American refining giant, with ****** ysts from Raymon James, UBS, and several others also improving their respective outlooks on MPC.
Morgan Stanley's vote of confidence suggests that Wall Street expects the ongoing refining upcycle to last longer than previously expected, especially given the fresh wave of attacks between Washington and Tehran. Even if the conflict in the Middle East subsides, the region's refined fuel output is expected to remain relatively tight, since the damaged or idled refineries in the Middle East are likely to take some time to return to full operations.
As the largest refiner by volume in the United States, Marathon has significant operating leverage to capitalize on the current high-margin environment. The company already demonstrated its ability to translate the high crack spreads into material earnings when it delivered an almost fourfold increase in profits in the second quarter.
#morgan #marathon #stanley #middle

4 days ago
SEOUL, Sept 20 (Reuters) - North Korea launched two missiles off its eastern coast on Sunday, its second set of tests in roughly a week and days after Pyongyang accused the US of driving tensions on the Korean Peninsula through a series of military drills.
Just three hours after launching a short-range ballistic missile (SRBM) toward the East Sea on Sunday afternoon, North Korea fired another short-range ballistic missile, according to South Korea's defence ministry.
If the subsequent launch is confirmed to be a ballistic missile, it will mark two consecutive ballistic missile tests by North Korea within a three-hour window.
South Korea's Joint Chiefs of Staff said it detected the first test firing from the Wonsan area around 3 p.m. (0600 GMT), identifying the weapon as a ballistic missile. ***** an's defence ministry also said it appeared to be a ballistic missile.
Japanese public broadcaster NHK said the projectile had come down outside ***** an's exclusive economic zone.
#sunday
Just three hours after launching a short-range ballistic missile (SRBM) toward the East Sea on Sunday afternoon, North Korea fired another short-range ballistic missile, according to South Korea's defence ministry.
If the subsequent launch is confirmed to be a ballistic missile, it will mark two consecutive ballistic missile tests by North Korea within a three-hour window.
South Korea's Joint Chiefs of Staff said it detected the first test firing from the Wonsan area around 3 p.m. (0600 GMT), identifying the weapon as a ballistic missile. ***** an's defence ministry also said it appeared to be a ballistic missile.
Japanese public broadcaster NHK said the projectile had come down outside ***** an's exclusive economic zone.
#sunday


4 days ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari

4 days ago
Americans are increasingly falling victim to so-called "ghost charges": small, frictionless payment purchases at Starbucks or McDonald's, or digital subscription deductions from your bank account you forgot about. The costs may only be $5 or $10 a pop, but they add up, and before you know it, $200 has disappeared from your savings every month.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
A recent study from Cashews, a digital bank tracking platform for serial small recurring charges, shows that 61% of people have more than $50 a month in these small charges; 38.7% have more than $100 a month; and 14.5% have more than $200 a month in charges where no single charge is over $100. Additionally, three of the median person's four small recurring monthly charges go to merchants they never otherwise interact with.
#charges #digital #bank #platform
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
A recent study from Cashews, a digital bank tracking platform for serial small recurring charges, shows that 61% of people have more than $50 a month in these small charges; 38.7% have more than $100 a month; and 14.5% have more than $200 a month in charges where no single charge is over $100. Additionally, three of the median person's four small recurring monthly charges go to merchants they never otherwise interact with.
#charges #digital #bank #platform
4 days ago
On Monday, Sept. 21, Sandisk (NASDAQ:SNDK) takes a spot in the S&P 100, a subset of the S&P 500 (SNPINDEX:^GSPC) made up of 100 of its largest blue-chip companies. Dell Technologies, Palo Alto Networks, and Arista Networks enter with it. The announcement came from S&P Dow Jones Indices on Sept. 4, and the changes take effect before Monday's open.
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies
Four companies are leaving to make room: Nike (NYSE:NKE), Colgate-Palmolive, Simon Property Group, and Honeywell Aerospace.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The swap says a lot about how 2026 has gone. Sandisk shares have gained more than 600% this year, more than any other stock in the S&P 500.
Nike's stock, meanwhile, reached a 52-week low this week. And Sandisk, worth about $260 billion, is currently more than four times the size of the roughly $54 billion sportswear giant.
#sandisk #networks #four #Companies

4 days ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel


4 days ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents

4 days ago
Automattic has a new interim chief financial officer: Jeremy Klaperman, the CFO of the company's WordPress VIP Enterprise business unit. The news, shared internally on Friday, follows last week's attempted ouster of Automattic CEO Matt Mullenweg, which ultimately resulted in the departure of the board members who voted him out and other executives, including then-CFO Mark Davies. Davies was briefly interim CEO before Mullenweg retook the position.
In a Slack post, Mullenweg shared that Klaperman had previously acted as Automattic CFO when Davies had been on sabbatical. He noted that the board — whose new members have yet to be announced — will still need to evaluate internal and external candidates for the position before a final decision is made.
In addition, Mullenweg said in the post that a candidate to become the company's chief legal officer had also just verbally accepted the position, replacing Chief Legal Officer Andy Missan, who has also since left the company alongside Davies. TechCrunch recently reported that Davies and Missan had signed reciprocal severance deals during Mullenweg's 33-hour leave of absence before he returned as CEO.
"I have 100% confidence in our cash and financial position," Mullenweg's post concluded, adding "There is still work to do, but everything is within our control and depends only on Automattic's ability to execute."
In subsequent updates, Mullenweg also said to "stay tuned" for board announcements, and noted that special advisor and creator of Wolfram|Alpha, Stephen Wolfram, will continue in his position. The company's next board meeting is scheduled for September 23.
#klaperman
In a Slack post, Mullenweg shared that Klaperman had previously acted as Automattic CFO when Davies had been on sabbatical. He noted that the board — whose new members have yet to be announced — will still need to evaluate internal and external candidates for the position before a final decision is made.
In addition, Mullenweg said in the post that a candidate to become the company's chief legal officer had also just verbally accepted the position, replacing Chief Legal Officer Andy Missan, who has also since left the company alongside Davies. TechCrunch recently reported that Davies and Missan had signed reciprocal severance deals during Mullenweg's 33-hour leave of absence before he returned as CEO.
"I have 100% confidence in our cash and financial position," Mullenweg's post concluded, adding "There is still work to do, but everything is within our control and depends only on Automattic's ability to execute."
In subsequent updates, Mullenweg also said to "stay tuned" for board announcements, and noted that special advisor and creator of Wolfram|Alpha, Stephen Wolfram, will continue in his position. The company's next board meeting is scheduled for September 23.
#klaperman

4 days ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Osaic has been hit with a class action suit claiming the firm put its own profits ahead of customers in how it has handled its various cash sweep programs.
In the suit filed in Arizona federal court, Osaic customers Robin Nackman and Douglas Whittaker accused Osaic of a "dramatic underpayment of interest" to their customers, violating their "contractual, implied and/or fiduciary obligations" to the plaintiffs.
"Despite its representation to the contrary, Osaic categorically has not adjusted interest rates paid to customers based on economic or prevailing market factors, but rather has kept the sweep rates artificially depressed as to reap substantial profits for itself," the complaint read.
In the complaint, Nackman and Whittaker argue that typically, uninvested cash from customer accounts is moved (or "swept") into interest-bearing accounts, generating client returns.
#osaic #wealthmanagement #whittaker #suit
Osaic has been hit with a class action suit claiming the firm put its own profits ahead of customers in how it has handled its various cash sweep programs.
In the suit filed in Arizona federal court, Osaic customers Robin Nackman and Douglas Whittaker accused Osaic of a "dramatic underpayment of interest" to their customers, violating their "contractual, implied and/or fiduciary obligations" to the plaintiffs.
"Despite its representation to the contrary, Osaic categorically has not adjusted interest rates paid to customers based on economic or prevailing market factors, but rather has kept the sweep rates artificially depressed as to reap substantial profits for itself," the complaint read.
In the complaint, Nackman and Whittaker argue that typically, uninvested cash from customer accounts is moved (or "swept") into interest-bearing accounts, generating client returns.
#osaic #wealthmanagement #whittaker #suit


5 days ago
Volkswagen cut its 2026 operating-margin forecast to no more than 1 per cent, down from a previous range of 4 to 5.5 per cent.
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion
Approximately €10 billion in special charges includes a €6 billion non-cash impairment connected with Porsche.
Volkswagen maintained its cash-flow outlook, but the downgrade highlights deeper pressure from China, restructuring costs and lower-margin electric vehicles.
Volkswagen AG (OTC:VWAGY) shares suffered their sharpest decline in months after the German automaker warned that Porsche's deteriorating outlook and additional restructuring costs would substantially reduce its 2026 profit.
Volkswagen's preferred shares fell as much as 7.5 per cent in Frankfurt on Friday before closing 5.6 per cent lower. Shares of Porsche AG declined 3.3 per cent, while Volkswagen's largest shareholder, Porsche Automobil Holding SE, lost 4.9 per cent.
#volkswagen #Margin #billion

5 days ago
On September 14, Evercore ISI raised its price target for Netflix, Inc. (NASDAQ:NFLX) from $100 to $110 while maintaining its Outperform rating. The research firm rolled its valuation framework forward to 2028 and applied a multiple of 25 times its 2028 EPS estimate.
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore
The new price target represents more than 40% upside from the share price of $76.41 as of September 16. However, the stock has declined about 16% year-to-date and remains well below its 52-week high of $124.86.
Evercore ISI conducted its 58th quarterly US survey and 12th semi-annual **** an survey on Netflix, Inc. (NASDAQ:NFLX), which showed multi-year high penetration of 63% in the US and a record-high 22% penetration in **** an.
Japan also showed strong subscriber engagement as 58% of subscribers said they were slightly or not at all likely to cancel. Subscriber satisfaction in **** an also reached 67%.
The company's new ads plan also showed encouraging signs in **** an. About 66% of new ads plan subscribers were either former Netflix users or people who were new to Netflix.
#netflix #price #september #evercore
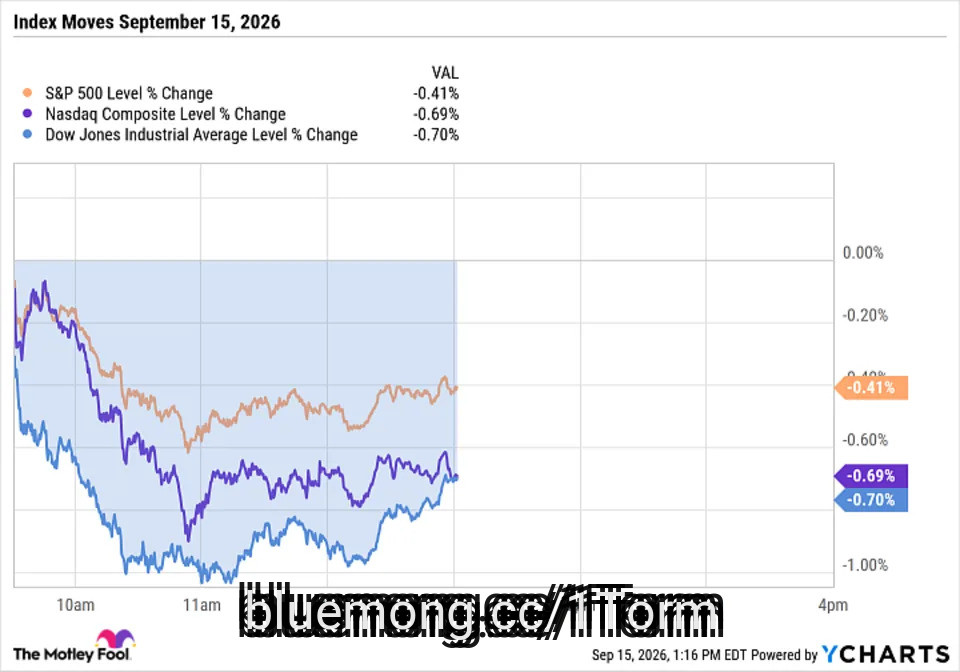


5 days ago
My husband, 59, and I, 55, are planning to retire over the next few years, and this is one of the biggest unknowns I'm struggling with. My mom had Alzheimer's disease and spent seven years in a really nice memory-care facility in a smaller town. It cost about $7,000 a month. Thankfully, my parents had purchased long-term-care insurance and had paid premiums for about 12 years.
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term
My dad died shortly after being diagnosed with cancer, so his policy was never used. But my mom's policy ended up being worth its weight in gold. It essentially covered all of her care. By the time my mother died, the insurance company had paid out almost $600,000. We only paid about $100 a month for some extras. Needless to say, that experience has made me think.
The 10-year Treasury is having its worst run in over 100 years. Why investors are buying bonds anyway.
'I'm burned out': I'm constantly helping my cousin who is running out of money. Is it too much to expect his sister to help?
I've looked into long-term-care insurance, but the premiums are so incredibly expensive, and I worry about what they'll cost by the time it makes sense for me to seriously consider a policy. We're fortunate financially. After 35 years in the corporate grind, we'll have substantial retirement savings; we've always saved carefully; and we have no debt or mortgage.
#insurance #paid #term

5 days ago
This story was originally published on Retail Dive. To receive daily news and insights, subscribe to our free daily Retail Dive newsletter.
It's been another week with far more retail news than there is time in the day. Below, we break down some things you may have missed during the week, and what we're still thinking about.
From executive shuffling in the athletics market to a truly sparkling KitchenAid stand mixer, here's our closeout for the week.
Express rides the nostalgia wave with 'Archives' menswear reissues
Express, which launched in the 1980s, peaked earlier this century and remains a mall fixture, is the latest apparel retailer to tap into consumers' affinity for nostalgia and vintage finds. The company has reissued designs first introduced in the 1990s and early 2000s, including some from its now-defunct Structure menswear brand, featuring "relaxed proportions, bold graphics, utility details and bootcut denim."
#retail #dive #express
It's been another week with far more retail news than there is time in the day. Below, we break down some things you may have missed during the week, and what we're still thinking about.
From executive shuffling in the athletics market to a truly sparkling KitchenAid stand mixer, here's our closeout for the week.
Express rides the nostalgia wave with 'Archives' menswear reissues
Express, which launched in the 1980s, peaked earlier this century and remains a mall fixture, is the latest apparel retailer to tap into consumers' affinity for nostalgia and vintage finds. The company has reissued designs first introduced in the 1990s and early 2000s, including some from its now-defunct Structure menswear brand, featuring "relaxed proportions, bold graphics, utility details and bootcut denim."
#retail #dive #express