2 hours ago
Travel credit cards offer points and miles rewards on your spending, which you can use toward travel-related redemptions, such as flights, hotel stays, and car rentals. You'll often earn the highest rewards rate on travel purchases with a travel credit card. However, many also offer boosted rewards on everyday purchases like groceries, gas, and more.
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#rewards #points #you 're
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#rewards #points #you 're



2 hours ago
Generating $2,200 monthly in dividends requires between $264,000 at a 10% yield and $754,000 at a 3.5% yield, with higher yields carrying greater principal erosion risk.
A blended portfolio of SCHD (35%), DGRO (25%), VYM (20%), and JEPI (20%) hits a 3.9% weighted yield requiring about $670,000 to reach the $2,200 target.
A 3.5% yield growing 8% annually doubles income in roughly nine years, while a flat 10% yield stays stagnant or declines if distributions are cut.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Turning zero into $2,200 a month in dividend income requires only two things: a target yield and the capital to support it. The annualized goal is $26,400, which lands somewhere between covering a mortgage payment and replacing a part-time salary. The capital needed depends entirely on the yield you choose, and the yield you choose determines how durable that income actually is.
#yield #choose #dgro
A blended portfolio of SCHD (35%), DGRO (25%), VYM (20%), and JEPI (20%) hits a 3.9% weighted yield requiring about $670,000 to reach the $2,200 target.
A 3.5% yield growing 8% annually doubles income in roughly nine years, while a flat 10% yield stays stagnant or declines if distributions are cut.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Turning zero into $2,200 a month in dividend income requires only two things: a target yield and the capital to support it. The annualized goal is $26,400, which lands somewhere between covering a mortgage payment and replacing a part-time salary. The capital needed depends entirely on the yield you choose, and the yield you choose determines how durable that income actually is.
#yield #choose #dgro


5 hours ago
Travel credit cards offer points and miles rewards on your spending, which you can use toward travel-related redemptions, such as flights, hotel stays, and car rentals. You'll often earn the highest rewards rate on travel purchases with a travel credit card. However, many also offer boosted rewards on everyday purchases like groceries, gas, and more.
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#credit #hotel #general
When you're comparing travel credit cards, it's useful to separate them into two distinct types: general travel rewards cards and co-branded airline and hotel credit cards.
With a general travel credit card, you'll have a number of flexible redemption options when you're ready to redeem your points and miles.
Travel card issuers generally have their own travel portals, like Chase Travel or American Express Travel, where you can book flights, hotels, rental cars, and more. These programs also have a number of travel transfer partners to which you can directly transfer points or miles. For example, American Express Membership Rewards points transfer to Delta SkyMiles at a rate of 1:1.
The flexibility of general travel cards means you can use your rewards to travel with different airlines or hotel brands. Each time you're ready to book, simply shop around between the portal or partners and compare the best options for your specific travel plans.
#credit #hotel #general



7 hours ago
PepsiCo (PEP) has gone nowhere for a year, down 1.8% over the past twelve months while the S&P 500 returned 16.6%. At about $135 a share it trades at 17.7 times earnings, against an S&P 500 median of 22.5. A big cash generator priced below the market is what value buyers hunt for, so is this discount impatience or a verdict?
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing
PepsiCo sells snacks and drinks everywhere consumer staples get sold: grocery aisles, convenience and gas stations, and the away-from-home locations it keeps adding. That reach turns into cash: free cash flow over the trailing twelve months was $9.28 billion, a 5.0% yield.
None of the recent numbers look like a business in trouble. Revenue over the trailing twelve months grew 5.6%, and the operating margin is holding at 15.0% against an S&P 500 median of 18.6%. Management says global volumes grew in both foods and beverages in the first half of 2026, the fastest growth in volume since 2022.
Widen the window and the picture changes. PepsiCo's revenue grew 5.6% over the trailing twelve months against an S&P 500 median of 8.3%, and its three-year average is just 2.5% a year. The trailing twelve months ran hotter, but one window is not a pace, and the pace is what the market pays for.
The company lowered prices in the U.S. early in 2026 to get volume moving. Management says salty snacks went from falling volume to rising volume and PepsiCo gained share, but volume in the second quarter of 2026 fell short of what it expected, which it blames on a consumer hurt by higher gas prices and on delays executing the price investment at some customers. None of this is lost on the market: it is pricing a company that grows slowly and has just spent money trying to grow faster. The problem sits in North America, while the international business stayed strong.
#months #trailing

12 hours ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue


14 hours ago
Invesco Aerospace & Defense ETF (NYSEMKT:PPA) offers a long track record and broad industrial exposure, while Global X Defense Tech ETF (NYSEMKT:SHLD) provides a lower-cost, technology-focused approach to the defense sector.
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach
Defense spending often stays resilient throughout various economic cycles, making aerospace and defense exchange-traded funds a popular choice for investors seeking sector-specific growth. While both funds target the same broad industry, they differ in their approach to legacy hardware versus emerging technologies and software-defined systems. This comparison looks at how the veteran PPA stacks up against the newer SHLD.
Metric
SHLD
PPA
#approach
15 hours ago
By Anna Szymanski
Sept 16 (Reuters) - An unsettled few days set the scene for the week's main event: the Federal Reserve's policy decision. Markets overwhelmingly expect a quarter-point rate hike, the central bank's first since 2023, against the backdrop of resurgent oil prices and a 10-year Treasury yield that's recently breached the important 5% mark.
A rate increase could put Fed Chair Kevin Warsh on a collision course with the White House, given President Donald Trump's continued preference for easing policy. But given all the economic data supporting calls for a hike, Warsh risks losing credibility if the central bank stays on hold.
Today's decision - and the messaging surrounding it - will be a major test for Warsh. The Fed chair struck a hawkish tone at Jackson Hole last month and, with U.S. inflation still running above target and the unemployment rate still low, policymakers risk undermining their credibility if they don't follow through and lift the benchmark rate to the 3.75%-4.00% range.
That's as Donald Trump continues to push for the U.S. to have the lowest borrowing costs in the world. The U.S. president recently threatened to stop trading with some countries if the Fed does not cut rates, though markets have not taken that threat very seriously.
#rate #markets #president #decision
Sept 16 (Reuters) - An unsettled few days set the scene for the week's main event: the Federal Reserve's policy decision. Markets overwhelmingly expect a quarter-point rate hike, the central bank's first since 2023, against the backdrop of resurgent oil prices and a 10-year Treasury yield that's recently breached the important 5% mark.
A rate increase could put Fed Chair Kevin Warsh on a collision course with the White House, given President Donald Trump's continued preference for easing policy. But given all the economic data supporting calls for a hike, Warsh risks losing credibility if the central bank stays on hold.
Today's decision - and the messaging surrounding it - will be a major test for Warsh. The Fed chair struck a hawkish tone at Jackson Hole last month and, with U.S. inflation still running above target and the unemployment rate still low, policymakers risk undermining their credibility if they don't follow through and lift the benchmark rate to the 3.75%-4.00% range.
That's as Donald Trump continues to push for the U.S. to have the lowest borrowing costs in the world. The U.S. president recently threatened to stop trading with some countries if the Fed does not cut rates, though markets have not taken that threat very seriously.
#rate #markets #president #decision


1 day ago
Applied Digital turned negative for the year after a 24% monthly slide, while peers Core Scientific and Cipher Mining each fell between 4% and 5% on Tuesday despite staying positive year to date.
The sector ETF DTCR fell just 0.6% as selling stays concentrated in leveraged buildout names, not the broader infrastructure basket.
Despite $36 billion in contracted lease value and strong Q4 results, Applied Digital's $2.7 billion debt load raises dilution risk as its share price falls.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Applied Digital's slide Tuesday afternoon matters most for what it does to the year. Applied Digital (NASDAQ:APLD) stock is down 4% to $23.72, pushing the year-to-date figure to a decline of 3%. That's a stark reversal for a name that was among the market's most favored artificial intelligence (AI) capacity plays earlier in 2026, and it caps a month in which the group has bled steadily lower.
#year #despite #date #billion
The sector ETF DTCR fell just 0.6% as selling stays concentrated in leveraged buildout names, not the broader infrastructure basket.
Despite $36 billion in contracted lease value and strong Q4 results, Applied Digital's $2.7 billion debt load raises dilution risk as its share price falls.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Applied Digital's slide Tuesday afternoon matters most for what it does to the year. Applied Digital (NASDAQ:APLD) stock is down 4% to $23.72, pushing the year-to-date figure to a decline of 3%. That's a stark reversal for a name that was among the market's most favored artificial intelligence (AI) capacity plays earlier in 2026, and it caps a month in which the group has bled steadily lower.
#year #despite #date #billion

1 day ago
Adobe (ADBE) reported a record fiscal Q3 2026 and raised its fiscal 2026 revenue and earnings targets. Revenue rose 13% as reported to $6.76 billion, above the $6.70 billion the company had guided. But the key figure that did not move is the one to hold the quarter against: the fiscal 2026 target for growth in ending annualized recurring revenue, or ARR, still 10.2%.
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
1 day ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry **** ysis delivered straight to their inbox with the free CRE Daily newsletter.
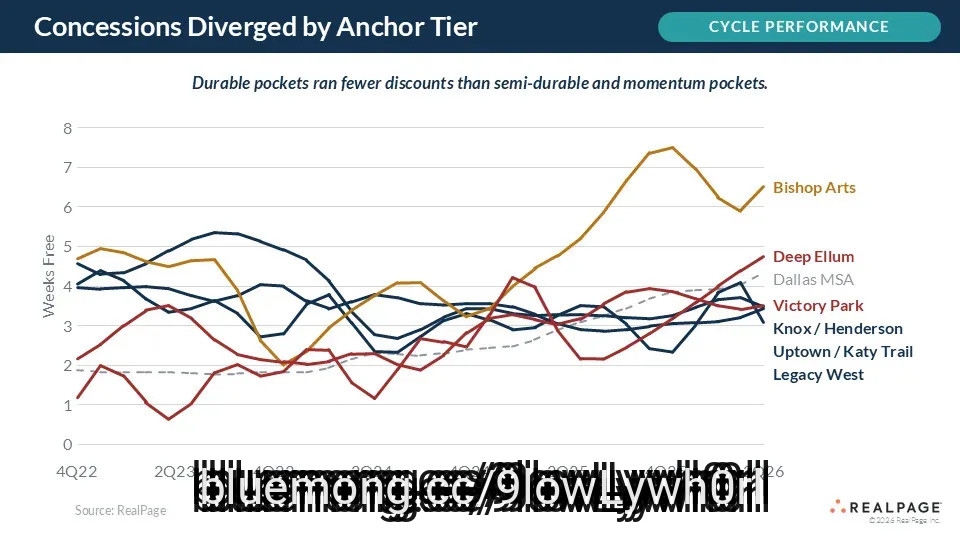
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand
Legacy West apartments average $1,845 a month, a 9% premium over comparable Dallas properties that's smaller than any other demand pocket RealPage tracks, yet the submarket needs the fewest concessions to stay leased.
The pocket posted 95.5% occupancy in the second quarter, two points above the Dallas metro average, anchored by roughly 12,000 corporate jobs from employers including Toyota, JPMorgan Chase, and Frito-Lay.
Because Legacy West's strength rests on continued corporate expansion rather than a larger price premium, its durability depends on employers in the Plano-Frisco corridor keeping up their hiring pace.
Apartments in Legacy West command the smallest rent premium of any demand pocket in the Dallas metro, yet the submarket needs fewer concessions to stay full than any of its peers, according to RealPage. The corporate-anchored district straddling the Plano-Frisco border averaged $1,845 in effective rent in the second quarter, a 9% premium over comparable metro properties. That's the smallest premium among the demand pockets RealPage tracks across Dallas, even though Legacy West's occupancy and leasing strength outperform them.
#legacy #dallas #demand


1 day ago
CrowdStrike (CRWD) stock is already having a huge 2026, but Nvidia CEO Jensen Huang just offered investors another reason to stay bullish. Speaking at a Goldman Sachs technology conference, Huang said cybersecurity could become the next major growth driver for artificial intelligence and described CrowdStrike as Nvidia's (NVDA) "number one cybersecurity partner."
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#crowdstrike #huang #goldman #become
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#crowdstrike #huang #goldman #become



1 day ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda


1 day ago
CrowdStrike (CRWD) stock is already having a huge 2026, but Nvidia CEO Jensen Huang just offered investors another reason to stay bullish. Speaking at a Goldman Sachs technology conference, Huang said cybersecurity could become the next major growth driver for artificial intelligence and described CrowdStrike as Nvidia's (NVDA) "number one cybersecurity partner."
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#become
That matters because the AI opportunity is expanding beyond chatbots and data centers. As companies deploy more AI agents, they also face a growing number of security risks. CrowdStrike is positioning its Falcon platform to capture that spending, potentially giving CRWD another growth engine after its powerful run this year.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#become


2 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue



2 days ago
Good morning. Stocks fell on Tuesday as oil prices stayed solidly above $100 per barrel ahead of the Federal Reserve's key policy meeting this week.
Brent crude futures (BZ=F) rose to $105 per barrel, raising concerns about persistent inflation.
The 10-year Treasury (^TNX) rose as high as 5.04%, its highest level since 2007, after breaching the 5% threshold on Monday.
Investors expect Fed policymakers to raise rates on Wednesday following their two-day policy meeting.
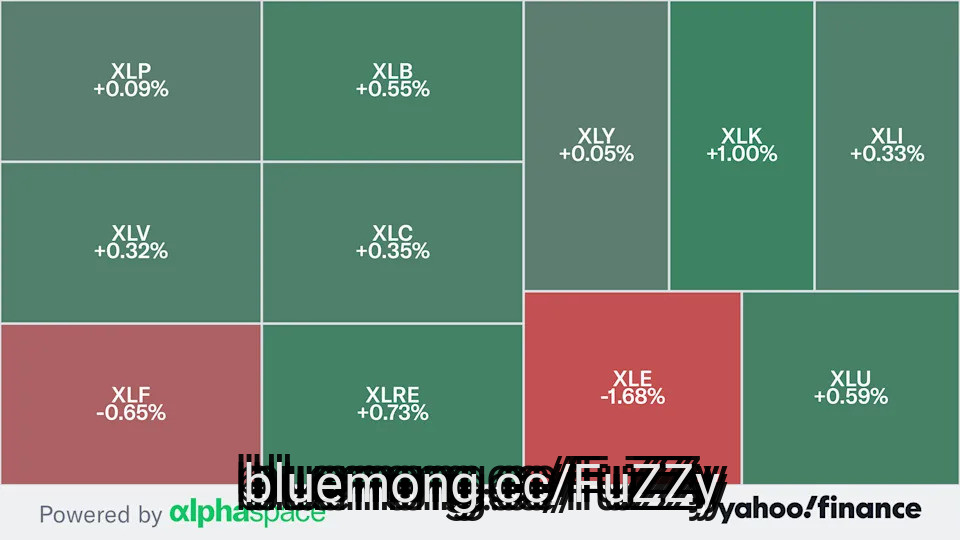
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
#meeting #brent
Brent crude futures (BZ=F) rose to $105 per barrel, raising concerns about persistent inflation.
The 10-year Treasury (^TNX) rose as high as 5.04%, its highest level since 2007, after breaching the 5% threshold on Monday.
Investors expect Fed policymakers to raise rates on Wednesday following their two-day policy meeting.
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
#meeting #brent

2 days ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal


2 days ago
Good morning. Stocks were mixed on Wednesday as oil prices eased but stayed solidly above $100 per barrel ahead of the Federal Reserve's key interest rate decision due this afternoon.
Brent crude futures (BZ=F) dropped to $107 per barrel, and the 10-year Treasury (^TNX) fell below 5%.
Investors overwhelmingly expect the Fed to raise rates by 25 basis points on Wednesday following its two-day policy meeting.
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
Tech stocks (XLK) gained as shares of chip heavyweight (NVDA) rose more than 1%. SK Hynix (SKHY) stock also jumped 3% following a report that the memory maker is exploring a deal with Intel (INTC).
#treasury #finance
Brent crude futures (BZ=F) dropped to $107 per barrel, and the 10-year Treasury (^TNX) fell below 5%.
Investors overwhelmingly expect the Fed to raise rates by 25 basis points on Wednesday following its two-day policy meeting.
Here's a check of the markets in the first few minutes of trading, based on a heat map powered by Yahoo Finance AlphaSpace data.
Tech stocks (XLK) gained as shares of chip heavyweight (NVDA) rose more than 1%. SK Hynix (SKHY) stock also jumped 3% following a report that the memory maker is exploring a deal with Intel (INTC).
#treasury #finance

3 days ago
Starbucks Corporation (NASDAQ:SBUX) is betting $1 billion that leather armchairs, rugs, and bookshelves can turn a recovering coffee business into a more profitable one. The company plans to upgrade as many as 9,000 North American stores into warmer, more comfortable **** es designed to bring back customers who stopped treating Starbucks as a place to sit and stay. The strategy arrives as CEO Brian Niccol's turnaround gains traction, but investors still need to see whether higher traffic can translate into stronger margins.
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions
Pixabay/Public Domain
The store upgrades are part of Niccol's broader "Back to Starbucks" strategy, which has already helped reverse a prolonged sales slump. Global comparable-store sales increased 7.9% in the latest quarter, with transactions up 4.2% and average ticket up 3.5%. U.S. comparable sales also rose 7.9%, indicating that the recovery is being driven by more than higher prices.
Starbucks Corporation (NASDAQ:SBUX) is spending roughly $150,000 per store on the new uplifts, far below the cost of previous renovations, and the work can generally be completed overnight without closing stores. The company expects about 1,500 upgrades to be finished by the end of September and ultimately wants to reach 8,000 to 9,000 company-operated North American locations.
That matters because Starbucks Corporation (NASDAQ:SBUX) has gradually become optimized for transactions rather than lingering. Mobile orders now account for roughly one-third of U.S. transactions, more than twice their share in 2019. The new design is therefore an attempt to restore the "third place" concept without abandoning the convenience that has become central to the business.
#corporation #NASDAQ #sales #transactions

3 days ago
AMD and Intel compete for processor customers, but they have a common interest in making developers comfortable staying with x86. A September 2 GCC commit added initial support for their AI Compute Extensions, or ACE, bringing that shared strategy into a widely used compiler's development code.
For Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC), the potential payoff is broader software adoption. The immediate event is much narrower: compiler infrastructure, followed by instruction-support commits. It is not evidence that compatible processors have shipped or that GCC 17 is a finished release.
The x86 Ecosystem Advisory Group's April whitepaper describes a common matrix-acceleration architecture shaped by both companies. Matrix multiplication is central to many AI workloads. A shared instruction interface could reduce the effort needed to target those operations across future processors.
That matters commercially because buyers consider the software work required to use hardware, alongside its price and performance. If developers can support both suppliers more easily, a processor purchase may depend more on execution and less on maintaining separate software paths.
For Advanced Micro Devices, Inc. (NASDAQ:AMD), the bull case is an easier route for compatible future CPUs into AI-related workloads. The risk is that a shared standard also improves the rival's appeal. Compiler support alone cannot demonstrate AMD's eventual performance advantage, customer adoption or incremental profit.
#Intel
For Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC), the potential payoff is broader software adoption. The immediate event is much narrower: compiler infrastructure, followed by instruction-support commits. It is not evidence that compatible processors have shipped or that GCC 17 is a finished release.
The x86 Ecosystem Advisory Group's April whitepaper describes a common matrix-acceleration architecture shaped by both companies. Matrix multiplication is central to many AI workloads. A shared instruction interface could reduce the effort needed to target those operations across future processors.
That matters commercially because buyers consider the software work required to use hardware, alongside its price and performance. If developers can support both suppliers more easily, a processor purchase may depend more on execution and less on maintaining separate software paths.
For Advanced Micro Devices, Inc. (NASDAQ:AMD), the bull case is an easier route for compatible future CPUs into AI-related workloads. The risk is that a shared standard also improves the rival's appeal. Compiler support alone cannot demonstrate AMD's eventual performance advantage, customer adoption or incremental profit.
#Intel


3 days ago
FC Barcelona have begun the process of renewing defender Gerard Martín's contract, per multiple reports. The 24-year-old footballer has risen through the ranks and become an important part of manager Hansi Flick's set-up.
Barça are said to be looking to tie him up for longer, with a bigger release clause and a higher salary. There is reportedly no hurry on either side, as he has a contract until 2028. There is a sense of optimism surrounding the negotations, as the team is happy with his performances and the player wants to stay.
Barça reportedly see him continuing to be a key part of the squad and possibly even improving as time goes on. A Barcelona native, Martín was a product of UE Cornellà's academy before going to Barcelona's B team. Reports say he's happy to stay with his hometown club.
So far, there have been no concrete negotiations or even a set date for a meeting on the matter. All that has been reported are preliminary conversations.
A left-back by training, he has broken through as a center-back under Flick. With Ronald Araujo on loan to Liverpool FC, Barça are set to use Martín often this season alongside Pau Cubarsí. There was talk of a potential center-back signing, though none came. Andreas Christensen has split duties as the other center-back to start this season. Barça also has Eric Garcia, though he often plays as a full-back.
#back #Barcelona #part #team
Barça are said to be looking to tie him up for longer, with a bigger release clause and a higher salary. There is reportedly no hurry on either side, as he has a contract until 2028. There is a sense of optimism surrounding the negotations, as the team is happy with his performances and the player wants to stay.
Barça reportedly see him continuing to be a key part of the squad and possibly even improving as time goes on. A Barcelona native, Martín was a product of UE Cornellà's academy before going to Barcelona's B team. Reports say he's happy to stay with his hometown club.
So far, there have been no concrete negotiations or even a set date for a meeting on the matter. All that has been reported are preliminary conversations.
A left-back by training, he has broken through as a center-back under Flick. With Ronald Araujo on loan to Liverpool FC, Barça are set to use Martín often this season alongside Pau Cubarsí. There was talk of a potential center-back signing, though none came. Andreas Christensen has split duties as the other center-back to start this season. Barça also has Eric Garcia, though he often plays as a full-back.
#back #Barcelona #part #team


3 days ago
The heavyweight division will have to move on without Tom Aspinall for now. The Englishman recently announced that he is vacating the 265lbs **** le after another incident caused further damage to his right eye. Aspinall has been sidelined for nearly a year after suffering a double eye poke at the hands of Ciryl Gane at UFC 321.
He was diagnosed with the rare bilateral traumatic Brown's syndrome and has since undergone triple eye surgery. Eddie Hearn recently revealed that Aspinall needed more time for additional tests before he could be considered 100% healthy. However, the prolonged recovery timeline became increasingly frustrating.
The former champion took to Instagram and penned a lengthy post explaining the circumstances behind his decision. Shortly after, Josh Hokit seized the opportunity to stake his claim to the now-vacant **** le.
The 10-0 heavyweight had recently rejected Alex Pereira's call for a rematch with Gane, who currently holds the interim **** le. Instead, Hokit pitched two blockbuster headliners for UFC 334 later this year, with himself facing Gane for the heavyweight gold and Pereira taking on Sergei Pavlovich.
Now that Aspinall has vacated the belt, Gane is seemingly expected to be upgraded to undisputed champion. However, staying true to his original plan, Hokit has doubled down on facing the Frenchman for the championship next.
#aspinall #heavyweight #year
He was diagnosed with the rare bilateral traumatic Brown's syndrome and has since undergone triple eye surgery. Eddie Hearn recently revealed that Aspinall needed more time for additional tests before he could be considered 100% healthy. However, the prolonged recovery timeline became increasingly frustrating.
The former champion took to Instagram and penned a lengthy post explaining the circumstances behind his decision. Shortly after, Josh Hokit seized the opportunity to stake his claim to the now-vacant **** le.
The 10-0 heavyweight had recently rejected Alex Pereira's call for a rematch with Gane, who currently holds the interim **** le. Instead, Hokit pitched two blockbuster headliners for UFC 334 later this year, with himself facing Gane for the heavyweight gold and Pereira taking on Sergei Pavlovich.
Now that Aspinall has vacated the belt, Gane is seemingly expected to be upgraded to undisputed champion. However, staying true to his original plan, Hokit has doubled down on facing the Frenchman for the championship next.
#aspinall #heavyweight #year



3 days ago
(NewsNation) — Two days into their first term at a school in the United Kingdom, Prince Archie and Princess Lilibet are already switching schools due to security concerns.
A spokesperson for the Duke and ***** ss of Sussex told People Magazine that the children were being removed from the school in the Cotswolds over security concerns that were unknown until the term began.
Those concerns included heavy traffic in the area, the distance between the school and the family's home, and that the concern was heightened after an incident that, ***** o magazine reports, "made it difficult for their vehicles to stay in convoy."
Meghan to head back to the US in 5 weeks for 'work'
"The parents remain extremely grateful to all the teachers and staff for the love, care and effort they have shown their family," the spokesperson said. "This decision should in no way be interpreted as a reflection on the school or the exceptional care the children have received there."
#security #spokesperson
A spokesperson for the Duke and ***** ss of Sussex told People Magazine that the children were being removed from the school in the Cotswolds over security concerns that were unknown until the term began.
Those concerns included heavy traffic in the area, the distance between the school and the family's home, and that the concern was heightened after an incident that, ***** o magazine reports, "made it difficult for their vehicles to stay in convoy."
Meghan to head back to the US in 5 weeks for 'work'
"The parents remain extremely grateful to all the teachers and staff for the love, care and effort they have shown their family," the spokesperson said. "This decision should in no way be interpreted as a reflection on the school or the exceptional care the children have received there."
#security #spokesperson


3 days ago
CLEVELAND (AP) — Tristan Peters fouled off 12 pitches in an 18-pitch at-bat that keyed Chicago's six-run outburst in the sixth inning and the White Sox beat the Cleveland Guardians 7-3 on Monday night to stay atop the AL Central.
Kyle Teel hit a two-run double and Miguel Vargas connected for a two-run homer following Peters' lengthy plate appearance — the longest in MLB this season, and tied for the third longest since 2000.
The White Sox, who lost 102 games and finished last in 2025, won the opener of the showdown series to push their lead over the Guardians to 1 1/2 games. Chicago has led the division since July 4.
Sean Burke (9-7) didn't allow an earned run in five innings and Chicago's bullpen kept the Guardians in check as the White Sox improved to 7-4 against Cleveland to clinch the season series and tiebreaker.
The Guardians altered their rotation so Gavin Williams (13-8) could start the opener, and the right-hander gave them five solid innings. They needed six.
#cleveland #opener
Kyle Teel hit a two-run double and Miguel Vargas connected for a two-run homer following Peters' lengthy plate appearance — the longest in MLB this season, and tied for the third longest since 2000.
The White Sox, who lost 102 games and finished last in 2025, won the opener of the showdown series to push their lead over the Guardians to 1 1/2 games. Chicago has led the division since July 4.
Sean Burke (9-7) didn't allow an earned run in five innings and Chicago's bullpen kept the Guardians in check as the White Sox improved to 7-4 against Cleveland to clinch the season series and tiebreaker.
The Guardians altered their rotation so Gavin Williams (13-8) could start the opener, and the right-hander gave them five solid innings. They needed six.
#cleveland #opener



3 days ago
Rookie defensive back Mansoor Delane is questionable to return to the Kansas City Chiefs' Week 1 matchup against the Denver Broncos on 'Monday Night Football' after sustaining a shoulder injury in the first quarter of the primetime tilt.
Delane joined Kansas City as the No. 6 overall pick in the first round of the 2026 NFL Draft and recorded his first career interception in front of a national audience on the game's first drive, which gave the Chiefs an early advantage over Denver.
The Chiefs shared an official update on Delane's status in a post to their official Twitter account:
While it remains unclear if Delane will be able to return to the field in Week 1, Chiefs defensive coordinator Steve Spagnuolo is already adjusting his scheme to account for the former LSU Tiger's absence.
Stay tuned to find out if Delane's absence will prove to be temporary, or if the rookie defender will need to miss games due to his shoulder injury.
#kansas #city #rookie #defensive
Delane joined Kansas City as the No. 6 overall pick in the first round of the 2026 NFL Draft and recorded his first career interception in front of a national audience on the game's first drive, which gave the Chiefs an early advantage over Denver.
The Chiefs shared an official update on Delane's status in a post to their official Twitter account:
While it remains unclear if Delane will be able to return to the field in Week 1, Chiefs defensive coordinator Steve Spagnuolo is already adjusting his scheme to account for the former LSU Tiger's absence.
Stay tuned to find out if Delane's absence will prove to be temporary, or if the rookie defender will need to miss games due to his shoulder injury.
#kansas #city #rookie #defensive


3 days ago
Drew Brees reportedly came close to Philip Rivers-like comeback with Broncos originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
Philip Rivers' unretirement shocked the NFL in 2025, but it was a last-ditch effort by the Colts just to salvage their season and get to the playoffs.
According to a report from ESPN's Adam Schefter, Drew Brees — who retired the same offseason as Rivers did — nearly rocked the league with his own stunning decision in the middle of the playoffs.
Brees even put himself through a workout to see if he could physically give it a shot, but he ultimately decided to stay retired. The Saints legend was elected to the Pro Football Hall of Fame just weeks later.
Here's what you need to know about Brees' near-comeback.
#brees #comeback
Philip Rivers' unretirement shocked the NFL in 2025, but it was a last-ditch effort by the Colts just to salvage their season and get to the playoffs.
According to a report from ESPN's Adam Schefter, Drew Brees — who retired the same offseason as Rivers did — nearly rocked the league with his own stunning decision in the middle of the playoffs.
Brees even put himself through a workout to see if he could physically give it a shot, but he ultimately decided to stay retired. The Saints legend was elected to the Pro Football Hall of Fame just weeks later.
Here's what you need to know about Brees' near-comeback.
#brees #comeback



3 days ago
Changing jobs is looking lucrative again.
Base pay for job changers in the private sector increased 4.7% in August, compared to 3% for job stayers, according to the latest report from payroll provider ADP.
When you consider gross pay, which includes tips, commissions, and bonuses, wages for job stayers rose 4.4% year over year, while gross pay for job changers increased substantially more: 7.3%.
In another recent report, the job-jumping news was just as promising.
The median pay increase for workers switching jobs rose to 5% last month from 4.4% in July, according to new data from the Atlanta Fed. For those who stay put, the average pay increase was 3.6%, the same as in July.
#Jobs #rose
Base pay for job changers in the private sector increased 4.7% in August, compared to 3% for job stayers, according to the latest report from payroll provider ADP.
When you consider gross pay, which includes tips, commissions, and bonuses, wages for job stayers rose 4.4% year over year, while gross pay for job changers increased substantially more: 7.3%.
In another recent report, the job-jumping news was just as promising.
The median pay increase for workers switching jobs rose to 5% last month from 4.4% in July, according to new data from the Atlanta Fed. For those who stay put, the average pay increase was 3.6%, the same as in July.
#Jobs #rose

3 days ago
Three and a half years of freight recession did two things to the truck financing market at once. It shredded the credit profiles of the carriers who most needed to borrow. It also pushed a large share of the lenders who would have lent to them out of the sector. Both are now rationing the equipment replacement cycle the industry has spent two years waiting on.
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large


3 days ago
ONE Bantamweight Kickboxing World Champion Jonathan "The General" Haggerty had a ringside view of his brother Freddie Haggerty's toughest ****** ignment yet, and he could not have been happier with how it played out.
The younger Haggerty overcame Rungruanglek TN Muaythai via unanimous decision in their strawweight Muay Thai battle at The Inner Circle 30 in Bangkok's Lumpinee Stadium this past Friday, September 11.
Freddie dropped Rungruanglek twice across the opening two rounds, first with a counter left hook off the ropes, then with a follow-up left hook to the temple off an exit from the clinch.
Rungruanglek tried to weather the storm with digging elbows and working Freddie's legs, but the 21-year-old Englishman stayed composed on the back foot, picking the Thai knockout artist apart with sharp counters until the final bell.
The unanimous decision snapped Rungruanglek's five-fight winning streak and pushed Freddie's record to 25-5 overall, marking his second straight victory of 2026 on the subscriber-exclusive Asia primetime card.
#unanimous #decision #hook #kickboxing
The younger Haggerty overcame Rungruanglek TN Muaythai via unanimous decision in their strawweight Muay Thai battle at The Inner Circle 30 in Bangkok's Lumpinee Stadium this past Friday, September 11.
Freddie dropped Rungruanglek twice across the opening two rounds, first with a counter left hook off the ropes, then with a follow-up left hook to the temple off an exit from the clinch.
Rungruanglek tried to weather the storm with digging elbows and working Freddie's legs, but the 21-year-old Englishman stayed composed on the back foot, picking the Thai knockout artist apart with sharp counters until the final bell.
The unanimous decision snapped Rungruanglek's five-fight winning streak and pushed Freddie's record to 25-5 overall, marking his second straight victory of 2026 on the subscriber-exclusive Asia primetime card.
#unanimous #decision #hook #kickboxing
4 days ago
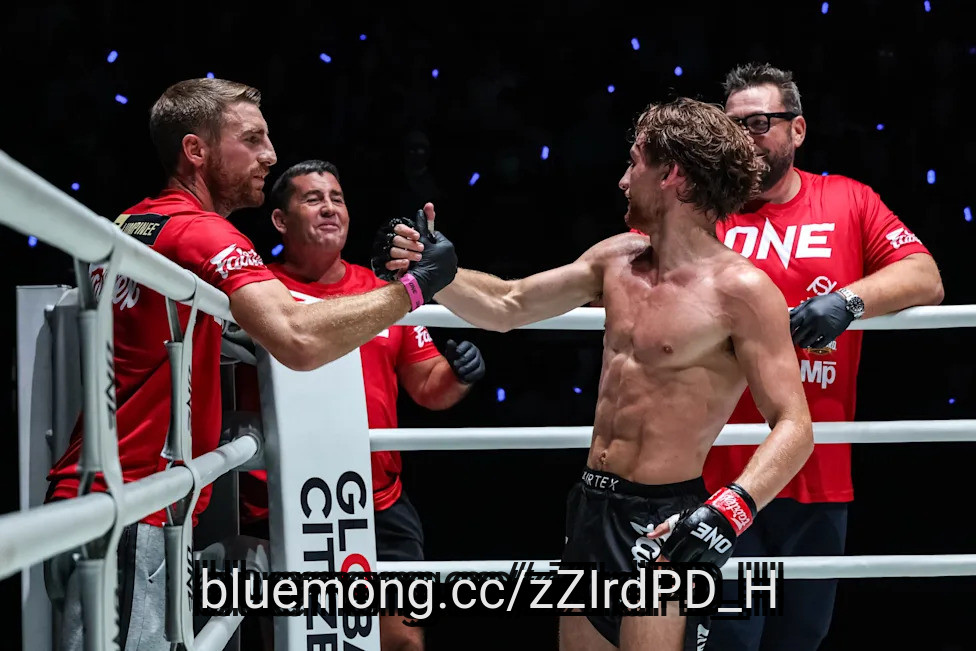
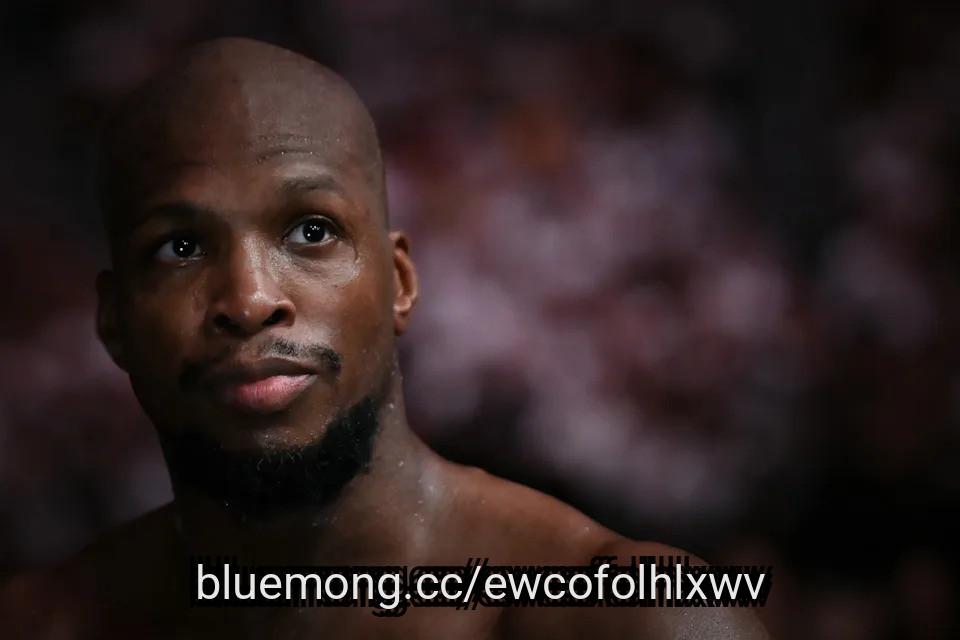
Michael Page won significantly more times than he lost in the UFC, yet it still wasn't enough to sway the promotion to keep him around after his contract expired.
The former Bellator superstar entered the UFC with plenty of fanfare in 2024, scoring a clear-cut unanimous decision win against Kevin Holland at UFC 299. Page, 39, styled on Holland in vintage fashion, utilizing his flashy striking skills to outpoint the veteran in a welterweight showdown. As it turned out, though, finishes — or even similarly entertaining performances — failed to materialize in Page's subsequent five UFC appearances.
Despite winning four straight fights, capped off by his fight against Nursulton Ruziboev at UFC Paris, the promotion opted not to re-sign Page without even having a discussion.
Speaking on Monday's edition of "The Ariel Helwani Show," Page vented his frustrations, saying he felt disrespected by the entire close to his UFC run.
"I had goals to achieve, so regardless of anything, I was winning my fights, which says to me you get to stay," Page told Uncrowned. "That's the premise of this game. Success should breed more opportunities. So, I still felt like we'd sit down at the table.
#holland #winning #fights
The former Bellator superstar entered the UFC with plenty of fanfare in 2024, scoring a clear-cut unanimous decision win against Kevin Holland at UFC 299. Page, 39, styled on Holland in vintage fashion, utilizing his flashy striking skills to outpoint the veteran in a welterweight showdown. As it turned out, though, finishes — or even similarly entertaining performances — failed to materialize in Page's subsequent five UFC appearances.
Despite winning four straight fights, capped off by his fight against Nursulton Ruziboev at UFC Paris, the promotion opted not to re-sign Page without even having a discussion.
Speaking on Monday's edition of "The Ariel Helwani Show," Page vented his frustrations, saying he felt disrespected by the entire close to his UFC run.
"I had goals to achieve, so regardless of anything, I was winning my fights, which says to me you get to stay," Page told Uncrowned. "That's the premise of this game. Success should breed more opportunities. So, I still felt like we'd sit down at the table.
#holland #winning #fights
4 days ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen