8 days ago
Pfizer (NYSE: PFE) is offering a dividend yield of roughly 6% today. That is well above the roughly 1% yield on offer from the S&P 500 index (SNPINDEX: ^GSPC) and the 1.4% average yield of pharmaceutical stocks. There are good reasons for the negative view of Pfizer, but investors may be ignoring the company's over 100-year history of success. Here's why you may want to consider buying this out-of-favor dividend stock while others are fearful.
Pfizer's stock rocketed higher during the coronavirus pandemic, as investors myopically focused on the company's COVID vaccine. When COVID turned out to be a less serious long-term threat than originally believed, Wall Street dumped Pfizer. At this point, the stock is down more than 50% from its 2021 high. That is a big part of the story behind the high yield.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
However, there's another piece that is more fundamental to the pharmaceutical industry. Like all drug makers, Pfizer's drugs receive time-limited patent protections. When patents expire, generic versions of the medications can be produced. That generally leads to a dramatic decline in revenue from Pfizer's drugs. Right now, Pfizer is facing down some notable patent expirations. This is a completely normal dynamic in the pharmaceutical sector.
Patent expirations are why drug companies are always on the lookout for new drugs. The problem is that patent expirations follow a set schedule, but drug development does not. Pfizer's drug pipeline isn't producing major new drugs right now, and it looks like it may have to work through a period in which new drugs won't fully offset revenue lost to patent expirations. This isn't uncommon, either, but investors are likely focusing on the short term rather than the long term when it comes to Pfizer.
#patent #yield #drug #expirations

9 days ago
Realty Income (NYSE: O) buyers who entered at the 2013 acquisition milestone turned $1,000 into $2,444, a 144% total return through October 2026.
Buying when Realty Income joined the Dividend Aristocrats in 2020 at $54.21 left investors with just 0.07% total return after six years, as dividends failed to offset share price decline.
Prestige-driven entries consistently underperformed, while the best recent result came after shares already fell, with the 2024 Spirit Realty entry returning 13%.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Realty Income (NYSE:O) built its reputation on reliable monthly income. (Seven of our favorite monthly payers are rounded up in this free report.) Among the key milestones discussed here, its first two were excellent entry points; the three that followed were poor ones. Each return below runs from the milestone's adjusted price to the October 6, 2026, close of $54.25, adjusted for splits and dividends.
#income #october #dividends #price

10 days ago
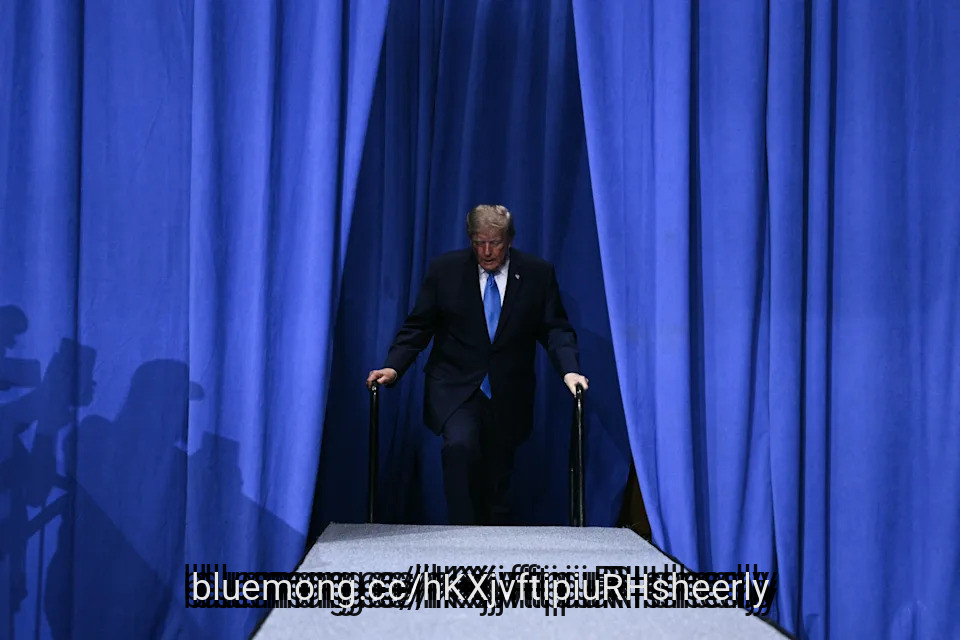
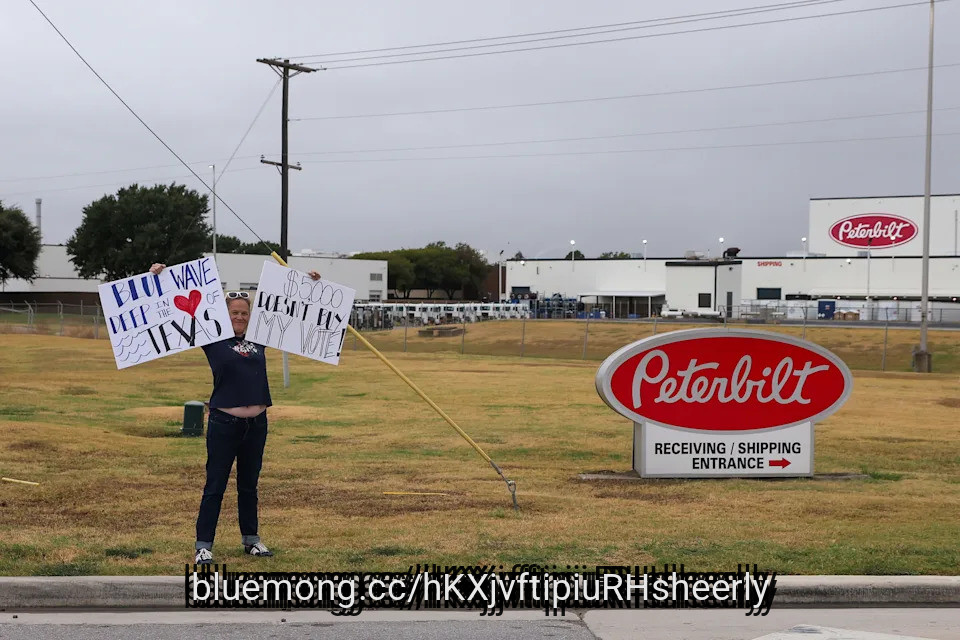
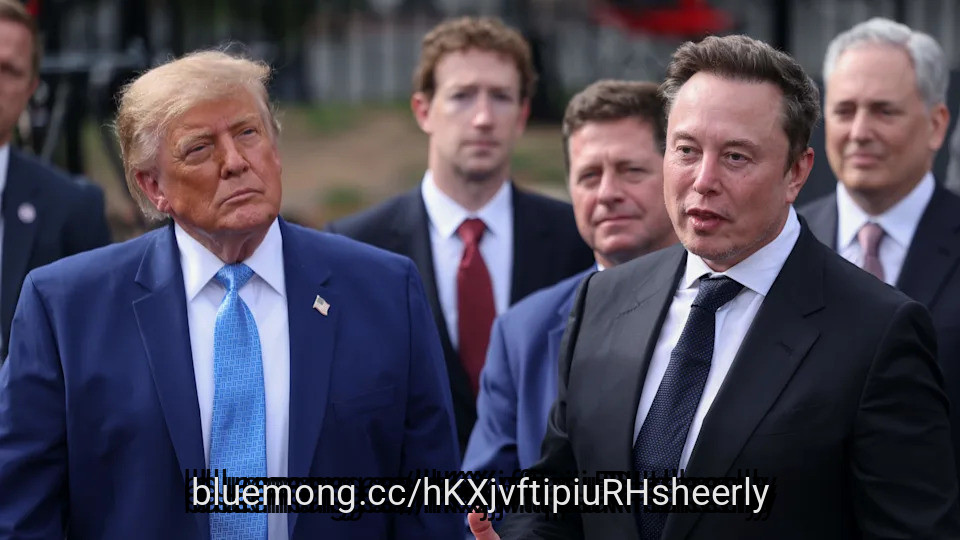
Giving out checks to Americans has emerged as one of President Trump's major messages in the final weeks of the campaign season.
But Americans are skeptical, as multiple polls show voters harbor serious doubts about whether Trump will deliver and whether the cost would hurt the economy.
The president is nevertheless determined to escalate the issue with 29 days until the midterm elections. This past weekend, he mentioned checks at every campaign stop and made a new pledge to send $90 to millions of seniors enrolled in Medicare Part B.
The payment is intended to offset October Medicare premiums and will be deposited this month, but Trump emphasized that it will come in the form of cash.
"Over 20 million seniors on Medicare will soon be receiving a deposit of nearly $100 directly into their bank accounts," he announced on Truth Social. "You'll get your money almost immediately."
#medicare #Trump #whether #part
10 days ago
Burry is mitigating near-term tax selling in underperforming holdings.
The investor foresees an early end to the artificial intelligence boom, positioning for a 2000–2003 style value equity revival.
Significant capital is being directed into discounted Chinese equities like BYD, while maintaining a cautious stance on Alibaba amidst its infrastructure spending.
Renowned value investor Michael Burry outlined his fourth-quarter portfolio maneuvers in an update on his Cassandra Unchained Substack platform on Monday, revealing how he is positioning around tax-loss harvesting headwinds while building long-term exposure to deeply discounted sectors.
Burry noted that the final quarter routinely brings heightened selling pressure on underperforming equities as investors sell underperforming ***** ets at a loss to offset capital gains.
#burry #positioning #capital #equities
11 days ago
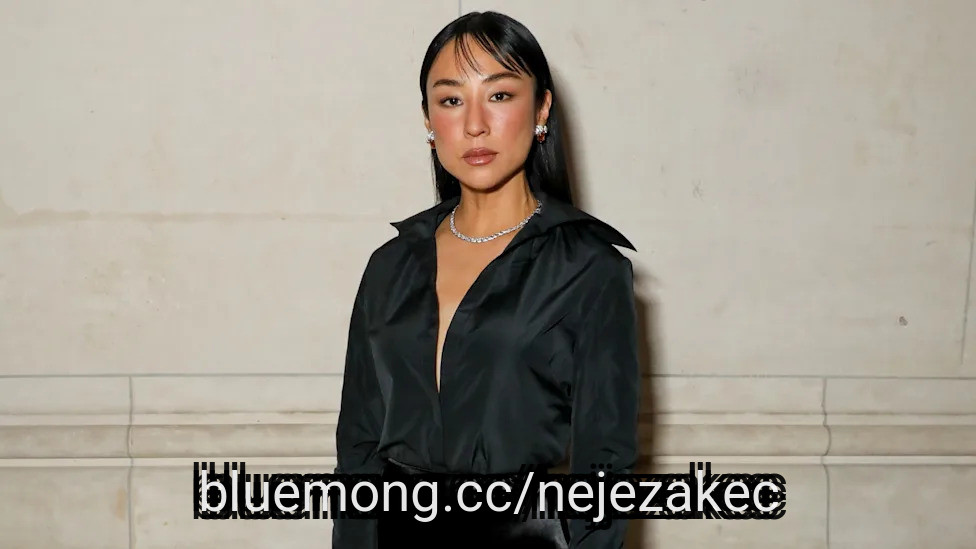
Greta Lee stripped everything back this week while in Paris, stepping out for a dinner in a Jil Sander two-piece ensemble.
On Monday (September 28), the Morning Show actor turned up to Tiffany & Co.'s Jean Schlumberger dinner at the Musée des Arts Décoratifs in a monochrome fit that left people doing a double take.
The black satin pencil skirt and a silky ***** on-down shirt, designed by Jil Sander creative director Simone Bellotti, was deliberately quiet and cut back so the jewelry could carry the evening.
As or the bling, Lee wore the Bird on a Rock by Tiffany & Co. Wings pavé necklace in platinum set with diamonds, high jewelry offset against the flat black of the Jil Sander separates.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#tiffany #greta
12 days ago
By Kanishka Singh
WASHINGTON, Oct 2 (Reuters) - President Donald Trump said the US government will send a one-time $90 payment to more than 20 million Americans enrolled in Medicare, a health insurance program for the elderly, to help offset the cost of their monthly medical insurance premiums.
Trump said on social media late on Friday the payments will come from the Medicare Improvement Fund, which he said was given $2 billion by Congress to improve the Medicare fee-for-service program.
The announcement is the latest in a series of financial promises the Republican leader has made to voters heading into the November midterm elections where control of Congress is at stake.
Trump's Republican Party currently has a narrow majority in both the Senate and the House of Representatives but his approval rating has been low over his handling of the high cost of living for Americans during the US-Israeli war on Iran that has spiked oil and gas prices.
#americans #insurance #program #singh


25 days ago
On September 17, Lucid Group, Inc. (NASDAQ:LCID) and Bolt, a leading European shared mobility platform, announced a strategic partnership to develop and deploy autonomous mobility services across Europe. This sent shares of Lucid Group, Inc. (NASDAQ:LCID) higher, and the stock ended the trading session with gains of nearly 6%.
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership
25 days ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
25 days ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

25 days ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral

25 days ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
25 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

25 days ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ

25 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
25 days ago
Transocean Ltd. (NYSE:RIG) received a boost on September 15 when the company announced that it had secured an approximately $80 million contract for its Deepwater Conqueror ultra-deepwater drillship in Equatorial Guinea. The estimated 170-day campaign with an undisclosed operator is expected to begin next year, directly following the rig's current contract in the US Gulf.
Built in 2016, the DSME 12000-design Deepwater Conqueror can operate in water depths of up to 12,000 feet and drill to a maximum depth of 40,000 feet.
The $80 million award provides Transocean with additional contract revenue and improves visibility into the company's future revenue base. If the award includes attractive day rates and limited mobilization costs, it could contribute positively to operating margins and cash flows. The company's backlog stood at approximately $6.7 billion as of August 5, 2026.
The contract could also improve the utilization of its high-value drilling rig. Since ultra-deepwater rigs require substantial investment, securing work for an idle or underutilized rig could help spread fixed operating costs over a larger revenue base. Deepwater Conqueror will move directly from its US Gulf contract to Equatorial Guinea, avoiding a gap between the two programs.
The latest award also provides Transocean with an alternative destination for its rigs. The company had already signaled in its Q2 earnings call that the growing demand for new deepwater contracts in Africa would also help offset a decline in awards in the US Gulf.
#deepwater #contract #gulf #equatorial
27 days ago
AGNC Investment (NASDAQ: AGNC) completed its IPO in May 2008 at $20 per share. Today, shares of the mortgage REIT trade at around $10 per share, a staggering 50% below their IPO price.
However, the company's monthly dividends have more than offset the slump in its share price. AGNC has paid out over $50 per share in ****** ulative dividends since its IPO, more than double its IPO price. With dividends reinvested, it has significantly outperformed mortgage REITs and other financial stocks since its IPO.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
AGNC Investment's founders formed it in the depths of the financial crisis, seeing an opportunity to create a leading Agency MBS (mortgage-backed securities guaranteed against credit losses by government agencies like Fannie Mae). It invests in Agency MBS on a leveraged basis, primarily through repurchase agreements, and uses dynamic risk management strategies to navigate market risks, including interest rate changes.
The company has had to maneuver around several market cycles, unexpected events, and market volatility over the years, which have weighed on its investment returns and earnings. AGNC Investment has still managed to significantly expand its Agency MBS portfolio (it reached $97.2 billion at the end of the second quarter), financed primarily by selling stock. As a result, its shares outstanding have risen a staggering 7,660% since its IPO. This combination of earnings volatility and dilution is why its share prices have fallen 50% since the IPO.
#since #agency #dividends


27 days ago
Interested in HCA Healthcare, Inc.? Here are five stocks we like better.
Exchange-related pressure is weighing on HCA's 2026 outlook: The expiration of enhanced tax credits is pushing some patients into uninsured status, with estimated full-year impact of $1 billion to $1.2 billion and slower elective-care utilization.
State supplemental payments and underlying demand provide offsets: HCA expects a $300 million to $500 million net benefit from state programs, while insured business excluding exchange plans grew 3.2% and adjusted admissions increased 2.7% in the second quarter.
HCA is pursuing long-term growth through capacity and efficiency investments: The company is expanding outpatient facilities, improving patient throughput and cost management, and maintaining a target of 4% to 6% long-term revenue growth with stable margins.
Healthcare Added 35,200 Jobs—3 Stocks Positioned to Benefit
#healthcare #Growth

27 days ago
On September 16, Evolution Petroleum Corporation (NYSEAMERICAN:EPM) held its fiscal fourth-quarter and full-year 2026 earnings call, and the numbers told a story of a company climbing out of a rough patch. Revenue jumped 20% sequentially to $24.2 million as oil prices realized before hedge settlements shot up 49% year over year to $90.74 a barrel. Adjusted EBITDA more than doubled to $6.5 million. After a bruising third quarter, the fourth quarter finally looked like the recovery management had promised investors back in May.
The fourth-quarter turnaround wasn't just about crude. NGL prices realized $32.49 a barrel, up 27% year over year, and because Evolution leaves its NGL production entirely unhedged, every dollar of that gain flowed straight through. That combination of higher liquids pricing, growing production, and the roll-off of a prior-period transportation adjustment at the Delhi Field pushed operating cash flow to $6.8 million in the quarter, nearly double the $3.5 million generated in the third quarter.
Behind the quarterly numbers sits a longer-term shift in how Evolution makes money. The company closed a roughly $16 million acquisition of mineral and royalty acreage in the Permian's Midland Basin after the fiscal year ended, adding about 3,420 net royalty acres and more than 200 barrels of oil equivalent per day of current production, all without Evolution spending a dime on development. That mirrors what's already happening in the SCOOP/STACK play, where fourth-quarter production climbed 14% year over year to 1,275 BOE per day while unit operating costs fell to $10.33 a barrel. Evolution also replaced more than 100% of the 2.6 million barrels of oil equivalent it produced during the year, ending fiscal 2026 with 27.2 million barrels of proved reserves, an outcome that matters directly to a dividend now in its 52nd consecutive quarter.
Not every part of the business bounced back. Average daily production fell 4% year over year to 6,901 barrels of oil equivalent per day, largely because the flush production from new Chaveroo wells that boosted last year's fourth quarter has since tapered off. Natural gas pricing remained the softest spot in the portfolio, especially at the Jonah Field, where CEO Kelly Loyd said "regional differentials have weighed on realizations" even as broader demand for gas keeps growing. CFO Ryan Stash noted that stronger oil and NGL results helped offset "continued weakness in natural gas realizations, particularly at Jonah."
#barrel

27 days ago
On September 8, 2026, CNBC reported that Novartis AG (NYSE:NVS) shares fell about 10% after the company said its experimental drug del-desiran failed to meet its primary goal in a late-stage trial for myotonic dystrophy type 1.
It marked the company's third clinical setback in a week following the earlier failure of cardiovascular drug pelacarsen and a separate pause of eight trials of cell therapy rap-cel after three patient deaths. The decline erased roughly 24 billion Swiss francs, or about $29.6 billion, in market value and put Novartis on pace for one of its worst trading days in company history.
Remibrutinib provides a major remaining pipeline catalyst since Novartis AG (NYSE:NVS) reported successful late-stage results for remibrutinib in multiple sclerosis. It gives investors a credible growth driver after the failures of pelacarsen and del-desiran. The business expects more remibrutinib data later this year, making the drug an important test of whether its remaining pipeline can help long-term growth.
Novartis still expects 5% to 6% annual sales growth through 2030. Management reaffirmed its full-year financial guidance and maintained its target for 5% to 6% compound annual sales growth from 2025 through 2030. That guidance shows the company still expects its overall portfolio and remaining pipeline ******* ets to offset pressure from aging drugs.
The company retains a diversified commercial portfolio. The del-desiran failure removes a potentially important future revenue contributor, but Novartis still makes substantial revenue from its existing medicines. It also retains other pipeline ******* ets. That diversification gives the firm financial capacity to absorb individual clinical failures while it rebuilds investor confidence in its growth pipeline.
#company #remibrutinib
27 days ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source

27 days ago
Virtus Investment Partners, Inc. (NYSE:VRTS) reported on September 11 that preliminary ****** ets under management, or AUM, totaled $147.501 billion at August-end, compared with $148.874 billion at July-end. That represents a $1.373 billion decline, or approximately 0.9%.
Management identified net outflows in institutional accounts, retail separate accounts, U.S. retail funds and global funds, partly offset by positive flows into exchange-traded funds, or ETFs, and tender-offer funds.
Positive market performance partly offset net outflows. The $1.373 billion AUM decline therefore differs from net client withdrawals, which the announcement did not quantify. The underlying business question is whether products attracting new money can become large enough to stabilize the revenue base.
Virtus Investment Partners, Inc. (NYSE:VRTS) has identifiable sources of customer demand. Positive net flows into ETFs and tender-offer funds provide a route toward a more balanced product mix.
ETF demand also appeared in the second quarter, when these products attracted $0.3 billion of net inflows. August's positive flows suggest the opportunity extends beyond a single reporting period.
#virtus #investment #partners
28 days ago
A $200,000 sale of MSFT held since 1995 generates a large capital gain that Section 213 nursing home deductions can largely erase on the same return.
Selling Dad's stock and paying his care costs must land on the same tax return; splitting them across two returns eliminates the deduction entirely.
Stock held since 1995 qualifies for a stepped-up basis at death, wiping the gain tax-free for heirs. Selling it makes sense only when Section 213 fully covers the cost.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
If your parent entered a nursing home this year and you sold a long-held stock position to cover the bills, Internal Revenue Code section 213 can quietly absorb most or all of the capital gain. A family can sell $200,000 of Microsoft (NASDAQ:MSFT) stock held since 1995, realize a large embedded gain, and end the year owing surprisingly little federal tax. The same fact pattern, structured slightly wrong, produces a full tax bill with no offset.
#since #same #large

28 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated
28 days ago
On August 4, Westlake Corporation (NYSE:WLK) reported second-quarter results that erased two consecutive quarterly losses in a single swing. Net income landed at $260 million, or $2.01 per share, compared with a $169 million loss just three months earlier and a $142 million loss a year ago. EBITDA nearly tripled from the second quarter of 2025. The numbers mark a sharp reversal for a company whose chemicals business had been bleeding red ink.
The turnaround centers on Performance and Essential Materials, the segment that makes chlorovinyls and other basic chemicals. PEM swung from a $318 million operating loss in the second quarter of 2025 to $185 million in income this quarter, while EBITDA excluding identified items jumped from a 3% margin to 21%. The driver was pricing: average sales prices across PEM rose 14% year over year, more than offsetting a 3% price decline in the Housing and Infrastructure Products segment. Combined with a 7% increase in companywide sales volume, excluding the effects of plant shutdowns and an acquisition, the pricing recovery pushed companywide EBITDA to $679 million from $210 million a year earlier.
Westlake is also working the balance sheet alongside the market recovery. The company reduced debt by $500 million during the quarter and returned $99 million to shareholders through dividends and share repurchases. Management says its three-pillar profitability improvement plan remains on track to deliver a $600 million operating income benefit, a target that, if it holds, would layer structural cost savings on top of whatever the market gives back in pricing.
Not every part of the story improved together. Housing and Infrastructure Products, the segment tied to home construction and building products, saw its EBITDA margin slip to 22% from 24% a year earlier, even as volume rose 6% excluding the ACI acquisition. Average sales prices in that segment fell 3% year over year, a sign that pricing power in housing products has softened even as the company sells more of it.
The improvement in the core chemicals business also leans heavily on price rather than volume. PEM's turnaround came from a 14% jump in average sales price, a figure that can move in either direction with commodity cycles. The first quarter of 2026 was a reminder of how quickly conditions shift: Westlake posted a $169 million net loss just three months before this result, weighed down by $85 million in identified items, including a $67 million charge to settle litigation over PVC pipe and fittings and $18 million tied to facility shutdowns. A year earlier, in the second quarter of 2025, the company absorbed another $130 million in shutdown-related charges. Restructuring and legal charges showed up in two of the last three reported quarters.
#million #year #quarter #loss

28 days ago
AARP projects a 3.6% Social Security COLA for 2027, adding roughly $75 monthly to the average check, while the Senior Citizens League forecasts 3.5%.
The official COLA drops October 14, but the Medicare Part B premium that offsets it won't be announced until November, leaving budgeters with incomplete data.
Hold-harmless rules protect most retirees from net payment cuts, but higher-income enrollees facing IRMAA surcharges and newly enrolled Medicare recipients get no such protection.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
The projected Social Security raise for 2027 is the biggest in years, and it is also a moving target, according to recent reports. In the same week, two of the most closely watched forecasters revised their estimates in opposite directions. Neither is official, and the actual number will not be announced until October; the Medicare premium that determines how much of the raise reaches a retiree's bank account will not be announced until November. Anyone budgeting today is working with half the picture.
#medicare #announced #november
28 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management is deliberately shifting the business model toward a more diversified energy company by balancing legacy long-life non-operated ******* ets with high-margin mineral and royalty interests.
The fourth quarter recovery was driven by the roll-off of temporary operational items, increased production, and improved operating costs per barrel, which more than doubled adjusted EBITDA sequentially.
Portfolio resilience was demonstrated by stronger liquids pricing and improved operations offsetting persistent natural gas pricing headwinds and regional differentials.
The company maintains a 'steady as she goes' outlook for oil demand while anticipating long-term natural gas demand growth from LNG expansion and data center power needs.
#company #improved #demand #NVIDIA


29 days ago
Interested in 3M Company? Here are five stocks we like better.
3M says it is ahead of its 2027 targets, citing 5.4% second-quarter organic growth, higher margins, improved execution and on-time, in-full delivery rising to about 90%.
Data centers are a major growth priority. Its expanded beam optics technology has been standardized by Microsoft Azure, is being evaluated by five other hyperscalers, and could address a market approaching $2 billion within the next two years.
Innovation and cost reductions are supporting the outlook: 3M plans more than 350 new-product launches this year, is consolidating factories, expects to offset $150 million–$175 million in oil-related costs through pricing, and is tracking above its 25% operating-margin goal for next year.
3 Stocks Whose Charts May Be Signaling the Next Big Move
#company

29 days ago
Inquiring about Walmart Inc. (NASDAQ:WMT) on September 10, a caller asked if they should "keep it." Mad Money host Jim Cramer replied:
I got to tell you, this one is a short and long-term, okay? Short-term, I think I know what Walmart's doing. I think that they're letting their customers have a big break. They're not passing along all of these costs. That is going to earn them tremendous love when things get better. So the wise situation is to say this: Walmart trades at 36 times earnings. It deserves to trade lower just because of what's happening at the company now and higher what's happening at the company when this inflation bout ends. So you buy some at $106, $105, and then buy some at $95. And yes, it could trade to $95. It does not have yield support. This is not like Target, which had that yield support. Target's doing better than Walmart right now. It is.
Walmart Inc.'s (NASDAQ:WMT) second-quarter fiscal 2027 revenue rose 5.9% year over year to $187.9 billion, while global e-commerce sales increased 23%. Global advertising revenue rose 38%, and membership-fee revenue increased 17% globally. Walmart U.S. comparable sales, excluding fuel, grew 2.6%. The company is also using tariff refunds to support lower prices. It said tariff refunds increased its gross profit rate during the quarter, while price investments partially offset the benefit.
Target Corporation (NYSE:TGT) has stronger recent comparable-sales momentum. Its second-quarter sales rose 5.3%, comparable sales increased 3.8%, and traffic rose 3.6%. The company also raised its full-year sales-growth outlook to approximately 5%. Its second-quarter GAAP and adjusted EPS were $4.11, including a $1.65 benefit from tariff refunds. Excluding tariff refunds, GAAP and adjusted EPS increased 20% year over year. CEO Michael Fiddelke said Target had reduced prices on more than 10,000 frequently purchased items over the past year and acknowledged that "there's still meaningful work ahead."
Walmart Inc.'s (NASDAQ:WMT) biggest risk is valuation. Its premium forward PE of 36.76 leaves the stock more exposed if U.S. comparable-sales growth remains modest while the company continues investing in prices. Walmart's 2.6% U.S. comparable-sales growth also trails Target's 3.8%.
#increased #rose
29 days ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
29 days ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year