

18 hours ago
The Jacksonville Jaguars are hosting a month-long celebration for Hispanic Heritage Month throughout September, launching community outreach programs and student-athlete recognition under the banner "Somos DUUUVAL."
The initiative addresses the growth of the Hispanic and Latino community in Northeast Florida through youth sports, literacy outreach, and leadership initiatives.
Adriel Rocha, the Jaguars vice president of community impact and youth development, emphasized the initiative's focus on community service and culture. "Hispanic Heritage Month is a reminder of the rich culture, contributions and leadership of the Hispanic community and through Somos DUUUVAL, the Jaguars strive to celebrate and strengthen that spirit in Jacksonville," Rocha said. "Through a month-long series of initiatives for the Hispanic community, we are harnessing the power of service to strengthen connections and make a lasting difference in this community."
As part of the initiative, Jaguars PREP, the foundation's youth programming branch, partnered with Ticketmaster and Farah & Farah to host two youth football camps focused on athletics and leadership skills.
Nearly 350 students in third through fifth grades at BridgePrep Academy and Englewood Elementary School are participating.
#hispanic #month #heritage #somos
The initiative addresses the growth of the Hispanic and Latino community in Northeast Florida through youth sports, literacy outreach, and leadership initiatives.
Adriel Rocha, the Jaguars vice president of community impact and youth development, emphasized the initiative's focus on community service and culture. "Hispanic Heritage Month is a reminder of the rich culture, contributions and leadership of the Hispanic community and through Somos DUUUVAL, the Jaguars strive to celebrate and strengthen that spirit in Jacksonville," Rocha said. "Through a month-long series of initiatives for the Hispanic community, we are harnessing the power of service to strengthen connections and make a lasting difference in this community."
As part of the initiative, Jaguars PREP, the foundation's youth programming branch, partnered with Ticketmaster and Farah & Farah to host two youth football camps focused on athletics and leadership skills.
Nearly 350 students in third through fifth grades at BridgePrep Academy and Englewood Elementary School are participating.
#hispanic #month #heritage #somos


22 hours ago
On August 10, Red Violet Inc. (NASDAQ:RDVT) reported second-quarter 2026 results for the period ended June 30 that showed the company converting growth into profit at an accelerating clip. Revenue rose 23% to $26.7 million, and net income nearly doubled to $5 million. For a company built on selling identity intelligence to businesses, watching net margin move from 12% to 19% says that growth is not costing more to produce.
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million
Gross profit climbed 29% to $20.2 million, pushing gross margin to 76% from 72%, while adjusted EBITDA jumped 48% to $11.2 million as its margin widened to 42% from 35%. Adjusted net income rose 58% to $7.2 million. Cash generation told the same story: operating cash flow increased 42% to a record $10.6 million for the quarter. None of that came from adding customers who barely move the needle. Red Violet signed on 447 new IDI customers in the quarter, a company record, ending with 10,869 customers on the platform.
FOREWARN, its product built for real estate agents, picked up 25,493 new users to reach 443,173, and 660 REALTOR ****** ociations across the country are now under contract to use it. The company also closed an underwritten public offering in August that sold 1,916,667 shares, including 250,000 shares from the underwriters' full exercise of their option, generating net proceeds of about $109.0 million. Between the funds already on hand and this new raise, Red Violet says it holds over $160 million in cash and carries no debt, money earmarked for working capital and possible acquisitions.
CEO Derek Dubner called it what he described as "the strongest pipeline of strategic initiatives" in the company's history. The company also repurchased 74,500 shares by June 30, paying $41.87 per share on average, and had $15.5 million left on its buyback authorization.
The August offering that padded Red Violet's cash balance also added 1,916,667 new shares to the count, arriving in the same year that per-share profit is climbing fastest. Diluted earnings came in a penny below basic at $0.34, and adjusted diluted earnings landed at $0.50 versus $0.51 on a basic basis, a gap new shares will only widen going forward. There is also a timing tension worth sitting with: Red Violet spent part of the quarter buying back its own stock at an average of $41.87 a share, then turned around weeks later and sold new shares to the public.
#million

1 day ago
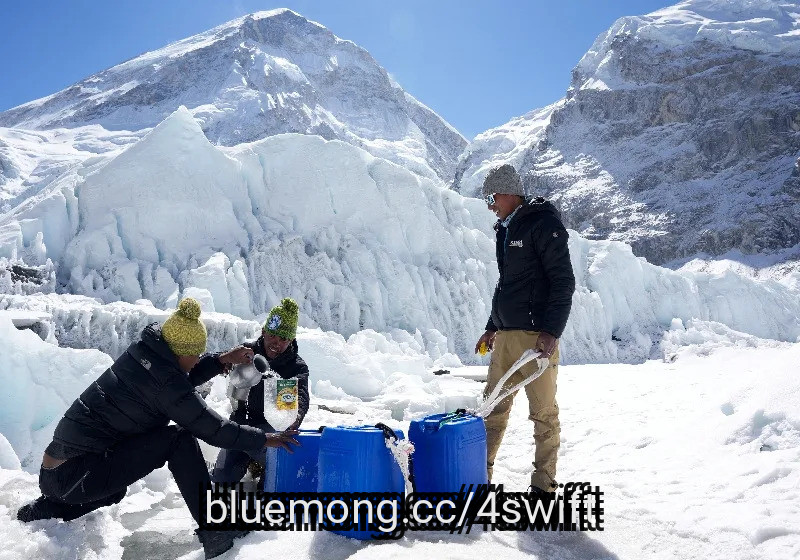
HONG KONG, Sept 14 (Reuters) - The Himalayas are approaching a tipping point as glaciers melt faster than a decade ago, threatening water security as the region approaches "peak water" by mid-century, according to a study released this month.
The findings come after the collapse of a Himalayan glacier in late August along the Nepal-Tibet border, which caused cascading landslides and flash floods in the valleys below. At least 1,300 people have been confirmed dead and more than 5,300 are missing across Nepal and China's Tibet region.
As glaciers retreat, they are leaving behind unstable glacial lakes held back by little more than loose rock and ice, above valleys where millions of people live, the study found.
The study was produced by Systemiq, a sustainability advisory firm, together with the Integrated Mountain Initiative, the International Centre for Integrated Mountain Development, and India's G.B. Pant National Institute of Himalayan Environment.
Himalayan glacier mass loss had accelerated in recent decades, while only 21 glaciers were currently monitored on the ground out of an estimated 40,000 glaciers across the Hindu Kush-Himalaya region, a vast mountain system spanning eight countries from Afghanistan to Myanmar, the study found.
#mountain #region #nepal
The findings come after the collapse of a Himalayan glacier in late August along the Nepal-Tibet border, which caused cascading landslides and flash floods in the valleys below. At least 1,300 people have been confirmed dead and more than 5,300 are missing across Nepal and China's Tibet region.
As glaciers retreat, they are leaving behind unstable glacial lakes held back by little more than loose rock and ice, above valleys where millions of people live, the study found.
The study was produced by Systemiq, a sustainability advisory firm, together with the Integrated Mountain Initiative, the International Centre for Integrated Mountain Development, and India's G.B. Pant National Institute of Himalayan Environment.
Himalayan glacier mass loss had accelerated in recent decades, while only 21 glaciers were currently monitored on the ground out of an estimated 40,000 glaciers across the Hindu Kush-Himalaya region, a vast mountain system spanning eight countries from Afghanistan to Myanmar, the study found.
#mountain #region #nepal


1 day ago
Walmart Inc. (NASDAQ:WMT) is expanding its restaurant-delivery business through a partnership with Papa John's, allowing customers in select U.S. markets to order pizzas, sides, and desserts through Walmart's app and website. The service is expected to launch this fall before expanding to thousands of participating Papa John's locations nationwide. Customers will be able to order restaurant food either separately or alongside Walmart groceries and household products, with Walmart's delivery network handling fulfillment.
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment


3 days ago
NVIDIA Corporation (NASDAQ:NVDA) is expanding its global AI infrastructure ambitions, with Australia emerging as an important new market for its growing portfolio of GPUs, CPUs, networking products, and AI software.
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian
On September 9, it announced strategic partnerships with Australian NVIDIA Cloud Partners (NCPs) and AI infrastructure providers as it works with local partners toward an AI infrastructure buildout of up to 2 gigawatts by 2027.
The initiative will expand the availability of land, power, and data center shell capacity designed to host multiple generations of Nvidia's DSX AI factory infrastructure. While the buildout is designed to meet Australia's growing demand for AI computing, it could also create a significant new source of demand for Nvidia's hardware and software ecosystem.
The Australian buildout could benefit NVIDIA Corporation (NASDAQ:NVDA) beyond the initial sale of GPUs. Nvidia will provide its DSX platform, accelerated computing, networking, software, and ecosystem support to the emerging network of AI factories. DSX is also compatible with Nvidia's CUDA ecosystem.
As enterprises, universities, government agencies, and startups increasingly build AI workloads around Nvidia's architecture, the company could strengthen CUDA's position as the underlying software platform for AI development and deployment.
#NASDAQ #australian

3 days ago
As continuous inflation squeezes household budgets, the discount retail sector should potentially benefit across the board, with middle- and lower-income consumers looking for value driving foot traffic into value chains. That's roughly what happened in the second-quarter reports from Dollar General Corporation (NYSE:DG) and Dollar Tree, Inc. (NASDAQ:DLTR), both of which were released in late August. Both retailers outperformed expectations, though only one company's stock was rewarded for this.
Dollar General Corporation (NYSE:DG) reported second-quarter results on August 27 that exceeded expectations, and shares rose more than 6.5% in premarket trading. Net sales increased 5.2% to $11.29 billion, surpassing the $11.2 billion market forecast, while diluted EPS came in at $2.48, up 33.3% year-over-year and well above the $2.01 ******* ysts projected. Same-store sales increased 3.5%, driven by a 2.0% increase in customer traffic and a 1.5% increase in average transaction amount, marking the fifth consecutive quarter of traffic growth and the sixth consecutive quarter of positive comps across all four merchandise categories.
Management improved their full-year estimate across the board: same-store sales growth is now expected to be 2.5% to 2.9%, up from 2.2% to 2.7% before, while full-year EPS guidance increased to $7.80-$8.00 from $7.20-$7.45. Tariff refunds, a lower LIFO provision, and improved shrink and damages helped increase the gross margin by 127 basis points to 32.6%. CEO Todd Vasos also pointed to continued market share gains from higher-income households switching away from traditional grocers, a trend the company has cited for several quarters, with management announcing plans to resume up to $700 million in share buybacks in the latter half of the year, backed by remodels under its Project Renovate and Project Elevate initiatives.
Dollar Tree's results, released on August 27, indicate a more complicated situation. Diluted EPS came in at $2.70, including a $1.31-per-share net benefit related to tariff refunds, while revenue increased 7% year-over-year to $4.89 billion. Comparable store sales up 3.7%, driven by a 3.3% gain in average ticket and a 0.4% increase in traffic, a return to positive traffic that occurred a full quarter ahead of management's internal plan.
However, the headline figure includes an important caveat: $1.31 of the $2.70 in EPS came from the net impact of $383 million in IEEPA tariff refunds after related reinvestment spending, duties, and taxes. Strip that out, and underlying EPS was $1.39, above the $1.00-$1.15 range management had guided to in May and about 23% above the $1.13 consensus estimate.
#TRAFFIC
Dollar General Corporation (NYSE:DG) reported second-quarter results on August 27 that exceeded expectations, and shares rose more than 6.5% in premarket trading. Net sales increased 5.2% to $11.29 billion, surpassing the $11.2 billion market forecast, while diluted EPS came in at $2.48, up 33.3% year-over-year and well above the $2.01 ******* ysts projected. Same-store sales increased 3.5%, driven by a 2.0% increase in customer traffic and a 1.5% increase in average transaction amount, marking the fifth consecutive quarter of traffic growth and the sixth consecutive quarter of positive comps across all four merchandise categories.
Management improved their full-year estimate across the board: same-store sales growth is now expected to be 2.5% to 2.9%, up from 2.2% to 2.7% before, while full-year EPS guidance increased to $7.80-$8.00 from $7.20-$7.45. Tariff refunds, a lower LIFO provision, and improved shrink and damages helped increase the gross margin by 127 basis points to 32.6%. CEO Todd Vasos also pointed to continued market share gains from higher-income households switching away from traditional grocers, a trend the company has cited for several quarters, with management announcing plans to resume up to $700 million in share buybacks in the latter half of the year, backed by remodels under its Project Renovate and Project Elevate initiatives.
Dollar Tree's results, released on August 27, indicate a more complicated situation. Diluted EPS came in at $2.70, including a $1.31-per-share net benefit related to tariff refunds, while revenue increased 7% year-over-year to $4.89 billion. Comparable store sales up 3.7%, driven by a 3.3% gain in average ticket and a 0.4% increase in traffic, a return to positive traffic that occurred a full quarter ahead of management's internal plan.
However, the headline figure includes an important caveat: $1.31 of the $2.70 in EPS came from the net impact of $383 million in IEEPA tariff refunds after related reinvestment spending, duties, and taxes. Strip that out, and underlying EPS was $1.39, above the $1.00-$1.15 range management had guided to in May and about 23% above the $1.13 consensus estimate.
#TRAFFIC

4 days ago
Oxford Industries, Inc. (NYSE:OXM) reported fiscal second-quarter net sales of $394.4 million, down 2.2%. Full-price direct-to-consumer sales declined 1%, while wholesale sales fell 14%, primarily reflecting lower off-price sales.
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap
GAAP gross margin increased to 73.8% from 61.4% after Oxford Industries, Inc. (NYSE:OXM) recognized approximately $42 million of tariff refund claims as a reduction of cost of goods sold. Company-defined non-GAAP adjusted gross margin, excluding tariff refunds and LIFO effects, still improved to 63.1% from 61.7%. Updated **** ortment, sourcing, and pricing strategies increased initial markups, while lower off-price wholesale sales improved the sales mix.
Oxford Industries, Inc. (NYSE:OXM) lowered full-year sales guidance to $1.43 billion to $1.47 billion from $1.475 billion to $1.505 billion. Company-defined non-GAAP adjusted EPS guidance fell to $1.60 to $2.00 from $2.30 to $2.70, reducing the midpoint by 28%. Adjusted EPS excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, distribution-center relocation costs, merchandising initiatives, store-closure impairments and related taxes.
Underlying margin expansion suggests Oxford Industries, Inc. (NYSE:OXM) improved product economics beyond the one-time refund. Company-defined non-GAAP adjusted operating income, which excludes LIFO effects, tariff refunds and related interest, Johnny Was amortization, and specified distribution-center, merchandising, and store-closure costs, increased to $29.3 million from $28.3 million. Adjusted operating margin rose to 7.4% from 7.0%.
Tommy Bahama remained the strongest major brand for Oxford Industries, Inc. (NYSE:OXM), with sales increasing 0.8% and adjusted gross margin rising to 63.6% from 60.7%. FIFO inventory fell $9 million, or 4%, from one year earlier, reducing markdown exposure.
#gaap


4 days ago
Frances Tiafoe and his girlfriend Ayan Broomfield have been together for 11 years
Broomfield previously played tennis professionally and gives Tiafoe advice on his game
Broomfield launched an initiative to champion representation for women of color on and off the tennis court
As Frances Tiafoe continues to reach career highs, the tennis player's girlfriend, Ayan Broomfield, is serving up endless support.
Tiafoe, who became a US Open semifinalist for the third time in September, has been with Broomfield for over a decade.
#broomfield #tennis #september
Broomfield previously played tennis professionally and gives Tiafoe advice on his game
Broomfield launched an initiative to champion representation for women of color on and off the tennis court
As Frances Tiafoe continues to reach career highs, the tennis player's girlfriend, Ayan Broomfield, is serving up endless support.
Tiafoe, who became a US Open semifinalist for the third time in September, has been with Broomfield for over a decade.
#broomfield #tennis #september



4 days ago
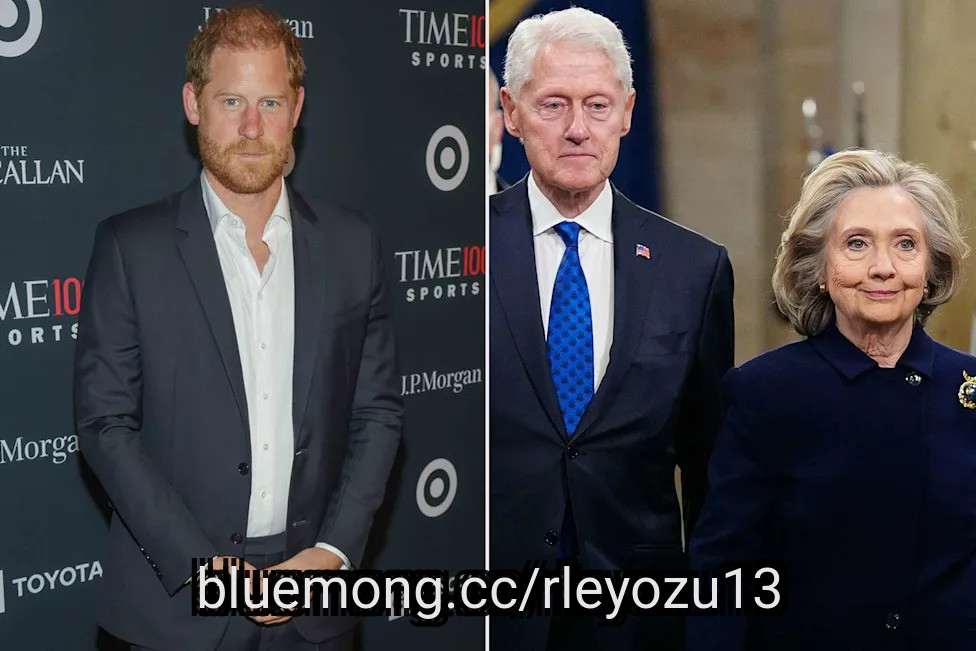
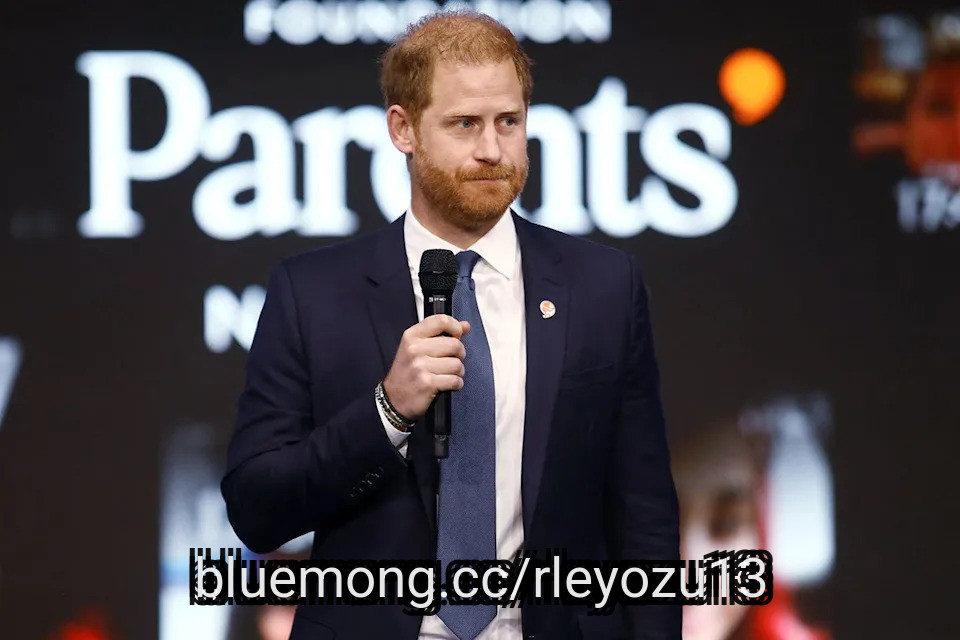
Prince Harry is preparing to return to the United States just weeks after moving back to the U.K. with Meghan Markle and their children. The Duke of Sussex, 41, is scheduled for another major appearance in New York.
Harry is set to attend Bill and Hillary Clinton's Clinton Global Initiative annual meeting in New York City on Sept. 22 and 23. This will be his second appearance at the event after he joined in 2024. The meeting will take place during United Nations General ******* embly week. It will also feature Chrissy Teigen, Bill Nye and LinkedIn co-founder Reid Hoffman.
Meanwhile, the trip comes less than a month after Harry, Meghan and their children, Prince Archie, 7, and Princess Lilibet, 5, returned to the U.K. on Aug. 26. The family is now living outside London. However, they continue to maintain their home in Montecito, Calif.
This year's meeting is ******* led "How Do We Get It Right?" It will focus on artificial intelligence, climate resilience, democracy, humanitarian response, economic opportunity and health.
At the same time, Harry's appearance comes as attention remains on the Sussexes' public role following their move to Britain. Recently, sources close to the couple pushed back against guidance from King Charles that described their position as "akin to private citizens."
#back
Harry is set to attend Bill and Hillary Clinton's Clinton Global Initiative annual meeting in New York City on Sept. 22 and 23. This will be his second appearance at the event after he joined in 2024. The meeting will take place during United Nations General ******* embly week. It will also feature Chrissy Teigen, Bill Nye and LinkedIn co-founder Reid Hoffman.
Meanwhile, the trip comes less than a month after Harry, Meghan and their children, Prince Archie, 7, and Princess Lilibet, 5, returned to the U.K. on Aug. 26. The family is now living outside London. However, they continue to maintain their home in Montecito, Calif.
This year's meeting is ******* led "How Do We Get It Right?" It will focus on artificial intelligence, climate resilience, democracy, humanitarian response, economic opportunity and health.
At the same time, Harry's appearance comes as attention remains on the Sussexes' public role following their move to Britain. Recently, sources close to the couple pushed back against guidance from King Charles that described their position as "akin to private citizens."
#back


4 days ago
By Sai Ishwarbharath B and Abhirami G
BENGALURU, Sept 10 (Reuters) - Wipro's AI initiatives have increased productivity equivalent to the output of 20,000 employees, who have since been redeployed within the Indian IT firm, its chief technology officer said.
The comments come as India's $315 billion software services industry grapples with adoption of AI, which is reshaping hiring, software development and contracts.
Wipro, with about 243,000 employees in June, is shifting to a "human-AI operating model," with more than 100,000 employees receiving advanced AI-related training and certifications, Sandhya Arun said in an interview.
"It could be the same engineer managing a bunch of agents, deployed on other projects or being trained for some other role. It doesn't necessarily mean person-to-person replacement by an agent."
#employees #ishwarbharath
BENGALURU, Sept 10 (Reuters) - Wipro's AI initiatives have increased productivity equivalent to the output of 20,000 employees, who have since been redeployed within the Indian IT firm, its chief technology officer said.
The comments come as India's $315 billion software services industry grapples with adoption of AI, which is reshaping hiring, software development and contracts.
Wipro, with about 243,000 employees in June, is shifting to a "human-AI operating model," with more than 100,000 employees receiving advanced AI-related training and certifications, Sandhya Arun said in an interview.
"It could be the same engineer managing a bunch of agents, deployed on other projects or being trained for some other role. It doesn't necessarily mean person-to-person replacement by an agent."
#employees #ishwarbharath


4 days ago
Pete Davidson marked the 25th anniversary of 9/11 by honoring the father he lost that day. The comedian joined 9/11 Day's UNIITE For Good campaign, turning grief into a call for kindness.
Davidson's father, Scott Davidson, died while responding to the attacks in New York City. This year, Pete encouraged Americans to remember the tragedy by reviving the spirit of unity that followed.
Davidson shared his story in a video for 9/11 Day. "He was a firefighter for Ladder 118, Engine 205 in Brooklyn Heights," he said. "My dad loved being a fireman, and he loved saving people," Davidson added. Scott died while responding to the attacks alongside fellow firefighters.
The Saturday Night Live alum explained why UNIITE For Good felt fitting this year. "9/11 is usually a tough day," Davidson said, according to the campaign. He explained that participants could perform a good deed and pass the idea along. The campaign then added those pledges to a nationwide map.
The goal was to cover the country with visible examples of people helping others. Davidson hoped the initiative could make an emotionally difficult anniversary feel slightly lighter. The campaign also focused on what happened after September 11. Communities came together and helped strangers despite their differences.
#davidson #uniite #anniversary #died
Davidson's father, Scott Davidson, died while responding to the attacks in New York City. This year, Pete encouraged Americans to remember the tragedy by reviving the spirit of unity that followed.
Davidson shared his story in a video for 9/11 Day. "He was a firefighter for Ladder 118, Engine 205 in Brooklyn Heights," he said. "My dad loved being a fireman, and he loved saving people," Davidson added. Scott died while responding to the attacks alongside fellow firefighters.
The Saturday Night Live alum explained why UNIITE For Good felt fitting this year. "9/11 is usually a tough day," Davidson said, according to the campaign. He explained that participants could perform a good deed and pass the idea along. The campaign then added those pledges to a nationwide map.
The goal was to cover the country with visible examples of people helping others. Davidson hoped the initiative could make an emotionally difficult anniversary feel slightly lighter. The campaign also focused on what happened after September 11. Communities came together and helped strangers despite their differences.
#davidson #uniite #anniversary #died

4 days ago
As Norway continues to follow the ongoing case involving Marius Borg Høiby, with a verdict expected on June 15, concern over Princess Mette-Marit's health has also intensified. The crown princess, who is reportedly on a waiting list for a lung transplant, was notably absent from a milestone event that holds special meaning for both her and her husband, Crown Prince Haakon.
On June 11, Haakon attended the 25th anniversary celebration of the Crown Prince and Crown Princess's Fund, a charitable initiative established on the day of their wedding and one that has since become a cornerstone of the couple's public work.
This year's event carried particular emotional significance. For the first time, Princess Mette-Marit was unable to attend the annual celebration of the fund that was created as a direct result of her marriage to Haakon. Her fragile health prevented her from taking part in an occasion they have always hosted together, adding a poignant note to an event that represents a major part of their shared legacy.
Her last public appearance was on Norway's National Day, May 17, when she appeared visibly weakened and was seen relying on supplemental oxygen.
Crown Prince Haakon married Mette-Marit Tjessem Høiby on August 25, 2001, at Oslo Cathedral in a ceremony attended by royals from across Europe, including Spain's Queen Sofía and the then-Prince Felipe.
#mette #princess #june #Health
On June 11, Haakon attended the 25th anniversary celebration of the Crown Prince and Crown Princess's Fund, a charitable initiative established on the day of their wedding and one that has since become a cornerstone of the couple's public work.
This year's event carried particular emotional significance. For the first time, Princess Mette-Marit was unable to attend the annual celebration of the fund that was created as a direct result of her marriage to Haakon. Her fragile health prevented her from taking part in an occasion they have always hosted together, adding a poignant note to an event that represents a major part of their shared legacy.
Her last public appearance was on Norway's National Day, May 17, when she appeared visibly weakened and was seen relying on supplemental oxygen.
Crown Prince Haakon married Mette-Marit Tjessem Høiby on August 25, 2001, at Oslo Cathedral in a ceremony attended by royals from across Europe, including Spain's Queen Sofía and the then-Prince Felipe.
#mette #princess #june #Health

4 days ago
For its Q3 FY26, ABM Industries Inc. (NYSE:ABM) posted a record topline figure of $2.3 billion. With year-over-year acquisitive growth and organic expansion of 2.1% each, the total jump in sales was 4.2%. The company's adjusted EBITDA for the quarter climbed 11% to $139.6 million, compared to Q3 FY25. Adjusted net income stood at $61.5 million, exhibiting a 19% growth and translating into an adjusted diluted EPS of $1.04. ABM generated operating cash flows for the third quarter totaling $146.8 million, while free cash flow stood at $128.4 million.
Dmitry Kalinovsky/Shutterstock.com
Third quarter print revealed that majority of the topline growth was concentrated across the company's Aviation, and Manufacturing & Distribution (M&D) segments, which expanded 12.5% and 17.6% respectively. Performance within the M&D segment was driven by strong technology market trends, with further support coming from ABM's acquisition of WGNstar. Aviation segment got a boost from robust demand for air travel and healthy progress around the company's newly secured London Heathrow contract.
Prudent cost management resulted in around $3 million reduction in ongoing corporate costs compared to the previous year. Overall growth in bottom line can be attributed to higher operating profits across most segments, a lower tax bill, and cut down in corporate overhead. Some of these were offset by rising interest burden due to the financing of the WGNstar transaction. The company's share buyback initiative was another factor that led to a 25% rise in diluted EPS for the quarter.
The Education segment's revenue held steady. Business & Industry (B&I) slipped 2.6%, largely in line with expectations, due to the previously disclosed loss of a major UK client and ongoing weakness along the US west coast. Technical Solutions (ATS) growth was hampered by certain deferred projects.
#Growth #adjusted #topline
Dmitry Kalinovsky/Shutterstock.com
Third quarter print revealed that majority of the topline growth was concentrated across the company's Aviation, and Manufacturing & Distribution (M&D) segments, which expanded 12.5% and 17.6% respectively. Performance within the M&D segment was driven by strong technology market trends, with further support coming from ABM's acquisition of WGNstar. Aviation segment got a boost from robust demand for air travel and healthy progress around the company's newly secured London Heathrow contract.
Prudent cost management resulted in around $3 million reduction in ongoing corporate costs compared to the previous year. Overall growth in bottom line can be attributed to higher operating profits across most segments, a lower tax bill, and cut down in corporate overhead. Some of these were offset by rising interest burden due to the financing of the WGNstar transaction. The company's share buyback initiative was another factor that led to a 25% rise in diluted EPS for the quarter.
The Education segment's revenue held steady. Business & Industry (B&I) slipped 2.6%, largely in line with expectations, due to the previously disclosed loss of a major UK client and ongoing weakness along the US west coast. Technical Solutions (ATS) growth was hampered by certain deferred projects.
#Growth #adjusted #topline

4 days ago
Daktronics Inc. (NASDAQ:DAKT) reported its Q1 FY27 results, showing continued momentum across core segments and its strategic push. The company reported topline figures of $234.6 million, which grew 7.1% compared to the same period last year. This growth was primarily driven by impressive numbers across the Live Events, Transportation, and International units. The diluted EPS of $0.40 was the highest quarterly figure in the last twelve quarters, exhibiting a substantial growth of more than 21%. The business generated $31.4 million in cash from operations, which pushed the cash balance to $154.6 million by the quarter end, after accounting for $4.4 million expenditure on share repurchases.
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results


4 days ago
Braze Inc. (NASDAQ:BRZE) turned in a strong second quarter. The reputed customer engagement platform showcased continued momentum across both its product strategy and financial performance. The company generated topline figure of $227.2 million, an impressive 26.2% increase compared to the same period last year. This revenue growth was fueled by upselling gains, customer additions and renewals. The company posted $24.2 million in cash flow from operating activities, a monumental growth relative to $7 million in the same period a year ago. This was paired with $21.7 million in free cash flow, against $3.5 million during Q2 FY26.
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue

4 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved a sixth consecutive quarter of top-line growth, driven by broad-based strength across all regions and industry groups despite macroeconomic headwinds.
Completed the acquisition of AMS to create a global leader in talent and organizational consulting, significantly expanding capabilities in contingent workforce solutions and early career recruiting.
Transitioned to a new geographic reporting structure (Americas, EMEA, APAC) to better align with 'We Are Korn Ferry' go-to-market initiatives and holistic client engagement.
Leveraged proprietary data and IP—including 113 million executive ******* sments—to differentiate services in an AI-saturated market where resume quality has become commoditized.
#market #NVIDIA #tell #americas
Achieved a sixth consecutive quarter of top-line growth, driven by broad-based strength across all regions and industry groups despite macroeconomic headwinds.
Completed the acquisition of AMS to create a global leader in talent and organizational consulting, significantly expanding capabilities in contingent workforce solutions and early career recruiting.
Transitioned to a new geographic reporting structure (Americas, EMEA, APAC) to better align with 'We Are Korn Ferry' go-to-market initiatives and holistic client engagement.
Leveraged proprietary data and IP—including 113 million executive ******* sments—to differentiate services in an AI-saturated market where resume quality has become commoditized.
#market #NVIDIA #tell #americas

4 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the sequential improvement in comparable sales to enhanced digital conversion and the successful scaling of private brand franchises like THERMACHILL.
The company is navigating a structural shift in customer behavior driven by GLP-1 medication adoption, which has led to temporary pauses in apparel purchasing during weight loss journeys.
Performance was significantly bolstered by a $4.6 million IEEPA tariff refund, which masked a 70 basis point decline in underlying merchandise margins caused by higher markdowns and shipping surcharges.
Strategic focus has shifted toward 'Fit Authority' through the FITMAP initiative, which has scanned 150,000 customers and resulted in higher average order values and lower return rates.
#performance
Management attributes the sequential improvement in comparable sales to enhanced digital conversion and the successful scaling of private brand franchises like THERMACHILL.
The company is navigating a structural shift in customer behavior driven by GLP-1 medication adoption, which has led to temporary pauses in apparel purchasing during weight loss journeys.
Performance was significantly bolstered by a $4.6 million IEEPA tariff refund, which masked a 70 basis point decline in underlying merchandise margins caused by higher markdowns and shipping surcharges.
Strategic focus has shifted toward 'Fit Authority' through the FITMAP initiative, which has scanned 150,000 customers and resulted in higher average order values and lower return rates.
#performance


4 days ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year

5 days ago
During a segment on the September 3 episode, Mad Money host Jim Cramer shared a detailed bullish thesis on Amazon.com, Inc. (NASDAQ:AMZN). He stated:
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi
Let's start with Amazon. Ever since we went out to see Amazon earlier this year, I've been stuck on something that CEO Andy Jassy told me. He said they're going to make an immense amount of money in artificial intelligence. They were going to profit from their gigantic commitment to data centers and next year will be huge for the compute sales. Well, I think it's being pulled forward. I think it may already be huge right now. I also remember Andy talking about the $50 billion semiconductor business that's buried in the company. I like the healthcare initiatives... Amazon Web Services is doing incredibly well. Their grocery delivery business, wow...
Alright, what can I say? All this for a stock that's up just 12% for the year; that's wrong. Amazon's balance sheet isn't as good as it was a year ago; enough already. What if Amazon Web Services is able to make four times what it just paid for 2 million GPUs from NVIDIA? That ratio, by the way, is what NVIDIA CEO Jensen Huang told me companies can expect to get when they buy NVIDIA chips. That makes me think that Amazon is cheap. We've all kind of forgotten that there's a reason why a smart executive like Andy Jassy is willing to wreck Amazon's balance sheet like the old days. It's because they're going to make fortunes with the money they spend. And we are getting closer and closer to seeing huge profits for investments that the Street has hated. You can't wait until next year to buy the stock of Amazon. And that's why it is a screaming buy with the stock trading at about 20 times this year's earnings. That's wrong.
Amazon Web Services remains the primary profit engine for the company. In the second quarter, AWS revenue surged 37% year over year to reach $42.2 billion, putting its annual run rate at roughly $169 billion. Operating income for the cloud unit jumped to $16.6 billion. Companies shifting their operations to handle AI and heavy workloads are turning those massive data center investments into high-margin profits. Aside from basic cloud hosting, Amazon.com, Inc. (NASDAQ:AMZN) is leaning into its own custom chips, like Trainium and Graviton, and growing adoption of the Bedrock platform to keep its revenue streams strong and diversified.
Not everyone on Wall Street shares Cramer's enthusiasm, as it could be pointed out that Amazon.com, Inc.'s (NASDAQ:AMZN) balance sheet is noticeably weaker than it was a year ago as its long-term debt increased from nearly $66 billion at the end of 2025 to nearly $129 billion by mid-2026. Heavy capital commitments and soaring data center expenses, with full-year capital expenditure guidance climbing around $220 billion, have strained cash flow flexibility. Investors could be worried that the company is spending too aggressively. If enterprise demand for artificial intelligence tools slows down or if the massi
5 days ago
Prince Harry is returning to the Clinton Global Initiative annual meeting in New York City, marking his second appearance after previously taking part in 2024
The appearance comes just weeks after the Duke of Sussex moved back to the U.K. with Meghan Markle and their children
The news comes amid renewed debate over the couple's public profile, with sources close to Harry and Meghan saying, "They are public figures," following King Charles' "private citizens" guidance
Prince Harry is heading back to the U.S. for another major appearance, just weeks after his family's move back to Britain.
The Duke of Sussex, 41, is set to return to Bill and Hillary Clinton's Clinton Global Initiative annual meeting in New York City on Sept. 22 and 23, marking his second appearance at the event after previously taking part in 2024. Harry will join a lineup that also includes Chrissy Teigen, Bill Nye and LinkedIn co-founder Reid Hoffman at the gathering, which is being held during United Nations General **** embly week.
#back #global #city
The appearance comes just weeks after the Duke of Sussex moved back to the U.K. with Meghan Markle and their children
The news comes amid renewed debate over the couple's public profile, with sources close to Harry and Meghan saying, "They are public figures," following King Charles' "private citizens" guidance
Prince Harry is heading back to the U.S. for another major appearance, just weeks after his family's move back to Britain.
The Duke of Sussex, 41, is set to return to Bill and Hillary Clinton's Clinton Global Initiative annual meeting in New York City on Sept. 22 and 23, marking his second appearance at the event after previously taking part in 2024. Harry will join a lineup that also includes Chrissy Teigen, Bill Nye and LinkedIn co-founder Reid Hoffman at the gathering, which is being held during United Nations General **** embly week.
#back #global #city
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
Saudi AI company Humain has begun preparations for its IPO, after its CEO Tareq Amin announced he was ***** embling a team of experts to help lay the groundwork for its listing.
While he did not specify a date, Amin told the Future Investment Initiative conference last October that his aim was to list Humain in both Saudi Arabia and New York by 2029.
Since its launch last year, Humain has secured deals and partnerships with xAI, Nvidia, Amazon Web Services, Adobe and Cisco, to name a few.
Those achievements have been underpinned by finance from Saudi Arabia's $900 billion Public Investment Fund which established Humain in May 2025 as the key engine for delivering its AI ambitions.
The pursuit of an IPO marks a notable shift for a company whose growth so far has largely been funded by state capital.
#initiative
While he did not specify a date, Amin told the Future Investment Initiative conference last October that his aim was to list Humain in both Saudi Arabia and New York by 2029.
Since its launch last year, Humain has secured deals and partnerships with xAI, Nvidia, Amazon Web Services, Adobe and Cisco, to name a few.
Those achievements have been underpinned by finance from Saudi Arabia's $900 billion Public Investment Fund which established Humain in May 2025 as the key engine for delivering its AI ambitions.
The pursuit of an IPO marks a notable shift for a company whose growth so far has largely been funded by state capital.
#initiative

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
CVS Health (NYSE: CVS) dealt with significant headwinds after the COVID-19 pandemic. The company's financial results suffered as sales of coronavirus-related products (such as diagnostic tests) declined, while expenses in its insurance business rose substantially, resulting in lower profits and margins. However, CVS Health has done a good job of addressing those problems, and the stock has rebounded. Shares are up 31% over the past 12 months. Wall Street thinks there may be even more upside on the horizon. CVS Health's average price target is $116.04 (according to Yahoo! Finance), implying a meaningful 20% upside from current levels. Is now a great time to buy the stock?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Over the past 18 months (or so), CVS Health has implemented several initiatives that have helped improve its business. For instance, the company closed dozens of stores, many of which were unprofitable. The pharmacy chain specialist also scaled back its insurance division, notably by exiting the Affordable Care Act marketplace. The results have been pretty impressive. Consider the company's second-quarter results. CVS Health's revenue increased by a healthy 7.3% year over year to $106.1 billion.
Adjusted earnings per share were $2.58, 42.5% higher than the year-ago period. Note the improvement in CVS Health's healthcare benefits segment, which offers health insurance services. Operating expenses as a percentage of revenue declined slightly to 12.4%, down from 12.5% in the prior-year quarter, even as revenue grew 3.5% year over year. And operating margins within this unit came in at 5.8%, up from the 2.8% reported in the year-ago period. Also, CVS Health's medical benefits ratio -- the percentage of insurance premiums the company spent on medical care (the lower the better) -- declined to 87.4% in the second quarter, down from 89.9% in Q2 2025.
CVS Health also increased its guidance for the full fiscal year 2026. The company now expects its adjusted EPS to fall between $7.90 and $8.10, up from its previous range of between $7.30 to $7.50. The company is also now projecting cash flow from operations of at least $11.5 billion, up from the previous lower bound of $9.5 billion. These are signs of a much-improved business.
#insurance
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
5 days ago
UK homeware retailer Dunelm Group has set out a three-year plan to cut around £100m ($135.6m) in costs.
The strategy, named Winning Hearts & Homes, was announced alongside preliminary results for the financial year ended 27 June 2026.
Dunelm said it would strip "£100m of unproductive costs from the FY26 base by FY29" and channel that amount into growth initiatives.
The retailer said its objectives include lifting customer loyalty and spend through repeat visits and share of wallet, together with "a return to sustainable mid-to-high single digit sales growth, supported by increasing LFL [like for like] sales, digital acceleration and store investment."
It added that it plans to invest while maintaining "adjusted PBT [profit before tax] margin of 11% and return on capital employed of 30%".
#Growth
The strategy, named Winning Hearts & Homes, was announced alongside preliminary results for the financial year ended 27 June 2026.
Dunelm said it would strip "£100m of unproductive costs from the FY26 base by FY29" and channel that amount into growth initiatives.
The retailer said its objectives include lifting customer loyalty and spend through repeat visits and share of wallet, together with "a return to sustainable mid-to-high single digit sales growth, supported by increasing LFL [like for like] sales, digital acceleration and store investment."
It added that it plans to invest while maintaining "adjusted PBT [profit before tax] margin of 11% and return on capital employed of 30%".
#Growth
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
ASML Holding N.V. (NASDAQ:ASML) and Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM) have given investors a clearer view of their next manufacturing transition. The important distinction is when each company might earn a return.
Their September 8 announcement says TSMC intends to introduce ASML's High-NA extreme ultraviolet technology into high-volume advanced-node manufacturing starting in 2030. A separate initiative targets a larger photomask pilot line in 2031 and corresponding lithography systems for advanced production in 2033.
Image: Courtesy of ASML
Those dates describe successive stages, not a single launch delayed until 2033. Initial production would use existing six-inch masks; the later transition would introduce twelve-inch masks.
For ASML, a major customer's stated adoption plan strengthens the long-term demand case. More advanced AI chips require increasingly complex manufacturing, and TSMC expects more layers to need High-NA technology as nodes progress.
#high #advanced #transition #technology
Their September 8 announcement says TSMC intends to introduce ASML's High-NA extreme ultraviolet technology into high-volume advanced-node manufacturing starting in 2030. A separate initiative targets a larger photomask pilot line in 2031 and corresponding lithography systems for advanced production in 2033.
Image: Courtesy of ASML
Those dates describe successive stages, not a single launch delayed until 2033. Initial production would use existing six-inch masks; the later transition would introduce twelve-inch masks.
For ASML, a major customer's stated adoption plan strengthens the long-term demand case. More advanced AI chips require increasingly complex manufacturing, and TSMC expects more layers to need High-NA technology as nodes progress.
#high #advanced #transition #technology

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
LOS ANGELES — The Los Angeles Lakers have announced their promotional schedule for the 2026-27 season, featuring player bobbleheads, championship memorabilia and celebrations honoring some of the franchise's most recognizable figures.
The giveaways begin Nov. 1, when fans in attendance will receive a Luka Dončić bobblehead. The promotion will celebrate Dončić winning the 2025-26 NBA scoring ***** le.
Austin Reaves will receive his own bobblehead night Dec. 27, two days after the Lakers host LeBron James and the Philadelphia 76ers in a Christmas Day matchup at Crypto.com Arena.
The Lakers will also introduce the League of Stars program. The new season-long initiative will recognize former players and coaches who contributed to the franchise's history.
Norm Nixon will be the first honoree Dec. 14, followed by former Lakers coach Paul Westhead on Jan. 14 and Kurt Rambis on March 17. Fans attending each game will receive a throwback bobblehead featuring that night's honoree.
#season
The giveaways begin Nov. 1, when fans in attendance will receive a Luka Dončić bobblehead. The promotion will celebrate Dončić winning the 2025-26 NBA scoring ***** le.
Austin Reaves will receive his own bobblehead night Dec. 27, two days after the Lakers host LeBron James and the Philadelphia 76ers in a Christmas Day matchup at Crypto.com Arena.
The Lakers will also introduce the League of Stars program. The new season-long initiative will recognize former players and coaches who contributed to the franchise's history.
Norm Nixon will be the first honoree Dec. 14, followed by former Lakers coach Paul Westhead on Jan. 14 and Kurt Rambis on March 17. Fans attending each game will receive a throwback bobblehead featuring that night's honoree.
#season


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
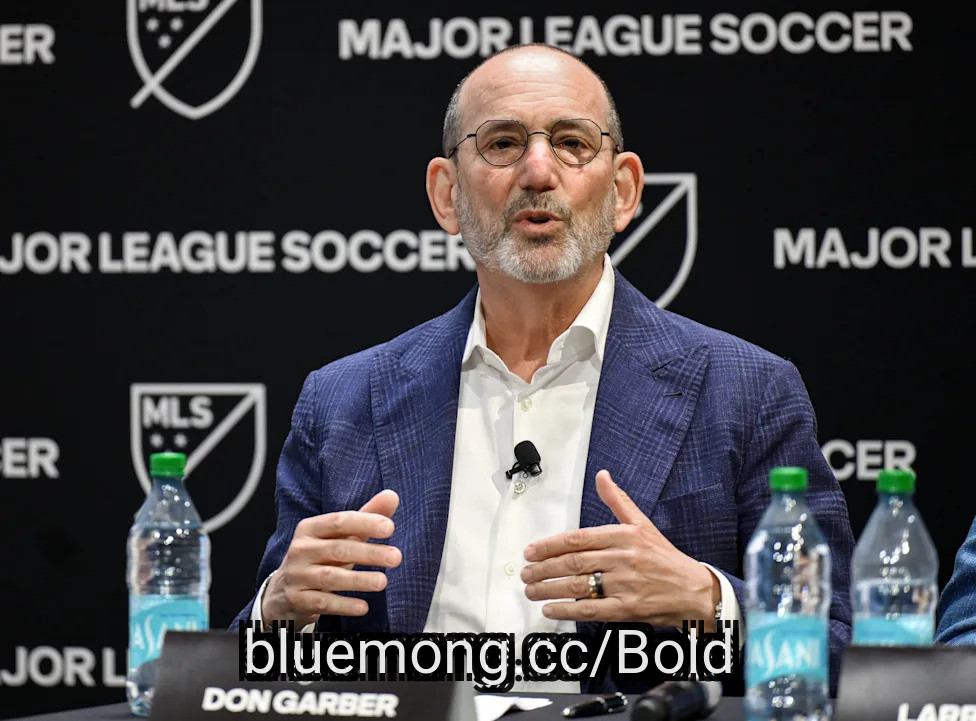
U.S. Soccer has announced that Don Garber will serve as the chair of the federation's Soccer Forward initiative.
Garber has served as MLS commissioner since 1999, but will be replaced by Larry Berg starting on Jan. 1, 2027.
Though Garber will stay involved with MLS, transitioning into a role as chairman, he will now take on a new position with U.S. Soccer's program that aims to grow the game at the grassroots level.
As part of his new role, U.S. Soccer said that Garber will "bring new partners to the table, grow support for U.S. Soccer's long-term priorities, and offer soccer to more people in more places than ever before."
"I've spent more than four decades working in professional sports, and I've always believed that our greatest progress comes through strong partnerships and a shared vision," said Garber.
#garber #Soccer #grow
Garber has served as MLS commissioner since 1999, but will be replaced by Larry Berg starting on Jan. 1, 2027.
Though Garber will stay involved with MLS, transitioning into a role as chairman, he will now take on a new position with U.S. Soccer's program that aims to grow the game at the grassroots level.
As part of his new role, U.S. Soccer said that Garber will "bring new partners to the table, grow support for U.S. Soccer's long-term priorities, and offer soccer to more people in more places than ever before."
"I've spent more than four decades working in professional sports, and I've always believed that our greatest progress comes through strong partnerships and a shared vision," said Garber.
#garber #Soccer #grow

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
7 days ago
Cash App segment is becoming a major driver of the growth story for Block Inc. (NYSE:XYZ) in 2026, as the underlying lending operations within the segment standout as key determinants of management's outlook for the remainder of the year. Recent initiatives around the company's proprietary credit signal support the narrative and broaden the company's lending reach. For the first time, Block will open its Cash App Score for external lenders by collaborating with Nova Credit's Cash Flow Intelligence Platform.
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#cash #Consumer
Photo by Clay Banks on Unsplash
Cash App Score was previously limited to internal use by the company for its consumer lending offerings such as the Cash App Borrow. This latest development could pave way for the monetization of company's data infrastructure, resulting in an additional revenue source.
During the second quarter, Block exceeded its prior guidance, reporting $3.17 billion in gross profit and $864 million in adjusted operating income. Revenue reached $6.62 billion, up 9.3% year over year. Gross profit expanded by 25% relative to the same period last year, and the company posted record 27% adjusted operating margins. Adjusted EPS clocked in at $1.02, exhibiting year-over-year growth of 65%.
Block's impressive second quarter print was driven by strong consumer spending, along with Cash App gross profit expansion of 31% year-over-year increase. This can be attributed to significant expansion in consumer lending, driven by Cash App Borrow. Block said Financial Solutions gross profit growth was driven primarily by Cash App Borrow. It reflects favorably on broader user engagement, who are utilizing Cash App for short-term credit financing instead of just a savings or payment mechanism. Despite a nominal 3% growth in monthly transacting actives, volumetric growth within Cash App was impressive. There was a 59% year-over-year jump in Cash App Consumer Lending origination volume, and 17% increase in Cash App Commerce Enablement volume.
#cash #Consumer

7 days ago
Luka Doncic is back in a position where he is the lone star of his team, and he has been fully focused on fulfilling his responsibilities as the leader.
The Los Angeles Lakers parted ways with LeBron James, who decided to become a free agent, ending his eight-year tenure with the historic franchise.
Left in Hollywood is Doncic, who will now be the team's main star—a role he embraced and carried out during his 6.5 seasons with the Dallas Mavericks. The Slovenian is not wasting any time. He made it clear what type of teammates he wanted around him, and once the roster was ***** embled, he made sure to welcome each and every one of them.
One of the Lakers' biggest challenges this season is the fact that more than half of the roster is new. Doncic is addressing that by bringing his old and new teammates together for bonding activities and mini-camps.
The NBA training camp will not officially open until September 29, but the six-time All-Star has taken the initiative to get an early start with his team. He flew nearly all of his teammates to Slovenia and, according to reports, paid for their plane tickets.
#star #time #made #roster
The Los Angeles Lakers parted ways with LeBron James, who decided to become a free agent, ending his eight-year tenure with the historic franchise.
Left in Hollywood is Doncic, who will now be the team's main star—a role he embraced and carried out during his 6.5 seasons with the Dallas Mavericks. The Slovenian is not wasting any time. He made it clear what type of teammates he wanted around him, and once the roster was ***** embled, he made sure to welcome each and every one of them.
One of the Lakers' biggest challenges this season is the fact that more than half of the roster is new. Doncic is addressing that by bringing his old and new teammates together for bonding activities and mini-camps.
The NBA training camp will not officially open until September 29, but the six-time All-Star has taken the initiative to get an early start with his team. He flew nearly all of his teammates to Slovenia and, according to reports, paid for their plane tickets.
#star #time #made #roster

7 days ago
France-based Mistral has completed a €3bn ($3.48bn) Series D funding round, putting the AI company's post-money valuation at more than €21bn ($24.4bn).
The fundraising was co-led by Samsung Electronics, the Scaleup Europe Fund managed by EQT, and existing investor PSG Equity.
The latest round provides capital to expand the company's "frontier research," along with increased compute capabilities for training AI models and broader international operations. This round comes three years after Mistral's founding.
Mistral currently has operations in 20 countries and supports more than 125 global enterprises with their AI initiatives. Its clients include ASML, Airbus, HSBC, and others.
According to Mistral, the new investment will help to scale its infrastructure, accelerate its commercial growth, and strengthen its position in AI provision for both enterprises and governments seeking control over data and AI deployment.
#mistral #round #france #series
The fundraising was co-led by Samsung Electronics, the Scaleup Europe Fund managed by EQT, and existing investor PSG Equity.
The latest round provides capital to expand the company's "frontier research," along with increased compute capabilities for training AI models and broader international operations. This round comes three years after Mistral's founding.
Mistral currently has operations in 20 countries and supports more than 125 global enterprises with their AI initiatives. Its clients include ASML, Airbus, HSBC, and others.
According to Mistral, the new investment will help to scale its infrastructure, accelerate its commercial growth, and strengthen its position in AI provision for both enterprises and governments seeking control over data and AI deployment.
#mistral #round #france #series

8 days ago
Americans are throwing big cash sums into college 529 plans, with U.S. households holding about 19.9 million total accounts, representing over $600 billion in **** ets by the end of 2025, according to the Education Data Initiative.
Now, Americans with no plans to attend college are using 529 plans as a retirement-plan booster.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#data #initiative
Now, Americans with no plans to attend college are using 529 plans as a retirement-plan booster.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#data #initiative




