

1 month ago
On September 9, American Eagle Outfitters Inc. (NYSE:AEO) revealed results for its fiscal 2026 second quarter. The company achieved an 8% year-over-year topline growth with net revenue figures of $1.38 billion. The second quarter operating profit jumped up to $211 million compared to $103 million during the same period last year. As a result, diluted earnings per share for the quarter stood at $0.79 in comparison with $0.45 for Q2 FY25. This led to a $21 million distribution to shareholders with a dividend payout of $0.125 per share.
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable


1 month ago
On September 8, United Natural Foods Inc. (NYSE:UNFI) announced its fourth quarter and full FY26 results. For the final quarter, the company posted an adjusted EBITDA of $172 million, which grew 48.3% compared to Q4 FY25. United's fourth quarter adjusted EPS of $0.69 took a sharp turn relative to a $0.11 adjusted loss per share for the same period last year. Cash flow from operating activities for the quarter stood at $197 million, along with free cash flow of $80 million.
Nejron Photo/Shutterstock.com
Amid a favorable customer mix and network optimizations, United delivered Q4 gross profit of $1,050 million, increasing marginally by 1.9% from the same period last year. This led to a gross margin of 13.7%, compared to 13.4% recorded in Q4 FY25. Cost-saving initiatives, which included efficient productivity through distribution centers and network optimizations, translated into lower operating expenses on a year-over-year basis. It helped United jump from an $87 million net loss for Q4 FY25 to a net income of $35 million during the recently concluded quarter.
For the complete fiscal year, the company delivered an adjusted EBITDA of $701 million, showcasing a 27% growth compared to FY25. Full-year adjusted EPS also climbed from $0.71 last year to $2.65. United generated FY26 operating cash flow of $540 million and free cash flow of $323 million.
Several encouraging operational developments took place during the fourth quarter. United initiated onboarding additional business from its existing customer base, as well as the new ones. Topline impact of such additions will be seen during FY27, once the broader optimization initiatives have cycled through. For its Lean Daily Management (LDM) program, the company concluded a preliminary rollout covering 44 distribution centers. This resulted in year-over-year enhancement in fill rates, throughput, and on-time deliveries, for four consecutive quarters.
#cash #flow #fourth #company

1 month ago
On September 10, Imperial Petroleum Inc. (NASDAQ:IMPP), a company involved in seaborne transportation of crude oil, dry bulk, and petroleum products, released its second quarter results. With a topline figure of $87.1 million, the company delivered record quarterly revenue, which also resulted in 139.9% year-over-year growth. Imperial's adjusted EBITDA for the second quarter stood at $41.7 million, while the Q2 adjusted net income of $35.3 million exhibited around 163% growth in comparison with Q2 FY25.
Ralf Gosch/Shutterstock.com
Several factors contributed to the second quarter topline growth. A 6.9 vessel rise in the company's average fleet size was the primary growth enabler. Other factors include encouraging dynamics across the drybulk segment, and higher rates for both drybulk and tankers amid the geopolitical uncertainties. Operating income for the quarter jumped to a near-record level of $33.4 million, which translates into a 307.3% growth relative to Q2 FY25. Imperial posted an adjusted EPS of $0.76 for the reported quarter, which almost doubled compared to the same quarter a year prior.
At the back of efficient fleet management, management remained focus on strengthening its financial position. The company ended the quarter with no debt, and its liquidity position also remained resilient. Cash and cash equivalents, including time deposits, increased from $179.1 million at the end of 2025 to $245.2 million as of June 30, 2026. The company added that its cash base had increased further to approximately $260 million as of the September 10 results release.
Certain areas of weakness warrant a closer examination. During the reported quarter, fleet operational utilization went down from 83.1% in prior year's second quarter to 73.5%. There was a substantial increase in some of the underlying operating expenses. For instance, the vessel operating expense stood at $14.4 million compared to $8.4 million during Q2 FY25. This $6 million rise can be attributed to Imperial's larger fleet size. Similarly, the voyage expenses also jumped from $10.7 million in last year's Q2 to $22.1 million for Q2 FY26. The incremental voyage expenses stemmed from higher bunkers' rates, as well as a 58.4% jump in spot days.
#fleet

1 month ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#vaccine #pfizer #NYSE
1 month ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Masco Corporation (NYSE:MAS). Masco Corporation (NYSE:MAS), a US-based home improvement and building products manufacturer, contributed positively to performance this quarter. On September 14, 2026, Masco Corporation (NYSE:MAS) closed at $69.41 per share. Over the past month, Masco Corporation (NYSE:MAS) declined 5.41%, but its shares are down 5.31% over the past year. Masco Corporation (NYSE:MAS) has a market capitalization of $13.69 billion, and its stock has traded within a 52-week range of $58.16 to $83.64.
Broyhill ***** et Management stated the following regarding Masco Corporation (NYSE:MAS) in its Q2 2026 investor letter:
"Masco Corporation (NYSE:MAS) gained 37%, the best result in the portfolio, and was initiated in the first quarter as one of two investments in the depressed housing sector. The quarter was plumbing-led and, more to the point, volume-led, with the strongest volume growth since the end of the pandemic and pricing intact. Management raised the topline outlook, took out delayed-draw leverage to repurchase stock, and increased the buyback guide by $200 million, to more than $800 million against a $2 billion authorization. Earlier in the quarter, our investment team also attended Masco's investor day and was able to interact with management at the event."
Masco Corporation (NYSE:MAS) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 46 hedge fund portfolios held Masco Corporation (NYSE:MAS) at the end of the second quarter, compared to 42 in the previous quarter. While we acknowledge the potential of Masco Corporation (NYSE:MAS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#corporation #letter


1 month ago
Pfizer Inc. (NYSE:PFE) and Valneva SE (NASDAQ:VALN) reported on August 14 that the European Medicines Agency has validated the Marketing Authorization Application for PF-07307405, the companies' experimental Lyme disease vaccine candidate, and will now begin the official review.
For a vaccine candidate first proposed in a 2020 collaboration deal between Pfizer Inc. (NYSE:PFE) and French biotech Valneva SE (NASDAQ:VALN), this represents the formal transition from years of clinical development into European regulatory review.
The application is based on the Phase 3 VALOR trial, a placebo-controlled, randomized study of 9,437 participants aged five and older from high-incidence Lyme disease locations in US, Canada, and Europe. Participants got four doses on a phased schedule: one at months 0, 2, and 5-9, followed by a fourth dosage around a year later, shortly before the start of the next Lyme season. Topline data released in March 2026 demonstrated efficacy of over 70% in reducing confirmed Lyme disease cases, with the vaccine generally tolerated and no safety issues detected. However, the statistical picture was less clean than the headline efficacy suggests. The first prespecified **** ysis, which served as the primary endpoint, showed 73.2% efficacy but failed the trial's predefined statistical criterion because the lower bound of the 95% confidence interval was 15.8%, below the required 20%. A second prespecified **** ysis showed 74.8% efficacy and did meet that threshold.
Valneva SE (NASDAQ:VALN), the smallest of the two partners, views the vaccine as a clean competitive setup. According to the company, PF-07307405 is the most advanced Lyme disease vaccine candidate currently in clinical development, a rare spot in the vaccine industry where new entrants often face competition from existing treatments. Under the terms of the 2020 partnership and license agreement, Pfizer Inc. (NYSE:PFE) will have exclusive rights to produce and commercialize the vaccine if it is approved, while Valneva SE (NASDAQ:VALN) will benefit as a development partner.
The institutional stance is very different between the two companies, reflecting their very different sizes. Pfizer Inc. (NYSE:PFE) is still a strong name in the institutional **** e, with hedge fund ownership stable at 83 funds in the second quarter of 2026, the same as the first quarter, reflecting its position as a large, diversified pharmaceutical holding, rather than a name driven by a specific pipeline event. Valneva SE (NASDAQ:VALN), however, has little hedge fund exposure, with only 4 funds holding a position in the second quarter, up from 1 in the first quarter, reflecting the continued lack of visibility of the smaller partner among institutional investors.
#disease


1 month ago
On September 1, Korn Ferry (NYSE:KFY) completed its £850 million acquisition of UK-based AMS, from OMERS Private Equity. The deal combines two well-reputed brands, resulting in a highly well-rounded solutions provider and a leading business within the global talent and organizational consulting **** e. It offers a broader market reach to Korn Ferry, along with more extensive coverage spanning several new industries.
Copyright: baranq / 123RF Stock Photo
AMS acquisition extends Korn Ferry's existing growth trajectory, which was highlighted in the company's recently announced first quarter results. It was the sixth back-to-back quarter of topline growth, which augments the durability of Korn Ferry's fundamental business model. The company also delivered a 9% growth in its adjusted diluted EPS of $1.43, relative to the same period last year.
The AMS deal results in several strategic benefits for Korn Ferry. Based on its long-standing client relationships, AMS offers robust operational strength, along with prospects of consistent, recurring income. Such relationships also enable the company to deliver technology-led solutions at scale.
Financing of this transaction involved a mix of existing cash, share issuance and borrowings. At closing, Korn Ferry paid approximately £473 million and $326 million in cash, covering consideration to the sellers, repayment of AMS indebtedness and other transaction obligations, and issued 3,118,628 Korn Ferry shares to the sellers.
#business


1 month ago
Amgen Inc. (NASDAQ:AMGN) shed roughly $12 billion in market value after hours on September 4, 2026. The stock declined by about 5% to $415. The reason, as strange as it sounds, is a drug it does not own. Novartis announced that pelacarsen, an Lp(a)-lowering therapy, missed its Phase 3 cardiovascular-outcomes trial, Lp(a)HORIZON. And since Amgen's late-stage ******* et olpasiran relies on the same biological premise, investors immediately marked down Amgen on the negative read-through.
The result strikes at a premise rather than at a product. Pelacarsenhad lowered Lp(a) by roughly 80% in earlier studies. In Lp(a)HORIZON, Novartis said pelacarsen substantially lowered Lp(a), but it still failed to reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. It still could not reduce the composite of cardiovascular death, heart attack, stroke, and urgent revascularization. And now the entire hypothesis that lowering Lp(a), a genetic cardiovascular risk factor, actually cuts events, is being directly challenged. Olpasiran is built on the same hypothesis, leading to the repricing of odds as soon as pelacarsen's data were out.
Amgen's olpasiran, an siRNA, lowered Lp(a) by more than 95% at certain doses in Phase 2, compared with reductions of roughly 80% for pelacarsen in earlier studies. The bull case is that this deeper reduction could help olpasiran deliver better cardiovascular outcomes.. The bull case is that this 15% will help Amgen to make a deeper cut and deliver results. While biologically possible, the Lp(a)HORIZON trial provided no evidence that a clinical threshold exists above an 80% reduction. The topline Phase 3 announcement did not establish that deeper Lp(a) lowering would have produced a cardiovascular benefit. It is therefore appropriate to say that the miss lowered olpasiran's probability of success rather than pretending it is irrelevant. Eli Lilly's lepodisiran is running the same deep-reduction experiment, so the hypothesis will be tested with or without Amgen.
Amgen is not an Lp(a) pure-play. MariTide in obesity, Repatha in cholesterol, and Tezspire in asthma drive more value for the company, and this diversification creates a cushion for the stock, although the selloff ultimately became much larger than the initial 5% after-hours reaction. Positioning has stayed calm since the beginning of 2026. Insider Monkey data shows 66 hedge funds held AMGN in the second quarter of 2026, up slightly from 65 in the first. Short interest, on the other hand, sits at just 2.4% of float, reflecting minimal bets against the stock in the market.
#horizon #pelacarsen

1 month ago
On September 10, Adobe (NASDAQ:ADBE) posted record third-quarter revenue of $6.76 billion, up 13% year over year, and raised its full-year revenue and profit targets. Non-GAAP EPS climbed 15% to $6.13, while GAAP EPS rose 11% to $4.62. Buried inside those headline numbers was a sharper story: AI-first ending ARR topped $650 million, growing more than 150% year over year. The same call brought a leadership change, with Anil S. Chakravarthy set to take over as CEO from Shantanu Narayen on December 1. Investors got a lot to digest in one afternoon.
Adobe's AI tools are no longer just a demo. Firefly ending ARR, which spans the Firefly app and its credit packs, grew 40% quarter over quarter, and the Acrobat AI ******* istant doubled its monthly active users over the same three months. Total monthly active users across Adobe's businesses surpassed 1 billion in the quarter, up more than 20% year over year, and creative premium MAU crossed 100 million, up more than 70%. Business professionals and consumers MAU passed 900 million, up more than 25%. That kind of user growth, concentrated in free and freemium tiers, is what feeds the paid AI upgrades now showing up in ARR.
The company backed that growth with cash. Operating cash flow hit a third-quarter record of $2.52 billion, and Adobe bought back roughly 9.5 million shares during the quarter, leaving $24.55 billion still authorized for repurchases. Management raised its full-year revenue target to a range of $26.58 billion to $26.63 billion and its non-GAAP EPS target to $24.45 to $24.50. On the product side, Adobe struck a deal to acquire Topaz Labs, whose AI enhancement models for image and video work would slot directly into Firefly and Creative Cloud. Enterprise demand held up too, with ending ARR growing more than 20% year over year at each of Adobe Experience Manager, Adobe Gen Studio, and Adobe Experience Platform.
Not every metric moved as fast. Remaining performance obligations, the backlog of contracted but unrecognized revenue, grew 8% year over year to $22.16 billion, trailing both the 13% revenue growth and the 11.2% growth in total ending ARR. Current RPO grew 9%, also behind the topline. Interim CFO Steven Day flagged a separate issue heading into the fourth quarter: a foreign-exchange headwind that partly offset the benefit of the third-quarter beat when management updated its full-year guidance.
AI-first ARR, for all its 150% growth rate, is still just over $650 million against a total ARR base of $27.50 billion, so it remains a small slice of the business even as it scales. The transition arrives at a pivotal moment too, with Chakravarthy set to take the CEO seat on Dec. 1 just as the company leans harder into an unproven agentic-software strategy, and the Topaz Labs deal still needs to clear regulatory approval before it adds anything to the numbers.
#adobe #billion #million


2 months ago
The Cooper Companies Inc. (NASDAQ:COO), a leading medical device company, announced its third quarter fiscal 2026 results on September 9. Topline went up 1% to $1.066 billion in comparison with the same quarter last year, which also included 1% organic growth. The company posted quarterly adjusted diluted EPS of $1.15, which represented a 4% jump from Q3 FY25. During the quarter, $339.1 million was spent on repurchasing around 4.9 million of the company's common shares. This leaves management with $1.5 billion of repurchase capacity, which remains available after the Board had raised its buyback authorization from $2 billion to $3 billion.
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash
2 months ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ***** e, released its fiscal second-quarter 2027 on September 9. The company registered a 25% growth in its annual recurring revenue compared to the same period last year, with figures of $1.231 billion. This was driven by a 36% expansion in SaaS ARR which clocked in at $847 million. SailPoint generated $45 million in operating cash flow during the quarter, along with $37 million in free cash flow.
Burben/Shutterstock.com
Topline for the quarter hit $309 million, exhibiting 17% growth compared to Q2 FY26, amid several underlying factors. The company's subscription revenue reached $295 million, up 19% from a year earlier. SaaS customer base increased by 16%, with net new SaaS ARR jumping 34% year-over-year. It contributed around 97% to overall net new ARR for the business, with AI-driven ARR crossing $70 million mark.
SailPoint's existing customer base showed highly encouraging trends in adopting the company's AI-enabled solutions, with a 60% increase in their annual spend during the second quarter. These solutions were incorporated within more than two-thirds of the completed migrations during the quarter. Quarterly adjusted operating income increased from $54 million a year prior to $63 million, translating into an adjusted margin of 20%.
The quarter also saw key strategic moves by the management. It introduced the SailPoint Identity Security solution, which integrates SailPoint Agentic Fabric with SailPoint Human Fabric to deliver a real-time cycle for discovering and securing intricate digital ecosystems. The company also launched its Cursor Enterprise connector, which enables enterprises to manage both autonomous AI agents and human developers through an integrated control plane.
#year #SaaS #fabric #identity

2 months ago
On September 9, AeroVironment Inc. (NASDAQ:AVAV) revealed its Q1 FY27 results, posting its highest ever first quarter revenue. Topline figure of $480.5 million marked a 6% year-over-year growth, fueled by a $15.5 million jump in product sales and a $10.3 million expansion of service revenue. The company reported a book-to-bill ratio of 1.4, after total bookings for the quarter came in at $0.7 billion. Let's explore the underlying drivers of AeroVironment's impressive first quarter print.
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first

2 months ago
For its Q3 FY26, ABM Industries Inc. (NYSE:ABM) posted a record topline figure of $2.3 billion. With year-over-year acquisitive growth and organic expansion of 2.1% each, the total jump in sales was 4.2%. The company's adjusted EBITDA for the quarter climbed 11% to $139.6 million, compared to Q3 FY25. Adjusted net income stood at $61.5 million, exhibiting a 19% growth and translating into an adjusted diluted EPS of $1.04. ABM generated operating cash flows for the third quarter totaling $146.8 million, while free cash flow stood at $128.4 million.
Dmitry Kalinovsky/Shutterstock.com
Third quarter print revealed that majority of the topline growth was concentrated across the company's Aviation, and Manufacturing & Distribution (M&D) segments, which expanded 12.5% and 17.6% respectively. Performance within the M&D segment was driven by strong technology market trends, with further support coming from ABM's acquisition of WGNstar. Aviation segment got a boost from robust demand for air travel and healthy progress around the company's newly secured London Heathrow contract.
Prudent cost management resulted in around $3 million reduction in ongoing corporate costs compared to the previous year. Overall growth in bottom line can be attributed to higher operating profits across most segments, a lower tax bill, and cut down in corporate overhead. Some of these were offset by rising interest burden due to the financing of the WGNstar transaction. The company's share buyback initiative was another factor that led to a 25% rise in diluted EPS for the quarter.
The Education segment's revenue held steady. Business & Industry (B&I) slipped 2.6%, largely in line with expectations, due to the previously disclosed loss of a major UK client and ongoing weakness along the US west coast. Technical Solutions (ATS) growth was hampered by certain deferred projects.
#Growth #adjusted #topline


2 months ago
Daktronics Inc. (NASDAQ:DAKT) reported its Q1 FY27 results, showing continued momentum across core segments and its strategic push. The company reported topline figures of $234.6 million, which grew 7.1% compared to the same period last year. This growth was primarily driven by impressive numbers across the Live Events, Transportation, and International units. The diluted EPS of $0.40 was the highest quarterly figure in the last twelve quarters, exhibiting a substantial growth of more than 21%. The business generated $31.4 million in cash from operations, which pushed the cash balance to $154.6 million by the quarter end, after accounting for $4.4 million expenditure on share repurchases.
Copyright: rawpixel / 123RF Stock Photo
The recently reported results point to enhanced profitability and the company's ongoing operational excellence initiatives, which would strengthen investor confidence. An impressive cash position backed with robust operating cash flows would enable Daktronics to pursue its 3-year strategic plan around growth, operational strength, and efficient capital allocation.
For growth, management focused on vertical market expansion during the quarter, with investments in service offerings and software to facilitate recurring revenue growth and customer value.
For operational excellence, the company took several initiatives around supply chain and manufacturing. These include scaling up of Mexico operations, adding automation, refining procurement, and more. Product backlog reached $311.3 million, the sixth straight quarter it has stayed above $300 million, pointing to continued demand spread across the company's varied business segments.
#million #cash #results


2 months ago
Braze Inc. (NASDAQ:BRZE) turned in a strong second quarter. The reputed customer engagement platform showcased continued momentum across both its product strategy and financial performance. The company generated topline figure of $227.2 million, an impressive 26.2% increase compared to the same period last year. This revenue growth was fueled by upselling gains, customer additions and renewals. The company posted $24.2 million in cash flow from operating activities, a monumental growth relative to $7 million in the same period a year ago. This was paired with $21.7 million in free cash flow, against $3.5 million during Q2 FY26.
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue


2 months ago
Netskope Inc. (NASDAQ:NTSK) announced its second quarter results on September 2. The cloud and AI-led security and networking company saw a 27% year-over-year jump in its annual recurring revenue that climbed to $899 million. Total revenue for the recent quarter came in at $220.5 million, equating to a 29% growth compared to the same period last year. The company surpassed management's prior guidance across all metrics.
Gts/Shutterstock.com
The second quarter strength can be attributed to a robust demand for Netskope One platform. This was further supported by the company's continued organic innovation. Netskope is currently positioned right at the convergence of AI, networking, security, and ****** ytics, which makes strengthen its position as enterprises look for secure AI adoption. On the profitability front, the company reported gross profit of $169.1 million on adjusted basis, resulting in a marginal jump in adjusted gross margins to 77%, compared to 75% during the same period last year.
During the quarter, Netskope also introduced some new offerings and advanced features. These include the Netskope One DataSec Command Center, which is a unified platform for tracking and protecting sensitive data across endpoints, cloud, AI environments, and more. The company also brought enhancements to its NewEdge AI Fast Path capability, which, according to company testing, reduced latency by as much as 90% to popular AI destinations.
Following the second quarter, management issued guidance for the upcoming quarter, estimating topline figures between $227 million and $229 million. It has projected full-year revenue between $888 million and $892 million, along with adjusted gross margin of around 77% and a free cash flow margin of nearly 2%.
#second


2 months ago
On September 2, NetApp Inc. (NASDAQ:NTAP) reported its Q1 FY27 results, posting record quarterly net revenue of $2.03 billion. Topline for the Intelligent Data Infrastructure company expanded by 30% compared to the first quarter in FY26. The quarter saw a broad-based growth across its core segments, resulting in a record adjusted earnings per share of $2.58, and a quarterly cash dividend of $0.52 per share. The company also strengthened its existing engagements with major players, covering a range of underlying functions.
During the first quarter, all-flash array net revenue went up 47% year-over-year, hitting a record $1.3 billion mark. This drove the overall net revenue for its Hybrid Cloud segment to $1.8 billion, translating into a 30% year-over-year growth. Public Cloud, which accounts for a smaller chunk of the business, saw its net revenue climb by 28%, also setting a record of $206 million. NetApp's total billings clocked in at $2.06 billion, exhibiting a 36% growth compared to Q1 FY26, while its non-GAAP operating margin reached 31.9%.
During the quarter, NetApp finalized the acquisition of an AI-enabled data infrastructure business, DataPelago. The deal is aimed toward facilitating customers streamline and accelerate large-scale AI deployments. On the product front, the company launched StorageGRID 12.1, to support scaling of AI workload through a federated global namespace. It also introduced Instaclustr for its fully managed Model Context Protocol Gateway, along with enhanced support for Azure NetApp Files up to 64 TiB.
NetApp also revealed new features for NetApp Trident software 26.06. These include deeper integration of OpenShift Virtualization, non-disruptive iSCSI rebalancing, efficient volume placement, and additional cloud support.
Despite encouraging numbers reported during the quarter, the free cash flows settled at $401 million. This was a 35% drop compared to figures reported for Q1 FY26. Additionally, NetApp remains heavily dependent on its Hybrid Cloud business, which generated roughly 90% of quarterly revenue, while Public Cloud still contributes a relatively small fraction of the topline despite growing 28% during the recent quarter. This leads to concerns regarding how much of the company's growth story is truly cloud-native compared to conventional on-premises hardware refresh cycles that are strongly tied to AI infrastructure investments. For the underlying all-flash arrays, such AI-linked demand trend could prove to be front-loaded or cyclical in case enterprise capital expenditure decelerates.
#netapp #Growth


2 months ago
On September 2, Michael Genovese from Rosenblatt Securities reiterated his Neutral rating for Credo Technology Group Holding Ltd (NASDAQ:CRDO). The **** yst increased his price target for the stock from $215 to $235, which implies upside potential of almost 38% as of September 4 closing. Genovese's upward adjustment in price target in based on the company's recently announced Q1 FY27 results, leading him to increase his projections for FY27 and FY28. Despite that, he has a Neutral stance because he still wants more visibility around the company's ZeroFlap Optical Transceivers proof points, as well as the incremental revenues from its acquisition of Dust Photonics in May.
Photo by Yogesh Phuyal on Unsplash
Credo's acquisition of DustPhotonics gives it a vertically integrated connectivity stack covering DSP, silicon photonics, SerDes and system integration. This allows the company to tap into both optical and electrical interconnects across the entire AI infrastructure buildout. Together with its optical DSPs and ZeroFlap transceivers, the deal is expected to be a key growth driver in FY27, supported by resilient hyperscale customer sentiment.
Following the DustPhotonics transaction, Credo reported a strong first quarter for FY27. Topline of $479 million jumped 115% compared to Q1 in FY26. Adjusted non-GAAP net income of $236.3 million was up 140% year-over-year, as the company broadens its connectivity portfolio stack. It now spans copper and optical solutions, ranging from millimeters to kilometers, which enables Credo to meet the scaling needs of AI infrastructure with energy-efficient and reliable products.
For FY27, Credo expects a strong inflection with optical revenues expected to exceed $600 million. Management projects contributions over $100 million each from silicon photonics, ZeroFlap optics, and optical DSPs. Full-year revenue growth is expected to be over 85% year-over-year. Adjusted gross margins are likely to remain consistent with fiscal 2026 levels, along with adjusted net margins of around 50%.
#expected

2 months ago
On August 5, Vaxcyte (NASDAQ:PCVX) reported second-quarter results that read less like a snapshot of today and more like a countdown to a verdict. The clinical-stage vaccine maker has no product on the market yet, but its three late-stage trials for its lead pneumococcal candidate are now fully enrolled, with the first major readout due before year-end. Add a net loss that nearly doubled and a boardroom that just brought in two vaccine-industry veterans, and you have a company betting its near-term story on data still to come.
Vaxcyte's three Phase 3 studies of VAX-31, its next-generation pneumococcal conjugate vaccine, have dosed 6,191 adults combined, with roughly 3,500 of them receiving the actual candidate. The largest, OPUS-1, put 4,049 participants through head-to-head comparisons against Prevnar 20 and Capvaxive, the two shots VAX-31 needs to beat to earn a spot in the standard vaccination schedule. Data on safety, tolerability, and immune response from that trial are due in the fourth quarter of 2026, with results from OPUS-2 and OPUS-3 following in the first half of 2027.
A separate Phase 2 study testing VAX-31 in infants, covering both the primary immunization series and a booster dose, is on a similar timeline. In June, Vaxcyte also dosed the first participants in a Phase 1 study of VAX-A1, aimed at preventing disease from Group A Streptococcus, with topline data expected in the second half of 2027. As of June 30, cash and investments stood at $2.5 billion, up from $2.44 billion at the end of 2025, and the board added Dr. Moncef Slaoui, previously chief scientific advisor to Operation Warp Speed and a three-decade GSK veteran, alongside Dr. John Markels, the former president of Merck's global vaccines business.
None of that pipeline progress comes cheap. Vaxcyte's net loss for the quarter ended June 30 was $284.3 million, up from $166.6 million in the same period a year earlier, and the increase shows up on both sides of the ledger. R&D spending rose to $267.9 million from $194.2 million, driven by manufacturing work to prepare for a possible launch and by the cost of running three simultaneous Phase 3 trials at once. G&A expenses climbed too, to $34.9 million from $32 million, largely from adding headcount.
Because Vaxcyte has no approved product generating sales, every one of those dollars comes straight off the balance sheet. The calendar adds pressure of its own: even a clean OPUS-1 readout in the fourth quarter of 2026 still leaves the OPUS-2 and OPUS-3 results, plus a required manufacturing consistency study, sitting in the first half of 2027, pushing any license application and launch well beyond that. The newer VAX-A1 program is earlier still, with its second stage contingent on a safety board signing off on the first.
#phase

2 months ago
On August 6, Xponential Fitness (NYSE:XPOF) reported results for the second quarter ended June 30, and the numbers came in well short of where the boutique-fitness franchisor wanted to be. Revenue fell 13% year over year to $66 million, and the company swung to a net loss of $4.8 million after posting net income in the same period last year. CEO Mike Nuzzo said the quarter came in "below expectations." The bigger story sits in the outlook section, where the company trimmed nearly every full-year target it had set.
Despite the weak headline numbers, Xponential kept adding to its network. The company opened 67 gross new studios and sold 53 franchise licenses during the quarter, a sign that franchisee demand for its brands hasn't disappeared. North America system-wide sales held essentially flat at $437.3 million, which means new locations are offsetting some of the softness at existing studios rather than the whole system contracting. Even after cutting its 2026 targets, the company still expects to open roughly 150 net new studios for the year and generate North America system-wide sales of $1.7 billion to $1.75 billion. Full-year adjusted EBITDA guidance, while lowered, still points to $91 million to $97 million, meaning the business is still projected to be solidly profitable on that measure.
The details underneath the topline number are worse than the revenue decline alone suggests. North America same-store sales fell 6.8%, a sharp reversal from 2.4% growth in the same period a year earlier, and the quarterly run-rate average unit volume dropped to $659,000 from $686,000. Franchise revenue slipped 3% to $44 million on that same-store weakness plus brand divestitures completed in 2025, while equipment revenue dropped 26% to $7.1 million as fewer studio openings and license sales meant fewer installations. Merchandise revenue nearly vanished, falling 90% to $0.5 million as the company shifted from an in-house wholesale model to an outsourced retail arrangement, a transition it admitted came with its own challenges.
Costs moved the wrong direction too, with selling, general and administrative expenses up 33% to $32 million on higher legal expenses, and marketing fund expenses up 29% to $11.4 million. Adjusted EBITDA fell 22% to $21.9 million, and adjusted net income collapsed to $0.8 million from $14.5 million a year earlier. The balance sheet adds another concern, with just $25 million in cash, cash equivalents, and restricted cash against $522.4 million in total long-term debt, and $25.7 million in cash used in operating activities during the quarter. Management responded by cutting full-year revenue guidance to $250 million to $260 million, a 19% decline at the midpoint from 2025 and down from a prior forecast of $260 million to $270 million.
#million #quarter #north #sales


2 months ago
On August 18, Austin Moeller from Canaccord Genuity reiterated his Buy rating for Intuitive Machines (NASDAQ:LUNR). Despite cutting his price target from $41 to $39, his estimates result in almost 165% upside potential as of September 1 closing. Moeller's stance is based on the company's second quarter announcement on August 13. The management reiterated its full-year 2026 guidance, projecting topline figures between $900 million and $1 billion, along with positive adjusted EBITDA. Chief Executive Officer, Steve Altemus, reflected on the company's performance by stating:
"We delivered a strong quarter, highlighted by revenue over four times Q2 2025 as we executed across our programs, recorded unprecedented bookings and backlog, and positioned the Company for the next phase of growth."
Sergey Nivens/Shutterstock.com
The second quarter saw Intuitive Machines (NASDAQ:LUNR) posting record quarterly revenue figures of $206.17 million. This equates to a 310% growth compared to a $50.31 million topline during the same period last year. This can be attributed to execution across the company's commercial lunar payload services, omnibus multidisciplinary engineering services, near ****** e network services, and ****** ecraft production programs. During the second quarter, it booked additional $920 million of awards and ended the quarter with an order backlog of $1.8 billion. This represented a substantial jump compared with December-end backlog of $213.1 million. It is pertinent to highlight that $612.8 million of the total order backlog is linked to the company's acquisition of Lanteris, earlier in 2026.
The business mix exhibited a material shift during the second quarter. National security programs saw a notable jump in revenue contribution, accounting for roughly 30% of the topline compared to just 3% in Q2 2025. The company has been actively pursuing opportunities to expand its pipeline of defense and satellite communication programs. It recently received authorization to proceed on a $600 million multi-satellite communications infrastructure program. The company will leverage its IM 1300 satellite platform to design, manufacture, integrate, and support multiple ****** ecraft. This award validates the Intuitive Machines' IM 1300 platform for large-scale procurements, and strengthens its footprint in satellite communications infrastructure.
#intuitive #machines #company

2 months ago
On August 5, Vaxcyte (NASDAQ:PCVX) reported second-quarter results that read less like a snapshot of today and more like a countdown to a verdict. The clinical-stage vaccine maker has no product on the market yet, but its three late-stage trials for its lead pneumococcal candidate are now fully enrolled, with the first major readout due before year-end. Add a net loss that nearly doubled and a boardroom that just brought in two vaccine-industry veterans, and you have a company betting its near-term story on data still to come.
Vaxcyte's three Phase 3 studies of VAX-31, its next-generation pneumococcal conjugate vaccine, have dosed 6,191 adults combined, with roughly 3,500 of them receiving the actual candidate. The largest, OPUS-1, put 4,049 participants through head-to-head comparisons against Prevnar 20 and Capvaxive, the two shots VAX-31 needs to beat to earn a spot in the standard vaccination schedule. Data on safety, tolerability, and immune response from that trial are due in the fourth quarter of 2026, with results from OPUS-2 and OPUS-3 following in the first half of 2027.
A separate Phase 2 study testing VAX-31 in infants, covering both the primary immunization series and a booster dose, is on a similar timeline. In June, Vaxcyte also dosed the first participants in a Phase 1 study of VAX-A1, aimed at preventing disease from Group A Streptococcus, with topline data expected in the second half of 2027. As of June 30, cash and investments stood at $2.5 billion, up from $2.44 billion at the end of 2025, and the board added Dr. Moncef Slaoui, previously chief scientific advisor to Operation Warp Speed and a three-decade GSK veteran, alongside Dr. John Markels, the former president of Merck's global vaccines business.
None of that pipeline progress comes cheap. Vaxcyte's net loss for the quarter ended June 30 was $284.3 million, up from $166.6 million in the same period a year earlier, and the increase shows up on both sides of the ledger. R&D spending rose to $267.9 million from $194.2 million, driven by manufacturing work to prepare for a possible launch and by the cost of running three simultaneous Phase 3 trials at once. G&A expenses climbed too, to $34.9 million from $32 million, largely from adding headcount.
Because Vaxcyte has no approved product generating sales, every one of those dollars comes straight off the balance sheet. The calendar adds pressure of its own: even a clean OPUS-1 readout in the fourth quarter of 2026 still leaves the OPUS-2 and OPUS-3 results, plus a required manufacturing consistency study, sitting in the first half of 2027, pushing any license application and launch well beyond that. The newer VAX-A1 program is earlier still, with its second stage contingent on a safety board signing off on the first.
#opus #data
2 months ago
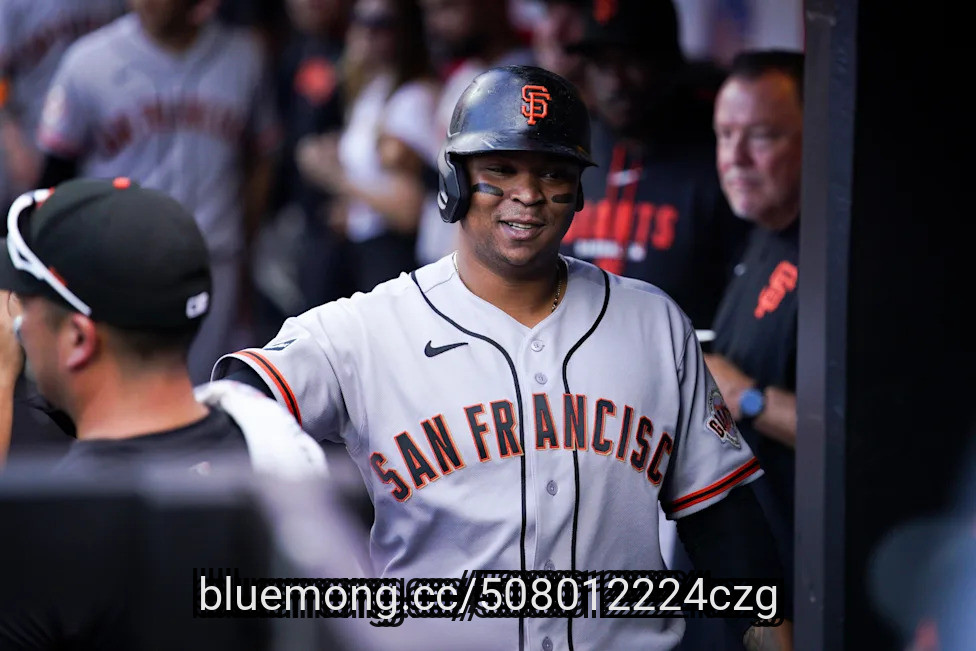
Zac Thornton entered today's game with a 2.93 ERA in 11 starts. It's been quite the surprising season for the rookie lefty, who has managed those impressive topline numbers despite boasting less than flashy stuff and underlying peripherals. Alas, those topline numbers look a little bit worse after today's game, as Thornton underwent his worst start as a major leaguer, and the Mets were not able to work themselves out of the hole he put them in, resulting in a 9-5 loss to the Giants.
San Francisco struck within minutes of the game's start, as Rafael Devers socked Thornton's fourth pitch of the afternoon over the right field wall for a one-out solo homer. The Mets answered back in the bottom of the second when A.J. Ewing—who has been struggling mightily in the second-half—socked a two-out, two-run homer off Giants starter Anthony Molina. That gave the Amazins a 2-1 lead, but unfortunately they would not hold it for long. Thornton surrendered a lead-off single in the third inning, followed by a two-run blast to Christian Koss to put the Giants back in front.
Thornton went on to retire his next eight batters, right up until Koss—who entered today's game with just one homer this season—came to the plate again in the top of the fifth, and he hit his second home run of the afternoon. Not to be outdone, Devers came up two batters later following a single and socked his second home run of the day. Thornton surrendered one hit—a double from Bryce Eldridge, the fourth straight two-out hit of the inning—before finally retiring the Giants, but it was now a 6-2 ballgame.
Meanwhile, the Mets's bats did little against Molina after Ewing's homer (that hit in fact remained the only one surrendered by the Giants through six innings). Both teams went to their bullpens in the sixth inning—albeit with Molina's final line looking a lot better than Thornton's ugly one (5 innings, 7 hits, 1 walk, 6 strikeouts, 6 runs). Chris Devenski was the first reliever up for the Mets, and he did his job by tossing two scoreless innings. The bats finally got something going in the bottom of the seventh, when two singles and a walk loaded the bases with one out. Francisco Alvarez struck out swinging for the second out, but the Mets then finally got another run on the board when Brett Baty walked to bring in a run and make it 6-3. Alas, the potential tying run was stranded, as Francisco Lindor grounded out to first to end the threat.
And the Giants quickly acted to make sure the Mets would not continue to claw their way back into the game. Jefry Yan took the mound in the top of the eighth and issued a one-out walk to Eldridge, followed by a two-run homer from Osleivis Basabe. That made it 8-3, but San Francisco still wasn't quite done. Justin Hagenman pitched the ninth, and just like every non-Devenski Mets pitcher of the day, he surrendered a homer—this one a one-out solo shot for Grant McCray. That made it six dingers for the Giants, in case you weren't keeping count.
#METS #h


2 months ago
On August 10, Joe Gomes from ***** le Capital reiterated his Outperform rating on CoreCivic Inc. (NYSE:CXW). In the process, the ***** yst increased his target price on the stock from $35 to $42, resulting in a revised upside potential in excess of 24% based on stock's closing price on August 27. This upward adjustment in price target came after an impressive second quarter print above management estimates. Let's explore the underlying drivers of this outperformance, and which additional factors are expected to shape up investor sentiment toward the stock.
Earlier in August, the company reported its second quarter results which exceeded management's expectations. Topline figures were recorded at $684.9 million, up by 27.3% compared to Q2 2025. Adjusted EBITDA of $109.4 million exhibited 5.9% year-on-year growth, while adjusted diluted EPS of $0.38 reflected a 5.6% growth compared to the same period last year. Such expansion in adjusted diluted EPS was supported by lower operating costs and slightly higher ICE populations, while strong federal revenue also contributed to growth. Following the quarter and subsequent facility sales, management raised its full-year 2026 guidance.
During 2026, CoreCivic has been focusing on strengthening its financial position while expanding its footprint as a federal detention operator. The company generated $734 million in gross proceeds from sales of Prairie Correctional Facility and Midwest Regional Reception Center, to the Department of Homeland Security. It expects to continue to operate both facilities under current arrangements, and was also awarded a new ICE contract to operate the 1,600 bed Prairie Correctional Facility till August 2031. The contract award offers potential for $75 million in revenue boost in the future once fully activated, with no material impact expected during 2026.
CoreCivic can benefit from this demand tailwind without the time and capital required to construct entirely new facilities, although activating idle sites still involves staffing and start-up costs. It also strengthens the company's position as a trusted partner for federal detention requirements, and might create potential opportunities for more contracts in the future.
The company has also taken an aggressive approach toward debt reduction and returning capital to shareholders. On August 10, it entered a $500 million accelerated share repurchase agreement, supported by the proceeds from recent facility sales. A portion of those sale proceeds was also utilized for $608.5 million debt repayment, which included early redemption of senior notes that were due in 2027.
#price

2 months ago
On August 13, Kodiak Sciences Inc. (NASDAQ:KOD) reported second-quarter financial results for the period ended June 30, alongside an update on its three late-stage eye disease programs. The clinical-stage biotech told investors it now sits within months of three separate Phase 3 readouts, a stretch CEO Victor Perlroth called the payoff of years of disciplined execution. For a company with no approved products and a widening cash burn, those trial results are about to decide a lot.
Kodiak's near-term story rests on Zenkuda and KSI-501, both being tested in the Phase 3 DAYBREAK study for treatment-naive wet age-related macular degeneration, with one-year primary endpoint topline data due in September 2026. Zenkuda already has four completed Phase 3 studies behind it. In GLOW1 and GLOW2, every patient remained on extended six-month dosing at one year, and in BEACON, nearly half of Zenkuda patients needed no further treatment in the second six months while matching aflibercept on vision and anatomical outcomes. That durability comes from a mean ocular half-life of 20 days, roughly three times longer than approved anti-VEGF drugs.
Behind DAYBREAK sits PEAK, evaluating KSI-101 in macular edema secondary to inflammation, where Kodiak finished enrolling the first 300-patient cohort during the quarter and expects Pivotal ***** ysis 1 data in December 2026. Earlier Phase 1b data showed more than half of MESI patients gaining at least 15 letters of vision, with over 90% resolution of retinal fluid by week eight. Kodiak also began enrolling patients in the roughly 910-patient ALTO study testing KSI-501 against aflibercept in diabetic macular edema, its second registrational trial for that molecule. Zenkuda and KSI-501 together are aimed at a $15 billion anti-VEGF market.
None of that comes cheap. Kodiak's net loss widened to $65.6 million in the second quarter of 2026, or $1.05 per share, up from $54.3 million and $1.03 per share a year earlier. R&D spending jumped to $56.1 million from $42.8 million, as the company ramped up clinical activity across PEAK and PINNACLE and stepped up manufacturing for its Phase 3 programs. General and administrative costs eased slightly to $10.8 million from $12.8 million, but that was not enough to offset the R&D increase.
Kodiak ended the quarter with $125.9 million in cash and equivalents, which management says covers operations into 2027, but working capital fell from $169.3 million at the end of 2025 to $78.6 million by June 30, and stockholders' equity dropped from $157.4 million to $61.1 million over the same stretch. With three separate trials due to report between September and December, any delay or disappointing result would hit a balance sheet that already has less room to absorb it.
#data


2 months ago
On August 5, LTC Properties (NYSE:LTC) reported second-quarter results for the period ended June 30, 2026, and the numbers show a real estate investment trust leaning harder into a strategy it only started a year ago. Total revenue climbed to $98.9 million from $60.2 million a year earlier, and net income available to common stockholders nearly doubled to $29.5 million. Diluted earnings per share rose to $0.56 from $0.32. Alongside the results, the company raised its full-year 2026 investment guidance by 50% at the midpoint, putting more weight behind a business line called SHOP.
LTC increased the midpoint of its 2026 SHOP investment guidance to $900 million, calling that figure a jump of 50% from the previous midpoint. Management now expects $700 million in year-to-date SHOP acquisitions by the end of the third quarter, and projects SHOP will represent 40% of pro forma annualized net operating income by that same point, which the company says is ahead of its own estimates. LTC expects that share to approach 50% by year-end, with a stated pathway toward 75% by the end of 2028.
Since launching the platform in May 2025, LTC has built the SHOP portfolio to 39 communities across 12 operators, 10 of which are new relationships for the company, representing 37% of total gross real estate investments as of July 31, 2026. Second quarter core SHOP NOI came in at $13.3 million. The company closed $171 million in acquisitions during the quarter and expects another $529 million to close in the third quarter, with $208 million of that already done. LTC also raised its full-year diluted earnings per share guidance to $8.08 to $8.10 and expanded its credit facility to $1.1 billion, leaving $648 million in total pro forma liquidity.
Growth this fast comes with a cost that shows up once you move past revenue. Core FFO per diluted share held flat at $0.68, unchanged from a year earlier even though revenue grew 64%. Core FAD per diluted share actually slipped to $0.70 from $0.71. Part of the explanation is share count. Diluted weighted average shares outstanding rose to 52.2 million from 46.0 million, and total shares outstanding climbed to 53.9 million from 46.1 million, dilution that has kept per-share growth well behind the topline.
Expenses grew just as fast as revenue did. Total expenses nearly doubled to $75.5 million from $44.5 million, with senior housing operating expenses, the direct cost of running SHOP, jumping to $42.2 million from $9.4 million as the new segment scaled up. Interest expense rose to $9.5 million from $8.0 million, and $356 million remains drawn on the revolving credit line even after that facility's expansion. SHOP also depends on the 12 third-party operators running those communities day to day, 10 of which have never worked with LTC before, concentrating execution risk in relationships still being tested.
#million #company

2 months ago
On August 11, Kristina Ruggeri from Argus upgraded The Boeing Company (NYSE:BA) from Hold to Buy, based on the company's long-term prospects within the expanding commercial aerospace segment. The ****** yst expects the company's impressive backlog, topline growth and margins to continue expanding after the management made progress in addressing concerns linked with production and profitability. Ruggeri's price target of $265 results in more than 26% upside potential as of August 28 closing. Let's explore the underlying business fundamentals that support this rating upgrade.
Recent financials clearly back the rating upgrade by Argus, as the company reported $24.6 billion in Q2 2026 revenue compared to $22.7 billion during Q2 2025. The 8% topline expansion primarily reflected 171 commercial deliveries during the quarter. Despite a core loss of ($0.76) per share, the company's cash flows turned positive amid improved working capital. In the second quarter, it posted $1.4 billion in operating cash flow and $631 million in free cash flow. Management reiterated its optimistic FCF projections, with a full-year guidance between $1 billion and $3 billion, depending partly on delivery volumes and timing of customer receipts.
The company's demand backlog further strengthens the bullish narrative, as it reported $715 billion in total backlog by the end of second quarter. This included a backlog of $597 billion for commercial airplanes segment, involving more than 6,200 aircraft. It is composed of thousands of orders for 737 MAX, along with elevated demand across its wide-body segment covering 767, 777, and 787 programs. Backlogs for Defense, ****** e & Security, and Global Services segments stood at $85 billion and $33 billion, respectively.
Company President and CEO, Kelly Ortberg, reflected on the remainder of the year, stating:
"While there is more work ahead in the second half of the year, the momentum we are building continues to move Boeing in the right direction."
#second

2 months ago
BioNTech SE (NASDAQ:BNTX) rallied following the first positive interim Phase 3 topline result for a personalized mRNA cancer therapy. Moderna and Merck said intismeran, combined with Keytruda, significantly improved recurrence-free and distant metastasis-free survival in patients with surgically removed high-risk melanoma. The result lifted other mRNA developers because it provided the strongest evidence yet that the technology can work against cancer in a large late-stage trial. For BioNTech SE (NASDAQ:BNTX), however, the rally raises a harder question: does validation of the therapeutic class meaningfully improve the odds for its own candidates, or has the market moved ahead of company-specific evidence?
The distinction matters. Moderna's intismeran is individually designed around mutations found in each patient's tumor. BioNTech SE (NASDAQ:BNTX) is awaiting an interim ******* ysis from the Phase 3 portion of AHEAD-MERIT, which tests BNT113 with pembrolizumab in first-line unresectable recurrent or metastatic HPV16-positive, PD-L1-positive head-and-neck squamous cell carcinoma. BNT113 is an off-the-shelf FixVac therapy encoding the HPV16 E6 and E7 oncoproteins. Different antigens, manufacturing approaches, cancer types and treatment settings prevent Moderna's result from functioning as a direct clinical read-through.
Still, BioNTech SE (NASDAQ:BNTX) has more than one attempt at building an oncology franchise. The company has 14 ongoing pivotal trials across mRNA immunotherapies, immunomodulators and antibody-drug conjugates. It expects three late-stage readouts during 2026, including the BNT113 interim ******* ysis, and ended June with €16.6 billion in cash, cash equivalents and security investments.
The bull case for BioNTech SE (NASDAQ:BNTX) is that Moderna and Merck have reduced skepticism around the broader platform. Their trial enrolled 1,137 patients and met its primary endpoint of recurrence-free survival and a secondary endpoint of distant metastasis-free survival, with no new safety concerns reported. The result shows that an mRNA therapy can add meaningful benefit to a checkpoint inhibitor in Phase 3.
BioNTech also has a personalized program that more closely resembles intismeran. Autogene cevumeran, partnered with Genentech, is being studied in randomized Phase 2 trials in pancreatic and colorectal cancer. Meanwhile, BNT113 has FDA Fast Track designation and could provide BioNTech's own pivotal mRNA evidence. The company's cash position gives it room to fund these programs and absorb failures elsewhere in the portfolio.
#biontech
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alcon Inc. (NYSE:ALC). Alcon Inc. (NYSE:ALC) is a Swiss-based healthcare and medical technology company focused on eye care products. On August 21, 2026, Alcon Inc. (NYSE:ALC) closed at $73.63 per share. The one-month return of Alcon Inc. (NYSE:ALC) was 9.44% and its shares lost 8.83% over the past 52 weeks. Alcon Inc. (NYSE:ALC) has a market capitalization of $36.68 billion.
SGA Global Growth Strategy stated the following regarding Alcon Inc. (NYSE:ALC) in its Q2 2026 investor letter:
"During the quarter, we exited our position in Alcon Inc. (NYSE:ALC). Alcon remains a leader in eye care with exposure to increasing secular demand driven by aging and myopia, with market leadership across multiple categories. Strong launches in new equipment and eye drops drove topline growth of 6% constant currency and earnings per share growth of 16%+ in Q1. This was slightly below expectations of 7% growth, as the market for cataracts and contact lenses remains subdued. Additionally, the premium intraocular lens for cataracts is getting more competitive, with Alcon remaining the leader but expected to continue to cede share from the highs of 80%+ as competitors are catching up. Management continues to execute well on product launches to offset pressures in intraocular lens, which accounts for 17% of total sales. However, to account for the increased competition and subdued market conditions overall, we gradually reduced the position before ultimately redeploying the capital into a higher growth opportunity in Schneider Electric."
#strategy
2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Alcon Inc. (NYSE:ALC). Alcon Inc. (NYSE:ALC) is a Swiss-based healthcare and medical technology company focused on eye care products. On August 21, 2026, Alcon Inc. (NYSE:ALC) closed at $73.63 per share. The one-month return of Alcon Inc. (NYSE:ALC) was 9.44% and its shares lost 8.83% over the past 52 weeks. Alcon Inc. (NYSE:ALC) has a market capitalization of $36.68 billion.
SGA Global Growth Strategy stated the following regarding Alcon Inc. (NYSE:ALC) in its Q2 2026 investor letter:
"During the quarter, we exited our position in Alcon Inc. (NYSE:ALC). Alcon remains a leader in eye care with exposure to increasing secular demand driven by aging and myopia, with market leadership across multiple categories. Strong launches in new equipment and eye drops drove topline growth of 6% constant currency and earnings per share growth of 16%+ in Q1. This was slightly below expectations of 7% growth, as the market for cataracts and contact lenses remains subdued. Additionally, the premium intraocular lens for cataracts is getting more competitive, with Alcon remaining the leader but expected to continue to cede share from the highs of 80%+ as competitors are catching up. Management continues to execute well on product launches to offset pressures in intraocular lens, which accounts for 17% of total sales. However, to account for the increased competition and subdued market conditions overall, we gradually reduced the position before ultimately redeploying the capital into a higher growth opportunity in Schneider Electric."
#market #strategy #Portfolio #quarter


