8 days ago
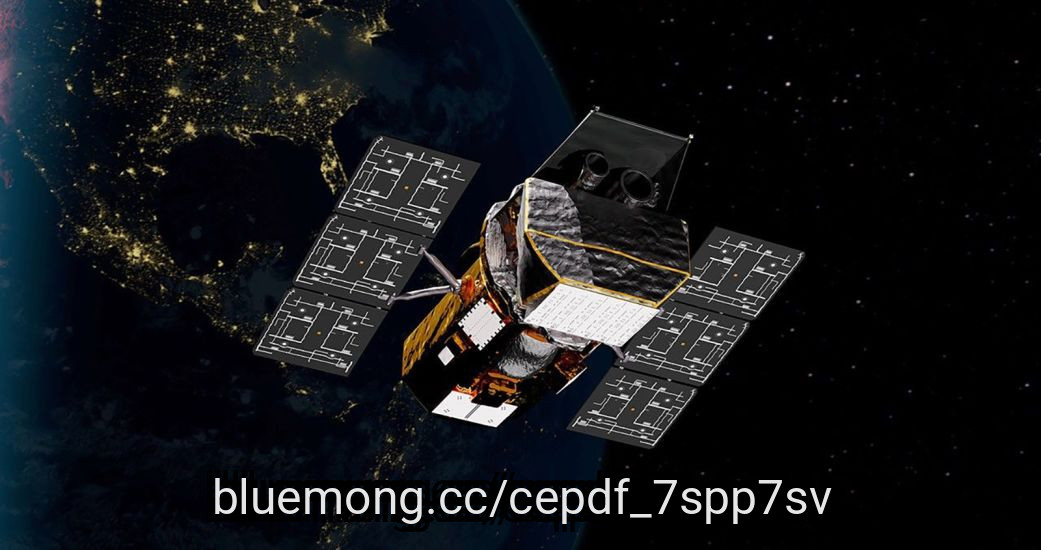
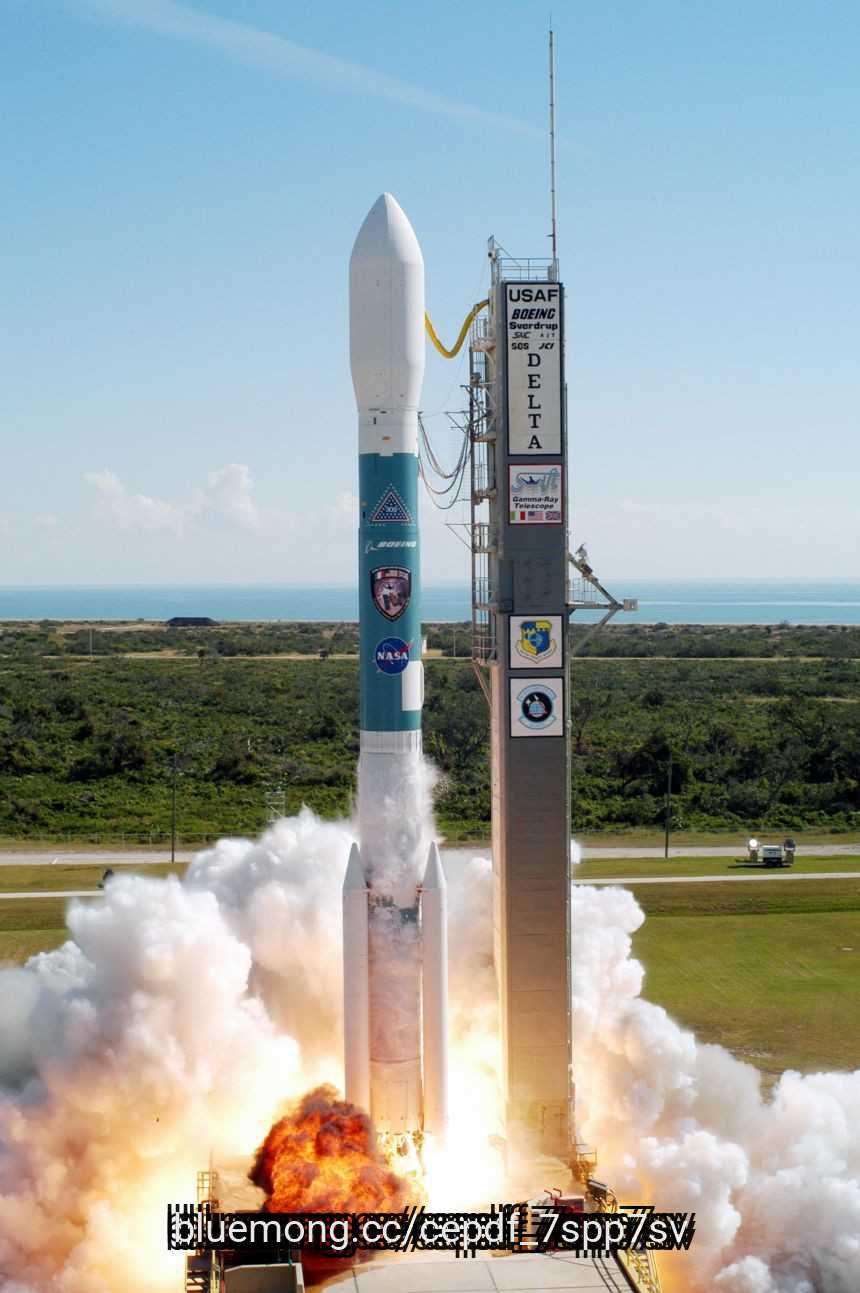
NASA’s Neil Gehrels Swift Observatory met a fiery end on Wednesday morning, nearly 22 years after it launched to study the most powerful explosions in the universe.
Data from the US ******* e Force estimates the 3,200-pound ******* ecraft plunged into Earth’s atmosphere over Indonesia around 7:39 a.m. ET.
While most of the observatory was expected to burn up as it blazed through the thick inner band of Earth’s atmosphere, NASA predicted some pieces of the vehicle would survive.
It was not immediately clear whether any surviving debris hit land. Previously, NASA had predicted that the “risk of harm coming to anyone on Earth is unlikely, approximately 1 in 2,100.”
If Swift were launched today, it would likely have to adhere to far stricter safety guidelines regarding end-of-life planning, according to The Aerospace Corporation, which is a federally funded research and development center.
#observatory
Data from the US ******* e Force estimates the 3,200-pound ******* ecraft plunged into Earth’s atmosphere over Indonesia around 7:39 a.m. ET.
While most of the observatory was expected to burn up as it blazed through the thick inner band of Earth’s atmosphere, NASA predicted some pieces of the vehicle would survive.
It was not immediately clear whether any surviving debris hit land. Previously, NASA had predicted that the “risk of harm coming to anyone on Earth is unlikely, approximately 1 in 2,100.”
If Swift were launched today, it would likely have to adhere to far stricter safety guidelines regarding end-of-life planning, according to The Aerospace Corporation, which is a federally funded research and development center.
#observatory
1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Internal Revenue Service is issuing notices to taxpayers stating that they may qualify for the Saver's Match, a government-funded $1,000 retirement account contribution, beginning in 2027. The program replaces the Saver's Credit, which ends on Dec. 31, 2026.
Taxpayers who previously filed for that credit are receiving a notification about the new program, which will provide a matching contribution of up to $1,000 for single filers and $2,000 for joint filers in the 2027 tax year.
Here's the latest on who is eligible.
Read more: Retirement planning by age: The complete guide for your 20s-70s
#credit #internal #revenue
The Internal Revenue Service is issuing notices to taxpayers stating that they may qualify for the Saver's Match, a government-funded $1,000 retirement account contribution, beginning in 2027. The program replaces the Saver's Credit, which ends on Dec. 31, 2026.
Taxpayers who previously filed for that credit are receiving a notification about the new program, which will provide a matching contribution of up to $1,000 for single filers and $2,000 for joint filers in the 2027 tax year.
Here's the latest on who is eligible.
Read more: Retirement planning by age: The complete guide for your 20s-70s
#credit #internal #revenue


1 month ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Deciding how much to withdraw from your retirement accounts means finding a balance between enjoying life and making your money last. Taking too little leaves you with unused savings, while taking too much risks running out of money later. Taxes also affect how much you can actually spend. To help you create a retirement budget, let's break down the example of a 67-year-old with $870,000 in a 401(k), $120,000 in an IRA and $26,400 annually from Social Security. Here's what a withdrawal plan could look based on two rates.
A financial advisor can help you create a withdrawal strategy that balances your lifestyle needs, tax impacts and long-term retirement goals.
A 401(k) and a traditional IRA are both retirement accounts funded with pre-tax dollars. Contributions are deducted from your taxable income, allowing you to grow savings faster because the money enters the account before taxes. In retirement, however, all withdrawals are taxed as ordinary income. This includes both the money you contributed and the investment earnings.
This is different from a Roth IRA, which is funded with after-tax dollars. You do not receive an upfront tax deduction for contributions. The benefit comes later: withdrawals in retirement are tax-free, including both contributions and earnings.
#taking #taxes #later #Help
Deciding how much to withdraw from your retirement accounts means finding a balance between enjoying life and making your money last. Taking too little leaves you with unused savings, while taking too much risks running out of money later. Taxes also affect how much you can actually spend. To help you create a retirement budget, let's break down the example of a 67-year-old with $870,000 in a 401(k), $120,000 in an IRA and $26,400 annually from Social Security. Here's what a withdrawal plan could look based on two rates.
A financial advisor can help you create a withdrawal strategy that balances your lifestyle needs, tax impacts and long-term retirement goals.
A 401(k) and a traditional IRA are both retirement accounts funded with pre-tax dollars. Contributions are deducted from your taxable income, allowing you to grow savings faster because the money enters the account before taxes. In retirement, however, all withdrawals are taxed as ordinary income. This includes both the money you contributed and the investment earnings.
This is different from a Roth IRA, which is funded with after-tax dollars. You do not receive an upfront tax deduction for contributions. The benefit comes later: withdrawals in retirement are tax-free, including both contributions and earnings.
#taking #taxes #later #Help

1 month ago
She's done everything right: raised four kids, largely as a single mother, has no debt and a fully funded emergency savings account. Her retirement savings are about $1 million split between a "Roth and 401(k)," and her paid-off home in Illinois is worth around $350,000.
By almost any measure, this woman has won. So why does she want to give it all up and rent?
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 reasons why retirees can't afford to waste time
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
#savings #illinois #americans #asap
By almost any measure, this woman has won. So why does she want to give it all up and rent?
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 reasons why retirees can't afford to waste time
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
#savings #illinois #americans #asap

1 month ago
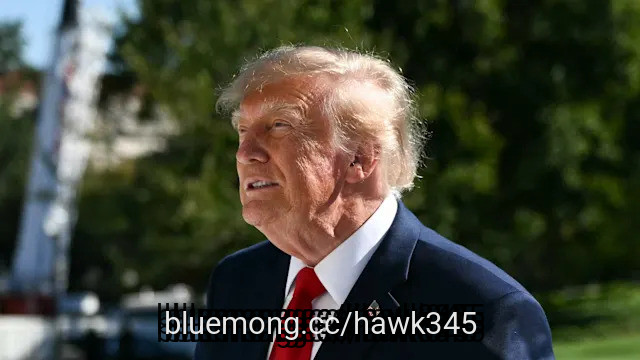
WASHINGTON (AP) — A day after President Donald Trump said he would start paying for controversial taxpayer-funded ads with a campaign account, there's no sign he plans to refund the millions of federal dollars already spent on them.
Nearly $12 million worth of ads have already aired, according to AdImpact, as part of the $20 million the Department of Homeland Security tapped for the contract.
But Trump's plan to pay for the ads with MAGA Inc. doesn't mean there's any reimbursement coming, said a White House official who was not authorized to talk publicly and spoke on the condition of anonymity.
Speaking to reporters Tuesday, Trump said the ads were "really good" and "promotion for the country, done by many presidents before." Asked whether he'd repay the funds already spent, he said, "We'll decide."
Senate Democratic Leader Chuck Schumer slammed Trump for not committing to reimbursement and said he believes the president's plan for covering future costs represents illegal coordination with his super PAC.
#Trump #donald
Nearly $12 million worth of ads have already aired, according to AdImpact, as part of the $20 million the Department of Homeland Security tapped for the contract.
But Trump's plan to pay for the ads with MAGA Inc. doesn't mean there's any reimbursement coming, said a White House official who was not authorized to talk publicly and spoke on the condition of anonymity.
Speaking to reporters Tuesday, Trump said the ads were "really good" and "promotion for the country, done by many presidents before." Asked whether he'd repay the funds already spent, he said, "We'll decide."
Senate Democratic Leader Chuck Schumer slammed Trump for not committing to reimbursement and said he believes the president's plan for covering future costs represents illegal coordination with his super PAC.
#Trump #donald

1 month ago
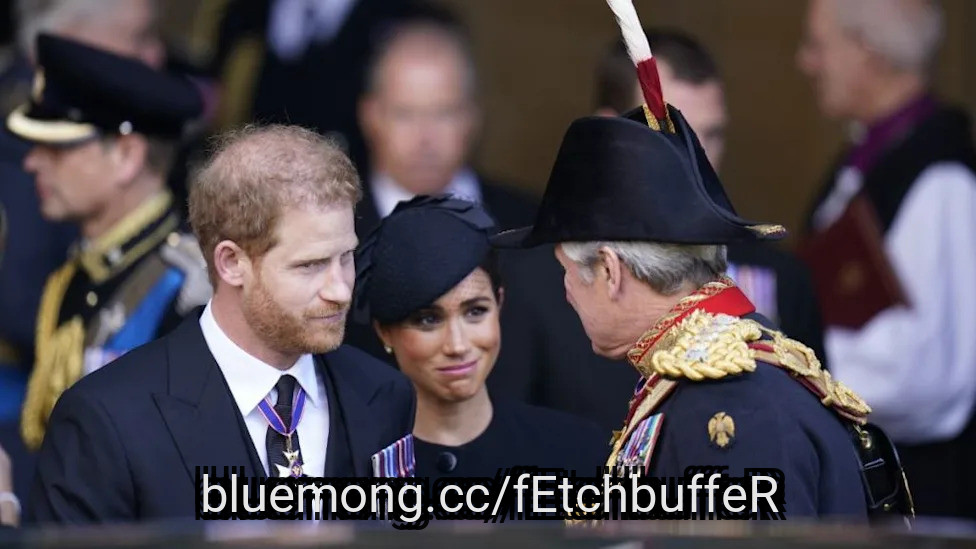
Prince Harry and Meghan Markle could use a recent security scare near their children's school to support their case for taxpayer-funded protection in the UK, royal author Ingrid Seward claimed. The Sussexes returned to Britain in August and are still waiting for a decision on whether they will receive publicly funded security while they are in the country.
Seward suggested Prince Harry and Meghan Markle may point to the incident when making their case for greater security. Speaking to The Sun's Royal Exclusive, Seward said she believed the couple could use the situation to their advantage. "I do feel certain that they (the Sussexes) probably will use this to try and benefit themselves in some kind of way," she said.
Harry has repeatedly raised concerns about his family's security while in the UK. Seward suggested that his security team would likely have stayed near the school because Harry uses a high level of protection when travelling with his family.
Harry and Meghan are currently waiting to learn whether they will receive taxpayer-funded security while living in the UK. Their security arrangements have remained a major issue since Harry stepped back as a working member of the Royal Family and moved to the US. The Duke has previously challenged decisions surrounding his security protection in Britain.
GB News royal correspondent Cameron Walker also discussed the incident and the security concerns involving Archie and Lilibet. Walker said British publications would generally avoid publishing unauthorized photos of the children. However, he noted that some European outlets could take a different approach.
#royal
Seward suggested Prince Harry and Meghan Markle may point to the incident when making their case for greater security. Speaking to The Sun's Royal Exclusive, Seward said she believed the couple could use the situation to their advantage. "I do feel certain that they (the Sussexes) probably will use this to try and benefit themselves in some kind of way," she said.
Harry has repeatedly raised concerns about his family's security while in the UK. Seward suggested that his security team would likely have stayed near the school because Harry uses a high level of protection when travelling with his family.
Harry and Meghan are currently waiting to learn whether they will receive taxpayer-funded security while living in the UK. Their security arrangements have remained a major issue since Harry stepped back as a working member of the Royal Family and moved to the US. The Duke has previously challenged decisions surrounding his security protection in Britain.
GB News royal correspondent Cameron Walker also discussed the incident and the security concerns involving Archie and Lilibet. Walker said British publications would generally avoid publishing unauthorized photos of the children. However, he noted that some European outlets could take a different approach.
#royal


1 month ago
One-time trillionaire Elon Musk is known for his bombastic behavior and predictions. At one point in early 2012, he proclaimed that Tesla would be entirely self-funded.
"Tesla does not need to ever raise another funding round," Musk said in February 2012 in response to a question on the company's financial position and the speed at which it was burning through cash. He relayed robust confidence in managing Tesla's self-funded future at the time.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
#tesla
"Tesla does not need to ever raise another funding round," Musk said in February 2012 in response to a question on the company's financial position and the speed at which it was burning through cash. He relayed robust confidence in managing Tesla's self-funded future at the time.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
#tesla

1 month ago
Royal sources claim that Prince Harry and Meghan Markle could meet King Charles again before Christmas. They state that this is not a casual get-together but a "deliberate" move on the monarch's part. This update comes a few months after the private reunion between King Charles, Camilla, and the Sussexes at Highgrove House.
Royal sources told Rob Shuter's Naughty but Nice that King Charles has reserved a meeting for Prince Harry and Meghan Markle before Christmas. They added that the time, date, and location currently remain publicly undisclosed. "This is not a casual 'let's get together sometime. **** ody drops in on the King. If Harry and Meghan are in Charles's diary, it is because he wants them there. This is deliberate," the source added.
Another source emphasized the fact that this will be another meeting, and that's a notable thing. "Charles is making room for his son again, and Harry knows how significant that is," they added. While King Charles has displayed openness in terms of reconciliation, the source added that Prince William hasn't.
The source claims that Harry had tried to reach out to William but had met with no response. "There is no meaningful communication with William or Catherine. Charles is willing to move forward. William is not," they mentioned.
The Sussexes moved to the UK on August 26, leaving behind their Montecito home. They are currently living in a non-royal base, outside London. They aren't provided with taxpayer-funded security.
#charles #king #source
Royal sources told Rob Shuter's Naughty but Nice that King Charles has reserved a meeting for Prince Harry and Meghan Markle before Christmas. They added that the time, date, and location currently remain publicly undisclosed. "This is not a casual 'let's get together sometime. **** ody drops in on the King. If Harry and Meghan are in Charles's diary, it is because he wants them there. This is deliberate," the source added.
Another source emphasized the fact that this will be another meeting, and that's a notable thing. "Charles is making room for his son again, and Harry knows how significant that is," they added. While King Charles has displayed openness in terms of reconciliation, the source added that Prince William hasn't.
The source claims that Harry had tried to reach out to William but had met with no response. "There is no meaningful communication with William or Catherine. Charles is willing to move forward. William is not," they mentioned.
The Sussexes moved to the UK on August 26, leaving behind their Montecito home. They are currently living in a non-royal base, outside London. They aren't provided with taxpayer-funded security.
#charles #king #source
1 month ago
Prince Harry and Meghan Markle's security dispute is in the news again after two men were spotted near the new school their children, Prince Archie and Princess Lilibet, are enrolled in.
The two men, said to be European paparazzi, were described by the Sussexes' spokesperson as exhibiting "extraordinarily reckless" behavior and compared it to the recent security incident at RAF Fairford.
As Prince Harry and Meghan's request for taxpayer-funded police protection is pending RAVEC review, a royal author has branded the way they have handled the recent paparazzi story a "cynical strategy."
Steven Bergman/AFF-USA.COM / MEGA
Royal author Robert Jobson believes that the way Harry and Meghan have publicly discussed their security incidents could make it hard for the Royal and VIP Executive Committee (RAVEC) to leave their security arrangements as is.
#harry #royal #meghan
The two men, said to be European paparazzi, were described by the Sussexes' spokesperson as exhibiting "extraordinarily reckless" behavior and compared it to the recent security incident at RAF Fairford.
As Prince Harry and Meghan's request for taxpayer-funded police protection is pending RAVEC review, a royal author has branded the way they have handled the recent paparazzi story a "cynical strategy."
Steven Bergman/AFF-USA.COM / MEGA
Royal author Robert Jobson believes that the way Harry and Meghan have publicly discussed their security incidents could make it hard for the Royal and VIP Executive Committee (RAVEC) to leave their security arrangements as is.
#harry #royal #meghan

2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
2 months ago
NEW YORK (AP) — Two major news networks were denied access to the White House on Saturday morning, with reporters from CNN and MS NOW both going live to report they'd been barred following a ban imposed by President Donald Trump.
The actions escalated Trump's long-running efforts to restrict news coverage by journalists he finds objectionable, and is the latest test of First Amendment protections in the United States. Trump said Friday he would ban both organizations and also Politico, because of their coverage — which he called "fake news."
CNN issued a statement saying it stood behind its reporters. "We will not be deflected from our duty to hold the government and other public bodies to account," it said. The statement was shown on the air before senior White House reporter Betsy Klein began to report on her ban.
MS NOW also said in a statement that it stands behind its journalists.
"The White House belongs to the American people and the decisions made inside are funded by our tax dollars," the network said in a statement Saturday. "MS NOW intends to take any and all steps necessary to defend our First Amendment rights and the essential role of independent journalism in our democracy."
#reporters
The actions escalated Trump's long-running efforts to restrict news coverage by journalists he finds objectionable, and is the latest test of First Amendment protections in the United States. Trump said Friday he would ban both organizations and also Politico, because of their coverage — which he called "fake news."
CNN issued a statement saying it stood behind its reporters. "We will not be deflected from our duty to hold the government and other public bodies to account," it said. The statement was shown on the air before senior White House reporter Betsy Klein began to report on her ban.
MS NOW also said in a statement that it stands behind its journalists.
"The White House belongs to the American people and the decisions made inside are funded by our tax dollars," the network said in a statement Saturday. "MS NOW intends to take any and all steps necessary to defend our First Amendment rights and the essential role of independent journalism in our democracy."
#reporters


2 months ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august

2 months ago
Consumer confidence decreased in August, according to The Conference Board's Consumer Confidence Index. This was the second straight month in decline. If September's report shows the same trend, investors might start looking for stocks that can prove resilient through tough economic times.
Procter & Gamble (NYSE: PG) fits the bill about as well as a company can. Let's have a look.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G has raised its dividend for 70 consecutive years. Not many businesses can claim that. Among Dividend Kings, or companies that have raised dividends for 50 years straight, only P&G and five other members qualify for that ultra-elite group. The dividend is also well-funded, as P&G's earnings per share and free cash flow comfortably exceed the amount needed. The company's payout ratio is around 64%.
P&G is diversified within its products. Everything consumers need, ranging from diapers to toothpaste, razors, and detergents, is held within its portfolio of everyday household staples. These are products that people will continue to buy regardless of macroeconomic conditions.
#same
Procter & Gamble (NYSE: PG) fits the bill about as well as a company can. Let's have a look.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
P&G has raised its dividend for 70 consecutive years. Not many businesses can claim that. Among Dividend Kings, or companies that have raised dividends for 50 years straight, only P&G and five other members qualify for that ultra-elite group. The dividend is also well-funded, as P&G's earnings per share and free cash flow comfortably exceed the amount needed. The company's payout ratio is around 64%.
P&G is diversified within its products. Everything consumers need, ranging from diapers to toothpaste, razors, and detergents, is held within its portfolio of everyday household staples. These are products that people will continue to buy regardless of macroeconomic conditions.
#same
2 months ago
Immigrants applying to live permanently in the United States can be rejected if they receive public benefits, beginning this week.
Use of Medicaid, food stamps, tuition ******* istance and free school lunch programs, among other government ******* istance, could all be grounds for denying a green-card application.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
The policy from President Donald Trump's administration, which took effect Friday, marks a dramatic change to a long-standing federal policy consistent with the president's efforts to restrict legal immigration pathways.
The rule could reduce federal and state payments by $13 billion a year, by persuading some 950,000 people to disenroll from or avoid federal safety net programs, according to estimates from the Department of Homeland Security. The agency said that the rule aligns with Congress's intent that noncitizens "in the United States be self-sufficient and not dependent on taxpayer-funded government benefits."
#states
Use of Medicaid, food stamps, tuition ******* istance and free school lunch programs, among other government ******* istance, could all be grounds for denying a green-card application.
Subscribe to The Post Most newsletter for the most important and interesting stories from The Washington Post.
The policy from President Donald Trump's administration, which took effect Friday, marks a dramatic change to a long-standing federal policy consistent with the president's efforts to restrict legal immigration pathways.
The rule could reduce federal and state payments by $13 billion a year, by persuading some 950,000 people to disenroll from or avoid federal safety net programs, according to estimates from the Department of Homeland Security. The agency said that the rule aligns with Congress's intent that noncitizens "in the United States be self-sufficient and not dependent on taxpayer-funded government benefits."
#states

2 months ago
AeroVironment, Inc. (NASDAQ:AVAV) reported on September 9, 2026, that revenue for fiscal Q1 2027, ended August 1, 2026, increased 6% to $480.5 million. Funded backlog reached approximately $1.5 billion at quarter-end, up from $1.2 billion at April 30, 2026. This represents remaining work under firm customer orders with funding already appropriated, providing a concrete base for future revenue.
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity
Non-GAAP adjusted diluted earnings were $0.59 per share, excluding acquired-intangible amortization, purchase-accounting adjustments, acquisition expenses, and net gains and losses on equity-method and equity-security investments. Adjusted EPS retains net interest income. The GAAP result was a $5.1 million net loss, or $0.10 per diluted share. The question is whether the expanding order base can produce stronger operating earnings and cash generation.
Bookings reached $683 million, producing a book-to-bill ratio of 1.4, calculated as bookings divided by revenue. Bookings measure authorized contract awards and modifications and can include work whose funding has not yet been obligated. The ratio indicates that new business exceeded revenue recognized during the quarter.
AeroVironment, Inc. (NASDAQ:AVAV) is also translating demand into sales in Autonomous Systems, where revenue rose 21% to $346 million. That provides operating evidence behind the opportunity in unmanned aircraft and precision-strike systems.
Management maintained fiscal 2027 revenue guidance of $2.125 billion to $2.225 billion, and non-GAAP adjusted EBITDA of $305 million to $325 million. Adjusted EBITDA excludes net interest income or expense, taxes, depreciation and amortization from net income and further adjusts for stock compensation, acquisition expenses, cloud-computing amortization, net gains and losses on equity-method and equity-security investments, and other specified items.
#Equity

2 months ago
Wealthfront Corporation (NASDAQ:WLTH) reported on September 9 that fiscal second-quarter revenue increased 1% to $91.9 million, despite platform ***** ets rising 12% to $99 billion. The quarter ended July 31, 2026. Funded clients increased 14% to 1.51 million, and platform ***** ets surpassed $100 billion by the end of August.
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment
Platform ***** ets measure financial ***** ets held in client accounts. Their growth reflects both net deposits and market movements, so the headline increase does not represent new client money alone.
Adjusted EBITDA declined 15% to $38.1 million, with its margin falling to 41% from 49%. Wealthfront Corporation (NASDAQ:WLTH) defines this non-GAAP measure as net income excluding interest expense, income taxes, depreciation and amortization, stock-based compensation, fair-value changes in convertible notes, warrant liabilities and simple agreements for future equity, and nonrecurring expenses. Adjusted EBITDA margin divides that figure by revenue.
The advisory business is translating ***** et growth into revenue. Investment advisory ***** ets increased 30% to $54.1 billion, while advisory revenue rose 31% to $28.8 million. Those results show that the expanding investment business is generating a larger recurring fee stream.
For Wealthfront Corporation (NASDAQ:WLTH), this creates an opportunity to deepen client relationships as savings move toward longer-term investment goals. A growing advisory base could support more durable relationships, provided clients remain invested and continue contributing.
#wealthfront #revenue #platform #investment

2 months ago
York Water holds the longest dividend streak in US public markets at 27 consecutive years, while WTW's $1.775B operating cash flow dwarfs its $358M dividend obligation.
Amdocs and Ituran both run near-recession-proof revenue models, with DOX posting near-100% managed services renewal rates and ITRN carrying zero debt alongside $103.7M in net cash.
All five stocks fund dividends from contracted or recurring revenue streams such as regulated rates, fee income, or subscriptions, insulating payouts from economic cycles.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter want payouts that don't wobble with the business cycle. The five names below share one thing: dividends funded by recurring, contracted, or fee-based revenue streams that keep flowing whether or not the macro cooperates. Each has raised its payout recently, and each trades on Nasdaq. As a grounding data point, Willis Towers Watson (NASDAQ:WTW) alone generated $360 million of first-half free cash flow, roughly double the prior-year period, giving the broker ample room to keep funding both dividends and buybacks.
#revenue #NASDAQ #Dividend
Amdocs and Ituran both run near-recession-proof revenue models, with DOX posting near-100% managed services renewal rates and ITRN carrying zero debt alongside $103.7M in net cash.
All five stocks fund dividends from contracted or recurring revenue streams such as regulated rates, fee income, or subscriptions, insulating payouts from economic cycles.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Income investors heading into the fourth quarter want payouts that don't wobble with the business cycle. The five names below share one thing: dividends funded by recurring, contracted, or fee-based revenue streams that keep flowing whether or not the macro cooperates. Each has raised its payout recently, and each trades on Nasdaq. As a grounding data point, Willis Towers Watson (NASDAQ:WTW) alone generated $360 million of first-half free cash flow, roughly double the prior-year period, giving the broker ample room to keep funding both dividends and buybacks.
#revenue #NASDAQ #Dividend
2 months ago
Once upon a time, the 'space race' meant the grand strategic competition between the USA and the USSR to gain control of the heavens. The superpowers designed and built satellites, manned capsules, orbital **** ecraft and long-endurance **** e stations, and NASA even sent the Apollo landers to put men on the Moon.
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
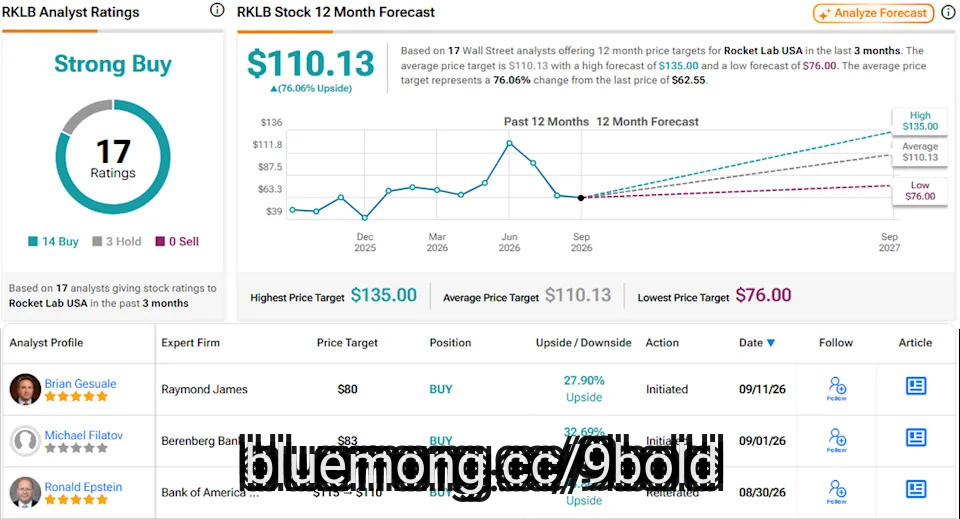
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once
Today, the **** e race is heating up again, but in a very different way. Yes, the governments are still involved – NASA's Artemis program is targeting the Moon, the Russians have a Soyuz escape ship docked at the International **** e Station, and other powers such as the EU, China, and India have large-scale **** e programs. But the real difference – and a lot of the innovation – is coming from commercial players working alongside government **** e agencies.
This past summer, Elon Musk's **** eX went public, in Wall Street's largest ever IPO. The company is pioneering reusable large rockets, and has already made history with privately launched and/or publicly funded missions of the Falcon 9 rocket and Crew Dragon capsule.
Promotion
55% Off TipRanks
#once

2 months ago
ARK Invest sold over 142,000 CRCL shares Monday across ARKK and ARKW, pushing Circle Internet down 8% despite a 25% monthly gain.
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin
COIN and BMNR each slid 5% as the Senate's Clarity Act vote threatens to open stablecoin markets to better-funded bank competitors.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Circle Internet Group didn't make the cut. Enter your email to see the names that beat CRCL. The report is free. Enter your email and see if any of your stocks made the cut.
Circle Internet Group (NYSE:CRCL) stock is falling on Tuesday after ARK Invest trimmed its position ahead of a U.S. Senate procedural vote on the Digital ******* et Market Clarity Act. Circle Internet stock is down 8% to $89.56 in midday trading. The move stands out among crypto-linked equities because the same manager cut several crypto positions but concentrated the sale in Circle Internet.
Coinbase Global (NASDAQ:COIN) shares are down 5% to $181.06. Also lower, Bitmine Immersion Technologies (NYSEAMERICAN:BMNR) stock is sliding 5% to $24.38. Meanwhile, the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is down 0.5% to $757.09, so the selling is concentrated in crypto-linked names.
#crcl #coin


2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
2 months ago
Meghan Markle reportedly secured her first government-backed security review since stepping back from royal duties in 2020. The ***** ss of Sussex and Prince Harry were set to receive separate official risk ***** sments after returning to Britain.
The review could consider their schedules, family routines, and public movements. It also marks a notable change for Meghan after six years without such an ***** sment. Meanwhile, the couple received interim security arrangements during the process.
As per People magazine, Meghan Markle would receive a new ***** sment. The security review would be her first since police protection ended following the couple's 2020 royal exit. Meanwhile, Prince Harry would receive a separate ***** sment.
The Royal and VIP Executive Committee reportedly commissioned both reviews after their UK move. RAVEC determines eligibility for taxpayer-funded police protection. The couple have also been granted an interim security provision during the ***** sment process.
Additionally, RAVEC reportedly requested detailed schedules from the Duke and ***** ss of Sussex. That includes daily routines involving Archie, seven, and Lilibet, five. Their school runs could help officials ***** s potential risks.
#review
The review could consider their schedules, family routines, and public movements. It also marks a notable change for Meghan after six years without such an ***** sment. Meanwhile, the couple received interim security arrangements during the process.
As per People magazine, Meghan Markle would receive a new ***** sment. The security review would be her first since police protection ended following the couple's 2020 royal exit. Meanwhile, Prince Harry would receive a separate ***** sment.
The Royal and VIP Executive Committee reportedly commissioned both reviews after their UK move. RAVEC determines eligibility for taxpayer-funded police protection. The couple have also been granted an interim security provision during the ***** sment process.
Additionally, RAVEC reportedly requested detailed schedules from the Duke and ***** ss of Sussex. That includes daily routines involving Archie, seven, and Lilibet, five. Their school runs could help officials ***** s potential risks.
#review

2 months ago
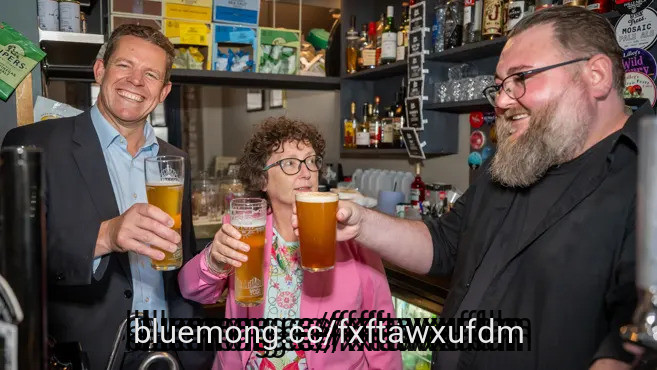
Taxes paid by pubs, hotels and cinemas in Wales will fall after the Welsh government announced a 30% cut in some business rates.
First Minister Rhun ap Iorwerth said hospitality, accommodation and leisure venues would receive the permanent cut in rates from April 2027.
"It is about helping businesses like this to thrive, so our communities can thrive," ap Iorwerth said on a visit to a pub in Cardiff.
The cut, which will be funded by an increase in the rates paid by businesses with the highest-value properties, was welcomed by UK Hospitality Cymru. But the trade body warned businesses still faced "massive amounts of taxation coming from all areas".
Pubs will be among the hospitality businesses in Wales to receive a permanent tax cut from April [Getty Images]
#april
First Minister Rhun ap Iorwerth said hospitality, accommodation and leisure venues would receive the permanent cut in rates from April 2027.
"It is about helping businesses like this to thrive, so our communities can thrive," ap Iorwerth said on a visit to a pub in Cardiff.
The cut, which will be funded by an increase in the rates paid by businesses with the highest-value properties, was welcomed by UK Hospitality Cymru. But the trade body warned businesses still faced "massive amounts of taxation coming from all areas".
Pubs will be among the hospitality businesses in Wales to receive a permanent tax cut from April [Getty Images]
#april

2 months ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
2 months ago
AVAV surged 6% on delayed earnings digestion after posting record Q1 revenue of $481M and a $1.5B funded backlog up 37% year over year.
ONDS gained just 2% and RCAT slipped 0.6% while the drone ETF DRNZ rose only 0.4%, confirming today's move belongs entirely to AeroVironment.
Despite the rally, AVAV remains 36% below its year-start price, and investors should watch for follow-through sessions before sizing up exposure.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
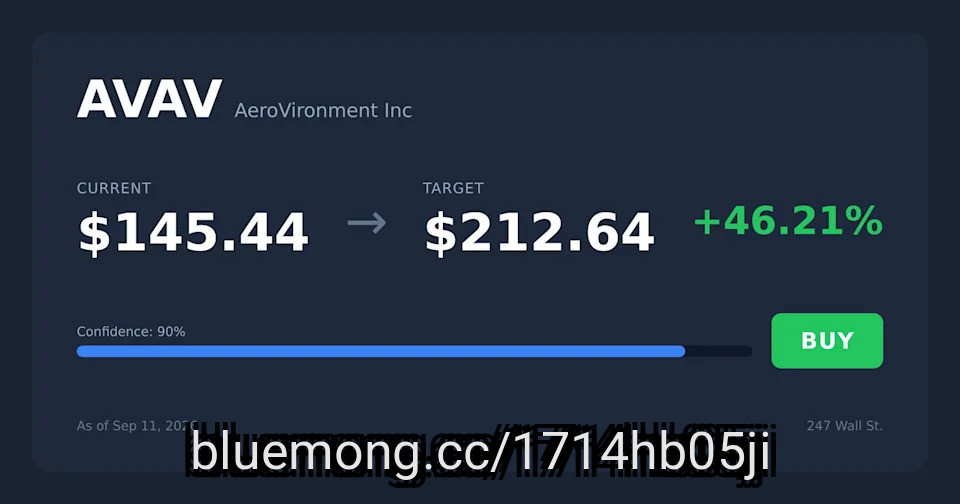
AeroVironment (NASDAQ:AVAV) stock is up 6% to $155.22 midday Monday, extending a post-earnings recovery the rest of the drone group hasn't joined. The move follows the defense contractor's fiscal first-quarter results reported earlier this month. The gain still leaves AeroVironment shares down 36% year to date.
#avav #move
ONDS gained just 2% and RCAT slipped 0.6% while the drone ETF DRNZ rose only 0.4%, confirming today's move belongs entirely to AeroVironment.
Despite the rally, AVAV remains 36% below its year-start price, and investors should watch for follow-through sessions before sizing up exposure.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
AeroVironment (NASDAQ:AVAV) stock is up 6% to $155.22 midday Monday, extending a post-earnings recovery the rest of the drone group hasn't joined. The move follows the defense contractor's fiscal first-quarter results reported earlier this month. The gain still leaves AeroVironment shares down 36% year to date.
#avav #move


2 months ago
Strategy (NASDAQ: $MSTR) has again left its Bitcoin (CRYPTO: $BTC) holdings unchanged as it focuses on repurchasing its preferred stock (NASDAQ: $STRC).
The serial cryptocurrency acquirer bought back 1.42 million of its preferred shares over the past week at a cost of $139.3 million U.S.
A regulatory filing with the U.S. Securities and Exchange Commission (SEC) shows that Strategy funded the stock repurchases through its cash reserve.
As of Sept. 14, the balance on the company's cash reserve stood at $6.4 billion U.S.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#preferred
The serial cryptocurrency acquirer bought back 1.42 million of its preferred shares over the past week at a cost of $139.3 million U.S.
A regulatory filing with the U.S. Securities and Exchange Commission (SEC) shows that Strategy funded the stock repurchases through its cash reserve.
As of Sept. 14, the balance on the company's cash reserve stood at $6.4 billion U.S.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#preferred

2 months ago
Jim Cramer sees Enterprise Products Partners L.P. (NYSE:EPD) as a major beneficiary of the disruption surrounding the Strait of Hormuz, as he said during the September 8 episode of Mad Money:
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
When I wrote How to Make Money in Any Market… I didn't know that Enterprise Products Partners was going to be the, maybe the single biggest pipeline winner in this country thanks to the war. I didn't see that war coming. The CEO of Enterprise, Jim Teague, has raised awareness for the company's profit opportunity because of the Hormuz closing. The margins of some of its liquids, like ethane to ethylene, ethylene to polyethylene, have soared. As Teague says, the Houston Ship Channel is now just as important as the Strait of Hormuz. Now, there's an endorsement. Stock yields 5.8%.
Enterprise Products Partners L.P. (NYSE:EPD) reported record second-quarter adjusted EBITDA of $2.8 billion, up 17% year over year, while operational distributable cash flow reached a record $2.3 billion, up 21%. Moreover, pipeline volumes reached a record 14.7 million barrels of oil equivalent per day, up 8%, while marine-terminal volumes increased 33% to 2.8 million barrels per day. Co-Chief Executive Officer James Teague said:
Volumes at our marine terminals have returned to normal levels in June and July after the initial rush to backfill volumes affected by hostilities in the Middle East in April and May.
In July, Enterprise Products Partners L.P. (NYSE:EPD) declared a quarterly distribution of $0.56 per unit, or $2.24 annualized, a 2.8% increase from a year earlier. At EPD's September 8 closing price of $38.83, that equates to a yield of approximately 5.8%. The company has increased its distribution for 27 consecutive years. The company's latest investor materials show $6.5 billion of major capital projects under construction. It expects 2026 organic growth capital spending, net of ***** et-sale proceeds, of $2.9 billion to $3.4 billion. The company retained $1.1 billion of DCF for internally funded growth capital expenditures and buybacks.
#partners #hormuz
2 months ago
AVAV stock has plunged 40% in a year despite a historic $464M Army laser contract and a record $1.5B funded backlog.
AeroVironment's LOCUST laser cuts drone intercept costs from millions to under $10 per shot, backed by 300 cartel drones already downed at the southern border.
Nawabi sold 28,265 shares at $139 while ***** ysts set a $226 average price target, leaving investors to weigh insider doubt against a 47x forward P/E.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and AeroVironment didn't make the cut. Enter your email to see the names that beat AVAV. The report is free. Enter your email and see if any of your stocks made the cut.
AeroVironment (NASDAQ:AVAV) chairman and chief executive Wahid Nawabi went on CNBC this week with an arithmetic problem for defense investors. Drones being thrown at Western militaries and border installations cost roughly $150,000 apiece, according to Nawabi, while the interceptors historically used to knock them down cost millions of dollars per shot. His pitch is that AeroVironment's LOCUST directed-energy laser, per Nawabi, brings that engagement cost down to less than $10 per shot.
#nawabi #avav #cost #locust
AeroVironment's LOCUST laser cuts drone intercept costs from millions to under $10 per shot, backed by 300 cartel drones already downed at the southern border.
Nawabi sold 28,265 shares at $139 while ***** ysts set a $226 average price target, leaving investors to weigh insider doubt against a 47x forward P/E.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and AeroVironment didn't make the cut. Enter your email to see the names that beat AVAV. The report is free. Enter your email and see if any of your stocks made the cut.
AeroVironment (NASDAQ:AVAV) chairman and chief executive Wahid Nawabi went on CNBC this week with an arithmetic problem for defense investors. Drones being thrown at Western militaries and border installations cost roughly $150,000 apiece, according to Nawabi, while the interceptors historically used to knock them down cost millions of dollars per shot. His pitch is that AeroVironment's LOCUST directed-energy laser, per Nawabi, brings that engagement cost down to less than $10 per shot.
#nawabi #avav #cost #locust
2 months ago
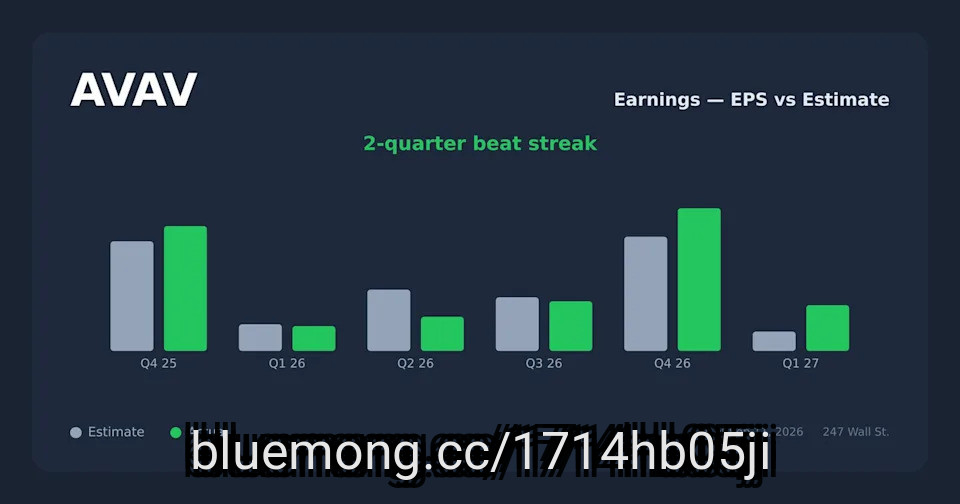
On September 9, AeroVironment Inc. (NASDAQ:AVAV) revealed its Q1 FY27 results, posting its highest ever first quarter revenue. Topline figure of $480.5 million marked a 6% year-over-year growth, fueled by a $15.5 million jump in product sales and a $10.3 million expansion of service revenue. The company reported a book-to-bill ratio of 1.4, after total bookings for the quarter came in at $0.7 billion. Let's explore the underlying drivers of AeroVironment's impressive first quarter print.
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first
Photo by NASA on Unsplash
The first quarter record topline figure reflects on strength across the underlying business lines. The Autonomous Systems (AxS) and the ***** e, Cyber and Directed Energy (SCDE) segments contributed $346 million and $134.5 million to the total revenue, respectively. The overall gross profit jumped 31% during the quarter to $124.6 million. This pushed gross margin to 26% from 21% posted a year earlier.
Adjusted diluted earnings per share for the first quarter almost doubled, from $0.32 in the same period last year to of $0.59 in the recently concluded quarter. The company also increased its funded backlog, which clocked in at $1.5 billion, compared to $1.2 billion recorded on April 30.
With a strong backlog position and landmark strategic wins, management upheld its full-year guidance, with topline figures estimated to land between $2.125 billion and $2.225 billion. It has forecasted an adjusted EBITDA ranging from $305 million to $325 million, along with diluted EPS between $3.02 and $3.34 on adjusted basis.
#million #quarter #billion #first
2 months ago
Zhihu Inc. (NYSE:ZH) disclosed on September 6 that a wholly owned subsidiary had signed a conditional RMB1.5 billion cash commitment to Tianjin Lisi Xingshen Equity Investment Partnership. The agreement, dated September 4, requires shareholder approval, with payments funded internally through capital calls.
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million
Zhihu Inc. (NYSE:ZH) expects to hold no more than 30% of the fund and will have no role in daily management or individual investment decisions. The blind-pool structure asks shareholders to approve a manager and strategy before specific investments are identified. The fund targets early-to-mid-stage private AI and technology companies with significant mainland China connections.
The strategic rationale fits the company's existing capabilities. Zhihu Inc. (NYSE:ZH) is developing AI search, expert-data solutions and AI-enabled content businesses. Exposure to foundation models, infrastructure, robotics and applications could create technology partnerships and help identify emerging customer needs.
A specialist fund also supplies investment research, deal sourcing and portfolio oversight that would require substantial internal resources to replicate. For shareholders, the potential benefit combines investment returns with commercial opportunities for the core content platform. Any cooperation would still require separate **** sment and agreement.
There is an operating business to build around. Second-quarter paid content and intellectual-property operations revenue increased to RMB425.9 million from RMB408.2 million. Zhihu Inc. (NYSE:ZH) also reduced total operating expenses by 13% to RMB469.4 million. These results support a focused approach in which outside technology complements established content and expert relationships.
#content #technology #million