2 days ago
Altria has raised its dividend 61 times in 57 years and yields ~6%, while Realty Income has raised its payout 115 consecutive quarters and yields ~6%.
Kinder Morgan carries a $9.6 billion project backlog, over 60% tied to power generation, while AT&T uses just 46% of adjusted EPS to fund its dividend.
VICI Properties yields ~7.5% with 100% portfolio occupancy and 39.6-year average lease terms, but its stock trades well below the average **** yst target of $31.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Retirees need two things from a dividend stock: the check must arrive on schedule, and it must grow faster than the cost of groceries. This month's list covers five cash-generating businesses in five different industries: tobacco, net-lease real estate, gaming real estate, natural gas pipelines, and telecom. In every case, earnings or cash flow will cover the payout, and each company has years of payment history behind it. Several of them pay in November, including Realty Income (NYSE:O), whose next monthly dividend of $0.2715 a share is scheduled to arrive on November 13.
#november #raised
Kinder Morgan carries a $9.6 billion project backlog, over 60% tied to power generation, while AT&T uses just 46% of adjusted EPS to fund its dividend.
VICI Properties yields ~7.5% with 100% portfolio occupancy and 39.6-year average lease terms, but its stock trades well below the average **** yst target of $31.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Altria didn't make the cut. Enter your email to see the names that beat MO. The report is free. Enter your email and see if any of your stocks made the cut.
Retirees need two things from a dividend stock: the check must arrive on schedule, and it must grow faster than the cost of groceries. This month's list covers five cash-generating businesses in five different industries: tobacco, net-lease real estate, gaming real estate, natural gas pipelines, and telecom. In every case, earnings or cash flow will cover the payout, and each company has years of payment history behind it. Several of them pay in November, including Realty Income (NYSE:O), whose next monthly dividend of $0.2715 a share is scheduled to arrive on November 13.
#november #raised


7 days ago
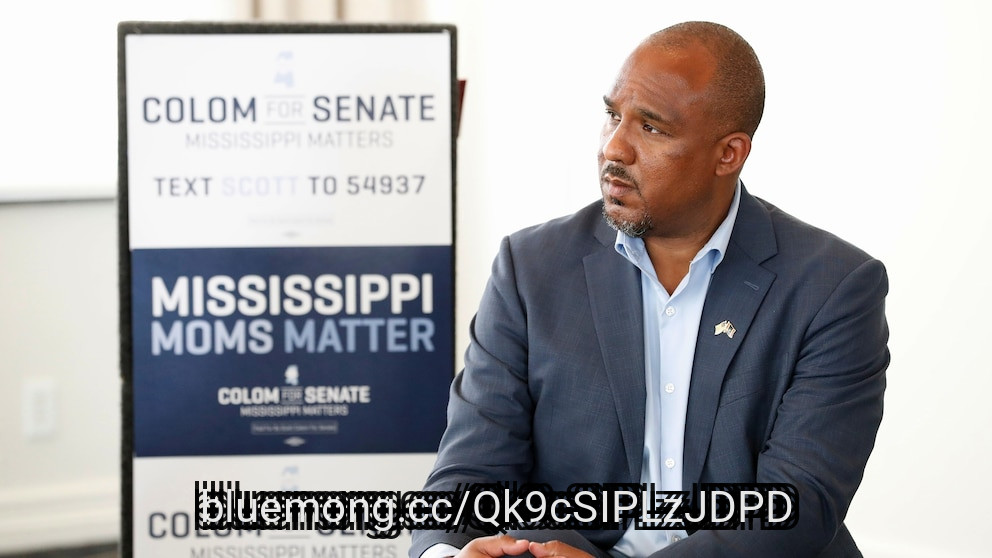
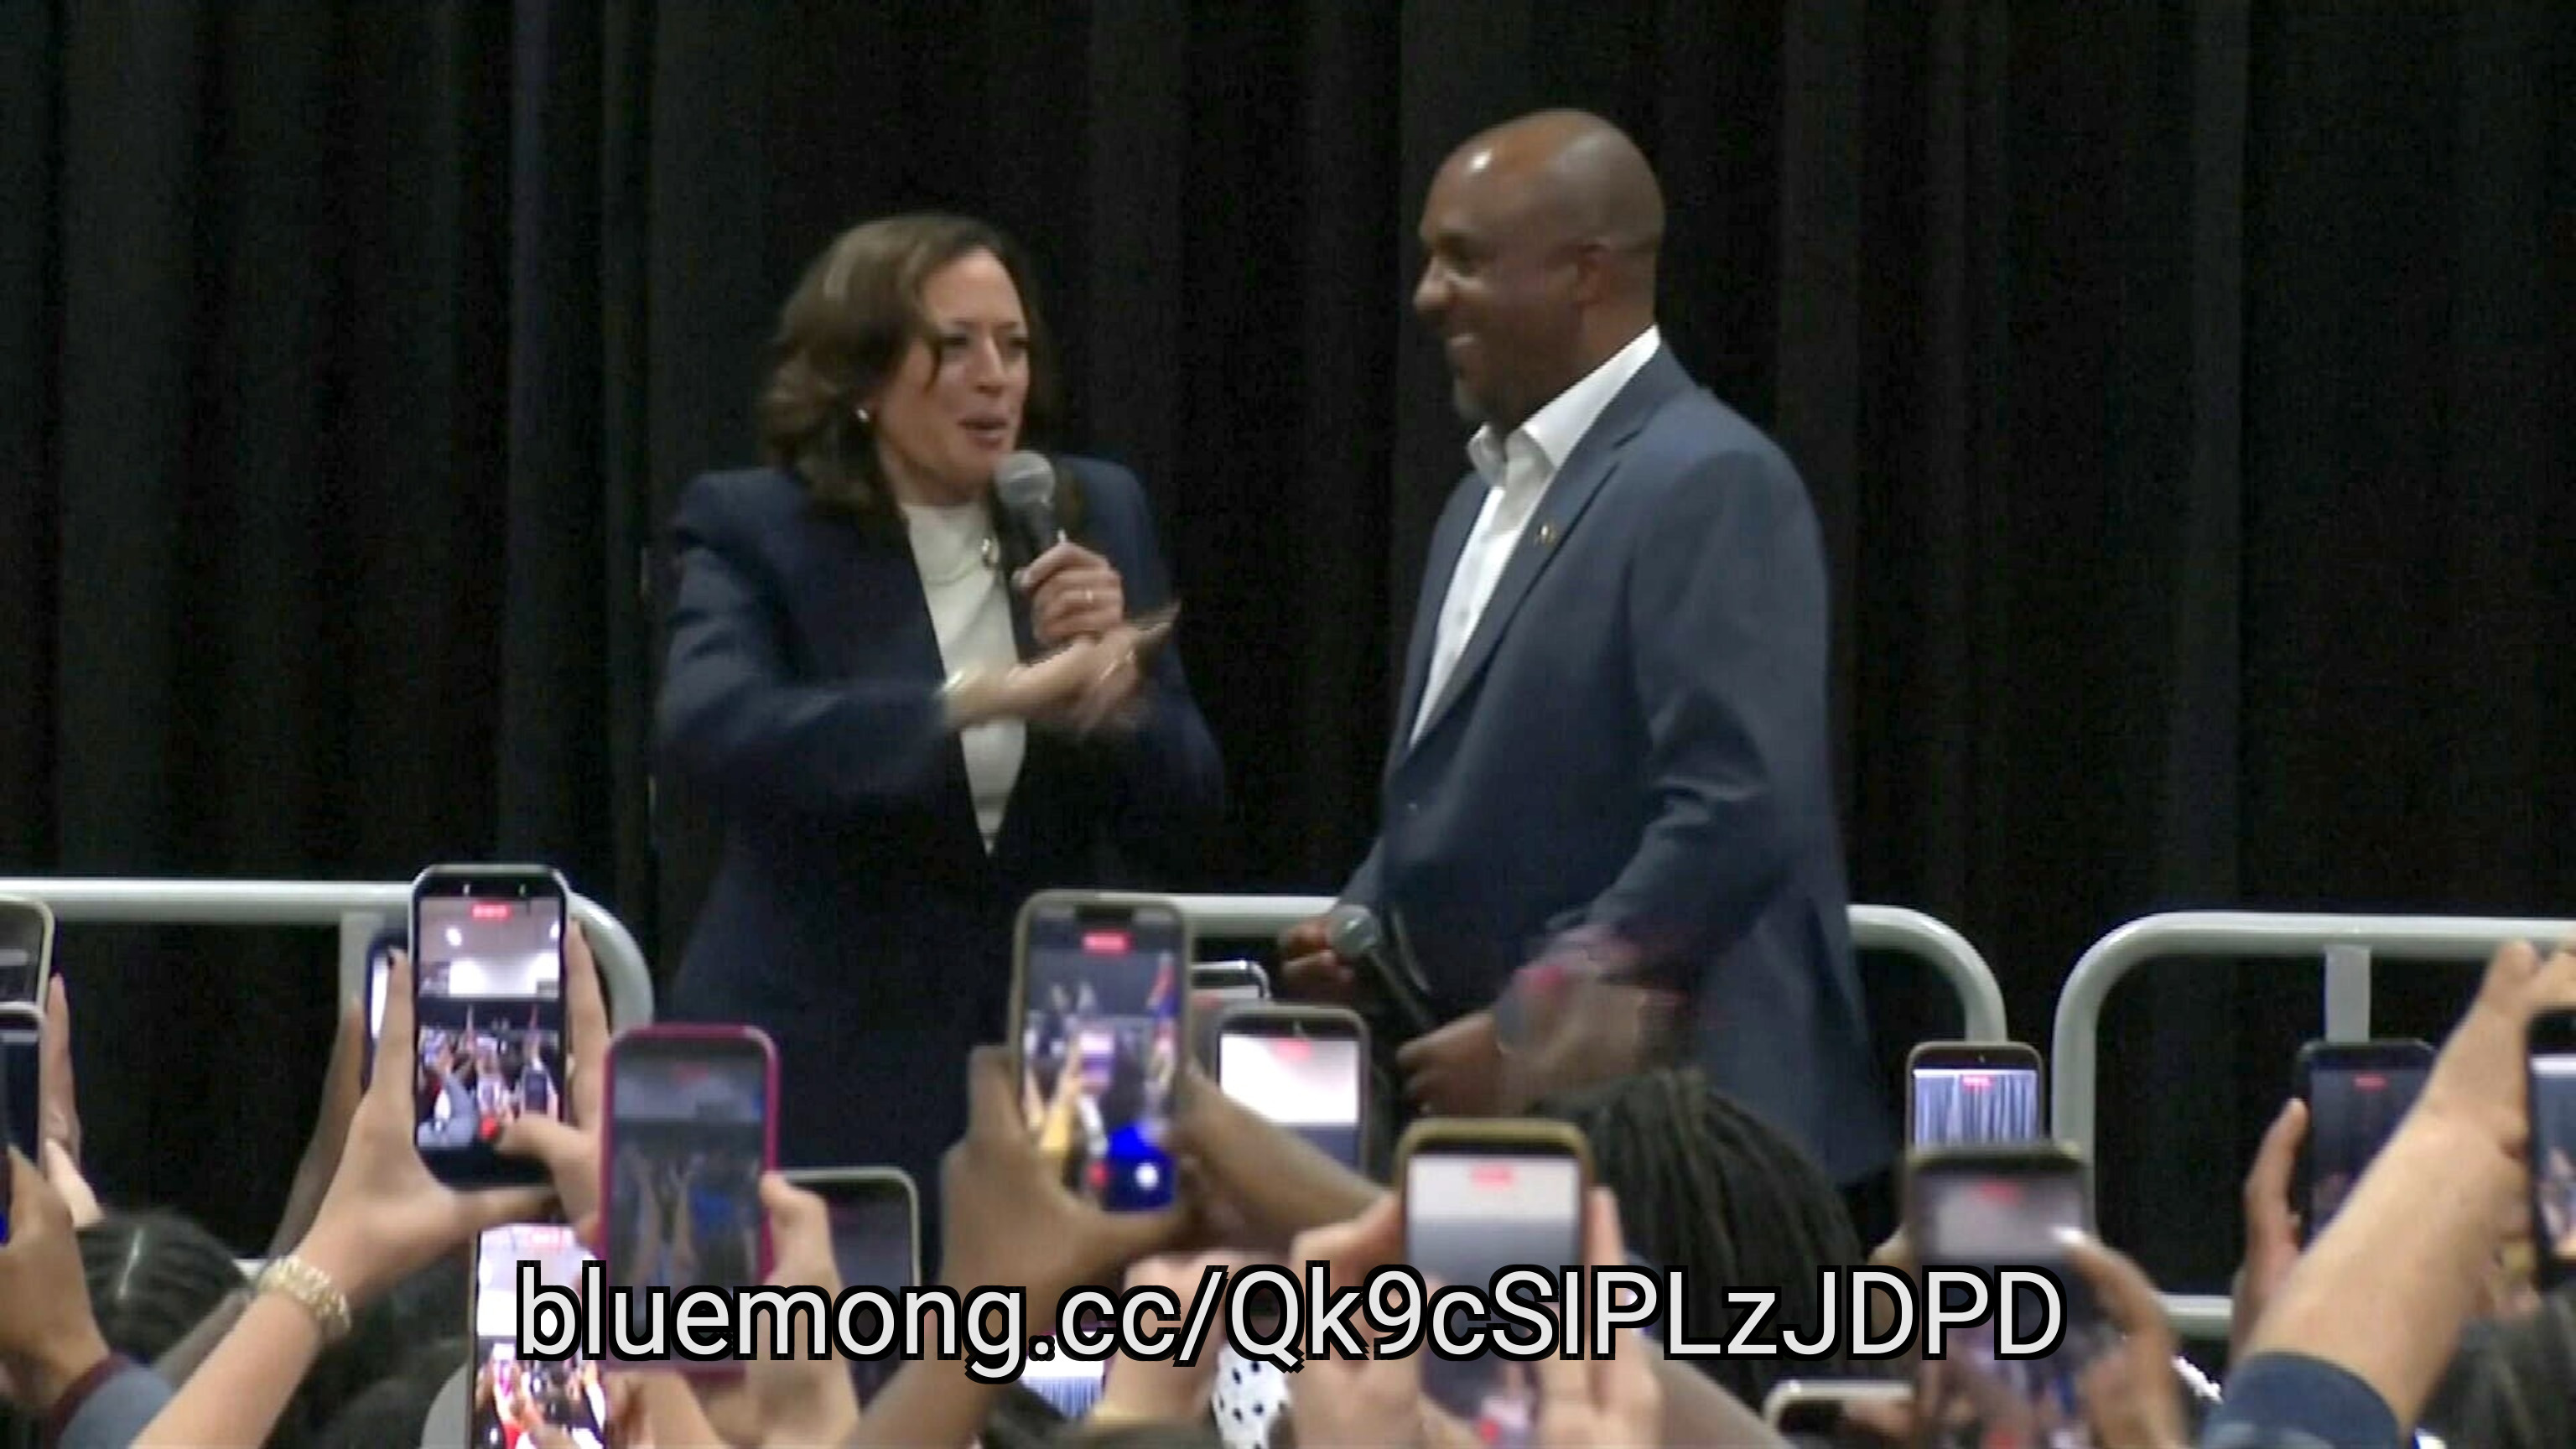
Colom would be Mississippi’s first Black U.S. senator since Reconstruction.
Why are major Democrats and Republicans flocking to Mississippi in recent weeks?
In a climate where polls show President Donald Trump's approval ratings cratering, Democrats are unusually optimistic about Scott Colom's chances of flipping the Senate seat held by incumbent Republican Cindy Hyde-Smith -- even in deep-red Mississippi.
"We got to have a senator that looks out for Mississippi, that puts Mississippi farmers first, Mississippi small businesses first, represent our values by not allowing corruption to ruin our country and actually delivers on the commitments to put America first," Colom told ABC News in an interview earlier this week.
The incumbent's campaign dismisses the Democratic push as the last-ditch effort of a campaign that will fall short.
#first #black #reconstruction
Why are major Democrats and Republicans flocking to Mississippi in recent weeks?
In a climate where polls show President Donald Trump's approval ratings cratering, Democrats are unusually optimistic about Scott Colom's chances of flipping the Senate seat held by incumbent Republican Cindy Hyde-Smith -- even in deep-red Mississippi.
"We got to have a senator that looks out for Mississippi, that puts Mississippi farmers first, Mississippi small businesses first, represent our values by not allowing corruption to ruin our country and actually delivers on the commitments to put America first," Colom told ABC News in an interview earlier this week.
The incumbent's campaign dismisses the Democratic push as the last-ditch effort of a campaign that will fall short.
#first #black #reconstruction

14 days ago
PARIS (AP) — The weekend of riots and looting in France did not spare soccer clubs Marseille and Lille.
The Ligue 1 teams said their shops have been vandalized during the protests against rising living costs and poor conditions in schools. Over half a million mainly peaceful protesters took to the streets on Saturday but small groups of people set fires in the streets and looted businesses in Paris, Lyon, Marseille and other cities.
Marseille said in a statement on Monday the looters caused "significant damage" to its official store located on La Canebière — the southern port city's most famous avenue — which has been temporarily closed.
Up north, Lille's city center store "suffered extensive damage and widespread looting," the club said, adding that the shop will remain closed until further notice.
Lille thanked "everyone who has offered their support over the past few hours — first and foremost, our store employees, but also the many passersby, whether supporters or not, who spontaneously stepped forward to offer their help, practical ****** istance and comfort."
#closed #ligue
The Ligue 1 teams said their shops have been vandalized during the protests against rising living costs and poor conditions in schools. Over half a million mainly peaceful protesters took to the streets on Saturday but small groups of people set fires in the streets and looted businesses in Paris, Lyon, Marseille and other cities.
Marseille said in a statement on Monday the looters caused "significant damage" to its official store located on La Canebière — the southern port city's most famous avenue — which has been temporarily closed.
Up north, Lille's city center store "suffered extensive damage and widespread looting," the club said, adding that the shop will remain closed until further notice.
Lille thanked "everyone who has offered their support over the past few hours — first and foremost, our store employees, but also the many passersby, whether supporters or not, who spontaneously stepped forward to offer their help, practical ****** istance and comfort."
#closed #ligue


25 days ago
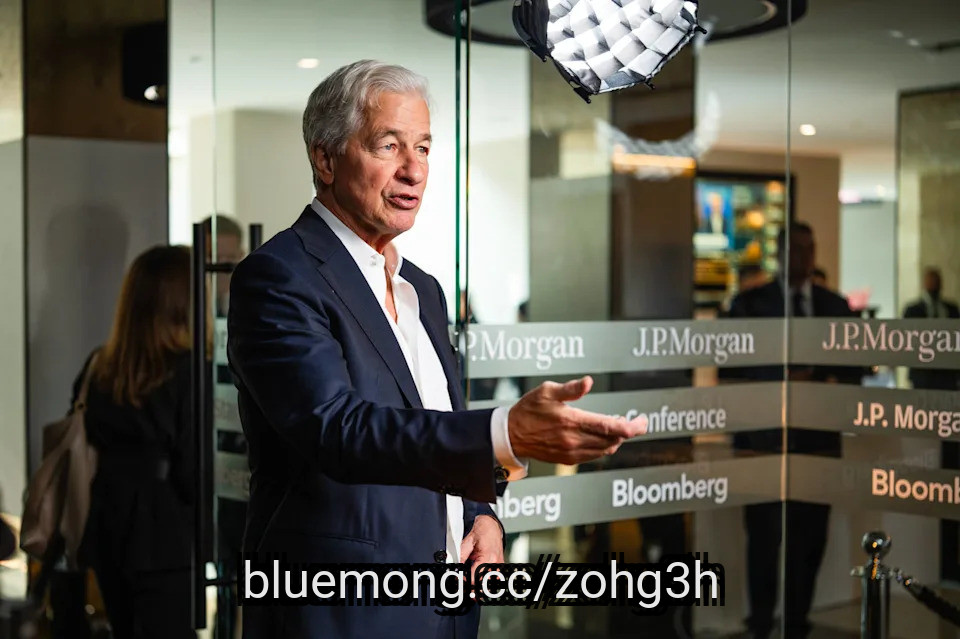
Jamie Dimon has spent much of this year warning that the bond market is a problem waiting to happen. On April 28, at a conference hosted by Norway's sovereign wealth fund, the JPMorgan Chase CEO said there would be "some kind of bond crisis," according to TheStreet.
The debt he had in mind was mostly owed by governments. But Dimon has long argued that the pain lands somewhere else.
In a 2025 Fox Business interview, he said bond market volatility hurts the people raising money, small businesses included. He admitted he could not tell whether trouble was six months or six years away. This time, he named the next group in line.
Also read: Scott Bessent just made a bold move on the bond market
Speaking on the sidelines of a JPMorgan event in London on Oct. 6, Dimon said the worldwide scramble for capital could begin to squeeze corporate borrowers, Bloomberg reported. Investors will keep asking for more, he said. At some point, that feeds into corporate debt and credit spreads.
#debt
The debt he had in mind was mostly owed by governments. But Dimon has long argued that the pain lands somewhere else.
In a 2025 Fox Business interview, he said bond market volatility hurts the people raising money, small businesses included. He admitted he could not tell whether trouble was six months or six years away. This time, he named the next group in line.
Also read: Scott Bessent just made a bold move on the bond market
Speaking on the sidelines of a JPMorgan event in London on Oct. 6, Dimon said the worldwide scramble for capital could begin to squeeze corporate borrowers, Bloomberg reported. Investors will keep asking for more, he said. At some point, that feeds into corporate debt and credit spreads.
#debt

25 days ago
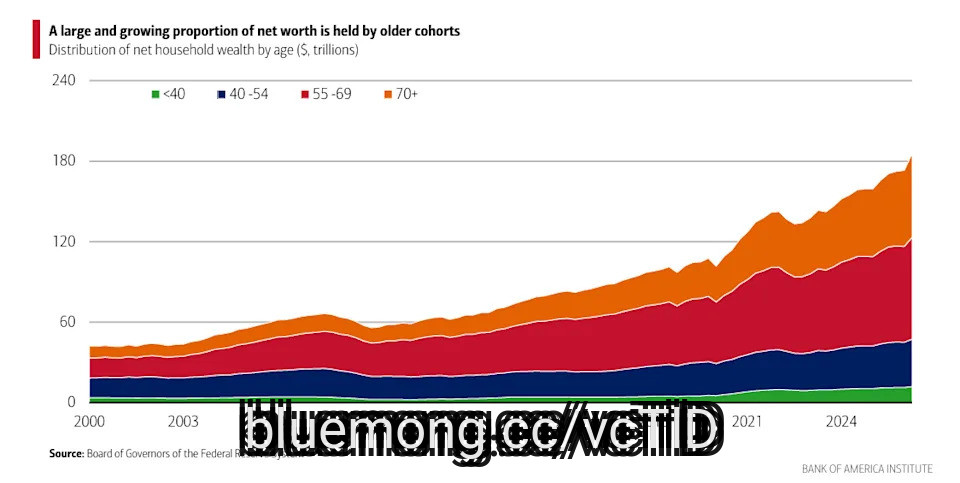
America's older households sit on nearly $140 trillion in wealth, and much of it showed up recently.
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report

26 days ago
Lots of investors keep coming back to dividend stocks for a pretty simple reason: While the market is often busy chasing whatever happens to be hot that week, a growing dividend is something a company actually has to earn. It has to generate the cash to keep paying investors quarter after quarter, year after year.
That makes dividends especially appealing when the market and the economy feel like they're being pulled in every direction. A company can dress up a press release, but it can't fake the cash sitting in its bank account. When it comes time to pay a dividend, the money is either there or it isn't.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
What interests me most, though, aren't necessarily the big, well-known dividend payers. I'm more interested in the companies flying under the radar that have increased their payouts for decades while also making meaningful changes to their underlying businesses today. These four companies fit that description.
Universal (NYSE: UVV) is the highest yielder here, paying out around 7.4% at recent prices, and it has raised its dividend for 56 consecutive years. This raise makes it a Dividend King, a company that has delivered 50 or more years of annual dividend increases. Universal isn't a cigarette maker, but it is the world's largest leaf tobacco exporter and importer. It supplies tobacco companies rather than selling to smokers directly, which is why it rarely shows up in articles about tobacco stocks.
#market
That makes dividends especially appealing when the market and the economy feel like they're being pulled in every direction. A company can dress up a press release, but it can't fake the cash sitting in its bank account. When it comes time to pay a dividend, the money is either there or it isn't.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
What interests me most, though, aren't necessarily the big, well-known dividend payers. I'm more interested in the companies flying under the radar that have increased their payouts for decades while also making meaningful changes to their underlying businesses today. These four companies fit that description.
Universal (NYSE: UVV) is the highest yielder here, paying out around 7.4% at recent prices, and it has raised its dividend for 56 consecutive years. This raise makes it a Dividend King, a company that has delivered 50 or more years of annual dividend increases. Universal isn't a cigarette maker, but it is the world's largest leaf tobacco exporter and importer. It supplies tobacco companies rather than selling to smokers directly, which is why it rarely shows up in articles about tobacco stocks.
#market

26 days ago
During the second quarter, Pershing Square Capital Management, the hedge fund firm founded by Bill Ackman, initiated positions in Visa (NYSE: V) and Mastercard (NYSE: MA). While their share prices have appreciated in recent months, these businesses traded at attractive valuations at purchase.
Here are three reasons the billionaire investor is bullish on these two S&P 500 stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman's firm believes these are two of the highest-quality businesses on Earth. There are three notable factors supporting this view.
Visa and Mastercard, which connect consumers, merchants, and banks around the world, have developed robust network effects. This makes their platforms almost impossible to disrupt.
#pershing
Here are three reasons the billionaire investor is bullish on these two S&P 500 stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman's firm believes these are two of the highest-quality businesses on Earth. There are three notable factors supporting this view.
Visa and Mastercard, which connect consumers, merchants, and banks around the world, have developed robust network effects. This makes their platforms almost impossible to disrupt.
#pershing


27 days ago
Before we get worried about recessions or market crashes, let's put a 10% drop in context. Going back to 1980, the S&P 500 has fallen 10% or more in roughly half of all calendar years, and a correction of that size has historically shown up about once every 12 to 18 months.
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month
What makes a 10% decline packed into a single month unusual isn't the size of the drop, it's the speed: that kind of compressed move tends to show up during sudden shocks rather than the slower grind most corrections take. Even so, it's happened before, and the market has recovered every time.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
My goal here isn't to predict whether October brings one. It's to point to three consumer businesses whose underlying demand doesn't particularly care what the stock market does that month.
Procter & Gamble (NYSE: PG) makes Tide, Pampers, Crest, and Gillette. These products are the kind of household basics people buy again almost automatically, recession or not. That steadiness shows up in the numbers. P&G generated more than $87 billion in revenue in its 2026 fiscal year and returned over $15 billion to shareholders through dividends and buybacks.
#market #flashing #every #month


27 days ago
At the end of 2025, Warren Buffett stepped down from his longtime position as the CEO of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB). Over the 61 years he ran the company, the stock produced incredible returns for shareholders, rising by more than six million percent. Over the same span, the S&P 500 index (SNPINDEX: ^GSPC) gained 46,000%.
Clearly, Buffett earned the nickname the "Oracle of Omaha." But can you still benefit from his investment wisdom now that the 96-year-old investor is no longer with Berkshire Hathaway? You sure can!
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Buffett's investment approach is deceptively simple to explain. He liked to buy well-run businesses while they were attractively priced. Then he liked to hold for the long term, so he could benefit from the growth of the businesses in which he invested. That's something that any investor can do. And while all investment approaches go in and out of favor over time, this one has clearly proven itself to be a long-term winner.
That said, Buffett was also highly selective. He once described investing as a baseball game where they don't call ******* and strikes. His point was that you don't have to swing at every pitch, even though you should have a diversified portfolio. The Motley Fool recommends 50 stocks as a good portfolio size, but there are thousands of investments you could choose from. Once again, Buffett's advice is very good: Be selective.
#hathaway #once #investor
Clearly, Buffett earned the nickname the "Oracle of Omaha." But can you still benefit from his investment wisdom now that the 96-year-old investor is no longer with Berkshire Hathaway? You sure can!
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Buffett's investment approach is deceptively simple to explain. He liked to buy well-run businesses while they were attractively priced. Then he liked to hold for the long term, so he could benefit from the growth of the businesses in which he invested. That's something that any investor can do. And while all investment approaches go in and out of favor over time, this one has clearly proven itself to be a long-term winner.
That said, Buffett was also highly selective. He once described investing as a baseball game where they don't call ******* and strikes. His point was that you don't have to swing at every pitch, even though you should have a diversified portfolio. The Motley Fool recommends 50 stocks as a good portfolio size, but there are thousands of investments you could choose from. Once again, Buffett's advice is very good: Be selective.
#hathaway #once #investor


27 days ago
Apple (NASDAQ: AAPL) is recognized as one of the world's most elite businesses. And as a result of its success, investors have profited immensely. The consumer discretionary stock has soared 1,070% in the past decade (as of Oct. 2).
But the company's capital allocation policy also favors investors in another minor way, one that brings in an income stream. Here's how many Apple shares you'd need to make $10,000 in yearly dividends.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Apple currently pays a dividend that totals $1.08 per share on an annual basis. This means that investors would need to own 9,259 shares to generate $10,000 in yearly income. At the current stock price of $331.22, investors must fork over almost $3.1 million to buy enough shares.
Clearly, Apple isn't a compelling dividend stock. Its dividend yield is extremely low at 0.32%. However, the payout has grown by 89% in the past 10 years.
#investors #Stock #income #yearly
But the company's capital allocation policy also favors investors in another minor way, one that brings in an income stream. Here's how many Apple shares you'd need to make $10,000 in yearly dividends.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Apple currently pays a dividend that totals $1.08 per share on an annual basis. This means that investors would need to own 9,259 shares to generate $10,000 in yearly income. At the current stock price of $331.22, investors must fork over almost $3.1 million to buy enough shares.
Clearly, Apple isn't a compelling dividend stock. Its dividend yield is extremely low at 0.32%. However, the payout has grown by 89% in the past 10 years.
#investors #Stock #income #yearly
1 month ago
Recently, Danny Trejo hosted the TMZ Brunch Bus through Hollywood, hanging out with the tour's DJ and stopping at his own businesses, Trejo's Coffee & Donuts and Trejo's Tacos.
He was telling the passengers about taking a low-budget movie as a favor to a director who needed a name to get financing.
"Everything good that has happened to me has happened as a direct result of helping someone else," he told the crowd.
Then, a woman leaned over and told him that his sister, Marlene, was her mother.
"Are you kidding?" Trejo said.
#happened #recently #danny #coffee
He was telling the passengers about taking a low-budget movie as a favor to a director who needed a name to get financing.
"Everything good that has happened to me has happened as a direct result of helping someone else," he told the crowd.
Then, a woman leaned over and told him that his sister, Marlene, was her mother.
"Are you kidding?" Trejo said.
#happened #recently #danny #coffee

1 month ago
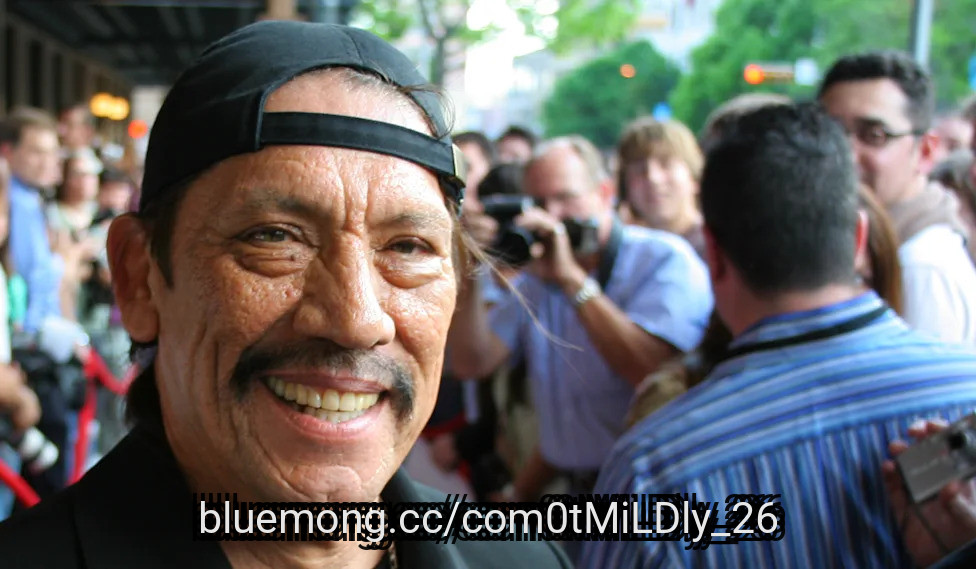
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) announced on September 21 a services agreement worth more than $700 million with La Compagnie du TransGuinéen. Combined with locomotive orders placed in 2024, announced agreements for the Simandou project now exceed $1.2 billion.
The railway stretches more than 600 kilometers between the Simandou mine and Guinea's Port of Morebaya. The new agreement extends the relationship beyond locomotive delivery into ongoing fleet support. For investors, the opportunity is to earn revenue throughout the equipment's operating life.
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) will provide scheduled and unscheduled maintenance, parts, component overhauls, logistics support, remote diagnostics, and training. These activities create multiple opportunities to serve the same fleet after the initial equipment sale.
That is an attractive business model when maintenance needs translate into repeat orders and efficient service delivery. Familiarity with the locomotives should help technicians diagnose problems and plan repairs. Remote monitoring could also help identify faults before they cause prolonged downtime, strengthening the customer's incentive to maintain the relationship.
Local workforce development and partnerships with Guinean businesses could improve responsiveness as the operation matures. Over time, an experienced local team could reduce dependence on specialists traveling to the site and make parts planning more efficient.
#westinghouse #brake #agreement
The railway stretches more than 600 kilometers between the Simandou mine and Guinea's Port of Morebaya. The new agreement extends the relationship beyond locomotive delivery into ongoing fleet support. For investors, the opportunity is to earn revenue throughout the equipment's operating life.
Westinghouse Air Brake Technologies Corporation (NYSE:WAB) will provide scheduled and unscheduled maintenance, parts, component overhauls, logistics support, remote diagnostics, and training. These activities create multiple opportunities to serve the same fleet after the initial equipment sale.
That is an attractive business model when maintenance needs translate into repeat orders and efficient service delivery. Familiarity with the locomotives should help technicians diagnose problems and plan repairs. Remote monitoring could also help identify faults before they cause prolonged downtime, strengthening the customer's incentive to maintain the relationship.
Local workforce development and partnerships with Guinean businesses could improve responsiveness as the operation matures. Over time, an experienced local team could reduce dependence on specialists traveling to the site and make parts planning more efficient.
#westinghouse #brake #agreement

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
1 month ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer

1 month ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
1 month ago
On September 9, 2026, Reuters reported that AI music startup Suno launched a new suite of models, including its flagship v6 and exploratory v6-Wild, built in partnership with Warner Music Group Corp. (NASDAQ:WMG) and BMG. It lets users make new music inspired by licensed recordings from participating artists. The launch follows Warner Music's copyright lawsuit settlement with Suno in November 2025, under which artists and songwriters can opt in to have their names, voices, and compositions used in AI-generated music in exchange for compensation.
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue
Warner Music Group Corp. (NASDAQ:WMG) can turn the Suno litigation dispute into a new licensing revenue opportunity. Suno has now launched its v6 models in partnership with Warner Music and BMG. It allows users to make music inspired by licensed works from participating artists. Warner previously sued Suno over copyright issues before reaching a licensing agreement. This gives the label a direct path to monetize AI-generated music rather than relying solely on litigation. The deal could create a new revenue stream as consumers increasingly adopt AI music tools.
Warner enters the AI-music market from a position of financial strength. The firm reported fiscal third-quarter revenue of $5.44 billion, up 9% year over year. Adjusted OIBDA increased 16% to $433 million, and its adjusted OIBDA margin expanded to 23.2%. Warner also said it had met or exceeded its financial targets for five consecutive quarters. That basic growth gives the company greater flexibility to invest in AI initiatives while using licensing agreements to add another potential growth driver to its existing streaming and publishing businesses.
Warner could help establish a more sustainable commercial model for AI-generated music. Suno said future products will include opt-in experiences that allow individual artists to participate and receive payment when users generate music around them. So Warner has an opportunity to help shape licensing and compensation practices as Spotify and other platforms develop their own AI-music products. If the industry increasingly adopts licensed models, Warner's large catalog and relationships with artists could solidify its negotiating position and create recurring AI-related revenue.
Suno's new licensing model does not eliminate the overall legal risks surrounding AI music. Warner Music Group Corp. (NASDAQ:WMG) has reached an agreement with Suno, but other copyright owners are challenging the firm's technology. Independent publisher Round Hill sued Suno in August, alleging that the company used copyrighted songs to train its AI system. Suno also faces separate litigation from Universal Music Group and Sony Music. Hence, lawsuits could increase legal costs and create uncertainty over the licensing framework that Warner hopes to monetize.
#music #licensing #corp #revenue

1 month ago
Anthropic's initial public offering (IPO) appears to be on pace to take place in late October or early November. Right now, it is difficult for retail investors to get a stake in the artificial intelligence (AI) giant, which is one of the fastest-growing businesses in the world.
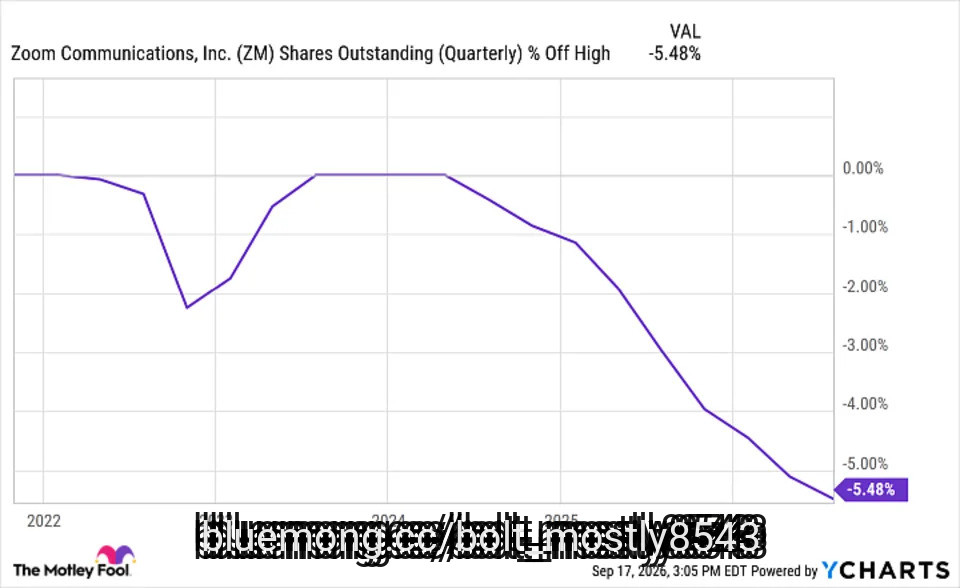
But there is an investment you could make that would get you sizable indirect exposure to Anthropic ahead of its listing. Zoom Communications (NASDAQ: ZM), the leading cloud video conferencing company, bought a stake in Anthropic back in May 2023, and that investment could now be worth billions.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's see whether that makes Zoom stock a buy right now.
Zoom made a $51 million investment in Anthropic in May 2023, and that has turned out to be one of the smartest decisions the company has ever made (maybe even smarter than its choice to go public right before the pandemic).
#investment #missed
But there is an investment you could make that would get you sizable indirect exposure to Anthropic ahead of its listing. Zoom Communications (NASDAQ: ZM), the leading cloud video conferencing company, bought a stake in Anthropic back in May 2023, and that investment could now be worth billions.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's see whether that makes Zoom stock a buy right now.
Zoom made a $51 million investment in Anthropic in May 2023, and that has turned out to be one of the smartest decisions the company has ever made (maybe even smarter than its choice to go public right before the pandemic).
#investment #missed


1 month ago
NextEra Energy, Inc. (NYSE:NEE) announced on September 8 that it had secured a loan of up to $1.9 billion from the U.S. Department of Energy to support the restart of a shuttered nuclear power plant in Iowa. The Duane Arnold Energy Center ceased operations in 2020 after 45 years of service. The plant is now expected to resume operations in early 2029, pending regulatory approvals.
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold

1 month ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet



1 month ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents


1 month ago
Palantir (PLTR) CEO Alex Karp has dropped a blunt theory about the AI industry's safety push.
The outspoken AI executive said that some companies might need government ownership to escape the financial consequences of their technology.
In his CNBC interview, Karp framed nationalization as the destination he believes those businesses are moving toward, with liability protection the prize.
His startling comments come as the industry's conversation shifts towards safeguards and whether development should slow down. Moreover, that also raises the question of who shoulders the risks created along the way?
Karp zeroes in on customers' intellectual property. He said businesses working with Palantir believe that their ideas and data are being fed into AI models, putting their competitive advantages at risk.
#businesses #alex #cnbc #moreover
The outspoken AI executive said that some companies might need government ownership to escape the financial consequences of their technology.
In his CNBC interview, Karp framed nationalization as the destination he believes those businesses are moving toward, with liability protection the prize.
His startling comments come as the industry's conversation shifts towards safeguards and whether development should slow down. Moreover, that also raises the question of who shoulders the risks created along the way?
Karp zeroes in on customers' intellectual property. He said businesses working with Palantir believe that their ideas and data are being fed into AI models, putting their competitive advantages at risk.
#businesses #alex #cnbc #moreover
1 month ago
On September 18, Prudential Financial (NYSE:PRU) announced it will sell every share it holds in Alexforbes, a company listed on the Johannesburg Stock Exchange. Two buyers are splitting the stake. Alexforbes will repurchase roughly 372.8 million shares itself, and ARC AF Holdings will take about 74.1 million more. The package is worth about $185 million, a small number for a company managing $1.642 trillion. But the message matters more than the money. A plan Prudential laid out in August is now turning into signed agreements.
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money
The logic is easy to follow. Prudential wants to operate in fewer places and put its money, people and attention where it thinks it can win for years. Andy Sullivan, the chief executive, says the aim is to lean harder on ***** et management, retirement and protection, and get those units working together more closely. David Legher, who leads emerging markets, called Alexforbes a successful investment, so this reads as a planned exit rather than a retreat from a problem.
The core business is giving management room to be choosy. On August 4, Prudential reported second-quarter net income of $985 million, up from $533 million a year earlier. That happened even though a charge from the yearly ***** umption update grew to $299 million from $134 million, so the underlying engine ran strong enough to absorb a bigger hit. The company also returned $743 million to shareholders in the quarter and held $4.2 billion in highly liquid ***** ets at the parent level. That does not look like a seller in a hurry.
Start with what has not happened yet. The deals are expected to close in the first half of 2027, and they still need Alexforbes shareholders to approve the buyback, along with regulatory sign-off. Until then, $185 million is an agreed price, not cash in the bank. Prudential also said New Veld's involvement continues before completion, so the company stays tied to the ***** et for now.
Then there is the size. Set against those trillions in ***** ets, this sale will not move results either way. Its value is strategic, and strategy takes years to judge. Prudential is giving up a foothold in a partnership it called important, and its remaining businesses have their own snags. Sales in Prudential of ***** an are suspended, and management said that weighed on international results even as earnings held up.
#august #money


1 month ago
Experienced investors know the advantages of buying and holding S&P 500 index funds like the Vanguard S&P 500 ETF (NYSEMKT: VOO) or the SPDR S&P 500 ETF Trust (NYSEMKT: SPY). Not only are they super simple, but statistically speaking, you're likely to get better performance from them than you are by picking individual stocks or by owning an actively managed fund.
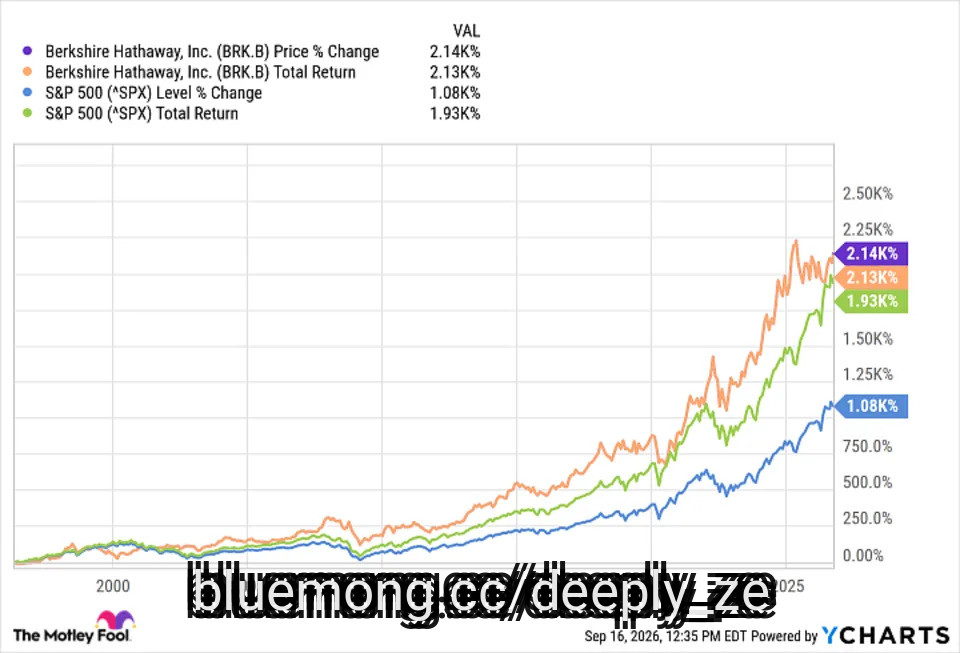
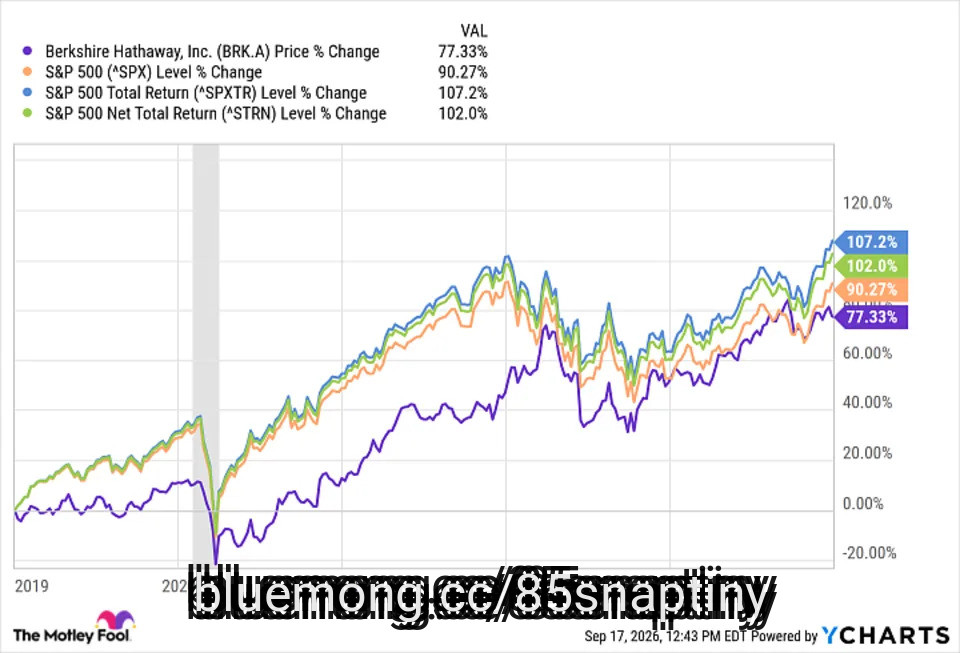
Nevertheless, given its long-term (and often market-beating) track record, even the most disciplined of investors might have the itch to step into a stake in Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB). But is it actually the better buy?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Berkshire Hathaway is a conglomerate consisting of several dozen reliable cash-producing businesses as well as a portfolio of hand-picked stocks. Brought to prominence by Warren Buffett, the company's flexible structure has enabled its shares to consistently outperform the S&P 500 since Buffett first took the helm in 1965.
It hasn't beaten the market every year since then, to be clear. Some years it did. Other years it didn't. It typically achieved the feat in five-year time frames.
#signal #years #buffett #flashing
Nevertheless, given its long-term (and often market-beating) track record, even the most disciplined of investors might have the itch to step into a stake in Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB). But is it actually the better buy?
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Berkshire Hathaway is a conglomerate consisting of several dozen reliable cash-producing businesses as well as a portfolio of hand-picked stocks. Brought to prominence by Warren Buffett, the company's flexible structure has enabled its shares to consistently outperform the S&P 500 since Buffett first took the helm in 1965.
It hasn't beaten the market every year since then, to be clear. Some years it did. Other years it didn't. It typically achieved the feat in five-year time frames.
#signal #years #buffett #flashing

1 month ago
Interested in Ally Financial Inc.? Here are five stocks we like better.
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis


1 month ago
Are you worried enough about rising interest rates jump-starting a recession that you're looking for ways of sidestepping the effect of such an economic headwind? It's not a terrible idea to at least start making a mental plan for that possibility.
You may have considered Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) to fill that role. Its wholly owned, private businesses generate plenty of cash flow regardless of the economic backdrop, after all.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But how do Berkshire shares actually perform during recessions? It's not like the data doesn't exist.
You probably know Berkshire Hathaway best by its stock picks. Although they're not built to be an actively managed mutual fund, its equity holdings -- and changes to these holdings -- are closely followed by investors looking for some new ideas for their own portfolios.
#berkshire #signal #NYSE #flashing
You may have considered Berkshire Hathaway (NYSE: BRKA) (NYSE: BRKB) to fill that role. Its wholly owned, private businesses generate plenty of cash flow regardless of the economic backdrop, after all.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
But how do Berkshire shares actually perform during recessions? It's not like the data doesn't exist.
You probably know Berkshire Hathaway best by its stock picks. Although they're not built to be an actively managed mutual fund, its equity holdings -- and changes to these holdings -- are closely followed by investors looking for some new ideas for their own portfolios.
#berkshire #signal #NYSE #flashing


1 month ago
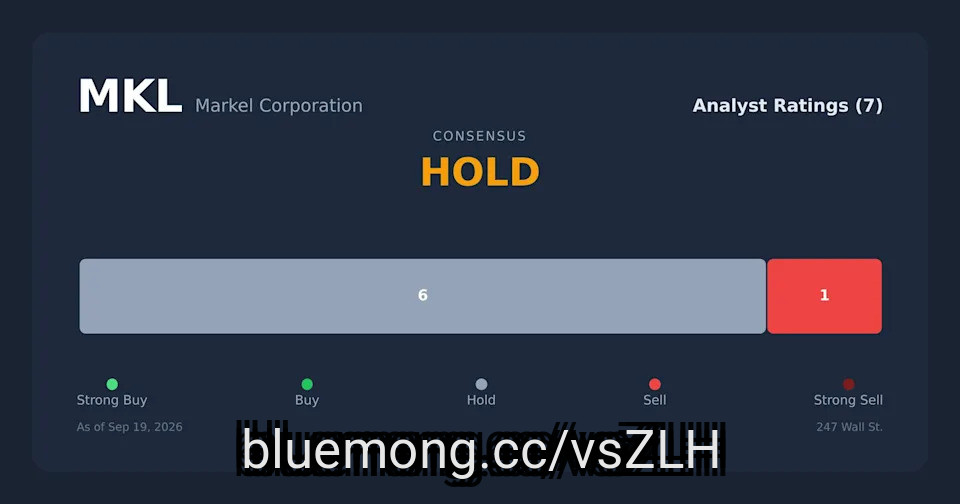
Markel mirrors Berkshire's three-engine model of insurance, equities, and operating businesses, with $18.84 billion in float and $429.5 million in 2025 buybacks, but its $22 billion market cap makes it a fundamentally different species.
Markel's combined ratio improved to 94.6% in 2025, yet shares are down 17% year to date while trailing Berkshire's 10-year return by 155 percentage points.
Three signals determine the Markel thesis: whether the combined ratio holds in the low 90s, buybacks sustain pace, and Markel Ventures remains inside the group.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Berkshire Hathaway didn't make the cut. Enter your email to see the names that beat BRK-B. The report is free. Enter your email and see if any of your stocks made the cut.
Warren Buffett has stepped down as board chair of Berkshire Hathaway, with Greg Abel now running the company. The handoff has revived a question value investors have batted around for a decade: with the Oracle off the field, is Markel Group (NYSE:MKL) the closest thing left to early Berkshire Hathaway (NYSE:BRK-B)?
#hathaway #group #market
Markel's combined ratio improved to 94.6% in 2025, yet shares are down 17% year to date while trailing Berkshire's 10-year return by 155 percentage points.
Three signals determine the Markel thesis: whether the combined ratio holds in the low 90s, buybacks sustain pace, and Markel Ventures remains inside the group.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Berkshire Hathaway didn't make the cut. Enter your email to see the names that beat BRK-B. The report is free. Enter your email and see if any of your stocks made the cut.
Warren Buffett has stepped down as board chair of Berkshire Hathaway, with Greg Abel now running the company. The handoff has revived a question value investors have batted around for a decade: with the Oracle off the field, is Markel Group (NYSE:MKL) the closest thing left to early Berkshire Hathaway (NYSE:BRK-B)?
#hathaway #group #market


1 month ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth

1 month ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august


1 month ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
Warren Buffett built one of the world's largest fortunes by investing in businesses he understood, buying at attractive prices and giving those investments plenty of time to grow.
But what would the legendary investor do if he had to start over with just $10,000?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#earn
Warren Buffett built one of the world's largest fortunes by investing in businesses he understood, buying at attractive prices and giving those investments plenty of time to grow.
But what would the legendary investor do if he had to start over with just $10,000?
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#earn

1 month ago
Des Moines, Iowa-based Principal Financial Group, Inc. (PFG) provides retirement, ******* et management, and insurance products and services to businesses, individuals, and institutional clients worldwide. The company has a market cap of $25 billion and operates through Retirement and Income Solutions, Principal ******* et Management, and Benefits and Protection segments.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." PFG fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the ******* et management industry.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#asset #management #market #moines
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." PFG fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the ******* et management industry.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#asset #management #market #moines