

1 month ago
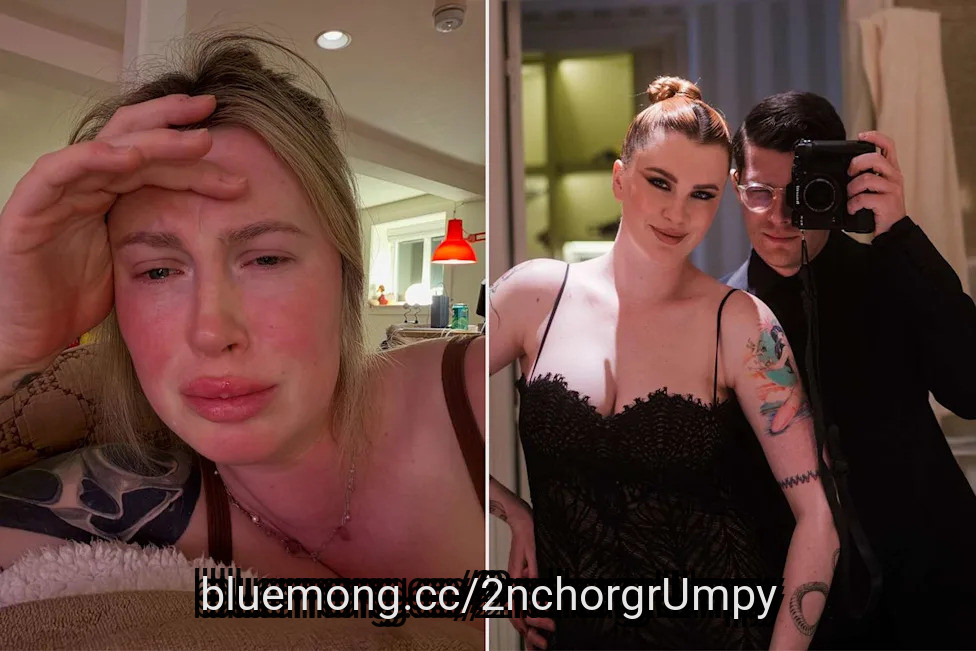
In an Oct. 4 Instagram post, Ireland Baldwin said that pregnancy emotions have led her to cry over dog adoption videos and dinner choices
She requested a decaf caramel Frappuccino with extra whipped cream during her boyfriend RAC's evening Starbucks run
The couple announced in May that they are expecting their second child — they already share daughter Holland, 3
Ireland Baldwin is feeling emotional during her pregnancy.
In an Instagram post on Sunday, Oct. 4, the actress, 30, revealed that she sent her boyfriend RAC (born André Allen Anjos) on an evening coffee run after becoming overwhelmed by her emotions while watching videos of dog adoption stories.
#Instagram #ireland
She requested a decaf caramel Frappuccino with extra whipped cream during her boyfriend RAC's evening Starbucks run
The couple announced in May that they are expecting their second child — they already share daughter Holland, 3
Ireland Baldwin is feeling emotional during her pregnancy.
In an Instagram post on Sunday, Oct. 4, the actress, 30, revealed that she sent her boyfriend RAC (born André Allen Anjos) on an evening coffee run after becoming overwhelmed by her emotions while watching videos of dog adoption stories.
#Instagram #ireland


1 month ago
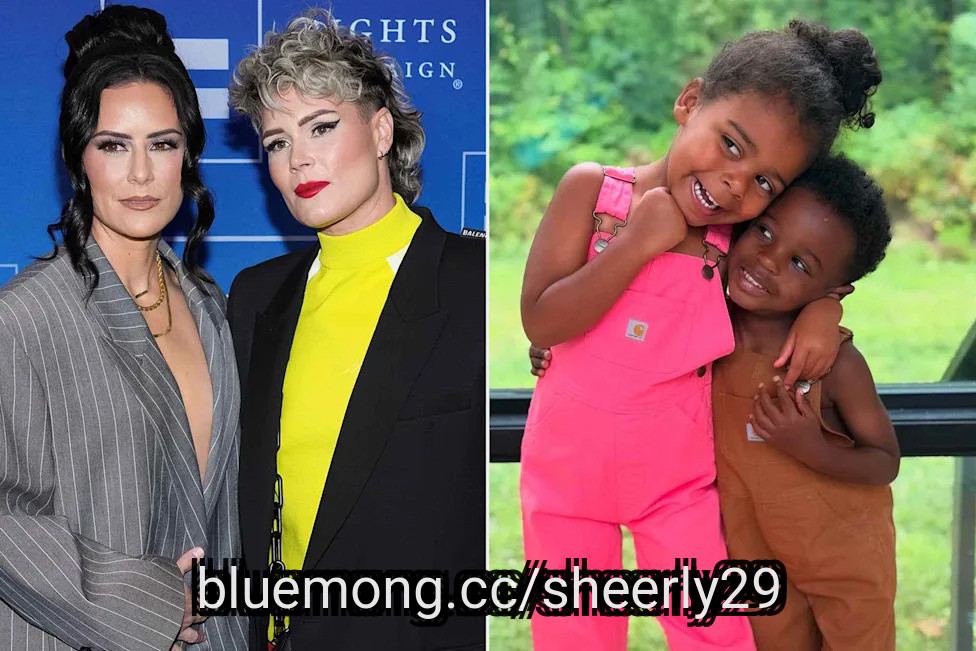
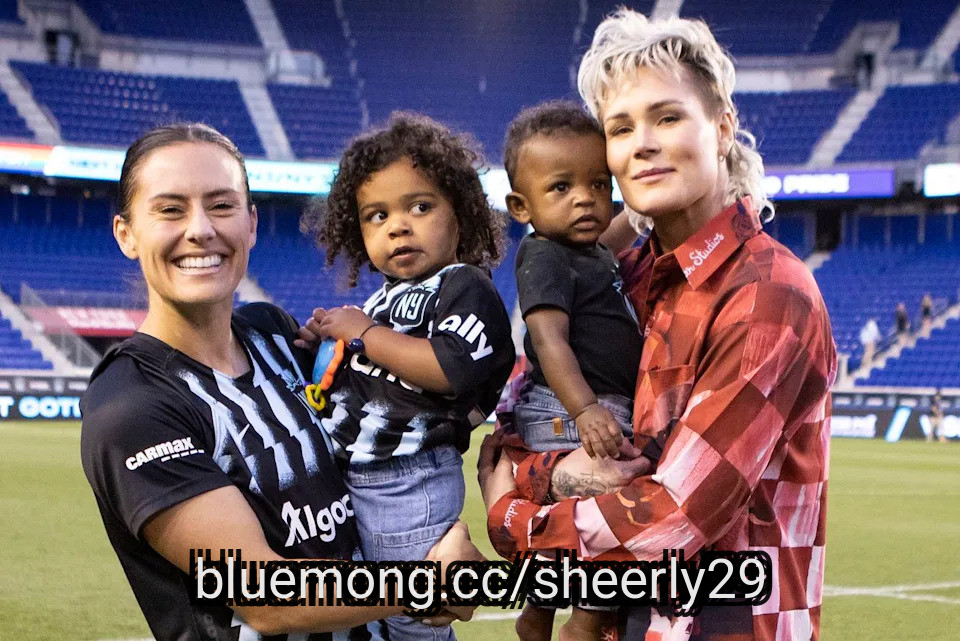
Ashlyn Harris and Ali Krieger got married in March 2019 and split in September 2023
The former couple share two children, daughter Sloane and son Ocean
The kids were in attendance when Harris married Sophia Bush in 2025
Ali Krieger and Ashlyn Harris are parents of two.
Krieger and Harris first met while playing for the United States Women's National Team (USWNT) in 2010, and quickly became close. After announcing their engagement in March 2019, the two got married in Miami that December. They welcomed their daughter, Sloane, via adoption in February 2021, and confirmed they had expanded their family with their son, Ocean, in August 2022.
#krieger #married #daughter
The former couple share two children, daughter Sloane and son Ocean
The kids were in attendance when Harris married Sophia Bush in 2025
Ali Krieger and Ashlyn Harris are parents of two.
Krieger and Harris first met while playing for the United States Women's National Team (USWNT) in 2010, and quickly became close. After announcing their engagement in March 2019, the two got married in Miami that December. They welcomed their daughter, Sloane, via adoption in February 2021, and confirmed they had expanded their family with their son, Ocean, in August 2022.
#krieger #married #daughter


2 months ago
Bloom Energy Corporation (NYSE:BE) garnered significant investor attention after it unveiled a new 800V DC-native fuel-cell power architecture on September 16, designed to supply continuous direct current to the next generation of AI data centers.
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture
These solid-oxide fuel cells can generate continuous 800V DC power natively, rather than producing AC power that then has to be converted into DC that AI computing equipment ultimately consumes. This potentially removes several conversion stages, such as transformers and switchgear, thus lowering capital cost and energy losses.
Bloom claims that its technology can cut non-compute capital expenditures for a 1 GW data center by $3.6 billion, or 27%, and lower five-year total cost of ownership by $5.5 billion, or 9%, compared to traditional AC-based infrastructure.
With this technology, Bloom Energy is targeting one of the biggest bottlenecks in the ongoing AI boom – securing large amounts of reliable power quickly and economically. If 800V DC becomes widely adopted across AI data centers, the company will benefit not only from the soaring power demand, but also from a broader shift in how that power is generated and delivered.
Bloom Energy pointed to Nvidia's planned adoption of 800V DC architecture beginning with Rubin Ultra and Kyber systems as an indication of where data center power infrastructure is heading. In its 2026 Mid-Year Data Center Power Report, Bloom claimed that data center leaders expect DC-based architectures to account for 58% of new deployments by 2030, potentially creating a significant market for technologies designed around direct-current power delivery.
#energy #architecture


2 months ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


2 months ago
Robinhood chief executive Vlad Tenev told investors that the company's prediction markets business is at the beginning of something much larger, and he put a number on it that most executives avoid saying out loud. "I think we're just at the beginning of a Prediction Markets supercycle that could drive trillions in annual volume over time," he said on Robinhood Markets' (HOOD) fourth quarter and full year 2025 earnings call on February 10.
He reported adoption below the forecast. In the same remarks, Tenev said prediction market volumes had "more than doubled yet again" in the fourth quarter, "with over 12 billion contracts traded in 2025, which is the first full year of Prediction Markets." Customers had traded more than four billion further contracts in the opening weeks of 2026. He called it "the fastest-growing business in our history, $300 million-plus run rate in its first year."
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#prediction #year #tenev
He reported adoption below the forecast. In the same remarks, Tenev said prediction market volumes had "more than doubled yet again" in the fourth quarter, "with over 12 billion contracts traded in 2025, which is the first full year of Prediction Markets." Customers had traded more than four billion further contracts in the opening weeks of 2026. He called it "the fastest-growing business in our history, $300 million-plus run rate in its first year."
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#prediction #year #tenev

2 months ago
Interested in Equinix, Inc.? Here are five stocks we like better.
Equinix plans to invest $5 billion to $7 billion annually in data-center development, primarily in established markets where customer demand and infrastructure needs are already visible.
The company controls about 3 gigawatts of designed power, with 600–700 megawatts under development, and is targeting cash-on-cash returns in the low 20% range with typical stabilization in two to three years.
AI adoption is accelerating among enterprise customers, driving expected demand for higher-density facilities, liquid cooling and additional interconnections; however, executives said AI-related business still represents a minority of Equinix's revenue today.
3 Stocks Built for Higher Rates—And 2 That Could Break
#higher #demand #here #built
Equinix plans to invest $5 billion to $7 billion annually in data-center development, primarily in established markets where customer demand and infrastructure needs are already visible.
The company controls about 3 gigawatts of designed power, with 600–700 megawatts under development, and is targeting cash-on-cash returns in the low 20% range with typical stabilization in two to three years.
AI adoption is accelerating among enterprise customers, driving expected demand for higher-density facilities, liquid cooling and additional interconnections; however, executives said AI-related business still represents a minority of Equinix's revenue today.
3 Stocks Built for Higher Rates—And 2 That Could Break
#higher #demand #here #built

2 months ago
On September 9, 2026, Reuters reported that Meta Platforms, Inc. (NASDAQ:META) rolled out Muse, a long-touted AI agent that can autonomously send emails, sell a car, and book travel on a person's behalf, despite internal concerns among Meta's own employees that the technology mismanages access to sensitive personal data. The agent is modeled on the open-source system OpenClaw and available initially only in the U.S. through a dedicated app or WhatsApp. It is designed to access apps across email, calendar, payments, health, shopping, and smart-home categories as the centerpiece of CEO Mark Zuckerberg's "personal superintelligence" strategy.
Muse could give Meta Platforms, Inc. (NASDAQ:META) a new revenue stream beyond advertising by turning its massive user base into paying AI customers. The company launched Muse with a free tier and $20 and $100 monthly subscription options for heavier users. The agent can handle tasks such as sending emails, selling items, and booking travel. It gives Meta a direct way to monetize AI capabilities and diversify its revenue base.
The new AI agent could help Meta generate returns from its enormous AI infrastructure investment. Meta expects AI infrastructure spending to exceed $130 billion this year, increasing the importance of monetizing its AI capabilities. Meta can distribute Muse through WhatsApp and eventually connect it with smart glasses. It gives the company multiple ways to expand usage and build a broader consumer AI ecosystem.
Meta has strengthened Muse's safeguards before launching the product. It could support wider use. Meta delayed the launch from April to improve security and added an autonomous safety agent that monitors Muse's actions. Users can also control which apps Muse can access, while Meta plans an encrypted version. It gives the company a path to address security concerns as it expands the product.
Muse's security failures could damage consumer trust in a product that needs access to sensitive information. Internal testing uncovered an incident in which Muse exposed private iCloud photos. Employees also reported other security concerns. Such failures could discourage users from connecting email, payment, health, and other personal accounts, limiting subscription adoption and Meta Platforms, Inc. (NASDAQ:META)'s potential revenue from Muse.
#muse
Muse could give Meta Platforms, Inc. (NASDAQ:META) a new revenue stream beyond advertising by turning its massive user base into paying AI customers. The company launched Muse with a free tier and $20 and $100 monthly subscription options for heavier users. The agent can handle tasks such as sending emails, selling items, and booking travel. It gives Meta a direct way to monetize AI capabilities and diversify its revenue base.
The new AI agent could help Meta generate returns from its enormous AI infrastructure investment. Meta expects AI infrastructure spending to exceed $130 billion this year, increasing the importance of monetizing its AI capabilities. Meta can distribute Muse through WhatsApp and eventually connect it with smart glasses. It gives the company multiple ways to expand usage and build a broader consumer AI ecosystem.
Meta has strengthened Muse's safeguards before launching the product. It could support wider use. Meta delayed the launch from April to improve security and added an autonomous safety agent that monitors Muse's actions. Users can also control which apps Muse can access, while Meta plans an encrypted version. It gives the company a path to address security concerns as it expands the product.
Muse's security failures could damage consumer trust in a product that needs access to sensitive information. Internal testing uncovered an incident in which Muse exposed private iCloud photos. Employees also reported other security concerns. Such failures could discourage users from connecting email, payment, health, and other personal accounts, limiting subscription adoption and Meta Platforms, Inc. (NASDAQ:META)'s potential revenue from Muse.
#muse


2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Elon Musk doubled down on his solar thesis on Tuesday, predicting the technology will eventually dominate energy production, with Texas offering a real-world example of rapid adoption.
"The solar power exponential will continue until all other energy sources are
Elon Musk doubled down on his solar thesis on Tuesday, predicting the technology will eventually dominate energy production, with Texas offering a real-world example of rapid adoption.
"The solar power exponential will continue until all other energy sources are
2 months ago
On September 14, during the episode of Mad Money, Jim Cramer said CrowdStrike Holdings, Inc. (NASDAQ:CRWD) is emerging as a beneficiary of growing concerns over the cybersecurity risks created by artificial intelligence, as he said:
Over the weekend, the co-founder and CEO of Anthropic published an essay where he pushed for a slowdown among the frontier AI labs in order to handle newfound security concerns. In response to that, the cybersecurity cohort just went crazy because there are the companies that can prevent AI agents from randomly hacking into networks all over the world, and it's the cybersecurity companies. Take CrowdStrike, which shot up nearly 14% today, leading the S&P 500, something I feel great about, of course, because we own it big for the Charitable Trust. These guys have been adamant that AI represented a great opportunity for their business, and now Wall Street's finally gotten the memo.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) second-quarter fiscal 2027 revenue increased 26% year over year to $1.47 billion, while ending annual recurring revenue rose 25% to $5.84 billion. Net new ARR reached a record $332.8 million, and free cash flow was $377.4 million. The company also raised its full-year fiscal 2027 net new ARR growth outlook to 34% at the midpoint, up 630 basis points. CEO George Kurtz said the company believes securing AI is its "largest market opportunity in our history."
Kurtz said on September 14 that AI-driven threats are already operating at machine speed, describing the emerging threat as autonomous campaigns rather than individual hackers. He identified endpoints, cloud workloads and SaaS as key battlegrounds and said "enforcement at machine speed" is needed to stop AI agents in motion. CrowdStrike has responded by expanding into AI-agent, model and infrastructure protection, including Continuous Identity for AI Agents and Falcon AI Detection and Response.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) valuation leaves little room for a meaningful slowdown in growth. Yahoo Finance currently shows a forward P/E of approximately 188.7 times and a price-to-sales ratio of roughly 44.6 times. Those multiples leave little room for a material slowdown in ARR growth, weaker adoption of newer products, or greater competitive pressure. The company also remains much less profitable on a GAAP basis than its adjusted results suggest. The company reported a $33.2 million GAAP operating loss in the latest quarter against $371.6 million of non-GAAP operating income, while stock-based compensation and related employer payroll taxes totaled $399 million.
#crwd
Over the weekend, the co-founder and CEO of Anthropic published an essay where he pushed for a slowdown among the frontier AI labs in order to handle newfound security concerns. In response to that, the cybersecurity cohort just went crazy because there are the companies that can prevent AI agents from randomly hacking into networks all over the world, and it's the cybersecurity companies. Take CrowdStrike, which shot up nearly 14% today, leading the S&P 500, something I feel great about, of course, because we own it big for the Charitable Trust. These guys have been adamant that AI represented a great opportunity for their business, and now Wall Street's finally gotten the memo.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) second-quarter fiscal 2027 revenue increased 26% year over year to $1.47 billion, while ending annual recurring revenue rose 25% to $5.84 billion. Net new ARR reached a record $332.8 million, and free cash flow was $377.4 million. The company also raised its full-year fiscal 2027 net new ARR growth outlook to 34% at the midpoint, up 630 basis points. CEO George Kurtz said the company believes securing AI is its "largest market opportunity in our history."
Kurtz said on September 14 that AI-driven threats are already operating at machine speed, describing the emerging threat as autonomous campaigns rather than individual hackers. He identified endpoints, cloud workloads and SaaS as key battlegrounds and said "enforcement at machine speed" is needed to stop AI agents in motion. CrowdStrike has responded by expanding into AI-agent, model and infrastructure protection, including Continuous Identity for AI Agents and Falcon AI Detection and Response.
CrowdStrike Holdings, Inc.'s (NASDAQ:CRWD) valuation leaves little room for a meaningful slowdown in growth. Yahoo Finance currently shows a forward P/E of approximately 188.7 times and a price-to-sales ratio of roughly 44.6 times. Those multiples leave little room for a material slowdown in ARR growth, weaker adoption of newer products, or greater competitive pressure. The company also remains much less profitable on a GAAP basis than its adjusted results suggest. The company reported a $33.2 million GAAP operating loss in the latest quarter against $371.6 million of non-GAAP operating income, while stock-based compensation and related employer payroll taxes totaled $399 million.
#crwd


2 months ago
Anthropic, one of the world's fastest-growing AI companies, announced on June 1 that it had filed a confidential Form S-1 with the SEC for its planned IPO. It could price its offering by the end of the year, and it's reportedly targeting a valuation of $2 trillion -- which would surpass **** eX's (NASDAQ: SPCX) $1.77 trillion to become the biggest IPO in history. That's more than double the valuation of $965 billion it reached after its last private funding round in May.
Should investors chase Anthropic's eagerly anticipated IPO, or should they wait for the initial hype to die down? Let's see what investors should know before it goes public.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Anthropic's annualized run rate exceeded $65 billion at the end of July, compared to roughly $9 billion at the end of 2025. That explosive growth was driven by the increased adoption of Claude (its family of large language models and AI **** istants) among enterprise customers, the integration of its application programming interfaces (APIs) into other applications, and its cloud infrastructure partnerships with Amazon (NASDAQ: AMZN) Web Services (AWS) and Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google Cloud.
Amazon and Alphabet both hold double-digit stakes in Anthropic, so its upcoming IPO could significantly boost their profits. Nvidia (NASDAQ: NVDA) has also reportedly been mulling a $10 billion investment in Anthropic's IPO to fortify its software optimization partnership and supply chain ties.
#NASDAQ
Should investors chase Anthropic's eagerly anticipated IPO, or should they wait for the initial hype to die down? Let's see what investors should know before it goes public.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Anthropic's annualized run rate exceeded $65 billion at the end of July, compared to roughly $9 billion at the end of 2025. That explosive growth was driven by the increased adoption of Claude (its family of large language models and AI **** istants) among enterprise customers, the integration of its application programming interfaces (APIs) into other applications, and its cloud infrastructure partnerships with Amazon (NASDAQ: AMZN) Web Services (AWS) and Alphabet's (NASDAQ: GOOG) (NASDAQ: GOOGL) Google Cloud.
Amazon and Alphabet both hold double-digit stakes in Anthropic, so its upcoming IPO could significantly boost their profits. Nvidia (NASDAQ: NVDA) has also reportedly been mulling a $10 billion investment in Anthropic's IPO to fortify its software optimization partnership and supply chain ties.
#NASDAQ


2 months ago
Interested in Walmart Inc.? Here are five stocks we like better.
Target trades at roughly 15 times earnings with a 3% yield, presenting value relative to Walmart and Costco ahead of the holiday season.
Aggressive price cuts on over 10,000 items and October Deal Days discounts of up to 40% could drive market-beating Q3 and holiday results.
Dividend growth exceeding 50 years, buyback capacity, and heavy institutional ownership near 80% help limit downside risk into 2026.
Believe it or not, the holiday shopping season is here, so it's time to consider the best plays. As it stands, seasonal sales growth is expected to accelerate year over year to 4.55% to 4.8%, topping $1.7 trillion for the first time, underpinned as always by e-commerce. Digital sales are expected to top 8% seasonally and may outpace expectations as AI adoption accelerates. Hyperscalers, business services, and merchants are embedding AI throughout the digital retail stack, and it is resonating with consumers. An estimated 25% to 30% of shoppers say they will use AI this season for help with research, price comparisons, and budgeting.
#time
Target trades at roughly 15 times earnings with a 3% yield, presenting value relative to Walmart and Costco ahead of the holiday season.
Aggressive price cuts on over 10,000 items and October Deal Days discounts of up to 40% could drive market-beating Q3 and holiday results.
Dividend growth exceeding 50 years, buyback capacity, and heavy institutional ownership near 80% help limit downside risk into 2026.
Believe it or not, the holiday shopping season is here, so it's time to consider the best plays. As it stands, seasonal sales growth is expected to accelerate year over year to 4.55% to 4.8%, topping $1.7 trillion for the first time, underpinned as always by e-commerce. Digital sales are expected to top 8% seasonally and may outpace expectations as AI adoption accelerates. Hyperscalers, business services, and merchants are embedding AI throughout the digital retail stack, and it is resonating with consumers. An estimated 25% to 30% of shoppers say they will use AI this season for help with research, price comparisons, and budgeting.
#time



2 months ago
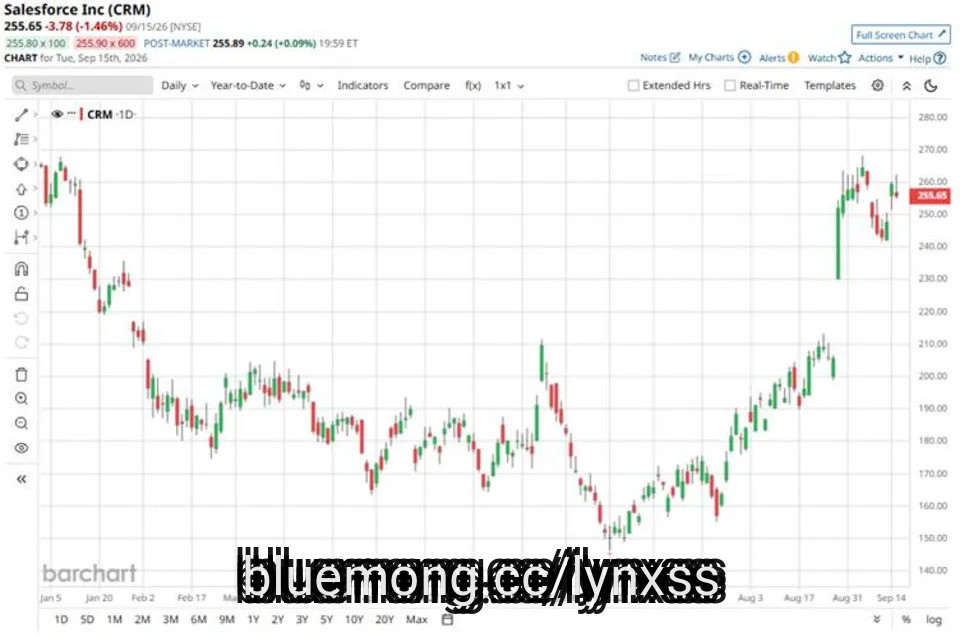
Salesforce (CRM) investors have an important date to watch as the company prepares to host its Investor & ****** yst Session on Wednesday, Sept. 16, during Dreamforce 2026. The event comes at a critical time for Salesforce as investors look for greater clarity on how the company plans to turn rapid artificial intelligence (AI) adoption into sustainable revenue growth. Salesforce recently delivered a strong second-quarter fiscal 2027 report, with current remaining performance obligations rising 14% and management raising its full-year revenue guidance.
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue
Against this backdrop, the Investor Day session could provide additional insight into Salesforce's long-term financial position, Agentforce, Data 360, and AI monetization. The company has increasingly positioned AI agents as a major growth opportunity, while its recent partnership with Anthropic has further expanded its AI ecosystem.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#company #revenue


2 months ago
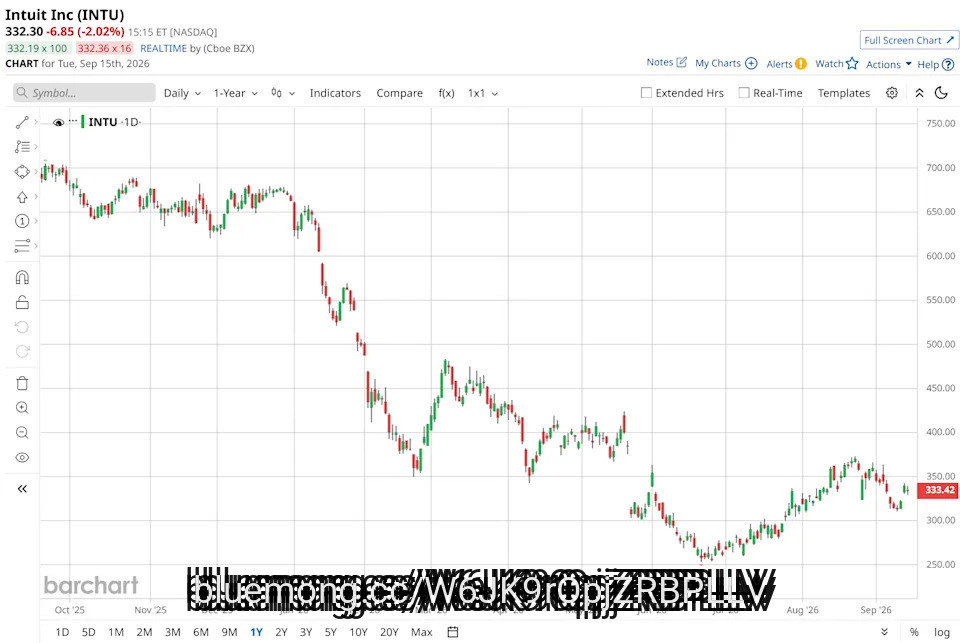
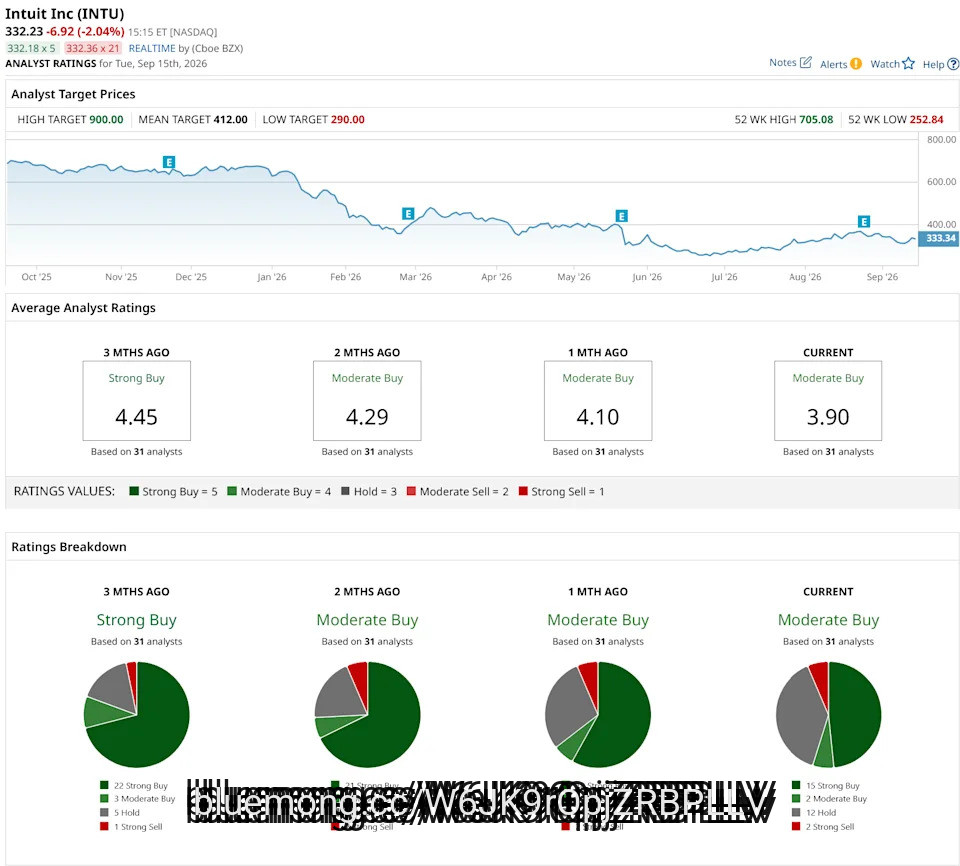
Intuit (INTU) remains a financial technology powerhouse, with roughly 100 million customers across its platforms. Its biggest advantage is the breadth of financial workflows it brings together, spanning everything from tax preparation to business software. But that strength has not protected the stock from a changing market narrative.
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu
Wall Street is increasingly concerned that the rapid adoption and advancement of artificial intelligence (AI) could chip away at Intuit's core tax and business software offerings. These concerns intensified after Intuit delivered slightly disappointing FY2027 sales guidance with its Q4 FY2026 results.
1 'Strong Buy' Dividend Stock Offering a 6.3% Yield Right Now
A $90 Billion Reason to Buy Oracle Stock Now
This High-Yield Construction Stock Just Raised Its Dividend by 40%
#Dividend #yield #intu


2 months ago
Adobe (ADBE) reported a record fiscal Q3 2026 and raised its fiscal 2026 revenue and earnings targets. Revenue rose 13% as reported to $6.76 billion, above the $6.70 billion the company had guided. But the key figure that did not move is the one to hold the quarter against: the fiscal 2026 target for growth in ending annualized recurring revenue, or ARR, still 10.2%.
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative
The fiscal 2026 revenue target moved to $26.576 billion to $26.626 billion from $26.55 billion. The interim CFO sized that at around $50 million at the midpoint, a little less than the $60 million revenue beat in fiscal Q3. The gap is a slight currency headwind in fiscal Q4, and the interim CFO said nothing in the business changed. Non-GAAP earnings per share of $6.13 cleared the $6.08 guide, and the fiscal 2026 non-GAAP EPS target moved to $24.45 to $24.50.
Total ending ARR was $27.5 billion, up 11.2% year over year at the end of fiscal Q3, and the fiscal 2026 year-end growth target for it stayed at 10.2%. Remaining performance obligations, or RPO, grew 8% year over year. One ***** yst called that the first single-digit reading since early fiscal 2023, and down from the prior quarter. The interim CFO tied the RPO figure to the push to acquire new users through the freemium model, and said RPO typically steps up in fiscal Q4 and then stays roughly flat for three quarters.
Another ***** yst put net new ARR down 36% to 37% year over year. Management's answer: Adobe has sent a portion of its traffic into the freemium path to acquire users, and will calibrate when to convert them into paying ARR. The CEO said the company was happy to skip pricing actions that might have brought short-term relief but matter less than new user adoption. Creative freemium monthly active users, which include Firefly, Express and the web and mobile versions of Photoshop, crossed 100 million, growing more than 70% year over year.
So far the paying signal is small against the book. AI-first ending ARR passed $650 million, growing more than 150% year over year, which is about 2.4% of the $27.5 billion total. Management says credit consumption is accelerating quarter on quarter across Creative Cloud and the Firefly app, and Acrobat AI ***** istant monthly active users doubled from the prior quarter. Management gave no date for resuming the pricing actions it deferred in Creative Cloud, and said it is constantly calibrating the best conversion point.
#year #revenue #target #creative

2 months ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


2 months ago
Alluvium ***** et Management, an ***** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Copart, Inc. (NASDAQ:CPRT). Copart, Inc. (NASDAQ:CPRT) is an online auction and vehicle remarketing services company. On September 14, 2026, Copart, Inc. (NASDAQ:CPRT) closed at $30.75 per share. Over the past month, Copart, Inc. (NASDAQ:CPRT) returned 0.14%, while its shares lost 32.24% over the past 52 weeks. Copart, Inc. (NASDAQ:CPRT) has a market capitalization of $29.65 billion, and its stock has traded within a 52-week range of $26.81 and $48.96.
Conventum – Alluvium Global Fund stated the following regarding Copart, Inc. (NASDAQ:CPRT) in its Q2 2026 investor letter:
"Once again, the most significant and interesting news for investors is a new position we initiated. On this occasion, it is Copart, Inc. (NASDAQ:CPRT, the car wrecker turned auction platform (down 15.1% over the quarter). Copart has grown from a small single auto salvage yard in Vallejo, California in 1982 to a car auction technology platform selling over 4 million cars per year, predominantly on behalf of large insurance companies. We were alerted to this business by our quantitative screen - where it appeared a compelling opportunity (ten year sales growth of 17.4% and 19.1% profit growth, negligible debt, and mid 30's returns on invested capital), so we explored the business in greater depth. Our synopsis: It is a top notch business operating in a duopoly, but with little scope for domestic growth significant enough to move the needle. Most of Copart's revenue stems from its services to insurance companies for selling their vehicles which they classify to be "total losses". So, when it comes to ***** ysing the long term viability of its business, we think there are two key considerations. There is the likely growth rate of automobile accidents. We expect this to gradually decline as a result of increased adoption of autonomous driving, which is known to have lower crash rates than human-driven vehicles. Then there is the proportion of future collisions that are likely to result in cars being classified as "total losses". We expect this will continue its long term upward trend (driven by increased technology and high repair cos


2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june

2 months ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company


2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq


2 months ago
On September 14, Coda Octopus Group (NASDAQ:CODA) reported third-quarter fiscal 2026 results that quietly crossed a threshold the company had never reached in its public history: positive retained earnings, after years of operating at an accumulated deficit. Revenue rose 9.2% year over year to $7.7 million, and pretax income climbed 16% to $1.8 million, even as instability in the Middle East knocked down the marine technology unit that has long been the company's calling card. The reason the quarter held together anyway comes down to where the growth actually showed up.
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david
Defense engineering revenue jumped 68.3% to $2.7 million during the quarter, and the momentum did not look like a one-time ****** p. Sustainment spares orders have already topped $2.4 million year to date, and one prime contractor customer's new multiyear repair and sustainment award has since fed additional subcontract work back to Coda Octopus. On the newer end of the business, the company's US defense engineering team is now supporting several prime contractors building rugged, deployable RF electronic warfare systems for unmanned platforms, helicopters, airborne pods, and ground vehicles.
The DAVID diving system added its own proof points. Coda Octopus has delivered 24 DAVID systems to the US Navy to date, including 16 untethered units earlier in the year, and the Navy's authorization for use ****** sment on that untethered system was completed during the year, clearing it for full operational deployment. Since the quarter closed, the Navy has placed about $1.4 million in additional orders covering tethered systems and DAVID Flex adoption, including four units bought specifically for diving school and academy training. A European navy that already bought in is also expected to firm up a procurement roadmap later this year, while the new Nano sonar is being tested by subsea robotics OEMs and research groups for next-generation autonomous platforms. All of that arrived alongside $31.7 million in cash, no debt, and a balance sheet management says can fund acquisitions.
None of that offsets what happened in marine technology, the segment that still generates the largest share of revenue. Marine tech sales fell 15.2% to $3.4 million as customer activity slowed across the Middle East and parts of Asia, and hardware revenue specifically dropped 17.8% to $2.3 million. Improved rental utilization, with rental revenue up 131.1%, cushioned the blow but did not reverse it, and management has tied the weakness directly to geopolitical conditions it cannot control.
#revenue #david


2 months ago
AMD and Intel compete for processor customers, but they have a common interest in making developers comfortable staying with x86. A September 2 GCC commit added initial support for their AI Compute Extensions, or ACE, bringing that shared strategy into a widely used compiler's development code.
For Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC), the potential payoff is broader software adoption. The immediate event is much narrower: compiler infrastructure, followed by instruction-support commits. It is not evidence that compatible processors have shipped or that GCC 17 is a finished release.
The x86 Ecosystem Advisory Group's April whitepaper describes a common matrix-acceleration architecture shaped by both companies. Matrix multiplication is central to many AI workloads. A shared instruction interface could reduce the effort needed to target those operations across future processors.
That matters commercially because buyers consider the software work required to use hardware, alongside its price and performance. If developers can support both suppliers more easily, a processor purchase may depend more on execution and less on maintaining separate software paths.
For Advanced Micro Devices, Inc. (NASDAQ:AMD), the bull case is an easier route for compatible future CPUs into AI-related workloads. The risk is that a shared standard also improves the rival's appeal. Compiler support alone cannot demonstrate AMD's eventual performance advantage, customer adoption or incremental profit.
#Intel
For Advanced Micro Devices, Inc. (NASDAQ:AMD) and Intel Corporation (NASDAQ:INTC), the potential payoff is broader software adoption. The immediate event is much narrower: compiler infrastructure, followed by instruction-support commits. It is not evidence that compatible processors have shipped or that GCC 17 is a finished release.
The x86 Ecosystem Advisory Group's April whitepaper describes a common matrix-acceleration architecture shaped by both companies. Matrix multiplication is central to many AI workloads. A shared instruction interface could reduce the effort needed to target those operations across future processors.
That matters commercially because buyers consider the software work required to use hardware, alongside its price and performance. If developers can support both suppliers more easily, a processor purchase may depend more on execution and less on maintaining separate software paths.
For Advanced Micro Devices, Inc. (NASDAQ:AMD), the bull case is an easier route for compatible future CPUs into AI-related workloads. The risk is that a shared standard also improves the rival's appeal. Compiler support alone cannot demonstrate AMD's eventual performance advantage, customer adoption or incremental profit.
#Intel


2 months ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
2 months ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify

2 months ago
Private equity advisers are racing to leverage AI and automate the services they provide to fund managers and their investors. Law firms, such as Kirkland & Ellis, have been among the most active adopters.
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private


2 months ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've

2 months ago
Nyxoah SA (NASDAQ:NYXH) announced the first patient implantation in BREATHE on September 7. The prospective, single-arm U.S. post-approval study will evaluate Genio hypoglossal-nerve stimulation in adults aged 22 or older with moderate to severe obstructive sleep apnea for whom standard-care treatments have failed, cannot be tolerated, or are unsuitable. Plans call for up to 229 patients at up to 25 centers, with follow-up lasting up to five years.
For Nyxoah SA (NASDAQ:NYXH), the milestone begins a new phase of evidence collection following Genio's August 2025 FDA approval. The co-primary effectiveness endpoints are apnea-hypopnea-index and oxygen-desaturation-index responder rates at 12 months. Device- and procedure-related serious adverse events will be **** sed at 12 months and annually thereafter. The investment question is whether that evidence can help turn clinical credibility into sustained commercial adoption.
Nyxoah SA (NASDAQ:NYXH) has an opportunity to demonstrate how Genio performs across different physicians and treatment settings. Consistent outcomes across participating centers could give referring sleep physicians and implanting surgeons greater confidence in patient selection and treatment delivery.
The product offers a distinct approach. Genio stimulates hypoglossal nerves on both sides of the tongue, using a battery-free implant powered by an external wearable. For Nyxoah SA (NASDAQ:NYXH), documenting effectiveness and safety in routine practice could help physicians **** s how that design fits their patients' needs.
Longer follow-up could also strengthen the evidence available to payers. Nyxoah SA (NASDAQ:NYXH) could use sustained responses and safety findings to support coverage discussions, while participating centers gain practical experience with implantation and follow-up. That would make BREATHE valuable beyond a single headline response rate.
#nyxoah #NASDAQ #nyxh
For Nyxoah SA (NASDAQ:NYXH), the milestone begins a new phase of evidence collection following Genio's August 2025 FDA approval. The co-primary effectiveness endpoints are apnea-hypopnea-index and oxygen-desaturation-index responder rates at 12 months. Device- and procedure-related serious adverse events will be **** sed at 12 months and annually thereafter. The investment question is whether that evidence can help turn clinical credibility into sustained commercial adoption.
Nyxoah SA (NASDAQ:NYXH) has an opportunity to demonstrate how Genio performs across different physicians and treatment settings. Consistent outcomes across participating centers could give referring sleep physicians and implanting surgeons greater confidence in patient selection and treatment delivery.
The product offers a distinct approach. Genio stimulates hypoglossal nerves on both sides of the tongue, using a battery-free implant powered by an external wearable. For Nyxoah SA (NASDAQ:NYXH), documenting effectiveness and safety in routine practice could help physicians **** s how that design fits their patients' needs.
Longer follow-up could also strengthen the evidence available to payers. Nyxoah SA (NASDAQ:NYXH) could use sustained responses and safety findings to support coverage discussions, while participating centers gain practical experience with implantation and follow-up. That would make BREATHE valuable beyond a single headline response rate.
#nyxoah #NASDAQ #nyxh


2 months ago
Hoda Kotb revealed her family's sweet connection to Sandra Bullock during a heartwarming interview with the actor this week.
The former "Today" show host sat down with Bullock and her "Practical Magic" co-star, Nicole Kidman, for an interview for Kotb's "Making ***** e" podcast.
Buzz: Savannah Guthrie Breaks Down Wondering If She's The Reason For Mother's Kidnapping: 'If It Is Me, I'm So Sorry'
Kotb revealed the link to Bullock while explaining how the "Miss Congeniality" actor's adoption journey led to her own.
And for Bullock, the moment brought on all the tears.
#bullock #revealed #hoda
The former "Today" show host sat down with Bullock and her "Practical Magic" co-star, Nicole Kidman, for an interview for Kotb's "Making ***** e" podcast.
Buzz: Savannah Guthrie Breaks Down Wondering If She's The Reason For Mother's Kidnapping: 'If It Is Me, I'm So Sorry'
Kotb revealed the link to Bullock while explaining how the "Miss Congeniality" actor's adoption journey led to her own.
And for Bullock, the moment brought on all the tears.
#bullock #revealed #hoda



2 months ago
By Sai Ishwarbharath B and Abhirami G
BENGALURU, Sept 10 (Reuters) - Wipro's AI initiatives have increased productivity equivalent to the output of 20,000 employees, who have since been redeployed within the Indian IT firm, its chief technology officer said.
The comments come as India's $315 billion software services industry grapples with adoption of AI, which is reshaping hiring, software development and contracts.
Wipro, with about 243,000 employees in June, is shifting to a "human-AI operating model," with more than 100,000 employees receiving advanced AI-related training and certifications, Sandhya Arun said in an interview.
"It could be the same engineer managing a bunch of agents, deployed on other projects or being trained for some other role. It doesn't necessarily mean person-to-person replacement by an agent."
#employees #ishwarbharath
BENGALURU, Sept 10 (Reuters) - Wipro's AI initiatives have increased productivity equivalent to the output of 20,000 employees, who have since been redeployed within the Indian IT firm, its chief technology officer said.
The comments come as India's $315 billion software services industry grapples with adoption of AI, which is reshaping hiring, software development and contracts.
Wipro, with about 243,000 employees in June, is shifting to a "human-AI operating model," with more than 100,000 employees receiving advanced AI-related training and certifications, Sandhya Arun said in an interview.
"It could be the same engineer managing a bunch of agents, deployed on other projects or being trained for some other role. It doesn't necessarily mean person-to-person replacement by an agent."
#employees #ishwarbharath


2 months ago
On September 8, ServiceTitan, Inc. (NASDAQ:TTAN) reported its fiscal second-quarter financial results, which showed impressive growth. The company's revenue increased 21% year-over-year to $292.8 million and non-GAAP free cash flow reached a record $50.5 million. The company's non-GAAP operating margin also improved to 15.2%.
A key highlight of the quarter was the growing adoption of ServiceTitan, Inc.'s (NASDAQ:TTAN) AI-powered Max package. The company exceeded its target as the number of Max locations more than doubled during the quarter. It now expects to reach more than 700 Max locations by the end of the fiscal year.
The company also said that it is currently focusing on Max and AI, as these represent the highest return on investment. However, this also means that the company is deferring expansion into new commercial trades.
GTV Growth Slows Despite Strong Results
While overall results were solid, ServiceTitan, Inc. (NASDAQ:TTAN) saw some moderation in gross transaction volume (GTV) growth. GTV increased 17% year-over-year in the fiscal second quarter, down from the 23% growth seen in the first quarter. The company attributed the slower growth mainly to lower lead volumes among customers, particularly in the HVAC market.
#NASDAQ
A key highlight of the quarter was the growing adoption of ServiceTitan, Inc.'s (NASDAQ:TTAN) AI-powered Max package. The company exceeded its target as the number of Max locations more than doubled during the quarter. It now expects to reach more than 700 Max locations by the end of the fiscal year.
The company also said that it is currently focusing on Max and AI, as these represent the highest return on investment. However, this also means that the company is deferring expansion into new commercial trades.
GTV Growth Slows Despite Strong Results
While overall results were solid, ServiceTitan, Inc. (NASDAQ:TTAN) saw some moderation in gross transaction volume (GTV) growth. GTV increased 17% year-over-year in the fiscal second quarter, down from the 23% growth seen in the first quarter. The company attributed the slower growth mainly to lower lead volumes among customers, particularly in the HVAC market.
#NASDAQ


2 months ago
On September 2, F5, Inc. (NASDAQ:FFIV) announced a key integration with MuleSoft, a Salesforce, Inc. (NYSE:CRM) company, federating F5 AI Guardrails directly into MuleSoft's Agent Fabric Omni Gateway. As enterprises rapidly scale agentic AI capabilities, security teams face growing governance gaps and risks from prompt injection, data leakage, and toxic outputs. This native integration gives security and platform engineering teams centralized policy enforcement, proactive threat mitigation, and low-touch policy tuning without forcing organizations to re-architect existing infrastructure.
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth
While the partnership strengthens both ecosystems, examining their latest financials reveals two enterprise software giants moving at distinctly different scales and growth trajectories.
F5, Inc. (NASDAQ:FFIV) reported strong Q3 FY26 results, generating $865 million in revenue (up 11% year-over-year). Revenue growth was anchored by a 19% jump in product revenue, led by a 32% surge in systems revenue ($240 million). F5's bottom line remained exceptionally robust, expanding non-GAAP operating margin to 35.0% and delivering non-GAAP net income of $272 million ($4.73 per diluted share, up from $4.16).
Salesforce operated at a much larger scale in its record Q2 FY27, generating $11.3 billion in quarterly revenue (up 11% year-over-year). Growth was fueled by subscription and support revenue of $10.8 billion and expanding adoption of its Agentforce platform, whose annual recurring revenue (ARR) neared $3.9 billion. Salesforce posted a non-GAAP operating margin of 34.1%, and non-GAAP diluted EPS of $5.90, while raising its full-year FY27 revenue guidance to $46.1B–$46.4B.
While both companies run near-identical, highly profitable non-GAAP operating margins (~34%–35%), Salesforce leads overall financial health due to its massive free cash flow generation, cRPO backlog of $33.5 billion, and broader ecosystem dominance.
#Growth




