

24 hours ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached

2 days ago
As the artificial intelligence revolution shifts from experimentation to industrial scale, choosing between Cerebras Systems (NASDAQ:CBRS) and CoreWeave (NASDAQ:CRWV) presents a unique choice for investors seeking infrastructure growth in 2026.
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer
Cerebras builds massive chips designed to accelerate intensive workloads, while CoreWeave offers specialized cloud services for those same tasks. Both companies have seen rapid growth as businesses scramble for computing power, making them key names to watch among semiconductor stocks and infrastructure providers.
Cerebras Systems focuses on a single, bold hardware proposition: the Wafer-Scale Engine. This processor is the size of an entire silicon wafer, designed to train complex models much faster than traditional clusters. The company serves enterprise, government, and high-performance computing customers across North America, Europe, and the Middle East. While its latest annual report does not disclose specific major customers, its global reach continues to expand as it targets large-scale research and national security projects.
Financial performance has trended upward significantly in recent years. In its 2025 fiscal year (FY), revenue reached $510.0 million, representing growth of 75.7% compared to the prior year. The company also achieved profitability during this period, reporting net income of $237.8 million. This results in a net margin of 46.6%, which measures the percentage of revenue that remains as profit after all expenses are paid.
As of its December 2025 balance sheet, the company maintains a current ratio of 2.1x, indicating its ability to cover short-term obligations with short-term ***** ets while the debt-to-equity ratio is -0.5x. During FY 2025, free cash flow was negative at $392.8 million. Free cash flow is the cash a business generates after paying for its operations and capital expenditures to maintain the business.
#cerebras #million #cash #wafer

2 days ago
On September 9, American Eagle Outfitters Inc. (NYSE:AEO) revealed results for its fiscal 2026 second quarter. The company achieved an 8% year-over-year topline growth with net revenue figures of $1.38 billion. The second quarter operating profit jumped up to $211 million compared to $103 million during the same period last year. As a result, diluted earnings per share for the quarter stood at $0.79 in comparison with $0.45 for Q2 FY25. This led to a $21 million distribution to shareholders with a dividend payout of $0.125 per share.
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable
Africa Studio/Shutterstock.com
A resilient performance during the second quarter was primarily driven by robust momentum within the Aerie sub-brand and OFFLINE collection. There was a 6% year-over-year growth in company-wide comparable sales, whereas the Aerie's comparable sales picked up by 19%. Total gross profit for the quarter reached $672 million, which shows a 34% increase against $500 million for Q2 FY25. This pushed Q2 gross margins to 48.7%, a jump of 980 basis points relative to the previous year's quarter, despite 330 basis points deleveraging across the merchandise margins. Compared to an 8% operating margin in Q2 FY25, the company posted 15.3% margin in the recent period.
Even with a slight dip in comparable sales, the American Eagle brand also exhibited some encouraging signs. It posted sequential gains from the previous quarter, which marks the fourth consecutive quarter of expansion across menswear.
Results for the reported period were bolstered by $196 million in International Emergency Economic Powers Act (IEEPA) tariff refunds, which also included interest payments. This resulted in an additional $35 million in incentive compensation set aside by the company, which affected both gross profit and SG&A. After taking these additional expenses into consideration, the overall operating income gains related to tariff refunds amounted to $161 million.
#comparable


2 days ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset


2 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
2 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#nepa #operations
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#nepa #operations

2 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june

2 days ago
Auxier ***** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong

2 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ***** ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ***** ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#cultural #company #lilly
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ***** ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ***** ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#cultural #company #lilly

2 days ago
Ocean Power Technologies Inc (NYSE-A:OPTT) reported first-quarter fiscal 2027 revenue of $1.7 million, up 44% from a year earlier, as the company expanded its work with US defense and security customers and moved forward with a strategic review process.
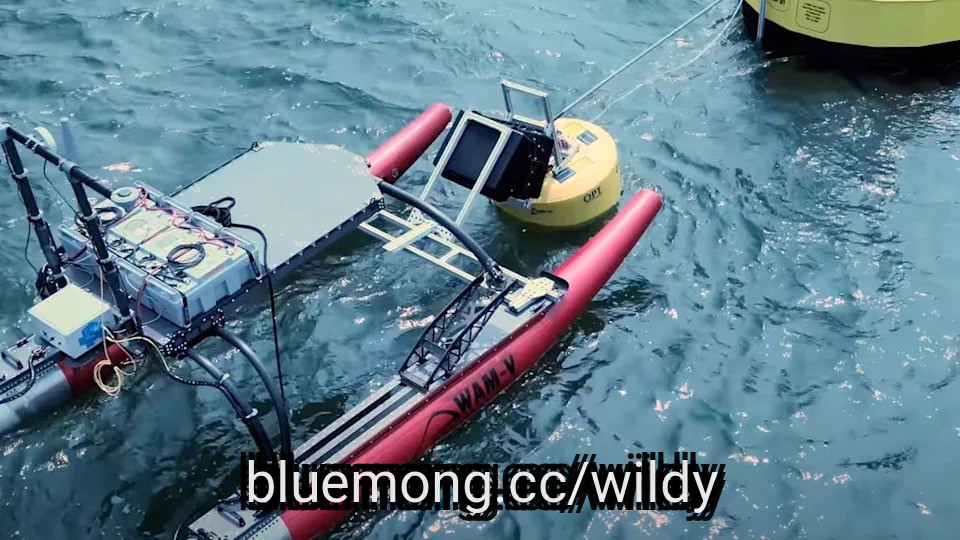
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy
Ocean Power Technologies ran three PowerBuoy systems off Southern California for a U.S. Department of Homeland Security maritime domain awareness program, integrated with Anduril's Lattice platform and including a deployment beyond 1,000 meters depth, calling it the company's largest deployment and recurring revenue contract to date.
Ocean Power Technologies also deployed a PowerBuoy system off New Jersey for Rutgers University and delivered a WAM-V unmanned surface vehicle to Stevens Institute of Technology within five weeks of receiving the order.
The company demonstrated autonomous docking, charging and redeployment of a WAM-V, a capability it is working to integrate with the PowerBuoy platform to support longer autonomous missions. It also acquired subsea developmental technology ****** ets from Columbia Power Technologies, extending its capabilities from the ocean surface to the seabed.
Ocean Power Technologies achieved Cybersecurity Maturity Model Certification Level 2 compliance, positioning it to pursue defense programs requiring protection of controlled unclassified information. After the quarter ended, the company was selected as one of six potential awardees under a $40 million multiple-award contract supporting the Naval Oceanographic Office, creating an opportunity to compete for ocean-floor mapping task orders using unmanned surface vehicles.
#ocean #power #technologies #powerbuoy
2 days ago
Anthropic is moving forward with plans for an initial public offering that could value the company at $2 trillion, with signs pointing to the listing remaining on track, according to Bloomberg. Nasdaq has been selected as the venue for the listing, and Nvidia is reportedly weighing a contribution of around $10 billion to the offering.
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according


2 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#cash
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#cash

2 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq


3 days ago
The energy landscape is evolving rapidly, and one company looking to disrupt the status quo and redefine the future of nuclear power is NuScale Power (NYSE: SMR). NuScale is the only small modular reactor (SMR) developer to receive a Standard Design Approval from the Nuclear Regulatory Commission.
On Sept. 1, NuScale achieved a major engineering breakthrough. In collaboration with MilleniTEK, it successfully fabricated specialized boron-oxide pellets, a critical component of NuScale's cutting-edge passive emergency cooling system.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This engineering triumph is a major step toward making safe, meltdown-proof modular nuclear power a reality. It also helps NuScale move closer to commercial deployment. But does this make NuScale Power stock a buy? Let's dive into the details and what it means for the stock.
In traditional nuclear reactors, reactivity control during nonstandard events often relies on active mechanical insertion of control rods or on powered chemical injection pumps. NuScale's 77 MWe Small Modular Reactor (SMR) design relies on passive safety mechanisms.
#power
On Sept. 1, NuScale achieved a major engineering breakthrough. In collaboration with MilleniTEK, it successfully fabricated specialized boron-oxide pellets, a critical component of NuScale's cutting-edge passive emergency cooling system.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
This engineering triumph is a major step toward making safe, meltdown-proof modular nuclear power a reality. It also helps NuScale move closer to commercial deployment. But does this make NuScale Power stock a buy? Let's dive into the details and what it means for the stock.
In traditional nuclear reactors, reactivity control during nonstandard events often relies on active mechanical insertion of control rods or on powered chemical injection pumps. NuScale's 77 MWe Small Modular Reactor (SMR) design relies on passive safety mechanisms.
#power

4 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product
Achieved record quarterly revenue of $24 million, validating the long-term strategy of transitioning toward higher-value integrated systems and custom cabling solutions.
Realized significant operating leverage as revenue surpassed the $20 million threshold, driving adjusted EBITDA margins to 11.1%, exceeding the company's 10% long-term goal.
Diversification efforts successfully reduced reliance on traditional telecom, with meaningful contributions from aerospace, defense, industrial manufacturing, and medical imaging.
Unified engineering and product management teams into a single structure to accelerate product launches and ensure technical innovation translates directly to revenue impact.
#long #product

4 days ago
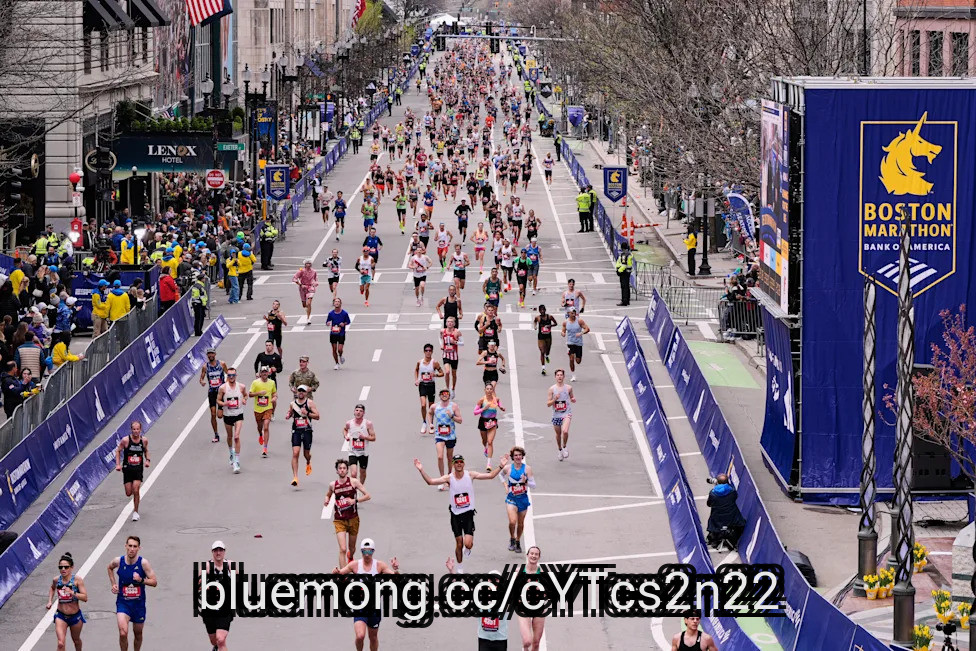
Qualifier registration is now open for the 2027 Boston Marathon.
Athletes can submit a registration application until Friday, September 18, at 5 p.m.
The 131st Boston Marathon will be held on Monday, April 19.
The B.A.A. will use the same registration process for qualified runners as it used for the 2021 through 2026 races, allowing any athlete who has achieved a currently valid Boston Marathon qualifying time to submit a registration application.
This year, the B.A.A. will add a Boston Qualifier Selection, an additional random selection component for applicants whose qualifying time was not faster than the cut-off. Approximately 1,000 qualifiers will be randomly selected for entry.
#registration #application #time
Athletes can submit a registration application until Friday, September 18, at 5 p.m.
The 131st Boston Marathon will be held on Monday, April 19.
The B.A.A. will use the same registration process for qualified runners as it used for the 2021 through 2026 races, allowing any athlete who has achieved a currently valid Boston Marathon qualifying time to submit a registration application.
This year, the B.A.A. will add a Boston Qualifier Selection, an additional random selection component for applicants whose qualifying time was not faster than the cut-off. Approximately 1,000 qualifiers will be randomly selected for entry.
#registration #application #time

7 days ago
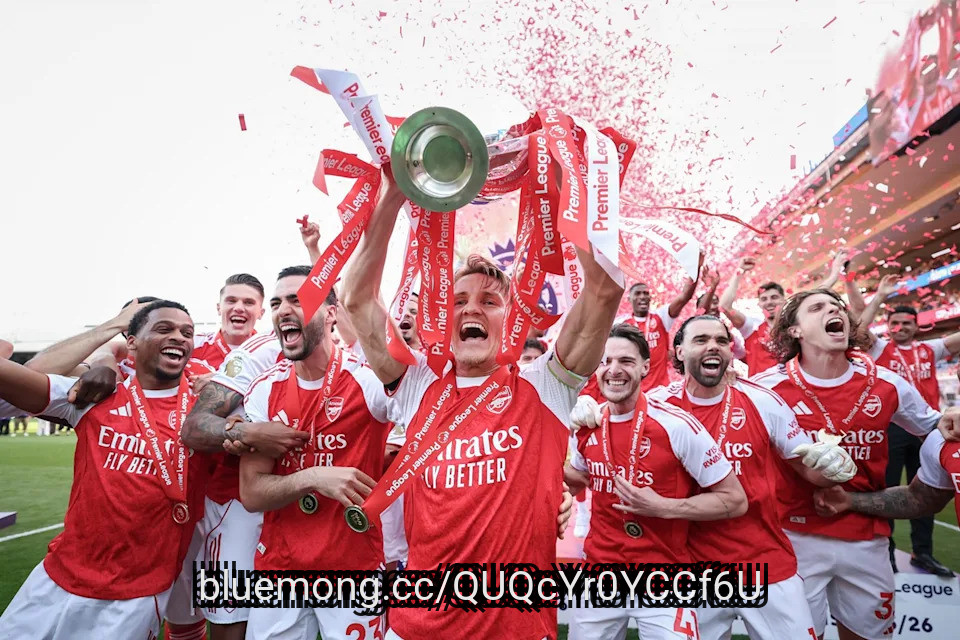
Arsenal may have just won the Premier League and reached the final of the Champions League, which means the club has been making significant amounts of money in recent campaigns.
However, the Gunners are also keen to ensure that they have their house in order financially, and the club has reportedly employed BCG to audit its finances in a bid to cut out waste.
Arsenal are one of the clubs that laid off staff during the COVID pandemic, and they also sacked their scouts and reorganised that part of the club despite the many successes it had achieved previously.
They came under significant criticism for that decision, and the Gunners will continue to do what they can to ensure the team remains the main focus of their operations.
The Daily Mail reports that BCG managing director Jean Paul Petranca is leading the review, and it has caused staff to become annoyed and shocked.
#club #arsenal #significant #staff
However, the Gunners are also keen to ensure that they have their house in order financially, and the club has reportedly employed BCG to audit its finances in a bid to cut out waste.
Arsenal are one of the clubs that laid off staff during the COVID pandemic, and they also sacked their scouts and reorganised that part of the club despite the many successes it had achieved previously.
They came under significant criticism for that decision, and the Gunners will continue to do what they can to ensure the team remains the main focus of their operations.
The Daily Mail reports that BCG managing director Jean Paul Petranca is leading the review, and it has caused staff to become annoyed and shocked.
#club #arsenal #significant #staff


7 days ago
LeBron James has faced criticism throughout his basketball career. On Friday, former NBA lottery pick Olden Polynice took aim at LBJ for falling short of a certain statistical feat.
Appearing on SiriusXM NBA Radio, Polynice (who was drafted eighth overall by the Chicago Bulls in 1987) gave James his props but proceeded to chastise the 22-time NBA All-Star.
"I love LeBron. I really do. I think he's one of the greatest ever… But, at the same time, I can still be critical of him on some things. One in particular: I thought LeBron should have averaged a triple-double way before Russell Westbrook. That's my personal opinion."
Polynice, who transitioned to coaching after playing 15 seasons in the NBA, went on to make an explosive claim about LBJ's career.
"Believe it or not, this is going to be the weirdest thing ever uttered. I believe LeBron James underachieved."
#believe
Appearing on SiriusXM NBA Radio, Polynice (who was drafted eighth overall by the Chicago Bulls in 1987) gave James his props but proceeded to chastise the 22-time NBA All-Star.
"I love LeBron. I really do. I think he's one of the greatest ever… But, at the same time, I can still be critical of him on some things. One in particular: I thought LeBron should have averaged a triple-double way before Russell Westbrook. That's my personal opinion."
Polynice, who transitioned to coaching after playing 15 seasons in the NBA, went on to make an explosive claim about LBJ's career.
"Believe it or not, this is going to be the weirdest thing ever uttered. I believe LeBron James underachieved."
#believe

7 days ago
Breakout loading. At least that's what the Dallas Cowboys hope after they inked tight end Brevyn Spann-Ford and receiver Ryan Flournoy to a pair of extensions this week. In a break from the norm, the Cowboys went out on a limb and played the speculation market. Channeling his inner oilman, owner Jerry Jones has put his money where his mouth is and bet big on breakouts.
In previous years, it was the Cowboys waiting until after a breakout was achieved before extensions were offered. Terence Steele was signed to a five-year, $82,500,000 deal after his breakout season in 2022. Jaylon Smith was regrettably signed to a five-year, $63,750,000 extension after his breakout season in 2018. And even Dak Prescott, Trevon Diggs and DaRon Bland got signed after already establishing themselves high among the NFL hierarchy.
It doesn't take Wallstreet stockbroker to know investing after something has already blown up has its drawbacks. Sure, seeing success insulates from risk, but it also means investors are buying high. Good deals are made through speculation. They come with risk since they're predictive rather than proven, but they also come at a much lower price and with a much higher upside.
After displaying significant growth in 2025, Flournoy has been a media and fan favorite to breakout in a big way this season. Signing a one-year, $6M extension, Flournoy retains his Cowboydom through the 2027 season. This is important because if George Pickens leaves after the current season, Flournoy ensures a level of continuity amongst the top receiver ranks.
Sources: The #cowboys and WR Ryan Flournoy have agreed to a 1-year contract extension worth up to $6M.
Flournoy is coming off a career year with 40 catches for 475 and 4 TDs. He’s expected to have an even bigger role in the offense this season as the solidified WR3 and now gets… pic.twitter.com/p04Q0S80A9
#extension
In previous years, it was the Cowboys waiting until after a breakout was achieved before extensions were offered. Terence Steele was signed to a five-year, $82,500,000 deal after his breakout season in 2022. Jaylon Smith was regrettably signed to a five-year, $63,750,000 extension after his breakout season in 2018. And even Dak Prescott, Trevon Diggs and DaRon Bland got signed after already establishing themselves high among the NFL hierarchy.
It doesn't take Wallstreet stockbroker to know investing after something has already blown up has its drawbacks. Sure, seeing success insulates from risk, but it also means investors are buying high. Good deals are made through speculation. They come with risk since they're predictive rather than proven, but they also come at a much lower price and with a much higher upside.
After displaying significant growth in 2025, Flournoy has been a media and fan favorite to breakout in a big way this season. Signing a one-year, $6M extension, Flournoy retains his Cowboydom through the 2027 season. This is important because if George Pickens leaves after the current season, Flournoy ensures a level of continuity amongst the top receiver ranks.
Sources: The #cowboys and WR Ryan Flournoy have agreed to a 1-year contract extension worth up to $6M.
Flournoy is coming off a career year with 40 catches for 475 and 4 TDs. He’s expected to have an even bigger role in the offense this season as the solidified WR3 and now gets… pic.twitter.com/p04Q0S80A9
#extension

7 days ago
Brock Purdy continues to prove doubters by exceeding his career expectations. And following the San Francisco 49ers' 2026 opener against the Los Angeles Rams in Australia on Thursday, he obtained another record to his collection.
Despite a slow start, Purdy had a great performance leading the offense. He completed 25 out of 34 passes for 205 yards and three touchdowns and one interception.
Purdy completed the 50th game of his career, including his 46th start. His passing accuracy has been remarkable, getting 68.1% of his throws to fellow receivers. This paved the way for him to make NFL history, via Real App.
When healthy, Purdy shines as one of the best quarterbacks in the league. He was the final pick in the 2022 draft, adding more lore to his resume as a player that defied expectations and achieved remarkable success in the NFL.
Aug 20, 2026; Inglewood, California, USA; San Francisco 49ers quarterback Brock Purdy (13) throws the ball against the Los Angeles Chargers in the first half at SoFi Stadium. Mandatory Credit: Kirby Lee-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#francisco #reuters
Despite a slow start, Purdy had a great performance leading the offense. He completed 25 out of 34 passes for 205 yards and three touchdowns and one interception.
Purdy completed the 50th game of his career, including his 46th start. His passing accuracy has been remarkable, getting 68.1% of his throws to fellow receivers. This paved the way for him to make NFL history, via Real App.
When healthy, Purdy shines as one of the best quarterbacks in the league. He was the final pick in the 2022 draft, adding more lore to his resume as a player that defied expectations and achieved remarkable success in the NFL.
Aug 20, 2026; Inglewood, California, USA; San Francisco 49ers quarterback Brock Purdy (13) throws the ball against the Los Angeles Chargers in the first half at SoFi Stadium. Mandatory Credit: Kirby Lee-Imagn Images Credit: IMAGN IMAGES via Reuters Connect (Reuters)
#francisco #reuters

8 days ago
BVB has never lost a competitive match against SC Paderborn: There have been two DFB-Pokal clashes, both of which saw the Black and Yellows advance to the next round. In the Bundesliga, Borussia has won two matches so far, with two others ending in draws. The most memorable encounter to date was the last Bundesliga match between the two sides at the end of May 2020. In that COVID-19-related match played behind closed doors in Paderborn, the Black and Yellows had a weak first half but stepped up their game after the break. All seven goals in the 6-1 victory came in the second half. Jadon Sancho (3), Thorgan Hazard, Achraf Hakimi, and Marcel Schmelzer—scoring his final professional goal—found the back of the net for BVB.
Best Start in Four Years With six points from two games, BVB has made its strongest start to the season in four years.
Sharp-shooting forwardSerhou Guirassy got on the scoresheet in Sinsheim with the goal that made it 1–2. The forward has been involved in three of BVB's five Bundesliga goals this season and has scored in four consecutive matches across both seasons.
Paderborn, a newly promoted team struggling to find its footing, arrives at SIGNAL IDUNA PARK with one point and still no goals scored. That said, the East Westphalians have already registered 23 shots on goal.
Milestone Within ReachBVB has achieved three wins to start the Bundesliga season only four times in its history (most recently in 2015–16). Now this milestone is once again within reach for the Black and Yellows.
#yellows #match #goals #goal
Best Start in Four Years With six points from two games, BVB has made its strongest start to the season in four years.
Sharp-shooting forwardSerhou Guirassy got on the scoresheet in Sinsheim with the goal that made it 1–2. The forward has been involved in three of BVB's five Bundesliga goals this season and has scored in four consecutive matches across both seasons.
Paderborn, a newly promoted team struggling to find its footing, arrives at SIGNAL IDUNA PARK with one point and still no goals scored. That said, the East Westphalians have already registered 23 shots on goal.
Milestone Within ReachBVB has achieved three wins to start the Bundesliga season only four times in its history (most recently in 2015–16). Now this milestone is once again within reach for the Black and Yellows.
#yellows #match #goals #goal

8 days ago
Two cybersecurity heavyweights, Rubrik, Inc. (NYSE:RBRK) and CrowdStrike Holdings, Inc. (NASDAQ:CRWD), both released Q2 FY2027 earnings in late August/early September while deepening their strategic alliance. On September 1, the companies announced a joint agentic identity resilience workflow orchestrated by CrowdStrike's Charlotte Agentic SOAR. By uniting CrowdStrike's Falcon Next-Gen Identity Security with Rubrik's Identity Resilience, joint customers can now detect, investigate, and recover from compromised identity environments in hours instead of days.
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow



8 days ago
On August 27, AstraZeneca PLC (NYSE:AZN) and Amgen Inc. (NASDAQ:AMGN) scored a shared clinical victory. Positive high-level results from the Phase III CROSSING trial showed that their co-developed severe asthma drug, TEZSPIRE, achieved statistically significant and clinically meaningful improvements across both co-primary endpoints, histologic remission and the frequency/severity of dysphagia, and all key secondary endpoints at week 24 in patients with eosinophilic esophagitis. These benefits were sustained through week 52 across both tested doses, accompanied by a safety profile consistent with its approved indications. While CROSSING highlights their joint R&D success, a closer look at their standalone financial performance reveals distinct growth trajectories.
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
8 days ago
On September 3, AbbVie Inc. (NYSE:ABBV) finalized its acquisition of clinical-stage biotech Apogee Therapeutics, Inc. (NASDAQ:APGE) for $135.11 per share in cash. The $10.9 billion buyouts immediately fold Apogee's promising inflammatory and immunology (I&I) pipeline into AbbVie's commercial engine. On the exact same day, AbbVie separately reported positive Phase 3 Cervino trial results for its bispecific T-cell engager, etentamig, in relapsed/refractory multiple myeloma. Together, the dual catalysts emphasize how mega-cap pharmaceutical giants are deploying cash flow from legacy franchises to lock in next-generation immunology and oncology ***** ets.
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth

8 days ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved a sixth consecutive quarter of top-line growth, driven by broad-based strength across all regions and industry groups despite macroeconomic headwinds.
Completed the acquisition of AMS to create a global leader in talent and organizational consulting, significantly expanding capabilities in contingent workforce solutions and early career recruiting.
Transitioned to a new geographic reporting structure (Americas, EMEA, APAC) to better align with 'We Are Korn Ferry' go-to-market initiatives and holistic client engagement.
Leveraged proprietary data and IP—including 113 million executive ******* sments—to differentiate services in an AI-saturated market where resume quality has become commoditized.
#market #NVIDIA #tell #americas
Achieved a sixth consecutive quarter of top-line growth, driven by broad-based strength across all regions and industry groups despite macroeconomic headwinds.
Completed the acquisition of AMS to create a global leader in talent and organizational consulting, significantly expanding capabilities in contingent workforce solutions and early career recruiting.
Transitioned to a new geographic reporting structure (Americas, EMEA, APAC) to better align with 'We Are Korn Ferry' go-to-market initiatives and holistic client engagement.
Leveraged proprietary data and IP—including 113 million executive ******* sments—to differentiate services in an AI-saturated market where resume quality has become commoditized.
#market #NVIDIA #tell #americas

8 days ago
Spanish World Cup-winner Juan Mata on Friday opted against playing another season with Australian side Melbourne Victory, but stopped short of calling time on his career.
The former Manchester United and Chelsea ace has enjoyed a late-career resurgence and was voted the domestic A-League player of the year in 2025-26.
But the 38-year-old has decided not to play on at the club as he mulls "the next steps in his career".
He will remain involved with the Australian side after taking an ownership stake.
"I loved every minute and so greatly enjoyed everything that we achieved last season, falling back in love with football at such a special place, in an amazing city that it was a privilege to call home," Mata said.
#season
The former Manchester United and Chelsea ace has enjoyed a late-career resurgence and was voted the domestic A-League player of the year in 2025-26.
But the 38-year-old has decided not to play on at the club as he mulls "the next steps in his career".
He will remain involved with the Australian side after taking an ownership stake.
"I loved every minute and so greatly enjoyed everything that we achieved last season, falling back in love with football at such a special place, in an amazing city that it was a privilege to call home," Mata said.
#season


8 days ago
On September 3, VersaBank (NASDAQ:VBNK) reported its results for the third quarter ended July 31, 2026.
The quarter marked another period of record credit **** ets, revenue, and net interest income. Strong growth was supported by continued momentum in the company's Structured Receivable Program (SRP) in the United States and steady growth in Canada.
Fiscal 2026 is proving to be a breakout year for the company in terms of top-line growth and the company expects the momentum to accelerate further in fiscal 2027 based on continued expansion of its US SRP business and the launch of its Real-Time SRP, which the company describes as a breakthrough in point-of-sale industry funding.
After the quarter ended, VersaBank (NASDAQ:VBNK) also achieved a very noteworthy milestone as it surpassed $7 billion in total **** ets for the first time. The company's business continues to expand and it said it is increasingly realizing the operating leverage of its cloud-based, branchless, business-to-business model. Net income rose 53% year-over-year, while adjusted (core) net income increased 27%.
A key part of the bullish case for VersaBank (NASDAQ:VBNK) is the continued expansion of its SRP portfolio in the US. The company set a fiscal 2027 target of at least $3 billion in new SRP fundings on its own balance sheet and also pointed to significant additional upside potential.
#versabank #business #fiscal
The quarter marked another period of record credit **** ets, revenue, and net interest income. Strong growth was supported by continued momentum in the company's Structured Receivable Program (SRP) in the United States and steady growth in Canada.
Fiscal 2026 is proving to be a breakout year for the company in terms of top-line growth and the company expects the momentum to accelerate further in fiscal 2027 based on continued expansion of its US SRP business and the launch of its Real-Time SRP, which the company describes as a breakthrough in point-of-sale industry funding.
After the quarter ended, VersaBank (NASDAQ:VBNK) also achieved a very noteworthy milestone as it surpassed $7 billion in total **** ets for the first time. The company's business continues to expand and it said it is increasingly realizing the operating leverage of its cloud-based, branchless, business-to-business model. Net income rose 53% year-over-year, while adjusted (core) net income increased 27%.
A key part of the bullish case for VersaBank (NASDAQ:VBNK) is the continued expansion of its SRP portfolio in the US. The company set a fiscal 2027 target of at least $3 billion in new SRP fundings on its own balance sheet and also pointed to significant additional upside potential.
#versabank #business #fiscal


8 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance improvement was driven by a meaningful recovery in the full-price business across both physical stores and direct channels, signaling successful product resonance.
Management is consolidating the 'Wearever' sub-brand into the core ***** ortment to simplify the portfolio and reallocate resources toward high-growth categories like Luxe Lounge and denim.
The denim relaunch serves as a strategic proof point for modernizing the brand, successfully introducing fashion-forward silhouettes like wide-leg and barrel shapes to a loyal customer base.
Customer file stabilization is being achieved through a dual focus on accelerating new-to-brand acquisition and successfully reactivating lapsed customers.
#like #denim #wearever
Performance improvement was driven by a meaningful recovery in the full-price business across both physical stores and direct channels, signaling successful product resonance.
Management is consolidating the 'Wearever' sub-brand into the core ***** ortment to simplify the portfolio and reallocate resources toward high-growth categories like Luxe Lounge and denim.
The denim relaunch serves as a strategic proof point for modernizing the brand, successfully introducing fashion-forward silhouettes like wide-leg and barrel shapes to a loyal customer base.
Customer file stabilization is being achieved through a dual focus on accelerating new-to-brand acquisition and successfully reactivating lapsed customers.
#like #denim #wearever

8 days ago
The $60 target depends on XRP closing a month above $3.66, a level it has never achieved on a monthly closing basis.
XRP came closest in July 2025, when it reached a cycle high and monthly high of $3.65 but closed the month at $3.02. Every month since has recorded a lower high.
XRP trades at $1.42, meaning it would need to gain more than 40 times to reach $60, while reclaiming $3.66 alone would require a 158% rally.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
XRP (CRYPTO: XRP) trades around $1.42 today, up 39% over the past 30 days but still down 22% since January 1 and 52% over the past 12 months.
#month #since #past
XRP came closest in July 2025, when it reached a cycle high and monthly high of $3.65 but closed the month at $3.02. Every month since has recorded a lower high.
XRP trades at $1.42, meaning it would need to gain more than 40 times to reach $60, while reclaiming $3.66 alone would require a 158% rally.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
XRP (CRYPTO: XRP) trades around $1.42 today, up 39% over the past 30 days but still down 22% since January 1 and 52% over the past 12 months.
#month #since #past


8 days ago
Dolly Parton's younger sister, Stella Parton, 77, says that she knew what the country singer—famous for her high-glam, Southern belle aesthetic—looked like without makeup.
"She looked like me without makeup," Stella joked during an interview with Gayle King on CBS Mornings.
The quotes come just over two weeks after Dolly's death at age 80 following a "brief battle with cancer."
When it came to fashion and beauty, Dolly Parton affirmed that more is more.
Throughout her seven-decade music career, the country singer achieved beauty icon status with her sky-high platinum-blonde hair and high-glam makeup. As such, Dolly would rarely be caught without makeup on—even in front of those closest to her.
#stella #parton
"She looked like me without makeup," Stella joked during an interview with Gayle King on CBS Mornings.
The quotes come just over two weeks after Dolly's death at age 80 following a "brief battle with cancer."
When it came to fashion and beauty, Dolly Parton affirmed that more is more.
Throughout her seven-decade music career, the country singer achieved beauty icon status with her sky-high platinum-blonde hair and high-glam makeup. As such, Dolly would rarely be caught without makeup on—even in front of those closest to her.
#stella #parton
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go




