1 day ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

2 days ago
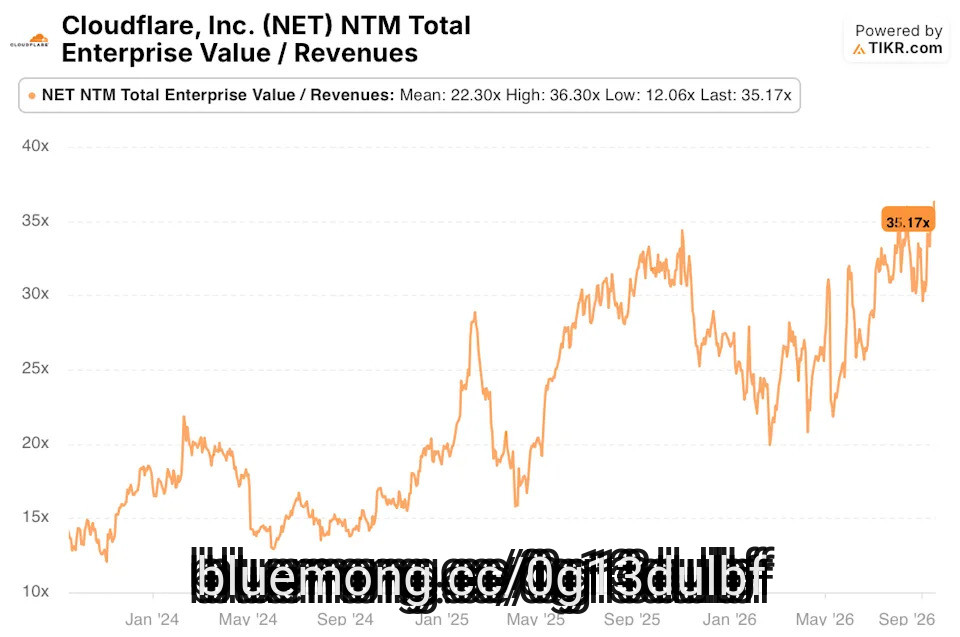
Cloudflare's Q2 beat and reaccelerating growth (36% revenue growth, 120% net dollar retention, record large customer adds) pushed NET stock to new highs, but the market has already paid up: NTM EV/Revenue sits at 35.17x, just below its all-time high of 36.30x and well above its roughly two-year average of 22.30x.
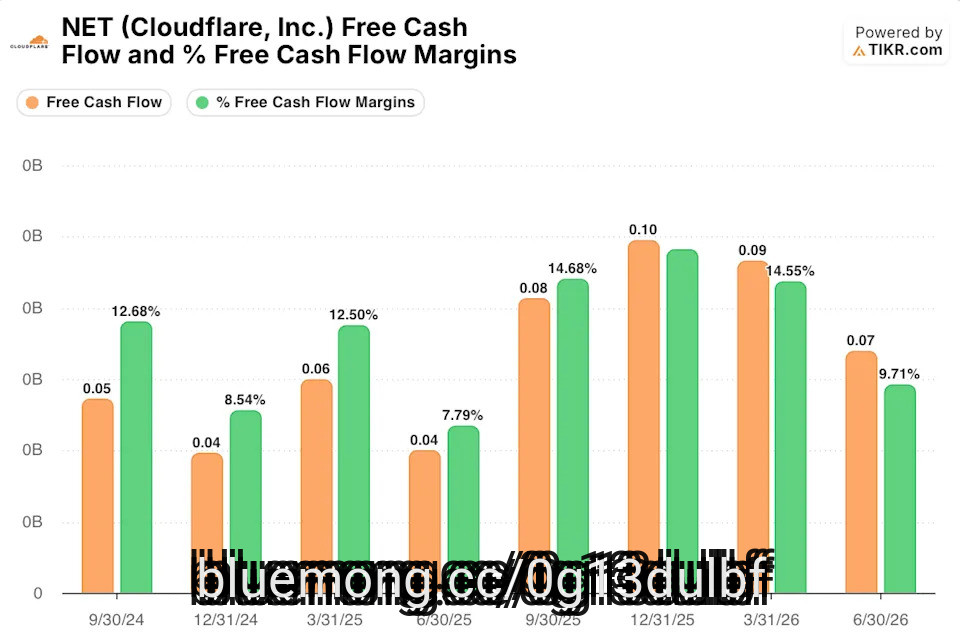
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar
Free cash flow margin, the exact metric management points to as evidence of a credible path to GAAP profitability by 2028, has fallen for two straight quarters, from 14.55% in Q1 2026 to 9.71% in Q2 2026, even as severance and restructuring costs climbed toward $165 million for the year.
President Michelle Zatlyn, CFO Thomas Seifert, and director John Graham-Cumming all sold stock in August and September, Zatlyn alone disposing of roughly $44 million across two separate filings, while the company also raised $2.175 billion in convertible debt despite already holding $4.2 billion in cash.
Street consensus, which saw NET stock as 13% to 22% undervalued for most of late 2025 and early 2026, has now caught up: the mean ****** yst target of $336.81 sits just 4% above the September 18 close of $323.60, a far thinner cushion than investors had earlier in the rally.
Cloudflare's second quarter gave bulls plenty to like. Revenue grew 36% year over year to $696.1 million, beating the $665.5 million ****** yst estimate. The company added a record 986 large customers over the trailing year and net dollar retention accelerated to 120%, up six points from a year earlier. Management used that momentum to lean harder into its Act 4 story, the plan to turn Cloudflare's network into infrastructure for agentic commerce through products like Monetization Gateway, Wallets, and cloudflare.pay.
#revenue #dollar

2 days ago
Johnson & Johnson (JNJ) stock has returned about 57% over the past year, against about 17% for the S&P 500. On the earnings it has already banked, that price looks expensive. But those earnings carry STELARA, which is losing share to biosimilar competition. What looks dear on earnings already reported comes down sharply on the earnings ***** ysts expect.
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings
At about $270 a share, Johnson & Johnson trades at about 28.3 times its trailing earnings. That figure sits on adjusted earnings: normalized net income with stock-based compensation added back, meant to sit closer to the basis ***** ysts use in their forecasts than a GAAP figure would, though the two measures are not defined identically. Measured as market value against consensus net income, the multiple on fiscal 2026 earnings is about 24.1 times, and on the earnings expected for 2027 it is about 20.9 times.
Those trailing twelve months were not a clean run. STELARA cost Johnson & Johnson about 460 basis points of operational sales growth in the second quarter of 2026. Strip it out and the company grew double digits in that quarter on the same basis, on management's own account.
The trailing multiple measures today's price against a period burdened by slowing STELARA revenue. The rest of the portfolio kept growing. Revenue over the trailing twelve months is close to $98 billion, and the company has 28 products and platforms that each sell more than $1 billion a year.
Immunology shows both sides at once. TREMFYA grew 71% in the second quarter of 2026, and it remains the fastest-growing advanced therapy in both Crohn's disease and ulcerative colitis. STELARA is shrinking under biosimilars in that same segment.
#johnson #earnings

3 days ago
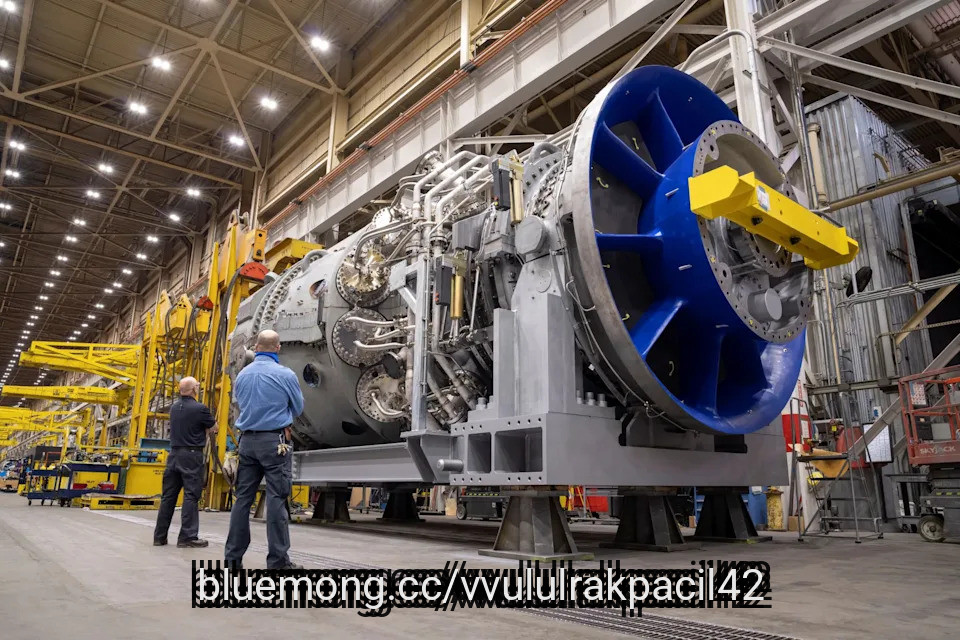
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

3 days ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion


3 days ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
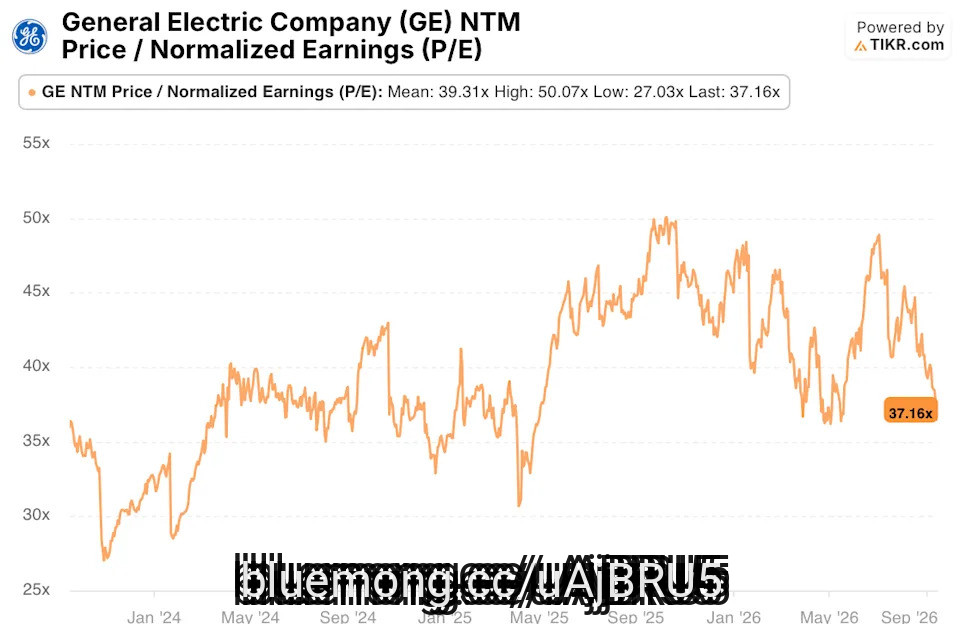
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion



3 days ago
On September 15, Needham ***** yst James Ricchiuti lifted the firm's price target on Teledyne Technologies Incorporated (NYSE:TDY) to $760 from $750, and reiterated a Buy rating. The revised price target reflected an upside of 27% from the close of the note.
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september
According to TipRanks, the ***** yst told investors that the company was well placed to gain from a broadening short cycle recovery and opportunities in modern defense applications. Needham further added that the stock offers a 2.6-to-1 risk/reward skew at current levels.
The adjustment is largely in line with the broader ***** yst community. As of the close on September 16, TDY is a Moderate Buy based on the consensus of 10 ***** ysts. It has a one-year average share price target of $758.20, representing an upside of 26%.
Needham noted 'broadening' improvements in the company's short cycle businesses, which suggests that momentum is spreading across product lines, rather than being limited to any one particular segment.
During the Q2 earnings call, the management noted that short-cycle commercial markets were beginning to show growth inflections after recent headwinds and lifted its short-cycle portfolio's growth outlook to mid-single-digits for the year, up from earlier estimates of flat to low-single-digit growth.
#cycle #september


3 days ago
On September 10, 2026, The Lovesac Company (NASDAQ:LOVE) reported second-quarter fiscal 2027 results for the period ended August 2, 2026. Net sales rose 0.4% to $161.2 million, a record for the quarter, and the company swung to net income of $7.4 million, or $0.51 per diluted share, from a loss of $6.7 million a year earlier. Inside that $0.51 sits $0.86 of net benefit from IEEPA tariff refunds. Omni-channel comparable sales fell 1.9%.
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter
Canaccord's Maria Ripps read the quarter as in line, with revenue and adjusted EBITDA both landing within guidance and near consensus while tariff refunds pushed gross margin and earnings above expectations; she cut the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 but held the Buy rating.
Roth Capital's Matt Koranda also called the quarter in line with consensus, though he flagged omni-channel comps trending modestly negative on soft lower-end consumer demand. He lowered the firm's target on The Lovesac Company (NASDAQ:LOVE) to $20 from $22 as well, keeping a Buy rating, and noted that management reset full-year guidance lower on a tough demand environment and modest product launch delays.
DA Davidson offered a similar interpretation of the lower guidance, arguing that the reset reflects the new CFO's approach more than a deterioration in the underlying business. The firm said the CFO, who joined during the quarter, appears to be establishing more conservative expectations that could restore a beat-and-raise pattern the stock had lacked. DA Davidson lowered its target on The Lovesac Company (NASDAQ:LOVE) to $18 from $20 while maintaining its Buy rating.
The operating case rests on the high end: configurations above $6,000 grew double digits against a tough comparison, showroom net sales rose 4.6% to $114.1 million on 14 net new locations, and Snugg helped push other products revenue up 198.2%. Lovesac ended the quarter with $68.8 million in cash and no debt.
#quarter


3 days ago
On September 2, 2026, Snowflake Inc. (NYSE:SNOW) reported second-quarter fiscal 2027 results for the period ended July 31, 2026. Revenue rose 35% to $1.55 billion against a $1.48 billion consensus, product revenue grew 37% to $1.49 billion, and adjusted earnings came in at $0.62 per share versus the $0.45 ******* ysts expected. Management raised full-year product revenue guidance to $6.07 billion from $5.84 billion. Shares surged more than 20% in extended trading, and within 48 hours eight firms had rewritten their models.
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target
The size of the target revisions tells the story.
Argus ******* yst Joseph Bonner moved to $450 from $300, keeping a Buy rating and arguing that new AI products are driving sales, customer conversion, and retention while Snowflake Inc. (NYSE:SNOW) grows well above management's 30% north star target with expanding margins.
Goldman Sachs also went to $436 from $300, noting product revenue landed 5% above the Street and EBIT margins 270 basis points ahead, and said the stock reaction reflects a setup where estimates keep moving higher over the next 18 months.
JPMorgan lifted its target to $426 from $285 on a third straight quarter of product revenue acceleration, while Raymond James ******* yst Adam Tindle went to $425 from $275, framing Snowflake Inc. (NYSE:SNOW) as an AI-native control plane for enterprise workflows beyond ******* ytics.
#target

3 days ago
Intuitive Surgical (ISRG), maker of the da Vinci surgical robots, trades at about $382, some 36% below its 52-week high. Even so, you pay about 35.9 times trailing adjusted earnings. That is normalized net income with stock-based compensation added back, a basis meant to sit closer to the one ****** ysts forecast on, though the two are not defined identically. ****** ysts' forecasts run to 2027, the year Intuitive plans to start lowering what customers pay per use on some instruments.
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures

4 days ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated
Qualcomm trades at a price-to-earnings ratio of just 22, well below rivals like NVIDIA, Broadcom, and AMD, despite its ties to the AI boom.
Analysts, including Rosenblatt Securities with a $235 price target, see upside from Qualcomm's expansion into AI data centers, automotive chips, and on-device AI processing.
Apple's shift to in-house modem chips and a sluggish Android market in China threaten to offset Qualcomm's diversification gains, keeping its consensus rating at Hold.
There's a certain irony in a stock that has just rallied hard still being written off, yet that's exactly where chipmaker Qualcomm Inc. (NASDAQ: QCOM) finds itself right now. After a brutal 44% slide through much of the summer, its shares staged an impressive comeback, climbing around 30% since the start of August.
#incorporated
4 days ago
CRDO reported $236M in adjusted profit, but stock-comp add-backs and a $62M inventory build shrunk free cash flow to just $83M.
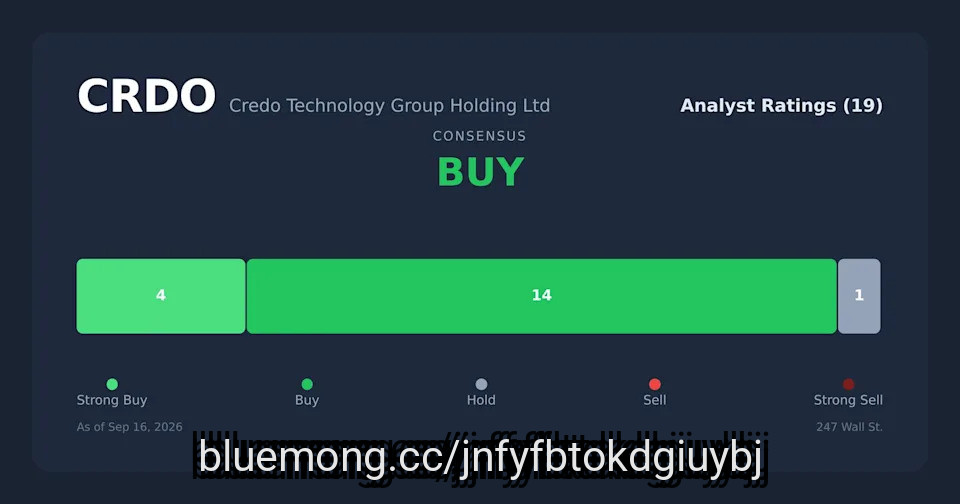
Shares fell 42% in one month to $150, while 18 of 19 ***** ysts maintain Buy ratings with a $281 consensus target.
Top two customers represent 33% and 28% of revenue, meaning a single push-out could flip Credo's inventory build into a demand shortfall.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Credo Technology Group didn't make the cut. Enter your email to see the names that beat CRDO. The report is free. Enter your email and see if any of your stocks made the cut.
Credo (NASDAQ:CRDO) closed its fiscal first quarter with $236.3 million in adjusted profit and $82.9 million in free cash flow, and the stock has moved as if investors noticed. Shares last traded at $150.39, down 42.14% over the past month, while the Wall Street consensus price target sits at $281.47. That leaves a wide spread between where the market is pricing the AI connectivity chipmaker and where the sell side thinks it belongs.
#profit #inventory #build
Shares fell 42% in one month to $150, while 18 of 19 ***** ysts maintain Buy ratings with a $281 consensus target.
Top two customers represent 33% and 28% of revenue, meaning a single push-out could flip Credo's inventory build into a demand shortfall.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Credo Technology Group didn't make the cut. Enter your email to see the names that beat CRDO. The report is free. Enter your email and see if any of your stocks made the cut.
Credo (NASDAQ:CRDO) closed its fiscal first quarter with $236.3 million in adjusted profit and $82.9 million in free cash flow, and the stock has moved as if investors noticed. Shares last traded at $150.39, down 42.14% over the past month, while the Wall Street consensus price target sits at $281.47. That leaves a wide spread between where the market is pricing the AI connectivity chipmaker and where the sell side thinks it belongs.
#profit #inventory #build



5 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors
Trustpilot's underlying business is still growing quickly, with revenue up 23%, bookings up 22% and adjusted EBITDA climbing 46% in the first half. But investors instead focused on a surprise statutory loss, several one-off charges and management's decision to leave full-year guidance unchanged after a huge run in the shares.
Trustpilot shares fell as much as 20% after the online review platform reported strong first-half growth but delivered a messier bottom line than investors had expected.
Revenue increased 23% to $151.4 million in the six months to June, equivalent to 19% growth at constant currencies, while bookings rose 22% to $171.2 million.
Adjusted EBITDA climbed 46% to a record $26.3 million and the margin expanded to 17.4%, although the profit figure came in slightly below the $27 million company-compiled consensus.
#ebitda #bookings #investors

5 days ago
Interested in Netflix, Inc.? Here are five stocks we like better.
Netflix received 25 negative revisions in 90 days, yet 54 **** ysts remain bullish, seeing over 20% upside despite reduced price targets.
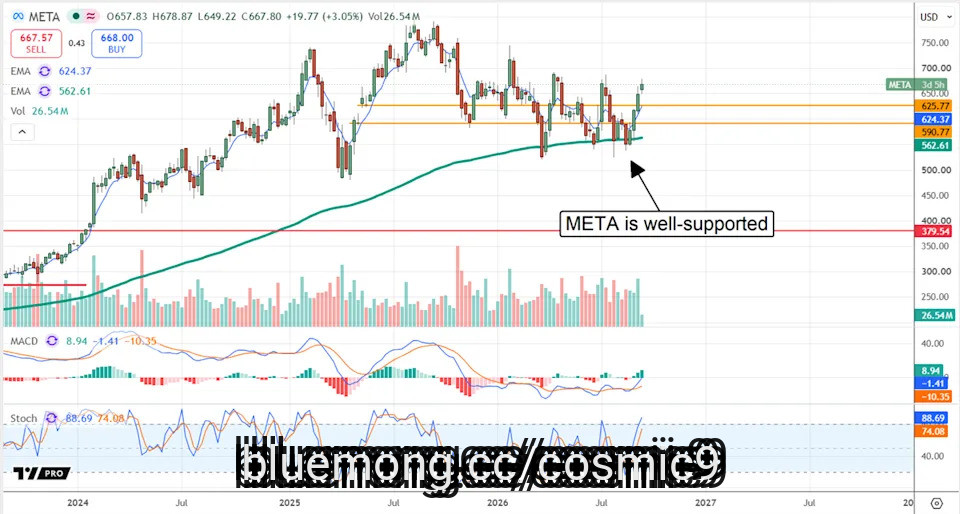
Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but **** ysts still rate it a Moderate Buy with about 20% upside.
Lululemon's downgrades reflect genuine fundamental deterioration, with 29 **** ysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
#bullish #upside #interested #here
Netflix received 25 negative revisions in 90 days, yet 54 **** ysts remain bullish, seeing over 20% upside despite reduced price targets.
Meta Platforms faces 21 downgrades tied to rising CapEx and weak Q2 results, but **** ysts still rate it a Moderate Buy with about 20% upside.
Lululemon's downgrades reflect genuine fundamental deterioration, with 29 **** ysts giving it a consensus Reduce rating and mostly Hold or Sell ratings.
Downgrades rarely help bullish traders, hurting sentiment and price action—unless, of course, you're looking for a good stock to buy into. As always, it's the trend that matters, because a downgrade or price target reduction can mean different things in different situations.
#bullish #upside #interested #here


5 days ago
On September 10, Canaccord cut its price target for The Lovesac Company (NASDAQ:LOVE) from $22 to $20 but maintained its Buy rating on the stock. This update came after the company reported its financial results for the second quarter of fiscal 2027, which ended August 2, 2026.
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
Canaccord noted that the company's fiscal Q2 results were in line with expectations. Revenue and adjusted EBITDA were both within the company's guidance and close to consensus estimates. The company received $21 million in IEEPA tariff refunds, which helped lift gross margins and earnings above consensus.
The Lovesac Company (NASDAQ:LOVE) reported net sales 0.4% higher than the prior-year period. This slight increase was mainly driven by 14 net new showrooms, although this was partly offset by a 1.9% decline in omni-channel comparable net sales and the closure of the company's Best Buy shop-in-shop locations. During the quarter, the company opened five additional showrooms and closed two.
The company reported net income of $7.4 million in the second quarter, compared with a net loss of $6.7 million in the same period last year. Operating income also improved to $10.9 million from an operating loss of $8.8 million a year earlier.
Gross profit rose 21.7% year-over-year while gross margin expanded to 68.4% of net sales from 56.4%, an increase of 1,200 basis points. The improvement was largely driven by IEEPA tariff recoveries, which contributed 1,240 basis points to gross margin. Excluding those recoveries, gross margin was 56.0%, down 40 basis points from the prior-year period.
#year #sales #period
5 days ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

5 days ago
KeyBanc targets $400 for MRVL, implying 83% upside, as the stock sits 34% below its 52-week high despite record Q2 revenue up 37% year-over-year.
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#sits

5 days ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
5 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
5 days ago
Third-party logistics provider Radiant Logistics beat fiscal fourth-quarter expectations Monday after the market closed. A volatile trade landscape is driving demand higher for its customs brokerage and compliance services. It also flagged further tightening in the domestic truckload and intermodal markets, which will propel financial results over time.
"While these market trends are not fully reflected in our results for the June quarter, we view these developments as constructive for our domestic operations in general and our U.S. Brokerage operations, in particular," said Bohn Crain, founder and CEO, in a news release. "If these trends continue, we believe they support a more broad-based and durable recovery for the domestic freight market."
The report sent shares of RLGT 16% higher in early trading on Tuesday versus the S&P 500, which was down 0.2%.
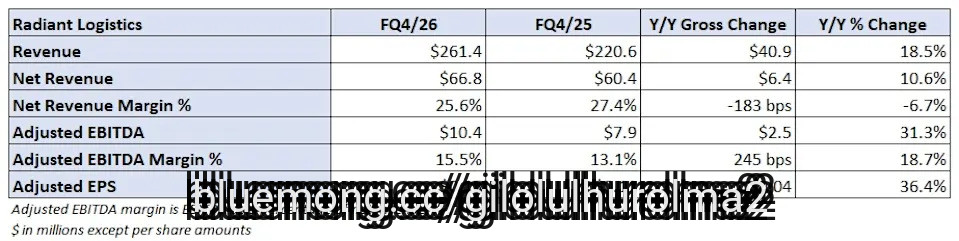
The Renton, Washington-based company reported revenue of $261 million for its fiscal fourth quarter, ended June 30. The result was 19% higher year over year and $30 million ahead of the consensus estimate.
Adjusted earnings per share of 15 cents ($7.4 million) were 4 cents higher y/y and 6 cents ahead of consensus. Disaster relief shipments following typhoons in the Western Pacific drove international airfreight results higher in the period.
#june
"While these market trends are not fully reflected in our results for the June quarter, we view these developments as constructive for our domestic operations in general and our U.S. Brokerage operations, in particular," said Bohn Crain, founder and CEO, in a news release. "If these trends continue, we believe they support a more broad-based and durable recovery for the domestic freight market."
The report sent shares of RLGT 16% higher in early trading on Tuesday versus the S&P 500, which was down 0.2%.
The Renton, Washington-based company reported revenue of $261 million for its fiscal fourth quarter, ended June 30. The result was 19% higher year over year and $30 million ahead of the consensus estimate.
Adjusted earnings per share of 15 cents ($7.4 million) were 4 cents higher y/y and 6 cents ahead of consensus. Disaster relief shipments following typhoons in the Western Pacific drove international airfreight results higher in the period.
#june

5 days ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor

5 days ago
The 10-year U.S. Treasury yield ($TNX) surged to 5.041% earlier today, marking its highest level since July 2007 and representing an 86-basis-point climb since the start of 2026. This 19-year high in benchmark borrowing costs has arrived at a critical juncture, with the Federal Reserve commencing its two-day policy meeting Tuesday and a rate decision expected Wednesday afternoon.
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #year #point #rate
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#prices #year #point #rate


5 days ago
Fidelity Investments, an investment management company, recently released its second-quarter 2026 investor letter for the "Fidelity Dividend Growth Fund". The letter can be downloaded here. The Fidelity Dividend Growth Fund is a diversified large-cap equity strategy focused on capital appreciation through investments in large- and mid-cap stocks with strong dividend growth prospects. The fund returned 17.05% in the quarter, outperforming the S&P 500 Index, which gained 15.20%. U.S. stocks experienced significant gains in Q2, driven by increased spending on artificial intelligence. Technology stocks gained 31.79%, mainly driven by semiconductor companies, while the index faced a slight decline in June as investors considered the sustainability of AI-related profits amidst rising interest rates. Despite recent turbulence from the Middle East conflict, the fund remains optimistic about key investment themes, particularly in artificial intelligence. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f
In its second-quarter 2026 investor letter, Fidelity Dividend Growth Fund highlighted Seagate Technology Holdings plc (NASDAQ:STX) as a notable performance contributor. Seagate Technology Holdings plc (NASDAQ:STX) is a data storage company providing data storage technology and infrastructure solutions. On September 14, 2026, Seagate Technology Holdings plc (NASDAQ:STX) closed at $805.55 per share. Over the past month, Seagate Technology Holdings plc (NASDAQ:STX) declined 10.86%, but its shares are up 281.54% over the past year. Seagate Technology Holdings plc (NASDAQ:STX) has a market capitalization of $183.18 billion, and its stock has traded within a 52-week range of $206.26 to $1,145.00.
Fidelity Dividend Growth Fund stated the following regarding Seagate Technology Holdings plc (NASDAQ:STX) in its Q2 2026 investor letter:
"Shares of Seagate Technology Holdings plc (NASDAQ:STX) gained about 147% the past three months. Seagate is one of the world's largest producers of digital storage and, along with Western Digital, one of two dominant makers of hard-disk drives. Exploding demand for HDDs used in AI capable data centers has led to surging sales and strong pricing power for the company. In its most recent quarterly filing in April, Seagate reported revenue, earnings and profitability that all exceeded consensus expectations, while raising financial guidance."
Seagate Technology Holdings plc (NASDAQ:STX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 131 hedge fund portfolios held Seagate Technology Holdings plc (NASDAQ:STX) at the end of the second quarter, compared to 93 in the previous quarter. While we acknowledge the potential of Seagate Technology Holdings plc (NASDAQ:STX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly f

5 days ago
KeyBanc targets $400 for MRVL, implying 83% upside, as the stock sits 34% below its 52-week high despite record Q2 revenue up 37% year-over-year.
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#marvell #below
A sector-wide AI chip selloff dragged Broadcom down 12% and NVIDIA down 6% over the past month, yet both still carry consensus upside above 54%.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Marvell Technology (NASDAQ:MRVL) currently trades at $218.82, well below the consensus 12-month ****** yst price target of $284.64. That gap implies roughly 30% upside to the average, but one outlier target from KeyBanc sits at $400, a call that would nearly double the stock and represents about 83% upside from here.
Marvell designs custom AI silicon and optical interconnect chips that hyperscalers stitch into their data center fabrics. The company's data center segment now accounts for 79% of total revenue, up from 74% a year ago, which is why Wall Street tracks every hyperscaler order like a leading indicator.
#marvell #below

5 days ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
5 days ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset

5 days ago
The 10-year U.S. Treasury yield ($TNX) surged to 5.041% earlier today, marking its highest level since July 2007 and representing an 86-basis-point climb since the start of 2026. This 19-year high in benchmark borrowing costs has arrived at a critical juncture, with the Federal Reserve commencing its two-day policy meeting Tuesday and a rate decision expected Wednesday afternoon.
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#since #rate
Markets are pricing in a 92.7% probability of a 25-basis-point hike, per CME's FedWatch Tool, which would lift the federal funds target range to 3.75%-4.00%. That overwhelming consensus in favor of a rate hike is a dramatic shift from roughly 59% just one week ago.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Middle East Supply Constraints Lift Crude Oil Prices
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#since #rate

6 days ago
SMCI trades at just 8x FY2027 EPS despite a record $60 billion order backlog and a 78% Q4 earnings beat, supporting a $60 price target by 2027.
Unlike NVDA, which only designs chips, SMCI builds complete AI factories covering rack servers, liquid cooling, and deployment, giving it a one-stop infrastructure moat.
FY2027 EPS estimates jumped 33% in 90 days with 16 upward revisions and zero cuts, yet Wall Street's consensus price target still sits at just $42.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Super Micro Computer (NASDAQ:SMCI) has quietly become one of the more interesting rebound stories in AI infrastructure. Shares are up 21.76% year to date, but the stock is still down 21.46% over the past year as investors work through governance overhangs and margin whiplash.
#fy2027 #target #unlike
Unlike NVDA, which only designs chips, SMCI builds complete AI factories covering rack servers, liquid cooling, and deployment, giving it a one-stop infrastructure moat.
FY2027 EPS estimates jumped 33% in 90 days with 16 upward revisions and zero cuts, yet Wall Street's consensus price target still sits at just $42.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Super Micro Computer (NASDAQ:SMCI) has quietly become one of the more interesting rebound stories in AI infrastructure. Shares are up 21.76% year to date, but the stock is still down 21.46% over the past year as investors work through governance overhangs and margin whiplash.
#fy2027 #target #unlike


6 days ago
CRDO reported $236M in adjusted profit, but stock-comp add-backs and a $62M inventory build shrunk free cash flow to just $83M.
Shares fell 42% in one month to $150, while 18 of 19 ***** ysts maintain Buy ratings with a $281 consensus target.
Top two customers represent 33% and 28% of revenue, meaning a single push-out could flip Credo's inventory build into a demand shortfall.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Credo Technology Group didn't make the cut. Enter your email to see the names that beat CRDO. The report is free. Enter your email and see if any of your stocks made the cut.
Credo (NASDAQ:CRDO) closed its fiscal first quarter with $236.3 million in adjusted profit and $82.9 million in free cash flow, and the stock has moved as if investors noticed. Shares last traded at $150.39, down 42.14% over the past month, while the Wall Street consensus price target sits at $281.47. That leaves a wide spread between where the market is pricing the AI connectivity chipmaker and where the sell side thinks it belongs.
#crdo #shares #inventory
Shares fell 42% in one month to $150, while 18 of 19 ***** ysts maintain Buy ratings with a $281 consensus target.
Top two customers represent 33% and 28% of revenue, meaning a single push-out could flip Credo's inventory build into a demand shortfall.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Credo Technology Group didn't make the cut. Enter your email to see the names that beat CRDO. The report is free. Enter your email and see if any of your stocks made the cut.
Credo (NASDAQ:CRDO) closed its fiscal first quarter with $236.3 million in adjusted profit and $82.9 million in free cash flow, and the stock has moved as if investors noticed. Shares last traded at $150.39, down 42.14% over the past month, while the Wall Street consensus price target sits at $281.47. That leaves a wide spread between where the market is pricing the AI connectivity chipmaker and where the sell side thinks it belongs.
#crdo #shares #inventory



6 days ago
Broadcom trades at $339 versus a Wall Street consensus target of $532, a 55% gap that formed after shares fell 13.7% in one month.
Hock Tan projects AI revenue reaching $115 billion in FY2027 and $230 billion in FY2028, despite an Anthropic slowdown report triggering the recent selloff.
Customer concentration among a handful of hyperscalers means a single negative headline can move AVGO 10% in an afternoon, making position sizing critical.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Broadcom (NASDAQ:AVGO) closed most recently at $339.27, while Wall Street's consensus 12-month price target is $531.85. On a market cap of roughly $1.6 trillion, that gap works out to well above 56%, a rare dislocation for a mega-cap that just posted record numbers.
#wall #billion
Hock Tan projects AI revenue reaching $115 billion in FY2027 and $230 billion in FY2028, despite an Anthropic slowdown report triggering the recent selloff.
Customer concentration among a handful of hyperscalers means a single negative headline can move AVGO 10% in an afternoon, making position sizing critical.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Broadcom (NASDAQ:AVGO) closed most recently at $339.27, while Wall Street's consensus 12-month price target is $531.85. On a market cap of roughly $1.6 trillion, that gap works out to well above 56%, a rare dislocation for a mega-cap that just posted record numbers.
#wall #billion