

14 hours ago
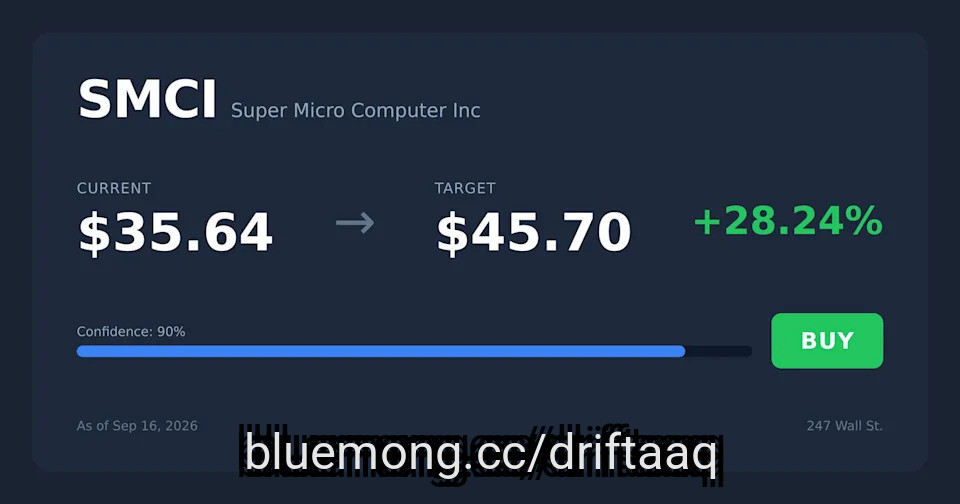
SMCI trades at just 8x FY2027 EPS despite a record $60 billion order backlog and a 78% Q4 earnings beat, supporting a $60 price target by 2027.
Unlike NVDA, which only designs chips, SMCI builds complete AI factories covering rack servers, liquid cooling, and deployment, giving it a one-stop infrastructure moat.
FY2027 EPS estimates jumped 33% in 90 days with 16 upward revisions and zero cuts, yet Wall Street's consensus price target still sits at just $42.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Super Micro Computer (NASDAQ:SMCI) has quietly become one of the more interesting rebound stories in AI infrastructure. Shares are up 21.76% year to date, but the stock is still down 21.46% over the past year as investors work through governance overhangs and margin whiplash.
#fy2027 #target #unlike
Unlike NVDA, which only designs chips, SMCI builds complete AI factories covering rack servers, liquid cooling, and deployment, giving it a one-stop infrastructure moat.
FY2027 EPS estimates jumped 33% in 90 days with 16 upward revisions and zero cuts, yet Wall Street's consensus price target still sits at just $42.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Super Micro Computer (NASDAQ:SMCI) has quietly become one of the more interesting rebound stories in AI infrastructure. Shares are up 21.76% year to date, but the stock is still down 21.46% over the past year as investors work through governance overhangs and margin whiplash.
#fy2027 #target #unlike


17 hours ago
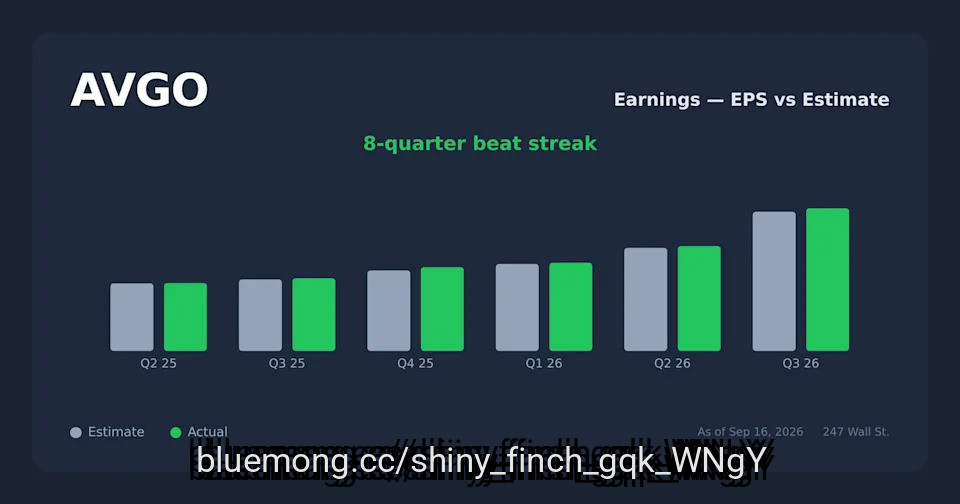
Broadcom trades at $339 versus a Wall Street consensus target of $532, a 55% gap that formed after shares fell 13.7% in one month.
Hock Tan projects AI revenue reaching $115 billion in FY2027 and $230 billion in FY2028, despite an Anthropic slowdown report triggering the recent selloff.
Customer concentration among a handful of hyperscalers means a single negative headline can move AVGO 10% in an afternoon, making position sizing critical.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Broadcom (NASDAQ:AVGO) closed most recently at $339.27, while Wall Street's consensus 12-month price target is $531.85. On a market cap of roughly $1.6 trillion, that gap works out to well above 56%, a rare dislocation for a mega-cap that just posted record numbers.
#wall #billion
Hock Tan projects AI revenue reaching $115 billion in FY2027 and $230 billion in FY2028, despite an Anthropic slowdown report triggering the recent selloff.
Customer concentration among a handful of hyperscalers means a single negative headline can move AVGO 10% in an afternoon, making position sizing critical.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Broadcom (NASDAQ:AVGO) closed most recently at $339.27, while Wall Street's consensus 12-month price target is $531.85. On a market cap of roughly $1.6 trillion, that gap works out to well above 56%, a rare dislocation for a mega-cap that just posted record numbers.
#wall #billion



6 days ago
Two cybersecurity heavyweights, Rubrik, Inc. (NYSE:RBRK) and CrowdStrike Holdings, Inc. (NASDAQ:CRWD), both released Q2 FY2027 earnings in late August/early September while deepening their strategic alliance. On September 1, the companies announced a joint agentic identity resilience workflow orchestrated by CrowdStrike's Charlotte Agentic SOAR. By uniting CrowdStrike's Falcon Next-Gen Identity Security with Rubrik's Identity Resilience, joint customers can now detect, investigate, and recover from compromised identity environments in hours instead of days.
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow
Den Rise/Shutterstock.com
CrowdStrike continues to operate at a massive scale with strong cash generation and expanding margins. For Q2 FY2027, CrowdStrike reported total revenue of $1.47 billion, up 26% year-over-year, with annual recurring revenue (ARR) reaching $5.84 billion (up 25%) after adding a record $333 million in net new ARR. GAAP net income turned positive at $5.3 million ($0.01 per diluted share), while non-GAAP net income reached $322.9 million ($0.31 per diluted share). Operating cash flow hit a Q2 record of $530.3 million, with free cash flow reaching $377.4 million. Expanding its momentum, CrowdStrike announced a partnership with OpenAI on September 2 to secure Codex agents and integrate GPT-5.6 Cyber into Falcon, prompting Raymond James to raise its price target to $250 from $240 on September 3, citing an "AI double whammy."
Rubrik, meanwhile, represents the hyper-growth challenger outperforming Wall Street's top-line expectations. For Q2 FY2027, Rubrik's total revenue surged 38% year-over-year to $427.3 million (up 43% when normalized for material rights), while Subscription ARR grew 33% to $1.66 billion. While GAAP net loss per share narrowed to $(0.30), Rubrik achieved non-GAAP net income per share of $0.20 ($0.47–$0.53 guidance for full FY27). Operating cash flow reached $76.8 million, generating $65.7 million in free cash flow. While CrowdStrike holds the stronger overall financial profile given its $5.84 billion ARR scale and $377.4 million free cash flow generation, Rubrik leads in top-line growth velocity.
CrowdStrike's bull case rests on its leadership in endpoint and identity security, proven GAAP and non-GAAP profitability, and deep AI integrations with platforms such as OpenAI and Charlotte AI, which could drive further platform consolidation and high-margin ARR growth. However, slower percentage growth compared with younger peers, elevated valuation multiples, and lingering customer scrutiny following past software update disruptions remain key risks.
#flow



13 days ago
Cisco (CSCO) rates BUY with a $134 price target, backed by $9.3 billion in hyperscale AI orders and 40% Q4 networking order growth.
Cisco's 21x forward P/E makes it the value standout versus Arista (ANET) near 70x trailing and HPE weighed down by acquisition charges.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Cisco Systems (NASDAQ:CSCO) has quietly become one of the most important names in the AI infrastructure buildout, yet trades like a legacy networking vendor. With $9.3 billion in FY2026 hyperscale AI orders and management guiding to $7.5 billion in AI infrastructure revenue in FY2027, the setup for the next twelve months looks compelling.
Our 24/7 Wall St. price target for Cisco is $134.21, roughly 21.47% above the recent close of $110.49. Our recommendation is buy, with a high confidence rating of 90%.
#cisco #Networking
Cisco's 21x forward P/E makes it the value standout versus Arista (ANET) near 70x trailing and HPE weighed down by acquisition charges.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
Cisco Systems (NASDAQ:CSCO) has quietly become one of the most important names in the AI infrastructure buildout, yet trades like a legacy networking vendor. With $9.3 billion in FY2026 hyperscale AI orders and management guiding to $7.5 billion in AI infrastructure revenue in FY2027, the setup for the next twelve months looks compelling.
Our 24/7 Wall St. price target for Cisco is $134.21, roughly 21.47% above the recent close of $110.49. Our recommendation is buy, with a high confidence rating of 90%.
#cisco #Networking


13 days ago
Global hyperscalers and enterprise buyers are committing record capital to artificial intelligence (AI) data centers, creating extraordinary demand for high-end GPUs and networking equipment. As the dominant supplier of AI accelerators, Nvidia is at the heart of this spending wave.
Nvidia's latest results only strengthened that case when the company surpassed its Q2 FY2027 top- and bottom-line expectations. Moreover, management added that demand continues to outpace supply, meaning available capacity, not customer appetite, is currently the more pressing limitation.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#demand
Nvidia's latest results only strengthened that case when the company surpassed its Q2 FY2027 top- and bottom-line expectations. Moreover, management added that demand continues to outpace supply, meaning available capacity, not customer appetite, is currently the more pressing limitation.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#demand


16 days ago
Interested in Snowflake Inc.? Here are five stocks we like better.
Despite a 50% year-to-date gain and mostly bullish **** yst ratings, Snowflake remains one of the market's most heavily shorted stocks, with short interest valued at $6.18 billion.
Snowflake continues to post GAAP net losses, including $1.33 billion in fiscal 2026, while heavy stock-based compensation and insider selling raise concerns about shareholder dilution.
Bulls point to Snowflake's strong Q1 FY2027 earnings beat, record 126% net revenue retention, growing AI adoption, and rising institutional investment as reasons for long-term optimism.
Establishing fair market value in 2026 has become a tricky proposition. That is particularly true of pre-profit, high-flying tech stocks.
#interested #Bulls #fy2027 #establishing
Despite a 50% year-to-date gain and mostly bullish **** yst ratings, Snowflake remains one of the market's most heavily shorted stocks, with short interest valued at $6.18 billion.
Snowflake continues to post GAAP net losses, including $1.33 billion in fiscal 2026, while heavy stock-based compensation and insider selling raise concerns about shareholder dilution.
Bulls point to Snowflake's strong Q1 FY2027 earnings beat, record 126% net revenue retention, growing AI adoption, and rising institutional investment as reasons for long-term optimism.
Establishing fair market value in 2026 has become a tricky proposition. That is particularly true of pre-profit, high-flying tech stocks.
#interested #Bulls #fy2027 #establishing
20 days ago
Alphabet tops NVDA on reported net income ($244B vs $193B), but NVDA dominates operating income at $198B with a 75% gross margin.
Microsoft's $134B net income ranks third behind both rivals, yet Alphabet's lead rests on a $94B non-cash paper gain from ****** eX.
Don't wait: the ****** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Alphabet (NASDAQ:GOOGL) and NVIDIA (NASDAQ:NVDA) have both reported. Which is now America's most profitable company? Two defensible metrics give opposite answers. Our August scoreboard named Alphabet the leader on reported net income and pointed readers to NVIDIA's Q2 FY2027 earnings report. That report has landed.
On a trailing twelve-month basis, Alphabet booked $244.119B in net income against NVIDIA's $192.879B. The windows differ: Alphabet's covers Q3 2025 through Q2 2026; NVIDIA's covers Q3 FY2026 through Q2 FY2027. Different fiscal calendars create a real mismatch.
#income #reported #NVIDIA #report
Microsoft's $134B net income ranks third behind both rivals, yet Alphabet's lead rests on a $94B non-cash paper gain from ****** eX.
Don't wait: the ****** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
Alphabet (NASDAQ:GOOGL) and NVIDIA (NASDAQ:NVDA) have both reported. Which is now America's most profitable company? Two defensible metrics give opposite answers. Our August scoreboard named Alphabet the leader on reported net income and pointed readers to NVIDIA's Q2 FY2027 earnings report. That report has landed.
On a trailing twelve-month basis, Alphabet booked $244.119B in net income against NVIDIA's $192.879B. The windows differ: Alphabet's covers Q3 2025 through Q2 2026; NVIDIA's covers Q3 FY2026 through Q2 FY2027. Different fiscal calendars create a real mismatch.
#income #reported #NVIDIA #report


20 days ago
On August 17, satellite communications giant Viasat, Inc. (NASDAQ:VSAT) selected launch and ****** e systems provider Rocket Lab Corporation (NASDAQ:RKLB) to build the ****** ecraft bus for the U.S. ****** e Force's Protected Tactical SATCOM-Global (PTS-G) program. Under the initial "Swarm 1" production award, a $218.8 million prime contract won by Viasat in May, Rocket Lab will supply a geosynchronous configuration of its Lightning ****** ecraft platform (Lightning-GEO) to host Viasat's dual-band X/Ka-band anti-jamming payload. Stifel ****** yst Erik Rasmussen maintained a Buy rating on Rocket Lab following the news, citing a "meaningful share" of the award for Rocket Lab that presents a high eight-figure revenue opportunity and positions the company well for follow-on contracts.
Viasat and Rocket Lab present two fundamentally different financial profiles, with Viasat emphasizing scale and improving cash flow while Rocket Lab delivers significantly faster growth. Viasat, Inc. (NASDAQ:VSAT) generated approximately $1.2 billion in Q1 FY2027 revenue, down 1% year over year, primarily reflecting a 4% decline in its Defense and Advanced Technology segment while Communications Services remained flat. Its net loss narrowed to $52 million from $56 million in Q1 FY2026, helped by lower interest expenses following debt repayment. Adjusted EBITDA declined 7% year over year to $381 million, while free cash flow increased 19% to $72 million, excluding non-recurring items. This improvement helped reduce net leverage to 3.2x, down 0.4x, while quarterly awards increased 10% year over year to $1.3 billion.
Rocket Lab Corporation (NASDAQ:RKLB), meanwhile, posted record Q2 2026 revenue of $234.1 million, up 62% year over year, driven by rapid expansion in its ****** e Systems business. Although the company recorded a GAAP net loss of $49.25 million, gross profit increased to $84.57 million, while backlog surged 137% year over year to $2.36 billion. Cash reserves also climbed to $2.13 billion following an ATM equity offering. While Viasat generates roughly five times the revenue and stronger operating cash flow, Rocket Lab is growing at a much faster pace, rapidly scaling its high-margin ****** e Systems business alongside launch services.
Viasat's bull case is supported by strong cash flow generation, with $72 million in free cash flow, and a multi-billion-dollar backlog that provides visibility for continued debt reduction. Its ****** e Force PTS-G win also reinforces the strength of its defense business and could support future growth. However, the bear case centers on declining top-line growth, with revenue down 1% year over year. Heavy capital expenditures on satellite constellations, combined with existing leverage constraints, could limit the company's ability to respond quickly to changing market conditions.
#viasat #space #cash
Viasat and Rocket Lab present two fundamentally different financial profiles, with Viasat emphasizing scale and improving cash flow while Rocket Lab delivers significantly faster growth. Viasat, Inc. (NASDAQ:VSAT) generated approximately $1.2 billion in Q1 FY2027 revenue, down 1% year over year, primarily reflecting a 4% decline in its Defense and Advanced Technology segment while Communications Services remained flat. Its net loss narrowed to $52 million from $56 million in Q1 FY2026, helped by lower interest expenses following debt repayment. Adjusted EBITDA declined 7% year over year to $381 million, while free cash flow increased 19% to $72 million, excluding non-recurring items. This improvement helped reduce net leverage to 3.2x, down 0.4x, while quarterly awards increased 10% year over year to $1.3 billion.
Rocket Lab Corporation (NASDAQ:RKLB), meanwhile, posted record Q2 2026 revenue of $234.1 million, up 62% year over year, driven by rapid expansion in its ****** e Systems business. Although the company recorded a GAAP net loss of $49.25 million, gross profit increased to $84.57 million, while backlog surged 137% year over year to $2.36 billion. Cash reserves also climbed to $2.13 billion following an ATM equity offering. While Viasat generates roughly five times the revenue and stronger operating cash flow, Rocket Lab is growing at a much faster pace, rapidly scaling its high-margin ****** e Systems business alongside launch services.
Viasat's bull case is supported by strong cash flow generation, with $72 million in free cash flow, and a multi-billion-dollar backlog that provides visibility for continued debt reduction. Its ****** e Force PTS-G win also reinforces the strength of its defense business and could support future growth. However, the bear case centers on declining top-line growth, with revenue down 1% year over year. Heavy capital expenditures on satellite constellations, combined with existing leverage constraints, could limit the company's ability to respond quickly to changing market conditions.
#viasat #space #cash


21 days ago
NVIDIA's $108B Q3 guide and supply-constraint warning sent WULF up 7% and APLD up 5% as contracted power capacity grows scarcer and more valuable.
DTCR rose only 0.8% while individual capacity operators surged, confirming today's flow targets contracted AI power hosts, not the broad data center sector.
Don't wait: the ******* yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
TeraWulf (NASDAQ:WULF) stock is up 6% to $16.90 Thursday morning, while Applied Digital (NASDAQ:APLD) shares are climbing 5% to $28.12. Both names are riding a read-across from someone else's earnings report.
That report came from NVIDIA (NASDAQ:NVDA), whose stock is up 7% to $224.38 following a blowout print delivered Wednesday afternoon. NVIDIA's Q2 FY2027 results and forward guide have reignited the AI compute trade across capacity operators tied to hyperscaler and AI-lab demand.
#NASDAQ #apld #contracted #operators
DTCR rose only 0.8% while individual capacity operators surged, confirming today's flow targets contracted AI power hosts, not the broad data center sector.
Don't wait: the ******* yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
TeraWulf (NASDAQ:WULF) stock is up 6% to $16.90 Thursday morning, while Applied Digital (NASDAQ:APLD) shares are climbing 5% to $28.12. Both names are riding a read-across from someone else's earnings report.
That report came from NVIDIA (NASDAQ:NVDA), whose stock is up 7% to $224.38 following a blowout print delivered Wednesday afternoon. NVIDIA's Q2 FY2027 results and forward guide have reignited the AI compute trade across capacity operators tied to hyperscaler and AI-lab demand.
#NASDAQ #apld #contracted #operators

22 days ago
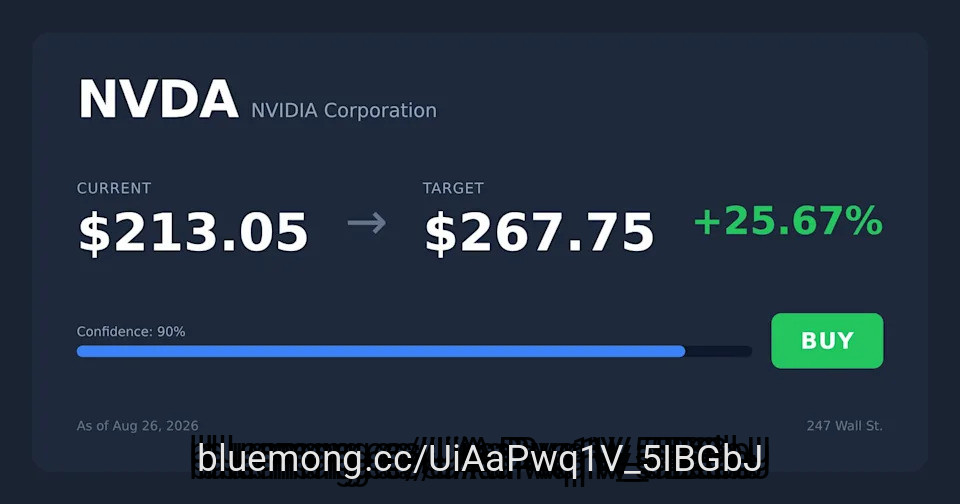
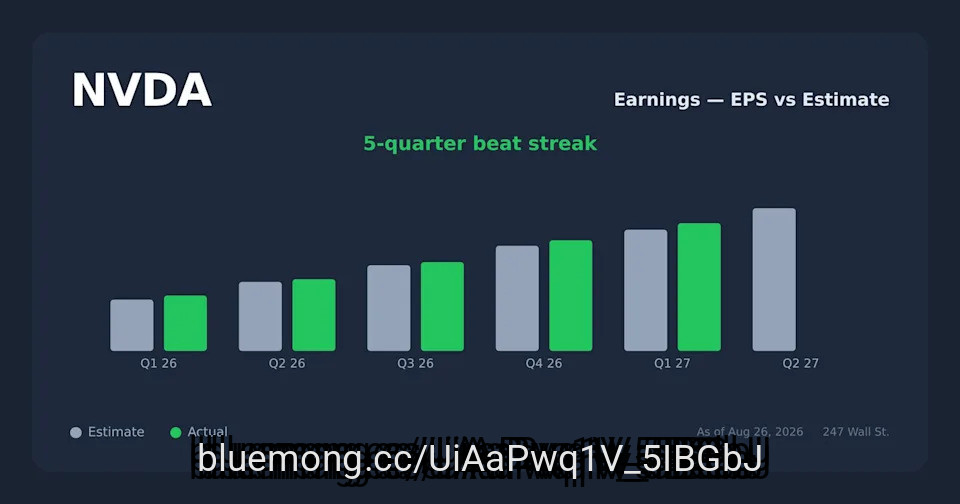
NVDA has beaten EPS estimates five straight quarters yet fallen on earnings day four times, with declines reaching roughly 6%.
With roughly 70% year-over-year growth already baked into FY2027 consensus, it is guidance rather than reported beats that decides how NVIDIA's stock moves after earnings.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
NVIDIA (NASDAQ:NVDA) reports fiscal second-quarter results after the close on Wednesday, August 26, 2026, and the setup is unusual for a company this dominant. Over the past five quarters, NVIDIA has beaten Wall Street on both earnings and revenue every time. Yet in the four quarters since Q1 FY2026, the stock has fallen after earnings.
Consensus estimates call for non-GAAP earnings of roughly $2.09 per share on revenue near $92 billion, roughly double year over year. NVIDIA guided last quarter to $91.0 billion, plus or minus 2%, with non-GAAP gross margin around 75.0% and no China Data Center compute revenue in the outlook. Wedbush ***** yst Matt Bryson expects a beat on both the top and bottom line and carries a $330 price target. He captured the dynamic well, noting NVIDIA has "consistently exceeded consensus" the last three quarters "yet the stock is roughly unchanged from October of last year."
#year #Stock #revenue
With roughly 70% year-over-year growth already baked into FY2027 consensus, it is guidance rather than reported beats that decides how NVIDIA's stock moves after earnings.
Don't wait: the ***** yst who called NVIDIA in 2010 just revealed his top 10 AI stocks. See the full list FREE now.
NVIDIA (NASDAQ:NVDA) reports fiscal second-quarter results after the close on Wednesday, August 26, 2026, and the setup is unusual for a company this dominant. Over the past five quarters, NVIDIA has beaten Wall Street on both earnings and revenue every time. Yet in the four quarters since Q1 FY2026, the stock has fallen after earnings.
Consensus estimates call for non-GAAP earnings of roughly $2.09 per share on revenue near $92 billion, roughly double year over year. NVIDIA guided last quarter to $91.0 billion, plus or minus 2%, with non-GAAP gross margin around 75.0% and no China Data Center compute revenue in the outlook. Wedbush ***** yst Matt Bryson expects a beat on both the top and bottom line and carries a $330 price target. He captured the dynamic well, noting NVIDIA has "consistently exceeded consensus" the last three quarters "yet the stock is roughly unchanged from October of last year."
#year #Stock #revenue


23 days ago
Microsoft (MSFT) cut a $6.8 billion dividend check in fiscal year 2026 while spending $116 billion on AI capex, an amount 4.5 times greater.
Applied Materials (AMAT) led the other 25 ex-dividend companies that same day at $421 million, less than 7% of Microsoft's single-day payout.
Amy Hood committed to staying free cash flow positive in FY2027 even as capex could reach $175 billion, with Azure already crossing $100 billion in annual revenue.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) went ex-dividend on August 20, 2026 at $0.91 a share, cutting a check to holders of record for $6,757,245,950, payable September 10, 2026. That single distribution was the largest of the 26 companies going ex-dividend that day, and it dwarfed the runner-up: Applied Materials (NASDAQ:AMAT) at $420,798,270. Marriott (NASDAQ:MAR), SBA Communications (NASDAQ:SBAC), and LKQ (NASDAQ:LKQ) also went ex-dividend the same day, but none came close to Microsoft's scale.
#Microsoft #billion #amat
Applied Materials (AMAT) led the other 25 ex-dividend companies that same day at $421 million, less than 7% of Microsoft's single-day payout.
Amy Hood committed to staying free cash flow positive in FY2027 even as capex could reach $175 billion, with Azure already crossing $100 billion in annual revenue.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Microsoft didn't make the cut. Grab the names FREE today.
Microsoft (NASDAQ:MSFT) went ex-dividend on August 20, 2026 at $0.91 a share, cutting a check to holders of record for $6,757,245,950, payable September 10, 2026. That single distribution was the largest of the 26 companies going ex-dividend that day, and it dwarfed the runner-up: Applied Materials (NASDAQ:AMAT) at $420,798,270. Marriott (NASDAQ:MAR), SBA Communications (NASDAQ:SBAC), and LKQ (NASDAQ:LKQ) also went ex-dividend the same day, but none came close to Microsoft's scale.
#Microsoft #billion #amat


24 days ago
Retailers' Walmart Inc. (NASDAQ:WMT) and Target Corporation (NYSE:TGT)'s shares are on two opposite spectrums when it comes to year-to-date performance. The latter's stock is down by 8% whole the latter is up by 64%. Cramer discussed the divergence between the two stocks and outlined that while he believed Walmart Inc. (NASDAQ:WMT)'s share price troubles had led to as tock that was too cheap, he didn't think the shares could drop further in terms of valuation:
"The one that I want to. . .I think Walmart is, I think you buy it and then you buy it after. Because we have not seen, Walmart does have a high PE, but I think it's worthy of it.
"I know that John Furner's unproven, as CEO. But I would say that Mr. McMillan, I love him and I think he's taught him well. And you still have John David Rainey there. I just feel like this is the stock that has already come down. I don't think it's going to get to a 20 PE ever again, I think it's got too much growth. But I recognize, it's unloved, it's only up 2.5%, everyone loves Target. And I do like the new management of Target and the comparisons are very easy. But Target's up 57%, 18 times earnings. . ."
Walmart Inc. (NASDAQ:WMT)'s shares haven't had a good week. They closed a painful 9% lower on August 20th after it reported its earnings in the morning. Had viewers bought the shares on Cramer's remarks, they would have missed an opportunity to utilize a major dip that occurred later in the week, as he had made the remarks on the 17th. The central theme for Walmart Inc. (NASDAQ:WMT), following the earnings, is whether the firm's gains in the online segment will transform into sustainable gains for the income statement. Starting from the basics, the firm beat ***** yst revenue and earnings estimates for its fiscal Q2.
While revenue in Q2 grew by 5.9%, Walmart Inc. (NASDAQ:WMT)'s global eCommerce sales jumped by 23% to significantly outpace revenue growth. More importantly, the firm also claimed that 50% US marketplace volume was through its fulfilment services. Additionally, media reports have also suggested that Walmart Inc. (NASDAQ:WMT) has managed to grow its digital advertising business by 26% annually to further complement its online growth. Yet, at the same time, the firm's status as a brick-and-mortar retailer generates worries about the impact of a consumer slowdown on the business. Walmart Inc. (NASDAQ:WMT)'s Q3 guidance for revenue growth and EPS undershot ***** yst estimates. Additionally, the firm also warned about $2 billion in incremental fuel costs in FY2027 and a dip in free cash flow.
#NASDAQ
"The one that I want to. . .I think Walmart is, I think you buy it and then you buy it after. Because we have not seen, Walmart does have a high PE, but I think it's worthy of it.
"I know that John Furner's unproven, as CEO. But I would say that Mr. McMillan, I love him and I think he's taught him well. And you still have John David Rainey there. I just feel like this is the stock that has already come down. I don't think it's going to get to a 20 PE ever again, I think it's got too much growth. But I recognize, it's unloved, it's only up 2.5%, everyone loves Target. And I do like the new management of Target and the comparisons are very easy. But Target's up 57%, 18 times earnings. . ."
Walmart Inc. (NASDAQ:WMT)'s shares haven't had a good week. They closed a painful 9% lower on August 20th after it reported its earnings in the morning. Had viewers bought the shares on Cramer's remarks, they would have missed an opportunity to utilize a major dip that occurred later in the week, as he had made the remarks on the 17th. The central theme for Walmart Inc. (NASDAQ:WMT), following the earnings, is whether the firm's gains in the online segment will transform into sustainable gains for the income statement. Starting from the basics, the firm beat ***** yst revenue and earnings estimates for its fiscal Q2.
While revenue in Q2 grew by 5.9%, Walmart Inc. (NASDAQ:WMT)'s global eCommerce sales jumped by 23% to significantly outpace revenue growth. More importantly, the firm also claimed that 50% US marketplace volume was through its fulfilment services. Additionally, media reports have also suggested that Walmart Inc. (NASDAQ:WMT) has managed to grow its digital advertising business by 26% annually to further complement its online growth. Yet, at the same time, the firm's status as a brick-and-mortar retailer generates worries about the impact of a consumer slowdown on the business. Walmart Inc. (NASDAQ:WMT)'s Q3 guidance for revenue growth and EPS undershot ***** yst estimates. Additionally, the firm also warned about $2 billion in incremental fuel costs in FY2027 and a dip in free cash flow.
#NASDAQ

28 days ago
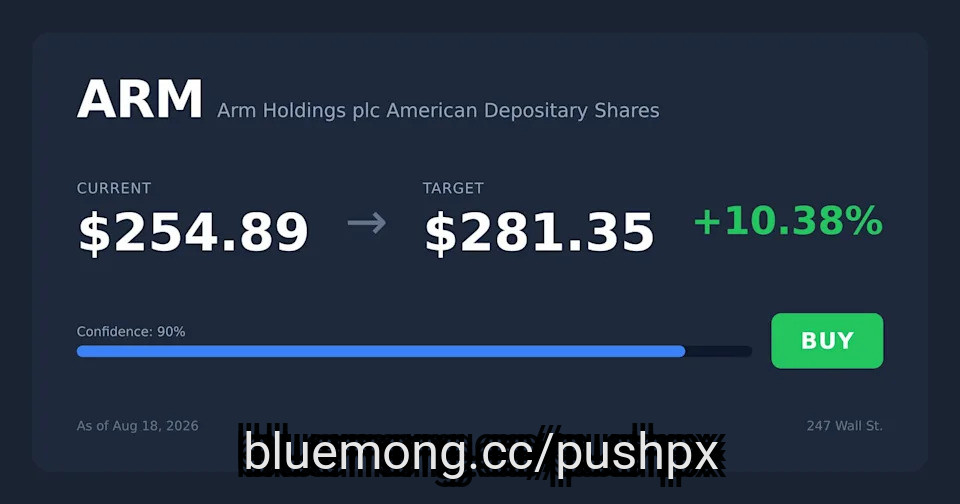
ARM's CEO doubled the AGI CPU demand pipeline to $2 billion, but at 127x forward earnings, the stock earns a HOLD at $284.95.
NVIDIA trades at just 25x forward earnings with 85% revenue growth, making ARM's 127x multiple nearly impossible to justify on fundamentals alone.
The bull case reaches $428 on AGI CPU revenue milestones, while an adverse Qualcomm ruling could drag ARM toward $226.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Arm didn't make the cut. Grab the names FREE today.
Arm Holdings (NASDAQ:ARM) story is straightforward: a licensing business is turning into a data center silicon business. On the fiscal Q1 2027 call, CEO Rene Haas doubled the customer demand pipeline for the Arm AGI CPU to more than $2 billion across FY2027 and FY2028, up from the $1 billion opportunity flagged a quarter earlier. That is the AI signal driving this call.
#doubled #pipeline #business
NVIDIA trades at just 25x forward earnings with 85% revenue growth, making ARM's 127x multiple nearly impossible to justify on fundamentals alone.
The bull case reaches $428 on AGI CPU revenue milestones, while an adverse Qualcomm ruling could drag ARM toward $226.
Act now: the ***** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Arm didn't make the cut. Grab the names FREE today.
Arm Holdings (NASDAQ:ARM) story is straightforward: a licensing business is turning into a data center silicon business. On the fiscal Q1 2027 call, CEO Rene Haas doubled the customer demand pipeline for the Arm AGI CPU to more than $2 billion across FY2027 and FY2028, up from the $1 billion opportunity flagged a quarter earlier. That is the AI signal driving this call.
#doubled #pipeline #business

1 month ago
Republican Sen. Mitch McConnell, after weeks of in-patient care following a fall in mid-June, announced via a statement on Thursday that he has been discharged from a rehabilitation center and will continue his recovery at home.
"Earlier today, I was discharged from the rehabilitation center to continue my recovery at home," McConnell said in a statement. "Elaine and I are grateful for the many well wishes and support from friends, colleagues, and Kentuckians, and for the attentive care I've received from excellent doctors, nurses, therapists, and hospital staff."
"On the advice of my doctors, I'll maintain an intensive regimen of physical therapy from home during the state work period, and I'll continue to engage with my staff and colleagues on important Senate business," McConnell added.
Chip Somodevilla/Getty Images - PHOTO: Mitch McConnell delivers an opening statement during a Senate Appropriations Committee hearing on the FY2027 budget request in the Dirksen Senate Office Building on Capitol Hill on May 12, 2026 in Washington, DC.
McConnell was first hospitalized on June 14 for reasons that were initially undisclosed by his office.
#mitch
"Earlier today, I was discharged from the rehabilitation center to continue my recovery at home," McConnell said in a statement. "Elaine and I are grateful for the many well wishes and support from friends, colleagues, and Kentuckians, and for the attentive care I've received from excellent doctors, nurses, therapists, and hospital staff."
"On the advice of my doctors, I'll maintain an intensive regimen of physical therapy from home during the state work period, and I'll continue to engage with my staff and colleagues on important Senate business," McConnell added.
Chip Somodevilla/Getty Images - PHOTO: Mitch McConnell delivers an opening statement during a Senate Appropriations Committee hearing on the FY2027 budget request in the Dirksen Senate Office Building on Capitol Hill on May 12, 2026 in Washington, DC.
McConnell was first hospitalized on June 14 for reasons that were initially undisclosed by his office.
#mitch


2 months ago
Global defense spending is entering a historic expansion phase, driven by geopolitical flashpoints from Ukraine to the Indo‑Pacific and record Pentagon budgets. NATO allies are racing to meet or exceed 2% of GDP defense commitments, while the U.S. has proposed a $1.5 trillion military budget for FY2027. Against this backdrop of rising military allocations and urgent weapons replenishment, Lockheed Martin Corp. (NYSE:LMT) has emerged as the sector's anchor, converting its record $230.4 billion backlog into profitable growth and securing new Pentagon contracts that reinforce its leadership in advanced defense systems.
Lockheed Martin Corp. (NYSE:LMT) shares surged more than 10% on July 23 after the company reported strong Q2 2026 earnings and secured additional business with the Pentagon. The stock is up more than 15% since the beginning of the year. This rally shows investor confidence in the company's ability to convert its massive backlog into profitable growth, even amid defense budget politics.
Jordan Tan / Shutterstock.com
Lockheed has won $67.7 million from the Pentagon for a new pair of contracts. One of the contracts covers US Navy submarine systems upgrades and is worth up to $44.6 million. The other covers F-35 fighter jet maintenance depots for allied nations and is worth $23.1 million.
Lockheed's latest Pentagon contract awards arrive as defense spending continues to rise. Amid persistent geopolitical tensions, countries are moving to upgrade their defense capabilities and replenish weapon inventories.
#million #martin #corp #NYSE
Lockheed Martin Corp. (NYSE:LMT) shares surged more than 10% on July 23 after the company reported strong Q2 2026 earnings and secured additional business with the Pentagon. The stock is up more than 15% since the beginning of the year. This rally shows investor confidence in the company's ability to convert its massive backlog into profitable growth, even amid defense budget politics.
Jordan Tan / Shutterstock.com
Lockheed has won $67.7 million from the Pentagon for a new pair of contracts. One of the contracts covers US Navy submarine systems upgrades and is worth up to $44.6 million. The other covers F-35 fighter jet maintenance depots for allied nations and is worth $23.1 million.
Lockheed's latest Pentagon contract awards arrive as defense spending continues to rise. Amid persistent geopolitical tensions, countries are moving to upgrade their defense capabilities and replenish weapon inventories.
#million #martin #corp #NYSE

2 months ago
Rep. Alexandria Ocasio-Cortez, D-N.Y., came under fire after claiming the House-passed National Defense Authorization Act (NDAA) would "merge parts of our military with the Israel Defense Forces," drawing accusations that she distorted what the legislation actually does.
The fight centers on Section 219 of the House-passed National Defense Authorization Act, a provision that calls for deeper U.S.-Israel defense integration through expanded cooperation on military technology, supply chains, research, artificial intelligence, cybersecurity and joint exercises.
On Wednesday, the House passed its version of the FY2027 NDAA in a 219-206 vote, leaving Section 219 intact.
But ahead of the vote, Ocasio-Cortez wrote on X that the NDAA "includes a provision to merge parts of our military with the IDF."
The Us-israel Strategic Alliance – Partnership, Not Charity
#passed #national #authorization
The fight centers on Section 219 of the House-passed National Defense Authorization Act, a provision that calls for deeper U.S.-Israel defense integration through expanded cooperation on military technology, supply chains, research, artificial intelligence, cybersecurity and joint exercises.
On Wednesday, the House passed its version of the FY2027 NDAA in a 219-206 vote, leaving Section 219 intact.
But ahead of the vote, Ocasio-Cortez wrote on X that the NDAA "includes a provision to merge parts of our military with the IDF."
The Us-israel Strategic Alliance – Partnership, Not Charity
#passed #national #authorization

2 months ago
Is DRI a good stock to buy? We came across a bullish thesis on Darden Restaurants, Inc. on Elliot's Musings's Substack by Elliot. In this article, we will summarize the bulls' thesis on DRI. Darden Restaurants, Inc.'s share was trading at $204.32 as of July 2nd. DRI's trailing and forward P/E were 19.34 and 17.92 respectively according to Yahoo Finance.
LeStudio/Shutterstock.com
Darden Restaurants, Inc., together with its subsidiaries, owns and operates full-service restaurants in the United States and Canada. DRI delivered a fundamentally strong Q4 FY2026 despite two temporary distortions that masked the underlying performance: a 53rd fiscal week that inflated reported results while creating an optical headwind for FY2027 comparisons, and Olive Garden's lighter-portions menu initiative, which reduced reported same-store sales by roughly 80 basis points despite underlying demand meeting expectations.
Read More: 15 AI Stocks That Are Quietly Making Investors Rich
Read More: Undervalued AI Stock Poised For Massive Gains: 10000% Upside Potential
LeStudio/Shutterstock.com
Darden Restaurants, Inc., together with its subsidiaries, owns and operates full-service restaurants in the United States and Canada. DRI delivered a fundamentally strong Q4 FY2026 despite two temporary distortions that masked the underlying performance: a 53rd fiscal week that inflated reported results while creating an optical headwind for FY2027 comparisons, and Olive Garden's lighter-portions menu initiative, which reduced reported same-store sales by roughly 80 basis points despite underlying demand meeting expectations.
Read More: 15 AI Stocks That Are Quietly Making Investors Rich
Read More: Undervalued AI Stock Poised For Massive Gains: 10000% Upside Potential


3 months ago
MRVL trades at a richer 68x forward P/E than AVGO's 33x, despite posting gross margins of 52% versus Broadcom's 67%.
Broadcom's 46% FCF margin and VMware's sticky software annuity make it a reliable compounder Marvell's hyperscaler-dependent model can't yet match.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Marvell Technology (NASDAQ: MRVL) and Broadcom (NASDAQ: AVGO) both just delivered AI-fueled earnings beats, yet the businesses look nothing alike under the hood. Marvell posted 231.37% YTD gains chasing custom XPU wins. Broadcom quietly compounded with elite margins and a software stack. The contrast deserves a closer look before anyone pays up.
Marvell delivered Q1 FY2027 revenue of $2.42B, up 27.6% YoY, with Data Center contributing $1.83B, or 76% of revenue. CEO Matt Murphy guided Q2 to $2.70B, calling out "exceptional AI-related bookings" across 800G/1.6T optics and custom XPU programs. Encouraging, but the GAAP gross margin sat at 52.1%. That is the structural reality of bespoke silicon: hyperscalers hold the leverage.
Broadcom's 46% FCF margin and VMware's sticky software annuity make it a reliable compounder Marvell's hyperscaler-dependent model can't yet match.
Act now: the ******* yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Broadcom didn't make the cut. Grab the names FREE today.
Marvell Technology (NASDAQ: MRVL) and Broadcom (NASDAQ: AVGO) both just delivered AI-fueled earnings beats, yet the businesses look nothing alike under the hood. Marvell posted 231.37% YTD gains chasing custom XPU wins. Broadcom quietly compounded with elite margins and a software stack. The contrast deserves a closer look before anyone pays up.
Marvell delivered Q1 FY2027 revenue of $2.42B, up 27.6% YoY, with Data Center contributing $1.83B, or 76% of revenue. CEO Matt Murphy guided Q2 to $2.70B, calling out "exceptional AI-related bookings" across 800G/1.6T optics and custom XPU programs. Encouraging, but the GAAP gross margin sat at 52.1%. That is the structural reality of bespoke silicon: hyperscalers hold the leverage.

3 months ago
We just covered Donald Trump Stock Portfolio: 10 Best AI and Tech Stock Picks in 2026. Marvell Technology (NASDAQ:MRVL) ranks #5 (see Donald Trump Stock Portfolio: 5 Best AI and Tech Stock Picks in 2026). The stocks identified in this article are based on Trump's financial disclosure filings released by the U.S. Office of Government Ethics. According to a statement from the Trump Organization cited by Reuters, Trump's investment holdings are maintained through fully discretionary accounts managed by third-party financial institutions, which have sole authority over investment decisions.
Stock Performance Since Trade Date: +180%
Marvell Technology (NASDAQ:MRVL) is another favorite stock of Donald Trump that has shown spectacular performance since his purchase in February 2026. It makes custom AI chips, networking solutions, and semiconductor products designed for hyperscalers and data centers. Its customers include the world's largest cloud and technology companies including Google, Amazon, and other major hyperscalers that are increasingly turning to custom ASICs as a more cost-effective way to scale computing power for AI clusters.
Trump isn't the only fan of Marvell Technology (NASDAQ:MRVL). Recently, Nvidia CEO Jensen Huang publicly endorsed Marvell as a potential trillion-dollar company, causing the stock to surge 45% in a single week. Nvidia also made a $2 billion strategic investment in Marvell, and the two companies are collaborating on NVLink Fusion, which makes Marvell's custom XPUs compatible with Nvidia's broader AI infrastructure stack including Vera CPUs, ConnectX NICs, BlueField DPUs, and Spectrum-X switches.
But beyond the Huang factor, there are strong fundamental growth catalysts for Marvell Technology (NASDAQ:MRVL). The company recently unveiled the first switch operating at a record speed of 102.4 Tbps designed for AI clusters, delivering energy savings of up to 25% compared to competitors. It also acquired Polariton Technologies to strengthen its photonics-based optical solutions, and has secured over 10 XPU attach program wins with custom revenue expected to grow 20% year-over-year in FY2027, doubling again in FY2028, and nearly tripling by FY2029 towards more than $10 billion.
Stock Performance Since Trade Date: +180%
Marvell Technology (NASDAQ:MRVL) is another favorite stock of Donald Trump that has shown spectacular performance since his purchase in February 2026. It makes custom AI chips, networking solutions, and semiconductor products designed for hyperscalers and data centers. Its customers include the world's largest cloud and technology companies including Google, Amazon, and other major hyperscalers that are increasingly turning to custom ASICs as a more cost-effective way to scale computing power for AI clusters.
Trump isn't the only fan of Marvell Technology (NASDAQ:MRVL). Recently, Nvidia CEO Jensen Huang publicly endorsed Marvell as a potential trillion-dollar company, causing the stock to surge 45% in a single week. Nvidia also made a $2 billion strategic investment in Marvell, and the two companies are collaborating on NVLink Fusion, which makes Marvell's custom XPUs compatible with Nvidia's broader AI infrastructure stack including Vera CPUs, ConnectX NICs, BlueField DPUs, and Spectrum-X switches.
But beyond the Huang factor, there are strong fundamental growth catalysts for Marvell Technology (NASDAQ:MRVL). The company recently unveiled the first switch operating at a record speed of 102.4 Tbps designed for AI clusters, delivering energy savings of up to 25% compared to competitors. It also acquired Polariton Technologies to strengthen its photonics-based optical solutions, and has secured over 10 XPU attach program wins with custom revenue expected to grow 20% year-over-year in FY2027, doubling again in FY2028, and nearly tripling by FY2029 towards more than $10 billion.


3 months ago
We just covered Billionaire Dan Loeb Pivots to AI and Sells Old Economy Stocks: His Top 7 AI Picks. KLA Corp. (NASDAQ:KLAC) ranks #5 (see Billionaire Dan Loeb's Top 5 AI Stock Picks).
Billionaire Dan Loeb's Stake: 110,000 Shares Valued at Approximately $16.20 Million (NEW position)
KLA Corp. (NASDAQ:KLAC) plays a key role in the AI revolution because it makes the machines used to inspect and measure semiconductor chips during manufacturing — essentially the quality control layer of every major fab on the planet. It holds a 58% global market share in process control, meaning most of the world's chip manufacturers rely on KLA equipment to ensure their chips come out correctly.
KLA Corp. (NASDAQ:KLAC) sits at the center of every major semiconductor tailwind right now. As chip geometries shrink down to 2nm, the inspection and metrology requirements become exponentially more demanding — older machines simply can't detect flaws at that level of precision, which forces chipmakers to upgrade their KLA equipment with every new node generation. Hyperscalers are projected to spend over $725 billion on AI infrastructure in 2026 alone, which flows directly into chip manufacturing demand, which flows directly into KLA.
KLA Corp. (NASDAQ:KLAC) targets $26 billion in revenue by 2030, representing a 13–17% revenue CAGR, alongside gross margin expansion to 63.5%. EPS is expected to grow around 34% in FY2027, outpacing peers like Applied Materials and Entegris on both volume and growth rate.
Billionaire Dan Loeb's Stake: 110,000 Shares Valued at Approximately $16.20 Million (NEW position)
KLA Corp. (NASDAQ:KLAC) plays a key role in the AI revolution because it makes the machines used to inspect and measure semiconductor chips during manufacturing — essentially the quality control layer of every major fab on the planet. It holds a 58% global market share in process control, meaning most of the world's chip manufacturers rely on KLA equipment to ensure their chips come out correctly.
KLA Corp. (NASDAQ:KLAC) sits at the center of every major semiconductor tailwind right now. As chip geometries shrink down to 2nm, the inspection and metrology requirements become exponentially more demanding — older machines simply can't detect flaws at that level of precision, which forces chipmakers to upgrade their KLA equipment with every new node generation. Hyperscalers are projected to spend over $725 billion on AI infrastructure in 2026 alone, which flows directly into chip manufacturing demand, which flows directly into KLA.
KLA Corp. (NASDAQ:KLAC) targets $26 billion in revenue by 2030, representing a 13–17% revenue CAGR, alongside gross margin expansion to 63.5%. EPS is expected to grow around 34% in FY2027, outpacing peers like Applied Materials and Entegris on both volume and growth rate.



