

1 month ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#quarter #revenue


1 month ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio

1 month ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care

1 month ago
On September 14, Radiant Logistics (NYSEAMERICAN:RLGT) held its fourth fiscal quarter earnings call, and the headline numbers landed harder than a typical logistics update. Net income jumped 53.1% to $7.5 million for the quarter ended June 30, while revenue climbed 18.5% to $261.4 million. Look past that one quarter, though, and the picture gets more complicated, because full-year adjusted profitability actually fell. That gap between a blowout quarter and a softer year is what makes this name worth a closer look.
The fourth fiscal quarter was strong from top to bottom. Adjusted EBITDA rose 31.6% to $10.4 million, margin expanded 240 basis points to 15.5%, and adjusted net income climbed 34.5% to $7.4 million, all against organic revenue growth of 8%. Management credited the acceleration to US forwarding operations and international airfreight, including work supporting disaster relief after typhoon activity hit the Western Pacific earlier this year, plus airfreight demand tied to capital flows into global data center buildouts.
The balance sheet backs up the story. Radiant enters fiscal 2027 with zero net debt, $25.6 million in cash as of June 30, and a $200 million senior credit facility that was extended and restated in August, pushing maturity out to August 7, 2031, while its acquisition-focused accordion grew to $100 million from $75 million. On the domestic side, capacity has been exiting the truckload and intermodal markets, and spot rates and tender rejections moved higher late in the quarter. Radiant also launched a new independent agent program at Radiant Road & Rail during the quarter, extending its freight forwarding agent network into truck brokerage and intermodal, while Navegate is gaining traction, with one enterprise customer now managing more than 1,400 vendors on the platform.
The full-year numbers tell a different story than the quarter does. Revenue rose just 3.5% to $934.4 million from $902.7 million, a fraction of the fourth quarter's 18.5% pace, and full-year net income grew a modest 8.7% to $18.8 million. Full-year adjusted EBITDA actually fell 5.4% to $36.7 million from $38.8 million, and that figure included a $1.3 million First Brands adjustment. Strip that out and normalized adjusted EBITDA comes in at $35.4 million, an even steeper decline than the headline number suggests.
The operating backdrop stays complicated too. Ocean shipping routes remain disrupted by the closure of the Strait of Hormuz and continued Houthi activity affecting Suez Canal transits, keeping capacity tight on key trade lanes. US tariff policy is generating elevated IEEPA-related filing activity, and Canada put new retaliatory tariff measures into effect in early September, adding fresh complexity for shippers moving goods across that border. Management itself acknowledged that the domestic truck brokerage improvement seen late in the fourth quarter is not yet fully reflected in the reported results.
#million #quarter #revenue #fiscal


1 month ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda

1 month ago
HSBC Holdings plc (NYSE:HSBC) is winding down its transaction services business in Germany, with more than 300 positions at HSBC Transaction Services GmbH and HSBC Service Company Germany GmbH expected to be phased out by 2028. The division provides securities processing, administration and custody services.
HSBC said the move is part of its broader strategy to strengthen its position in businesses where it has competitive advantages and sees stronger growth opportunities. The decision follows HSBC Germany's sale of its private banking business to BNP Paribas last year, highlighting the bank's continued effort to streamline its European operations.
Northfoto/Shutterstock.com
The biggest positive for HSBC Holdings plc (NYSE:HSBC) is that the German exit could improve the bank's efficiency and profitability over time. Rather than continuing to allocate capital and employees to a transaction-services operation that HSBC apparently sees as less strategically attractive, the bank can redirect resources toward areas where it has stronger competitive advantages. This fits CEO Georges Elhedery's broader restructuring strategy of reducing complexity, cutting costs and concentrating HSBC on businesses with better growth prospects. Reuters has reported that HSBC has already been selling non-core operations as part of this transformation, while its shares have risen substantially since the restructuring began.
The timing could also be constructive. Germany's economy remains under pressure, with industrial production falling unexpectedly in July and manufacturing activity still facing significant challenges. Reducing exposure to a business tied to the German market could therefore protect HSBC Holdings plc (NYSE:HSBC) from maintaining costs in an environment where growth is relatively weak.
#german

1 month ago
General Motors is developing a domestic battery supply chain it expects to complete within two to three years, even as the company currently relies on some Chinese-sourced materials for its existing battery production.
Kurt Kelty, GM's vice president of battery and sustainability, told CNBC that the company's near-term goal is full domestic sourcing. "We're developing a supply chain such that, two years from now, three years from now, it will be domestic," Kelty said. "That's what we're aiming for — when we get into market, we've got a domestic source for that."
Kelty's comments center on sodium-ion battery cells that GM is developing with Denver-based startup Peak Energy for use in stationary energy storage systems for homes, businesses, and data centers. GM expects to reach commercial production of those cells around 2029, according to CNBC. A GM spokesperson confirmed to CNBC that the company would apply the same domestic sourcing priority to battery cells for future electric vehicles.
Unlike conventional lithium iron phosphate chemistry, sodium-ion cells are built around sodium from soda ash — a resource the U.S. holds in abundance — sidestepping the lithium and ferrous sulfate supply chains that China currently controls. Kelty added that sodium-ion cells handle a broader span of temperatures, which means they can function without the active thermal management that drives up the cost and complexity of stationary storage installations.
"The better thing to do is try to leapfrog, come up with a different technology that's actually better that we can actually source here," Kelty told CNBC.
#battery #supply #years #we 're


2 months ago
A cryptocurrency ETF is an exchange-traded fund that gives investors exposure to cryptocurrency through a regular brokerage account with no crypto wallet, exchange, or private keys required. The most important type is the spot ETF, which holds the actual cryptocurrency (Bitcoin, Ether, etc.) in secure custody, so the fund's price tracks the real-time price of the coin. When you buy a share, you're getting direct exposure to the underlying **** et, wrapped in the familiar, regulated ETF structure. One technical note: U.S. spot crypto funds are structured as exchange-traded products — grantor trusts registered under the Securities Act of 1933 — rather than as 1940 Act ETFs, so they trade just like ETFs but do not carry all of the same investor protections.
This is a big deal because it removes the biggest barriers to crypto investing: custody risk, exchange hacks, and technical complexity. It also brings crypto into tax-advantaged accounts and lets investors hold it alongside their stocks and bonds in one place.
Spot Bitcoin ETFs launched in the U.S. in January 2024 and have become the fastest-growing ETF category ever. In 2026 they dominate the crypto ETF landscape.
IBIT (iShares Bitcoin Trust) was one of the first to market and is the runaway leader, with roughly $71 billion in **** ets — well over half of the entire spot Bitcoin ETF market. BlackRock's fund has become the default vehicle for institutional and retail Bitcoin exposure alike, prized for its deep liquidity and low cost. FBTC (Fidelity Wise Origin Bitcoin Fund) is second with about $18 billion, and GBTC (Grayscale Bitcoin Trust), the converted legacy fund, holds around $15 billion despite its higher fee. For most investors seeking Bitcoin exposure, IBIT and FBTC are the go-to, low-cost choices.
Spot Ethereum ETFs followed in July 2024 and form the second pillar of the crypto ETF world. ETHA (iShares Ethereum Trust) leads with roughly $11 billion in **** ets, followed by FETH (Fidelity Ethereum Fund) at about $2.3 billion. Ethereum offers a different investment thesis than Bitcoin as it's the backbone of decentralized applications, smart contracts, and much of the tokenization trend. This means ether ETFs give investors exposure to a distinct part of the digital-asset ecosystem.
#Bitcoin


2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
The phrase 'AI weapons' often conjures images of machines making life-and-death decisions without human oversight. Xtend AI Robotics, Inc. Common Stock CEO Aviv Shapira believes that narrative has outpaced reality. While autonomy is advancing rapidly across modern defense systems, he argues the industry's trajectory is not about removing humans from the battlefield, but enabling them to make better decisions by letting AI handle speed, complexity and dangerous tasks.
Shapira rejected the idea that autonomous weapons are headed toward fully independent lethal decision-making. "That is a misconception, at least in terms of where the industry is today," he told Benzinga in an exclusive email interview.
Don't Miss:
A single bad hire can set a startup back years. Here are the 5 hires founders most often misjudge — and why
#benzinga #shapira #weapons #decisions


2 months ago
Stanley Black & Decker, Inc. (NYSE:SWK) entered into a definitive agreement to sell Excel Industries to Bad Boy Mowers. Excel Industries, which includes the Hustler Turf Equipment brand, is expected to generate approximately $300 million of fiscal 2026 revenue.
The purchase price and expected proceeds were not disclosed. The transaction remains subject to regulatory approval and customary closing conditions. Until closing, Excel Industries will remain in continuing operations and will not be classified as a discontinued operation.
Stanley Black & Decker, Inc. (NYSE:SWK) does not expect the transaction to dilute adjusted EPS. Adjusted EPS is a company-defined non-GAAP measure calculated as diluted GAAP EPS excluding certain gains and charges, including divestiture-related items, restructuring, footprint actions, and gains or losses on business sales.
The sale advances the portfolio-simplification strategy of Stanley Black & Decker, Inc. (NYSE:SWK). Divesting a specialized turf-equipment platform could reduce complexity and concentrate investment on larger brands and markets.
Stanley Black & Decker, Inc. (NYSE:SWK) plans to continue investing in its Outdoor business, including electrical products and high-performance residential ride-on and zero-turn mowers. The remaining portfolio includes DEWALT, CRAFTSMAN, Cub Cadet, Troy-Bilt and BLACK+DECKER, providing established platforms for outdoor growth.
#black #industries
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management characterizes the current period as the midpoint of a multi-quarter transformation, moving from a 'technical debt' cleanup phase toward a projected 'acceleration phase' in fiscal year 2028.
Performance was driven by a 'Bear Hug' strategy focused on enterprise retention, resulting in renewal rates improving and completed sales transactions increasing 30% year-over-year.
The company is seeing a strategic shift among large enterprises away from point solutions toward unified AI-native platforms to reduce complexity and lower costs.
Professional services underperformed due to partner cost overruns and execution challenges in one specific region following the completion of a massive implementation project.
#phase #NVIDIA #bear #analysts

2 months ago
Artisan Partners, an investment management company, released its second-quarter 2026 investor commentary for the "Artisan Global Opportunities Strategy". The letter can be downloaded here. Global equities rebounded sharply during the quarter, with the MSCI ACWI Index returning 15.3% as resilient economic growth, strong corporate earnings, and continued enthusiasm around artificial intelligence supported markets despite persistent inflation, higher bond yields, and geopolitical uncertainty. The portfolio reported strong absolute returns of 12.65% (net) but underperformed the benchmark, mainly because of its underweight exposure to information technology and overweight position in health care. Strong stock selection in technology and energy partially offset these headwinds. The fund continues to see attractive long-term opportunities across AI infrastructure, health care and consumer internet, while remaining disciplined on valuation as several AI-related stocks have appreciated sharply. Management remains focused on durable franchises with identifiable profit cycles and attractive long-term earnings potential. Also, check the Strategy's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Artisan Global Opportunities Strategy highlighted Corning Incorporated (NYSE:GLW) as a new position. Corning Incorporated (NYSE:GLW) is a technology company that operates through optical communication, display technologies, environmental technologies, specialty materials, and life sciences business segments. On September 01, 2026, Corning Incorporated (NYSE:GLW) closed at $145.56 per share. Corning Incorporated (NYSE:GLW) declined 8.08% over the past month, while its shares gained 107.73% over the past 52 weeks. Corning Incorporated (NYSE:GLW) has a market capitalization of $125.38 billion with a 52-week trading range between $66.14 - $271.78.
Artisan Global Opportunities Strategy stated the following regarding Corning Incorporated (NYSE:GLW) in its Q2 2026 investor letter:
"During the quarter, we initiated positions in Corning Incorporated (NYSE:GLW). Corning and STMicroelectronics represent earlier stage semiconductor supply chain opportunities that we believe will see growing demand as AI infrastructure spending broadens beyond today's most obvious beneficiaries. In both cases, we see a potential opportunity for higher value, higher margin products as data centers require greater optical connectivity, semiconductor content and related infrastructure. Corning is a leading global supplier of specialty glass and optical connectivity solutions. We initiated a GardenSM position because we believe Corning is well positioned to meet rising optical connectivity needs as AI infrastructure shifts toward larger clusters and scale-up architectures. While we are not early to the story, we believe the company's fiber capacity, US-based manufacturing footprint and ability to deliver higher complexity optical solutions to hyperscaler

2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Lam Research Corporation (NASDAQ:LRCX), a leading semiconductor equipment company that supplies semiconductor processing equipment. Lam Research Corporation (NASDAQ:LRCX), with a 4.7% portfolio weight, contributed 2.2% to the Fund's performance this quarter. On September 1, 2026, Lam Research Corporation (NASDAQ:LRCX) closed at $290.20 per share. Over the past month, Lam Research Corporation (NASDAQ:LRCX) declined 5.60%, but its shares are up 196.91% over the past year. Lam Research Corporation (NASDAQ:LRCX) has a market capitalization of $363.13 billion.
Sands Capital Select Growth Fund stated the following regarding Lam Research Corporation (NASDAQ:LRCX) in its Q2 2026 investor letter:
"Lam Research Corporation (NASDAQ:LRCX) is a leading global provider of semiconductor fabrication equipment. Shares of the business benefited from renewed confidence in semiconductor capital spending and the rising complexity of chip manufacturing. In the first quarter, revenue grew 24 percent and adjusted earnings per share grew 42 percent year over year, while June-quarter guidance exceeded consensus expectations. The company is a critical supplier of etch and deposition equipment, both of which become increasingly important as memory architectures and leading-edge semiconductor manufacturing grow more complex. We believe Lam's exposure to high-bandwidth memory, advanced NAND, and a recovering memory investment cycle gives it a differentiated role within the AI infrastructure supply chain."
#NASDAQ #fund #select


2 months ago
UK retailers selling online to EU consumers face new customs costs and data requirements as the bloc reforms its treatment of low-value imports, adding complexity to post-Brexit cross-border trade ahead of the Golden Quarter.
UK retailers selling goods directly to EU consumers face a new customs cost following the introduction of a temporary €3 duty on low-value imports.
The EU measure took effect on 1 July 2026 and applies to qualifying goods in consignments worth up to €150 imported from outside the EU. It replaces the previous customs duty exemption for low-value consignments and is scheduled to remain in place until 1 July 2028.
The duty is charged at €3 for each tariff category represented in a consignment, rather than per parcel or physical unit. For example, five T-shirts in the same tariff category would attract a €3 duty, while a T-shirt and a watch could attract €6 because they fall into different categories.
The reform is not aimed specifically at the UK. It applies to low-value imports from non-EU countries regardless of their country of origin.
#value #duty #customs
2 months ago
Andvari ***** ociates, an investment management firm, released its first-quarter 2025 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ***** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ***** ociates highlighted Tyler Technologies, Inc. (NYSE:TYL). Tyler Technologies, Inc. (NYSE:TYL) is a leading US-based integrated software and technology solutions provider for the public sector. On August 28, 2026, Tyler Technologies, Inc. (NYSE:TYL) closed at $377.94 per share. The one-month return of Tyler Technologies, Inc. (NYSE:TYL) was 23.70%, and its shares lost 32.86% over the past 52 weeks. Tyler Technologies, Inc. (NYSE:TYL) has a market capitalization of $15.48 billion.
Andvari ***** ociates stated the following regarding Tyler Technologies, Inc. (NYSE:TYL) in its Q2 2026 investor letter:
"Tyler Technologies, Inc. (NYSE:TYL), a software company focused solely on state and local government customers, recently raised its 2030 financial goals because the cloud transition for its customers has moved from aspiration to solid proof. Since its 2023 investor day, Tyler has met or exceeded its 2025 interim targets, shifted more than 95% of new-client total contract value to SaaS ("software as a service"), completed the migration of its roughly 5,000 hosted customers onto AWS, and exited its last private data center on schedule. All this gives management more confidence in both future growth and margins. Tyler's remaining on-premise maintenance base still represents a large conversion pool, and each maintenance-to-SaaS "Lip" is expected to lift recurring revenue by roughly 1.7x before any cross-sell, payments attach, or module expansion. Just as important, Tyler's next phase—"Cloud Living"—should reduce version complexity, lower support burden, speed upgrades, and create a more scalable operating model…" (Click here to read the full text)
#andvari #quarter


2 months ago
Steel and aluminum stocks surged and then retreated last week as the escalating trade war between the United States and Canada sent investors scrambling to reprice exposure to North American metals supply chains.
SLX gained 1.6% on Monday, Aug. 25, following the breakdown of U.S.-Canada trade talks, and the State Street Materials Select Sector SPDR (XLB) reached a new intraday record that session, topping the peak it had set in February. Shares of Nucor, Steel Dynamics, Cleveland-Cliffs, and Century Aluminum all climbed. The gains proved short-lived, however: by Friday's close, XLB had slipped into the red for the week and SLX was essentially unchanged, according to CNBC. Through Aug. 28, Morningstar data show SLX has gained more than 28% on the year and XLB more than 18%.
The swing reflects the complexity of a trade war between two countries whose metals industries are deeply intertwined. Dan Luttner, who serves as managing partner of the supply chain consulting firm NEOS by Argon & Company, characterized the initial stock move to CNBC as a repricing reflex rather than a durable signal. "The stock pop is a headline reflex, honestly — mills reprice to replacement cost the second a 50% wall goes up, so of course Nucor and Cleveland-Cliffs jumped," Luttner said. "But that's not the interesting question. The interesting question is who controls their feedstock inside the wall versus who's still exposed to it?"
Luttner noted that both Nucor and Cleveland-Cliffs use electric arc furnace technology whose inputs have no dependence on Canadian ore or slab, positioning them to capture tariff-driven pricing benefits without the same exposure. Cleveland-Cliffs stock is nonetheless in negative territory for 2026 because of balance sheet stress. Century Aluminum is a more complicated case: because domestic primary aluminum production is thin, the raw inputs that sustain it — alumina and semi-finished material — largely still flow across the Canadian border, undermining the protection the tariffs were meant to provide.
Atsi Sheth, chief credit officer at Moody's Ratings, said uncertainty will persist. "Expect much more of this uncertainty for some time to come," Sheth said. She added that U.S. steel companies hold a modest edge over their Canadian counterparts because the U.S. market is larger, but said the auto sector has no clear winner given how deeply integrated cross-border production is.
#cliffs #nucor

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributed a June same-store sales decline of 7% to an 'extraordinary stretch' of at-home sports viewership, specifically the World Cup and NBA Finals, which disrupted typical weekend bowling patterns.
The company reported a 3.5-point improvement in same-store sales comps over the prior year, driven by strength in retail bowling, shoe revenue, and a significant 8% growth in food sales.
California remains the weakest market, comping at minus 4% compared to plus 1% for the rest of the company, prompting a leadership overhaul and a restructuring of the state's corporate sales organization.
Strategic integration of five directly managed water parks increased operational complexity but delivered double-digit per capita spending growth through disciplined revenue management.
#store #revenue


2 months ago
Aristotle Capital Management, LLC, an investment management company, released its "Value Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund delivered a 4.32% total return in Q2 2026, underperforming the 13.87% gain for the Russell 1000 Value Index and the 15.20% return for the S&P 500, while its 1.99% year-to-date return also lagged the Russell 1000 Value Index's 16.26% and the S&P 500's 10.21%. The Fund attributed the performance gap largely to limited exposure to the AI infrastructure spending boom, noting that the U.S. has about 4,000 existing data centers and nearly 3,000 more planned or under construction, while AI-related demand has created bottlenecks in processors and memory. The letter highlighted the scale of the cycle, with industry cash flows in key AI hardware areas rising sharply, while the Russell 1000 Value Index's top 10 contributors gained an average 182% year to date and accounted for 9.29 percentage points of the index's 16.23% return. Looking ahead, the fund expects investors to eventually reassess the sustainability of current AI infrastructure earnings and valuations. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Value Equity Fund highlighted stocks like Corteva, Inc. (NYSE:CTVA). Corteva, Inc. (NYSE:CTVA) provides advanced seeds, crop protection products, and agricultural technologies designed to improve farm productivity and resilience. The one-month return of Corteva, Inc. (NYSE:CTVA) was 4.69% while its shares traded between $60.54 and $90.97 over the last 52 weeks. On August 27, 2026, Corteva, Inc. (NYSE:CTVA) stock closed at approximately $82.88 per share, with a market capitalization of about $54.98 billion.
Aristotle Value Equity Fund stated the following regarding Corteva, Inc. (NYSE:CTVA) in its Q2 2026 investor letter:
Corteva, Inc. (NYSE:CTVA), the seed and crop protection company, was one of the largest detractors during the period. While fundamentals remained healthy, with first-quarter FREE cash flow supported by strength in both Seed and Crop Protection, the stock lagged a sharply rising market as investors focused on Corteva's more tempered outlook for the balance of the year. The management team cited potential second-half headwinds from tariffs, higher oil-related input costs, farmer fuel expenses, and competitive crop protection pricing in Latin America and Asia. We believe the market also weighed the near-term complexity of Corteva's planned fourth-quarter separation into New Corteva and Vylor, including potential dis-synergies from operating two public companies. Nevertheless, our investment thesis remains intact. Farmers continue to adopt Corteva's latest hybrids, varieties, and premium crop protection technologies, supporting Corteva's margin expansion. Meanwhile, the company's R&D-led innovation, disciplined cost management, and path toward net royalty income sho

2 months ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management attributes the Q2 sales beat to tangible progress in the 'Consumer First Formula,' specifically citing a return to digital growth and accelerated expanded distribution through Amazon and Ulta.
The company is shifting from seasonal collections to enduring franchises, exemplified by the Fruit Fusion launch which exceeded expectations and achieved higher average unit retail (AUR) than core **** ortments.
Strategic portfolio discipline led to the decision to exit the Home Care category (laundry and kitchen), as it represents less than 1% of sales and creates disproportionate operational complexity.
Digital performance improved 4 percentage points sequentially, driven by enhanced storytelling, personalization, and a lower free shipping threshold of $50.
#tell #formula

2 months ago
On August 10, 2026, Teledyne Technologies Incorporated (NYSE:TDY) agreed to acquire Varex Imaging for $18.90 a share in an all-cash deal valued at about $1.1 billion. It sent Varex Imaging Corporation (NASDAQ:VREX) shares up nearly 50% before the opening bell.
Teledyne is paying a large premium for a smaller X-ray components maker just as Varex posted a genuine earnings beat of its own. Is Teledyne buying real, complementary technology at a fair long-term price, or paying a steep premium right as Varex's turnaround was already starting to work?
CEO Robert Mehrabian said the companies serve similar customers with "uniquely complementary" products and minimal overlap. He noted Teledyne Technologies Incorporated (NYSE:TDY) doesn't make X-ray detectors suited for high-radiation environments like oncology the way Varex does. Both boards unanimously approved the deal, which is expected to close in early 2027.
Nearly a 50% one-day jump in Varex's stock shows the market sees this as a rich price for Teledyne to pay. Integrating Varex's X-ray business, which serves medical, security, and industrial markets, adds real complexity to Teledyne Technologies Incorporated (NYSE:TDY)'s existing operations.
CEO Sunny Sanyal said the deal marks "an exciting new chapter," giving Varex Imaging Corporation (NASDAQ:VREX) access to Teledyne's resources to accelerate use of its imaging technology. Varex also posted third-quarter adjusted profit of 31 cents a share, 10 cents ahead of **** yst estimates, after recovering tariff-related costs and generating $21 million in operating cash flow. It shows the business was already improving before the deal was announced.
#NASDAQ


2 months ago
SAP (NYSE:SAP) faces a slower path to monetizing artificial intelligence, according to UBS, which downgraded the German software giant to Neutral from Buy on concerns that agentic AI is reaching customers too slowly.
The Swiss bank said SAP remains a dominant system of record with a deep moat around its core enterprise resource planning business, but the pace of "out-of-the-box" AI agent delivery is lagging. SAP has rolled out just 17 such agents to date, with another 15 in ramp-up, leaving its target of 200 by year-end looking difficult to reach, UBS **** ysts wrote.
The complexity of SAP's largest customers, many running multiple ERP instances across different versions and often on private cloud deployments with custom coding, complicates the company's ability to deliver standardized AI tools, according to the note. UBS said it is hearing positive signals on customers building their own agents through Joule Studio, but adoption remains gradual, making it hard to disprove bearish views on SAP's AI relevance in the near term.
UBS expects cloud backlog growth to decelerate in the second half of the year toward management's guided ~23% constant-currency pace, down from Q2's 26% (24.6% organic), a slowdown likely to pressure shares without clearer AI traction.
UBS also cited falling cloud gross, higher AI token costs pressuring R&D spending, a 100 million euro cut to 2026 EBIT guidance from acquisition dilution, and management's warnings about IT spending risks tied to the Gulf conflict.
#remains #german


2 months ago
Coty Inc. (NYSE:COTY) traded about 7% lower shortly after its earnings release, with the after-hours decline later approaching 8.5%, as a fourth-quarter revenue beat was accompanied by a wider-than-expected adjusted loss and weaker near-term profit guidance. Revenue increased 1.3% to $1.27 billion, outperforming the consensus forecast for a 4.6% decline. However, the company-defined adjusted loss was $0.02 per share versus the $0.01 consensus loss, like-for-like sales fell 1%, and the reported net loss widened to $141 million.
The larger red flag is visibility. Coty Inc. (NYSE:COTY) expects first-quarter company-defined adjusted earnings of $0.11 to $0.13 per share, below the $0.14 consensus estimate, while like-for-like revenue is projected to decline by a low- to mid-single-digit percentage. Management also withheld fiscal 2027 guidance and described the period as a transition year, even though fiscal 2025 carried the same label.
The revenue beat showed that Coty Inc. (NYSE:COTY) still owns brands with meaningful consumer demand. Fourth-quarter like-for-like sales declined only 1%, improving substantially from the 7% decline in the third quarter. Fragrance demand remains comparatively resilient, supporting a portfolio centered on brands such as Burberry, Hugo Boss, Calvin Klein, Marc Jacobs and Chloé.
Portfolio simplification could also strengthen Coty Inc. (NYSE:COTY)'s balance sheet. Coty received $250 million at the signing of the Gucci Beauty agreement and is due another $150 million by September 30, 2027, subject to a possible holdback of up to $30 million. The immediate proceeds can support debt reduction and investment in core brands. Potential sales of CoverGirl, Rimmel, or other Consumer Beauty **** ets could further reduce complexity and concentrate capital on higher-return prestige fragrances.
The first-quarter outlook leaves Coty Inc. (NYSE:COTY) without a demonstrated earnings inflection point. Management is forecasting another like-for-like sales decline, adjusted earnings below consensus, and no full-year framework. Investors therefore lack a clear bridge between the restructuring program and sustainable earnings or free-cash-flow growth.
#coty #earnings #quarter #revenue

2 months ago
As years and seasons pass, the modern NFL becomes increasingly obsessed with disguise. Coaches and their coordinators spend countless hours searching for ways to confuse quarterbacks, hide intentions, and create pre-snap hesitation. The challenge, however, is that complexity can become a double-edged sword. A defense that confuses opponents can sometimes confuse the players who execute it.
That balancing act is something the Baltimore Ravens have been working through during training camp. Eric DeCosta and company have ***** embled a unit filled with versatile players who can line up in multiple spots. Jesse Minter and Anthony Weaver are charged with teaching players to handle a variety of responsibilities.
The more flexibility a defense possesses, the more options coaches have at their disposal. The question becomes how to maximize that versatility without overwhelming the players expected to execute it. Recently, Ravens defensive coordinator Anthony Weaver spoke with reporters and was asked about the ripple effects of having so many defenders capable of moving around the formation.
"The ripple effect for the players, I think, is you have to have a very smart team — because if you are going to move guys around, ultimately that means other guys are going to have to do different jobs, too."
Weaver's answer offered an interesting look at the philosophy guiding Baltimore's defensive approach. That comment highlights an often-overlooked aspect of defensive football. Versatility isn't just about one player learning multiple positions.
#players #coaches #defense

2 months ago
This story was originally published on QSR. To receive daily news and insights, subscribe to our free daily QSR AM Jolt.
Delaware North, one of the largest and most diversified hospitality and food service companies in the world, has partnered with TipHaus to streamline and automate tip management across its portfolio of venues.
For an operator of Delaware North's scale and diversity, spanning stadiums, arenas, resorts, destination restaurants, and entertainment venues, tip management has traditionally meant a patchwork of manual, location-by-location processes, each with its own rules and reconciliation headaches. Since bringing TipHaus on board in March 2025, Delaware North has replaced that fragmented approach with a single automated system that handles hundreds of distinct tip-pooling and distribution use cases across its operations. Today, TipHaus supports more than 40 locations for Delaware North.
"Partnering with TipHaus has helped Delaware North streamline and modernize our tip management process, reducing administrative effort while improving accuracy and transparency for our leaders," said Michele Seaver, Director of Payroll and Workforce Management at Delaware North. "What used to take a full day of coordination now takes just a couple of hours to pull a single enterprise-wide export. Given the diversity and complexity of our portfolio, the flexibility of the TipHaus platform, and the collaborative partnership we have built with the TipHaus team have been extremely valuable. Their willingness to adapt solutions and get creative to meet our unique operational needs has helped us drive greater consistency across our business while supporting a better experience for all involved," Seaver said.
TipHaus integrates directly with the systems Delaware North already runs, including Oracle Simphony, Toast, and UKG Dimensions, pulling sales, shift, and labor data automatically so that tip calculations run without manual data entry from each location. Rather than forcing a rigid, one-size-fits-all model, TipHaus configures to the specific rules of each property, allowing Delaware North to standardize oversight at the enterprise level while honoring the operational realities of each individual venue.
#Delaware #location

2 months ago
Guinness Global Innovators, an investment management company, recently released its Q2 2026 quarterly investor update for its "Guinness Global Innovators Fund". You can download the letter here. The Guinness Global Innovators Fund focuses on investing in global companies that benefit from innovation in technology, communication, globalization, and management strategies. In the second quarter of 2026, the Guinness Global Innovators Fund returned 13.8% in GBP, compared with 13.0% for the MSCI World Index and 13.1% for the IA Global sector average. Easing Middle East tensions, falling oil prices, and renewed enthusiasm for artificial intelligence helped reverse much of the caution seen earlier in the year, with investors rotating back toward growth stocks and AI infrastructure beneficiaries. The Fund benefited from its overweight position in the Information Technology sector, while its overweight position in Communication Services detracted. Avoiding weaker Utilities, Materials, and Energy also supported relative performance. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Guinness Global Innovators Fund highlighted Nasdaq, Inc. (NASDAQ:NDAQ) as a new holding. Nasdaq, Inc. (NASDAQ:NDAQ) operates as a technology company that serves capital markets and other industries. On August 21, 2026, Nasdaq, Inc. (NASDAQ:NDAQ) closed at $98.22 per share. One-month return of Nasdaq, Inc. (NASDAQ:NDAQ) was 4.56% and its shares gained 4.13% over the past 52 weeks. Nasdaq, Inc. (NASDAQ:NDAQ) has a market capitalization of $54.9 billion.
Guinness Global Innovators Fund stated the following regarding Nasdaq, Inc. (NASDAQ:NDAQ) in its Q2 2026 investor letter:
"Nasdaq, Inc. (NASDAQ:NDAQ) is best understood not as a traditional exchange but as a global technology, data, and ******* ytics company that happens to own a major stock exchange, a positioning it has deliberately built since its 2017 strategic pivot away from transaction-driven revenue towards higher-growth, higher-margin software and ******* ytics. Nasdaq's business is diversified across three segments. Through its Financial Technology segment, the firm is strategically positioned to benefit from a structural rise in compliance and transparency requirements as regulators demand more granular and frequent reporting from banks globally. This segment also houses Calypso, a trading and risk-management platform whose demand is underpinned by the growing complexity of trading, collateral, and risk requirements at large financial institutions. The Capital Access Platforms segment includes listing fees, market data subscriptions and index licensing on products such as the Nasdaq-100. Lastly, its exchange business, although originally the direct driver of the business, has become more of an enabler for other business segments, as trading activity generates proprietary pricing data that the company repackages and monetises, while providing the

2 months ago
Liverpool are expected to step up their pursuit of Bradley Barcola this week, with fresh movement anticipated as the club weighs a bid that could challenge, or even surpass, their current transfer record. According to Nicolo Schira, an offer is imminent, a significant development in a chase that has been building for months.
Barcola has been on Liverpool's radar for some time, with recruitment staff identifying the Paris Saint-Germain winger as a major opportunity in the market. Interest has remained strong despite the complexity of dealing with PSG, who have shown little willingness to soften their stance. The French champions are understood to value the 23-year-old at an elite level, leaving suitors with only one realistic route, table a huge proposal.
That is where Liverpool now appear to be heading. There is an acceptance internally that a conventional offer will not shift PSG's position. If a breakthrough is to come, it will likely require a figure beyond anything Liverpool have previously committed for a wide attacker, and potentially above the £125m paid for Alexander Isak.
The timing is notable. Liverpool have several areas of the squad to address before the window closes, and that creates pressure around both budget and prioritisation. Bradley Barcola remains one of the standout names under consideration, while other attacking options continue to be monitored in parallel.
What stands out in this situation is Liverpool's willingness to keep pushing despite PSG's hard-line approach. That suggests belief in the player's quality, profile and long-term fit. Barcola offers pace, directness and top-level upside, qualities that are clearly being valued highly during this market cycle.
#despite #willingness


2 months ago
Guinness Global Innovators, an investment management company, recently released its Q2 2026 quarterly investor update for its "Guinness Global Innovators Fund". You can download the letter here. The Guinness Global Innovators Fund focuses on investing in global companies that benefit from innovation in technology, communication, globalization, and management strategies. In the second quarter of 2026, the Guinness Global Innovators Fund returned 13.8% in GBP, compared with 13.0% for the MSCI World Index and 13.1% for the IA Global sector average. Easing Middle East tensions, falling oil prices, and renewed enthusiasm for artificial intelligence helped reverse much of the caution seen earlier in the year, with investors rotating back toward growth stocks and AI infrastructure beneficiaries. The Fund benefited from its overweight position in the Information Technology sector, while its overweight position in Communication Services detracted. Avoiding weaker Utilities, Materials, and Energy also supported relative performance. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, Guinness Global Innovators Fund highlighted Nasdaq, Inc. (NASDAQ:NDAQ) as a new holding. Nasdaq, Inc. (NASDAQ:NDAQ) operates as a technology company that serves capital markets and other industries. On August 21, 2026, Nasdaq, Inc. (NASDAQ:NDAQ) closed at $98.22 per share. One-month return of Nasdaq, Inc. (NASDAQ:NDAQ) was 4.56% and its shares gained 4.13% over the past 52 weeks. Nasdaq, Inc. (NASDAQ:NDAQ) has a market capitalization of $54.9 billion.
Guinness Global Innovators Fund stated the following regarding Nasdaq, Inc. (NASDAQ:NDAQ) in its Q2 2026 investor letter:
"Nasdaq, Inc. (NASDAQ:NDAQ) is best understood not as a traditional exchange but as a global technology, data, and ****** ytics company that happens to own a major stock exchange, a positioning it has deliberately built since its 2017 strategic pivot away from transaction-driven revenue towards higher-growth, higher-margin software and ****** ytics. Nasdaq's business is diversified across three segments. Through its Financial Technology segment, the firm is strategically positioned to benefit from a structural rise in compliance and transparency requirements as regulators demand more granular and frequent reporting from banks globally. This segment also houses Calypso, a trading and risk-management platform whose demand is underpinned by the growing complexity of trading, collateral, and risk requirements at large financial institutions. The Capital Access Platforms segment includes listing fees, market data subscriptions and index licensing on products such as the Nasdaq-100. Lastly, its exchange business, although originally the direct driver of the business, has become more of an enabler for other business segments, as trading activity generates proprietary pricing data that the company repackages and monetises, while providing the f

2 months ago
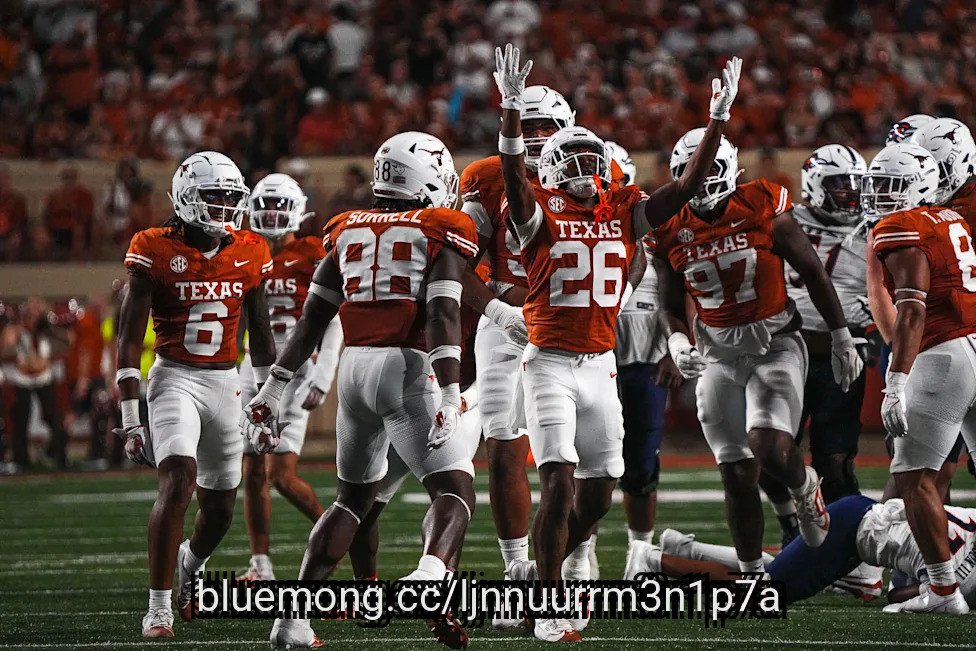
We are officially two weeks from Texas football and another major piece of news has popped up. Ty'Anthony Smith, the third-year linebacker, has been dismissed from the team following a tumultuous fall camp.
As has been discussed throughout the offseason, the LB room is not the deepest on the team. The trio of freshmen, led by Tyler Atkinson, will need to play a bigger role this season. I believe they are up to the task but it's unlikely to come as quickly as Texas would like.
One of the single biggest storylines this offseason has been the freshmen LBs. Tyler Atkinson came in as the top dawg, but Rocky ******* s and Kosi Okpala were the story during spring camp. Since then, Atkinson has taken a step forward and seems poised to back up Rasheem Biles. ******* s will get looks behind Justin Cryer at MLB and Okpala is likely to occupy a role similar to Brad Spence.
That trio of players are talented enough to make this a relative non-problem. However, LB is not always a position that comes quickly to young players. It's a position largely defined off your experience and knowledge of the game. That's something this trio will have to find early in the season or the Texas LB unit will have to lean on the trio of Biles, Cryer and Spence more than they'd like.
So, how quickly can this group be ready? I'd argue Tyler Atkinson will be a consistent and confident contributor by the Oklahoma game. Before that, he will get reps but might not be ready to fill the role he'll eventually have to. The entire trio needs to find the field consistently against Texas State and UTSA, to speed up the process as much as possible. I would expect the veterans to carry the majority of the weight against Ohio State, simply because of the complexity and intensity that game will contain.
#tyler
2 months ago
Incoming Apple (AAPL) CEO John Ternus will have a tall order to fill when he enters the same chief executive class as outgoing CEO Tim Cook.
And one clever new number compiled by Bank of America ******* yst Wamsi Mohan shows what Ternus is up against: $32 million.
According to Mohan's calculations, Apple's market cap has grown at a rate of roughly $32 million per hour, every hour, for nearly 15 years, for a total of $4.5 trillion under Cook.
Apple's market capitalization has climbed to $4.5 trillion from around $350 billion during Cook's time as CEO, according to Yahoo Finance AlphaSpace ******* ysis.
"Tim Cook took Apple from a company driven by a small number of product cycles into an institution capable of producing growth, cash flow, customer loyalty, and innovation at enormous scale and SKU complexity," Mohan said.
#according

2 months ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Silver (SI=F) September futures opened at $63.43 per ounce on Wednesday, August 19, 2026, down 1% from Tuesday's closing price. The silver price moved higher this morning, reaching $65 as of 8:55 a.m. ET.
Despite signs of strength Wednesday morning, the silver price is down about 9% for the year — after spiking in late January and then dipping into negative territory in March. Catalysts have included ongoing tensions in the Middle East and higher rate hike expectations. While the war in Iran is ongoing, the interest-rate outlook has improved. Silver has not meaningfully appreciated, however.
The metal's industrial applications add complexity to its price drivers relative to gold. As a result, silver tends to be far more volatile. The current gold-to-silver ratio near 68 is in line with the long-term average range of 50 and 80.
The opening price of silver futures on Wednesday, August 19, 2026, was 1% lower compared to Tuesday's closing price. Here's how today's opening silver price has changed versus last week, month, and year:
#silver #closing




