

2 days ago
Comedian Bill Maher called Democratic politicians "cowards" while doubling down on his stance that the Sept. 11, 2001, hijackers were not — a position that infamously led to ABC canceling his show more than two decades ago.
In a segment on HBO's "Real Time with Bill Maher" Friday, the comedian reaffirmed his opinion that "the terrorists weren't cowards" which he initially said after the Sept. 11 terrorist attacks.
"I know a guy whose show got canceled just for saying the terrorists weren't cowards. And that guy was right. They weren't cowards, but I'll tell you who is: Democratic Party politicians," Maher said.
He added that this "moral confusion" within the party is most notable when talking about "a place called Gaza."
"A little strip of land that was not part of the original Israel, but which they won in a war launched against them, but then gave back as a peace gesture," he said.
#cowards #democratic #called #politicians
In a segment on HBO's "Real Time with Bill Maher" Friday, the comedian reaffirmed his opinion that "the terrorists weren't cowards" which he initially said after the Sept. 11 terrorist attacks.
"I know a guy whose show got canceled just for saying the terrorists weren't cowards. And that guy was right. They weren't cowards, but I'll tell you who is: Democratic Party politicians," Maher said.
He added that this "moral confusion" within the party is most notable when talking about "a place called Gaza."
"A little strip of land that was not part of the original Israel, but which they won in a war launched against them, but then gave back as a peace gesture," he said.
#cowards #democratic #called #politicians


3 days ago
James Rodríguez's arrival at Atlético Nacional continues to draw major reactions in Colombian football. This time, the club's legendary former goalkeeper and idol, René Higuita, dedicated an emotional welcome message to him, full of affection and verdolaga mystique.
Through his words, the iconic goalkeeper highlighted the institutional weight of the jersey the midfielder from Cúcuta will wear. "This jersey has history, it has heart, and it has fans who are always with us. We love you, welcome to our beloved Atlético Nacional," the former player said.
Higuita ended his greeting by wishing the Colombia national team midfielder the greatest success in this new stage of his professional career: "May the victories come, my brother. Welcome to green," he concluded, reaffirming the enormous excitement this signing has generated among Antioquia's fans.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#tico #fans
Through his words, the iconic goalkeeper highlighted the institutional weight of the jersey the midfielder from Cúcuta will wear. "This jersey has history, it has heart, and it has fans who are always with us. We love you, welcome to our beloved Atlético Nacional," the former player said.
Higuita ended his greeting by wishing the Colombia national team midfielder the greatest success in this new stage of his professional career: "May the victories come, my brother. Welcome to green," he concluded, reaffirming the enormous excitement this signing has generated among Antioquia's fans.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#tico #fans


3 days ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
3 days ago
Updated Sept 11, 2026, 1:55 pm EDT / Original Sept 11, 2026, 7:30 am EDT
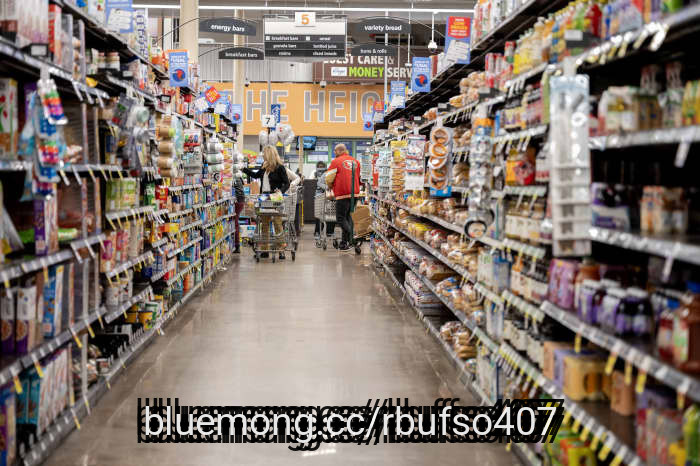
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare
The grocery giant now expects same-store sales excluding fuel to rise between 0.2% and 0.8% for the fiscal year, down from a prior range of 1% to 2% growth. The new guidance includes a hit of roughly 140 basis points tied to the Inflation Reduction Act, which lowered prescription drug prices for Medicare beneficiaries and impacted pharmacy revenue. Management separately reaffirmed its earnings guidance of $5.10 to $5.30 a share for the fiscal year.
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#inflation #medicare

4 days ago
Renowned Argentine journalist and influencer Flavio Azzaro has once again shaken up the world of sports media after openly stating his greatest institutional ambition: to become president of Racing Club.
During a live broadcast on his Azz Stream channel, the commentator expressed how firmly he views this life goal. "Everything I do in my life, consciously or unconsciously, is to become president of Racing," he stated categorically.
The statements from the Avellaneda journalist reaffirm his ambition to jump from media debate into the internal politics of "La Academia." The idea is for him to be able to run in the 2032 elections.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#journalist #argentine
During a live broadcast on his Azz Stream channel, the commentator expressed how firmly he views this life goal. "Everything I do in my life, consciously or unconsciously, is to become president of Racing," he stated categorically.
The statements from the Avellaneda journalist reaffirm his ambition to jump from media debate into the internal politics of "La Academia." The idea is for him to be able to run in the 2032 elections.
This article was translated into English by Artificial Intelligence. You can read the original version in 🇪🇸 here.
#journalist #argentine


4 days ago
Prince Harry is wasting no time stepping back into the spotlight since returning to England.
Harry, 41, has unveiled a busy schedule of appearances in Britain and the U.S., according to a People report published Friday, September 11. The news comes just days after King Charles III made clear that Harry and his wife, Meghan Markle, remain non-working royals whose charitable activities are carried out privately — a position sources close to the Sussexes have challenged.
"Members of the public know who they are. The idea that they can live a normal, 'private' life is sadly not realistic," an insider said, per the outlet.
Mirrorpix / MEGA
Issues arose shortly after Harry and Meghan, 45, returned to Britain with their children Prince Archie, 7, and Princess Lilibet, 5. Charles, 77, authorized guidance reaffirming that the couple's decision to step away from royal duties in 2020 remains in effect despite their move back to the U.K.
#harry #people
Harry, 41, has unveiled a busy schedule of appearances in Britain and the U.S., according to a People report published Friday, September 11. The news comes just days after King Charles III made clear that Harry and his wife, Meghan Markle, remain non-working royals whose charitable activities are carried out privately — a position sources close to the Sussexes have challenged.
"Members of the public know who they are. The idea that they can live a normal, 'private' life is sadly not realistic," an insider said, per the outlet.
Mirrorpix / MEGA
Issues arose shortly after Harry and Meghan, 45, returned to Britain with their children Prince Archie, 7, and Princess Lilibet, 5. Charles, 77, authorized guidance reaffirming that the couple's decision to step away from royal duties in 2020 remains in effect despite their move back to the U.K.
#harry #people



5 days ago
On August 27, AstraZeneca PLC (NYSE:AZN) and Amgen Inc. (NASDAQ:AMGN) scored a shared clinical victory. Positive high-level results from the Phase III CROSSING trial showed that their co-developed severe asthma drug, TEZSPIRE, achieved statistically significant and clinically meaningful improvements across both co-primary endpoints, histologic remission and the frequency/severity of dysphagia, and all key secondary endpoints at week 24 in patients with eosinophilic esophagitis. These benefits were sustained through week 52 across both tested doses, accompanied by a safety profile consistent with its approved indications. While CROSSING highlights their joint R&D success, a closer look at their standalone financial performance reveals distinct growth trajectories.
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products

5 days ago
The pharmaceutical sector was hit with major pipeline news on September 1 when Novartis AG (NYSE:NVS) paused eight clinical trials of rap-cel, its experimental CAR-T cell therapy targeting autoimmune and neurological disorders. The suspension, effective August 24, followed three patient deaths caused by severe, life-threatening immune reactions (immune effector cell-associated hemophagocytic syndrome). Novartis is currently conducting a safety review alongside independent monitoring boards. Following the news, Bristol-Myers Squibb Company (NYSE:BMY) voluntarily paused trials for its competing CAR-T treatment, zola-cel, as a precautionary measure after detecting transient inflammatory side effects.
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis


5 days ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year

5 days ago
All major indices closed sharply lower Tuesday as Brent Crude surged near $99 and looming PPI and CPI readings raised fears of a Fed rate hike.
Qualcomm earned a Strong Buy upgrade at CFRA while Wells Fargo downgraded Eagle Materials and slashed Vulcan Materials' target to $254 from $305.
Robinhood Markets and Affirm Holdings received fresh Buy initiations with $170 and $105 targets from StoneX and Loop Capital, respectively.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Thermo Fisher Scientific didn't make the cut. Enter your email to see the names that beat TMO. The report is free. Enter your email and see if any of your stocks made the cut.
Futures are trading lower after a rough start to the holiday-shortened trading week. All the major indices finished the day sharply lower on rising oil prices and two huge inflation readings on deck: the producer price index on Thursday and the consumer price index on Friday. If both come in above expectations, you can count on an interest rate hike next week when the Federal Reserve governors meet. The venerable Dow Jones Industrial Average took the biggest shot, closing down 1.18% at 52,786, while the S&P 500 finished the session at 7,673, down 0.58%. The Russell 2000 fell 0.52% to 2,960, while the tech-heavy Nasdaq finished the day at 26,421, down 0.32%. With market-moving data on the way and sentiment falling, this could be a tough week for investors as we could catch some September blues.
#week
Qualcomm earned a Strong Buy upgrade at CFRA while Wells Fargo downgraded Eagle Materials and slashed Vulcan Materials' target to $254 from $305.
Robinhood Markets and Affirm Holdings received fresh Buy initiations with $170 and $105 targets from StoneX and Loop Capital, respectively.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Thermo Fisher Scientific didn't make the cut. Enter your email to see the names that beat TMO. The report is free. Enter your email and see if any of your stocks made the cut.
Futures are trading lower after a rough start to the holiday-shortened trading week. All the major indices finished the day sharply lower on rising oil prices and two huge inflation readings on deck: the producer price index on Thursday and the consumer price index on Friday. If both come in above expectations, you can count on an interest rate hike next week when the Federal Reserve governors meet. The venerable Dow Jones Industrial Average took the biggest shot, closing down 1.18% at 52,786, while the S&P 500 finished the session at 7,673, down 0.58%. The Russell 2000 fell 0.52% to 2,960, while the tech-heavy Nasdaq finished the day at 26,421, down 0.32%. With market-moving data on the way and sentiment falling, this could be a tough week for investors as we could catch some September blues.
#week

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
6 days ago
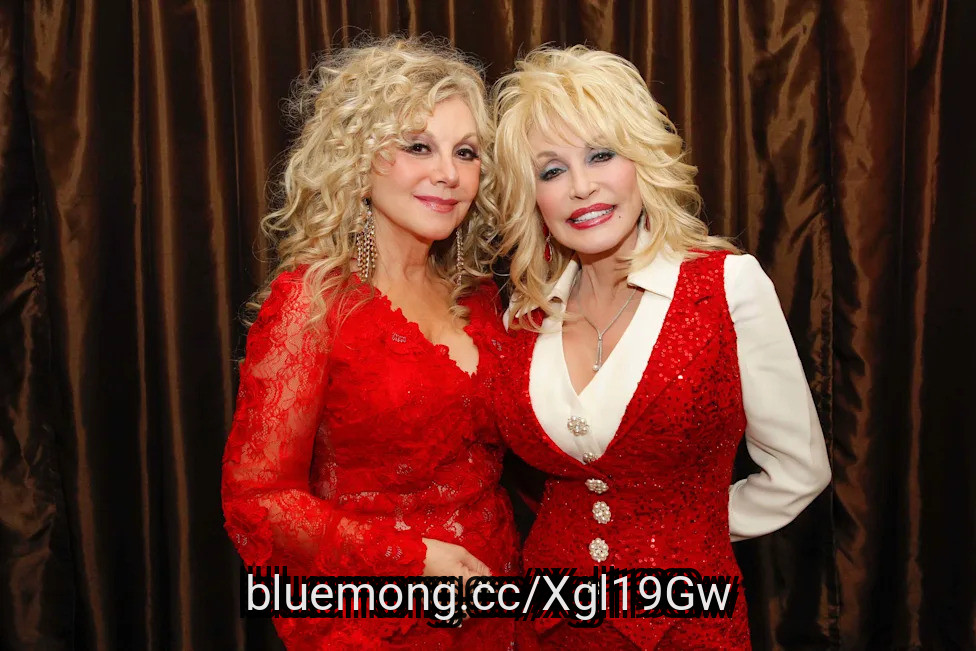
Dolly Parton's younger sister, Stella Parton, 77, says that she knew what the country singer—famous for her high-glam, Southern belle aesthetic—looked like without makeup.
"She looked like me without makeup," Stella joked during an interview with Gayle King on CBS Mornings.
The quotes come just over two weeks after Dolly's death at age 80 following a "brief battle with cancer."
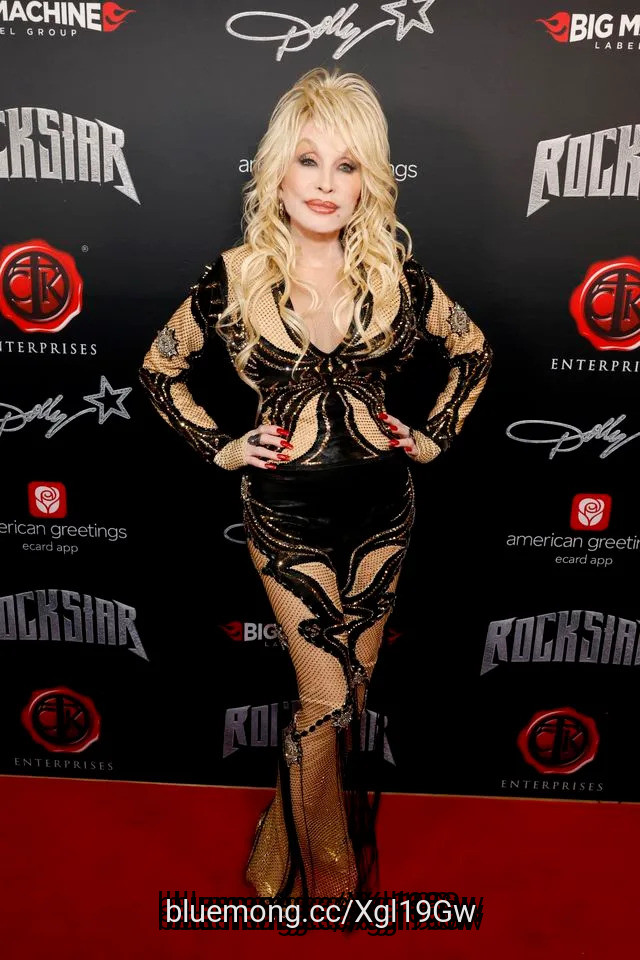
When it came to fashion and beauty, Dolly Parton affirmed that more is more.
Throughout her seven-decade music career, the country singer achieved beauty icon status with her sky-high platinum-blonde hair and high-glam makeup. As such, Dolly would rarely be caught without makeup on—even in front of those closest to her.
#stella #parton
"She looked like me without makeup," Stella joked during an interview with Gayle King on CBS Mornings.
The quotes come just over two weeks after Dolly's death at age 80 following a "brief battle with cancer."
When it came to fashion and beauty, Dolly Parton affirmed that more is more.
Throughout her seven-decade music career, the country singer achieved beauty icon status with her sky-high platinum-blonde hair and high-glam makeup. As such, Dolly would rarely be caught without makeup on—even in front of those closest to her.
#stella #parton
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

6 days ago
A federal appeals court ruled that a Texas woman can't sue two Santa Fe police officers who pinned her face down on a fire ant hill while she was handcuffed, causing her to receive hundreds of painful bites to her face.
In an August 6 opinion, a three-judge panel of the U.S. Court of Appeals for the 5th Circuit reversed a lower court decision allowing Taylor Rogers' lawsuit against the City of Santa Fe and the two officers to move forward. Instead, the panel held that the officers were shielded from her claims under the doctrine of qualified immunity.
In a press conference last Friday, Rogers' attorney, Randy Kallinen, criticized the ruling.
"The United States 5th Circuit Court of Appeals is out of touch with the Constitution and the public, granting police immunity in the most egregious of cases," Kallinen said. "The people need to elect officials who will nominate and affirm judges loyal to the Constitution."
Kallinen told The Daily News that he has requested an en banc hearing for the full 15-member 5th Circuit to review the case, and he'll petition the Supreme Court for review if that fails.
#kallinen #santa #constitution #police
In an August 6 opinion, a three-judge panel of the U.S. Court of Appeals for the 5th Circuit reversed a lower court decision allowing Taylor Rogers' lawsuit against the City of Santa Fe and the two officers to move forward. Instead, the panel held that the officers were shielded from her claims under the doctrine of qualified immunity.
In a press conference last Friday, Rogers' attorney, Randy Kallinen, criticized the ruling.
"The United States 5th Circuit Court of Appeals is out of touch with the Constitution and the public, granting police immunity in the most egregious of cases," Kallinen said. "The people need to elect officials who will nominate and affirm judges loyal to the Constitution."
Kallinen told The Daily News that he has requested an en banc hearing for the full 15-member 5th Circuit to review the case, and he'll petition the Supreme Court for review if that fails.
#kallinen #santa #constitution #police

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

8 days ago
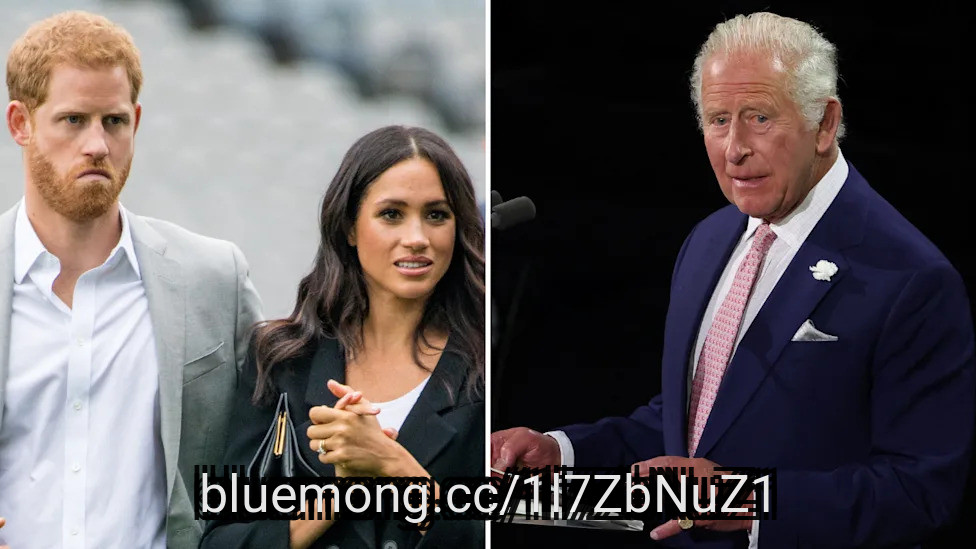
Prince Harry and Meghan Markle had little warning before King Charles III publicly clarified in a letter to government officials that their royal status would remain unchanged.
On Tuesday, September 8, the day after the letter was released, a spokesperson for Harry, 41, and Meghan, 45, told the BBC that they "were a little surprised not to have been told about this in advance."
As In Touch previously reported, the unusual missive followed the couple's move back to Britain with their two children, Prince Archie, 7, and Princess Lilibet, 5, marking their return after six years in California.
James Whatling / MEGA
"To help avoid doubt or confusion, the King has directed that the following information be shared," the letter, issued on September 7 by Lord Chamberlain Richard Benyon, stated (per The Guardian), reaffirming the arrangement established when Harry, 41, and Meghan, 45, stepped back as working royals in 2020.
#told
On Tuesday, September 8, the day after the letter was released, a spokesperson for Harry, 41, and Meghan, 45, told the BBC that they "were a little surprised not to have been told about this in advance."
As In Touch previously reported, the unusual missive followed the couple's move back to Britain with their two children, Prince Archie, 7, and Princess Lilibet, 5, marking their return after six years in California.
James Whatling / MEGA
"To help avoid doubt or confusion, the King has directed that the following information be shared," the letter, issued on September 7 by Lord Chamberlain Richard Benyon, stated (per The Guardian), reaffirming the arrangement established when Harry, 41, and Meghan, 45, stepped back as working royals in 2020.
#told


8 days ago
Reuters reported that Solstice Advanced Materials, Inc. (NASDAQ:SOLS) and Element Solutions Inc (NYSE:ESI) mutually agreed to terminate their $14.5 billion merger agreement, the companies said on August 27, citing feedback from shareholders on both sides who preferred each to stay independent. Neither side will pay a termination fee.
Solstice Chairman Rajeev Gautam said the company valued that feedback, including shareholders' "excitement about Solstice's strategy and growth trajectory as an independent company." Solstice's board also authorized its first-ever buyback, up to $500 million, and reaffirmed its recently raised guidance. Solstice shares jumped 15% in after-hours trading, while Element gained 4%. The deal, announced July 6 just 10 months after Solstice's Honeywell spin-off, would have combined Solstice's refrigerants and specialty materials businesses with Element's electronics chemicals operations, paying Element holders $10 cash plus 0.5 Solstice shares per share. The original announcement got a rough welcome: Solstice fell nearly 15% that day, which CEO David Sewell blamed on arbitrage trading, not doubts about the deal.
Both companies continue to perform strongly on their own. Solstice's second-quarter net sales rose 11% to $1.148 billion, and the company raised its full-year sales guidance to $4.125 billion-$4.185 billion. Element delivered an even stronger quarter, with record net sales up 56% to $978 million and full-year adjusted EBITDA guidance raised to $690 million-$710 million.
Solstice Advanced Materials, Inc. (NASDAQ:SOLS) sheds significant deal risk by walking away. The termination removes the financing and merger risks linked to the acquisition and eliminates the need to use the $4.685 billion bridge facility. It also lets Solstice maintain its 1.3x net leverage. Its new $500 million buyback, the company's first ever, also gives Solstice a direct way to return capital to shareholders while it focuses on organic growth.
Element Solutions Inc (NYSE:ESI) also maintains the strengths that its shareholders wanted to preserve. Chairman Ian Ashken said investors valued Element's management team, culture, and existing business portfolio. CEO Benjamin Gliklich said the company's growth remains compelling. Remaining independent allows Element to continue investing in its existing businesses and pursuing its own growth strategy without taking on the risks of a larger combination.
#billion #million #Growth
Solstice Chairman Rajeev Gautam said the company valued that feedback, including shareholders' "excitement about Solstice's strategy and growth trajectory as an independent company." Solstice's board also authorized its first-ever buyback, up to $500 million, and reaffirmed its recently raised guidance. Solstice shares jumped 15% in after-hours trading, while Element gained 4%. The deal, announced July 6 just 10 months after Solstice's Honeywell spin-off, would have combined Solstice's refrigerants and specialty materials businesses with Element's electronics chemicals operations, paying Element holders $10 cash plus 0.5 Solstice shares per share. The original announcement got a rough welcome: Solstice fell nearly 15% that day, which CEO David Sewell blamed on arbitrage trading, not doubts about the deal.
Both companies continue to perform strongly on their own. Solstice's second-quarter net sales rose 11% to $1.148 billion, and the company raised its full-year sales guidance to $4.125 billion-$4.185 billion. Element delivered an even stronger quarter, with record net sales up 56% to $978 million and full-year adjusted EBITDA guidance raised to $690 million-$710 million.
Solstice Advanced Materials, Inc. (NASDAQ:SOLS) sheds significant deal risk by walking away. The termination removes the financing and merger risks linked to the acquisition and eliminates the need to use the $4.685 billion bridge facility. It also lets Solstice maintain its 1.3x net leverage. Its new $500 million buyback, the company's first ever, also gives Solstice a direct way to return capital to shareholders while it focuses on organic growth.
Element Solutions Inc (NYSE:ESI) also maintains the strengths that its shareholders wanted to preserve. Chairman Ian Ashken said investors valued Element's management team, culture, and existing business portfolio. CEO Benjamin Gliklich said the company's growth remains compelling. Remaining independent allows Element to continue investing in its existing businesses and pursuing its own growth strategy without taking on the risks of a larger combination.
#billion #million #Growth

9 days ago
King Charles' new guidance reiterates that Prince Harry and Meghan Markle's "His and Her Royal Highness" styles remain in abeyance and are not used
Harry and Meghan retained their HRH styles after stepping back as working royals in 2020, but agreed they would no longer use them publicly
The clarification comes after a "number of requests" for guidance following the Duke and **** ss of Sussex's return to the U.K.
Prince Harry and Meghan Markle's return to the U.K. isn't changing their royal **** les — or the important distinction in how they use them.
In new guidance issued at King Charles' direction following the Duke and **** ss of Sussex's move back to Britain, the couple are repeatedly referred to by their Sussex **** les, reaffirming the **** les they have held since their 2018 wedding.
#meghan #prince
Harry and Meghan retained their HRH styles after stepping back as working royals in 2020, but agreed they would no longer use them publicly
The clarification comes after a "number of requests" for guidance following the Duke and **** ss of Sussex's return to the U.K.
Prince Harry and Meghan Markle's return to the U.K. isn't changing their royal **** les — or the important distinction in how they use them.
In new guidance issued at King Charles' direction following the Duke and **** ss of Sussex's move back to Britain, the couple are repeatedly referred to by their Sussex **** les, reaffirming the **** les they have held since their 2018 wedding.
#meghan #prince



9 days ago
A B Graphic International (ABG) has renamed Enprom Solutions as ABG Girona, as part of the continued integration of its Spain-based operation into the wider group.
The move follows the 2019 acquisition of the business by ABG and Kocher+Beck and affirms the site as the group's centre of excellence for flexible packaging.
Based in Girona, the operation designs and builds machinery, converting systems, sleeve products and automated production lines for the flexible packaging and label sectors.
Within the ABG group, the Girona business is set to take on a larger role in flexible packaging work, including the FlexPack range.
The name change is intended to clarify the Girona operation's position within the group for customers while retaining the technical knowledge developed by the existing team.
#packaging #based #business #international
The move follows the 2019 acquisition of the business by ABG and Kocher+Beck and affirms the site as the group's centre of excellence for flexible packaging.
Based in Girona, the operation designs and builds machinery, converting systems, sleeve products and automated production lines for the flexible packaging and label sectors.
Within the ABG group, the Girona business is set to take on a larger role in flexible packaging work, including the FlexPack range.
The name change is intended to clarify the Girona operation's position within the group for customers while retaining the technical knowledge developed by the existing team.
#packaging #based #business #international

10 days ago
On August 5, Southwest Gas Holdings (NYSE:SWX) reported second quarter results for the period ended June 30 and reaffirmed its full year 2026 guidance. Net income attributable to the company reached $42.1 million, a sharp turnaround from a $40.2 million loss in the same quarter of 2025. But the number that stood out was the Great Basin 2028 Expansion Project, where contracted demand has grown enough that management now expects capital costs of $2.3 billion instead of the $1.7 billion baked into current five year guidance.
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin
Southwest Gas's growth story increasingly runs through Nevada. Binding precedent agreements for the Great Basin 2028 Expansion Project have grown to roughly 1 billion cubic feet per day of contracted demand, and the company has fielded another 1.8 billion cubic feet of expressions of interest for phases running from 2029 through 2035. Based on that demand, management now projects an annual margin of $270 million to $300 million once the pipeline is in service, on capital investment of about $2.3 billion.
Regulators have been cooperating too. California's Public Utilities Commission approved the non-cost-of-capital pieces of Southwest Gas's rate case, adding roughly $40 million of incremental annual revenue and triggering recognition of $9.7 million of previously deferred first-quarter income. Nevada regulators approved a Triennial Resource Plan with prudency pre-determinations for about $186 million of capital spending, and the company filed for a general rate case increase of roughly $74 million.
Arizona's new System Integrity Mechanism, effective April 1 this year, lets Southwest Gas recover safety and reliability spending faster, up to a $50 million annual cap. The company put $520 million into its network in the first six months of 2026, including $115 million toward Great Basin, and closed the quarter with $270.5 million in cash and nearly $1 billion in available liquidity.
Look past the headline swing to profit, and the picture gets murkier. The core natural gas distribution segment actually earned less this quarter, with its contribution to net income falling from $45.6 million a year earlier to $40.8 million, and its adjusted net income slipping from $33.7 million to $31 million. Depreciation and amortization rose $8.7 million, or 13%, as gas plant in service grew 7% year over year, a reminder that heavy pipeline spending shows up in expenses well before it shows up in rates.
#million #company #basin


12 days ago
On September 1, Rezolve AI (NASDAQ:RZLV) reported first-half revenue of $130.8 million, up from just $6.3 million a year earlier, a jump of roughly 1,970%. The AI commerce and payments company also said its enterprise customer base grew to 1,640 accounts. Numbers like that demand attention, but the same report showed losses widening even faster than sales. Here's what's really going on underneath the headline growth rate.
Rezolve's enterprise base grew from 950 customers at the end of the prior fiscal year to 1,640 by June 30, and management is leaning on partnerships with Microsoft, Google, Tata Consultancy Services, and Tech Mahindra to keep that pipeline filling without building out its own global sales force. That distribution strategy got a notable vote of confidence after the quarter closed: Google selected Rezolve's proprietary distributed database technology following a technical evaluation of 24 competing companies, and the system is now indexing roughly 100 terabytes of data across 10 blockchain networks inside Google Cloud's infrastructure.
The platform also proved it can handle real traffic. During the FIFA 2026 World Cup measurement window from June 1 through July 31, Rezolve's technology logged about 103 million app opens from 9.86 million unique devices across 16 stadiums, along with 5.84 million geofence events. On the loyalty and payments side, the recently completed acquisition of Reward Loyalty expanded Rezolve's footprint to more than 15 markets, and a partnership with Zilch now touches almost 6 million customers, driving over $3.3 billion a year to partner merchants. Management reaffirmed guidance for approximately $360 million in full-year 2026 revenue, implying second-half sales near $229 million, and reiterated a target of at least $500 million in annual recurring revenue by year-end.
Growth this fast has come at a steep price. Rezolve's operating loss widened to $128.1 million in the first half of 2026, compared with $32.4 million a year earlier, and net loss grew to $139.5 million from $57.9 million. Some of that reflects noncash items, including $41.5 million in share-based compensation and $20.4 million in depreciation and amortization, but cash is also going out the door faster. Net cash used in operating activities jumped to $96.1 million from $19.8 million in the prior-year period, and investing activities consumed another $148.3 million, largely tied to acquisitions and platform development.
#million #revenue #grew #june
Rezolve's enterprise base grew from 950 customers at the end of the prior fiscal year to 1,640 by June 30, and management is leaning on partnerships with Microsoft, Google, Tata Consultancy Services, and Tech Mahindra to keep that pipeline filling without building out its own global sales force. That distribution strategy got a notable vote of confidence after the quarter closed: Google selected Rezolve's proprietary distributed database technology following a technical evaluation of 24 competing companies, and the system is now indexing roughly 100 terabytes of data across 10 blockchain networks inside Google Cloud's infrastructure.
The platform also proved it can handle real traffic. During the FIFA 2026 World Cup measurement window from June 1 through July 31, Rezolve's technology logged about 103 million app opens from 9.86 million unique devices across 16 stadiums, along with 5.84 million geofence events. On the loyalty and payments side, the recently completed acquisition of Reward Loyalty expanded Rezolve's footprint to more than 15 markets, and a partnership with Zilch now touches almost 6 million customers, driving over $3.3 billion a year to partner merchants. Management reaffirmed guidance for approximately $360 million in full-year 2026 revenue, implying second-half sales near $229 million, and reiterated a target of at least $500 million in annual recurring revenue by year-end.
Growth this fast has come at a steep price. Rezolve's operating loss widened to $128.1 million in the first half of 2026, compared with $32.4 million a year earlier, and net loss grew to $139.5 million from $57.9 million. Some of that reflects noncash items, including $41.5 million in share-based compensation and $20.4 million in depreciation and amortization, but cash is also going out the door faster. Net cash used in operating activities jumped to $96.1 million from $19.8 million in the prior-year period, and investing activities consumed another $148.3 million, largely tied to acquisitions and platform development.
#million #revenue #grew #june


12 days ago
Interested in Daktronics, Inc.? Here are five stocks we like better.
Daktronics delivered a strong fiscal Q1: Revenue rose 7.1% year over year, operating income increased 7.2% to $24.9 million, and EPS climbed 21.2% to $0.40, the company's highest quarterly EPS in three years. Gross margin expanded 80 basis points to 30.5%.
Demand remains solid despite lower bookings: Backlog stood at $311 million, exceeding $300 million for the sixth consecutive quarter. Management attributed weaker bookings primarily to project timing and expects several substantial purchase orders later in Q2, with revenue contributions beginning mostly in Q3.
The company is investing while managing cost pressures: Daktronics plans to increase annual capital expenditures to about $20 million for automation and manufacturing capacity, while implementing price increases and procurement savings to offset rising input costs. It reaffirmed fiscal 2028 targets for 7%–10% revenue CAGR, 10%–12% operating margins and 17%–20% ROIC.
This Is Why Daktronics Fell 40% In One Day
#revenue
Daktronics delivered a strong fiscal Q1: Revenue rose 7.1% year over year, operating income increased 7.2% to $24.9 million, and EPS climbed 21.2% to $0.40, the company's highest quarterly EPS in three years. Gross margin expanded 80 basis points to 30.5%.
Demand remains solid despite lower bookings: Backlog stood at $311 million, exceeding $300 million for the sixth consecutive quarter. Management attributed weaker bookings primarily to project timing and expects several substantial purchase orders later in Q2, with revenue contributions beginning mostly in Q3.
The company is investing while managing cost pressures: Daktronics plans to increase annual capital expenditures to about $20 million for automation and manufacturing capacity, while implementing price increases and procurement savings to offset rising input costs. It reaffirmed fiscal 2028 targets for 7%–10% revenue CAGR, 10%–12% operating margins and 17%–20% ROIC.
This Is Why Daktronics Fell 40% In One Day
#revenue


13 days ago
Vikings' J.J. McCarthy decision changes meaning of his former franchise-QB label originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
The Minnesota Vikings insist they have not given up on J.J. McCarthy. Their depth chart tells a more complicated story.
Minnesota general manager Nolan Teasley reaffirmed the organization's belief in McCarthy this week and said he expects the former first-round pick to remain with the Vikings. McCarthy currently projects behind Kyler Murray and Carson Wentz after another injury-disrupted offseason, according to the New York Post.
That is an extraordinary position for a quarterback selected 10th overall only two years ago. It does not necessarily mean his opportunity has ended.
Minnesota originally drafted McCarthy as its possible long-term answer. A torn meniscus erased his rookie season before it began. Ankle and concussion issues then limited him to 10 games last year, preventing the Vikings from receiving a clean evaluation of his development.
#Vikings #former #preferred #teasley
The Minnesota Vikings insist they have not given up on J.J. McCarthy. Their depth chart tells a more complicated story.
Minnesota general manager Nolan Teasley reaffirmed the organization's belief in McCarthy this week and said he expects the former first-round pick to remain with the Vikings. McCarthy currently projects behind Kyler Murray and Carson Wentz after another injury-disrupted offseason, according to the New York Post.
That is an extraordinary position for a quarterback selected 10th overall only two years ago. It does not necessarily mean his opportunity has ended.
Minnesota originally drafted McCarthy as its possible long-term answer. A torn meniscus erased his rookie season before it began. Ankle and concussion issues then limited him to 10 games last year, preventing the Vikings from receiving a clean evaluation of his development.
#Vikings #former #preferred #teasley


13 days ago
Affirm Holdings (AFRM) just handed Wall Street a quarter that was hard to argue with, and Bank of America came away more bullish than before.
The buy now, pay later company reported record fiscal fourth-quarter results in late August, and its shares jumped on the news.
Now BofA is telling clients the market still hasn't priced in what could come next.
The bank raised its 12-month price target on Affirm to $104 from $93 while keeping its Buy rating. That's a call that points to roughly 34% to 35% upside from where the stock traded after earnings.
BofA **** yst Matthew O'Neill lifted the target after Affirm's fiscal Q4 2026 report, and his reasoning starts with the company's own forecast.
#affirm #quarter #holdings #street
The buy now, pay later company reported record fiscal fourth-quarter results in late August, and its shares jumped on the news.
Now BofA is telling clients the market still hasn't priced in what could come next.
The bank raised its 12-month price target on Affirm to $104 from $93 while keeping its Buy rating. That's a call that points to roughly 34% to 35% upside from where the stock traded after earnings.
BofA **** yst Matthew O'Neill lifted the target after Affirm's fiscal Q4 2026 report, and his reasoning starts with the company's own forecast.
#affirm #quarter #holdings #street

13 days ago
On August 21, Martin Marietta Materials (NYSE:MLM) completed its combination with Lhoist North America, a subsidiary of Lhoist Group and one of the country's leading producers of lime and industrial mineral products. The deal hands Martin Marietta more than 2 billion tons of high-quality limestone reserves and, according to the company, makes it the nation's leading producer of limestone products. It caps months of dealmaking that has quietly reshaped what kind of company Martin Marietta is becoming.
Lhoist North America serves steel manufacturing, infrastructure, heavy nonresidential construction and environmental solutions, markets Martin Marietta says it can now reach through a shared limestone base. Company leadership has pointed to lime's mission-critical role in steel production and water treatment, businesses that lean on Martin Marietta's expanding Specialties platform. In the second quarter, that platform delivered $152 million in revenue and $50 million in gross profit, both records, aided by the July 2025 Premier Magnesia acquisition and organic pricing gains. One example the company highlighted: its Woodville lime plant saw shipments exceed 2006 levels by 2% even as broader U.S. aggregates production stayed 25% below its prior peak, a sign of how differently lime demand behaves through a downturn.
The core aggregates business is not standing still either. Second-quarter revenue there hit $1.5 billion, up 16%, while total shipments rose 17% to 61.6 million tons on acquisitions and organic growth in the Central and West divisions. Organic shipments alone grew 2.3%, the fourth straight quarter of gains. Management raised full-year revenue guidance to a range of $7.2 billion to $7.4 billion to reflect the New Frontier Materials acquisition, while reaffirming adjusted EBITDA guidance of $2.36 billion to $2.5 billion. Data center activity in company-served markets climbed 90% year to date, warehouse construction rose 53%, and 70% of under-construction data center and manufacturing square footage sits within 55 miles of a Martin Marietta facility.
Growth has not come free. Average selling prices fell 2% on a headline basis in the second quarter, even though they rose 3.7% once adjusted for geographic mix, a gap that shows how much the picture depends on how you slice it. Reported aggregate gross profit of $418 million absorbed a $52 million noncash inventory step-up charge tied to purchase accounting, and organic cost of goods sold per ton rose 3.6%, including a 150 basis point hit from higher pass-through freight costs.
#billion
Lhoist North America serves steel manufacturing, infrastructure, heavy nonresidential construction and environmental solutions, markets Martin Marietta says it can now reach through a shared limestone base. Company leadership has pointed to lime's mission-critical role in steel production and water treatment, businesses that lean on Martin Marietta's expanding Specialties platform. In the second quarter, that platform delivered $152 million in revenue and $50 million in gross profit, both records, aided by the July 2025 Premier Magnesia acquisition and organic pricing gains. One example the company highlighted: its Woodville lime plant saw shipments exceed 2006 levels by 2% even as broader U.S. aggregates production stayed 25% below its prior peak, a sign of how differently lime demand behaves through a downturn.
The core aggregates business is not standing still either. Second-quarter revenue there hit $1.5 billion, up 16%, while total shipments rose 17% to 61.6 million tons on acquisitions and organic growth in the Central and West divisions. Organic shipments alone grew 2.3%, the fourth straight quarter of gains. Management raised full-year revenue guidance to a range of $7.2 billion to $7.4 billion to reflect the New Frontier Materials acquisition, while reaffirming adjusted EBITDA guidance of $2.36 billion to $2.5 billion. Data center activity in company-served markets climbed 90% year to date, warehouse construction rose 53%, and 70% of under-construction data center and manufacturing square footage sits within 55 miles of a Martin Marietta facility.
Growth has not come free. Average selling prices fell 2% on a headline basis in the second quarter, even though they rose 3.7% once adjusted for geographic mix, a gap that shows how much the picture depends on how you slice it. Reported aggregate gross profit of $418 million absorbed a $52 million noncash inventory step-up charge tied to purchase accounting, and organic cost of goods sold per ton rose 3.6%, including a 150 basis point hit from higher pass-through freight costs.
#billion

13 days ago
When the 2025-26 Spurs season tipped off last fall, ***** ody knew who the Jackals were. But that all changed over the following months as the Victor Wembanyama-founded fan section went viral for their over-the-top energy, hilarious signs and memorable moments. This season will be no different, except for the fact that everyone knows who they are - and everyone wants in.
But not everyone will be allowed in the Frost Bank Center's sections 114 and 115 for the 2026-27 season, the Jackals said on social media. Auditions for the upcoming season, which will take place on September 19 and add 100 members, require an 18+ age limit. The sign-up form on the Spurs website requires Jackal hopefuls to check a box affirming they are 18 or older before they can RSVP for auditions.
One social media user asked the fan section on X what was behind the decision to "raise the age limit and force kids out of the program? Just don't quite understand that."
"It was a tough choice for sure, we love our kid Jackals, but as the Jackals have and will continue to grow, the atmosphere will become more intense, with constant standing, chanting, and coordinated movement and support," the fan club explained in a post on X. "After evaluating the past season, we feel an 18+ environment is the best fit for the direction of the section."
Not everyone seems to be happy with that change. Paul Salazar, who was an inaugural Jackal along with his son, said on Instagram that he felt "that PJ was one of the Best Jackals that showed up every night and gave it his all! never complaining about standing not one time!"
#best #Media
But not everyone will be allowed in the Frost Bank Center's sections 114 and 115 for the 2026-27 season, the Jackals said on social media. Auditions for the upcoming season, which will take place on September 19 and add 100 members, require an 18+ age limit. The sign-up form on the Spurs website requires Jackal hopefuls to check a box affirming they are 18 or older before they can RSVP for auditions.
One social media user asked the fan section on X what was behind the decision to "raise the age limit and force kids out of the program? Just don't quite understand that."
"It was a tough choice for sure, we love our kid Jackals, but as the Jackals have and will continue to grow, the atmosphere will become more intense, with constant standing, chanting, and coordinated movement and support," the fan club explained in a post on X. "After evaluating the past season, we feel an 18+ environment is the best fit for the direction of the section."
Not everyone seems to be happy with that change. Paul Salazar, who was an inaugural Jackal along with his son, said on Instagram that he felt "that PJ was one of the Best Jackals that showed up every night and gave it his all! never complaining about standing not one time!"
#best #Media
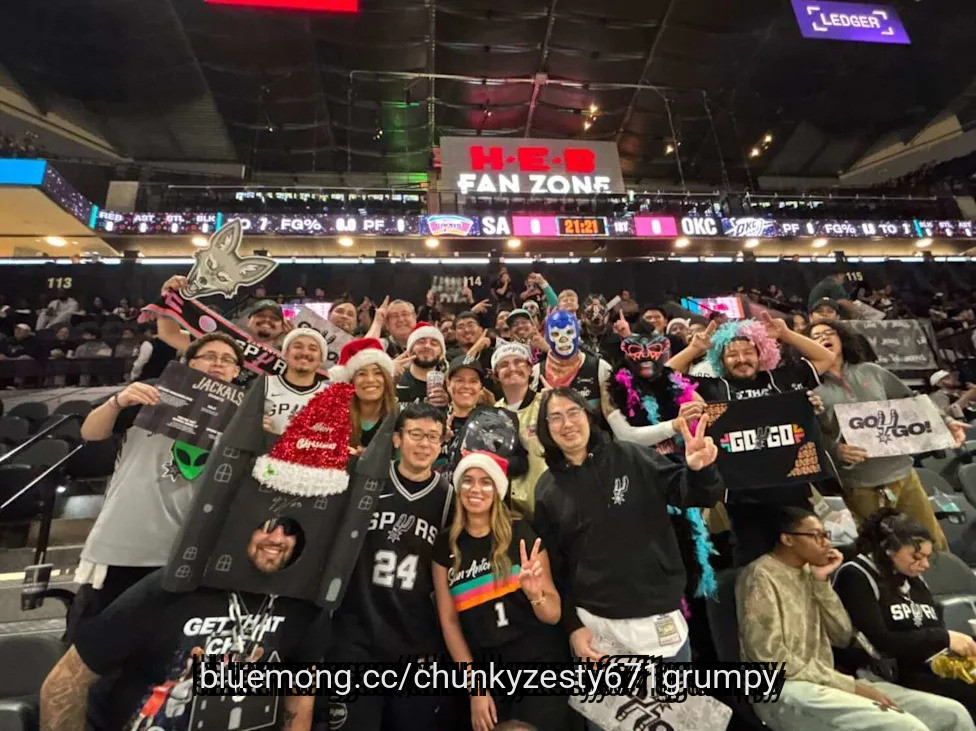
14 days ago
As Big Tech continues to spend aggressively on artificial intelligence, one Wall Street firm believes there is a clear winner when it comes to return on invested capital (ROIC). On August 31, Piper Sandler reiterated an Overweight rating on Amazon (NASDAQ:AMZN) with a $320.00 price target.
According to the firm, AMZN's return on invested capital is holding up far better than giants Meta Platforms, Inc. (NASDAQ: META) and Alphabet Inc. (NASDAQ:GOOGL). Interestingly, the firm projects this ROIC figure to fall from about 17% in 2018-2025 to about 14% in 2026.
Piper's note states the obvious: Amazon spending is more focused on AWS. Revenue for AWS jumped 37% year-over-year to $42.2 billion in Q2, the fastest growth it has had in four years. Meanwhile, AWS contract backlogs at the end of the quarter stood at $496 billion, up from $364 billion in the prior three-month period.
The bull case for Amazon lies in its ROIC, the figure Piper sees deteriorating the least amongst Meta, Alphabet, and Amazon. The note affirms that Amazon is the best-positioned amongst the three, and that its ROIC is the most consistent.
The company-specific ROIC trends generally match management commentary on ROIC, the note stated.
#piper
According to the firm, AMZN's return on invested capital is holding up far better than giants Meta Platforms, Inc. (NASDAQ: META) and Alphabet Inc. (NASDAQ:GOOGL). Interestingly, the firm projects this ROIC figure to fall from about 17% in 2018-2025 to about 14% in 2026.
Piper's note states the obvious: Amazon spending is more focused on AWS. Revenue for AWS jumped 37% year-over-year to $42.2 billion in Q2, the fastest growth it has had in four years. Meanwhile, AWS contract backlogs at the end of the quarter stood at $496 billion, up from $364 billion in the prior three-month period.
The bull case for Amazon lies in its ROIC, the figure Piper sees deteriorating the least amongst Meta, Alphabet, and Amazon. The note affirms that Amazon is the best-positioned amongst the three, and that its ROIC is the most consistent.
The company-specific ROIC trends generally match management commentary on ROIC, the note stated.
#piper


15 days ago
Kanye West's former security guard wants one subject kept out of their upcoming Donda Academy employment trial, any attempt to argue that Ye was of "unsound mind" during the period covered by Benjamin Deshon Provo's discrimination and wrongful-termination claims.
Provo has asked a Los Angeles judge to bar that argument after an Aug. 24 pretrial discussion in which, according to his attorneys, Ye's counsel would not agree to keep the rapper's mental-health history out of the case. Provo's side says mental health was never pleaded as an affirmative defense and no supporting medical records or expert testimony were produced during discovery.
The new filing is a pretrial attempt to determine what his lawyers may argue or introduce when the civil case is heard, and TMZ reports that Provo wants the court to prevent the issue from being raised at all.
Provo's lawyers are also relying on Ye's own deposition. Asked whether he felt he was not himself around the period when he ran Donda Academy, Ye answered no and said that time was "close to me being myself."
According to MyNewsLA, Provo's attorneys say the issue surfaced during an Aug. 24 meeting over pretrial motions. They claim Ye's counsel said he was "certainly not agreeing" to exclude references to Ye's "documented mental health issues" because those issues could relate to things Ye had said.
#pretrial #provo #according #wants
Provo has asked a Los Angeles judge to bar that argument after an Aug. 24 pretrial discussion in which, according to his attorneys, Ye's counsel would not agree to keep the rapper's mental-health history out of the case. Provo's side says mental health was never pleaded as an affirmative defense and no supporting medical records or expert testimony were produced during discovery.
The new filing is a pretrial attempt to determine what his lawyers may argue or introduce when the civil case is heard, and TMZ reports that Provo wants the court to prevent the issue from being raised at all.
Provo's lawyers are also relying on Ye's own deposition. Asked whether he felt he was not himself around the period when he ran Donda Academy, Ye answered no and said that time was "close to me being myself."
According to MyNewsLA, Provo's attorneys say the issue surfaced during an Aug. 24 meeting over pretrial motions. They claim Ye's counsel said he was "certainly not agreeing" to exclude references to Ye's "documented mental health issues" because those issues could relate to things Ye had said.
#pretrial #provo #according #wants

15 days ago
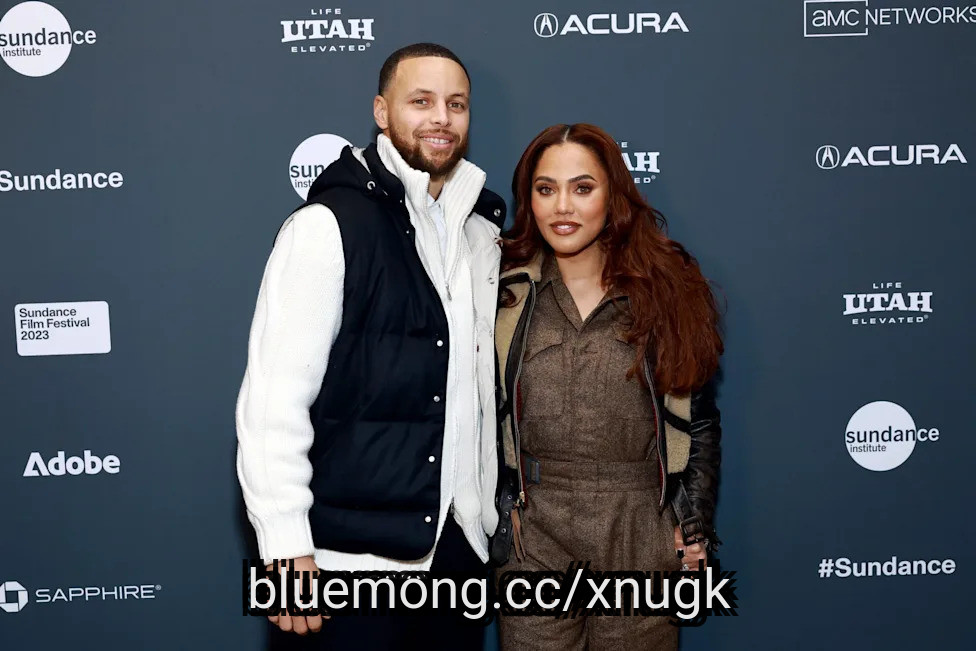
Ayesha Curry has opened up about her husband Stephen Curry's future with the Golden State Warriors in a recent interview.
As of September 1, 2026, Curry is eligible to sign a contract extension with the Warriors that could pay him up to $136.7 million.
The 38-year-old legend has always been considered a one-team man by fans, but GSW's recent competitive struggles and grim immediate future have created uncertainty until Curry signs on the dotted line.
The Currys were interviewed by Dalton Johnson, with Ayesha being asked about Curry's playing future. She reaffirmed that Steph can easily continue his career, while hinting at incoming 'fun surprises.'
"Of course, (Steph) is the hardest-working man in the room. He has no days off. He hasn't stopped since last season ended. He's ready. He's ready to get out there. I think we're going to be in for some fun surprises over the next couple of years."
#golden
As of September 1, 2026, Curry is eligible to sign a contract extension with the Warriors that could pay him up to $136.7 million.
The 38-year-old legend has always been considered a one-team man by fans, but GSW's recent competitive struggles and grim immediate future have created uncertainty until Curry signs on the dotted line.
The Currys were interviewed by Dalton Johnson, with Ayesha being asked about Curry's playing future. She reaffirmed that Steph can easily continue his career, while hinting at incoming 'fun surprises.'
"Of course, (Steph) is the hardest-working man in the room. He has no days off. He hasn't stopped since last season ended. He's ready. He's ready to get out there. I think we're going to be in for some fun surprises over the next couple of years."
#golden

15 days ago
On August 28, Affirm Holdings (NASDAQ:AFRM) gave investors two very different signals in the same breath. The buy now, pay later company posted a fiscal fourth quarter that blew past Wall Street's numbers, yet CEO Max Levchin used the moment to flag something less comfortable: gas prices are squeezing the very shoppers driving that growth. The stock barely moved on the news, leaving the market to sort out which story matters more.
The headline numbers were hard to argue with. Revenue rose 33% to $1.17 billion for the three months ended June 30, ahead of the $1.11 billion ****** ysts expected, while gross merchandise volume climbed 36% to $14.1 billion against a $13.39 billion estimate. Adjusted operating income reached $353 million, a 30% margin, and the GAAP operating margin expanded six percentage points to 12.6%. For the full fiscal year, GMV hit $50.2 billion, up from $36.7 billion, on $4.26 billion in revenue.
The user base kept expanding too. Active consumers grew 21% to 27.8 million, and transactions per active consumer rose 20% to 7.0, while the Affirm Card's active user count more than doubled to 5.2 million. Newly appointed president Michael Linford, who moved into the role Thursday, Aug. 27, after nearly two years as chief operating officer, called it the eleventh straight quarter of GMV growth above 30%. Credit quality held up alongside that growth, with the 30-day delinquency rate improving to 2.5% from the 2.7% to 2.8% range of the prior three quarters, something Compass Point's Giuliano Bologna called evidence of "resilient credit performance." Affirm also deepened its Shopify tie-up, extending Shop Pay Installments into Australia after last year's UK expansion, part of what Linford described as Shopify "pulling us into a new market" as both a partner and shareholder. Susquehanna's James Friedman raised his price target to $110 from $105, calling the guidance for fiscal 2027 "exceptionally strong."
Levchin's own commentary complicated the celebration. "The US consumer undoubtedly sees the higher gas prices, so can't, can't ignore that," he told CNBC, noting shoppers are increasingly turning to Affirm to manage costs across "all the various inflationary points." The national average gas price sat at $4.09 a gallon as of August 28, down from above $4.50 in May but still well above pre-Iran war levels, and it hasn't dipped below $3 since March 2. Levchin was direct about the risk: "I do think that sustained pressure on prices isn't great in the long term, and so can't ignore that either."
#prices #Growth #can 't
The headline numbers were hard to argue with. Revenue rose 33% to $1.17 billion for the three months ended June 30, ahead of the $1.11 billion ****** ysts expected, while gross merchandise volume climbed 36% to $14.1 billion against a $13.39 billion estimate. Adjusted operating income reached $353 million, a 30% margin, and the GAAP operating margin expanded six percentage points to 12.6%. For the full fiscal year, GMV hit $50.2 billion, up from $36.7 billion, on $4.26 billion in revenue.
The user base kept expanding too. Active consumers grew 21% to 27.8 million, and transactions per active consumer rose 20% to 7.0, while the Affirm Card's active user count more than doubled to 5.2 million. Newly appointed president Michael Linford, who moved into the role Thursday, Aug. 27, after nearly two years as chief operating officer, called it the eleventh straight quarter of GMV growth above 30%. Credit quality held up alongside that growth, with the 30-day delinquency rate improving to 2.5% from the 2.7% to 2.8% range of the prior three quarters, something Compass Point's Giuliano Bologna called evidence of "resilient credit performance." Affirm also deepened its Shopify tie-up, extending Shop Pay Installments into Australia after last year's UK expansion, part of what Linford described as Shopify "pulling us into a new market" as both a partner and shareholder. Susquehanna's James Friedman raised his price target to $110 from $105, calling the guidance for fiscal 2027 "exceptionally strong."
Levchin's own commentary complicated the celebration. "The US consumer undoubtedly sees the higher gas prices, so can't, can't ignore that," he told CNBC, noting shoppers are increasingly turning to Affirm to manage costs across "all the various inflationary points." The national average gas price sat at $4.09 a gallon as of August 28, down from above $4.50 in May but still well above pre-Iran war levels, and it hasn't dipped below $3 since March 2. Levchin was direct about the risk: "I do think that sustained pressure on prices isn't great in the long term, and so can't ignore that either."
#prices #Growth #can 't

15 days ago
Kelly Osbourne is platforming freedom in every sense as she raises her lovely son, Sidney.
The singer affirmed that when it comes to explaining gender related terms to her 3-year-old, she does not slam labels on it; instead, she is giving him a chance to express himself fully.
Kelly Osbourne welcomed Sidney with her ex-fiancé, Sid Wilson, in late 2022 in what the media personality described as a hectic birth process.
ZUMAPRESS.com / MEGA
The doting mom got candid in an interview published on Monday, August 31, about how she handles parenting with Sidney and the lessons she has learned along the journey. Kelly admitted that patience has become a mainstay in her life now, thanks to motherhood.
#august
The singer affirmed that when it comes to explaining gender related terms to her 3-year-old, she does not slam labels on it; instead, she is giving him a chance to express himself fully.
Kelly Osbourne welcomed Sidney with her ex-fiancé, Sid Wilson, in late 2022 in what the media personality described as a hectic birth process.
ZUMAPRESS.com / MEGA
The doting mom got candid in an interview published on Monday, August 31, about how she handles parenting with Sidney and the lessons she has learned along the journey. Kelly admitted that patience has become a mainstay in her life now, thanks to motherhood.
#august


17 days ago
Qiagen N.V. (NYSE:QGEN) announced on August 10 that the U.S. FDA cleared its QIAstat-Dx BCID GPF Plus AMR Panel, marking the company's first entry into the U.S. bloodstream infection testing market. Operating on the QIAstat-Dx platform, which boasts over 5,200 global placements, the automated panel detects 20 gram-positive bacterial and fungal targets, alongside 10 genetic antimicrobial resistance markers, in about one hour.
This regulatory milestone comes shortly after Qiagen N.V. (NYSE:QGEN) reported solid Q2 2026 financial results on August 5. Net sales reached $535 million (flat YoY at constant exchange rates), beating guidance for a 2% decline. Adjusted diluted EPS rose 3% YoY to $0.62, topping expectations. Performance across core growth pillars (+5% CER), including Sample Technologies (+9% CER) and QIAcuity digital PCR, helped offset a 7% drop in QIAstat-Dx respiratory testing sales. QGEN reaffirmed its full-year 2026 outlook for 1%–2% CER net sales growth and adjusted EPS of at least $2.43.
Additionally, Qiagen announced that Jonathan Pratt will take over as CEO effective September 1, succeeding Thierry Bernard. Joining at a pivotal time, Pratt will lead executive execution following an intensive portfolio evaluation and ongoing corporate efficiency programs.
This brings up a key question: Does the FDA clearance and steady execution under incoming leadership position Qiagen N.V. (NYSE:QGEN) for a valuation rerating, or will soft regional demand and product mix headwinds keep shares range-bound?
Bulls argue that Qiagen's high-margin, consumable-driven business model (comprising 90% of total Q2 sales) provides defensive recurring cash flow, generating $301 million in H1 operating cash flow. The new FDA approval expands QIAstat-Dx into its fourth major infectious disease area in the U.S., unlocking higher-margin hospital diagnostic channels. Furthermore, solid growth across core pillars like Sample Technologies and QIAcuity demonstrates fundamental demand. Strong internal cash generation also gives incoming CEO Jonathan Pratt ample balance sheet capacity to pursue disciplined capital deployment and portfolio innovation.
#qiagen
This regulatory milestone comes shortly after Qiagen N.V. (NYSE:QGEN) reported solid Q2 2026 financial results on August 5. Net sales reached $535 million (flat YoY at constant exchange rates), beating guidance for a 2% decline. Adjusted diluted EPS rose 3% YoY to $0.62, topping expectations. Performance across core growth pillars (+5% CER), including Sample Technologies (+9% CER) and QIAcuity digital PCR, helped offset a 7% drop in QIAstat-Dx respiratory testing sales. QGEN reaffirmed its full-year 2026 outlook for 1%–2% CER net sales growth and adjusted EPS of at least $2.43.
Additionally, Qiagen announced that Jonathan Pratt will take over as CEO effective September 1, succeeding Thierry Bernard. Joining at a pivotal time, Pratt will lead executive execution following an intensive portfolio evaluation and ongoing corporate efficiency programs.
This brings up a key question: Does the FDA clearance and steady execution under incoming leadership position Qiagen N.V. (NYSE:QGEN) for a valuation rerating, or will soft regional demand and product mix headwinds keep shares range-bound?
Bulls argue that Qiagen's high-margin, consumable-driven business model (comprising 90% of total Q2 sales) provides defensive recurring cash flow, generating $301 million in H1 operating cash flow. The new FDA approval expands QIAstat-Dx into its fourth major infectious disease area in the U.S., unlocking higher-margin hospital diagnostic channels. Furthermore, solid growth across core pillars like Sample Technologies and QIAcuity demonstrates fundamental demand. Strong internal cash generation also gives incoming CEO Jonathan Pratt ample balance sheet capacity to pursue disciplined capital deployment and portfolio innovation.
#qiagen


18 days ago
A judge has granted a hearing to explore claims that a man wants to recant allegations of ****** ual abuse years ago by Penn State ****** istant football coach Jerry Sandusky.
Sandusky, 82, has been serving a decades-long prison sentence since he was convicted of 45 counts of ****** ual abuse in 2012. Eight young men testified about what happened to them as boys. He has repeatedly lost efforts to get a new trial, but Sandusky's lawyers are trying again.
A man identified in court documents as R.R. said he was coached extensively by authorities.
"I was told — both directly and indirectly — that trauma may have fragmented my memory, and that I could safely affirm details I did not fully recall. I was ****** ured this was common and even expected," R.R. said in an affidavit filed by Sandusky's attorneys.
A court hearing in Centre County has been scheduled for Sept. 8.
#hearing #abuse #penn
Sandusky, 82, has been serving a decades-long prison sentence since he was convicted of 45 counts of ****** ual abuse in 2012. Eight young men testified about what happened to them as boys. He has repeatedly lost efforts to get a new trial, but Sandusky's lawyers are trying again.
A man identified in court documents as R.R. said he was coached extensively by authorities.
"I was told — both directly and indirectly — that trauma may have fragmented my memory, and that I could safely affirm details I did not fully recall. I was ****** ured this was common and even expected," R.R. said in an affidavit filed by Sandusky's attorneys.
A court hearing in Centre County has been scheduled for Sept. 8.
#hearing #abuse #penn



