

1 day ago
Interested in Gladstone Commercial Corporation? Here are five stocks we like better.
Q3 FFO and core FFO were $0.35 per share, unchanged year over year. Revenue rose to $42.4 million from $40.8 million, while expenses increased to $32.9 million, partly due to depreciation and an office-property impairment.
Portfolio occupancy improved to 99.3%, and industrial ******* ets made up 69% of annualized straight-line rent, nearing the company's goal of more than 70%. Leasing activity during the quarter added approximately $2.5 million in annual straight-line rent.
Higher interest rates and a gap between buyer and seller pricing are limiting acquisitions; the company is reviewing about 15 opportunities worth more than $200 million but says it will maintain its underwriting standards. It reported $99.9 million of debt maturities in 2027 and $70.2 million available on its credit line.
Gladstone Commercial (NASDAQ:GOOD) reported third-quarter funds from operations and core funds from operations of $0.35 per share, unchanged from the same period a year earlier, as the real estate investment trust increased portfolio occupancy and continued to emphasize industrial properties.
#year #increased
Q3 FFO and core FFO were $0.35 per share, unchanged year over year. Revenue rose to $42.4 million from $40.8 million, while expenses increased to $32.9 million, partly due to depreciation and an office-property impairment.
Portfolio occupancy improved to 99.3%, and industrial ******* ets made up 69% of annualized straight-line rent, nearing the company's goal of more than 70%. Leasing activity during the quarter added approximately $2.5 million in annual straight-line rent.
Higher interest rates and a gap between buyer and seller pricing are limiting acquisitions; the company is reviewing about 15 opportunities worth more than $200 million but says it will maintain its underwriting standards. It reported $99.9 million of debt maturities in 2027 and $70.2 million available on its credit line.
Gladstone Commercial (NASDAQ:GOOD) reported third-quarter funds from operations and core funds from operations of $0.35 per share, unchanged from the same period a year earlier, as the real estate investment trust increased portfolio occupancy and continued to emphasize industrial properties.
#year #increased

1 day ago
On its third-quarter 2026 earnings call, held on Nov. 3, 2026, Eaton (NYSE:ETN) raised its full-year 2026 organic revenue growth guidance, which excludes acquisitions and currency shifts, to a midpoint of 14%.
Management also raised its full-year adjusted earnings per share guidance, a profit measure that excludes one-time items and non-cash expenses, to a midpoint of $13.75. Expanding factory capacity allows the company to convert a record backlog, which represents unfilled customer orders, into long-term margin expansion.
Three things management said stand out.
Eaton restructured its international operations early and expanded its product lineup in high-demand markets like data centers. Electrical Global, the division serving international power markets, sharply accelerated its organic growth by gaining share with the same global customers that Eaton serves in North America.
We now expect organic growth about 16% in 2026, well above our prior guidance, and more than double the 7% we delivered in 2025. This acceleration is no accident. It reflects deliberate strategic moves we made over the past few years.
-- Paulo Ruiz, Chief Executive Officer
#eaton #guidance #earnings #full
Management also raised its full-year adjusted earnings per share guidance, a profit measure that excludes one-time items and non-cash expenses, to a midpoint of $13.75. Expanding factory capacity allows the company to convert a record backlog, which represents unfilled customer orders, into long-term margin expansion.
Three things management said stand out.
Eaton restructured its international operations early and expanded its product lineup in high-demand markets like data centers. Electrical Global, the division serving international power markets, sharply accelerated its organic growth by gaining share with the same global customers that Eaton serves in North America.
We now expect organic growth about 16% in 2026, well above our prior guidance, and more than double the 7% we delivered in 2025. This acceleration is no accident. It reflects deliberate strategic moves we made over the past few years.
-- Paulo Ruiz, Chief Executive Officer
#eaton #guidance #earnings #full

18 days ago
I'm living proof of the saying that "kids keep you young." My wife and I don't need social media. We've got multiple social barometers living in our house. But my usual reaction to every new trend or slang that enters their lexicon ("cooked" and "tuff" have been the new favorites) is skepticism. Before I try to figure out how much attention I need to put into what has them hyped, I try to figure out how serious they are about their enthusiasm.
Sunday's fantasy football action left me in a similar spot. We didn't get many massive box score performances from our stars. Instead, Week 6 was about our mid- and late-round picks or waiver-wire acquisitions. And with some giving us repeat results, the storylines coming out of Sunday should have us adjusting how we approach fantasy free agency on Tuesday.
Both Trevor Lawrence and C.J. Stroud were hooping all morning. They were the perfect pivot from whatever we had to watch on TNF. But as I was watching the Texans offense, a couple of things stood out.
what a throw from Stroud, too. pic.twitter.com/fz4EbOAKvT https://t.co/2MaTqWpPgd
First, Stroud's command of the offense was at an all-time high. Jacksonville came into the game with the 12th-highest pressure rate. Houston had a twofold response. It used an extra lineman on 35.6% of its plays (a season-high), and Stroud was getting rid of the football in 2.31 seconds (a season-low). The result was not only his lowest pressure rate (8.6%) but also his highest EPA per dropback (0.35). More importantly, the Jaguars' defensive measures, which included blitzing Stroud on 31.4% of his dropbacks, didn't stop him from throwing the ball.
#fantasy
Sunday's fantasy football action left me in a similar spot. We didn't get many massive box score performances from our stars. Instead, Week 6 was about our mid- and late-round picks or waiver-wire acquisitions. And with some giving us repeat results, the storylines coming out of Sunday should have us adjusting how we approach fantasy free agency on Tuesday.
Both Trevor Lawrence and C.J. Stroud were hooping all morning. They were the perfect pivot from whatever we had to watch on TNF. But as I was watching the Texans offense, a couple of things stood out.
what a throw from Stroud, too. pic.twitter.com/fz4EbOAKvT https://t.co/2MaTqWpPgd
First, Stroud's command of the offense was at an all-time high. Jacksonville came into the game with the 12th-highest pressure rate. Houston had a twofold response. It used an extra lineman on 35.6% of its plays (a season-high), and Stroud was getting rid of the football in 2.31 seconds (a season-low). The result was not only his lowest pressure rate (8.6%) but also his highest EPA per dropback (0.35). More importantly, the Jaguars' defensive measures, which included blitzing Stroud on 31.4% of his dropbacks, didn't stop him from throwing the ball.
#fantasy


1 month ago
Titan International, Inc. (NYSE:TWI) announced a definitive agreement on September 21 to sell its Italtractor ITM undercarriage business to USCO S.p.A. The initial purchase price is approximately $207 million, while the stated total cash value reaches up to approximately $285 million. Understanding that difference is central to ******* sing the financial flexibility the disposal could create.
Titan International, Inc. (NYSE:TWI) expects approximately $23 million from closing adjustments and $11 million in dividends before closing. A further $6 million depends on ITM meeting specified 2026 performance criteria. The headline also includes $38 million in dividends received in earlier years.
Subtracting those historical dividends leaves approximately $247 million in potential future gross receipts, including the earnout, or $241 million without it. These calculations use the announced estimates and span different payment dates. Final adjustments, taxes, and transaction costs will determine how much cash becomes available for deployment.
The disclosed dollar amounts were translated at €1.00 to $1.148, the September 18, 2026 exchange rate. Currency movements could increase or reduce the eventual dollar receipts.
Titan International, Inc. (NYSE:TWI) intends to use part of the proceeds to reduce debt and pursue growth investments, including acquisitions and partnerships. The disposal would also concentrate resources on wheel and tire operations.
#september #announced
Titan International, Inc. (NYSE:TWI) expects approximately $23 million from closing adjustments and $11 million in dividends before closing. A further $6 million depends on ITM meeting specified 2026 performance criteria. The headline also includes $38 million in dividends received in earlier years.
Subtracting those historical dividends leaves approximately $247 million in potential future gross receipts, including the earnout, or $241 million without it. These calculations use the announced estimates and span different payment dates. Final adjustments, taxes, and transaction costs will determine how much cash becomes available for deployment.
The disclosed dollar amounts were translated at €1.00 to $1.148, the September 18, 2026 exchange rate. Currency movements could increase or reduce the eventual dollar receipts.
Titan International, Inc. (NYSE:TWI) intends to use part of the proceeds to reduce debt and pursue growth investments, including acquisitions and partnerships. The disposal would also concentrate resources on wheel and tire operations.
#september #announced

2 months ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

2 months ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

2 months ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


2 months ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year

2 months ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


2 months ago
If you're trying to build a consumer-focused corner of your portfolio that can grow through a lot of different economic backdrops, three names stand out right now: Church & Dwight Co. (NYSE: CHD), YETI Holdings (NYSE: YETI), and Newell Brands (NASDAQ: NWL). Each of these is making deliberate moves in 2026 and into 2027 that communicate to me more about their future than any single rocky quarter's earnings line.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Church & Dwight has built its identity on everyday products like baking soda, laundry detergents, and cleaners that quietly show up in millions of homes. In May 2026, it moved to deepen that footprint by buying the Miss Mouth's Messy Eater brand, a fast-growing, non-toxic stain remover built for parents. It's a small thing on paper, but it fits this successful company's patterns: Keep layering niche, repeat-use products into an existing distribution machine instead of chasing flashy new categories.
The company's first-quarter 2026 update backs that strategy up. Organic sales rose 5% even though reported net sales were basically flat due to past portfolio pruning, per company management. Management described 2026 as a year of "volume-driven" organic growth, meaning they're focused on selling more units to real customers, not just leaning on price increases. On top of that, Church & Dwight extended its long dividend record yet again. Although it is not quite a Dividend King, it has consistently raised its dividend for 29 years.
For investors, my advice here is straightforward: Treat Church & Dwight as a core holding in a consumer bucket. It's unlikely to deliver fireworks in a single year, but it keeps making acquisitions to deepen its understanding of existing categories.
#flashing #organic


2 months ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management

2 months ago
Interested in Cardinal Health, Inc.? Here are five stocks we like better.
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions
Cardinal Health expects growth to normalize in fiscal 2027 after fiscal 2026 benefited from unusually strong specialty growth, customer onboarding, acquisitions and solid healthcare utilization. Management said all five operating segments delivered double-digit earnings growth in fiscal 2026.
The company is expanding its specialty and at-home healthcare strategy through MSO platforms, bolt-on acquisitions and diabetes-related deals. Strive Medical has closed, while the AdaptHealth diabetes acquisition is expected to close in the second half of fiscal 2027, strengthening Cardinal's continuous glucose monitoring business.
Cardinal is prioritizing automated, small-parcel distribution of higher-value at-home products and plans to add three more automated distribution centers. Management also said cash flow was strong in fiscal 2026, putting the company about 90% of the way toward its previously announced $10 billion objective.
Cardinal Health Earnings: Can Perfection Get Priced In Twice?
#acquisitions
2 months ago
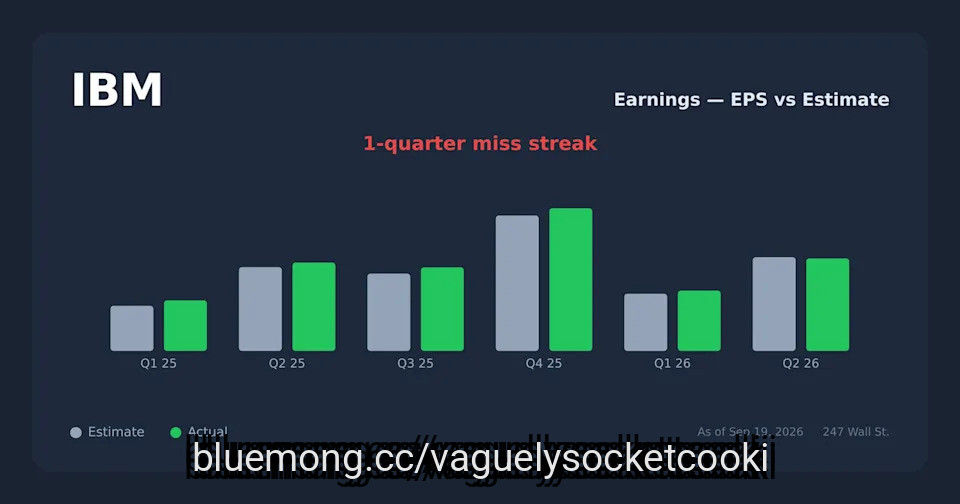
IBM raised its quarterly dividend a single penny, from $1.68 to $1.69, marking its 31st consecutive increase but delivering just $0.04 more annually to shareholders.
Microsoft grew its quarterly dividend from $0.13 to $0.98 since 2010, making it the stronger pick for investors seeking real income growth over IBM's 2.83% yield.
IBM's dividend appears safe, with $14.7B in free cash flow comfortably covering its $6.3B payout, though capital is flowing toward acquisitions, $62B in debt, and quantum computing bets.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and IBM didn't make the cut. Enter your email to see the names that beat IBM. The report is free. Enter your email and see if any of your stocks made the cut.
The headline is easy to sell. IBM (NYSE:IBM) has paid consecutive quarterly dividends every year since 1916 and, with the April declaration, notched its 31st consecutive year of dividend increases. The reality a retiree actually banks is smaller. Much smaller.
#Dividend #year
Microsoft grew its quarterly dividend from $0.13 to $0.98 since 2010, making it the stronger pick for investors seeking real income growth over IBM's 2.83% yield.
IBM's dividend appears safe, with $14.7B in free cash flow comfortably covering its $6.3B payout, though capital is flowing toward acquisitions, $62B in debt, and quantum computing bets.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and IBM didn't make the cut. Enter your email to see the names that beat IBM. The report is free. Enter your email and see if any of your stocks made the cut.
The headline is easy to sell. IBM (NYSE:IBM) has paid consecutive quarterly dividends every year since 1916 and, with the April declaration, notched its 31st consecutive year of dividend increases. The reality a retiree actually banks is smaller. Much smaller.
#Dividend #year


2 months ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


2 months ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta


2 months ago
On August 6, Millicom International Cellular (NASDAQ:TIGO) released its second-quarter 2026 results, and the numbers pulled in two directions at once. Revenue jumped 59.4% year over year to $2.18 billion, while Adjusted EBITDA crossed $1 billion for the first time in the company's history at $1.01 billion, up 58% from a year earlier. Yet net profit attributable to company owners fell 83.9% to just $109 million. Investors weighing this quarter have to decide which of those two stories actually describes the business.
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio


2 months ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
2 months ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source


2 months ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange

2 months ago
Interested in The Goldman Sachs Group, Inc.? Here are five stocks we like better.
Goldman Sachs expects its revenue base to reach roughly $70 billion this year, up from the mid-$30 billion range when its strategic plan began in 2018–19, supported by greater diversification and operating leverage.
Asset & Wealth Management is exceeding its targeted high-single-digit growth rate, overseeing about $4 trillion in ******* ets and targeting 30% margins and high-teen returns. Acquisitions and partnerships are expanding its alternatives, ETF, retirement and real estate capabilities.
Goldman expects alternatives fundraising above $125 billion this year and sees major financing opportunities from AI infrastructure investment, while near-term results may face higher expenses, softer FICC activity and a muted investments line.
Digging for Value: Alpha Metallurgical Resources Insider Buys Big
#year #here
Goldman Sachs expects its revenue base to reach roughly $70 billion this year, up from the mid-$30 billion range when its strategic plan began in 2018–19, supported by greater diversification and operating leverage.
Asset & Wealth Management is exceeding its targeted high-single-digit growth rate, overseeing about $4 trillion in ******* ets and targeting 30% margins and high-teen returns. Acquisitions and partnerships are expanding its alternatives, ETF, retirement and real estate capabilities.
Goldman expects alternatives fundraising above $125 billion this year and sees major financing opportunities from AI infrastructure investment, while near-term results may face higher expenses, softer FICC activity and a muted investments line.
Digging for Value: Alpha Metallurgical Resources Insider Buys Big
#year #here


2 months ago
Galliford Try Holdings PLC (LSE:GFRD, FRA:3WC) chief financial officer Kris Hampson spoke with Proactive's Stephen Gunnion about the construction group's latest results, growing order book, margin progression and outlook for 2027, as well as its approach to acquisitions and shareholder returns.
Hampson said Galliford Try delivered a sixth consecutive year of growth across key metrics, supported by its building, infrastructure and specialist services operations. Adjusted profit before tax rose 24% on revenue growth of 3% to nearly £56 million, with adjusted divisional operating margin advancing from 3% to 3.5% and average cash up 21% to £216.2 million. "We make revenue, we turn it into profit, and we turn that profit into cash," Hampson said.
Looking ahead, he highlighted the £4.3 billion order book, up 5%, with more than 90% of current-year revenue already secured, alongside 60% for 2028. He said 91% of the order book sits within long-term frameworks and 95% is with government and regulated clients.
Hampson also discussed opportunities across water, highways, education and affordable housing, including growth tied to AMP8, newer frameworks on improved terms, and expects continued progression towards the group's 4% adjusted operating margin target for 2030.
On capital allocation, Galliford Try announced a £15 million share buyback alongside its results, following last year's £10 million buyback. Hampson also discussed the company's active M&A pipeline and its commitment to maintaining a dividend at 1.8 times cover based on adjusted EPS.
#million #profit
Hampson said Galliford Try delivered a sixth consecutive year of growth across key metrics, supported by its building, infrastructure and specialist services operations. Adjusted profit before tax rose 24% on revenue growth of 3% to nearly £56 million, with adjusted divisional operating margin advancing from 3% to 3.5% and average cash up 21% to £216.2 million. "We make revenue, we turn it into profit, and we turn that profit into cash," Hampson said.
Looking ahead, he highlighted the £4.3 billion order book, up 5%, with more than 90% of current-year revenue already secured, alongside 60% for 2028. He said 91% of the order book sits within long-term frameworks and 95% is with government and regulated clients.
Hampson also discussed opportunities across water, highways, education and affordable housing, including growth tied to AMP8, newer frameworks on improved terms, and expects continued progression towards the group's 4% adjusted operating margin target for 2030.
On capital allocation, Galliford Try announced a £15 million share buyback alongside its results, following last year's £10 million buyback. Hampson also discussed the company's active M&A pipeline and its commitment to maintaining a dividend at 1.8 times cover based on adjusted EPS.
#million #profit


2 months ago
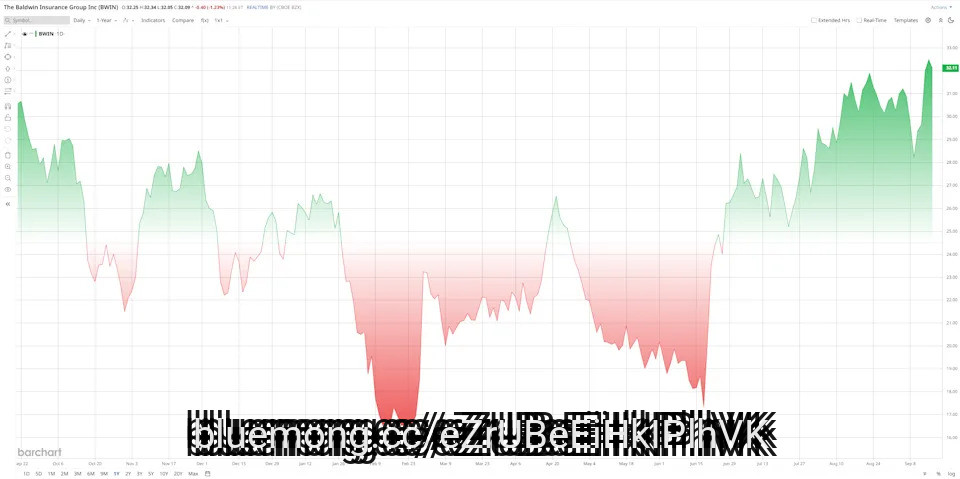
The Baldwin Insurance Group (BWIN) is suddenly in the spotlight after Michael Dell's family office and Sequence Holdings agreed to take the insurance broker private in a deal valued at about $7.7 billion. The offer calls for $32.50 in cash for each share. That represents an 88% premium to Baldwin's unaffected June 17 closing price. Shares jumped 7.5% to $31.89 after the deal was announced on Sept. 14.
For investors, the story is now less about what Baldwin might be worth as a standalone public company and more about whether the proposed transaction closes as planned. The deal also gives Baldwin access to long-duration capital outside the public markets. That could help the company keep investing in acquisitions, technology, and artificial intelligence without the same pressure to deliver results every quarter.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#sequence
For investors, the story is now less about what Baldwin might be worth as a standalone public company and more about whether the proposed transaction closes as planned. The deal also gives Baldwin access to long-duration capital outside the public markets. That could help the company keep investing in acquisitions, technology, and artificial intelligence without the same pressure to deliver results every quarter.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#sequence

2 months ago
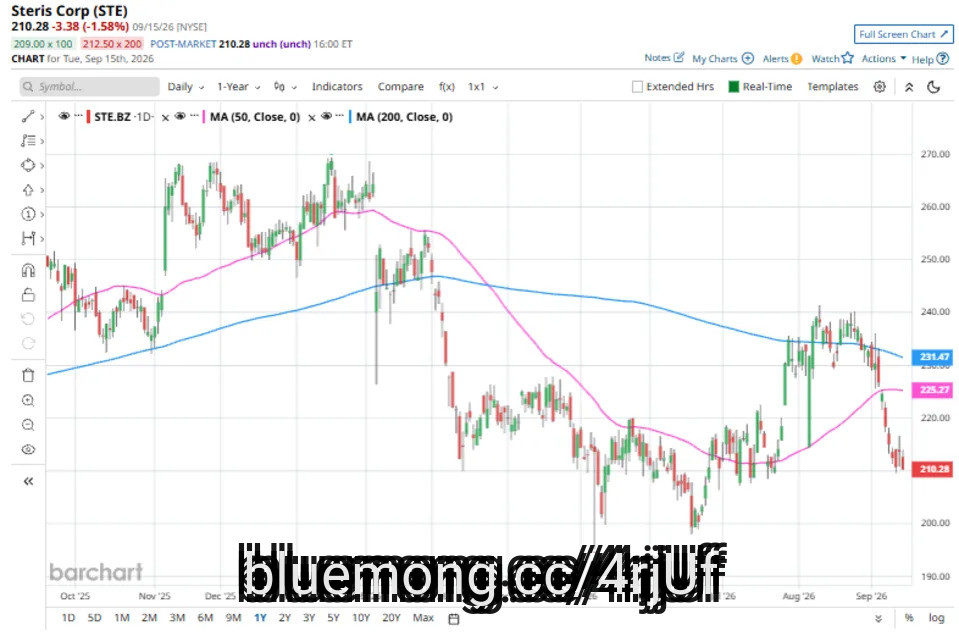
STERIS plc (STE), with a market capitalization of approximately $20.8 billion, is a global healthcare company focused on infection prevention and patient care. The Mentor, Ohio-based company provides consumable products, capital equipment, maintenance and repair services, sterilization solutions, laboratory testing, outsourced reprocessing, and operating room connectivity solutions.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and STERIS fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. STERIS stands out by combining a leading position in infection prevention with a broad range of healthcare and sterilization products and services. Its trusted brand, loyal customer base, strong financial position, and strategic acquisitions strengthen its competitive position while supporting continued expansion and innovation.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#steris #position
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and STERIS fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. STERIS stands out by combining a leading position in infection prevention with a broad range of healthcare and sterilization products and services. Its trusted brand, loyal customer base, strong financial position, and strategic acquisitions strengthen its competitive position while supporting continued expansion and innovation.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#steris #position

2 months ago
HIVE Digital Technologies (Nasdaq: HIVE), a Canada-based Bitcoin miner and data center operator, has appointed Hubert Marleau as an independent director at BUZZ HPC.
The company, which trades on the Nasdaq and Toronto Stock Exchange, said Marleau will serve on the board of its wholly owned AI cloud and high-performance computing subsidiary.
Marleau brings more than 50 years of experience in Canadian capital markets. He co-founded Palos Capital Corp. and Palos Management Inc. and has served as governor of both the Montreal and Vancouver stock exchanges, chairman of the Toronto Stock Exchange Listing Committee, and a director of the Investment Dealers ******* ociation of Canada.
Related: Dogecoin co-founder mocks Trump's $5,000 dividend plan
During his five-decade-long career, he has sat on the boards of more than 50 publicly traded companies in Canada and the United States and advised on numerous mergers, acquisitions, and financings, according to the company.
#canada #marleau #palos
The company, which trades on the Nasdaq and Toronto Stock Exchange, said Marleau will serve on the board of its wholly owned AI cloud and high-performance computing subsidiary.
Marleau brings more than 50 years of experience in Canadian capital markets. He co-founded Palos Capital Corp. and Palos Management Inc. and has served as governor of both the Montreal and Vancouver stock exchanges, chairman of the Toronto Stock Exchange Listing Committee, and a director of the Investment Dealers ******* ociation of Canada.
Related: Dogecoin co-founder mocks Trump's $5,000 dividend plan
During his five-decade-long career, he has sat on the boards of more than 50 publicly traded companies in Canada and the United States and advised on numerous mergers, acquisitions, and financings, according to the company.
#canada #marleau #palos

2 months ago
Hive Digital Technologies Chief Financial Officer Darcy Daubaras joined Steve Darling from Proactive to discuss the appointment of renowned capital markets executive Hubert Marleau as an Independent Director of HIVE's wholly owned subsidiary, BUZZ High Performance Computing (BUZZ HPC), a move designed to strengthen governance and strategic oversight as the company expands its sovereign AI infrastructure platform across Canada.
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across

2 months ago
This story was originally published on CFO Dive. To receive daily news and insights, subscribe to our free daily CFO Dive newsletter.
Stewart Grierson took the fifth CFO seat of his career this summer, joining Austin, Texas-based AI development company Anaconda.
In addition to his two decades of experience in the data infrastructure sector, Grierson brings to his new post all the experience gained after helping to complete multiple initial public offerings: Like when serving as the CFO of the security management company ArcSight, which went public and then was acquired in 2010 by HP in a $1.5 billion transaction.
Yet Grierson in a recent interview said taking Anaconda or any company public has never been an end goal for him, **** erting that it is just one path that any company may take as it evolves and grows.
"We have shareholders who will want liquidity at some point and I think my background gives [Anaconda] the optionality" of either looking at public markets in the futuure or taking other routes, including private equity investments or acquisitions, Grierson told CFO Dive.
#taking
Stewart Grierson took the fifth CFO seat of his career this summer, joining Austin, Texas-based AI development company Anaconda.
In addition to his two decades of experience in the data infrastructure sector, Grierson brings to his new post all the experience gained after helping to complete multiple initial public offerings: Like when serving as the CFO of the security management company ArcSight, which went public and then was acquired in 2010 by HP in a $1.5 billion transaction.
Yet Grierson in a recent interview said taking Anaconda or any company public has never been an end goal for him, **** erting that it is just one path that any company may take as it evolves and grows.
"We have shareholders who will want liquidity at some point and I think my background gives [Anaconda] the optionality" of either looking at public markets in the futuure or taking other routes, including private equity investments or acquisitions, Grierson told CFO Dive.
#taking
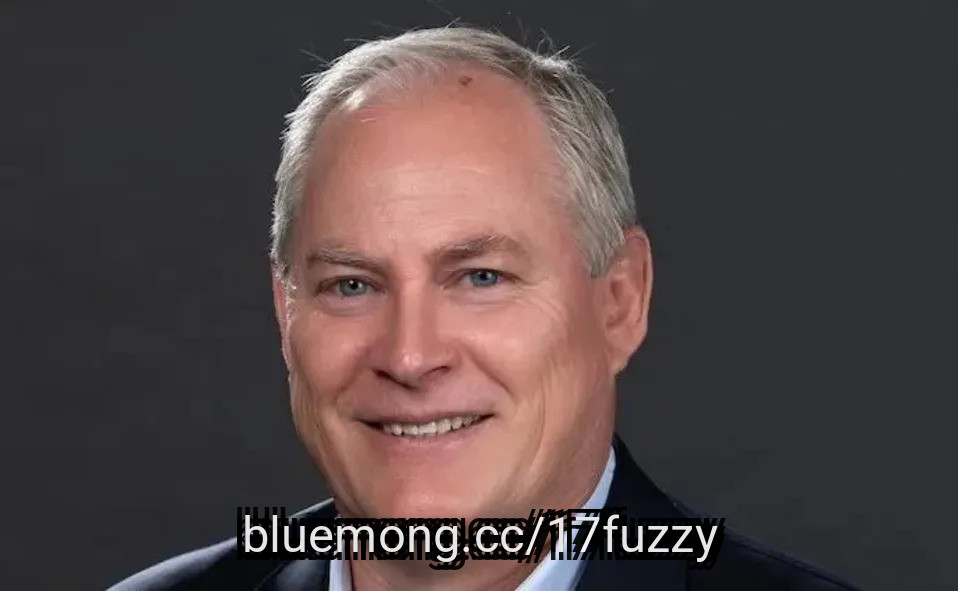

2 months ago
With a market cap of $23.9 billion, Global Payments Inc. (GPN) is a leading provider of payment technology and software solutions worldwide. The company operates primarily through its Merchant Solutions and Issuer Solutions segments, offering businesses and financial institutions secure, seamless, and innovative payment processing and software services.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant

2 months ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
2 months ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) provides strategy and consulting, industry X, song, and technology and operation services. On September 14, 2026, Accenture plc (NYSE:ACN) closed at $195.00 per share. Over the past month, Accenture plc (NYSE:ACN) was up 12.35%, and its shares lost 17.96% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $119.33 billion.
Broyhill ******* et Management stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"Accenture plc (NYSE:ACN) fell 38%, and we exited in June. Our case rested on unpriced optionality appearing as revenue per employee, and that measure grew only marginally while bookings declined 3% and the managed services book to-bill fell below one. Management's response was to raise the acquisition guide to $9 billion. An inflection in bookings was a key point in the thesis, and the fact that management fell back on acquisitions when it came in weak does not inspire confidence in the core business. We sold the position following these results."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#management #investor
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted Accenture plc (NYSE:ACN). Accenture plc (NYSE:ACN) provides strategy and consulting, industry X, song, and technology and operation services. On September 14, 2026, Accenture plc (NYSE:ACN) closed at $195.00 per share. Over the past month, Accenture plc (NYSE:ACN) was up 12.35%, and its shares lost 17.96% over the past 52 weeks. Accenture plc (NYSE:ACN) has a market capitalization of $119.33 billion.
Broyhill ******* et Management stated the following regarding Accenture plc (NYSE:ACN) in its Q2 2026 investor letter:
"Accenture plc (NYSE:ACN) fell 38%, and we exited in June. Our case rested on unpriced optionality appearing as revenue per employee, and that measure grew only marginally while bookings declined 3% and the managed services book to-bill fell below one. Management's response was to raise the acquisition guide to $9 billion. An inflection in bookings was a key point in the thesis, and the fact that management fell back on acquisitions when it came in weak does not inspire confidence in the core business. We sold the position following these results."
Accenture plc (NYSE:ACN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 69 hedge fund portfolios held Accenture plc (NYSE:ACN) at the end of the second quarter, compared to 64 in the previous quarter. While we acknowledge the potential of Accenture plc (NYSE:ACN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#management #investor
2 months ago
Dover Corporation (DOV) is a diversified global manufacturer and solutions provider based in Downers Grove, Illinois. It produces equipment, components, consumables, aftermarket parts, software and digital solutions across five operating segments, serving customers worldwide. The company has a market capitalization of approximately $25.5 billion.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and Dover comfortably fits this category. Dover's market leadership comes from making specialized industrial products that serve a wide range of markets worldwide. Its diversified portfolio reduces dependence on any single market, while strategic acquisitions and divestitures sharpen its focus on profitable businesses. Its growing exposure to clean energy and fueling technologies adds further growth potential.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #worldwide #downers #grove
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and Dover comfortably fits this category. Dover's market leadership comes from making specialized industrial products that serve a wide range of markets worldwide. Its diversified portfolio reduces dependence on any single market, while strategic acquisitions and divestitures sharpen its focus on profitable businesses. Its growing exposure to clean energy and fueling technologies adds further growth potential.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#market #worldwide #downers #grove



