2 days ago
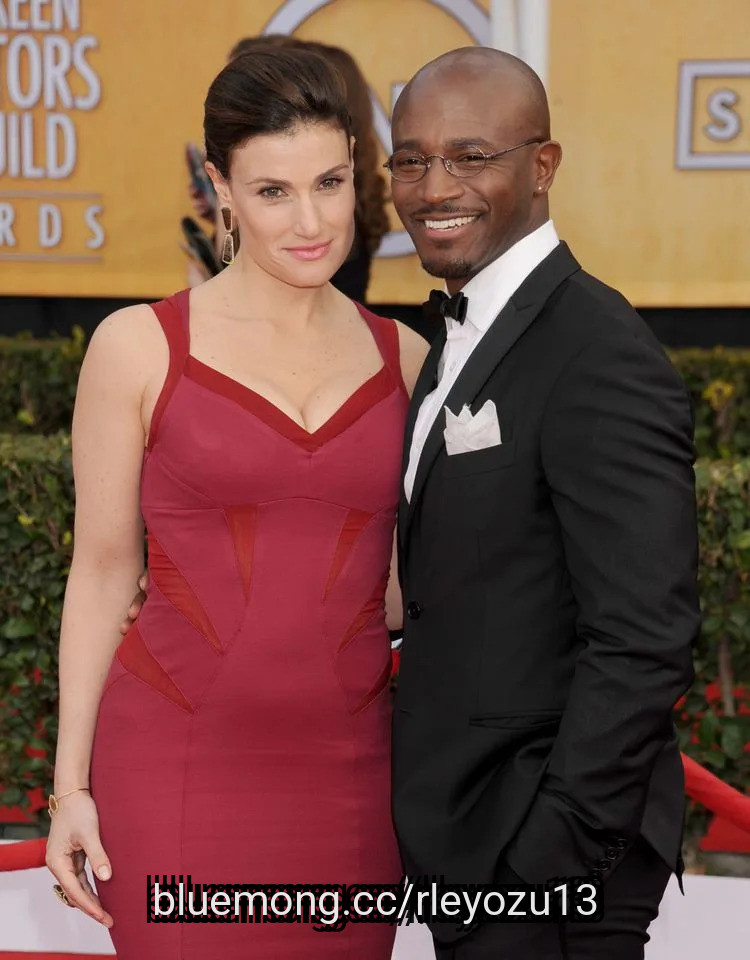
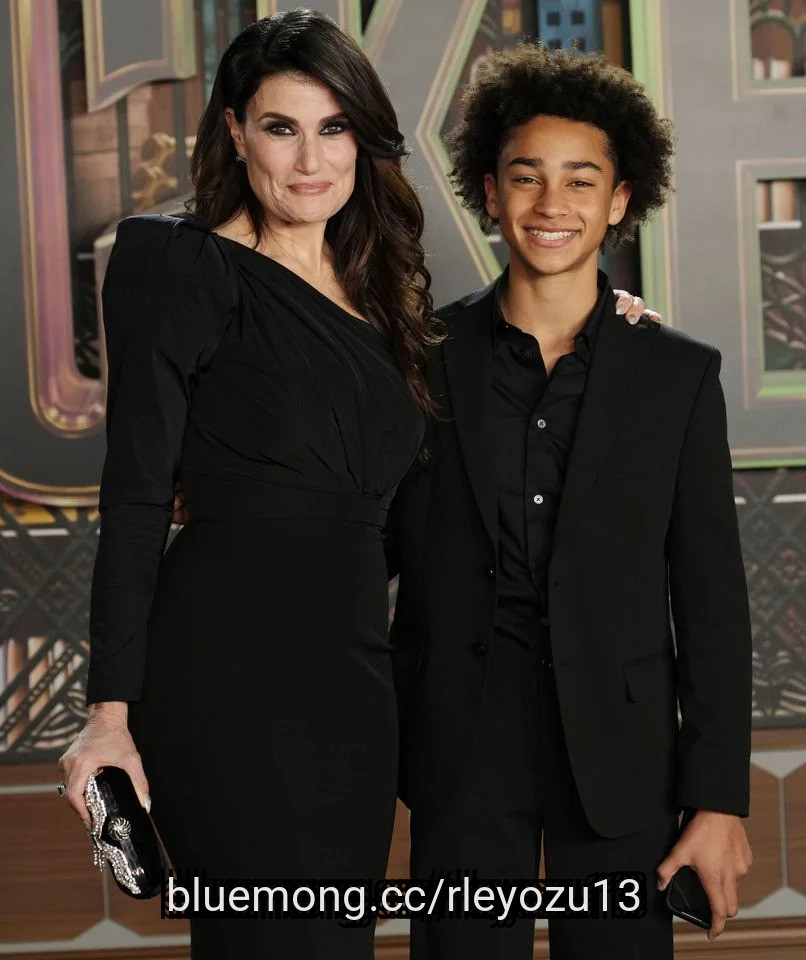
Idina Menzel opened up about her split with Taye Diggs 12 years after their divorce.
She discussed the dissolution of their relationship during an appearance at New York Comic Con on October 8.
"It was very complicated, that whole time," Menzel said.
Idina Meznel is reflecting on her split with Taye Diggs 12 years after their divorce. Appearing at New York Comic Con on October 8, the actress explained how her work on Frozen and the musical If/Then helped her process the major life change.
"We were separating and it was really hard," Menzel said. She and Diggs were married from 2003 and 2014, and the couple welcomed their son Walker in 2009.
#york #october #years

3 days ago
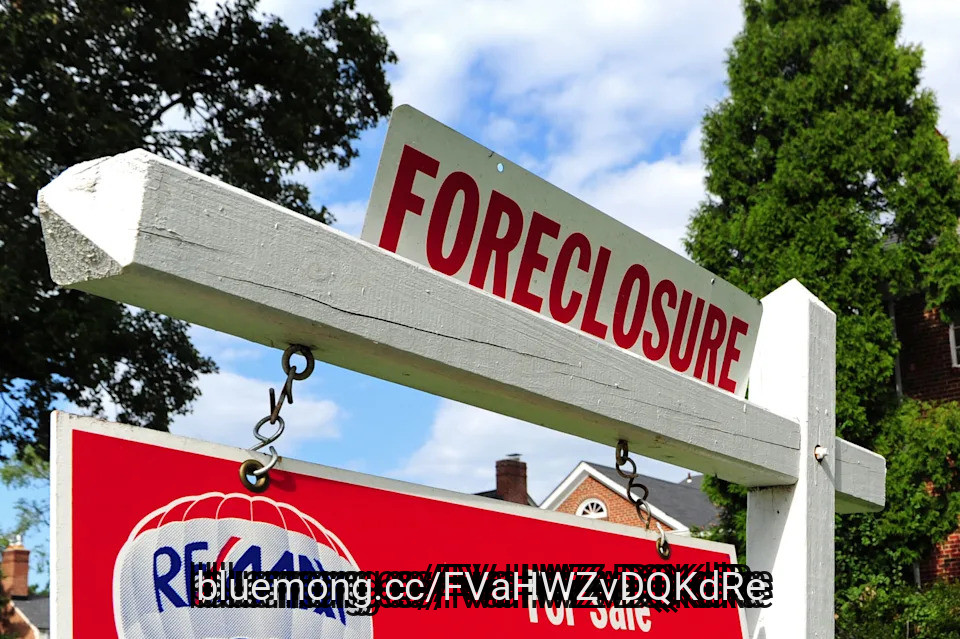
Americans are falling behind on their mortgages and are increasingly having their homes repossessed, a new report has found.
New data from real estate data firm ATTOM's August 2026 U.S. Foreclosure Market Report showed lenders repossessed 5,794 U.S. properties in August through completed foreclosures (REOs), an increase of a whopping 42 percent from a year earlier, and 22 percent from the previous month.
Texas was the hardest-hit state, with 1,835 REOs, followed by California (589 REOs), North Carolina (356 REOs), Arizona (296 REOs) and Alabama (286 REOs).
The report also showed a total of 40,277 U.S. properties with foreclosure filings – default notices, scheduled auctions or bank repossessions – a 13 percent increase from a year ago and up 1 percent from a month ago.
Rob Barber, CEO of ATTOM – a leading provider of property data, AI-powered intelligence and real estate ******* ytics solutions – said: "August's data shows that foreclosure activity continues to trend above year-ago levels, particularly in completed foreclosures, which saw a notable annual increase.
#Foreclosure
5 days ago
Americans are falling behind on their mortgages and are increasingly having their homes repossessed, a new report has found.
New data from real estate data firm ATTOM's August 2026 U.S. Foreclosure Market Report showed lenders repossessed 5,794 U.S. properties in August through completed foreclosures (REOs), an increase of a whopping 42 percent from a year earlier, and 22 percent from the previous month.
Texas was the hardest-hit state, with 1,835 REOs, followed by California (589 REOs), North Carolina (356 REOs), Arizona (296 REOs) and Alabama (286 REOs).
The report also showed a total of 40,277 U.S. properties with foreclosure filings – default notices, scheduled auctions or bank repossessions – a 13 percent increase from a year ago and up 1 percent from a month ago.
Rob Barber, CEO of ATTOM – a leading provider of property data, AI-powered intelligence and real estate ***** ytics solutions – said: "August's data shows that foreclosure activity continues to trend above year-ago levels, particularly in completed foreclosures, which saw a notable annual increase.
#real
5 days ago
Actress Jaime King and investment banker Austin Sosa have ended their marriage after completing California's required waiting period. A Los Angeles County Superior Court judge signed the final dissolution decree Friday, October 2, making the pair legally single.
According to court records cited by PEOPLE, neither King nor Sosa will receive spousal support. The court permanently ended King's ability to seek payments from Sosa, while Sosa waived his right to receive ongoing support from the actress.
The couple did not have children together, so their divorce did not require custody or child support arrangements. Sosa's initial filing also stated that the pair had no community property, real estate, or marital debts that needed to be divided by the court.
The divorce follows a brief marriage. King and Sosa reportedly married in April 2025 and publicly announced their engagement that July. Sosa filed for divorce on January 22, citing irreconcilable differences.
California law requires a divorce to remain pending for at least six months after the respondent receives the petition and summons. The final court decision came nearly nine months after the initial filing.
#sosa #divorce

7 days ago
Iran's top diplomat insisted on Sunday that there would be no military solution to the United States' war against the Islamic republic, with talks on ending the conflict apparently at an impasse.
A campaign of heavy bombardment failed to bring a decisive close to the war launched by the US and Israel in late February, and Washington in recent weeks has dialled back military operations in favour of economic pressure.
The main point of contention remains Iran's attempt to blockade the Strait of Hormuz, a vital conduit for Gulf oil and gas where a UK maritime agency reported on Sunday another tanker struck by an unknown projectile.
"If our enemies again choose the path of military confrontation, our response will be stronger than before, and we will defend ourselves with even more force," Iranian Foreign Minister Abbas Araghchi said at a gathering of foreign ambassadors.
"There is no military solution, nor any solution based on new sanctions," he continued, adding "only negotiations based on justice and fairness" could end the conflict.
#sunday #Israel


13 days ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ
20 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#adjusted #revenue #august
20 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
20 days ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount

20 days ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
20 days ago
Toward the end of the lightning round on September 17, a caller asked for Mad Money's host Jim Cramer's thoughts on Iron Mountain Incorporated (NYSE:IRM), and he replied:
It's been an incredible stock. It's a real estate investment trust, basically. And you know, we know that they shred, 3% yield, down 20 points from its high. I think it's a buy.
Iron Mountain Incorporated (NYSE:IRM) operates a highly durable business model centered on physical records management, secure document destruction, and expanding digital infrastructure. In Q2, total revenue reached $2.03 billion, representing an 18.7% increase year-over-year and 16.8% organic growth. The core physical storage business provides reliable cash flow, with storage rental revenue expanding 11.5% year-over-year excluding foreign-exchange effects across a global customer base of 240,000. Adjusted funds from operations grew 17% to $432.7 million, or $1.44 per share.
At the same time, management has channeled capital into scaling higher-growth segments, including digital solutions, ***** et lifecycle management, and data center operations. The data center segment posted 39% revenue growth during the second quarter, securing 110 megawatts in new leases through July and increasing power capacity across major enterprise markets. Operating as a real estate investment trust, the company maintains a quarterly dividend of $0.864 per share, offering shareholders a forward yield of over 3%.
On the other hand, Iron Mountain Incorporated (NYSE:IRM) faces risks inherent to capital-intensive real estate infrastructure expansion. Rapid buildouts of data center power capacity demand substantial capital expenditure, leading to elevated leverage across the balance sheet. Long-term debt, net of the current portion, reached approximately $17.1 billion at the end of the second quarter, increasing sensitivity to interest rate fluctuations and refinancing costs.
#revenue #Growth
21 days ago
Forgent Power Solutions, Inc. (NYSE:FPS) reported fiscal fourth-quarter revenue of approximately $462 million on September 15, up 94% year over year. Bookings reached $1.503 billion, increasing 375%, while backlog stood at $3.0 billion as of June 30, 2026.
The reported 3.3 times book-to-bill ratio compares quarterly bookings with quarterly revenue. Bookings and backlog are operating measures of order activity and outstanding contractual work, respectively. Neither represents cash collected, and backlog does not guarantee the timing of future revenue.
Forgent Power Solutions, Inc. (NYSE:FPS) expects fiscal 2027 revenue of $2.4 billion to $2.6 billion, implying 76% growth at the midpoint. The question is whether factories, employees, and working capital can support that expansion while preserving cash generation.
Forgent Power Solutions, Inc. (NYSE:FPS) already has evidence of stronger production economics. Fourth-quarter operating income reached $91.9 million, compared with $8.3 million a year earlier. Operating cash flow was $74 million, exceeding the quarter's $31 million of capital expenditures.
Those results suggest that rising output is beginning to cover the costs of expansion. Management attributed stronger profitability partly to revenue growing faster than operating costs as new campuses approached target production levels.
#operating #power #solutions #NYSE
21 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The Social Security trust fund is projected to be depleted by the end of 2032 — at which point benefits could be automatically cut by as much as 22% on average, according to the 2026 Trustees Report (1) put out by the Social Security Administration (SSA).
Now, two Democrat lawmakers have proposed a solution that would not only avoid the cut but also boost benefits for some older Americans on the program.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#Social #benefits #democrat
21 days ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year
21 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission
21 days ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily

21 days ago
Interested in Apollo Global Management Inc.? Here are five stocks we like better.
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade

21 days ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet


21 days ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast

21 days ago
SailPoint Inc. (NASDAQ:SAIL), a leading player within the enterprise identity security ****** e, recently expanded its strategic alliance with CrowdStrike. As part of the revised arrangement, the company's SailPoint SecOps Identity Intelligence will be integrated with CrowdStrike Falcon Next-Gen SIEM. This will help in expediting threat detection procedures, and will also incorporate access data and identity governance into the overall investigation process. The expanded partnership will facilitate security teams in lining up the identity insights with Falcon's existing security telemetry.
Copyright: franckito / 123RF Stock Photo
The announcement aligns strongly with SailPoint's broader strategic narrative revealed in its Q2 FY27 print. It builds upon several recent initiatives undertaken by the management, such as introduction of the SailPoint Identity Security solution. This is aimed toward integrating SailPoint Agentic Fabric with SailPoint Human Fabric for real-time discovery and security of complex digital ecosystems. The company also launched its Cursor Enterprise connector, which helps organizations to leverage a highly-integrated control plane to manage human developers and autonomous AI agents.
The recently released financials also back this narrative as the company delivered a 25% year-over-year growth in its annual recurring revenue, which stood at $1.231 billion. SailPoint generated $45 million in operating cash flow during the second quarter, along with $37 million in free cash flow.
By weaving SailPoint's identity intelligence into Falcon Next-Gen SIEM, customers gain extra context inside workflows they already rely on, making it easier to probe identity-related risks. The integration augments SailPoint's position at a time when identity threats are on a rise. This leads to an opportunity for SailPoint to cement itself as a leading provider of advanced security solutions.
#sailpoint #falcon #next

22 days ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment

22 days ago
Interested in Motorola Solutions, Inc.? Here are five stocks we like better.
Motorola Solutions expects broad-based growth, projecting 2026 gains of 10%–11% in mission-critical networks, about 11% in video security and about 15% in command-center software, supported by modernization of public-safety and federal infrastructure.
Silvus Technologies is becoming a major defense growth driver, with approximately $850 million in expected 2026 sales at current capacity. Motorola is expanding production, sales and R&D as demand grows for secure communications in contested environments and unmanned-systems operations.
D-Fend Solutions expands Motorola's counter-drone opportunity in public safety, airports, critical infrastructure and venues. The business was selected for a $1.5 billion U.S. Department of Homeland Security grant program and uses cyber-based technology to take control of and safely land threatening drones.
Motorola's $1.5B Bet to Own the Skies
#Growth #safety #infrastructure

22 days ago
On August 5, Cencora (NYSE:COR) reported results for its fiscal third quarter, which closed on June 30, and the headline numbers looked clean. Revenue rose 5.1% to $84.8 billion, adjusted earnings per share climbed 12.0% to $4.48, and management raised its full-year adjusted EPS outlook to $17.75 to $17.95. The company also repurchased $1 billion of its own stock during the quarter. But the profit story has moving parts, and a few of them pull in opposite directions.
Start with the gap between profit growth and sales growth. Adjusted operating income rose 17.0% while revenue grew only 5.1%. Much of the help came from gross profit, which jumped 23.2% on an adjusted basis as both segments contributed and the OneOncology acquisition in February lifted margins in the US business. In plain terms, adjusted gross margin widened 61 basis points to 4.16%, so the company keeps more gross profit from every dollar it sells.
The strength was not confined to one corner, either. US Healthcare Solutions grew operating income 15.9% on higher pharmaceutical sales and the OneOncology deal, while specialty volume to health systems and physician groups lifted its revenue. International Healthcare Solutions did better still, with operating income up 20.8% on strength in European distribution and global specialty logistics. Management also put cash to work, completing in one quarter the $1 billion of buybacks it had expected to finish by the close of calendar 2026. The board declared a $0.60 quarterly dividend as well, payable August 31, to holders of record on August 14.
Growth is costing more than it first appears. Adjusted operating expenses jumped 26.8%, faster than adjusted gross profit, because OneOncology brought expenses along with its profits. Even so, adjusted operating income amounts to just 1.46% of revenue, a thin cushion on a business this large. Financing adds weight too. Cencora funded part of the purchase with new senior notes plus variable-rate term loans, and net interest expense rose $58.9 million from a year earlier.
The sales mix carries its own drag. GLP-1 drugs for diabetes and weight loss are adding to revenue, but they earn lower gross margins, so each dollar of that growth is worth less to profit. Meanwhile, an oncology customer Cencora lost in 2025, and lower sales to a large mail order customer both held back US revenue, as did lower manufacturer prices on some brand pharmaceuticals. Cencora is also exploring strategic alternatives for a group of other businesses, and its April divestiture of US Consulting Services trimmed consulting sales.
#profit #operating #Growth #august

22 days ago
Des Moines, Iowa-based Principal Financial Group, Inc. (PFG) provides retirement, ******* et management, and insurance products and services to businesses, individuals, and institutional clients worldwide. The company has a market cap of $25 billion and operates through Retirement and Income Solutions, Principal ******* et Management, and Benefits and Protection segments.
Companies with a market cap of $10 billion or more are typically called "large-cap stocks." PFG fits squarely into that category, with a market cap above this threshold that reflects its substantial size and influence in the ******* et management industry.
Mark Cuban Says He Was Dizzy for Months, So He Built a VR Fix That Does at Home 'Much Of What A 180k Machine' Does
Bank of America Just Declared a 'Generational Entry Point' in U.S. Bonds. Why Investors Should Be Backing Up the Truck on Treasuries Here.
Nvidia, OpenAI, and Oracle's $745B Financing Circle Just Hit Its First Stress Test: A Fed Rate Hike
#asset #management #market #moines

22 days ago
GE Aerospace's $11.75 billion purchase of Consolidated Precision Products, announced September 8, is billed as fixing the castings bottleneck behind the company's $170 billion services backlog and a spare-parts delinquency rate that grew 20% sequentially in the second quarter.
The deal will not close until the second half of 2027, covers roughly a quarter of GE's airfoil needs, and CFO Rahul Ghai has told investors twice this month that "broad vertical integration is not the solution," calling CPP a "unique situation."
Sell-side price targets jumped hard after the announcement, with the mean target rising from $350.95 on June 30 to $401.00 by September 16, pushing the target-to-price ratio to 128.2%, the widest gap in over a year.
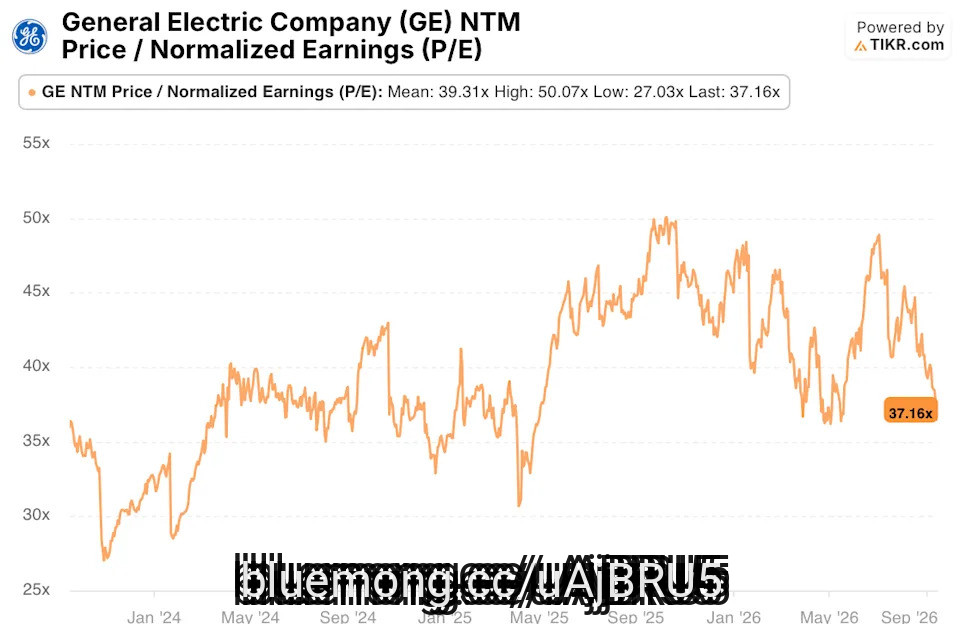
Over that same window, GE's share price fell from $373.73 to $312.90 and its NTM P/E multiple compressed to 37.16x, below its own two-year average of 39.31x and well off the roughly 50x peak reached a year earlier, even as consensus EPS estimates kept climbing smoothly through 2030 with no visible step-up.
GE Aerospace's (GE) own numbers make the case for urgency. Services backlog sits near $170 billion, internal shop visit capacity is running 40% oversubscribed, and spare-parts delinquency, shipments delayed by material shortages, grew 20% sequentially in the second quarter even as revenue rose. Management has said engines removed but not yet inducted into shops are up 60% year over year. That is the backdrop against which GE agreed to buy CPP, the world's third-largest maker of precision castings used in turbine blades and vanes.
#year #billion


22 days ago
Quantum computers can be better at processing data-heavy workloads in areas like science and cryptography, because they can use a concept called superposition to simulate multiple solutions to a problem at the same time. However, even the best quantum systems today are still making far too many errors to solve complex real-world problems.
Rigetti Computing (NASDAQ: RGTI) is one of the industry leaders right now, and it's making genuine progress. But considering even the company's most powerful quantum computers aren't overly useful yet, it's struggling to generate meaningful sales, so it's burning through truckloads of cash while it continues to conduct research and development.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
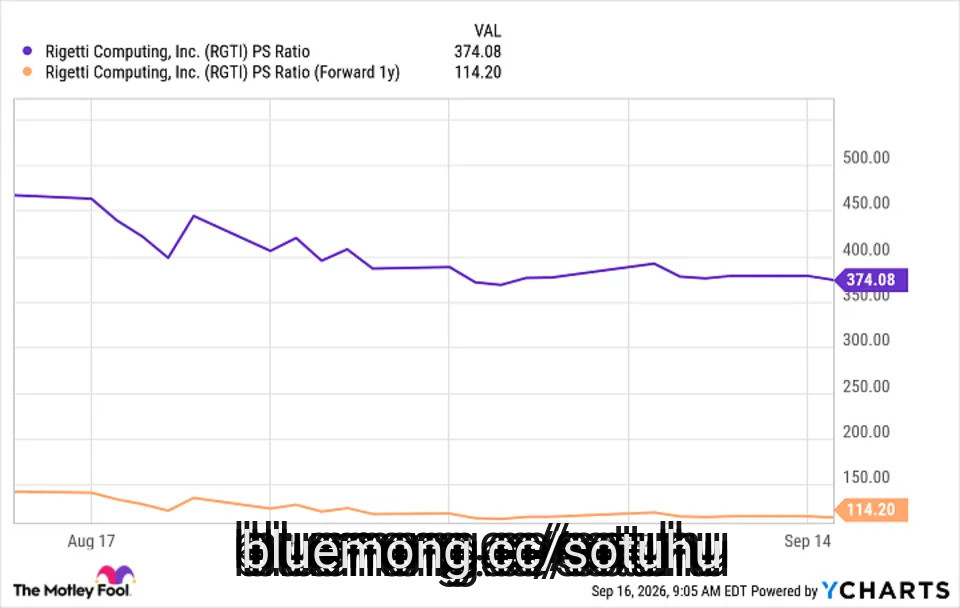
That creates a problem for shareholders, because Rigetti stock is trading at a sky-high valuation, which opens the door to potential downside if the company can't find a way to bring in significantly more revenue in the near future. Here's why I predict the stock will plummet over the next 12 months.
Rigetti built its own fabrication facility to produce chips, developed its own quantum programming language, and even created its own cloud platform, which it can rent to other businesses, thereby monetizing quantum computing capacity. By effectively operating its own end-to-end supply chain, the company can bring new systems to market much faster than many of its competitors.
#quantum #signal #even #company

22 days ago
During the September 14 episode of Mad Money, Jim Cramer addressed the broader tech sector pullback and mentioned Broadcom Inc. (NASDAQ:AVGO) as an attractive option for investors looking past short-term volatility. He stated:
Well, it's a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don't know… pulling in their horns. Actually, I think there's some real bargains in this group. Take Broadcom, the maker of chips, networking equipment, and tech infrastructure and software with a stock that's down more than 10% over the past month. At the beginning of this month, Broadcom reported a strong set of results, issued a spectacular multi-year forecast, but their guidance for the current quarter was, I don't know, viewed by some as in line.
The stock got slammed. I think Broadcom's still on track to put up some incredible growth because they're at the heart of the AI ecosystem because the company's never let us down in all the years my Charitable Trust has owned it. And down here, roughly 150 points below its June high, the stock may be too cheap to ignore.
Recent financial reports from Broadcom Inc. (NASDAQ:AVGO) highlights the scale of expansion driving its core semiconductor and infrastructure divisions. Total revenue for the fiscal third quarter reached $29.6 billion, representing an 85.5% increase compared to the same period in the previous year. Artificial intelligence semiconductor revenue surged 221% to $16.7 billion, accounting for roughly 56% of total revenue. Remaining performance obligations climbed significantly to $179.2 billion, providing substantial visibility into future contracted revenue. Broadcom also serves major hyperscale AI customers including Alphabet and Meta Platforms.
Management raised its full year guidance to $58 billion from $56 billion in artificial intelligence revenue, while projecting $115 billion for fiscal 2027 and $230 billion for fiscal 2028. The figures highlight a deep integration into the enterprise artificial intelligence ecosystem through custom accelerators and high-speed networking solutions.
#down #year #fiscal #NASDAQ

22 days ago
On September 2, 2026, Phreesia, Inc. (NYSE:PHR) reported second-quarter fiscal 2027 results for the period ended July 31, 2026. Revenue rose 10% to $129.5 million and adjusted EBITDA climbed to $32.9 million from $22.1 million a year earlier, a 25% margin. Net income reached $1.9 million, marking the company's fifth consecutive quarter of profitability. Management reaffirmed full-year revenue guidance of $510 million to $520 million and adjusted EBITDA of $125 million to $135 million.
The disagreement on Wall Street is about what that reaffirmation actually signals.
Wells Fargo found the highlight in Network Solutions, which grew 9% year-over-year, and pointed to the ProviderConnect pilot delivering a 4% prescription lift in a GLP-1 campaign that management says is generating follow-on business; the firm raised its target on Phreesia, Inc. (NYSE:PHR) to $10 from $9 while holding an Equal Weight rating.
DA Davidson stayed at Buy despite trimming its target on Phreesia, Inc. (NYSE:PHR) to $13 from $14, arguing the stock sold off on a reiterated guide even though network solutions activity is tracking more encouragingly than the prior outlook and AccessOne is opening a growing opportunity in alternative consumer payment options.
Baird ******* yst Joe Vruwink lifted his target to $11 from $10 at Neutral after updating his model.
#million #solutions
22 days ago
Generac Holdings (GNRC) shares ripped higher on Sept. 17 after management announced a multi-billion-dollar commercial partnership with Amazon (AMZN). In its press release, GNRC said its pivotal supply agreement with the cloud and e-commerce giant is designed to furnish backup power solutions for its expanding data center footprint.
The AMZN news brings much-needed reprieve to Generac stock that was otherwise down roughly 40% versus its year-to-date high in late June.
Why It's Time to Load Up on Nvidia Stock
ORCL Stock Layoffs: What to Know About the Latest Oracle Job Cuts
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#amzn #holdings #load


23 days ago
Toast (NYSE: TOST) is a leading provider of financial technology services for businesses in the restaurant industry. The business is growing rapidly and still seems to have a long runway for expansion, but some of its business segments are carrying a lot more weight on the profitability front than others.
In the second quarter, Toast's revenue grew 23% to reach roughly $1.91 billion. Meanwhile, the business posted net income of $154 million in the period -- good for a margin of roughly 80.7%. The company's payments business once again did the heavy lifting in driving profits, but the picture is also more nuanced.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, the financial technology solutions segment that includes Toast's payments business accounted for $1.57 billion of its overall sales in the period -- roughly 82.2% of the total pie. While the segment's total cost of revenue accounted for roughly $1.21 billion of the total $1.39 billion cost of sales in the quarter, it was still central to the business's gross profit of roughly $516 million in the quarter.
Notably, the company's hardware and professional services segment had a substantially negative gross margin in Q2. While the unit posted revenue of roughly $48 million in the period, it had a cost of revenue of $116 million -- and that doesn't factor in operating expenses for the segment.
#business