1 day ago
Layoff plans in October fell to the lowest level since 2023 as companies turned their attention to retaining existing employees and adding seasonal help ahead of the holidays.
US employers announced 43,994 job cuts in October, up slightly from September but down 71% from a year earlier, according to outplacement firm Challenger, Gray & Christmas.
Job cuts have been muted this year as the labor market stays in "low hire, low fire" mode. Announced cuts in the first 10 months of the year are at their lowest level since 2022.
"This is a low-fire environment," Andy Challenger, chief revenue officer at Challenger, said in a statement. "Employers are holding on to the workers they have heading into the holidays, and the hiring they are announcing is largely short-term, seasonal work. Companies want the flexibility to meet holiday demand without adding permanent headcount."
Food companies announced nearly 10,000 layoffs in October, followed by the technology sector's 5,600 cuts. Tech companies have announced more than 170,000 job cuts this year, usurping their total for all of 2025.
#announced #since
US employers announced 43,994 job cuts in October, up slightly from September but down 71% from a year earlier, according to outplacement firm Challenger, Gray & Christmas.
Job cuts have been muted this year as the labor market stays in "low hire, low fire" mode. Announced cuts in the first 10 months of the year are at their lowest level since 2022.
"This is a low-fire environment," Andy Challenger, chief revenue officer at Challenger, said in a statement. "Employers are holding on to the workers they have heading into the holidays, and the hiring they are announcing is largely short-term, seasonal work. Companies want the flexibility to meet holiday demand without adding permanent headcount."
Food companies announced nearly 10,000 layoffs in October, followed by the technology sector's 5,600 cuts. Tech companies have announced more than 170,000 job cuts this year, usurping their total for all of 2025.
#announced #since


1 day ago
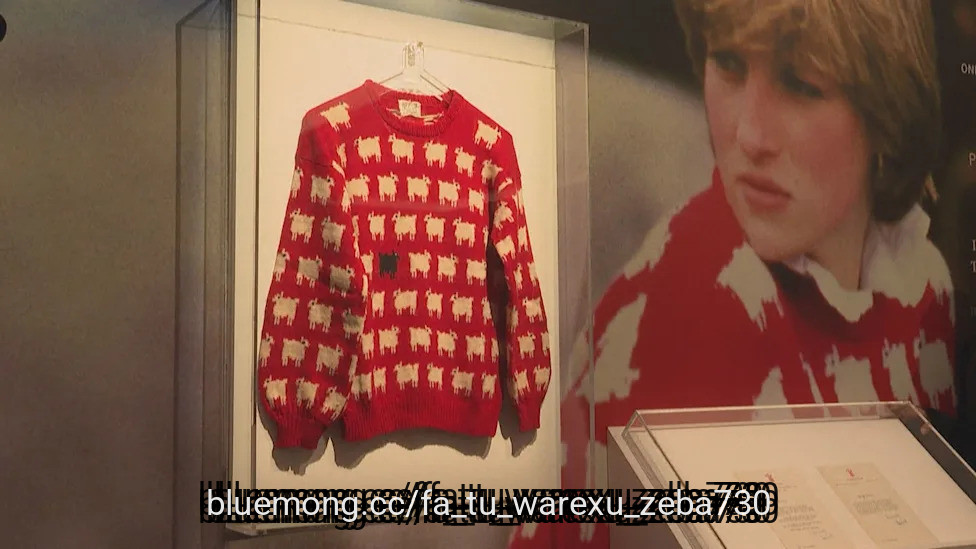
Princess Diana remains one of the most influential royal style figures decades after her death. From glamorous evening gowns to casual sweatshirts, her clothes attracted enormous attention and often carried meanings that went far beyond fashion. Few pieces illustrate that fascination better than her famous red Black Sheep sweater, featuring rows of white sheep and a single black one standing apart from the flock.
Diana first wore the Warm & Wonderful sweater in 1981, shortly after her engagement to Prince Charles. The playful design quickly attracted attention, particularly because the lone black sheep invited interpretations about Diana's own position within royal life. Those interpretations remain speculative, but there is clear evidence that she valued the garment. After the original sweater was damaged, Buckingham Palace contacted the designers seeking a repair or replacement. Diana later appeared publicly in the replacement.
Years later, the original sweater was rediscovered and offered at auction through Sotheby's in 2023. Before the sale, it carried an estimate of $50,000 to $80,000. Its significance came from more than Diana simply having worn it. The accompanying correspondence helped establish its history, while photographs of Diana wearing the distinctive design made it instantly recognizable to collectors and royal fashion enthusiasts.
The final result dramatically exceeded expectations. The sweater sold for $1.143 million, including fees, setting a record at the time for an item of clothing worn by Diana at auction. The price also demonstrated how dramatically demand for objects connected with the princess had grown. Other pieces from her wardrobe had already achieved impressive results, including a purple Victor Edelstein evening gown that sold for more than $600,000 earlier in 2023.
Diana's wardrobe continues to attract this level of interest because her clothing became closely connected with her public identity. Early in her royal life, she embraced romantic dresses and traditional silhouettes. Over time, her wardrobe became increasingly confident, incorporating streamlined tailoring, memorable eveningwear and relaxed casual pieces.
#pieces #princess #evening #casual
Diana first wore the Warm & Wonderful sweater in 1981, shortly after her engagement to Prince Charles. The playful design quickly attracted attention, particularly because the lone black sheep invited interpretations about Diana's own position within royal life. Those interpretations remain speculative, but there is clear evidence that she valued the garment. After the original sweater was damaged, Buckingham Palace contacted the designers seeking a repair or replacement. Diana later appeared publicly in the replacement.
Years later, the original sweater was rediscovered and offered at auction through Sotheby's in 2023. Before the sale, it carried an estimate of $50,000 to $80,000. Its significance came from more than Diana simply having worn it. The accompanying correspondence helped establish its history, while photographs of Diana wearing the distinctive design made it instantly recognizable to collectors and royal fashion enthusiasts.
The final result dramatically exceeded expectations. The sweater sold for $1.143 million, including fees, setting a record at the time for an item of clothing worn by Diana at auction. The price also demonstrated how dramatically demand for objects connected with the princess had grown. Other pieces from her wardrobe had already achieved impressive results, including a purple Victor Edelstein evening gown that sold for more than $600,000 earlier in 2023.
Diana's wardrobe continues to attract this level of interest because her clothing became closely connected with her public identity. Early in her royal life, she embraced romantic dresses and traditional silhouettes. Over time, her wardrobe became increasingly confident, incorporating streamlined tailoring, memorable eveningwear and relaxed casual pieces.
#pieces #princess #evening #casual

8 days ago
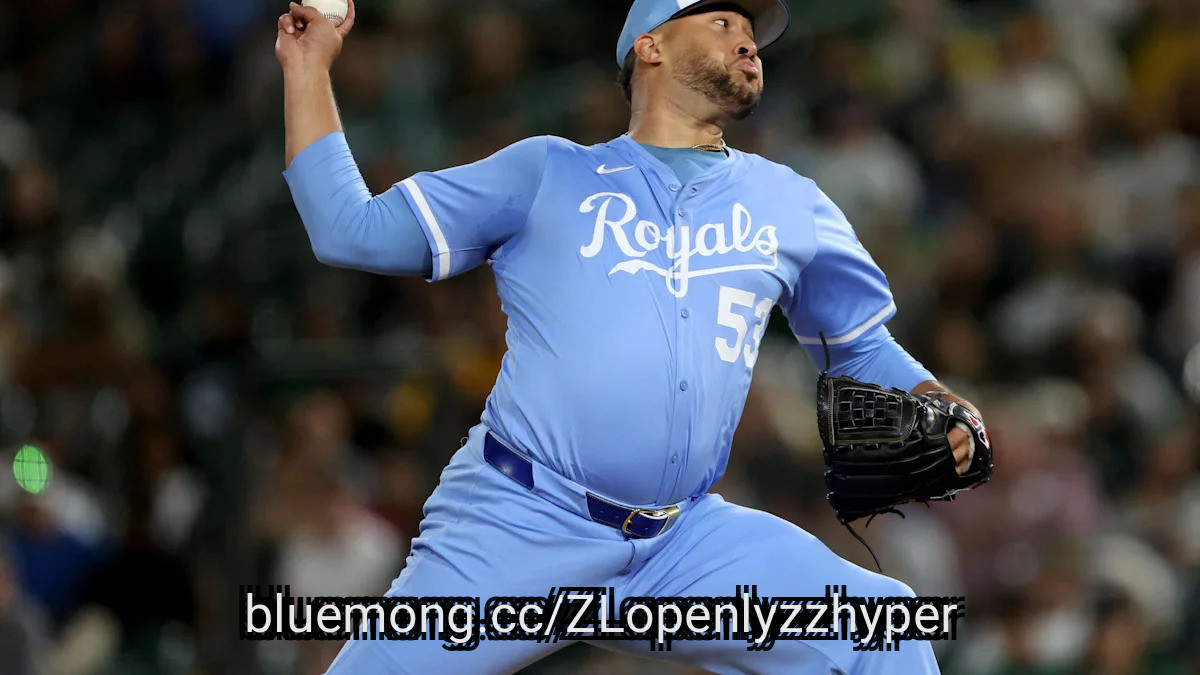
The Kansas City Royals made their first big offseason move on Thursday by cutting ties with closer Carlos Estévez. The team declined his $13 million club option, which means he hits the open market. Instead of paying that high price, Kansas City will hand him a $2 million buyout. This decision clears the books but leaves a huge hole in the bullpen after he led the league with 42 saves in 2025.
At the same time, the club exercised a $2.5 million option on right-hander Tony Gonsolin. Per MLB.com Royals, this move keeps a former All-Star under contract for 2027 despite his recent injury struggles. It is a low-cost gamble for a pitcher who once went 16-1 with a 2.14 ERA in 2022. After ending last season with a 5.07 bullpen ERA that ranked 29th in the majors, the Royals must acquire all available pitching help.
Letting Estévez walk feels risky, but the math makes sense for a small-market team. He signed a two-year, $22.2 million deal before 2025 and delivered a 2.45 ERA that year. However, his 2026 season was a disaster filled with injuries and blown saves. He was limited to just one appearance before a comebacker hit his foot and a rotator cuff strain ended his year. According to Yardbarker, his strikeout rate dropped while his walk rate climbed in 2025, showing he was already losing a step.
Paying $13 million for a pitcher who might not even throw a pitch in 2027 is hard to justify. The Royals are better off taking the $2 million buyout and trying to find a cheaper replacement. They need to fix a relief corps that allowed too many runs and lost too many games. The 69-93 record from last year proves the bullpen was a major problem that this move attempts to address.
Bringing back Gonsolin is a different kind of bet, one based on potential rather than recent results. He joined the team on August 13 while recovering from elbow surgery he had in August 2025. In just one major league outing this year against the White Sox, the 32-year-old surrendered five runs across 2 2/3 innings. Per Royals Keep, the $2.5 million price tag is very affordable for a starter with his career stats of 37 wins and 13 losses.
#year #kansas #city
At the same time, the club exercised a $2.5 million option on right-hander Tony Gonsolin. Per MLB.com Royals, this move keeps a former All-Star under contract for 2027 despite his recent injury struggles. It is a low-cost gamble for a pitcher who once went 16-1 with a 2.14 ERA in 2022. After ending last season with a 5.07 bullpen ERA that ranked 29th in the majors, the Royals must acquire all available pitching help.
Letting Estévez walk feels risky, but the math makes sense for a small-market team. He signed a two-year, $22.2 million deal before 2025 and delivered a 2.45 ERA that year. However, his 2026 season was a disaster filled with injuries and blown saves. He was limited to just one appearance before a comebacker hit his foot and a rotator cuff strain ended his year. According to Yardbarker, his strikeout rate dropped while his walk rate climbed in 2025, showing he was already losing a step.
Paying $13 million for a pitcher who might not even throw a pitch in 2027 is hard to justify. The Royals are better off taking the $2 million buyout and trying to find a cheaper replacement. They need to fix a relief corps that allowed too many runs and lost too many games. The 69-93 record from last year proves the bullpen was a major problem that this move attempts to address.
Bringing back Gonsolin is a different kind of bet, one based on potential rather than recent results. He joined the team on August 13 while recovering from elbow surgery he had in August 2025. In just one major league outing this year against the White Sox, the 32-year-old surrendered five runs across 2 2/3 innings. Per Royals Keep, the $2.5 million price tag is very affordable for a starter with his career stats of 37 wins and 13 losses.
#year #kansas #city

8 days ago
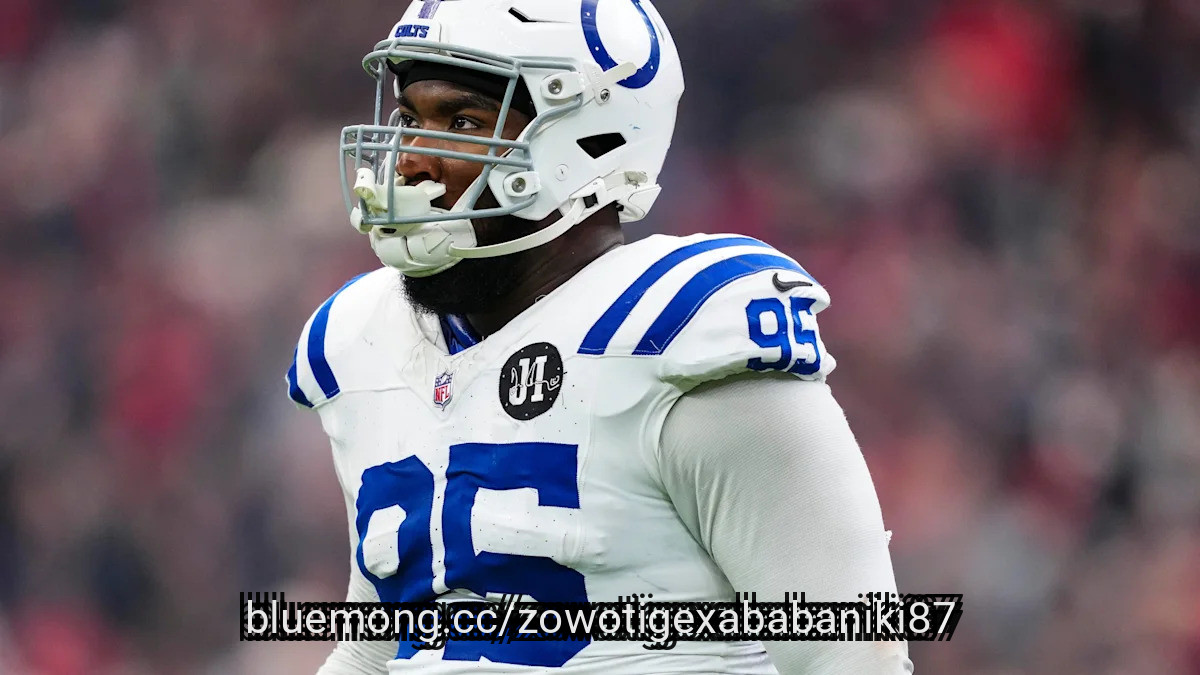
According to NFL Network's Mike Garafolo, despite other team's recent inquiries, the Indianapolis Colts have no intentions of trading breakout defensive tackle Ade Adebawore ahead of the league's trade deadline:
With longtime veteran DeForest Buckner's departure, the 25-year-old Adebawore, who was originally a 2023 4th round pick by Indianapolis, is expected to immediately start full-time as his replacement going forward in 2026.
While those are big shoes to fill at 3T, Adebawore has had a standout campaign in a rotational role, recording 17 tackles (7 solo), a pass defensed, 4.0 sacks, and 15 total QB pressures during 7 games (1 start) this season.
Athletic, fast, twitchy, and featuring a surprisingly strong bull rush for his size at 6,'2", 282 pounds, Adebawore has really been flashing his immense athleticism so far this season and turning it into significant on-the-field production—albeit during rotational reps previously:
As a pending free agent in the last year of his current rookie contract, Adebawore appears to be an ascending young player and potential building block, who the rebuilding Colts would ******* uredly like to keep long-term defensively, with an ample amount of projected 2027 available team salary cap ******* e at $61.9M right now.
#season
With longtime veteran DeForest Buckner's departure, the 25-year-old Adebawore, who was originally a 2023 4th round pick by Indianapolis, is expected to immediately start full-time as his replacement going forward in 2026.
While those are big shoes to fill at 3T, Adebawore has had a standout campaign in a rotational role, recording 17 tackles (7 solo), a pass defensed, 4.0 sacks, and 15 total QB pressures during 7 games (1 start) this season.
Athletic, fast, twitchy, and featuring a surprisingly strong bull rush for his size at 6,'2", 282 pounds, Adebawore has really been flashing his immense athleticism so far this season and turning it into significant on-the-field production—albeit during rotational reps previously:
As a pending free agent in the last year of his current rookie contract, Adebawore appears to be an ascending young player and potential building block, who the rebuilding Colts would ******* uredly like to keep long-term defensively, with an ample amount of projected 2027 available team salary cap ******* e at $61.9M right now.
#season

18 days ago
Paris Saint-Germain have a selection problem on the left of defence before their Champions League meeting with Barcelona: Nuno Mendes is injured, and Lucas Digne is the natural alternative against Lamine Yamal. Mundo Deportivo reported the situation on 19 October, describing Mendes as Luis Enrique's preferred answer to the Barcelona winger.
The timing matters for the Catalans, with Yamal in excellent form. His impact in Barcelona's comeback against Galatasaray underlined the threat PSG will need to manage on Tuesday.
Digne's recent outing against Strasbourg did little to strengthen his case. Mundo Deportivo **** sed the Frenchman's display in PSG's 3-1 defeat as laboured and lacking in decisiveness, and reported that Luis Enrique substituted him as he changed course after starting several reserves.
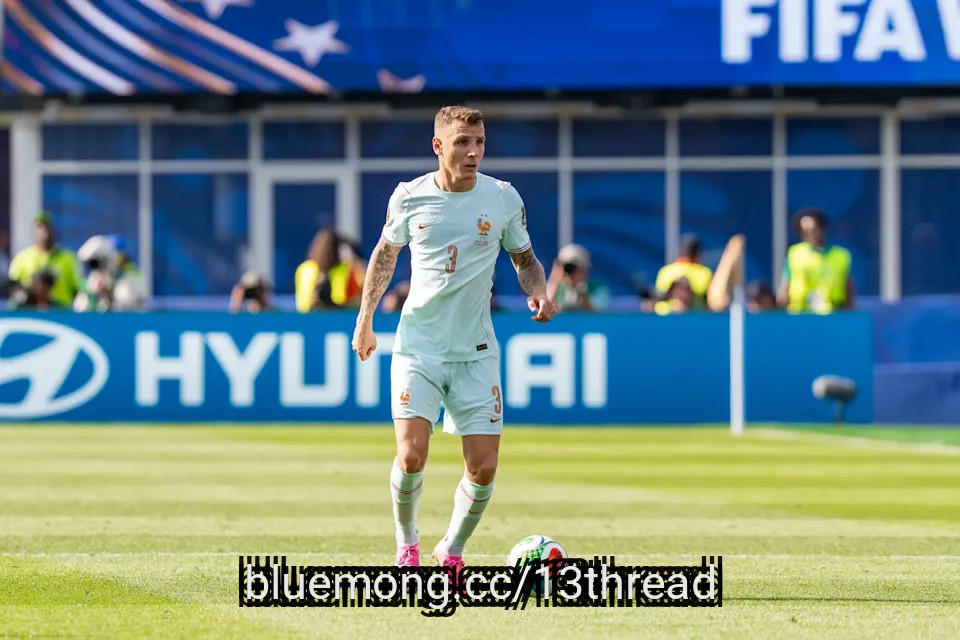
Lucas Digne playing for France. – Photo: Bryan Berlin / CC BY-SA 4.0
That leaves the coach weighing a natural replacement whose latest performance raised questions, rather than simply making a like-for-like switch without concern. Digne is also a former Barcelona player, having spent two seasons at the club from 2016 to 2018.
#mundo #luis
The timing matters for the Catalans, with Yamal in excellent form. His impact in Barcelona's comeback against Galatasaray underlined the threat PSG will need to manage on Tuesday.
Digne's recent outing against Strasbourg did little to strengthen his case. Mundo Deportivo **** sed the Frenchman's display in PSG's 3-1 defeat as laboured and lacking in decisiveness, and reported that Luis Enrique substituted him as he changed course after starting several reserves.
Lucas Digne playing for France. – Photo: Bryan Berlin / CC BY-SA 4.0
That leaves the coach weighing a natural replacement whose latest performance raised questions, rather than simply making a like-for-like switch without concern. Digne is also a former Barcelona player, having spent two seasons at the club from 2016 to 2018.
#mundo #luis


18 days ago
The Los Angeles Rams are facing growing concerns over their special teams after an 18-16 defeat to the Arizona Cardinals left Sean McVay's side with a 2-4 record.
Los Angeles lost kicker Blake Grupe to a knee injury during the game, raising the possibility that the team could need another replacement after releasing Harrison Mevis following his missed kick against the Buffalo Bills.
The latest setback has added to the pressure on a Rams team that entered the season with Super Bowl ambitions but has struggled to find consistency.
According toThe Athletic's Nate Atkins, the Rams are becoming increasingly nervous about their special teams unit as the problems continue to mount.
"The problems are just so widespread that it can be hard to know where to start," Atkins wrote. "The kicking game is chief among them, because the Rams could need a third starting kicker if Grupe's knee injury is serious, after Grupe replaced the waived Harrison Mevis last week."
#grupe #mevis #kicker
Los Angeles lost kicker Blake Grupe to a knee injury during the game, raising the possibility that the team could need another replacement after releasing Harrison Mevis following his missed kick against the Buffalo Bills.
The latest setback has added to the pressure on a Rams team that entered the season with Super Bowl ambitions but has struggled to find consistency.
According toThe Athletic's Nate Atkins, the Rams are becoming increasingly nervous about their special teams unit as the problems continue to mount.
"The problems are just so widespread that it can be hard to know where to start," Atkins wrote. "The kicking game is chief among them, because the Rams could need a third starting kicker if Grupe's knee injury is serious, after Grupe replaced the waived Harrison Mevis last week."
#grupe #mevis #kicker


29 days ago
The United States military has had 81 aircraft destroyed or damaged in the war with Iran, a Congressional Research Service report released this week says.
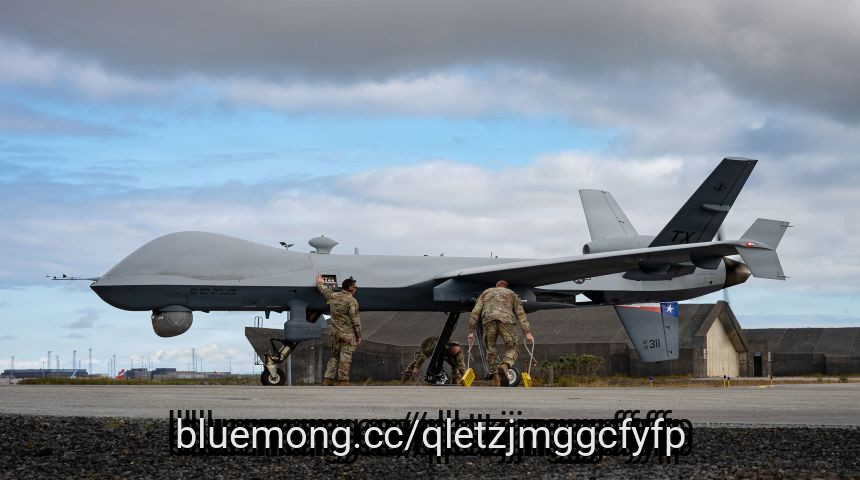
The number includes both airplanes and helicopters as well as drones, with the MQ-9 Reaper drone – used for intelligence, surveillance and reconnaissance, close air support and combat search and rescue – accounting for more than half of the losses.
But also on the list are some of the Pentagon’s most-prized ***** ets, including an F-35A fighter jet and an E-3 Sentry, the four-engine jet with a large radar dome atop the fuselage used for target tracking and airspace management.
The total cost of the aircraft lost is between $1.9 billion and $3.3 billion, depending on the Defense Department’s plans for replacements, the report said, citing figures from the Congressional Budget Office.
The total cost of the war is much higher – at least $45 billion, sources have told CNN. That figure doesn’t include damage to infrastructure at US bases in the region, including those where some of the aircraft losses happened.
#congressional #report #including #total
The number includes both airplanes and helicopters as well as drones, with the MQ-9 Reaper drone – used for intelligence, surveillance and reconnaissance, close air support and combat search and rescue – accounting for more than half of the losses.
But also on the list are some of the Pentagon’s most-prized ***** ets, including an F-35A fighter jet and an E-3 Sentry, the four-engine jet with a large radar dome atop the fuselage used for target tracking and airspace management.
The total cost of the aircraft lost is between $1.9 billion and $3.3 billion, depending on the Defense Department’s plans for replacements, the report said, citing figures from the Congressional Budget Office.
The total cost of the war is much higher – at least $45 billion, sources have told CNN. That figure doesn’t include damage to infrastructure at US bases in the region, including those where some of the aircraft losses happened.
#congressional #report #including #total
29 days ago
When a caller mentioned that they are thinking about adding to their position in Simon Property Group, Inc. (NYSE:SPG) during the October 2 episode of Mad Money, Jim Cramer commented:
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate

1 month ago
Sean "Diddy" Combs is headed back into solitary confinement, a day after a report described a prison life of massages, smuggled liquor, and contraband phones.
Staff at FCI Fort Dix are returning Combs to the facility's Special Housing Unit, according to TMZ, which was told the move came in direct response to this week's NBC News reporting on his alleged perks. Sources described the placement as typical procedure while prison officials run an investigation.
The report in question drew on four men who spent time in Combs' unit at the New Jersey prison. They said the mogul had other inmates making his bed, doing his laundry, and cleaning his toilet before he used it.
Sources also revealed to NBC News that inmates cooked for him on makeshift heating elements, turning out curry chicken, pizza and empanadas, and that others gave him Chinese-style massages. Thousands of dollars a month allegedly flowed into their commissary accounts.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#shop
Staff at FCI Fort Dix are returning Combs to the facility's Special Housing Unit, according to TMZ, which was told the move came in direct response to this week's NBC News reporting on his alleged perks. Sources described the placement as typical procedure while prison officials run an investigation.
The report in question drew on four men who spent time in Combs' unit at the New Jersey prison. They said the mogul had other inmates making his bed, doing his laundry, and cleaning his toilet before he used it.
Sources also revealed to NBC News that inmates cooked for him on makeshift heating elements, turning out curry chicken, pizza and empanadas, and that others gave him Chinese-style massages. Thousands of dollars a month allegedly flowed into their commissary accounts.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#shop

1 month ago
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of Hollywood because his fellow A-listers would "make fun" of him—while opening up about the very different life he has built away from Los Angeles.
The 53-year-old "Ransom Canyon" star recently spoke about his experience with testosterone replacement therapy, revealing that his former representatives had warned him that publicly attaching himself to the treatment could damage his image and career.
Duhamel, who co-founded men's health company Gatlan, said during an appearance on Dave Asprey's "The Human Upgrade" podcast that he initially had reservations about becoming so publicly involved with the company because of the potential response in Hollywood.
"I won't tell you the agency that I'm no longer with, but they said, 'Don't do it. It's bad for your image,'" he recalled. "And I was like, 'All right, watch.'"
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of town in Hollywood—while opening up about the very different life he has built away from Los Angeles. (CBS Mornings)
#duhamel #left
The 53-year-old "Ransom Canyon" star recently spoke about his experience with testosterone replacement therapy, revealing that his former representatives had warned him that publicly attaching himself to the treatment could damage his image and career.
Duhamel, who co-founded men's health company Gatlan, said during an appearance on Dave Asprey's "The Human Upgrade" podcast that he initially had reservations about becoming so publicly involved with the company because of the potential response in Hollywood.
"I won't tell you the agency that I'm no longer with, but they said, 'Don't do it. It's bad for your image,'" he recalled. "And I was like, 'All right, watch.'"
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of town in Hollywood—while opening up about the very different life he has built away from Los Angeles. (CBS Mornings)
#duhamel #left



1 month ago
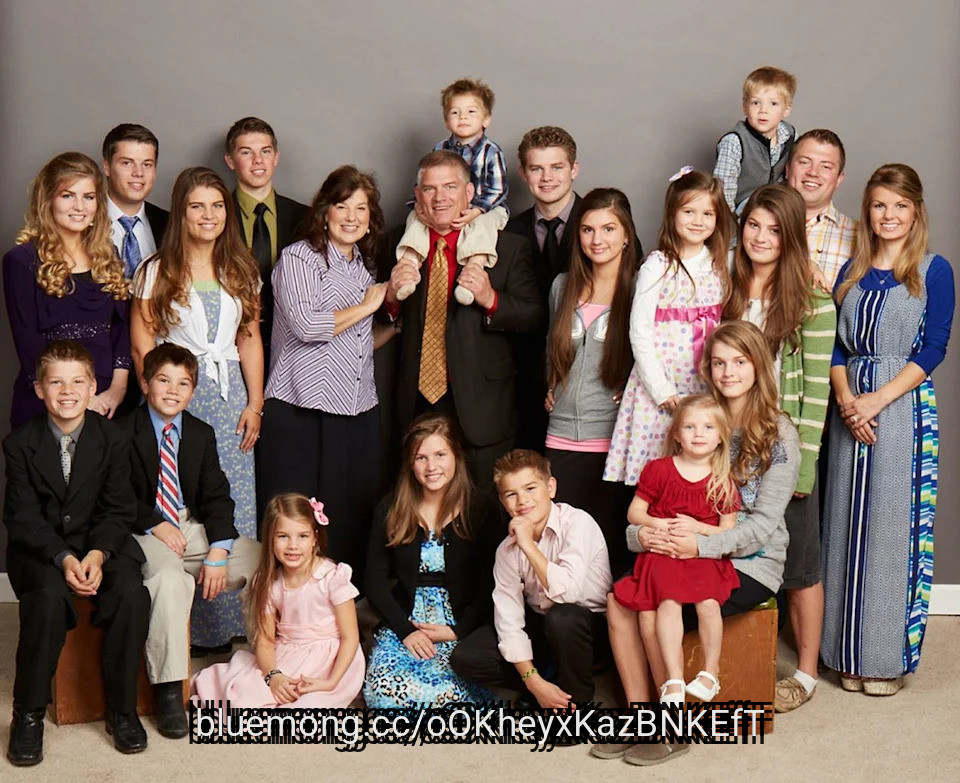
Bringing Up Bates alum Gil Bates suffered a heart attack after experiencing unusual chest sensations and occasional jaw pain for two weeks
Doctors discovered an 80% blockage in his LAD artery and a 95% blockage in his RCA artery, leading to the placement of two stents
Gil's wife, Kelly Jo Bates, said he is heading home and will begin cardiac therapy next week
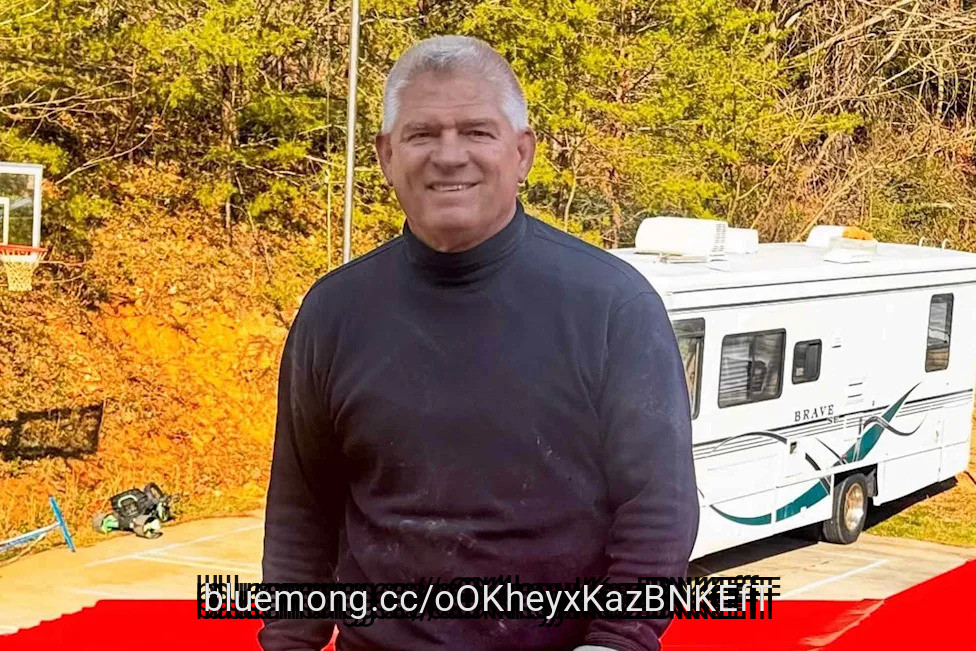
Gil Bates is recovering after suffering a heart attack.
The Bringing Up Bates alum, 61, was hospitalized earlier this week after experiencing an unusual sensation in his chest for approximately two weeks, his wife, Kelly Jo Bates, revealed in an Instagram post on Wednesday, Sept. 30.
#chest #weeks
Doctors discovered an 80% blockage in his LAD artery and a 95% blockage in his RCA artery, leading to the placement of two stents
Gil's wife, Kelly Jo Bates, said he is heading home and will begin cardiac therapy next week
Gil Bates is recovering after suffering a heart attack.
The Bringing Up Bates alum, 61, was hospitalized earlier this week after experiencing an unusual sensation in his chest for approximately two weeks, his wife, Kelly Jo Bates, revealed in an Instagram post on Wednesday, Sept. 30.
#chest #weeks


1 month ago
Shares of AutoZone (NYSE: AZO) rose on Tuesday after the automotive replacement parts and accessories distributor reported stronger-than-expected profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AutoZone's net sales grew 5.6% year over year to $6.6 billion in its fiscal 2026 fourth quarter, which ended on Aug. 29.
The auto-parts purveyor opened 175 stores during the quarter and a total of 374 over the trailing 12 months. AutoZone ended the period with 8,031 stores, including 6,863 stores in the U.S., 1,001 in Mexico, and 167 in Brazil.
Additionally, same-store sales, which measure revenue from locations open for at least a year, increased by 2.7%, or 1.5% when excluding foreign currency fluctuations.
#year #autozone #quarter #NYSE
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AutoZone's net sales grew 5.6% year over year to $6.6 billion in its fiscal 2026 fourth quarter, which ended on Aug. 29.
The auto-parts purveyor opened 175 stores during the quarter and a total of 374 over the trailing 12 months. AutoZone ended the period with 8,031 stores, including 6,863 stores in the U.S., 1,001 in Mexico, and 167 in Brazil.
Additionally, same-store sales, which measure revenue from locations open for at least a year, increased by 2.7%, or 1.5% when excluding foreign currency fluctuations.
#year #autozone #quarter #NYSE

2 months ago
Veteran ******* yst Jim Cramer sees something in Apple's (AAPL) latest launch that is more than a reason for its customers to buy another replacement phone.
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran


2 months ago
On September 15, Digital Realty (NYSE:DLR) made ServiceFabric MCP available, a software layer that lets AI agents design, monitor and troubleshoot network connections across more than 800 data centers, including third-party sites. That nudges a real estate company toward becoming a control panel for enterprise AI. It arrives after second quarter results reported on July 23, when Core FFO per share, the company's preferred earnings yardstick, excluding net promote rose to $2.13 from $1.87 a year earlier. Here is what the launch does, and what it has yet to prove.
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18

2 months ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable

2 months ago
On September 15, Arthur J. Gallagher & Co. (NYSE:AJG) announced that it had bought McMillan Insurance & Bonding Inc., an Englewood, Colorado, firm that operates as Innovise Business Consultants. Gallagher did not say what it paid. On its own, the deal is a footnote. But it is one of many, and the way those deals show up in earnings is where the debate over this stock really lives.
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth
On July 30, Gallagher reported results for the quarter ended June 30, and the top line was hard to argue with. Revenue from its combined Brokerage and Risk Management businesses grew 24%, and organic growth, which leaves out acquisitions, was 6%. That second number shows clients are staying and spending. It was not confined to one corner, either, since organic fees in the risk management arm rose 12%. Management adds that retention is strong and customers want broader help from the platform. Adjusted earnings per share climbed to $2.84 from $2.30, which means growth is reaching profit once one-time acquisition costs are set aside.
Innovise fits the pattern. It sells surety bonds and commercial insurance brokerage with a focus on manufacturing, energy, construction and real estate, and Chairman and CEO J. Patrick Gallagher, Jr. said that niche expertise adds depth in Colorado. Jason McMillan's team will move into Gallagher's Denver office and work under Bret VanderVoort, who oversees retail property/casualty brokerage for the Western Zone. Buying specialists and folding them into existing offices is a repeatable playbook, and Gallagher closed 14 brokerage acquisitions in the first six months of 2026.
Now look at reported earnings, because that is where you see the cost. Diluted earnings per share fell to $1.25, from $1.40 in the second quarter of 2025, even though revenue jumped. Much of the gap between reported and adjusted results is the price of buying growth. Amortization of acquired intangibles alone weighs on brokerage net earnings by $218 million, up from $130 million a year ago, and integration costs rose as well. Adjusted figures set those aside, but they are real expenses, and they keep landing as long as Gallagher keeps buying.
Margins tell a similar story. The brokerage segment's adjusted EBITDAC margin, a stand-in for operating profit, slipped to 33.3% from 36.1%. Gallagher points to last year's interest income on cash raised for the ***** uredPartners deal, which closed in the third quarter of 2025, plus seasonality and newly added tuck-ins. That is a fair explanation. But the debt behind the deal is still here, including $9.55 billion of public debt, plus more in private placements and on a credit line. And the deal flow is thinner: brokerage acquisitions closed in the first six months of 2026 carried $107 million of annualized revenue, versus $354 million a year earlier, which puts more weight on organic growth.
#Growth


2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like

2 months ago
On September 4, the U.S. Department of War (DoW) announced a $336,112,000 Navy contract for Huntington Ingalls Industries, Inc. (NYSE:HII) to advance procurement of long-lead materials for the construction of the future USS William J. Clinton (CVN 82).
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries


2 months ago
While he stepped down as CEO of Berkshire Hathaway at the end of last year, Warren Buffett's wealth, and thus his portfolio, is still tied to the conglomerate and its stock portfolio. On that end, Berkshire's top-three positions -- consisting of Apple (NASDAQ: AAPL), American Express (NYSE: AXP), and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) (Nasdaq) -- make up more than half of its equity portfolio.
All three are strong compounding businesses with wide moats, but which looks like the best of the group to buy today? Let's take a look at each.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple is Berkshire's largest holding, making up about 22% of its portfolio. The stock is a Buffett favorite because it has one of the best compounding business models out there.
Apple, of course, is best known for its iPhone and other devices. Smartphones and computers tend to have very predictable replacement cycles, which creates an almost recurring type of revenue stream for the company. However, the beauty of the business stems from its closed-garden ecosystem that helps lock in consumers, from which it then collects high-margin service revenue. This revenue comes from a variety of sources, including a search revenue-sharing deal with Alphabet, commissions on app downloads, Apple Pay, and subscriptions for things like cloud storage.
#NASDAQ #revenue #best #alphabet
All three are strong compounding businesses with wide moats, but which looks like the best of the group to buy today? Let's take a look at each.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple is Berkshire's largest holding, making up about 22% of its portfolio. The stock is a Buffett favorite because it has one of the best compounding business models out there.
Apple, of course, is best known for its iPhone and other devices. Smartphones and computers tend to have very predictable replacement cycles, which creates an almost recurring type of revenue stream for the company. However, the beauty of the business stems from its closed-garden ecosystem that helps lock in consumers, from which it then collects high-margin service revenue. This revenue comes from a variety of sources, including a search revenue-sharing deal with Alphabet, commissions on app downloads, Apple Pay, and subscriptions for things like cloud storage.
#NASDAQ #revenue #best #alphabet


2 months ago
Burford Capital Limited (NYSE:BUR) announced on September 14 that its indirect, wholly owned subsidiary, Burford Capital Global Finance LLC, priced $300 million of 8% senior secured notes due 2029. Closing is expected September 17, subject to customary conditions.
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE

2 months ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and **** ysis, subscribe to Bisnow's free suite of newsletters.
The following article is a collaboration between Bisnow and business tech publication IT Brew.
It was Thanksgiving week in 2022 — a time when most employees are hard to find, let alone critical pieces of data center power infrastructure. And Kurt Bogle needed a transformer.
Bogle, then a senior regional director of critical facilities operations at NTT Global Data Centers, oversaw seven operational buildings around Chicago and Virginia and a staff of about 150 people. After a transformer failed a test, Bogle had to find a replacement and coordinate a swap with the on-site managers — all without disrupting service.
Thankfully, Bogle found a spare, but his experience illustrates the importance of systems thinkers at data centers who know how to acquire the resources necessary to maintain data centers' high uptime expectations. Given supply chain limitations and a steady build-out of data centers, such expertise is more crucial than ever — and there are signs a labor shortage is underway, threatening Big Tech's artificial intelligence ambitions and the reliable operation of mission-critical facilities.
#data #critical
The following article is a collaboration between Bisnow and business tech publication IT Brew.
It was Thanksgiving week in 2022 — a time when most employees are hard to find, let alone critical pieces of data center power infrastructure. And Kurt Bogle needed a transformer.
Bogle, then a senior regional director of critical facilities operations at NTT Global Data Centers, oversaw seven operational buildings around Chicago and Virginia and a staff of about 150 people. After a transformer failed a test, Bogle had to find a replacement and coordinate a swap with the on-site managers — all without disrupting service.
Thankfully, Bogle found a spare, but his experience illustrates the importance of systems thinkers at data centers who know how to acquire the resources necessary to maintain data centers' high uptime expectations. Given supply chain limitations and a steady build-out of data centers, such expertise is more crucial than ever — and there are signs a labor shortage is underway, threatening Big Tech's artificial intelligence ambitions and the reliable operation of mission-critical facilities.
#data #critical


2 months ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE

2 months ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction


2 months ago
Johnson & Johnson (JNJ) has been a rewarding stock to hold, up about 53% over the past year against about 17% for the S&P 500. The change worth noticing over that stretch is quieter than the price. Management said sales still rose 5.6% despite a STELARA drag of about 460 basis points. Management is encouraging investors to evaluate the company's underlying momentum by presenting growth rates that exclude STELARA alongside its reported figures.
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus

2 months ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Robert Half Inc. (NYSE:RHI). Robert Half Inc. (NYSE:RHI) is a leading staffing and consulting company. On September 15, 2026, Robert Half Inc. (NYSE:RHI) closed at $38.30 per share. Over the past month, Robert Half Inc. (NYSE:RHI) declined 12.03% and its shares gained 10.28% over the past 52 weeks. Robert Half Inc. (NYSE:RHI) has a market capitalization of $3.92 billion, and its stock has traded within a 52-week range of $21.83 and $46.70.
Conventum – Alluvium Global Fund stated the following regarding Robert Half Inc. (NYSE:RHI) in its Q2 2026 investor letter:
"We last wrote about Robert Half Inc. (NYSE:RHI) (up 23.5%) in our December report, where we mentioned that hindsight suggests our purchasing during price descents in May, August and October were mistakes. This remains the case - but less so. Our expectation that the recruitment / outplacement market will slowly recover, appears, going by Robert Half's recent results, to be bearing fruit. And management remain cautiously optimistic. We did not trade the stock. The Fund's position is now 2.7%."
Robert Half Inc. (NYSE:RHI) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 30 hedge fund portfolios held Robert Half Inc. (NYSE:RHI) at the end of the second quarter which was 36 in the previous quarter. While we acknowledge the potential of Robert Half Inc. (NYSE:RHI) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#half #NYSE
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted Robert Half Inc. (NYSE:RHI). Robert Half Inc. (NYSE:RHI) is a leading staffing and consulting company. On September 15, 2026, Robert Half Inc. (NYSE:RHI) closed at $38.30 per share. Over the past month, Robert Half Inc. (NYSE:RHI) declined 12.03% and its shares gained 10.28% over the past 52 weeks. Robert Half Inc. (NYSE:RHI) has a market capitalization of $3.92 billion, and its stock has traded within a 52-week range of $21.83 and $46.70.
Conventum – Alluvium Global Fund stated the following regarding Robert Half Inc. (NYSE:RHI) in its Q2 2026 investor letter:
"We last wrote about Robert Half Inc. (NYSE:RHI) (up 23.5%) in our December report, where we mentioned that hindsight suggests our purchasing during price descents in May, August and October were mistakes. This remains the case - but less so. Our expectation that the recruitment / outplacement market will slowly recover, appears, going by Robert Half's recent results, to be bearing fruit. And management remain cautiously optimistic. We did not trade the stock. The Fund's position is now 2.7%."
Robert Half Inc. (NYSE:RHI) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 30 hedge fund portfolios held Robert Half Inc. (NYSE:RHI) at the end of the second quarter which was 36 in the previous quarter. While we acknowledge the potential of Robert Half Inc. (NYSE:RHI) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#half #NYSE

2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
DEUTZ is transforming itself from an engine manufacturer into a broader industrial and defense group, but that expansion is proving expensive.
The company raised €179 million (about $207 million) overnight by issuing new shares to institutional investors, strengthening its balance sheet at the cost of another round of dilution for existing shareholders.
DEUTZ shares dropped roughly 5% after the German engine maker completed an accelerated share placement that raised approximately €179 million. The company issued 15.26 million new shares at €11.70 each, increasing its share capital by 10% to almost 168 million shares.
The placement price was 4.8% below the previous session's €12.29 Xetra close, and the stock opened around 5.7% lower at €11.58 before recovering some ground.
#shares #deutz #company
DEUTZ is transforming itself from an engine manufacturer into a broader industrial and defense group, but that expansion is proving expensive.
The company raised €179 million (about $207 million) overnight by issuing new shares to institutional investors, strengthening its balance sheet at the cost of another round of dilution for existing shareholders.
DEUTZ shares dropped roughly 5% after the German engine maker completed an accelerated share placement that raised approximately €179 million. The company issued 15.26 million new shares at €11.70 each, increasing its share capital by 10% to almost 168 million shares.
The placement price was 4.8% below the previous session's €12.29 Xetra close, and the stock opened around 5.7% lower at €11.58 before recovering some ground.
#shares #deutz #company

2 months ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects


2 months ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
2 months ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor