2 days ago
Investors are worried. CNN's Fear and Greed Index is at "extreme fear." Inflation remains persistently high, with the ongoing Iran war and tariffs not helping matters. Stock market valuations are frothy by most metrics.
In times of uncertainty, many investors look to safe havens. Utility stocks rank high on the list. But if the stock market crashes, will utility stocks really protect your portfolio?
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Arguments for buying utility stocks as a defensive portfolio move make sense. Consumers don't stop using electricity, natural gas, or water during an economic downturn or stock market sell-off.
There's also historical precedent for utility stocks protecting against a market crash. For example, the S&P 500 (SNPINDEX: ^GSPC) sank almost 50% from its peak in early 2000 by October 2002 when the dot-com bubble burst. The Nasdaq-100 index plunged more than 80%. Meanwhile, shares of NextEra Energy (NYSE: NEE) and The Southern Company (NYSE: SO), both large electric utility providers, jumped more than 20% during the same period.
#utility #Stock #fear #high
In times of uncertainty, many investors look to safe havens. Utility stocks rank high on the list. But if the stock market crashes, will utility stocks really protect your portfolio?
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Arguments for buying utility stocks as a defensive portfolio move make sense. Consumers don't stop using electricity, natural gas, or water during an economic downturn or stock market sell-off.
There's also historical precedent for utility stocks protecting against a market crash. For example, the S&P 500 (SNPINDEX: ^GSPC) sank almost 50% from its peak in early 2000 by October 2002 when the dot-com bubble burst. The Nasdaq-100 index plunged more than 80%. Meanwhile, shares of NextEra Energy (NYSE: NEE) and The Southern Company (NYSE: SO), both large electric utility providers, jumped more than 20% during the same period.
#utility #Stock #fear #high
6 days ago
Generating $1,000 a month in dividends is a simple process but it usually requires a substantial capital outlay. The Schwab U.S. Dividend Equity ETF (NYSEMKT: SCHD) is perhaps the best dividend ETF for accomplishing this. Not only does it offer a much-above-average yield, but it's also backed by a portfolio of durable, high-quality companies.
That's exactly what you want in your portfolio, so let's run through the path for how to get there.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The Schwab U.S. Dividend Equity ETF tracks the Dow Jones U.S. Dividend 100 Index. It starts with a universe of U.S. equities that have paid dividends for at least 10 consecutive years. From there, it examines the stock's dividend growth rate, yield, and several fundamental metrics, including return on equity (ROE) and cash flow-to-debt ratio. The 100 stocks with the best combination of these factors make the cut for the portfolio.
It's the combination of dividend yield and dividend quality that makes this fund so effective. The screens act as cross-checks on each other, so investors can get the best of both worlds. Choosing stocks based solely on yield can leave investors vulnerable to yield traps or potential dividend cuts. The quality screen here helps steer clear of that and gives people a sustainable high yield along with the quality portfolio.
#Dividend
That's exactly what you want in your portfolio, so let's run through the path for how to get there.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The Schwab U.S. Dividend Equity ETF tracks the Dow Jones U.S. Dividend 100 Index. It starts with a universe of U.S. equities that have paid dividends for at least 10 consecutive years. From there, it examines the stock's dividend growth rate, yield, and several fundamental metrics, including return on equity (ROE) and cash flow-to-debt ratio. The 100 stocks with the best combination of these factors make the cut for the portfolio.
It's the combination of dividend yield and dividend quality that makes this fund so effective. The screens act as cross-checks on each other, so investors can get the best of both worlds. Choosing stocks based solely on yield can leave investors vulnerable to yield traps or potential dividend cuts. The quality screen here helps steer clear of that and gives people a sustainable high yield along with the quality portfolio.
#Dividend


19 days ago
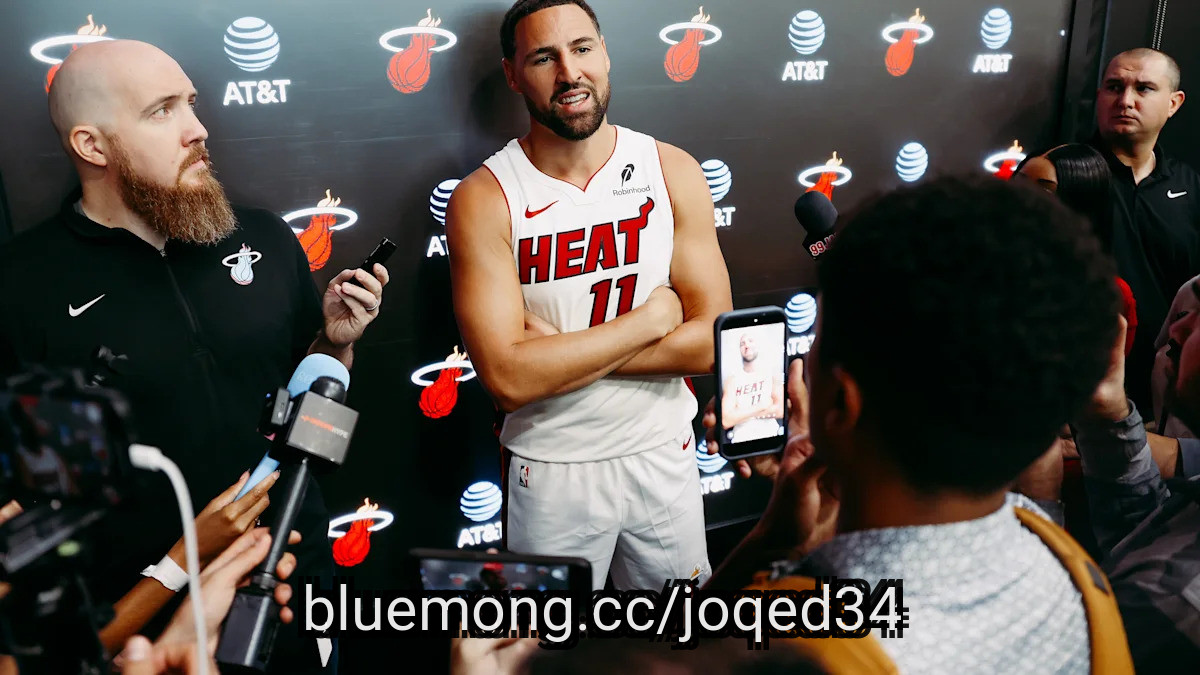
MIAMI — Exhale. Because at some point during seasons, that's what Klay Thompson does. And then he becomes Klay Thompson again.
For all the metrics compiled by the Miami Heat during their now-completed 3-2 preseason schedule, one stands particularly stark:
In his four preseason appearances, Thompson shot 7 of 26 from the field, but even more starkly, only 3 of 20 on 3-pointers.
And yet history says not only isn't the sky falling for the four-time NBA champion and five-time All-Star, but he only is getting warmed up.
With a body of work lengthy enough where it offers ample context, the player who stands No. 4 on the NBA's all-time list of 3-pointers made stands in somewhat familiar territory.
#exhale
For all the metrics compiled by the Miami Heat during their now-completed 3-2 preseason schedule, one stands particularly stark:
In his four preseason appearances, Thompson shot 7 of 26 from the field, but even more starkly, only 3 of 20 on 3-pointers.
And yet history says not only isn't the sky falling for the four-time NBA champion and five-time All-Star, but he only is getting warmed up.
With a body of work lengthy enough where it offers ample context, the player who stands No. 4 on the NBA's all-time list of 3-pointers made stands in somewhat familiar territory.
#exhale

19 days ago
Titans' Cam Ward finally got a win, but his brutal numbers still made unwanted history appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
A 26-20 win over the Indianapolis Colts was just what the doctor ordered for the Tennessee ******* ans as coach Robert Saleh got his first win with the franchise. Cam Ward's bright spots were pointed by OC Brian Daboll in the days leading up to the game, leading to a mediocre performance in Week 6.
Ward did enough to help his team secure the W, but he didn't do well on the stat sheet by traditional metrics. The former top overall pick became the fifth QB since 2024 to start and finish a game, attempt 20+ passes, throw for less than 105 yards and still win, according to NFL on FOX.
On the positive side of the equation, the other four guys to join him have all done well thus far, including Bryce Young, Jalen Hurts, Bo Nix and Caleb Williams.
Watch sports LIVE with fuboTV (free trial)
#leading #game
A 26-20 win over the Indianapolis Colts was just what the doctor ordered for the Tennessee ******* ans as coach Robert Saleh got his first win with the franchise. Cam Ward's bright spots were pointed by OC Brian Daboll in the days leading up to the game, leading to a mediocre performance in Week 6.
Ward did enough to help his team secure the W, but he didn't do well on the stat sheet by traditional metrics. The former top overall pick became the fifth QB since 2024 to start and finish a game, attempt 20+ passes, throw for less than 105 yards and still win, according to NFL on FOX.
On the positive side of the equation, the other four guys to join him have all done well thus far, including Bryce Young, Jalen Hurts, Bo Nix and Caleb Williams.
Watch sports LIVE with fuboTV (free trial)
#leading #game


2 months ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

2 months ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

2 months ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

2 months ago
Property and casualty insurer Progressive (NYSE: PGR) is probably best known for selling auto insurance. That's a highly competitive segment of the industry, but the company has proven its chops, reporting a strong combined ratio of 87.3% in the second quarter of 2026. Is the roughly 10% pullback from the 52-week high, and about 25% drawdown from 2025's peak, as of this writing, enough to make the stock a buy? Probably not if you are a value investor.
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive
The combined ratio is a measure of profitability in the insurance sector, with numbers below 100% indicating that a company is earning more from premiums than it costs to support those premiums and cover claims. Progressive has a strong history of running its business well on this front. Basically, it is a good business. But paying too much for a good business can turn it into a bad investment, as Benjamin Graham was fond of saying (Graham notably helped train Warren Buffett).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
So the real question here is whether the drawdowns noted above were sufficient to make Progressive's valuation attractive. The answer there isn't clean cut. For example, the price-to-sales ratio of 1.4x is in the middle of the historical range of roughly 0.5x to 2.2x. If anything, the P/S ratio is kind of toward the high side. The same general story holds with the price-to-book ratio. So these two metrics hint at a stock that isn't expensive, but it also isn't trading at bargain-basement prices.
The price-to-earnings ratio is a bit more positive, with the 11.1x P/E toward the lower end of its historical range. And the average insurance company has a P/E ratio of around 11.8x, so this makes Progressive look reasonably priced. Only Progressive's P/B ratio is 3.7x compared to the industry average of 1.7x, so the broader industry comparison still isn't a clear-cut win.
#ratio #progressive


2 months ago
On September 8, 2026, the Wall Street Journal reported United Natural Foods, Inc. (NYSE:UNFI)'s fiscal fourth-quarter results, in which adjusted earnings per share of $0.69 beat ***** yst expectations even as revenue of $7.64 billion came in below consensus.
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion
The grocery wholesaler guided for fiscal 2027 net sales of $31.2 billion to $31.8 billion, a return to growth after full-year fiscal 2026 sales declined 2% to $31.2 billion. The business said full-year adjusted EBITDA rose 27% to $701 million and free cash flow hit a record $323 million as it continued executing what CEO Sandy Douglas called its second year of a value-creation strategy.
United Natural Foods, Inc. (NYSE:UNFI)'s turnaround is improving the financial metrics that matter most for a food distributor. Full-year adjusted EBITDA increased 27%. Net debt fell by $295 million and net leverage improved to 2.2 times. The stronger balance sheet gives UNFI more financial flexibility as it works to return to sales growth.
UNFI's natural-products business is providing an important growth engine. Fourth-quarter natural-products sales increased 6.6%, even as conventional-products sales declined 8.6%. The stronger performance in natural products backs up UNFI's strategy of expanding business with customers that can drive growth as the business restructures its operations.
Management also expects fiscal 2027 sales to reach $31.2 billion to $31.8 billion, up from $31.15 billion in fiscal 2026. Adjusted EPS should reach $3.00 to $3.50 versus $2.65 previously. Management anticipates about 10 basis points of margin expansion at the midpoint, which could help UNFI reach its fiscal 2028 margin target a year earlier than planned.
#billion


2 months ago
Netflix (NFLX) has fallen about 35% over the past year, while the S&P 500 returned about 17%. The complaint is simple. Sales growth is slowing, and management will not show the quality metrics it leans on. That case misses the engine under per-share earnings, a wider margin, and a shrinking share count.
Why Are ***** ysts Pressing Netflix On Its Slowing Top Line?
Management guided revenue growth of 11% excluding currency for the third quarter of 2026, below the second quarter's 12% on the same basis. The CFO put part of that step down to a back-half-weighted year-ago comparison. ***** ysts have also pressed on viewing hours per member, which they say has softened.
The shares trade near $78, about 63% of their 52-week high. At that price the market appears to be paying for a mature business. The buy case has to rest on something other than the top line.
How Do Netflix's Earnings Grow Faster Than Its Sales?
#sales
Why Are ***** ysts Pressing Netflix On Its Slowing Top Line?
Management guided revenue growth of 11% excluding currency for the third quarter of 2026, below the second quarter's 12% on the same basis. The CFO put part of that step down to a back-half-weighted year-ago comparison. ***** ysts have also pressed on viewing hours per member, which they say has softened.
The shares trade near $78, about 63% of their 52-week high. At that price the market appears to be paying for a mature business. The buy case has to rest on something other than the top line.
How Do Netflix's Earnings Grow Faster Than Its Sales?
#sales


2 months ago
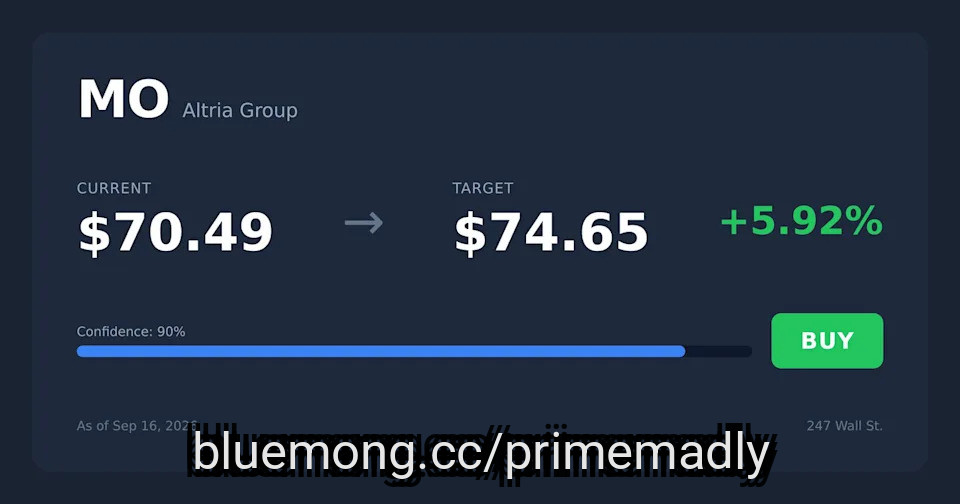
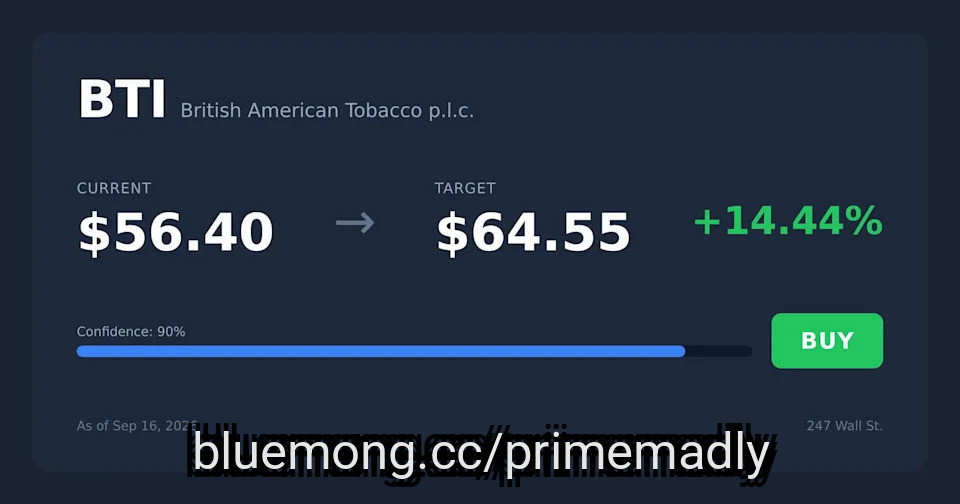
BTI yields 5.83% and beats MO on growth, trading at a cheaper forward P/E of 11 with EPS guidance of 5 to 8% versus Altria's 2.5 to 5.5%.
Altria wins on income reliability, having raised its dividend 60 times in 56 years with a 6.10% yield paid in dollars with zero currency risk.
BTI's Modern Oral segment surged 47% while Altria's nicotine pouch share fell 4 points and cigarette volumes dropped 10% in 2025.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
For a retirement-focused investor weighing high-yield tobacco names, the question is direct: British American Tobacco (NYSE:BTI) or Altria Group (NYSE:MO), which screens better for income investors right now? Both throw off cash, both trade at single-digit-to-low-teens forward earnings, and both are racing to replace shrinking combustible volumes with nicotine pouches, vapor, and heated tobacco. But when you line them up on the metrics that actually matter for a retiree cashing checks, one name comes out ahead.
#tobacco
Altria wins on income reliability, having raised its dividend 60 times in 56 years with a 6.10% yield paid in dollars with zero currency risk.
BTI's Modern Oral segment surged 47% while Altria's nicotine pouch share fell 4 points and cigarette volumes dropped 10% in 2025.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
For a retirement-focused investor weighing high-yield tobacco names, the question is direct: British American Tobacco (NYSE:BTI) or Altria Group (NYSE:MO), which screens better for income investors right now? Both throw off cash, both trade at single-digit-to-low-teens forward earnings, and both are racing to replace shrinking combustible volumes with nicotine pouches, vapor, and heated tobacco. But when you line them up on the metrics that actually matter for a retiree cashing checks, one name comes out ahead.
#tobacco

2 months ago
Galliford Try Holdings PLC (LSE:GFRD, FRA:3WC) chief financial officer Kris Hampson spoke with Proactive's Stephen Gunnion about the construction group's latest results, growing order book, margin progression and outlook for 2027, as well as its approach to acquisitions and shareholder returns.
Hampson said Galliford Try delivered a sixth consecutive year of growth across key metrics, supported by its building, infrastructure and specialist services operations. Adjusted profit before tax rose 24% on revenue growth of 3% to nearly £56 million, with adjusted divisional operating margin advancing from 3% to 3.5% and average cash up 21% to £216.2 million. "We make revenue, we turn it into profit, and we turn that profit into cash," Hampson said.
Looking ahead, he highlighted the £4.3 billion order book, up 5%, with more than 90% of current-year revenue already secured, alongside 60% for 2028. He said 91% of the order book sits within long-term frameworks and 95% is with government and regulated clients.
Hampson also discussed opportunities across water, highways, education and affordable housing, including growth tied to AMP8, newer frameworks on improved terms, and expects continued progression towards the group's 4% adjusted operating margin target for 2030.
On capital allocation, Galliford Try announced a £15 million share buyback alongside its results, following last year's £10 million buyback. Hampson also discussed the company's active M&A pipeline and its commitment to maintaining a dividend at 1.8 times cover based on adjusted EPS.
#million #profit
Hampson said Galliford Try delivered a sixth consecutive year of growth across key metrics, supported by its building, infrastructure and specialist services operations. Adjusted profit before tax rose 24% on revenue growth of 3% to nearly £56 million, with adjusted divisional operating margin advancing from 3% to 3.5% and average cash up 21% to £216.2 million. "We make revenue, we turn it into profit, and we turn that profit into cash," Hampson said.
Looking ahead, he highlighted the £4.3 billion order book, up 5%, with more than 90% of current-year revenue already secured, alongside 60% for 2028. He said 91% of the order book sits within long-term frameworks and 95% is with government and regulated clients.
Hampson also discussed opportunities across water, highways, education and affordable housing, including growth tied to AMP8, newer frameworks on improved terms, and expects continued progression towards the group's 4% adjusted operating margin target for 2030.
On capital allocation, Galliford Try announced a £15 million share buyback alongside its results, following last year's £10 million buyback. Hampson also discussed the company's active M&A pipeline and its commitment to maintaining a dividend at 1.8 times cover based on adjusted EPS.
#million #profit


2 months ago
This story was originally published on CFO.com. To receive daily news and insights, subscribe to our free daily CFO.com newsletter.
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement
Is there a disconnect between finance teams and procurement teams? A new survey of 2,005 procurement leaders in the U.S. and the U.K. suggests there is for some companies, and it may ultimately be affecting their bottom lines.
Released Tuesday, the report from California-based contract lifecycle management company Agiloft showed that about one in 10 respondents said they have no shared metrics between chief procurement officers and CFOs. The lack of shared metrics was cited among the biggest obstacles preventing companies from "closing the gap between what procurement negotiates and what finance realizes."
Other barriers cited were lack of contract data visibility, selected by 14% of respondents, along with manual processes that create exceptions that go unseen (23%).
Agiloft's survey included responses gathered from 2,005 chief procurement officers and other procurement leaders Aug. 5-20.
#procurement


2 months ago
Interested in Truist Financial Corporation? Here are five stocks we like better.
Truist will sell its $5.5 billion near-prime auto loan portfolio and exit its Regional Acceptance Corporation business, which was roughly break-even despite high loan yields. The transaction is expected to modestly improve earnings, tangible book value and credit metrics.
The bank reaffirmed its financial outlook, including third-quarter net interest income growth of about 1.5%, full-year growth of 1% to 1.5%, and its $5 billion share-repurchase plan. The sale is expected to generate approximately $950 million in capital but reduce net interest margin by 4 to 5 basis points.
New CEO Mike Lyons is accelerating a broader portfolio and capital-allocation review, with Truist emphasizing relationship banking, deposits, commercial lending, payments, wealth management and potentially credit cards, mortgages and home equity lending.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
#truist #financial #loan #credit
Truist will sell its $5.5 billion near-prime auto loan portfolio and exit its Regional Acceptance Corporation business, which was roughly break-even despite high loan yields. The transaction is expected to modestly improve earnings, tangible book value and credit metrics.
The bank reaffirmed its financial outlook, including third-quarter net interest income growth of about 1.5%, full-year growth of 1% to 1.5%, and its $5 billion share-repurchase plan. The sale is expected to generate approximately $950 million in capital but reduce net interest margin by 4 to 5 basis points.
New CEO Mike Lyons is accelerating a broader portfolio and capital-allocation review, with Truist emphasizing relationship banking, deposits, commercial lending, payments, wealth management and potentially credit cards, mortgages and home equity lending.
Smart Money Shifts: U.S. Bancorp Pairs Tech With Yield
#truist #financial #loan #credit


2 months ago
When it comes to long-term success with dividend investing, you need to focus on criteria beyond just yield. While some high yield dividend stocks can be worth the risk, there are plenty that are trading at a high yield for a good reason.
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing
That is, either they are at risk of cutting or suspending their payouts, and/or other risks may lead to stock price declines that outweigh the returns generated by their large payouts. So, instead of focusing on yield alone, consider criteria such as dividend coverage and dividend growth, along with metrics like valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Taking all of these into account, three blue chip dividend stocks stand out as strong, dare I say, "no brainer," buys right now: AbbVie (NYSE: ABBV), Realty Income (NYSE: O), and Procter & Gamble (NYSE: PG).
Several years ago, uncertainty ran high about AbbVie, mostly due to concerns about the impact of losing patent exclusivity for its flagship drug product, the rheumatoid arthritis treatment Humira. Yet while this did hurt AbbVie's revenue and earnings after exclusivity ended in 2023, the company has staged a comeback, largely thanks to the success of the anti-inflammatory drugs Skyrizi and Rinvoq.
#NYSE #abbvie #flashing


2 months ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


2 months ago
Willing and Abel: Berkshire's New CEO Makes Huge Portfolio Changes in Q1
American Express raised its 2026 revenue-growth outlook toward 10% after reporting strong first-half trends, including 10% foreign-exchange-adjusted revenue growth, mid-teens EPS growth, 16% card-fee growth and double-digit net interest income growth.
The company plans to direct better-than-expected performance toward customer acquisition, technology and product development, while maintaining long-term aspirations of 10% revenue growth and mid-teens EPS growth.
International, travel and younger-cardmember growth remain key opportunities: international billings have risen about 50% in three years, travel spending is contributing to growth, and Millennials and Gen Z represent 65% of new accounts, with credit metrics remaining stable.
Capital One's Big Bet Faces Rising Credit Risk
#Growth #international #travel #makes
American Express raised its 2026 revenue-growth outlook toward 10% after reporting strong first-half trends, including 10% foreign-exchange-adjusted revenue growth, mid-teens EPS growth, 16% card-fee growth and double-digit net interest income growth.
The company plans to direct better-than-expected performance toward customer acquisition, technology and product development, while maintaining long-term aspirations of 10% revenue growth and mid-teens EPS growth.
International, travel and younger-cardmember growth remain key opportunities: international billings have risen about 50% in three years, travel spending is contributing to growth, and Millennials and Gen Z represent 65% of new accounts, with credit metrics remaining stable.
Capital One's Big Bet Faces Rising Credit Risk
#Growth #international #travel #makes

2 months ago
Sep. 14—The term sabermetrics was first coined by Bill James in 1980. It took quite a bit longer, however, for the idea to catch on with the baseball populace, but eventually acronyms like WAR, VORP and UZR caught on as a way to ****** yze the sport.
Analytics are equally as important these days in college basketball. It's why you hear Illinois coach Brad Underwood constantly referencing his team's adjusted offensive efficiency and offensive rebounding rate. Paid services like Synergy give coaching staffs an ****** ytical breakdown of their team to the finest detail.
Publicly available sites like , and , however, have broadened the usage and acceptance of a different way to follow and break down the sport. (KenPom and CBBAnalytics do have a subscription piece but are drastically cheaper than Synergy).
It's through those sites Illinois fans could track one of the most efficient offenses in the modern era during the 2025-26 season. The Illini eventually finished second in adjusted offensive efficiency behind Purdue last season. That particular metric was helped by the Illini not turning the ball over (eighth in turnover rate) and dominating the offensive glass (third in offensive rebounding rate).
One particular metric Illinois tracks is shot volume.
#like #rate #synergy
Analytics are equally as important these days in college basketball. It's why you hear Illinois coach Brad Underwood constantly referencing his team's adjusted offensive efficiency and offensive rebounding rate. Paid services like Synergy give coaching staffs an ****** ytical breakdown of their team to the finest detail.
Publicly available sites like , and , however, have broadened the usage and acceptance of a different way to follow and break down the sport. (KenPom and CBBAnalytics do have a subscription piece but are drastically cheaper than Synergy).
It's through those sites Illinois fans could track one of the most efficient offenses in the modern era during the 2025-26 season. The Illini eventually finished second in adjusted offensive efficiency behind Purdue last season. That particular metric was helped by the Illini not turning the ball over (eighth in turnover rate) and dominating the offensive glass (third in offensive rebounding rate).
One particular metric Illinois tracks is shot volume.
#like #rate #synergy

2 months ago
During the September 3 episode of Mad Money, Jim Cramer mentioned Microsoft Corporation (NASDAQ:MSFT) for its unconventional approach to powering hyperscale data centers in partnership with Chevron Corporation (NYSE:CVX). He said:
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
How about Microsoft? Look, Mr. Softee is getting religion. They've realized that by giving us more disclosure on Azure, their cloud infrastructure business, we'll find more things to like. They're right. In the end, I come to praise Microsoft CFO Amy Hood, not bury her. They've been very clever getting power for the data centers, pumping it right out of the Permian. They got this deal with Chevron as a partner… 2.67 gigawatts. No one's talking about it. It's the cleanest behind the meter plan for power I have seen yet. People even, and this is not a stretch, I'm not kidding, people even like Copilot.
CFO Amy Hood provided Wall Street with a much clearer look at actual cloud demand by breaking down detailed Azure growth metrics and data center capacity constraints. At the same time, enterprise adoption of Microsoft 365 Copilot is moving past initial trials, with major corporations deploying the AI ***** istant across workforce segments.
A major highlight of the company's infrastructure strategy is a twenty-year agreement with Chevron Corporation (NYSE:CVX) for a proposed 2.67-gigawatt natural gas power plant in West Texas. Designed to supply dedicated off-grid electricity directly to a hyperscale data center in the Permian Basin, the project bypasses regional grid transmission queues to secure reliable power for continuous AI workloads. Microsoft Corporation's (NASDAQ:MSFT) president of Cloud Operations + Innovation, Noelle Walsh, commented:
Our agreement with Chevron helps ensure we'll have dedicated, large-scale power to support the evolution and reliability of advanced compute. Through this partnership, we're delighted to grow with and become a deeper part of the West Texas community.
#chevron #power #they 've
2 months ago
The San Francisco 49ers' 27-7 win over the Los Angeles Rams looked dominant enough in the traditional box score. Brock Purdy threw three touchdown passes, the team rushed for 174 yards, and the defense added a pair of takeaways.
But the advanced numbers tell an even more complete story of just how thoroughly the 49ers controlled the game. The underlying metrics suggest this wasn't just a good night on the scoreboard. It was a genuinely elite performance across nearly every phase of the game.
Here are five advanced stats that go beyond the box score to explain how San Francisco pulled it off.
Brock Purdy's 39-yard touchdown to Demarcus Robinson traveled 44 air yards relative to the line of scrimmage, according to Next Gen Stats. That's the longest completion by air yards of his career. Yes, just 44 air yards. It was a notable outlier in a game where Purdy's average intended air yards per attempt (4.4) was actually his lowest of any season on record, a sign San Francisco mixed shot plays into an otherwise efficient, high-percentage passing attack.
Brock Purdy's 39-yard touchdown pass to Demarcus Robinson traveled 44 yards relative to the line of scrimmage, Purdy's longest completion by air yards of his career.#SFvsLAR | #FTTB pic.twitter.com/qLcN8wCCLm
#advanced
But the advanced numbers tell an even more complete story of just how thoroughly the 49ers controlled the game. The underlying metrics suggest this wasn't just a good night on the scoreboard. It was a genuinely elite performance across nearly every phase of the game.
Here are five advanced stats that go beyond the box score to explain how San Francisco pulled it off.
Brock Purdy's 39-yard touchdown to Demarcus Robinson traveled 44 air yards relative to the line of scrimmage, according to Next Gen Stats. That's the longest completion by air yards of his career. Yes, just 44 air yards. It was a notable outlier in a game where Purdy's average intended air yards per attempt (4.4) was actually his lowest of any season on record, a sign San Francisco mixed shot plays into an otherwise efficient, high-percentage passing attack.
Brock Purdy's 39-yard touchdown pass to Demarcus Robinson traveled 44 yards relative to the line of scrimmage, Purdy's longest completion by air yards of his career.#SFvsLAR | #FTTB pic.twitter.com/qLcN8wCCLm
#advanced


2 months ago
College football has evolved so rapidly over the last several years, and there are an increasing variety of ways to break down any given Saturday.
Here on Scarlet Spreadsheet, we are going to compile all of the various ****** ytical models to get the best possible preview of each of Ohio State's matchups throughout the 2026 season based on the underlying numbers and metrics.
With the tune-up game out of the way, the Buckeyes now travel to Austin, Texas for a battle against the Longhorns. Ohio State is an underdog for the first time since 2023, and Steve Sarkisian will be looking for revenge at home after back-to-back losses to Ryan Day's group.
With only one game under the belt for both of these two teams thus far, our ability to break it down from an ****** ytical standpoint is limited, but we can take a look at how these two teams looked in Week 1, the updated computer models and some projections.
FPI: 30.0 (Rank: 2)
#college
Here on Scarlet Spreadsheet, we are going to compile all of the various ****** ytical models to get the best possible preview of each of Ohio State's matchups throughout the 2026 season based on the underlying numbers and metrics.
With the tune-up game out of the way, the Buckeyes now travel to Austin, Texas for a battle against the Longhorns. Ohio State is an underdog for the first time since 2023, and Steve Sarkisian will be looking for revenge at home after back-to-back losses to Ryan Day's group.
With only one game under the belt for both of these two teams thus far, our ability to break it down from an ****** ytical standpoint is limited, but we can take a look at how these two teams looked in Week 1, the updated computer models and some projections.
FPI: 30.0 (Rank: 2)
#college

2 months ago
Braze Inc. (NASDAQ:BRZE) turned in a strong second quarter. The reputed customer engagement platform showcased continued momentum across both its product strategy and financial performance. The company generated topline figure of $227.2 million, an impressive 26.2% increase compared to the same period last year. This revenue growth was fueled by upselling gains, customer additions and renewals. The company posted $24.2 million in cash flow from operating activities, a monumental growth relative to $7 million in the same period a year ago. This was paired with $21.7 million in free cash flow, against $3.5 million during Q2 FY26.
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue
Jirsak/Shutterstock.com
The quarter brought several meaningful strategic moves. Braze broadened its BrazeAI Operator tool, which allows users to build new Canvas steps straight from conversational prompts. The company also signed a three-year Strategic Collaboration Agreement with AWS to support collaborative co-selling and go-to-market initiatives. The arrangement will incentivize AWS sellers for integrating Braze within their accounts.
For the latest quarter, subscription revenue jumped to $207.7 million from $171.8 million a year prior, while professional services and other revenue more than doubled, reaching $19.6 million. Dollar-based net retention among larger accounts, defined as those with annual recurring revenue of $500,000 or more, edged up to 112% in comparison to 111% a year earlier. Profitability metrics improved considerably as well, with adjusted operating income jumping to $22 million from $6 million, and adjusted diluted EPS increasing from $0.15 to $0.19.
Management cited growing demand for measurable return on investment as the primary force behind faster uptake of Braze's AI product lineup, which includes BrazeAI Operator, BrazeAI Agent Console, and BrazeAI Decisioning Studio.
#revenue


2 months ago
On September 2, Shell Offshore, a subsidiary of Shell plc (NYSE:SHEL), announced the acquisition of a 30% working interest in Conifer, an exploration prospect operated by BP p.l.c. (NYSE:BP) in the U.S. Gulf of Mexico. Located offshore within Keathley Canyon near BP's Kaskida host development, Conifer represents a significant deep-water play. BP retains operatorship, with the initial exploration well expected to spud in 2027. While the deal reflects shared risk and capital efficiency in high-cost offshore basins, comparing the two giants' Q2 2026 earnings shows that Shell is currently executing from a position of superior financial strength.
Shell plc (NYSE:SHEL) delivered an exceptionally clean Q2 2026 report. Adjusted earnings reached $9.8 billion, driven by record upstream production in Brazil and record refinery utilization, which offset Middle East operational outages. Cash flow from operations (CFFO) came in at $21.4 billion, supported by higher realized prices and a $3.4 billion working capital inflow. Shell maintained strict capital discipline, reiterating its full-year capex outlook of $24 billion–$26 billion while completing $5.8 billion in structural cost reductions since 2022. Balance sheet health remains robust, with gearing at 19% and net debt at $42 billion ($12 billion excluding leases).
BP p.l.c. (NYSE:BP) also turned in a solid Q2 recovery, but its headline metrics lag behind Shell's scale. BP reported underlying replacement cost profit (its proxy for net income) of $5.7 billion, a 78% quarter-over-quarter rebound fueled by strong refining margins and oil trading. Operating cash flow reached $10.9 billion after absorbing a $1.0 billion working capital build. BP used strong cash generation to trim net debt down to $22.25 billion, while guiding full-year capex to $13.5 billion–$14.0 billion.
Although BP raised its quarterly dividend by 4% to 8.66 cents, Shell's cash engine allowed it to announce its 19th consecutive quarter of at least $3 billion in share buybacks, distributing 44% of CFFO over the trailing 12 months.
Shell's bull case centers on superior capital allocation, aggressive portfolio high-grading, including the ARC Resources acquisition targeting a 4% production CAGR through 2030, and consistent share buybacks. The bear case focuses on execution risks in integrated gas and LNG amid volatile market conditions, as well as the challenges of integrating large-scale acquisitions.
#cost
Shell plc (NYSE:SHEL) delivered an exceptionally clean Q2 2026 report. Adjusted earnings reached $9.8 billion, driven by record upstream production in Brazil and record refinery utilization, which offset Middle East operational outages. Cash flow from operations (CFFO) came in at $21.4 billion, supported by higher realized prices and a $3.4 billion working capital inflow. Shell maintained strict capital discipline, reiterating its full-year capex outlook of $24 billion–$26 billion while completing $5.8 billion in structural cost reductions since 2022. Balance sheet health remains robust, with gearing at 19% and net debt at $42 billion ($12 billion excluding leases).
BP p.l.c. (NYSE:BP) also turned in a solid Q2 recovery, but its headline metrics lag behind Shell's scale. BP reported underlying replacement cost profit (its proxy for net income) of $5.7 billion, a 78% quarter-over-quarter rebound fueled by strong refining margins and oil trading. Operating cash flow reached $10.9 billion after absorbing a $1.0 billion working capital build. BP used strong cash generation to trim net debt down to $22.25 billion, while guiding full-year capex to $13.5 billion–$14.0 billion.
Although BP raised its quarterly dividend by 4% to 8.66 cents, Shell's cash engine allowed it to announce its 19th consecutive quarter of at least $3 billion in share buybacks, distributing 44% of CFFO over the trailing 12 months.
Shell's bull case centers on superior capital allocation, aggressive portfolio high-grading, including the ARC Resources acquisition targeting a 4% production CAGR through 2030, and consistent share buybacks. The bear case focuses on execution risks in integrated gas and LNG amid volatile market conditions, as well as the challenges of integrating large-scale acquisitions.
#cost

2 months ago
Netskope Inc. (NASDAQ:NTSK) announced its second quarter results on September 2. The cloud and AI-led security and networking company saw a 27% year-over-year jump in its annual recurring revenue that climbed to $899 million. Total revenue for the recent quarter came in at $220.5 million, equating to a 29% growth compared to the same period last year. The company surpassed management's prior guidance across all metrics.
Gts/Shutterstock.com
The second quarter strength can be attributed to a robust demand for Netskope One platform. This was further supported by the company's continued organic innovation. Netskope is currently positioned right at the convergence of AI, networking, security, and ****** ytics, which makes strengthen its position as enterprises look for secure AI adoption. On the profitability front, the company reported gross profit of $169.1 million on adjusted basis, resulting in a marginal jump in adjusted gross margins to 77%, compared to 75% during the same period last year.
During the quarter, Netskope also introduced some new offerings and advanced features. These include the Netskope One DataSec Command Center, which is a unified platform for tracking and protecting sensitive data across endpoints, cloud, AI environments, and more. The company also brought enhancements to its NewEdge AI Fast Path capability, which, according to company testing, reduced latency by as much as 90% to popular AI destinations.
Following the second quarter, management issued guidance for the upcoming quarter, estimating topline figures between $227 million and $229 million. It has projected full-year revenue between $888 million and $892 million, along with adjusted gross margin of around 77% and a free cash flow margin of nearly 2%.
#second
Gts/Shutterstock.com
The second quarter strength can be attributed to a robust demand for Netskope One platform. This was further supported by the company's continued organic innovation. Netskope is currently positioned right at the convergence of AI, networking, security, and ****** ytics, which makes strengthen its position as enterprises look for secure AI adoption. On the profitability front, the company reported gross profit of $169.1 million on adjusted basis, resulting in a marginal jump in adjusted gross margins to 77%, compared to 75% during the same period last year.
During the quarter, Netskope also introduced some new offerings and advanced features. These include the Netskope One DataSec Command Center, which is a unified platform for tracking and protecting sensitive data across endpoints, cloud, AI environments, and more. The company also brought enhancements to its NewEdge AI Fast Path capability, which, according to company testing, reduced latency by as much as 90% to popular AI destinations.
Following the second quarter, management issued guidance for the upcoming quarter, estimating topline figures between $227 million and $229 million. It has projected full-year revenue between $888 million and $892 million, along with adjusted gross margin of around 77% and a free cash flow margin of nearly 2%.
#second


2 months ago
Interested in Qualcomm Incorporated? Here are five stocks we like better.
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm
Qualcomm's Amazon agreement gives its data center strategy a major anchor beyond smartphones.
Amazon's warrants are tied to up to $60 billion in potential purchases over a decade, making the deal meaningful but gradual.
Qualcomm's valuation still trails many AI infrastructure peers, but dilution risk and execution timing remain important factors.
Investors continue to seek disciplined strategies to participate in the evolving artificial intelligence (AI) economy without paying inflated multiples for standard graphics hardware. Capital remains focused on businesses positioned to sustain steady enterprise workload expansion while maintaining reasonable valuation metrics.
#interested #qualcomm


2 months ago
The Washington Huskies saw their top two running backs, second-year Quaid Carr and fourth-year Jayden Limar, both suffer significant injuries in the Apple Cup, dealing a significant blow to Jedd Fisch's backfield
However, during his Thursday press conference, Fisch delivered some good news about the injury-ravaged position, as third-year running back Jordan Washington continues to recover from a neck injury that he suffered during spring practice, stating that there's a chance the former four-star recruit returns this season.
"I am more optimistic (that Washington can play in 2026) based upon how his rehab has gone," Fisch said on Thursday.
"He's gotten a lot stronger; he's stronger than he was before he got hurt, with all of his weight room metrics...His speed is the same; the thing that we have to look at is cleared for contact. That decision gets made by the surgeon who took care of him, and then we have to look at conditioning. But in terms of how things are trending, he's doing exceptionally well, but we don't know anything until he gets scanned, and the scans—we're not ready for that yet."
Fisch added that a potential return could happen before the end of the season, but at the same time, tried to temper expectations around what that may look like, adding that he has several benchmarks to hit before he can even get scanned in an attempt to return.
#washington #look #season
However, during his Thursday press conference, Fisch delivered some good news about the injury-ravaged position, as third-year running back Jordan Washington continues to recover from a neck injury that he suffered during spring practice, stating that there's a chance the former four-star recruit returns this season.
"I am more optimistic (that Washington can play in 2026) based upon how his rehab has gone," Fisch said on Thursday.
"He's gotten a lot stronger; he's stronger than he was before he got hurt, with all of his weight room metrics...His speed is the same; the thing that we have to look at is cleared for contact. That decision gets made by the surgeon who took care of him, and then we have to look at conditioning. But in terms of how things are trending, he's doing exceptionally well, but we don't know anything until he gets scanned, and the scans—we're not ready for that yet."
Fisch added that a potential return could happen before the end of the season, but at the same time, tried to temper expectations around what that may look like, adding that he has several benchmarks to hit before he can even get scanned in an attempt to return.
#washington #look #season


0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Dell Technologies Inc. (NYSE:DELL) reported fiscal second-quarter 2027 revenue of $47.0 billion, up 58% year over year. AI server orders reached $60.9 billion, while recognized AI server revenue totaled $16.4 billion and ending AI server backlog reached $95.0 billion.
Orders and backlog are company-reported operating metrics, not recognized revenue. Orders measure booked demand, while backlog represents orders awaiting conversion. The backlog provides substantial revenue visibility, although Dell Technologies Inc. (NYSE:DELL) did not disclose its conversion schedule.
Dell Technologies Inc. (NYSE:DELL) raised its fiscal 2027 revenue outlook by $25 billion to $192 billion and increased expected AI-optimized server revenue from $60 billion to $74 billion. However, cash flow from operating activities decreased 13% to $2.225 billion. First-half operating cash flow still increased 18% to $6.306 billion.
The company-defined non-GAAP cash measures require a closer look. Free cash flow was $986 million, calculated from $2.225 billion of operating cash flow less $1.239 billion of capital expenditures and capitalized software development costs, net of **** et-sale proceeds. Adjusted free cash flow was $8.149 billion after adding the $6.667 billion operating-cash-flow impact from changes in financing receivables and the $496 million net impact of capital expenditures and depreciation for equipment under operating leases. Dell Technologies Inc. (NYSE:DELL) excludes these Dell Financial Services items because their initial funding is largely replaced by cash inflows from related debt.
Infrastructure Solutions Group revenue increased 89% to $31.8 billion, while operating income rose 225% to $4.8 billion. The company-reported ISG operating income rate, calculated as segment operating income divided by segment revenue, improved to 15.0% from 8.8%. Scale, pricing discipline, and operating leverage are producing stronger segment economics.
#operating #technologies
Orders and backlog are company-reported operating metrics, not recognized revenue. Orders measure booked demand, while backlog represents orders awaiting conversion. The backlog provides substantial revenue visibility, although Dell Technologies Inc. (NYSE:DELL) did not disclose its conversion schedule.
Dell Technologies Inc. (NYSE:DELL) raised its fiscal 2027 revenue outlook by $25 billion to $192 billion and increased expected AI-optimized server revenue from $60 billion to $74 billion. However, cash flow from operating activities decreased 13% to $2.225 billion. First-half operating cash flow still increased 18% to $6.306 billion.
The company-defined non-GAAP cash measures require a closer look. Free cash flow was $986 million, calculated from $2.225 billion of operating cash flow less $1.239 billion of capital expenditures and capitalized software development costs, net of **** et-sale proceeds. Adjusted free cash flow was $8.149 billion after adding the $6.667 billion operating-cash-flow impact from changes in financing receivables and the $496 million net impact of capital expenditures and depreciation for equipment under operating leases. Dell Technologies Inc. (NYSE:DELL) excludes these Dell Financial Services items because their initial funding is largely replaced by cash inflows from related debt.
Infrastructure Solutions Group revenue increased 89% to $31.8 billion, while operating income rose 225% to $4.8 billion. The company-reported ISG operating income rate, calculated as segment operating income divided by segment revenue, improved to 15.0% from 8.8%. Scale, pricing discipline, and operating leverage are producing stronger segment economics.
#operating #technologies
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go
2 months ago
Botafogo will face RB Bragantino on 09/12 at Nilton Santos Stadium, for the 27th round of the Brazilian Championship. Members on the Glorioso plan can already check in at botafogo.ingresse.com.
Access to all sections of Nilton Santos Stadium will be exclusively through facial biometrics. All fans, including those eligible for free tickets, must register their facial biometrics on the website and have an Ingresse account. Children under 12 must be registered as dependents on their guardian's Ingresse account. Cria+ members must check in on the Ingresse website as a dependent of their guardian starting from the opening date of the guardian's plan, and the ticket must be redeemed in the same section as the guardian.
ATTENTION TO THE OPENING ORDER: Glorioso Plan (09/08, at 12 pm), Alvinegro Plan, Alvinegro OFF Rio and JOIAS DO BAIRRO (09/08, at 2 pm), Preto Plan and ESCOLHIDO (09/08, at 4 pm), Branco Plan and NOSSA GENTE (09/08, at 6 pm), General Public and Free Tickets (09/09, at 12 pm), In-Person Service (09/11, at 9 am).
MATCH INFORMATION:
Match: Botafogo x RB Bragantino
#must #botafogo #stadium
Access to all sections of Nilton Santos Stadium will be exclusively through facial biometrics. All fans, including those eligible for free tickets, must register their facial biometrics on the website and have an Ingresse account. Children under 12 must be registered as dependents on their guardian's Ingresse account. Cria+ members must check in on the Ingresse website as a dependent of their guardian starting from the opening date of the guardian's plan, and the ticket must be redeemed in the same section as the guardian.
ATTENTION TO THE OPENING ORDER: Glorioso Plan (09/08, at 12 pm), Alvinegro Plan, Alvinegro OFF Rio and JOIAS DO BAIRRO (09/08, at 2 pm), Preto Plan and ESCOLHIDO (09/08, at 4 pm), Branco Plan and NOSSA GENTE (09/08, at 6 pm), General Public and Free Tickets (09/09, at 12 pm), In-Person Service (09/11, at 9 am).
MATCH INFORMATION:
Match: Botafogo x RB Bragantino
#must #botafogo #stadium


2 months ago
Earnings season refuses to end. While others may have had enough, earnings reports are my lifeblood! Well, that and 1,500 milligrams of caffeine a day.
I'm glad earnings season rages on because it gives us the very latest insights on all things AI. This is super helpful information as I embark for the Super Bowl of tech conferences: the Goldman Sachs Communacopia tech gathering. More on that in a moment.
The past two weeks have been bonkers for the AI investment thesis. Any talk about peak AI needs to be tossed aside.
Broadcom's (AVGO) revenue surged 86% year over year in its most recent quarter. Adjusted earnings per share exploded 96%. Both metrics easily thumped ***** yst estimates.
The massive outperformance was fueled by relentless hyperscaler demand for custom AI chips and networking gear, with quarterly AI semiconductor revenue alone tripling to $16.7 billion.
#super #season #revenue #sachs
I'm glad earnings season rages on because it gives us the very latest insights on all things AI. This is super helpful information as I embark for the Super Bowl of tech conferences: the Goldman Sachs Communacopia tech gathering. More on that in a moment.
The past two weeks have been bonkers for the AI investment thesis. Any talk about peak AI needs to be tossed aside.
Broadcom's (AVGO) revenue surged 86% year over year in its most recent quarter. Adjusted earnings per share exploded 96%. Both metrics easily thumped ***** yst estimates.
The massive outperformance was fueled by relentless hyperscaler demand for custom AI chips and networking gear, with quarterly AI semiconductor revenue alone tripling to $16.7 billion.
#super #season #revenue #sachs