

9 days ago
Intuitive Surgical (ISRG), maker of the da Vinci surgical robots, trades at about $382, some 36% below its 52-week high. Even so, you pay about 35.9 times trailing adjusted earnings. That is normalized net income with stock-based compensation added back, a basis meant to sit closer to the one ****** ysts forecast on, though the two are not defined identically. ****** ysts' forecasts run to 2027, the year Intuitive plans to start lowering what customers pay per use on some instruments.
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures
The shares were trading about 11% lower the day after second-quarter results in July showed slower US procedure growth. US da Vinci procedures grew 12% in the second quarter, against 14% in the first. Management pointed to two likely causes, with the CFO noting that some customers say coverage changes are delaying deferrable procedures, alongside a little of the law of large numbers.
What the price still pays for is revenue growing faster than procedures. On the first-quarter call, the CFO credited that largely to da Vinci 5 and its higher pricing. More than half of the da Vinci systems Intuitive placed in the second quarter were da Vinci 5.
On ****** ysts' 2026 estimates, today's price is about 35.1 times earnings. On their 2027 estimates, it is about 31.4 times. The revenue forecast behind that looks modest: about 13.1% growth a year through 2027, against 20.7% growth over the past twelve months.
Consensus has earnings and revenue growing at a similar pace between 2026 and 2027, so margins hold roughly steady. Intuitive enters that stretch with an operating margin of 31.3% over the past twelve months, above its three-year average of 27.7%.
#intuitive #analysts #year #procedures

11 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
11 days ago
White House chief of staff Susie Wiles is "cancer free," she announced on X on Sept. 16, 2026. "Some personal news I'm grateful to share. After a medical appointment at the Mayo Clinic this week, my pathology results came back clear," she explained.
Wiles was diagnosed with early-stage breast cancer in March and told the New York Times that her prognosis was "strong." Wiles did not disclose at the time what treatment she would undergo, but said it would last several weeks — during which time she planned to continue working. Noting that one in eight American women develops breast cancer at some point in their lives, Wiles posted on X at the time: "Every day, these women continue to raise their families, go to work and serve their communities with strength and determination. I now join their ranks."
A breast cancer diagnosis is life-altering, but Wiles's comments highlighted the progress that's been made in recent years. Breast cancer is now detected at Stage 0 or 1 — before it has spread — in the majority of cases. Survival rates have risen dramatically, but "the treatments we use to treat early-stage breast cancer have become more tailored" and less disruptive to women's lives, Dr. Lynn Dengel, a University of Virginia surgical oncologist, told Yahoo in March.
"Because [Wiles] was taking care of her health [and getting screened], not only will her prognosis be better, but it will probably minimize what treatment she has to go through and will benefit her work-life and overall balance," Dengel said. She added that most of her patients are diagnosed early and can continue to work while undergoing breast cancer treatment, reducing the financial burden and overall disruption to their lives.
Wiles was diagnosed at age 68 — slightly older than the median age (62) when most women learn they have breast cancer. More than 380,000 American women are diagnosed with some form of breast cancer each year, according to the American Cancer Society (ACS).
Breast cancer remains the most common form of cancer among women in the U.S., except for skin cancers. And rates are rising. But there's good news: More women are surviving the disease. Treatments have also improved, becoming tolerable enough that many women still work, as Wiles intends to do. Here's what to know about the disease, why rates are rising and how women can reduce their risks.
#breast #diagnosed
Wiles was diagnosed with early-stage breast cancer in March and told the New York Times that her prognosis was "strong." Wiles did not disclose at the time what treatment she would undergo, but said it would last several weeks — during which time she planned to continue working. Noting that one in eight American women develops breast cancer at some point in their lives, Wiles posted on X at the time: "Every day, these women continue to raise their families, go to work and serve their communities with strength and determination. I now join their ranks."
A breast cancer diagnosis is life-altering, but Wiles's comments highlighted the progress that's been made in recent years. Breast cancer is now detected at Stage 0 or 1 — before it has spread — in the majority of cases. Survival rates have risen dramatically, but "the treatments we use to treat early-stage breast cancer have become more tailored" and less disruptive to women's lives, Dr. Lynn Dengel, a University of Virginia surgical oncologist, told Yahoo in March.
"Because [Wiles] was taking care of her health [and getting screened], not only will her prognosis be better, but it will probably minimize what treatment she has to go through and will benefit her work-life and overall balance," Dengel said. She added that most of her patients are diagnosed early and can continue to work while undergoing breast cancer treatment, reducing the financial burden and overall disruption to their lives.
Wiles was diagnosed at age 68 — slightly older than the median age (62) when most women learn they have breast cancer. More than 380,000 American women are diagnosed with some form of breast cancer each year, according to the American Cancer Society (ACS).
Breast cancer remains the most common form of cancer among women in the U.S., except for skin cancers. And rates are rising. But there's good news: More women are surviving the disease. Treatments have also improved, becoming tolerable enough that many women still work, as Wiles intends to do. Here's what to know about the disease, why rates are rising and how women can reduce their risks.
#breast #diagnosed



11 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson

13 days ago
Interested in Johnson & Johnson? Here are five stocks we like better.
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested
Johnson & Johnson raised its growth ambitions, forecasting 6.5% adjusted operational sales growth and 7.3% adjusted EPS growth in 2026, with revenue expected to surpass $100 billion. Executives see 2027 improving further and aim for double-digit growth by the end of the decade despite STELARA biosimilar competition.
The company plans to detail its long-term growth strategy at an enterprise review in December, highlighting new product launches, a pipeline that includes 12 proof-of-concept molecules in Phase III, and the durability of growth beyond 2030.
Capital spending is focused on Innovative Medicine and MedTech launches, including ICOTYDE, cancer treatments, and the OTTAVA robotic surgical system. J&J also expects continued momentum from its myeloma therapies, ICOTYDE's expanding coverage, and MedTech products, while using acquisitions mainly to support growth beyond the current decade.
5 Defensive Stocks to Watch as CPI and the Fed Put the Rally to the Test
#adjusted #interested

13 days ago
The Cooper Companies, Inc. (NASDAQ:COO) cut its fiscal 2026 profit and revenue forecasts after weaker-than-expected demand for contact lenses weighed on its CooperVision business. The company now expects adjusted earnings of $4.51–$4.55 per share, down from its previous forecast of $4.58–$4.66, while revenue guidance was reduced to $4.23–$4.25 billion from $4.29–$4.32 billion. Third-quarter revenue came in at $1.07 billion, below Wall Street's $1.10 billion estimate, although adjusted EPS of $1.15 beat expectations.
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision
The weakness was concentrated in CooperVision, where revenue fell to $717 million. Cooper said a reduction in U.S. channel inventory hurt results and is expected to continue affecting the fourth quarter. At the same time, the company completed its strategic review and decided to retain CooperSurgical rather than sell the business.
The biggest bullish argument is that some of the current weakness may be temporary rather than a fundamental deterioration in the contact lens market. The Cooper Companies, Inc. (NASDAQ:COO) specifically pointed to U.S. channel inventory reductions, meaning part of the sales pressure reflects distributors and customers working through existing stock rather than consumers permanently abandoning contact lenses. If inventories normalize, CooperVision could see a recovery in sales growth.
Cooper also continues to have a strong position in the global contact lens market. The company is investing in new products, expanding CooperVision's sales and marketing organization and improving inventory and logistics operations. Its strategic review also identified opportunities to reduce costs and improve operational efficiency.
There are encouraging signs beneath the weak headline numbers. Adjusted third-quarter EPS still increased 4% year over year to $1.15, while free cash flow jumped 66% to $273 million. The Cooper Companies, Inc. (NASDAQ:COO) also increased its share-repurchase authorization from $2 billion to $3 billion, giving the company another way to support per-share earnings if the stock remains depressed.
#Companies #revenue #contact #coopervision


15 days ago
Interested in Intuitive Surgical, Inc.? Here are five stocks we like better.
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable
Global procedure growth remains intact despite a recent U.S. slowdown and Affordable Care Act-related uncertainty; Intuitive Surgical maintained its 13.5%–15.5% global procedure-growth outlook, expecting results near the midpoint.
Ambulatory surgery centers and international markets remain important expansion opportunities, with second-quarter system placements rising in the U.S. and abroad. However, China remains pressured by local competition and slower tenders, with improved visibility not expected until 2027.
Future growth could come from da Vinci 5 upgrades, Force Feedback instruments, new procedures and sites of care, and AI services such as Case Insights. The company also reported strong financial performance, including 21% revenue growth and operating and free-cash-flow margins above historical averages.
This AI ETF Is Missing the Biggest AI Winners
#affordable

15 days ago
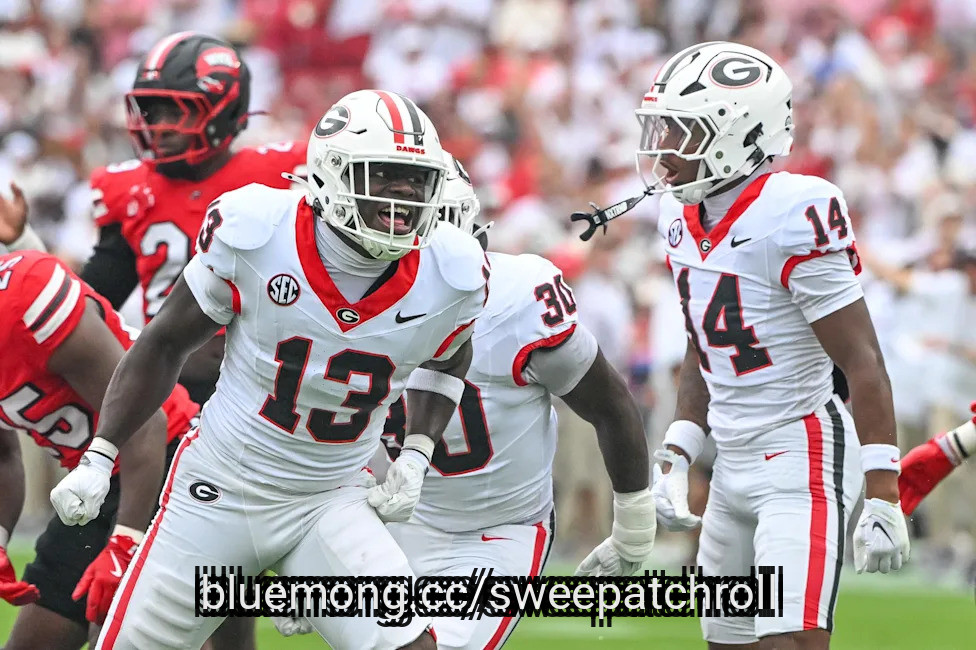
You don't put up 60+ points in back-to-back games for the first time since 1915 without a total team effort. But even then some Bulldogs are bound to distinguish themselves. Those valiant warriors in Red and Black are your MVDs, the Most Valuable Dawgs from Georgia's 70-20 victory over Western Kentucky.
Offense: Gunner Stockton. There's no point in overthinking this one. Gunner finished 13 of 16 for 234 yards passing and 5 touchdowns in a shade under two quarters of work. That's downright surgical in its efficiency. If he can continue to carve up defenses that way in the SEC schedule, the Bulldog offense is heading for a big year.
Defense:Chris Cole. Like most of the Bulldog starters Cole took limited snaps, but while he was in he was all over the Hilltopper offense. Cole finished with 3 tackles, 2 of them solo stops, and got consistent pass rush pressure both inside and outside. It was a really solid, consistent effort for the physically gifted linebacker.
Special teams: AJ Kruah. Kruah also led the team in tackles, by the way, but his forced fumble on the game's opening play set the tone for the day. On a day when Kirby Smart specifically called out his second and third teamers for not being prepared to play, Kruah absolutely came ready to work.
Go 'Dawgs!!!
#team #effort
Offense: Gunner Stockton. There's no point in overthinking this one. Gunner finished 13 of 16 for 234 yards passing and 5 touchdowns in a shade under two quarters of work. That's downright surgical in its efficiency. If he can continue to carve up defenses that way in the SEC schedule, the Bulldog offense is heading for a big year.
Defense:Chris Cole. Like most of the Bulldog starters Cole took limited snaps, but while he was in he was all over the Hilltopper offense. Cole finished with 3 tackles, 2 of them solo stops, and got consistent pass rush pressure both inside and outside. It was a really solid, consistent effort for the physically gifted linebacker.
Special teams: AJ Kruah. Kruah also led the team in tackles, by the way, but his forced fumble on the game's opening play set the tone for the day. On a day when Kirby Smart specifically called out his second and third teamers for not being prepared to play, Kruah absolutely came ready to work.
Go 'Dawgs!!!
#team #effort

15 days ago
The Cooper Companies Inc. (NASDAQ:COO), a leading medical device company, announced its third quarter fiscal 2026 results on September 9. Topline went up 1% to $1.066 billion in comparison with the same quarter last year, which also included 1% organic growth. The company posted quarterly adjusted diluted EPS of $1.15, which represented a 4% jump from Q3 FY25. During the quarter, $339.1 million was spent on repurchasing around 4.9 million of the company's common shares. This leaves management with $1.5 billion of repurchase capacity, which remains available after the Board had raised its buyback authorization from $2 billion to $3 billion.
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash
The quarter featured several encouraging highlights. These include earnings that exceeded projections, notable growth across the fertility segment within CooperSurgical, record free cash flow generation, and a major tax resolution in the company's favor.
GAAP gross margin went up from 65% in Q3 FY25 to 67% during the recent quarter, largely reflecting the comparison against fiscal 2025 inventory write-downs tied to a CooperSurgical product line exit. Adjusted operating margin improved by 30 basis points to 26%, supported by cost discipline and productivity gains, though partly offset by currency headwinds.
Interest expense fell to $21.5 million from $25.4 million a year prior, reflecting lower rates and reduced average debt. Free cash flow surged 66% to $273.0 million, driven by $341.7 million in operating cash flow less $68.7 million in capital spending.
Due to unfavorable currency movements and rising manufacturing costs, the Q3 gross margin settled at 67% on adjusted basis. This was a 60 basis point drop from Q3 FY25. Certain areas of the business grant caution, such as the CooperVision segment. It generated flat organic growth amid notable weakness across the Asia Pacific and Americas regions.
#billion #cash

16 days ago
Investors hammered Cooper Companies (COO) on Thursday after the medtech's fiscal third-quarter sales lagged Wall Street's expectations, leading to a guidance cut.
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall
Specifically, the CooperVision segment — which sells contact lenses — missed expectations by 4.5%, William Blair **** yst Steven Lichtman said in a report. The miss was due to destocking. Further, the company opted against selling its CooperSurgical business following a strategic review.
"The 'no sale' is a surprise after management highlighted prospective buyers on the last earnings call," he said. "With CVI (CooperVision) results also disappointing, the stock moves back into the penalty box."
On today's stock market, Cooper Companies shares toppled 14.7%, closing at 54.17. Shares are already trading well below their key moving averages, IBD MarketSurge charts show.
Cooper said it couldn't sell the surgical division due to competition for its implantable contraceptive, Paragard, an intrauterine device. In June, Organon (OGN) licensed Miudella, a rival to Cooper's non-hormonal IUD. Cooper is also facing fertility litigation, BofA Securities **** yst Travis Steed said in a note to clients.
#Companies #expectations #investors #wall

16 days ago
Patrick Mahomes sparks concern with awkward walk before Chiefs season opener originally appeared on The Sporting News. Add The Sporting News as a Preferred Source by clicking here.
Patrick Mahomes wanted to end the questions about his surgically repaired left knee. A brief moment after his latest press conference only created more of them. The Kansas City Chiefs quarterback smiled as he left the podium Thursday and delivered a playful message to reporters.
"Hopefully I'm done with the questions about the leg," Mahomes said, according to a video shared by Ari Meirov.
Some fans focused less on the comment and more on the way Mahomes appeared to walk away. A second post highlighting the clip helped fuel speculation that the three-time Super Bowl MVP might have been favoring his injured leg.
The short video does not prove that Mahomes experienced a setback, and the Chiefs have not announced a new problem. It does, however, demonstrate how closely every movement will be watched when Mahomes returns Monday night against the Denver Broncos.
#chiefs
Patrick Mahomes wanted to end the questions about his surgically repaired left knee. A brief moment after his latest press conference only created more of them. The Kansas City Chiefs quarterback smiled as he left the podium Thursday and delivered a playful message to reporters.
"Hopefully I'm done with the questions about the leg," Mahomes said, according to a video shared by Ari Meirov.
Some fans focused less on the comment and more on the way Mahomes appeared to walk away. A second post highlighting the clip helped fuel speculation that the three-time Super Bowl MVP might have been favoring his injured leg.
The short video does not prove that Mahomes experienced a setback, and the Chiefs have not announced a new problem. It does, however, demonstrate how closely every movement will be watched when Mahomes returns Monday night against the Denver Broncos.
#chiefs



19 days ago
Reuters reported that McKesson Corporation (NYSE:MCK) said it would buy privately held Precision Medicine Group in a deal valued at about $2.25 billion as part of a "years-long effort to strengthen its higher-growth businesses."
McKesson has been reshaping its portfolio by exiting non-core **** ets and streamlining its operations while investing in businesses such as oncology and specialty care. Precision Medicine Group, based in Bethesda, Maryland, provides clinical research, laboratory testing, and commercialization services that help biopharma companies develop and launch new medicines. It will become part of McKesson's Oncology & Multispecialty segment once the deal closes, though McKesson gave no completion timeline. CEO Brian Tyler said the acquisition would "enhance our clinical research and commercialization services, strengthen clinical trial execution, and broaden our clinical service offerings."
The deal fits neatly into a growth strategy McKesson Corporation (NYSE:MCK) has already been executing, not a scattershot bet. The company has spent recent years exiting non-core **** ets while specifically building out oncology and specialty care. It means this acquisition extends a strategy management has already proven willing to follow through on.
McKesson is adding Precision Medicine to its strongest-performing division rather than using the acquisition to revive a struggling business. Revenue in the Oncology & Multispecialty segment jumped 33% to $14.2 billion in the first quarter of fiscal 2026, while JP Morgan **** yst Lisa Gill said the acquisition will likely strengthen McKesson's biopharma offerings.
The purchase reflects disciplined capital recycling, not new debt-fueled expansion. McKesson said in April it would sell a minority stake in its medical-surgical solutions business to Apollo Funds for $1.25 billion while pursuing an IPO for that unit, showing the company is actively shedding slower-growth **** ets to help fund investments like this one.
#medicine #acquisition #deal
McKesson has been reshaping its portfolio by exiting non-core **** ets and streamlining its operations while investing in businesses such as oncology and specialty care. Precision Medicine Group, based in Bethesda, Maryland, provides clinical research, laboratory testing, and commercialization services that help biopharma companies develop and launch new medicines. It will become part of McKesson's Oncology & Multispecialty segment once the deal closes, though McKesson gave no completion timeline. CEO Brian Tyler said the acquisition would "enhance our clinical research and commercialization services, strengthen clinical trial execution, and broaden our clinical service offerings."
The deal fits neatly into a growth strategy McKesson Corporation (NYSE:MCK) has already been executing, not a scattershot bet. The company has spent recent years exiting non-core **** ets while specifically building out oncology and specialty care. It means this acquisition extends a strategy management has already proven willing to follow through on.
McKesson is adding Precision Medicine to its strongest-performing division rather than using the acquisition to revive a struggling business. Revenue in the Oncology & Multispecialty segment jumped 33% to $14.2 billion in the first quarter of fiscal 2026, while JP Morgan **** yst Lisa Gill said the acquisition will likely strengthen McKesson's biopharma offerings.
The purchase reflects disciplined capital recycling, not new debt-fueled expansion. McKesson said in April it would sell a minority stake in its medical-surgical solutions business to Apollo Funds for $1.25 billion while pursuing an IPO for that unit, showing the company is actively shedding slower-growth **** ets to help fund investments like this one.
#medicine #acquisition #deal


23 days ago
Medtronic (NYSE: MDT), one of the world's largest medical device makers, was once considered a stable blue chip stock. But over the past five years, it has declined by more than 30% due to supply chain constraints, higher costs, quality control issues, and competitive pressure. However, Medtronic's stock is worth buying again for four simple reasons.
In fiscal 2026 (which ended this April), Medtronic's revenue grew 8.4% (and 5.8% organically) to $36.4 billion, marking its strongest top-line growth in ten years.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That acceleration was driven by 9.3% organic growth in its cardiovascular business, which accounted for more than 38% of its enterprise revenue. All of its other segments (neuroscience, medical surgical, and diabetes) also grew organically.
Medtronic expects its organic revenue to rise 7.25%-7.75% in fiscal 2027, representing another multi-year high and easily exceeding its historical average of around 5%. Once again, that growth will be led by its rising sales of cardiovascular devices. From fiscal 2026 to fiscal 2029, ****** ysts expect its reported revenue to grow at a 5% CAGR.
#fiscal #NVIDIA
In fiscal 2026 (which ended this April), Medtronic's revenue grew 8.4% (and 5.8% organically) to $36.4 billion, marking its strongest top-line growth in ten years.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
That acceleration was driven by 9.3% organic growth in its cardiovascular business, which accounted for more than 38% of its enterprise revenue. All of its other segments (neuroscience, medical surgical, and diabetes) also grew organically.
Medtronic expects its organic revenue to rise 7.25%-7.75% in fiscal 2027, representing another multi-year high and easily exceeding its historical average of around 5%. Once again, that growth will be led by its rising sales of cardiovascular devices. From fiscal 2026 to fiscal 2029, ****** ysts expect its reported revenue to grow at a 5% CAGR.
#fiscal #NVIDIA

23 days ago
In the world of robotic surgery, one company is both the undisputed leader and the most expensive option, forcing investors to ask if operational excellence is worth the premium.
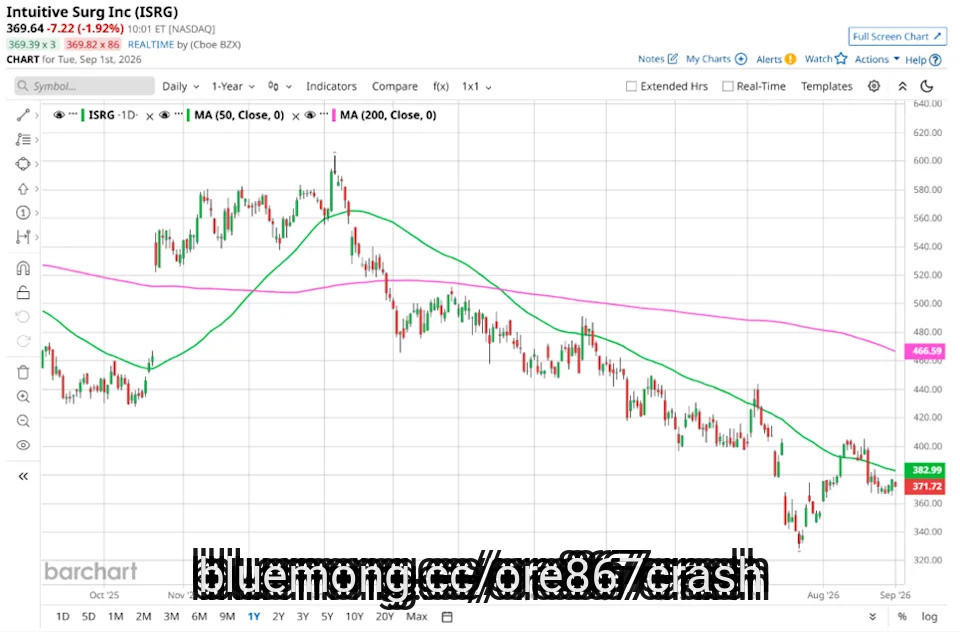
Intuitive Surgical (ISRG), the pioneer of robotic-assisted surgery, trades around $370, a share after a tough year. The stock has delivered a -21% return over the last twelve months, badly trailing the S&P 500's +19.2% gain. Yet, within its peer group, it commands the highest valuation. Why does the market charge a top-tier price for the company with the group's worst-performing stock?
By the numbers, Intuitive Surgical's operational lead is real, even if Globus Medical sits close behind at 19.7%. The company's revenue grew 21% over the last twelve months, well ahead of diversified rivals like Medtronic, which grew at 8.4%.. Its 31% operating margin also leads the pack, again comfortably ahead of Medtronic's 18.8%. This is a business that executes at a higher level than its competition. The market sees this performance and charges accordingly. Intuitive Surgical trades at 42.5 times earnings, the highest multiple in its group. For comparison, Medtronic trades at a much lower 24.2 times earnings. The mismatch is stark: investors are paying a premium for leading fundamentals, but so far, that premium has not translated into positive returns.
ISRG
MDT
#robotic
Intuitive Surgical (ISRG), the pioneer of robotic-assisted surgery, trades around $370, a share after a tough year. The stock has delivered a -21% return over the last twelve months, badly trailing the S&P 500's +19.2% gain. Yet, within its peer group, it commands the highest valuation. Why does the market charge a top-tier price for the company with the group's worst-performing stock?
By the numbers, Intuitive Surgical's operational lead is real, even if Globus Medical sits close behind at 19.7%. The company's revenue grew 21% over the last twelve months, well ahead of diversified rivals like Medtronic, which grew at 8.4%.. Its 31% operating margin also leads the pack, again comfortably ahead of Medtronic's 18.8%. This is a business that executes at a higher level than its competition. The market sees this performance and charges accordingly. Intuitive Surgical trades at 42.5 times earnings, the highest multiple in its group. For comparison, Medtronic trades at a much lower 24.2 times earnings. The mismatch is stark: investors are paying a premium for leading fundamentals, but so far, that premium has not translated into positive returns.
ISRG
MDT
#robotic


24 days ago
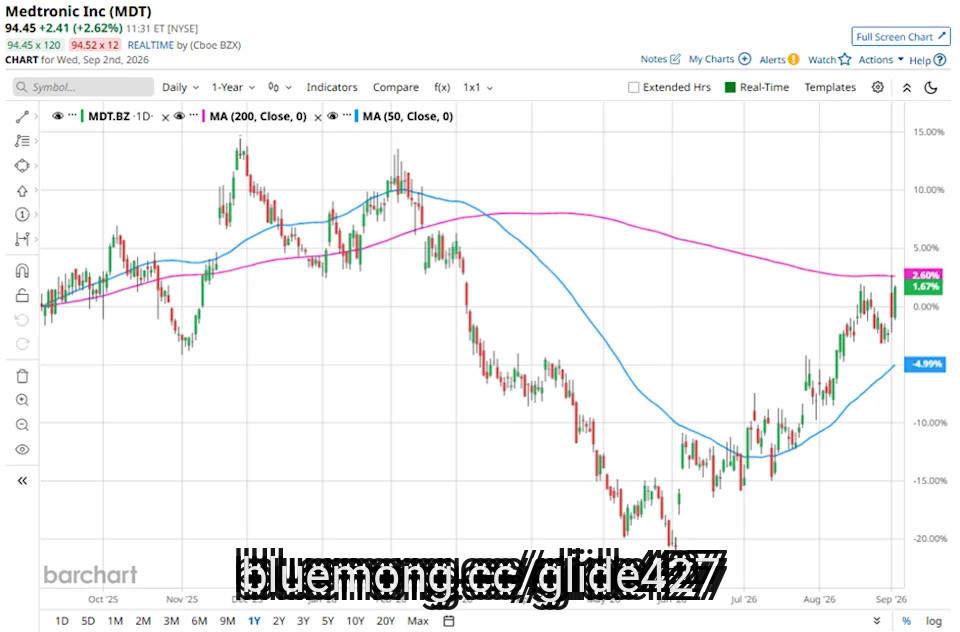
With a market cap of $117.8 billion, Medtronic plc (MDT) is a leading global healthcare technology company focused on addressing complex health challenges through innovative medical solutions. With a global workforce serving patients across more than 150 countries, its technologies span cardiac devices, surgical robotics, insulin pumps, surgical tools, and patient monitoring systems.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#surgical #guided
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ****** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#surgical #guided

24 days ago
With a market cap of $117.8 billion, Medtronic plc (MDT) is a leading global healthcare technology company focused on addressing complex health challenges through innovative medical solutions. With a global workforce serving patients across more than 150 countries, its technologies span cardiac devices, surgical robotics, insulin pumps, surgical tools, and patient monitoring systems.
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ******* ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Health #surgical #Companies
Companies valued at $10 billion or more are generally considered "large-cap" stocks, and Medtronic fits this criterion perfectly. Guided by its mission to alleviate pain, restore health, and extend life, Medtronic's innovations aim to improve outcomes and transform lives worldwide.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why ******* ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#Health #surgical #Companies


24 days ago
There's few things more excruciating for a fantasy football manager than watching one of your players waste away on a bad offense. Whether it's poor play-calling, offensive line play or an incompetent quarterback, even the best receivers and running backs can struggle to break through because of their circumstances.
We've already identified the teams to avoid in fantasy for that reason, and now it's the flip side of that coin. Here are five teams worth targeting in 2026 fantasy football drafts, as they could produce enough offensive fireworks to have several players worth rostering.
The Chargers brought in OC Mike McDaniel to revitalize their offense after he did wonders with Tua Tagovailoa in Miami. Tackles Rashawn Slater and Joe Alt are now healthy as well, so it's full speed ahead for Justin Herbert, running back Omarion Hampton and receivers Ladd McConkey and Quentin Johnston. I'm targeting Johnston late in all my drafts, as he's the Chargers' undisputed deep threat with Herbert one of the NFL's best deep passers. Johnston is a steal at his current ADP.
Dallas has the NFL's most fearsome wide receiver duo in CeeDee Lamb and George Pickens, plus a surgically accurate quarterback in Dak Prescott. Javonte Williams is also coming off a career year as the team's lead running back, and his powerful style should continue to be a perfect complement to the high-flying pass game. All four players are worth targeting, but tight end Jake Ferguson is a fade at his current ADP as his game is touchdown-reliant and lacks the verticality of, say, Isaiah Likely or Juwan Johnson.
Ben Johnson has a case to be the NFL's brightest offensive mind, so it's wise to load up on Bears in drafts. D'Andre Swift is a perfect RB2 if you go WR heavy early. Rome Odunze and Luther Burden III have a big chance to outplay their ADP if Caleb Williams can take the leap many are expecting. And as for the tight end skyrocketing up draft boards, Colston Loveland has a chance for a Travis Kelce-type season if he can stay healthy and build off the momentum he had late last season.
#johnston
We've already identified the teams to avoid in fantasy for that reason, and now it's the flip side of that coin. Here are five teams worth targeting in 2026 fantasy football drafts, as they could produce enough offensive fireworks to have several players worth rostering.
The Chargers brought in OC Mike McDaniel to revitalize their offense after he did wonders with Tua Tagovailoa in Miami. Tackles Rashawn Slater and Joe Alt are now healthy as well, so it's full speed ahead for Justin Herbert, running back Omarion Hampton and receivers Ladd McConkey and Quentin Johnston. I'm targeting Johnston late in all my drafts, as he's the Chargers' undisputed deep threat with Herbert one of the NFL's best deep passers. Johnston is a steal at his current ADP.
Dallas has the NFL's most fearsome wide receiver duo in CeeDee Lamb and George Pickens, plus a surgically accurate quarterback in Dak Prescott. Javonte Williams is also coming off a career year as the team's lead running back, and his powerful style should continue to be a perfect complement to the high-flying pass game. All four players are worth targeting, but tight end Jake Ferguson is a fade at his current ADP as his game is touchdown-reliant and lacks the verticality of, say, Isaiah Likely or Juwan Johnson.
Ben Johnson has a case to be the NFL's brightest offensive mind, so it's wise to load up on Bears in drafts. D'Andre Swift is a perfect RB2 if you go WR heavy early. Rome Odunze and Luther Burden III have a big chance to outplay their ADP if Caleb Williams can take the leap many are expecting. And as for the tight end skyrocketing up draft boards, Colston Loveland has a chance for a Travis Kelce-type season if he can stay healthy and build off the momentum he had late last season.
#johnston

24 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Organic revenue growth of 13.7% was driven by strong underlying market demand and execution across the 'Big 3' businesses: CRM, CST, and Surgical.
Cardiac Ablation Solutions (CAS) delivered 88% growth, fueled by Sphere-9 share gains and the Affera mapping platform reaching a $2 billion trailing 12-month revenue milestone.
The AiBLE ecosystem in Cranial & Spinal Technologies is driving growth by connecting AI-driven planning, robotics, and navigation, which traditionally operated in silos.
Management attributes the broad-based performance to the compounding impact of multi-year strategic, operational, and cultural changes aimed at commercial consistency.
#Growth #driven #solutions
Organic revenue growth of 13.7% was driven by strong underlying market demand and execution across the 'Big 3' businesses: CRM, CST, and Surgical.
Cardiac Ablation Solutions (CAS) delivered 88% growth, fueled by Sphere-9 share gains and the Affera mapping platform reaching a $2 billion trailing 12-month revenue milestone.
The AiBLE ecosystem in Cranial & Spinal Technologies is driving growth by connecting AI-driven planning, robotics, and navigation, which traditionally operated in silos.
Management attributes the broad-based performance to the compounding impact of multi-year strategic, operational, and cultural changes aimed at commercial consistency.
#Growth #driven #solutions

25 days ago
Sunnyvale, California-based Intuitive Surgical, Inc. (ISRG) develops, manufactures, and markets products that enable physicians and healthcare providers to enhance the quality of and access to minimally invasive care. Valued at $133.1 billion by market cap, the company offers endoscopes, endoscopic retractors and disectors, scissors, scalpels, forceps, needle holders, electrocautery, ultrasonic cutters, and accessories during surgical procedures.
Companies worth $10 billion or more are generally described as "large-cap stocks," and ISRG definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical instruments & supplies industry. Intuitive Surgical excels in robotic-assisted surgery with its gold-standard da Vinci system, backed by strong brand reputation, continuous R&D investment, and comprehensive surgeon training, driving user proficiency and patient outcomes.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#intuitive #dear
Companies worth $10 billion or more are generally described as "large-cap stocks," and ISRG definitely fits that description, with its market cap exceeding this threshold, reflecting its substantial size, influence, and dominance in the medical instruments & supplies industry. Intuitive Surgical excels in robotic-assisted surgery with its gold-standard da Vinci system, backed by strong brand reputation, continuous R&D investment, and comprehensive surgeon training, driving user proficiency and patient outcomes.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#intuitive #dear

28 days ago
The dream of seeing Spencer Schwellenbach on the mound this season is officially over. The Braves announced Friday that the young starter will undergo surgery to repair a fractured right elbow. This procedure inserts a screw to stabilize the joint, a move the team and player tried hard to avoid for months. Per MLB.com Braves, Schwellenbach was "barely able to feel his arm" during a recent bullpen session in Florida, leaving the team with no other choice.
Schwellenbach knew this day might come, even as he fought to heal naturally. Last year, during a June 28 start versus the Phillies, he fractured his bone and expected it to heal naturally. "When you fracture your bone, the hopes are that it heals itself over six to eight weeks," Schwellenbach said. The team gave him that initial time, then another three months, but the pain kept returning. Now, the 26-year-old has accepted the reality of the operation.
Rehab was a frustrating cycle of small gains followed by painful stops. Schwellenbach removed bone spurs this past winter and felt encouraged when his fastball hit 94 mph recently. Yet, he could never clear the final hurdle of discomfort. "It was almost like every time I'd get to the finish line, I couldn't get over the top," Schwellenbach said. This pattern forced the decision to finally fix the fracture surgically.
The timeline for his return is now set for the distant future. While some hope existed for a July or August comeback, those chances vanished with this setback. The surgery marks the end of his 2026 campaign, joining Hurston Waldrep, who is also undergoing elbow surgery. Both pitchers are out for the year, a blow to a rotation that needed depth.
Despite the bad news, Braves manager Walt Weiss sees a path forward. He noted that Schwellenbach has youth and elite ability working in his favor. "It's going to be a long haul, but he's got youth on his side and he's got talent on his side," Weiss said. The manager remains optimistic, though he admits there are no guarantees for a full recovery to his pre-injury form.
#elbow
Schwellenbach knew this day might come, even as he fought to heal naturally. Last year, during a June 28 start versus the Phillies, he fractured his bone and expected it to heal naturally. "When you fracture your bone, the hopes are that it heals itself over six to eight weeks," Schwellenbach said. The team gave him that initial time, then another three months, but the pain kept returning. Now, the 26-year-old has accepted the reality of the operation.
Rehab was a frustrating cycle of small gains followed by painful stops. Schwellenbach removed bone spurs this past winter and felt encouraged when his fastball hit 94 mph recently. Yet, he could never clear the final hurdle of discomfort. "It was almost like every time I'd get to the finish line, I couldn't get over the top," Schwellenbach said. This pattern forced the decision to finally fix the fracture surgically.
The timeline for his return is now set for the distant future. While some hope existed for a July or August comeback, those chances vanished with this setback. The surgery marks the end of his 2026 campaign, joining Hurston Waldrep, who is also undergoing elbow surgery. Both pitchers are out for the year, a blow to a rotation that needed depth.
Despite the bad news, Braves manager Walt Weiss sees a path forward. He noted that Schwellenbach has youth and elite ability working in his favor. "It's going to be a long haul, but he's got youth on his side and he's got talent on his side," Weiss said. The manager remains optimistic, though he admits there are no guarantees for a full recovery to his pre-injury form.
#elbow

30 days ago
BioNTech SE (NASDAQ:BNTX) rallied following the first positive interim Phase 3 topline result for a personalized mRNA cancer therapy. Moderna and Merck said intismeran, combined with Keytruda, significantly improved recurrence-free and distant metastasis-free survival in patients with surgically removed high-risk melanoma. The result lifted other mRNA developers because it provided the strongest evidence yet that the technology can work against cancer in a large late-stage trial. For BioNTech SE (NASDAQ:BNTX), however, the rally raises a harder question: does validation of the therapeutic class meaningfully improve the odds for its own candidates, or has the market moved ahead of company-specific evidence?
The distinction matters. Moderna's intismeran is individually designed around mutations found in each patient's tumor. BioNTech SE (NASDAQ:BNTX) is awaiting an interim ******* ysis from the Phase 3 portion of AHEAD-MERIT, which tests BNT113 with pembrolizumab in first-line unresectable recurrent or metastatic HPV16-positive, PD-L1-positive head-and-neck squamous cell carcinoma. BNT113 is an off-the-shelf FixVac therapy encoding the HPV16 E6 and E7 oncoproteins. Different antigens, manufacturing approaches, cancer types and treatment settings prevent Moderna's result from functioning as a direct clinical read-through.
Still, BioNTech SE (NASDAQ:BNTX) has more than one attempt at building an oncology franchise. The company has 14 ongoing pivotal trials across mRNA immunotherapies, immunomodulators and antibody-drug conjugates. It expects three late-stage readouts during 2026, including the BNT113 interim ******* ysis, and ended June with €16.6 billion in cash, cash equivalents and security investments.
The bull case for BioNTech SE (NASDAQ:BNTX) is that Moderna and Merck have reduced skepticism around the broader platform. Their trial enrolled 1,137 patients and met its primary endpoint of recurrence-free survival and a secondary endpoint of distant metastasis-free survival, with no new safety concerns reported. The result shows that an mRNA therapy can add meaningful benefit to a checkpoint inhibitor in Phase 3.
BioNTech also has a personalized program that more closely resembles intismeran. Autogene cevumeran, partnered with Genentech, is being studied in randomized Phase 2 trials in pancreatic and colorectal cancer. Meanwhile, BNT113 has FDA Fast Track designation and could provide BioNTech's own pivotal mRNA evidence. The company's cash position gives it room to fund these programs and absorb failures elsewhere in the portfolio.
#biontech
The distinction matters. Moderna's intismeran is individually designed around mutations found in each patient's tumor. BioNTech SE (NASDAQ:BNTX) is awaiting an interim ******* ysis from the Phase 3 portion of AHEAD-MERIT, which tests BNT113 with pembrolizumab in first-line unresectable recurrent or metastatic HPV16-positive, PD-L1-positive head-and-neck squamous cell carcinoma. BNT113 is an off-the-shelf FixVac therapy encoding the HPV16 E6 and E7 oncoproteins. Different antigens, manufacturing approaches, cancer types and treatment settings prevent Moderna's result from functioning as a direct clinical read-through.
Still, BioNTech SE (NASDAQ:BNTX) has more than one attempt at building an oncology franchise. The company has 14 ongoing pivotal trials across mRNA immunotherapies, immunomodulators and antibody-drug conjugates. It expects three late-stage readouts during 2026, including the BNT113 interim ******* ysis, and ended June with €16.6 billion in cash, cash equivalents and security investments.
The bull case for BioNTech SE (NASDAQ:BNTX) is that Moderna and Merck have reduced skepticism around the broader platform. Their trial enrolled 1,137 patients and met its primary endpoint of recurrence-free survival and a secondary endpoint of distant metastasis-free survival, with no new safety concerns reported. The result shows that an mRNA therapy can add meaningful benefit to a checkpoint inhibitor in Phase 3.
BioNTech also has a personalized program that more closely resembles intismeran. Autogene cevumeran, partnered with Genentech, is being studied in randomized Phase 2 trials in pancreatic and colorectal cancer. Meanwhile, BNT113 has FDA Fast Track designation and could provide BioNTech's own pivotal mRNA evidence. The company's cash position gives it room to fund these programs and absorb failures elsewhere in the portfolio.
#biontech
30 days ago
Aug 28 (Reuters) - BioNTech SE said on Friday it has decided to terminate the mid-stage trial of its experimental mRNA-based cancer vaccine for patients with a type of colorectal cancer, sending the German firm's U.S.-listed shares down nearly 9%.
An independent data safety monitoring board, responsible for overseeing the safety and integrity of the trial, recommended discontinuing treatment of patients and terminating the study.
The immunotherapy, autogene cevumeran, is being jointly developed by BioNTech and Roche's Genentech. The trial was evaluating it as an adjuvant monotherapy in patients with high-risk stage II or stage III colorectal cancer whose tumors had been surgically removed but who remained ctDNA-positive.
In its most recent review of the available data of this trial, the board identified a numerical imbalance in overall survival between treatment arms in this specific patient population and noted that further trial continuation was unlikely to change the efficacy outcome.
(Reporting by Sriparna Roy in Bengaluru; Editing by Shilpi Majumdar)
#patients #colorectal
An independent data safety monitoring board, responsible for overseeing the safety and integrity of the trial, recommended discontinuing treatment of patients and terminating the study.
The immunotherapy, autogene cevumeran, is being jointly developed by BioNTech and Roche's Genentech. The trial was evaluating it as an adjuvant monotherapy in patients with high-risk stage II or stage III colorectal cancer whose tumors had been surgically removed but who remained ctDNA-positive.
In its most recent review of the available data of this trial, the board identified a numerical imbalance in overall survival between treatment arms in this specific patient population and noted that further trial continuation was unlikely to change the efficacy outcome.
(Reporting by Sriparna Roy in Bengaluru; Editing by Shilpi Majumdar)
#patients #colorectal

30 days ago
NEW DELHI: Anaya Bangar has responded to criticism from South Africa all-rounder Marizanne Kapp over her bid to return to competitive women's cricket, urging those opposed to her participation to "educate themselves" on the subject.
Kapp had strongly criticised Cricket Australia's decision to offer Anaya a pathway back into competitive women's cricket, calling it "absolutely ridiculous" and saying "this should not be allowed".
The comments came after Cricket Australia cleared Anaya, daughter of former India cricketer and coach Sanjay Bangar, for a pathway towards elite women's cricket under its Inclusion of Transgender and Gender Diverse Players in Elite Cricket Policy.
Anaya, who underwent gender-affirming surgery in March this year, is currently eligible to play community cricket in any state or territory of Australia. Her eligibility for elite cricket from March 2027 remains subject to the policy requirements.
Anaya's potential return has generated reactions on both sides, with the 25-year-old now responding directly to Kapp's criticism.
"I think people who want to raise their voice against it should actually educate themselves on this topic, and I've already provided the necessary information in terms of not having any unfair advantage, and also complying with the guidelines set by Cricket Australia.
"If anyone's personal opinion is in that sort of way, I hope they go and educate themselves," she said with a shrug while speaking to PTI.
Anaya is hoping to eventually pursue a pathway to the Women's Big Bash League, although she is yet to sign up with a local club. Her immediate focus is on playing at the community level and proving herself through her performances.
Anaya said she had spent a long period in "survival mode" and was only now beginning to process everything she had experienced during her transition and the long road back to cricket.
"...basically now, the next role is to go there and play club cricket and prove myself by my performances, and if I do well, I hopefully might have a chance to be picked for the Women's Big Bash League. So, baby steps from here, but the major part of having a place to play has been cleared," she said.
She is currently in talks with a few cricket clubs and is waiting to decide on the right one "to go there and start playing."
For Anaya, the CA decision represents a significant breakthrough after years away from competitive cricket. While she has been given a pathway, it does not guarantee selection in any team.
Anaya further added that the process was neither "automatic or informal", with CA considering her medical and surgical history, hormone and testosterone levels, cricketing background, playing footage and scientific and athletic performance work undertaken with Manchester Metropolitan University's Institute of Sport.
She also said her most recent blood test in July recorded total testosterone at 0.6 nanomoles, which she said was within the female reference rang
Kapp had strongly criticised Cricket Australia's decision to offer Anaya a pathway back into competitive women's cricket, calling it "absolutely ridiculous" and saying "this should not be allowed".
The comments came after Cricket Australia cleared Anaya, daughter of former India cricketer and coach Sanjay Bangar, for a pathway towards elite women's cricket under its Inclusion of Transgender and Gender Diverse Players in Elite Cricket Policy.
Anaya, who underwent gender-affirming surgery in March this year, is currently eligible to play community cricket in any state or territory of Australia. Her eligibility for elite cricket from March 2027 remains subject to the policy requirements.
Anaya's potential return has generated reactions on both sides, with the 25-year-old now responding directly to Kapp's criticism.
"I think people who want to raise their voice against it should actually educate themselves on this topic, and I've already provided the necessary information in terms of not having any unfair advantage, and also complying with the guidelines set by Cricket Australia.
"If anyone's personal opinion is in that sort of way, I hope they go and educate themselves," she said with a shrug while speaking to PTI.
Anaya is hoping to eventually pursue a pathway to the Women's Big Bash League, although she is yet to sign up with a local club. Her immediate focus is on playing at the community level and proving herself through her performances.
Anaya said she had spent a long period in "survival mode" and was only now beginning to process everything she had experienced during her transition and the long road back to cricket.
"...basically now, the next role is to go there and play club cricket and prove myself by my performances, and if I do well, I hopefully might have a chance to be picked for the Women's Big Bash League. So, baby steps from here, but the major part of having a place to play has been cleared," she said.
She is currently in talks with a few cricket clubs and is waiting to decide on the right one "to go there and start playing."
For Anaya, the CA decision represents a significant breakthrough after years away from competitive cricket. While she has been given a pathway, it does not guarantee selection in any team.
Anaya further added that the process was neither "automatic or informal", with CA considering her medical and surgical history, hormone and testosterone levels, cricketing background, playing footage and scientific and athletic performance work undertaken with Manchester Metropolitan University's Institute of Sport.
She also said her most recent blood test in July recorded total testosterone at 0.6 nanomoles, which she said was within the female reference rang
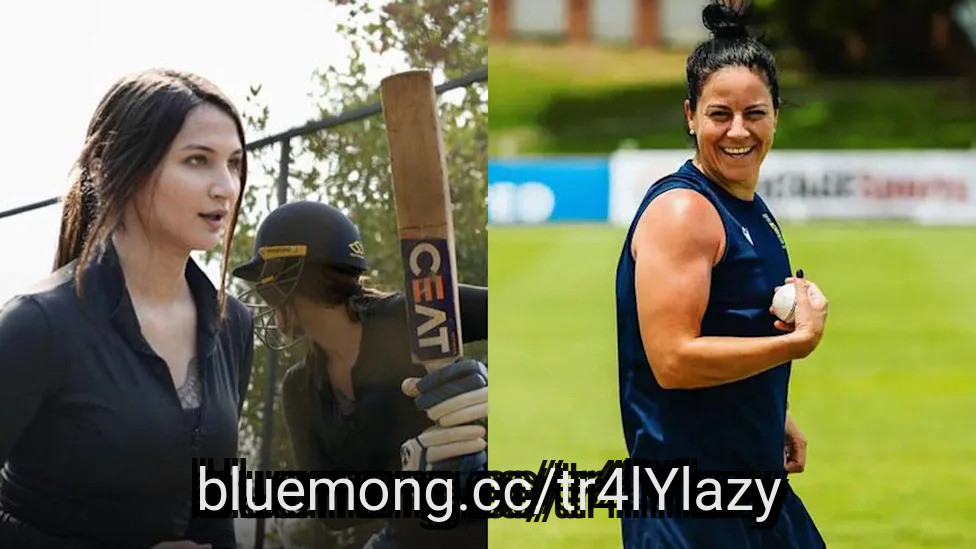

1 month ago
NEW DELHI: South Africa all-rounder Marizanne Kapp has strongly criticised Cricket Australia's decision to offer transgender cricketer Anaya Bangar a pathway back into competitive women's cricket, calling the development "absolutely ridiculous" and saying it "should not be allowed".
Kapp's reaction came after Australian media reported that Cricket Australia (CA) had cleared Anaya, the daughter of former India cricketer and coach Sanjay Bangar, to return to competitive cricket under its Inclusion of Transgender and Gender Diverse Players in Elite Cricket Policy. The decision has since become a major talking point in the cricketing world.
Sharing a report on her Instagram, Kapp wrote: "Absolutely ridiculous. This should not be allowed."
Anaya underwent gender-affirming surgery in March this year and has now been given a pathway towards elite women's cricket in Australia. Under CA's decision, she can play community cricket in any state or territory of Australia until March 2027.
From March 2027, Anaya can become eligible for elite-level women's cricket if she continues to meet the policy requirements, including the stipulated testosterone threshold.
An expert panel comprising CA's Head of Integrity Jacqui Partridge, Integrity Partner and Legal representative Emily Yates, Head of Scheduling, Operations and Domestic Cricket Peter Roach, Anti-Doping Medical Officer Dr Peter Harcourt and Team Doctor Dr Pip Inge considered Anaya's case before confirming the pathway.
"Under Cricket Australia's Policy, a player seeking to participate in the female category of Elite Cricket must establish that their serum testosterone concentration has been below 10 nmol/L continuously for a period of no less than 12 months," CA said in an email to Anaya.
The governing body added that, based on the medical information submitted, the requirement would be satisfied in March 2027. Her eligibility from that point will remain conditional on a blood test confirming that her testosterone level remains below 10 nmol/L and that she continues to meet the policy's requirements.
Anaya said the process was neither "automatic or informal" and that CA had considered her medical and surgical history, hormone and testosterone levels, cricketing background, playing footage and scientific and athletic performance work conducted with Manchester Metropolitan University's Institute of Sport.
She also revealed that her most recent blood test in July recorded total testosterone at 0.6 nanomoles, which she said was within the female reference range reported by the laboratory.
For Anaya, however, the CA decision represents an opportunity rather than a guarantee of a place in elite cricket.
"I want to make another point very clearly. Eligibility is not selection. Cricket Australia has given me a pathway, which does not mean that I have been given a place in a team. I still have to train, compete, perform and earn that opportunity," she said.
"I don't expect my history
Kapp's reaction came after Australian media reported that Cricket Australia (CA) had cleared Anaya, the daughter of former India cricketer and coach Sanjay Bangar, to return to competitive cricket under its Inclusion of Transgender and Gender Diverse Players in Elite Cricket Policy. The decision has since become a major talking point in the cricketing world.
Sharing a report on her Instagram, Kapp wrote: "Absolutely ridiculous. This should not be allowed."
Anaya underwent gender-affirming surgery in March this year and has now been given a pathway towards elite women's cricket in Australia. Under CA's decision, she can play community cricket in any state or territory of Australia until March 2027.
From March 2027, Anaya can become eligible for elite-level women's cricket if she continues to meet the policy requirements, including the stipulated testosterone threshold.
An expert panel comprising CA's Head of Integrity Jacqui Partridge, Integrity Partner and Legal representative Emily Yates, Head of Scheduling, Operations and Domestic Cricket Peter Roach, Anti-Doping Medical Officer Dr Peter Harcourt and Team Doctor Dr Pip Inge considered Anaya's case before confirming the pathway.
"Under Cricket Australia's Policy, a player seeking to participate in the female category of Elite Cricket must establish that their serum testosterone concentration has been below 10 nmol/L continuously for a period of no less than 12 months," CA said in an email to Anaya.
The governing body added that, based on the medical information submitted, the requirement would be satisfied in March 2027. Her eligibility from that point will remain conditional on a blood test confirming that her testosterone level remains below 10 nmol/L and that she continues to meet the policy's requirements.
Anaya said the process was neither "automatic or informal" and that CA had considered her medical and surgical history, hormone and testosterone levels, cricketing background, playing footage and scientific and athletic performance work conducted with Manchester Metropolitan University's Institute of Sport.
She also revealed that her most recent blood test in July recorded total testosterone at 0.6 nanomoles, which she said was within the female reference range reported by the laboratory.
For Anaya, however, the CA decision represents an opportunity rather than a guarantee of a place in elite cricket.
"I want to make another point very clearly. Eligibility is not selection. Cricket Australia has given me a pathway, which does not mean that I have been given a place in a team. I still have to train, compete, perform and earn that opportunity," she said.
"I don't expect my history


1 month ago
Carlos Ulberg is disappointed he can't compete, but won't rush his recovery.
The UFC light heavyweight champion has been on the sidelines since winning the ***** le at UFC 327. Ulberg (14-1 MMA, 10-1 UFC) tore his ACL in his victory over Jiri Prochazka, making for a bittersweet crowning moment.
After undergoing a successful surgery on his right knee, Ulberg has been focused on his recovery. He is currently aiming for a return to action in early 2027.
"It sucks to be on the sidelines watching the guys," Ulberg told reporters during a news conference in Shanghai, China, ahead of UFC Fight Night 286. "I'm still in the gym watching the guys and also doing my rehab. I'd much prefer to be in the gym, having a push and pull with the boys – but I'm a working man, and I'm doing everything to make sure that as the champion, I get myself back on the mats. I'm ready to get myself healthy again so that I can come and defend my ***** le early next year."
Right now, Ulberg wants to ensure this time on the sidelines is his only time out of the game. He doesn't want to rush back and risk re-injuring his surgically repaired knee, which would cause more problems for the light heavyweight ***** le picture.
#sidelines #title #recovery #knee
The UFC light heavyweight champion has been on the sidelines since winning the ***** le at UFC 327. Ulberg (14-1 MMA, 10-1 UFC) tore his ACL in his victory over Jiri Prochazka, making for a bittersweet crowning moment.
After undergoing a successful surgery on his right knee, Ulberg has been focused on his recovery. He is currently aiming for a return to action in early 2027.
"It sucks to be on the sidelines watching the guys," Ulberg told reporters during a news conference in Shanghai, China, ahead of UFC Fight Night 286. "I'm still in the gym watching the guys and also doing my rehab. I'd much prefer to be in the gym, having a push and pull with the boys – but I'm a working man, and I'm doing everything to make sure that as the champion, I get myself back on the mats. I'm ready to get myself healthy again so that I can come and defend my ***** le early next year."
Right now, Ulberg wants to ensure this time on the sidelines is his only time out of the game. He doesn't want to rush back and risk re-injuring his surgically repaired knee, which would cause more problems for the light heavyweight ***** le picture.
#sidelines #title #recovery #knee



1 month ago
Irving, Texas-based McKesson Corporation (MCK) distributes pharmaceuticals, medical-surgical supplies, and health and beauty care products. With a market cap of $100.1 billion, the company also develops, implements, and supports software that facilitates the integration of data throughout the health enterprise. In addition, McKesson offers **** ytic, care management, and patient solutions for payers.
Shares of this healthcare giant have outperformed the broader market over the past year. MCK has gained 25.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.5%. However, in 2026, MCK stock is up 5.5%, compared to the SPX's 12.1% rise on a YTD basis.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#data #Health #care #broader
Shares of this healthcare giant have outperformed the broader market over the past year. MCK has gained 25.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 20.5%. However, in 2026, MCK stock is up 5.5%, compared to the SPX's 12.1% rise on a YTD basis.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#data #Health #care #broader


1 month ago
San Ramon, California-based The Cooper Companies, Inc. (COO) develops, manufactures, and markets contact lenses for wearers. The company has a market cap of $14.9 billion and operates in two segments, CooperVision and CooperSurgical, and offers spherical, toric, and multifocal contact lenses that address vision challenges, such as astigmatism, presbyopia, and myopia, and more.
Shares of Cooper Companies have lagged behind the broader market over the past year, growing 1.6% compared to the S&P 500 Index's ($SPX) 20.5% surge. Moreover, in 2026, the stock has fallen by nearly 6.7%, also underperforming SPX's 12.1% gain.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#california
Shares of Cooper Companies have lagged behind the broader market over the past year, growing 1.6% compared to the S&P 500 Index's ($SPX) 20.5% surge. Moreover, in 2026, the stock has fallen by nearly 6.7%, also underperforming SPX's 12.1% gain.
Soros Fund Management Opened a New Position in Nebius During Q2. What This Means for NBIS Stock.
Nvidia Earnings, Jackson Hole and Other Key Things to Watch this Week
Ahead of Nvidia Earnings, Here's What Barchart Data Says Comes Next for NVDA Stock
#california



1 month ago
Healthcare investors often face a difficult decision when choosing between companies with very different paths to growth. Some businesses are emerging from temporary industry slowdowns, while others continue compounding through durable competitive advantages.
Danaher Corporation (NYSE:DHR) and Intuitive Surgical (NASDAQ:ISRG) illustrate that contrast perfectly. Danaher (NYSE:DHR) is beginning to benefit from improving life sciences spending after several challenging years, whereas Intuitive Surgical (NASDAQ:ISRG) continues to expand one of the healthcare industry's strongest recurring revenue businesses through robotic surgery. Both companies reported encouraging results, but the question for investors is whether a cyclical recovery or a structural growth story offers the better long-term opportunity.
The strongest argument supporting Danaher is that its recovery appears to be broadening. Its Life Sciences business delivered its strongest performance in several years, and although bioprocessing revenue was affected by customer project timings, the underlying order trends remained strong, with bioprocessing orders growing mid-teens in the quarter. This shows that the underlying demand for bioprocessing remained solid, including consumables and equipment necessary to make biologic drugs.
Danaher Corporation (NYSE:DHR) also stated that a little over $100 million of revenue has shifted into next year, primarily from the second and third quarters. This suggests that customer demand has been delayed rather than cancelled, potentially supporting future revenue growth.
Intuitive Surgical (NASDAQ:ISRG), by contrast, continues to benefit from the strength of a business model that has consistently generated growth regardless of broader industry cycles. Intuitive Surgical's (NASDAQ:ISRG) business model remains one of its biggest competitive advantages. Approximately 85% of total revenue came from recurring sources during the quarter, providing investors with significant revenue visibility as the installed base continues to grow.
#danaher #surgical
Danaher Corporation (NYSE:DHR) and Intuitive Surgical (NASDAQ:ISRG) illustrate that contrast perfectly. Danaher (NYSE:DHR) is beginning to benefit from improving life sciences spending after several challenging years, whereas Intuitive Surgical (NASDAQ:ISRG) continues to expand one of the healthcare industry's strongest recurring revenue businesses through robotic surgery. Both companies reported encouraging results, but the question for investors is whether a cyclical recovery or a structural growth story offers the better long-term opportunity.
The strongest argument supporting Danaher is that its recovery appears to be broadening. Its Life Sciences business delivered its strongest performance in several years, and although bioprocessing revenue was affected by customer project timings, the underlying order trends remained strong, with bioprocessing orders growing mid-teens in the quarter. This shows that the underlying demand for bioprocessing remained solid, including consumables and equipment necessary to make biologic drugs.
Danaher Corporation (NYSE:DHR) also stated that a little over $100 million of revenue has shifted into next year, primarily from the second and third quarters. This suggests that customer demand has been delayed rather than cancelled, potentially supporting future revenue growth.
Intuitive Surgical (NASDAQ:ISRG), by contrast, continues to benefit from the strength of a business model that has consistently generated growth regardless of broader industry cycles. Intuitive Surgical's (NASDAQ:ISRG) business model remains one of its biggest competitive advantages. Approximately 85% of total revenue came from recurring sources during the quarter, providing investors with significant revenue visibility as the installed base continues to grow.
#danaher #surgical
1 month ago
Premium healthcare stocks often trade at elevated valuations for very different reasons. Thermo Fisher's (NYSE:TMO) investment case increasingly depends on whether the life sciences industry is emerging from its post-pandemic slowdown, while Intuitive Surgical (NASDAQ:ISRG) continues to hold a dominant position in robotic surgery through factors such as its highly recurring revenue model. Both companies delivered encouraging quarters, but the market is asking different questions of each.
The key issue for investors in this scenario is which premium valuation is better supported by long-term fundamentals.
Thermo Fisher's (NYSE:TMO) investment case increasingly depends on whether life sciences spending is finally emerging from its post-pandemic slowdown. Thermo Fisher Scientific Inc.'s (NYSE:TMO) quarter suggests that the recovery in life sciences spending is becoming increasingly broad-based. Management highlighted improving customer activity across pharmaceutical and biotechnology markets, while multiple operating segments returned to healthy growth. That broadening recovery is particularly important because earlier signs of improvement had been concentrated in bioprocessing, and stronger demand across multiple businesses suggests the recovery is becoming more durable.
Thermo Fisher Scientific Inc.'s (NYSE:TMO) Life Sciences Solutions segment reinforced the recovery narrative. Reported revenue climbed 13% year over year, while organic revenue rose 3%, led by continued strength in the high-margin bioproduction business. Healthy demand in this segment suggests pharmaceutical and biotechnology customers continue investing in biologic drug manufacturing, supporting management's view that end-market conditions are improving.
Perhaps the biggest positive from the quarter was the recovery in **** ytical Instruments, a business that had faced weak demand for nearly two years as biotechnology funding slowed. Its return to growth provides another indication that laboratory spending is beginning to normalize.
#suggests
The key issue for investors in this scenario is which premium valuation is better supported by long-term fundamentals.
Thermo Fisher's (NYSE:TMO) investment case increasingly depends on whether life sciences spending is finally emerging from its post-pandemic slowdown. Thermo Fisher Scientific Inc.'s (NYSE:TMO) quarter suggests that the recovery in life sciences spending is becoming increasingly broad-based. Management highlighted improving customer activity across pharmaceutical and biotechnology markets, while multiple operating segments returned to healthy growth. That broadening recovery is particularly important because earlier signs of improvement had been concentrated in bioprocessing, and stronger demand across multiple businesses suggests the recovery is becoming more durable.
Thermo Fisher Scientific Inc.'s (NYSE:TMO) Life Sciences Solutions segment reinforced the recovery narrative. Reported revenue climbed 13% year over year, while organic revenue rose 3%, led by continued strength in the high-margin bioproduction business. Healthy demand in this segment suggests pharmaceutical and biotechnology customers continue investing in biologic drug manufacturing, supporting management's view that end-market conditions are improving.
Perhaps the biggest positive from the quarter was the recovery in **** ytical Instruments, a business that had faced weak demand for nearly two years as biotechnology funding slowed. Its return to growth provides another indication that laboratory spending is beginning to normalize.
#suggests
1 month ago
Chargers left tackle Rashawn Slater returned to the practice field on Saturday.
Slater missed the entire 2025 season after suffering a torn patellar tendon during last summer's training camp. While he was initially cleared, a little flare-up in his surgically repaired left knee on August 4 forced the team to exercise caution.
After sitting out eight consecutive practices and missing the preseason matchup against the 49ers, Slater finally made his way back to action in a limited capacity. He participated in individual drills and the opening period of 11-on-11 team reps before moving aside to finish his day under the supervision of trainers.
Though Slater's workload is being heavily managed, there is plenty of reason for optimism regarding his return. Slater previously stated that his knee feels "strong and stable," adding that he appreciates the organization's "smart and thoughtful" approach to his long-term health.
Head coach Jim Harbaugh has indicated that he hopes to play his healthy starters for two full drives in the upcoming preseason game against the Rams on Thursday. Whether the coaching staff fields Slater or keeps him for the Week 1 opener against the Cardinals, his return signals that the offensive anchor is right on track.
#saturday
Slater missed the entire 2025 season after suffering a torn patellar tendon during last summer's training camp. While he was initially cleared, a little flare-up in his surgically repaired left knee on August 4 forced the team to exercise caution.
After sitting out eight consecutive practices and missing the preseason matchup against the 49ers, Slater finally made his way back to action in a limited capacity. He participated in individual drills and the opening period of 11-on-11 team reps before moving aside to finish his day under the supervision of trainers.
Though Slater's workload is being heavily managed, there is plenty of reason for optimism regarding his return. Slater previously stated that his knee feels "strong and stable," adding that he appreciates the organization's "smart and thoughtful" approach to his long-term health.
Head coach Jim Harbaugh has indicated that he hopes to play his healthy starters for two full drives in the upcoming preseason game against the Rams on Thursday. Whether the coaching staff fields Slater or keeps him for the Week 1 opener against the Cardinals, his return signals that the offensive anchor is right on track.
#saturday


