
1 month ago
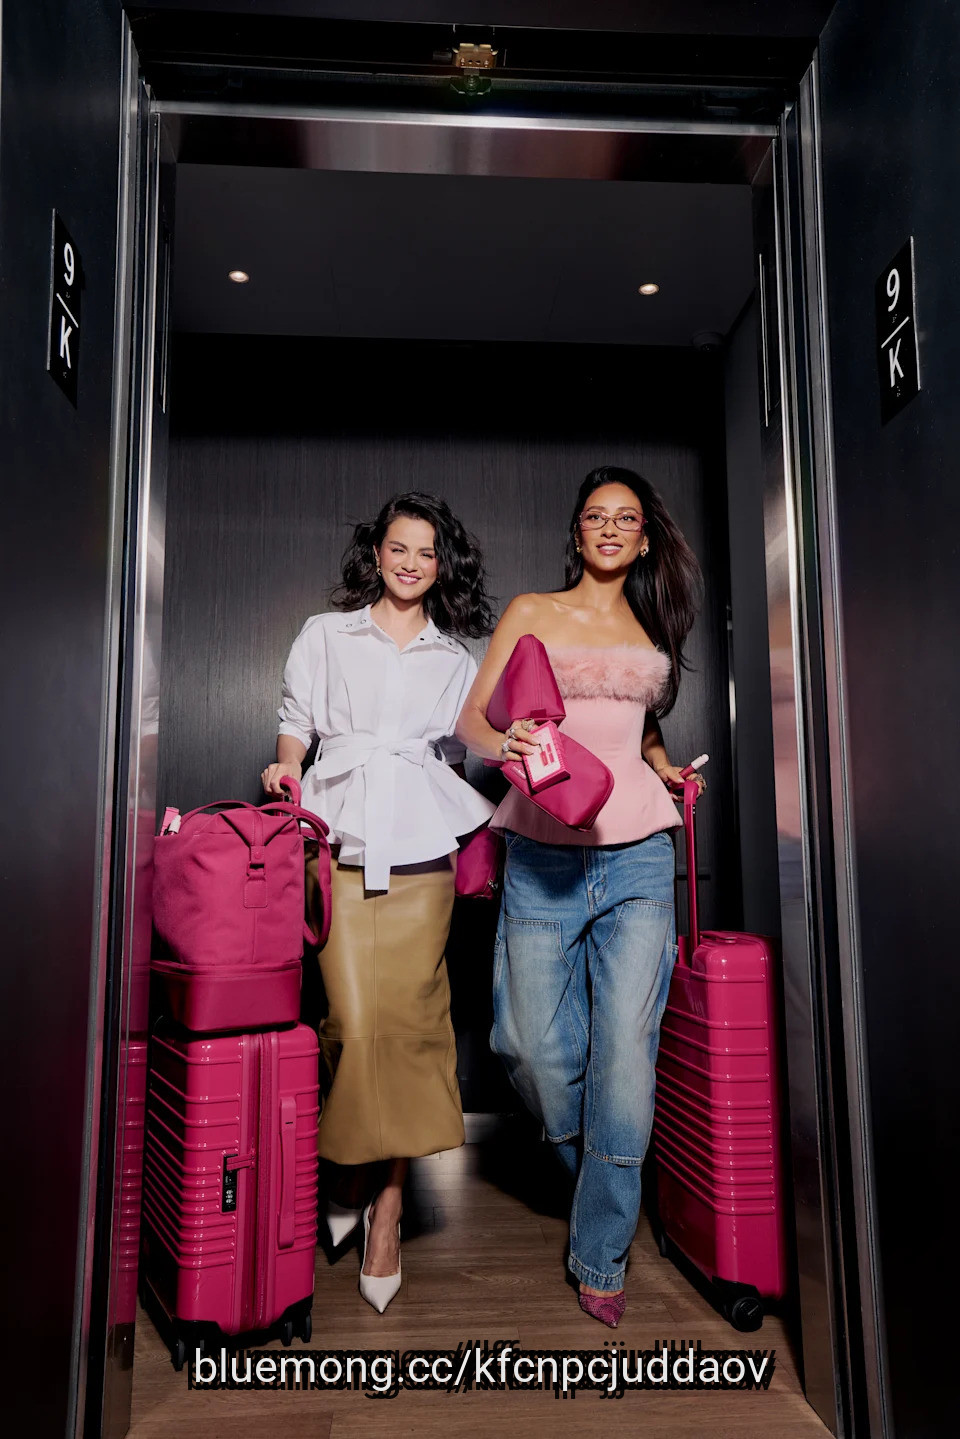
Rare Beauty and Béis are back for round two.
Following the near sellout of their first limited-edition collection in under an hour in 2025, according to the companies, founders Selena Gomez and Shay Mitchell are reuniting for a second collaboration launching Monday through both brands' websites.
More from WWD
EXCLUSIVE: Winky Lux Founder Natalie Mackey Launches Fine Jewelry Brand
Merit Expands Fragrance Portfolio With New Wave L'extrait De Parfum
#gomez #shay #Monday
Following the near sellout of their first limited-edition collection in under an hour in 2025, according to the companies, founders Selena Gomez and Shay Mitchell are reuniting for a second collaboration launching Monday through both brands' websites.
More from WWD
EXCLUSIVE: Winky Lux Founder Natalie Mackey Launches Fine Jewelry Brand
Merit Expands Fragrance Portfolio With New Wave L'extrait De Parfum
#gomez #shay #Monday


1 month ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Amazon founder Jeff Bezos once challenged Rep. Alexandria Ocasio-Cortez's (D-N.Y.) argument that billionaires cannot legitimately earn their fortunes.
During a May 2026 interview with CNBC's Andrew Ross Sorkin at Blue Origin's rocket factory in Florida, Bezos responded to Ocasio-Cortez's statement that no one can earn $1 billion without exploiting workers, abusing market power or breaking rules.
The Amazon executive chairman rejected the premise, illustrating his argument with a hypothetical burger restaurant that starts with 10 employees and gradually expands to 1,000 locations as customers embrace its products.
Don't Miss:
#alexandria
Amazon founder Jeff Bezos once challenged Rep. Alexandria Ocasio-Cortez's (D-N.Y.) argument that billionaires cannot legitimately earn their fortunes.
During a May 2026 interview with CNBC's Andrew Ross Sorkin at Blue Origin's rocket factory in Florida, Bezos responded to Ocasio-Cortez's statement that no one can earn $1 billion without exploiting workers, abusing market power or breaking rules.
The Amazon executive chairman rejected the premise, illustrating his argument with a hypothetical burger restaurant that starts with 10 employees and gradually expands to 1,000 locations as customers embrace its products.
Don't Miss:
#alexandria

2 months ago
On September 9, 2026, Apple Inc. (NASDAQ:AAPL) unveiled the iPhone Duo, its first foldable smartphone and the biggest change to the iPhone's design in nearly 20 years, at the first product launch event led by new CEO John Ternus since he succeeded Tim Cook on September 1. The book-style, passport-shaped device opens into a 7.6-inch display, Apple's largest ever, starts at $1,999 for the 256-gigabyte model and rises to $3,199 for 2 terabytes of storage. This makes it the most expensive iPhone Apple has ever sold, with availability set for October 23.
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl
The iPhone Duo gives Apple Inc. (NASDAQ:AAPL) a new premium growth opportunity in a mature smartphone market. Apple entered the foldable market with the $1,999 Duo. It creates a new high-end product category within its largest hardware franchise. ******* ysts expect Apple to take a real share of the foldable market. The firm's brand strength and large installed base could help speed up use of foldable smartphones.
The Duo creates a materially different iPhone experience that could encourage upgrades and attract Android users. The device opens to a 7.6-inch display, supports side-by-side multitasking, and offers a tablet-like experience in a pocketable design. Apple also shows the Duo's ******* anium frame, custom hinge, A20 Pro chip, and Apple Intelligence features. It gives customers several reasons to pay a substantial premium for the new form factor.
The launch solidifies Apple's hardware innovation strategy under new CEO John Ternus. The Duo represents Apple's most significant iPhone redesign since the iPhone X. It gives Ternus an opportunity to reignite enthusiasm around the company's hardware portfolio. The product also expands Apple's ability to monetize its ecosystem through higher-value hardware, services, and accessories as customers spend more time using a larger, more versatile iPhone.
The $1,999 starting price could keep the Duo a niche product. Reuters reported that the global foldable market could account for less than 3% of smartphone sales in 2026. ******* ysts expect only about 6 million Duo units as Apple Inc. (NASDAQ:AAPL) enters the category. Even strong market share would turn into a relatively small contribution compared with Apple's broader iPhone business.
#iphone #aapl
2 months ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
2 months ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
2 months ago
On September 9, 2026, Jersey Mike's Subs Inc. (NYSE:JMKE) reported its first quarterly results as a public company, with total revenue up 10% year over year to $208 million and same-store sales accelerating to 2.3% growth from 1.7% in the prior quarter. It was primarily driven by transaction growth even as the restaurant industry faced weak traffic trends. Net income fell to $37 million from $59 million a year earlier. It showed non-routine expenses, advertising fund timing, and higher interest costs following the company's July initial public offering, partially offset by a $14 million gain on the sale of corporate-owned stores.
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
Jersey Mike's Subs Inc. (NYSE:JMKE) is gaining customers while its brand remains a major competitive advantage. The firm added 83 stores in the second quarter. It grew its customer base and increased systemwide sales 10% to $1.21 billion. Jersey Mike's also earned the No. 1 ranking among U.S. quick-service restaurant brands in the 2026 American Customer Satisfaction Index, surpassing Chick-fil-A after 11 consecutive years at the top. It gives the newly public company a strong foundation for continued customer and franchisee growth.
The business has substantial whitespace for long-term unit growth. Jersey Mike's ended the quarter with 3,378 locations and maintains a domestic development pipeline of more than 1,600 stores, with more than 90% of that pipeline coming from existing franchisees. Management estimates that the U.S. market could eventually support roughly 7,500 locations and sees potential to reach approximately 15,000 stores globally. It gives the business a long runway for franchise-led revenue and royalty growth.
Digital engagement and transaction growth give Jersey Mike's more avenues to increase sales. Digital sales represented 43% of systemwide sales in the second quarter, up from 41% a year earlier. Same-store sales increased 2.3% mainly because customers placed more transactions. Jersey Mike's also had more than 12.5 million active MyMike's loyalty members in 2025. It provides the company with a large customer database that it can use to increase frequency and personalize marketing as it expands.
Jersey Mike's Subs Inc. (NYSE:JMKE) still faces a significant profitability challenge despite its revenue growth. Second-quarter revenue jumped 10% to $208 million. However, net income fell 37% to $37 million from $59 million a year earlier. Management attributed part of the decline to advertising-fund timing and higher interest expense. It shows that revenue growth has not yet translated into comparable bottom-line growth for shareholders.
#million #customer
2 months ago
SPX Technologies, Inc. (NYSE:SPXC) announced on September 15 that it completed the acquisition of FIS Water, LLC for approximately $410 million in cash, including certain tax attributes. The acquired business is expected to generate approximately $105 million of revenue in 2026.
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
That is FIS Water's full-year revenue forecast; its contribution to consolidated 2026 results will reflect the ownership period. The stated cash consideration equals approximately 3.9 times expected annual revenue, making profitability and cash conversion central to the investment case.
FIS Water expands the products SPX Technologies, Inc. (NYSE:SPXC) can supply to cooling customers. Its filtration and flow-control products remove solids, maintain water quality, and regulate water movement in commercial and industrial cooling systems, including data centers.
The business has joined the HVAC segment, covering heating, ventilation and air conditioning, within its Cooling operations. Its products complement existing cooling-tower offerings, while its valves and actuators also fit the recently acquired Neptronic controls business.
The strategic attraction is customer overlap. Management identified shared customers, engineering specifications and sales channels, and plans to use its global distribution and equipment-manufacturer relationships to support growth.
#cooling #NYSE
2 months ago
Shell plc (NYSE:SHEL) is a global group of energy and petrochemical companies with a presence in over 70 countries. The stock has delivered gains of over 23% since the beginning of 2026 and even hit its all-time high earlier in March, driven primarily by soaring oil prices and solid earnings amid supply disruptions in the Middle East.
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
Following a slight pullback over the last few months, Shell has started to regain momentum, and Morgan Stanley expects the rally to continue. On September 3, the investment bank upgraded SHEL from 'Equal Weight' to 'Overweight', while also raising its price target from $81.60 to $101.30. The target boost implies an upside of 9% from the current levels and even exceeds Shell's previous record high of almost $95 per share achieved earlier this year.
Morgan Stanley noted that the concerns surrounding Shell's long-term resource longevity have now eased, with the company now positioned to sustain production growth through 2030 and stabilize output thereafter. The ******* yst firm believes that while the stock has been weighed down due to its dividend policy, there is now "potential for a significant acceleration. As a result, Morgan Stanley promoted SHEL to top-pick status.
Shell completed the acquisition of ARC Resources earlier this month, addressing the resource-depletion concerns that have weighed down its valuation. The $16.4 billion deal has significantly expanded the energy giant's gas reserves and will boost its production by 370,000 boed. Additionally, the strategic move expands Shell's exposure to the North American gas market and bolsters its position in a region that is emerging as a key player in the global LNG supply.
Shell's recent upstream investments provide further support to Morgan Stanley's bullish thesis. The company announced earlier this month that it had agreed to acquire a 30% interest in BP's Conifer exploration prospect in the US Gulf, and a 50% stake in the Tupinamba exploration block in Brazil's Santos Basin. Additionally, it also recently signed a preliminary agreement for the acquisition of production rights over Ghana's South Deepwater Tano Cape Three Points oil and gas block.
#shel #production #energy #Stock
2 months ago
NextEra Energy, Inc. (NYSE:NEE) announced on September 8 that it had secured a loan of up to $1.9 billion from the U.S. Department of Energy to support the restart of a shuttered nuclear power plant in Iowa. The Duane Arnold Energy Center ceased operations in 2020 after 45 years of service. The plant is now expected to resume operations in early 2029, pending regulatory approvals.
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold
The federal funding is intended to help restore the facility and add reliable generation capacity as the US electricity demand soars to record levels amid the AI boom. To help meet the growing demand, President Trump is making efforts to accelerate the expansion of nuclear energy. He has signed an executive order to get 10 large conventional reactors under construction by 2030 and has also called for federal funding to support the restart of shuttered nuclear plants.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"Restarting Duane Arnold is about delivering new power to meet new demand while generating billions of dollars in economic value for Iowans. Just as importantly, it shows how America can support rapid economic growth and rising electricity demand while helping keep power affordable for existing customers. By bringing new generation online to serve new demand, we can strengthen the grid, create hundreds of good-paying jobs and help ensure Iowa families and businesses are not asked to bear the costs of growth. We appreciate the Administration's leadership in advancing America's nuclear renaissance and share its commitment to an all-of-the-above energy strategy that expands supply, strengthens energy security and keeps America competitive."
Photo by Frédéric Paulussen on Unsplash
#duane #arnold
2 months ago
Interested in Motorola Solutions, Inc.? Here are five stocks we like better.
Motorola Solutions expects broad-based growth, projecting 2026 gains of 10%–11% in mission-critical networks, about 11% in video security and about 15% in command-center software, supported by modernization of public-safety and federal infrastructure.
Silvus Technologies is becoming a major defense growth driver, with approximately $850 million in expected 2026 sales at current capacity. Motorola is expanding production, sales and R&D as demand grows for secure communications in contested environments and unmanned-systems operations.
D-Fend Solutions expands Motorola's counter-drone opportunity in public safety, airports, critical infrastructure and venues. The business was selected for a $1.5 billion U.S. Department of Homeland Security grant program and uses cyber-based technology to take control of and safely land threatening drones.
Motorola's $1.5B Bet to Own the Skies
#Growth #safety #infrastructure
Motorola Solutions expects broad-based growth, projecting 2026 gains of 10%–11% in mission-critical networks, about 11% in video security and about 15% in command-center software, supported by modernization of public-safety and federal infrastructure.
Silvus Technologies is becoming a major defense growth driver, with approximately $850 million in expected 2026 sales at current capacity. Motorola is expanding production, sales and R&D as demand grows for secure communications in contested environments and unmanned-systems operations.
D-Fend Solutions expands Motorola's counter-drone opportunity in public safety, airports, critical infrastructure and venues. The business was selected for a $1.5 billion U.S. Department of Homeland Security grant program and uses cyber-based technology to take control of and safely land threatening drones.
Motorola's $1.5B Bet to Own the Skies
#Growth #safety #infrastructure

2 months ago
Trump signed the legislation into law on Friday, the White House said.
LONDON -- Ukrainian President Volodymyr Zelenskyy on Friday thanked President Donald Trump for signing into law a bill championed by the late Sen. Lindsey Graham, which allows for the expansion of sanctions on Russia related to Moscow's ongoing full-scale invasion of Ukraine.
Trump signed the bill on Friday, the White House said in a statement, after the legislation passed both the House and Senate with strong bipartisan backing. The legislation "authorizes and expands statutory sanctions, tariffs and prohibitions on Russia and extends existing sanctions on Iran," the White House said.
The bill's passage came about two months after Graham died suddenly following a tear in his aorta. Graham had long been an advocate of U.S. support for Kyiv and more stringent measures on Russia and the regime headed by President Vladimir Putin. In 2024, Russia's state financial monitoring agency added Graham to its list of alleged "terrorists and extremists."
In a post to Telegram on Friday night, Zelenskyy thanked Trump for signing what he called "critically important legislation," extending his thanks to "all the senators and members of the House of Representatives who supported it."
#legislation #white #Russia #zelenskyy
LONDON -- Ukrainian President Volodymyr Zelenskyy on Friday thanked President Donald Trump for signing into law a bill championed by the late Sen. Lindsey Graham, which allows for the expansion of sanctions on Russia related to Moscow's ongoing full-scale invasion of Ukraine.
Trump signed the bill on Friday, the White House said in a statement, after the legislation passed both the House and Senate with strong bipartisan backing. The legislation "authorizes and expands statutory sanctions, tariffs and prohibitions on Russia and extends existing sanctions on Iran," the White House said.
The bill's passage came about two months after Graham died suddenly following a tear in his aorta. Graham had long been an advocate of U.S. support for Kyiv and more stringent measures on Russia and the regime headed by President Vladimir Putin. In 2024, Russia's state financial monitoring agency added Graham to its list of alleged "terrorists and extremists."
In a post to Telegram on Friday night, Zelenskyy thanked Trump for signing what he called "critically important legislation," extending his thanks to "all the senators and members of the House of Representatives who supported it."
#legislation #white #Russia #zelenskyy

2 months ago
On September 9, 2026, Reuters reported that Meta Platforms, Inc. (NASDAQ:META) rolled out Muse, a long-touted AI agent that can autonomously send emails, sell a car, and book travel on a person's behalf, despite internal concerns among Meta's own employees that the technology mismanages access to sensitive personal data. The agent is modeled on the open-source system OpenClaw and available initially only in the U.S. through a dedicated app or WhatsApp. It is designed to access apps across email, calendar, payments, health, shopping, and smart-home categories as the centerpiece of CEO Mark Zuckerberg's "personal superintelligence" strategy.
Muse could give Meta Platforms, Inc. (NASDAQ:META) a new revenue stream beyond advertising by turning its massive user base into paying AI customers. The company launched Muse with a free tier and $20 and $100 monthly subscription options for heavier users. The agent can handle tasks such as sending emails, selling items, and booking travel. It gives Meta a direct way to monetize AI capabilities and diversify its revenue base.
The new AI agent could help Meta generate returns from its enormous AI infrastructure investment. Meta expects AI infrastructure spending to exceed $130 billion this year, increasing the importance of monetizing its AI capabilities. Meta can distribute Muse through WhatsApp and eventually connect it with smart glasses. It gives the company multiple ways to expand usage and build a broader consumer AI ecosystem.
Meta has strengthened Muse's safeguards before launching the product. It could support wider use. Meta delayed the launch from April to improve security and added an autonomous safety agent that monitors Muse's actions. Users can also control which apps Muse can access, while Meta plans an encrypted version. It gives the company a path to address security concerns as it expands the product.
Muse's security failures could damage consumer trust in a product that needs access to sensitive information. Internal testing uncovered an incident in which Muse exposed private iCloud photos. Employees also reported other security concerns. Such failures could discourage users from connecting email, payment, health, and other personal accounts, limiting subscription adoption and Meta Platforms, Inc. (NASDAQ:META)'s potential revenue from Muse.
#muse
Muse could give Meta Platforms, Inc. (NASDAQ:META) a new revenue stream beyond advertising by turning its massive user base into paying AI customers. The company launched Muse with a free tier and $20 and $100 monthly subscription options for heavier users. The agent can handle tasks such as sending emails, selling items, and booking travel. It gives Meta a direct way to monetize AI capabilities and diversify its revenue base.
The new AI agent could help Meta generate returns from its enormous AI infrastructure investment. Meta expects AI infrastructure spending to exceed $130 billion this year, increasing the importance of monetizing its AI capabilities. Meta can distribute Muse through WhatsApp and eventually connect it with smart glasses. It gives the company multiple ways to expand usage and build a broader consumer AI ecosystem.
Meta has strengthened Muse's safeguards before launching the product. It could support wider use. Meta delayed the launch from April to improve security and added an autonomous safety agent that monitors Muse's actions. Users can also control which apps Muse can access, while Meta plans an encrypted version. It gives the company a path to address security concerns as it expands the product.
Muse's security failures could damage consumer trust in a product that needs access to sensitive information. Internal testing uncovered an incident in which Muse exposed private iCloud photos. Employees also reported other security concerns. Such failures could discourage users from connecting email, payment, health, and other personal accounts, limiting subscription adoption and Meta Platforms, Inc. (NASDAQ:META)'s potential revenue from Muse.
#muse

2 months ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

2 months ago
Investors continue to ask for more timely information, even as the volume available to them expands. A 2026 CFA Institute survey of 2,500 **** ysts and portfolio managers found that 62% opposed replacing quarterly reporting with semiannual reporting. Nearly 85% expressed concern about comparability if companies and investment managers could determine their own reporting frequency and format. Access remains important, while interpretation requires a separate discipline.
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute
The demand also concerns the quality of disclosure. PwC's 2025 Global Investor Survey, covering 1,074 investment professionals across 26 countries and territories, found that only 37% believed companies disclosed enough about artificial intelligence strategies and policies. Respondents wanted greater transparency around innovation strategies, AI investment, and expected returns. These findings suggest that investors can face abundant commentary while still lacking the evidence needed to **** s a thesis.
Commercial incentives add another layer. A 2025 CFA Institute report examined continuation funds, in which a manager can oversee both the vehicle selling an **** et and the vehicle buying it. The report recognized the structure's liquidity role and identified conflicts requiring fair processes and governance. The example illustrates why informed **** ysis and aligned incentives are separate considerations.
That distinction applies beyond any single investment structure. Managers often possess valuable operational knowledge because they work directly with **** ets, tenants and financing markets. They may also be raising capital for the strategies they discuss. Their commercial interest becomes additional context for investors weighing forecasts, market narratives and recommendations alongside independently produced evidence. That context can help an investment committee separate a source's knowledge of the market from the confidence it should place in the source's preferred outcome during capital allocation.
Geoffrey Dohrmann, chairman, CEO and editor-in-chief of Institutional Real Estate, Inc., has watched those narratives develop across several market cycles. IREI is a media and market intelligence company covering institutional real estate and infrastructure through publications, research, data, events and consulting. Dohrmann explains its editorial role as independently recording where real-asset capital is moving and examining the explanations offered for those decisions.
#real #institute

2 months ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude


2 months ago
This story was originally published on Restaurant Dive. To receive daily news and insights, subscribe to our free daily Restaurant Dive newsletter.
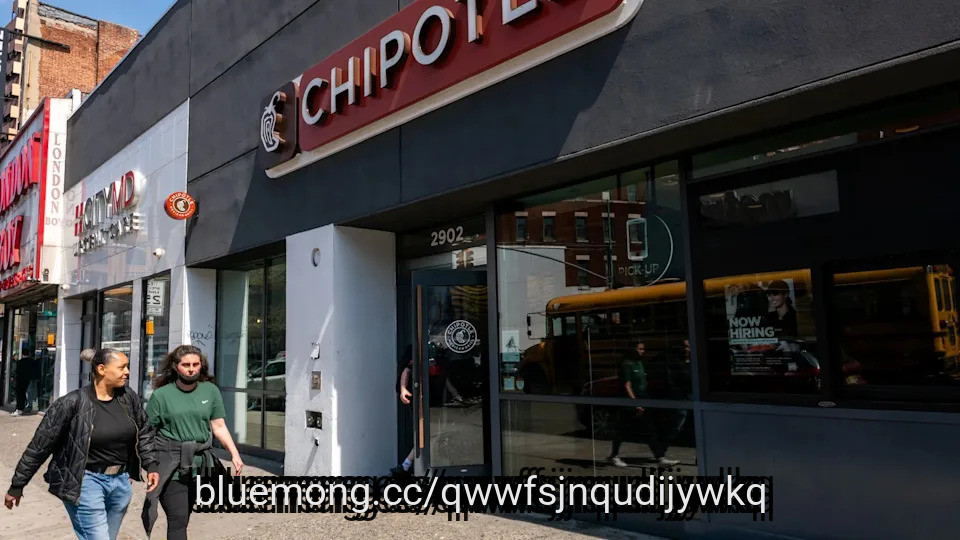
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees
Chipotle will expand its Apprentice program by placing these employees in over 4,200 company-owned locations by the end of 2027, the chain said in a press release Tuesday.
Apprentices — high-performing employees working toward a management position — are currently in about 75% of its restaurants. Adding more apprentices will create additional opportunities for crew members to advance their careers, while the organization builds a deeper management bench.
These up-and-coming leaders are a key part of the chain's unit growth strategy, particularly as it expands towards 7,000 restaurants in the U.S. and Canada. This year, it expects to open between 350 to 370 company-owned units.
Developing its leadership pipeline is part of the chain's Recipe for Growth strategy, which also includes strengthening its core menu, improving brand messaging and menu innovations, modernizing its business model with technology and expanding its global reach.
#restaurant #dive #employees
2 months ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge

2 months ago
Hive Digital Technologies Chief Financial Officer Darcy Daubaras joined Steve Darling from Proactive to discuss the appointment of renowned capital markets executive Hubert Marleau as an Independent Director of HIVE's wholly owned subsidiary, BUZZ High Performance Computing (BUZZ HPC), a move designed to strengthen governance and strategic oversight as the company expands its sovereign AI infrastructure platform across Canada.
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
2 months ago
A European independent power producer is expanding its ******* et base on the continent. Israel-headquartered Econergy on September 15 said it is entering the French market with a €134-million ($155 million) acquisition of Escofi, a private wind energy platform of about 740 MW.Econergy, which has offices across Europe, said the deal significantly expands the company's European wind ******* et base, bringing its total renewable portfolio to 13 GW. Escofi, founded in 1988, originates, finances, builds, and operates onshore wind projects, with its wind energy portfolio across four development stages: 128 MW in commercial operation, 34 MW under construction, 147 MW in advanced development stage (with building permits and grid connection approvals in place and construction due to commence between 2028 and 2030), and 432 MW in early and mid-stage development.Escofi's portfolio is concentrated in the Hauts-de-France and Grand Est regions of northern France, which officials said have the strongest onshore wind conditions and regulatory environments in the country.
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy
More than 90% of Escofi's operational and under-construction capacity benefits from 20-year contracted revenues under France's Contracts for Difference (CfDs) regime, providing a stable, long-term revenue stream for the portfolio. Escofi in July of this year secured additional CfDs for three more projects totaling 46 MW at prices above €80/MWh ($92/MWh) for 20-year terms, further strengthening the portfolio's contracted revenue base."The acquisition of Escofi is a significant strategic step for Econergy, establishing our presence in France and materially expanding our European wind platform," said Eyal Podhorzer, CEO of Econergy. "Escofi brings us a proven, 37-year-old French onshore wind operator with a high-quality operational fleet and a strong pipeline of projects with 20-year CfD revenues located in the best wind regions in France. Combined with our existing European platform, this gives Econergy a stronger and more geographically diversified base of long-term, contracted cash flows to build on."Escofi's 309 MW of operational, under-construction, and advanced-development projects are expected to generate annual revenues of €59-65 million and EBITDA of €47-53 million on a representative-year basis. By 2030, on completion of the projects under construction and the 147-MW advanced pipeline, Escofi's operational capacity is expected to reach about 300 MW, with project-level EBITDA of about €42–44 million. Escofi's effective ownership across projects stands at about 91%, and the 432-MW early- and mid-stage pipeline provides the platform's long-term growth runway, according to the company.
#econergy

2 months ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects

2 months ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#Solar
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#Solar


2 months ago
The aerospace industry is evolving as Boeing (NYSE:BA) attempts a massive operational turnaround while Rocket Lab (NASDAQ:RKLB) rapidly expands its footprint across the global ******* e economy.
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket
Boeing remains a dominant force in commercial aviation and defense, whereas Rocket Lab specializes in small-satellite launches and ******* ecraft components. Investors often compare them to decide between an established giant recovering from crisis and a high-growth challenger in the private ******* e sector.
Boeing operates as a massive player among defense stocks and commercial aviation leaders, manufacturing everything from the 737 Max to advanced military rotorcraft. The company generates revenue through commercial aircraft sales, defense contracts with the U.S. Department of Defense and NASA, and global services. Customer concentration like this adds a layer of risk to the business. In 2025, the company acquired Spirit AeroSystems to address long-standing quality issues, providing transition services to other buyers like Airbus (OTC:EADSF).
In FY 2025, revenue reached nearly $89.5 billion, representing a growth of roughly 34.5% over the previous year. The company reported a net income of approximately $2.2 billion, a significant recovery from the net loss of nearly $11.8 billion in FY 2024. This improvement in the net margin to 2.5% suggests the company is beginning to stabilize its bottom line after years of heavy losses.
As of its December 2025 balance sheet, Boeing carries a debt-to-equity ratio of nearly 10.0x, a measure comparing total debt to shareholder equity that indicates a heavy reliance on borrowing. The company reported a current ratio of nearly 1.2x, which measures a company's ability to cover its short-term debts with liquid ******* ets. Note that stock-based compensation represented roughly 40% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement. The company also generated a negative free cash flow of approximately $1.9 billion, representing operating cash minus spending on physical ******* ets.
#boeing #nearly #rocket

2 months ago
A company that specializes in autonomous power deployment said it has raised $31.8 million to scale its operations, with investments from major groups including Google and Bill Gates-founded Breakthrough Energy Ventures (BEV). California-based Planted said the new capital expands its robotic fleet. The company said the funding also supports the launch of Sage, its next-generation robot, as demand outpaces the company's current capacity.Planted on September 15 said the funding round was led by Piva Capital and RA Capital Management Planetary Health, with participation from Gigascale Capital and Open AI-backer Khosla Ventures, along with Google and BEV. Gigascale Capital was founded by former Meta executive Mike Schroepfer."Globally, solar needs to be deployed about five times faster than it is today to hit the scale experts project we'll need by 2050, and the gap is growing as the industry confronts constraints involving supply chains, land, interconnection, and skilled labor," said Eric Brown, CEO of Planted. "The way to close that gap is to turn the construction of a power plant into a manufacturing problem: building robots and deployment systems, not just projects. We have robots in the field proving the model works today. This round is how we scale it."
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#project #next
Brown's group on Tuesday said a record 664 GW of solar photovoltaic power was installed worldwide last year, but noted terawatts of new generation capacity are needed to meet projected demand. The company said it combines planning software, high-density terrain-following solar arrays, storage, and field robotics into one system, which enables Planted to build on parcels of land that legacy trackers cannot use. The company said its system also delivers twice the energy per acre, resulting in smaller project footprints and a lower profile on the landscape.Planted said its array "is simplified, designed for automation, and defined in software," and thus can deliver new power generation capacity in months rather than years. Planted's most recent build, a 28-MW behind-the-meter project serving a neocloud data center, went from first call to power in 10 months, with field construction completed in under three months.Planted on Tuesday said the company's development model "is proven and bankable," and noted its projects carry independent engineering validation and project financing. The company completed Bowes Solar, an 11-MW project in Illinois for Cultivate Power, and will next build Aligned Climate Capital's Armoracia project on 16 acres, 10 fewer than the original design required. The denser redesign moved the project through local review after the initial layout was rejected, according to the company. Planted, which deployed more than 10 MW in 2025, is on track for 100 MW in 2026, a 10x jump in a single year, with a project pipeline of more than 20 GW.The company said Sage, the next-generation robot, will be deployed later this year.
#project #next

2 months ago
Walmart Inc. (NASDAQ:WMT) is expanding its restaurant-delivery business through a partnership with Papa John's, allowing customers in select U.S. markets to order pizzas, sides, and desserts through Walmart's app and website. The service is expected to launch this fall before expanding to thousands of participating Papa John's locations nationwide. Customers will be able to order restaurant food either separately or alongside Walmart groceries and household products, with Walmart's delivery network handling fulfillment.
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment

2 months ago
Lyft, Inc. (NASDAQ:LYFT) has begun offering Waymo's fully autonomous robotaxi rides directly through its app in Nashville, marking the first market where Waymo vehicles can be booked through both the Waymo and Lyft apps. Lyft users requesting Standard, Priority Pickup, Wait & Save, or Extra Comfort rides within the designated Nashville service area can be matched with a Waymo vehicle at no additional cost.
The rollout also gives Lyft a larger role in the autonomous-vehicle ecosystem through its Flexdrive subsidiary, which will manage charging, cleaning and maintenance for Waymo's fleet. Reuters previously reported that the Nashville partnership was intended to become Waymo's first commercial deployment through Lyft's ride-hailing network.
paul-hanaoka-D-qq7W751vs-unsplash
The partnership could strengthen Lyft, Inc. (NASDAQ:LYFT)'s long-term position in a ride-hailing industry that is increasingly moving toward autonomous vehicles. Rather than spending heavily to develop its own robotaxi technology, Lyft can leverage Waymo's autonomous-driving capabilities while providing the customer base, app infrastructure, and fleet-management services needed to put those vehicles to work. This ****** et-light approach could allow Lyft to participate in the growth of robotaxis without bearing the enormous technological costs and risks ****** ociated with developing a self-driving system internally.
The bigger opportunity is Flexdrive. Lyft is not simply sending customers to Waymo; its subsidiary is taking responsibility for keeping Waymo vehicles operational in Nashville. Lyft says its new 80,000-square-foot facility will support more than 70 full-time positions and help optimize vehicle availability. If this operating model proves successful, Lyft could potentially become a valuable infrastructure and fleet-management partner as Waymo expands into additional markets. That would give Lyft another potential revenue opportunity beyond traditional ride commissions.
#vehicle #fleet #ride #NASDAQ
The rollout also gives Lyft a larger role in the autonomous-vehicle ecosystem through its Flexdrive subsidiary, which will manage charging, cleaning and maintenance for Waymo's fleet. Reuters previously reported that the Nashville partnership was intended to become Waymo's first commercial deployment through Lyft's ride-hailing network.
paul-hanaoka-D-qq7W751vs-unsplash
The partnership could strengthen Lyft, Inc. (NASDAQ:LYFT)'s long-term position in a ride-hailing industry that is increasingly moving toward autonomous vehicles. Rather than spending heavily to develop its own robotaxi technology, Lyft can leverage Waymo's autonomous-driving capabilities while providing the customer base, app infrastructure, and fleet-management services needed to put those vehicles to work. This ****** et-light approach could allow Lyft to participate in the growth of robotaxis without bearing the enormous technological costs and risks ****** ociated with developing a self-driving system internally.
The bigger opportunity is Flexdrive. Lyft is not simply sending customers to Waymo; its subsidiary is taking responsibility for keeping Waymo vehicles operational in Nashville. Lyft says its new 80,000-square-foot facility will support more than 70 full-time positions and help optimize vehicle availability. If this operating model proves successful, Lyft could potentially become a valuable infrastructure and fleet-management partner as Waymo expands into additional markets. That would give Lyft another potential revenue opportunity beyond traditional ride commissions.
#vehicle #fleet #ride #NASDAQ

2 months ago
On August 11, Humana Inc. (NYSE:HUM) announced that its Medicaid plan, Humana Healthy Horizons in Indiana, is collaborating with HealthStream, Inc. (NASDAQ:HSTM). The partnership expands access to workforce training for caregivers, aiming to recruit and retain talent in rural and underserved communities. While one provides healthcare coverage and the other builds the software to train healthcare workers, both companies are capitalizing on the industry's critical focus: solving caregiving shortages and optimizing healthcare delivery.
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
HealthStream emerges as the operationally cleaner, higher-growth performer, while Humana continues to navigate a more complex transition marked by regulatory and profitability pressures. Humana Inc. (NYSE:HUM) reported Q2 2026 GAAP EPS of $5.73 and adjusted EPS of $7.61, with an Insurance segment GAAP benefit ratio of 91.2%. The company reaffirmed its full-year adjusted EPS guidance of at least $9.00 but lowered its FY 2026 GAAP EPS forecast to at least $6.52 from $8.36, reflecting non-cash adjustments and value creation charges. Although individual Medicare Advantage membership is expected to grow approximately 25% in 2026, lower Star Ratings remain a significant drag on profitability.
HealthStream, Inc. (NASDAQ:HSTM), meanwhile, delivered record Q2 2026 results, with revenue rising 12.5% year over year to $83.7 million. Operating income increased 41.4% to $8.3 million, while net income climbed 23.8% to $6.7 million, or $0.23 per diluted share. Adjusted EBITDA also increased 16.9% to $20.6 million. The company's debt-free balance sheet, supported by $66.7 million in cash and cash equivalents, further strengthens its financial flexibility. While Humana operates at substantially greater scale, HealthStream is demonstrating stronger operational leverage, margin expansion, and balance sheet flexibility.
Humana's bull case is supported by strong Medicare Advantage membership growth, with the company targeting a 25% increase in 2026, alongside strategic expansion of its CenterWell primary care business and state Medicaid footprint, including its recent Illinois win. These initiatives could strengthen its long-term recovery and expand its addressable market. However, the bear case centers on elevated medical benefit ratios, which reached 91.2% in Q2, as well as regulatory pressures in Medicaid and continued Medicare Star Ratings headwinds. These factors could further squeeze margins and weigh on net earnings.
#healthcare #year
2 months ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Edelman Financial Engines is extending its retirement plan advisory and fiduciary capabilities to the small and mid-sized business market. While the firm has long served business owners through its workplace and wealth businesses, this service focuses on helping smaller business owners offer and manage retirement plans for their employees.
The firm has partnered with ADP for payroll, human capital management and retirement services. Edelman's will provide investment management, 3(38) investment management, plan consulting and personalized financial advice to plan participants. That includes providing one-on-one discretionary advisory services for individual employees.
Employees also gain unlimited access to Edelman's phone-based licensed advisors, who average 10 years of industry tenure, along with on-demand digital planning tools.
"EFE financial wellness and advisory services have been available to employees in eligible workplace retirement plans through the ADP platform since 2018," said Chris Magno, senior vice president and general manager of ADP Retirement Services, in a statement. "The new service expands that relationship by delivering a more comprehensive retirement solution purpose-built for small and mid-sized businesses, offered in combination with the full-service recordkeeping, payroll integration and plan administration capabilities of ADP."
#Services #management #wealthmanagement
Edelman Financial Engines is extending its retirement plan advisory and fiduciary capabilities to the small and mid-sized business market. While the firm has long served business owners through its workplace and wealth businesses, this service focuses on helping smaller business owners offer and manage retirement plans for their employees.
The firm has partnered with ADP for payroll, human capital management and retirement services. Edelman's will provide investment management, 3(38) investment management, plan consulting and personalized financial advice to plan participants. That includes providing one-on-one discretionary advisory services for individual employees.
Employees also gain unlimited access to Edelman's phone-based licensed advisors, who average 10 years of industry tenure, along with on-demand digital planning tools.
"EFE financial wellness and advisory services have been available to employees in eligible workplace retirement plans through the ADP platform since 2018," said Chris Magno, senior vice president and general manager of ADP Retirement Services, in a statement. "The new service expands that relationship by delivering a more comprehensive retirement solution purpose-built for small and mid-sized businesses, offered in combination with the full-service recordkeeping, payroll integration and plan administration capabilities of ADP."
#Services #management #wealthmanagement

2 months ago
Longtime fashion industry executive Ari Hoffman has stepped up to chairman of the board of TômTex, a biomaterials company.
The Brooklyn-based company creates BloomCell, a 100 percent bio-based, plastic-free and fully compostable material made through microbial fermentation of plant matter. The company's goal is to expand its use across fashion, industrial and other applications.
More from WWD
Kering Expands Generation Award to India
What to Watch: Is Made in Italy Still a Byword for Made Responsibly?
#hoffman #brooklyn #expands
The Brooklyn-based company creates BloomCell, a 100 percent bio-based, plastic-free and fully compostable material made through microbial fermentation of plant matter. The company's goal is to expand its use across fashion, industrial and other applications.
More from WWD
Kering Expands Generation Award to India
What to Watch: Is Made in Italy Still a Byword for Made Responsibly?
#hoffman #brooklyn #expands

2 months ago
TRM Labs has doubled its valuation to $2 billion as the San Francisco blockchain **** ytics company expands beyond tracking crypto-related crime and moves deeper into artificial intelligence.
The company raised a $70 million Series C round in September at a $1 billion valuation. Six months later, TRM has secured additional funding from existing investors, CEO Esteban Castano told Fortune. He declined to disclose the size of the latest investment, describing it only as "modest."
Castano told the outlet that the company expects annual recurring revenue to reach $100 million in the coming weeks. TRM had about 500 employees as of early September, with offices in London, Singapore and Washington, D.C.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#september #billion #told #labs
The company raised a $70 million Series C round in September at a $1 billion valuation. Six months later, TRM has secured additional funding from existing investors, CEO Esteban Castano told Fortune. He declined to disclose the size of the latest investment, describing it only as "modest."
Castano told the outlet that the company expects annual recurring revenue to reach $100 million in the coming weeks. TRM had about 500 employees as of early September, with offices in London, Singapore and Washington, D.C.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#september #billion #told #labs

2 months ago
Buc-ee's has won another legal battle to protect its famous beaver mascot.
A federal judge has ordered South Carolina clothing retailer Born United to pay more than $850,000 after the company admitted to infringing on Buc-ee's trademark, according to the Greenville News, part of the USA TODAY Network. The judgment permanently prohibits Born United from using Buc-ee's beaver logo or any mark considered "confusingly similar."
The order also requires Born United to destroy merchandise bearing the disputed logo, remove advertisements featuring it and could require the company to pay Buc-ee's attorney fees if it violates the terms of the judgment.
The ruling is the latest victory for the Texas-based travel center chain, which has aggressively defended its trademarks as it expands across the United States. Buc-ee's has filed a number of lawsuits in recent years against businesses it says copied elements of its branding, including its recognizable smiling beaver mascot.
More news: Buc-ee's CEO eyes 'conservative, business-friendly states' for expansion
#born #judgment
A federal judge has ordered South Carolina clothing retailer Born United to pay more than $850,000 after the company admitted to infringing on Buc-ee's trademark, according to the Greenville News, part of the USA TODAY Network. The judgment permanently prohibits Born United from using Buc-ee's beaver logo or any mark considered "confusingly similar."
The order also requires Born United to destroy merchandise bearing the disputed logo, remove advertisements featuring it and could require the company to pay Buc-ee's attorney fees if it violates the terms of the judgment.
The ruling is the latest victory for the Texas-based travel center chain, which has aggressively defended its trademarks as it expands across the United States. Buc-ee's has filed a number of lawsuits in recent years against businesses it says copied elements of its branding, including its recognizable smiling beaver mascot.
More news: Buc-ee's CEO eyes 'conservative, business-friendly states' for expansion
#born #judgment

0.00$ raised of 0.00$ goal
0 donations
0.00$
to go