9 days ago
For a subset of young workers, the name of the game is to squirrel away enough savings and investments so retirement can come early, substituting strategic personal finance for a lifetime of labor. (FIRE!)
It turns out that the post-pandemic boom and explosion of stock prices has already gifted many older Americans with a version of that lifestyle, according to Bank of America — and it's affecting the economy.
Labor force participation — which measures the share of people employed or seeking work among the total population — never recovered after the shock of the pandemic.
According to BofA's economics team, led by Aditya Bhave, the biggest driver behind the decline in overall labor force participation has been workers over age 55 leaving the workforce.
"This debunks a popular bearish narrative on the labor market: 'the u-rate would have been higher if participation hadn't fallen,'" Bhave wrote.
#according #workers #FIRE #americans


9 days ago
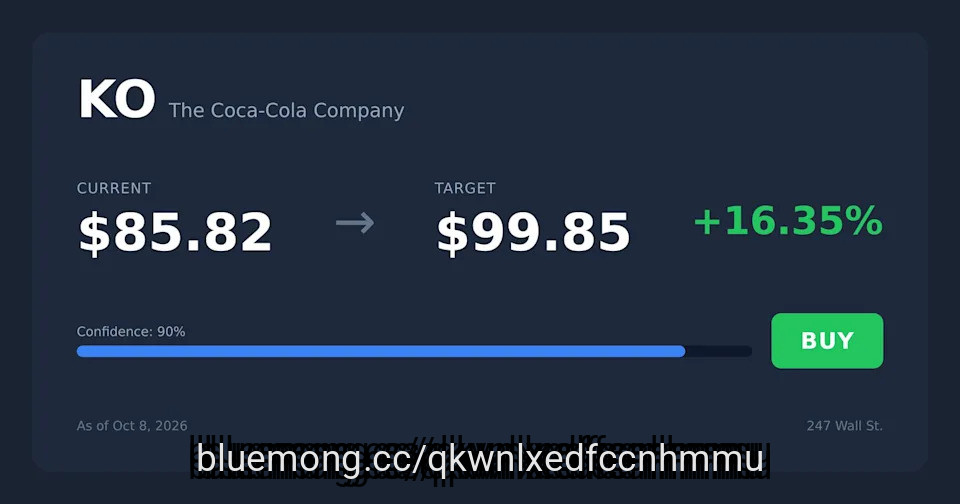
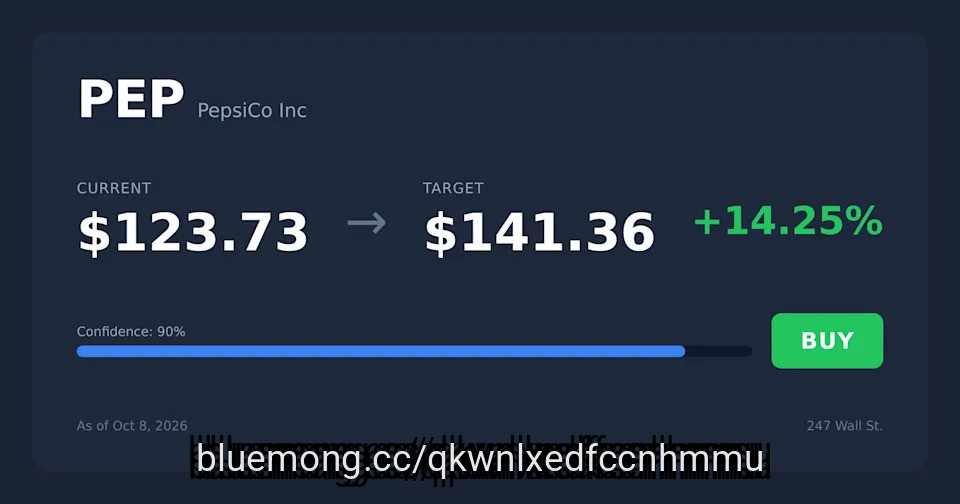
Coca-Cola ($KO) beats PepsiCo ($PEP) for generational portfolios with 63 consecutive dividend increases, wider margins, and 182% 10-year share gains versus 60%.
PepsiCo's free cash flow barely covers its 4.44% dividend yield, while Coca-Cola's expected $12.4B free cash flow dwarfs its $8.8B dividend payout.
A pending IRS appeals ruling and a premium P/E of 28 are the two risks that could crack Coca-Cola's otherwise dominant long-term case.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Coca-Cola didn't make the cut. Enter your email to see the names that beat KO. The report is free. Enter your email and see if any of your stocks made the cut.
Coca-Cola (NYSE:KO) or PepsiCo (NASDAQ:PEP): Which one better suits someone investing for retirement right now, knowing the shares may pass to the next generation? Looked at over several decades, Coca-Cola wins. PepsiCo pays the bigger yield today. Coca-Cola has the safer dividend, the stronger brand economics and fewer structural cracks.
#stocks


10 days ago
Rich Americans are getting richer, but not all equally. The K-shaped split that let high earners pull away from low earners now cuts through the top 1% too, with the ultra-rich far ahead of the rest.
The average household in the top 0.1% is now worth about $204 million, or 7.7 times as much as one in the rest of the top 1%, according to a Fortune ******* ysis of Federal Reserve data. That ratio is the highest in the Fed's quarterly series going back to 1989, up from 6.2 times at the end of 2019. Currently, the Fed counts 136,779 households in the top 0.1%
The top 0.1%'s wealth has more than doubled since the end of 2019, from $13.4 trillion to nearly $28 trillion in the second quarter of 2026. Over the same period, the rest of the top 1% saw its wealth grow 68%, from $19.3 trillion to $32.5 trillion. The top 0.1% now holds 15% of the nation's household wealth, up 0.5 percentage point since the first quarter.
"We are talking about continued redistribution upward and further concentration of wealth at the top," Markus Schneider, an ******* ociate professor of economics at the University of Denver, told Fortune.
The clearest difference between the two groups is what they own.
#earners

11 days ago
American Tower Corporation (NYSE:AMT) traded at around $165 on October 6, within five dollars of its 52-week low of $160.06.
The company keeps 45.41% of revenue as operating profit on a portfolio of communications towers leased to wireless carriers. A business that profitable sitting at a 52-week low is usually a disagreement about the future rather than the present.
READ ALSO: What is eBay's (EBAY) Economic Moat, and is it Widening or Narrowing?
A tower is difficult to replicate for reasons that have nothing to do with engineering. Local authorities restrict where new structures can go, so an existing site near a highway or a dense suburb cannot simply be copied next door.
The economics follow from that scarcity. The first tenant on a tower covers the construction and the ground lease, and each additional tenant is close to pure margin. Gross margin of 73.77% is what that layering produces, and the 45.41% operating margin is what survives after the overheads.
#NYSE

11 days ago
The US trade deficit jumped to more than $100 billion in August as importers wrestled with a new round of President Trump's tariffs and continued to bring in billions of dollars' worth of components for AI data centers.
The total gap: $105.6 billion, a 13.8% increase from July's revised $92.8 billion deficit, the highest level since early 2025, when importers stocked up ahead of Trump's "Liberation Day" and a later four-month surge in imports that pushed average monthly trade deficits north of $120 billion.
Imports rose in August by 4.3%, compared with a 1.4% increase in exports. The US brought in $420.8 billion in total imports in August against $315.2 billion in exports.
In an **** ysis, Capital Economics said the "sharp rise in imports suggests third quarter GDP growth will be well below our current forecast of 4.0%," suggesting that the final annualized figure could be closer to 2.5%."
"The relatively broad-based rise in goods imports mean net trade was still a drag overall," the group added.
#billion #imports #total #increase
27 days ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
27 days ago
On September 8, 2026, Reuters reported that ASML Holding N.V. (NASDAQ:ASML) plans to work with major customers. It includes Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), Nvidia, Intel, Samsung, and SK Hynix to adapt its next-generation "High NA" extreme ultraviolet lithography tools so they can print larger data-center chips. It addresses a current limitation where the newer machines use a smaller mask than ASML's widely deployed standard EUV tools.
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next

27 days ago
Forgent Power Solutions, Inc. (NYSE:FPS) reported fiscal fourth-quarter revenue of approximately $462 million on September 15, up 94% year over year. Bookings reached $1.503 billion, increasing 375%, while backlog stood at $3.0 billion as of June 30, 2026.
The reported 3.3 times book-to-bill ratio compares quarterly bookings with quarterly revenue. Bookings and backlog are operating measures of order activity and outstanding contractual work, respectively. Neither represents cash collected, and backlog does not guarantee the timing of future revenue.
Forgent Power Solutions, Inc. (NYSE:FPS) expects fiscal 2027 revenue of $2.4 billion to $2.6 billion, implying 76% growth at the midpoint. The question is whether factories, employees, and working capital can support that expansion while preserving cash generation.
Forgent Power Solutions, Inc. (NYSE:FPS) already has evidence of stronger production economics. Fourth-quarter operating income reached $91.9 million, compared with $8.3 million a year earlier. Operating cash flow was $74 million, exceeding the quarter's $31 million of capital expenditures.
Those results suggest that rising output is beginning to cover the costs of expansion. Management attributed stronger profitability partly to revenue growing faster than operating costs as new campuses approached target production levels.
#operating #power #solutions #NYSE
27 days ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
27 days ago
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies
27 days ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel

29 days ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply
29 days ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain

29 days ago
Realty Income Corporation (NYSE:O) announced on September 14 a European property venture in which capital accounts advised by KKR & Co. Inc. (NYSE:KKR) intend to invest €528 million for a 49% interest. Closing is expected September 30, subject to customary conditions.
Realty Income Corporation (NYSE:O) would receive approximately €528 million in gross proceeds while retaining 51% ownership and day-to-day ******* et management. The contributed portfolio carries a 5.9% effective initial capitalization rate after recurring management fees. The question is whether redeploying the capital and earning fees can more than offset the rental economics transferred to the partner.
The venture could provide another funding source for acquisitions. Selling a minority interest in existing properties can release capital while preserving operational continuity. It also gives management an alternative when public equity or debt financing offers less attractive terms.
Management fees add a second source of income alongside retained property earnings. Realty Income Corporation (NYSE:O) could use its existing European operating platform to manage the venture, potentially spreading overhead across a broader pool of investor capital. The benefit depends on fee revenue exceeding the incremental costs of providing those services.
The structure includes a further source of potential upside. Realty Income Corporation (NYSE:O) would have an option to redeem the partner's interest after year 10 and through year 17. The redemption price would provide a capped internal rate of return, an annualized return accounting for cash-flow timing, expected at 6.3% to 6.5% and finalized at closing.
#NYSE #corporation #management #source

29 days ago
Alcoa Corporation (NYSE:AA) priced $2.6 billion of acquisition financing on September 9, 2026, through two wholly owned subsidiaries. Alumina Pty Ltd will issue $1.5 billion of 6.625% notes due 2034, while Alcoa Nederland Holding B.V. will issue $1.1 billion of 6.875% notes due 2036. Alcoa Corporation (NYSE:AA) and certain subsidiaries will guarantee the notes on a senior unsecured basis.
The tranches imply annual coupons of $99.375 million and $75.625 million, respectively, totaling exactly $175 million. Settlement is expected on September 23. Net proceeds and cash on hand would fund the approximately $3.1 billion cash portion of the South32 Limited (ASX:S32) ****** et acquisition, plus related fees and expenses.
For Alcoa Corporation (NYSE:AA), successful settlement would secure longer-dated funding and allow termination of the remaining 364-day bridge commitments. Maturities in 2034 and 2036 give management time to integrate the ****** ets before principal comes due.
The operating opportunity lies in linking additional bauxite resources, alumina refining and aluminum production. Better coordination could strengthen feedstock security and improve purchasing, logistics and plant economics. Acquired earnings and operating improvements could produce recurring cash to service the debt while funding reinvestment.
Fixed coupons also make the interest burden predictable. Strong ****** et performance could support debt reduction and give shareholders a growing share of incremental cash generation.
#notes #september

29 days ago
Cognyte Software Ltd. (NASDAQ:CGNT) reported on September 9 that revenue for the fiscal second quarter ended July 31, 2026, increased 12.0% to $109.2 million. Total software revenue, comprising software and software services, rose 20.9% to $100.8 million.
Company-defined non-GAAP adjusted EBITDA increased 35.7% to $14.9 million. The measure adds depreciation, amortization, stock-based compensation, restructuring costs, and other specified adjustments to GAAP operating income. Yet quarterly billings fell to $76.3 million from $93.0 million. The central question is whether a more profitable revenue mix can produce stronger cash generation while sustaining future growth.
The portfolio transition is visible in the revenue base. Total software revenue represented more than 92% of sales. Recurring revenue, primarily support contracts and subscription offerings, reached $56.2 million, or 51.4% of total revenue.
For Cognyte Software Ltd. (NASDAQ:CGNT), a larger recurring base could make revenue more predictable and support continued product investment. Renewals also create opportunities to expand customer relationships without rebuilding the sales pipeline from scratch. The benefit depends on retention and expansion within those accounts.
Profitability improved under both accounting measures. GAAP operating margin increased to 4.3% from 2.8%, while adjusted EBITDA margin expanded to 13.6% from 11.3%. That combination strengthens the case that the transition is improving operating economics, even after recognizing expenses excluded from adjusted results.
#gaap #NASDAQ


29 days ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

30 days ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved group-adjusted EBITDA break-even just 15 months post-acquisition by applying Mytheresa's 'secret sauce'—focusing on top-tier customers, full-price selling, and rigorous cost discipline—to the distressed YNAP business.
Mytheresa reached a EUR 1 billion milestone in FY 2026, outperforming the industry through superior customer economics where top customers (4.8% of base) generated 48.4% of total GMV.
NET-A-PORTER and MR PORTER reached a strategic inflection point, returning to top-line growth and positive adjusted EBITDA in Q4 by pivoting from promotional discounting to editorial-led luxury discovery.
YOOX's turnaround is being driven by a deliberate retreat from high-cost overseas markets to focus on a 'healthy core' in Europe, resulting in losses being cut nearly in half compared to the prior year.
#porter #customers #cost #reached
30 days ago
Andy Burnham has warned of a "challenging" Budget as the Iran war drives up oil and gas prices.
The Prime Minister said he would do what he could to ease the cost of living after the Middle East conflict pushed price rises to a five-month high.
Mr Burnham branded the latest up-tick in inflation a "concern", as official figures showed the headline rate rose from 2.9pc in July to 3.1pc in August. However, he insisted that Britain's economy had shown "resilience across the board".
His warning of a difficult Budget in October will raise fears of tax rises as the fallout from the Iran war continues to weaken the public finances and erode the Government's fiscal headroom.
Oxford Economics has warned that the Chancellor will need to find £11bn if he wants to maintain the same wiggle room on the Treasury's books.
#warned #rises



1 month ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill **** et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#fcnca #market
1 month ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created ****** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#june
1 month ago
Broyhill ******* et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ******* et Management highlighted First Citizens BancShares, Inc. (NASDAQ:FCNCA). First Citizens BancShares, Inc. (NASDAQ:FCNCA) operates as the holding company for First-Citizens Bank & Trust Company, providing retail and commercial banking services. On September 14, 2026, First Citizens BancShares, Inc. (NASDAQ:FCNCA) closed at $2,173.88 per share. Over the past month, First Citizens BancShares, Inc. (NASDAQ:FCNCA) declined 1.03%, but its shares are up 17.10% over the past year. First Citizens BancShares, Inc. (NASDAQ:FCNCA) has a market capitalization of $24.55 billion, and its stock has traded within a 52-week range of $1,623.76 to $2,296.30.
Broyhill ******* et Management stated the following regarding First Citizens BancShares, Inc. (NASDAQ:FCNCA) in its Q2 2026 investor letter:
"First Citizens BancShares, Inc. (NASDAQ:FCNCA), initiated in June, is a well-run company which we believe to be undervalued and with catalysts on the horizon. The company has retired almost 20% of its Class A shares since July 2024, and inside its roughly $25 billion market capitalization sits a rail leasing fleet of approximately 128,000 cars valued by the market at bank multiples. Management has proven themselves highly competent and highly aligned with shareholders, with the Holding family in key executive positions, owning over 20% of the economics and controlling roughly half the vote through their Class B shares. Much of what we are waiting on has a date attached to it: two separations have completed, and Masco and First Citizens are retiring shares at a pace that improves per-share value whether or not the multiples change."
#first #fcnca

1 month ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Revenue growth of 60% year-over-year was driven by a combination of competitive share gains, market expansion, and a higher mix of in-network patients.
Management attributes the 11th consecutive quarter of gross margin expansion to attractive unit economics and volume leverage inherent in the rental business model.
The 'integrated care model' is cited as a key differentiator, where therapeutic protection is paired with responsive support services to convert clinical insights into urgent patient care.
Strategic territory management, including splitting high-volume 'platinum' territories and adding clinical specialists, is compounding growth by deepening penetration in existing accounts.
#Growth #tell

1 month ago
Our **** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Launched ReefIQ in June as a proprietary substrate layer designed to convert unstructured biological data into structured representations for pharmaceutical AI models.
Transitioned the commercial strategy from discrete fee-for-service projects to broader platform partnerships where MindWalk participates in the long-term economics of created **** ets.
Achieved a significant infrastructure milestone by validating OpenFold3 on AMD Instinct MI325X GPUs, enhancing discovery scale and ReefIQ's biological context layer.
Leveraged a deep wet-lab discovery franchise, including relationships with 19 of the top 20 global pharma companies, as a primary distribution channel for new AI platform adoption.
#reefiq

1 month ago
By Lucia Mutikani
WASHINGTON, Sept 16 (Reuters) - U.S. retail sales rebounded sharply in August as households boosted purchases of a range of goods while also spending more at restaurants and bars, reinforcing the economy's resilience even as consumers grow more anxious about high inflation.
The stronger-than-expected report from the Commerce Department on Wednesday prompted economists to upgrade their gross domestic product growth estimates for the third quarter. Together with other data on Wednesday showing a surge in import prices last month, strong demand sealed the argument for a widely anticipated interest rate increase from the Federal Reserve later in the day, economists said.
The reports followed data this month showing producer and consumer prices accelerated in August, while the labor market regained its poise after wobbling through much of summer.
"This reaffirms that the economy is more than capable of handling higher interest rates, providing the Fed plenty of scope to hike to get inflation under control," said Bradley Saunders, North America economist at Capital Economics.
#economists #data #month
1 month ago
NVIDIA Corporation (NASDAQ:NVDA) has an argument against rapid hardware obsolescence: older accelerators still command rental prices. For CoreWeave, Inc. (NASDAQ:CRWV), which sells access to computing infrastructure, the harder question is how much of that rent becomes a return.
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return
1 month ago
Walmart Inc. (NASDAQ:WMT) is expanding its restaurant-delivery business through a partnership with Papa John's, allowing customers in select U.S. markets to order pizzas, sides, and desserts through Walmart's app and website. The service is expected to launch this fall before expanding to thousands of participating Papa John's locations nationwide. Customers will be able to order restaurant food either separately or alongside Walmart groceries and household products, with Walmart's delivery network handling fulfillment.
The move builds on Walmart's broader push into fast delivery. The company recently reported that U.S. e-commerce sales increased 24% in its latest quarter, while fast-delivery services for groceries and general merchandise grew 48%. Walmart also said 30-minute-or-less delivery was available in 38 U.S. markets, highlighting the infrastructure it can potentially leverage for restaurant orders.
The Papa John's partnership could strengthen Walmart Inc. (NASDAQ:WMT)'s position as a broader consumer-delivery platform rather than simply a retailer. Adding restaurant meals gives shoppers another reason to open Walmart's app, while the ability to combine a pizza order with groceries and household products creates an opportunity to increase basket sizes and order frequency. This is particularly attractive because Walmart already has a large store network that increasingly functions as a last-mile fulfillment system; roughly 80% of its e-commerce orders are fulfilled from stores.
The deal could also improve the economics of Walmart's existing delivery infrastructure. Instead of building a completely separate restaurant-delivery network, Walmart can utilize its established fulfillment capabilities and Spark driver network to serve incremental demand. The Papa John's relationship also expands Walmart's restaurant offering beyond earlier partnerships, helping the company build a more comprehensive alternative to dedicated delivery platforms such as DoorDash and Uber Eats.
More importantly, restaurant delivery could become another engagement tool for Walmart Inc. (NASDAQ:WMT)'s increasingly digital customer base. With e-commerce approaching a quarter of Walmart's overall sales and growing substantially faster than traditional store sales, initiatives that increase digital traffic could support Walmart's broader ecosystem of e-commerce, memberships and advertising.
#walmart #network #fulfillment


1 month ago
Enbridge Inc. (NYSE:ENB) has agreed to buy Blackstone-owned Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its presence in the U.S. liquids pipeline market. The deal includes a 75% stake in the 1,050-mile Pony Express Pipeline, a 51% interest in the Powder River Gateway system, around 8.4 million barrels of storage capacity and crude marketing operations.
Pony Express can move roughly 460,000 barrels of crude per day between the Rockies and the Cushing, Oklahoma, hub. The deal also gives Enbridge greater exposure to major producing regions, including the Bakken, Powder River and Denver-Julesburg basins.
The acquisition gives Enbridge Inc. (NYSE:ENB) a stronger position in U.S. crude transportation at a time when domestic oil production is expected to remain important. Pony Express gives the company a larger presence in the Rockies and complements its existing Express-Platte system.
That combination could allow Enbridge to bring the operations together more efficiently and find synergies across its wider liquids network. The deal also gives Enbridge more than additional pipeline capacity. It adds storage infrastructure and crude marketing operations, giving the company more flexibility in how it manages and optimizes volumes. Bringing these parts of the business together could also improve the economics of the acquired **** ets.
Enbridge Inc. (NYSE:ENB) expects the **** ets to generate significant free cash flow. The company also says the transaction should add to distributable cash flow per share in the first full year after closing. The **** ets also offer relatively predictable infrastructure-style cash flows. This means Enbridge does not need higher crude prices to benefit from the acquisition. The deal fits with the company's broader strategy of growing its fee-based energy infrastructure business across North America, backed by its C$41 billion secured growth backlog.
#enbridge #cash #gives #business
1 month ago
Private equity advisers are racing to leverage AI and automate the services they provide to fund managers and their investors. Law firms, such as Kirkland & Ellis, have been among the most active adopters.
The dominant name in private fund formation and sponsor-backed M&A, the firm rolled out its own AI platform in June, built with Palantir and designed to reshape the repetitive, boilerplate elements of fund formation work, such as drafting limited partnership agreements, closing investor commitments and conducting compliance.
Earlier this year, Kirkland reportedly earmarked $500 million to develop a proprietary AI tool over three to four years, no small sum even for a law firm that generated $10.6 billion in annual revenue last year.
Erica Berthou
Erica Berthou, a partner at Kirkland and a member of the firm's executive committee, recently spoke with PitchBook about how AI could reshape the practice of law—including how it will change the economics of legal work—and how the adoption of AI may affect practitioners, especially the young talent.
#kirkland #private


1 month ago
A fresh reading on inflation showed monthly prices rose more than expected in August, increasing the likelihood the Federal Reserve will raise interest rates next week.
A rebound to oil at $100 per barrel also complicates the picture.
Stripping out volatile food and energy prices — the way the Fed likes to scrutinize underlying inflation — the Consumer Price Index rose 0.3% month over month, compared with expectations for 0.2%. The year-over-year rate was in line with expectations for 2.4% and down a tenth of a percentage point from July. On a headline basis, CPI rose 3.4% in August, in line with expectations, and 0.4% month over month.
"The upside surprise to core CPI in August means the Fed looks set to hike next week," said Stephen Brown, North America chief economist for Capital Economics.
Markets are now betting on a 90% chance of a rate hike at Wednesday's Fed policy meeting, according to CME FedWatch.
#august #expectations #inflation