49 mins. ago
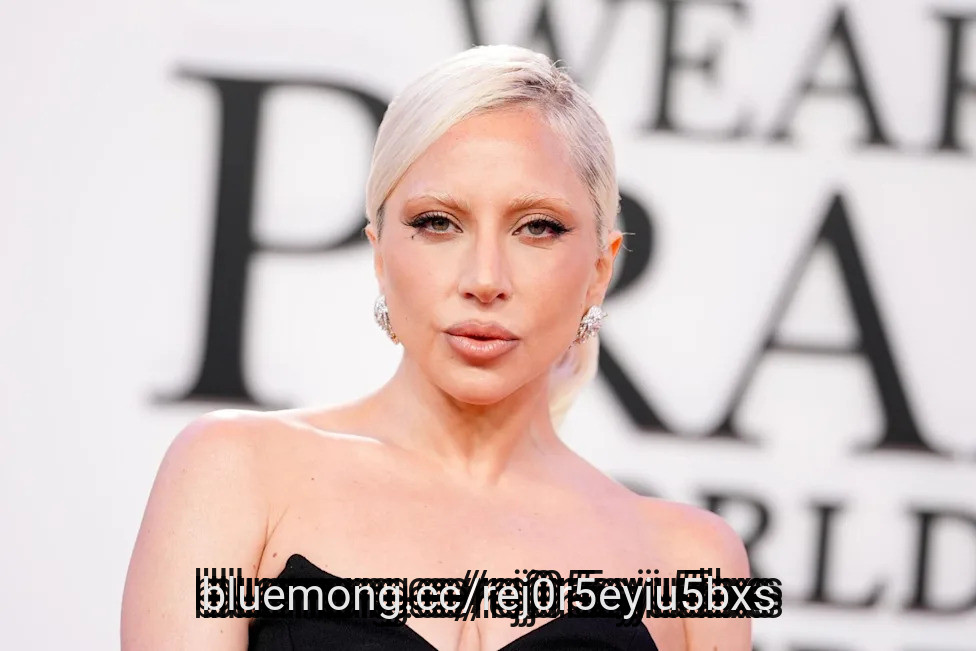
Lady Gaga is addressing the Haus Labs controversy that began after beauty creator Golloria criticized one of the brand's upcoming products earlier this year.
On Thursday (Oct. 1), Gaga shared a statement through Haus Labs' Instagram addressing the situation surrounding the Sun Dipped Bronzing Veil, acknowledging that both the product's original shade range and the way the brand responded to Golloria's criticism fell short.
More from Billboard
Lady Gaga Shouldn't Get $230K 'Consolation Prize' After 'Mayhem' Lawsuit, Surf Brand Tells Judge
Lady Gaga's Baby Girl Has a Very Gaga Name
#haus #labs #thursday #dipped
3 hours ago
On Thursday, Oct. 1, Lady Gaga issued an apology to influencer Golloria after the creator criticized the singer's brand Haus Labs for its new bronzer's lack of shade diversity
"I don't know what or who you guys switched up in that lab, but switch it back," the influencer said in her video from May
In her statement, Gaga admitted the brand made "the wrong decision" and said that the product would "launch soon" with a wider shade range
Lady Gaga is apologizing to influencer Golloria four months after she called out the singer's brand Haus Labs for its new bronzer.
In May, Golloria made a video criticizing the upcoming product Sun Dipped Bronzing Veil, which was initially planed to launch with six shades. The influencer was disappointed upon swatching the three darkest shades on her face, explaining that she generally likes Haus Labs' complexion products. "I don't know what or who you guys switched up in that lab, but switch it back. Thank you," she said.
#golloria #lady #shade #don 't

3 hours ago
Lady Gaga released a statement through her Haus Labs makeup brand, apologizing to beauty influencer Golloria.
Golloria previously made a video calling out one of the line's new products for a non-inclusive shade range, though Haus Labs asked her to remove it as the product was under an embargo.
"I truly apologize to Golloria," Gaga said in the statement, with the brand adding that it paused the launch and added five more inclusive shades following Golloria's "powerful voice."
Lady Gaga has apologized to social media star Golloria following a clash the pop icon's beauty brand Haus Labs had with the beauty influencer over a new product.
Golloria — a longtime supporter of Haus Labs for its typically inclusive shade range suitable for a variety of skin tones — previously shared a video criticizing the brand's upcoming Sun Dipped Bronzing Veil product for launching with only six shades. The influencer later said that Haus Labs reached out and asked for the post to be removed, which Gaga's statement confirmed — "on the technicality that she was under embargo," as the product hadn't yet hit stores.
#product


6 hours ago
For the 57 years Princess Anne has been a working royal, her hair is usually seen swept up into a bouffant, ballerina-like chignon.
The late Queen Elizabeth II's daughter rarely deviates from the sleek and elegant hairstyle, which she has been rocking ever since she was a teenager.
While the infamous beehive has dipped in and out of style through the decades, the Princess Royal has remained its most loyal fan. She even had time to pin it up before leaving the hospital after giving birth to her children, Peter and Zara.
Princess Anne's chignon has become her most-trusted style weapon since the 60s (@ Getty)
"It's like armour," Claudia Harrison (who plays Princess Anne in The Crown) told Marie Claire, who added that Anne's loyalty to her perfectly-executed 'do is parallel with her unmatched work ethic and undisputed reputation as the hardest working royal.
#queen



11 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. ******* an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in ******* an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In ******* an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that ******* an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. ******* an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#earnings #fell
12 days ago
On August 6, Aflac (NYSE:AFL) reported second-quarter numbers that point in opposite directions. Net earnings climbed to $825 million, helped along by investment losses that shrank to $153 million from $421 million a year ago. Adjusted earnings, though, fell 7.7% to $883 million. Both numbers are real, but they answer different questions. Which measure you trust changes the story, so here is what sits underneath.
Start with the yen, because it is muddying the picture. The average rate was 159.45 to the dollar, 9.3% weaker than a year earlier, and that cost adjusted earnings $0.05 a share. Take the currency out of the first half and adjusted earnings per share rose 4.1% to $3.57. **** an is also running more profitably. Its pretax adjusted margin widened to 34.3% from 32.0% as claims took a smaller bite out of premiums, and yen-based pretax adjusted earnings rose 3.4%. So part of the decline in **** an's dollar-reported profit is currency, not operations.
The US business is still growing at the top line. Net earned premiums rose 2.3% to $1.5 billion, and sales climbed 2.6% to $349 million, led by group voluntary benefits along with dental and vision plans. In **** an, the refreshed Tsumitasu life policy and the new Anshin Palette medical product grew strongly in the quarter, and first-half sales rose 7.0% to ¥37.3 billion. Then there is the cash. Aflac returned $1.3 billion to shareholders in the quarter, $983 million of it through buybacks, and declared a $0.61 third-quarter dividend, payable September 1 to holders of record on August 19, 2026. Management notes 43 straight years of dividend increases through 2025 and says the board is on a path to extend that in 2026.
The catch is that **** an's profit gains came from lower claims, not a bigger business. Net earned premiums in yen fell 3.7%, mainly because of a new external reinsurance deal and older limited-pay policies reaching paid-up status. Premium persistency, the share of policies customers keep, slipped to 92.7% from 93.7%. **** an's pretax adjusted earnings still fell 2.1% once currency is stripped out, and new sales dipped 5.6% in the quarter against a tough comparison for the Miraito cancer product, which launched in March 2025.
The US segment has its own soft spot. Pretax adjusted earnings fell 4.6% to $370 million, and the margin narrowed to 20.9% from 22.5% as claims and benefits took a bigger share of premiums. Corporate and Other swung to a $10 million pretax adjusted loss from a $20 million gain a year earlier, with interest expense up 21.6% to $62 million. And adjusted book value per share, excluding foreign currency remeasurement, slid to $41.22 at June 30 from $42.97 a year earlier.
#adjusted #pretax

14 days ago
Bitcoin (BTC) dipped by 3.2% yesterday, following news that a procedural vote on the Clarity Act in the U.S. Senate failed to meet the required threshold.
With 49 votes in favor, 11 less than the minimum established to move the bill to the main floor, the Clarity Act has now been shelved for what remains of the year.
Republicans made a few amendments to the bill in the past few days to entice Democrats, but apparently failed to ease their concerns regarding the ethical provisions they were demanding.
Most other cryptocurrencies experienced strong declines following the news, but seem to be starting to recover this morning.
Truth be told, the market had already priced in that the Clarity Act would not be passed this year. Odds in Polymarket have been collapsing for months, although they recovered to 30% last week ahead of this key vote.
#clarity #following #bill



15 days ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
15 days ago
US stocks mostly rose on Wednesday morning ahead of the Federal Reserve's decision on whether to hike interest rates for the first time in three years.
The Dow Jones Industrial Average (^DJI) dipped below the flat line, while the S&P 500 (^GSPC) rose 0.2%. The Nasdaq Composite (^IXIC) gained 0.4%
Stocks searched for gains after ending Tuesday's session lower. A bond sell-off that has pushed the 10-year yield (^TNX) to its highest level since the financial crisis weighed on stock sentiment.
Crypto prices tumbled, meanwhile, after the Senate failed to pass a key procedural vote for a regulatory framework for digital ****** ets, known as the Clarity Act. Bitcoin's price (BTC-USD) dropped below $76,000.
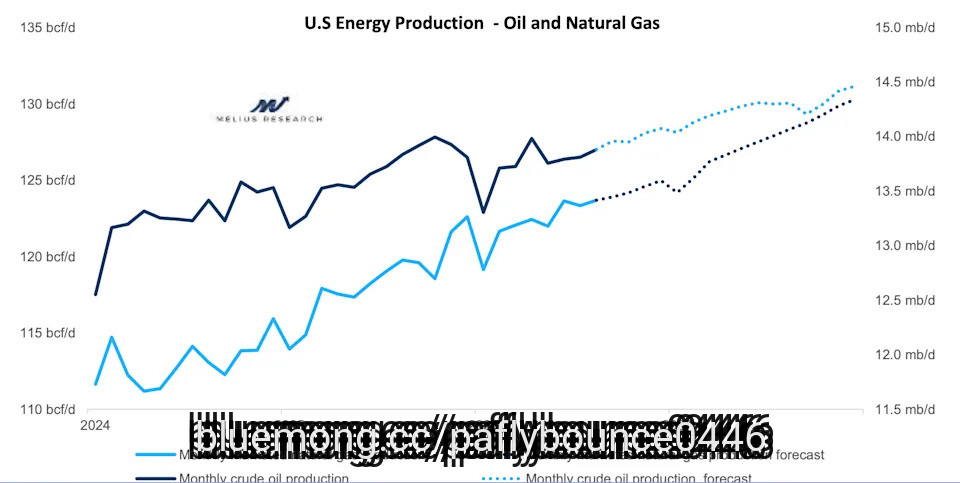
At the same time, rising oil prices have contributed to worries that inflation will remain stubbornly high. Despite a pause in crude oil's rally, benchmark Brent (BZ=F) and WTI (CL=F) futures remain above $100 per barrel.
#stocks #time #below #federal

19 days ago
By Noel Randewich
Sept 11 (Reuters) - Wall Street ended higher on Friday as oil prices retreated and strong consumer price data reinforced expectations the Federal Reserve will raise interest rates next week to fight inflation.
AI server maker Dell soared 12% to a record high. Hewlett Packard Enterprise jumped 12% and HP gained 8.4% after Oracle's quarterly results topped estimates. Oracle dipped 1.8%.
U.S. consumer prices accelerated last month as the cost of gasoline rebounded after two straight monthly declines, adding pressure on the Fed to tighten monetary policy to fight inflation.
Interest rate futures now reflect a nearly 90% probability that the central bank will raise rates at its policy meeting on Wednesday, according to the CME FedWatch tool. That is up from a 72% likelihood on Thursday.
#raise #rates

19 days ago
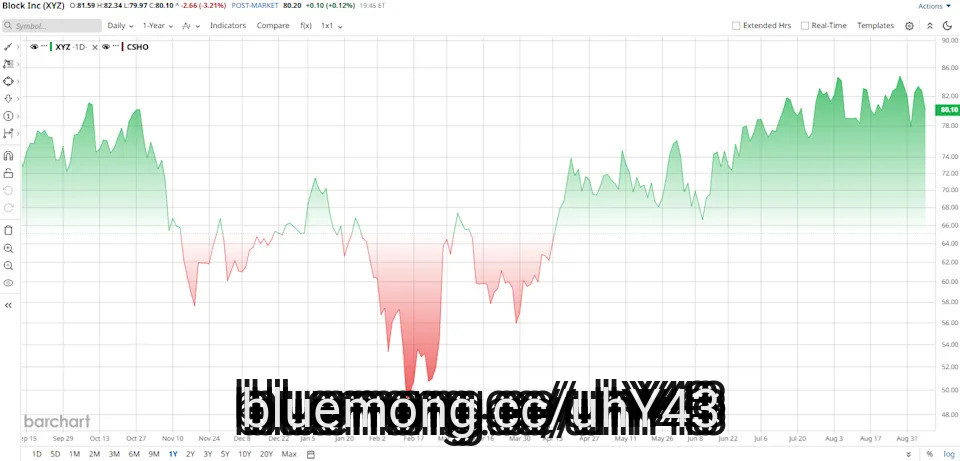
Cathie Wood just sent a fresh signal on Block (XYZ), and the timing is hard to miss.
Ark Invest bought 456,059 shares of Block across three exchange-traded funds (ETFs) last week, worth about $37.4 million. The purchase came after Block dipped nearly 2% that day. But the bigger story is what came before it. In February 2026, CEO Jack Dorsey cut more than 4,000 jobs, or roughly 40% of the workforce, as he pushed Block toward a leaner, more artificial intelligence (AI) driven model. XYZ stock jumped about 22% on the news.
Why It's Time to Load Up on Intel Stock
Google Plans to Build Mammoth Solar Farm on an Abandoned Coal Mine. This Penny Stock Just Won the Deal.
NVDA Stock Alert: What to Know as Nvidia Faces DOJ Probe
#Stock #came #cathie #Invest
20 days ago
Ticket prices for the Ohio State-Texas game on Sept. 12 remain pricey.
On Aug. 7, the lowest ticket price available on resale sites for the Ohio State-Texas game was $554. One day before the game, prices have dipped slightly, though they continue to be among the most expensive in college football.
Both the Buckeyes and Longhorns are ranked within the top five of the US LBM Coaches Poll and the ****** ociated Press poll. OSU holds the top spot in both polls, while Texas ranks No. 3 in the Coaches and No. 4 in the AP. The matchup will be the only game of the weekend between two top-10 teams in the polls.
See the latest prices for the Ohio State-Texas game below.
Below is a list of the lowest ticket prices listed on select resale sites for the Ohio State-Texas game.
#texas #prices #coaches #poll

20 days ago
You can watch a US Open semifinal match for about the price of the Honey Deuce.
The get-in price for Session 24 of the US Open—the semifinal match at 2 p.m. ET between Alexander Zverev and Karen Khachanov—dropped as low as $28, down from about $300 at the start of the main draw two weeks ago, according to TicketData. It's a 91% dip compared to just three days ago.
The price dip is likely due to the lack of star power between the two players, even though Zverev is the tournament's No. 1 seed.
TicketData listed its final pre-match average as $40 two hours before the match; pairs of tickets were available on resale sites for $33 shortly after.
The night session match between Americans Frances Tiafoe and Ben Shelton still has a $300 get-in price. It has dipped by 27% over the last three days—ticket prices often drop on the day of the event—but it's still above the tournament average of $296 at the start of the main draw on Aug. 30.
#session

23 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#water #pennsylvania

24 days ago
On August 4, Essential Utilities (NYSE:WTRG) reported second-quarter results that read like two different stories stapled together. Revenue climbed, the dividend grew for the 36th time in 35 years, and the merger with American Water inched closer to the finish line. But earnings per share actually dipped from a year earlier, and the company had to strip out merger costs just to show flat profitability. For a utility this steady, that split is worth a closer look.
Essential's regulated water segment posted revenue of $357.5 million in the quarter, up 7.6% from $332.3 million a year earlier, and the whole company's first-half revenue climbed 7.2% to nearly $1.4 billion. Much of that growth came from rate cases: state regulators approved $43.9 million in new annual water revenue across Pennsylvania, Illinois, Ohio, North Carolina and Indiana, plus $12.7 million more for the gas business in Kentucky and Pennsylvania. Another $79.7 million in water rate requests and a $163.2 million gas case in Pennsylvania, tied to replacing aging pipelines, are still working through the process.
The company keeps buying its way into new customers, too. In May, it closed a $4.9 million wastewater deal in Bastrop County, Texas, and it has signed agreements worth roughly $282 million to add over 200,000 more customers in Pennsylvania, Texas, North Carolina and New Jersey, including the $276.5 million purchase of Philadelphia-area sewer authority DELCORA. Since 2015, acquisitions have added more than 138,000 customers to Essential's base.
Layer on the pending American Water merger, which cleared Virginia and Ohio regulators this year after nearly unanimous shareholder approval in February, and Essential is positioning itself as a much larger multi-state utility by early 2027. The board's decision to raise the dividend 5.25% to $0.3606 per share, continuing a streak of 36 increases over 35 years, signals confidence that this growth is durable.
Look past the top line and the picture gets less flattering. Second quarter net income actually fell to $105.7 million from $107.8 million a year ago, pulling GAAP earnings per share down to $0.37 from $0.38. Essential had to report an adjusted $0.38 figure just to exclude merger-related costs and show earnings roughly matching last year's. The slide is sharper over six months: net income dropped to $330.1 million, or $1.16 per share, from $391.6 million, or $1.41 per share, in the first half of 2025.
#million #revenue #merger #year

26 days ago
On August 4, Archrock (NYSE:AROC) posted second-quarter results that told two different stories at once. Revenue slipped to $371.2 million from $383.2 million a year earlier, yet net income climbed to $66.7 million, and earnings per share rose to $0.38. That gap between a shrinking top line and a growing bottom line is the puzzle this quarter leaves investors to sort out.
The clearest bull signal came from a new long-term agreement with an existing strategic customer covering roughly 665,000 horsepower, structured with an eight-year base term and a two-year extension option. That kind of commitment locks in cash flow well into the next decade and reinforces management's multi-year growth capital expenditure guidance of $1.4 billion to $1.6 billion **** ulatively from 2027 through 2030. The core contract operations segment backed that confidence with real numbers. Revenue there rose 3% to $329.3 million, and adjusted gross margin improved to 71% from 70%, with period-end utilization at 94.4%.
The balance sheet also moved in the right direction. Archrock's leverage ratio fell to 2.6x as of June 30, down from 3.3x a year earlier, even after the company redeemed its entire $800 million of 6.250% senior notes due 2028 on April 1. The board kept rewarding shareholders through it all, declaring a quarterly dividend of $0.23 per share, about 10% higher than a year ago, marking the fifth increase in two years, with coverage still comfortable at 3.1x.
The softer parts of this quarter center on aftermarket services and forward guidance. That segment's revenue fell to $42.0 million from $64.8 million, as last year's non-recurring sales of overhauled engines did not repeat and maintenance demand skipped its usual mid-year seasonal **** p. Total operating horsepower also declined to 4.5 million from 4.7 million, partly from the sale of about 165,000 non-strategic units.
On the guidance front, Archrock tightened its full-year adjusted EBITDA range to $865 million to $885 million, down from a prior range of $865 million to $915 million, pointing to lube oil cost pressure, higher make-ready spending to reactivate idle equipment, and increased SG&A tied to stock-based incentive compensation. Adjusted net income actually dipped to $66.5 million and adjusted EPS to $0.38, both slightly below last year's $68.4 million and $0.39. Long-term debt still sits at $2.3 billion, and Archrock did not repurchase any shares during the quarter, leaving $113.2 million of buyback capacity untouched.
#million
27 days ago
In Bitcoin ETF news today, US spot ETFs posted approximately $236.46M in net outflows on September 1, wiping out the previous session's $216.70 million inflow in a single trading day. The reversal landed just as BTC price briefly dipped below $77,000, having traded above $80,000 as recently as late August.
At the time this data was reported, BTC traded near $77,900.00, up +1.3% on the day, a sign the drop wasn't a rout but rather a pause after a bullish month that saw Bitcoin move up +23%.
August was the strongest month of 2026 for Bitcoin ETFs by a wide margin, yet September opened with the largest daily outflow since July 31. One number doesn't cancel the other, but it does raise the question of whether institutional demand is cooling or just catching its breath.
August wasn't a fluke session – it was a month-long accumulation. According to SoSoValue data cited in the primary reporting, US spot Bitcoin ETFs pulled in roughly $3.52Bn in net inflows, dwarfing July's approximately $172M. Bitcoin itself gained about +25% over the same stretch, its best monthly performance since November 2024.
The funds posted inflows in 16 of August's 21 trading sessions, anchored by a nine-day streak from August 17 through August 27, as detailed in coverage of that inflow streak.
#month #spot #posted

27 days ago
This story was originally published on Food Dive. To receive daily news and insights, subscribe to our free daily Food Dive newsletter.
The Campbell's Company cut 13% of its salaried workforce as part of a plan to slash $500 million in costs by 2030, with CEO Mick Beekhuizen saying the company needs to take "decisive action" to improve performance.
The packaged food maker is also closing two snack plants as it aims to protect margins and support higher levels of investment. Campbell's added it will cut its quarterly dividend by 36% to generate savings that will be directed to other parts of its business.
The announcement comes as Campbell's posted a loss during its fourth quarter, with sales slipping 8% to $2.14 billion. Sales in its snacks business, which includes Goldfish and Pepperidge Farm, plunged 12% during the period. In meals and beverages, home to Rao's, V8 and its iconic soups, sales dipped 4%.
As consumers continue to rein in their spending, food companies are feeling the heat. Beekhuizen said cost cuts at Campbell's are necessary to support greater investment in brands to position them for success.
#sales #investment

27 days ago
Diageo is to cut 305 jobs at its North American headquarters in New York as the drinks group pushes ahead with CEO Sir Dave Lewis' turnaround plans.
The location and number of job cuts were confirmed by a WARN notice by the company, with the permanent layoffs effective from 30 September and the reason cited as "economic".
In a statement, a Diageo spokesperson said: "As we shared at the start of August, we have been redesigning our operating framework to deliver a more competitive Diageo. We understand that this is a difficult time for colleagues, and we remain committed to supporting everyone through these changes."
For the year to 30 June, the Captain Morgan rum distiller booked a 3% decline in reported net sales at $19.64bn. Organically, net sales dipped 2%.
Its North America business, 37% of group sales, saw organic net sales fall by 8.4%.
#lewis

28 days ago
Andrea Kimi Antonelli happy at Mercedes and he knows it is divided fan group with him leading and Ferrari doing well for Italian fans coming to the F1 Italian GP, as Lewis Hamilton chimes in.
When Antonelli arrived at the scene, it was not clear to everyone how well he could do, even though there was hype about him certainly. After how F1 2025 went, some enthusiasm dipped but midway into 2026, it is going through the roof for the Italian, especially in Italy.
When he went to pick up the Lorenzo Bandini Trophy earlier this year, there was massive stream of fans waiting for him. Even at race tracks, there is considerable growth in the numbers. In general as well, Italian fans are quite emotional about their sports persons and also teams.
Ferrari is at par with football if not larger, in certain sphere. For a top Italian driver to race for an Italian manufacturer is icing on the cake. The last to drive in F1 was Giancarlo Fisichella in 2009. It's been 17 years since and it will be longer than that as Antonelli is happy to be at Mercedes.
The Italian was taken up by the German team at a very young age and rose through the ranks, with Toto Wolff's backing. He is their prodigy, much like how Max Verstappen is for Red Bull and Charles Leclerc is in some ways for Ferrari. And for the near future, Antonelli doesn't see himself anywhere else.
#antonelli #Ferrari #even #race

29 days ago
WASHINGTON (AP) — Employers posted slightly more job openings in July but the American labor market remained sturdy in the face of higher costs that are squeezing household budgets.
U.S. job openings ticked up to 7.27 million in July from a revised 7.18 million in June, the Labor Department reported Tuesday.
The department's Job Openings and Labor Turnover Survey (JOLTS) also showed that layoffs fell. But so did the number of people quitting their jobs — a sign of confidence in their prospects. The report showed that gross hiring — before subtracting those who lost or quit their jobs — dipped to 5.1 million in July from 5.3 million in June.
The American job market is hardly booming, but it is ambling along despite an energy shock caused by the fighting with Iran that has squeezed family budgets.
So far this year, U.S. employers — companies, nonprofits and government agencies — added an average of 61,000 net jobs a month. The figure — which was dragged down by job losses in February and July — is unimpressive. But it's an improvement on 2025 when job growth came in below 10,000 a month — weakest hiring outside a recession since 2002 — as the lingering effect of high interest rates and uncertainty caused by Trump's tariffs discouraged firms from hiring.
#july #american


29 days ago
Quinn Ewers went from looking like a potential answer in the Miami Dolphins to becoming one of the biggest quarterback mysteries of the Dolphins' offseason. The former Texas standout flashed enough during OTAs to make a starting push seem plausible. Then training camp arrived, and the picture changed fast.
His decision-making dipped. The consistency disappeared. Suddenly, the same QB who looked aggressive and decisive in the spring was struggling to keep his footing in the summer. That sharp regression had Omar Kelly wondering how Ewers' camp fell apart so quickly.
Oct 26, 2025; Atlanta, Georgia, USA; Miami Dolphins quarterback Quinn Ewers (14) on the field before the game against the Atlanta Falcons at Mercedes-Benz Stadium. Mandatory Credit: Dale Zanine-Imagn Images
Kelly raised the issue on September 2, calling Ewers' regression one of the biggest mysteries of the Dolphins 2026 training camp. The bigger surprise was not simply that Ewers struggled but was how different he looked from the quarterback who had impressed during the offseason program.
Quinn Ewers regression was one of the biggest mysteries of this 2026 training camp. A QB who looked like he should be competing for a starting role in OTAs (quick decisions, bold throws) look lost and was inconsistent in camp.
#camp #regression

30 days ago
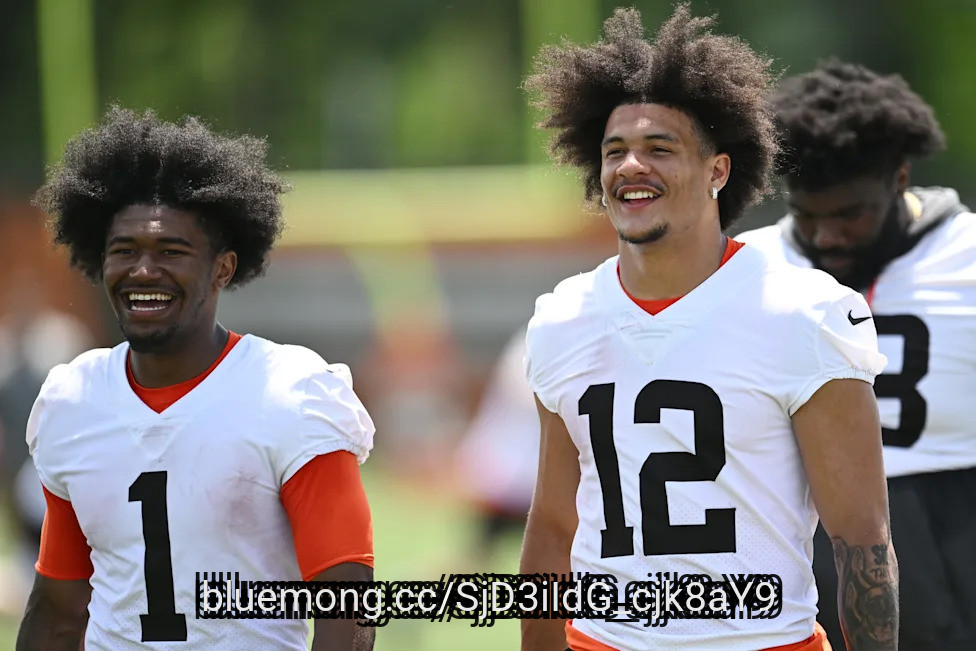
For the second year in a row, the Cleveland Browns double-dipped early at a key offensive position in the NFL Draft. In 2025, Cleveland took Quinshon Judkins in round two and took Dylan Sampson in round four. This year, Cleveland took wide receiver KC Concepcion in round one and followed up with Denzel Boston in round two. Similarly to 2025, a 2026 rookie has seemingly locked down a starting role in this offense.
The staff over at ESPN went through and gave the rookie outlook for all 32 NFL teams, and noted that Concepcion is going to be a real weapon for this offense and wants to get him the ball early and often:
Concepcion has been a dynamic addition to the Browns' offense. Coach Todd Monken is using Concepcion in a role similar to the one he created for Zay Flowers in Baltimore, with plenty of motion and a variety of touches. Monken envisions a versatile role for Concepcion as a rookie -- possibly as a punt returner, too. "We've got to find a number of ways to get him the ball with his explosiveness, his quickness, his contact balance," Monken said. "He's going to be a real weapon for us."
Boston also got plenty of praise, with ***** ysts saying his "contested-catch ability and reliable hands" should have him playing the X receiver next to Concepcion. Overall, there is a lot to like about what Cleveland is building on offense.
This article originally appeared on Browns Wire: Browns rookie WR seems to have locked down a starting role
#Browns #rookie #took
1 month ago
T.J. Watt is coming off one of the worst performances of his NFL career, which subsequently resulted in the Pittsburgh Steelers edge rusher tumbling down ESPN's top 100 players prediction for the 2026 season.
In ESPN's new top 100 players list, Watt saw his ranking tumble 54 spots from last year to No. 65 for the 2026 season. Honestly, this could still be viewed as a compliment considering how his 2025 season played out.
"Watt's production has dipped since he led the league with 19 sacks in 2023, but part of the reason he dropped off in 2025 is a freak situation where he suffered a partially collapsed a lung during dry needling treatment," ESPN's Brooke Pryor wrote. "He is fully healthy entering his 10th season and has vowed to be open to moving around in Graham's system -- something he admitted he was too stubborn to do under the previous regime."
It's true that Watt is going to be moving around the defensive line a lot more in 2026, but he's no doubt at his best when coming off the left side. That was until offenses found a way to neutralize his presence, leaving the Steelers, and Watt, with no choice but to shake things up in 2026.
For up-to-date Steelers coverage, including any roster news and injury updates, follow us on X TheSteelersWire and give our Facebook page a like.
#coming #players #moving #pittsburgh

1 month ago
US stock futures meandered on Tuesday morning as uncertainty around the war in Iran, the bond market, and the Fed's next interest rate move largely kept buyers on the sidelines.
Futures on the Dow Jones Industrial Average (YM=F) and S&P 500 (ES=F) fell about 0.5%, while Nasdaq-100 (NQ=F) contracts dipped 1% after stocks closed August with solid gains.
Stocks entered September with double-digit year-to-date returns and earnings expectations that continue to rise. However, volatile oil prices and the potential return of Fed rate hikes have given investors reason to worry heading into the historically weakest month for stocks.
Crude oil prices remained elevated after the US and Iran returned to a hot war on Sunday, with Brent futures (BZ=F), the global benchmark, trading near $90 per barrel. Treasury yields have also stayed high, with the 10-year yield (^TNX) rising to 4.75%.
On Tuesday, the Job Openings and Labor Turnover Survey (JOLTS) will kick off a string of labor market updates this week, offering a look at hiring and quits ahead of the monthly jobs report on Friday. Data releases from S&P Global and the Institute for Supply Management will also give insight into manufacturing activity.
#futures #market #year

1 month ago
Mercedes' Kimi Antonelli will try to tighten his grip on the drivers' championship on home ground at this weekend's Italian Grand Prix at Monza.
However, the 20-year-old can expect to face a challenge from a resurgent McLaren and in particular Lando Norris, who has won the past two grands prix.
And Monza is of course also home territory for Ferrari, although the long straights of the historic circuit may not suit the characteristics of their car.
BBC Sport F1 correspondent Andrew Benson answers your latest questions before round 13 of the 2026 season.
What does Lando Norris' new contract extension mean for Oscar Piastri? There clearly is some tension behind the scenes and this season his development performance-wise has clearly dipped. - Juha
#monza
1 month ago
On August 28, Affirm Holdings (NASDAQ:AFRM) gave investors two very different signals in the same breath. The buy now, pay later company posted a fiscal fourth quarter that blew past Wall Street's numbers, yet CEO Max Levchin used the moment to flag something less comfortable: gas prices are squeezing the very shoppers driving that growth. The stock barely moved on the news, leaving the market to sort out which story matters more.
The headline numbers were hard to argue with. Revenue rose 33% to $1.17 billion for the three months ended June 30, ahead of the $1.11 billion ****** ysts expected, while gross merchandise volume climbed 36% to $14.1 billion against a $13.39 billion estimate. Adjusted operating income reached $353 million, a 30% margin, and the GAAP operating margin expanded six percentage points to 12.6%. For the full fiscal year, GMV hit $50.2 billion, up from $36.7 billion, on $4.26 billion in revenue.
The user base kept expanding too. Active consumers grew 21% to 27.8 million, and transactions per active consumer rose 20% to 7.0, while the Affirm Card's active user count more than doubled to 5.2 million. Newly appointed president Michael Linford, who moved into the role Thursday, Aug. 27, after nearly two years as chief operating officer, called it the eleventh straight quarter of GMV growth above 30%. Credit quality held up alongside that growth, with the 30-day delinquency rate improving to 2.5% from the 2.7% to 2.8% range of the prior three quarters, something Compass Point's Giuliano Bologna called evidence of "resilient credit performance." Affirm also deepened its Shopify tie-up, extending Shop Pay Installments into Australia after last year's UK expansion, part of what Linford described as Shopify "pulling us into a new market" as both a partner and shareholder. Susquehanna's James Friedman raised his price target to $110 from $105, calling the guidance for fiscal 2027 "exceptionally strong."
Levchin's own commentary complicated the celebration. "The US consumer undoubtedly sees the higher gas prices, so can't, can't ignore that," he told CNBC, noting shoppers are increasingly turning to Affirm to manage costs across "all the various inflationary points." The national average gas price sat at $4.09 a gallon as of August 28, down from above $4.50 in May but still well above pre-Iran war levels, and it hasn't dipped below $3 since March 2. Levchin was direct about the risk: "I do think that sustained pressure on prices isn't great in the long term, and so can't ignore that either."
#prices #Growth #can 't

1 month ago
The Oregon Ducks coaching staff is hard at work recruiting the quarterback position in the 2028 class, reportedly emerging recently among the favorites for four-star Tristin Gaines, who's scheduled a gameday visit this fall. But that's not stopping Dan Lanning and Co. from continuing to cast a wide net, as four-star passer Tommy Devany has scheduled a gameday visit as well in Eugene.
Devany, the No. 16 quarterback and No. 236 player overall in the 2028 class according to 247Sports Composite, will be in Eugene for the Ducks' Nov. 14 matchup against the Michigan Wolverines. He's also set to take gameday visits to California (Sept. 5), Arkansas (Sept. 26), Utah (Nov. 7) and Stanford (Nov. 28).
A Clovis, CA, native, Devany competes for Buchanan High school and is the 18th-ranked player in the talent-rich state of California. As a sophomore in 2025, Devany completed 62% of his passes for 2,408 yards and 18 touchdowns while adding another three scores on the ground.
Standing 6-foot-3 and 190 pounds, Devany collected a bevy of offers earlier this year, but appears to have narrowed his lift down to five with Oregon included. Having received the commitment of Will Mencl, the No. 4 quarterback in the 2027 class, it's not necessarily imperative for the Ducks to have a quarterback commit in the 2028 class.
After all, they survived without one in the 2026 class after four-star Bryson Beaver signed his letter of intent but entered the transfer portal and landed with the Georgia Bulldogs. Oregon has dipped into the transfer portal for both depth and starting-level talent, and could do so in the future.
#devany

1 month ago
Two leading automotive giants, General Motors Company (NYSE:GM) and Toyota Motor Corporation (NYSE:TM), represent contrasting strategies in the U.S. auto market. Twenty years ago, GM sold twice as many vehicles in the U.S. as Toyota. Today, that gap has narrowed dramatically. Through July, GM's sales lead over Toyota dwindled to just over 100,000 vehicles, as reported on August 21. The shifting dynamic highlights two distinct operating models: GM prioritizing disciplined volume and profit margins, while Toyota aggressively expands its hybrid-heavy lineup to capture market share.
Toyota's push into electrified vehicles, predominantly gas-electric hybrids, is rapidly closing the volume gap. In Q2 2026, Toyota Motor North America reported U.S. sales of 673,971 vehicles, up 1.1% year-over-year. Driver demand was led by its electrified options, which jumped 19.5% to 383,091 units, representing 56.8% of Toyota's total Q2 volume.
Financially, Toyota's hybrid strategy gives it strong top-line momentum without forcing full reliance on pure electric vehicles. Its multi-pathway approach offers 33 electrified models across the Toyota and Lexus lineups, helping maintain high consumer interest while keeping incentive spending among the lowest among full-line automakers.
While Toyota closes the distance, GM retained its spot as America's #1 automaker by volume in Q2 2026, selling 714,896 vehicles. Total sales dipped 4.2% year-over-year due to inventory constraints, discontinued models, and a softer EV backdrop. However, GM intentionally chose not to chase lower-margin volume, focusing instead on high-margin trucks and SUVs like the Chevrolet Suburban and GMC Sierra.
GM's financial execution remains sharp. In Q2 2026, GM delivered an 8.6% North American EBIT-adjusted margin, up 2.5 percentage points year-over-year, and raised its full-year 2026 guidance for the second time. Reduced EV manufacturing losses and pricing stability have kept profitability resilient despite lower unit sales growth.
#full #NYSE

1 month ago
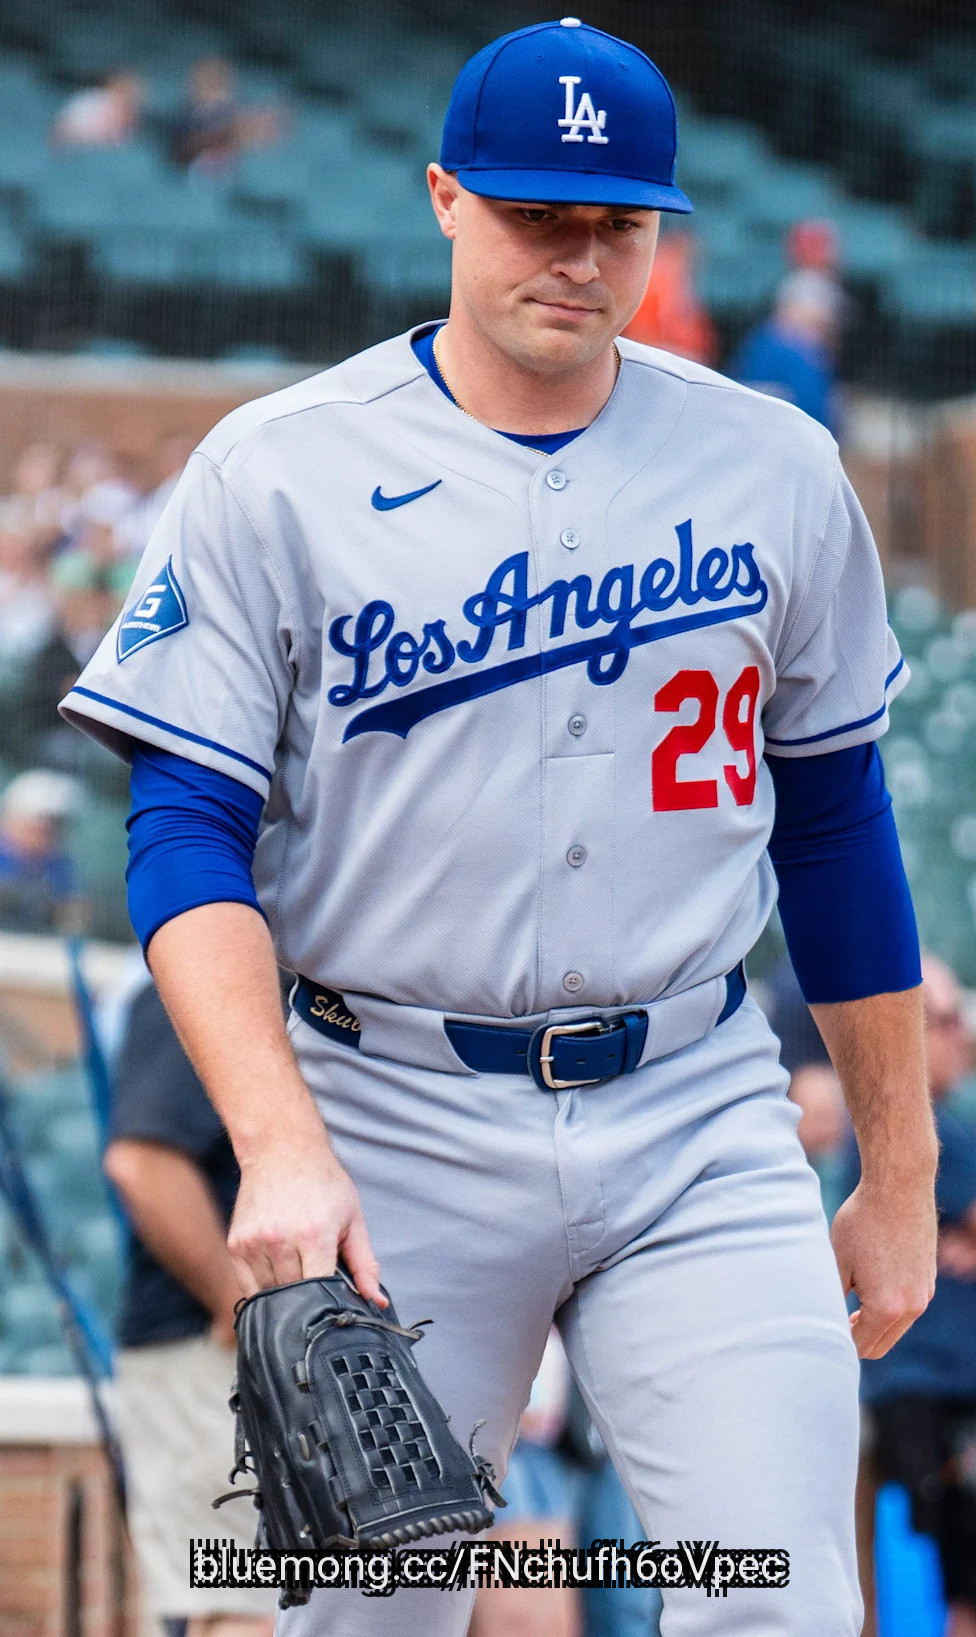
Los Angeles Dodgers pitcher Tarik Skubal looked comfortable sitting in the first-base dugout in the stadium he called home for his first seven MLB seasons – minus a few inconveniences that come from playing for the visiting team.
"I've never been on this side of the clubhouse. So when I first got here, I'm like, 'which way is the field?'" he said. "It's much farther down there. There's a lot more steps going on, but I guess it's good for your health."
The setting was familiar, but the threads were not. Skubal wore his usual headband and sleeveless hoodie, but both were dipped in Dodger blue instead of stamped with the Olde English D. The night before, he pitched six brilliant innings in the Dodgers' 2-1 win over the Detroit Tigers, returning to Comerica Park less than a month after the Tigers traded him to Los Angeles at the deadline for three prospects.
Skubal didn't have a say in where he went. But based on his interaction with the media before Detroit's game with the Dodgers on Saturday, Aug. 29, he looks to have landed in a situation he really likes.
"[The Dodgers] have won the last two World Series for a reason. It's not a mistake," he said. "You watch [first baseman Freddie Freeman's] ground ball routine, he does the same thing every single day. I think those routines matter, and they translate to the field, stuff they do in the cage, the way pitchers prepare ... no little thing is overlooked, and I think that's what makes good teams really good."
#really #thing