

22 days ago
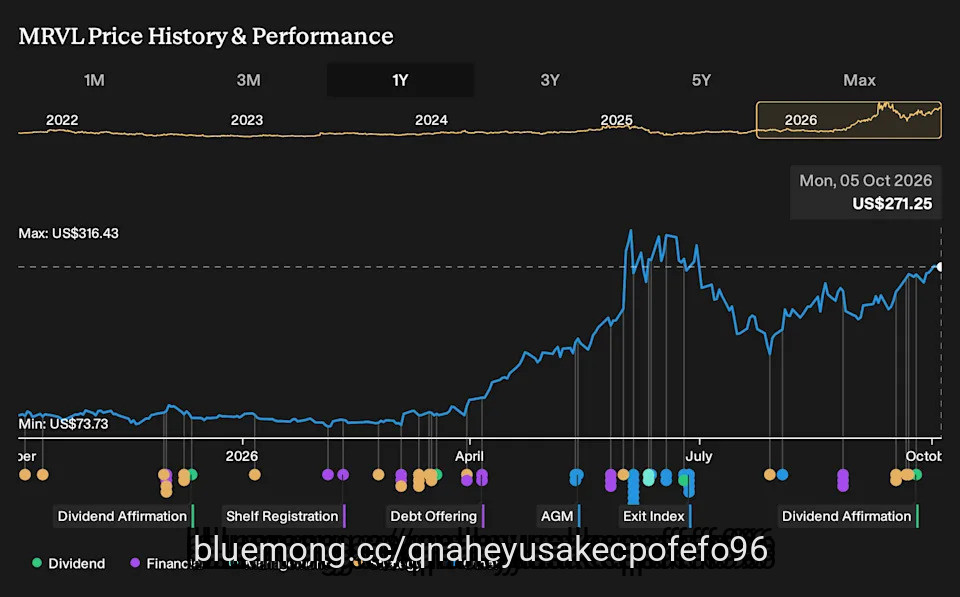
In late September 2026, AT&S Austria Technologie & Systemtechnik AG announced an expanded collaboration with Marvell Technology to increase advanced IC substrate capacity for next-generation AI and cloud infrastructure, while Marvell also affirmed a quarterly dividend of US$0.06 per share payable on October 29, 2026.
This deeper manufacturing partnership gives Marvell greater access to complex packaging technologies that are increasingly critical for high-performance AI chips and data center hardware.
Next, we'll examine how this expanded AT&S manufacturing capacity could influence Marvell's AI-focused growth story and longer-term investment narrative.
The future of work is here. Discover the 89 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
To own Marvell, you need to believe its AI and data center franchises can justify today's rich valuation and eventually translate into stronger, more consistent earnings power. The expanded AT&S IC substrate deal directly supports Marvell's near term AI optics and custom silicon ramp, while also amplifying the existing risk that long term supplier prepayments and capacity commitments could weigh on margins and free cash flow if AI demand or customer ramps slow.
#term #substrate #Manufacturing #data

22 days ago
McKenna Woods (ken_hairstylist), a hairstylist from Iowa, told TikTok about her allegedly disruptive client. Throughout his hair appointment, Woods said he had been making inappropriate comments and then using his supposed autism as an excuse.
Woods responded to a viral clip of her client, Chris, which accused her of being rude and mean. He also told others not to seek her services. Woods replied on TikTok, "I think this guy came in here thinking he's high and mighty because he's this upcoming rapper, a content creator."
Woods claimed she made small talk with her client, asking him how many followers he had on social media. She clarified that her issue wasn't his follower count but his alleged behavior in the salon. The hairstylist continued, "My problem is the way he acted in here, while my coworker had a client in here who is nine years old."
In a clip stitched to her TikTok, the nine-year-old can be overheard addressing Woods' client, saying, "Do you realize she has a boyfriend?" The client replied, "I'm not doing that. I'm just being autistic."
"And he's rapping. He's being very disruptive, being very disrespectful, making these comments about how he's autistic," Woods added. She alleged he was using his supposed condition to justify his behavior. In addition to comments about his mental health, Woods said he also made an inappropriate remark to her.
#woods #here #making

24 days ago
The OpenAI CEO sought to distinguish his policy stance from rival developer Anthropic.
OpenAI CEO Sam Altman argued in an exclusive interview with Decoded by POLITICO that AI’s benefits justify accepting some risks. | Heather Diehl/Getty Images
10/05/2026 05:55 AM GMT+9
OpenAI CEO Sam Altman said there remains a fundamental difference in worldview between his company and rival Anthropic on artificial intelligence regulation, arguing in an exclusive interview with Decoded by POLITICO that the technology’s benefits justify accepting some risks — and that AI should remain broadly accessible to the public.
#anthropic #decoded #benefits #justify

1 month ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long

1 month ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

1 month ago
Morgan Stanley has cut Novo Nordisk A/S (NYSE:NVO) to Underweight on September 11, 2026. Semaglutide, the underlying molecule for Wegovy and Ozempic, generates roughly 75% of 2026 revenue. Morgan Stanley models that it will still represent 59% of total sales when its patent protection expires in 2031. And according to the firm, the valuation does not price in the impact it has on Novo's terminal value. The stock, currently trading at 10.6x earnings and down 33% from its 52-week high, slipped another 2% following the call. At this point, the question isn't about whether the patent cliff is real or not, but whether the 10x multiple reflects an actual bargain.
Semaglutide loses exclusivity in Europe in 2031 and the US in 2032. And Morgan Stanley believes Novo's oral-obesity business, projected to reach $10 billion by 2031, could not offset the pricing collapse after the arrival of generics. Growth decelerates to a 4% compound rate between 2027 and 2030. If the deceleration continues, it will justify 10x earnings as a fair price instead of a cheap one.
The 10.6x multiple already prices aggressive pessimism into a market leader of one of the fastest-growing drug classes in history. Morgan Stanley fueled the pessimism by discounting a 2031 cliff five years earlier. However, pharmaceutical patent expirations frequently face extensions and prove difficult to time. Second, the ***** umption that oral obesity treatments cannot offset patent losses relies on oral semaglutide being the bridge. But Novo's next-generation portfolio, including CagriSema and amycretin, offers a significant defense against the patent cliff. This remains unproven, however, specifically after CagriSema's earlier weight-loss data failed to impress, yet Morgan Stanley's terminal-value model discounts this pipeline almost entirely. The company is also expanding its franchise. On September 7, the STEP Young trial hit its endpoint in children aged six to twelve, strengthening the base its successors inherit.
The smart money is leaning in. As per the Insider Monkey database, 59 hedge funds held NVO in the second quarter of 2026, up from 55 in the first, indicating a slight increase in the modest institutional interest in the stock. Short interest on the ADR is negligible at about 0.7%. The positioning reflects a beaten-down value stock quietly seeing institutional accumulation while Wall Street turns increasingly bearish.
#semaglutide #oral


1 month ago
On September 9, 2026, Reuters reported that Alphabet Inc. (NASDAQ:GOOGL)'s Google will invest at least €13 billion, or about $15.1 billion, in AI infrastructure in Finland over the next two years, its biggest European investment, including three new data centers and a 22-year deal for up to 50% of the output of one of Finland's two nuclear power plants. The agreement with Finnish utility Fortum is Google's first nuclear energy deal outside the United States, and Fortum's stock jumped as much as 15.5% on the news, its biggest gain in Europe that day.
Finland gives Alphabet Inc. (NASDAQ:GOOGL) a potentially more cost-efficient location for its expanding AI infrastructure. Google plans to invest at least €13 billion ($15.1 billion) in three new data centers and related infrastructure in Finland during 2027 and 2028. The country's cold climate can reduce the need for energy-intensive cooling. The investment will also help grid improvements, clean-energy projects and battery storage.
The 22-year nuclear power agreement gives Google greater control over a critical input for AI infrastructure. Google will purchase up to 50% of the electricity generated by Finland's Loviisa nuclear plant, providing a long-term source of low-carbon power for its data-center operations. The agreement also gives Fortum greater economic certainty to extend and upgrade the plant through 2050. Google and Fortum plan to explore more nuclear and renewable projects.
Alphabet has strong demand drivers that can justify investment in AI capacity. The firm has increased its 2026 global capital investment target to $195 billion-$205 billion as it seeks to capture growing AI computing demand. Google is using the additional infrastructure to support Gemini, Search, Maps, and YouTube. It gives Alphabet multiple major products through which it can monetize greater AI capacity over time.
The Finland project adds another major commitment to Alphabet Inc. (NASDAQ:GOOGL)'s already enormous AI spending program. Alphabet expects to spend $195 billion-$205 billion on capital investment globally in 2026. The Finnish project will require at least another €13 billion during 2027 and 2028. Investors need Alphabet to make enough incremental revenue and cash flow from AI services to justify an infrastructure buildout that is rapidly increasing the company's capital requirements.
#billion #Google #investment #googl

1 month ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional
1 month ago
Cybersecurity provider CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s shares are up by more than 100% year to date. With AI continuing to dominate the market narrative, the firm has found itself at the center of the industry's concerns about cybersecurity. While some, such as Anthropic's Dario Amodei, have claimed that their AI software is sufficient for cybersecurity purposes, others have argued that firms such as CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play a key role in the industry. Cramer is in the latter camp, and in his morning appearance on September 15th, the CNBC TV host discussed the recent discussions about AI being a threat:
"I had George Kurtz last night, who has partnered both with OpenAI and Anthropic. And he encouraged me to say look, they are doing a lot of things about safeguards. I think he was so much surprised, that there was so much doomsaying, of course, doomsaying being heavily refuted. Now there's a stock, remember that stock was up the most of any stock in the S&P."
While Cramer believes CrowdStrike Holdings, Inc. (NASDAQ:CRWD) will play an important role in cybersecurity in the AI era, the broader debate about the firm is about its AI-driven cybersecurity initiatives and whether they are sufficient to stay competitive and justify the eye-watering share price performance. On this front, the firm's annual recurring revenue (ARR) grew by 25% and net new ARR grew by 55% in its fiscal second quarter. Additionally, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s net new ARR set a new record of $333 million. Cramer's bullishness on the firm is also matched by others, such as ******* ysts from Argus. Argus has set a $425 share price target for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) and argued that growth in agentic AI use presents a major tailwind for the firm.
Yet, in a classic case of the bigger you are, the harder you fall, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s massive growth creates risk. For its fiscal second quarter, the firm has guided net new ARR to range between $343 million and $347 million to imply growth ranging between 29% to 31%. Considering that the metric grew by 55% in Q1, the new figures do indicate a slowdown. As for catalysts from agentic AI, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s next-gen SIEM (Security Information and Event Management) ending ARR grew by 60% to $695 million in the second quarter.
Hedge fund interest in CrowdStrike Holdings, Inc. (NASDAQ:CRWD) grew in Q2. According to Insider Monkey's data, 89 out of 1,006 funds had held a stake in the firm during the period. This marked a jump over the 89 out of the 1,022 funds in Q1. As for valuation, CrowdStrike Holdings, Inc. (NASDAQ:CRWD)'s forward P/E ratio of 188 is significantly higher than peer firm Palo Alto's 89 which should increase the pressure to maintain growth. Short interest as a percentage of float is 2.41% for CrowdStrike Holdings, Inc. (NASDAQ:CRWD) compared to 2.65% for Palo Alto.
#NASDAQ #firm #grew


1 month ago
GE Vernova Inc. (NYSE:GEV) is trying to recover after an 8.5% decline, with Bernstein defending the stock as "wired to win" and highlighting that data centers account for only 38% of its electrification order book. This supports the argument that the company's utility exposure extends beyond AI power demand alone. That diversification is a real consideration, but it does not directly address the concern raised by GLJ Research. The firm's Sell rating is not based on doubts about AI-driven power demand. Instead, GLJ Research argues that GE Vernova is still a fundamentally cyclical gas-turbine manufacturer, while its current valuation reflects an **** umption that the ongoing boom can remain permanent.
GE Vernova shares stabilized after an 8.5% decline triggered by GLJ Research's new Sell rating and broader concerns that a slowdown in AI spending could weigh on the company's order book. Bernstein **** yst Sunaina Ocalan directly challenged the view that GE Vernova's outlook depends mainly on AI infrastructure spending:
While data center orders were $5 billion in H1 2026, or about 38% of electrification orders, the remaining 62% was utility-driven. Utility spend should continue to grow, supported by grid reliability and resilience investments. A slowdown in data center demand may alleviate generation bottlenecks but would do little to address existing grid constraints.
Bernstein continues to rate the stock a Buy with a $1,298 price target, while nearly 80% of **** ysts covering GE Vernova also have a Buy rating. In a separate development, the company announced a wind turbine supply agreement with Eurus Energy Holdings in **** an.
GLJ Research's Gordon Johnson argued that GE Vernova's turbines being sold out does not justify the stock trading at roughly 38.9x forward EV/EBITDA at the time the report was released. Johnson described the company as "a cyclical gas turbine manufacturer priced as a secular compounder," highlighting the premium valuation placed on a fundamentally cyclical business. His model estimates 2027 EBITDA at $7.42 billion, which is 22% below Wall Street consensus. The lower forecast is partly based on the timing of turbine orders, as equipment scheduled for 2027 delivery was ordered in 2024, before the company introduced its more recent price increase.
#bernstein #turbine #Stock #data

1 month ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply

1 month ago
Ascendis Pharma A/S (NASDAQ:ASND) announced on September 14 that it will regain exclusive rights to develop, manufacture, and commercialize TransCon products in metabolic and cardiovascular diseases following the termination of its collaboration with Novo Nordisk A/S (NYSE:NVO).
The rights include once-monthly TransCon Semaglutide, an investigational long-acting prodrug of semaglutide intended for obesity and type 2 diabetes. Neither party will have continuing financial obligations to the other. Once termination becomes effective and the rights revert, management plans to initiate multiple programs across rare and large indications.
The investment question is whether greater control over future products can justify the resources needed to develop them.
Ascendis Pharma A/S (NASDAQ:ASND) would regain flexibility over which indications to pursue, how quickly to advance candidates, and whether to seek another partner. Successful independent development could retain more of a product's commercial economics, while a new collaboration could provide another way to share costs and risk.
Monthly dosing offers a clear development objective. If clinical studies demonstrate effective treatment with acceptable tolerability, fewer injections could make long-term therapy more convenient. That potential benefit would matter most if it helps patients stay on treatment without sacrificing outcomes.
#ascendis #pharma #asnd #regain


1 month ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas

1 month ago
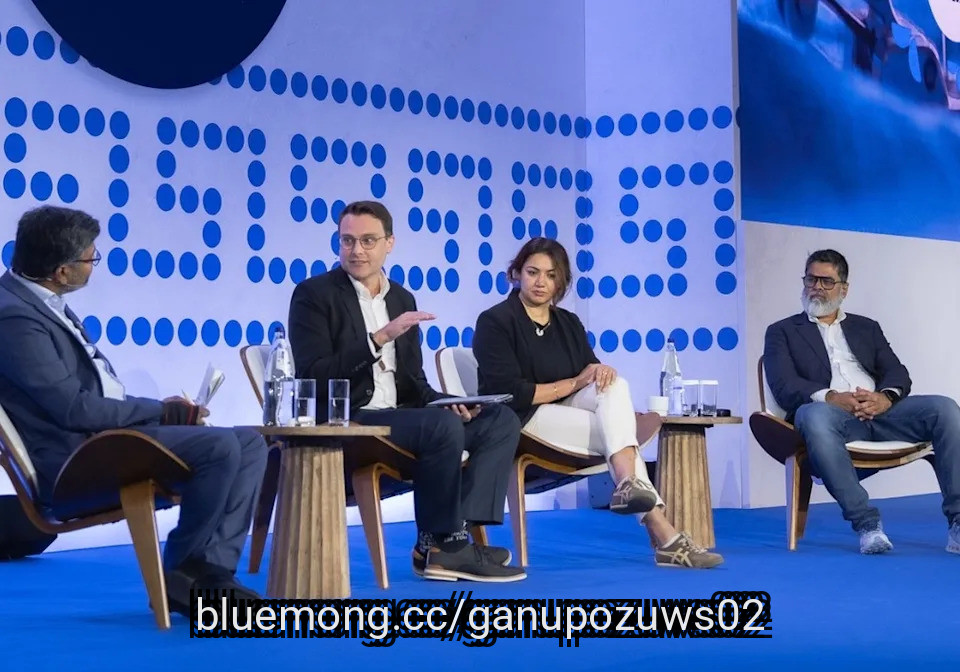
At the Cascale annual meeting in Athens on Wednesday, Asif Khan, executive director of supply chain and sustainability at Mondetta, acknowledged the central conflict undercutting fashion's green ambitions: while sustainability demands a long-term sourcing strategy, brands rely entirely on the ability to pivot at a moment's notice.
It's a commercial reality that constrains companies such as his, Khan admitted. Navigating a volatile environment shaped by fast-changing consumer demands, evolving trends and geopolitical instability, brands are unable to offer the multi-year purchasing guarantees that factories need to justify significant capital investments, he said.
More from WWD
Cascale Wants to Put the 'Collective' Back in Collective Action
As Fashion's Emissions Rise for Second Straight Year, Aii Knows What Needs to Change
#Sustainability #asif

1 month ago
Alphabet's (GOOGL) Search revenue grew 17% to $63B and Cloud surged 82% to $25B, even as GOOGL still trades at a market-level P/E of 15.
Alphabet's cloud is outpacing Azure's growth at a cheaper multiple than Microsoft (MSFT), while Meta (META) owns none of Alphabet's cloud, OS, or Waymo ***** ets.
Alphabet's $175B+ CapEx pushed free cash flow negative, but a $460B cloud backlog and 34% operating margin justify the infrastructure bet.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Google made the cut. Enter your email to see the other nine names and why GOOGL earned its spot. The report is free. Enter your email and see the full list.
I keep adding to my position in Alphabet (NASDAQ:GOOGL) because the loudest bear case, that AI would gut Google Search and hollow out the ad engine, keeps getting louder while the numbers keep going the other way. The skeptics said generative AI would strip clicks out of the funnel. Instead, AI is actively boosting the advertising business, and my cost basis has been rising alongside the buy ***** on.
#free


1 month ago
When a caller inquired about SoFi Technologies, Inc. (NASDAQ:SOFI) during the September 10 episode of Mad Money, Jim Cramer commented:
Well, you know, it's a financial tech. It's a bank, but let's put it this way: It's doing as well as it can, but it has a very high price-to-earnings multiple versus the others in its cohort. So, it's going to mark time until the earnings continue to go up. I do like the company. I like the management. I wouldn't mind you owning it for the long term.
SoFi Technologies, Inc. (NASDAQ:SOFI) reported record second-quarter adjusted net revenue of $1.2 billion, up 40% year over year, while GAAP net income rose 61% to $156.6 million. Adjusted EBITDA increased 44% to $358 million. Loan originations reached a record $14.8 billion, while members increased 35% to 15.8 million and deposits reached $45.5 billion. Moreover, at the September 8 Goldman Sachs conference, CFO Chris Lapointe said SoFi generated approximately 40% year-over-year revenue growth in each of the first two quarters and approximately 30% adjusted EBITDA margins. He also said the company had outpaced the Rule of 40 for 20 consecutive quarters. Additionally, the company raised its 2026 adjusted net revenue outlook to $4.75 billion to $4.85 billion but maintained its adjusted EPS outlook at $0.60.
A concern is that SoFi Technologies, Inc.'s (NASDAQ:SOFI) earnings growth may not be sufficient to justify the multiple investors are paying. SoFi is trading at a premium valuation compared to its traditional banking peers, with Yahoo Finance's latest data showing a trailing P/E of 35.12 and a forward P/E of 21.51. That valuation leaves the shares sensitive to a slowdown in earnings growth. Credit performance is another important consideration as SoFi expands its lending business. For the six months ended June 30, total net charge-offs were $406.1 million, up $77.2 million from the prior-year period, while the total net charge-off ratio declined to 1.91% from 2.24%. The increase in charge-offs was driven primarily by higher personal-loan net charge-offs and student-loan net charge-offs, reflecting growth in average loans.
According to Insider Monkey, which tracks more than 1,000 hedge funds, 44 hedge funds held SoFi in Q2, down from 47 in Q1. Its short interest stood at about 14% to 15% of the float. SoFi Technologies, Inc.'s (NASDAQ:SOFI) growth and improving profitability give Cramer's long-term view a fundamental basis, but its valuation still leaves the stock dependent on continued earnings growth. The company's ability to turn strong revenue and loan growth into higher earnings will remain important to the stock's valuation.
#earnings #adjusted #million #charge

1 month ago
September's debate over Chinese and American AI spending puts Alibaba Group Holding Limited (NYSE:BABA) and Amazon.com, Inc. (NASDAQ:AMZN) on opposite sides of the same investment question. Both report strong demand for computing services. Shareholders still need that demand to justify the infrastructure bill.
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services

1 month ago
NVIDIA Corporation (NASDAQ:NVDA) has an argument against rapid hardware obsolescence: older accelerators still command rental prices. For CoreWeave, Inc. (NASDAQ:CRWV), which sells access to computing infrastructure, the harder question is how much of that rent becomes a return.
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return

1 month ago
This summer, a 28-year-old digital content marketer packed up his suitcases and duct-taped boxes and fled Russia, leaving behind his family and friends and not knowing when he'll be able to return.
"It is very sad to leave Russia," he said in the southern city of Krasnodar before heading for the border with Georgia.
He blamed "the political situation" in Russia and complications over authorities restricting internet access as his reasons for leaving. Otherwise, "I never would have left for more than several months," he told The ******* ociated Press, speaking on condition of anonymity because of security concerns.
He is one of a number of people who either left or are contemplating a move amid recent Ukrainian drone attacks inside Russia and persistent rumors of a coming mobilization of troops for the 4 1/2-year-old war.
The attacks this summer caused an unprecedented fuel crisis and dealt crippling blows to the booming e-commerce sector. Since last year, the government has cited the attacks to justify harsh restrictions on connecting to the internet.
#Russia #year #otherwise



1 month ago
This offseason, the Heat witnessed a complete change in its roster. From superstar acquisitions through trade exchanges to top players leaving impressive salaries to join the roster, they saw a major upheaval. However, two players who were unaffected by these events were Andrew Wiggins and Simone Fontecchio.
Both players not only get to continue on the team but were also offered retention; a lifeline offered to only a handful this time. Now, with the next season approaching, the players have to meet high expectations to justify their contracts.
Earlier in the summer, Wiggins exercised the $30.1 million player option for the final year of his contract with Miami. But on June 29, the Heat decided to hand him a two-year, $34 million extension, bringing his term to a three-year, $64 million contract with them overall. He will be getting $16.5 million in 2027-28 and will have the player-option season worth $17.5 million in 2028-29. This is a huge financial security for any player, especially in a team that is aggressively looking to reinvent itself at the cost of its roster.
Wiggins was a dependable starter and brought stability last season,which he needs to continue this year. Wiggins averaged 15.4 points, 4.8 rebounds, and 2.7 ****** ists per game across 68 appearances. Maintaining his distance from defense, the 31-year-old needs to focus on being a high-efficiency 3-and-D wing, a role that saw him shine last year. He knocked down two threes a game at a career-best 41.4% clip in 2025-26.
At his rate, he could surely increase his average and show improvement. For the upcoming season, Wiggins should get perimeter shooting help from Klay Thompson, who he was teammates with in Golden State.
#wiggins #players #heat #continue



2 months ago
HBCU coach has $1 million hot take on money games appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
Tennessee State head coach Reggie Barlow stood in solidarity with Edward Waters' president, Dr. A. Zachary Faison, after his comments about money games. Faison's comments came after Edward Waters played Jackson State, and he believes that the team did not get a fair shake in the deal he made years ago.
"Going forward, Edward Waters University will not schedule Division I opposition in football except on terms this institution sets and that materially and substantially advance our program goals," he said in the post. "I want you and our supporters to understand exactly why. The economics do not work. We were paid a $65,000 guarantee, which covered none of our costs. Travel and related expenses ran roughly $30,000 to $35,000, so we cleared about $30,000. That does not begin to justify what such a game asks of a team, a coaching staff, and a program."
Barlow, whose team recently played the University of Georgia in Week 1, expressed solidarity with Faison on Monday's OVC-Big South coaches call. He started by acknowledging that guarantee games between HBCUs (and FCS schools generally) and Power Conference opponents are common practice.
Watch sports LIVE with fuboTV (free trial)
#games #team #clutchpoints #state

2 months ago
GE Aerospace (NYSE:GE) is making its largest acquisition since becoming a standalone publicly traded company. It agreed to acquire Consolidated Precision Products (CPP) for around $12 billion.
CPP is one of the world's largest precision castings providers. It's a major GE supplier. Precision castings is a major pressure point for the aerospace engines industry. Acquiring CPP would give GE Aerospace greater control over a critical part of its engine supply chain.
And the deal could strengthen GE's ability to meet demand already sitting in its backlog. But the investment case depends on whether additional production capacity generates enough free cash flow to justify the deal's premium price.
rommma/Shutterstock.com
Engine manufacturers like GE Aerospace (NYSE:GE) are struggling to keep pace with surging demand due to supply chain constraints. CPP is a major supplier of precision castings for GE's LEAP and GEnx engines. GE plans to raise CPP's output. It would do that by improving factory yields and machine use. With the CPP deal, GE also sees a path to accelerate production of new engine technologies.
#NYSE #largest #engines #supply


2 months ago
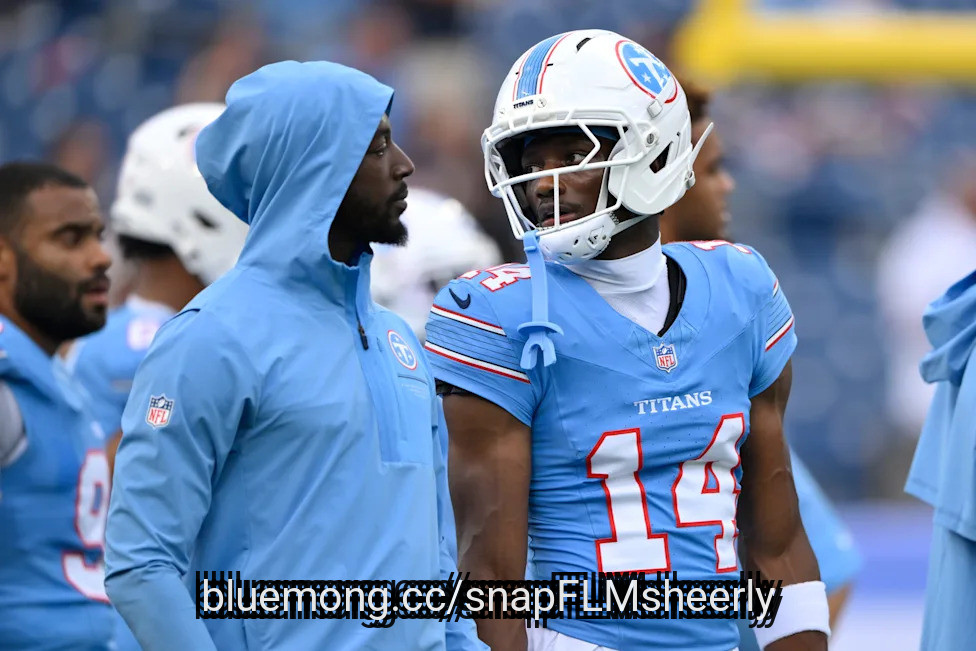
The Tennessee **** ans made the first somewhat surprising pick of the 2026 NFL Draft when they selected former Ohio State wide receiver Carnell Tate with the number four overall pick. With his first NFL game on the horizon, CBS Sports' Ryan Wilson believes he was worth the fourth overall pick for the **** ans.
Tate was drafted with the expectation that he can become a foundational piece of the offense and a long-term number one target for second-year quarterback Cam Ward. That might be a lot to ask from a rookie, but everything about the situation suggests the **** ans had a plan.
The biggest question surrounding the **** ans' selection was whether Tate's talent will eventually justify taking him fourth overall. Including Tate, only five wide receivers (six if you include Travis Hunter) have been selected in the top five of the NFL Draft since 2015.
Excluding Jacksonville Jaguars WR/CB Travis Hunter, former **** ans WR Corey Davis had the worst rookie season of those top five selections with 375 yards and 0 touchdowns. So, it made sense why **** ans fans, specifically, may have had concerns about the Tate selection.
However, a strong training camp has many anticipating his NFL regular-season debut. Tate doesn't need to immediately become one of the best receivers in the NFL for the pick to be successful, but Tennessee needs to see enough flashes to believe they have found a long-term offensive cornerstone.
#tate #draft

2 months ago
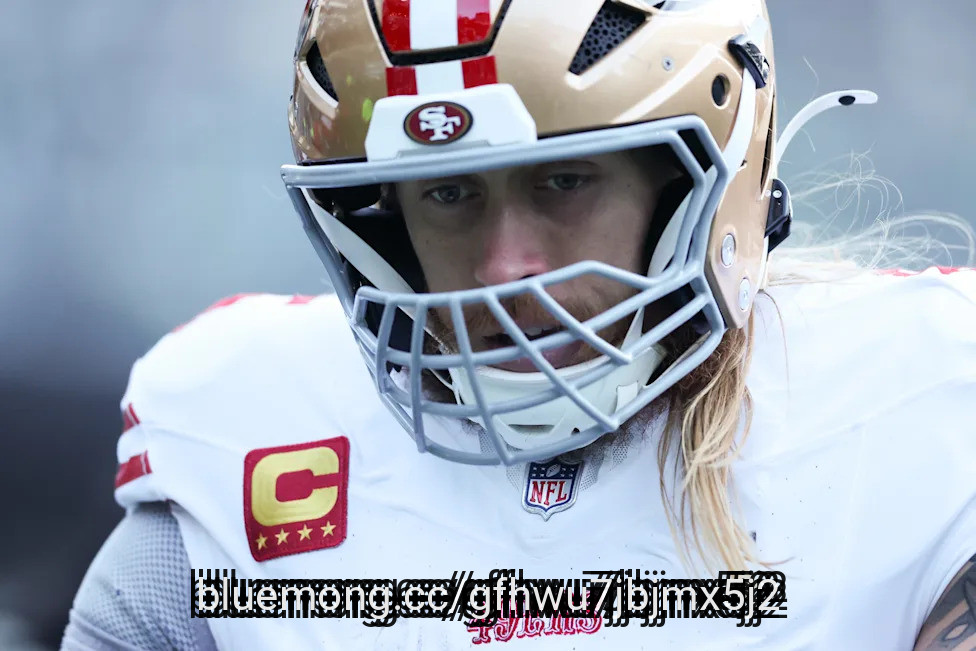
San Francisco 49ers TE George Kittle had two receptions for 12 yards in Week 1 against the Los Angeles Rams. Kittle was targeted five times.
SOURCE: ESPN
Why It Matters: In a game where most things went right for the 49ers, Kittle struggled with just two catches for 12 yards. Don't overreact. It was a testament to Kittle's dedication that he was even active in Week 1 after suffering a torn Achilles in January. He got some reps in and didn't suffer a setback. Now he'll get a few extra days to rest up before Week 2. You might want to continue holding him out until he has a breakthrough performance, but if you lack appealing alternatives you can justify rolling the dice on Kittle versus the Dolphins next weekend.
This article originally appeared on USA TODAY: George Kittle quiet in season opener
#source
2 months ago
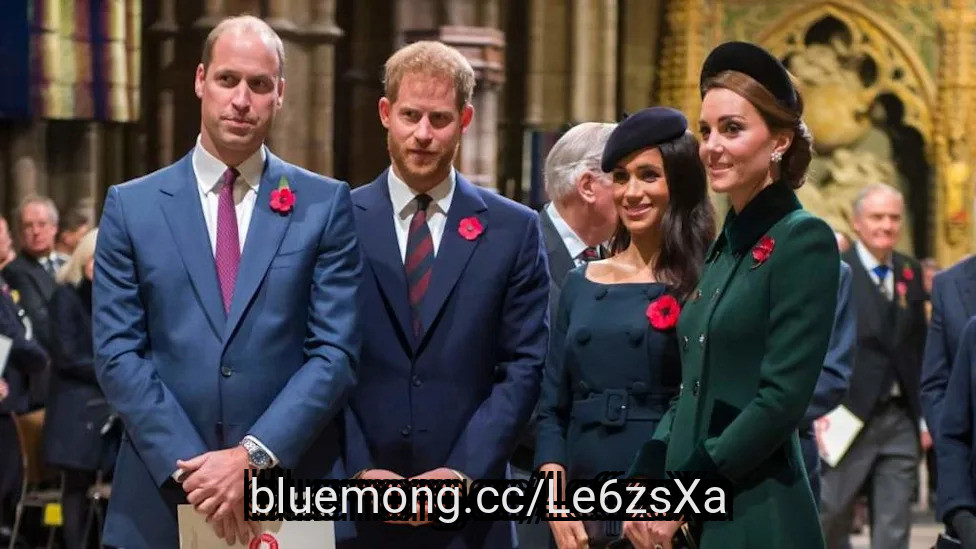
Kate Middleton is reportedly encouraging Prince William to let their children build a relationship with Prince Harry and Meghan Markle's kids. The change in approach comes as the Sussexes settle back in England. The move has brought the cousins closer than they have been in years.
Prince William and Kate Middleton's children reportedly did not meet Prince Harry and Meghan Markle's children during the Sussexes' recent U.K. visit. But according to a source speaking to Closer, Kate now believes the situation could become harder to avoid. The source claims Kate has told William that the children should have the chance to know their cousins.
When Archie and Lilibet lived across the Atlantic, the distance made contact easier to avoid, the insider said. With Harry and Meghan now spending more time in Britain, however, that separation could become much more difficult to maintain. Harry, Meghan, Archie, and Lilibet reportedly arrived in Birmingham, England, by private jet on Tuesday, August 26. The reported situation could also affect how William and Kate explain the family rift to their own children.
Prince George, Princess Charlotte, and Prince Louis have grown up hearing about the importance of family relationships, according to the source. The insider believes the children may eventually struggle to understand why they remain distant from their Sussex cousins. "It's going to be very difficult to explain and justify" the estrangement, the source claimed. The insider added that William and Kate have always stressed the importance of getting along. That could make the ongoing divide even harder to explain now that Harry and Meghan live much closer.
The reported olive branch does not mean Kate expects William to erase everything that happened between the brothers. Harry and Meghan stepped down as senior working royals in 2020. The couple later spoke publicly about their experience within the royal family and released their Netflix docuseries, "Harry & Meghan," which explored the tensions surrounding their departure.
#prince

2 months ago
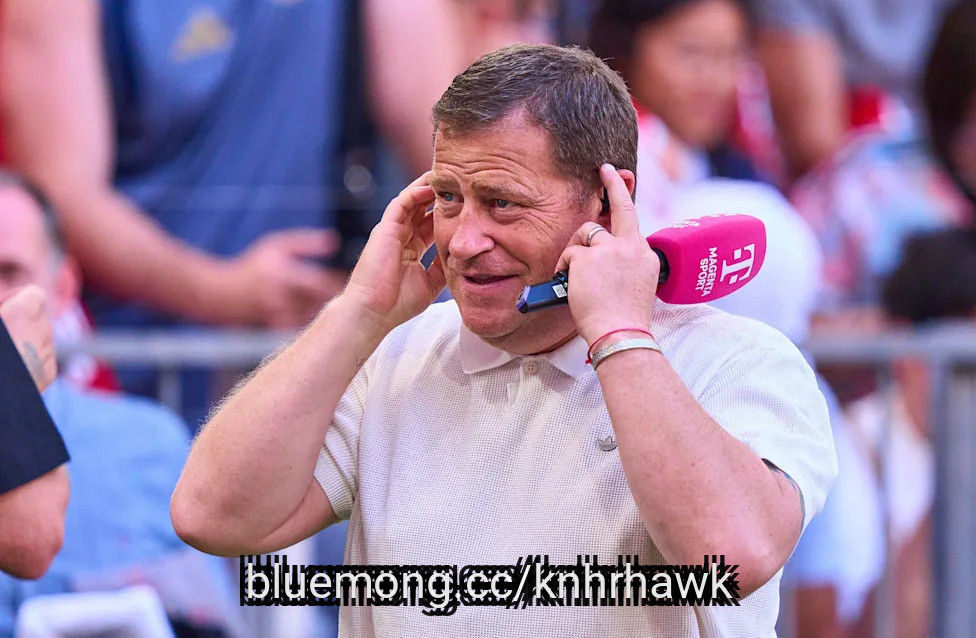
Michael Reschke believes Max Eberl has done enough to justify his new contract at Bayern Munich, and his ***** sment carries plenty of weight given his own history at the club.
Reschke joined Bayern Munich in 2014 as the club's first technical director, following 35 years at Bayer Leverkusen. He spent three seasons in Munich before leaving in 2017 to become sporting director at VfB Stuttgart. During his time with Bayern Munich, he was heavily involved in squad building and scouting.
Now, Reschke is backing Eberl after Bayern Munich extended his contract through 2029.
"If I look purely at Max's record, then we have a top team that plays exciting football. He's brought in one of the best coaches in the world, someone you simply have to admire, and who is a gift to FC Bayern. Overall, his transfer policy is sound. That there are internal discussions about one or two personnel decisions is just business as usual at a club like FC Bayern. The squad is extremely well-planned and of the highest European standard. There's a lot I really like about it," Reschke told Abendzeitung.
Reschke's argument is ultimately about looking at the bigger picture.
#bayern #like

2 months ago
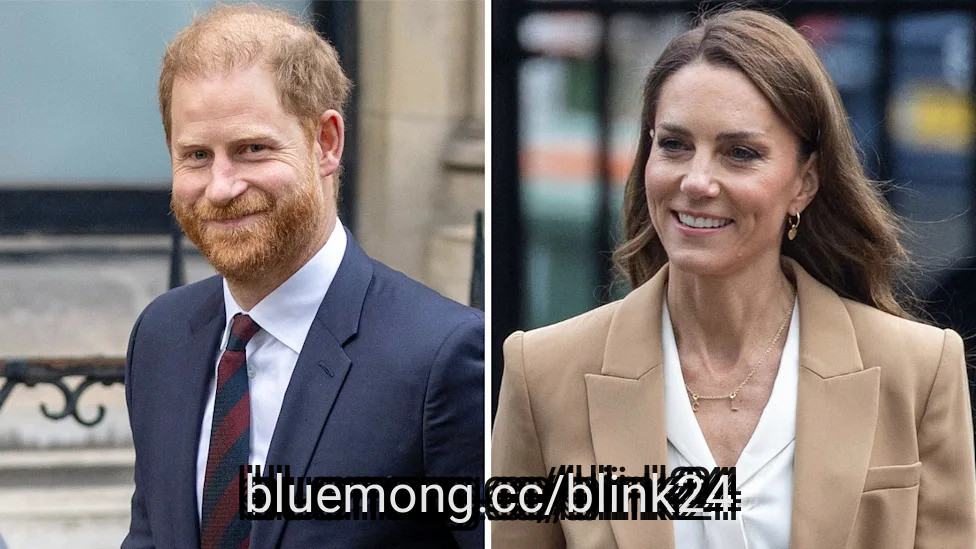
Prince William and Princess Kate's children might not have met up with Prince Harry and Meghan Markle's kids during their recent trip to the U.K., but now that the Sussexes have officially moved back to England, that could soon change.
"Kate's telling [William] that the children deserve the opportunity to get to know their cousins," a source tells Closer. "It was one thing when Archie and Lilibet were on another continent. It was easy to make excuses then. But now, they will be so close."
On Tuesday, August 26, the BBC reported that Harry, 41, and Meghan, 45, and their children, Prince Archie, 7, and Princess Lilibet, 5, touched down in Birmingham, England via private jet.
The Wales' ongoing estrangement from the Sussexes "is going to be very difficult to explain and justify to" Prince George, 13, Princess Charlotte, 11, and Prince Louis, 8, the source notes. "Especially when William and Kate have always emphasized how important it is for them to get along and now here is this example of the adults not being able to make peace."
Francis Dias/NEWSPIX INTERNATIONAL / MEGA
#prince #lilibet

2 months ago
Coca-Cola (NYSE: KO) is one of the best-known companies in the world, thanks to its namesake beverage brand, so it needs little introduction. However, what's most impressive right now is the stock's performance. It is up 28% over the past year, as of this writing. The average consumer staples stock is only up 5% over that span. Even the S&P 500 index (SNPINDEX: ^GSPC) is "only" up 20%. After a run like that, is Coca-Cola a buy, hold, or sell?
Coca-Cola is a well-run business. It is one of the world's largest consumer staples companies. It is globally diversified and has industry-leading capabilities in distribution, marketing, and innovation. The company's fundamental strength is evident in its status as a Dividend King, with 64 consecutive annual dividend increases. The only consumer staples peer with a better record is Procter & Gamble (NYSE: PG), but P&G doesn't make food. So, Coca-Cola is the food company with the best dividend record.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
If you want to own industry-leading businesses, Coca-Cola should be on your short list. And, with an above-market yield of 2.4%, you could easily justify adding it to your portfolio. That's particularly true given recent results, with organic revenue growth of 6% in the second quarter of 2026, even as consumers tighten their belts. In fact, Coca-Cola raised its full-year guidance despite the broader food industry's struggles.
Certainly, if you have owned Coca-Cola for years, selling it right when it is performing so well as a business probably isn't something you should be considering. Unless, of course, the stock's valuation was running ahead of its historical norms. But that's not the case.
#staples

2 months ago
Palantir shares gained 7.7% on September 3, the same day PwC US expanded an alliance built around enterprise AI, M&A, and ERP modernization. The companies described an AI-native deals platform intended to execute transactions up to 50% faster and cut one-time costs by as much as 45%, but disclosed no new contract value. The same day, Globant introduced a MuleSoft AI Pod for Salesforce integration. Palantir Technologies Inc. (NASDAQ:PLTR) and Globant S.A. (NYSE:GLOB) are packaging expertise around software in very different ways.
Palantir's bull case is productized delivery. PwC can bring industry relationships and implementation capacity, while Foundry and AIP remain the recurring platform. Palantir's Q2 revenue rose 93% to $1.94 billion, including 149% growth in U.S. commercial revenue, so the alliance lands on real momentum. Arrowstreet Capital held 20,517,115 shares at June 30 after increasing its stake by 97%.
The valuation is the obvious counterweight. A partnership announcement without disclosed revenue cannot by itself justify a large daily move. Receivables concentration, stock-based compensation, and competition from clouds and consultants deserve attention. Hedge-fund breadth had already weakened: Insider Monkey counted 86 funds holding Palantir at June 30, down from 96 at March 31.
Globant's AI Pod offers a more explicit delivery unit. Configurations support roughly six, 12, or 24 integration flows or APIs per month, and the company cited benchmarks including up to 80% automation and 15% to 25% faster time to value. That makes capacity tangible. Twenty-three hedge funds held Globant S.A. (NYSE:GLOB) in Q2, down from 25 in Q1. Pzena Investment Management reported 3,859,718 shares after adding 31%.
Globant's problem is that reusable pods can still be labor businesses. The service remains on a waitlist, the benchmark outcomes are not guaranteed customer results, and AI may pressure billing rates even as it improves productivity.
#glob


2 months ago
Vertiv, Applied Optoelectronics, and Innodata entered September well below their 2026 highs despite strong operating growth. The pullbacks do not make them interchangeable bargains. Vertiv Holdings Co. (NYSE:VRT) sells power and cooling, Applied Optoelectronics, Inc. (NASDAQ:AAOI) supplies optical transceivers, and Innodata Inc. (NASDAQ:INOD) provides data engineering and model-evaluation services.
Vertiv's second-quarter sales rose 24% to $3.27 billion, adjusted operating margin expanded 410 basis points to 22.6%, and adjusted free cash flow reached $925 million. The bull case is rising power and thermal content per AI rack. The bear case is project timing, supply congestion, and expectations built around long-duration demand. Insider Monkey counted 112 hedge funds holding Vertiv Holdings Co. (NYSE:VRT) in Q2, up from 96 in Q1. Cliff Asness's AQR Capital reported 2,686,683 shares, 0.5% more sequentially.
Applied Optoelectronics posted record revenue of $191.9 million, while 800G volume more than doubled from Q1. Management expects 800G and 1.6-terabit demand to exceed production capacity through mid-2027. That capacity ramp is the bull case; a 27.7% GAAP gross margin, a $22.8 million GAAP loss, customer concentration, and execution are the bear case. Fifty-four hedge funds held Applied Optoelectronics, Inc. (NASDAQ:AAOI), down from 55. Value Aligned Research disclosed 1,595,124 shares, 26% more sequentially.
Innodata's revenue grew 58% to $92.1 million and adjusted EBITDA rose 92% to $25.4 million. Its reusable data sets and evaluation work can expand margins, but large-customer dependence and rapidly changing model-training methods create risk. Twenty-five hedge funds held Innodata Inc. (NASDAQ:INOD), up from 20. Mitch Rubin's RiverPark Advisors reported 2,042 shares, 18% more than in Q1.
AAOI's August 14 short-interest settlement showed 10,421,985 shares sold short, equal to 12.81% of float, with 0.69 days to cover..The elevated short-float percentage signals substantial bearish positioning, while the low days-to-cover ratio suggests shorts could cover relatively quickly at recent trading volumes.Vertiv has the strongest cash generation, AAOI the sharpest capacity upside, and Innodata the lightest physical footprint. A buying opportunity exists only if margins, customer diversification, and cash conversion justify each stock's remaining expectations. The risks also differ in timing. Vertiv can lose on delayed data-center construction, AAOI can lose during the manufacturing ramp, and Innodata can lose when a major customer changes vendors or training methods. Investors should therefore avoid using distance from a high as valuation ******* ysis. Order conversion, gross-margin durability, customer concentration, and diluted share growth are the comparable checkpoints. The pullback improves entry prices, but only operating evidence can establish value. Balance-sheet resilience matters most when capacity plans meet a weaker cycle.
#innodata




