50 mins. ago
A $300,000 investment in SCHD grew to $468,150 over five years versus $573,900 in VOO, leaving a $105,750 gap driven by missing big tech.
SCHD's dividend quality screen kept out the tech giants that led the market, yet that same tilt powered its 23.86% one-year return.
SCHD suits retirees drawing income today, but younger investors should know the yield cost a $300,000 account over $100,000 in five years.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Putting $300,000 into the Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) on October 1, 2021 left a holder with $468,150 by October 5, 2026. The same money in the Vanguard S&P 500 ETF (NYSEARCA:VOO) grew to $573,900. That leaves a shortfall of $105,750.
#nysearca #Dividend #income #same

5 hours ago
Dividend-paying stocks are taking a beating as surging Treasury yields make bonds a more competitive income source, creating a difficult environment for baby boomers who lean on dividend funds and individual stocks to cover living expenses in retirement.
Utilities, real estate, and materials have all experienced share-price declines as climbing bond yields have drawn income-seeking investors away from dividend stocks. The 10-year Treasury yield has remained north of 5%, recently hovering between 5.2% and 5.3%, while the 20-year has hit 5.68% and the 30-year has reached 5.62% — marks last seen more than two decades ago, according to Benzinga.
The pain shows up clearly in fund performance. The Invesco S&P 500 High Dividend Low Volatility ETF (SPHD) lost 7.59% over the trailing month, and the iShares Select Dividend ETF (DVY) shed 6.02% in the same window, according to CNBC. The Vanguard High Dividend Yield Index ETF (VYM) gave back 3.85% over the past month. The WisdomTree U.S. Quality Dividend Growth Fund (DGRW) stands apart, with its heavy tilt toward technology helping limit its one-month loss to just 0.81%.
The Federal Reserve raised its overnight rate by a quarter percentage point on Sept. 16, and markets are pricing in additional increases, keeping pressure on rate-sensitive dividend sectors. The 10-year yield touched 5.342% and the 30-year reached 5.683%, their highest marks in 24 years, driven in part by rising public debt, geopolitical tensions, and the prospect of a prolonged high-rate environment.
Despite the pressure, financial advisors caution retirees against making reactive moves. "The worst thing that a retiree could do is sell a high-quality dividend payer at depressed prices to chase income somewhere else in the stock market just to get higher yield," Timothy Chubb, chief investment officer at Girard, a Univest Wealth Division, told CNBC. Chubb said he would rather own a company growing 4% to 5% annually with a 3% dividend yield than pursue an 8% yield from a deteriorating business.
#Dividend #yield #month #treasury
9 hours ago
FYEE beat JEPI on a $100,000 investment in 2026, paying $7,023 versus $6,070, but FYEE's quarterly payout has fallen from $0.82 to $0.56 per share.
JEPI's monthly distributions better match recurring expenses for retirees, while FYEE's quarterly schedule suits investors who reinvest or can wait between payments.
FYEE's lower share price ($30 vs. JEPI's $56) means $100,000 buys nearly twice as many shares, which is why it delivers more cash despite lower per-share payouts.
Building a portfolio and living off one are two completely different skills, and almost ***** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
The JPMorgan Equity Premium Income ETF (NYSEARCA:JEPI) built its following on a simple promise. It holds lower-volatility U.S. stocks, adds income from S&P 500 call-option premium, and sends a check every month. JEPI holders value that rhythm, and JEPI remains the default name in covered-call income. On an identical $100,000 investment this year, though, the Fidelity Yield Enhanced Equity ETF (CBOE:FYEE) has paid more cash while writing far fewer checks.
#income #quarterly
9 hours ago
SmartAsset and Yahoo Finance LLC may earn commission or revenue through links in the content below.
During most of the decades you are preparing financially for retirement, you are likely focused on saving as close as you can get to the recommended amount, without worrying too much about the details. As you approach retirement, however, it's a good idea to look more closely at what might be a realistic retirement budget. At age 62, with $890,000 in a 401(k) account, $115,000 in a Roth IRA and accounting for Social Security benefits, you can likely generate enough income to cover typical retiree lifestyle expenses. Your individual needs may vary, of course, but there are likely moves you can make now and in retirement to give you the flexibility you'll need to fund a comfortable and secure retirement.
Consider speaking with a financial advisor for help building an effective retirement strategy.
A typical retirement budget starts with the income side and Social Security benefits represent an important part of that for a large majority of retirees. Social Security is lifelong, guaranteed by the U.S. government and includes annual cost-of-living adjustments to keep up with inflation. The amount of your specific benefit is controlled by your work history and age at claiming. ****** uming your current income is $90,000 annually, here are estimates of your annual Social Security benefit based on your age when you start claiming benefits:
Age
#annual

9 hours ago
GNL paid out more in dividends than it earned in operating cash for four straight years and has already slashed its quarterly dividend from $0.53 to $0.19; PSEC's NAV fell from $6.56 to $5.71 while distributions exceeded net investment income.
IEP carries a 30% yield but posted net losses every year from 2019 through 2025 and slashed distributions from $2 to $0.50 per quarter while units dropped 66% over five years.
BEP and CWEN both rely on billions in annual financing inflows to fund distributions, with BEP's 2025 capex hitting $6.7 billion against just $1.5 billion in operating cash flow.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
One stock on this list has a forward yield of about 30%. For a retiree, a number like that looks like a solid paycheck. A high yield only means something if the payout is sustainable, and each of the five names below has spent years sending out more cash than the business brought in.
#distributions #operating #slashed

12 hours ago
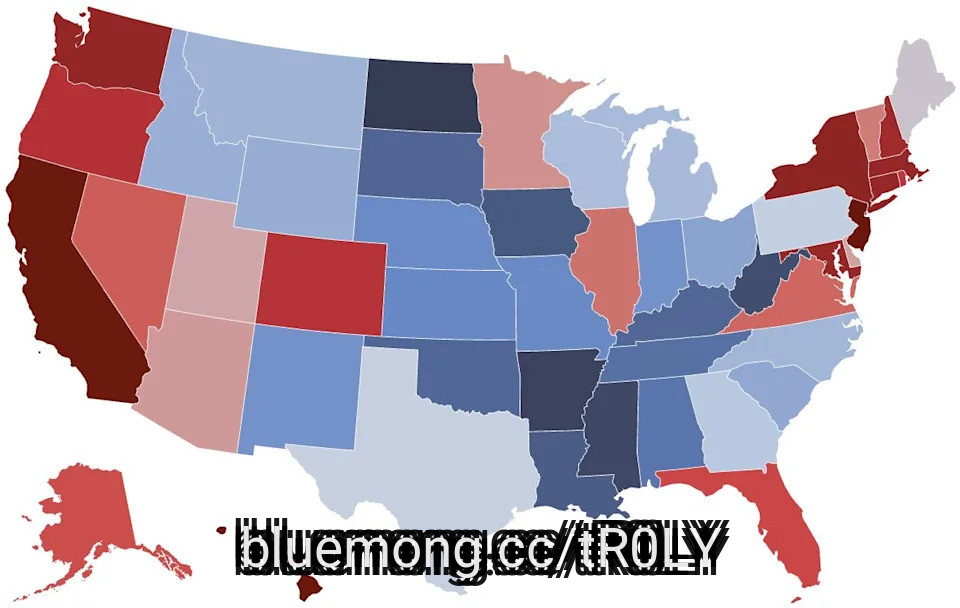
A typical single retiree needs about $898,000 invested for a comfortable retirement, but $1,000 a month in annuity income can reduce that to about $598,000.
Because part of your savings would be used to buy the annuity, these figures show what must remain invested, not your total savings target.
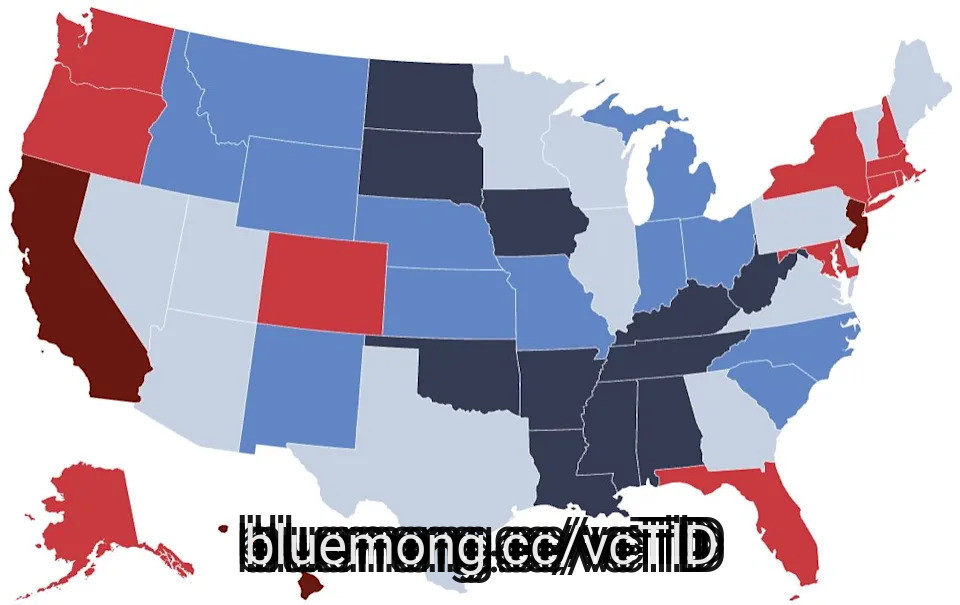
With $2,000 a month in annuity income, the remaining nest egg ranges from about $44,000 in North Dakota to about $418,000 in New Jersey.
For retirees, an annuity can meaningfully shrink the nest egg needed for a comfortable retirement—but only after you spend down some savings to buy the annuity.
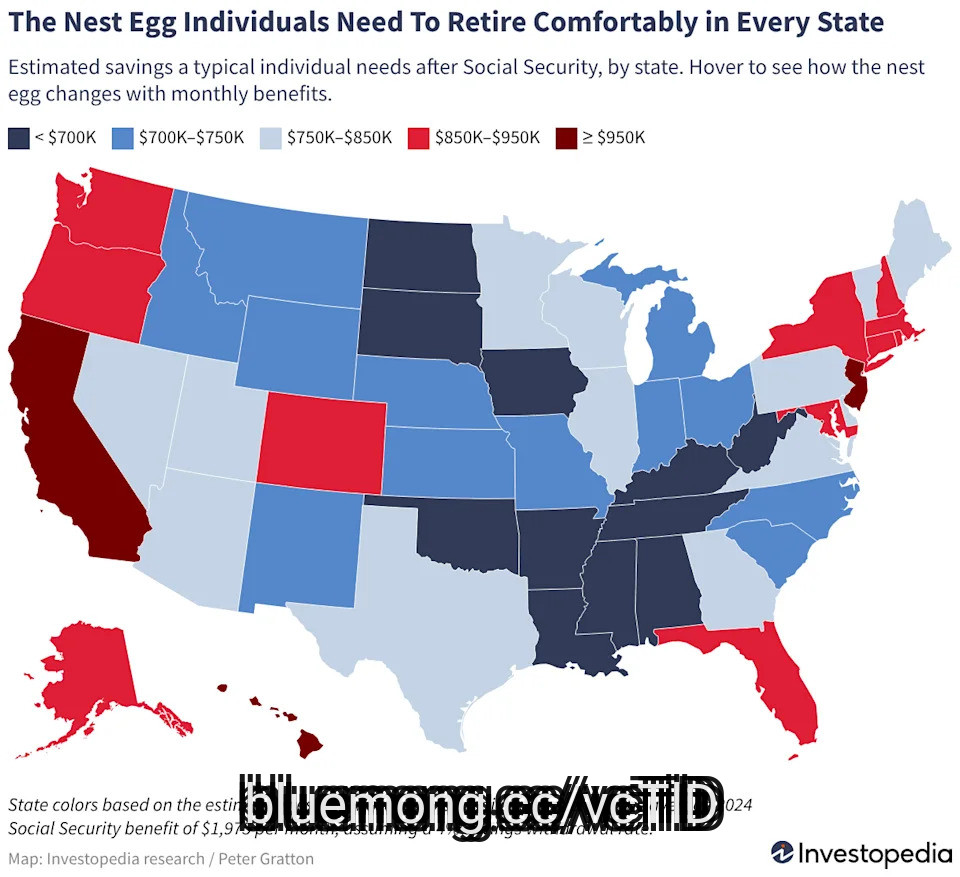
A typical single retiree age 65 or older needs about $898,000 saved to fund a comfortable retirement after accounting for roughly $23,700 a year in Social Security, according to an Investopedia ***** ysis of federal data. Across the 50 states and Washington, D.C., that figure ranges from about $644,000 to nearly $1.02 million.
#Retirement #invested

12 hours ago
A $100,000 split equally across KO, ABBV, and CVX plus two others yields a blended 3.72%, generating $3,715 in annual passive income.
Realty Income (O) leads the group at a 6.04% yield, paying monthly dividends raised for 115 consecutive quarters on 98.8% occupancy.
Five industries fund the income stream, so a weak year in oil, pharma, or ****** et management hits only a fraction of total payouts.
Building a portfolio and living off one are two completely different skills, and almost ****** ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Retirement changes how income works on the day the paychecks stop. Social Security covers part of the monthly bill, and the rest has to come from savings, an annuity, or a portfolio that pays cash on a schedule. Selling shares to cover groceries works fine until a bear market forces those sales at bad prices. Dividends let a retiree collect income and keep the same number of shares.
#income #works #five

13 hours ago
JNJ and PG both trade at 21x forward earnings, but J&J's 46% payout ratio versus P&G's 62% signals stronger long-term dividend coverage.
P&G carries a $1.4 billion after-tax earnings headwind into fiscal 2027, while J&J has already absorbed its Stelara biosimilar competition.
J&J's 10-year share price gain of 181% nearly doubled P&G's 117%, with management targeting double-digit earnings growth by decade's end.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Johnson & Johnson (NYSE:JNJ) orProcter & Gamble (NYSE:PG): If someone saving for retirement could hold only one Dividend King for the next 20 years, which one should it be? My pick is Johnson & Johnson, and the gap is wider than the yields suggest. Both stocks trade near 21 times forward earnings (P&G at 21), so valuation is effectively a tie. The decision comes down to three things that matter more to a retiree: dividend coverage, durability and structural risk.
#trade


13 hours ago
Even famed "bond king" Bill Gross is warning investors about the risks of owning longer-term bonds, arguing that excessive debt and current macroeconomic conditions have made them increasingly risky. But his recommendation comes with one important exception.
In a Sept. 30 op-ed for the Financial Times, Gross, who co-founded ***** et management giant Pacific Investment Management Company (PIMCO), put it bluntly: "Don't own bonds."
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 reasons why retirees can't afford to waste time
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
#gross #bill #bonds

16 hours ago
A 62-year-old retiree can withdraw up to $66,500 annually from a 401(k) at just 12% federal tax, moving roughly $532,000 before RMDs begin.
RMDs force a $1.2 million account holder to withdraw $45,283 in year one, potentially pushing effective tax rates to 41% when Social Security is included.
Leaving $900,000 untouched grows it to roughly $1.7 million by 73, creating a first RMD larger than the current 73-year-old's and repeating the same tax trap.
Building a portfolio and living off one are two completely different skills, and almost ******* ody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Picture two retirees. One is 62 with $900,000 in a traditional 401(k). The other is 73 with $1.2 million. Most people would take the bigger account. The smaller one is worth more because the 62-year-old still determines when that money gets taxed and at what rate. The 73-year-old has already gave that decision to the IRS.
#year #rmds
17 hours ago
Florida exempts a $600,000 IRA from Medicaid's $2,000 **** et limit once the account enters payout status through RMDs or regular distributions.
Every IRA distribution counts as income against Florida's $2,982 monthly cap, and nearly all of it goes directly to the nursing home.
A named IRA beneficiary keeps the remaining balance out of probate, blocking Florida's estate recovery claim under Fla. Stat. § 409.9101.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
A Florida retiree entering long-term care with $600,000 in her IRA looks like an automatic Medicaid denial. A single applicant there can't hold more than $2,000 in countable **** ets. Thankfully, Florida's IRA Medicaid rules leave a narrow opening: once a retirement account is in payout status, the state can exclude the balance from the **** et count. This means withdrawals still count, each distribution is treated as income, and that income ends up paying most of her nursing home bill.
#Florida


17 hours ago
The size of your Social Security check changes the nest egg you need more than any differences between states.
Under the 4% rule, each additional $100 a month in benefits cuts the savings a single retiree needs by about $30,000, regardless of state.
A maximum earner who delays to 70 can cover the average comfortable budget on Social Security alone, with essentially nothing saved—but very few qualify for the maximum benefit.
For a single retiree, your monthly Social Security benefit shapes the savings you need more than your address does—there's no second check to fall back on.
But regional costs of living matter, too. An Investopedia ******* ysis of federal cost and benefit data found that the savings a typical single American age 65 or older needs for a comfortable retirement is about $898,000. The least expensive state, North Dakota, runs about $644,000, while the priciest, New Jersey, costs about $1.02 million—a spread of about $375,000.
#security #check #retiree

6 days ago
What theory did Bank of America economists propose about older workers' retirement?
What percentage of early retirees cited financial reasons in the Allianz study?
How many women have been executed in the U.S. in the last 50 years?
Full Summary
Older Americans make up an ever-larger share of the workforce, a trend that dates to the 1990s.
#americans
What percentage of early retirees cited financial reasons in the Allianz study?
How many women have been executed in the U.S. in the last 50 years?
Full Summary
Older Americans make up an ever-larger share of the workforce, a trend that dates to the 1990s.
#americans
16 days ago
No matter how well you plan for retirement, there are surprises that could throw you for a loop. The stock market might crash unexpectedly. Your healthcare costs might increase. Or, worse yet, you could end up needing long-term care at some point.
But one hiccup you should know to plan for is inflation. Over time, the cost of living is likely to rise. And if you aren't prepared, you could easily end up losing out on buying power. These two adjustments to your retirement plan could help you avoid that fate.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
It's fairly common for retirees to reduce their stock holdings to minimize risk in their portfolios. But while it's OK to de-risk to some degree, you don't want to dump your stocks completely. Doing so could cause your portfolio to trail inflation, leading you to lose buying power and putting your savings at risk of being depleted.
If you're not comfortable holding individual stocks in retirement, buy shares of an S&P 500 exchange-traded fund (ETF). This effectively gives you exposure to the market. Or load up on dividend ETFs that generate steady income.
#plan #market

16 days ago
The 'half-a-loaf' plan gifts roughly half of excess ***** ets to children, then uses a Medicaid-compliant annuity to bridge the penalty period.
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly
17 days ago
Moneywise and Yahoo Finance LLC may earn commission or revenue through links in the content below.
The future of America's social safety net is hanging in limbo as the underlying trust fund reserves for Social Security benefits will be depleted in just six years.
And not only is the U.S. government not offering solutions for the funding crisis, it's actually making the problem worse — even if there's money on the table for retirees as a result.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
A single line on your car insurance policy could be inflating your premium by up to 30% — here's what to change
#actually #moneywise #bezos #commission
17 days ago
You've been working for decades and are eagerly anticipating your retirement years, when you'll finally be free to do whatever you want — whether that's travel, golfing, hiking or volunteering.
But while you may be looking forward to ending your worklife, you may not have yet created a strong enough plan. A 2026 study from the Employee Benefit Research Institute, for instance, found that only half of retirees rated their household financial well-being as at least very good, while two in five said healthcare costs have been higher than they expected. Two in five also said their overall spending in retirement was more than they expected.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#bezos
17 days ago
HDV has outpaced VYM by nearly 9 points year-to-date in 2026 while paying a 3.34% yield versus VYM's 2.20%.
HDV's 75-stock tilt toward energy, healthcare, and staples drives its 2026 edge but can lag equally in growth-led markets.
Taxable investors switching from VYM should redirect new contributions into HDV rather than selling lots with large embedded capital gains.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
If you own the Vanguard High Dividend Yield ETF (NYSEARCA:VYM), you own it for a good reason. VYM tracks the FTSE High Dividend Yield Index, holds roughly 500 above-average payers, and delivers a broad, cheap slice of dividend-paying American stocks. It is one of the most widely held income ETFs on the market, and for buy-and-hold investors who want a diversified basket of yielders without thinking too hard about it, VYM has done its job. But in 2026, VYM is losing ground to a much smaller, more concentrated peer from BlackRock that pays a higher yield and follows a very different rulebook.
#same
17 days ago
JEPI, DIVO, and GPIX each pay near 8% monthly yields while growing share price by writing calls on only a portion of holdings.
GPIX has beaten SPY with an 80% return since its 2023 launch by capping its options overlay at just 25 to 75% of the portfolio.
DIVO's tactical options sleeve delivers a lower 6% yield but drives 72% five-year price appreciation, nearly matching SPY's gains.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Covered call ETFs have a reputation problem. For years, the category was defined by funds like QYLD and XYLD that wrote at-the-money calls on entire index portfolios, harvested rich premiums, and quietly bled principal every time markets rallied. Investors got their monthly check and watched their share price drift lower. That is the trap worth avoiding.
#gpix #calls #lower #years
17 days ago
A $10,000 SPY investment at its 1993 launch would have compounded to $312,667 today, representing a 3,027% gain without adding a single dollar.
SPY's 0.0945% expense ratio costs roughly three times more than VOO or IVV, a gap that quietly compounds against long-term buy-and-hold investors.
RSP owns the same 500 stocks as SPY but weights each equally, cutting megacap dominance and serving as a hedge against a leadership rotation.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A $10,000 stake placed in the SPDR S&P 500 ETF (NYSEARCA:SPY) on its opening day in January 1993 would be worth roughly $312,667 today. That works out to a 3,027% **** ulative gain, or about 10.8% a year compounded across 33 years. No stock picking, no market timing, no additional contributions.
#roughly #years #january

17 days ago
A home Medicaid excludes from **** et tests during life becomes fully exposed to estate recovery after death, potentially consuming most of an inheritance.
Transfers of a home within 60 months of a Medicaid application trigger a penalty period, and a stroke can eliminate the legal capacity needed to act.
Penalty-free exceptions exist, including spousal transfer, caregiver-child, and protected-relative rules, but qualifying circumstances must be in place well before a crisis.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
An 82-year-old widower has a stroke. From the hospital he moves to rehabilitation, then to permanent nursing-home care. His paid-off house is worth $340,000. His daughter asks the elder-law attorney whether they can deed her the house or drop it into an irrevocable trust before Medicaid pays a dime. The answer is the one no family wants to hear: probably not, because Dad no longer has the capacity to sign, and his durable power of attorney authorizes bill payment but not gifts or trust transfers.
#home #stroke #free

17 days ago
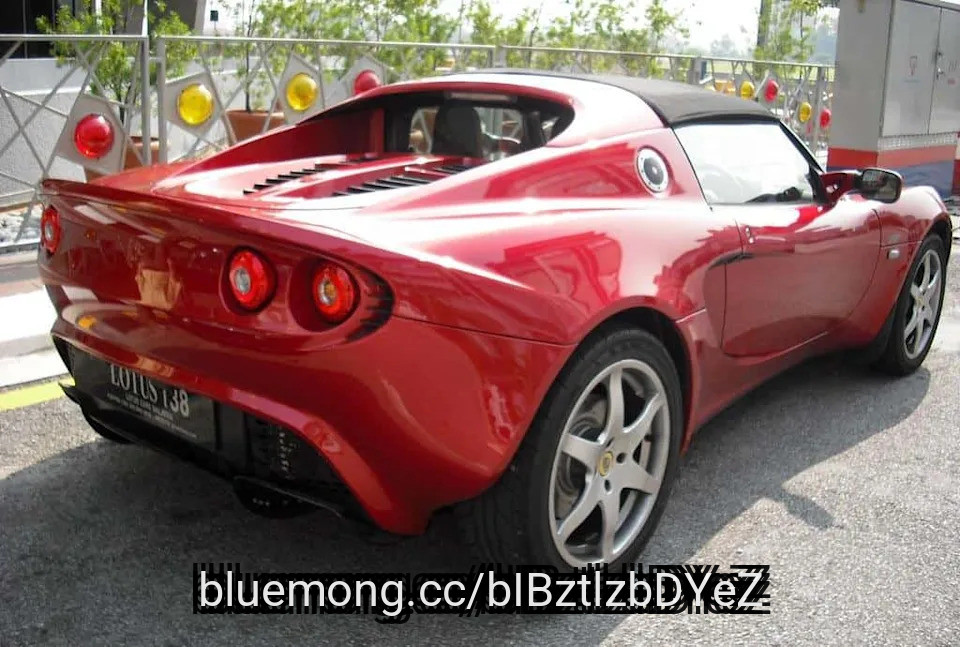
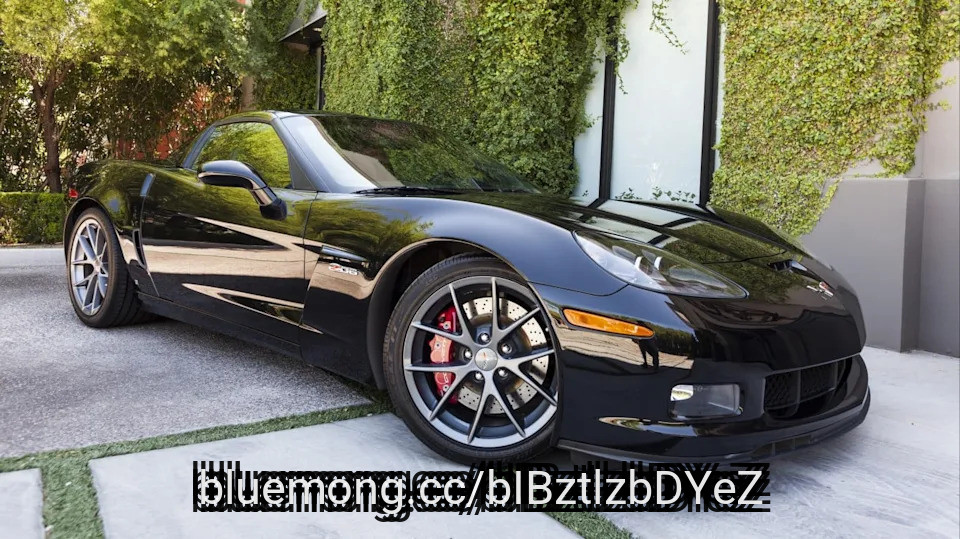
Ramsey warns that depreciating ****** ets like cars erode wealth, and 84% of millionaires credited ditching car payments as key to building it.
A $30,000 car loses roughly $18,000 in value within five years, and average annual ownership costs hit $11,577, making cars a major wealth drag.
Since Micah maxes retirement accounts, carries zero debt, and pays cash, buying the sports car is defensible if he maintains those financial habits.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A caller to the Dave Ramsey Show recently sparked a pointed conversation about cars, wealth, and what it actually means to earn a solid income. The caller was Micah, a 24-year-old earning $80,000 per year. He maxes out both his 401(k) and IRA and carries zero debt. His question was simple: he has $30,000 in cash and wants to put it toward a 2019 Nissan 370Z as a weekend car, but he wonders whether investing the money instead would serve him better long-term.
#zero

17 days ago
SCHD delivers nearly double VIG's forward yield at roughly 3% compared to 1.7%, making it the stronger cash anchor for retirees funding withdrawals today.
Despite radically different portfolios, both funds produced nearly identical 10-year returns: VIG at 243% versus SCHD's 237%.
With the 10-year Treasury at 5%, rising rates are punishing VIG's growth tilt, and SCHD leads year-to-date by a wide margin of 25% to 8%.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Retirees weighing a dividend anchor keep landing on the same two funds: Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) and Vanguard Dividend Appreciation ETF (NYSEARCA:VIG). They look like siblings but diverge sharply under the hood. SCHD screens hard for cash-flow quality and pays a meaningfully higher current yield. VIG buys only companies with 10-plus consecutive years of dividend increases and explicitly kicks out the highest-yielding quartile. That single rule sends the two funds toward very different portfolios, and it is showing up in the returns.
#Dividend #same #nearly #cash

17 days ago
TIPS held in taxable brokerage accounts generate phantom income from inflation-adjusted principal, potentially pushing up to 85% of Social Security benefits into taxable income.
30-year TIPS currently yield 2.96% above inflation, but account placement determines how much of that real return retirees actually keep after taxes.
Holding TIPS inside a traditional IRA defers inflation-adjustment taxation until withdrawal, shielding annual principal increases from the Social Security provisional income formula.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
A 71-year-old retiree did what the textbooks suggest. He built a ladder of Treasury Inflation-Protected Securities in his brokerage account to keep inflation from quietly eating away at retirement. The timing looks unusually attractive. As of August 28, Treasury's real-yield curve put 10-year TIPS at 2.42% and 30-year TIPS at 2.96%. Those are yields above inflation for an investor buying at current market prices and holding to maturity. That 2.96% is a real yield, meaning it sits on top of the inflation adjustment rather than competing with the inflation rate itself.
#real #taxable
17 days ago
Without a signed, prospective contract, Medicaid treats family caregiver payments as gifts, exposing $60,000 in payments to a six-month nursing home ineligibility penalty.
A defensible care agreement must be signed before services begin, specify duties and market-rate pay, and be backed by time sheets and traceable payments.
At 20 documented hours per week, $2,500 monthly works out to roughly $29 per hour, defensible against the 2025 national median caregiver rate of $35.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a widow in her 80s who pays her adult daughter $2,500 a month for two years to handle bathing, meals, medications, driving to appointments, and overnight supervision. The care is real. The daughter cuts back her own job to provide it. One year later, mom breaks a hip, lands in a nursing home, and applies for institutional Medicaid. The caseworker pulls five years of bank statements, spots $60,000 in recurring payments to the daughter, and finds no signed agreement, no time sheets, no invoices. In that state, the agency treats every dollar as an uncompensated transfer, effectively a gift.
#signed #daughter
17 days ago
Leaving $650,000 in IRAs untouched for 11 years grew the balance to $1.11 million, forcing a $42,000 first-year RMD on top of pension income.
The couple missed 11 years of Roth conversion opportunities at the 12% rate, pushing RMD dollars into the 22% bracket instead.
When one spouse dies, the survivor files under single brackets where the 22% rate starts at $50,400, making the same RMD far more costly.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Let's start by considering a couple retiring at 62. His pension covers the mortgage, the groceries, the property tax, and the trip to see the grandkids twice a year. Two traditional IRAs, hers and his, hold a combined $650,000 on the day they stop working, and they never take a distribution. Now imagine that eleven quiet years have passed, and then the first required minimum distribution letter arrives, followed by a second, and the number attached to those letters is larger than either of them planned for.
#iras
17 days ago
Gov. Abbott says Texas data centers "dug their own grave" by expanding too fast, with fewer than 10% responding to a state electricity demand survey.
Claiming Social Security at 63 instead of 67 permanently locks in just 75% of the full benefit, costing a $2,500 earner roughly $625 monthly.
A long-term ground lease can bridge the income gap to delay Social Security claiming, and passive rental income generally avoids the Social Security earnings test.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Texas spent years courting the data-center boom. Now Gov. Greg Abbott says the industry "dug their own grave" by expanding too quickly without winning over the communities expected to host the projects. The backlash is real.
#texas #grave

17 days ago
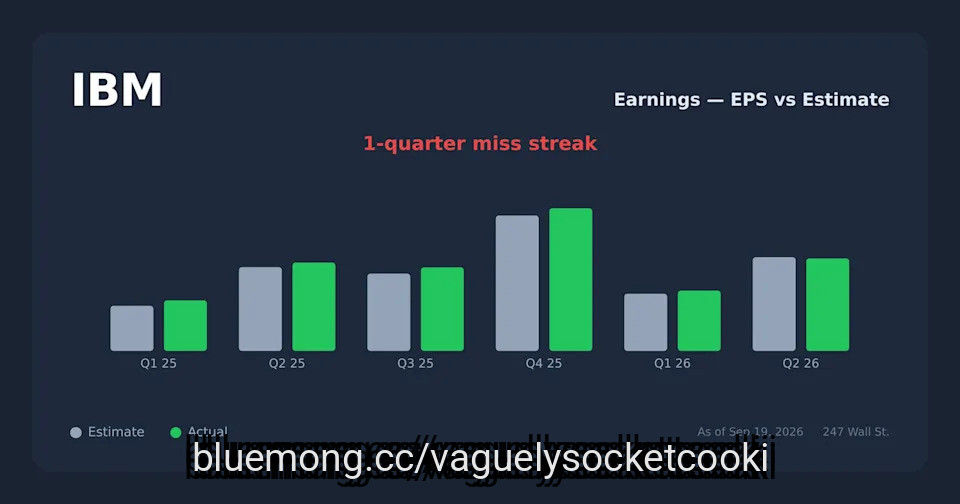
IBM raised its quarterly dividend a single penny, from $1.68 to $1.69, marking its 31st consecutive increase but delivering just $0.04 more annually to shareholders.
Microsoft grew its quarterly dividend from $0.13 to $0.98 since 2010, making it the stronger pick for investors seeking real income growth over IBM's 2.83% yield.
IBM's dividend appears safe, with $14.7B in free cash flow comfortably covering its $6.3B payout, though capital is flowing toward acquisitions, $62B in debt, and quantum computing bets.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and IBM didn't make the cut. Enter your email to see the names that beat IBM. The report is free. Enter your email and see if any of your stocks made the cut.
The headline is easy to sell. IBM (NYSE:IBM) has paid consecutive quarterly dividends every year since 1916 and, with the April declaration, notched its 31st consecutive year of dividend increases. The reality a retiree actually banks is smaller. Much smaller.
#Dividend #year

17 days ago
Owning a $400,000 Villages home costs owners roughly 4.5% annually in forgone investment income alone, before taxes, insurance, or CDD bond payments.
Annual rentals run between $2,200 and $3,000 a month, but renting beats owning only for stays under eight years once all costs are counted.
A 75-year-old facing a forced sale in a narrow buyer pool at 3.98 million existing home sales risks losing the flexibility a lease ending provides.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
At the end of the day, renting versus buying in The Villages comes down to one thing: math. More owners are running the numbers and finding that renting wins on the spreadsheet, so here is what the comparison actually looks like when every line is filled in.
#income

18 days ago
When developers hand governance to residents at build-out, HOA fees spike as homeowners absorb true amenity costs and cover reserve underfunding through special ****** sments.
HOA fee increases in post-transition communities routinely outpace the 2027 Social Security COLA of roughly 3%, squeezing retirees on fixed incomes.
Demand the reserve study, CC&Rs, and community development district bond balance before signing. If the sales office stalls, the pitch was rehearsed, not substantiated.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Readers in their late fifties and early sixties ask weekly: Can I retire to a Margaritaville community, and what will it cost over twenty or thirty years? The brochure sells one version, while the sales center sells another. The real question a retiree should ask is what happens once marketing wears off and the structural issue the sales presentation almost never covers emerges.
#retirees #community #years #sells