1 day ago
The Green Bay Packers are 5-3 after beating the Carolina Panthers by a 27-19 final score on "Thursday Night Football" from Lambeau Field. There were **** ps along the way, especially early and late, but the Packers got three touchdown passes from Jordan Love and six sacks from Jonathan Gannon's defense to power what ended up being a winning performance.
Highlighting the good, the bad and the ugly coming out of Thursday night's win:
Jordan Love during the first three quarters, the adversity defense, and the pass-rush: Love was on fire for the first 45 minutes, completing 26 of his first 33 passes for 262 yards and three scores. He threw a pick early in the fourth quarter, starting a disappointing finish for the offense overall, but the Packers quarterback was terrific for most of the contest, playing on time from the pocket and consistently finding completions. Jonathan Gannon's defense was dominant at times, allowing only three points off three Packers turnovers, and the only three points came after the fumbled opening kickoff that gave the Panthers the ball in field goal range. It took a few crazy conversions for the Panthers to score a touchdown in the second half. The Packers were dominant up front, sacking Bryce Young six times and consistently disrupting the pocket.
The start, and most of the finish: How did the Packers open the game? By fumbling away the opening kickoff, dropping three first-quarter passes and committing a pre-snap penalty. The turnover spotted the Panthers three early points. To Green Bay's credit, the first quarter ended with the Packers leading. During most of the second and third quarters, the Packers were in complete control, leading 20-10 at the half and 27-13 with a chance to dagger the Panthers to start the fourth quarter. But Jordan Love threw a pick on the second play of the fourth, turning the game sharply, and the Panthers eventually scored on a 70-yard drive and had the ball down one score with a chance to tie the game. What should have been a comfortable, two- or three-score win ended up being a nail biter because the Packers made costly mistakes and couldn't run the ball. One more bad: Trey Smack missed an extra point, so the kicking worries continue to linger. The lost point mattered because it kept the Panthers within one score in the fourth quarter.
The run game. The Packers returned Aaron Banks to the lineup at left guard, and Josh Jacobs got a full workload against the NFL's worst run defense entering Week 8, but it wasn't nearly enough to awaken Green Bay's dormant run game. Jacobs turned 21 rushes into only 39 yards, and 18 of the Packers' 66 rushing yards came on a well-executed Savion Williams gadget play. The 25 designed runs to running backs gained all of 48 yards. Jacobs didn't have a run longer than six yards. It's possible the Packers run game just isn't going to happen in 2026. This is a historically bad start -- the Packers are just the 14th team since 1935 to rush for fewer than 500 yards


1 day ago
EJ Gibson was given two options with three seconds left in the game. Catch or run.
In the dying seconds of Ensworth football's game against Montgomery Bell Academy on Oct. 29, junior quarterback Isaiah Hasselbeck located junior tight end Champ Banks to pull within a point of the lead.
Going for the win on a 2-point conversion, Gibson gave his teammates a simple answer.
"Trust me, Give me the ball and I'm going to knock it in," the senior running back said.
The game winning conversion was the cherry on top of 200 rushing yard performance as Ensworth (5-5, 3-2 Division II-AAA East) stunned Montgomery Bell Academy (8-2, 3-2 Division II-AAA East) in a 15-14 victory.
#gibson #going


5 days ago
Former Rep. Mary Peltola is rescheduling several upcoming campaign events after she and her family sustained "minor" injuries in a car crash, her campaign announced Sunday.
"Mary and her family sustained minor injuries but are in good spirits. Unfortunately, per the advice of medical professionals, Mary's upcoming events in Fairbanks and Bethel will be rescheduled for later in the week as she takes time to recover," Peltola campaign manager Cheryl Bruce said in a statement.
"Mary is disappointed that the accident is delaying the start of her Alaska Always Tour, and she is eager to get back on the campaign trail to speak directly with Alaskans about her plan to take on the rigged system and lower costs for working families," Bruce added.
Peltola was en route to the Alaska Federation of Natives' annual banquet Saturday when a vehicle transporting the candidate and her family was struck by another driver, according to the campaign. A spokesperson for the campaign said they had no reason to believe the accident had been politically motivated.
The police department in Anchorage confirmed Sunday that a collision involving three vehicles occurred on evening and those involved sustained "non-life threatening injuries."
#injuries

5 days ago
Former Rep. Mary Peltola is rescheduling several upcoming campaign events after she and her family sustained “minor” injuries in a car crash, her campaign announced Sunday.
“Mary and her family sustained minor injuries but are in good spirits. Unfortunately, per the advice of medical professionals, Mary’s upcoming events in Fairbanks and Bethel will be rescheduled for later in the week as she takes time to recover,” Peltola campaign manager Cheryl Bruce said in a statement.
“Mary is disappointed that the accident is delaying the start of her Alaska Always Tour, and she is eager to get back on the campaign trail to speak directly with Alaskans about her plan to take on the rigged system and lower costs for working families,” Bruce added.
Peltola was en route to the Alaska Federation of Natives’ annual banquet Saturday when a vehicle transporting the candidate and her family was struck by another driver, according to the campaign. A spokesperson for the campaign said they had no reason to believe the accident had been politically motivated.
The police department in Anchorage confirmed Sunday that a collision involving three vehicles occurred on evening and those involved sustained “non-life threatening injuries.”
#mary #sustained #injuries #bruce

12 days ago
The Green Bay Packers got a pair of first half touchdowns from Jordan Love to take a commanding lead, and Jonathan Gannon's aggressive defense confounded Dak Prescott the rest of the way, leading Matt LaFleur's team to a 23-13 win over the Dallas Cowboys on "Sunday Night Football" in Week 6. The Packers have now won three straight games since a 1-2 start.
Highlighting the good, the bad and the ugly coming out of the Packers' primetime win over the Cowboys:
The start on offense, and finish on defense: Jordan Love was picked off on Green Bay's second possession, but the Packers offense scored on three of the four first-half drives, all gaining at least 70 yards. The long, time-consuming drives helped the Packers keep the Dallas offense on the sideline and build a 17-0 lead at the half. But when the Packers offense sputtered over the final 30 minutes, Jonathan Gannon's defense had answers, producing a pair of stops on fourth down in the fourth quarter. The garbage time touchdown meant little. The Packers ended up holding the Cowboys to only 13 points, a winning performance 10 times out of 10.
Love under pressure: Jordan Love's passer rating finished at 74.8, a pedestrian number in today's NFL, but drops drastically affected his final stat line, and Love was excellent when pressured. He found completions on 11 pressured dropbacks. Many of his best throws came on third down against pressure. The Packers started the game converting nine of the first 10 opportunities on third down.
The offensive line: Sunday night was a step backwards for the offensive line, which allowed Jordan Love to be pressured on 45.5 percent of his dropbacks, per Next Gen Stats, and paved the way for a lifeless run game that averaged 2.2 yards per carry. Love was sacked three times, and the Cowboys were credited with eight quarterback hits. In the run game, the Packers didn't have a designed run over six yards, and the three running backs combined to rush 20 times for 36 yards. Matt LaFleur wants to build continuity up front, but it's probably time to see what Kevin Zeitler can do at right guard, and there will be a decision to make on who starts at left guard between Laken Tomlinson and Aaron Banks next week.
#packers #jordan

23 days ago
SCHD yields 3.82% with principal at risk daily, while VIG targets dividend growers built to outpace inflation over a long horizon.
Qualified dividends face tax rates between 0% and 20%, compared to up to 37% for savings interest, a gap that can exceed the difference in yields.
High-yield savings protect dollars with FDIC coverage up to $250,000, but rates float and can drop the moment the Fed cuts.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
High-yield savings rates were holding steady on Oct. 8, 2026, according to Forbes. They are holding at a higher level than a month ago because the Federal Reserve raised its target range in September. Online banks use the federal funds rate's upper bound to price their accounts, and it moved from 3.75% to 4.00% on Sept. 16, 2026 and was unchanged as of Oct. 7. On that date the 4-week Treasury bill, the closest market benchmark for overnight cash, yielded 3.95%. Typical banks pay much less. The FDIC national average 12-month CD rate was 1.73% as of Sept. 1, 2026, and top online banks routinely pay a multiple of that average. Rates differ from bank to bank, so the posted APY at your own bank is the number that applies to you.
#savings #sept

24 days ago
During the second quarter, Pershing Square Capital Management, the hedge fund firm founded by Bill Ackman, initiated positions in Visa (NYSE: V) and Mastercard (NYSE: MA). While their share prices have appreciated in recent months, these businesses traded at attractive valuations at purchase.
Here are three reasons the billionaire investor is bullish on these two S&P 500 stocks.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Ackman's firm believes these are two of the highest-quality businesses on Earth. There are three notable factors supporting this view.
Visa and Mastercard, which connect consumers, merchants, and banks around the world, have developed robust network effects. This makes their platforms almost impossible to disrupt.
#pershing

24 days ago
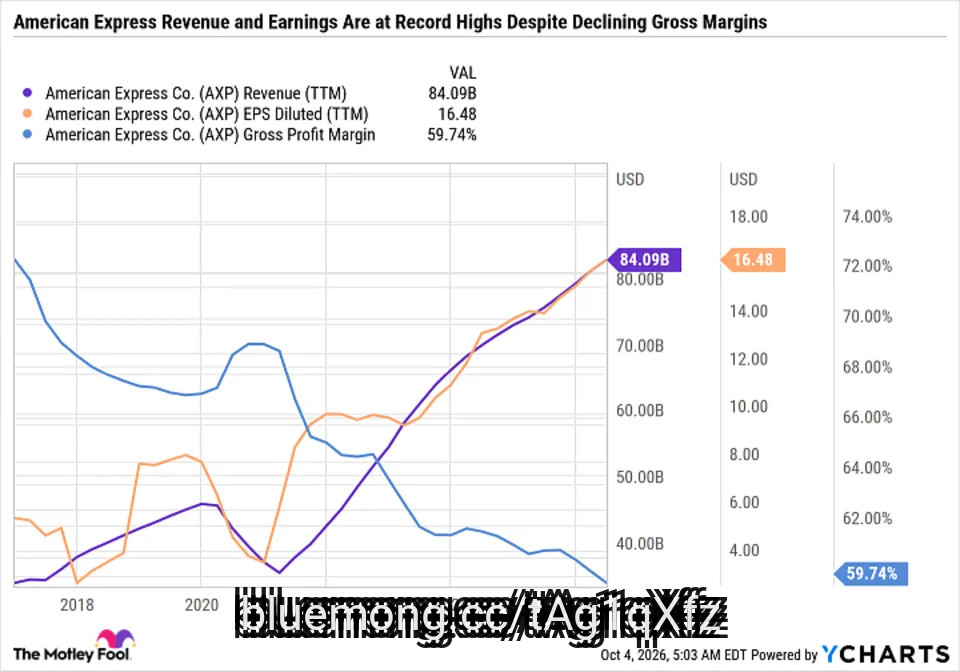
American Express (NYSE: AXP) has been a staple of Berkshire Hathaway's (NYSE: BRKA) (NYSE: BRKB) portfolio for decades -- with Warren Buffett essentially completing purchases of the stock by 1995. Buffett's hand-picked successor -- Greg Abel -- expects American Express to remain a long-term compounder and a core Berkshire holding because it's a business Berkshire understands well and trusts its management team.
American Express also features a growing dividend. It doesn't raise it every year, but even during the 2008 financial crisis, when many banks and financial services companies were slashing their payouts, American Express held its quarterly dividend steady at $0.18 per share.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
American Express has substantially increased its dividend since then. The next payment of $0.95 per share is payable on Nov. 10 to shareholders on record as of Oct. 9.
Here's how many shares of American Express you'd need to generate $1,000 in yearly dividends, and the three levers American Express pulls to reward long-term shareholders.
#signal



24 days ago
Capital One (COF) paid $390M for failing to flag money laundering, then faced suit for closing Trump-linked accounts; JPMorgan (JPM) faces a similar lawsuit.
Fewer than 1% of over 8,000 CFPB debanking complaints alleged political bias, yet federal programs like Operation Choke Point cut off entire industries.
FinCEN withdrew two proposed crypto reporting rules, but compliance teams will stay cautious until courts rule on banks' right to close any account freely.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
American banks are caught between two kinds of punishment. If they miss dirty money, regulators fine them. If they flag it and close the account, they get sued for debanking. Capital One (NYSE:COF) has paid on both sides, and its record shows which way the pressure is moving.
#capital #debanking

24 days ago
The S&P 500 hit a record Tuesday as it rose for a fourth straight day, supported by rising technology stocks, hopes for a positive earnings season and a pause in oil’s recent surge.
The broad-based index closed higher by 0.58%, its first record closing high since Aug. 13. The Nasdaq Composite also jumped 0.45%. It also hit a record high for the second time this week.
The S&P 500 and the Nasdaq’s gains were overwhelmingly powered by gains in tech companies, such as chipmakers Marvell and Broadcom.
Nvidia, the world’s largest public company, also rose and moved closer to becoming the first company to ever reach $6 trillion in market value. Other trillion-dollar tech stocks also rose Tuesday. Microsoft, Amazon, **** eX, Meta Platforms and Tesla shares all traded in the green.
Investors are also looking forward to the start of the third quarter’s earnings season, which begins in earnest next week with the country’s biggest banks reporting their results.
#rose


1 month ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
1 month ago
Gold is the ******* et people buy when they have stopped believing in promises. Then most of them hand it to a bank in another country for safekeeping, which is itself a promise.
That arrangement is older than most of the world's central banks. The Bank of England has provided gold custody services to developing nations for decades, according to Reuters, and it usually works for the simple reason that ******* ody involved has any incentive to argue about it.
Custody is boring. It stays boring right up until two governments claim the same account.
Then the metal in the vault ceases to be a reserve ******* et and becomes a legal exhibit. It does not move, and it does not get sold.
It sits in a basement in London, earning nothing and settling nothing, while lawyers on two continents argue over whose signature counts on the paperwork.
#reuters


1 month ago
JPMorgan Chase (NYSE: JPM) is the largest bank in the U.S., by far. It's a financial giant with robust consumer and commercial segments, and it's reliable in driving growth under pressure. It also pays a growing dividend that yields 1.7% at the current price, and it's a fantastic value addition to any investor's diversified portfolio.
While it's likely to become the first bank stock with a $1 trillion valuation in the near future (it currently sports a $927.5 billion market capitalization), there are smaller digital banks that are likely to grow much faster in the next two years, and probably a lot longer. SoFi Technologies (NASDAQ: SOFI) and Nu Holdings (NYSE: NU) are two of them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
SoFi is a young digital bank that's growing at the rate of a tech start-up, which makes sense, since it's a combination of both -- a classic fintech company.
What started as a loan cooperative for college students has expanded into a comprehensive financial app for anyone seeking an easy-to-use digital platform. It's attracting new members at a fast pace, and its strategy of bringing customers into the ecosystem and getting them to adopt more products is working.
#sofi #bank


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Find out how much you could earn by locking in a high CD rate today. The Federal Reserve cut its federal funds rate three times in 2025. So far in 2026, the Fed has left interest rates alone, and so now could be your last chance to lock in a competitive CD rate before rates move further. CD rates vary widely across financial institutions, so it's important to ensure you're getting the best rate possible when shopping around for a CD.
The following is a breakdown of CD rates today and where to find the best offers.
Generally, the best CD rates today are offered on shorter terms of around one year or less. Online banks and credit unions, in particular, offer the top CD rates.
Today, Saturday, September 19, 2026, the highest CD rate is 4.40%, and it's offered by Happen Bank on its 2-year CD.
#rates #find #offered



1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The FOMC began a new interest rate cycle, raising the federal funds rate a quarter point on Sept. 16. Wall Street traders expect at least one more rate increase before the end of 2026.
The federal funds rate. The Fed. The FOMC. No doubt you've heard and read these terms before. But what do they mean? How does this impact your financial life?
The federal funds rate is the interest rate the government sets for one bank to charge another bank for ultra-short-term loans, usually just overnight. It's actually an interest rate range. Banks negotiate a specific rate with each other within that range set by the Federal Reserve.
The current federal funds rate is now 3.75% to 4.00%.
#advertiser #disclosure



1 month ago
Federal Reserve Chair Kevin Warsh has revealed himself. If not a card-carrying monetarist, he is at least a camp follower. This represents a dramatic change at the Fed, where the past Chairman Jerome Powell repeatedly rejected the basic tenets of monetarism.
This is a welcomed earthquake. After all, there are almost no monetarists left in the world (except for us, and we've been fighting a lonely rearguard action for over 40 years). The Federal Reserve has rejected monetarism consistently — and on the record — because it preferred other models for understanding the economy. In academia, monetarism has been out of fashion for decades. But by his own words, a monetarist is now leading the central bank.
Just what is monetarism? It's a doctrine which holds that money has a major influence on both the level of ***** et prices, economic activity, and the price level. Any discussion of national income determination must, therefore, center on the quantity of money and the banking system, since banks produce most of the money in modern economies. When it comes to monetary policy, its objectives are best met by targeting the rate of growth of the money supply.
Today, most economists pooh-pooh monetarism. Money and banking are nowhere to be found in their macroeconomic models, or their discourses about the course of ***** et prices, economic activity, and prices. Indeed, their forecasting exercises are typically based on elaborations of Keynesian income-expenditure models that exclude money and banking.
If that's not enough, we think that the Fed's backroom staff, mostly Keynesian-leaning Democrats, don't want alignment with a philosophy usually affiliated with Milton Friedman, but that's another story. Just look at what Joe Biden said in 2020 about how the dean of monetarism wasn't "running the show anymore."
#monetarist

1 month ago
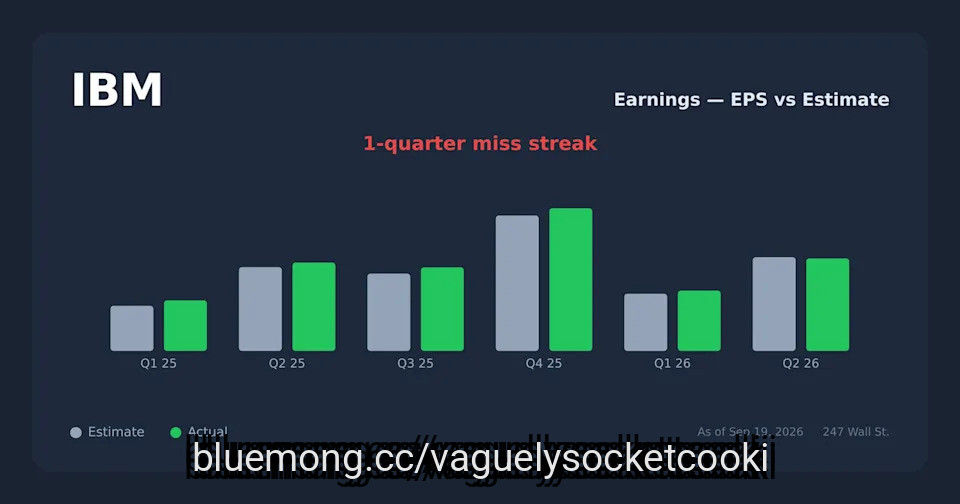
IBM raised its quarterly dividend a single penny, from $1.68 to $1.69, marking its 31st consecutive increase but delivering just $0.04 more annually to shareholders.
Microsoft grew its quarterly dividend from $0.13 to $0.98 since 2010, making it the stronger pick for investors seeking real income growth over IBM's 2.83% yield.
IBM's dividend appears safe, with $14.7B in free cash flow comfortably covering its $6.3B payout, though capital is flowing toward acquisitions, $62B in debt, and quantum computing bets.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and IBM didn't make the cut. Enter your email to see the names that beat IBM. The report is free. Enter your email and see if any of your stocks made the cut.
The headline is easy to sell. IBM (NYSE:IBM) has paid consecutive quarterly dividends every year since 1916 and, with the April declaration, notched its 31st consecutive year of dividend increases. The reality a retiree actually banks is smaller. Much smaller.
#Dividend #year


1 month ago
SEIC provides investment processing, management, and operational platforms for private banks, financial advisors, institutional investors, and financial managers. SEIC's second-quarter fiscal 2026 report showed revenue of $641.6 million (a 14.7% year-over-year gain), adjusted per-share earnings of $1.66 (a 38% rise), $207 million in operating income (a 36% jump) – all of which were quarterly records – and the company has nearly $400 million in cash for more growth ahead.
It's no wonder SEIC shares are up 28% so far this year – and they could rise more. MoneyFlows data shows how Big Money investors are again betting heavily on the stock
Institutional volumes reveal plenty. Over the last year, SEIC has enjoyed strong investor demand, which we believe to be institutional support.
Each green bar signals unusually large volumes in SEIC shares. They reflect our proprietary inflow signal, pushing the stock higher:
Plenty of financials names are under accumulation right now. But there's a powerful fundamental story happening with SEI.
#institutional #investors #Stock



1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
If you're looking for a secure place to store your savings, a certificate of deposit (CD) may be a great choice. These accounts often provide higher interest rates than traditional checking and savings accounts. However, CD rates can vary widely. Learn more about CD rates today and where to find high-yield CDs with the best rates available. Here is a look at some of the best CD rates available today from our verified partners:
Today's CD rates vary quite a bit. In general, however, CD rates have been declining for quite some time due to the Fed's decision to cut its benchmark rate three times in the latter part of 2024 and three times in 2025. Even so, with the Fed leaving rates unchanged so far in 2026, some banks are still offering competitive CD rates.
For institutions offering competitive rates, top rates reach about 4% APY. This is especially true for shorter terms of one year or less.
Today, Friday, September 18, 2026, the highest CD rate is 4.40%, and it's offered by Happen Bank on its 2-year CD.
#quite #rate



1 month ago
Back in 2021, banks treated crypto like radioactive waste. Fast forward to 2026, and financial giant Visa (NYSE: V) isn't just dipping a toe in -- it's basically cannonballing into the deep end of the stablecoin pool.
Here's what Visa has done recently, and why it's huge for anyone holding crypto.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In July, Visa introduced the Visa Stablecoin Platform (VSP). Think of it as a plug-and-play stablecoin toolkit for traditional banks and fintechs.
Instead of traditional institutions sweating over managing private keys, setting up multi-sig wallets, or figuring out how to mint and burn tokens, Visa handed them a slick "Wallet-as-a-Service." Starting with Open USD, an upcoming token, Visa will also support the popular USDC (CRYPTO: USDC) coin later this year. Banks can now hold, move, and settle stablecoins using the same enterprise-grade security tools they're already comfortable with. It's in beta testing for now, pending the Open USD launch.
#Crypto #stablecoin


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Opening a savings account for a child can help them build good money habits while giving their savings a safe place to grow. But because minors generally can't open bank accounts on their own, a parent or guardian will usually need to help. Here's how to open a savings account for a child, what you'll need, and how to choose the right account.
You must follow the right steps if you want to open savings account for your child. Much of the process is similar to opening a savings account for yourself, with some additional considerations.
Keep in mind that banks often require a parent or legal guardian to be present when opening a savings account for a child.
Start by choosing the right bank for your child's bank account. A simple and convenient option is to open an account where you do your own banking.
#account #opening #bank

1 month ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

1 month ago
Apollo Global Management warned Wednesday that credit default swaps on hyperscaler debt are pricing in more risk. Chief economist Torsten Slok tied the shift to weakening credit fundamentals rather than routine bond-dealer hedging.
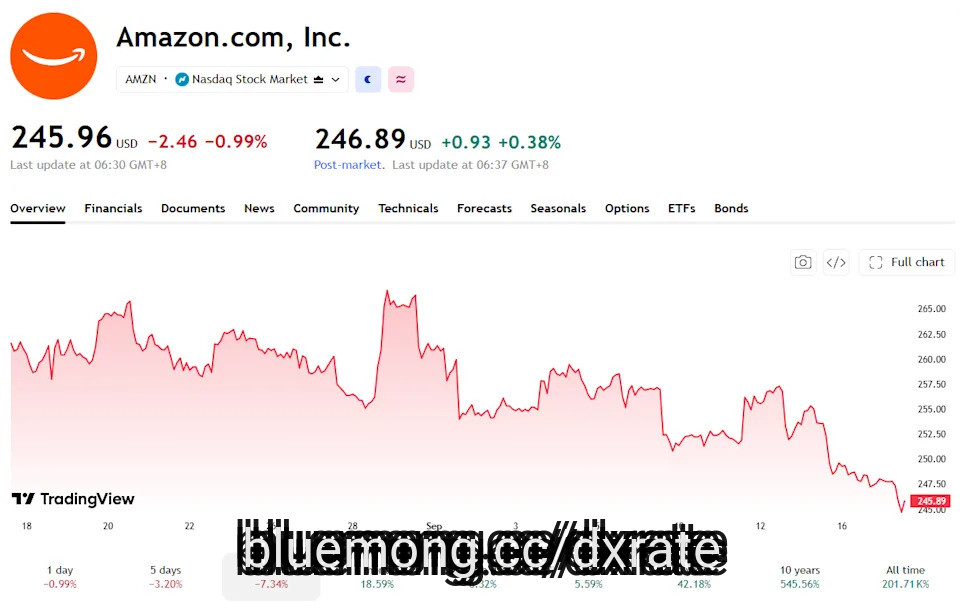
Hyperscalers are the cloud computing giants, including Amazon, Microsoft, Google, and Meta, that run the infrastructure behind the AI boom. They face a credit default swap (CDS) gap against bank debt, widened to about 60 basis points since October 2025.
Slok made the case in a Wednesday note reported by CNBC.
"What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating ****** ets."
Dan Alpert, founding managing partner of Westwood Capital, compared the setup to the run-up to the 2008 mortgage crisis. He said banks have since built far bigger equity buffers and are more diversified than they were then.
#slok

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#funds

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
Maybe you only think about the Federal Reserve when interest rate decisions make headlines. However, the Fed does much more than that, and it often impacts Americans' personal finances.
Discover how Fed rate moves affect your money.
The Federal Reserve acts as a bank for banks. It holds bank deposits, lends money to financial institutions, and facilitates the process by which banks borrow funds from each other.
The Federal Reserve also ensures the smooth operation of the banking system and guides the nation's economy by managing U.S. currency and by steering interest rates.
#affect #interest #advertiser

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#federal #rates #loans


1 month ago
Sept 16 (Reuters) - Top U.S. banks raised their prime lending rate on Wednesday after the Federal Reserve lifted its benchmark interest rate, a move that would increase borrowing costs for consumers and businesses with loans.
Following the Fed's first rate hike since 2023, the prime rate of JPMorgan , Bank of America, Citigroup, Wells Fargo, KeyCorp, Huntington Bancshares, Fifth Third Bancorp and Truist Financial from Thursday will rise to 7% from 6.75%.
The Fed raised rates by a quarter of a percentage point on Wednesday and flagged further increases in borrowing costs in the coming months as policymakers focus on addressing persistent inflation.
Shares of big banks ended lower amid broader weakness in U.S. stocks. BofA closed down 2.7%, Citi 2.4%, Wells Fargo 3%, and JPMorgan 1%. Morgan Stanley slipped 1.9% and Goldman Sachs fell 4%.
The prime rate, which follows the federal funds rate, is used by U.S. banks as a reference for setting rates on many financial products such as credit cards and personal loans.
#prime #jpmorgan #raised

1 month ago
While the average personal loan interest rate is 12.44%, borrowers with excellent credit may have access to rates as low as 5.96%.
Credit unions tend to offer the lowest overall borrowing costs, with a national average of 10.64% and a legal rate cap of 18% at federal institutions.
Online fintech lenders advertise competitive rates starting just below 6%, though maximum rates can climb up to 36% or higher.
Commercial banks remain competitive, with an average rate of 12%, but they demand a high credit score and solid work history for approval.
Tracking average personal loan rates can help you benchmark your borrowing costs for major goals like consolidating credit cards, financing home renovations or covering emergencies. Because personal loans offer fixed monthly payments, they are a solid tool for eliminating credit card debt, provided your credit profile qualifies you for the lowest market pricing.
#average #rates #lowest #borrowing

1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve influences consumer loan rates by setting the federal funds rate, which affects how much banks charge each other for overnight lending. That cost typically gets passed on to borrowers through higher or lower rates on personal, auto, and student loans.
By tracking the Fed's moves, you can get a better sense of whether taking out a loan will be more expensive or more affordable. It may even help you time your borrowing decisions so you can secure the best possible rate.
The Fed recently raised its rate by 25 basis points during its September 2026 meeting. See what impact that could have on your borrowing costs.
The Federal Reserve sets a target range for the federal funds rate, a benchmark rate that determines how much lenders charge one another for overnight lending. When the Fed increases this rate, lenders generally pass along the higher costs to consumers by raising interest rates on consumer loans and credit cards. When the Fed decreases this rate, lenders may lower the interest rates on their loans as well.
#Consumer


1 month ago
Some offers on this page are from advertisers who pay us, which may affect which products we write about, but not our recommendations. See our Advertiser Disclosure.
The Federal Reserve doesn't set student loan rates directly, but its federal funds rate influences the 10-year Treasury yield (which determines federal loan rates) and the prime rate (which determines private loan rates).
But exactly how the Fed affects your cost of borrowing depends on the type of student loans and interest rate you have.
After the Federal Reserve's September 2026 meeting, it raised interest rates by 25 basis points. See how that might impact the cost of your student loans.
One of the Federal Reserve's main goals is to keep inflation under control. It does this partly by adjusting the federal funds rate — the rate banks charge one another for short-term loans.
#rate #loan #determines #interest