2 hours ago
On September 17, Lucid Group, Inc. (NASDAQ:LCID) and Bolt, a leading European shared mobility platform, announced a strategic partnership to develop and deploy autonomous mobility services across Europe. This sent shares of Lucid Group, Inc. (NASDAQ:LCID) higher, and the stock ended the trading session with gains of nearly 6%.
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership
The partnership will combine Lucid Group, Inc.'s (NASDAQ:LCID) software-defined vehicle platform with Bolt's European data, operating infrastructure, and mobility expertise. The companies will be looking to develop and launch autonomous mobility services at scale, using vehicles based on Lucid Group, Inc.'s (NASDAQ:LCID) upcoming Midsize platform.
Bolt plans to deploy at least 25,000 fully autonomous vehicles across multiple European cities and countries, supporting its ambitious goal of having 100,000 autonomous vehicles on its platform by 2035.
The financial details of the partnership were not disclosed.
The deal comes as Lucid Group, Inc. (NASDAQ:LCID) continues to face significant financial pressure. The company has been pursuing an ambitious expansion strategy. However, its revenue growth has not yet been enough to offset substantial operating losses and the high costs ****** ociated with building its global factories.
#lcid #european #platform #partnership
4 hours ago
On September 9, 2026, Casey's General Stores, Inc. (NASDAQ:CASY) reported fiscal first-quarter revenue of $5.68 billion, up 24.3% year over year, and earnings per share of $7.37, beating the $6.78 ******* yst consensus. Yet shares fell roughly 10-15% after same-store sales grew just 3.2%, below the 3.8% Wall Street had expected.
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue
CEO Darren Rebelez described a "volatile" fuel environment during the quarter. Same-store fuel gallons sold declined 0.3% as elevated prices pushed customers toward fewer gallons per visit, more frequent trips, and cheaper fuel grades.
Fuel profitability more than offset softer gallon volumes. Fuel gross profit jumped 19.6% to $446.9 million as the fuel margin expanded to 47.8 cents per gallon from 41.0 cents a year earlier. It shows Casey's General Stores, Inc. (NASDAQ:CASY)'s pricing discipline can protect profitability even when customers buy fewer gallons. Prepared food added another source of margin strength, with same-store sales rising 4.8% and margins expanding to 59.3% from 58.0%.
Strong earnings growth gives Casey's a solid start to fiscal 2027. EBITDA grew 17.1% to $485.1 million, while net income rose 27.1% to $273.7 million. It shows that Casey's can grow earnings despite softer same-store sales. The firm also delivered $5.68 billion of revenue, up 24% year over year and above the $5.56 billion ******* yst estimate. It gives investors evidence that the overall business remains capable of producing strong growth.
Casey's is expanding its store base and integrating Fikes. The business said the Fikes integration remains ahead of schedule and maintained its plan to open at least 120 stores in fiscal 2027 through construction and acquisitions. Ongoing unit growth can expand Casey's geographic reach, increase purchasing scale, and support long-term revenue growth even if mature-store sales remain uneven.
#fuel #revenue

5 hours ago
On September 9, 2026, Independence Realty Trust, Inc. (NYSE:IRT) and Centerspace announced a definitive all-stock merger agreement. It creates a combined middle-market apartment REIT with a pro forma equity market capitalization of about $5.0 billion and a total enterprise value of approximately $8.1 billion, encompassing more than 44,000 units.
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management
The combined company will retain the Independence Realty Trust name and NYSE ticker "IRT." IRT's Scott Schaeffer continues as Chairman and CEO. The management projects the deal will be roughly 5% accretive to 2027 Core FFO per share for shareholders of both companies.
The merger gives Independence Realty Trust, Inc. (NYSE:IRT) higher scale and significantly broader geographic diversification. The combined company will own 44,354 apartment units across 163 communities in 17 states, with 58% of pro forma NOI coming from Sunbelt markets, 27% from the Midwest, and 15% from the Mountain West. The overall footprint reduces reliance on any single regional apartment market while keeping substantial exposure to markets with strong population and employment growth.
IRT can apply its existing value-creation strategy across a much larger portfolio. Its value-add renovation program has delivered about a 16% historical return on investment. The firm expects to grow its Wi-Fi initiative and other technology and income-generating programs across Centerspace's properties. Management also expects approximately $24 million in annualized synergies. It supports roughly 5% accretion to 2027 Core FFO per share on a leverage-neutral basis.
The all-stock structure allows the companies to chase greater scale without adding acquisition debt. IRT and Centerspace expect the combined company to retain BBB/BBB investment-grade credit ratings and maintain a well-laddered debt maturity profile. Centerspace shareholders will receive IRT shares and own approximately 22% of the combined company. It gives them exposure to the larger platform. Management also expects the transaction to improve access to capital markets and reduce the combined firm's cost of capital over time.
#management


5 hours ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount


5 hours ago
On September 8, 2026, Reuters reported that ASML Holding N.V. (NASDAQ:ASML) plans to work with major customers. It includes Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM), Nvidia, Intel, Samsung, and SK Hynix to adapt its next-generation "High NA" extreme ultraviolet lithography tools so they can print larger data-center chips. It addresses a current limitation where the newer machines use a smaller mask than ASML's widely deployed standard EUV tools.
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next
ASML targets a pilot production line using the larger masks by 2031 and high-volume manufacturing readiness by 2033. Chief technology officer Marco Pieters said these changes could lift the productivity of these systems by roughly 40%.
The larger-mask project could create a new growth opportunity for ASML Holding N.V. (NASDAQ:ASML) while helping TSMC manufacture larger AI chips more efficiently. ASML plans to use its High NA EUV tools to handle chips as large as today's biggest data-center processors. The business expects the larger masks to increase system productivity by 40%. It could scale up demand for its next-generation equipment and help TSMC improve the economics of producing increasingly large and complex chips.
Taiwan Semiconductor Manufacturing Company Limited (NYSE:TSM)'s planned use gives ASML a clear path toward commercializing the technology. TSMC plans to introduce High NA EUV into advanced-node high-volume production from 2030. ASML aims to show its larger-mask technology through a pilot line in 2031. TSMC's commitment could give ASML greater visibility into future equipment demand. Early use could help TSMC maintain its advanced-chip manufacturing advantage.
The collaboration could solidify both companies' positions as chipmakers develop larger and more powerful processors. ASML can extend its High NA roadmap beyond its current chip-size limitation. TSMC can prepare its manufacturing processes for the next generation of AI chips. The partnership gives ASML an opportunity to deepen its relationship with one of its largest customers and gives TSMC access to a technology that could support future advanced-chip production.
#asml #technology #plans #next


5 hours ago
On September 17, B. Riley initiated coverage of Nokia Oyj (NYSE:NOK), giving the stock a Buy rating and setting the price target at $15. The firm pointed to the company's position in telecom infrastructure, cloud software, and hardware networking solutions.
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm
Riley noted that the company's networking businesses are seeing strong growth. In Q2 2026, Optical Networks revenue increased 20% year-over-year, while IP Networks grew 16%. Net sales to AI and cloud customers also surged 105%. The research firm noted that hyperscalers continue to purchase Nokia Oyj's (NYSE:NOK) AI networking products to support large-scale computing clusters.
The company's AI and cloud opportunity is also reflected in its order book. Nokia Oyj (NYSE:NOK) reported EUR 2.8 billion in AI and cloud order intake during the second quarter of 2026. B. Riley pointed out that this provides revenue visibility into 2027. The firm also noted that the carrier inventory correction cycle that had weighed on global capital expenditures has now concluded.
Riley derived its $15 price target using a sum-of-the-parts valuation that separates the company's legacy ****** ets from its data center business. The firm applied a premium hardware multiple to the data center segment, reflecting its view of the potential operating leverage in that business.
Profitability Remains a Concern
#riley #NYSE #firm

5 hours ago
On September 9, 2026, Reuters reported that Amazon.com, Inc. (NASDAQ:AMZN) raised £4.25 billion, or about $5.76 billion, in its first-ever sterling bond sale, slightly more than initially expected, as part of a four-tranche deal spanning 3 to 19 years. Final investor demand came in at more than £10.65 billion, roughly 2.5 times the amount raised, but that was notably lower than the demand Alphabet saw for its own sterling debut in February, a sign ******* ysts said shows hyperscaler borrowing may be starting to test the limits of investor appetite.
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn
Amazon.com, Inc. (NASDAQ:AMZN)'s first sterling bond sale shows that investors still have a strong appetite for its debt. The firm raised $5.8 billion through the offering, and demand reached roughly 2.5 times the amount available. The sterling market also has relatively limited supply of large technology-company debt. It could back up demand for future Amazon issuance in the currency. Strong demand gives Amazon another funding channel as it finances its large-scale AI and cloud infrastructure investments.
Amazon can put the proceeds toward AWS, its fastest-growing major business. AWS revenue increased 36.7% year over year in the second quarter. It marks its fastest growth rate in 18 quarters as demand for AI infrastructure accelerated. Funding more data centers, computing capacity and related infrastructure could allow Amazon to capture more of that demand. If AWS sustains its growth while making strong operating profits, the additional debt could support investments in one of Amazon's most important long-term earnings drivers.
The sterling offering diversifies Amazon's funding base as its capital requirements grow. Amazon issued four tranches with maturities ranging from three to 19 years. It gives the business access to UK investors while adding sterling financing alongside its existing dollar, euro, Swiss franc and yen debt. This overall investor base gives Amazon greater flexibility to raise capital across different markets and currencies. So diversification could become more valuable as Amazon funds an unprecedented AI infrastructure buildout without relying entirely on one debt market.
Amazon.com, Inc. (NASDAQ:AMZN)'s weaker reception compared with Alphabet signals that investors may demand higher borrowing costs from hyperscalers. Amazon's sterling offering attracted about 2.5 times coverage, below Alphabet's roughly 3.5 times coverage for its recent euro bond sale. The difference shows that demand for hyperscaler debt is not unlimited. If investor appetite continues to weaken, Amazon could face higher yields on future borrowing, increasing the cost of financing its AI infrastructure expansion.
#sterling #infrastructure #NASDAQ #amzn

9 hours ago
Trip.com Group Limited (NASDAQ:TCOM) reported second-quarter 2026 net revenue of RMB15.7 billion, up 6% year over year, in results released September 15. Revenue on its international platform increased more than 50%, highlighting a promising source of expansion against slower group growth.
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ
Trip.com Group Limited (NASDAQ:TCOM) also recognized a RMB5.2 billion antimonopoly penalty in general and administrative expenses. The investment question extends beyond that charge: can international expansion generate enough profitable growth to offset pressure on domestic monetization?
International expansion gives Trip.com Group Limited (NASDAQ:TCOM) a potential route to reducing dependence on revenue earned from domestic travel. A broader customer base could make growth less reliant on a single market's commercial practices and regulatory environment.
The opportunity is especially attractive if new customers become repeat users. Over time, repeat bookings could reduce acquisition spending per transaction and allow technology and service costs to be spread across more revenue. That would turn international scale into operating leverage, with profits growing faster than sales.
Trip.com Group Limited (NASDAQ:TCOM) also grew accommodation revenue 6% year over year despite a regulator-imposed revenue reduction. That result offers some evidence of resilience, although reservation growth and the revenue earned from those reservations remain separate considerations.
#NASDAQ


10 hours ago
Sempra (NYSE:SRE) added a long-term customer commitment on September 14, when its infrastructure subsidiary announced a 20-year sales and purchase agreement with Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR). The agreement covers approximately 0.8 million tonnes annually of liquefied natural gas, or LNG.
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term
Supply will come from the subsidiary's contracted liquefaction capacity at Port Arthur LNG Phase 2 in Texas. The project is under construction, with trains 3 and 4 expected to begin commercial operations in 2030 and 2031, respectively. The agreement improves visibility into future sales, while the earnings contribution depends on delivery and contract economics.
Petróleo Brasileiro S.A. - Petrobras (NYSE:PBR) becomes the infrastructure subsidiary's first South American LNG customer. That broadens the geographic base of buyers and establishes a commercial relationship extending over two decades.
For Sempra (NYSE:SRE), the practical benefit is an external buyer for part of the subsidiary's contracted capacity. Securing that relationship before startup could reduce the need to find buyers for the covered volumes as production approaches, while supporting longer-term supply planning.
The annual commitment equals approximately 6.2% of Phase 2's planned 13-million-tonne annual capacity. This provides a measure of scale, although it does not establish the percentage of capacity still available for sale.
#agreement #petr #supply #term

11 hours ago
Centrus Energy Corp. (NYSE:LEU) reported on September 17 that it had signed a multi-year contract to supply high-assay low-enriched uranium (HALEU) to Antares Nuclear, with deliveries expected to begin before the end of the decade. Although financial terms were not disclosed, the deal includes prepayments from Antares to help fund Centrus' expanded HALEU capacity.
The deal holds strategic importance as Antares is developing compact microreactors for critical missions on Earth and in ***** e. The company was also recently selected for the U.S. Army's Janus Program, a $2.2 billion initiative to build and operate tiny nuclear reactors on military bases, with the hope that they will one day power remote installations.
Amir Vexler, President and CEO of Centrus Energy, commented:
"This contract is another sign that demand for HALEU is real and it is accelerating, and Centrus is in prime position to meet this need. Binding orders from Antares and others are supporting our expansion to commercial-scale production – an expansion that is now well underway. We look forward to supporting Antares' continued growth and success."
dan-meyers-xXbQIrWH2_A-unsplash
#centrus #haleu
The deal holds strategic importance as Antares is developing compact microreactors for critical missions on Earth and in ***** e. The company was also recently selected for the U.S. Army's Janus Program, a $2.2 billion initiative to build and operate tiny nuclear reactors on military bases, with the hope that they will one day power remote installations.
Amir Vexler, President and CEO of Centrus Energy, commented:
"This contract is another sign that demand for HALEU is real and it is accelerating, and Centrus is in prime position to meet this need. Binding orders from Antares and others are supporting our expansion to commercial-scale production – an expansion that is now well underway. We look forward to supporting Antares' continued growth and success."
dan-meyers-xXbQIrWH2_A-unsplash
#centrus #haleu


12 hours ago
Definium Therapeutics, Inc. (NASDAQ:DFTX) has now delivered a third consecutive positive Phase 3 readout for its LSD-based medication, the second in generalized anxiety disorder. The result puts the company on a viable route toward a potential FDA approval of an LSD-based treatment for generalized anxiety disorder, and considering how closely psychedelic stocks have historically traded on each other's data, the reading carries far more weight than Definium's own ticker.
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo
On September 14, Definium Therapeutics, Inc. (NASDAQ:DFTX) announced that its drug DT120, an orally disintegrating tablet formulation of LSD, was successful in Panorama, the company's second late-stage anxiety trial. Over 12 weeks, patients who received a 100-microgram dose experienced a 9.8-point decline on the Hamilton Anxiety Rating Scale, a typical clinical measure, compared to a 4.7-point drop with placebo.
The resulting 5.1-point placebo-adjusted improvement is similar to what the company's first pivotal anxiety trial, Voyage, showed back in August: an 11.6-point improvement versus 6.2 for placebo, a 5.4-point separation that Jefferies called one of the strongest placebo-adjusted efficacy results ever seen in generalized anxiety disorder, and that Stifel simply described as "a clean win."
Psychedelic equities have a history of trading as a group rather than as individual names, and this tendency applies both ways. In February 2026, when Compass Pathways, the sector's other clinical leader developing a psilocybin-based drug for treatment-resistant depression, reported positive late-stage data, shares of Definium Therapeutics, Inc. (NASDAQ:DFTX), Atai Beckley, GH Research, and Helus Pharma all rose, some by double digits.
That correlation is significant here because Definium's win is an independent validation of the broader therapeutic argument on which Compass and others are betting: a single dose of a classic psychedelic, administered in a controlled clinical setting, can produce lasting improvements in serious mental health conditions via pathways different from existing SSRIs and other standard-of-care drugs.
#definium #placebo


12 hours ago
Elon Musk has never shied away from ambitious timelines, and his most recent one connects two companies directly together. In a post on X dated September 13, Musk stated that he is "highly confident" that **** e Exploration Technologies Corp. (NASDAQ:SPCX) will transport NVIDIA Corporation (NASDAQ:NVDA) Vera Rubin NVL72 AI computers into orbit next year, repeating a plan that has already moved both companies' stock this year.
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies
The comment strengthens **** eX's Starmind concept, which aims to establish AI data centers in orbit rather than on the ground. The first satellite, named Starmind AI1, will carry a **** e-optimized version of NVIDIA's Vera Rubin NVL72 rack-scale system. The standard terrestrial NVL72 combines 72 Rubin GPUs and 36 Vera CPUs, although **** eX and NVIDIA have not disclosed the final configuration of the orbital version. **** e Exploration Technologies Corp. (NASDAQ:SPCX) plans to launch the satellite in the fourth quarter of 2027 and reach substantial scale by 2028. Musk's plan isn't new; during **** eX's first earnings conference as a public company in August, he stated that the company would build exclusively on NVIDIA hardware in the future, calling the Vera Rubin architecture the best available AI computer design.
Musk's central point is that **** e is, in the long run, the most cost-effective area to develop AI computing. He cites solar power availability in orbit as a crucial advantage, and estimates that within two to three years, **** e might become the lowest-cost place for AI computing in general, describing the orbital architecture as simpler, less expensive, denser, and lighter than a standard data-center rack. Not everyone believes the physics and economics will align on Musk's timeframe. Microsoft President Brad Smith has publicly questioned the broader concept, telling reporters that he would be surprised if companies actually transferred computation from land to low-Earth orbit.
For NVIDIA Corporation (NASDAQ:NVDA), the read-through is simple: **** e-based computing would represent a new, if early-stage and speculative, source of demand for its Vera Rubin platform, on top of the company's strong position in terrestrial AI infrastructure. According to some **** yst models, **** eX accounts for approximately 5% of NVIDIA's revenue.
SpaceX's reasoning is more convoluted. The plan is entirely dependent on the success of Starship, **** eX's next-generation rocket system, which still needs to demonstrate its capacity to handle launch frequency and reliability on the scale Musk describes. When Musk said during **** eX's August earnings call that the company would build its future AI infrastructure exclusively on NVIDIA, NVDA shares rose more than 4%, while **** eX's shares fell more than 10% before paring losses, reflecting investor concerns about execution risk and capital intensity, despite the fact that the NVIDIA relationship was well received.
#Companies

12 hours ago
On September 14, NextEra Energy, Inc. (NYSE:NEE) and Dominion Energy, Inc. (NYSE:D) announced a "transformational" Virginia benefits package to address concerns regarding their proposed $66.8 billion merger. The Virginia supplier program, worth up to $1 billion annually for five years, will direct spending toward contractors, suppliers, and service providers in the state.
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs
Additionally, the companies also proposed doubling residential bill credits to four years, protecting retail customers from grid costs tied to Northern Virginia's rapidly expanding AI data centers, and committing $100 million toward directly supporting workforce development in the Commonwealth. NextEra also stated that it plans to add 600 new energy jobs in Virginia, while expecting suppliers to create another 400 positions.
The updated package comes after the proposed merger attracted a great deal of political scrutiny due to the impact it can have on everyday consumers. Virginia Governor Abigail Spanberger also stated last month that she would formally intervene in the regulatory review to press for commitments on electric bill affordability, job protections, and clean-energy investments.
John Ketchum, Chairman, President, and CEO of NextEra Energy, commented:
"This is a Virginia-first package, and it starts with customers. We are proposing to double residential bill relief from two years to four years, along with expanded low-income financial ******* istance and long-term affordability benefits. We are also reaffirming our support for the State Corporation Commission, Governor and General ******* embly's efforts to protect residential and small business customers from costs ******* ociated with serving data centers. Just as important, this package would help Virginia build more of the clean energy and infrastructure it needs faster, so the Commonwealth can reduce its reliance on expensive imported power. And it would do that while positioning Virginia as a major energy leader, bringing NextEra Energy jobs, good-paying supplier jobs, workforce investment, economic development and national-scale energy technology and innovation to Virginia. This is the kind of customer-focused, job-creating package this combination makes possible."
#energy #years #Jobs


12 hours ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target


17 hours ago
On August 6, Wheaton Precious Metals (NYSE:WPM) reported second-quarter net earnings of $543 million on $929 million of revenue, both records. Through the first half, net earnings rose 106% to $1.1 billion. During the quarter, the company also made net upfront cash payments of $4.5 billion relative to mineral stream interests, and it now carries $2.0 billion of total debt against $100 million of cash on hand. Here is what that trade looks like up close.
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
Start with what the streaming model does when prices climb. Wheaton sold 14% more gold equivalent ounces than a year ago, but the average realized gold equivalent price jumped 61% in Q2, and that higher price explains most of the revenue surge. Costs per ounce rose from $406 to $568, yet the cash operating margin per ounce still grew 65% to $3,875, faster than gold itself appreciated. Operating cash flow hit $650 million in the quarter and $1.4 billion for the half.
The second argument is that plenty of growth hasn't arrived yet. Only about 3% of this year's production comes from **** ets still in construction or ramp-up, and the company forecasts a rise of roughly 50% to 1,200,000 gold equivalent ounces by 2030. Some of that ramp has dates attached. Ivanhoe now expects commercial production at Platreef in the fourth quarter of 2026, and Montage Gold is targeting first gold at Koné in late Q4. Effective April 1, Wheaton expanded its share of silver production from Antamina from 33.75% to 67.5% through the newly acquired BHP Antamina PMPA.
Growth on this scale wasn't free. Wheaton had no bank debt at the end of 2025. On April 1, it drew $1.5 billion on a new two-year term loan to help pay for Antamina, and finance costs that were negligible a year ago now take a real bite. Net debt stands at $1.9 billion. Taxes are heavier too. Wheaton paid $109 million of global minimum tax on June 24, and another Cdn$346 million is due around March 31, 2027.
Operations also gave investors a few reasons for caution. Gold ounces produced slipped 2.6% year over year, so the 6% rise in gold equivalent production leaned heavily on the Antamina purchase. Gold output at Salobo fell 11% on lower grades. At Constancia, it fell 35% after mining at the higher-grade Pampacancha pit finished in the fourth quarter of 2025. Hemlo Mining said on July 20 that its second-quarter output fell below the first quarter's, and Rio2 said on May 15 that Fenix missed planned tonnes and grade in Q1. And because the revenue jump came mainly from price, the same leverage works in reverse if metals slip.
#wheaton
18 hours ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily

19 hours ago
Interested in Apollo Global Management Inc.? Here are five stocks we like better.
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade
Apollo expects interest rates to remain higher for longer, while estimating only a 10%–20% chance of a recession over the next year. Consumer spending, inflation and AI infrastructure investment are supporting economic activity, though geopolitical and energy risks remain.
The firm views AI primarily as a large-scale financing opportunity, providing structured capital to investment-grade companies involved in digital infrastructure, energy, logistics and defense rather than betting on individual technology winners.
Apollo reported strong institutional fundraising, including a $12 billion first close for its Fund XI, and expects private-equity industry consolidation as smaller or overexpanded managers struggle to return capital. Its high-grade capital-solutions business has completed more than 200 transactions totaling roughly $150 billion.
Baggage Claim: Apollo's $7.7 Billion Bid to Acquire easyJet
#apollo #infrastructure #energy #grade

19 hours ago
With a market cap. of $13.4 billion, McCormick & Company, Incorporated (MKC) is a global leader in flavor, manufacturing and distributing herbs, spices, seasonings, condiments, and flavors across 150 countries and territories. Its portfolio includes well-known brands such as McCormick, French's, Frank's RedHot, OLD BAY, Cholula, and Gourmet Garden, serving retailers, food manufacturers, and foodservice businesses.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and McCormick comfortably fits this category. Headquartered in Hunt Valley, Maryland, McCormick operates through its Consumer and Flavor Solutions segments, leveraging its global scale, expertise, and technology to support sustainable growth.
Elon Musk, Who Became the World's First Trillionaire, Still Sleeps in a Tiny $50,000 House Where His Mom Uses the Garage — 'It's Kinda Awesome Though'
How to Play AMZN Stock as Amazon Unveils Project Mercury
JPMorgan Gives Up Forecasting Iran War Endgame as Trump Tells Reporters 'Anything Could Happen With Me'
#mccormick #gourmet


19 hours ago
Intel Corporation (NASDAQ:INTC) is targeting a potentially significant opportunity through its strategic Terafab partnership with companies **** ociated with Elon Musk, including **** eX, Tesla, and xAI. The initiative is part of an ambitious semiconductor manufacturing project focused on producing advanced chips for artificial intelligence (AI), robotics, autonomous vehicles, and other compute-intensive applications.
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel
On September 15, Tigress Financial highlighted the strategic importance of the alliance to Intel's turnaround prospects. The research firm reiterated its Buy rating on Intel and raised its price target to $145 from $118, citing the company's long-term growth opportunity.
The Terafab partnership could provide Intel's foundry business with exposure to customers that have substantial AI and high-performance computing requirements. Securing external customers could help Intel increase manufacturing scale while improving the utilization and economics of its foundry operations.
The partnership could also support Intel Corporation (NASDAQ:INTC)'s efforts to improve its semiconductor manufacturing technology. Greater production volumes and engagement with demanding customers could provide opportunities to improve manufacturing economics, yields, and scalability as Intel works to strengthen its competitive position in advanced chip manufacturing.
Beyond manufacturing scale, Terafab could expand Intel's role in the broader AI semiconductor supply chain. The company has historically been heavily **** ociated with CPUs, but growing its foundry business could give it greater exposure to AI accelerators, custom silicon, and other specialized compute applications. A relationship with major AI-focused customers could also help provide greater visibility into future manufacturing demand.
#Intel

1 day ago
The first full week of trading in September didn't give Zscaler (NASDAQ: ZS) investors much to celebrate. During the shortened trading week that followed Labor Day, Zscaler dropped about 3%. This week, however, is a very different story, thanks to a firm providing an auspicious outlook for the cybersecurity stock.
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week
According to data provided by S&P Global Market Intelligence, Zscaler shares were up 20.7% from the end of trading last Friday through 3:37 p.m. today.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Maintaining its outperform rating, Bernstein hiked its price target on Zscaler stock to $298 from $224 on Thursday morning. Based on Zscaler's closing price of $191.58 on Wednesday, the Bernstein price target implies 56% upside.
According to Thefly.com, Bernstein based its improved outlook on the belief that there's growing positive market sentiment toward cybersecurity stocks. In addition, Bernstein notes that cybersecurity stocks it had previously identified as "too cheap" are now reasonable valued, yet Zscaler is one option that still provides material upside.
#week

1 day ago
By Exec-Edge Editorial Staff
Sir Lynton Crosby has spent four decades reading public opinion for people who couldn't afford to get it wrong — prime ministers, presidents, and the boards of some of the world's largest companies. As Executive Chairman of CT Group, the research and strategy firm he co-founded, Crosby has built one of the most quietly influential shops in political and corporate consulting, with offices across eight countries and a client roster that spans government, industry, and advocacy. In recent years, CT Group has turned its research apparatus toward a subject closer to home for the business community it serves: capitalism itself, and why the system's public standing hasn't kept pace with its performance. We spoke with Crosby about what the firm's research found, and what it means for how business leaders talk about the system they operate in.
Exec Edge: CT Group ran a large-scale study on public attitudes toward capitalism. What prompted that?
We had seen a number of signals that some of the trending narratives on how the public felt about the predominant economic system were misleading. But we don't operate on feelings, but instead we respond to data, so we tested it. There's a narrative that's taken hold since the financial crisis — that the public has simply given up on capitalism, that a decade of scandals and populist politics has turned the average voter against the system outright. We fielded a nationally representative survey of 3,000 people, backed by focus groups, to find out if that was actually true or if something more specific was going on. It turned out to be the latter.
Exec Edge: What did the research actually find?
#edge #Research #turned
Sir Lynton Crosby has spent four decades reading public opinion for people who couldn't afford to get it wrong — prime ministers, presidents, and the boards of some of the world's largest companies. As Executive Chairman of CT Group, the research and strategy firm he co-founded, Crosby has built one of the most quietly influential shops in political and corporate consulting, with offices across eight countries and a client roster that spans government, industry, and advocacy. In recent years, CT Group has turned its research apparatus toward a subject closer to home for the business community it serves: capitalism itself, and why the system's public standing hasn't kept pace with its performance. We spoke with Crosby about what the firm's research found, and what it means for how business leaders talk about the system they operate in.
Exec Edge: CT Group ran a large-scale study on public attitudes toward capitalism. What prompted that?
We had seen a number of signals that some of the trending narratives on how the public felt about the predominant economic system were misleading. But we don't operate on feelings, but instead we respond to data, so we tested it. There's a narrative that's taken hold since the financial crisis — that the public has simply given up on capitalism, that a decade of scandals and populist politics has turned the average voter against the system outright. We fielded a nationally representative survey of 3,000 people, backed by focus groups, to find out if that was actually true or if something more specific was going on. It turned out to be the latter.
Exec Edge: What did the research actually find?
#edge #Research #turned

1 day ago
A crypto whale appears to be shifting a large portion of its portfolio from Bitcoin into Ethereum.
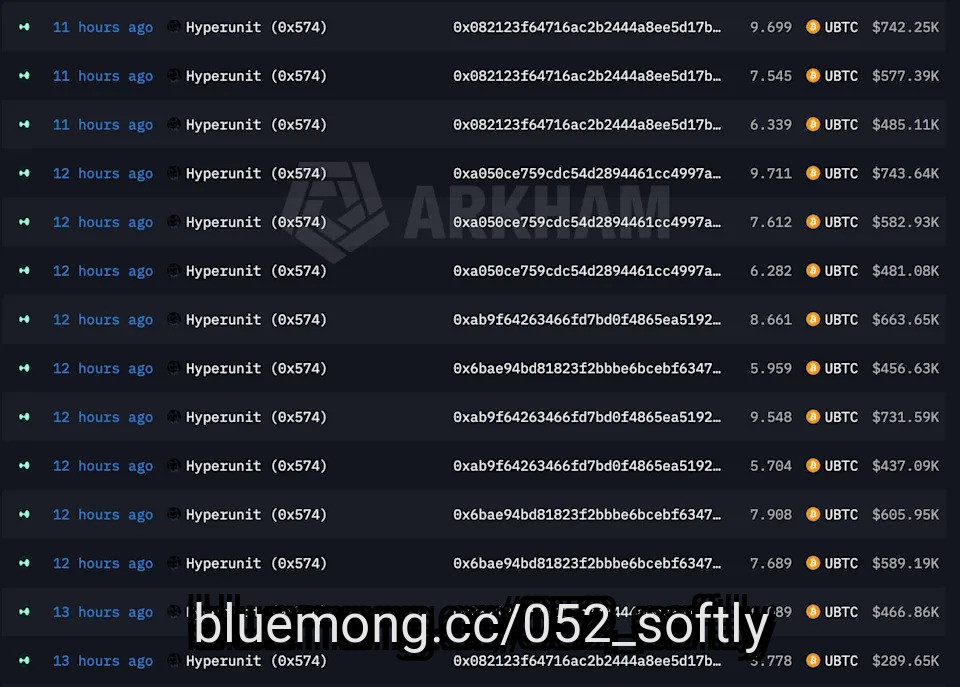
According to blockchain ***** ytics platform Lookonchain, 11 newly created wallets suspected to belong to the same whale, sold 602 BTC and bought 18,780 ETH on Hyperliquid over the past three days. Both sides of the transactions were worth roughly $45.83 million, indicating a large-scale portfolio rebalancing.
At press time, Bitcoin was trading around $81,001, up nearly 5.5% over the past 24 hours, while Ether was around $2,594, gaining about 5%.
JPMorgan says one ***** et class could soon beat gold
Kevin O'Leary has a warning on Washington's tax plans
#whale #Portfolio #ethereum #lookonchain
According to blockchain ***** ytics platform Lookonchain, 11 newly created wallets suspected to belong to the same whale, sold 602 BTC and bought 18,780 ETH on Hyperliquid over the past three days. Both sides of the transactions were worth roughly $45.83 million, indicating a large-scale portfolio rebalancing.
At press time, Bitcoin was trading around $81,001, up nearly 5.5% over the past 24 hours, while Ether was around $2,594, gaining about 5%.
JPMorgan says one ***** et class could soon beat gold
Kevin O'Leary has a warning on Washington's tax plans
#whale #Portfolio #ethereum #lookonchain



1 day ago
One of the world's largest companies has become a cash-return machine of historic scale, but its engine is now facing a serious test.
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market
With Apple (AAPL) stock trading near $337 a share, an owner might ask a simple question. The company has returned a fortune in cash while the stock has dramatically outperformed the market; was holding worth it, and can this machine keep running?
Over the last five years, Apple sent $510.4 billion in cash back to its shareholders. That sum, equal to about 10.3% of the company's current market value, is the largest capital return of any U.S. company Trefis tracks over that period. The question is what that extraordinary payout says about the business today.
The money printer is Apple's core business, which generated $136.68 billion in free cash flow over the last twelve months. In its most recent quarter, the company reported record June-quarter revenue, with iPhone sales growing 22% and Mac sales growing an impressive 29% from a year ago. Management noted that the iPhone and Mac were "both doing remarkably better than we thought they would do."
That operational strength funds the shareholder returns. The five-year payout was heavily weighted toward share repurchases, which totaled $434.5 billion, with another $75.9 billion paid in dividends. Apple's absolute dollar payout stands alone, even though the 10.3% of market value it returned sits well below the 16.9% median for S&P 500 companies.
#market

1 day ago
By Stine Jacobsen, Jacob Gronholt-Pedersen and Tom Little
COPENHAGEN, Sept 19 (Reuters) - Denmark and Greenland on Saturday said any agreement with the United States would not compromise Greenland's sovereignty, after President Donald Trump said the deal would give Washington "permanent control" over the Arctic island's security, leaving its precise scope unclear.
The United States, Denmark and Greenland said late on Friday they had reached an agreement for the US to develop a significant military presence on Greenland, while prohibiting US adversaries from building their own bases on the island.
Key details of the agreement have not been made public, including the scale of US military presence in the self-governing Danish territory and whether any formal power over foreign policy and resources would be ceded to Washington.
Denmark and Greenland expressed hope that a deal, which is expected to be signed during the UN General ******* embly next week, would end months of uncertainty triggered by Trump's threats to seize control of Greenland.
#greenland #control
COPENHAGEN, Sept 19 (Reuters) - Denmark and Greenland on Saturday said any agreement with the United States would not compromise Greenland's sovereignty, after President Donald Trump said the deal would give Washington "permanent control" over the Arctic island's security, leaving its precise scope unclear.
The United States, Denmark and Greenland said late on Friday they had reached an agreement for the US to develop a significant military presence on Greenland, while prohibiting US adversaries from building their own bases on the island.
Key details of the agreement have not been made public, including the scale of US military presence in the self-governing Danish territory and whether any formal power over foreign policy and resources would be ceded to Washington.
Denmark and Greenland expressed hope that a deal, which is expected to be signed during the UN General ******* embly next week, would end months of uncertainty triggered by Trump's threats to seize control of Greenland.
#greenland #control



1 day ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment

1 day ago
The Federal Reserve raised interest rates for the first time since July 2023 on Wednesday, and the S&P 500 (SNPINDEX: ^GSPC) immediately dropped. It rose again before the day was over, but it's been steadily declining over the past month since hitting a high in mid-August.
There are a number of reasons for the fall, and part of that has been the anticipation of rate hikes. The Fed's decision has a lot to do with the other reasons, including high inflation and rising oil prices, and none of these spell enthusiasm for the market. Here's how the inflation outlook and accompanying interest rates signal a warning for investors.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The simple version is that rising oil prices increase production costs, leading to higher consumer prices. The artificial intelligence (AI) buildout is contributing as well; memory prices are skyrocketing as hyperscalers have an insatiable demand for scarce memory products, and Apple, for example, said it's going to raise some prices.
As inflation surges and prices go up, it's harder for shoppers to keep spending. The worry is that lower consumer spending will lead to sagging sales for many companies, and the market is pricing that in as the inflation outlook persists.
#inflation #since #high #market
There are a number of reasons for the fall, and part of that has been the anticipation of rate hikes. The Fed's decision has a lot to do with the other reasons, including high inflation and rising oil prices, and none of these spell enthusiasm for the market. Here's how the inflation outlook and accompanying interest rates signal a warning for investors.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our **** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The simple version is that rising oil prices increase production costs, leading to higher consumer prices. The artificial intelligence (AI) buildout is contributing as well; memory prices are skyrocketing as hyperscalers have an insatiable demand for scarce memory products, and Apple, for example, said it's going to raise some prices.
As inflation surges and prices go up, it's harder for shoppers to keep spending. The worry is that lower consumer spending will lead to sagging sales for many companies, and the market is pricing that in as the inflation outlook persists.
#inflation #since #high #market

1 day ago
Nvidia (NASDAQ: NVDA) and Micron Technology (NASDAQ: MU) are two of the biggest companies in the world. Nvidia holds the top spot, sitting at a $5.3 trillion valuation. Micron currently sits at 13th place worldwide, with a $1.1 trillion valuation. These companies are also two of the biggest beneficiaries of the artificial intelligence (AI) build-out, and with that expected to ramp up again in 2027, these two are in a prime position to benefit.
But which stock stands to benefit more? Let's take a look at these two and see which stock makes the most sense for your investment dollars.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Nvidia and Micron are partners in the AI arms race. Micron makes memory chips, including DRAM memory that's utilized inside Nvidia GPUs. Micron's DRAM chips are also utilized in several other competitors' products, and demand for these products continues to rise.
Nvidia forecasts that the big five AI hyperscalers will spend nearly $800 billion on data center capital expenditures during 2026. Next year, that figure is projected to rise to $1.3 trillion. That's a lot of GPUs from Nvidia, filled with memory chips from Micron. There is huge demand for each company's product, but there is a stark difference in the long-term demand curve for each.
#memory #demand #gpus
But which stock stands to benefit more? Let's take a look at these two and see which stock makes the most sense for your investment dollars.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Nvidia and Micron are partners in the AI arms race. Micron makes memory chips, including DRAM memory that's utilized inside Nvidia GPUs. Micron's DRAM chips are also utilized in several other competitors' products, and demand for these products continues to rise.
Nvidia forecasts that the big five AI hyperscalers will spend nearly $800 billion on data center capital expenditures during 2026. Next year, that figure is projected to rise to $1.3 trillion. That's a lot of GPUs from Nvidia, filled with memory chips from Micron. There is huge demand for each company's product, but there is a stark difference in the long-term demand curve for each.
#memory #demand #gpus


2 days ago
Trump signed the legislation into law on Friday, the White House said.
LONDON -- Ukrainian President Volodymyr Zelenskyy on Friday thanked President Donald Trump for signing into law a bill championed by the late Sen. Lindsey Graham, which allows for the expansion of sanctions on Russia related to Moscow's ongoing full-scale invasion of Ukraine.
Trump signed the bill on Friday, the White House said in a statement, after the legislation passed both the House and Senate with strong bipartisan backing. The legislation "authorizes and expands statutory sanctions, tariffs and prohibitions on Russia and extends existing sanctions on Iran," the White House said.
The bill's passage came about two months after Graham died suddenly following a tear in his aorta. Graham had long been an advocate of U.S. support for Kyiv and more stringent measures on Russia and the regime headed by President Vladimir Putin. In 2024, Russia's state financial monitoring agency added Graham to its list of alleged "terrorists and extremists."
In a post to Telegram on Friday night, Zelenskyy thanked Trump for signing what he called "critically important legislation," extending his thanks to "all the senators and members of the House of Representatives who supported it."
#legislation #white #Russia #zelenskyy
LONDON -- Ukrainian President Volodymyr Zelenskyy on Friday thanked President Donald Trump for signing into law a bill championed by the late Sen. Lindsey Graham, which allows for the expansion of sanctions on Russia related to Moscow's ongoing full-scale invasion of Ukraine.
Trump signed the bill on Friday, the White House said in a statement, after the legislation passed both the House and Senate with strong bipartisan backing. The legislation "authorizes and expands statutory sanctions, tariffs and prohibitions on Russia and extends existing sanctions on Iran," the White House said.
The bill's passage came about two months after Graham died suddenly following a tear in his aorta. Graham had long been an advocate of U.S. support for Kyiv and more stringent measures on Russia and the regime headed by President Vladimir Putin. In 2024, Russia's state financial monitoring agency added Graham to its list of alleged "terrorists and extremists."
In a post to Telegram on Friday night, Zelenskyy thanked Trump for signing what he called "critically important legislation," extending his thanks to "all the senators and members of the House of Representatives who supported it."
#legislation #white #Russia #zelenskyy