

3 days ago
SAKS — Childersburg capped a remarkable turnaround Thursday night, defeating Saks 35-7 at Jack Stewart Field to close the season with a winning record.
After going 0-10 in head coach Matt Zedaker's first season in charge of the program, the Tigers improved to 6-4 this year, narrowly missing the playoffs.
"A great way to go out right here with six wins from zero wins last year," Zedaker said. "We're on an uphill ascend."
The bounce-back season would not have been possible without contributions from seniors like JaMarion Davis. In his final game in a Childersburg uniform, the 5-foot-11, 165-pound quarterback accounted for four of the Tigers' five touchdowns.
Davis scored on runs of 15 and 13 yards and threw touchdown passes of 37 yards to J'Kolby Thomas and 56 yards to Tristan Powell.
#season #yards #tigers #year
After going 0-10 in head coach Matt Zedaker's first season in charge of the program, the Tigers improved to 6-4 this year, narrowly missing the playoffs.
"A great way to go out right here with six wins from zero wins last year," Zedaker said. "We're on an uphill ascend."
The bounce-back season would not have been possible without contributions from seniors like JaMarion Davis. In his final game in a Childersburg uniform, the 5-foot-11, 165-pound quarterback accounted for four of the Tigers' five touchdowns.
Davis scored on runs of 15 and 13 yards and threw touchdown passes of 37 yards to J'Kolby Thomas and 56 yards to Tristan Powell.
#season #yards #tigers #year



14 days ago
HAMDEN - Arguably, no program in Connecticut has been more affected by college basketball's ever-changing NIL, revenue sharing, transfer portal, and eligibility rules than Quinnipiac men's basketball.
With the season approaching, the Bobcats have lost all five starters from last season either to transfers or to the ambiguity of the new fifth-year eligibility rule.
The five starters lost accounted for the majority of Quinnipiac's scoring and rebounding last year.
"I am not fond of the changes that have been made in the college game," coach Tom Pecora said. "I started coaching in the early 80s and you were thrilled to get a scholarship, meal money and a chance to travel somewhere outside of your region or your state. I think it would be great if you paid kids after they graduated. Motivate them to graduate even if they go to several schools."
Two-time first-team All-Metro forward Amarri Monroe transferred to Syracuse while Jaden Zimmerman left for Grand Canyon, Grant Randall moved on to Dayton and Spence Wewe is now at Hofstra.
#starters #hamden
With the season approaching, the Bobcats have lost all five starters from last season either to transfers or to the ambiguity of the new fifth-year eligibility rule.
The five starters lost accounted for the majority of Quinnipiac's scoring and rebounding last year.
"I am not fond of the changes that have been made in the college game," coach Tom Pecora said. "I started coaching in the early 80s and you were thrilled to get a scholarship, meal money and a chance to travel somewhere outside of your region or your state. I think it would be great if you paid kids after they graduated. Motivate them to graduate even if they go to several schools."
Two-time first-team All-Metro forward Amarri Monroe transferred to Syracuse while Jaden Zimmerman left for Grand Canyon, Grant Randall moved on to Dayton and Spence Wewe is now at Hofstra.
#starters #hamden


14 days ago
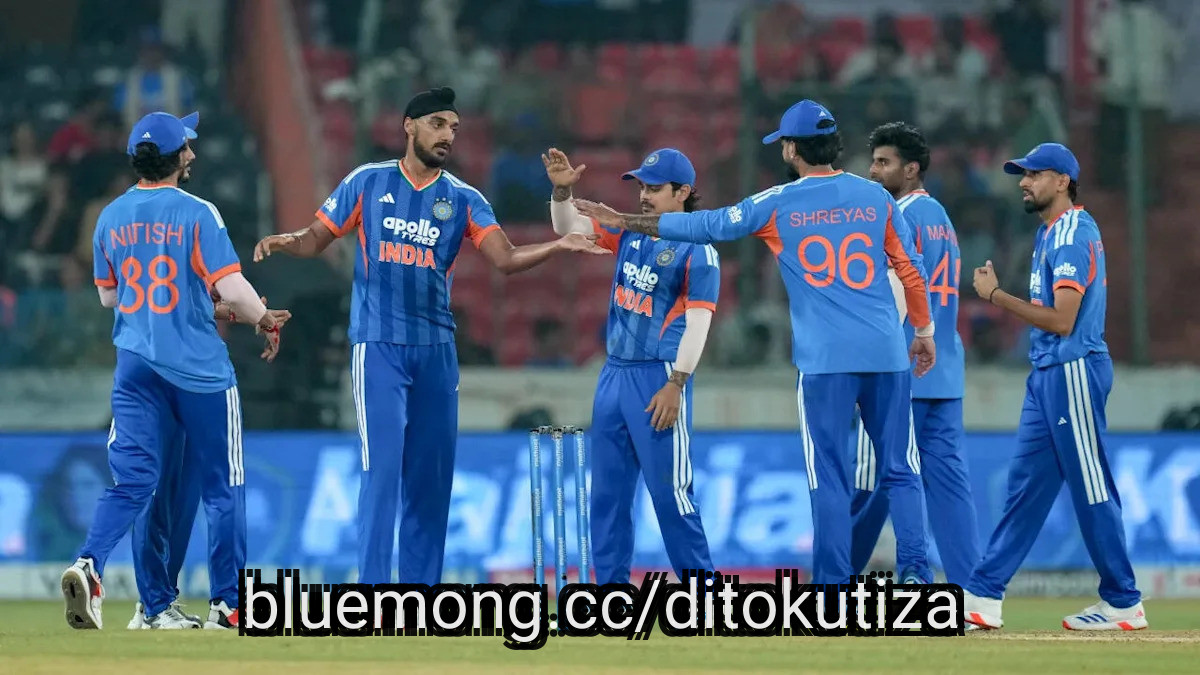
Bengaluru: When batters are scoring at 11.46 runs an over, even quality bowling attacks can be made to look ordinary. India's T20I series against the West Indies has exposed the vulnerability of the hosts' pace unit, with flat pitches, dew and short boundaries proving a punishing combination for bowlers.
West Indies' stunning 250-run chase in Ranchi, completed with nine **** to spare, prompted a stern **** sment from India head coach Gautam Gambhir.
"These bowlers are our bowlers, not someone else's bowlers. Their careers are at stake," he had said, underlining the scrutiny facing the attack.
With the exception of Indore, where India successfully defended 223, the bowlers struggled to contain a fearless West Indies batting line-up. While the absence of Jasprit **** rah and, to an extent, Hardik Pandya has been felt, the bigger concern for the team management is the inconsistency shown by Arshdeep Singh, Mayank Yadav and Prince Yadav.
The two young quicks, Mayank and Prince, have alternated between brilliance and waywardness during the series, highlighting the challenges of adjusting to different match situations. The fourth T20I in Hyderabad offered a clear example. India conceded 18 extras, including 13 wides. Arshdeep accounted for six, while Mayank and Prince leaked two and one, respectively. Their attempts to execute wide yorkers and fuller deliveries repeatedly missed the mark, allowing the West Indies batters to maintain the pressure.
India's lack of proven T20 pace-bowling depth has consequently become a talking point. That has put renewed focus on the return of Bhuvneshwar **** ar, whose recall after nearly four years away from the national side could prove timely.
The experienced swing bowler has enjoyed a productive run in the IPL, taking 45 wickets across the last two seasons. More importantly, his success has been built on control and execution rather than sheer pace, qualities that India's younger quicks have often lacked in this series.
Conditions, however, have offered little respite to bowlers. High-scoring surfaces and heavy dew have meant that even small lapses have come at a significant cost.
As India prepare for a demanding tour of New Zealand, they know the challenges ahead will be very different. The pitches may offer more **** istance, but the key question remains whether the bowling group can quickly adapt and improve its consistency.
On the eve of the rain-affected series finale in Bengaluru, fast-bowling coach Morne Morkel urged observers to consider the physical and mental demands placed on modern cricketers.
"We sometimes forget that mental fatigue plays a big part. We have to manage that and be smart with it. Some of the players went for the Asian Games and then straight into a full series against the West Indies. These guys are also human," Morkel said.
"Execution and skills become better when you've recovered, slept well and mentally refreshed. That's a challenge. We're going to N
West Indies' stunning 250-run chase in Ranchi, completed with nine **** to spare, prompted a stern **** sment from India head coach Gautam Gambhir.
"These bowlers are our bowlers, not someone else's bowlers. Their careers are at stake," he had said, underlining the scrutiny facing the attack.
With the exception of Indore, where India successfully defended 223, the bowlers struggled to contain a fearless West Indies batting line-up. While the absence of Jasprit **** rah and, to an extent, Hardik Pandya has been felt, the bigger concern for the team management is the inconsistency shown by Arshdeep Singh, Mayank Yadav and Prince Yadav.
The two young quicks, Mayank and Prince, have alternated between brilliance and waywardness during the series, highlighting the challenges of adjusting to different match situations. The fourth T20I in Hyderabad offered a clear example. India conceded 18 extras, including 13 wides. Arshdeep accounted for six, while Mayank and Prince leaked two and one, respectively. Their attempts to execute wide yorkers and fuller deliveries repeatedly missed the mark, allowing the West Indies batters to maintain the pressure.
India's lack of proven T20 pace-bowling depth has consequently become a talking point. That has put renewed focus on the return of Bhuvneshwar **** ar, whose recall after nearly four years away from the national side could prove timely.
The experienced swing bowler has enjoyed a productive run in the IPL, taking 45 wickets across the last two seasons. More importantly, his success has been built on control and execution rather than sheer pace, qualities that India's younger quicks have often lacked in this series.
Conditions, however, have offered little respite to bowlers. High-scoring surfaces and heavy dew have meant that even small lapses have come at a significant cost.
As India prepare for a demanding tour of New Zealand, they know the challenges ahead will be very different. The pitches may offer more **** istance, but the key question remains whether the bowling group can quickly adapt and improve its consistency.
On the eve of the rain-affected series finale in Bengaluru, fast-bowling coach Morne Morkel urged observers to consider the physical and mental demands placed on modern cricketers.
"We sometimes forget that mental fatigue plays a big part. We have to manage that and be smart with it. Some of the players went for the Asian Games and then straight into a full series against the West Indies. These guys are also human," Morkel said.
"Execution and skills become better when you've recovered, slept well and mentally refreshed. That's a challenge. We're going to N



14 days ago
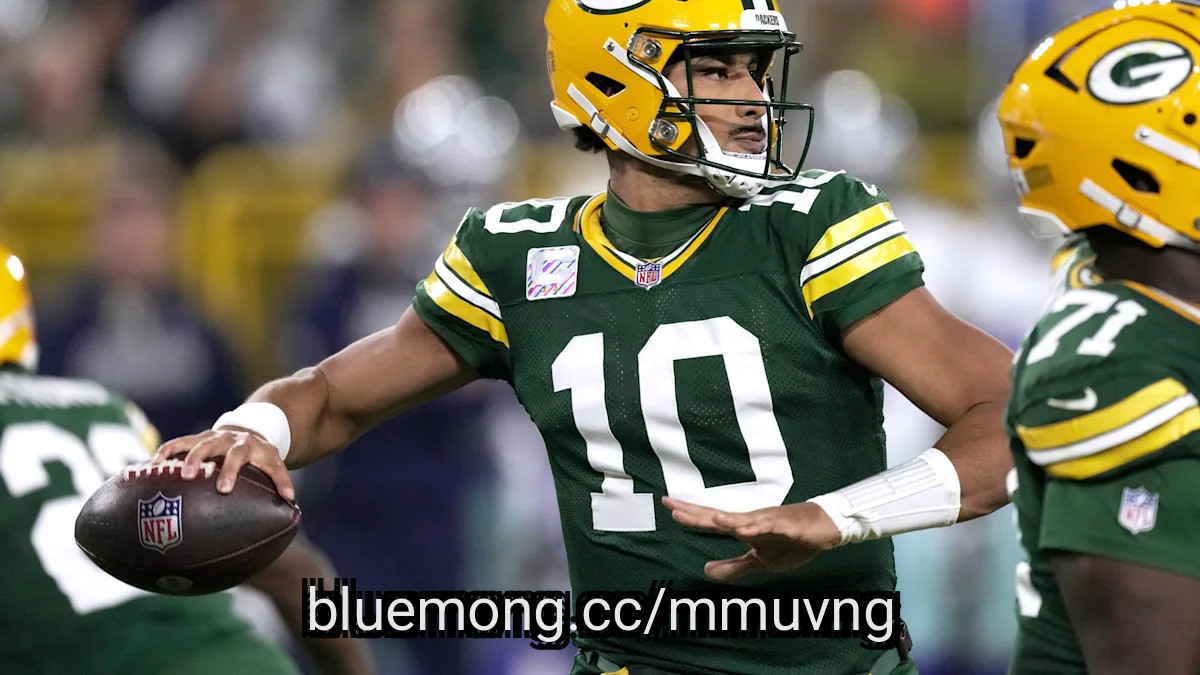
Green Bay Packers QB Jordan Love completed 23 of his 41 pass attempts for 276 yards, one touchdown, and one interception versus the Dallas Cowboys in Week 6. Love also had 12 yards and a touchdown on four carries.
SOURCE: USA TODAY
Why It Matters: It's almost impossible to overstate how much Green Bay's receivers undercut Love's output on Sunday night. Matthew Golden dropped three passes, including two touchdowns, and Christian Watson dropped another sure touchdown as well in a win over the Cowboys. Despite that, Love still threw for almost 300 yards and accounted for two touchdowns while navigating porous blocking from his offensive line. The Packers' inability to run the ball has put the onus on Love to move the offense, and that has helped the Utah State product develop into arguably the NFL's most aggressive downfield passer. It seems to work out more often than not, and Love has a high-end end matchup in Week 7 against Detroit. Love is a strong QB2 that's playable as a QB1 in plus matchups.
This article originally appeared on USA TODAY: Jordan Love accounts for two total touchdowns in win
#love #touchdowns #packers #jordan
SOURCE: USA TODAY
Why It Matters: It's almost impossible to overstate how much Green Bay's receivers undercut Love's output on Sunday night. Matthew Golden dropped three passes, including two touchdowns, and Christian Watson dropped another sure touchdown as well in a win over the Cowboys. Despite that, Love still threw for almost 300 yards and accounted for two touchdowns while navigating porous blocking from his offensive line. The Packers' inability to run the ball has put the onus on Love to move the offense, and that has helped the Utah State product develop into arguably the NFL's most aggressive downfield passer. It seems to work out more often than not, and Love has a high-end end matchup in Week 7 against Detroit. Love is a strong QB2 that's playable as a QB1 in plus matchups.
This article originally appeared on USA TODAY: Jordan Love accounts for two total touchdowns in win
#love #touchdowns #packers #jordan

25 days ago
It's common for new investors to want to hit home runs in their first at-bats. That situation is arguably amplified at a time when major equity indexes are regularly hitting record highs.
With glamorous, high-octane growth stocks leading the charge, some market participants may be losing sight of the value of the singles-and-doubles approach to dividend investing. Those investors shouldn't ignore history. Though the percentage trended lower over the past decade due to the prominence of low-yield and non-dividend tech darlings, dividends accounted for about a third of the S&P 500's total returns over the past century.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Most investors don't think in 100-year increments, and that's understandable, but when it comes to dividend investing, history and long-term perspectives matter. And the Schwab U.S. Dividend Equity ETF (NYSEMKT: SCHD) is a prime example of a dividend exchange-traded fund (ETF) with a compelling history for long-term investors.
Locked in a seemingly daily battle with the Vanguard Dividend Appreciation ETF for the ******* le of the largest dividend ETF, the $108 billion Schwab fund has a nearly unmatched track record. Two weeks shy of its 15th birthday, this ETF, which tracks the Dow Jones U.S. Dividend 100 Index, has returned 532% since its launch.
#investors
With glamorous, high-octane growth stocks leading the charge, some market participants may be losing sight of the value of the singles-and-doubles approach to dividend investing. Those investors shouldn't ignore history. Though the percentage trended lower over the past decade due to the prominence of low-yield and non-dividend tech darlings, dividends accounted for about a third of the S&P 500's total returns over the past century.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Most investors don't think in 100-year increments, and that's understandable, but when it comes to dividend investing, history and long-term perspectives matter. And the Schwab U.S. Dividend Equity ETF (NYSEMKT: SCHD) is a prime example of a dividend exchange-traded fund (ETF) with a compelling history for long-term investors.
Locked in a seemingly daily battle with the Vanguard Dividend Appreciation ETF for the ******* le of the largest dividend ETF, the $108 billion Schwab fund has a nearly unmatched track record. Two weeks shy of its 15th birthday, this ETF, which tracks the Dow Jones U.S. Dividend 100 Index, has returned 532% since its launch.
#investors

25 days ago
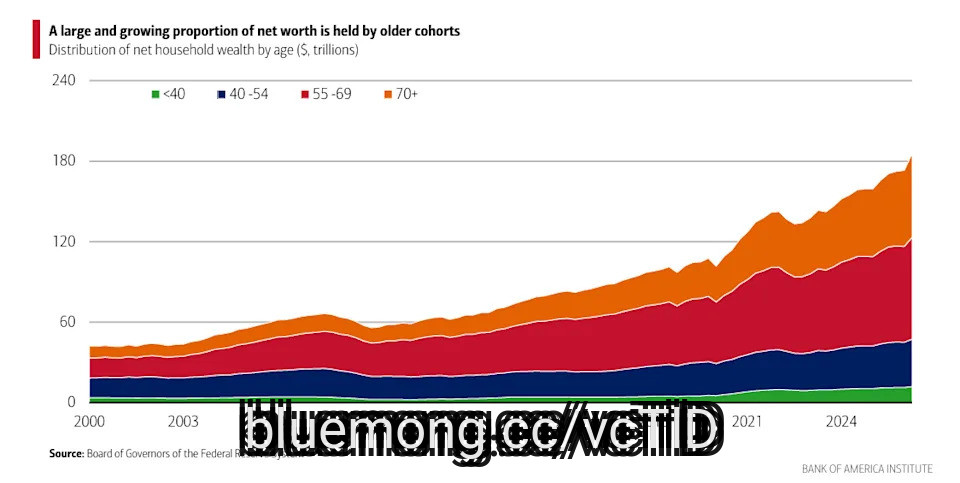
America's older households sit on nearly $140 trillion in wealth, and much of it showed up recently.
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report
Households age 55 and over held around three-quarters of the nation's total net worth in the second quarter of 2026, according to an Oct. 1 report from Bank of America Institute, based on ******* ysis of Federal Reserve data. "With equity markets rising strongly," wrote senior economist David Michael Tinsley, those households have seen "a more than 20% increase in their net worth over the past two years."
That rally has run on AI. The Magnificent Seven accounted for more than half of the S&P 500's gains last year, Fortune reported in April, and Goldman Sachs strategists found technology stocks drove 85% of the index's return through mid-May this year. "AI-driven return has been the single most important structural driver of equity performance," Capgemini's Luca Russignan told Yahoo Finance in June. Boomers own 54% of all U.S. stocks.
That's a lopsided split. Americans 55 and over make up about 31% of the population, according to Census Bureau estimates, but control roughly 75% of its net worth.
The pile gives many older Americans what the institute calls "considerable capacity to spend on travel and other leisure categories." Add their growing share of the population and their extra free time, and they become an increasingly influential market for businesses chasing consumer dollars. The BofA report focused mainly on the economic implications of a growing mass of older consumers, but the generational wealth composition was striking.
#households #institute #according #report

26 days ago
Michael Jackson's estate reported about $20 million in benefits for his three children and his mother during 2024, according to an annual accounting obtained by TMZ.
The filing, submitted by executor John Branca, details spending for Prince Jackson, Paris Jackson, Bigi Jackson and Katherine Jackson, including bills paid on their behalf.
Prince's approximately $4.9 million tax bill accounted for most of his reported benefits.
Katherine's entries included $145 at Cordie Cakes, $242 for balloons and $400 for cleaning services.
Prince had the largest reported benefits total at approximately $6.4 million. Payments connected to a Chevron gas card were also listed among his expenses.
#million #prince #approximately
The filing, submitted by executor John Branca, details spending for Prince Jackson, Paris Jackson, Bigi Jackson and Katherine Jackson, including bills paid on their behalf.
Prince's approximately $4.9 million tax bill accounted for most of his reported benefits.
Katherine's entries included $145 at Cordie Cakes, $242 for balloons and $400 for cleaning services.
Prince had the largest reported benefits total at approximately $6.4 million. Payments connected to a Chevron gas card were also listed among his expenses.
#million #prince #approximately

1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

1 month ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth

1 month ago
GDEV Inc. (NASDAQ:GDEV) saw a year-on-year drop in bookings from both its in-app purchases and advertising, during the second quarter fiscal 2026. Consequently, the quarterly revenue figure of $94 million was down 22% compared to Q2 FY25. On the flip side, SG&A expenses and costs related to platform commissions were lower relative to the corresponding period last year. Along with other factors, the lower cost base helped GDEV report $20 million in net profit, up from $17 million in the second quarter of 2025.
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower
Copyright: artush / 123RF Stock Photo
Breaking down the expenses, selling and marketing costs came down by 38% compared to the same quarter last year, clocking in at $33 million. It reflects on management's continued focus on deploying an efficient approach for its user acquisition initiatives. The approach is based on a more targeted performance marketing across certain channels that lead to durable high-value users, instead of broader campaigns for near-term benefits.
The reported quarter marked a turnaround related to the equity accounted ******* ociates. These contributed a $2 million profit share, which was a reversal from a $2 million loss share in Q2 FY25. Most notably, cash flows from operating activities turned from negative $10 million in Q2 FY25 to positive $10 million in the reported period.
Several operating metrics weakened during the reported quarter. Monthly paying users dropped by 23% year-over-year, along with a 15% decline for the entire first half. This was the major underlying reason for a sluggish performance in bookings, which stood at $73 million and $156 million for the second quarter and first half of the year, respectively. These fell short in comparison to $92 million and $173 million recorded in the corresponding periods last year. GDEV also said the decline in first-half platform commissions was driven by lower revenues recognized from PC platforms, while PC's share of bookings fell to 36% from 39%.
#million #lower

1 month ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment


1 month ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
1 month ago
Shoulder-season travel is giving some hotels opportunities to trade for longer and reduce their dependence on peak months. But additional demand only changes the investment proposition if those extra trading periods generate durable profit and improve the quality of annual cash flow.
Across parts of Europe, tourism demand is becoming less concentrated in traditional peak periods.
The shift should not be overstated. July and August still accounted for 31.1% of all EU tourist-accommodation nights in 2025, according to Eurostat. In highly seasonal markets, the concentration was much greater: 54.5% of Croatia's annual nights and 41.6% of Greece's occurred during those two months.
But demand is moving at the margins. The European Travel Commission reported stronger autumn demand in several markets in late 2025. In Hungary, for example, growth in international arrivals and nights during autumn exceeded summer growth.
For hotel investors, however, a longer potential travel season is only the starting point.
#season
Across parts of Europe, tourism demand is becoming less concentrated in traditional peak periods.
The shift should not be overstated. July and August still accounted for 31.1% of all EU tourist-accommodation nights in 2025, according to Eurostat. In highly seasonal markets, the concentration was much greater: 54.5% of Croatia's annual nights and 41.6% of Greece's occurred during those two months.
But demand is moving at the margins. The European Travel Commission reported stronger autumn demand in several markets in late 2025. In Hungary, for example, growth in international arrivals and nights during autumn exceeded summer growth.
For hotel investors, however, a longer potential travel season is only the starting point.
#season



1 month ago
Toast (NYSE: TOST) is a leading provider of financial technology services for businesses in the restaurant industry. The business is growing rapidly and still seems to have a long runway for expansion, but some of its business segments are carrying a lot more weight on the profitability front than others.
In the second quarter, Toast's revenue grew 23% to reach roughly $1.91 billion. Meanwhile, the business posted net income of $154 million in the period -- good for a margin of roughly 80.7%. The company's payments business once again did the heavy lifting in driving profits, but the picture is also more nuanced.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, the financial technology solutions segment that includes Toast's payments business accounted for $1.57 billion of its overall sales in the period -- roughly 82.2% of the total pie. While the segment's total cost of revenue accounted for roughly $1.21 billion of the total $1.39 billion cost of sales in the quarter, it was still central to the business's gross profit of roughly $516 million in the quarter.
Notably, the company's hardware and professional services segment had a substantially negative gross margin in Q2. While the unit posted revenue of roughly $48 million in the period, it had a cost of revenue of $116 million -- and that doesn't factor in operating expenses for the segment.
#business
In the second quarter, Toast's revenue grew 23% to reach roughly $1.91 billion. Meanwhile, the business posted net income of $154 million in the period -- good for a margin of roughly 80.7%. The company's payments business once again did the heavy lifting in driving profits, but the picture is also more nuanced.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, the financial technology solutions segment that includes Toast's payments business accounted for $1.57 billion of its overall sales in the period -- roughly 82.2% of the total pie. While the segment's total cost of revenue accounted for roughly $1.21 billion of the total $1.39 billion cost of sales in the quarter, it was still central to the business's gross profit of roughly $516 million in the quarter.
Notably, the company's hardware and professional services segment had a substantially negative gross margin in Q2. While the unit posted revenue of roughly $48 million in the period, it had a cost of revenue of $116 million -- and that doesn't factor in operating expenses for the segment.
#business

2 months ago
GE Vernova Inc (NYSE:GEV) rebounded with Bernstein's backing after an earlier sell-off that followed broader concerns about technology infrastructure spending.
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing


2 months ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion


2 months ago
During the September 10 episode of Mad Money, a caller inquired about Mad Money host Jim Cramer's confidence that Arista Networks, Inc. (NYSE:ANET) will not go down the same path as Ciena Corporation. He replied:
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year
Okay, so let me just tell you, Arista is up a lot this year. My confidence is with Jayshree Ullall. I think she's amazing and I think it every time the stock has dipped, if you've noticed it. Since her tenure began, you have to buy it, and I'm not backing away from that. I feel the same way I do now, the way I did, oh man, how many years ago when we first met her. She is money, and the company's fantastic.
In its second quarter, the company shattered records by delivering its first-ever $3 billion quarter, reporting $3.036 billion in revenue, a 38% year-over-year and over 12% sequential increase. Management lifted its full-year 2026 revenue guidance to approximately $12.6 billion, representing roughly 40% annual top-line growth. The acceleration is supported by deep integration into cloud architectures, where Arista Networks, Inc. (NYSE:ANET) expects its dedicated AI fabrics revenue to reach at least $3.5 billion in 2026, supported by more than 100 **** ulative Etherlink customers.
Bottom-line performance remains equally strong, with non-GAAP diluted earnings per share reaching $1.02, driven by a 49.9% non-GAAP operating margin and $1.3 billion in non-GAAP quarterly net income. Arista Networks, Inc. (NYSE:ANET) ended the quarter with roughly $13.3 billion in cash and marketable securities, offering substantial liquidity. However, its $9.7 billion of non-cancellable purchase commitments also increase working-capital and inventory risk as the company secures components ahead of expected AI demand.
The company's financial results remain heavily tied to two hyperscale customers. According to its 10-K filings, Microsoft accounted for 26%, and Meta Platforms generated 16% of total revenue in fiscal 2025, bringing combined spending from these two cloud giants to 42%. It leaves Arista Networks, Inc. (NYSE:ANET) vulnerable to sudden capital expenditure adjustments, vendor diversification shifts, or project delays by its core buyers.
#billion #NYSE #year

2 months ago
MiKargo247 is expanding its spot cargo insurance coverage to include strategic cargo theft under a new partnership with Verified Carrier.
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies
The coverage is designed to address a growing category of freight fraud involving double brokering, carrier identity theft and fictitious pickups. Under the partnership, brokers using Verified Carrier can purchase MiKargo247 spot cargo insurance and have the strategic theft exclusion removed when the load is hauled by an eligible verified carrier. The companies announced the partnership Sept. 1.
Strategic cargo theft accounted for about 30% of reported U.S. cargo theft incidents in 2025, according to a June report from Munich Re Specialty and BSI Consulting. The report found that criminals are increasingly using deception, impersonation and other fraud-based methods to obtain freight rather than relying solely on physically stealing cargo from trucks or facilities.
The shift creates a challenge for brokers and insurers because fraudulent actors can make it difficult to determine who is actually hauling a load.
The FBI warned in April that cyber-enabled strategic cargo theft is increasing, with criminals using compromised accounts, fictitious companies and double-brokering schemes to divert legitimate freight. The agency recommended that transportation companies independently verify shipment requests and pickups before releasing loads.
#carrier #partnership #Companies

2 months ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
2 months ago
Investors choosing between Carnival (NYSE:CCL) and Uber Technologies (NYSE:UBER) must decide between a capital-intensive cruise leader and a high-growth technology platform. Both companies have shown resilience, but their financial structures offer very different risks.
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current
Carnival operates as a global giant in the travel industry, managing a diverse fleet of ships that cater to millions of vacationers. Uber dominates the gig economy by connecting riders, diners, and shippers with service providers through its proprietary mobile applications and digital infrastructure.
As a major player among consumer discretionary stocks, Carnival operates a massive fleet of over 90 ships across eight distinct brands. In its latest annual report, the company highlighted a workforce of over 160,000 team members who served approximately 13.5 million guests throughout 2025. This scale allows the company to source passengers from major global markets, and notably, no single travel agency group accounted for more than 10% of total revenue during the year.
In FY 2025, revenue reached nearly $26.6 billion, representing a growth rate of roughly 6.4% compared to the prior year. This top-line expansion helped the company generate a net income of approximately $2.8 billion, a significant improvement over the $1.9 billion recorded in 2024. The net margin improved to 10.4%, indicating that the company is successfully converting a larger portion of its sales into actual profit.
Based on its November 2025 balance sheet, Carnival carries a debt-to-equity ratio of 2.3x, which is the total debt divided by shareholder equity. Its current ratio, a measure of current **** ets relative to current liabilities, is nearly 0.3x, suggesting tight short-term liquidity. However, the company generated close to $2.6 billion in free cash flow, which is cash from operations minus capital expenditures, providing capital for debt reduction and fleet maintenance.
#carnival #fleet #current

2 months ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care

2 months ago
AI investors are weighing warnings from technology executives about the safety risks posed by the rapid advancement of artificial intelligence. However, some believe that slowing AI development could leave the US behind China and other competitors in the global race. Brad Gerstner, founder and CEO of Altimeter Capital, said on CNBC that he supports AI safety measures but believes some fears are being exaggerated to advance a political agenda.
"I've not talked to a single person in AI who says, full steam ahead, disregard safety," Gerstner said. "It turns out we all care about kids. We all care about the future of the country. We know the massive benefits it offers, but we also want to take the extra time to make sure that we do this safely. But what I didn't like this week is these hyperbolic scare tactics, which I think are hiding behind a political agenda. We learn that all of this catastrophizing about data centers may in fact, have had support from the CCP. Right? So I want a little investigation. Who is behind all of this negativity? Is it coordinated? Right? Where is the money coming from?"
Altimeter's second-quarter 13F filings show that the fund opened new positions in several technology and AI-related companies, including Qualcomm (QCOM) and Micron Technology (MU).
Altimeter bought 1.88 million Qualcomm shares valued at about $347.9 million as of June 30. The position accounted for 3.54% of the fund's reported US equity portfolio. It also acquired 209,520 Micron shares worth roughly $241.8 million, representing 2.46% of the portfolio.
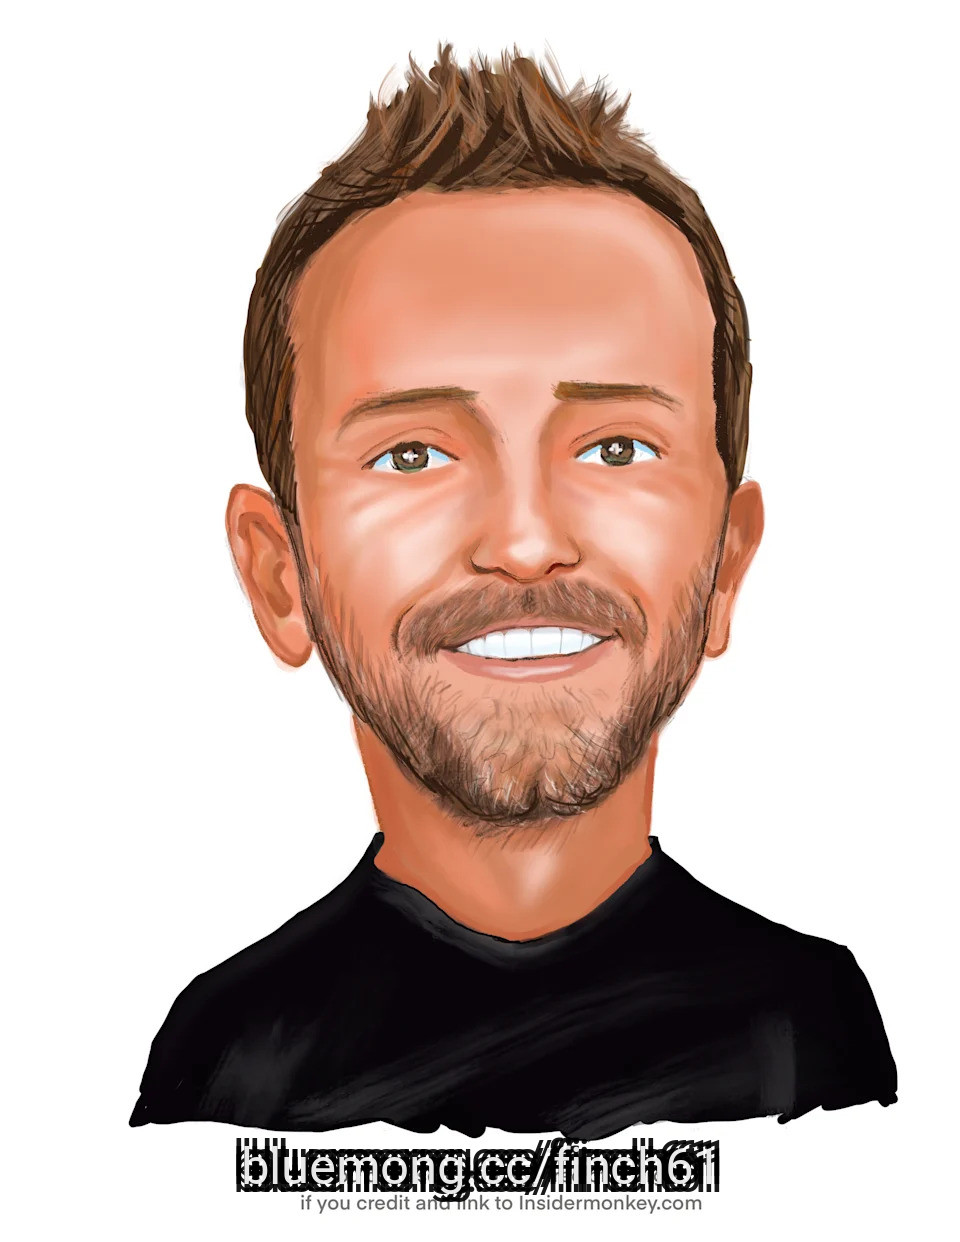
Brad Gerstner of Altimeter Capital
#behind #qualcomm
"I've not talked to a single person in AI who says, full steam ahead, disregard safety," Gerstner said. "It turns out we all care about kids. We all care about the future of the country. We know the massive benefits it offers, but we also want to take the extra time to make sure that we do this safely. But what I didn't like this week is these hyperbolic scare tactics, which I think are hiding behind a political agenda. We learn that all of this catastrophizing about data centers may in fact, have had support from the CCP. Right? So I want a little investigation. Who is behind all of this negativity? Is it coordinated? Right? Where is the money coming from?"
Altimeter's second-quarter 13F filings show that the fund opened new positions in several technology and AI-related companies, including Qualcomm (QCOM) and Micron Technology (MU).
Altimeter bought 1.88 million Qualcomm shares valued at about $347.9 million as of June 30. The position accounted for 3.54% of the fund's reported US equity portfolio. It also acquired 209,520 Micron shares worth roughly $241.8 million, representing 2.46% of the portfolio.
Brad Gerstner of Altimeter Capital
#behind #qualcomm

2 months ago
While Youngstown State quarterback Beau Brungard received the Stats Perform FCS National Offensive Player of the Week honor on Monday, Indiana State quarterback Elijah Owens was listed among others for honorable mention.
Brungard, a fifth-year senior, accounted for a touchdown in all eight of the Penguins' series possessions, with him at QB, in YSU's 70-13 rout of Duquesne on Saturday. He completed 20 of 23 passes for 290 yards and six TDs, while also running for two touchdowns.
Five other players received honorable mention for the weekly award, including Owens, former Sycamore running back Plez Lawrence (now at North Carolina Central), Montana running back Eli Gillman, Stonehill quarterback Jack O'Connell, and Alcorn State quarterback Jaylon Tolbert.
Owens delivered his best performance as a Sycamore in Indiana State's 42-35 win at Eastern Illinois on Saturday night. The redshirt junior quarterback threw for 284 yards, ran for 98 yards, and scored five total touchdowns (three passing, two rushing). Overall, Owens was 21-of-33 through the air for 284 yards and three passing touchdowns, while adding 18 carries for 98 yards and two additional scores.
Meanwhile, Lawrence — who played at ISU from 2023-25 and rushed for 1,164 total yards in 270 carries — ran for 210 yards and three touchdowns in North Carolina Central's 30-22 win against North Carolina A&T on Saturday in Durham. Lawrence also had a 200-plus-yard game as a Sycamore, gaining 203 yards in 29 carries at Murray State on Sept. 30, 2023.
#state #owens #sycamore #carolina
Brungard, a fifth-year senior, accounted for a touchdown in all eight of the Penguins' series possessions, with him at QB, in YSU's 70-13 rout of Duquesne on Saturday. He completed 20 of 23 passes for 290 yards and six TDs, while also running for two touchdowns.
Five other players received honorable mention for the weekly award, including Owens, former Sycamore running back Plez Lawrence (now at North Carolina Central), Montana running back Eli Gillman, Stonehill quarterback Jack O'Connell, and Alcorn State quarterback Jaylon Tolbert.
Owens delivered his best performance as a Sycamore in Indiana State's 42-35 win at Eastern Illinois on Saturday night. The redshirt junior quarterback threw for 284 yards, ran for 98 yards, and scored five total touchdowns (three passing, two rushing). Overall, Owens was 21-of-33 through the air for 284 yards and three passing touchdowns, while adding 18 carries for 98 yards and two additional scores.
Meanwhile, Lawrence — who played at ISU from 2023-25 and rushed for 1,164 total yards in 270 carries — ran for 210 yards and three touchdowns in North Carolina Central's 30-22 win against North Carolina A&T on Saturday in Durham. Lawrence also had a 200-plus-yard game as a Sycamore, gaining 203 yards in 29 carries at Murray State on Sept. 30, 2023.
#state #owens #sycamore #carolina



2 months ago
A few weeks ago, I used Uber Eats to deliver me a case of bottled water, a dozen Starbucks iced coffee bottles, and a 12-pack of Gatorade Zero.
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero
It cost a little more than going to the store less than two miles from our house, but instead of having to lug those bulky items from the store to my car and then my kitchen, I only had to bring them in from the front door.
That was either a lazy choice or evidence of excellent time management skills, but it's a solid example of how people use the internet. Because while people generally think it's much higher (I've asked the question to thousands of people on various podcasts and live shows over the years), digital sales are still a relatively small percentage of total retail sales.
"E-commerce sales in the second quarter of 2026 accounted for 17.1 percent of total sales," United States Census Bureau data showed.
Consumers have shifted some of their purchases online, and they're looking for convenience.
#people #zero
2 months ago
For much of the past year, the "AI trade" has been focused on infrastructure: processors, data centers, and cloud capacity. Snowflake Inc. (NYSE:SNOW)'s blowout quarter, which was reported after the market closed on September 2, provided something unique: clear evidence that AI is translating into real, incremental spending within software companies that are closer to the end customer. The reaction echoed throughout corporate software the next morning, adding to a rally that, for Salesforce, Inc. (NYSE:CRM) in particular, had already begun for its own reasons.
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
Snowflake Inc. (NYSE:SNOW) boosted its fiscal 2027 product revenues target to $6.07 billion from $5.84 billion, following a 37% increase in second-quarter product revenue to $1.49 billion. CEO Sridhar Ramaswamy stated that the company's AI products accounted for around half of that growth acceleration, which ****** ysts took as implying that AI demand is increasing Snowflake's core data platform, instead of just adoption of standalone AI add-ons. UBS ****** yst Karl Keirstead said the figures, together with Palantir and Databricks' rapid growth, gave compelling proof of robust enterprise AI adoption.
Snowflake's beat rippled across enterprise software, with ServiceNow, Atlassian, Adobe, Intuit, and Salesforce, Inc. (NYSE:CRM) all up 3.5% to 6% on the same day, while the sector-wide iShares Expanded Tech-Software ETF rose 3%.
That Snowflake-driven spike was piled on top of a much bigger adjustment made by Salesforce, Inc. (NYSE:CRM) on its own. The company released its second-quarter fiscal 2027 results on August 26, a week before Snowflake Inc. (NYSE:SNOW), with revenue of $11.35 billion, up 11% year-over-year, with current remaining performance obligations up 14% to $33.5 billion and adjusted EPS of $5.90, exceeding the $3.27 consensus. Along with those results, Salesforce and Anthropic announced Claudeforce, an expanded partnership that initially brings Salesforce data, workflows and business logic directly into Claude through a plugin with 37 prebuilt sales skills. The companies plan additional integrations across Claude, Salesforce and Slack. That said, Salesforce recorded $2.61 billion in net gains on strategic investments during the quarter, which added $2.53 per share to non-GAAP EPS.
Taken together, the two events suggest that enterprise AI adoption can increase the value and consumption of established software platforms when AI is connected to existing corporate data and workflows
#billion #software #data #quarter
2 months ago
On September 10, Copart (NASDAQ:CPRT) held its fourth-quarter earnings call and used it to unveil a deal that could reshape its business: an all-cash agreement to acquire ACV, a digital auto marketplace that moved roughly $10 billion of vehicles last year without owning a single lot. The announcement landed alongside a quarter that captured the company's central tension. Revenue rose, but net income fell, and management is now betting that pairing its junkyards with someone else's software can fix that.
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
The ACV deal is the headline, and for good reason. ACV brings more than 22,000 active buyers and inspection and valuation technology, while Copart contributes over 275 locations, roughly 4 million vehicles sold annually, and about 1 million members across more than 185 countries. Management structured it as an all-cash tender offer funded from cash on hand, with a close targeted by the end of the calendar year and earnings accretion expected in fiscal 2028. Executives framed the fit as physical scale meeting digital liquidity, giving dealers, banks, and fleet sellers a single partner for disposing of vehicles.
That diversification push is already showing up in the numbers. International revenue grew 11.7% to $222.1 million on 15% service revenue growth, and international buyers accounted for 45.7% of total US sales dollars despite making up only 38.2% of units, a sign they are chasing pricier vehicles. Domestically, non-insurance units returned to growth of 0.2% in the quarter after a full-year decline, dealer units rose 5.8%, and BluCar, which serves banks and fleets, expanded nearly 20%. Global average selling prices climbed 3.5%, evidence that Copart's auctions still command pricing power even as volumes soften.
The quarter's numbers show where the strain is. Consolidated revenue grew 2.4% to $1.2 billion, yet net income dropped 17.4% to $327.4 million and diluted earnings per share fell 14.6% to $0.35. Operating expense per car jumped 12.7% year over year as the company poured money into long-haul delivery, **** leExpress, and dedicated wholesale facilities, and US facility costs alone rose 7.7% in the quarter. Lower interest income, a byproduct of the $1.63 billion spent on buybacks earlier in the fiscal year, added to the squeeze.
The core insurance business is also cooling. Global insurance units fell 4.2%, with domestic insurance **** ignments down 7.5%, though management noted that figure would have been up 2.3% excluding the loss of a single customer. Collision claim frequency declined 3.4% even as total loss frequency hit a record 23.3% for a second quarter and severity topped $6,300 per claim, up 8.8%. And the ACV deal itself carries integration risk, since management expects only breakeven results before accretion arrives in fiscal 2028.
#quarter #vehicles #insurance
2 months ago
On September 10, Designer Brands (NYSE:DBI) reported second-quarter results that pushed full-year earnings guidance sharply higher, even as net sales slipped 1% year over year to $730.6 million. Adjusted operating income reached $39.4 million for the quarter, and management raised its adjusted diluted earnings per share outlook to a range of $0.47 to $0.52, up from $0.28 to $0.38. That kind of upward revision usually calms skeptics. Here, more than a third of the float is still sold short.
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands
The clearest story in this report is a company reorganizing itself around its own brands rather than its stores. Brand portfolio sales climbed 18% in the quarter to $86.3 million, and the growth showed up on the bottom line too, with year-to-date adjusted operating income of $58.8 million, more than doubling what Designer Brands produced over the same stretch last year. Topo grew revenue more than 24% during the quarter, and management now expects the brand to clear $100 million in 2027. Jessica Simpson sales rose about 24% as well, with growth across every major account, and intercompany sales between the brand and retail segments rose by double digits, a sign the two sides of the business are reinforcing each other rather than splitting the same customer dollar.
Profitability improved even where the headlines are less flashy. Gross margin expanded 430 basis points to 47.9%, and while $20.2 million in tariff refunds accounted for much of that, the company still added 150 basis points of margin from better ***** ortment and inventory management alone. Merchandise margin in retail widened 140 basis points, with 100 of those points coming from less markdown activity, meaning more inventory is selling at full price. Debt fell by $93 million to $423.1 million compared with a year earlier, and total liquidity stood at roughly $198 million, funding room for projects like the Topo sourcing integration and the new Edit at DSW store-within-a-store pilot without leaning further on the balance sheet.
The retail side of the business is still the drag. CEO Doug Howe said sandals, the company's largest seasonal category, "were pressured by early weather-related headwinds and never fully rebounded," and that alone accounted for roughly 200 basis points of the retail segment's 2% sales decline. Comparable sales fell 2.6% in retail and 2.4% companywide, and the segment battled a sequential traffic headwind even as average unit retail and average dollars per sale held firm. Strip out the brand portfolio's 18% growth, and the underlying store business is still shrinking.
#million #brands


2 months ago
Philippine authorities said it could take weeks or months to identify victims of a ferry fire that killed 76 people last week.
"Most of them are already in a charred condition," Richard Allan Mangalip, a forensic specialist from the Philippine National Police, told reporters on Sunday. Family members have been asked to help identify victims with personal items or DNA samples.
The MV June Aster was heading from Manila to Coron in Palawan province, a popular holiday destination, when a fire started in its cargo hold and spread rapidly throughout the vessel.
Forty-three people survived the disaster, while 13 people remain unaccounted for, authorities said.
Mangalip said they were "trying [their] best to collect the possible identifying marks" from victims' remains.
#mangalip #authorities #national
"Most of them are already in a charred condition," Richard Allan Mangalip, a forensic specialist from the Philippine National Police, told reporters on Sunday. Family members have been asked to help identify victims with personal items or DNA samples.
The MV June Aster was heading from Manila to Coron in Palawan province, a popular holiday destination, when a fire started in its cargo hold and spread rapidly throughout the vessel.
Forty-three people survived the disaster, while 13 people remain unaccounted for, authorities said.
Mangalip said they were "trying [their] best to collect the possible identifying marks" from victims' remains.
#mangalip #authorities #national
2 months ago
FORT COLLINS, Colo. (AP) — Hauss Hejny accounted for five touchdowns to lead Colorado State to a 58-24 victory over Southern Utah on Saturday night.
Hejny finished 18 of 30 for 325 yards and threw four touchdown passes. He added 85 yards on the ground on five carries that included a 75-yard touchdown run with 12:31 left in the game to cap the scoring.
Colorado State, which is 2-0 for the first time since 2011, led 48-21 at halftime and finished with 678 yards of offense. It was their highest scoring output since posting 52 points against Boise State on Nov. 11, 2017.
Mel Brown had a 73-yard touchdown run and finished with nine carries for 171 yards and two touchdowns. Jackson Harper made six catches for 102 yards receiving with a touchdown. Terrence Smith Jr. caught two touchdown passes and finished with four receptions for 90 yards. Cedric Ross had a pair of catches for 87 yards and a score.
Will Burns was 12-of-23 passing for 233 yards and threw a touchdown pass and two interceptions for Southern Utah (1-2). Floyd Chalk had 17 catches for 144 yards with two scores for the Thunderbirds.
#state #catches #Colorado #southern
Hejny finished 18 of 30 for 325 yards and threw four touchdown passes. He added 85 yards on the ground on five carries that included a 75-yard touchdown run with 12:31 left in the game to cap the scoring.
Colorado State, which is 2-0 for the first time since 2011, led 48-21 at halftime and finished with 678 yards of offense. It was their highest scoring output since posting 52 points against Boise State on Nov. 11, 2017.
Mel Brown had a 73-yard touchdown run and finished with nine carries for 171 yards and two touchdowns. Jackson Harper made six catches for 102 yards receiving with a touchdown. Terrence Smith Jr. caught two touchdown passes and finished with four receptions for 90 yards. Cedric Ross had a pair of catches for 87 yards and a score.
Will Burns was 12-of-23 passing for 233 yards and threw a touchdown pass and two interceptions for Southern Utah (1-2). Floyd Chalk had 17 catches for 144 yards with two scores for the Thunderbirds.
#state #catches #Colorado #southern


2 months ago
Duke improved to 2-0 on the season with a hard-fought 31-27 victory over Illinois on the road in Champaign in a sold out Gies Memorial Stadium. A non-conference Power Four win is a huge accomplishment in Week Two of the season.
Quarterback Walker Eget completed 15 of 21 passes for 206 yards and three touchdowns. Nate Sheppard rushed 24 times for 147 yards and one touchdown, and caught five passes for 41 yards and two touchdowns. Wide receiver Jonah Burton caught four passes for 76 yards and a touchdown.
Cornerback Evan Smith accounted for the game's only turnover when he intercepted a pass from Illinois quarterback Katin Houser.
Play One: Illinois was leading 17-7 and Duke was facing a 4th down and four yards to go with nine minutes and 41 seconds remaining in the 2nd quarter. Duke lined up to punt but hiked the ball to Nate Sheppard instead of punter Kade Reynoldson and Sheppard ran for 15 yards and a 1st down. This play switched momentum from the Illini to the Blue Devils. Four plays later Nate Sheppard rushed two yards for a touchdown cutting the Illini lead to 17-14.
Play Two: At the eight minutes and 28 seconds mark of the 1st quarter, quarterback Walker Eget hit wide receiver Jonah Burton for a 12 yards touchdown pass to tie the game at 7-7. Burton did a great job securing the ball as he went to the ground.
#illinois
Quarterback Walker Eget completed 15 of 21 passes for 206 yards and three touchdowns. Nate Sheppard rushed 24 times for 147 yards and one touchdown, and caught five passes for 41 yards and two touchdowns. Wide receiver Jonah Burton caught four passes for 76 yards and a touchdown.
Cornerback Evan Smith accounted for the game's only turnover when he intercepted a pass from Illinois quarterback Katin Houser.
Play One: Illinois was leading 17-7 and Duke was facing a 4th down and four yards to go with nine minutes and 41 seconds remaining in the 2nd quarter. Duke lined up to punt but hiked the ball to Nate Sheppard instead of punter Kade Reynoldson and Sheppard ran for 15 yards and a 1st down. This play switched momentum from the Illini to the Blue Devils. Four plays later Nate Sheppard rushed two yards for a touchdown cutting the Illini lead to 17-14.
Play Two: At the eight minutes and 28 seconds mark of the 1st quarter, quarterback Walker Eget hit wide receiver Jonah Burton for a 12 yards touchdown pass to tie the game at 7-7. Burton did a great job securing the ball as he went to the ground.
#illinois




