2 days ago
Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) could be positioning itself for its next major phase of growth following its roughly $10 billion acquisition of Crinetics Pharmaceuticals. The deal gives the company immediate exposure to the endocrinology market and provides a new commercial platform beyond its established cystic fibrosis franchise.
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify
On September 3, Citigroup **** yst Geoff Meacham highlighted the strategic importance of the Crinetics acquisition, arguing it could diversify Vertex's business while complementing its existing cystic fibrosis franchise and newer businesses in renal disease, hematology, and pain.
Through the transaction, Vertex Pharmaceuticals Incorporated (NASDAQ:VRTX) gains access to Palsonify (paltusotine), an oral treatment for acromegaly that has already received regulatory approval in Europe. Paltusotine is also in Phase 3 development for carcinoid syndrome **** ociated with neuroendocrine tumors.
Palsonify is particularly important because it provides an immediate commercial revenue opportunity, rather than requiring the company to wait several years for an entirely new drug to reach the market.
Early uptake of Palsonify has been encouraging, supported by expanding physician adoption and improving reimbursement coverage. If that momentum continues, the drug could become an important contributor to Vertex's revenue growth.
#palsonify


2 days ago
On August 13, a federal appeals court ruled in favor of Gilead Sciences, Inc. (NASDAQ:GILD), upholding a preliminary injunction that bars the defendants from importing or facilitating the sale of foreign-market Gilead-branded medications in the US. The US Court of Appeals for the Fourth Circuit found that the differences between Gilead's HIV medication for the US market and the foreign versions being imported were "material, not theoretical." The controversy began in December 2024 when Gilead Sciences, Inc. (NASDAQ:GILD) filed suit against a number of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its best-selling HIV drug Biktarvy.
The dispute dates back to December 2024, when Gilead Sciences, Inc. (NASDAQ:GILD) sued a group of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its top-selling HIV drug Biktarvy. The lawsuit arose from a specific instance in which a patient in Maryland received the medicine in the mail from Turkey, with label instructions written in Turkish.
A federal district court in Baltimore ruled in Gilead's favor and ordered a preliminary injunction, determining that the company was likely to succeed on its Lanham Act trademark violation and unfair competition arguments. As the case continued, the injunction was increased to include new sellers like CanaRx, ElectRx, and ScriptSourcing. The defendants filed an appeal with the Fourth Circuit, and the district judge declined to suspend the injunction while the appeal was pending, thus the import restriction has been in effect the entire time. The recent ruling maintains the order rather than overturning it.
In court documents, Rx Valet stated that the Turkish-sourced Biktarvy was chemically identical to the US version, which was offered at a significantly higher price. Meritain, for its part, said that it has never supported getting non-FDA-approved pharmaceuticals from outside the US and denies the claims, despite being named as a defendant.
The Fourth Circuit rejected the defendants' main argument that the imported and domestic versions of Biktarvy are interchangeable. The court's judgment that the two versions differ materially, not just in packaging or labeling, but also in the quality-control protocols that each version goes through before reaching a patient, challenges the basic argument that these alternative funding programs have used to support their business model.
#gild
The dispute dates back to December 2024, when Gilead Sciences, Inc. (NASDAQ:GILD) sued a group of companies, including third-party administrator Meritain Health, pharmacy benefit manager ProAct, and pharmacies Rx Valet and Advanced Pharmacy, alleging illegal imports of its top-selling HIV drug Biktarvy. The lawsuit arose from a specific instance in which a patient in Maryland received the medicine in the mail from Turkey, with label instructions written in Turkish.
A federal district court in Baltimore ruled in Gilead's favor and ordered a preliminary injunction, determining that the company was likely to succeed on its Lanham Act trademark violation and unfair competition arguments. As the case continued, the injunction was increased to include new sellers like CanaRx, ElectRx, and ScriptSourcing. The defendants filed an appeal with the Fourth Circuit, and the district judge declined to suspend the injunction while the appeal was pending, thus the import restriction has been in effect the entire time. The recent ruling maintains the order rather than overturning it.
In court documents, Rx Valet stated that the Turkish-sourced Biktarvy was chemically identical to the US version, which was offered at a significantly higher price. Meritain, for its part, said that it has never supported getting non-FDA-approved pharmaceuticals from outside the US and denies the claims, despite being named as a defendant.
The Fourth Circuit rejected the defendants' main argument that the imported and domestic versions of Biktarvy are interchangeable. The court's judgment that the two versions differ materially, not just in packaging or labeling, but also in the quality-control protocols that each version goes through before reaching a patient, challenges the basic argument that these alternative funding programs have used to support their business model.
#gild


3 days ago
TROY - With a pair of former University at Albany quarterbacks at the controls, the Utica offense shredded RPI again on Saturday.
Former Great Danes backup Tyler Szalkowski completed 29 of 38 passes for 402 yards and a pair of touchdowns to lead the Pioneers to a 38-14 victory over the Engineers at East Campus Stadium.
"I enjoyed my time at Albany," said Szalkowski, who spent the 2021 and 2022 seasons with the Great Danes. "Everything they did for me just made me who I am today."
Utica improved to 2-0, while RPI fell to 1-1.
It was the second straight year Szalkowski picked apart RPI. He was 27-of-29 passing for 385 yards and six touchdowns when the Pioneers blew out the Engineers 41-14 in Utica last season.
#utica #great #former
Former Great Danes backup Tyler Szalkowski completed 29 of 38 passes for 402 yards and a pair of touchdowns to lead the Pioneers to a 38-14 victory over the Engineers at East Campus Stadium.
"I enjoyed my time at Albany," said Szalkowski, who spent the 2021 and 2022 seasons with the Great Danes. "Everything they did for me just made me who I am today."
Utica improved to 2-0, while RPI fell to 1-1.
It was the second straight year Szalkowski picked apart RPI. He was 27-of-29 passing for 385 yards and six touchdowns when the Pioneers blew out the Engineers 41-14 in Utica last season.
#utica #great #former


3 days ago
UTICA - The Utica, Northridge and Johnstown football teams all used late scores to earn victories in Week 4 on a wild night across Licking County and beyond.
Licking Valley and Newark Catholic each improved to 4-0, and Heath and Watkins Memorial also were victorious.
Columbus Academy 36, Granville 14
Heath 58, Washington CH 28
Johnstown 37, Mount Vernon 30
#johnstown #heath #week
Licking Valley and Newark Catholic each improved to 4-0, and Heath and Watkins Memorial also were victorious.
Columbus Academy 36, Granville 14
Heath 58, Washington CH 28
Johnstown 37, Mount Vernon 30
#johnstown #heath #week


3 days ago
Biohaven (BHVN) stock plummeted Thursday after the company paused enrollment in a midstage study of its seizure treatment due to safety concerns.
The Food and Drug Administration is now requiring Biohaven to ***** s the potential for human toxicity from a metabolite in the drug, opakalim. Opakalim is in testing as a treatment for focal onset seizures. But, in rats, it proved toxic.
Dosing is still ongoing. But the rodent toxicity setback likely delays potential regulatory approval. That's a boon for Xenon Pharmaceuticals (XENE), which is in late-stage testing with its drug, azetukalner. Both drugs work by opening potassium channels in the nervous system to calm overactive brain cells.
On the stock market today, Biohaven stock dropped 14.7% to 12.79. Shares fell below their 21-day and 50-day moving averages on the news, MarketSurge shows. Xenon stock slid a fraction to 58.80.
To ask for FDA approval, Biohaven will need the results of studies called RISE-2 and RISE-3. The hold was placed on the former, but the latter is still ongoing. The company expects to have the results from RISE-3 later this year.
#toxicity
The Food and Drug Administration is now requiring Biohaven to ***** s the potential for human toxicity from a metabolite in the drug, opakalim. Opakalim is in testing as a treatment for focal onset seizures. But, in rats, it proved toxic.
Dosing is still ongoing. But the rodent toxicity setback likely delays potential regulatory approval. That's a boon for Xenon Pharmaceuticals (XENE), which is in late-stage testing with its drug, azetukalner. Both drugs work by opening potassium channels in the nervous system to calm overactive brain cells.
On the stock market today, Biohaven stock dropped 14.7% to 12.79. Shares fell below their 21-day and 50-day moving averages on the news, MarketSurge shows. Xenon stock slid a fraction to 58.80.
To ask for FDA approval, Biohaven will need the results of studies called RISE-2 and RISE-3. The hold was placed on the former, but the latter is still ongoing. The company expects to have the results from RISE-3 later this year.
#toxicity


4 days ago
Royalty Pharma plc (NASDAQ:RPRX) disclosed that pelacarsen failed the Phase 3 Lp(a)HORIZON cardiovascular-outcomes trial conducted by Novartis AG (NYSE:NVS). The randomized, double-blind study enrolled 8,323 patients with elevated lipoprotein(a), or Lp(a), and established cardiovascular disease.
Pelacarsen lowered Lp(a), but the study did not meet its primary endpoint of reducing cardiovascular events compared with placebo in the overall population. The endpoint combined cardiovascular death, nonfatal heart attack, nonfatal stroke, and urgent coronary revascularization requiring hospitalization. Complete results have not yet been presented.
Royalty Pharma plc (NASDAQ:RPRX) provided Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) with $500 million in January 2023. The transaction allocated $150 million to pelacarsen royalties and $350 million to Spinraza royalties. The clinical failure shifts the financial focus from uncertain pelacarsen upside to recovery through Spinraza.
Royalty Pharma plc (NASDAQ:RPRX) acquired 25% of the Spinraza royalties received by Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) through 2027. That share increases to 45% in 2028 on Spinraza annual sales of up to $1.5 billion.
Following the HORIZON result, the Spinraza interest will revert after aggregate payments to Royalty Pharma plc (NASDAQ:RPRX) reach $550 million, equal to 1.1 times the original funding. Management expects the structure to recover the entire investment and generate a modest positive return despite the clinical failure.
#royalty #pharma #cardiovascular #horizon
Pelacarsen lowered Lp(a), but the study did not meet its primary endpoint of reducing cardiovascular events compared with placebo in the overall population. The endpoint combined cardiovascular death, nonfatal heart attack, nonfatal stroke, and urgent coronary revascularization requiring hospitalization. Complete results have not yet been presented.
Royalty Pharma plc (NASDAQ:RPRX) provided Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) with $500 million in January 2023. The transaction allocated $150 million to pelacarsen royalties and $350 million to Spinraza royalties. The clinical failure shifts the financial focus from uncertain pelacarsen upside to recovery through Spinraza.
Royalty Pharma plc (NASDAQ:RPRX) acquired 25% of the Spinraza royalties received by Ionis Pharmaceuticals, Inc. (NASDAQ:IONS) through 2027. That share increases to 45% in 2028 on Spinraza annual sales of up to $1.5 billion.
Following the HORIZON result, the Spinraza interest will revert after aggregate payments to Royalty Pharma plc (NASDAQ:RPRX) reach $550 million, equal to 1.1 times the original funding. Management expects the structure to recover the entire investment and generate a modest positive return despite the clinical failure.
#royalty #pharma #cardiovascular #horizon

4 days ago
American Century Investments, an investment management company, released its second-quarter 2026 investor letter for the "American Century Investments Focused Dynamic Growth Fund". The letter can be downloaded here. U.S. stocks advanced sharply with double-digit quarterly gains largely due to robust earnings, resilient economic data, and momentum in AI-related stocks. However, there was a slight pullback in June as momentum waned and investors anticipated potential interest rate hikes by the Federal Reserve. Growth and AI stocks outperformed value stocks, while large-cap companies generally surpassed small- and mid-cap stocks. Underperformance was noted in healthcare and communication services, while industrials, particularly in aerospace and defense, contributed positively to performance. The fund's investor class returned 16.38%, slightly below the Russell 1000 Growth Index's 16.74%. The investment approach focuses on bottom-up financial ***** ysis to identify large-cap companies with long-term earnings growth potential, while aiming to mitigate non-financial risks. Please review the Fund's top five holdings to gain insights into its key selections for 2026.
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century
In its second-quarter 2026 investor letter, American Century Investments Focused Dynamic Growth Fund highlighted Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY), a biopharmaceutical company that discovers and commercializes therapeutics based on ribonucleic acid interference, detracted from the Fund's performance this quarter. On September 09, 2026, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) closed at $258.00 per share. Over the past month, Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) returned 13.60%, but its shares are down 44.94% over the past year. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) has a market capitalization of $34.52 billion, and its stock has traded within a 52-week range of $197.81 to $495.55.
American Century Investments Focused Dynamic Growth Fund stated the following regarding Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY) in its Q2 2026 investor letter:
"Stock choices and a sector overweight relative to the benchmark detracted as many biotechnology stocks, including Alnylam Pharmaceuticals and Insmed, underperformed the market. Alnylam Pharmaceuticals, Inc. (NASDAQ:ALNY). The biotechnology company's stock underperformed amid concerns of its upcoming late-stage clinical trial readouts despite what we believed was its otherwise strong recent financial performance."
#alny #century


4 days ago
On August 27, AstraZeneca PLC (NYSE:AZN) and Amgen Inc. (NASDAQ:AMGN) scored a shared clinical victory. Positive high-level results from the Phase III CROSSING trial showed that their co-developed severe asthma drug, TEZSPIRE, achieved statistically significant and clinically meaningful improvements across both co-primary endpoints, histologic remission and the frequency/severity of dysphagia, and all key secondary endpoints at week 24 in patients with eosinophilic esophagitis. These benefits were sustained through week 52 across both tested doses, accompanied by a safety profile consistent with its approved indications. While CROSSING highlights their joint R&D success, a closer look at their standalone financial performance reveals distinct growth trajectories.
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products
Both pharmaceutical giants delivered solid Q2 2026 results, but AstraZeneca is showing stronger overall financial momentum. AstraZeneca PLC (NYSE:AZN)'s Q2 revenue increased 6% year over year to $15.38 billion, supported by its Oncology franchise, which grew 18% in H1 to $14.12 billion, and its Rare Disease portfolio, which increased 13%. Core EPS rose 21% to $2.63, beating expectations, while management reaffirmed its full-year 2026 outlook for mid-to-high single-digit revenue growth and low double-digit Core EPS growth.
Amgen Inc. (NASDAQ:AMGN) reported Q2 revenue of $10.1 billion, up 10% year over year, while non-GAAP EPS increased 4% to $6.29. Although its key growth products advanced 26%, mature products faced significant biosimilar pressure, with Prolia revenue declining 32% and XGEVA falling 34%. Amgen nevertheless raised its 2026 revenue guidance midpoint to $39.4 billion.
Overall, AZN holds the financial edge due to stronger EPS growth, broader portfolio momentum, and less exposure to the biosimilar erosion affecting AMGN's mature products.
Amgen's bull case is supported by robust growth in key products, which increased 26%, and $3.5 billion in Q2 free cash flow, providing substantial capital flexibility. Wells Fargo raised its Amgen price target to $435 from $400 on September 4, citing potential upside from HORIZON and pipeline ****** ets such as olpasiran. New Phase III VESALIUS-CV data also showed Repatha reduced the risk of death by 20% in high-risk adults without a prior heart attack or stroke, with heart attack risk reductions emerging as early as six months. However, accelerating biosimilar competition affecting legacy franchises such as Prolia and XGEVA remains a key risk to sustained margin expansion.
#revenue #astrazeneca #increased #products

4 days ago
The pharmaceutical sector was hit with major pipeline news on September 1 when Novartis AG (NYSE:NVS) paused eight clinical trials of rap-cel, its experimental CAR-T cell therapy targeting autoimmune and neurological disorders. The suspension, effective August 24, followed three patient deaths caused by severe, life-threatening immune reactions (immune effector cell-associated hemophagocytic syndrome). Novartis is currently conducting a safety review alongside independent monitoring boards. Following the news, Bristol-Myers Squibb Company (NYSE:BMY) voluntarily paused trials for its competing CAR-T treatment, zola-cel, as a precautionary measure after detecting transient inflammatory side effects.
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis
Looking at Q2 2026 earnings, Bristol Myers Squibb is currently demonstrating stronger financial momentum. Bristol-Myers Squibb Company (NYSE:BMY) reported total revenue of $13.0 billion, up 6% year over year, driven by a 15% increase in its Growth Portfolio to $7.6 billion, led by Opdivo, Qvantig, Reblozyl, and Camzyos. Non-GAAP EPS reached $2.04, while net income totaled $3.3 billion, or $4.2 billion on a non-GAAP basis. The company also raised its full-year 2026 revenue guidance from approximately $46.0–$47.5 billion to $49.0–$50.0 billion and increased its non-GAAP EPS outlook to $6.75–$7.00.
Novartis AG (NYSE:NVS), meanwhile, reported Q2 net sales of $14.4 billion, up 3% in U.S. dollars and 1% at constant currencies, supported by Kisqali and Kesimpta, which grew 43% and 32% at constant currencies, respectively. However, generic competition reduced growth by 14 percentage points, while core operating income remained flat at $5.9 billion and GAAP net income fell 19% to $3.3 billion. Novartis reaffirmed rather than raised its full-year guidance, calling for low single-digit sales growth and a low single-digit decline in core operating income.
Overall, Bristol Myers stands out as the stronger financial story this quarter, with its Growth Portfolio offsetting legacy patent-cliff pressures and supporting a guidance increase, while Novartis continues to contend with generic erosion weighing on earnings.
Novartis' bull case rests on strong double-digit growth from high-margin blockbusters such as Kisqali, Kesimpta, and Scemblix, supporting robust Q2 free cash flow of $5.6 billion. However, CAR-T safety setbacks could threaten a key pipeline platform, while intense generic competition has already reduced top-line growth by 14 percentage points.
#billion #novartis

4 days ago
On September 3, AbbVie Inc. (NYSE:ABBV) finalized its acquisition of clinical-stage biotech Apogee Therapeutics, Inc. (NASDAQ:APGE) for $135.11 per share in cash. The $10.9 billion buyouts immediately fold Apogee's promising inflammatory and immunology (I&I) pipeline into AbbVie's commercial engine. On the exact same day, AbbVie separately reported positive Phase 3 Cervino trial results for its bispecific T-cell engager, etentamig, in relapsed/refractory multiple myeloma. Together, the dual catalysts emphasize how mega-cap pharmaceutical giants are deploying cash flow from legacy franchises to lock in next-generation immunology and oncology ***** ets.
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth
In Q2 2026, AbbVie Inc. (NYSE:ABBV) posted $16.99 billion in net revenue, up 10.2% year over year, while adjusted diluted EPS increased 22.9% to $3.65. Growth was driven by its immunology blockbusters, Skyrizi and Rinvoq, which generated $5.505 billion and $2.525 billion in revenue, respectively, representing growth of 24.4% and 24.5%. These gains more than offset the continued decline in Humira revenue, which fell 35.9% to $756 million amid biosimilar competition. AbbVie reiterated its full-year 2026 adjusted EPS guidance of $13.87–$14.07, including a $0.14 dilutive impact from the Apogee transaction.
As a clinical-stage biotech, Apogee Therapeutics, Inc. (NASDAQ:APGE) generated no product revenue in Q2 2026, while R&D expenses reached $67.3 million and G&A expenses totaled $24.3 million, resulting in a quarterly net loss of $85.9 million. Despite the cash burn, the company maintained a strong liquidity position, with $1.3 billion in cash and marketable securities, alongside a $1.3 billion non-dilutive credit collaboration with Blackstone Life Sciences to support Phase 3 trials of its lead ***** et, zumilokibart.
Financially, AbbVie is vastly superior in immediate cash generation and profitability, whereas Apogee represented pure clinical optionality backed by robust liquidity.
For AbbVie, acquiring Apogee's optimized antibody portfolio, including zumilokibart for atopic dermatitis, strengthens its post-Humira immunology franchise. Combined with internal R&D advances such as etentamig, which achieved statistically significant overall response rate and progression-free survival results in the Phase 3 Cervino study, along with an 87.9% 12-month overall survival rate, AbbVie demonstrates potential to sustain strong organic growth.
#phase #revenue #Growth


4 days ago
By Karen Roman
Veraxa Biotech AG (Nasdaq: VRXA) said it appointed Raju Willener as Chief Financial Officer, having previously served as Director of Corporate Development at Exentis Group AG, before becoming its CFO in 2025.
Mr. Willener has more than three decades of international financial leadership experience in global capital markets and all aspects of the biopharmaceutical development process, the company stated.
"As we advance our proprietary BiTAC technology platform and growing oncology pipeline, Raju's expertise will be highly valuable in optimizing our capital strategy, evaluating strategic opportunities and supporting disciplined execution and long-term shareholder value creation," said Christoph Antz, Ph.D., VERAXA's CEO and co-founder.
Contact:
#willener #roman #NASDAQ
Veraxa Biotech AG (Nasdaq: VRXA) said it appointed Raju Willener as Chief Financial Officer, having previously served as Director of Corporate Development at Exentis Group AG, before becoming its CFO in 2025.
Mr. Willener has more than three decades of international financial leadership experience in global capital markets and all aspects of the biopharmaceutical development process, the company stated.
"As we advance our proprietary BiTAC technology platform and growing oncology pipeline, Raju's expertise will be highly valuable in optimizing our capital strategy, evaluating strategic opportunities and supporting disciplined execution and long-term shareholder value creation," said Christoph Antz, Ph.D., VERAXA's CEO and co-founder.
Contact:
#willener #roman #NASDAQ

5 days ago
Our ***** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was anchored by the 'Reimagined 200' stores, which outperformed the broader fleet by 80 basis points, validating the strategy of enhanced staffing and curated ***** ortments.
Bloomingdale's achieved its highest second-quarter sales volume in its 154-year history, driven by a 1,700 basis point step-change on a two-year stack as it captures market share in premium and luxury segments.
Management attributed the 9% increase in Average Unit Retail (AUR) to a deliberate shift toward 'fashion authority' positioning, prioritizing better/best brand tiers over high-volume, low-margin units.
The company successfully leveraged enterprise-wide capabilities, such as Macy's is leveraging its marketplace business to fill white-space opportunities, while dermatological skincare brands like SkinCeuticals drove growth at Bluemercury.
#volume #year #management #average
Performance was anchored by the 'Reimagined 200' stores, which outperformed the broader fleet by 80 basis points, validating the strategy of enhanced staffing and curated ***** ortments.
Bloomingdale's achieved its highest second-quarter sales volume in its 154-year history, driven by a 1,700 basis point step-change on a two-year stack as it captures market share in premium and luxury segments.
Management attributed the 9% increase in Average Unit Retail (AUR) to a deliberate shift toward 'fashion authority' positioning, prioritizing better/best brand tiers over high-volume, low-margin units.
The company successfully leveraged enterprise-wide capabilities, such as Macy's is leveraging its marketplace business to fill white-space opportunities, while dermatological skincare brands like SkinCeuticals drove growth at Bluemercury.
#volume #year #management #average
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

5 days ago
Biopharmaceutical leader Kiniksa Pharmaceuticals (KNSA) is approaching a new buy point in the wake of a strong quarterly sales report. That makes Kiniksa stock Thursday's pick for IBD 50 Growth Stocks To Watch from Investor's Business Daily.
Kiniksa develops and commercializes medicines for cardiovascular, autoimmune and autoinflammatory diseases. Its only drug, Arcalyst, treats recurrent pericarditis, a condition in which the sac protecting the heart, the pericardium, becomes inflamed. The risk of recurrence increases with each subsequent flare-up of pericarditis, according to the Arcalyst website.
The company expects to replace Arcalyst with a next-generation version, now called KPL-387, in 2028 or 2029.
While Arcalyst requires a weekly under-the-skin shot, KPL-387 is a monthly injection. KPL-387 sales are expected to start slow at $21.7 million in 2028, growing to $173.7 million, $486.3 million and $1.03 billion over the next three years.
During the second quarter, Arcalyst generated $243.6 million in sales, growing 55% year over year. That crushed estimates from FactSet that called for $227.7 million.
#next #biopharmaceutical
Kiniksa develops and commercializes medicines for cardiovascular, autoimmune and autoinflammatory diseases. Its only drug, Arcalyst, treats recurrent pericarditis, a condition in which the sac protecting the heart, the pericardium, becomes inflamed. The risk of recurrence increases with each subsequent flare-up of pericarditis, according to the Arcalyst website.
The company expects to replace Arcalyst with a next-generation version, now called KPL-387, in 2028 or 2029.
While Arcalyst requires a weekly under-the-skin shot, KPL-387 is a monthly injection. KPL-387 sales are expected to start slow at $21.7 million in 2028, growing to $173.7 million, $486.3 million and $1.03 billion over the next three years.
During the second quarter, Arcalyst generated $243.6 million in sales, growing 55% year over year. That crushed estimates from FactSet that called for $227.7 million.
#next #biopharmaceutical
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

7 days ago
Harbor Funds, an investment management company, released its Q2 2026 investor letter for "Harbor Mid Cap Value Fund". The letter can be downloaded here. Global equities experienced a sharp rally in Q2 2026, with the S&P 500 returning 15.2%, its strongest quarter since 2020, driven by a shift from software to hardware in the Artificial Intelligence capital spending cycle. Small caps outperformed large caps, with the Russell 2000® gaining 21.5% compared to the Russell 1000's 15.1%. Growth stocks led within large caps, while Information Technology rose about 33%, contributing significantly to the S&P 500's return. The Harbor Mid Cap Value Fund returned 13.99%, outperforming its benchmark, the Russell Midcap Value Index. Strong stock selection in Consumer Discretionary, Real Estate, and Financials contributed positively, although an underweight in Information Technology negatively impacted results. Despite ongoing economic uncertainties, the investment philosophy remains committed to a disciplined value approach. Check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) as a newly added position. Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) is a biotechnology company that develops and commercializes medicines to treat various diseases. On September 04, 2026, Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) closed at $827.72 per share, reflecting a market capitalization of $85.21 billion. Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) posted a one‑month return of 2.43%, while its shares gained 48.22% over the past 52 weeks.
Harbor Mid Cap Value Fund stated the following regarding Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) in its Q2 2026 investor letter:
"We added to our position in Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN), a biotech company in the Health Care sector. The stock ranks high on multiple cash flow and forecasted earnings measures — two of our most important measures of valuation. While the company pays a below-average dividend, Regeneron has been buying back stock, which we view positively. Price momentum over the past 12 months has been strong. In addition, several indicators of operating momentum also are attractive with improving operating margins and growth in sales. Overall, the stock ranks in the top 10% in our stock-ranking universe, which led to the second quarter purchase."
Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 63 hedge fund portfolios held Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) at the end of the second quarter, down from 72 in the previous quarter. While we acknowledge the potential of Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalue
In its second-quarter 2026 investor letter, Harbor Mid Cap Value Fund highlighted Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) as a newly added position. Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) is a biotechnology company that develops and commercializes medicines to treat various diseases. On September 04, 2026, Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) closed at $827.72 per share, reflecting a market capitalization of $85.21 billion. Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) posted a one‑month return of 2.43%, while its shares gained 48.22% over the past 52 weeks.
Harbor Mid Cap Value Fund stated the following regarding Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) in its Q2 2026 investor letter:
"We added to our position in Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN), a biotech company in the Health Care sector. The stock ranks high on multiple cash flow and forecasted earnings measures — two of our most important measures of valuation. While the company pays a below-average dividend, Regeneron has been buying back stock, which we view positively. Price momentum over the past 12 months has been strong. In addition, several indicators of operating momentum also are attractive with improving operating margins and growth in sales. Overall, the stock ranks in the top 10% in our stock-ranking universe, which led to the second quarter purchase."
Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 63 hedge fund portfolios held Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) at the end of the second quarter, down from 72 in the previous quarter. While we acknowledge the potential of Regeneron Pharmaceuticals, Inc. (NASDAQ:REGN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalue

7 days ago
Impax ***** et Management, based in London and specializing in sustainable investing, released its Q2 2026 investor letter for the "Impax US Sustainable Economy Fund". The letter can be downloaded here. The US Sustainable Economy portfolio outperformed the Russell 1000 in Q2 2026, with Institutional Class at 17.96%, Investor Class at 17.95%, and Class A at 17.92%, versus the index's 15.14%. Sector allocation and stock selection drove performance. The sustainability tools, including the Impax Sustainability Lens and Corporate Resilience framework, contributed positively. Equity markets rallied, with both the S&P 500 and Nasdaq reaching new highs before retreating. A key trend was rotation into AI and tech stocks, supported by mega-cap earnings and data center investments (US$750bn to US$1tn). In the second half of 2026, markets may remain volatile amid debates on AI adoption pace and economic momentum. However, growth tied to energy security and efficiency remains compelling, with demand for power, grid, and resource-efficient solutions supporting companies that benefit. The team focuses on businesses with strong growth, sound management, and attractive valuations, adjusting holdings as needed. This approach aims to build well-diversified, differentiated portfolios. Also, please check the fund's top five holdings for its best picks in 2026.
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On September 04, 2026, Zoetis Inc. (NYSE:ZTS) closed at $75.81 per share. Over the past month, Zoetis Inc. (NYSE:ZTS) returned 1.31%, but its shares are down 50.04% over the past year. Zoetis Inc. (NYSE:ZTS) has a market capitalization of $31.33 billion.
Impax US Sustainable Economy Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor letter:
"Zoetis Inc. (NYSE:ZTS) (Pharmaceuticals, Health Care) is owned for its attractive sustainability opportunity profile in areas including Wellbeing and Evolving Health Care Challenge, as well as its strong governance profile. The stock declined sharply in the quarter following a downward revision to near-term earnings guidance. Sales of Librela, the company's key canine arthritis pain management product, continued to face headwinds from safety perception concerns among some veterinarians, and management indicated that the ramp-up of next-generation product launches would extend into the following year."
#economy #Health
In its second-quarter 2026 investor letter, Impax US Sustainable Economy Fund highlighted Zoetis Inc. (NYSE:ZTS). Zoetis Inc. (NYSE:ZTS), an animal health company focused on animal health medications, vaccines, and diagnostic products, detracted from the Fund's performance during the quarter. On September 04, 2026, Zoetis Inc. (NYSE:ZTS) closed at $75.81 per share. Over the past month, Zoetis Inc. (NYSE:ZTS) returned 1.31%, but its shares are down 50.04% over the past year. Zoetis Inc. (NYSE:ZTS) has a market capitalization of $31.33 billion.
Impax US Sustainable Economy Fund stated the following regarding Zoetis Inc. (NYSE:ZTS) in its Q2 2026 investor letter:
"Zoetis Inc. (NYSE:ZTS) (Pharmaceuticals, Health Care) is owned for its attractive sustainability opportunity profile in areas including Wellbeing and Evolving Health Care Challenge, as well as its strong governance profile. The stock declined sharply in the quarter following a downward revision to near-term earnings guidance. Sales of Librela, the company's key canine arthritis pain management product, continued to face headwinds from safety perception concerns among some veterinarians, and management indicated that the ramp-up of next-generation product launches would extend into the following year."
#economy #Health

9 days ago
Here are a few favorite images from the past week, selected by Utica Observer-Dispatch staff photographer Daniel DeLoach.
The Pioneers fell to the Bombers 3-1, with Utica's lone goal coming from senior defender Cora Kraft's 37-yard free kick.
New Hartford defeated Baldwinsville 2-1 in their home opener, with senior Grace Bannigan scoring twice and securing her 100th career point as a Spartan.
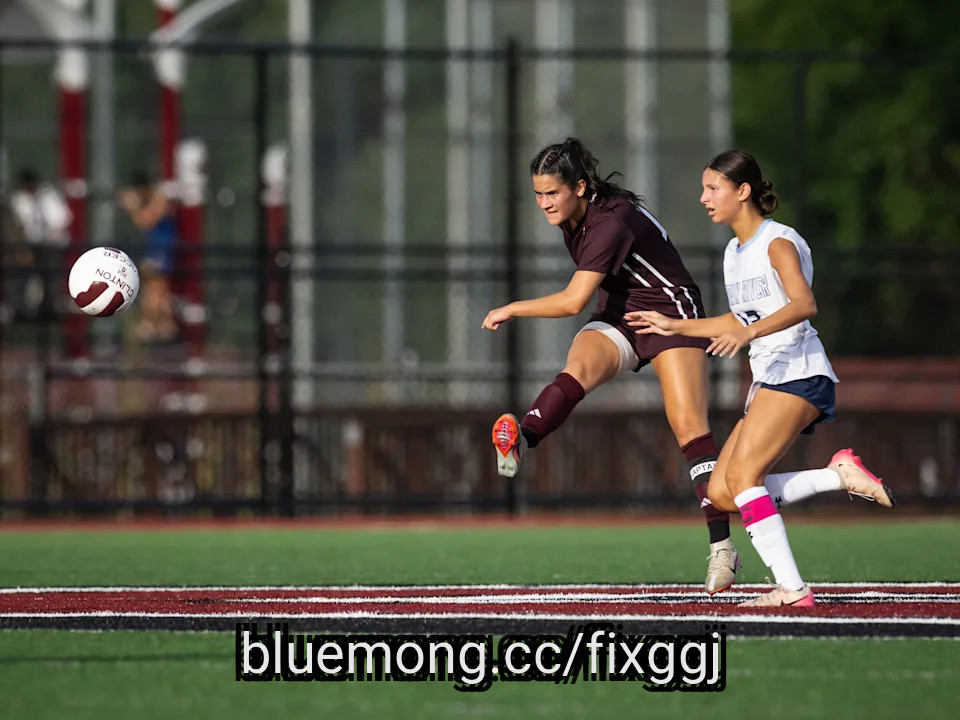
The Clinton Comets defeated the Indian River Wolves 2-1, with both first-half goals coming from seniors Kiersten Majka and Devyn Roy.
This article originally appeared on Observer-Dispatch: Top photos of the week from Daniel DeLoach of the Observer-Dispatch
#observer #dispatch #week #coming
The Pioneers fell to the Bombers 3-1, with Utica's lone goal coming from senior defender Cora Kraft's 37-yard free kick.
New Hartford defeated Baldwinsville 2-1 in their home opener, with senior Grace Bannigan scoring twice and securing her 100th career point as a Spartan.
The Clinton Comets defeated the Indian River Wolves 2-1, with both first-half goals coming from seniors Kiersten Majka and Devyn Roy.
This article originally appeared on Observer-Dispatch: Top photos of the week from Daniel DeLoach of the Observer-Dispatch
#observer #dispatch #week #coming


10 days ago
Over the past five years, Eli Lilly (NYSE: LLY) stock managed a total return of 376%. If the stock managed a repeat over the next five years, share prices would top $5,500. Much of its current performance boost is thanks to enthusiasm over its GLP-1 offerings.
Are the same factors that led to the healthcare company's sharp rise likely to recur? The simple answer is no. While its metabolic GLP-1 weight-loss therapies helped spike revenue, it's not likely to happen again. Still, there are reasons to believe the pharmaceutical stock could double in value over the next five years, making a $5,000 investment in Eli Lilly stock worth more than $10,000 in five years. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly, through tirzepatide, marketed as Mounjaro for type 2 diabetes and Zepbound for chronic weight management, is still a leader in the GLP-1 **** e. Tirzepatide is showing to be an incredibly versatile incretin-based peptide drug.
Excess weight is tied to many health problems, and tirzepatide could expand to adjacent indications. It has already been approved to treat obstructive sleep apnea, and on Aug. 28, the Food and Drug Administration (FDA) approved Mounjaro to lower the risk of major adverse cardiovascular (CV) events, including cardiovascular death, non-fatal heart attack, or non-fatal stroke in adults with type 2 diabetes who are at high risk.
#Stock #signal #weight #total
Are the same factors that led to the healthcare company's sharp rise likely to recur? The simple answer is no. While its metabolic GLP-1 weight-loss therapies helped spike revenue, it's not likely to happen again. Still, there are reasons to believe the pharmaceutical stock could double in value over the next five years, making a $5,000 investment in Eli Lilly stock worth more than $10,000 in five years. Here's why.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly, through tirzepatide, marketed as Mounjaro for type 2 diabetes and Zepbound for chronic weight management, is still a leader in the GLP-1 **** e. Tirzepatide is showing to be an incredibly versatile incretin-based peptide drug.
Excess weight is tied to many health problems, and tirzepatide could expand to adjacent indications. It has already been approved to treat obstructive sleep apnea, and on Aug. 28, the Food and Drug Administration (FDA) approved Mounjaro to lower the risk of major adverse cardiovascular (CV) events, including cardiovascular death, non-fatal heart attack, or non-fatal stroke in adults with type 2 diabetes who are at high risk.
#Stock #signal #weight #total

10 days ago
Gilead Sciences (NASDAQ: GILD) has no major concerns about its HIV franchise until the next decade. That hasn't kept the pharmaceutical company from preparing for the loss of exclusivity for its legacy HIV therapies. Gilead has spent heavily on its pipeline, and that's paying off.
The company has received three Food and Drug (FDA) approvals over the past four months, and not coincidentally, its shares are up more than 21% so far this year, nearly doubling the S&P 500 index's rise. The most recent approval was on Aug. 27 for Bixlenvo as a daily pill to treat virologically suppressed adults with HIV.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Prior to that, on June 24, Trodelvy received two new approvals to treat triple-negative breast cancer. On May 22, the FDA granted Hepcludex accelerated approval to treat chronic hepatitis delta virus (HDV) infection in adults without cirrhosis or with compensated cirrhosis.
Despite the stock's rise and all the good news on the pipeline front, Gilead may be underrated. There are three reasons why I feel that is the case.
#gilead #NVIDIA #three
The company has received three Food and Drug (FDA) approvals over the past four months, and not coincidentally, its shares are up more than 21% so far this year, nearly doubling the S&P 500 index's rise. The most recent approval was on Aug. 27 for Bixlenvo as a daily pill to treat virologically suppressed adults with HIV.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Prior to that, on June 24, Trodelvy received two new approvals to treat triple-negative breast cancer. On May 22, the FDA granted Hepcludex accelerated approval to treat chronic hepatitis delta virus (HDV) infection in adults without cirrhosis or with compensated cirrhosis.
Despite the stock's rise and all the good news on the pipeline front, Gilead may be underrated. There are three reasons why I feel that is the case.
#gilead #NVIDIA #three

10 days ago
On August 6, Ligand Pharmaceuticals (NASDAQ:LGND) reported second-quarter 2026 results showing royalty revenue up 32% year over year, just weeks after the company closed its acquisition of XOMA Royalty. Total revenue reached $63.7 million for the quarter, up from $47.6 million a year earlier, and Ligand raised the low end of its full-year adjusted earnings guidance. The headline growth numbers are easy to like. What is harder to ignore is that Ligand just more than doubled its royalty portfolio and added $700 million in convertible debt in the same stretch.
Royalty revenue is where Ligand's growth is actually coming from, and it has been strong on its own merits. Royalties totaled $48.0 million in the second quarter, up from $36.4 million a year earlier, with Travere Therapeutics' Filspari, Pelthos Therapeutics' Zelsuvmi, and Merck's Ohtuvayre leading the increase. That growth compounded further in the first half, when royalties reached $91.0 million, up 42% from $63.9 million a year ago. The Filspari story helps explain why: the FDA approved the drug in April to treat FSGS, a second rare kidney disease beyond its original approval, and Travere reported $141 million in US net sales in early August, up 96% year over year.
Then there is the XOMA deal. On July 14, Ligand closed its acquisition of XOMA Royalty, adding more than 120 commercial, clinical, and preclinical **** ets, including Roche's Vabysmo, Servier's Ojemda, and Zevra Therapeutics' Miplyffa. That pushed Ligand's total portfolio past 200 royalty **** ets, more than double what it held before. Management expects the deal to add roughly $0.50 per share to 2026 adjusted earnings and $1.50 per share in 2027, and it came with about $700 million in deployable capital left over to keep buying royalty streams at a stated pace of $150 million to $250 million a year.
That growth is not coming cheap. G&A expense jumped to $29.1 million in the second quarter from $20.2 million a year earlier, driven by transaction costs tied to the XOMA deal along with higher headcount and stock compensation. R&D expense nearly tripled to $14.7 million, largely because of a $12.3 million funding arrangement with Orchestra BioMed. A large share of the quarter's reported profit also did not come from the royalty business at all: net non-operating income of $55.7 million included a $35.7 million non-cash gain tied to swings in the value of Ligand's Pelthos Therapeutics stock holdings, a figure that can move the other way just as easily.
#reported
Royalty revenue is where Ligand's growth is actually coming from, and it has been strong on its own merits. Royalties totaled $48.0 million in the second quarter, up from $36.4 million a year earlier, with Travere Therapeutics' Filspari, Pelthos Therapeutics' Zelsuvmi, and Merck's Ohtuvayre leading the increase. That growth compounded further in the first half, when royalties reached $91.0 million, up 42% from $63.9 million a year ago. The Filspari story helps explain why: the FDA approved the drug in April to treat FSGS, a second rare kidney disease beyond its original approval, and Travere reported $141 million in US net sales in early August, up 96% year over year.
Then there is the XOMA deal. On July 14, Ligand closed its acquisition of XOMA Royalty, adding more than 120 commercial, clinical, and preclinical **** ets, including Roche's Vabysmo, Servier's Ojemda, and Zevra Therapeutics' Miplyffa. That pushed Ligand's total portfolio past 200 royalty **** ets, more than double what it held before. Management expects the deal to add roughly $0.50 per share to 2026 adjusted earnings and $1.50 per share in 2027, and it came with about $700 million in deployable capital left over to keep buying royalty streams at a stated pace of $150 million to $250 million a year.
That growth is not coming cheap. G&A expense jumped to $29.1 million in the second quarter from $20.2 million a year earlier, driven by transaction costs tied to the XOMA deal along with higher headcount and stock compensation. R&D expense nearly tripled to $14.7 million, largely because of a $12.3 million funding arrangement with Orchestra BioMed. A large share of the quarter's reported profit also did not come from the royalty business at all: net non-operating income of $55.7 million included a $35.7 million non-cash gain tied to swings in the value of Ligand's Pelthos Therapeutics stock holdings, a figure that can move the other way just as easily.
#reported

10 days ago
On the September 2 episode of Mad Money, Jim Cramer called Cardinal Health, Inc. (NYSE:CAH) one of his "absolute favorites" and mentioned its growing exposure to specialty pharmaceuticals and higher-margin healthcare services.
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE
Cardinal's been running circles around McKesson and Cencora. They consistently put up the best numbers because this company has gradually become less of a commoditized service provider and more of a specialized player.
Cardinal Health, Inc.'s (NYSE:CAH) fiscal fourth-quarter revenue rose 6% to $63.7 billion but missed estimates, while adjusted earnings per share came in at $2.91. Excluding a $0.31 per share tariff refund benefit, adjusted EPS was $2.60. Management forecast fiscal 2027 non-GAAP EPS of $12.40 to $12.60, a 13% to 15% growth, while adjusted free cash flow is expected at $3.5 billion to $4 billion.
The revenue miss is less significant if the company continues converting pharmaceutical volume into earnings. Lower branded-drug prices, including those affected by Medicare negotiations, can reduce reported sales without a proportional decline in distributor fees. The shift toward generics can have a similar effect because lower-priced drugs generate less revenue but can support attractive margins and high volumes. As Cramer said:
Remember, volume is where Cardinal really makes the money, volume, okay? That's why I keep shrugging off the revenue misses.
#cardinal #less #billion #NYSE


11 days ago
As the old saying goes, "If something sounds too good to be true, it probably is."
That clichéd wisdom presents something of a problem for any investor eyeing a new stake in pharmaceutical outfit Pfizer (NYSE: PFE) while its stock is priced at less than 10 times this year's expected per-share profit of $2.98, with a forward-looking dividend yield that's unusually high at just over 6%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
What's the market seeing? Maybe it's what the market's not seeing. To this end, if you're thinking about diving in, here are the top three things you need to know about Pfizer today.
All stock prices reflect that company's plausible future more so than its past, or even its present. The challenge for investors interested in Pfizer at this time is how far into the future they need to look.
#need
That clichéd wisdom presents something of a problem for any investor eyeing a new stake in pharmaceutical outfit Pfizer (NYSE: PFE) while its stock is priced at less than 10 times this year's expected per-share profit of $2.98, with a forward-looking dividend yield that's unusually high at just over 6%.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
What's the market seeing? Maybe it's what the market's not seeing. To this end, if you're thinking about diving in, here are the top three things you need to know about Pfizer today.
All stock prices reflect that company's plausible future more so than its past, or even its present. The challenge for investors interested in Pfizer at this time is how far into the future they need to look.
#need

11 days ago
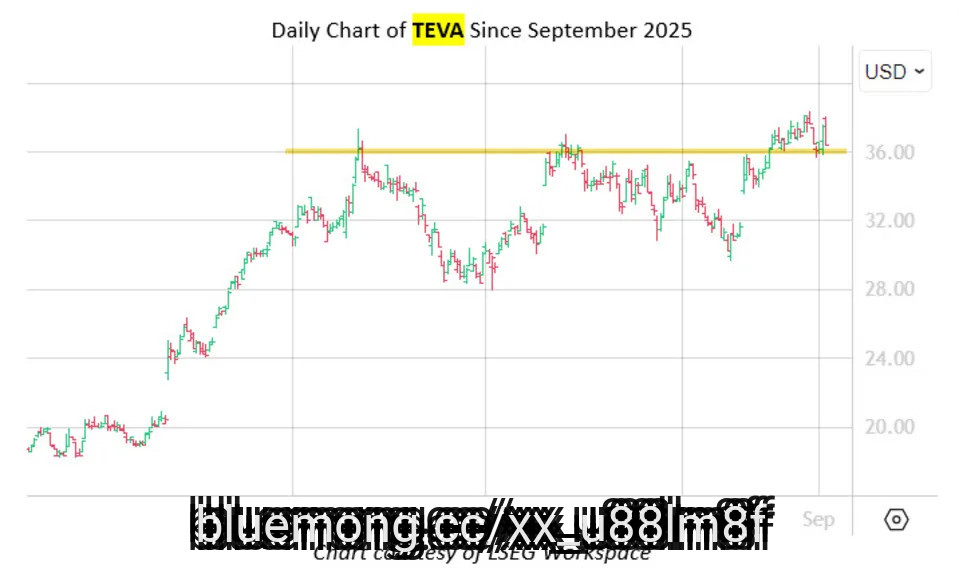
Teva Pharmaceuticals Industries (NYSE:TEVA) is moving 2.9% lower to trade at $36.41, pulling back from its Aug. 27, nearly nine-year high of $38.36. The $36 level looks to have moved in as a floor of support, a former level of resistance for the shares since late January. More gains could be on the table, however, with a fresh bull signal now flashing for the drug maker.
TEVA's long-term outperformance comes amid historically low implied volatility (IV). Specifically, the equity's current SVI of 29% stands in the low 5th percentile of its annual range.
According to data from Schaeffer's Senior Quantitative ******* yst Rocky White, there have been five instances in the past five years when the equity traded within 2% of its 52-week high, while its Schaeffer's Volatility Index (SVI) ranked in the 20th percentile of its annual range or lower.
TEVA was higher one month later 80% of the time after those signals, averaging a 5.5% gain. From its current perch, a shift of this amount would put the equity back above $38 -- within a chip-shot of its August peak.
Options traders are still not convinced. This is per the equity's 10-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX), which sits higher than 96% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger more tailwinds for the shares.
#exchange
TEVA's long-term outperformance comes amid historically low implied volatility (IV). Specifically, the equity's current SVI of 29% stands in the low 5th percentile of its annual range.
According to data from Schaeffer's Senior Quantitative ******* yst Rocky White, there have been five instances in the past five years when the equity traded within 2% of its 52-week high, while its Schaeffer's Volatility Index (SVI) ranked in the 20th percentile of its annual range or lower.
TEVA was higher one month later 80% of the time after those signals, averaging a 5.5% gain. From its current perch, a shift of this amount would put the equity back above $38 -- within a chip-shot of its August peak.
Options traders are still not convinced. This is per the equity's 10-day put/call volume ratio at the International Securities Exchange (ISE), Cboe Options Exchange (CBOE), and NASDAQ OMX PHLX (PHLX), which sits higher than 96% of readings from the past year. Should this bearish sentiment begin to unwind, it could trigger more tailwinds for the shares.
#exchange
11 days ago
With a market cap of $138.2 billion, Bristol-Myers Squibb Company (BMY) is a global biopharmaceutical company that discovers, develops, manufactures, and markets innovative medicines worldwide. Its portfolio spans key therapeutic areas including oncology, hematology, immunology, cardiovascular disease, and neuroscience, with well-known products such as Opdivo, Eliquis, Revlimid, and Yervoy.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Bristol-Myers Squibb fits this criterion perfectly. The company serves patients through a broad commercial network that includes wholesalers, distributors, specialty pharmacies, hospitals, clinics, and government agencies.
Nvidia CEO Jensen Huang Says His $3.5 Billion MediaTek Deal Is 'Not Circular' Because 'They Do Their Own Business'
Strategy's Strategy Appears to Have Failed, and the Outlook of MSTR Stock Is Unfavorable
A Potential ***** eX Deal Could Meaningfully Accelerate Growth for Technip Stock
#company #bristol #squibb #Stock


11 days ago
Pfizer (NYSE: PFE) has faced several issues in recent years that have weighed on its share price. First, the company's coronavirus business isn't nearly as strong as it once was. Second, Pfizer is racing toward important patent cliffs, including that of Eliquis, an anticoagulant. Third, the pharmaceutical giant has faced clinical setbacks with otherwise promising pipeline candidates, including some it acquired. This problem has led to billions in impairment charges. Because of these headwinds (and others), Pfizer's shares have lagged broader equities over the past two years and have hovered below $30 apiece. Is it finally time to invest in the company? Let's see whether there is a rebound on the horizon.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's start with Pfizer's recent second-quarter update. The company's revenue increased by 1% year over year to $15 billion. While that top-line growth doesn't look impressive, it beat ***** yst estimates. On the bottom line, Pfizer's adjusted earnings per share were $0.77, slightly lower than the $0.78 reported in the prior-year quarter. Here too, Pfizer beat expectations. And it's important to highlight what drove the revenue and earnings beat.
The company noted that non-COVID revenue increased 5% year over year, while sales from launched and acquired products jumped 18%. This is great news for Pfizer. It suggests that newer (and acquired) products will help pull sales in the right direction over the medium term, while older medicines, especially within its coronavirus business, continue to lose steam.
Even with the progress Pfizer is making with relatively new launches, upcoming patent cliffs will be a major problem for the company. Consider, for instance, that Eliquis was the drugmaker's best-selling therapy during the second quarter. Pfizer's revenue from Eliquis came in at $2.4 billion, up 21% year over year. So, it arguably remains its single most important growth driver. Pfizer will have to launch more new drugs to fill the gap Eliquis will leave behind as it faces generic competition by the end of the decade. Can the company pull it off? My view is that it can.
#company #revenue #years
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Let's start with Pfizer's recent second-quarter update. The company's revenue increased by 1% year over year to $15 billion. While that top-line growth doesn't look impressive, it beat ***** yst estimates. On the bottom line, Pfizer's adjusted earnings per share were $0.77, slightly lower than the $0.78 reported in the prior-year quarter. Here too, Pfizer beat expectations. And it's important to highlight what drove the revenue and earnings beat.
The company noted that non-COVID revenue increased 5% year over year, while sales from launched and acquired products jumped 18%. This is great news for Pfizer. It suggests that newer (and acquired) products will help pull sales in the right direction over the medium term, while older medicines, especially within its coronavirus business, continue to lose steam.
Even with the progress Pfizer is making with relatively new launches, upcoming patent cliffs will be a major problem for the company. Consider, for instance, that Eliquis was the drugmaker's best-selling therapy during the second quarter. Pfizer's revenue from Eliquis came in at $2.4 billion, up 21% year over year. So, it arguably remains its single most important growth driver. Pfizer will have to launch more new drugs to fill the gap Eliquis will leave behind as it faces generic competition by the end of the decade. Can the company pull it off? My view is that it can.
#company #revenue #years

11 days ago
Dividend stocks can be tricky for investors. If you're looking to invest $1,000 and benefit from a stock that pays a dividend, you have to look past the stock's yield.
Yes, it's nice to have an above-average yield, but a company with an unsustainable dividend is no bargain. If the payout ratio is too high, there's a good chance a dividend cut is in the future, and that will likely lead to the stock's price tumbling as well, a double-whammy for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Two healthcare stocks offering above-average dividend yields, paired with valuations that appear underpriced relative to historical standards and broader industry peers, are Bristol Myers Squibb (NYSE: BMY) and Pfizer (NYSE: PFE). Their shares are up more than 23% and 14%, respectively, so far this year.
Here's why I think investing $1,000 in either of these pharmaceutical stocks makes sense for income-oriented investors.
#NYSE
Yes, it's nice to have an above-average yield, but a company with an unsustainable dividend is no bargain. If the payout ratio is too high, there's a good chance a dividend cut is in the future, and that will likely lead to the stock's price tumbling as well, a double-whammy for investors.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Two healthcare stocks offering above-average dividend yields, paired with valuations that appear underpriced relative to historical standards and broader industry peers, are Bristol Myers Squibb (NYSE: BMY) and Pfizer (NYSE: PFE). Their shares are up more than 23% and 14%, respectively, so far this year.
Here's why I think investing $1,000 in either of these pharmaceutical stocks makes sense for income-oriented investors.
#NYSE

11 days ago
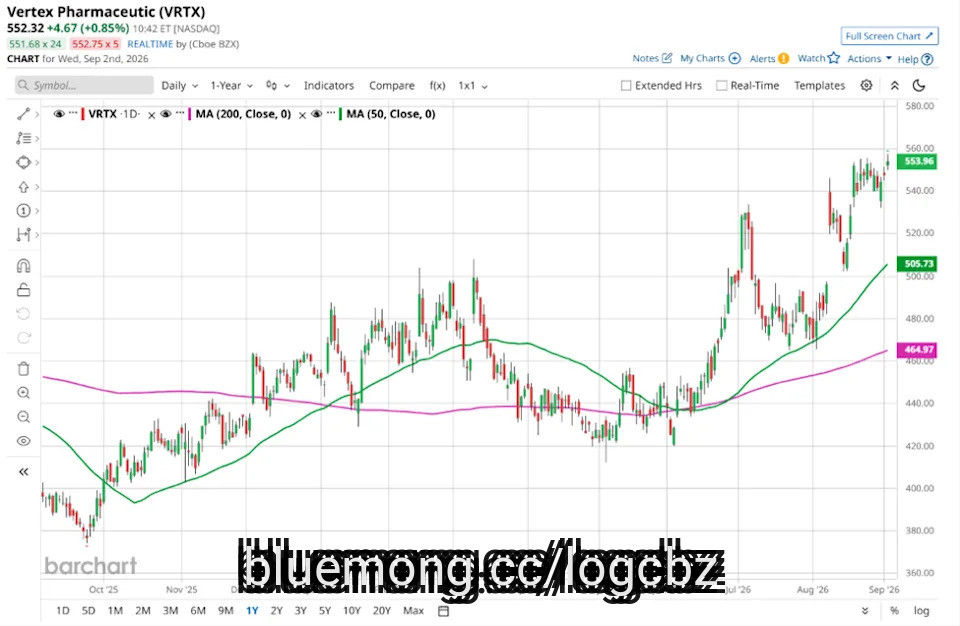
Boston, Massachusetts-based Vertex Pharmaceuticals Incorporated (VRTX) develops and commercializes therapies for treating cystic fibrosis (CF). Valued at $139 billion by market cap, the company invests in scientific innovation to create transformative medicines for people with serious diseases.
Companies worth $10 billion or more are generally described as "large-cap stocks," and VRTX perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the biotechnology industry. VRTX derives its primary competitive strength from its global monopoly in CF treatments, anchored by flagship blockbusters like Trikafta/Katori which generate robust cash flow to fuel its high-impact clinical pipeline.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#vrtx #massachusetts
Companies worth $10 billion or more are generally described as "large-cap stocks," and VRTX perfectly fits that description, with its market cap exceeding this mark, underscoring its size, influence, and dominance within the biotechnology industry. VRTX derives its primary competitive strength from its global monopoly in CF treatments, anchored by flagship blockbusters like Trikafta/Katori which generate robust cash flow to fuel its high-impact clinical pipeline.
Dear GameStop Stock Fans, Mark Your Calendars for September 8
SMCI vs. CoreWeave: 1 AI Infrastructure Model Has the Bigger Opportunity
Why **** ysts Think Sellas Life Sciences Stock Can Gain 150% From Here
#vrtx #massachusetts


12 days ago
Welcome to the high school football live scoreboard, with in-game updates from all of the Mohawk Valley's football teams in action this week as playoffs begin.
Scores refresh every 60 seconds, so be sure to check in often, and we'll be adding highlights from social media and on-site reporters and photographers throughout the night.
Follow us on X, formerly Twitter, TimesTelegram and uticaOD for stories, photos and videos from around the Mohawk Valley.
You can also check here following this weekend's action for final results, as well as links to stories from key area games and photo galleries.
Watch high school football games on NFHS Network
#check
Scores refresh every 60 seconds, so be sure to check in often, and we'll be adding highlights from social media and on-site reporters and photographers throughout the night.
Follow us on X, formerly Twitter, TimesTelegram and uticaOD for stories, photos and videos from around the Mohawk Valley.
You can also check here following this weekend's action for final results, as well as links to stories from key area games and photo galleries.
Watch high school football games on NFHS Network
#check

12 days ago
On August 26, Biohaven (NYSE:BHVN) and SK Biopharmaceuticals announced a global licensing agreement covering opakalim, Biohaven's lead epilepsy candidate, in a deal worth up to $795 million plus royalties. SK Biopharmaceuticals picks up exclusive worldwide rights to Biohaven's Kv7 ion channel platform, while Biohaven walks away with $400 million in near-term cash. The timing lines up with an August 10, 2026 earnings report that showed Biohaven still losing well over $100 million a quarter, and the gap between those two dates explains a lot about why this deal happened now.
SK Biopharmaceuticals will pay up to $795 million in upfront and milestone payments connected to the Kv7 platform, on top of tiered royalties on US net sales of opakalim that range from the mid-teens to low twenties. Biohaven collects $350 million at closing and another $50 million in 2027, with as much as $150 million more available through development and regulatory milestones plus royalties on global sales. SK Biopharmaceuticals is also taking over Kv7 program costs going forward, including certain Knopp Biosciences obligations. CEO Vlad Coric described the structure as proof Biohaven can monetize its pipeline through partnerships rather than leaning on public markets for cash.
The deal only makes sense because opakalim looks like it works. In a proof-of-concept study in idiopathic generalized epilepsy, the median time to a second generalized tonic-clonic seizure stretched to 141 days on opakalim versus 47 days on placebo, and a third of patients made it through the full 24 weeks without a second seizure. In focal epilepsy, 54% of patients in an open-label extension study saw at least a 50% drop in seizure frequency over any six months, in a group of more than 100 patients.
Opakalim is also designed as a once-daily pill with no ******* ration required, a real edge over older antiseizure drugs. Pairing that data with SK Biopharmaceuticals, the company behind XCOPRI and the only firm to bring a new focal-seizure drug to the US market since 2016, gives Opakalim a commercial path Biohaven would have struggled to build alone. The cash also buys runway for the rest of the pipeline, including protein degraders BHV-1300 and BHV-1400, which have shown rapid, selective reductions in disease-driving antibodies in Graves' disease and IgA nephropathy with clean safety data across nearly 200 patients dosed.
Biohaven is giving up full ownership of an ******* et it now believes could be a major seller. Royalties in the mid-teens to low twenties are real money, but they are a fraction of what outright ownership of an approved epilepsy drug would be worth, and $50 million of the $400 million upfront does not arrive until 2027. The Knopp Biosciences obligations SK Biopharmaceuticals is absorbing, worth up to $245 million plus mid-single-digit royalties, are a reminder that other parties already have claims on opakalim's future revenue before Biohaven sees a dollar of profit from it.
#ro
SK Biopharmaceuticals will pay up to $795 million in upfront and milestone payments connected to the Kv7 platform, on top of tiered royalties on US net sales of opakalim that range from the mid-teens to low twenties. Biohaven collects $350 million at closing and another $50 million in 2027, with as much as $150 million more available through development and regulatory milestones plus royalties on global sales. SK Biopharmaceuticals is also taking over Kv7 program costs going forward, including certain Knopp Biosciences obligations. CEO Vlad Coric described the structure as proof Biohaven can monetize its pipeline through partnerships rather than leaning on public markets for cash.
The deal only makes sense because opakalim looks like it works. In a proof-of-concept study in idiopathic generalized epilepsy, the median time to a second generalized tonic-clonic seizure stretched to 141 days on opakalim versus 47 days on placebo, and a third of patients made it through the full 24 weeks without a second seizure. In focal epilepsy, 54% of patients in an open-label extension study saw at least a 50% drop in seizure frequency over any six months, in a group of more than 100 patients.
Opakalim is also designed as a once-daily pill with no ******* ration required, a real edge over older antiseizure drugs. Pairing that data with SK Biopharmaceuticals, the company behind XCOPRI and the only firm to bring a new focal-seizure drug to the US market since 2016, gives Opakalim a commercial path Biohaven would have struggled to build alone. The cash also buys runway for the rest of the pipeline, including protein degraders BHV-1300 and BHV-1400, which have shown rapid, selective reductions in disease-driving antibodies in Graves' disease and IgA nephropathy with clean safety data across nearly 200 patients dosed.
Biohaven is giving up full ownership of an ******* et it now believes could be a major seller. Royalties in the mid-teens to low twenties are real money, but they are a fraction of what outright ownership of an approved epilepsy drug would be worth, and $50 million of the $400 million upfront does not arrive until 2027. The Knopp Biosciences obligations SK Biopharmaceuticals is absorbing, worth up to $245 million plus mid-single-digit royalties, are a reminder that other parties already have claims on opakalim's future revenue before Biohaven sees a dollar of profit from it.
#ro

13 days ago
The biotechnology sector has long rewarded companies that can translate early clinical promise into late-stage validation, and nowhere is that dynamic more ******* ounced than in oncology. Acute myeloid leukemia (AML) remains one of the most challenging cancers to treat, with limited durable options for patients who relapse after standard therapy.
That unmet need has made AML-focused immunotherapy a magnet for both strategic pharmaceutical partnerships and investor capital willing to underwrite clinical-stage risk in exchange for outsized upside potential. SELLAS Life Sciences Group, Inc. (SLS) sits squarely within this high-stakes corner of the market.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#dear #fans #sellas
That unmet need has made AML-focused immunotherapy a magnet for both strategic pharmaceutical partnerships and investor capital willing to underwrite clinical-stage risk in exchange for outsized upside potential. SELLAS Life Sciences Group, Inc. (SLS) sits squarely within this high-stakes corner of the market.
Dear Sandisk Stock Fans, Mark Your Calendars for August 31
Bill Gates Says 'We Need Time to Prepare' for an Economic Upheaval — Especially the $20-an-Hour Workers Being Replaced by $10-an-Hour Robots
Dear Palantir Stock Fans, Here's What Maven's Billion-Dollar ARR Means for PLTR
#dear #fans #sellas


13 days ago
Riverwater Partners, an investment management company, released its 'Small Cap Strategy' Q2 2026 investor letter. The letter can be downloaded here. The Small Cap Strategy underperformed the Russell 2000 in the second quarter as the benchmark experienced one of its strongest risk-on rallies in recent memory, although the strategy remained ahead year-to-date. The quarter was defined by accelerating AI investment, energy market disruptions, and renewed investor appetite for higher-beta stocks, creating headwinds for the firm's quality-focused approach and healthcare positioning. Despite this, stock selection contributed positively in energy, materials, and financials, while healthcare and consumer discretionary detracted due to the fund's disciplined avoidance of speculative businesses. Looking ahead, the firm remains cautiously optimistic, focusing on opportunities created by market dislocations, including AI infrastructure enablers, select consumer companies, healthcare innovators, and energy businesses trading below intrinsic value. The strategy continues to emphasize high-quality companies with strong management teams and attractive valuations, positioning the portfolio for a potential rotation away from speculative market leadership. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor
In its second-quarter 2026 investor letter, Riverwater Partners Small Cap Strategy highlighted Stevanato Group S.p.A. (NYSE:STVN) as a new holding. Stevanato Group S.p.A. (NYSE:STVN) is an Italian company that designs and distributes products and processes that offer integrated solutions for the biopharma and healthcare industries. On August 31, 2026, Stevanato Group S.p.A. (NYSE:STVN) closed at $21.03 per share. Stevanato Group S.p.A. (NYSE:STVN) gained 9.06% in the past month while its shares lost 5.39% over the past 52 weeks. Stevanato Group S.p.A. (NYSE:STVN) has a market capitalization of $5.85 billion and its stock has traded within a 52-week range of $12.89 to $28.00.
Riverwater Partners Small Cap Strategy stated the following regarding Stevanato Group S.p.A. (NYSE:STVN) in its Q2 2026 investor letter:
"In addition, we initiated positions in Stevanato Group S.p.A. (NYSE:STVN), a leading global provider of drug containment, drug delivery, and diagnostic solutions to the pharmaceutical, biotechnology, and life sciences industries. The stock sold off following the launch of oral GLP-1s, which many believe will end the need for injectable forms. Experts believe an expanding GLP-1 TAM, coupled with varying use cases, will necessitate ongoing need for injectable forms. Indeed, 25% of drugs approved in 2025 were biologics which will require injectable devices. This market overreaction offered an attractive entry valuation of 12.5x FY2026E EBITDA vs. STVN's historic multiple of 20X and its nearest comp West Pharmaceutical (WST) at approximately 22–25x."
#stevanato #partners #investor