

10 hours ago
(NewsNation) — The family of an Alaskan boy who survived four days at sea wants the world to know what they say kept him alive: prayer.
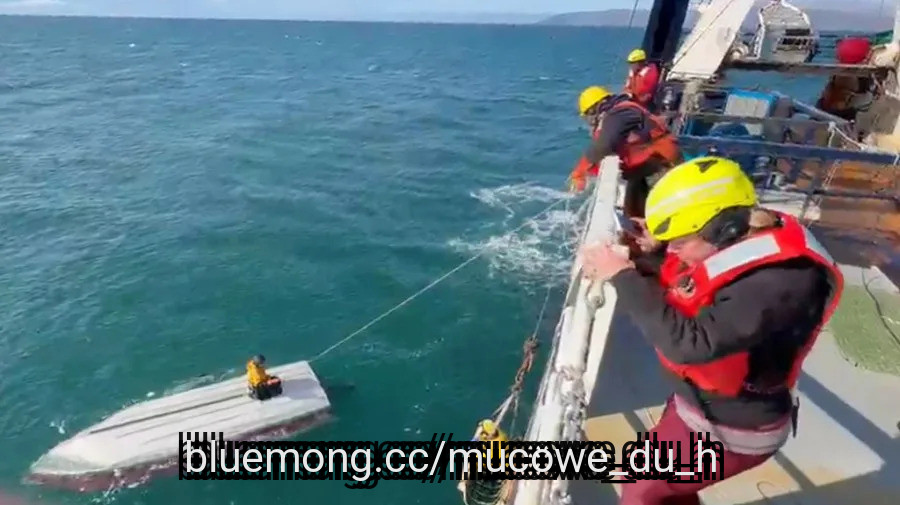
Fifteen-year-old Parker of Savoonga, Alaska set out with his older brother Sidney Kulowiyi, 35, and their cousin, Barton Rookok, 34, to fish for halibut on September 4, according to Anchorage Daily News. They planned on returning in the early hours of September 6. When they didn't return, search and rescue efforts were launched.
US Air Force officer reveals his prayer after getting shot down in Iran
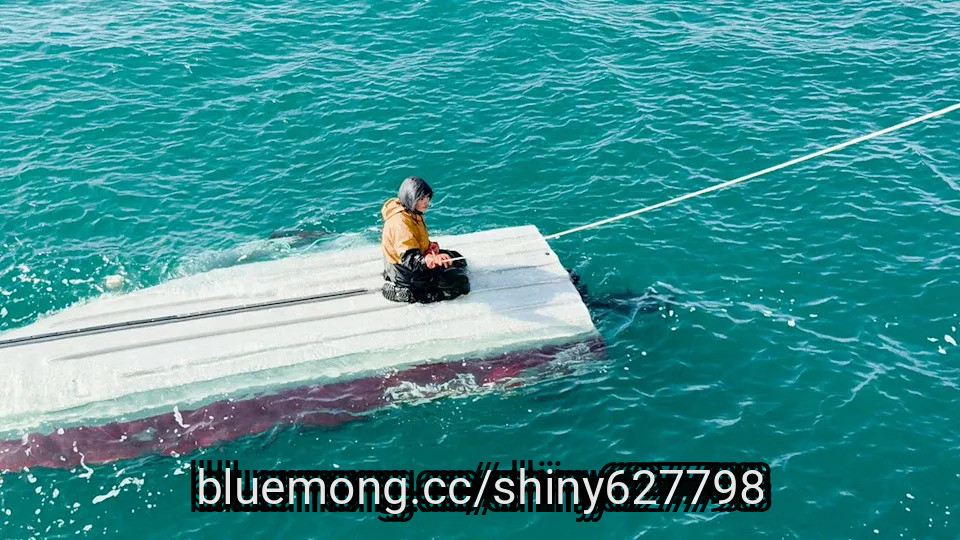
On Monday, around 10:30am, the Coast Guard spotted Parker around 10:30 a.m. on top of the capsized vessel in the Bering Sea and asked another boat to pick him up.
According to Alaska's News Source, their 18-foot skiff capsized after a fishing line got tangled in the motor. The boy's older brother Sidney reportedly got caught in the line and was pulled under the ship.
#sidney #september #brother #around
Fifteen-year-old Parker of Savoonga, Alaska set out with his older brother Sidney Kulowiyi, 35, and their cousin, Barton Rookok, 34, to fish for halibut on September 4, according to Anchorage Daily News. They planned on returning in the early hours of September 6. When they didn't return, search and rescue efforts were launched.
US Air Force officer reveals his prayer after getting shot down in Iran
On Monday, around 10:30am, the Coast Guard spotted Parker around 10:30 a.m. on top of the capsized vessel in the Bering Sea and asked another boat to pick him up.
According to Alaska's News Source, their 18-foot skiff capsized after a fishing line got tangled in the motor. The boy's older brother Sidney reportedly got caught in the line and was pulled under the ship.
#sidney #september #brother #around


12 hours ago
In an early offseason move, the Kansas City Chiefs shocked the football world when they traded away former All-Pro cornerback Trent McDuffie to the Los Angeles Rams. After all, how could a Chiefs team, ostensibly in the middle of a Super Bowl window, trade away a 26-year-old cornerback entering his prime like McDuffie? Couldn't they have used him during monster matchups like their home date with the Denver Broncos on Monday night?
At face value, the move is honestly still kind of baffling from a Kansas City perspective, considering that older Chiefs veterans like Travis Kelce and Chris Jones aren't getting any younger. But as you watch the Chiefs' defense try to adjust without McDuffie, know that they did have a good reason for dealing one of their better young players.
As explained by ESPN's Nate Taylor, the Chiefs entered the 2026 offseason knowing they wanted a big draft haul so they could try to open a new Super Bowl window while their current core begins to age out of the NFL. After reviewing their best options, they eventually came to the conclusion that trading away McDuffie, a player they weren't too keen on giving a lucrative contract extension to, was their optimal path toward that goal.
I would say acquiring a first-round draft pick in 2026 (which became defensive tackle Peter Woods) and a host of other solid draft ****** ets for McDuffie was a pretty good deal for the team, with all things considered.
More from ESPN:
#away #super
At face value, the move is honestly still kind of baffling from a Kansas City perspective, considering that older Chiefs veterans like Travis Kelce and Chris Jones aren't getting any younger. But as you watch the Chiefs' defense try to adjust without McDuffie, know that they did have a good reason for dealing one of their better young players.
As explained by ESPN's Nate Taylor, the Chiefs entered the 2026 offseason knowing they wanted a big draft haul so they could try to open a new Super Bowl window while their current core begins to age out of the NFL. After reviewing their best options, they eventually came to the conclusion that trading away McDuffie, a player they weren't too keen on giving a lucrative contract extension to, was their optimal path toward that goal.
I would say acquiring a first-round draft pick in 2026 (which became defensive tackle Peter Woods) and a host of other solid draft ****** ets for McDuffie was a pretty good deal for the team, with all things considered.
More from ESPN:
#away #super


12 hours ago
September's debate over Chinese and American AI spending puts Alibaba Group Holding Limited (NYSE:BABA) and Amazon.com, Inc. (NASDAQ:AMZN) on opposite sides of the same investment question. Both report strong demand for computing services. Shareholders still need that demand to justify the infrastructure bill.
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services
September 7 coverage of Jefferies' ***** ysis highlighted differences in spending intensity. The companies' own results suggest a more useful test than choosing a winner from headline capital expenditures: distinguish operating progress from cash committed ahead of future growth.
Alibaba's August 20 report showed June-quarter AI Cloud and Compute Services revenue increasing 45% to RMB48.44 billion. Segment adjusted EBITA reached RMB5.63 billion. The reporting group now combines its former Cloud Intelligence Group with T-Head, so investors should use the company's recast comparisons.
That operating improvement supports the case that computing demand can generate returns. It does not mean the spending cycle has already paid for itself. Group capital expenditures reached RMB67.68 billion, while free cash flow, a non-GAAP liquidity measure, was negative RMB44.67 billion for the quarter.
The opportunity is to keep expanding customer demand and utilization as new infrastructure becomes available. The risk is that cash outlays remain elevated while weaker returns elsewhere in the group reduce the room for error. Cloud growth alone cannot settle the value of the entire business.
#spending #cash #Services


12 hours ago
NVIDIA Corporation (NASDAQ:NVDA) has an argument against rapid hardware obsolescence: older accelerators still command rental prices. For CoreWeave, Inc. (NASDAQ:CRWV), which sells access to computing infrastructure, the harder question is how much of that rent becomes a return.
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return

12 hours ago
On August 4, Willis Lease Finance Corporation (NASDAQ:WLFC) reported second-quarter results that pulled in two directions at once. The lessor of commercial aircraft engines grew its operating business at a healthy clip, yet net income fell by more than half, a split that makes this quarter harder to read than the headline suggests.
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
Income from operations climbed 20.2% to $34.0 million in the quarter ended June 30, 2026, and the engine underneath that number is lease rent revenue, which rose 6.7% to $77.1 million as the average size of Willis Lease's portfolio expanded from a year earlier. Over the first six months of 2026, lease rent revenue is up 10.4% to $154.5 million, a steadier pace than the quarterly figure alone implies.
The company's trading business added to that. Willis Lease booked a $32.0 million gain on the sale of leased equipment, up 16.2%, after selling 21 engines and other parts and equipment during the quarter, compared with 14 engines and two airframes a year earlier. That kind of turnover matters for a leasing company, since selling ****** ets at a gain confirms that engine values in the market are holding up.
The bigger story sits in how Willis Lease is expanding beyond its own balance sheet. ****** ets under management, which folds in the company's on-balance-sheet fleet along with its Willis Aviation Capital business, grew 21% year over year to $4.4 billion. CEO Austin C. Willis tied that growth directly to building out Willis Aviation Capital, and the fee income backs that up: management and advisory fees jumped 113.4% to $5.5 million in the quarter and 194.9% to $13.4 million over six months. Two new investment fund partnerships, one with Liberty Mutual Investments that began operating in March 2026 and one with Blackstone Credit & Insurance that started in April 2026, are the mechanics behind that shift toward managing other people's capital rather than only deploying its own.
Net income attributable to common shareholders fell 51.2% to $28.7 million, and diluted earnings per share dropped from $2.81 to $1.31. Some of that gap traces to a tough comparison rather than a weaker quarter, since the second quarter of 2025 included a $43.0 million gain from the sale of the BAML business that had no counterpart this year. Willis Lease also recognized a $5.4 million loss on debt extinguishment in the quarter, and $12.4 million over six months, a cost tied to refinancing that simply was not there in 2025.
#lease #capital #months
12 hours ago
On August 5, Clear Channel Outdoor Holdings Inc. (NYSE:CCO) reported second-quarter results that showed the billboard and airport advertising company accelerating just as it prepares to leave the public markets. On February 9, Clear Channel agreed to be acquired by an investor consortium advised by Mubadala Capital for $2.43 per share, a deal stockholders approved on May 12, and one expected to close by the end of the third quarter of 2026. Because of the pending Merger, Clear Channel skipped its usual earnings call and offered no forward guidance.
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations
Consolidated revenue climbed 8.7% to $438.0 million in the quarter and 10.2% to $811.9 million over the first half, with the 2026 FIFA World Cup pulling in extra advertising spend across both of Clear Channel's segments. The America division, which houses the roadside billboard and street furniture business, grew revenue 7% to $324.3 million as demand from technology advertisers in the San Francisco/Bay Area market broadened out and digital billboard revenue rose 7.2% to $122 million. Airports revenue jumped 14% to $113.6 million, helped by strong demand at San Francisco
International Airport and digital sales that climbed 15.6% to $73.4 million, with national advertisers now accounting for 57.8% of that segment's revenue. Profitability grew even faster than the top line. Adjusted EBITDA rose 11.6% to $143.4 million for the quarter and 19% to $247.3 million for the first half, while Airports Segment Adjusted EBITDA jumped 22.8% to $29.9 million. Adjusted Funds From Operations climbed 61.6% to $44.9 million in the quarter, and for the first half it went from just $5 million a year ago to $51.5 million. On August 4, Clear Channel also closed the sale of its Spain business for about $132.3 million, proceeds it plans to put toward paying down debt.
The growth did not reach the bottom line. Clear Channel posted a loss from continuing operations of $10 million in the quarter, reversing a $6.3 million profit a year earlier, and the consolidated net loss came to $5 million versus net income of $10.6 million in the same period of 2025. Over six months, the loss from continuing operations widened 21.4% to $59.4 million. Costs rose alongside revenue. Direct operating and SG&A expenses increased 5.9% for the quarter, and Airports site lease expense alone jumped 12.0% to $67.1 million on higher minimum guaranteed payments and the renewed contract with the Metropolitan Washington Airports Authority.
#channel #revenue #airports #operations

15 hours ago
An Alaska teenager who survived nearly two days atop an overturned fishing skiff told his rescuers that his cousin had slipped away during the night and that his older brother remained beneath the vessel after the three were thrown into the frigid Bering Sea, according to rescuers and family members.
Derek Parker Aghnaanga, 15, was spotted Monday morning on the capsized skiff roughly four miles east of St. Lawrence Island after he, his 35-year-old brother Sidney Kulowiyi and their cousin disappeared during a fishing trip.
"Through the teeth chattering, he had mentioned that his brother was still under the skiff," Adam White, captain of the fishing vessel Northwest Explorer, told Anchorage affiliate KTUU-TV. "And then he said that, in the previous night, before our rescue, that his cousin had slipped away."
A GoFundMe page organized by relatives said Aghnaanga tried to hold onto his brother and cousin after they died, before their bodies were recovered.
Tragedy At Sea Leaves Teen Stranded On Overturned Boat For Nearly 3 Days In Frigid Waters
#skiff #frigid
Derek Parker Aghnaanga, 15, was spotted Monday morning on the capsized skiff roughly four miles east of St. Lawrence Island after he, his 35-year-old brother Sidney Kulowiyi and their cousin disappeared during a fishing trip.
"Through the teeth chattering, he had mentioned that his brother was still under the skiff," Adam White, captain of the fishing vessel Northwest Explorer, told Anchorage affiliate KTUU-TV. "And then he said that, in the previous night, before our rescue, that his cousin had slipped away."
A GoFundMe page organized by relatives said Aghnaanga tried to hold onto his brother and cousin after they died, before their bodies were recovered.
Tragedy At Sea Leaves Teen Stranded On Overturned Boat For Nearly 3 Days In Frigid Waters
#skiff #frigid

17 hours ago
Nasdaq-listed DeFi Development Corp (NASDAQ: $DFDV) has increased its Solana (CRYPTO: $SOL) treasury by 55,491 SOL, bringing its total holdings to about 2.39 million SOL and SOL equivalents.
The company said Monday that its treasury has grown roughly 2% since August 27 as it resumed regular Solana purchases and continued generating yield from its holdings. DeFi Development Corp is now the second-largest public-company holder of Solana after Forward Industries.
Alongside the treasury increase, the company established a $300 million at-the-market offering for its CHAD perpetual preferred stock. The Variable Rate Series C Perpetual Preferred Stock carries an initial annual dividend rate of 13%. DeFi Development said it plans to issue the shares at or above their $10 par value, with most of the proceeds expected to fund additional SOL purchases.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#NASDAQ #offering
The company said Monday that its treasury has grown roughly 2% since August 27 as it resumed regular Solana purchases and continued generating yield from its holdings. DeFi Development Corp is now the second-largest public-company holder of Solana after Forward Industries.
Alongside the treasury increase, the company established a $300 million at-the-market offering for its CHAD perpetual preferred stock. The Variable Rate Series C Perpetual Preferred Stock carries an initial annual dividend rate of 13%. DeFi Development said it plans to issue the shares at or above their $10 par value, with most of the proceeds expected to fund additional SOL purchases.
More From Cryptoprowl:
MEXC Launches Earn Plus With Limited-Time Event Offering Up to 800% APR Booster
#NASDAQ #offering

19 hours ago
Energy Transfer LP (NYSE:ET) is set to move the primary listing of its common and Series I preferred units from the New York Stock Exchange to the Texas Stock Exchange in early October, making it the first major company to make such a switch from the NYSE to the newly established Dallas exchange. Reuters said the companies moving to TXSE, including Energy Transfer and related energy businesses, represent nearly $100 billion in combined market value, giving the fledgling exchange an important early credibility boost.
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
For Energy Transfer LP (NYSE:ET), however, the more important question is whether the move can eventually translate into better investor visibility or valuation rather than simply giving the company a stronger Texas identity. WSJ reported that Energy Transfer is worth roughly $75 billion and that Executive Chairman Kelcy Warren is a major backer of TXSE, owning about 30% of its parent company. That relationship makes the listing particularly significant, but it also means investors may scrutinize whether the decision creates a tangible benefit for Energy Transfer unitholders rather than primarily helping establish the new exchange.
The strongest bull argument is that Energy Transfer LP (NYSE:ET) is positioning itself ahead of a potentially important shift in the U.S. energy infrastructure market. TXSE is backed by major financial institutions including BlackRock, Citadel Securities, and Charles Schwab, and winning a roughly $75 billion company gives the exchange substantially more credibility with institutional investors. If TXSE attracts additional large energy companies, Energy Transfer could benefit from becoming one of the exchange's anchor names and gaining greater visibility among investors already focused on Texas-based energy infrastructure.
More importantly, the listing decision fits the underlying environment in which Energy Transfer LP (NYSE:ET) operates. Reuters has highlighted continued investment in U.S. gas-fired generation, LNG infrastructure, and pipeline networks as electricity demand rises and countries seek reliable energy supplies. The U.S. is also building substantial additional LNG export capacity. That matters because Energy Transfer's extensive midstream network can benefit from higher volumes of natural gas, crude oil, and NGLs without taking the same direct commodity-price exposure as upstream producers. If rising power demand from data centers and continued LNG development drive greater demand for U.S. gas transportation, Energy Transfer could see expanding opportunities to place additional infrastructure into service and lock in long-duration cash flows.
#transfer #company #infrastructure #listing
19 hours ago
Most investors bury their mistakes in a footnote. Warren Buffett prints his in the shareholder letter, in plain English, with his name on it.
For most of the past decade, the story around Berkshire Hathaway (BRK.A) (BRK.B) and its industrial businesses was maintenance rather than growth. Railroads, utilities, insurance float, a slow grind of cash into the same pile.
The exciting money went somewhere else. It went into chips, cloud contracts and anything with a graphics processing unit bolted to it.
That framing skipped a physical step. Before one chip in a new data center draws a watt, somebody has to build the machine that produces the watt.
And the hottest, most stressed piece inside that machine is a cast slab of superalloy that only a handful of companies on earth know how to pour without cracking it.
#machine #warren #buffett #english
For most of the past decade, the story around Berkshire Hathaway (BRK.A) (BRK.B) and its industrial businesses was maintenance rather than growth. Railroads, utilities, insurance float, a slow grind of cash into the same pile.
The exciting money went somewhere else. It went into chips, cloud contracts and anything with a graphics processing unit bolted to it.
That framing skipped a physical step. Before one chip in a new data center draws a watt, somebody has to build the machine that produces the watt.
And the hottest, most stressed piece inside that machine is a cast slab of superalloy that only a handful of companies on earth know how to pour without cracking it.
#machine #warren #buffett #english


20 hours ago
Louisville Kings fans have two opportunities this week to commemorate the team's United Football League championship.
A celebration is set for 6-8 p.m. Wednesday, Sept. 16, at Lynn Family Stadium. Attendees will have the chance to meet coach Chris Redman and select players from the team, take photos with the United Bowl trophy and more.
For more information, click here.
Then, at 6 p.m. Thursday, Redman will serve as the grand marshal of the Jeffersontown Gaslight Festival Parade. He'll be joined by players and members of the coaching staff; and up to 50 season ticket holders will be walking alongside them. The parade begins at Jeffersontown Commons Shopping Center. For more information, click here.
Both events are free to the public.
#information
A celebration is set for 6-8 p.m. Wednesday, Sept. 16, at Lynn Family Stadium. Attendees will have the chance to meet coach Chris Redman and select players from the team, take photos with the United Bowl trophy and more.
For more information, click here.
Then, at 6 p.m. Thursday, Redman will serve as the grand marshal of the Jeffersontown Gaslight Festival Parade. He'll be joined by players and members of the coaching staff; and up to 50 season ticket holders will be walking alongside them. The parade begins at Jeffersontown Commons Shopping Center. For more information, click here.
Both events are free to the public.
#information
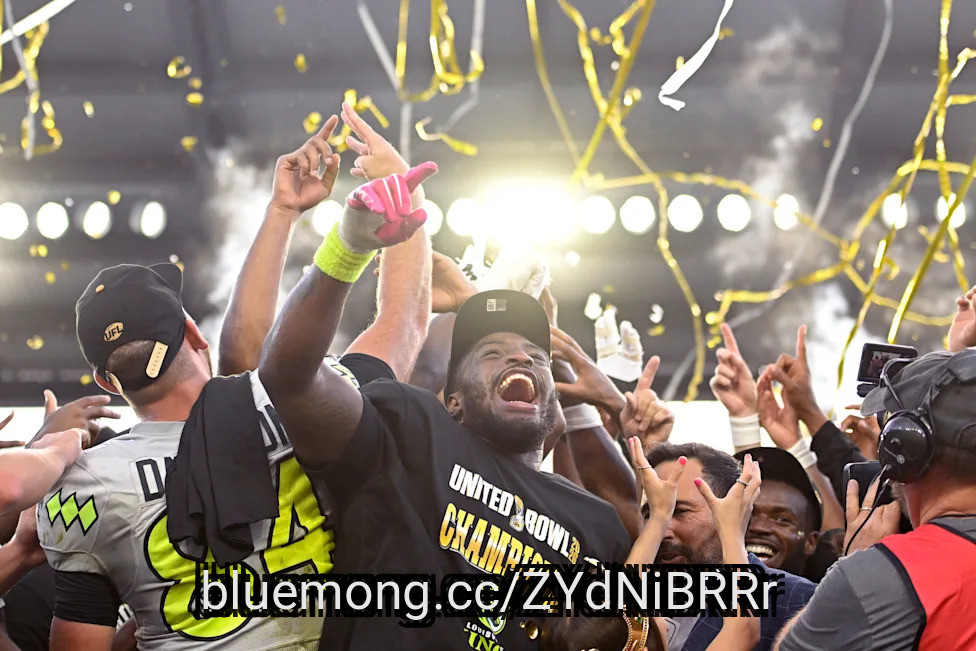

20 hours ago
Many older Americans are millionaires. In fact, the average household net worth among 65- to 74-year-olds is $1.79 million, according to Fidelity.
Some people have far more than that in retirement, which provides them with the financial security that people dream of enjoying during their later years in life. Of course, you still need to be cautious about how much money you withdraw each year so you don't drain your accounts dry.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#americans #year #ramsey
Some people have far more than that in retirement, which provides them with the financial security that people dream of enjoying during their later years in life. Of course, you still need to be cautious about how much money you withdraw each year so you don't drain your accounts dry.
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
Dave Ramsey warns nearly 50% of Americans are making 1 big Social Security mistake. Here's what it is and 3 simple steps to fix it ASAP
The tax breaks in Trump's 'big beautiful bill' expire after 2028. Here are 4 moves to make before the window closes
#americans #year #ramsey
20 hours ago
Sydney Sweeney has come under fire for another advertising campaign.
The Euphoria actor has teamed up with Novig, a new platform that combines sports trading with prediction-market features and is restricted to users aged 21 and above.
But the conversation isn't about the platform, which she is the new strategic partner and equity holder for. Instead, the marketing campaign has sparked a debate about how women are represented in sports.
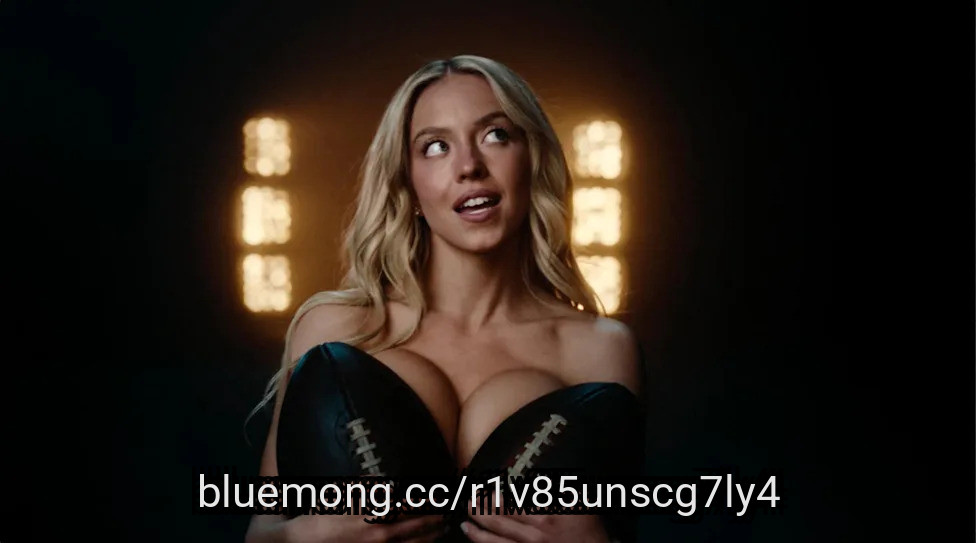
The minute-long ad, ****** led "Just Sports," features the Christy actress posing in nothing but strategically placed footballs, basketball hoops, hockey pads, and a pool cue. The concept is that the platform focuses on sports and nothing else.
Marissa Womack, manager of game day promotions for the Harrisburg Senators, addressed the video and its backlash in a TikTok video: "This isn't about me being jealous or insecure. It's about the fact that this is already a male-dominated field where we constantly have to prove we belong. When the only representation is ****** ualization, you see fewer and fewer young women wanting to pursue this industry."
#sports #platform #nothing
The Euphoria actor has teamed up with Novig, a new platform that combines sports trading with prediction-market features and is restricted to users aged 21 and above.
But the conversation isn't about the platform, which she is the new strategic partner and equity holder for. Instead, the marketing campaign has sparked a debate about how women are represented in sports.
The minute-long ad, ****** led "Just Sports," features the Christy actress posing in nothing but strategically placed footballs, basketball hoops, hockey pads, and a pool cue. The concept is that the platform focuses on sports and nothing else.
Marissa Womack, manager of game day promotions for the Harrisburg Senators, addressed the video and its backlash in a TikTok video: "This isn't about me being jealous or insecure. It's about the fact that this is already a male-dominated field where we constantly have to prove we belong. When the only representation is ****** ualization, you see fewer and fewer young women wanting to pursue this industry."
#sports #platform #nothing

20 hours ago
Nicole Kidman's younger daughter is still rarely seen in public, but the gaps between appearances are getting shorter.
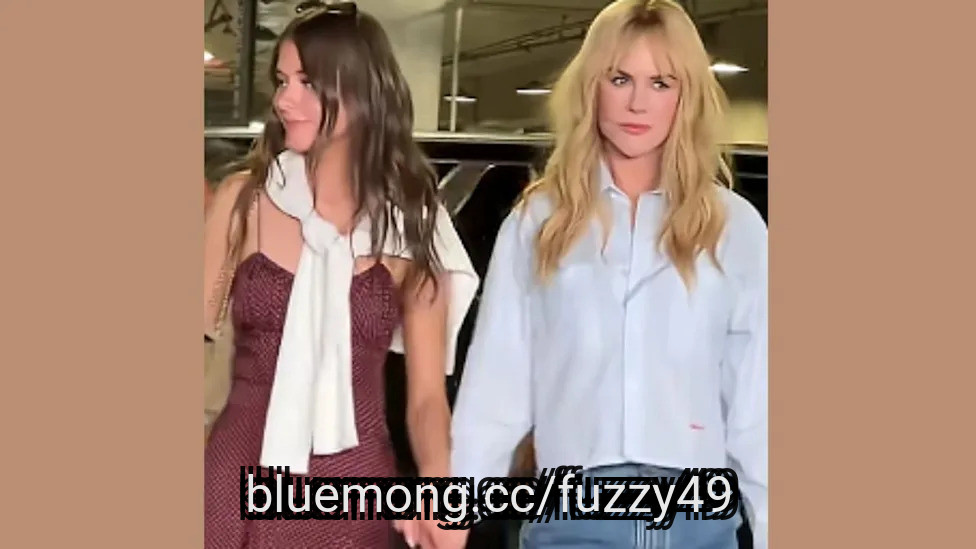
The 59-year-old actor brought 15-year-old Faith Margaret to the U.S. Open in New York on Sept. 11, with the mother and daughter arriving at the USTA Billie Jean King National Tennis Center hand in hand before watching the men's semifinals.
Faith has generally maintained a lower public profile than her older sister Sunday Rose, who has already built a modeling résumé. That made the relaxed outing particularly noticeable as Faith walked beside her mother in a polka-dot maxi dress while Kidman traded her recent premiere gowns for jeans, sneakers and a pale blue shirt.
Faith has also joined Kidman at several public events over the past year, appeared with her in a beauty campaign and traveled with her to Australia earlier this month, although most of those appearances have remained tied to her mother's work.
Kidman and Faith attended Day 13 of the tournament at Arthur Ashe Stadium on Friday. E! News reported that the pair entered the venue holding hands before settling in for the men's semifinal action.
#hand
The 59-year-old actor brought 15-year-old Faith Margaret to the U.S. Open in New York on Sept. 11, with the mother and daughter arriving at the USTA Billie Jean King National Tennis Center hand in hand before watching the men's semifinals.
Faith has generally maintained a lower public profile than her older sister Sunday Rose, who has already built a modeling résumé. That made the relaxed outing particularly noticeable as Faith walked beside her mother in a polka-dot maxi dress while Kidman traded her recent premiere gowns for jeans, sneakers and a pale blue shirt.
Faith has also joined Kidman at several public events over the past year, appeared with her in a beauty campaign and traveled with her to Australia earlier this month, although most of those appearances have remained tied to her mother's work.
Kidman and Faith attended Day 13 of the tournament at Arthur Ashe Stadium on Friday. E! News reported that the pair entered the venue holding hands before settling in for the men's semifinal action.
#hand

20 hours ago
Sydney Sweeney's latest ad campaign has landed very differently with some of the women who have spent their lives competing in sports.
Four-time Olympic gold medalist Ariarne ***** mus is among a growing group of athletes criticizing Sweeney's new "Just Sports" campaign for Novig, a sports prediction market. The campaign shows Sweeney nude or minimally dressed while footballs, basketballs, hockey equipment and other sports gear strategically cover her body.
Athletes including former UCLA gymnast Gracie Kramer, Olympic swimmer Lani Pallister, British sprinter Amy Hunt and water polo Olympian Tilly Kearns have responded by putting competition, training and athletic achievement back at the center of their own posts.
Sweeney is more closely tied to the campaign than a typical celebrity spokesperson. Novig announced that she joined the company as a strategic partner and equity holder, while Sweeney said she had participated in the creative process from the beginning.
The four-time Olympic champion, who retired from competitive swimming in 2025, wrote on Instagram that she had believed this kind of marketing belonged in the past.
#four
Four-time Olympic gold medalist Ariarne ***** mus is among a growing group of athletes criticizing Sweeney's new "Just Sports" campaign for Novig, a sports prediction market. The campaign shows Sweeney nude or minimally dressed while footballs, basketballs, hockey equipment and other sports gear strategically cover her body.
Athletes including former UCLA gymnast Gracie Kramer, Olympic swimmer Lani Pallister, British sprinter Amy Hunt and water polo Olympian Tilly Kearns have responded by putting competition, training and athletic achievement back at the center of their own posts.
Sweeney is more closely tied to the campaign than a typical celebrity spokesperson. Novig announced that she joined the company as a strategic partner and equity holder, while Sweeney said she had participated in the creative process from the beginning.
The four-time Olympic champion, who retired from competitive swimming in 2025, wrote on Instagram that she had believed this kind of marketing belonged in the past.
#four

2 days ago
ATLANTA − Tennessee football played its first road game of the season at Georgia Tech but it sure didn't look that way.
UT fans helped sell out Bobby Dodd Stadium as the No. 18 Vols (2-0) beat Georgia Tech 45-24 on Sept. 12. UT coach Josh Heupel noticed the support from the fans before he stepped on the field to play the Yellow Jackets (0-2).
"We leave our hotel and you see nothing but orange and white on our way here," Heupel said. "From older fans who have been here for a lot of generations to some younger ones who don't know how to tie their shoes yet, you walk into the stadium 60 minutes before kickoff and a majority of the crowd is Tennessee orange. It's pretty special."
Freshman quarterback Faizon Brandon, making the first road start of his college career, said UT fans gave him and his teammates a distinct advantage when operating the offense.
"It was a lot of orange," Brandon said. "It definitely made things easier. Wasn't too much noise. Definitely got a little rowdy sometimes, but seeing all the orange, it definitely made me proud."
#orange #definitely #brandon #first
UT fans helped sell out Bobby Dodd Stadium as the No. 18 Vols (2-0) beat Georgia Tech 45-24 on Sept. 12. UT coach Josh Heupel noticed the support from the fans before he stepped on the field to play the Yellow Jackets (0-2).
"We leave our hotel and you see nothing but orange and white on our way here," Heupel said. "From older fans who have been here for a lot of generations to some younger ones who don't know how to tie their shoes yet, you walk into the stadium 60 minutes before kickoff and a majority of the crowd is Tennessee orange. It's pretty special."
Freshman quarterback Faizon Brandon, making the first road start of his college career, said UT fans gave him and his teammates a distinct advantage when operating the offense.
"It was a lot of orange," Brandon said. "It definitely made things easier. Wasn't too much noise. Definitely got a little rowdy sometimes, but seeing all the orange, it definitely made me proud."
#orange #definitely #brandon #first


2 days ago
Brothers T.J., J.J., and Derek have been through thick and thin, with all three charting a life in the NFL. They have now moved on to build their own little families, but the brotherly bond is as strong as ever. J.J. showed up to congratulate the youngest Watt, who will soon have a noisy household.
Pittsburgh Steelers' T.J. Watt and his wife, Dani, are expecting their second child together, they announced on Instagram. They shared a maternity photoshoot set in a field of purple flowers, along with their older daughter, Blakely.
"Let's Goooo!!!!!" J.J. commented.
The elder Watt had also honored his younger brother when the couple was expecting Marie. J.J. surprised his younger brother on-air with a custom No. 90 Steelers jersey that had "Dad" written across the back and handed that jersey before Pittsburgh's home opener.
T.J. Watt's career moves and life off the field are always worth following. Subscribe for more interesting stories.
#field #brothers
Pittsburgh Steelers' T.J. Watt and his wife, Dani, are expecting their second child together, they announced on Instagram. They shared a maternity photoshoot set in a field of purple flowers, along with their older daughter, Blakely.
"Let's Goooo!!!!!" J.J. commented.
The elder Watt had also honored his younger brother when the couple was expecting Marie. J.J. surprised his younger brother on-air with a custom No. 90 Steelers jersey that had "Dad" written across the back and handed that jersey before Pittsburgh's home opener.
T.J. Watt's career moves and life off the field are always worth following. Subscribe for more interesting stories.
#field #brothers

2 days ago
What's been exciting about Robinhood Chain (RHC) is seeing tokens attempt new mechanisms to answer questions like: why would someone hold this token? How can we make participating in this token attractive? And, more broadly, how can market activity around a token overall be designed to contribute to its success?
All new projects should ask this and the best ones do, but when you have a new chain, with a new market and new infrastructure, it can be sort of a "clean slate" or fresh design ***** e and breathe new life into the solutions to such questions.
The dominant answer right now seems to be distributions: hold this token and get stock, tokens, etc. Below are projects which execute this with a twist, expanding either the type of rewards or the source for rewards that end up in the hands of holders.
Others attempt to answer the second question, experimenting with new infrastructure that tries to make market activity, of whatever kind, directly contribute to the token's success.
These are all shared to give you a sense of what novelty can look like amidst this meta and act as a guiding force to understand what's been done, what's working, and overall where to direct your attention towards.
#make
All new projects should ask this and the best ones do, but when you have a new chain, with a new market and new infrastructure, it can be sort of a "clean slate" or fresh design ***** e and breathe new life into the solutions to such questions.
The dominant answer right now seems to be distributions: hold this token and get stock, tokens, etc. Below are projects which execute this with a twist, expanding either the type of rewards or the source for rewards that end up in the hands of holders.
Others attempt to answer the second question, experimenting with new infrastructure that tries to make market activity, of whatever kind, directly contribute to the token's success.
These are all shared to give you a sense of what novelty can look like amidst this meta and act as a guiding force to understand what's been done, what's working, and overall where to direct your attention towards.
#make


2 days ago
Dell Technologies (DELL) stock more than quadrupled over the past year, a 323% gain, against about 18% for the S&P 500, and even Hewlett Packard Enterprise (HPE), up 130.6%, finished far behind. Management had described most of the drivers before the run began: customers sitting on old servers, AI orders that had outrun shipments earlier in the year, and costs falling while sales rose. Those signs could not tell you how far the stock would go.
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server

2 days ago
Andrea Celina is a social media influencer best known as the ex-wife of WBC welterweight champion Ryan Garcia and the mother of two of his three children. Garcia, who also has an older daughter named Rylie, is preparing to defend his WBC welterweight ****** le against Conor Benn at T-Mobile Arena in Las Vegas on September 12. Here's what you need to know.
Celina and Garcia began dating in 2019 and became parents before they were married.
Their first child together, daughter Bela, was born in December 2020. According to the former couple's legal documents, Garcia and Celina married on January 14, 2021.
Garcia occasionally shared their relationship with his social media followers. During a 2021 trip to Hawaii, the boxer posted a photo of himself and Celina posing with a surfboard.
"In love with you 💍❤️," he captioned the picture.
#garcia #daughter
Celina and Garcia began dating in 2019 and became parents before they were married.
Their first child together, daughter Bela, was born in December 2020. According to the former couple's legal documents, Garcia and Celina married on January 14, 2021.
Garcia occasionally shared their relationship with his social media followers. During a 2021 trip to Hawaii, the boxer posted a photo of himself and Celina posing with a surfboard.
"In love with you 💍❤️," he captioned the picture.
#garcia #daughter


2 days ago
Extreme weather is creating a more demanding environment for property owners, insurers, and communities. According to the National Centers for Environmental Information (NCEI), the United States recorded 27 confirmed billion-dollar weather and climate disasters in 2024, resulting in a total cost of $182.7 billion. These events spanned a wide range of extremes, including severe storm events, tropical cyclones, wildfires, drought/heat waves, and winter storm/cold wave events. Over the last decade, ***** ulative losses from these disasters have exceeded $1.4 trillion, driven significantly by population growth, material wealth, and increased development in hazard-prone areas. These figures suggest that the financial consequences of extreme events may increasingly depend on how accurately the value of exposed property is understood before a loss occurs.
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information
That question becomes especially consequential during reconstruction. A 2026 report from Bloomberg, featured in Claims Journal, noted that surveys conducted by United Policyholders since 2007 found an average of two-thirds of wildfire survivors reporting that they were underinsured, with an average shortfall of $200,000 or more. The Insurance Information Institute has similarly estimated that two-thirds of American homeowners may be underinsured for wildfire losses, typically by about 20%, and in some cases by as much as 60%. These findings illustrate how the presence of an insurance policy can still leave a substantial difference between available coverage and the resources required to rebuild, particularly when construction costs rise after a catastrophe.
The financial implications can extend across the broader insurance ecosystem. Aon's 2026 Climate and Catastrophe Insight reported approximately $260 billion in global economic losses from natural catastrophes during 2025, compared with $127 billion in insured losses. For property stakeholders, such a figure may place greater attention on the relationship between the value ***** igned to an ***** et, the cost of restoring it, and the capital available when a loss occurs.
Frequency can add another layer to that calculation. Data from NCEI indicate that the average interval between U.S. billion-dollar disaster events was approximately 16 days during 2020–2024, compared with 82 days during the 1980s. NCEI notes that shorter intervals can leave less time and fewer resources for response, recovery, and preparation for subsequent events. As the time between major events contracts, property valuations may require more frequent attention because construction costs, labor conditions, materials, and local economic circumstances can change between policy reviews.
#property #losses #insurance #information


2 days ago
At about $644.38 a share, Meta Platforms (META) stock carries options that price a range from roughly $418 to $993 for about a year out. The floor of that band would take about a third off a position, and the ceiling would add more than half. Wide as it is, the range carries only a normal premium over how much the shares actually moved in the past year.
What Could That Range Do To Your Shares?
On each share, the ceiling is a gain of about $349 and the floor a loss of about $226. The gap is lopsided because a price can rise without limit but cannot fall below zero. The options put roughly a two-in-three chance on the stock finishing between them.
That leaves roughly a 16% chance of finishing above the ceiling and roughly a 16% chance of finishing below the floor. For a holder, the downside tail is the one to sit with: about one-in-six odds of losing more than a third. The floor also sits more than $100 below $525.23, the lowest price of the past 52 weeks. The shares are already down 15.6% over twelve months, against a 17.9% return for the S&P 500, though they have returned 13.0% over the past three months.
Does Meta Stock Usually Move This Much?
#ceiling #past #below
What Could That Range Do To Your Shares?
On each share, the ceiling is a gain of about $349 and the floor a loss of about $226. The gap is lopsided because a price can rise without limit but cannot fall below zero. The options put roughly a two-in-three chance on the stock finishing between them.
That leaves roughly a 16% chance of finishing above the ceiling and roughly a 16% chance of finishing below the floor. For a holder, the downside tail is the one to sit with: about one-in-six odds of losing more than a third. The floor also sits more than $100 below $525.23, the lowest price of the past 52 weeks. The shares are already down 15.6% over twelve months, against a 17.9% return for the S&P 500, though they have returned 13.0% over the past three months.
Does Meta Stock Usually Move This Much?
#ceiling #past #below


2 days ago
Toward the end of the lightning round on September 8, when a caller inquired about AstraZeneca PLC (NYSE:AZN), Mad Money host Jim Cramer commented:
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
Alright, now, AstraZeneca reminds me of a company, it's not unlike Novartis. I'm a little nervous about it. It's been missing some of its trials. I don't think COPD is enough to change my mind… I am not going to put my money on AstraZeneca.
AstraZeneca PLC (NYSE:AZN) maintains a solid financial foundation supported by steady top-line growth and disciplined cost management. In its second-quarter report, the company generated total revenue of $15.38 billion, marking a 6.4% increase compared to the same period last year. Adjusted earnings per share reached $2.63, outperforming ****** yst consensus estimates.
The profitability was driven by strong global demand for core oncology and rare disease treatments, which successfully offset revenue headwinds from generic competition affecting older blockbusters like Farxiga and Brilinta. With a net margin hovering around 17.02% and management reiterating its full-year guidance for mid-to-high single-digit revenue growth along with low double-digit core EPS expansion, the core business continues to demonstrate commercial resilience.
The primary driver behind the skepticism could be based on tangible execution risks and regulatory hurdles that threaten AstraZeneca PLC's (NYSE:AZN) long-term top line. A significant blow to the rare disease division came when anselamimab failed to achieve statistical significance for the primary endpoint in the overall AL amyloidosis population in the Phase III CARES program, although AstraZeneca reported encouraging results in a prespecified subgroup of patients with kappa light-chain amyloidosis.
#management
2 days ago
Investors seeking exposure to artificial intelligence infrastructure must weigh the explosive growth of Astera Labs Inc (NASDAQ:ALAB) against the established scale and diverse portfolio of Marvell Technology Inc(NASDAQ:MRVL) to determine the better buy.
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million
Both companies focus on the plumbing of the digital world, ensuring data moves quickly between processors and memory. While Astera Labs focuses on specialized connectivity for AI racks, Marvell offers a broader range of networking, storage, and custom compute solutions. This comparison explores which strategy offers more potential for long-term investors.
Astera Labs designs connectivity solutions that integrate various protocols to support rack-scale AI infrastructure, a high-growth niche among semiconductor stocks. The company serves major hyperscalers and equipment manufacturers who need to overcome data bottlenecks in massive data centers, though its revenue is highly concentrated. In 2025, one end customer -- Amazon.com Inc (NASDAQ:AMZN) -- accounted for over 70% of revenue, which adds a significant layer of risk to the business model.
According to its latest annual report, filed for the fiscal year ended Dec. 31, 2025, revenue reached close to $853 million, representing a significant jump of 115% compared with the prior fiscal year. This growth trajectory helped the company transition to a net income of just over $219 million after recording losses in the previous two years. The net margin for the latest year was close to 26%.
As of its December 2025 balance sheet, the debt-to-equity ratio was 0.0x, meaning the company carries no debt relative to its shareholder equity, while the so-called current ratio was 10.2x. Free cash flow for the period reached nearly $282 million. Note that stock-based compensation (SBC) represented roughly 50.1% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#company #million

2 days ago
DE and CAT have surged 47% and 44% YTD respectively, roughly four times the industrial sector's gain, forcing holders to weigh profits against further upside.
PCAR, a comparable industrial name, has gained only 14% YTD alongside XLI, confirming the rally is stock-specific rather than a broad sector re-rating.
Neither stock has flashed a sell signal, and benchmark-driven money chasing year-to-date winners could extend both rallies before the gap narrows.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Caterpillar didn't make the cut. Enter your email to see the names that beat CAT. The report is free. Enter your email and see if any of your stocks made the cut.
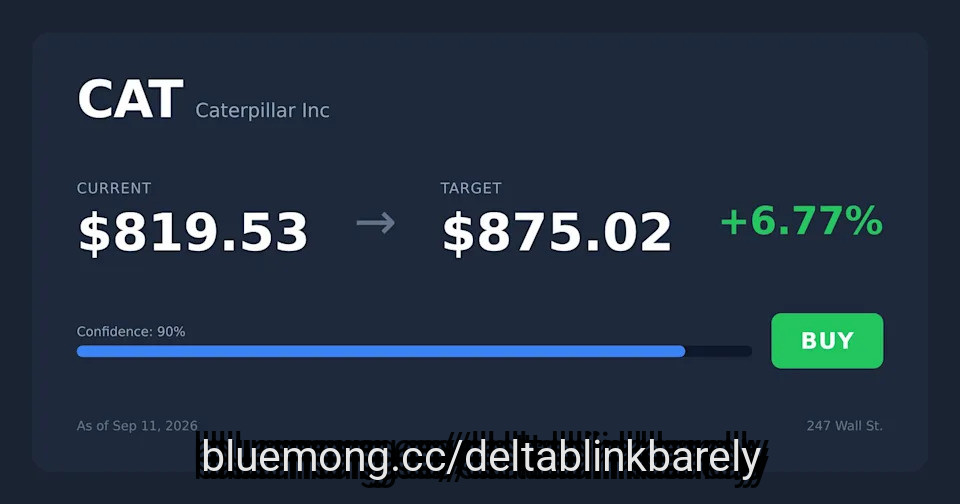
Shares of Deere & Company (NYSE:DE) and Caterpillar (NYSE:CAT) sit near the top of the industrial leaderboard this year, and both are adding to the gain again in Friday midday trading. Deere stock is up 47% year to date (YTD) to $680.98, and it's up 0.5% on the session. Meanwhile, Caterpillar stock is up 44% YTD to $821.19, rising 2% Friday.
#enter #date
PCAR, a comparable industrial name, has gained only 14% YTD alongside XLI, confirming the rally is stock-specific rather than a broad sector re-rating.
Neither stock has flashed a sell signal, and benchmark-driven money chasing year-to-date winners could extend both rallies before the gap narrows.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Caterpillar didn't make the cut. Enter your email to see the names that beat CAT. The report is free. Enter your email and see if any of your stocks made the cut.
Shares of Deere & Company (NYSE:DE) and Caterpillar (NYSE:CAT) sit near the top of the industrial leaderboard this year, and both are adding to the gain again in Friday midday trading. Deere stock is up 47% year to date (YTD) to $680.98, and it's up 0.5% on the session. Meanwhile, Caterpillar stock is up 44% YTD to $821.19, rising 2% Friday.
#enter #date


2 days ago
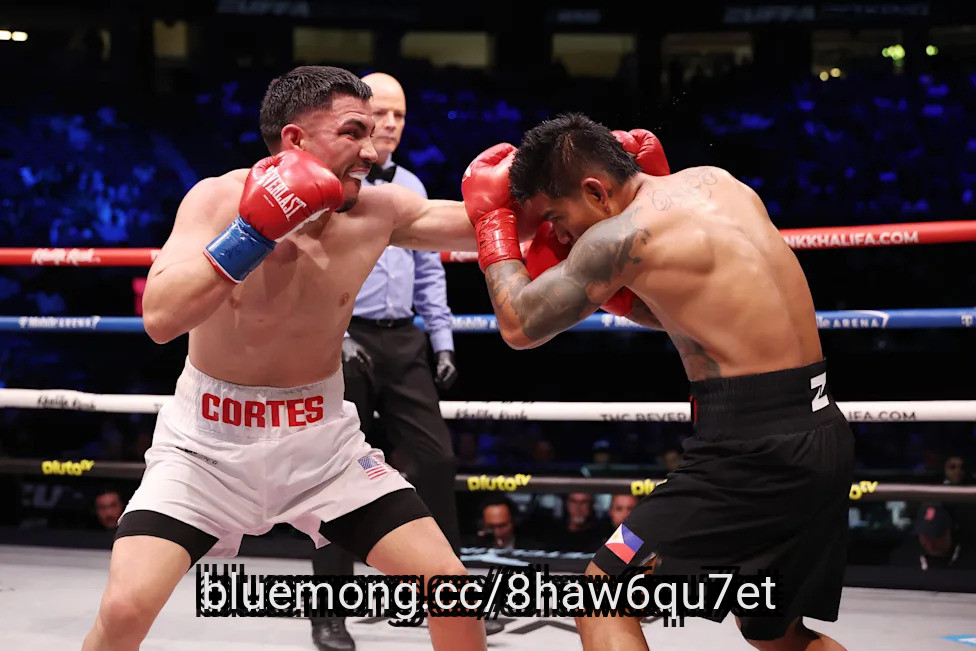
Andres Cortes remained unbeaten with a solid but somewhat strange victory over Mark Magsayo, who may have set a new record for amount of times a fighter was knocked down but officially wasn't, and a late rally from Magsayo wasn't nearly enough.
Two knockdown calls by referee Celestino Ruiz were reversed, and Magsayo was down without being ruled down twice after that, which was probably the most memorable thing about the fight.
The former featherweight ****** leholder Magsayo (29-3, 19 KO) did show some signs of life late in the fight, but it couldn't overcome the earlier lead built by Cortes, who improves to 26-0 (13 KO).
Join us NOW for LIVE, round-by-round updates during the rest of the Garcia vs Benn show! Click here!
Judges Eric Cheek, Chris Migliore, and Davis Sutherland all scored the fight 97-93 for Cortes.
#magsayo #andres
Two knockdown calls by referee Celestino Ruiz were reversed, and Magsayo was down without being ruled down twice after that, which was probably the most memorable thing about the fight.
The former featherweight ****** leholder Magsayo (29-3, 19 KO) did show some signs of life late in the fight, but it couldn't overcome the earlier lead built by Cortes, who improves to 26-0 (13 KO).
Join us NOW for LIVE, round-by-round updates during the rest of the Garcia vs Benn show! Click here!
Judges Eric Cheek, Chris Migliore, and Davis Sutherland all scored the fight 97-93 for Cortes.
#magsayo #andres
2 days ago
High-performance computing is currently undergoing a massive generational shift. Deciding between Astera Labs Inc (NASDAQ:ALAB) and Applied Materials Inc (NASDAQ:AMAT) means choosing between a fast-growing connectivity specialist and an established ******* an of manufacturing equipment.
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ
Astera Labs focuses on the internal plumbing of data centers, providing chips that move data between processors. Applied Materials builds the actual machines that make those chips possible. While both benefit from artificial intelligence, they occupy very different rungs on the technology ladder.
Astera Labs sells high-speed connectivity hardware and software designed for AI-heavy data centers. Its primary products include PCIe and Ethernet solutions that help hyperscale cloud providers manage massive data workloads. In its latest annual report, filed for the period ending December 31, 2025, the company noted that one end customer represented more than 70% of its revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached nearly $853 million, which is an increase of approximately 115% over the prior year. This growth resulted in a net income of roughly $219 million, compared to a net loss in the previous fiscal year. The company recorded a net margin of close to 26% during this period. Such expansion is notable among semiconductor stocks catering to the cloud market.
The company carries no debt, resulting in a debt-to-equity ratio of 0.0x. This metric compares total debt to shareholder equity to show how a firm finances its ******* ets. As of its December 2025 balance sheet, the so-called current ratio was nearly 10.2x, indicating a strong ability to cover short-term debts. Free cash flow was roughly $282 million. Note that stock-based compensation represented just about 50% of operating cash flow, which inflates reported cash generation since SBC is a non-cash expense added back in the cash flow statement.
#million #flow #NASDAQ

2 days ago
As artificial intelligence matures, investors must decide between the high-growth niche players and the foundational giants. Choosing between Astera Labs Inc (NASDAQ:ALAB) and Taiwan Semiconductor Manufacturing Co (NYSE:TSM) involves weighing explosive potential against established dominance.
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company
Astera Labs provides the critical connectivity infrastructure that allows AI chips to communicate within data centers. Meanwhile, Taiwan Semiconductor Manufacturing operates as the world's largest dedicated chip foundry, producing the actual processors for almost every major tech firm. Both companies are central to the future of semiconductor stocks.
Astera Labs specializes in connectivity solutions designed to remove bottlenecks in high-performance data centers. The company sells hardware and software that helps AI accelerators, such as those made by major chip designers, communicate efficiently across servers. Its customer base is highly concentrated, primarily consisting of the largest cloud providers and system manufacturers. In 2025, one end customer accounted for over 70% of total revenue. Customer concentration like this adds a layer of risk to the business.
In FY 2025, revenue reached more than $852.5 million, representing an impressive increase of roughly 115% compared to the prior year. This rapid growth helped the company pivot from a loss in previous years to a net income of approximately $219 million. The net margin, which measures how much of each dollar of sales remains as profit, stood at nearly 26%. This trajectory highlights the surging demand for the specialized connectivity chips required for large-scale AI deployments.
As of its December 2025 balance sheet, the company reported a debt-to-equity ratio of 0.0x, indicating it holds no debt relative to its shareholder equity. Its so-called current ratio, which compares short-term ******* ets to short-term liabilities, was a robust 10.2x. Free cash flow, or the cash left over after paying for operations and equipment, was approximately $282 million. Note that stock-based compensation represented roughly 50% of operating cash flow, which inflates reported cash generation since this is a non-cash expense added back in the cash flow statement.
#company

2 days ago
Apple (AAPL) is selling iPhones and Macs faster than it can build them, but the number a holder should fear most is the gross margin underneath those sales. Leaving out tariff refunds, that margin fell in the June quarter and is guided lower again for the September quarter. Management puts both steps down to rising memory prices, while the stock's price-to-earnings multiple sits near the top of its 10-year range.
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year
Excluding Tariff Refunds, Apple's Margin Slips As iPhone And Mac Set June-Quarter Records
Demand is not the worry. iPhone revenue rose 22% from a year earlier in the June quarter and Mac revenue rose 29%, both June-quarter records. Management says the brake on sales is supply of the advanced nodes its chips are made on.
Reported gross margin was 50.1% in the June quarter, but tariff refunds supplied about two points of it. Without them, the margin fell 120 basis points from 49.3% in the March quarter, and the September-quarter guide takes off another 160 basis points at its midpoint. On $466.8 billion of revenue over the past year, each point of gross margin is worth about $4.7 billion of gross profit.
And Management Says Memory Prices Explain All Of That Slide
#gross #tariff #year


2 days ago
AKRON, Ohio (AP) — Marty Whims II got to experience the joy and frustration of being the offensive coordinator for a Football Bowl Subdivision team on Saturday.
Unfortunately, it lasted for only four plays.
Akron was moving the ball on its first possession against Robert Morris when wide receiver Marcel Williams fumbled at the Colonials' 37-yard line. David Johnson recovered the ball after Tasheen Howard and Jake Lopinto forced the fumble.
"We moved the ball, got some first downs. I thought we were going to get a touchdown if we didn't fumble," Whims said shortly after his OC stint ended.
Whims got to call plays as part of Akron's "Offensive Coordinator of the Game" for its home opener. The 46-year-old Whims — a longtime season-ticket holder — graduated from Akron and is the chief financial officer for Stark Enterprises.
#fumble
Unfortunately, it lasted for only four plays.
Akron was moving the ball on its first possession against Robert Morris when wide receiver Marcel Williams fumbled at the Colonials' 37-yard line. David Johnson recovered the ball after Tasheen Howard and Jake Lopinto forced the fumble.
"We moved the ball, got some first downs. I thought we were going to get a touchdown if we didn't fumble," Whims said shortly after his OC stint ended.
Whims got to call plays as part of Akron's "Offensive Coordinator of the Game" for its home opener. The 46-year-old Whims — a longtime season-ticket holder — graduated from Akron and is the chief financial officer for Stark Enterprises.
#fumble





