

5 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#

6 days ago
Chevron Corporation (NYSE:CVX) is about to significantly expand its operations in Venezuela. The company's CFO, Eimear Bonner, revealed at a Barclays conference on September 8 that the American oil giant plans to more than double the number of oil rigs it operates in the country as part of its five-year plan to increase output.
The statement follows the company's recent announcement that its joint venture partnerships in Venezuela would invest more than $7 billion to more than double oil output to 600,000 barrels per day by 2031. The current production from Chevron's three Venezuelan JVs totals around 290,000, which is all exported to the United States.
The move builds on Chevron's longstanding presence in Venezuela, as it was the only American oil major that continued operating in the country under a special US license, allowing it to produce and export oil despite the sanctions.
The expansion comes alongside a much larger agreement between Washington and Caracas announced this month, which gave the US majority control over around 20% of Venezuela's proven crude reserves. The White House has now invited American oil companies to revive and modernize the South American country's oil infrastructure and more than double its crude production in the next few years.
Chevron has maintained operations in Venezuela since 1923 and even stayed through the nationalizations that forced ExxonMobil and ConocoPhillips to exit in 2007. This gives it a significant competitive advantage, since it already has a longstanding relationship with the state-owned PDVSA and extensive experience operating in the country's complex regulatory environment.
#around
The statement follows the company's recent announcement that its joint venture partnerships in Venezuela would invest more than $7 billion to more than double oil output to 600,000 barrels per day by 2031. The current production from Chevron's three Venezuelan JVs totals around 290,000, which is all exported to the United States.
The move builds on Chevron's longstanding presence in Venezuela, as it was the only American oil major that continued operating in the country under a special US license, allowing it to produce and export oil despite the sanctions.
The expansion comes alongside a much larger agreement between Washington and Caracas announced this month, which gave the US majority control over around 20% of Venezuela's proven crude reserves. The White House has now invited American oil companies to revive and modernize the South American country's oil infrastructure and more than double its crude production in the next few years.
Chevron has maintained operations in Venezuela since 1923 and even stayed through the nationalizations that forced ExxonMobil and ConocoPhillips to exit in 2007. This gives it a significant competitive advantage, since it already has a longstanding relationship with the state-owned PDVSA and extensive experience operating in the country's complex regulatory environment.
#around

6 days ago
SEOUL, Sept 20 (Reuters) - North Korea launched two missiles off its eastern coast on Sunday, its second set of tests in roughly a week and days after Pyongyang accused the US of driving tensions on the Korean Peninsula through a series of military drills.
Just three hours after launching a short-range ballistic missile (SRBM) toward the East Sea on Sunday afternoon, North Korea fired another short-range ballistic missile, according to South Korea's defence ministry.
If the subsequent launch is confirmed to be a ballistic missile, it will mark two consecutive ballistic missile tests by North Korea within a three-hour window.
South Korea's Joint Chiefs of Staff said it detected the first test firing from the Wonsan area around 3 p.m. (0600 GMT), identifying the weapon as a ballistic missile. ***** an's defence ministry also said it appeared to be a ballistic missile.
Japanese public broadcaster NHK said the projectile had come down outside ***** an's exclusive economic zone.
#sunday
Just three hours after launching a short-range ballistic missile (SRBM) toward the East Sea on Sunday afternoon, North Korea fired another short-range ballistic missile, according to South Korea's defence ministry.
If the subsequent launch is confirmed to be a ballistic missile, it will mark two consecutive ballistic missile tests by North Korea within a three-hour window.
South Korea's Joint Chiefs of Staff said it detected the first test firing from the Wonsan area around 3 p.m. (0600 GMT), identifying the weapon as a ballistic missile. ***** an's defence ministry also said it appeared to be a ballistic missile.
Japanese public broadcaster NHK said the projectile had come down outside ***** an's exclusive economic zone.
#sunday


6 days ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year

6 days ago
Applied Materials (NASDAQ:AMAT) primarily generates its revenue by designing, developing, manufacturing, and selling the critical fabrication equipment, specialized factory automation software, and materials engineering solutions utilized to produce integrated circuits for customers globally.
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily
While launching multiple new hardware systems to address technical production challenges in advanced memory scaling, it formalized a joint development agreement for augmented reality optics and reported a 34% operating margin for the quarter ended July 26, 2026.
Intel (NASDAQ:INTC) primarily generates its revenue by designing, developing, and manufacturing commercial central processing units, discrete graphics processors, and edge computing components, alongside operating its independent wafer fabrication and advanced packaging services.
It finalized a large-scale public common stock offering and confirmed pending organizational workforce reductions within its data center operations, while reporting a 12% operating margin for the quarter ended June 27, 2026.
Revenue establishes a fundamental baseline for investors seeking to measure the total incoming capital a business generates before any operating expenses, interest, or taxes are deducted. This metric reveals whether an organization is successfully attracting customers and growing its overall business volume over time.
#generates #primarily


6 days ago
Accenture plc (NYSE:ACN) investors are having a rough year, with the shares down more than 25%. Now Wall Street is divided over the company's outlook.
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo
Morgan Stanley raised its price target on Accenture to $175 from $130 on September 14. Accenture shares soared more than 6% in afternoon trading following the price target increase, even though the firm reiterated its Equal weight rating on the stock.
Meanwhile, UBS recently maintained a Buy rating on the stock with a price target of $275. The bank pointed to confidence in the company's positioning around AI and, in separate notes, its acquisition strategy. However, Wells Fargo downgraded Accenture to Equal Weight. According to Wells Fargo, macroeconomic pressures could weigh on fiscal 2027 growth expectations.
The question is whether Accenture's expanding AI capabilities and acquisitions can translate into long-term growth.
Accenture's AI fortunes are tied to enterprise deployment of the technology. The company has formed a joint business group with Google Cloud to deploy AI engineers across enterprise clients. That arrangement gives Accenture another channel through which AI adoption can create demand for consulting, implementation, and integration services.
#fargo


6 days ago
Two years of Synopsys (SNPS) earnings calls show management changing what it explains. The company used to open on problems, some outside its control and some its own. The August 2026 call is built around a joint product with Ansys, agentic AI, and a new way to charge for its design IP. Most of that switch is earned, but parts of it are still a promise.
Synopsys Once Opened Its Calls With Bad News
Management used to point to underperformance in the IP business, where expected deals did not arrive, and to challenges at a major foundry customer that were having a sizable impact. The CEO said it plainly on an earlier call: "new export restrictions disrupted design starts in China."
None of that comes up on the August 2026 call. China does not come up. The closest thing to the old worry is that design starts outside AI have stopped declining.
Synopsys Now Leads With Multiphysics Fusion And Agentic AI
#China
Synopsys Once Opened Its Calls With Bad News
Management used to point to underperformance in the IP business, where expected deals did not arrive, and to challenges at a major foundry customer that were having a sizable impact. The CEO said it plainly on an earlier call: "new export restrictions disrupted design starts in China."
None of that comes up on the August 2026 call. China does not come up. The closest thing to the old worry is that design starts outside AI have stopped declining.
Synopsys Now Leads With Multiphysics Fusion And Agentic AI
#China

7 days ago
On September 9, 2026, Reuters reported that U.S. Transportation Secretary Sean Duffy sent a letter to Ford Motor Company (NYSE:F) CEO Jim Farley criticizing the automaker's business relationships with Chinese battery maker CATL and Chinese automakers Geely and BYD as raising "profound concern."
It specifically flagged Ford's licensed CATL battery technology at its Marshall, Michigan plant, its joint venture with Geely in Spain, and its decision not to move Lincoln Nautilus production out of China until 2030. Ford responded that Duffy's letter was "a wrongheaded attempt to capture headlines," noting that it owns the Marshall plant, controls its operations, and employs the workforce there, unlike companies that simply import Chinese-made batteries.
Ford Motor Company (NYSE:F) can argue that its CATL partnership still solidifies U.S. battery manufacturing rather than becoming more dependent on Chinese imports. Ford owns and operates its Marshall, Michigan battery plant. It allows the company to manufacture batteries domestically while licensing CATL technology. That structure could help Ford expand its U.S. EV production capacity and reduce the need to import finished Chinese battery packs.
Ford's improving financial performance gives the firm more flexibility to manage the political pressure. The automaker raised its full-year adjusted EBIT guidance to $10 billion-$11 billion after second-quarter results exceeded expectations, with record Bronco sales and a stronger product mix supporting the improvement. Stronger operating earnings could give Ford more resources to adjust its battery strategy if policymakers impose more restrictions on Chinese technology.
The company's existing U.S. manufacturing footprint could become a competitive advantage if Washington tightens restrictions on Chinese automotive technology. Ford has already invested in domestic battery production instead of relying entirely on imported battery packs. Model e losses have narrowed for three consecutive quarters. If policymakers force automakers to cut Chinese supply-chain reliance, Ford can use its existing U.S. factories to adapt faster than rivals that depend heavily on Chinese parts.
#ford #catl #motor
It specifically flagged Ford's licensed CATL battery technology at its Marshall, Michigan plant, its joint venture with Geely in Spain, and its decision not to move Lincoln Nautilus production out of China until 2030. Ford responded that Duffy's letter was "a wrongheaded attempt to capture headlines," noting that it owns the Marshall plant, controls its operations, and employs the workforce there, unlike companies that simply import Chinese-made batteries.
Ford Motor Company (NYSE:F) can argue that its CATL partnership still solidifies U.S. battery manufacturing rather than becoming more dependent on Chinese imports. Ford owns and operates its Marshall, Michigan battery plant. It allows the company to manufacture batteries domestically while licensing CATL technology. That structure could help Ford expand its U.S. EV production capacity and reduce the need to import finished Chinese battery packs.
Ford's improving financial performance gives the firm more flexibility to manage the political pressure. The automaker raised its full-year adjusted EBIT guidance to $10 billion-$11 billion after second-quarter results exceeded expectations, with record Bronco sales and a stronger product mix supporting the improvement. Stronger operating earnings could give Ford more resources to adjust its battery strategy if policymakers impose more restrictions on Chinese technology.
The company's existing U.S. manufacturing footprint could become a competitive advantage if Washington tightens restrictions on Chinese automotive technology. Ford has already invested in domestic battery production instead of relying entirely on imported battery packs. Model e losses have narrowed for three consecutive quarters. If policymakers force automakers to cut Chinese supply-chain reliance, Ford can use its existing U.S. factories to adapt faster than rivals that depend heavily on Chinese parts.
#ford #catl #motor

7 days ago
Intel (NASDAQ:INTC), the leading chip manufacturer, closed at $108.80, up 7.67%. Shares rose after news reports yesterday of a possible tie-up with SK Hynix (NASDAQ:SKHY). They continued to rise today, even though the South Korean firm issued a statement saying that nothing has been finalized.
Trading volume reached 147.2 million shares, coming in about 35% above its three-month average of 109.0 million shares.
The S&P 500 closed at 7,638, up 1.14%, while the Nasdaq Composite finished at 26,418, up 1.69%. Among semiconductors, Advanced Micro Devices closed at $545.09, up 6.36%, and Qualcomm closed at $188.71, up 2.09%, as chip-sector strength and memory-share momentum lifted the group.
Chip stocks rallied today after a rough week in which interest rate hikes and tech leaders' calls for a slowdown in artificial intelligence (AI) development weighed on the sector. Intel got an extra boost from a deal that may not even materialize: Even a whisper that SK Hynix might, possibly, maybe lease part of its Ohio complex or enter into a joint venture proved tantalizing to investors.
The difficulty with these types of speculative price jumps is that they often aren't sustainable. SK Hynix saying it is "exploring various options" is a long way from signing a deal. More concrete news? Barclays upgraded the stock from "Underperform" to "Overweight." Ultimately, Intel is well-placed to benefit from growing AI demand, but finding a client for its foundry business -- whether or not that's SK Hynix -- would represent a significant win.
#hynix #chip #saying
Trading volume reached 147.2 million shares, coming in about 35% above its three-month average of 109.0 million shares.
The S&P 500 closed at 7,638, up 1.14%, while the Nasdaq Composite finished at 26,418, up 1.69%. Among semiconductors, Advanced Micro Devices closed at $545.09, up 6.36%, and Qualcomm closed at $188.71, up 2.09%, as chip-sector strength and memory-share momentum lifted the group.
Chip stocks rallied today after a rough week in which interest rate hikes and tech leaders' calls for a slowdown in artificial intelligence (AI) development weighed on the sector. Intel got an extra boost from a deal that may not even materialize: Even a whisper that SK Hynix might, possibly, maybe lease part of its Ohio complex or enter into a joint venture proved tantalizing to investors.
The difficulty with these types of speculative price jumps is that they often aren't sustainable. SK Hynix saying it is "exploring various options" is a long way from signing a deal. More concrete news? Barclays upgraded the stock from "Underperform" to "Overweight." Ultimately, Intel is well-placed to benefit from growing AI demand, but finding a client for its foundry business -- whether or not that's SK Hynix -- would represent a significant win.
#hynix #chip #saying


7 days ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Thursday's trading session was a good one for Intel shareholders. The chipmaker's stock closed up about 8%, a day after a Reuters report that the company held exploratory talks about a deal with SK Hynix to produce memory chips in the U.S.
The deal could see SK Hynix lease part of Intel's new Ohio mega-campus, though neither company has confirmed. Another scenario, per Reuters, could be a joint venture between the two firms and cloud computing companies who need the firehose of memory.
Nasdaq-listed SK Hynix shares closed up nearly 5%.
One stock. Nvidia-level potential. 30M+ investors trust Moby to find it first. Get the pick. Tap here.
#Stock #NVIDIA #reuters #here
Thursday's trading session was a good one for Intel shareholders. The chipmaker's stock closed up about 8%, a day after a Reuters report that the company held exploratory talks about a deal with SK Hynix to produce memory chips in the U.S.
The deal could see SK Hynix lease part of Intel's new Ohio mega-campus, though neither company has confirmed. Another scenario, per Reuters, could be a joint venture between the two firms and cloud computing companies who need the firehose of memory.
Nasdaq-listed SK Hynix shares closed up nearly 5%.
One stock. Nvidia-level potential. 30M+ investors trust Moby to find it first. Get the pick. Tap here.
#Stock #NVIDIA #reuters #here

7 days ago
Digital Realty Trust, Inc. (NYSE:DLR) announced a joint venture with Rönesans Infrastructure on September 14 to develop and operate data centers in Türkiye. The first Ankara campus is designed for more than 22 megawatts of IT capacity. Land, power and permits are secured, early construction has begun, and the first facility is scheduled for completion in 2028.
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture


8 days ago
The casual Mexican restaurant sector has faced a challenging year in 2026, as dining chains have closed underperforming locations, filed for Chapter 11 bankruptcy protection to reorganize their businesses, and in at least one case, filed for Chapter 7 liquidation to shut down all operations.
Once popular Mexican chain On the Border ceased operations in 2026, after closing all of its locations before its operating company, OTB Hospitality, filed for Chapter 7 liquidation on June 19, 2026, the company shared in a press release.
Another chain facing financial distress is Session Taco, a St. Louis-based casual Mexican dining chain, which closed one of its restaurant locations for the second time in seven months. The chain has not filed for bankruptcy.
The Mexican chain, originally branded Mission Taco Joint until a 2023 name change, closed its Sobremesa restaurant in St. Charles, Mo., on Sept. 13 after only three months of operation, according to its Facebook page.
The St. Charles location was previously branded as Session Taco until the company closed the restaurant on Feb. 13 to redesign and rebrand the restaurant as Sobremesa before reopening in June 2026.
#mexican #locations
Once popular Mexican chain On the Border ceased operations in 2026, after closing all of its locations before its operating company, OTB Hospitality, filed for Chapter 7 liquidation on June 19, 2026, the company shared in a press release.
Another chain facing financial distress is Session Taco, a St. Louis-based casual Mexican dining chain, which closed one of its restaurant locations for the second time in seven months. The chain has not filed for bankruptcy.
The Mexican chain, originally branded Mission Taco Joint until a 2023 name change, closed its Sobremesa restaurant in St. Charles, Mo., on Sept. 13 after only three months of operation, according to its Facebook page.
The St. Charles location was previously branded as Session Taco until the company closed the restaurant on Feb. 13 to redesign and rebrand the restaurant as Sobremesa before reopening in June 2026.
#mexican #locations


8 days ago
With a market cap of $18.8 billion, Zimmer Biomet Holdings, Inc. (ZBH) is a global medical technology company specializing in musculoskeletal healthcare solutions. The company designs, manufactures, and markets products ranging from orthopedic reconstructive implants to sports medicine, spine, craniomaxillofacial, and thoracic solutions.
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Zimmer Biomet fits this criterion perfectly. Its innovations support surgeons and healthcare providers worldwide in treating disorders and injuries of bones, joints, and soft tissues.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#Stock
Companies worth more than $10 billion are generally labeled as "large-cap" stocks and Zimmer Biomet fits this criterion perfectly. Its innovations support surgeons and healthcare providers worldwide in treating disorders and injuries of bones, joints, and soft tissues.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Why It's Time to Load Up on Nvidia Stock
The Case for Selling CrowdStrike Stock
#Stock


8 days ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#still


8 days ago
Uber Technologies (NYSE:UBER) and Costco Wholesale (NASDAQ:COST) have expanded their US delivery partnership to 47 states, up from 17, making nearly 600 Costco locations available through the Uber Eats platform.
The companies said the expanded service allows Costco members to place orders for on-demand or scheduled delivery through the Uber Eats app.
Customers can purchase fresh produce, bulk groceries and household products, link their Costco membership during checkout and track their deliveries in real time.
The expansion increases the geographic reach of Costco's delivery service through Uber Eats, giving members access to products from participating warehouses.
Nearly 600 Costco locations are now available on the platform, according to the companies' joint statement.
#costco #expanded #available #platform
The companies said the expanded service allows Costco members to place orders for on-demand or scheduled delivery through the Uber Eats app.
Customers can purchase fresh produce, bulk groceries and household products, link their Costco membership during checkout and track their deliveries in real time.
The expansion increases the geographic reach of Costco's delivery service through Uber Eats, giving members access to products from participating warehouses.
Nearly 600 Costco locations are now available on the platform, according to the companies' joint statement.
#costco #expanded #available #platform

8 days ago
A fresh wave of nuclear stock listings is sweeping Wall Street as the explosive growth of data centers puts mounting pressure on electricity grids and reignites investor appetite for nuclear power. Joining this initial public offering (IPO) frenzy is nuclear stock Holtec Nuclear, which is gearing up for its public debut this month. The company plans to offer 50 million shares of Class A common stock at a price range of $15 to $18 per share, potentially raising up to $900 million and valuing the company at as much as $10.2 billion.
Holtec plans to list on the Nasdaq Global Select Market and Nasdaq Texas under the ticker symbol "HNUC" on Sept. 18. The underwriters also have a 30-day option to purchase up to an additional 7.5 million shares. Leading the offering as joint lead book-running managers are J.P. Morgan, Guggenheim Securities, Goldman Sachs, Citigroup, and BofA Securities, while Morgan Stanley, Cantor, BMO Capital Markets, and Oppenheimer & Co. round out the group of joint book-running managers.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#shares #securities
Holtec plans to list on the Nasdaq Global Select Market and Nasdaq Texas under the ticker symbol "HNUC" on Sept. 18. The underwriters also have a 30-day option to purchase up to an additional 7.5 million shares. Leading the offering as joint lead book-running managers are J.P. Morgan, Guggenheim Securities, Goldman Sachs, Citigroup, and BofA Securities, while Morgan Stanley, Cantor, BMO Capital Markets, and Oppenheimer & Co. round out the group of joint book-running managers.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#shares #securities

9 days ago
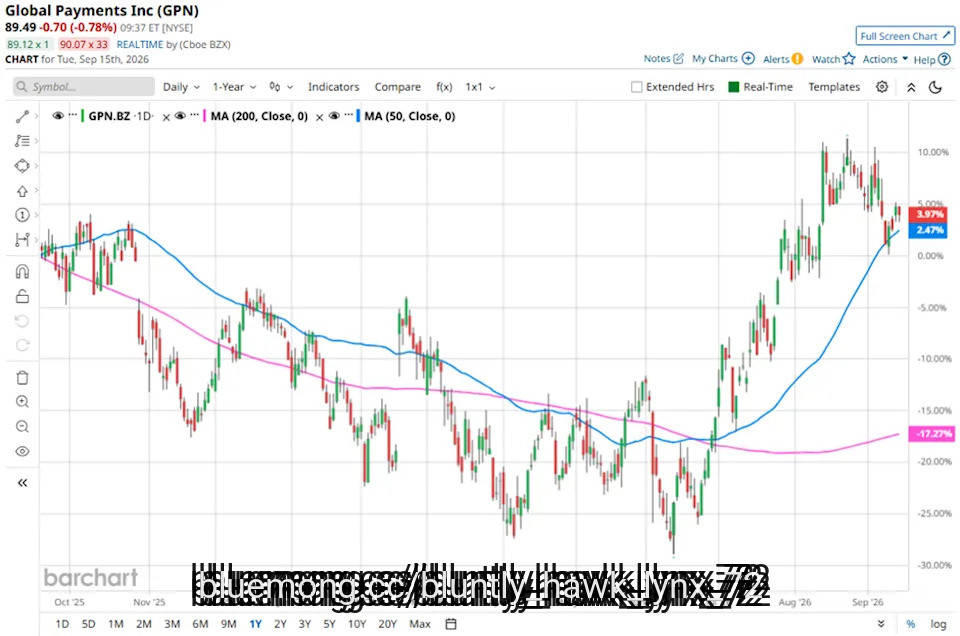
With a market cap of $23.9 billion, Global Payments Inc. (GPN) is a leading provider of payment technology and software solutions worldwide. The company operates primarily through its Merchant Solutions and Issuer Solutions segments, offering businesses and financial institutions secure, seamless, and innovative payment processing and software services.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #billion #payment #merchant

9 days ago
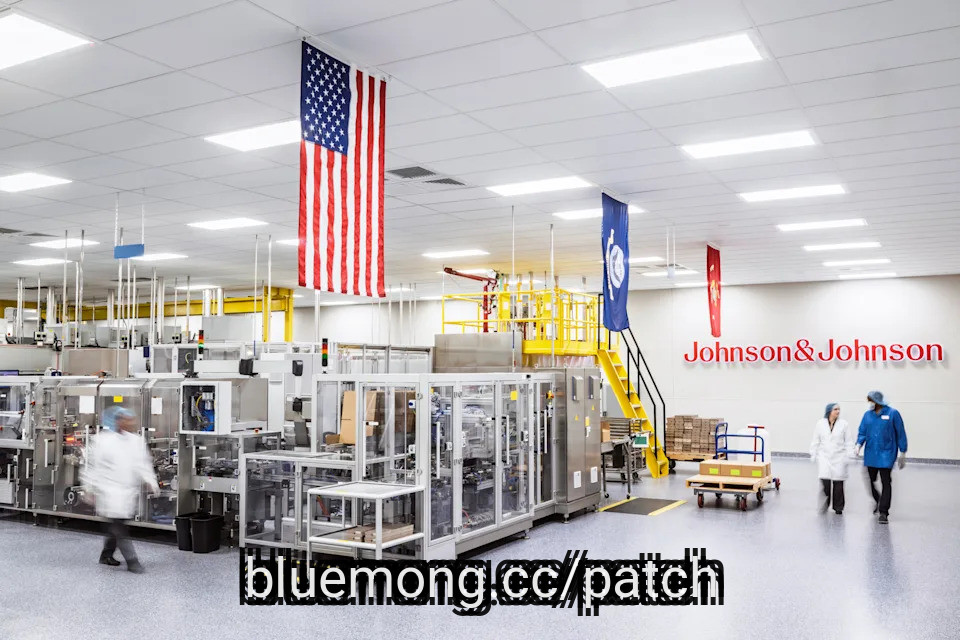
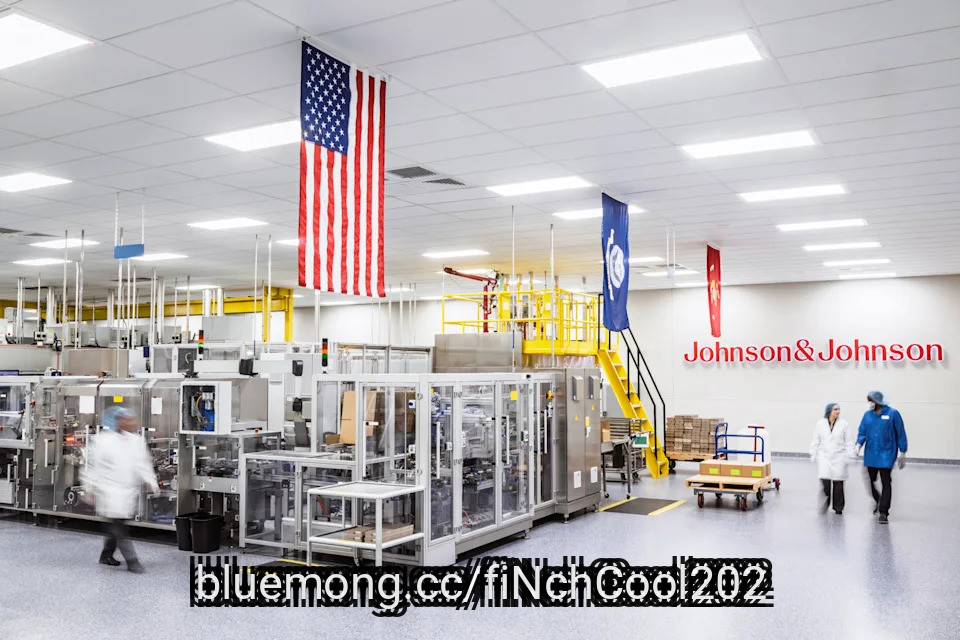
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy

9 days ago
Retiring at 62 and living off a 401(k) until 70 keeps a couple in the 12% tax bracket, with an effective federal rate near 8% on roughly $133,000 in annual withdrawals.
Delaying Social Security to 70 grows each spouse's benefit by 8% per year, producing roughly $6,200 combined monthly in guaranteed, inflation-adjusted income plus a maximized survivor benefit.
Medicare's two-year income lookback means couples must keep joint MAGI below $218,000 or face IRMAA surcharges that add over $160 per month in Part B premiums.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 62-year-old couple with $1.8 million in a traditional 401(k) and matching $3,100 monthly Social Security benefits available at full retirement age is looking at one of the most tax-efficient windows in the entire retirement code. The plan: retire now, live off the 401(k) for eight years, and switch to two delayed Social Security checks totaling roughly $6,200 a month at 70. It sounds aggressive. The math says it is close to optimal.
#security #year #benefit
Delaying Social Security to 70 grows each spouse's benefit by 8% per year, producing roughly $6,200 combined monthly in guaranteed, inflation-adjusted income plus a maximized survivor benefit.
Medicare's two-year income lookback means couples must keep joint MAGI below $218,000 or face IRMAA surcharges that add over $160 per month in Part B premiums.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
A 62-year-old couple with $1.8 million in a traditional 401(k) and matching $3,100 monthly Social Security benefits available at full retirement age is looking at one of the most tax-efficient windows in the entire retirement code. The plan: retire now, live off the 401(k) for eight years, and switch to two delayed Social Security checks totaling roughly $6,200 a month at 70. It sounds aggressive. The math says it is close to optimal.
#security #year #benefit


9 days ago
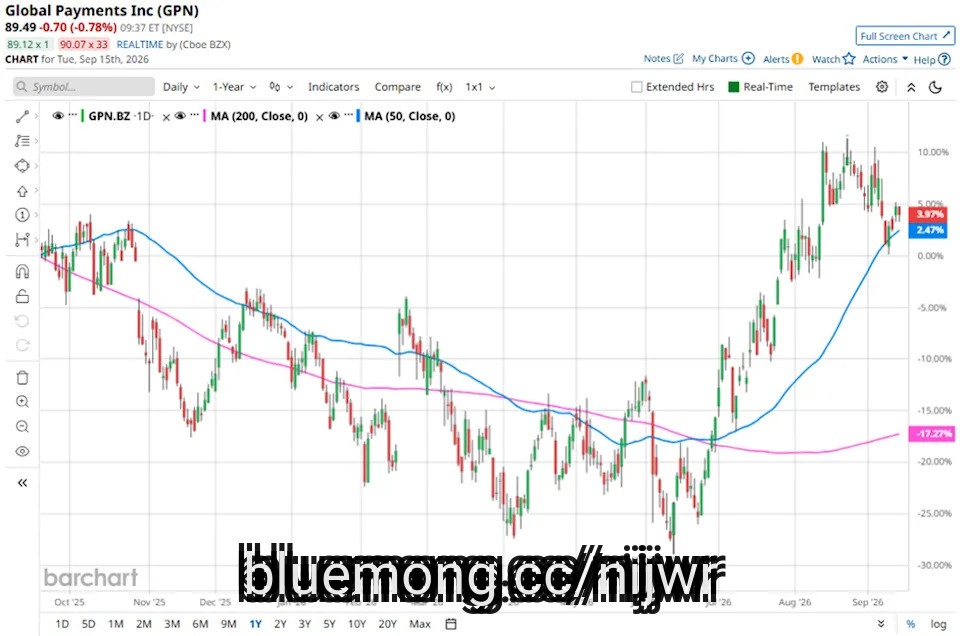
With a market cap of $23.9 billion, Global Payments Inc. (GPN) is a leading provider of payment technology and software solutions worldwide. The company operates primarily through its Merchant Solutions and Issuer Solutions segments, offering businesses and financial institutions secure, seamless, and innovative payment processing and software services.
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #Stock #financial
Companies valued over $10 billion are generally described as "large-cap" stocks, and Global Payments fits right into that category. With a global presence across the Americas, Europe, and Asia-Pacific, Global Payments continues to expand through strategic acquisitions, joint ventures, and advanced financial technology solutions.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#payments #Stock #financial



9 days ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
9 days ago
Realty Income (NYSE:O) aims to be the real estate partner to the world's leading companies. It has really leaned into forming new capital partnerships with leading institutional investors over the past year. It just formed a new joint venture (JV) with KKR, adding to prior strategic partnership deals with Apollo and GIC.
These partnerships might have income investors wondering if they're a sign of financial strength or weakness. Here's how they align with Realty Income's strategic plan to continue growing its high-yielding monthly dividend (currently 5.5%).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Realty Income is a real estate investment trust (REIT) with a globally diversified portfolio of net lease real estate. It launched an investment management platform (Realty Income Investment Management or RIM) last year to allow institutional investors to invest alongside it through funds, JVs, and separately managed mandates. This strategy has four key advantages: accelerating its adjusted funds from operations (AFFO) per share growth through capital-light revenue, expanding its addressable market, reducing its reliance on public equity, and providing its partners with distinct, non-overlapping vehicles.
#income #estate #continue
These partnerships might have income investors wondering if they're a sign of financial strength or weakness. Here's how they align with Realty Income's strategic plan to continue growing its high-yielding monthly dividend (currently 5.5%).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: Getty Images.
Realty Income is a real estate investment trust (REIT) with a globally diversified portfolio of net lease real estate. It launched an investment management platform (Realty Income Investment Management or RIM) last year to allow institutional investors to invest alongside it through funds, JVs, and separately managed mandates. This strategy has four key advantages: accelerating its adjusted funds from operations (AFFO) per share growth through capital-light revenue, expanding its addressable market, reducing its reliance on public equity, and providing its partners with distinct, non-overlapping vehicles.
#income #estate #continue


10 days ago
On September 15, CareTrust REIT (NYSE:CTRE) announced it had closed on a $400 million skilled nursing portfolio in the Southwest, effective September 1, and unveiled a reloaded $600 million investment pipeline behind it. The deal covers 2,622 licensed beds triple net leased back to the existing operator, sourced off-market and structured through a joint venture that put roughly $380 million of CareTrust's own capital to work. It is the latest entry in a buying spree that has now pushed the company's 2026 investment total past $1.9 billion.
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed
The new portfolio is expected to generate a stabilized yield of about 8.6%, in line with the 8.7% blended yield CareTrust has posted across two dozen deals closed so far in 2026. That consistency matters more than any single transaction. The company has now closed roughly $710 million in investments in the third quarter alone, including a small UK care home purchase in mid-August, on top of the $899.6 million it closed in the second quarter at an 8.9% yield.
Management says the $600 million pipeline of near-term, actionable deals, about half of it aimed at the senior housing operating portfolio, does not even include a set of larger transactions still being pursued, so the deal flow may not be finished. The balance sheet backs up that ambition. CareTrust ended the second quarter, on June 30, 2026, with net debt to annualized normalized EBITDA of just 1.01x, and as of the September announcement it still had $725 million available under its revolver plus $612 million of remaining ATM capacity. That combination let the company raise its full year 2026 guidance on August 6 to normalized FFO of $2.03 to $2.06 per share, an increase of 16.2% at the midpoint over 2025, even before this latest acquisition was on the books.
This growth has come with a real cost to existing shareholders. Diluted weighted average shares outstanding rose from about 192.9 million in the second quarter of 2025 to 234.2 million a year later, as CareTrust leaned on forward equity offerings and its ATM program to fund the buying spree. The company still had $439 million of expected net proceeds sitting in unsettled forward equity contracts as of September 15, meaning more shares are still coming.
The second quarter also carried a $4.7 million provision for loan losses, a line that did not appear in the prior year period and is worth watching as the loan and financing receivable book grows alongside the property portfolio. Interest expense rose to $15.3 million in the quarter from $13.0 million a year earlier, and 2026 guidance leans on rent escalators of just 2.5% a year, a modest built-in growth rate once the acquisition pace eventually slows. The company's own risk disclosures flag reliance on tenants to keep meeting their lease obligations, along with exposure to healthcare reform, staffing requirements, and currency swings tied to its UK operations.
#closed


10 days ago
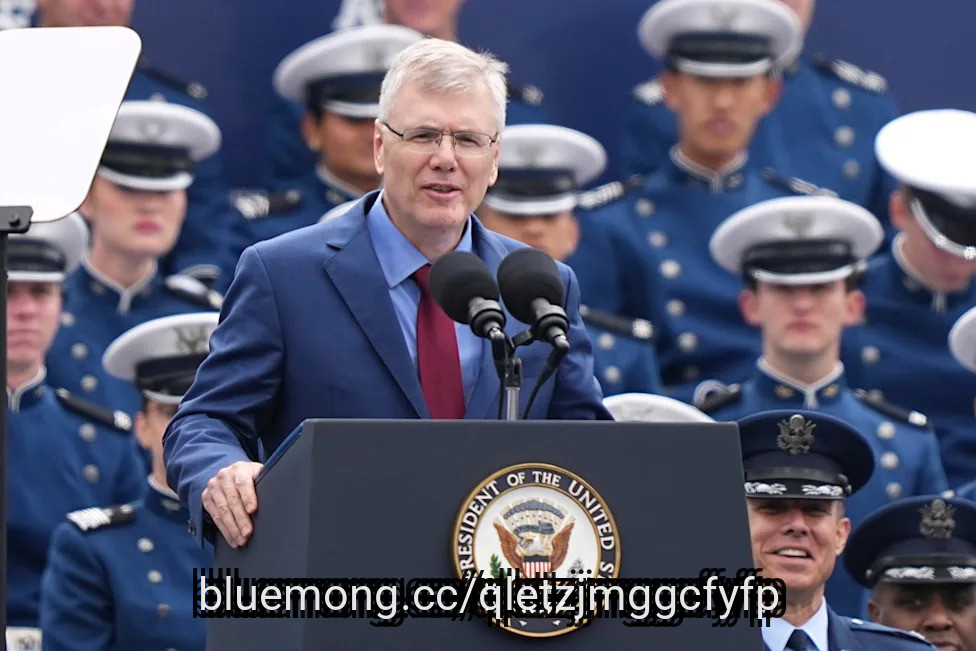
WASHINGTON (AP) — The United States has confirmed for the first time that it has deployed weapons in ******* e, a remarkable revelation after previous warnings about countries such as Russia possibly weaponizing a global frontier long agreed in treaties to be used for only peaceful purposes.
Air Force Secretary Troy Meink said Monday that the U.S. has fielded "on-orbit ******* e control weapons capable of defending the Joint Force against hostile adversary action."
Meink did not detail what the weapons were, how they work or if they were targeting other objects in ******* e or on Earth. The U.S. had warned two years ago that Russia was developing a new ******* e-based, anti-satellite weapon, though the White House said the danger wasn't imminent at the time.
But reports of the anti-satellite weapon reflected longstanding worries about ******* e threats from Russia and China, given that much U.S. infrastructure is dependent on satellite communications. The U.S. has also previously demonstrated its own abilities to shoot down satellites from Earth.
In his remarks to the Air and ******* e Forces ******* ociation's Air, ******* e & Cyber Conference, Meink also said the Air Force was adding more autonomous systems to its capabilities and predicted the service would look "radically different" by 2032. For example, he foresaw one-way attack drones replacing artillery as the "primary killer."
#space #earth
Air Force Secretary Troy Meink said Monday that the U.S. has fielded "on-orbit ******* e control weapons capable of defending the Joint Force against hostile adversary action."
Meink did not detail what the weapons were, how they work or if they were targeting other objects in ******* e or on Earth. The U.S. had warned two years ago that Russia was developing a new ******* e-based, anti-satellite weapon, though the White House said the danger wasn't imminent at the time.
But reports of the anti-satellite weapon reflected longstanding worries about ******* e threats from Russia and China, given that much U.S. infrastructure is dependent on satellite communications. The U.S. has also previously demonstrated its own abilities to shoot down satellites from Earth.
In his remarks to the Air and ******* e Forces ******* ociation's Air, ******* e & Cyber Conference, Meink also said the Air Force was adding more autonomous systems to its capabilities and predicted the service would look "radically different" by 2032. For example, he foresaw one-way attack drones replacing artillery as the "primary killer."
#space #earth

11 days ago
The Seattle Seahawks issued a cryptic but encouraging update regarding the health of injured quarterback Sam Darnold Monday.
While the precise nature of his injury remains ambiguous, the update points to Darnold returning to the field sooner than later.
Per the Seahawks, Darnold sustained a "very unique soft-tissue." The injury is actually to a glute muscle rather than his hip and is considered "short-term."
Here's the full statement released by the Seahawks Monday evening:
"Darnold, who was injured on a sack that ended Seattle's first drive, has a very unique soft-tissue injury, but the hip joint is unaffected by the injury. While there is no firm timeline on Darnold's return, it is considered a short-term injury."
#unique #soft #tissue
While the precise nature of his injury remains ambiguous, the update points to Darnold returning to the field sooner than later.
Per the Seahawks, Darnold sustained a "very unique soft-tissue." The injury is actually to a glute muscle rather than his hip and is considered "short-term."
Here's the full statement released by the Seahawks Monday evening:
"Darnold, who was injured on a sack that ended Seattle's first drive, has a very unique soft-tissue injury, but the hip joint is unaffected by the injury. While there is no firm timeline on Darnold's return, it is considered a short-term injury."
#unique #soft #tissue

11 days ago
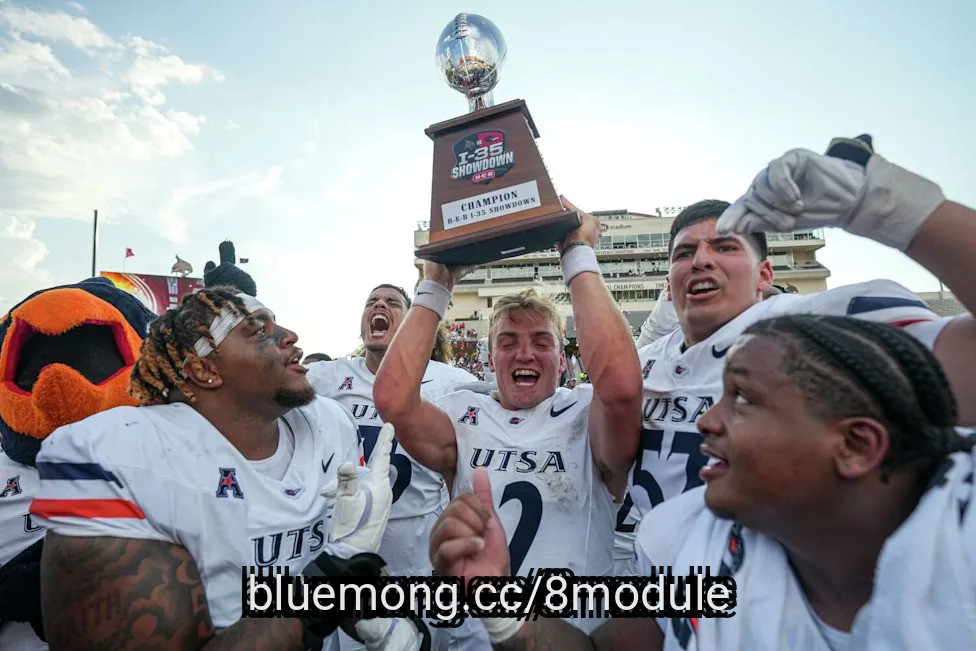
A Southern California high school has suspended its varsity football team, and will forfeit its next matchup, for unsportsmanlike actions in a heated rivalry game that also saw the school's mascot flipping off the opposing crowd.
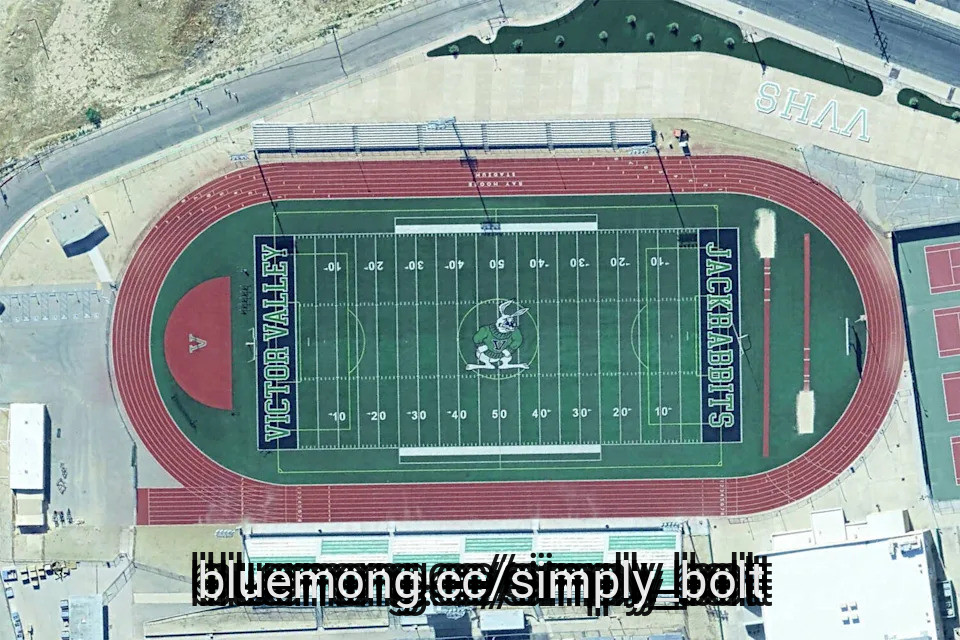
Victor Valley High School defeated Apple Valley 20-7 on Friday in the 56th edition of the annual rivalry game known as the Bell Game. The winning side not only gets bragging rights but also possession of the rivalry trophy, a large bell that is currently painted green to match the school's colors. However, Victor Valley's celebrations, and the antics of their jackrabbit mascot, crossed a line, according to district officials. Victor Valley Union High School District Superintendent Carl Coles and Victor Valley Principal Darius Robinson released joint a statement announcing the team would be suspended as a result.
"There is a clear line between passionate competition and unacceptable conduct," the statement read. "That line was crossed at the Bell Game on Friday, September 11. Members of the Victor Valley High School football team behaved in an unsportsmanlike manner toward the opposing team and its fans, including offensive gestures and language."
With the suspension, Victor Valley will forfeit its upcoming game against Brea Olinda.
While the district's letter did not specify the actions and gestures made that warranted this punishment - the letter also didn't identify offending players - videos circulating on social media seem to provide some insight into what led to the decision. For one thing, the Jackrabbits mascot gave the middle finger to the Sun Devil crowd early on in the game as it walked down the track surrounding the field on Apple Valley's side of the stadium.
#high #bell
Victor Valley High School defeated Apple Valley 20-7 on Friday in the 56th edition of the annual rivalry game known as the Bell Game. The winning side not only gets bragging rights but also possession of the rivalry trophy, a large bell that is currently painted green to match the school's colors. However, Victor Valley's celebrations, and the antics of their jackrabbit mascot, crossed a line, according to district officials. Victor Valley Union High School District Superintendent Carl Coles and Victor Valley Principal Darius Robinson released joint a statement announcing the team would be suspended as a result.
"There is a clear line between passionate competition and unacceptable conduct," the statement read. "That line was crossed at the Bell Game on Friday, September 11. Members of the Victor Valley High School football team behaved in an unsportsmanlike manner toward the opposing team and its fans, including offensive gestures and language."
With the suspension, Victor Valley will forfeit its upcoming game against Brea Olinda.
While the district's letter did not specify the actions and gestures made that warranted this punishment - the letter also didn't identify offending players - videos circulating on social media seem to provide some insight into what led to the decision. For one thing, the Jackrabbits mascot gave the middle finger to the Sun Devil crowd early on in the game as it walked down the track surrounding the field on Apple Valley's side of the stadium.
#high #bell

12 days ago
Chargers news: NFL ***** yst tries making sense of LA's 'horrific' Cardinals loss appeared first on ClutchPoints. Add ClutchPoints as a Preferred Source by clicking here.
The Los Angeles Chargers suffered undoubtedly the most shocking loss of the Week 1 NFL slate by dropping a home game to the (seemingly) lowly Arizona Cardinals. The Chargers entered this game as the biggest favorites of any team this weekend but ended up losing by a score of 26-14, with Mike McDaniel's new-look offense never getting off the ground.
On Monday, NFL ***** yst Kevin Clark of ESPN stopped by The Dan Patrick Show and tried to explain what went wrong with Los Angeles.
"This is as bad as it gets. You want to talk about offseason hype, the Chargers, it's every year… You can't lose this game. You can't have Jim Harbaugh saying that Justin Herbert's going to go down as the best quarterback in history and then lose to the Arizona Cardinals… this was horrific, and it just seemed disjointed. It seemed like not a Jim Harbaugh team," he said, per Dan Patrick Show on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#chargers #clutchpoints #arizona #analyst
The Los Angeles Chargers suffered undoubtedly the most shocking loss of the Week 1 NFL slate by dropping a home game to the (seemingly) lowly Arizona Cardinals. The Chargers entered this game as the biggest favorites of any team this weekend but ended up losing by a score of 26-14, with Mike McDaniel's new-look offense never getting off the ground.
On Monday, NFL ***** yst Kevin Clark of ESPN stopped by The Dan Patrick Show and tried to explain what went wrong with Los Angeles.
"This is as bad as it gets. You want to talk about offseason hype, the Chargers, it's every year… You can't lose this game. You can't have Jim Harbaugh saying that Justin Herbert's going to go down as the best quarterback in history and then lose to the Arizona Cardinals… this was horrific, and it just seemed disjointed. It seemed like not a Jim Harbaugh team," he said, per Dan Patrick Show on X, formerly Twitter.
Watch sports LIVE with fuboTV (free trial)
#chargers #clutchpoints #arizona #analyst


12 days ago
After briefly exiting Sunday's win over the Cleveland Browns, Jacksonville Jaguars' head coach Liam Coen fully expects wide receiver Brian Thomas Jr. to be available in Week 2 against Denver -- although he may be limited during the week of upcoming practices.
"I fully imagine him being able to play this game," Coen said on Monday. "No issues, just might not be able to get hit throughout the week or something."
Thomas Jr. left the Jaguars' Week 1 win in the first half with a shoulder injury. He was initially questionable to return, but did go back into the game.
Thomas Jr. finished the game with three receptions for 40 yards.
He also sustained a shoulder injury in the Jaguars' first joint practice with the Tampa Bay Buccaneers. Whether or not that injury and the current one are related has not been reported.
#fully #able #shoulder
"I fully imagine him being able to play this game," Coen said on Monday. "No issues, just might not be able to get hit throughout the week or something."
Thomas Jr. left the Jaguars' Week 1 win in the first half with a shoulder injury. He was initially questionable to return, but did go back into the game.
Thomas Jr. finished the game with three receptions for 40 yards.
He also sustained a shoulder injury in the Jaguars' first joint practice with the Tampa Bay Buccaneers. Whether or not that injury and the current one are related has not been reported.
#fully #able #shoulder

12 days ago
Alan Ritchson and his wife of 19 years, Catherine, announced their separation on Instagram Saturday, Sept. 12
Nine months earlier, the Reacher star filed for divorce from Catherine in December 2025, according to court records viewed by PEOPLE
In their joint statement, the exes said their three sons "will always be the center of our world"
Alan Ritchson quietly filed for divorce nine months before publicly announcing that he and his wife Catherine broke up.
Alan, 43, and Catherine, 37, shared the news of their separation in a joint Instagram post on Saturday, Sept. 12. "After twenty years together, Cat and I have decided to end our marriage and continue alongside one another in a different way," they wrote in a lengthy statement.
#catherine #saturday #years
Nine months earlier, the Reacher star filed for divorce from Catherine in December 2025, according to court records viewed by PEOPLE
In their joint statement, the exes said their three sons "will always be the center of our world"
Alan Ritchson quietly filed for divorce nine months before publicly announcing that he and his wife Catherine broke up.
Alan, 43, and Catherine, 37, shared the news of their separation in a joint Instagram post on Saturday, Sept. 12. "After twenty years together, Cat and I have decided to end our marriage and continue alongside one another in a different way," they wrote in a lengthy statement.
#catherine #saturday #years



12 days ago
Dow Inc. (NYSE:DOW) is reportedly considering selling its 35% stake in Sadara Chemical, its $20 billion chemicals joint venture with Saudi Aramco, as the company continues to reshape its portfolio amid a prolonged downturn in the global chemicals industry. No final decision has been made, and Aramco or another strategic or financial investor could potentially acquire Dow's stake.
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals
The potential exit comes as Sadara has become a significant financial burden for Dow. As of June 30, Dow Inc. (NYSE:DOW) had a negative investment balance of $793 million in Sadara and had suspended recognition of its share of the venture's equity losses in the first quarter. Dow has also been exposed to Sadara's financing obligations and previously disclosed that the venture had drawn on a credit facility.
At the same time, Sadara remains a major industrial ****** et, operating a complex in Jubail with more than 3 million metric tons of annual chemicals and plastics capacity. Its operations were disrupted earlier this year by the Middle East conflict, adding transportation, supply-chain, and operating pressures to an industry already dealing with weak demand and global oversupply.
The strongest argument for Dow Inc. (NYSE:DOW) is that exiting Sadara could remove a persistent drag on cash flow and allow management to redirect capital toward businesses with better returns. Dow's exposure to Sadara is no longer simply an investment in a large Saudi chemicals complex; the company has accumulated a negative investment balance and financial obligations ****** ociated with the venture. A sale could therefore reduce Dow's exposure to future funding requirements and limit the amount of capital that could otherwise have to be committed to the partnership.
That would be particularly valuable because Dow is already trying to improve its cash generation. Management has said its objective is to reach free-cash-flow breakeven while pursuing significant cost reductions. In March, CEO Jim Fitterling said Dow's goal was to avoid putting additional cash into Sadara during 2026, while describing the venture as having low operating cash costs but more challenging fixed costs and financing obligations.
#chemicals


