10 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition

10 days ago
On September 9, 2026, Chewy, Inc. (NYSE:CHWY) reported fiscal second-quarter net sales of $3.33 billion, up 7.3% year over year, and adjusted earnings per share of $0.36, nearly double the roughly $0.18 ******* ysts had expected, prompting the company to raise its full-year revenue and profitability outlook. CEO Sumit Singh said the broader pet market did not meaningfully recover during the quarter but also did not deteriorate further, with Chewy continuing to outperform the category by two to three times through share gains across its established and newer businesses.
Chewy, Inc. (NYSE:CHWY)'s recurring revenue base is solid. It gives the company greater visibility into future sales. Autoship sales jumped by 9.3% year over year to $2.82 billion and represented 84.6% of total net sales. The growing contribution from subscription-based purchases gives Chewy a more predictable revenue stream and reduces its exposure to fluctuations in discretionary pet spending.
Chewy is also building growth engines beyond its core retail business. Chewy Health, which includes veterinary care and pharmacy services, delivered triple-digit revenue growth. Specialty categories such as equine and exotics recorded a seventh consecutive quarter of mid-double-digit growth. These businesses give Chewy additional opportunities to increase customer spending and diversify its sources of revenue as the overall pet market matures.
Chewy is combining customer growth with stronger profitability and shareholder returns. The firm added 208,000 net active customers during the quarter. It takes its customer base to 21.7 million while returning $200 million to shareholders through share repurchases. Management also noted structural SG&A leverage, automation, and AI-driven cost reductions as contributors to margin expansion. It shows that Chewy can improve earnings while investing in customer acquisition and growth.
Part of Chewy, Inc. (NYSE:CHWY)'s profitability improvement came from benefits that may not recur. CFO Chris Deppe said the quarter's profitability upside included about $10 million from timing benefits and more than $5 million from discrete benefits. Those items boosted the latest results but do not provide a recurring earnings contribution. It means investors may need to lower their expectations for the pace of margin expansion in future quarters.
#customer
10 days ago
Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) announced on September 15 that it had acquired 60% of White Desert Antarctica and its new aviation travel business, Echo Charlie. Consideration comprises approximately $61 million in cash, plus approximately $6 million relating to acquired cash, subject to working-capital, cash, and indebtedness adjustments.
The purchase broadens the travel portfolio beyond expedition cruises. For investors, the test is whether additional bookings and cash generation justify the acquisition price and subsequent investment.
White Desert takes guests into Antarctica's interior, including the Geographic South Pole. Echo Charlie offers journeys aboard a restored DC-3 aircraft carrying 12 guests. These experiences add distinctive products that Lindblad Expeditions Holdings, Inc. (NASDAQ:LIND) could market to existing adventure travelers.
Cross-selling could reduce marketing costs per booking and encourage repeat travel across the portfolio. Established customer relationships provide a starting point; the financial benefit depends on generating additional profitable departures.
The company already operates a growing land-travel business. Second-quarter Land Experiences revenue increased 23% to $70.0 million, driven by additional trips and higher pricing. That provides a relevant commercial foundation for the expansion.
#additional

10 days ago
LifeMD, Inc. (NASDAQ:LFMD) announced an exclusive healthcare collaboration on September 15 that initially makes virtual-health membership benefits available to approximately 29 million eligible AT&T wireless and fiber customers across 11 states. Customers must be 18 or older, and some services have additional eligibility and state restrictions. A nationwide expansion planned for January 2027 would extend eligibility beyond 100 million customers.
The $19 monthly membership fee is waived, but customers must enroll. Visits, prescriptions, and other services remain separately payable. For LifeMD, Inc. (NASDAQ:LFMD), the opportunity is converting access to a large audience into recurring demand for paid care.
The partnership gives LifeMD, Inc. (NASDAQ:LFMD) a distribution channel through the website, mobile app and customer-benefits program of AT&T Inc. (NYSE:T). Reaching customers through an established relationship could reduce reliance on advertising and lower acquisition costs per paying patient.
Removing the membership charge also reduces the financial commitment required to try the service. Announced visit prices start at $29 for message-based care, $49 for urgent and primary care video visits, and $79 for specialty care. Customers may use insurance, Medicare, or discounted cash-pay rates for visits and prescriptions.
LifeMD, Inc. (NASDAQ:LFMD) could benefit from repeat consultations and prescription fulfillment when clinically appropriate. Primary care, chronic-condition management and other services create opportunities for continuing patient relationships. If satisfied patients return, the revenue earned over those relationships could exceed the cost of acquiring and serving them.
#Services

10 days ago
The transition toward renewable energy is creating massive opportunities for infrastructure providers. Eos Energy Enterprises (NASDAQ:EOSE) and GE Vernova (NYSE:GEV) represent two distinct ways to play this trend in 2026.
Eos focuses on specialized zinc-based batteries for long-duration energy storage. GE Vernova is a diversified giant that services a massive portion of the world's electricity grid. Comparing these two helps clarify whether you prefer a high-growth disruptor or an established power leader.
Eos Energy Enterprises produces aqueous zinc batteries designed as a safer, scalable alternative to lithium-ion. It operates primarily within the industrial stocks **** e, targeting utilities and commercial developers. Customer concentration like this adds a layer of risk to the business, as two clients accounted for approximately 70% of total revenue in 2025.
In FY 2025, revenue reached approximately $114.2 million. This represents growth of nearly 631.8% compared to the prior fiscal year. The company reported a pre-tax net loss of roughly $969.6 million, resulting in a negative net margin of approximately 849.1%.
As of its December 2025 balance sheet, the company had a debt-to-equity ratio of -1.0x. This value indicates that total liabilities exceed shareholder equity. The current ratio, which measures the ability to cover short term obligations with short term **** ets, was approximately 4.9x, while free cash flow was nearly negative $265.0 million.
#enterprises #massive #Growth
11 days ago
The CLARITY Act failed to pass votes in the Senate earlier this week, a piece of legislature that would set out guardrails and ground rules for crypto **** ets in the U.S. With the failure of passage, the Securities and Exchange Commission took matters into its own hands, passing a conditional exemption Thursday for tokenized stocks. This Innovation Exemption allows for a limited type of tokenized securities to trade on specific Tokenized Securities Venues (TSVs), giving them a 5-year runway to prove their trading chops.
Tokenization is one of the latest trends in the investing world, whereby an **** et is represented digitally on a blockchain. It's seen as the next frontier in finance, with digital trading opening up greater access both for a broader investor base as well as the potential to trade 24/7, while also offering the potential for increased efficiency. However, some argue that tokenized **** ets come with added, unique risks and that by moving investments to the blockchain you introduce greater exposure to bad actors in an as-yet unregulated **** e in the U.S. That is, until now.
The SEC exemption allows for a specific type of tokenized stocks to be traded, specifically ones that retain the investor rights of the stock they are tied to (voting and dividends for example). Only tokenized U.S. National Market System (NMS) stocks qualify that trade through U.S. venues who have established standards for who can trade, limit trading volumes to a certain percentage of the stock, and make public their trading activities as well as any affiliates on the TSV. In addition, venues must halt trading when the primary exchange halts, and leverage is not permitted. Any company that does not want tokenized shares has 30 days to object and prevent their shares from being created.
It's important to note that currently there are two main types of tokenized securities, those that are directly linked to the **** et they represent digitally and those that provide synthetic exposure. Of the two, only the direct exposure tokenized stocks qualify that meet all of the exemption's restrictions.
"The Commission is not cementing today's technology as the standard for tomorrow. Instead, it is allowing the market to evolve, monitoring its development, and using that insight to inform a nimbler and future-ready regulatory framework," SEC Chair Paul Atkins said in a statement.
#exposure #commission

11 days ago
Zipline is putting a fresh valuation on the increasingly crowded race to make drone delivery a mainstream part of American last-mile logistics networks, all while the regulatory system is still playing catch-up.
The autonomous delivery company is in talks to raise roughly $1 billion that would value the firm of roughly $20 billion, according to Bloomberg, nearly tripling the $7.6 billion valuation it established in January.
More from WWD
Ravel Raises $8.2M to Tackle Fashion's Elastane Problem
Auction Marketplace Buywander Secures $21M in Funding
#delivery

11 days ago
Choosing between a niche equipment provider and a diversified industry **** an requires balancing high growth potential against established stability. Here is how Aehr Test Systems (NASDAQ:AEHR) and KLA (NASDAQ:KLAC) compare for investors.
Aehr Test Systems focuses on specific stress-testing solutions for power semiconductors and memory, while KLA provides broad process control tools used across the entire chip-making industry. While they both operate in the same sector, their scale and risk profiles differ significantly, making them attractive to different types of portfolios.
Aehr Test Systems designs and sells specialized equipment for the testing and stabilization of semiconductor products in various forms, including wafers and singulated dies. The company focuses on the high-growth silicon carbide market for electric vehicles and high-bandwidth memory for artificial intelligence infrastructure. In its 2026 fiscal year (FY), which ended May 29, its five largest customers accounted for nearly 70% of net sales, and customer concentration like this adds a layer of risk to the business.
In FY 2026, revenue reached $50.0 million, representing a decline of 15.2% compared to the previous year. This contraction followed a period of higher operating costs, resulting in a net loss of $7.1 million for the period. The net margin, which represents the percentage of revenue remaining as profit after all expenses, was -14.3% in the latest fiscal year.
As of its May 2026 balance sheet, the debt-to-equity ratio is zero, indicating that the company has no debt relative to its shareholder equity. The current ratio, which measures a company's ability to cover short-term liabilities with short-term **** ets, is 10.3x. Free cash flow, defined as cash from operations minus capital expenditures, was a negative $5.4 million for the fiscal year ended in May.
#year #equipment

11 days ago
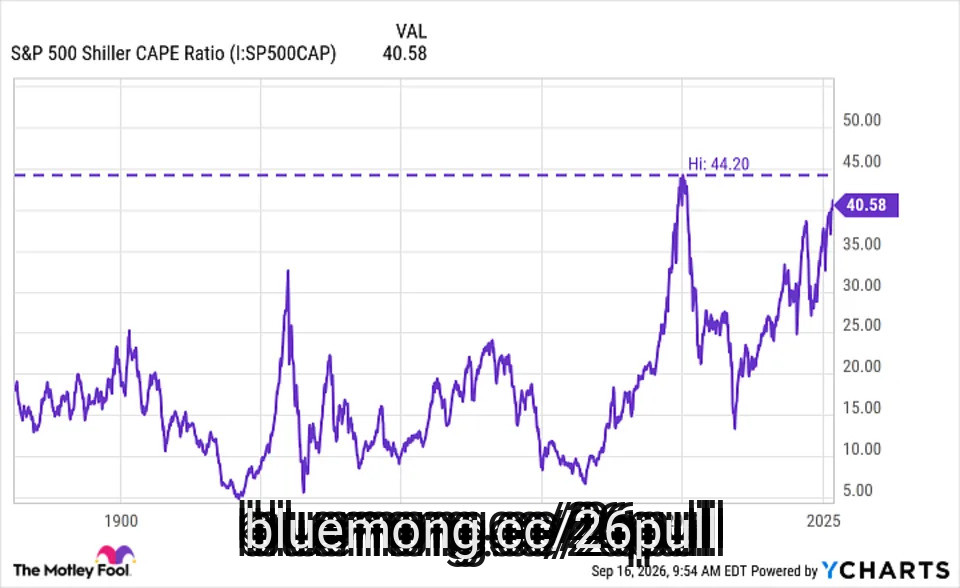
With just over three months left in the year, the S&P 500 (SNPINDEX: ^GSPC) is up 11% year to date. If it manages to stay there, it will end 2026 with four consecutive years of double-digit gains, a feat not accomplished since 1999 -- incidentally, right before it crashed and lost nearly 50% of its value. It lost that over three years, and it didn't reach a new high until mid-2007. Many companies went out of business then as the dot-com bubble burst.
If history is any indication of what's about to happen, every investor should be doing this one thing right now.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
The artificial intelligence (AI) revolution is real, but the hype might not exactly align with reality. Some well-established AI powerhouses, like Nvidia and Alphabet, don't look expensive at today's prices. They trade at 14 and 23 times forward, one-year earnings, respectively. However, other, smaller stocks look riskier as their valuations soar.
Bloom Energy, for example, trades at 53 times forward, one-year earnings, and only recently became profitable, while Marvell Technology trades at 33 times earnings. CoreWeave isn't yet profitable. It appears that investors are willing to take a chance on these stocks for the massive expected payoff as they grow.
#years #right #lost



11 days ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi


11 days ago
Interested in Equinix, Inc.? Here are five stocks we like better.
Equinix plans to invest $5 billion to $7 billion annually in data-center development, primarily in established markets where customer demand and infrastructure needs are already visible.
The company controls about 3 gigawatts of designed power, with 600–700 megawatts under development, and is targeting cash-on-cash returns in the low 20% range with typical stabilization in two to three years.
AI adoption is accelerating among enterprise customers, driving expected demand for higher-density facilities, liquid cooling and additional interconnections; however, executives said AI-related business still represents a minority of Equinix's revenue today.
3 Stocks Built for Higher Rates—And 2 That Could Break
#higher #demand #here #built
12 days ago
On September 15, Guggenheim ****** yst Michael Ciarmoli initiated coverage of almost two dozen defense stocks, with a bullish, sector-wide buy-the-pullback call.
He issued 13 Buy ratings with an average upside of roughly 50%, with the standout being Applied Aerospace & Defense, Inc. (NYSE:AADX). The ****** yst sees the stock around $30, up by about 150% from the share's closing price that day.
Ciarmoli described AADX as a "merchant supplier of established and proven military subsystems and components". The ****** yst believes the company is well positioned to benefit from favorable growth trends across the aerospace, defense, and ****** e industries.
Several defense stocks have struggled since the advent of the Iran war. Investors are also concerned about the possibility of a split Congress after the midterm elections, which could result in a spending gridlock.
However, Ciarmoli says the fears are overblown. The Guggenheim ****** yst is urging investors to be buyers on the pullback. He expects the current trend of increased spending on autonomous systems, ****** e, and replenishing depleted stockpiles to sustain.
#pullback

12 days ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE

12 days ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
12 days ago
Digital Realty Trust, Inc. (NYSE:DLR) announced a joint venture with Rönesans Infrastructure on September 14 to develop and operate data centers in Türkiye. The first Ankara campus is designed for more than 22 megawatts of IT capacity. Land, power and permits are secured, early construction has begun, and the first facility is scheduled for completion in 2028.
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture

12 days ago
Logistic Properties of the Americas (NYSEAMERICAN:LPA) moved closer to selling Parque Logístico Lima Sur after Peru's antitrust authority, INDECOPI, approved the transaction on September 11. FIBRA Prime would acquire the entire 1.3-million-square-foot logistics park for $145 million. Customary administrative closing matters remain outstanding.
Management expects approximately $85 million of net proceeds after debt repayment and before taxes, with Mexico the intended destination. Approval advances the financing of that expansion, while the investment case rests on replacing an established income stream.
Lima Sur generated $10.3 million of cash net operating income, or cash NOI, during the 12 months ended March 31, 2026. Cash NOI is a company-defined non-IFRS measure of property income after operating expenses, adjusted to remove straight-line rental accounting. It excludes corporate overhead, financing costs, income taxes, and other non-property items.
Logistic Properties of the Americas (NYSEAMERICAN:LPA) has demonstrated an ability to develop, lease and operate logistics ***** ets. Second-quarter revenue increased 26.1% to $14.7 million, while stabilized portfolio occupancy reached 100% as of June 30.
Mexico already contributes revenue. Two properties acquired in Puebla in August 2025 generated approximately $0.5 million during the second quarter. That provides an operating foothold for deploying proceeds.
#cash #logistic #nyseamerican #Mexico
12 days ago
Pharming Group N.V. (NASDAQ:PHAR) announced on September 11 that the U.S. Food and Drug Administration approved Joenja for children aged 4–11 with activated PI3K delta syndrome, or APDS, who weigh at least 27 kilograms. APDS disrupts immune function.
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric

13 days ago
Fox Corporation (NASDAQ:FOXA) disclosed on September 9 that the U.S. Department of Justice issued a second request for information concerning the proposed acquisition of Roku, Inc. (NASDAQ:ROKU). Cooperation with the review continues, and the expected closing remains in the first half of 2027, according to The Wall Street Journal.
A second request extends the premerger waiting period while regulators seek additional documents and data. For investors, the question is whether Fox Corporation (NASDAQ:FOXA) can preserve the acquisition's streaming benefits through a potentially longer review and any conditions attached to clearance.
The strategic fit centers on combining content with distribution. Roku, Inc. (NASDAQ:ROKU) reaches more than 100 million households globally and would provide Fox Corporation (NASDAQ:FOXA) with an established connected-television platform, advertising technology and direct consumer relationships.
That reach could create additional opportunities to promote live news, sports and streaming services. For advertisers, a broader combination of content, audience data and campaign tools could make the combined offering more useful, provided integration improves targeting and measurement.
The commercial opportunity also extends beyond audience growth. Better advertising monetization and more efficient promotion of streaming services could improve the value generated from existing viewers. Household reach provides the starting point; advertising revenue, engagement and customer acquisition costs would determine the financial payoff.
#advertising #second #request #review

13 days ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

13 days ago
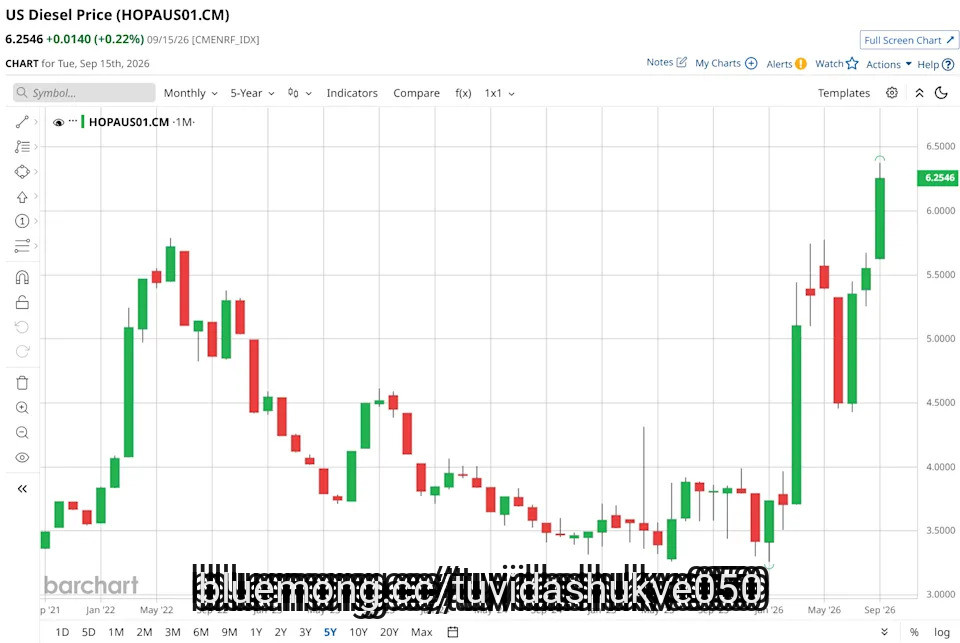
U.S. diesel prices have moved into record territory. The national average price of diesel climbed to a record $6.23 per gallon on Sept. 14, after first breaking above the $6 threshold last week. And diesel is hitting new highs again today at around $6.31. According to AAA data, the national average diesel price reached about $6.05 per gallon on Sept. 11, 2026, surpassing the previous record established in June 2022. The latest price is roughly 68% higher than the level of about $3.71 per gallon a year ago, highlighting the extraordinary speed of the rally.
The surge is being driven by a global shortage of refined petroleum products rather than crude oil alone. Disruptions to Middle Eastern energy infrastructure, sharply reduced traffic through the Strait of Hormuz, and attacks on Russian refineries have reduced the availability of diesel and other middle distillates. The situation has become serious enough that diesel prices are now adding to broader inflation concerns while simultaneously creating a potentially attractive environment for U.S. refiners.
Crude Oil Prices Sharply Lower as Middle East Disruptions Ease
Crude Oil Prices Retreat as Supply Fears Ease
Why UBS Just Turned Bearish on NuScale Power Stock
#Diesel
13 days ago
VICTORIA, SEYCHELLES, September 16th, 2026, Chainwire
Bitget has published its August 2026 Proof of Reserves report, marking the 45th consecutive monthly disclosure since the program began in December 2022, with a total reserve ratio of 122% for the month. Separately, Bitget's August 2026 Protection Fund valuation report recorded an average monthly value of $382 million, backed by 5,500 BTC held as a separate protection reserve.
Bitget publishes both monthly Proof of Reserves and monthly Protection Fund valuation reports — two separate disclosures providing visibility into different parts of the platform's **** et-protection framework. The August PoR reserve ratio of 122% means Bitget's reported reserves for tracked **** ets exceeded the corresponding user balances included in the snapshot. A full per-asset breakdown is available on Bitget's Proof of Reserves page.
A reserve ratio above 100% reflects the position captured in a particular reporting snapshot and should not be interpreted as a financial audit or a guarantee of future solvency.
The Protection Fund's August valuation ranged from approximately $345.3 million on Aug 1, 2026 to $441.5 million on Aug 27, 2026, with an average monthly valuation of $382 million. Its dollar value fluctuates with Bitcoin's market price because the fund is backed by 5,500 BTC. Bitget established the fund in 2022 with an initial $300 million commitment, and its valuation remained above that level throughout August.
#proof
13 days ago
By Katharine Jackson and Mike Scarcella
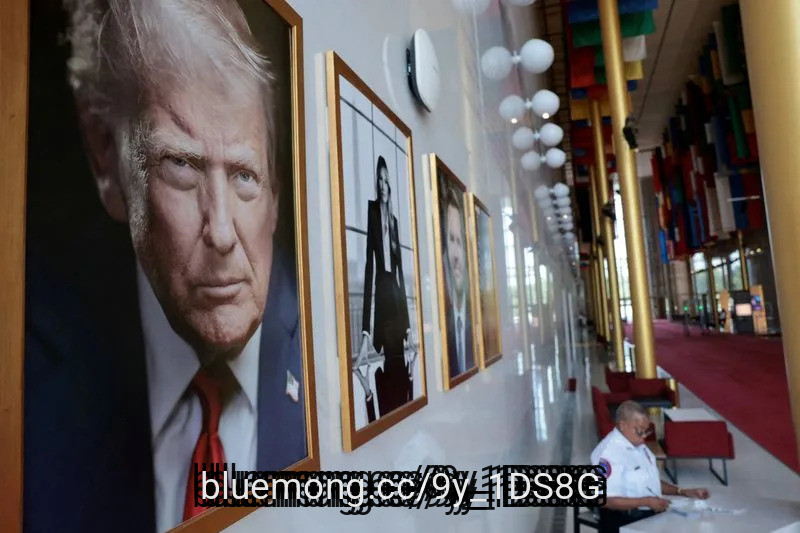
WASHINGTON, Sept 17 (Reuters) - A federal judge ordered President Donald Trump's administration on Thursday to provide at least 30 days' notice before taking any steps to demolish the Kennedy Center, the landmark performing arts venue that has become a flashpoint in his efforts to reshape the U.S. capital.
U.S. District Judge Christopher Cooper issued the order after lawyers for a Democratic congresswoman who is suing to keep the venue open and Trump's name off its facade submitted new evidence citing the Republican president's comments on Wednesday referring to demolishing the Kennedy Center.
"I think that the Trump administration should certainly have recognition. Because frankly, if we don't do that, it's going to close. It'll end up being ripped down," Trump told reporters in North Carolina, referring to putting his name on the facility established by Congress and opened in 1971 as a memorial to slain President John Kennedy.
Matt Floca, the Kennedy Center's Trump-backed executive director, said in a court filing earlier on Thursday that the building was being temporarily closed to ****** s safety risks in areas "exhibiting severe structural deterioration."
#president #venue

13 days ago
Bitcoin (BTC) dipped by 3.2% yesterday, following news that a procedural vote on the Clarity Act in the U.S. Senate failed to meet the required threshold.
With 49 votes in favor, 11 less than the minimum established to move the bill to the main floor, the Clarity Act has now been shelved for what remains of the year.
Republicans made a few amendments to the bill in the past few days to entice Democrats, but apparently failed to ease their concerns regarding the ethical provisions they were demanding.
Most other cryptocurrencies experienced strong declines following the news, but seem to be starting to recover this morning.
Truth be told, the market had already priced in that the Clarity Act would not be passed this year. Odds in Polymarket have been collapsing for months, although they recovered to 30% last week ahead of this key vote.
#clarity #following #bill


13 days ago
The choice between established ****** ans and digital-first challengers defines many modern portfolios. In the financial realm, investors must decide if JPMorgan Chase (NYSE:JPM) or SoFi Technologies (NASDAQ:SOFI) is the better buy for long-term growth.
JPMorgan Chase operates as a global financial heavyweight, offering everything from wealth management to retail branches. Conversely, SoFi Technologies focuses on an integrated mobile app to help members borrow, save, and invest. While one relies on massive scale, the other bets on fintech innovation to capture a younger, tech-savvy demographic.
JPMorgan Chase functions as a cornerstone of the global economy, managing a vast array of services including ****** et management and investment banking. In its latest annual report, filed for 2025, the firm highlighted its reach through more than 5,000 branches across the 48 contiguous states. It serves a diverse client base ranging from individual consumers and small businesses to large corporations and governments. The firm provides a comprehensive range of financial services, including transaction processing and commercial banking on a global scale.
Financial performance remained robust in FY 2025, with revenue reaching nearly $182.4 billion. This represented a growth rate of approximately 3.3% compared to the previous year, contributing to a net income of close to $57.0 billion. The net margin, which measures the percentage of revenue kept as profit after all expenses, sat at roughly 20.4% for the period. This consistent profitability underscores the scale of its operations across diverse global markets.
As of its December 2025 balance sheet, the firm reported a debt-to-equity ratio of nearly 2.6x. This ratio measures total debt against shareholder equity, with a higher number indicating more reliance on borrowed funds to finance growth. The current ratio, which compares short-term ****** ets to short-term liabilities, was approximately 0.5x, while free cash flow reached a negative $147.8 billion. Free cash flow is the cash a company generates after accounting for cash outflows to support operations and maintain its capital ****** ets.
#sofi #global #term

13 days ago
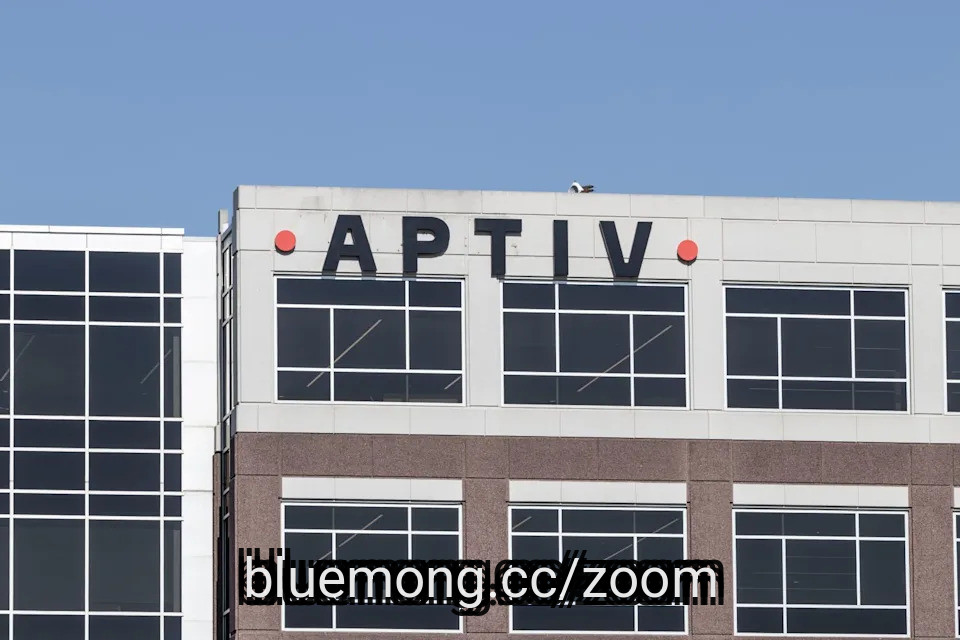
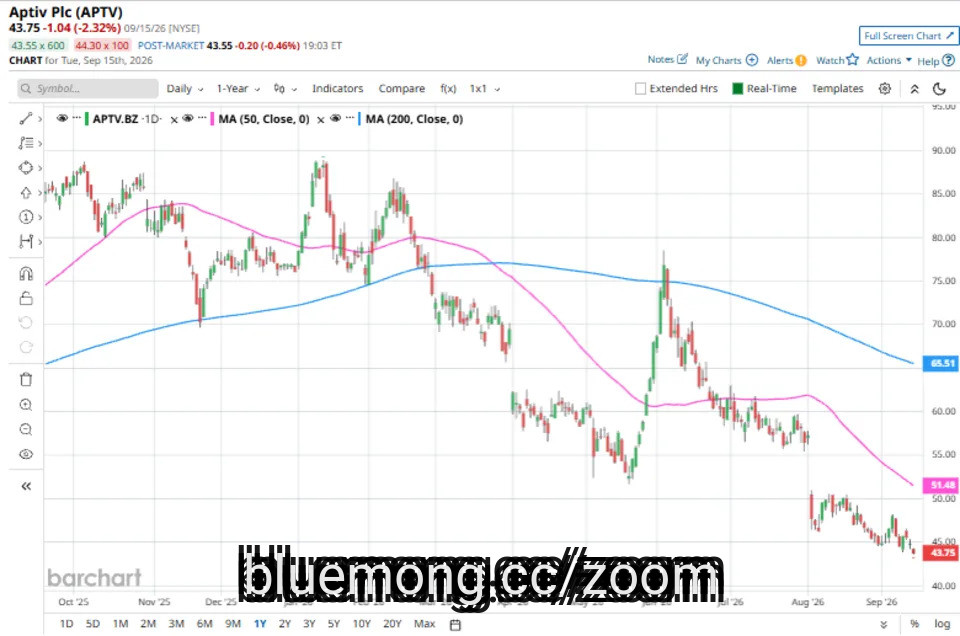
Schaffhausen, Switzerland-based Aptiv PLC (APTV) is a global industrial technology company developing automated, electrified and digitalized solutions. Its businesses provide software, advanced hardware, perception systems and connectivity technologies for mission-critical applications across mobility and other end markets. It has a market capitalization of approximately $9.3 billion.
Companies valued between $2 billion and $10 billion are generally classified as "small-cap stocks," and Aptiv comfortably fits this category. Its substantial market capitalization reflects its size, influence and established position within the auto parts industry. Aptiv stands out for its expertise in advanced automotive technology, including connectivity, electrification and intelligent systems. Its above-average margins, strong free cash flow and growing non-automotive business provide differentiation. Its established customer relationships and exposure to electrification and autonomous driving could support long-term growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#aptiv #technology #advanced #connectivity

13 days ago
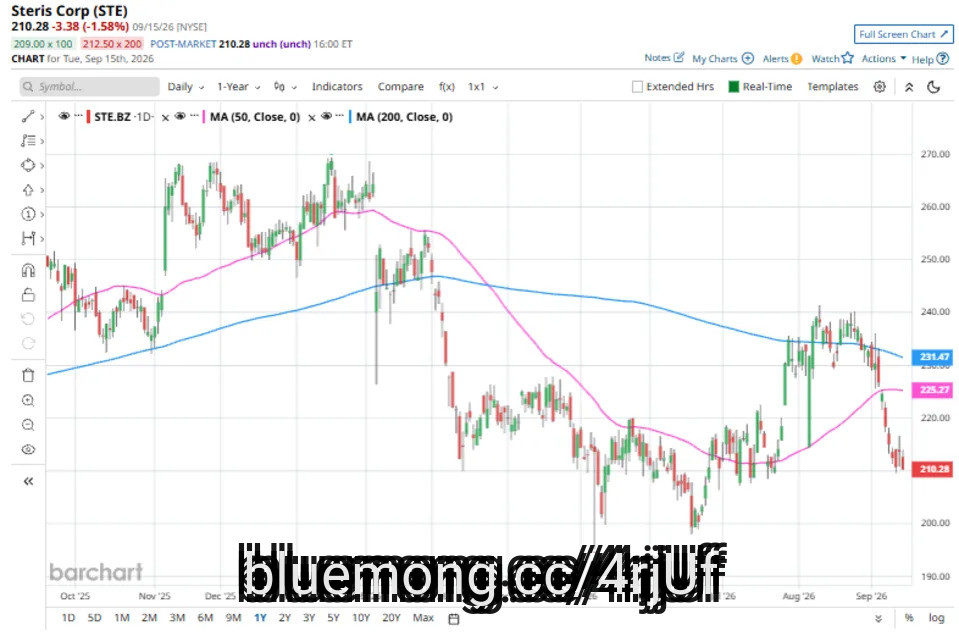
STERIS plc (STE), with a market capitalization of approximately $20.8 billion, is a global healthcare company focused on infection prevention and patient care. The Mentor, Ohio-based company provides consumable products, capital equipment, maintenance and repair services, sterilization solutions, laboratory testing, outsourced reprocessing, and operating room connectivity solutions.
Companies worth between $10 billion and $200 billion are generally classified as "large-cap stocks," and STERIS fits this description, with its market capitalization reflecting its substantial size and established position within the healthcare sector. STERIS stands out by combining a leading position in infection prevention with a broad range of healthcare and sterilization products and services. Its trusted brand, loyal customer base, strong financial position, and strategic acquisitions strengthen its competitive position while supporting continued expansion and innovation.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#steris #position
13 days ago
Biogen Inc. (BIIB) is a global biotechnology company that develops and commercializes therapies for serious and complex diseases. Headquartered in Cambridge, Massachusetts, Biogen has built a strong presence in neurology, specialized immunology, and rare diseases, with a portfolio spanning multiple sclerosis, spinal muscular atrophy, Alzheimer's disease, ALS, and other conditions.
Companies worth $10 billion or more are typically classified as "large-cap stocks," and Biogen, with a market cap of $32.1 billion, fits the label perfectly. Biogen's core strength lies in its deep neuroscience expertise and a portfolio of established therapies for complex neurological and rare diseases. Its long-standing research capabilities, specialized commercial infrastructure, and broad pipeline also provide scale and expertise that smaller biotech rivals can find hard to replicate.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#biogen #complex #expertise

13 days ago
The House of Representatives on Tuesday passed a bipartisan bill aimed at shielding Americans from increased electricity costs **** ociated with data centers being built across the country.
The Ratepayer Protection Act, which passed with an overwhelming 417-3 majority, "ensures American families are not left footing the bill for the grid upgrades and new energy generation required to operate large data centers," Republican Rep. Gabe Evans, one of the bill's sponsors, said ahead of the vote.
The bill now moves to the Senate, where its prospects of passing are uncertain.
The Ratepayer Protection Act is the first major piece of legislation taken up by Congress to address the growing public discontent over the mass buildout of data centers among the American public. Even if it passes, though, it won't directly set the rates that data center operators pay for their electricity.
Congress doesn't have the power to compel utilities to set higher rates for the facilities. Only states have that authority. What the Ratepayer Protection Act would do is compel state utility regulators to consider adopting a federal standard under which large data centers would cover the extra costs of upgrades. The bill is comparable to a proclamation signed by President Trump earlier this year that established a similar voluntary pledge for tech companies.
#passed


14 days ago
Tesla, Inc. (NASDAQ:TSLA) spent nearly two years raising anticipation for the Cybercab. When the time arrived on September 3 in Austin, the result was a stock that popped, then rapidly returned all of its gains, and a robotaxi race that still seems to be Alphabet's to lose.
Tesla, Inc. (NASDAQ:TSLA) had its long-awaited Cybercab launch event in Austin, Texas, but it was invitation-only, not livestreamed, and CEO Elon Musk wasn't there. The company's main public update was a 51-second video released on X of the two-seat, steering-wheel-free vehicle roaming city streets and people hailing it by app. Shares rose roughly 5% throughout the session, finishing near $376. By September 4, enthusiasm had waned, with the stock plummeting as much as 6% as investors realized how little the event revealed about deployment timelines, production ramp, or regulatory clearance.
Only 45 Cybercabs were registered in Texas, and Tesla, Inc. (NASDAQ:TSLA) did not seek an NHTSA exemption before deployment, instead self-certifying the Cybercab as compliant with applicable federal safety standards. NHTSA subsequently opened an audit into that certification and has ordered Tesla to provide additional information about the basis for its compliance claims. CNBC summarized the reaction bluntly: the update "underwhelmed" Wall Street, which had been relying on Tesla, Inc. (NASDAQ:TSLA) becoming a strong rival in the robotaxi sector, which Alphabet's Waymo currently leads.
That comparison is at the heart of the story. Waymo has established the operational track record that Tesla, Inc. (NASDAQ:TSLA) is still chasing: more than 4,000 autonomous vehicles across its U.S. fleet and more than 500,000 fully autonomous rides per week.
Wall Street's take on the incident was severely divided along those lines. Despite Tesla's efforts to control the narrative, some ******* ysts, including Gary Black of Future Fund, called the Cybercab debut largely a bust. Others, such as Deepwater ******* et Management's Gene Munster, predicted that Tesla, Inc. (NASDAQ:TSLA) will add approximately 300 Cybercabs in Austin over the next month.
#tesla #NASDAQ #cybercab
14 days ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
Columbia Threadneedle Investments and alternative ******* et manager Hamilton Lane announced a strategic collaboration to deliver new investment products for the wealth channel. An interval fund combining public and private equity exposure, currently awaiting SEC approval, will likely be the first product launched through the two firms' partnership.
Columbia Threadneedle brings its public markets expertise, multi-asset investment capabilities and strategic distribution relationships to the collaboration. Hamilton Lane specializes in alternatives, with an established private markets platform, investment sourcing capabilities and data ******* ytics expertise.
Columbia Threadneedle filed a preliminary registration statement with the SEC for the Columbia Hamilton Lane Growth Innovation Fund, a public-private growth equity interval fund. If the fund is approved by the SEC, it will be offered to the wealth channel through financial advisors.
According to the filing, the fund will focus on capital appreciation, allocating at least 80% of its net ******* ets to investments in growth innovation companies. The fund will be roughly evenly split in exposure to publicly traded securities and private ******* ets. At least 40% of the fund's ******* ets will be invested in underlying funds managed by Hamilton Lane.
#lane