

2 days ago
Marvell Technology (NASDAQ: MRVL) has been a big winner this year, with the stock up more than 130% in 2026, as of the end of October. However, an announced deal to acquire Lumentum (NASDAQ: LITE) could be a game changer for what has already been a good story.
This deal is all about optical networking, as it will combine Marvell's leadership in optical interconnects with Lumentum's strength in lasers. Marvell called the deal a "once-in-a-generation opportunity to define and lead AI connectivity in the era of integrated optics," as it will provide the company with end-to-end design capabilities that will allow it to accelerate its time to market and solve the increasing complexity of scale-up and scale-out networks.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's see what this could all mean for investors.
The two companies' optics technologies are very complementary. In an optical network, Marvell provides electronic components such as DSPs (digital signal processors) that prepare data to be converted into optical signals; transimpedance amplifiers (TIAs) that convert light signals back into electrical signals; and silicon photonics (SiPho) engines that combine hundreds of components to improve the performance and energy efficiency of optical interconnects.
#interconnects
This deal is all about optical networking, as it will combine Marvell's leadership in optical interconnects with Lumentum's strength in lasers. Marvell called the deal a "once-in-a-generation opportunity to define and lead AI connectivity in the era of integrated optics," as it will provide the company with end-to-end design capabilities that will allow it to accelerate its time to market and solve the increasing complexity of scale-up and scale-out networks.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Let's see what this could all mean for investors.
The two companies' optics technologies are very complementary. In an optical network, Marvell provides electronic components such as DSPs (digital signal processors) that prepare data to be converted into optical signals; transimpedance amplifiers (TIAs) that convert light signals back into electrical signals; and silicon photonics (SiPho) engines that combine hundreds of components to improve the performance and energy efficiency of optical interconnects.
#interconnects

7 days ago
ORCHARD PARK - One of the most fascinating aspects of the Buffalo Bills' 5-1 start is how efficient Josh Allen and the offense have been, and given the terrible play of the defense, it's exactly what has been needed.
The Bills lead the NFL in points per game at 32.8, and since the defense has allowed at least 29 points in five of the games, every point was necessary, and that will probably be the case Sunday at Highmark Stadium when the Bills host the Baltimore Ravens.
But here's what's crazy: The Bills have scored all these points despite the fact that they have run just 359 plays, tied for the second-fewest in the NFL. Yes, some of that has to do with playing only six games while others have played seven, but consider this: While the Bills average 59.8 offensive snaps, the Chicago Bears average 72.1, and the Los Angeles Rams average 68.2.
"I just think it's efficiency. Like, I go back to Week 1 when we had the ball at our two-yard line, and then I think three plays and we scored," said center Connor McGovern, recalling a series against the Texans late in the first half when the Bills actually went 96 yards to take a 24-14 lead, one of nine TD drives this season that have been achieved in six plays or less. "We're able to just get up there, calm, cool, if we get that first first down we're just rolling with that."
Of course, part of the low offensive snap count has to do with the Bills' defense not being able to get off the field and the opposition has averaged 32 minutes of time of possession. That's a key reason why the Bills are in hyper speed mode so often.
#bills #average
The Bills lead the NFL in points per game at 32.8, and since the defense has allowed at least 29 points in five of the games, every point was necessary, and that will probably be the case Sunday at Highmark Stadium when the Bills host the Baltimore Ravens.
But here's what's crazy: The Bills have scored all these points despite the fact that they have run just 359 plays, tied for the second-fewest in the NFL. Yes, some of that has to do with playing only six games while others have played seven, but consider this: While the Bills average 59.8 offensive snaps, the Chicago Bears average 72.1, and the Los Angeles Rams average 68.2.
"I just think it's efficiency. Like, I go back to Week 1 when we had the ball at our two-yard line, and then I think three plays and we scored," said center Connor McGovern, recalling a series against the Texans late in the first half when the Bills actually went 96 yards to take a 24-14 lead, one of nine TD drives this season that have been achieved in six plays or less. "We're able to just get up there, calm, cool, if we get that first first down we're just rolling with that."
Of course, part of the low offensive snap count has to do with the Bills' defense not being able to get off the field and the opposition has averaged 32 minutes of time of possession. That's a key reason why the Bills are in hyper speed mode so often.
#bills #average



7 days ago
The Tennessee **** ans are having one of the worst seasons in their history. At 1-6, they're off to their worst start to a season in nearly 20 years. Cam Ward's **** ans have struggled on both offense and defense, and they have been unfortunate with injuries.
Ward has also had a troubling start. He has been criticized for his efficiency and decision-making all season. In seven games, he has thrown for 1,179 passing yards with four touchdowns and five interceptions.
There have been rumors of the **** ans looking to go away from Ward, especially after defensive tackle Jeffery Simmons' trade to the Chicago Bears. But NFL insider Adam Schefter reported that the **** ans will continue to back Ward despite a 1-6 start.
Fans reacted to Schefter's comments.
"It will be their ultimate downfall. They are not a QB developing team, or they make bad picks with high draft choices. Vince Young, Jake Locker, Will Levis, now it's Cam Ward!" one fan said.
#ward #tennessee #simmons #Chicago
Ward has also had a troubling start. He has been criticized for his efficiency and decision-making all season. In seven games, he has thrown for 1,179 passing yards with four touchdowns and five interceptions.
There have been rumors of the **** ans looking to go away from Ward, especially after defensive tackle Jeffery Simmons' trade to the Chicago Bears. But NFL insider Adam Schefter reported that the **** ans will continue to back Ward despite a 1-6 start.
Fans reacted to Schefter's comments.
"It will be their ultimate downfall. They are not a QB developing team, or they make bad picks with high draft choices. Vince Young, Jake Locker, Will Levis, now it's Cam Ward!" one fan said.
#ward #tennessee #simmons #Chicago


1 month ago
In December 2025, about a month before the U.S. invaded Venezuela and captured its president, Nicolás Maduro, President Trump had a secret meeting with Elon Musk, Time magazine reports. This was roughly seven months after Musk left his role in the Trump administration at the Department of Government Efficiency (DOGE).
During this meeting, Trump "spent hours" talking to Musk's Grok chatbot, including asking how Venezuelans would respond to the capture of their president, a source told Time. Just a few months earlier, in September, Trump began ordering U.S. military strikes against Venezuelan boats that Trump alleged were involved in drug trafficking.
People had apparently been turning to Grok asking about the boat strikes and political climate in Venezuela, as The Atlantic reported at the time. So Grok told Trump that Maduro was a "deeply unpopular dictator and that many Venezuelans would likely celebrate his downfall," Time reported.
When such celebrations indeed happened after the U.S. invaded on January 3, Trump apparently "came away thinking Grok was ingenious," that source told Time.
So perhaps it should come as no surprise that in June of this year, the Pentagon's head of AI said that the military used Grok Gov to deploy and strike targets during the Iran War.
#grok #told #musk
During this meeting, Trump "spent hours" talking to Musk's Grok chatbot, including asking how Venezuelans would respond to the capture of their president, a source told Time. Just a few months earlier, in September, Trump began ordering U.S. military strikes against Venezuelan boats that Trump alleged were involved in drug trafficking.
People had apparently been turning to Grok asking about the boat strikes and political climate in Venezuela, as The Atlantic reported at the time. So Grok told Trump that Maduro was a "deeply unpopular dictator and that many Venezuelans would likely celebrate his downfall," Time reported.
When such celebrations indeed happened after the U.S. invaded on January 3, Trump apparently "came away thinking Grok was ingenious," that source told Time.
So perhaps it should come as no surprise that in June of this year, the Pentagon's head of AI said that the military used Grok Gov to deploy and strike targets during the Iran War.
#grok #told #musk

2 months ago
Meta Platforms, Inc. (NASDAQ:META) is taking another step toward monetizing artificial intelligence beyond its core advertising business. On September 9, the company acquired AI startup Stilla.ai.
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents
The acquisition will strengthen the company's agentic AI capabilities as it moves to capitalize on growing demand for AI agents that can handle business transactions. Plans are underway to integrate Stilla.ai's team and technology into Meta Business Agent, which already helps businesses interact with customers across various platforms.
Stilla.ai's technology could help Meta's Business Agent enable more sophisticated interactions between customers and AI agents across its messaging platforms. In the long term, customers could use AI agents to inquire about products, discuss pricing, and potentially complete purchases without leaving Meta's ecosystem.
Such capabilities could result in new monetization opportunities as the company faces increasing pressure to generate returns from its substantial artificial intelligence investments. Rather than relying exclusively on AI to improve advertising efficiency, Meta could use AI to facilitate transactions and capture value from the commercial activity taking place across its platforms.
The acquisition could help the company build an AI-driven commerce layer across its massive messaging ecosystem. The company has access to billions of users across Facebook, Instagram, Messenger, and WhatsApp, while millions of businesses already use its platforms to communicate with customers.
#customers #agents

2 months ago
The CLARITY Act failed to pass votes in the Senate earlier this week, a piece of legislature that would set out guardrails and ground rules for crypto **** ets in the U.S. With the failure of passage, the Securities and Exchange Commission took matters into its own hands, passing a conditional exemption Thursday for tokenized stocks. This Innovation Exemption allows for a limited type of tokenized securities to trade on specific Tokenized Securities Venues (TSVs), giving them a 5-year runway to prove their trading chops.
Tokenization is one of the latest trends in the investing world, whereby an **** et is represented digitally on a blockchain. It's seen as the next frontier in finance, with digital trading opening up greater access both for a broader investor base as well as the potential to trade 24/7, while also offering the potential for increased efficiency. However, some argue that tokenized **** ets come with added, unique risks and that by moving investments to the blockchain you introduce greater exposure to bad actors in an as-yet unregulated **** e in the U.S. That is, until now.
The SEC exemption allows for a specific type of tokenized stocks to be traded, specifically ones that retain the investor rights of the stock they are tied to (voting and dividends for example). Only tokenized U.S. National Market System (NMS) stocks qualify that trade through U.S. venues who have established standards for who can trade, limit trading volumes to a certain percentage of the stock, and make public their trading activities as well as any affiliates on the TSV. In addition, venues must halt trading when the primary exchange halts, and leverage is not permitted. Any company that does not want tokenized shares has 30 days to object and prevent their shares from being created.
It's important to note that currently there are two main types of tokenized securities, those that are directly linked to the **** et they represent digitally and those that provide synthetic exposure. Of the two, only the direct exposure tokenized stocks qualify that meet all of the exemption's restrictions.
"The Commission is not cementing today's technology as the standard for tomorrow. Instead, it is allowing the market to evolve, monitoring its development, and using that insight to inform a nimbler and future-ready regulatory framework," SEC Chair Paul Atkins said in a statement.
#exposure #commission
Tokenization is one of the latest trends in the investing world, whereby an **** et is represented digitally on a blockchain. It's seen as the next frontier in finance, with digital trading opening up greater access both for a broader investor base as well as the potential to trade 24/7, while also offering the potential for increased efficiency. However, some argue that tokenized **** ets come with added, unique risks and that by moving investments to the blockchain you introduce greater exposure to bad actors in an as-yet unregulated **** e in the U.S. That is, until now.
The SEC exemption allows for a specific type of tokenized stocks to be traded, specifically ones that retain the investor rights of the stock they are tied to (voting and dividends for example). Only tokenized U.S. National Market System (NMS) stocks qualify that trade through U.S. venues who have established standards for who can trade, limit trading volumes to a certain percentage of the stock, and make public their trading activities as well as any affiliates on the TSV. In addition, venues must halt trading when the primary exchange halts, and leverage is not permitted. Any company that does not want tokenized shares has 30 days to object and prevent their shares from being created.
It's important to note that currently there are two main types of tokenized securities, those that are directly linked to the **** et they represent digitally and those that provide synthetic exposure. Of the two, only the direct exposure tokenized stocks qualify that meet all of the exemption's restrictions.
"The Commission is not cementing today's technology as the standard for tomorrow. Instead, it is allowing the market to evolve, monitoring its development, and using that insight to inform a nimbler and future-ready regulatory framework," SEC Chair Paul Atkins said in a statement.
#exposure #commission

2 months ago
Interested in HCA Healthcare, Inc.? Here are five stocks we like better.
Exchange-related pressure is weighing on HCA's 2026 outlook: The expiration of enhanced tax credits is pushing some patients into uninsured status, with estimated full-year impact of $1 billion to $1.2 billion and slower elective-care utilization.
State supplemental payments and underlying demand provide offsets: HCA expects a $300 million to $500 million net benefit from state programs, while insured business excluding exchange plans grew 3.2% and adjusted admissions increased 2.7% in the second quarter.
HCA is pursuing long-term growth through capacity and efficiency investments: The company is expanding outpatient facilities, improving patient throughput and cost management, and maintaining a target of 4% to 6% long-term revenue growth with stable margins.
Healthcare Added 35,200 Jobs—3 Stocks Positioned to Benefit
#healthcare #Growth
Exchange-related pressure is weighing on HCA's 2026 outlook: The expiration of enhanced tax credits is pushing some patients into uninsured status, with estimated full-year impact of $1 billion to $1.2 billion and slower elective-care utilization.
State supplemental payments and underlying demand provide offsets: HCA expects a $300 million to $500 million net benefit from state programs, while insured business excluding exchange plans grew 3.2% and adjusted admissions increased 2.7% in the second quarter.
HCA is pursuing long-term growth through capacity and efficiency investments: The company is expanding outpatient facilities, improving patient throughput and cost management, and maintaining a target of 4% to 6% long-term revenue growth with stable margins.
Healthcare Added 35,200 Jobs—3 Stocks Positioned to Benefit
#healthcare #Growth


2 months ago
Amazon (AMZN) has spent the bulk of 2026 giving investors tons to debate, from its growing cloud business to the enormous bill for its AI ambitions. Now, it's putting another spending decision in the spotlight, one that goes directly into workers' household budgets.
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn
Amazon has announced more than $1.5 billion in higher pay for U.S. operations employees, alongside benefits aimed at everyday expenses.
For workers, the appeal is the obvious, immediate financial breathing room.
For Amazon, the calculation goes further. Keeping experienced employees helps the business built around getting orders to doorsteps a lot quickly. The details point to how Amazon is trying to make those interests meet, even as its broader efficiency push leaves questions about job security.
For perspective, Amazon's pay ******* p adds $2,080 to an eligible worker's annual earnings before taxes, ******* uming 40 paid hours weekly for 52 weeks.
#amazon #goes #employees #amzn


2 months ago
Picture a snowy mountain slope in France or an elite tennis court during a grand slam. Whether it is an Arc'teryx jacket designed for the harshest alpine conditions or a Wilson racket in the hands of a professional, Amer Sports (NYSE:AS) equips the world's most demanding athletes. The company functions as a global powerhouse in athletic gear and apparel, operating a premium multi-brand platform that spans from high-end technical clothing to specialized sports equipment. With its current stock price at $27.26 as of Sept. 16, 2026, the company has seen the stock decline 26% over the past year, reflecting the market's digestion of its rapid post-IPO scaling.
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium
Our proprietary Hidden Gems scoring system **** igns Amer Sports an overall Superscore of 75 out of 100, placing it in the Above Average category. This score ranks the company in the Top ~21% of every company we evaluate, ahead of roughly 79 out of every 100 firms we score. The Superscore serves as a data-driven starting point, and this article examines both the operational momentum fueling its recent success and the structural hurdles that keep the company below top-tier rankings, helping you weigh these signals against your own research.
Strong revenue momentum: The company achieved 27% year-over-year revenue growth in 2025, reaching $6.6 billion as it successfully scaled its brand-led platform across global markets.
Effective channel pivot: Direct-to-consumer revenue surged 43% in 2025, allowing the company to capture higher margins and deepen its direct relationship with premium consumers.
Expanding operational efficiency: Adjusted EBITDA margins widened to 18% in 2025, demonstrating that the company's shared infrastructure strategy is successfully converting scale into bottom-line profitability.
#company #sports #global #premium


2 months ago
Hub Group, Inc. (NASDAQ:HUBG) disclosed on September 14 that preliminary, unaudited first-half 2026 revenue was expected to reach $1.7 billion to $1.8 billion, near management's expectations. Yet management anticipated an operating loss before one-time charges. This non-GAAP presentation excludes those charges, but neither the loss nor the exclusions were quantified.
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better
Hub Group, Inc. (NASDAQ:HUBG) identified higher fuel, rail, and drayage costs, excess warehouse capacity, and accounting-review and restatement expenses. The central issue is whether pricing and efficiency improvements can restore profitability on the revenue already moving through the business.
Hub Group, Inc. (NASDAQ:HUBG) began implementing rate increases in the third quarter, after transportation costs had pressured first-half results. Relatively stable intermodal volume trends suggest an existing customer base on which better pricing could improve margins. If increases hold without significant volume losses, revenue could become more profitable without requiring a broad freight recovery.
Hub Group, Inc. (NASDAQ:HUBG) also launched additional efficiency initiatives in the second quarter, including warehouse consolidation and improvements in driver and warehouse-worker productivity. These actions address specific weaknesses: underused ***** e spreads fixed costs across fewer orders, while low productivity raises the cost of each shipment or handling task. Better utilization could reinforce the benefit of higher rates.
Hub Group, Inc. (NASDAQ:HUBG) is also targeting order-to-cash processes, which cover the steps from taking orders through billing and collection. Improvements could reduce administrative friction and accelerate cash collection. That would support liquidity while operational changes take effect, although faster collections alone would not repair an operating loss.
#improvements #better


2 months ago
Aristotle International Equity Fund, sub-advised by Aristotle Capital Management, LLC, released its second-quarter 2026 investor letter. The letter can be downloaded here. Global equity markets reached record highs in Q2, with the MSCI ACWI Index rising 14.93%, while global fixed income grew modestly by 0.87%. Geopolitical tensions, particularly in the Middle East, affected energy markets and investor sentiment, highlighting volatility and fragility in global supply. Central banks reacted variably to inflationary pressures, with the ECB raising rates amidst concerns of stagflation, while the Fed and Bank of England held rates steady. Despite economic challenges, robust earnings continued in Europe and Asia, driven by AI infrastructure demand. The Aristotle International Equity Fund (Class I-2) recorded an 8.40% return in the quarter, underperforming both the MSCI EAFE Index, which returned 10.82%, and the MSCI ACWI ex USA Index, which returned 14.49%. Going forward, the fund remains focused on quality investments as geopolitical and macroeconomic complexities make forecasting returns challenging. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa
In its second-quarter 2026 investor letter, Aristotle International Equity Fund highlighted Unilever PLC (NYSE:UL). Unilever PLC (NYSE:UL) is a British consumer goods giant, that sell products across food, homecare, beauty, and personal care categories. On September 17, 2026, Unilever PLC (NYSE:UL) closed at $62.22 per share. Over the past month, Unilever PLC (NYSE:UL) declined 2.99%, but its shares are down 5.09% over the past year. Unilever PLC (NYSE:UL) has a market capitalization of $133.98 billion, and its stock has traded within a 52-week range of $54.75 to $74.98.
Aristotle International Equity Fund stated the following regarding Unilever PLC (NYSE:UL) in its Q2 2026 investor letter:
"We first invested in Unilever PLC (NYSE:UL), the global consumer staples company, in the second quarter of 2013. We have long been attracted to the company's broad portfolio of leading personal care and food brands (such as Dove, Knorr and Axe), global scale, significant emerging markets exposure and strong position across everyday use categories. Over our more than decade-long holding period, Unilever strengthened and simplified its portfolio, divesting lower-growth food ***** ets, improving efficiency, increasing focus behind its largest brands and shifting the business toward faster-growing, higher-margin beauty, wellbeing, personal care and home care categories. More recently, the separation of the ice cream business and continued reshaping of the food portfolio have further narrowed Unilever's strategic focus. While we continue to view the remaining Unilever franchise as high quality, we believe the more compelling opportunity now resides in the independent ice cream business, where dedicated management and a category-specific strategy should provide a clearer pa

2 months ago
Pharming Group N.V. (NASDAQ:PHAR) announced on September 11 that the U.S. Food and Drug Administration approved Joenja for children aged 4–11 with activated PI3K delta syndrome, or APDS, who weigh at least 27 kilograms. APDS disrupts immune function.
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric


2 months ago
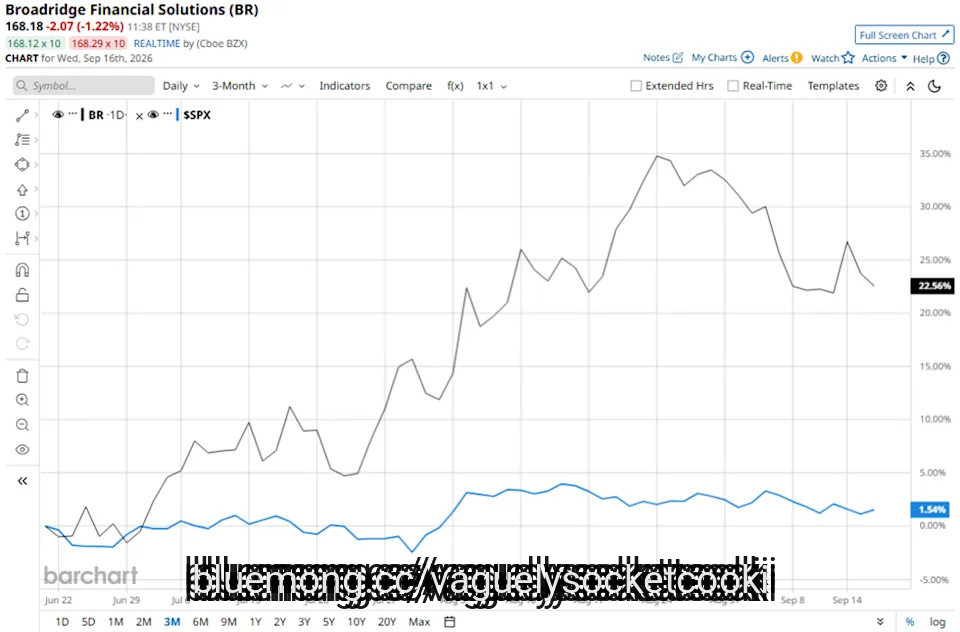
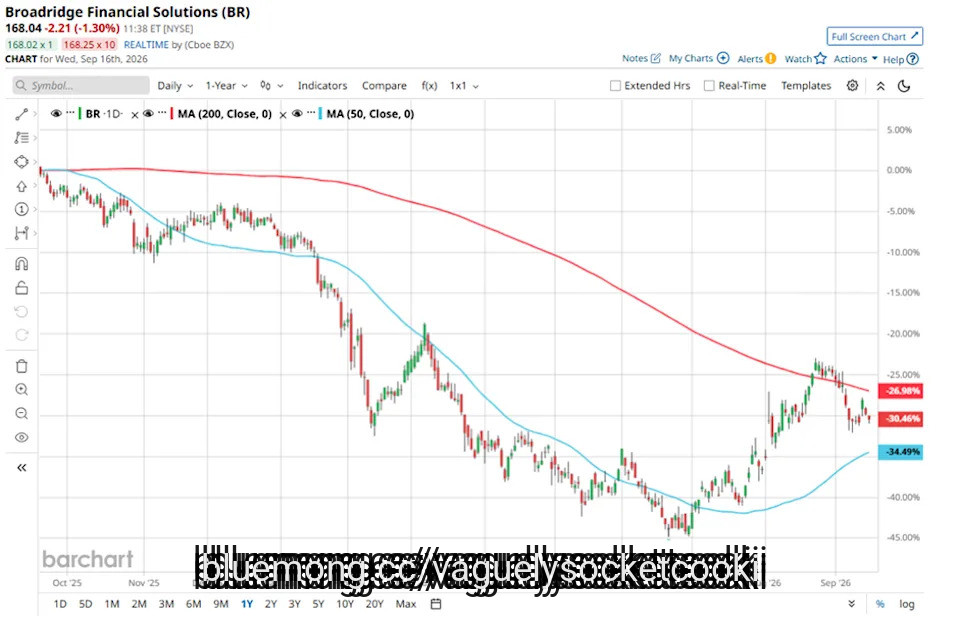
With a market cap of $19.4 billion, Broadridge Financial Solutions, Inc. (BR) is a global financial technology leader that provides investor communications and technology-driven solutions to banks, broker-dealers, ***** et managers, corporate issuers, and other financial institutions. Broadridge plays a critical role in enhancing transparency, efficiency, and engagement across the financial services industry.
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Broadridge Financial fits this criterion perfectly. Through its two segments: Investor Communication Solutions and Global Technology & Operations, the company delivers services ranging from regulatory and shareholder communications to front-to-back securities processing and data-driven solutions.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#financial #broadridge
Companies valued at $10 billion or more are generally classified as "large-cap" stocks, and Broadridge Financial fits this criterion perfectly. Through its two segments: Investor Communication Solutions and Global Technology & Operations, the company delivers services ranging from regulatory and shareholder communications to front-to-back securities processing and data-driven solutions.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Why It's Time to Load Up on Nvidia Stock
#financial #broadridge

2 months ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#jetson #robotics

2 months ago
Walk into a Burlington Stores (NYSE:BURL) location on a Saturday afternoon, and you will see the mechanism of the company's business model in action. It's a literal hunt for value: a customer finds a name-brand jacket at a steep discount, checks the tag, and takes it to the register. Burlington operates as an off-price retailer of apparel, footwear, and home goods. With the stock priced at $228.73 as of Sept. 15, 2026, it has fallen by 15% over the past 12 months, a period marked by significant operational expansion and active navigation of the retail sector.
Our proprietary Hidden Gems scoring system ****** igns Burlington Stores an overall Superscore of 78 out of 100, placing it in the Strong category. The Superscore is an AI-powered metric that evaluates a company's overall strength by combining financial performance, product-market position, technological capabilities, leadership quality, and relative valuation. It represents the unification of all our scores into a single score for public companies, with five rating bands: Exceptional (90-100), Strong (75-89), Above Average (60-74), Average (40-59), and Cautious (0-39).
This 78 Superscore places the company in the Top ~14% of every company we score. This ****** ysis provides a data-driven signal to help you weigh the company's operational strengths against its risks as part of your own due diligence.
Accelerated store growth: Management successfully opened 104 net new stores in fiscal 2025, executing a long-term strategy to reach 2,000 total locations.
Operational efficiency gains: Gross margin reached 46% in Q2 fiscal 2026, driven by improved inventory turnover and a sophisticated supply chain that distributes goods from six regional centers.
#strong
Our proprietary Hidden Gems scoring system ****** igns Burlington Stores an overall Superscore of 78 out of 100, placing it in the Strong category. The Superscore is an AI-powered metric that evaluates a company's overall strength by combining financial performance, product-market position, technological capabilities, leadership quality, and relative valuation. It represents the unification of all our scores into a single score for public companies, with five rating bands: Exceptional (90-100), Strong (75-89), Above Average (60-74), Average (40-59), and Cautious (0-39).
This 78 Superscore places the company in the Top ~14% of every company we score. This ****** ysis provides a data-driven signal to help you weigh the company's operational strengths against its risks as part of your own due diligence.
Accelerated store growth: Management successfully opened 104 net new stores in fiscal 2025, executing a long-term strategy to reach 2,000 total locations.
Operational efficiency gains: Gross margin reached 46% in Q2 fiscal 2026, driven by improved inventory turnover and a sophisticated supply chain that distributes goods from six regional centers.
#strong

2 months ago
Interested in NVIDIA Corporation? Here are five stocks we like better.
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here

2 months ago
Generate Capital, a leading investor, owner and operator of critical infrastructure, on September 15 announced the closing of a $117-million term debt facility with MUFG to finance a portfolio of community solar projects. The transaction marks Generate's first community solar financing with MUFG and further expands the company's network of leading institutional financing partners.The facility supports Generate's Community Solar Fund 11, comprising 18 projects and 114-MWdc across Illinois and New York. The financing will support Generate's continued investment in community solar infrastructure that expands access to reliable and affordable power for communities and businesses."The closing of this facility with MUFG further expands our financing partner network and provides additional capital to support the continued growth of our community solar platform," said Ed Bossange, Chief Capital Formation Officer at Generate Capital. "Combined with the significant financing activity we completed during the first half of the year, this transaction reflects the strength of our platform and our ability to attract capital from leading institutions across a diverse range of infrastructure solutions.""We are pleased to partner with Generate on this financing and support the continued growth of its community solar platform," said Fred Zelaya, managing director at MUFG. "Generate has built a strong track record of developing and operating high-quality distributed energy ****** ets, and this transaction reflects our shared commitment to financing critical infrastructure that delivers reliable, affordable power to communities across the country."The transaction builds on significant capital formation momentum for Generate in 2026. During the first half of the year, the company closed approximately $1.4 billion of financing commitments across a diversified portfolio of infrastructure investments spanning community solar, battery energy storage systems and energy efficiency.First-half highlights included:
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects
Closing of a 104-MW community solar portfolio alongside Monarch Private Capital, supporting more than 15 community solar projects expected to deliver approximately $200 million in investment tax credits.
A $61-million senior secured U.S. Private Placement to finance energy efficiency projects for a leading investment-grade industrial customer. The 15-year construction-to-term financing represents Generate's inaugural 4(a)2 U.S. Private Placement, further diversifying the firm's funding sources and financing partner base.
#community #generate #leading #projects


2 months ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ******* et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in

2 months ago
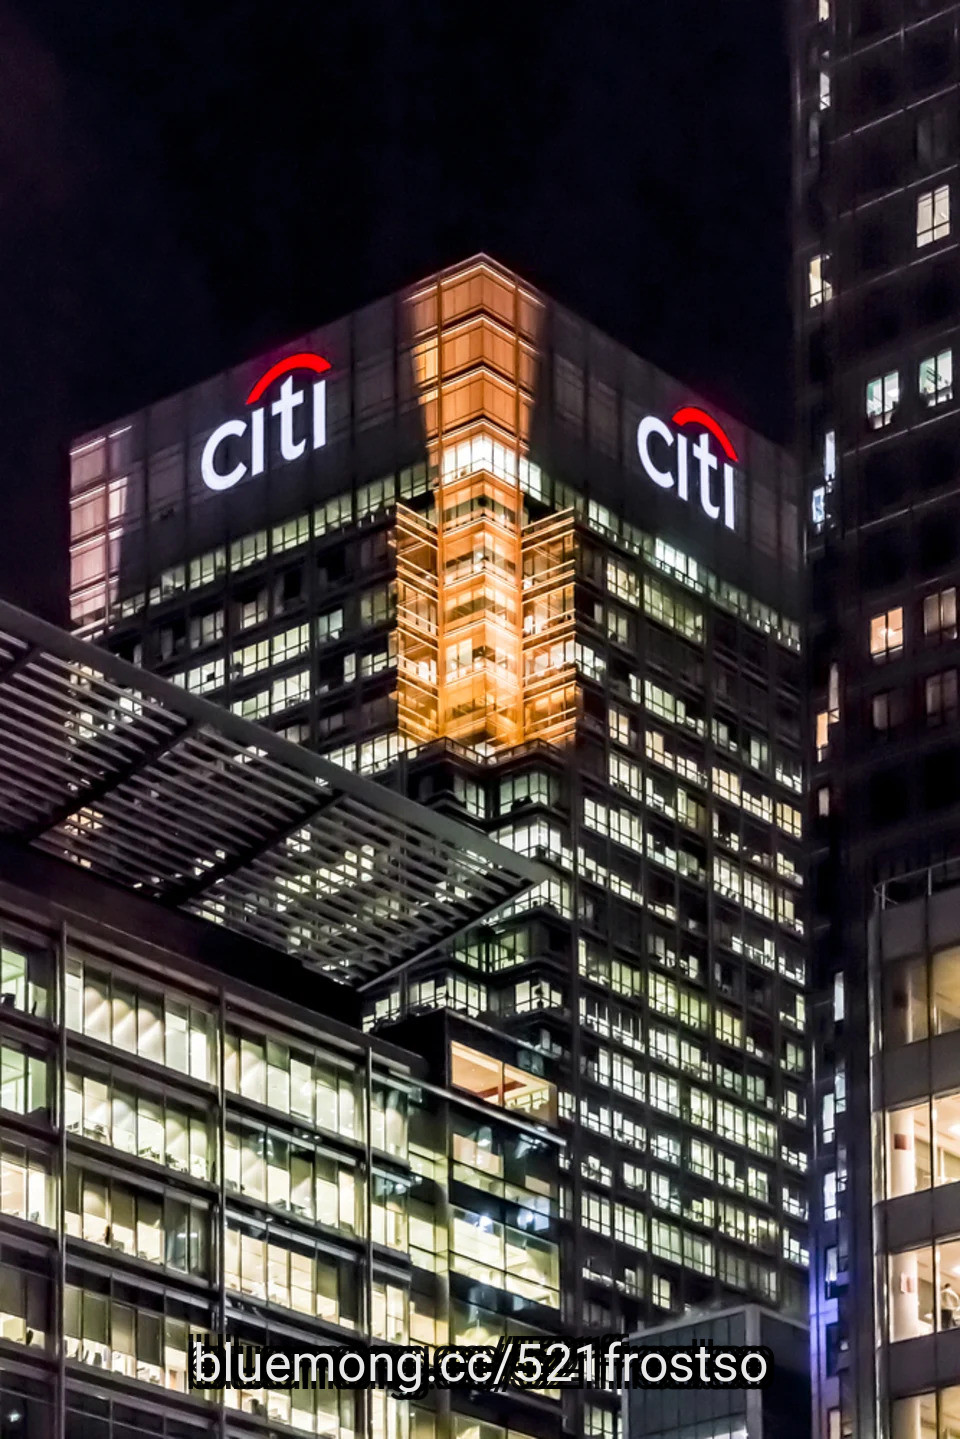
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management

2 months ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million


2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ******* yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ******* yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700
2 months ago
The artificial intelligence (AI) boom is entering a new phase, and this time, the battle is moving deeper into the data center. It is no longer simply about who can build the fastest AI accelerator. Hyperscalers are scrambling for more compute, faster connectivity, and better power efficiency as AI workloads continue to grow at a breakneck pace. That is opening the door for chipmakers that can deliver customized, energy-efficient solutions at scale.
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #hyperscalers #amzn
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #hyperscalers #amzn



2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#nepa #operations
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#nepa #operations
2 months ago
Auxier ****** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ****** et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in me
In its second-quarter 2026 investor letter, Auxier ****** et Management highlighted UnitedHealth Group Incorporated (NYSE:UNH) as a material contributor. UnitedHealth Group Incorporated (NYSE:UNH) is a multinational health benefits company based in Eden Prairie, Minnesota. On September 14, 2026, UnitedHealth Group Incorporated (NYSE:UNH) closed at $383.55 per share. Over the past month, UnitedHealth Group Incorporated (NYSE:UNH) declined 4.38%, while its shares gained 10.86% over the past 52 weeks. UnitedHealth Group Incorporated (NYSE:UNH) has a market capitalization of $344.27 billion with a 52-week trading range between $255.97 and $461.62.
Auxier ****** et Management stated the following regarding UnitedHealth Group Incorporated (NYSE:UNH) in its Q2 2026 investor letter:
"UnitedHealth Group Incorporated (NYSE:UNH) Leads the Way in Reshaping the Insurance Industry with AI UnitedHealth Group is among the companies that have successfully integrated AI into various parts of their operations. One of the most significant benefits has been in administrative functions, where AI has helped save tens of thousands of hours through increased automation and efficiency. As an example, automated transcription of patient encounters has contributed to lower levels of clinician burnout. Management reports that they are generating about $2 of value for every $1 spent on AI due to reductions in manual labor. We like this measured approach to implementing AI where it can provide clear operational benefits and attractive returns, which has been a key strategy of current CEO Stephen Hemsley. UnitedHealth's success in AI use highlights the technology's potential on the user side where companies can benefit without the high upfront cost of building the infrastructure. Cigna Group is projecting $200 million in me

2 months ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
2 months ago
Oracle Corporation (NYSE:ORCL) is increasing the expected cost of its fiscal 2026 restructuring plan by about $700 million to roughly $2.8 billion as it simultaneously ramps up spending to capture demand for AI cloud services. The additional costs include severance, contract terminations and other exit expenses, with some restructuring directly linked to adopting AI across parts of the organization.
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
Oracle had already recorded $1.8 billion of restructuring expenses in fiscal 2026, compared with $299 million in fiscal 2025, showing how materially the company is accelerating its operational transformation. The restructuring comes alongside an unusually large AI investment cycle. Oracle booked more than $30 billion of new AI cloud contracts in its latest quarter, lifting its remaining performance obligations/revenue backlog to $664 billion, while roughly half of that backlog is expected to convert into revenue over the next 36 months.
The strongest bull argument is that the additional restructuring expense is part of a broader shift toward a higher-growth cloud and AI business rather than simply a deterioration in cost control. Oracle Corporation (NYSE:ORCL)'s restructuring program is explicitly aimed at improving efficiency while reallocating resources toward cloud-based offerings and second-generation cloud infrastructure. If the $2.8 billion restructuring program reduces lower-growth costs and enables Oracle to redirect personnel and capital toward AI infrastructure, the near-term earnings pressure could support stronger operating leverage later as cloud revenue scales.
More importantly, the restructuring is occurring against evidence that AI demand is already translating into contracted revenue. Oracle added more than $30 billion of AI cloud contracts in one quarter, pushing its backlog to $664 billion, above the $639.89 billion ****** yst estimate. Management said most of the newly contracted revenue would not require substantial incremental capital because customers are using prepayments or supplying their own hardware. That is particularly important because Oracle's biggest weakness has been the mismatch between rapid infrastructure investment and current cash generation. If customer-funded capacity continues to reduce Oracle's upfront capital burden, the company could convert its huge backlog into revenue without proportionally increasing its cash burn.
The early financial evidence also supports the possibility that the AI strategy is beginning to improve Oracle's growth profile. Revenue in the recent quarter rose 30% year over year to $19.3 billion, adjusted EPS reached $1.92 versus the $1.74 ****** yst consensus, and Oracle Corporation (NYSE:ORCL) raised its fiscal 2027 adjusted EPS forecast from $8.05 to $8.10. Meanwhile, first-quarter free cash flow of negative $5.4 billion was substantially better than both the expected negative $9.56 billion and the previous-quarter negative $11.48 billion. If this trajectory continues, the $700 mi
2 months ago
The artificial intelligence (AI) boom is entering a new phase, and this time, the battle is moving deeper into the data center. It is no longer simply about who can build the fastest AI accelerator. Hyperscalers are scrambling for more compute, faster connectivity, and better power efficiency as AI workloads continue to grow at a breakneck pace. That is opening the door for chipmakers that can deliver customized, energy-efficient solutions at scale.
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #amzn
Qualcomm (QCOM) wants a seat at that table. The company just landed a major multi-generational collaboration with Amazon (AMZN) to supply customized silicon, systems, and related technology for large-scale AI data centers, with a focus on inference. The partnership also extends into high-speed optical connectivity, an increasingly critical piece of the AI infrastructure puzzle.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#customized #amzn


2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#cash
Achieved first-ever adjusted gross profit of $1.7 million, driven by a 400% revenue increase and the realization of economies of scale at the first recycling facility.
Improved operational efficiency by reducing cash spend on operations by 16% despite a fourfold increase in throughput, demonstrating a decoupling of volume from variable costs.
Secured a zero long-term debt position while increasing the cash balance to $49.5 million, providing a stable foundation for capital-intensive expansion projects.
Advanced the Tonopah Flats Lithium Project by receiving BLM certification for the plan of operations, marking the transition from pre-NEPA to the formal NEPA permitting process.
#cash

2 months ago
On August 25, Aptiv (NYSE:APTV) said it will support NVIDIA's newly announced Jetson Orin Nano 2 processor, extending a partnership that already covers the more powerful Jetson Thor platform. The move puts Aptiv squarely inside the buildout of "physical AI," the term for machines like drones, robots, and industrial systems that need to sense and react to the real world in real time. For a company still just months removed from spinning off its electrical distribution business, betting on edge robotics is a statement about where it thinks the next decade of growth actually lives.
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real
NVIDIA's Jetson Orin Nano 2 packs 78 TOPS of processing power into an 8GB, 8-core Arm chip that doubles the inference speed of its predecessor while cutting power draw by 40% at equivalent performance. That kind of efficiency gain matters for battery-powered devices like delivery drones and mobile robots, where every watt saved extends run time. Aptiv isn't just supplying compute support; it is layering in its PULSE surround-view camera and radar system for 360-degree sensing, its Gen 8 radar for object detection in tough conditions, and Wind River software to handle the unglamorous but essential work of long-term maintenance and security updates. That full-stack approach is the pitch: instead of stitching together sensors, chips, and software from separate vendors, customers get one partner who can carry a device from prototype to a fleet running in the field.
The timing lines up with what Aptiv reported in its second-quarter results on August 4, 2026. Revenue reached $3.3 billion, up 2%, while adjusted EBITDA climbed to $613 million from $547 million a year earlier, pushing margins to 18.7% from 17.1%. CEO Kevin Clark pointed to double-digit growth in non-automotive revenue, progress moving robotics from partnership talks to actual commercial deployments, and a major drone industry win secured in early July. North America sales rose 10% and Asia Pacific grew 6%, including 5% growth in China, giving the company some geographic momentum to lean on as it chases this new business line.
The quarter wasn't clean underneath the headline numbers. Free cash flow came in at just $12 million in the second quarter, down from $219 million a year earlier, and the first half of 2026 actually posted negative free cash flow of $196 million versus a positive $264 million a year ago. Operating cash flow from continuing operations fell to $82 million for the first half, down sharply from $531 million. Management also flagged automotive demand and customer mix as an incremental headwind, a reminder that Aptiv's legacy business still carries real weight even as it chases robotics and drones. EMEA revenue dropped 8%, and South America fell 4% in the quarter, both drags even as North America and Asia Pacific grew.
#America #real


2 months ago
Nokia stock surged 6% to $10.39 after its AI-RAN platform advanced to live field trials with eight global operators, delivering 20%+ spectral efficiency gains.
Ericsson's near-flat 0.7% move signals markets aren't pricing AI-RAN as a category-wide event, keeping today's rally a Nokia-specific story.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Nokia (NYSE:NOK) stock is rising in early Wednesday trading, up 6% to $10.39 after the company said its artificial intelligence-powered radio access network (AI-RAN) platform is moving from evaluation to live field trials at eight global operators. The list spans North America, Europe, Asia-Pacific and the Middle East, and it reframes AI-RAN as a shared industry priority rather than a single-vendor pilot. That geographic reach is what today's move is paying up for.
The move is Nokia-specific. The iShares U.S. Technology ETF (NYSEARCA:IYW) is unchanged at $250.08, and the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.4% to $760.33. Nokia stock is climbing while U.S. technology sits still and the broad benchmark is only marginally higher, which frames today as a name-specific catalyst.
#trials
Ericsson's near-flat 0.7% move signals markets aren't pricing AI-RAN as a category-wide event, keeping today's rally a Nokia-specific story.
Read More: Learn 7 secret wealth tips high net worth investors use that most investors miss (sponsor)
Nokia (NYSE:NOK) stock is rising in early Wednesday trading, up 6% to $10.39 after the company said its artificial intelligence-powered radio access network (AI-RAN) platform is moving from evaluation to live field trials at eight global operators. The list spans North America, Europe, Asia-Pacific and the Middle East, and it reframes AI-RAN as a shared industry priority rather than a single-vendor pilot. That geographic reach is what today's move is paying up for.
The move is Nokia-specific. The iShares U.S. Technology ETF (NYSEARCA:IYW) is unchanged at $250.08, and the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is up 0.4% to $760.33. Nokia stock is climbing while U.S. technology sits still and the broad benchmark is only marginally higher, which frames today as a name-specific catalyst.
#trials



