

17 hours ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ******* ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #credit #quarter #Portfolio

18 hours ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth

18 hours ago
On September 9, 2026, Signet Jewelers Limited (NYSE:SIG) reported second-quarter net profit of more than $52 million, reversing a net loss of over $9 million a year earlier, with adjusted earnings per share of $2.19 beating ***** yst estimates of $1.72 by a wide margin. It sent shares up as much as 24% in trading.
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited
The parent of Kay Jewelers, Zales, and Jared also raised its full-year profit guidance for the second time this fiscal year. It also extended its consumer credit partnership with Bread Financial through 2035, a deal it said includes new profit-sharing terms expected to make more than $1 billion in incremental value over time.
Signet Jewelers Limited (NYSE:SIG) is showing demand improvement across its core jewelry brands. Same-store sales increased 2.2% in the second quarter, beating Wall Street's 1.9% expectation. Management reported positive comparable sales across all three months of the quarter. Performance also improved across Kay, Zales, Jared, and Blue Nile. It shows the recovery extends beyond a single brand or temporary sales spike.
Margin expansion is allowing Signet to make substantially stronger earnings despite limited revenue growth. Adjusted operating margin expanded 140 basis points to 7%, while adjusted EPS reached $2.19, well above ***** ysts' $1.74 estimate. Stronger bridal and timepiece sales, tighter inventory management, and operating improvements helped Signet expand profitability. Redesigned Kay and Jared websites provide additional opportunities to back up digital sales.
Signet's higher earnings outlook and shareholder returns solidify the investment case. The company raised full-year adjusted EPS guidance to $10.45-$12.15 versus $9.20-$11.00 and plans a $125 million accelerated share repurchase program. Signet also extended its consumer-credit partnership with Bread Financial through 2035. It added improved technology and data ***** ytics while supporting customer financing and marketing capabilities over the long term.
#adjusted #jewelers #limited


19 hours ago
On September 4, 2026, the Wall Street Journal reported that Starbucks Corporation (NASDAQ:SBUX)' longtime chai latte devotees have turned against the company's reformulated recipe, introduced in March. It reduced sweetener and shifted from a pre-made concentrate to a new base with just two grams of sugar.
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer
Customers have signed petitions, flooded Starbucks' corporate lines, and taken to Reddit and store review sites demanding the original formula back. Starbucks says the change gives customers more control over sweetness and has introduced new variations like Mango Cream Chai and Pumpkin Cream Chai.
Starbucks Corporation (NASDAQ:SBUX)' broader turnaround remains intact despite the backlash over its chai reformulation. Global comparable sales increased 7.9% in fiscal Q3, with comparable transactions rising 4.2%. The company raised its fiscal 2026 adjusted EPS guidance to $2.55-$2.65 from $2.25-$2.45. Stronger customer traffic and higher earnings give investors evidence that one unpopular menu change has not derailed the recovery.
The chai backlash appears concentrated among loyal customers of one product rather than across Starbucks' broader customer base. The business introduced the new chai formula as part of a personalization strategy. Customers can customize sweetness and other ingredients. If Starbucks keeps transaction growth across its wider menu, the business could improve its product economics without materially damaging overall customer demand.
Starbucks is improving profitability while it executes its turnaround. Non-GAAP operating margin expanded 430 basis points year over year to 14.4% in fiscal Q3, while North America revenue increased 7% to $7.4 billion. These results give investors evidence that the company can improve margins and sales even as it experiments with its menu and customer experience.
#customer

19 hours ago
On September 8, 2026, Reuters reported that Paramount Skydance Corporation (NASDAQ:PSKY) said California Attorney General Rob Bonta made television statements that contradict his own legal arguments against Paramount's request for a $1.88 billion bond in the ongoing court fight over its roughly $110 billion acquisition of Warner Bros. Discovery, Inc. (NASDAQ:WBD).
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount
Bonta's office has argued the bond is unnecessary because Paramount voluntarily agreed to pause the deal's closing rather than wait for a court injunction. But Paramount described that same pause as equivalent to an injunction in media interviews, which it argues legally requires the states to post a bond under antitrust law. A hearing is scheduled for September 24.
Paramount Skydance Corporation (NASDAQ:PSKY) could protect a significant portion of its financial position if the court grants its $1.88 billion bond request. Paramount says the delay could cost it about $1.3 billion in fees to Warner Bros. Discovery shareholders by the time the case concludes in April 2027. A bond would give Paramount a potential path to recover those losses if it ultimately defeats the states' challenge. It reduces the financial damage from a prolonged legal process.
Warner Bros. Discovery, Inc. (NASDAQ:WBD) is receiving financial protection from the transaction's delay through Paramount's ticking fees. Paramount agreed to pay WBD shareholders approximately $7 million per day starting October 1 if the transaction does not close, creating a growing payment obligation for Paramount. It is also providing WBD shareholders with compensation for waiting. The arrangement gives WBD a financial benefit from the prolonged closing process even as the companies await a final legal resolution.
The legal dispute has not eliminated the strategic rationale for combining the two media companies. Paramount argues that the merger would strengthen the film and television industry and lead to more content while giving the combined company greater scale to compete with Netflix and Disney. For Paramount, completing the acquisition would speed up David Ellison's plan to build a larger media competitor. WBD shareholders would receive the transaction consideration rather than remain exposed to the company's standalone turnaround.
#paramount


19 hours ago
On September 3, 2026, lululemon athletica inc. (NASDAQ:LULU) reported second-quarter fiscal 2026 results for the period ended August 2, 2026. Net revenue fell 4% to $2.4 billion, missing the $2.46 billion ****** ysts expected, and comparable sales dropped 10% on a constant dollar basis. Management cut full-year revenue guidance to a decline of 5% to 7%, down from a prior forecast of flat to down 1%, and lowered full-year earnings per share guidance to $9.48 to $9.73 from its prior forecast of $10.95 to $11.15, compared with $13.26 earned in fiscal 2025. Shares fell about 18% in extended trading. Incoming CEO Heidi O'Neill was set to start the following week.
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ
Photo by Ian Deng Quddu on Unsplash
Citi's cut to $117 from $130 came with a Neutral rating and the observation that the stock's risk-reward is "slightly more favorable" after the selloff, even though the firm called fiscal 2027 visibility "very unclear." The operational bright spots are real.
lululemon athletica inc. (NASDAQ:LULU) increased its chase volume, the supply chain capability that lets it reorder fast-moving styles quickly, by about 20% this year, and away-from-body styles including the Groove Wide-Leg, Align Foldover Jogger, Breezily, and an updated Dance Studio Pant are trending well as shoppers shift from tight-fitting leggings. The brand's community pull held up too.
The SeaWheeze Half Marathon and Festival returned in August for the first time since 2019, drawing nearly 10,000 runners from 24 countries and roughly 14,000 festival attendees, while more than 85,000 people from 120 countries joined the companion Strava challenge, strong enough that Lululemon already committed to bringing the event back next summer. Rest of World revenue, spanning EMEA and APAC, grew 5% on a reported basis, and the company ended the quarter with $1.4 billion in cash and no outstanding borrowings.
#revenue #billion #NASDAQ

1 day ago
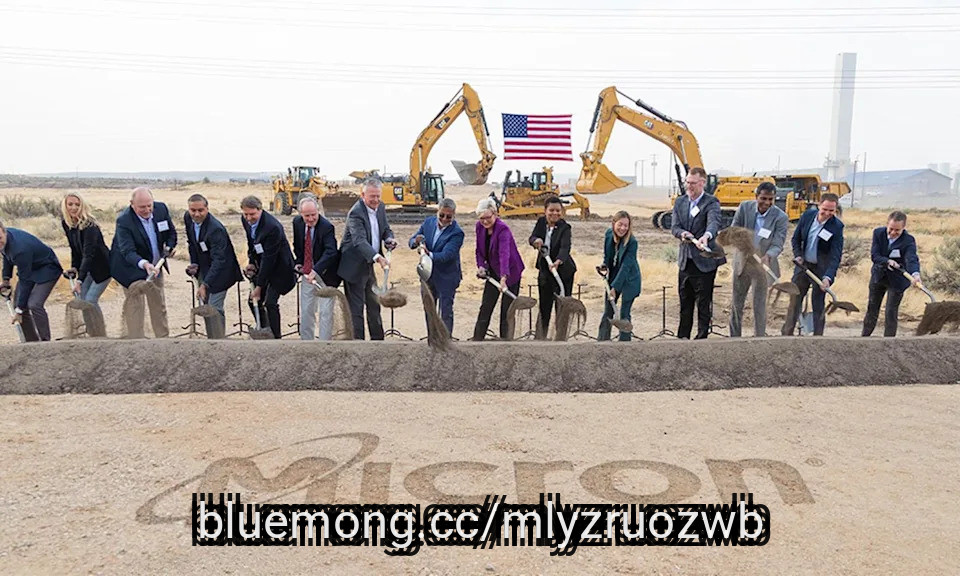
Microsoft's (NASDAQ:MSFT) fiscal 2026, which ended June 30, was arguably the strongest year in the software giant's history. Revenue grew 18% to $331.8 billion. Net income jumped 31% year over year, to $133.7 billion.
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter
Micron Technology (NASDAQ:MU) is approaching that number from a different direction. The memory specialist earned $8.5 billion in its fiscal 2025.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
But for the fiscal fourth quarter of 2026, which ended in early September, management guided to earnings of $30.73 per diluted share, plus or minus $1.00, on a generally accepted accounting principles (GAAP) basis. On about 1.15 billion diluted shares, the guidance works out to about $35 billion of profit in one quarter (about four times what the whole prior fiscal year produced).
Here's my prediction: In fiscal 2027, Micron will earn more than Microsoft. That means beating the year Microsoft is now in, not the one it just reported. It's a bold call, and it relies almost entirely on the price of memory.
#Microsoft #quarter

1 day ago
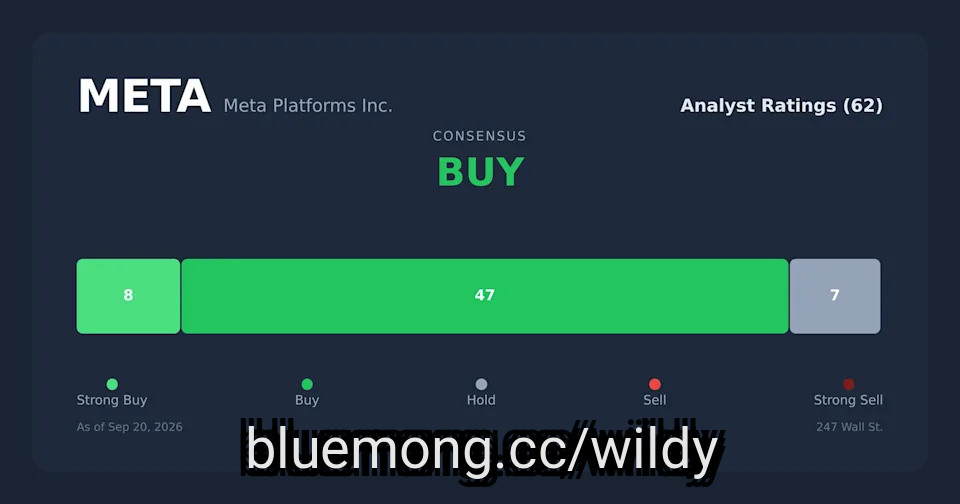
Helfstein estimates META needs 115 million paying Muse subscribers at $20/month to unlock $28 billion in AI revenue, but doubts it happens.
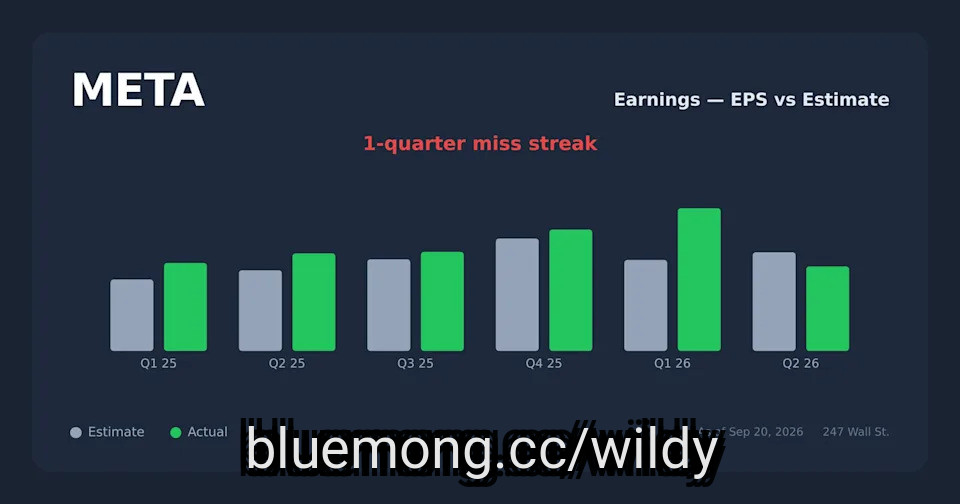
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million
META's Q2 operating margin collapsed from 43% to 31%, while full-year capex guidance soared to a range of $130 billion to $145 billion.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Meta didn't make the cut. Enter your email to see the names that beat METAPLATFORMS. The report is free. Enter your email and see if any of your stocks made the cut.
Jason Helfstein, Oppenheimer's Managing Director and Senior ******* yst covering the Internet sector, laid out a striking scenario in a September 2026 note: Meta Platforms (NASDAQ:META) would need roughly 115 million paying Muse subscribers at a $20/month price point to generate about $27.5 to $28 billion in annual AI agent revenue. His conclusion, however, was skeptical. For long-term investors, the math frames just how high the bar is for Meta stock to earn a consumer-AI premium on top of its advertising engine.
Ticker
#million
1 day ago
The 'half-a-loaf' plan gifts roughly half of excess ***** ets to children, then uses a Medicaid-compliant annuity to bridge the penalty period.
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly
Keeping retained cash in a bank account prevents the penalty clock from starting, since ***** ets above $2,000 disqualify the applicant outright.
One flawed annuity term or miscalculated divisor can unravel the entire plan, making elder law attorney guidance essential before any money moves.
Two retirees, same $1 million, same 4% rule, buy one finished with $1.4 million, the other hit $0 in 12 years. Our free reader guide explains the flaw that separated them, and the income-first method built to avoid it.
Picture a common scenario in a state where this type of crisis planning is welcome: Dad moves into a nursing home with roughly $200,000 sitting above the $2,000 countable-asset limit that most states use for single Nursing Home Medicaid applicants. His family gifts about $100,000 to the children, then uses the other half to buy a short-term Medicaid-compliant annuity that pays the nursing home while the gift penalty runs. When the penalty ends, Medicaid picks up the bill. The children keep the gift.
#annuity #roughly

1 day ago
Enbridge Inc. (NYSE:ENB) has declined by around 17% since hitting its record high in May, likely as a result of rising bond yields, lack of visibility on the company's 5% growth guidance through the end of the decade, and the recently closed equity offering intended to fund the midstream operator's strategic acquisitions.
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target
However, BMO Capital sees this pullback as an opportunity and on September 15, the firm upgraded ENB from 'Market Perform' to 'Outperform', while also slightly raising its price target from C$79 to C$79.50. The target boost implies an upside of 18% from the current levels.
The **** yst believes that Enbridge's scale, limited commodity exposure, and diversified **** ets are underappreciated. BMO also cited the company's improving visibility on growth, robust backlog, opportunistic acquisitions, and improved balance sheet as reasons behind the upgrade.
Enbridge's aggressive expansion strategy adds significantly to its bull case. The company announced on September 9 that it would acquire Tallgrass Energy's crude oil business for $2.55 billion in cash, expanding its US liquids pipeline network by buying a majority stake in the Pony Express Pipeline and other **** ets. The midstream operator expects the acquisition to be accretive to distributable cash flow per share in the first full year of ownership.
Similarly, Enbridge announced last month that it had agreed to acquire Salt Creek Midstream's crude oil gathering business for $600 million in cash, further bolstering its presence in the prolific Permian Basin. The acquired **** ets have an average remaining contract life of about 10 years, providing stable long-term cash flows.
#visibility #target

1 day ago
On August 6, Targa Resources Corp. (NYSE:TRGP) reported a record second quarter. Adjusted EBITDA reached $1.60 billion, a 38% jump from the same period a year earlier, and management now expects full-year results near the top of its guidance range. Targa moves and processes natural gas and natural gas liquids out of the Permian Basin, and these numbers suggest that system is running fuller than ever.
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record
The strength came from volume, not just price. Adjusted EBITDA also climbed 14% from the first quarter, helped by Permian gas volumes that added over 450 million cubic feet of daily throughput. Some producers held back output because Waha gas prices went negative, and Targa still set a volume record. Volumes for NGL pipelines, fractionation, and LPG exports also hit records, helped by Train 11, a new fractionator in Mont Belvieu, Texas, that started up early in the quarter.
Construction is also landing on time. East Driver, a new processing plant serving the Midland side of the Permian, started up late in the quarter and ahead of schedule, and the other gathering and logistics projects are tracking their plans. Shareholders get a cut too. On July 16, Targa declared a $1.25 per share quarterly dividend, 25% above the payout for the second quarter of 2025, payable August 14 to holders of record on July 31. It also spent $80 million buying back shares during the quarter.
Growth at this pace costs real money. Targa plans about $4.5 billion in net growth spending this year, and its consolidated debt stood at $19,578 million on June 30. About $3.2 billion of liquidity gives it a cushion. In July, it also extended its receivables securitization facility to July 30, 2027 and raised the size to as much as $800 million. More borrowing capacity helps, but it is still borrowing.
Not every dollar of the profit surge is as steady as a pipeline volume. Management tied the higher outlook partly to strong marketing margin and optimization work in the first two quarters, and the quarter's jump in marketing margin came from greater optimization opportunities. That kind of income can be lumpy. Meanwhile, lower natural gas prices trimmed margins in the gathering business, and the Waha curtailments showed that producers can pull back when local prices turn ugly.
#record

1 day ago
On September 17, Ferrari N.V. (NYSE:RACE) announced a partnership with the technology company Rakuten Group, Inc., effective January 1, 2027. The announcement gives no scope and no price tag, so it works better as a signal than as a number. The real substance sits in the results Ferrari posted on July 30, when it raised its 2026 guidance because buyers are ordering more personalization than the company expected.
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
In the second quarter, revenue rose 8%, but operating profit rose 10%, which means each euro of sales is leaving more behind. Ferrari credits a richer mix of cars, with the F80 helping, along with more buyers paying up for personalization. Strip out currency swings, and the gap widens, with revenue up 11% and operating profit up 16%. Deliveries of the Purosangue and the 296 Speciale family grew even in the middle of a planned model changeover.
Cash and demand back that up. Industrial free cash flow jumped 39% to €276 million, and Ferrari also returned more than €800 million to shareholders through a dividend and buybacks. Racing helped too, as higher sponsorships and engine rentals to other Formula 1 teams lifted revenue. Meanwhile, the order book covers 2027 in full, and the new 12Cilindri Manuale is already fully allocated, which is about as strong a demand signal as a carmaker can send. Those trends are why revenue guidance moved up to about €7.60 billion from about €7.50 billion.
Part of the strength is timing. Operating profit got a boost from temporarily lower depreciation and amortization while Ferrari swaps out models, and the company says those charges will climb once the new cars enter production. Net profit also leaned on a 23.0% tax rate, which reflects an estimated benefit from the new Patent Box. Neither says much about how profitable the cars themselves are.
Costs are climbing too. Higher industrial and marketing expenses weighed on operating profit, EBITDA margin slipped to 39.0% from 39.7% a year earlier, and management expects heavier brand, racing and digital spending for the year. Currency is a drag as well, mostly from the dollar and the yen, which is why 11% growth at constant currency shrank to 8% as reported. Deliveries totaled 3,366 cars while the 296 GTS, Roma Spider and SF90 XX family wound down, and sponsorship, commercial and brand revenue grew just 2%. And the whole outlook leans on current visibility into the Middle East crisis, which Ferrari cannot control.
#Ferrari
1 day ago
On August 10, Simon Property Group (NYSE:SPG) reported results for the three months through June 30 and raised its full-year profit outlook once again. Real estate funds from operations (FFO), a cash-flow measure suited to landlords, hit $3.29 per share. Tenants are earning more from their stores, and management is confident enough to lift its guidance again. Yet the professionals who own the stock are heading the other way.
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate
Start with the tenants, because they pay the rent. Reported retailer sales reached $838 per square foot over the year through June 30, up from $736 a year earlier, on June 30, 2025. Stronger sales tend to make higher rent easier to swallow, and base minimum rent per square foot did climb to $62.42 from $58.70.
That demand flowed through to profit. Real estate FFO rose to $3.29 per diluted share from $3.05, and net operating income at Simon's domestic properties grew 8.5%. Management responded by lifting its full-year real estate FFO range to $13.20 to $13.30 per share, moving the midpoint up by $0.08.
Shareholders get paid while they wait. The board declared a third-quarter dividend of $2.25 per share, $0.10 more than a year ago, to be paid on September 30 to anyone on the books by September 9. Simon also put $211.4 million into buying back stock at an average of $205.10 per share, and it finished June with about $9.3 billion of liquidity.
Now the less flattering side. Net income for common stockholders was $483.1 million, or $1.49 per diluted share, versus $1.70 a year earlier. The 2025 quarter included a non-cash gain of $0.21 per share from investment activity, which flatters that comparison. Still, plain FFO followed the same path, slipping to $3.12 from $3.15.
#Share #year #june #estate

1 day ago
On August 20, Royal Caribbean Group (NYSE:RCL) said it had completed a sale of $1.25 billion of notes that carry a 5.55% coupon and come due on January 20, 2034. The money is earmarked first for floating-rate term loans, with anything left over used to repay or refinance other debt, and the offering rode on a shelf registration filed on February 29, 2024. That sounds like routine upkeep. But next to an earnings beat and a flat third-quarter pricing outlook, the deal gives you a handy lens on where the company stands.
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
Start with the debt itself. Swapping floating-rate borrowings for notes with a stated 5.550% coupon takes some interest-rate guesswork out of the picture, and the notes don't mature until January 20, 2034. That matters because $2.7 billion comes due in 2027 and $3.4 billion in 2028. Against those bills, the company held $6.9 billion of liquidity as of June 30, and it added $250 million to its revolving credit line in July.
The business generating the cash is running well. On July 28, Royal Caribbean reported second-quarter adjusted earnings of $4.21 per share, ahead of its own guidance on stronger last-minute demand, lower costs, and better results from joint ventures. Management then raised full-year adjusted EPS guidance to a range of $17.73 to $17.87, which implies 14% growth. It also kept returning cash to shareholders in the second quarter, through $404 million of dividends and $199 million of buybacks. Booking volumes are running above last year, and 2027 bookings are tracking ahead of past years, even on routes that geopolitical events hit in 2026.
Beat or not, that $4.21 is still below the $4.38 from the same quarter in 2025. Costs excluding fuel per passenger cruise day rose 4.4%, and the cost beat came largely from the timing of expenses. Then there is pricing, where the story gets less rosy. Third-quarter net yields are guided to roughly flat against 2025 while capacity grows 8.5%, so the expected 8% revenue growth comes from more capacity, not from better yields. Management also says prolonged geopolitical activity has dented bookings on select itineraries. It calls the hit modest, but it is now built into guidance.
The refinancing also doesn't shrink the debt pile. New notes pay off old borrowings, so the total owed stays roughly where it was, and the company still expects net interest of $980 million to $990 million this year. Add roughly $4.7 billion of capital spending in 2026, mostly for new ships and destination projects, and it is clear this business needs a steady supply of capital. The April ship orders, Icon VI and Icon VII, extend that appetite, though their financing is already committed.
#billion #quarter #company #year
1 day ago
On August 6, Republic Services (NYSE:RSG) reported earnings of $1.84 per diluted share for the quarter that closed on June 30, up from $1.75 a year earlier, and lifted most of its full-year targets. Here is the odd part. The company moved less volume than it did a year ago and still grew profit. Understanding how that works, and how long it can last, is the whole story.
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year
Start with pricing, because that is the engine. Core price on total revenue added 5.3% to growth, which helped lift total revenue by 4.6%. Inside the related business, price contributed 4.1% in the restricted portion and 7.8% in the open market. Management says price beat cost inflation, and the margin backs that up. Adjusted EBITDA reached $1.42 billion at a 32.1% margin, matching the prior year even after Republic absorbed a 50 basis point drag from event-driven landfill volumes it received in 2025.
Cash generation is just as sturdy. Through the first half of 2026, operations produced $2.38 billion, and adjusted free cash flow came to $1.58 billion. That paid for $860 million of acquisitions and $1.04 billion returned to shareholders, so Republic is buying growth and rewarding owners from the same pool. The board added 4.5 cents to the quarterly dividend, setting it at $0.670 per share with an October 2 record date and payment on October 15. Management also raised full-year revenue, adjusted EBITDA, and free cash flow guidance, and set adjusted earnings at $7.23 to $7.28 per share.
The catch is that volume is moving the wrong way. Average yield added 3.4% to total revenue, while volume took away 1.6%, and the related business gave up 1.9% to volume. That makes this a price-led story, and price can only carry so much weight if volumes keep shrinking. Acquisitions also supplied 1.1% of the 4.6% total growth, so organic growth is smaller than the headline suggests.
Other lines were softer too. The environmental solutions business slipped 0.2%, so it added no lift. Recycled commodities sold for an average of $136 per ton at Republic's recycling centers, which is $13 lower than a year earlier. Margin only matched last year's level, and adjusted earnings per share rose 4.5%, just under revenue growth, so profit grew in step with sales rather than faster.
#year

1 day ago
NextEra Energy, Inc. (NYSE:NEE) has outlined its growth targets for 2026 and beyond. This comes as the company advances plans to acquire Dominion Energy Inc (NYSE:D). It's a $67 billion all-stock transaction expected to close before the end of next year. If the merger is completed as expected, it would result in the largest US electricity producer.
NextEra's business is already growing, and Dominion is expected to increase the growth rate. The deal's promise is exciting, but its value to investors ultimately depends on NextEra securing regulatory approvals and successfully integrating Dominion ***** ets.
NextEra Energy, Inc. (NYSE:NEE) has reaffirmed its 2026 adjusted EPS guidance of $3.92 to $4.02 and said it was targeting the high end of that range. NextEra also said it expects adjusted EPS to grow at a compound annual rate of at least 8% through 2032 and is targeting the same growth rate through 2035, off the 2025 base.
NextEra also plans to continue rewarding its shareholders with higher dividends. The company expects its dividend per share to grow at a roughly 10% annual rate through 2026, off the 2024 base. It expects the dividend to grow 6% a year through 2028 from the 2026 base.
The EPS and dividend growth projections give investors a financial foundation for evaluating the Dominion deal. NextEra does not need Dominion simply to prevent a growth slowdown. Instead, it's looking to add another growth engine through the acquisition.
#dominion #rate
NextEra's business is already growing, and Dominion is expected to increase the growth rate. The deal's promise is exciting, but its value to investors ultimately depends on NextEra securing regulatory approvals and successfully integrating Dominion ***** ets.
NextEra Energy, Inc. (NYSE:NEE) has reaffirmed its 2026 adjusted EPS guidance of $3.92 to $4.02 and said it was targeting the high end of that range. NextEra also said it expects adjusted EPS to grow at a compound annual rate of at least 8% through 2032 and is targeting the same growth rate through 2035, off the 2025 base.
NextEra also plans to continue rewarding its shareholders with higher dividends. The company expects its dividend per share to grow at a roughly 10% annual rate through 2026, off the 2024 base. It expects the dividend to grow 6% a year through 2028 from the 2026 base.
The EPS and dividend growth projections give investors a financial foundation for evaluating the Dominion deal. NextEra does not need Dominion simply to prevent a growth slowdown. Instead, it's looking to add another growth engine through the acquisition.
#dominion #rate
1 day ago
For custom chip designer Broadcom Inc. (NASDAQ:AVGO), the debate is all about whether the demand for AI products will sustain and grow. It is among the few firms capable of designing custom AI chips that big technology firms rely on to supplement NVIDIA's high-power and expensive AI chips. Anthropic CEO Dario Amodei's latest remarks about the need to slow down AI development due to safety concerns have generated quite a buzz, and Cramer discussed what Broadcom Inc. (NASDAQ:AVGO)'s CEO told him when asked about AI infrastructure development losing traction:
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong
"What's refuted by Hock Tan, of course, maybe Hock Tan is one of the biggest providers of semis, other than NVIDIA, and when I asked him about, give me a prediction about the AI slowdown, would there be one, he said, not in the least. We see the demand for compute infrastructure for development of AI and inference as extremely strong and durable. So I know those stocks were the most heavily hammered, other than the fiber stocks. But David, when you listen to what Hock Tan said last night on Mad Money, you are inclined to do buying.
"I think David, you recognize, and a lot of people don't, when you're speaking about Hock Tan, whom I had on, you're talking about a 1.6 trillion dollar company. This isn't just someone. . .worried about what orders are going to be. . .this man has more orders than almost anybody other than Jensen Huang. So I think Carl, when we get very, very negative we still have to rely on the facts And the facts do not support there are some people who are very worried about mankind, I did not get the mankind worry when I spoke yesterday."
The CNBC TV host's remarks about Broadcom Inc. (NASDAQ:AVGO) sit right at the center of the debate for the firm. This debate is about whether it will be able to continue to capture additional orders for custom AI chips. Looking at the third quarter earnings, released on September 2nd, the growth narrative appears to be quite strong.
It boosts Cramer's claims of Broadcom Inc. (NASDAQ:AVGO) experiencing strong orders, as during the quarter, the firm's revenue grew by 86%, AI semiconductor revenue jumped by 221% and fiscal year 2026 guidance implied 186% annual AI revenue growth. Not to mention, CEO Tan reaffirmed that Broadcom Inc. (NASDAQ:AVGO) could pull in $115 billion in annual AI chip sales in 2027 and a whopping $230 billion in 2028.
#orders #debate #strong


2 days ago
Super Micro Computer (SMCI) stock rose 9.5% on Thursday, September 17, closing just over $40. The move followed a bullish call on how big the market for AI servers gets. That call may well be right. But it answers a question Super Micro's own results never raised. That is why one big session tells you less than it looks like it does.
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast
Analysts at Goldman Sachs said the addressable market for AI servers will expand aggressively through the end of the decade. That is a forecast about an industry rather than about one manufacturer. Another account of Thursday morning's climb credited a broader equity rebound after Wednesday afternoon's Federal Reserve rate decision, not the forecast. Hewlett Packard Enterprise (HPE) jumped 8.0% the same day against the S&P 500's 1.1% gain, showing that capital was rotating heavily into primary AI server makers.
Company-specific headlines that day ran the other way: after the close, a shareholder rights law firm issued a press release soliciting clients for a potential investigation into company management.
A bigger market is not what this company is short of. In its fiscal fourth quarter, ended June 2026, Super Micro booked over $60 billion of new orders. That backlog underpins management's fiscal 2027 revenue guidance of $65 billion to $72 billion—up sharply from the $39 billion booked over the prior twelve months, but spread out as delivery and deployment constraints allow customers to take delivery.
What it is short of is customers ready to take delivery. Super Micro sells data center building block solutions, which bundle the servers with the power, cooling, networking and software around them. The company's manufacturing capability is on track to include more than 3,000 direct liquid-cooled racks a month.
#forecast

2 days ago
Volkswagen announced a steep cut to its full-year profit outlook on Friday, citing roughly €10 billion ($11.5 billion) in one-time charges concentrated at its troubled Porsche division, amid mounting pressure from U.S. tariffs and a weakening Chinese auto market on the world's second-largest automaker.
The company said it now expects an operating return on sales of up to 1% for 2026, down from its previous guidance of 4% to 5.5%. Volkswagen also said full-year revenue is expected to fall to about €315 billion, from €321.9 billion in 2025.
The bulk of the charges — about €6 billion — stem from revised mid-term ******* umptions for Porsche, in which Volkswagen holds a 75.4% stake. The sports car brand has been hit by U.S. tariffs and a collapse in demand for foreign luxury vehicles in China. On top of that, Volkswagen said it would book a further €2 billion in impairments in the second half of the year, covering China-related writedowns as well as restructuring charges such as costs from early-retirement schemes and the pending divestiture of its Osnabrück plant in Germany, according to The Wall Street Journal.
Volkswagen stock closed down 5.6% following the announcement. Shares of Porsche and Volkswagen's top shareholder Porsche SE fell 3.3% and 4.9%, respectively.
The company cautioned that "further deterioration in the market environment, especially in China, as well as an accelerated shift in demand in favour of battery-electric vehicles" would drag down results, with its Audi and Volkswagen passenger car brands bearing the brunt. Volkswagen noted that its outlook ******* umes tariffs remain unchanged and does not account for possible future effects from the war in the Middle East.
#charges #tariffs #full
The company said it now expects an operating return on sales of up to 1% for 2026, down from its previous guidance of 4% to 5.5%. Volkswagen also said full-year revenue is expected to fall to about €315 billion, from €321.9 billion in 2025.
The bulk of the charges — about €6 billion — stem from revised mid-term ******* umptions for Porsche, in which Volkswagen holds a 75.4% stake. The sports car brand has been hit by U.S. tariffs and a collapse in demand for foreign luxury vehicles in China. On top of that, Volkswagen said it would book a further €2 billion in impairments in the second half of the year, covering China-related writedowns as well as restructuring charges such as costs from early-retirement schemes and the pending divestiture of its Osnabrück plant in Germany, according to The Wall Street Journal.
Volkswagen stock closed down 5.6% following the announcement. Shares of Porsche and Volkswagen's top shareholder Porsche SE fell 3.3% and 4.9%, respectively.
The company cautioned that "further deterioration in the market environment, especially in China, as well as an accelerated shift in demand in favour of battery-electric vehicles" would drag down results, with its Audi and Volkswagen passenger car brands bearing the brunt. Volkswagen noted that its outlook ******* umes tariffs remain unchanged and does not account for possible future effects from the war in the Middle East.
#charges #tariffs #full
2 days ago
On August 10, Ferguson Enterprises Inc. (NYSE:FERG) reported results for the quarter ended June 30, and the numbers show a company growing straight through a soft housing market. Sales rose 4.6% to $8.8 billion, and management lifted its outlook for the full year. But profit grew more slowly than sales, and that gap is what makes this report worth a closer look.
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management
The strongest engine was non-residential work, where US revenue jumped 8% on share gains in what management called a mixed market. Large capital projects are part of the story, with open order volumes growing and bidding activity strong, so there is a pipeline behind the current numbers. Housing, roughly half of revenue, is the weak spot. Yet residential sales still rose 2% in the US even though new construction is weak and repair work is soft, which means Ferguson is beating its markets rather than riding them.
Capital deployment is the second pillar. Ferguson closed five acquisitions in the quarter, and on July 13, it announced a deal for FWI Holdings, known as FloWorks, an industrial distributor of valves and flow-control products that is expected to close in the third quarter. The eight deals announced this year carry about $1.4 billion in annualized revenue, a second growth path alongside organic sales. Net debt sits at 1.3 times adjusted EBITDA, a level management calls strong. The company also returned cash, buying back $202 million of stock in the quarter and declaring a $0.89 dividend payable October 7 to holders of record on August 21. Management raised its full-year sales outlook to mid-single-digit growth, before counting FloWorks.
Start with the gap between sales and profit. Adjusted operating profit rose 2.9%, behind the 4.6% sales gain, and gross margin slipped 20 basis points to 31.0%. Ferguson notes that last year's gross margin was temporarily lifted by the timing of supplier price increases, which is fair context, but the direction is still down. Reported earnings per share of $3.43 rose 6.9%, while the adjusted figure of $3.39 grew a slower 5.3%.
Then there are the soft spots. About half of revenue comes from residential markets that management describes as subdued, so a 2% gain there is modest. Canada's sales slipped 1.9%, with a business divestment outweighing organic growth, and management calls the market there challenging, especially in residential. Management also describes the economic environment as uncertain, and the margin part of the guidance raise is small. The low end of the adjusted operating margin range moved from 9.4% to 9.5%, while the top stayed at 9.8%. The guidance also leaves out FloWorks, and net debt to adjusted EBITDA is 1.3 times, against 1.2 times a year ago.
#management

2 days ago
For the recently reported second quarter, PicS N.V. (NASDAQ:PICS) outperformed relative to its previous guidance across all profitability metrics. The total account base for the company went up to 70.4 million during the second quarter, showcasing a 10% jump from the prior year. Moving on to the bottom line figures, the adjusted earnings before tax, without factoring in costs ****** ociated with stock-based compensation came in at R$291 million for the quarter. This represented a 2.1% outperformance relative to the company's R$285 million guidance. Similarly, compared to the R$245 million projection, adjusted net income for the period actually stood 15.5% higher at R$283 million.
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total
welcomia/Shutterstock.com
The second quarter concluded with strong financial and operating momentum for PicS. The company recorded a 9% annual and 2% sequential growth in its client base, which went up to 45.4 million active users. The total credit portfolio jumped to R$31.9 billion, exceeding management's guidance by 3%. This outperformance came due to a higher number of mature credit card cohorts, and accelerated origination within secured and partly secured categories. An additional factor that accounted for the credit portfolio growth was management's measured expansion into higher risk areas such as newer platform credit and private payroll lending.
Managerial revenue rose to R$3,730 million, topping guidance by 3.6%, and net interest income reached R$2,002 million, 5.4% above projections, boosted by growing credit income. Total cash in totaled R$136.4 billion, up 17% from a year earlier and 9% from the previous quarter, with customers bringing in an average of approximately R$45.4 billion to the platform each month. Total deposits climbed to R$35.8 billion, a 45% yearly jump and 10% quarterly rise.
Some concerns related to the company's loan portfolio emerged during the quarter. Non-performing loans more than 90 days overdue increased to 9.8% of the credit portfolio during the quarter, up 93 basis points sequentially. Stage 3 exposure, which includes a broader set of credit-impaired loans, reached 12.9% of the total credit portfolio.
#million #total

2 days ago
Interested in Ally Financial Inc.? Here are five stocks we like better.
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis
Ally Financial reaffirmed its full-year net interest margin guidance of 3.6% to 3.7%, supported by balance-sheet growth in higher-yielding retail auto and Corporate Finance loans. However, about $20 million in third-quarter lease losses tied to recalled Stellantis vehicles is expected to keep sequential margin growth roughly flat.
Stellantis-related lease pressure is expected to persist through 2026 but ease in 2027 as Ally's lease portfolio becomes more diversified and protected leases begin to mature. Ally also reaffirmed its 2026 retail auto net charge-off guidance of 1.8% to 2%.
Ally reported growth across its core businesses, including a 7% year-over-year increase in deposit customers and roughly 25% loan growth in Corporate Finance since launching Focus Forward. The company maintained guidance for 3% to 5% average earning-asset growth and approximately 1% operating-expense growth while continuing capital returns.
OneMain's Yield Comes With a Catch
#year #stellantis


2 days ago
PLTR trades near $176 and a $5,000 stake could grow to $8,162 in the bull case or fall to $4,629 in the bear case by 2031.
Palantir posted 93% revenue growth in Q2 2026, raised full-year guidance to $8.15 billion, and hit a Rule of 40 score of 155.
A P/E near 250 and beta of 1.6 mean any growth stumble or government budget shift could rapidly compress the stock toward the bear case.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Palantir didn't make the cut. Enter your email to see the names that beat PLTR. The report is free. Enter your email and see if any of your stocks made the cut.
Palantir Technologies (NASDAQ:PLTR) has become one of the most closely watched names in enterprise AI, riding a wave of sovereign-AI demand that pushed U.S. commercial revenue up 149% year-over-year in the second quarter of 2026.
#year #bear #Growth
Palantir posted 93% revenue growth in Q2 2026, raised full-year guidance to $8.15 billion, and hit a Rule of 40 score of 155.
A P/E near 250 and beta of 1.6 mean any growth stumble or government budget shift could rapidly compress the stock toward the bear case.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and Palantir didn't make the cut. Enter your email to see the names that beat PLTR. The report is free. Enter your email and see if any of your stocks made the cut.
Palantir Technologies (NASDAQ:PLTR) has become one of the most closely watched names in enterprise AI, riding a wave of sovereign-AI demand that pushed U.S. commercial revenue up 149% year-over-year in the second quarter of 2026.
#year #bear #Growth
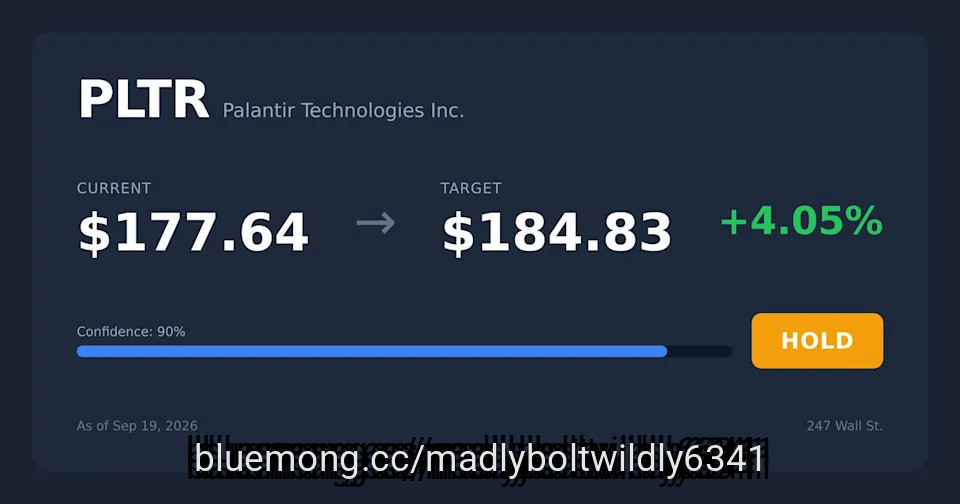
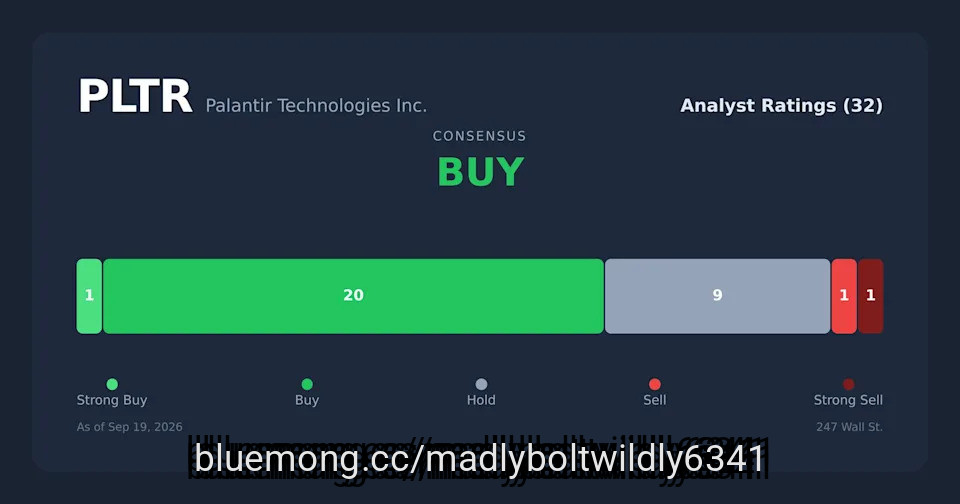

2 days ago
Amgen (AMGN) yields 2.6% with a $10.08 annualized payout, topping Merck (MRK) at 2.29%, and has raised its dividend 6% annually versus Merck's smaller step-ups.
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen
Amgen's 17 billion-dollar products and $3.5B quarterly free cash flow dwarf Merck's reliance on a single Keytruda franchise facing peak penetration.
Merck absorbed a $5.7B acquisition charge that pushed Q2 earnings to a loss, while Amgen raised 2026 EPS guidance to as high as $23.50.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Merck didn't make the cut. Enter your email to see the names that beat MRK. The report is free. Enter your email and see if any of your stocks made the cut.
For a retirement portfolio that leans on pharma dividends, the choice between Amgen (NASDAQ:AMGN) and Merck (NYSE:MRK) comes down to one question: which check is more likely to keep getting bigger through the next wave of patent expirations? Both companies deliver quarterly income today. Only one has the coverage, the growth cadence, and the portfolio breadth to keep raising through the cliff.
#merck #amgen


2 days ago
The State Department's approval of two potential arms sales to Saudi Arabia totaling $5.75 billion, including JDAM-ER munitions and AGT-1500 tank engines, offers a modest but meaningful data point for two very different defense players. For The Boeing Company (NYSE:BA), the potential sale represents an additional international defense opportunity as the company continues working through margin pressure elsewhere. For Honeywell Aerospace Inc. (NASDAQ:HONA), the package reinforces a stable business line while the firm tackles its first quarter as a standalone public company.
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi
The State Department approved a potential $5 billion sale of JDAM-ER guidance kits and bombs to Saudi Arabia, along with a separate potential $750 million deal for AGT-1500 tank engines. The JDAM package consists of 5,004 KMU-572 and 5,000 KMU-556 JDAM guidance kits and 5,004 BLU-111 and 5,000 BLU-117 bombs. Boeing has been identified as the principal contractor for the JDAM-ERs, with Honeywell handling the engines. The State Department said the sales would strengthen Saudi Arabia's airborne defense capabilities and improve interoperability with U.S. and Gulf partner forces.
Boeing stands to gain only modestly from the deal, given its roughly $85 billion Defense, ******* e and Security backlog. International orders already account for 27% of that total. The segment reported a second-quarter operating loss, largely due to charges tied to the VC-25B (Air Force One) program. That makes mature, lower-risk munitions programs such as JDAM-ER a more dependable part of the portfolio, though the deal is unlikely to have a meaningful impact on margins. For Honeywell Aerospace, the contract is smaller, but the AGT-1500 fits within its established defense propulsion business. It also adds to the company's international defence business, which makes up about 30% of its total Defense and ******* e revenue.
Honeywell Aerospace is owned by 74 hedge funds as of Q2 2026, which is consistent with Honeywell (NASDAQ:HON) hedge fund ownership prior to the spinoff. Unlike Honeywell, the number of hedge funds holding Boeing stock dropped from 99 at the end of the first quarter of fiscal 2026 to 90 at the end of Q2 2026.
Neither potential sale is large enough to have a meaningful impact on either company's short-term results by itself. Still, each supports a different investment story. For Boeing, the potential sales add to international defense exposure if finalized, as its defense unit continues dealing with fixed-price losses. For Honeywell, they support the steady flow of high-margin legacy revenue across its broader defense franchise.
#international #saudi

2 days ago
On August 6, James Hardie Industries (NYSE:JHX) reported results for the quarter ended June 30 and beat its own numbers by enough to raise guidance just three months into the fiscal year. Net sales jumped 64% year over year to $1.475 billion, adjusted EBITDA climbed 79% to $422.1 million, and both figures came in ahead of what management had originally guided investors to expect. For a company that closed a transformative acquisition less than a year earlier, that kind of overshoot forces a reassessment of the growth story ahead.
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management
The headline growth number is inflated by the AZEK Exteriors deal folded into the base, so the more telling figure is the 12% pro forma net sales growth, which also beat original guidance. Siding & Trim, the core fiber cement business, posted organic net sales growth of 20% as North American fiber cement volumes returned to growth for the first time in several quarters. CEO Aaron Erter tied that to share gains against vinyl and other competing materials, along with programs like ColorPlus and Expanded Statement drawing more of the higher-end repair and remodel market. Adjusted EBITDA margin in that segment expanded 140 basis points to 33.5%, powered by favorable pricing, cheaper raw materials, and continued savings from the company's Hardie Manufacturing Operating System even as freight costs rose.
Management also said cost synergies from the AZEK integration are running ahead of schedule and revenue synergies are on track, evidenced by newly expanded nationwide distribution partnerships with Boise Cascade and other regional distributors. In Deck, Rail & Accessories, sell-through accelerated every month of the quarter and outpaced shipments, pulling channel inventory back to normal levels and setting up a cleaner back half of the year. Free cash flow more than doubled to $254.2 million, and the company used the cash to pay down $400 million of senior unsecured notes.
Erter was careful to frame the beat as execution rather than a healthier market, telling investors the company is "not ***** uming a housing market improvement" for the rest of fiscal 2027. Part of the quarter's strength came from an easy comparison, since channel inventory was deliberately reduced a year earlier, and management said that benefit is expected to moderate as the year goes on. Deck, Rail & Accessories net sales actually fell 5% on a pro forma basis because the company intentionally cut production to work down channel inventory, leaving the segment with an operating loss of $3.3 million for the quarter.
#Growth #sales #management


2 days ago
On August 6, APA Corporation (NASDAQ:APA) held its second-quarter earnings call, and one number stood out from the rest. The oil and gas producer is now holding its Permian oil production steady with four drilling rigs, half the eight it once estimated it would need. Adjusted production of 347,000 barrels of oil equivalent per day beat management's own guidance, free cash flow kept climbing, and the balance sheet is healing faster than planned. That combination is the story of the quarter.
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion
APA raised its full-year US oil guidance to 123,000 barrels per day, up from an original 120,000, while holding its capital budget at $1.3 billion despite higher diesel and other input costs. Management also lifted its cost-savings target to $500 million in annualized run-rate savings by year-end, up from the $450 million goal it set at the start of the year.
That flexibility is showing up in cash flow. Free cash flow hit $738 million in the second quarter, pushing the first half of 2026 past $1.2 billion, which topped what APA generated in each of the past three full years. The company returned $189 million of that to shareholders through dividends and the repurchase of 2.8 million shares at an average price of $35.26, continuing a streak of returning at least 60% of free cash flow to investors every year since 2021.
The balance sheet is moving just as fast. Net debt stood at $3.3 billion at quarter-end after APA repaid $752 million of bonds in the first half, including $673 million in the second quarter alone, cutting total debt by $2.3 billion since the end of 2024 and lowering annualized interest expense by roughly $175 million. Management now expects to hit its $3 billion net debt target in 2027, well ahead of the three- to four-year window it laid out when the goal was first announced.
Further out, APA is building option value beyond its core Permian and Egypt ****** ets. It agreed to acquire Savant Alaska for $70 million, picking up an airstrip, a dock, and a pipeline connection into the Trans Alaska system to support two exploration wells planned for 2027. In Uruguay, ENI signed on as a partner in Block 6, funding a significant share of the first exploration well while APA keeps 60% ownership. In Suriname, the GranMorgu project remains on budget for first oil in mid-2028.
#billion

2 days ago
On August 18, Amer Sports (NYSE:AS) reported second-quarter results that beat its own guidance and then raised the bar for the rest of the year. Revenue climbed 32% to $1.63 billion, adjusted operating profit nearly tripled, and every region and segment posted double-digit growth. Diluted earnings per share reached $0.18, up from a much smaller figure a year earlier. What stands out about August 18 is not just the size of the beat but how broad it was.
Technical Apparel grew 32% to $674 million, led by Arc'teryx and backed by a 17% omni-comp gain across owned stores and e-commerce. Outdoor Performance grew even faster, up 37% to $569 million, driven by Salomon Softgoods. Ball & Racquet Sports rose 24% to $390 million on the strength of Wilson Tennis 360. CEO James Zheng pointed to strong double-digit growth across every segment, geography, and channel as the reason for confidence in the outlook.
That confidence showed up in the numbers: Amer Sports raised full-year 2026 guidance to roughly 24% reported revenue growth, a gross margin of 60.5% to 61.0%, an operating margin of 14.2% to 14.5%, and diluted EPS of $1.27 to $1.30. The balance sheet backs up the reinvestment CFO Andrew Page described, with $573 million in net cash and $720 million in cash and equivalents at quarter-end.
Some of the second quarter's biggest numbers lean on a one-time tailwind. Gross margin expanded 710 basis points to 65.6%, but 390 of those points came from net tariff refunds. Operating margin's 820 basis point jump included the same 390-point benefit. The effect is largest in Ball & Racquet Sports, where adjusted segment operating margin rose 1,300 basis points to 17.2%, yet 970 of those points came from tariff refunds alone. Selling, general and administrative expenses rose 30% to $909 million, and on an adjusted basis SG&A grew 33%, faster than revenue itself.
Inventories climbed 19% year over year to $1,897 million. The guidance for the next quarter also points to a slower pace: third quarter revenue growth is guided at 18% to 20%, well below the 32% just reported, with gross margin guided down to about 59.0% and net finance cost alone guided to $15 million to $20 million, against roughly $85 million for the entire year.
#revenue #basis
Technical Apparel grew 32% to $674 million, led by Arc'teryx and backed by a 17% omni-comp gain across owned stores and e-commerce. Outdoor Performance grew even faster, up 37% to $569 million, driven by Salomon Softgoods. Ball & Racquet Sports rose 24% to $390 million on the strength of Wilson Tennis 360. CEO James Zheng pointed to strong double-digit growth across every segment, geography, and channel as the reason for confidence in the outlook.
That confidence showed up in the numbers: Amer Sports raised full-year 2026 guidance to roughly 24% reported revenue growth, a gross margin of 60.5% to 61.0%, an operating margin of 14.2% to 14.5%, and diluted EPS of $1.27 to $1.30. The balance sheet backs up the reinvestment CFO Andrew Page described, with $573 million in net cash and $720 million in cash and equivalents at quarter-end.
Some of the second quarter's biggest numbers lean on a one-time tailwind. Gross margin expanded 710 basis points to 65.6%, but 390 of those points came from net tariff refunds. Operating margin's 820 basis point jump included the same 390-point benefit. The effect is largest in Ball & Racquet Sports, where adjusted segment operating margin rose 1,300 basis points to 17.2%, yet 970 of those points came from tariff refunds alone. Selling, general and administrative expenses rose 30% to $909 million, and on an adjusted basis SG&A grew 33%, faster than revenue itself.
Inventories climbed 19% year over year to $1,897 million. The guidance for the next quarter also points to a slower pace: third quarter revenue growth is guided at 18% to 20%, well below the 32% just reported, with gross margin guided down to about 59.0% and net finance cost alone guided to $15 million to $20 million, against roughly $85 million for the entire year.
#revenue #basis

2 days ago
On September 15, Jazz Pharmaceuticals plc (NASDAQ:JAZZ) completed its acquisition of privately held Actio Biosciences for $820 million upfront, adding a clinical-stage epilepsy drug called ABS-1230 to its rare disease pipeline. The deal lands weeks after Jazz posted its highest quarterly revenue ever on August 3, and raised its full-year guidance, so a fresh acquisition now sits on top of a business that was already accelerating. The question for investors is whether that combination adds up to durable growth or just a bigger bill.
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta
ABS-1230 targets KCNT1-related epilepsy, a rare and hard-to-treat form of the disease. In an early clinical proof-of-concept trial, children who received the drug experienced meaningful seizure reductions, and preclinical testing showed it inhibited KCNT1 across every pathogenic mutation researchers evaluated, hinting it could work across the whole patient population rather than a narrow subset. The FDA has already granted ABS-1230 Orphan Drug, Rare Pediatric Disease and Fast Track designations, and accepted it into the agency's Rare Disease Evidence Principles process, a set of regulatory advantages that can speed a drug toward approval.
The acquisition also arrives while Jazz's existing business is firing on multiple cylinders. Second-quarter revenue climbed 16% year over year to $1.2 billion, the company's highest quarterly total on record, and management raised full-year 2026 revenue guidance to a range of $4.6 billion to $4.75 billion. Growth was not confined to one product. Xywav sales rose 13% to $471 million on 525 net new patients, Epidiolex grew 16% to $292 million, and Zepzelca jumped 42% to $106 million. Zanidatamab, sold as Ziihera in biliary tract cancer, also received Breakthrough Therapy designation from the FDA for a form of colorectal cancer, adding another avenue for the oncology franchise Jazz has been building beyond its epilepsy and sleep businesses.
None of that came free. The $820 million upfront payment for Actio lands on top of $4.4 billion in long-term debt that Jazz already carried as of June 30, even after the company used part of its cash to repay $1.0 billion of exchangeable notes that matured this year. Cash, equivalents and investments stood at $2.2 billion at that point, meaning the Actio payment alone accounts for a meaningful share of the company's liquid resources.
Jazz's recent history also shows how acquisitions can distort the bottom line before they pay off. A $905.4 million in-process research and development charge tied to the 2025 Chimerix acquisition pushed second-quarter 2025 GAAP earnings to a loss of $11.74 per share, and a smaller $77 million IPR&D charge from the AbCellera and Werewolf deals still dented second-quarter 2026 results. ABS-1230 itself remains early, with only proof-of-concept data in hand and no late-stage trial results yet. The portfolio is not without setbacks, either. Jazz is moving to voluntarily drop the second-line indication for Zepzelca in meta

2 days ago
On August 6, Millicom International Cellular (NASDAQ:TIGO) released its second-quarter 2026 results, and the numbers pulled in two directions at once. Revenue jumped 59.4% year over year to $2.18 billion, while Adjusted EBITDA crossed $1 billion for the first time in the company's history at $1.01 billion, up 58% from a year earlier. Yet net profit attributable to company owners fell 83.9% to just $109 million. Investors weighing this quarter have to decide which of those two stories actually describes the business.
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio
The headline figures are hard to ignore. Service revenue reached $2.04 billion in the quarter, up 60.1% year over year, while H1 2026 revenue climbed to $4.16 billion from $2.74 billion a year earlier, a 52.3% increase. Equity free cash flow hit a quarterly record of $327 million, up 50.1% from a year ago, and leverage actually fell to 2.73x even after Millicom absorbed acquisitions in Colombia, Ecuador and Uruguay. That combination, rising cash generation alongside falling leverage during an acquisition spree, is the kind of signal that tends to matter more than a single quarter's headline growth rate.
Management is backing that signal with cash. Millicom already declared a $3.00 per share dividend in May, to be paid out quarterly over the next 12 months, and on August 5, the board approved an additional interim dividend of $1.50 per share, split into two $0.75 installments due January 15, 2027, and April 15, 2027. The company also raised its full-year 2026 equity free cash flow guidance from at least $900 million to around $1.1 billion, while lowering its year-end leverage target from about 2.5x to below 2.5x. CEO Marcelo Benitez pointed to Ecuador and Uruguay as evidence the integration playbook works, saying both markets have reached margins and cash generation broadly in line with the Millicom average, with Colombia and Chile now showing early improvement on the same path.
Strip out the acquisitions, and the picture looks far less dramatic. Organic revenue growth was just 4.3% in the quarter and 4.2% for the first half, a fraction of the 59.4% and 52.3% reported figures. Most of what shows up in the headline number is Millicom buying its way to a bigger top line, not the existing business accelerating on its own.
The profit line raises a separate question. Net profit attributable to company owners dropped to $109 million from $676 million a year earlier, and the first-half figure fell 74.9% to $218 million from $869 million, even as EBITDA and cash flow set records over the same stretch. That gap between a surging EBITDA number and a collapsing bottom line is the kind of divergence that deserves scrutiny rather than a shrug. Capital spending is climbing too, up 51.2% to $234 million in the quarter and 48.8% to $426 million for the half, running well ahead of the organic growth rate it is meant to fund. And the balance sheet is still in motion: in July 2026, Bolivia took on five new local bank loans totaling roughly $44 millio
