9 days ago
(NEXSTAR) – The days getting shorter serve as a reminder that we’re barreling toward the end of our seasonal observation of daylight saving time, but the wheels may be in motion to stop that – a move more than a dozen states have been waiting to happen.
Earlier this year, the House passed the Sunshine Protection Act, which would make daylight saving time permanent throughout the U.S., with few exceptions. It’s been held up in the Senate since July but, now that the chamber has returned from recess, there’s a chance the legislation could be picked up.
If it can pass the Senate, the bill seems to stand a fair chance of becoming law, with President Trump already expressing support.
For more than a dozen states, this is the closest they’ve been in years to seeing some of their own legislation finally take effect. The U.S. hasn’t been this close to permanent daylight saving time since a version of the Sunshine Protection Act passed in the Senate in 2022 but fizzled in the House.
At present, states are only allowed to opt into year-round permanent standard time, as Hawaii and much of Arizona have done. But that hasn’t stopped 19 states from enacting legislation that would make daylight saving time permanent in their jurisdiction, pending approval from Congress.
#House


10 days ago
On September 15, Digital Realty (NYSE:DLR) made ServiceFabric MCP available, a software layer that lets AI agents design, monitor and troubleshoot network connections across more than 800 data centers, including third-party sites. That nudges a real estate company toward becoming a control panel for enterprise AI. It arrives after second quarter results reported on July 23, when Core FFO per share, the company's preferred earnings yardstick, excluding net promote rose to $2.13 from $1.87 a year earlier. Here is what the launch does, and what it has yet to prove.
The pitch is that enterprise AI needs more than servers. It needs power, cooling, and sovereign placement that software can control. ServiceFabric MCP handles four jobs: designing and provisioning connections, spotting capacity and watching live network health, managing access through OAuth 2, and handing troubleshooting to agents with links into chat and monitoring tools. It is also open by design. Customers do not have to live only in Digital Realty buildings or commit to a single AI model. An IDC research VP argues that public cloud interfaces alone cannot give enterprises enough control over data movement and policy, which favors providers that pair global reach with programmable interconnection. Digital Realty runs the system on its own AI workloads, and See All AI, a medical imaging developer, leans on the Boston campus and ServiceFabric to move large datasets quickly and securely.
The financial engine underneath is running hot. Renewal leases in the second quarter were signed at rates 25.4% higher on a cash basis, which shows customers will pay more to stay put. Signed leases waiting to start added up to a $1.9 billion backlog of annualized base rent at 100% share, so future revenue is already lined up. Management responded by lifting its 2026 Core FFO per share outlook, excluding net promote, to $8.15 to $8.20.
Start with what the launch has not shown yet. Digital Realty itself calls MCP an emerging standard, and ServiceFabric MCP is still being validated across internal, enterprise, and partner deployments. The announcement puts no dollar figure on what it could add to revenue, and the company describes it only as the first programmable surface of a larger architecture that may later stretch into ***** e, power and inventory. Until customers pay for this layer, it is a promising idea more than a line item.
Then there is the bill for the physical side. Digital Realty carried about $18.6 billion of debt at June 30, 2026, and its 2026 development spending outlook, net of partner contributions, now sits at $4.25 billion to $4.75 billion. The outlook also ***** umes new long-term debt priced at 4.5% to 5.5%, up from the earlier 4.0% to 4.5%. To help pay for growth, the company has sold roughly 13.5 million shares this year for about $2.5 billion, which spreads future earnings across more owners. And the quarter's headline flattered a bit: Core FFO per share of $2.65 included a $18

10 days ago
Nvidia (NASDAQ:NVDA) has constructed an artificial intelligence (AI) empire over the past few years. The company sells the world's most powerful AI chips, known as graphics processing units (GPUs), and an entire portfolio of related tools that are generating triple-digit growth and record levels of revenue.
Investors have piled into Nvidia stock to gain access to this incredible growth story, and so far, they've scored a major win. The stock has soared about 800% over the past five years. But, in recent times, investors have worried about one particular challenge: competition. Though Nvidia remains in the lead, a number of companies also sell AI chips -- and these products are becoming more powerful with each update.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ***** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
These players include chip companies like Advanced Micro Devices as well as broader tech giants like Amazon (NASDAQ:AMZN). All of this has prompted some investors to pause before getting in on Nvidia stock at this stage of the AI story. Nvidia stock has climbed about 14% this year, which isn't a big leap for this stock.
Just recently, however, some bright news emerged during Amazon's earning call. In fact, these 15 words from Amazon chief Andy Jassy may eliminate Nvidia's biggest risk.
#chips
10 days ago
Interested in Motorola Solutions, Inc.? Here are five stocks we like better.
Motorola Solutions expects broad-based growth, projecting 2026 gains of 10%–11% in mission-critical networks, about 11% in video security and about 15% in command-center software, supported by modernization of public-safety and federal infrastructure.
Silvus Technologies is becoming a major defense growth driver, with approximately $850 million in expected 2026 sales at current capacity. Motorola is expanding production, sales and R&D as demand grows for secure communications in contested environments and unmanned-systems operations.
D-Fend Solutions expands Motorola's counter-drone opportunity in public safety, airports, critical infrastructure and venues. The business was selected for a $1.5 billion U.S. Department of Homeland Security grant program and uses cyber-based technology to take control of and safely land threatening drones.
Motorola's $1.5B Bet to Own the Skies
#Growth #safety #infrastructure

11 days ago
Shoulder-season travel is giving some hotels opportunities to trade for longer and reduce their dependence on peak months. But additional demand only changes the investment proposition if those extra trading periods generate durable profit and improve the quality of annual cash flow.
Across parts of Europe, tourism demand is becoming less concentrated in traditional peak periods.
The shift should not be overstated. July and August still accounted for 31.1% of all EU tourist-accommodation nights in 2025, according to Eurostat. In highly seasonal markets, the concentration was much greater: 54.5% of Croatia's annual nights and 41.6% of Greece's occurred during those two months.
But demand is moving at the margins. The European Travel Commission reported stronger autumn demand in several markets in late 2025. In Hungary, for example, growth in international arrivals and nights during autumn exceeded summer growth.
For hotel investors, however, a longer potential travel season is only the starting point.
#season


11 days ago
On September 9, 2026, Reuters reported that U.S. Transportation Secretary Sean Duffy sent a letter to Ford Motor Company (NYSE:F) CEO Jim Farley criticizing the automaker's business relationships with Chinese battery maker CATL and Chinese automakers Geely and BYD as raising "profound concern."
It specifically flagged Ford's licensed CATL battery technology at its Marshall, Michigan plant, its joint venture with Geely in Spain, and its decision not to move Lincoln Nautilus production out of China until 2030. Ford responded that Duffy's letter was "a wrongheaded attempt to capture headlines," noting that it owns the Marshall plant, controls its operations, and employs the workforce there, unlike companies that simply import Chinese-made batteries.
Ford Motor Company (NYSE:F) can argue that its CATL partnership still solidifies U.S. battery manufacturing rather than becoming more dependent on Chinese imports. Ford owns and operates its Marshall, Michigan battery plant. It allows the company to manufacture batteries domestically while licensing CATL technology. That structure could help Ford expand its U.S. EV production capacity and reduce the need to import finished Chinese battery packs.
Ford's improving financial performance gives the firm more flexibility to manage the political pressure. The automaker raised its full-year adjusted EBIT guidance to $10 billion-$11 billion after second-quarter results exceeded expectations, with record Bronco sales and a stronger product mix supporting the improvement. Stronger operating earnings could give Ford more resources to adjust its battery strategy if policymakers impose more restrictions on Chinese technology.
The company's existing U.S. manufacturing footprint could become a competitive advantage if Washington tightens restrictions on Chinese automotive technology. Ford has already invested in domestic battery production instead of relying entirely on imported battery packs. Model e losses have narrowed for three consecutive quarters. If policymakers force automakers to cut Chinese supply-chain reliance, Ford can use its existing U.S. factories to adapt faster than rivals that depend heavily on Chinese parts.
#ford #catl #motor

11 days ago
Palantir Technologies (Nasdaq: PLTR) and Rocket Lab Corporation (Nasdaq: RKLB) are among the biggest climbers in the Roundtable 100 this week.
While Palantir climbed 30 places to No. 33, Rocket Lab rose 34 places to No. 45.
Published with TheStreet, the Roundtable 100 ranks 100 publicly traded technology growth ****** ets. The Blue Ribbon Committee ****** ysts score each ****** et on team, safety, value, innovation and market dominance, with the average forming its power ranking.
Committee member Sam Badawi said the ****** ysts moved Palantir from No. 67 to No. 33 after the AI giant's revenue growth accelerated from 85% to 93% year over year and adjusted operating margin widened to 62%.
"This continues to strengthen through AIP, Foundry, and the Ontology, which are becoming deeply embedded into mission-critical government and enterprise workflows," he remarked.
#NASDAQ #rocket #places #technologies

11 days ago
On September 9, 2026, Reuters reported that GE Aerospace (NYSE:GE) agreed to buy castings maker Consolidated Precision Products for $11.75 billion. It is its largest acquisition since becoming a standalone company in 2024, to secure the supply of the precision metal turbine-blade components that have been a persistent bottleneck across the jet engine industry. CPP is the world's third-largest maker of these parts. CEO Larry Culp called the capacity "mission-critical" as the company works through a backlog stretching into the next decade.
GE Aerospace (NYSE:GE) can use the acquisition to convert its massive backlog into revenue faster. The company's backlog exceeded $210 billion after its second-quarter results. It includes roughly $170 billion in commercial services and more than $30 billion in defense. The $11.75 billion acquisition of Consolidated Precision Products directly targets one of the supply-chain bottlenecks that has limited GE's ability to increase engine production. CPP supplies about one-quarter of GE's casting needs. It gives GE greater control over a critical manufacturing process and could help it meet deliveries tied to its long-term backlog.
Bringing CPP in-house could improve GE's production economics while reducing supplier dependence. Spare-parts delinquencies jumped 20% sequentially in the second quarter. It shows the ongoing operational impact of supply constraints. GE plans to apply its Flight Deck lean operating model at CPP to improve factory yields and machine utilization and reduce scrap and rework. The company expects the acquisition to generate about $200 million in net synergies and achieve double-digit return on invested capital by the fifth year. It gives investors a measurable path to stronger returns from the deal.
The acquisition makes GE's position solid in the next generation of engines. GE expects demand for airfoils to increase more than 30% by 2030 from 2026 levels. CPP's casting expertise could help GE bring new airfoil designs into production faster. The business also expects CPP to make roughly $2 billion in revenue in 2027. That combination gives investors a potential path to higher production capacity, faster technology development, and stronger long-term participation in commercial and defense aerospace demand.
GE Aerospace (NYSE:GE) must justify a nearly $12 billion investment, and investors already ******* ign a premium valuation to the stock. GE Aerospace trades at roughly 46 times forward earnings. It leaves investors with limited tolerance for execution problems or weaker-than-expected returns. The company will fund $7 billion of the acquisition with cash and finance the remainder with new debt. So GE needs CPP's earnings and operating improvements to make sufficient returns to support the purchase price and protect shareholder value.
#billion #backlog #supply

11 days ago
Michael Kliger, CEO of LuxExperience, said the luxury market is becoming increasingly polarized, with affluent customers continuing to spend heavily while middle-class shoppers pull back under inflationary pressure. He said the company is less concerned about total active customers, which are around 900,000, than about growing the small group of top customers that generate a disproportionate share of sales. He speaks with Romaine Bostick on "The Close."
#michael #becoming
#michael #becoming
12 days ago
XLE's put/call ratio hit 2.57, with the most crowded trade being a one-month put that only pays off if energy stocks drop 12%.
USO has surged 126% YTD, but $6 diesel and freight earnings warnings of 5 to 10% signal that high crude is becoming an economic drag.
If energy breaks, defensive rotation candidates XLP (up 10% YTD) and XLV (up 25% over one year) stand to benefit.
Read More: Avoid these 13 retirement mistakes before they derail your future (sponsor)
Energy is the year's best-performing sector, and on Wednesday the options market bet heavily that it is about to break. Volume in Energy Select Sector SPDR (NYSEARCA:XLE) options ran roughly 70% above normal, with more than twice as many puts as calls changing hands and nine of the ten busiest contracts on the day being puts. The single most crowded trade was a 57-strike put expiring one month out, a structure that only pays off if XLE falls roughly 12% from here. Our own full-chain read on XLE puts a live put/call ratio at 2.57, with ratios above 16 at the Sept. 23 expiration and above 13 at Sept. 25.
#above #call #ratio #trade

12 days ago
Saudi Arabia's oil supply crisis is rapidly becoming Europe's problem.
The September 10 attacks on Saudi Arabia's East-West Pipeline struck the system at multiple locations and damaged at least one pumping station, forcing Riyadh to shut down the Kingdom's critical alternative to the Strait of Hormuz.
The 1,200-kilometer Petroline can carry around 7 million barrels per day from Saudi Arabia's eastern producing regions to Yanbu on the Red Sea. Since the war effectively closed Hormuz, it has become one of the most important pieces of energy infrastructure in the world.
Kpler estimates the pipeline had been moving roughly 4 million bpd around Hormuz before the attack. A prolonged outage could ultimately threaten 3.5–4 million bpd of Saudi crude exports. The figure is below Petroline's nameplate capacity because Saudi Arabia can still export some crude from eastern terminals such as Ras Tanura, despite the severe constraints on Gulf shipping.
The immediate problem is storage.
#hormuz #crude

12 days ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
America's retirement bill is getting harder to ignore. Social Security is already the largest expenditure in the federal budget, and as more Americans reach retirement age, an increasingly large share of government spending is going toward older Americans. Podcast host and NYU Stern professor Scott Galloway thinks the imbalance is becoming a problem for everyone else.
"We now spend $5 on seniors for every $1 on children. Enough already," Galloway wrote in his "The Grown-Up Tax Bill" column in 2025. He argued that Social Security is part of a much larger transfer of wealth from younger and poorer Americans to an older, wealthier generation.
Don't Miss:
This Jeff Bezos-backed platform lets eligible investors buy fractional shares of rental properties for as little as $100.
#older
12 days ago
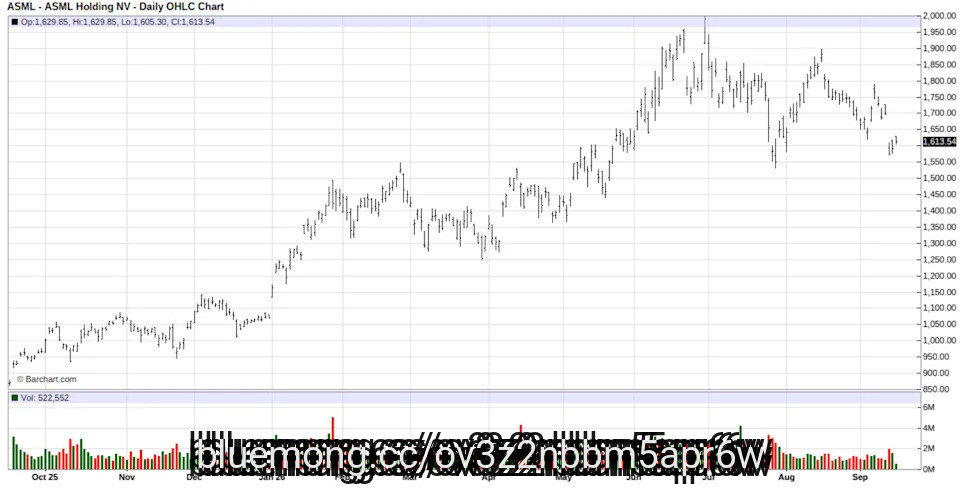
The U.S. has between 3,000 and 4,700 active data centers, with plans to build another 1,500. Globally, there are about 11,800, with plans to add about 100 gigawatts of new capacity by 2030. All of which creates substantial opportunity for beaten-down stocks such as ASML Holding (ASML). However, to run all of those data centers, the world needs advanced AI chips. Today's most advanced data-center AI processors, manufactured on 4nm, 5nm, and certain 7nm processes, depend heavily on ASML's lithography technology. And as the industry moves toward 2nm production, that dependence on ASML's EUV systems will become even more important.
Some of those companies include Samsung Electronics (SMSN.L.IX), Taiwan Semiconductor Manufacturing (TSM), and Intel (INTC). All of which are moving forward with ASML's High-Numerical Aperture extreme ultraviolet lithography systems, better known as High-NA EUV. In short, AI must have powerful chips to run. And those chips are becoming much harder to manufacture, with ASML producing the machines that make their production possible.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Dear Tesla Stock Fans, Mark Your Calendars for October 1
#asml #advanced #lithography

12 days ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude


12 days ago
Hewlett Packard Enterprise Company (HPE) is becoming a major beneficiary of the enterprise artificial intelligence (AI) infrastructure growth. While many companies are working on AI applications, Hewlett Packard primarily focuses on infrastructure, supplying servers, networking, and other technology essential for large-scale AI deployment.
The company's latest quarterly results showed rising demand, with both revenue and profit exceeding **** yst expectations and robust growth across all segments. Its integration of Juniper Networks has further strengthened the company's position in AI networking, giving the company greater access to the infrastructure needs driven by AI's rapid growth.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
How to Play GME Stock as GameStop CEO Ryan Cohen Buys $20.3 Million in Shares
#infrastructure #company #juniper


13 days ago
Tesla, Inc. (NASDAQ:TSLA) spent nearly two years raising anticipation for the Cybercab. When the time arrived on September 3 in Austin, the result was a stock that popped, then rapidly returned all of its gains, and a robotaxi race that still seems to be Alphabet's to lose.
Tesla, Inc. (NASDAQ:TSLA) had its long-awaited Cybercab launch event in Austin, Texas, but it was invitation-only, not livestreamed, and CEO Elon Musk wasn't there. The company's main public update was a 51-second video released on X of the two-seat, steering-wheel-free vehicle roaming city streets and people hailing it by app. Shares rose roughly 5% throughout the session, finishing near $376. By September 4, enthusiasm had waned, with the stock plummeting as much as 6% as investors realized how little the event revealed about deployment timelines, production ramp, or regulatory clearance.
Only 45 Cybercabs were registered in Texas, and Tesla, Inc. (NASDAQ:TSLA) did not seek an NHTSA exemption before deployment, instead self-certifying the Cybercab as compliant with applicable federal safety standards. NHTSA subsequently opened an audit into that certification and has ordered Tesla to provide additional information about the basis for its compliance claims. CNBC summarized the reaction bluntly: the update "underwhelmed" Wall Street, which had been relying on Tesla, Inc. (NASDAQ:TSLA) becoming a strong rival in the robotaxi sector, which Alphabet's Waymo currently leads.
That comparison is at the heart of the story. Waymo has established the operational track record that Tesla, Inc. (NASDAQ:TSLA) is still chasing: more than 4,000 autonomous vehicles across its U.S. fleet and more than 500,000 fully autonomous rides per week.
Wall Street's take on the incident was severely divided along those lines. Despite Tesla's efforts to control the narrative, some ******* ysts, including Gary Black of Future Fund, called the Cybercab debut largely a bust. Others, such as Deepwater ******* et Management's Gene Munster, predicted that Tesla, Inc. (NASDAQ:TSLA) will add approximately 300 Cybercabs in Austin over the next month.
#tesla #NASDAQ #cybercab

13 days ago
Liberty Media Formula One (FWONK) is increasingly looking like more than a fast-growing sports franchise — it is becoming a premium global media and entertainment ******* et. That view is gaining traction on Wall Street, with Jefferies initiating coverage of FWONK stock with a "Buy" rating and a $115 price target, implying about 22% potential upside from current levels. Jefferies views Formula One as a high-quality media and consumer-experiences business, supported by its premium sports ******* ets, ******* et-light model, and margin-expansion opportunity.
Jefferies believes that the company streamlining Formula One and MotoGP after the Liberty Live separation and MotoGP acquisition could improve how its allocates capital and executes. Moreover, ******* ysts highlighted Apple's (AAPL) new U.S. F1 media-rights deal for Apple TV, estimating it could add revenue of about $55 million annually through 2030. Overall, the firm expects revenue to grow to $5.84 billion in 2028, and adjusted OIBDA margins to expand to 27.2%.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#liberty


13 days ago
Eli Lilly (NYSE: LLY) has been on a historic run over the past five years, outperforming similarly sized peers in the pharmaceutical industry and becoming the first healthcare stock to reach a $1 trillion market cap. The company's diabetes and weight-loss portfolio has been the main engine behind its terrific performance of late, and it remains strong. During the second quarter, Eli Lilly's revenue jumped 48% year over year to $23 billion, while adjusted earnings per share rose 33% year over year to $8.38.
Sales from Eli Lilly's Mounjaro, a diabetes medicine, soared 91% year over year to $9.9 billion, while sales of Zepbound, approved for weight loss and obstructive sleep apnea, grew 46% to $4.9 billion. Can anything stop Eli Lilly's momentum? Here's one thing that might do so.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Eli Lilly generates most of its revenue from Mounjaro and Zepbound, which have the same active ingredient, tirzepatide, a medicine that mimics the action of the GLP-1 and GIP gut hormones. In the second quarter, sales from these two medicines accounted for almost 65% of the company's top line. Eli Lilly also markets Foundayo, an oral GLP-1 approved for weight loss, although it was approved in April and doesn't yet contribute much to its financial results.
Still, the point is that Eli Lilly's lineup is concentrated at the top, with just a couple of brands responsible for most of the recent momentum. Other pharmaceutical giants are well aware of Eli Lilly's GLP-1 success, and they are seeking to launch competing therapies.
#lilly #sales #loss #billion

13 days ago
What happened: Bitcoin (BTC-USD) fell 4% to hover below $76,000 on Tuesday.
What's behind the move: The world's largest cryptocurrency lost ground ahead of a Fed decision this week, and as the CLARITY Act struggled to clear a cloture vote in the Senate.
Hopes of securing the 60 votes needed to proceed faded ahead of the afternoon vote as Republicans and Democrats remained divided over the latest version of the bill.
Polymarket bettors gave the bill a 5% chance of becoming law this year. Investors now fear it will be shelved until after the midterm elections and potentially pushed to 2029.
The crypto market has been closely following the bill aimed at establishing a comprehensive federal framework for digital ****** et markets.
#bill #ahead #hopes
13 days ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and ******* ysis, subscribe to Bisnow's free suite of newsletters.
A pair of national real estate investment managers closed their U.S. office credit fund with $1.1B in investor commitments.
Hines and Rialto Capital secured 126 investors for their Hines Rialto Credit Partners, a co-general partnership focused on U.S. office credit investments. The fund required a minimum investment of $100K, according to a filing with the U.S. Securities and Exchange Commission.
With the rapid growth of private credit, Hines said it believes investors are searching for real estate credit strategies grounded in specialized underwriting and deep market knowledge.
"Yield alone does not tell you the quality of the risk," Alfonso Munk, Hines' global co-head of investment management, said in a statement. "In real estate credit, understanding the underlying ******* et — what it is worth, how it performs and how it may hold up under pressure — is becoming increasingly important as the market works through a significant refinancing cycle."
#real #rialto
13 days ago
Interested in NVIDIA Corporation? Here are five stocks we like better.
NVIDIA released CUDA-Q Logical, an open-source software layer that links GPUs with quantum processors to solve practical error correction challenges.
Early testing by Fermilab and Sandia National Laboratories shows dramatic efficiency gains, including a seven-fold faster design cycle and reduced physical qubit requirements.
Quantum hardware firms IonQ, Rigetti Computing, and D-Wave Quantum could benefit as standardized software lowers development costs and enables deeper integration with NVIDIA's infrastructure.
Many investors view quantum hardware developers and classical semiconductor leaders as competing forces in high-performance computing. Recent developments demonstrate that the two architectures are becoming deeply interdependent.
#hardware #here

13 days ago
Enova International Inc (NYSE:ENVA) withdrew regulatory applications for its planned Grasshopper Bancorp acquisition on Tuesday, sending shares sharply lower despite reaffirmed growth forecasts and plans for faster buybacks.
Shares fell 25% to $169.50 following the company's acquisition update.
The technology and ******* ytics company pulled applications with the Office of the Comptroller of the Currency and the Federal Reserve after reviewing the transaction and bank approval process.
CEO Steve Cunningham said withdrawing the applications was the best choice for Enova and its shareholders, adding that the company can keep growing without becoming a bank.
He argued that banking rules have not kept pace with the credit needs of consumers and small businesses that banks do not adequately serve.
#acquisition #bank #international

13 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and **** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#patients #weight #c


13 days ago
The Kroger Co. (NYSE:KR) cut its full-year 2026 identical-sales forecast excluding fuel to 0.2%–0.8% from 1%–2%, reflecting a sharper-than-expected slowdown in consumer demand. Second-quarter identical sales rose just 0.2%, down from 3.4% a year earlier and below the 0.9% ****** yst estimate.
The weakness reflects pressure on middle- and lower-income consumers, while a Cyclospora outbreak reduced quarterly identical sales by roughly 35 basis points and Medicare prescription-drug pricing changes created an approximately 140-basis-point headwind for pharmacy revenue. Importantly, Kroger maintained its full-year adjusted FIFO operating-profit forecast of $5.0 billion–$5.2 billion and delivered adjusted EPS of $1.09, ahead of the $1.06 consensus.
The strongest bullish argument is that The Kroger Co. (NYSE:KR) is currently protecting earnings despite the deterioration in sales momentum. Second-quarter adjusted EPS increased 5% year over year to $1.09, while adjusted FIFO operating profit was $1.076 billion. Kroger's gross margin rate actually increased by 13 basis points, although the overall gross-margin percentage was 22.4% versus 22.5% a year earlier, suggesting that pricing, sourcing, and cost-management initiatives are helping offset weaker volumes. The company's higher-margin businesses are also becoming increasingly important: adjusted e-commerce sales grew 20% in the quarter, and Kroger Precision Marketing profit increased 24%. That mix shift gives Kroger an earnings lever even when supermarket traffic and comparable sales are weak.
There is also evidence that management is actively responding to the competitive pressure rather than simply accepting slower growth. CEO Greg Foran has been pursuing tighter sourcing, simpler operations and lower prices, with Reuters reporting plans to cut prices across thousands of products to regain shoppers from Walmart, Costco and Aldi. The Kroger Co. (NYSE:KR)'s balance sheet provides room to fund that strategy: its net debt-to-adjusted-EBITDA ratio was 1.91x, below its stated target range of 2.30x–2.50x, while the company repurchased $1.0 billion of shares in the second quarter and $1.2 billion year to date. It also raised its dividend 11%, marking the 20th consecutive year of increases. If sales stabilize while e-commerce, retail media and cost efficiencies continue expanding, the unchanged $5.0 billion–$5.2 billion operating-profit forecast could prove more important to valuation than the reduced top-line outlook.
#year
13 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
13 days ago
White House chief of staff Susie Wiles is "cancer free," she announced on X on Sept. 16, 2026. "Some personal news I'm grateful to share. After a medical appointment at the Mayo Clinic this week, my pathology results came back clear," she explained.
Wiles was diagnosed with early-stage breast cancer in March and told the New York Times that her prognosis was "strong." Wiles did not disclose at the time what treatment she would undergo, but said it would last several weeks — during which time she planned to continue working. Noting that one in eight American women develops breast cancer at some point in their lives, Wiles posted on X at the time: "Every day, these women continue to raise their families, go to work and serve their communities with strength and determination. I now join their ranks."
A breast cancer diagnosis is life-altering, but Wiles's comments highlighted the progress that's been made in recent years. Breast cancer is now detected at Stage 0 or 1 — before it has spread — in the majority of cases. Survival rates have risen dramatically, but "the treatments we use to treat early-stage breast cancer have become more tailored" and less disruptive to women's lives, Dr. Lynn Dengel, a University of Virginia surgical oncologist, told Yahoo in March.
"Because [Wiles] was taking care of her health [and getting screened], not only will her prognosis be better, but it will probably minimize what treatment she has to go through and will benefit her work-life and overall balance," Dengel said. She added that most of her patients are diagnosed early and can continue to work while undergoing breast cancer treatment, reducing the financial burden and overall disruption to their lives.
Wiles was diagnosed at age 68 — slightly older than the median age (62) when most women learn they have breast cancer. More than 380,000 American women are diagnosed with some form of breast cancer each year, according to the American Cancer Society (ACS).
Breast cancer remains the most common form of cancer among women in the U.S., except for skin cancers. And rates are rising. But there's good news: More women are surviving the disease. Treatments have also improved, becoming tolerable enough that many women still work, as Wiles intends to do. Here's what to know about the disease, why rates are rising and how women can reduce their risks.
#breast #diagnosed


13 days ago
Eli Lilly and Company (NYSE:LLY) says its newly launched oral obesity drug Foundayo has captured more than 30% of new U.S. patients starting oral weight-loss medicines, a notable early gain against Novo Nordisk's Wegovy pill. Reuters reports that Wegovy initially held roughly 90% of the oral market, making Lilly's rapid share capture an important sign that the oral GLP-1 market is becoming a two-player competition rather than a Novo-dominated segment. The broader U.S. obesity-drug market is expected to exceed $100 billion annually by 2030, with oral treatments potentially accounting for more than one-third of GLP-1 use.
The timing is strategically important for Lilly because Foundayo was only launched in the U.S. in April 2026. The drug starts at $149 per month for self-pay patients and can cost as little as $25 for eligible commercially insured patients, while Medicare beneficiaries can access it through the GLP-1 Bridge program at $50 per month. Lilly's SEC filing says Mounjaro and Zepbound already represented 65% of its revenue in the first six months of 2026, highlighting both the importance of the incretin franchise and the opportunity for Foundayo to broaden Lilly's cardiometabolic revenue base.
The strongest bullish implication is that Foundayo appears to be overcoming the biggest behavioral barrier in obesity treatment: patients' preference for an oral medicine over an injection. Capturing more than 30% of new oral patients only months after launch suggests Eli Lilly and Company (NYSE:LLY) is establishing meaningful competitive positioning before the oral GLP-1 market fully scales. Foundayo's formulation also has a practical advantage because it can be taken at any time of day without food or water restrictions, while Lilly's clinical data showed an average 27.3-pound, or 12.4%, weight reduction at the highest dose among patients who remained on treatment in ATTAIN-1.
The commercial opportunity could become considerably larger if Foundayo gains indications beyond obesity. Lilly reported that in the ACHIEVE-3 trial, Foundayo produced a 57.1% greater relative reduction in A1C and a 73.6% greater relative reduction in body weight compared with oral semaglutide 14 mg. Lilly submitted Foundayo for type 2 diabetes in the U.S., EU, and ***** an, potentially expanding the addressable market beyond weight management.
The early oral-market traction also complements Eli Lilly and Company (NYSE:LLY)'s existing injectable franchise rather than simply cannibalizing it. A Lilly trial found that patients switching from maximum-tolerated Wegovy to Foundayo maintained all but 0.9 kg of their previous weight loss after one year, while patients switching from maximum-dose Zepbound to Foundayo maintained all but 5.0 kg. That suggests Foundayo could serve as a maintenance or lower-burden treatment within Lilly's broader obesity portfolio, increasing lifetime value per patient rather than limiting the opportunity to new prescriptions.
#weight
13 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#colgate #company #care

14 days ago
As the stock market rebounds, it's important to watch the stocks that are holding up and are most loved by equity ****** ysts. They may end up becoming the next big opportunities.
Amazon.com (AMZN), Alphabet (GOOGL) and Dell Technologies (DELL) are three of the seven best stocks where investors can find magnificent profit growth prospects. Investors should be seeking new buy opportunities after the S&P 500 climbed to new highs.
Amphenol (APH) is forming a cup-with-handle base with an 88.17 buy point, according to IBD MarketSurge pattern recognition. The stock, however, slipped below its 50-day moving average. A 2-for-1 stock split went into effect Sept. 2.
Shares gapped up July 29 after Q2 sales and earnings breezed past expectations on solid growth in the IT datacom market.
The company is one of the world's largest providers of fiber-optic and high-speed connectors, including cables and connectors for data centers. Data centers have become an important market for Amphenol as hyperscalers continue the aggressive expansion of AI infrastructure.
#amphenol #investors #data

15 days ago
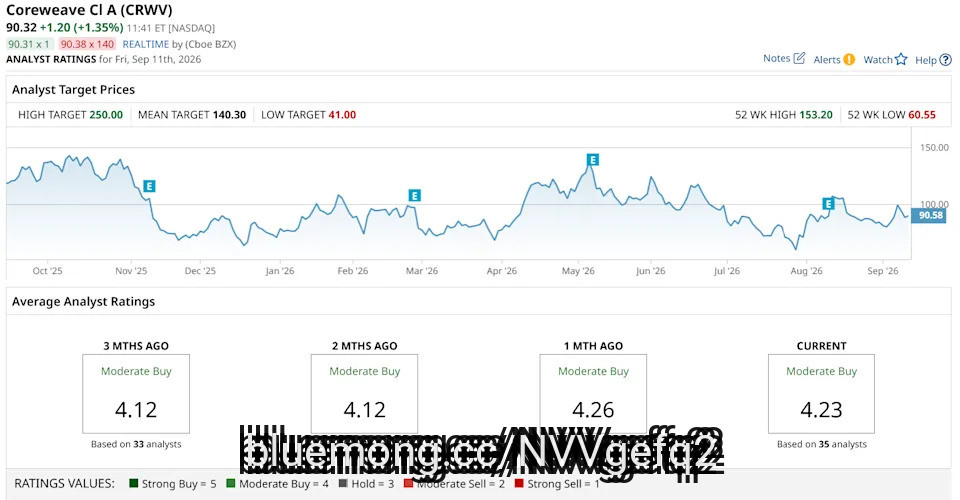
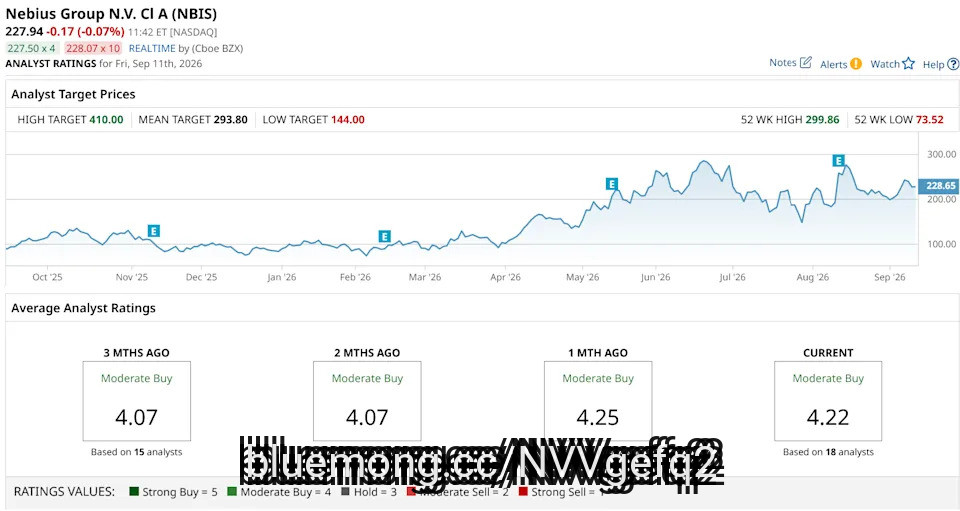
The artificial intelligence infrastructure race is moving from a chip shortage story into a race for something harder to manufacture: data center capacity. Land, electricity, and finished buildings are becoming the bottlenecks as hyperscalers pour hundreds of billions of dollars into AI. That is creating an opening for a new breed of cloud providers that can secure capacity where the largest cloud companies cannot.
At Thursday's Goldman Sachs Communacopia + Technology Conference, Nvidia (NVDA) CEO Jensen Huang made clear that he sees this market expanding for years—and his comments were particularly bullish for CoreWeave (CRWV) and Nebius Group (NBIS).
Dear ***** eX Stock Fans, Mark Your Calendars for September 21
How to Play IBM Stock as It Teams Up with NASA to Launch a New Open-Source Model
GF Securities Says NAND Prices May Stabilize Later This Year. What This Means for Sandisk Stock.
#capacity #land