
3 days ago
Google and Constellation Energy announced a 20-year power purchase agreement on Tuesday to bring 890 megawatts of new nuclear capacity onto the PJM Interconnection grid, with Constellation committing more than $4.3 billion to fund the build-out.
The capacity will be generated through turbine, steam generator, and digital control system upgrades at 11 Constellation nuclear units in Illinois, Pennsylvania, and New Jersey, the companies said. The first uprate is expected to be delivered by 2028. The agreement is expected to sustain roughly 4,400 existing jobs and create approximately 7,200 new construction jobs during the building period.
Alongside the power purchase agreement, the companies entered into a separate 15-year energy supply agreement covering an additional 2,700 megawatts from Constellation's existing fleet in the PJM market, the company said.
"We're committed to meeting our growth responsibly by actively investing in clean, reliable power that brings new capacity to our nation's grids," Amanda Peterson Corio, global head of energy and power at Google, said in a statement. "Our agreement with Constellation to fund nuclear reactor uprates will strengthen the PJM grid, which serves 67 million people, all while protecting energy affordability and supporting local union jobs."
Joe Dominguez, chairman, president and CEO of Constellation, said in a statement that the collaboration "can serve as a model for how technology companies and the energy industry can work together to responsibly develop the digital economy."
#energy #capacity #Jobs
21 days ago
SPCX trades at $151.89, up 5.86%, as Musk claims next-gen V3 satellites will push Starlink's total bandwidth 100x above today's levels.
Musk argues that even if revenue per bit drops tenfold, the V3 upgrade still produces a 10x increase in Starlink's total revenue.
Starlink's ARPU has already fallen from $85 to $66, and roughly 1,000 V3 satellites must launch before service meaningfully improves, expected Q2 next year.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and **** eX made the cut. Enter your email to see the other nine names and why SPCX earned its spot. The report is free. Enter your email and see the full list.
Elon Musk used a post on X to argue that the next generation of Starlink satellites now beginning deployment will eventually push the constellation's total bandwidth to more than 100 times what the roughly 11,000 satellites currently in orbit deliver today. That is a capability claim from the company's chief executive, not audited performance data, and investors in **** eX (NASDAQ:SPCX) should treat it that way. Still, it is the kind of claim that reframes how you think about the biggest revenue engine inside the business.
#musk #satellites #still #push


1 month ago
NRG Energy gained 6.4% and Constellation Energy rose 4.9% on September 4 while the S&P 500 fell 0.4%. The gains were consistent with the broader AI-power trade where data-center projects increasingly depend on generators that can add reliable capacity, navigate interconnection queues, and sign contracts before construction. NRG Energy, Inc. (NYSE:NRG) and Constellation Energy Corporation (NASDAQ:CEG) offer different versions of that opportunity.
NRG is advancing a Bring Your Own Power strategy with a hyperscaler for a 1.2-gigawatt combined-cycle gas project in Texas. It also brought a 415-megawatt facility into commercial operation and reported $1.03 billion of second-quarter free cash flow before growth investments. The bull case is speed: pairing contracted data-center load with dispatchable generation can bypass part of the grid bottleneck. The bear case is project execution, fuel exposure, financing, and the possibility that forecast load never materializes.
Insider Monkey counted 59 hedge funds holding NRG Energy, Inc. (NYSE:NRG) at June 30, down from 76 at March 31. Israel Englander's Millennium Management nevertheless disclosed 4,257,712 shares, 115% more than in Q1. The contrast between a falling fund count and one manager's larger position argues against treating institutional sentiment as uniform.
Constellation brings the largest U.S. nuclear fleet plus gas **** ets acquired with Calpine. It raised full-year adjusted operating EPS guidance to $11.50 to $12.50 and said it had signed another 920 megawatts of long-term power agreements. The bull case is scarce around-the-clock clean generation. The bear case includes plant outages, regulatory intervention, integration risk, and the danger of overpaying to expand capacity during a demand boom.
Seventy-three hedge funds held Constellation Energy Corporation (NASDAQ:CEG) in Q2, down from 79 in Q1. Philippe Laffont's Coatue Management disclosed 4,632,475 shares at quarter-end; the available profile did not show a usable sequential activity figure, so no motive or timing is inferred.
#energy #management
1 month ago
Shares of NuScale Power (NYSE:SMR) trade around $9.63 as of this writing, down about 83% from their $57.42 52-week high.
But the demand that sent nuclear stocks soaring in the first place hasn't reversed. Constellation Energy (NASDAQ:CEG), for instance, reported an additional 920 megawatts of long-term power purchase agreements alongside its second-quarter results.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In other words, the crash and the demand can both be true at once, because these companies do very different jobs. NuScale designs reactors, Cameco (NYSE:CCJ) sells the fuel, and Constellation already sells the power. A $2,000 investment split across the three buys three different claims on the same electricity demand.
Image source: The Motley Fool.
#power #constellation #down #first

1 month ago
Billionaire technology investor Peter Thiel's hedge fund, Thiel Macro LLC, disclosed 372,755 shares of Vistra Corp. (NYSE:VST) at the end of Q2 2026, worth about $59.1 million.
The position is interesting because Vistra sits directly in the argument over whether electricity, rather than GPUs, becomes the scarce ******* et in the next leg of the AI buildout. Data centers need large blocks of reliable power, and Vistra owns a broad generation fleet with exposure to fast-growing power markets. Wolfe Research has argued that the market may be underestimating Vistra's ability to convert data-center demand into sustained EBITDA and free-cash-flow growth.
Image by Markus Distelrath from Pixabay
There is also a valuation wrinkle though. Recent Insider Monkey ******* ysis put Vistra at roughly 15.8 times forward earnings, below Constellation Energy at about 22.9 times. Vistra Corp. (NYSE:VST) does not have Constellation's same nuclear-heavy contracted profile, but that discount gives the stock room to rerate if data-center contracts make more of its future cash flows visible.
The caution is that Thiel Macro's Q2 filing says nothing about why the fund owns Vistra, or exactly when during the quarter it accumulated the position. The filing establishes the position at quarter end, not a same-day purchase and not Peter Thiel's reasoning for holding it. It would be sloppy to call it an AI bet on Thiel's behalf. Power prices, hedges, plant economics and capital allocation can matter as much as data-center headlines, and a cheap multiple versus Constellation can persist if investors continue to prefer nuclear ******* ets and long-duration contracts.
#constellation

1 month ago
As electricity demand surges amid AI data center growth, two utility companies stand out. NextEra Energy (NYSE: NEE) and Constellation Energy (NASDAQ: CEG) are both incredibly strong businesses, but are taking different approaches to this new chapter in North American power.
NextEra is both a traditional utility provider and a powerhouse in renewable energy. It is planning to spend $94 billion through 2030 in an aggressive push to build out its footprint. In May, the energy giant announced an all-stock agreement to acquire Dominion Energy. This deal will make NextEra the world's largest utility business, but the megamerger is facing intense regulatory scrutiny.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
The company's dividend yield is holding strong at over 3%. The stock has risen just 2% this year. NextEra is a reliable income producer, but could see substantial growth through the early 2030s.
Constellation's approach is completely different from NextEra's. Constellation is the largest nuclear power operator in the U.S. It's also an independent power producer, meaning it sells electricity on the open market and not through a regulated utility model. This gives it greater pricing volatility, but potentially more upside.
#energy #flashing
1 month ago
Andvari ****** ociates, an investment management firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ****** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ****** ociates highlighted Texas Instruments Incorporated (NASDAQ:TXN), a semiconductor manufacturer providing chips and solutions for electronics designers and manufacturers. On September 02, 2026, Texas Instruments Incorporated (NASDAQ:TXN) closed at $254.80 per share. Over the past month, Texas Instruments Incorporated (NASDAQ:TXN) fell 8.48%, while its shares gained 36.05% over the past 52 weeks. Texas Instruments Incorporated (NASDAQ:TXN) has a market capitalization of $232.7 billion.
Andvari ****** ociates stated the following regarding Texas Instruments Incorporated (NASDAQ:TXN) in its Q2 2026 investor letter:
"I also added Texas Instruments Incorporated (NASDAQ:TXN), which makes ****** og and power management chips. Texas Instruments and Martin Marietta might be getting a nice temporary ****** p in profits and revenues from helping build out AI infrastructure, but AI and data center-related revenues are by no means the majority of revenues for either of these two companies."
Texas Instruments Incorporated (NASDAQ:TXN) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 111 hedge fund portfolios held Texas Instruments Incorporated (NASDAQ:TXN) at the end of the second quarter, up from 71 in the previous quarter. While we acknowledge the potential of Texas Instruments Incorporated (NASDAQ:TXN) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#andvari
1 month ago
Andvari **** ociates, an investment management firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow **** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari **** ociates highlighted Martin Marietta Materials, Inc. (NYSE:MLM). Martin Marietta Materials, Inc. (NYSE:MLM) is a building materials company that supplies aggregates and heavy-side building materials to the construction industry. On September 02, 2026, Martin Marietta Materials, Inc. (NYSE:MLM) closed at $517.07 per share, reflecting a market capitalization of $36.72 billion. Martin Marietta Materials, Inc. (NYSE:MLM) posted a one‑month return of ‑3.94%, while its shares lost 16.46% over the past 52 weeks.
Andvari **** ociates stated the following regarding Martin Marietta Materials, Inc. (NYSE:MLM) in its Q2 2026 investor letter:
"All this said, Andvari does have some exposure to the AI theme. Martin Marietta Materials, Inc. (NYSE:MLM) one of the largest aggregates companies in the U.S., is also a minor beneficiary of the AI theme given robust construction activity in data centers and power generation. Texas Instruments and Martin Marietta might be getting a nice temporary **** p in profits and revenues from helping build out AI infrastructure, but AI and data center-related revenues are by no means the majority of revenues for either of these two companies."
Martin Marietta Materials, Inc. (NYSE:MLM) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 67 hedge fund portfolios held Martin Marietta Materials, Inc. (NYSE:MLM) at the end of the second quarter, which was 65 in the previous quarter. While we acknowledge the potential of Martin Marietta Materials, Inc. (NYSE:MLM) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report


1 month ago
Andvari ***** ociates, an investment management firm, released its first-quarter 2025 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ***** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ***** ociates highlighted Tyler Technologies, Inc. (NYSE:TYL). Tyler Technologies, Inc. (NYSE:TYL) is a leading US-based integrated software and technology solutions provider for the public sector. On August 28, 2026, Tyler Technologies, Inc. (NYSE:TYL) closed at $377.94 per share. The one-month return of Tyler Technologies, Inc. (NYSE:TYL) was 23.70%, and its shares lost 32.86% over the past 52 weeks. Tyler Technologies, Inc. (NYSE:TYL) has a market capitalization of $15.48 billion.
Andvari ***** ociates stated the following regarding Tyler Technologies, Inc. (NYSE:TYL) in its Q2 2026 investor letter:
"Tyler Technologies, Inc. (NYSE:TYL), a software company focused solely on state and local government customers, recently raised its 2030 financial goals because the cloud transition for its customers has moved from aspiration to solid proof. Since its 2023 investor day, Tyler has met or exceeded its 2025 interim targets, shifted more than 95% of new-client total contract value to SaaS ("software as a service"), completed the migration of its roughly 5,000 hosted customers onto AWS, and exited its last private data center on schedule. All this gives management more confidence in both future growth and margins. Tyler's remaining on-premise maintenance base still represents a large conversion pool, and each maintenance-to-SaaS "Lip" is expected to lift recurring revenue by roughly 1.7x before any cross-sell, payments attach, or module expansion. Just as important, Tyler's next phase—"Cloud Living"—should reduce version complexity, lower support burden, speed upgrades, and create a more scalable operating model…" (Click here to read the full text)
#andvari #quarter


1 month ago
Andvari **** ociates, an investment management firm, released its first-quarter 2025 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow **** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari **** ociates highlighted Mobility Global, Inc. (NYSE:MBGL). Previously known as S&P Global Mobility Holding Company, the company rebranded to Mobility Global, Inc. in February 2026. Mobility Global, Inc. (NYSE:MBGL) specializes in offering essential data and **** ysis throughout the entire vehicle lifecycle. On August 28, 2026, Mobility Global, Inc. (NYSE:MBGL) closed at $20.24 per share. Over the past month, Mobility Global, Inc. (NYSE:MBGL) returned -4.98%. Mobility Global, Inc. (NYSE:MBGL) has a market capitalization of $6.48 billion.
Andvari **** ociates stated the following regarding Mobility Global, Inc. (NYSE:MBGL) in its Q2 2026 investor letter:
"As a new separate entity, Mobility Global, Inc. (NYSE:MBGL) will likely be a good business to hold on to as it has many trusted products (CARFAX, Polk, Automotive Mastermind, and Market Scan) that are deeply embedded in the automotive ecosystem. MBGL's customers span from nearly every global auto OEM and tier 1 supplier to thousands of car dealers. With annual revenues of just $1.75 billion, high margins, >80% subscription-based revenues, and now with greater Lexibility to invest and acquire, MBGL management believes it can continue to grow at a high single-digit rate and expand margins."
Mobility Global, Inc. (NYSE:MBGL) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 3 hedge fund portfolios held Mobility Global, Inc. (NYSE:MBGL) at the end of the second quarter, which was 0 in the previous quarter. While we acknowledge the potential of Mobility Global, Inc. (NYSE:MBGL) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tarif
1 month ago
Andvari ******* ociates, an investment management firm, released its first-quarter 2025 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow ******* ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari ******* ociates highlighted NVIDIA Corporation (NASDAQ:NVDA). NVIDIA Corporation (NASDAQ:NVDA) is a leading data center-scale AI infrastructure company operating through Compute & Networking and Graphics segments. On August 28, 2026, NVIDIA Corporation (NASDAQ:NVDA) stock closed at $217.55 per share. The one-month return of NVIDIA Corporation (NASDAQ:NVDA) was 5.28%, and its shares gained 24.90% over the past 52 weeks. NVIDIA Corporation (NASDAQ:NVDA) has a market capitalization of $5.25 trillion.
Andvari ******* ociates stated the following regarding NVIDIA Corporation (NASDAQ:NVDA) in its Q2 2026 investor letter:
"Another reason why I am increasingly cautious here is I've begun to see more examples of circular financing among the companies involved with the AI investment boom. For example, when NVIDIA Corporation (NASDAQ:NVDA) invested in OpenAI in late 2025, it was reported most of the money would be used to lease Nvidia chips. Also, some companies like Nvidia and Anthropic have invested directly into special purpose vehicles (SPVs), which in turn use that money to buy hardware from those exact same hardware makers. Then there are AI companies like Anthropic who have begun to use massive SPVs, backed by private equity firms, to borrow billions to buy chips and servers. The AI company then leases the chips from the SPV and thus the debt can stay on its own balance sheet. I've also read that some Nvidia customers are using Nvidia chips as collateral for loans to buy even more chips. This is the same type of behavior that eventually got many telecom and tech companies into huge trouble during the dot com bubble of the 1990s."
#andvari #chips #letter
1 month ago
Andvari **** ociates, an investment management firm, released its first-quarter 2025 investor letter. The letter can be downloaded here. Andvari's portfolio has performed strongly in the quarter, highlighted by Constellation Software's 19.9% revenue growth and its plans to spend on acquisitions in 2026. The company is also focusing on AI tools to enhance productivity and customer relationships. However, the AI sector is experiencing extreme hype, leading to a growing disconnect between valuations and future cash flows. Predictions suggest the AI investment phase may decline in 1-3 years, despite current high demand for AI infrastructure, which is expected to attract significant competition. Concerns about overbuilding and risky financial behaviors, like Oracle's downgraded credit rating amid a $90-$95 billion AI cloud investment, reflect potential pitfalls. Andvari has minimized exposure to this sector, aiming to protect and grow **** ets through disciplined investments in stable industries despite recent underperformance during the AI boom. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Andvari **** ociates highlighted S&P Global Inc. (NYSE:SPGI). S&P Global Inc. (NYSE:SPGI) is a financial services and **** ytics company that provides benchmarks, data, **** ytics, and workflow solutions in the global capital, energy, commodity, and automotive markets. On August 28, 2026, S&P Global Inc. (NYSE:SPGI) closed at $442.89 per share, reflecting a market capitalization of $130.56 billion. S&P Global Inc. (NYSE:SPGI) posted a one‑month return of 6.40%, while its shares lost 14.62% over the past 52 weeks.
Andvari **** ociates stated the following regarding S&P Global Inc. (NYSE:SPGI) in its Q2 2026 investor letter:
"Another portfolio company with notable activity is S&P Global Inc. (NYSE:SPGI) which recently spun out its Mobility Global (MBGL) division to shareholders. The remaining S&P Global is now an even higher quality business because its crown jewels can shine even brighter. In 2025, S&P's credit ratings business had adjusted operating margins of 65%, its S&P Dow Jones Indices business had 71% adjusted operating margins, and its Energy business had 48% adjusted operating margins. Mobility Global had just 40% margins."
S&P Global Inc. (NYSE:SPGI) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 124 hedge fund portfolios held S&P Global Inc. (NYSE:SPGI) at the end of the second quarter, up from 122 in the previous quarter. While we acknowledge the potential of S&P Global Inc. (NYSE:SPGI) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #associates #busines
1 month ago
Kenneth Lonergan has taken a firm stand for Mark Ruffalo amid antisemitism accusations tied to his Israel-Gaza remarks. The Oscar-winning filmmaker and longtime friend of Ruffalo addressed the allegations in a letter to The Hollywood Reporter. He called the antisemitism accusation against Ruffalo "overtly preposterous" and said it was being used to silence his criticism of Israel.
Ruffalo's latest controversy followed his criticism of Oracle founder Larry Ellison and the company's reported ties to Israeli military technology. He also faced backlash from Paramount Skydance after criticizing the proposed Warner Bros. Discovery merger. The company accused him of using antisemitic tropes, but Ruffalo denied it and said he was criticizing political and corporate actions.
Lonergan's relationship with Ruffalo dates back to You Can Count on Me, his 2000 directorial debut starring Laura Linney and Ruffalo. The film was widely praised and marked the beginning of their friendship, which has continued for decades.
Their long friendship led Lonergan to publicly defend the actor. In his letter, he referred to Ruffalo as his "dear friend for thirty years." Lonergan called the antisemitism accusation "a cynical and disgusting lie" and questioned the motives behind it. He wants the Simon Wiesenthal Center to review its response and clarify where it detects any antisemitism.
Lonergan said that attacking Ruffalo personally helps critics avoid addressing his actual arguments. He also acknowledged that he "disagrees profoundly with many of his positions on the Middle East, Israel, Gaza, and Iran's constellation of fanatical Islamic fundamentalist proxies." However, Lonergan said people can disagree with Ruffalo's views without labeling his criticism of Israel as antisemitic.
#ruffalo #friend #letter #accusation

1 month ago
At this point more than two months before the midterm elections, Democrats retaking control of Congress and its subpoena power is far from certain. But President Donald Trump is already laying down legal markers for how he'll fight any attempt by lawmakers to investigate him.
In a Justice Department memo and legal filings, the Trump administration is arguing that the president can keep secret not just the conversations he has with his advisers within the White House, but that his dealings with individuals outside the government can be shielded as well. The White House is also saying in court that even disclosing the identities of the people who worked on significant policy efforts would infringe upon the presidential confidentiality to which Trump is entitled. And the administration has taken the stance that it can ignore a Watergate-era law prohibiting the destruction of White House documents.
The posturing comes as Trump, in his second term, has been notably reliant on a constellation of business moguls, non-government attorneys and old friends to help shape his agenda.
"There has been an unprecedented amount of interaction between the Executive Branch — particularly the White House — and the private sector that Congress has made clear is going to be the subject of oversight," said Jamie Bair, a partner and head of congressional investigations at the law firm Crowell & Moring.
Congressional Democrats are already probing the administration's interactions with FIFA, how Trump's ties to the crypto-industry are affecting federal policy, and other examples of Trump family business maneuverings that Democrats say can be tied to government policies.
#congressional

1 month ago
On August 18, Keysight Technologies (NYSE:KEYS) delivered a fiscal third quarter that beat the high end of its own guidance across the board. Revenue climbed 36% year over year to $1.85 billion, non-GAAP earnings per share jumped 79% to $3.07, and orders topped $2 billion for the second straight quarter. Management raised its outlook for both the fourth quarter and the full fiscal year, pointing to demand tied to artificial intelligence infrastructure, defense modernization, and next-generation communications standards. The results position Keysight as one of the more direct ways to invest in the testing and validation side of the AI buildout, a corner of the market most investors rarely think about.
Orders reached $2.091 billion in the quarter, up 56% on a reported basis, the second straight quarter above the $2 billion mark. Wireline orders more than doubled year over year as customers scaled out AI data center infrastructure, and Commercial Communications crossed $1 billion in quarterly revenue for the first time, up 56%, while revenue from wireline products outpaced wireless within that segment for the first time. The Electronic Industrial Solutions Group posted a record $501 million in revenue, up 21%, with double-digit order growth across general electronics, semiconductors, and automotive and energy. Aerospace, defense and government revenue grew 14% to $339 million as spending shifted toward lower-cost autonomous platforms, including UAVs and low earth orbit satellite constellations built by venture-funded defense technology firms.
Profitability expanded right alongside the growth: operating margin hit 33.2%, up 820 basis points and above the company's long-term target range of 31% to 32%, while free cash flow rose to $403 million from $291 million a year earlier. The company also added nearly 3,000 new customers so far this fiscal year, a group that has already contributed more than $100 million in new business, and said July was its busiest month yet for incoming sales opportunities, pushing the trailing 12-month pipeline to a record. Further out, the 3GPP standards body confirmed in June that the first 6G standard is targeted for March 2029, a milestone management said is already moving customers from exploratory research into funded development work.
CFO Neil Dougherty tempered the enthusiasm, warning that supply availability remains "a governor of our ability to convert demand into revenue" over the next several quarters, meaning orders are outrunning what the company can actually ship and book as revenue right now. He also noted that one-time tariff impacts in fiscal 2026 inflated this year's profitability in ways that are not expected to repeat in fiscal 2027. That combination, a backlog constrained by supply and a margin base partly lifted by tariffs, complicates how much of this quarter's strength carries forward unchanged. The integration of recent acquisitions is also still working through the system.
#quarter #billion #m

1 month ago
On August 17, satellite communications giant Viasat, Inc. (NASDAQ:VSAT) selected launch and ****** e systems provider Rocket Lab Corporation (NASDAQ:RKLB) to build the ****** ecraft bus for the U.S. ****** e Force's Protected Tactical SATCOM-Global (PTS-G) program. Under the initial "Swarm 1" production award, a $218.8 million prime contract won by Viasat in May, Rocket Lab will supply a geosynchronous configuration of its Lightning ****** ecraft platform (Lightning-GEO) to host Viasat's dual-band X/Ka-band anti-jamming payload. Stifel ****** yst Erik Rasmussen maintained a Buy rating on Rocket Lab following the news, citing a "meaningful share" of the award for Rocket Lab that presents a high eight-figure revenue opportunity and positions the company well for follow-on contracts.
Viasat and Rocket Lab present two fundamentally different financial profiles, with Viasat emphasizing scale and improving cash flow while Rocket Lab delivers significantly faster growth. Viasat, Inc. (NASDAQ:VSAT) generated approximately $1.2 billion in Q1 FY2027 revenue, down 1% year over year, primarily reflecting a 4% decline in its Defense and Advanced Technology segment while Communications Services remained flat. Its net loss narrowed to $52 million from $56 million in Q1 FY2026, helped by lower interest expenses following debt repayment. Adjusted EBITDA declined 7% year over year to $381 million, while free cash flow increased 19% to $72 million, excluding non-recurring items. This improvement helped reduce net leverage to 3.2x, down 0.4x, while quarterly awards increased 10% year over year to $1.3 billion.
Rocket Lab Corporation (NASDAQ:RKLB), meanwhile, posted record Q2 2026 revenue of $234.1 million, up 62% year over year, driven by rapid expansion in its ****** e Systems business. Although the company recorded a GAAP net loss of $49.25 million, gross profit increased to $84.57 million, while backlog surged 137% year over year to $2.36 billion. Cash reserves also climbed to $2.13 billion following an ATM equity offering. While Viasat generates roughly five times the revenue and stronger operating cash flow, Rocket Lab is growing at a much faster pace, rapidly scaling its high-margin ****** e Systems business alongside launch services.
Viasat's bull case is supported by strong cash flow generation, with $72 million in free cash flow, and a multi-billion-dollar backlog that provides visibility for continued debt reduction. Its ****** e Force PTS-G win also reinforces the strength of its defense business and could support future growth. However, the bear case centers on declining top-line growth, with revenue down 1% year over year. Heavy capital expenditures on satellite constellations, combined with existing leverage constraints, could limit the company's ability to respond quickly to changing market conditions.
#viasat #space #cash

1 month ago
Constellation Brands, Inc. (STZ), with a market capitalization of approximately $23.2 billion, is a leading international producer and marketer of beer, wine, and spirits. The Rochester, New York-based company's portfolio includes Corona, Modelo, Pacifico, and Victoria beers, along with premium wine and craft spirits brands. The company operates across the U.S., Mexico, New Zealand, and Italy.
Shares of the beverage alcohol giant have considerably underperformed the broader market over the past year. STZ has declined 17.9% over this period, while the broader S&P 500 Index ($SPX) has advanced 18.3%. On a year-to-date basis, STZ has also continued to underperform, declining marginally, compared with the index's 11.8% gain over the same period.
IonQ vs. Rigetti: The Better Quantum Computing Stock for Long-Term Investors
QQQ is Still in a Negative Gamma Regime. Here's How a 'Put Wall' and Fibonacci Support Could Come Into Play.
IBM Just Hit a New Quantum Computing Milestone. How to Play IBM Stock Now.
#play


1 month ago
This story was originally published on Food Dive. To receive daily news and insights, subscribe to our free daily Food Dive newsletter.
Constellation Brands will invest $100 million over five years to boost U.S. farmer profitability in states that produce hops, barley and other ingredients in the Modelo and Corona maker's beers.
The investment will include additional purchases from farmers in Idaho, Montana and North Dakota, plus initiatives to improve market access and economic resiliency.
The beer maker will also establish a farmer-led advisory committee that will provide insight on how the investments can best support growers in the company's agricultural supply chain.
The farm economy is facing a "generational downturn," according to the American Farm Bureau Federation, as increased production costs and sustained weather challenges strain financials.
#farmer


1 month ago
SpaceX (NASDAQ: SPCX), Tesla (NASDAQ: TSLA), and Intel (NASDAQ: INTC) recently broke ground on the Terafab, the world's largest vertically integrated chipmaking factory. The massive plant is located in Grimes County, approximately 70 miles outside of Houston.
The initial phase of the Terafab will cost $16.8 billion, while its total costs across all phases could surpass $119 billion. Upon completion, the 100-million-square-foot facility will meet ******* eX and Tesla's projected computing demand of more than 1 terawatt per year.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
SpaceX and Tesla will fund the plant's construction, while Intel will support its development with its licensed chipmaking process and foundry operations. ******* eX and Tesla haven't disclosed the exact dollar-for-dollar equity split for the project, but ******* eX will absorb a larger portion of those costs because it will claim more of those chips. Approximately 75% of the Terafab's chips will be allocated to ******* eX's orbital data centers and satellite constellations, while the remaining 25% will power Tesla's Optimus robots, self-driving vehicles, and Cybercabs.
Those chips could help ******* eX achieve Elon Musk's ambitious goal of becoming the first company to generate over $1 trillion in annual revenue by 2030. To achieve that goal, ******* eX would need its Starlink, rocket launch, and AI businesses to grow exponentially.
#tesla #Intel #approximately
2 months ago
Few topics have been as widely discussed in recent years as artificial intelligence (AI). It has taken over the tech world, the business world, and seemingly everything in between. The many companies with their hands in the AI pot all rely on one core thing: data centers.
Data centers are the backbone of AI, but demand for what they can provide is being far outweighed by electricity needs. This isn't the best news for AI hyperscalers (companies that operate large cloud platforms), but it's working in favor of the following two companies.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Hyperscalers need two things: 24/7 access to massive amounts of power and power that is as green as possible. That's where Constellation Energy (NASDAQ: CEG) comes into the picture. Constellation is a clean energy company with the largest nuclear power fleet in the U.S.
Nuclear power is a good go-to because energy sources like natural gas emit carbon emissions, and it's not feasible to expect that much 24/7 power from wind or solar. Nuclear power, on the other hand, is carbon-free and can run continuously.
#nuclear #signal #constellation

2 months ago
On August 20, Intuitive Machines (NASDAQ:LUNR) reported second-quarter revenue of $206 million, more than four times what it brought in a year earlier, and closed the quarter with a record $1.8 billion in backlog. The company reaffirmed its full-year guidance of $900 million to $1 billion in revenue and said it still expects positive adjusted EBITDA for 2026. Behind those headline numbers sits a business spending heavily to chase a market it says has grown far beyond the moon.
The quarter's standout number was bookings. Intuitive Machines logged $1.7 billion in bookings so far this year, including $1.2 billion in the second quarter alone, the highest quarterly total in company history. Management said that volume reflects a shift away from depending on any single customer or mission type. The $1.8 billion backlog now splits roughly 37% civil, 49% commercial and 14% national security, and Q2 bookings skewed even further toward commercial and national security work, at 50% and 30% respectively.
That diversification showed up across every part of the business. NASA selected Intuitive Machines for the CS-8 lunar delivery mission, its sixth award under the CLPS contract, extending its delivery cadence into 2030. On the national security side, the company finished delivering all 16 satellites for the SDA's Tranche 1 tracking layer, added an 18-satellite Tranche 3 award, and picked up another 18 satellites tied to the Golden Dome missile defense architecture. It now has more than 70 IM-300 series ****** ecraft under contract. Commercially, it landed three geostationary communication satellites worth over $600 million and deployed SiriusXM-11 during the quarter. Gross profit swung to $36 million from negative $12 million a year earlier, evidence that the growing satellite manufacturing business is starting to convert into real profit.
That expansion is not free. Operating loss widened to $47 million, driven by higher SG&A, amortization, and a $14.7 million cost adjustment tied to the IM-4 lunar lander program. SG&A itself hit $60 million for the quarter, including $11 million in stock-based compensation and $8 million in acquisition and integration costs from recent deals. Operating cash used came to $60 million, and total cash deployed for the quarter reached $84 million once inventory buildup, acquisition costs, and a $17 million milestone payment to ****** eX are included.
The company is also leaning on equity markets to fund the buildout. It raised $235 million in net proceeds this quarter through its at-the-market stock program, bringing total gross proceeds raised to date to $291 million at an average price of $26.81 a share. Capital expenditures of $24 million went largely toward its NSNS satellite constellation and ground network, and management said CapEx will stay elevated in coming quarters as it builds out five satellites at once.
#million #quarter #bookings

2 months ago
Our ******* ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Performance was driven by the rapid scaling of the AI infrastructure ecosystem, leading to record wireline orders that more than doubled year-over-year.
Management attributed outperformance to increased test intensity as design margins shrink, requiring lossless performance that necessitates testing at the signal, bit, and protocol levels.
The Commercial Communications segment achieved its first $1 billion quarter, with wireline revenue surpassing wireless for the first time due to AI-driven demand for 800G and 1.6T optical transceivers.
Aerospace and defense growth was fueled by global deterrence needs and a shift toward advanced radar architectures and autonomous platforms like UAVs and LEO satellite constellations.
#first #tell #management


2 months ago
T-Mobile US Inc. (NASDAQ:TMUS)'s shares are down by 26% over the past year and by 8% year-to-date. As with other carriers, the firm's narrative depends on its subscriber growth, and more recently, on its ability to compete with ******* eX. The rocket firm, which now also markets itself as an AI firm, also operates the largest satellite internet constellation in the world. ******* eX also aims to offer its cellular service based on its satellites. On August 6th, Cramer discussed T-Mobile US Inc. (NASDAQ:TMUS)'s latest earnings results:
"Some of these are, actually fear of, what's going to happen. I mean, look, T-Mobile was not perfect, it's a good example. T-Mobile was not perfect, it was deceleration of what I'm used to. And then it's a one-two punch, because it's that and then it's ******* eX."
After T-Mobile US Inc. (NASDAQ:TMUS) reported its second quarter earnings in the morning on July 23rd, the shares closed a whopping 11% lower on the same day. The results saw the firm's profit per share beat ******* yst estimates. However, a key factor in its narrative, i.e. postpaid subscribers, missed estimates. As part of the earnings, T-Mobile US Inc. (NASDAQ:TMUS) outlined that it expected to add 250,000 postpaid accounts in the third quarter whcih was quite low over ******* yst estimates of 275,000.
Additionally, during the quarter, T-Mobile US Inc. (NASDAQ:TMUS)'s management also announced that more than 60% of its new additions chose its premium plans. These plans can prove to be more profitable in the future but at the cost of higher customer churn. However, during the call, management also warned that the new plans can increase its churn rate. While T-Mobile US Inc. (NASDAQ:TMUS) outlined that its postpaid churn was 0.85% in the second quarter, the 250,000 subscriber addition guide was based on the costs of the shift to the premium plans.
The focus on the premium and positive metrics, such as a low churn appear to be reflected in T-Mobile US Inc. (NASDAQ:TMUS)'s valuation as well. The firm's shares trade at a forward P/E ratio of 16.45, which is higher than Verizon's P/E of 9.38. 85 out of the 1,022 hedge funds part of Insider Monkey's Q1 2026 database had held T-Mobile US Inc. (NASDAQ:TMUS)'s shares. Furthermore, the short interest appeared to have cleared out a bit after the post-earnings share price movement. As of July-end, it was 3.79% of the float, which was lower than mid-July's 4.70%.
#NASDAQ #shares #churn #estimates

2 months ago
Intuitive Machines (NASDAQ: LUNR) published its second-quarter results after the market closed yesterday, and its stock is seeing strong gains in Friday's trading. The company's share price was up 10.5%in the daily session as of 12:30 p.m. ET.
Intuitive Machines' Q2 sales and earnings actually came in below Wall Street's expectations, but there was some good news for investors. In addition to reaffirming its full-year sales forecast, the company provided new details about its lunar satellite constellation plans.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In the second quarter, Intuitive Machines recorded a net loss of $0.29 per share and revenue of roughly $206.2 million. The average Wall Street **** yst estimate had only targeted a per-share loss of $0.10 in the quarter, and the average forecast called for sales in the period to be roughly $15 million higher. Despite the sales and earnings misses, other updates from the company has been enough to spur big gains for the stock today.
While the company's Q2 sales came in below expectations, Intuitive Machines still expects to post revenue between $900 million and $1 billion this year. The company also expects to record positive non-GAAP (adjusted) earnings before interest, taxes, depreciation, and amortization (EBITDA).
#intuitive #sales #company
2 months ago
September WTI crude oil (CLU26) is up +2.76 (+3.53%) on Friday, and September RBOB gasoline (RBU26) is up +0.1203 (+4.03%).
Crude oil and gasoline prices are sharply higher today, with gasoline climbing to a 1-week high. The lack of an agreement between Iran and Oman to reopen the Strait of Hormuz is limiting crude supplies from the Middle East and is boosting oil prices. Also, an attack on a Saudi oil refinery by Houthi militants is further straining global fuel supplies and is pushing energy prices higher.
What Was Driving Markets Early Monday Morning?
Vistra Corp (VST) Stock's Underperformance Could Open Up a Contrarian Options Trade
The Biggest AI Power Opportunity May Be Hiding in Constellation Energy
#crude #higher #rbob

2 months ago
Constellation Energy (CEG) is turning its nuclear fleet into something rare in the power business. It has locked in decades of demand ahead of time. On its latest earnings call, the company said most of its generation output is now contracted through 2050 and beyond. For a sector where revenue usually swings with volatile wholesale prices, that kind of visibility is almost unheard of. It also comes at a time when artificial intelligence is driving the steepest jump in electricity demand in a generation.
The second quarter showed the strategy in motion. Constellation signed 920 megawatts of new long-term nuclear power agreements. These contracts run 15 to 20 years and start delivering power between 2029 and 2032. Among them is a 176-megawatt Walmart (WMT) deal, split across two 15-year contracts, that will help fund an expansion at the Dresden plant in Illinois. These sit on top of earlier 20-year agreements with Microsoft (MSFT) and Meta (META), tying some of the world's largest firms to Constellation's output well into the 2040s.
What Was Driving Markets Early Monday Morning?
Vistra Corp (VST) Stock's Underperformance Could Open Up a Contrarian Options Trade
Crude Prices Soar as Middle East Tensions Curb Global Oil Supplies
#power #constellation #nuclear #generation


2 months ago
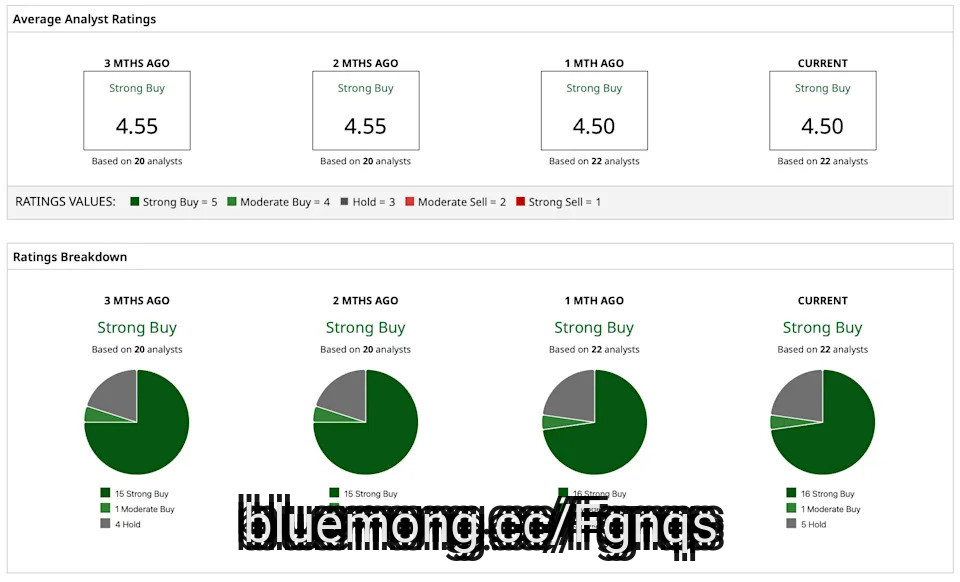
Kansas City, Missouri-based Evergy, Inc. (EVRG), generates, transmits, distributes, and sells electricity. Valued at $19.2 billion by market cap, the company generates electricity through coal, landfill gas, uranium, and natural gas and oil sources, as well as solar, wind, other renewable sources.
Shares of this utility company have underperformed the broader market over the past year. EVRG has gained 14.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 22.4%. However, in 2026, EVRG stock is up 15%, surpassing the SPX's 13.3% rise on a YTD basis.
What Was Driving Markets Early Monday Morning?
Vistra Corp (VST) Stock's Underperformance Could Open Up a Contrarian Options Trade
The Biggest AI Power Opportunity May Be Hiding in Constellation Energy
#sources #broader #kansas


2 months ago
Constellation Energy (NASDAQ:CEG) gave investors a lot to unpack on August 6 with the release of its second-quarter earnings report. The report raised full-year adjusted operating earnings guidance to $11.50 to $12.50 per share and stacked on a run of nuclear contract wins and regulatory approvals tied to its Crane Clean Energy Center restart. The headline story is growth. The details show a company juggling more moving parts than it has in years.
Constellation signed 920 megawatts of new long-term power purchase agreements in the quarter, contracts running 15 to 20 years that won't start delivering power until 2029 through 2032. One, a 176-megawatt deal with Walmart (NASDAQ:WMT), split into two 15-year contracts that start in 2029 and 2030, will fund a 30-megawatt expansion at the Dresden Clean Energy Center, located in Illinois. The batch averages 18.5 years in length, adding to earlier 20-year agreements with Microsoft Corp. (NASDAQ:MSFT) and Meta Platforms (NASDAQ:META).
The bigger prize is Crane, the plant once known as Three Mile Island Unit 1. FERC granted a waiver letting Constellation shift grid connection rights to Crane, and the NRC approved its fuel license amendment, clearing two of the last hurdles before the 835 megawatt unit restarts in 2027 to serve its Microsoft contract. Constellation also filed to extend the licenses of its Ginna and Nine Mile Point 1 reactors in New York out to 2049, stretching value from ****** ets it already owns. Management guided to 20% annualized adjusted earnings growth through 2029, a number that excludes any contracts signed after this quarter.
GAAP numbers moved the other way. Earnings per share fell to $1.42 from $2.67 a year earlier, even as adjusted operating earnings rose to $2.55. Part of that gap traces to a bigger share count after the Calpine acquisition, with average diluted shares outstanding climbing to 360 million from 314 million. The nuclear fleet had a rougher quarter too: output slipped to 44,160 gigawatt-hours from 45,170, and the capacity factor at plants Constellation operates fell to 93.0% from 94.8%, with planned refueling outage days more than doubling to 86 from 41.
There's also cleanup work left from Calpine. Constellation agreed to sell the 606 megawatt Brazos Valley Energy Center to LS Power for $860 million, the last divestiture regulators required, but the deal still needs Department of Justice approval to close. And as a merchant power seller, Constellation stays exposed to regulatory pushback, including from consumer advocates who argue that connecting data centers directly to nuclear plants lets big tech dodge grid costs that land on residential customers instead.
#quarter #center
2 months ago
"Is there an AI bubble?" is such a tired thought. Here's something altogether more wired: The AI boom is paying off, but not in a way that the current equities market has accounted for. The success of the technology in one area of the economy could make the bubble real in another, more precisely.
In a blog post published on Friday, Apollo Chief Economist Torsten Slok highlighted that the parts of the AI value chain with the highest profit margins—companies making AI models and applications—actually have the lowest levels of profitability, a departure from the standard business model of, well business, in which profit margins are higher for companies selling an end product to consumers.
Slok broke down AI companies into four categories: models and applications, cloud and compute, energy and grid, and silicon and equipment. Using data from Pitchbook and Bloomberg for companies including OpenAI, Anthropic, Microsoft, Amazon, Constellation Energy, Nvidia, AMD, and Micron, Slok calculated that silicon and equipment—such as chipmakers—has the highest profit margin, 41%, in the AI value chain. Meanwhile, models and applications—like Anthropic—have a -59% operating margin.
Slok warns that this sharp disparity is because money from the AI boom is not coming from natural demand for AI applications, but rather shareholders hoping to cash in on what they hope is the next technological revolution.
"AI boom's profits are currently being funded by investors rather than earned from customers," Slok said. "The upstream margins are real, but they are paid for out of capital raised by the layer losing money, not out of cash generated by end demand."
#profit #boom

2 months ago
Earnings continue to roll in, driving the stock market to new highs.
The latest reports from Datadog (DDOG), AMD (AMD), Sandisk (SNDK), and Western Digital (WDC) suggest some profit-taking on Wall Street, as robust earnings and raised guidance haven't been enough to stanch post-earnings sell-offs after those stocks made huge gains so far this year.
On Thursday, ConocoPhillips (COP), Constellation Energy (CEG), Airbnb (ABNB), DraftKings (DKNG), and Celsius Holdings (CELH) also report.
Overall, it's shaping up to be a strong earnings season for the S&P 500 (^GSPC). According to FactSet data, ******* ysts estimate the year-over-year S&P 500 earnings growth rate for the second quarter will be 47.5% — surging past the five-year average of 16.4% and the 10-year average of 10.3%.
If that holds, it will mark the second consecutive quarter of earnings growth above 20% for the index and the seventh straight quarter of double-digit growth.
#second


