
7 days ago
AGNC Investment has seen a mix of setbacks and gains in recent years, which raises a straightforward question for anyone looking at the stock today: Is the current share price meaningfully supported by the returns the business earns on its capital base?
Over the past 3 years, AGNC Investment has delivered a total return of about 48.1%, which puts real weight on whether those past gains are grounded in sustainable returns on the equity it deploys.
The mortgage REIT model relies on how efficiently AGNC Investment can fund and reinvest its portfolio. The valuation story therefore hinges on whether that capital structure can keep generating attractive excess returns after funding costs and hedging.
What if you looked at AGNC Investment through its earnings instead? See what AGNC Investment's 4.9x P/E says about the price.
For investors, the debate is whether AGNC Investment's current price fairly reflects the level and quality of the returns it earns on its capital.
#investment #returns #whether #earns
8 days ago
Kim Kardashian and Kanye West's kids have a squad of nannies helping them around the clock. During a recent interview, the 45-year-old mom revealed that she has help at home. While she reportedly hired five nannies, one is always on duty. For those unversed, the socialite has four kids: North, Saint, Chicago, and Psalm. She has primary custody of her children after her divorce from West.
Kim Kardashian has been raising her four kids with the help of five nannies. Recently, the reality TV star opened up about her personal life and daily routine in an interview with The Times. She talked about her children and how she's raising them. Kardashian admitted that she has a surprising amount of help.
She said that she has "one nanny on duty" and four nannies on rotation. With a whole help squad, Kardashian has been taking care of her four kids. Despite the nanny squad, she makes sure to be present in the children's lives as much as possible. Therefore, she is on school duty as the mom drops off and picks up the kids from school every day. She also has dinner with them daily and reads bedtime stories to them.
"I'm extremely patient and loving. I still have a kid sleep in my bed when they want. I read books with the kids every night," Kardashian said. Meanwhile, Saint, 10, Chicago, 8, and Psalm, 7, have not reportedly shown much interest in the entertainment world. But the socialite addressed how her eldest daughter, North, 13, has already been making her way into the music and fashion industries.
"Each kid does what they're comfortable with. So, my little ones come around when I'm filming, but they don't really do storylines. North loves it a little bit more than the rest," Kardashian added.
#kids #north #squad #Chicago


9 days ago
Dolly Parton's estate says yellow caution tape and barbed wire crisscrossed the steps to her nephew Bryan Seaver's front door as a process server was making repeated attempts to serve him with a lawsuit accusing him of using a "campaign of threats" to "extract money" from the late music icon's business interests.
Lawyers for the estate filed a photo of the alleged barricade as they urged a judge to deny Seaver's request for additional time to find a lawyer in the messy legal dispute. They also argued that Seaver's security company missed a deadline last week to challenge an emergency restraining order granted in the case, so the order should therefore be converted into a permanent injunction covering both the company and Seaver himself, as its chief. A hearing on the matter is set for Friday, Oct. 9, unless the court grants Seaver's request for more time to hire an attorney.
More from Rolling Stone
CMA's Dolly Parton Tribute Will Star Ella Langley, Reba McEntire, and Brad Paisley
Ken Paxton Makes Excuses for Floundering Campaign in New Leaked Audio
#campaign #company

9 days ago
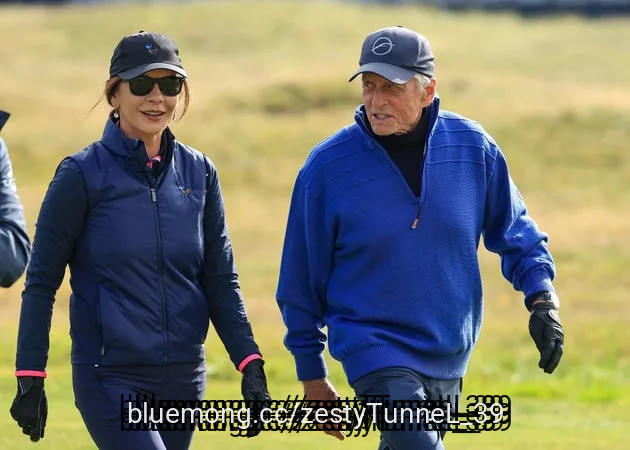
Michael Douglas hit back at a decades-old rumor that he went to rehab for an alleged *** addiction during a strained interview published Sunday by the U.K.'s Sunday Times.
Douglas, 82, was discussing his new memoir, "One **** uva Ride," with British journalist Decca Aitkenhead. She reminded him that he wrote about having to break things off with five women before becoming monogamous with actor Catherine Zeta-Jones, whom he married in 2000 shortly after the end of his first marriage, to Diandra Luker.
Crime: Harvey Weinstein Admits He 'Misled' Women — But Still Won't Accept ****** **** ault Allegations
"No, no, it's not what it was," the actor told Aitkenhead of how he became monogamous with his now-wife. "What Catherine said is, if we're going to continue this, then I want it to be monogamous. And so I therefore, that evening, you know, made some calls to some people I was seeing, and that was that."
In her article, Aitkenhead writes that Douglas then gives her an expression that "suggests that he thinks he's just corrected me."
#women
16 days ago
SK Hynix is exploring something it has never done before: manufacturing memory chips in the United States.
Reuters reported on September 16 that the Korean memory giant is discussing several possibilities with Intel Corporation (NASDAQ:INTC), including leasing part of Intel's long-delayed Ohio complex or forming a venture involving Intel and large cloud customers. SK Hynix said no specific plan has been finalized.
For Micron Technology, Inc. (NASDAQ:MU), the talks matter because one of its strongest strategic advantages is being the major U.S.-based memory producer while AI has made DRAM and HBM increasingly scarce.
Intel has committed enormous capital to Ohio, with the broader project potentially reaching around $100 billion over time. Delays have pushed planned production into the next decade. A tenant or joint-venture partner could therefore help Intel share the financial burden of developing the Ohio site rather than relying entirely on its own foundry demand to justify the buildout.
That is the bull case. The bear case is that exploratory talks are a long way from revenue. Bringing advanced Korean memory production to the U.S. could face cost problems, technology-transfer restrictions and objections from Seoul. Intel still needs its core manufacturing roadmap to work.
#long
24 days ago
Huntington Bancshares Incorporated (NASDAQ:HBAN) dropped 5.55% to $15.82 on September 16, 2026, close to its 52-week low. The price movement was triggered by a profit warning at a Barclays conference. Huntington brought down its 2027 EPS guidance from above $1.90 to the range of $1.75-$1.83, and its 2026 net interest income growth from 39%-43% to roughly 35%. What matters more than these numbers is the reason behind them. Deposit costs are rising, and loan pricing is tightening, and it landed on the day the Fed delivered its first interest rate hike since 2023. The drop therefore raises the question: is this an oversold bank or the opening crack in regional-bank margins?
A well-run bank has just lowered its guidance, citing intense competition for deposits and loans. If Huntington feels the margin pressure, then it is likely that its peers feel the same. This explains why Fifth Third shares slid 4.1% on the same afternoon alongside the whole financials group. The Fed's new hike makes the environment more unfavorable for the group in the near term. While rate increases eventually lift ***** et yields, banks must immediately offer higher deposit yields to retain balances, squeezing net interest margins in the near term. Furthermore, accelerated commercial real estate loan payoffs reduced total earning ***** ets, though these early payoffs lower credit risk on the loan book.
The selloff leans too much into the reset. A move to $1.75-$1.83 from above $1.90 is a modest single-digit trim. Huntington sustains its profit as well as its operational performance. Loans reached $189 billion from $50 billion in 2015. Deposits touched $222 billion. And one of the company's biggest growth engines, value-added fee income, compounded at a 14% annual rate since mid-2024, with year-to-date growth near 32%. The income helps offset a notable portion of the spread pressure and offers a competitive edge against pure spread lenders.
A higher-for-longer rate environment carries trade-offs for commercial banks. It drives up deposit expenses, reflecting the margin pressure Huntington reported. It also expands loan yields as credit ***** ets reprice. Deposit beta determines the net effect by measuring how much of each benchmark rate increase the bank transfers to depositors. After the rate hikes, deposit costs typically rise further, so betting on a near-term peak takes some faith. A lower beta allows fee revenue to support earnings, whereas a higher beta keeps the squeeze sustained over multiple quarters.
#bank #interest #Growth
24 days ago
On September 9, 2026, ****** og Devices, Inc. (NASDAQ:ADI) agreed to acquire privately held Alif Semiconductor for $1.35 billion in cash, with up to $200 million in additional contingent payments. It adds Alif's low-power, AI-native microcontrollers and fusion processors to ADI's portfolio of sensing, signal-processing and power-management technology. ADI CEO Vincent Roche described the deal as advancing "Physical Intelligence," letting systems sense, reason and act locally in real time. The acquisition is expected to close by the end of 2026 pending U.S. antitrust review.
Alif gives ****** og Devices, Inc. (NASDAQ:ADI) a direct foothold in the fast-growing edge-AI market. Alif's AI-native microcontrollers and fusion processors support low-latency inference, sensor fusion, and on-device AI. It allows systems to process information locally rather than relying entirely on the cloud. The acquisition also expands ADI's addressable market across industrial, data-center infrastructure, defense, energy, robotics, digital health and wearable applications.
ADI is acquiring technology that already has commercial traction. Alif's silicon already ships in production and has design wins with leading consumer and industrial customers. It gives ADI an established platform rather than an early-stage technology project. ADI can combine Alif's digital processing capabilities with its own sensing, signal-processing, power, connectivity and software technologies to offer more complete system solutions.
The acquisition fits ADI's push into AI while the core business makes strong cash flow. ADI completed its $1.5 billion Empower Semiconductor acquisition in July to strengthen power delivery for AI computing, while third-quarter revenue reached a record $4.02 billion, up 40% year over year, and trailing 12-month free cash flow reached $4.94 billion. The Alif deal therefore adds edge intelligence to an AI strategy while ADI retains substantial financial capacity to fund acquisitions and shareholder returns.
Analog Devices, Inc. (NASDAQ:ADI) must make enough returns to justify the $1.35 billion upfront price. The firm will pay $1.35 billion in cash at closing and could pay another $200 million in contingent consideration. It takes the potential consideration to $1.55 billion. ADI therefore needs Alif's technology, customer wins, and expanded addressable market to turn into real revenue and earnings growth rather than simply adding another promising technology platform to its portfolio.
#analog #NASDAQ #power #acquisition
24 days ago
On September 9, 2026, Reuters reported that CEO Brian Niccol's first two years as Starbucks Corporation (NASDAQ:SBUX) CEO have succeeded in bringing customers back to the coffee chain. Comparable sales rose 7.9% in the fiscal third quarter for a fourth straight quarter of improvement, but his "Back to Starbucks" restructuring has raised costs and squeezed margins along the way. Global operating margin has fallen to 12.9% from 15.8% two years earlier. Niccol, who marks his second anniversary in the role, now faces pressure to convert the sales recovery into the sustainable profit growth investors are demanding.
Niccol's turnaround strategy has already restored customer momentum at Starbucks Corporation (NASDAQ:SBUX). The "Back to Starbucks" strategy reversed six consecutive quarters of declining comparable sales as the company focused on reducing wait times, simplifying menus, improving store ambiance, and increasing staffing. Starbucks has moved beyond the sales deterioration that preceded Niccol's tenure. It gives investors a stronger foundation for the next phase of the turnaround. If management can sustain traffic gains while improving productivity, the sales recovery could provide a path toward stronger earnings growth.
The China joint venture with Boyu Capital gives Starbucks a more capital-efficient way to participate in China's growth. Starbucks sold control of its China retail operations to Boyu. It retained a 40% stake and continues to own and license its brand and intellectual property. The structure reduces Starbucks' direct capital requirements while allowing it to retain economic exposure to the Chinese market. Reuters cited ****** ysts who said the arrangement leaves Starbucks well positioned to convert stronger organic sales growth into profit growth, which could support returns as the recovery progresses.
Starbucks now has an opportunity to turn its customer investments into margin expansion. The firm committed at least $500 million toward labor as part of the restructuring. Niccol prioritized staffing and store improvements to rebuild the customer experience. That spending helped help the sales recovery. But it also pushed global operating margins down to 12.9% from 15.8% over two years. With sales now improving, management can focus more heavily on productivity, cost control, and operating leverage. It creates an opportunity for stronger earnings if it can improve margins without damaging customer traffic.
Labor tensions could undermine Starbucks Corporation (NASDAQ:SBUX)' recovery and keep costs elevated. Starbucks has yet to reach a first contract with its U.S. barista union. The union called for a consumer boycott in August. Negotiations or labor actions could disrupt store operations, increase labor costs, and create reputational pressure just as Starbucks tries to improve profitability. Therefore, investors face a risk that labor issues could offset some of the productivity gains management needs to expand margins.
#
24 days ago
Vera Bradley, Inc. (NASDAQ:VRA) reported on September 15 that fiscal 2027 second-quarter revenue from continuing operations increased 1.1% to $71.6 million. For the quarter ended August 1, 2026, GAAP operating income from continuing operations reached $4.2 million, compared with a $4.6 million loss a year earlier.
However, gross profit included a $7.7 million tariff refund relating to prior-period imports. Subtracting that benefit from reported operating income, with all other items unchanged, produces an illustrative operating loss of approximately $3.5 million and an operating margin of negative 4.9%.
The quarter therefore shows improving customer demand alongside an earnings recovery that still depends heavily on refunds.
Direct-channel performance gives Vera Bradley, Inc. (NASDAQ:VRA) tangible evidence of customer traction. Direct revenue increased 8.0% to $65.4 million, while comparable sales rose 9.2%. Management attributed the comparable-sales improvement to better e-commerce conversion and higher average transaction values across direct channels.
That combination matters because stronger conversion means more shoppers complete purchases, while larger transactions support revenue without requiring equivalent growth in customer traffic. Continued momentum could help spread store, distribution, and corporate costs across a larger sales base.
#bradley

24 days ago
California Resources Corporation (NYSE:CRC) announced on September 17 that it had agreed to sell its Uinta Basin **** ets, located mostly in Utah and Colorado, to an undisclosed buyer for $90 million in cash. The company had come to own the Uinta **** ets, which span about 100,000 net acres, after it acquired Berry Corp last year. However, CRC considered them non-core to its operations. The net proceeds from the sale will be used for shareholder returns and other corporate purposes.
Francisco Leon, President and CEO of California Resources Corporation, commented:
"Today's transaction strengthens our business. The monetization of our Uinta Basin **** ets sharpens our focus on California and captures additional value from the Berry merger. This transaction enhances our capital allocation flexibility, allowing us to invest in higher-return opportunities within the Golden State and supports our shareholder return strategy. The sale also helps offset the purchase price of our recent midstream transaction."
The transaction is expected to close by year-end, subject to the receipt of certain third-party consents and other customary conditions.
The sale will allow CRC to redeploy the $90 million toward **** ets that are central to its operating strategy while avoiding additional capital commitments to Uinta. The company already stated in its Q2 earnings call that Uinta has higher capital intensity, higher break-evens, lower crude quality, higher transportation and operating costs, and steeper declines. Therefore, the sale removes a portfolio distraction at a time when CRC is concentrating investment in California infrastructure and production.
#uinta #assets #transaction #capital
24 days ago
Federal Reserve Chair Kevin Warsh has revealed himself. If not a card-carrying monetarist, he is at least a camp follower. This represents a dramatic change at the Fed, where the past Chairman Jerome Powell repeatedly rejected the basic tenets of monetarism.
This is a welcomed earthquake. After all, there are almost no monetarists left in the world (except for us, and we've been fighting a lonely rearguard action for over 40 years). The Federal Reserve has rejected monetarism consistently — and on the record — because it preferred other models for understanding the economy. In academia, monetarism has been out of fashion for decades. But by his own words, a monetarist is now leading the central bank.
Just what is monetarism? It's a doctrine which holds that money has a major influence on both the level of ***** et prices, economic activity, and the price level. Any discussion of national income determination must, therefore, center on the quantity of money and the banking system, since banks produce most of the money in modern economies. When it comes to monetary policy, its objectives are best met by targeting the rate of growth of the money supply.
Today, most economists pooh-pooh monetarism. Money and banking are nowhere to be found in their macroeconomic models, or their discourses about the course of ***** et prices, economic activity, and prices. Indeed, their forecasting exercises are typically based on elaborations of Keynesian income-expenditure models that exclude money and banking.
If that's not enough, we think that the Fed's backroom staff, mostly Keynesian-leaning Democrats, don't want alignment with a philosophy usually affiliated with Milton Friedman, but that's another story. Just look at what Joe Biden said in 2020 about how the dean of monetarism wasn't "running the show anymore."
#monetarist

25 days ago
Ondas Inc. (NASDAQ:ONDS) completed its acquisitions of GATE Technologies Ltd. and Bron Technologies on September 14, adding electronic safety and fuzing components used across precision weapons. GATE supplies the technology, while Bron provides manufacturing and certification capabilities in Poland.
Base consideration comprises $105 million in cash and $100 million in equity. The SEC filing specifies an additional $25 million working-capital adjustment. Of the stock consideration, approximately $22.5 million is scheduled for issuance within nine months, subject to conditions. Performance payments could add up to $185 million.
The investment question is whether owning qualified components can improve supply reliability and profitability enough to justify the purchase price and manufacturing investment.
GATE's technology is integrated into dozens of weapons systems. Qualification and integration requirements can make replacing a supplier difficult, supporting repeat demand as customer programs enter production. Ondas Inc. (NASDAQ:ONDS) can therefore participate in orders across multiple manufacturers alongside sales of its own systems.
Management says approximately 80% of GATE's revenue comes from outside the Middle East. The combination of Israeli engineering and Polish production provides an established international base. U.S.-produced finished products and integrated systems are targeted for the first half of 2027, potentially expanding access to programs with domestic sourcing requirements.
#ondas
25 days ago
Virtus Investment Partners, Inc. (NYSE:VRTS) reported on September 11 that preliminary ****** ets under management, or AUM, totaled $147.501 billion at August-end, compared with $148.874 billion at July-end. That represents a $1.373 billion decline, or approximately 0.9%.
Management identified net outflows in institutional accounts, retail separate accounts, U.S. retail funds and global funds, partly offset by positive flows into exchange-traded funds, or ETFs, and tender-offer funds.
Positive market performance partly offset net outflows. The $1.373 billion AUM decline therefore differs from net client withdrawals, which the announcement did not quantify. The underlying business question is whether products attracting new money can become large enough to stabilize the revenue base.
Virtus Investment Partners, Inc. (NYSE:VRTS) has identifiable sources of customer demand. Positive net flows into ETFs and tender-offer funds provide a route toward a more balanced product mix.
ETF demand also appeared in the second quarter, when these products attracted $0.3 billion of net inflows. August's positive flows suggest the opportunity extends beyond a single reporting period.
#virtus #investment #partners
26 days ago
Digital Realty Trust, Inc. (NYSE:DLR) announced a joint venture with Rönesans Infrastructure on September 14 to develop and operate data centers in Türkiye. The first Ankara campus is designed for more than 22 megawatts of IT capacity. Land, power and permits are secured, early construction has begun, and the first facility is scheduled for completion in 2028.
Digital Realty Trust, Inc. (NYSE:DLR) has established credible development foundations. The investment question is whether those foundations can support attractive returns once construction spending, customer contracts, and operating costs enter the calculation.
For Digital Realty Trust, Inc. (NYSE:DLR), securing land, electricity and permits reduces uncertainty around whether development can proceed. That matters because customer interest has limited commercial value when a developer cannot offer a credible delivery schedule. Construction progress can make discussions with prospective tenants more concrete.
Digital Realty Trust, Inc. (NYSE:DLR) also combines its global customer relationships and operating experience with Rönesans Infrastructure's local development and construction capabilities. The potential benefit is practical: a partner familiar with local execution can help deliver the buildings, while an established data-center operator can help attract customers and manage their deployments.
Digital Realty Trust, Inc. (NYSE:DLR) is entering through a venture that also plans an additional Istanbul facility. A presence in both cities could appeal to customers seeking multiple locations for resilience and connectivity. Success in Ankara could therefore create a commercial foundation for further expansion, provided demand supports additional investment.
#digital #construction #development #venture

26 days ago
Seagate Technology Holdings plc (NASDAQ:STX) announced on September 9 that its subsidiary, Seagate HDD Cayman, completed the redemption and exchange of its remaining 3.50% exchangeable senior notes due 2028 on September 8. Approximately $150.7 million of principal was retired through a settlement involving approximately $150.97 million in cash and 1,647,862 ordinary shares.
For notes submitted for exchange, principal was paid in cash, and the exchange obligation above principal was settled in shares, with cash for fractional shares where applicable. The share delivery therefore satisfied an existing contractual obligation.
Seagate Technology Holdings plc (NASDAQ:STX) has removed a 2028 maturity and the remaining settlement uncertainty attached to this instrument. Based on the approximately $150.7 million principal balance and 3.50% coupon, the transaction eliminates roughly $5.3 million of annual stated interest. That is a calculated annualized saving before taxes and any interest income lost on the cash used.
Recent cash generation supports the ability to absorb the payment. As of July 3, 2026, Seagate Technology Holdings plc (NASDAQ:STX) reported $1.704 billion in cash and cash equivalents. Fiscal fourth-quarter free cash flow was $1.118 billion. This company-defined non-GAAP measure is operating cash flow less acquisitions of property, equipment, and leasehold improvements.
The settlement cash payment equals approximately 8.9% of that reported cash balance. Although the July figure predates settlement, it provides a useful measure of the transaction's scale.
#technology #million #exchange
27 days ago
PulteGroup, Inc. (PHM) is one of America's largest homebuilders, headquartered in Atlanta, Georgia. It acquires and develops land for residential use and constructs and sells single-family detached homes, townhomes, condominiums, and duplexes. Operating in U.S. markets, the company serves diverse homebuyers through brands including Centex, Pulte Homes, Del Webb, and DiVosta Homes. The company has a market capitalization of $22.76 billion, which makes it a "large-cap" stock.
PulteGroup's shares reached a 52-week low of $108.49 on May 19, but are up 10.1% from that level. Over the past three months, the stock has dropped 2.7%, as investors weigh persistent housing-market headwinds. Meanwhile, the broader S&P 500 Index ($SPX) is up marginally over the past three months. Therefore, PHM has clearly underperformed over this period.
Billionaire Charlie Munger, Who Died at 99, Skipped Insurance on His Mansion Since He Could Just Write a Check to Rebuild — 'All Intelligent People Do It My Way'
The Case for Selling CrowdStrike Stock
Nvidia CEO Jensen Huang Just Dropped Huge News for This Cybersecurity Stock
#Stock #months #atlanta


27 days ago
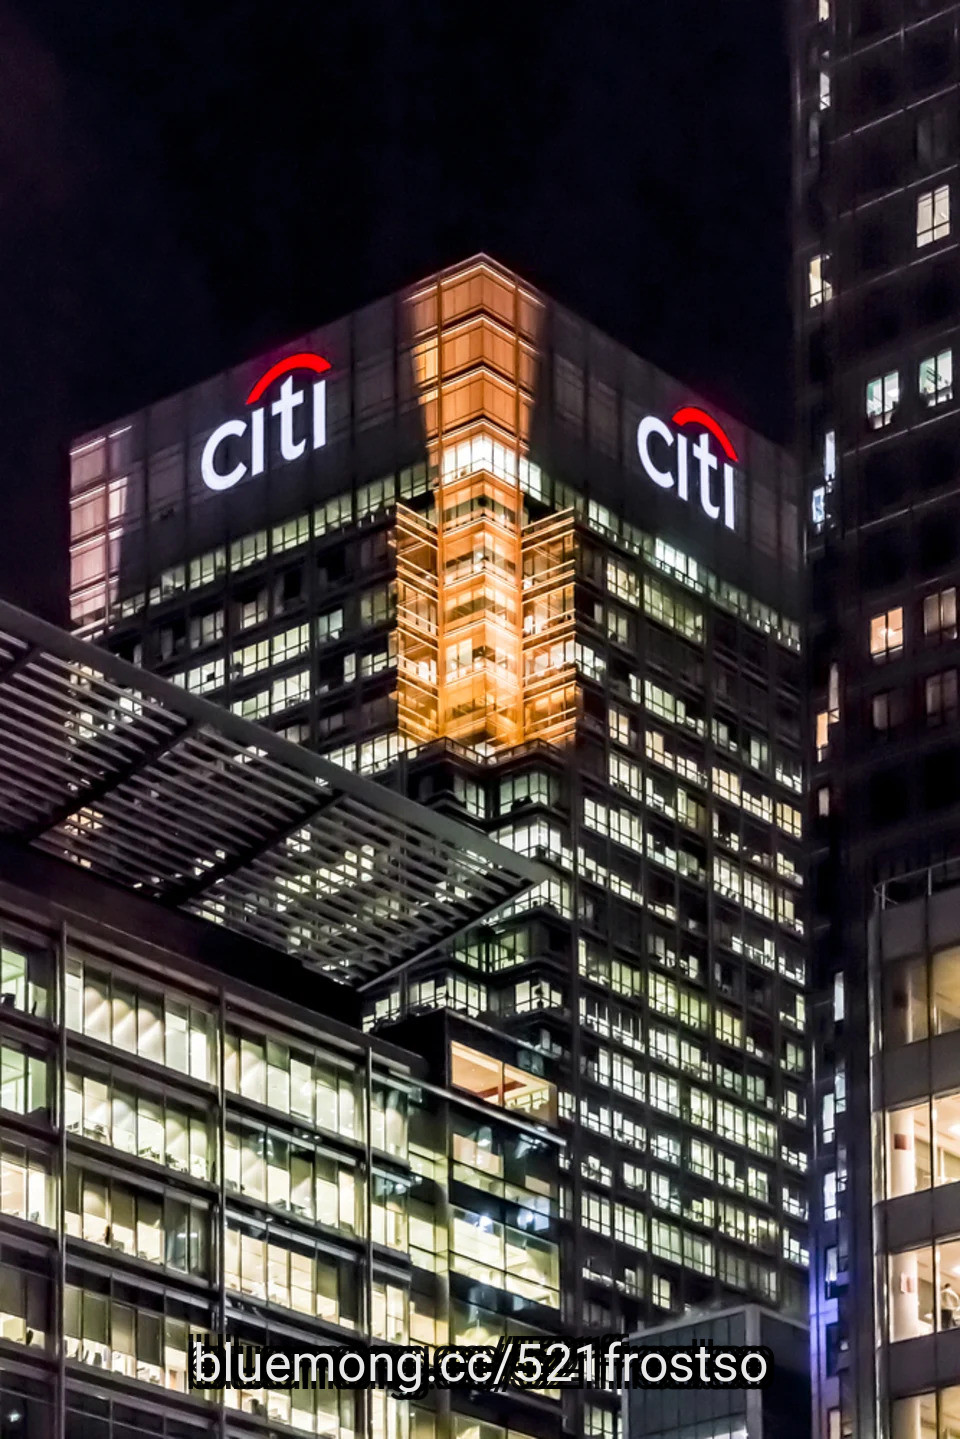
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#rotce #citi #management
27 days ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather

27 days ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ****** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#stage #survival

27 days ago
Novo Nordisk A/S (NYSE:NVO)'s decision to rebrand its day-to-day identity as "Novo" and launch a cultural reset is primarily a strategic response to the company's loss of momentum in the obesity-drug market, rather than a financial restructuring in itself. Reuters reports that the company is trying to regain competitiveness as pressure from Eli Lilly intensifies. The move comes as Novo prepares to unveil new strategic ambitions at its September 21 Capital Markets Day, making the cultural reset potentially important if it leads to faster decision-making, stronger commercial execution and a more aggressive R&D approach.
The underlying business still has substantial scale to protect. Novo generated DKK 309.1 billion of 2025 sales and DKK 127.7 billion of operating profit, while obesity-care sales rose 31% at constant exchange rates to DKK 82.3 billion. However, the company also spent around DKK 8 billion on its transformation in 2025, and its diabetes value-market share fell 3.6 percentage points to 30.1%. The reset therefore comes at a critical point: Novo remains the global obesity-market leader, with a 59.6% branded-volume share in 2025, but Lilly is rapidly narrowing the competitive gap.
A successful cultural reset could improve Novo Nordisk A/S (NYSE:NVO)'s execution at a time when the company needs to convert its scientific and commercial ******* ets into faster growth. Reuters reported that CEO Mike Doustdar is already seeking to accelerate R&D and streamline decision-making following investor concerns about the pipeline and competition from Lilly. If the reorganization reduces internal bureaucracy and improves the speed of clinical, regulatory and commercial decisions, it could help Novo extract more value from its existing obesity portfolio while advancing next-generation treatments before the semaglutide patent cliff expected early next decade.
The company also has ******* ets that give a cultural and operational reset something concrete to build around. Wegovy was available in 52 countries by the end of 2025, while the company's higher-dose Wegovy achieved 20.7% weight loss in Phase 3 studies and its oral Wegovy achieved 16.6% weight loss. More recently, Wegovy received approval in China for MASH, expanding its potential beyond weight management and cardiovascular benefits into another large metabolic-disease market. If Novo Nordisk A/S (NYSE:NVO) can combine these products with better execution, the reset could support higher patient volumes and extend the commercial life of its GLP-1 franchise, helping defend revenue and cash flow despite pricing pressure.
#nordisk #lilly
27 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing **** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited **** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial **** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested **** ets are among Kenvue's stronger European businesses.
#kimberly #revenue #ebitda

27 days ago
On September 13, Reuters reported that Anthropic is in talks to bring NVIDIA Corporation (NASDAQ:NVDA) in as an anchor investor in what could become one of the largest IPOs in history, potentially raising as much as $100 billion at a valuation of around $2 trillion. Nvidia is reportedly considering an investment of up to $10 billion. Anthropic's annualized revenue run rate has reportedly increased from about $9 billion in 2025 to more than $65 billion by mid-2026, with the company targeting as much as $200 billion of revenue by 2028.
The strategic significance for Nvidia is greater than the potential financial return from the investment: Anthropic is a major buyer and user of AI computing infrastructure, and Reuters reported that it has committed $30 billion to Microsoft Azure infrastructure powered by Nvidia chips. Anthropic is also pursuing major capacity agreements with other providers and developing custom chips, making its future hardware choices strategically important to Nvidia.
The move would also deepen an already established relationship. NVIDIA Corporation (NASDAQ:NVDA) has previously disclosed an investment and technology partnership with Anthropic, while its fiscal 2026 filing said it had entered into an agreement to invest up to $10 billion in Anthropic. Nvidia generated $215.9 billion of fiscal 2026 revenue, up 65%, with Data Center revenue up 68%, demonstrating the enormous economic leverage of continued AI infrastructure spending.
The strongest bullish argument is that an equity investment could help NVIDIA Corporation (NASDAQ:NVDA) protect and expand one of the fastest-growing sources of demand for its GPUs. Anthropic's reported annualized revenue growth from $9 billion to more than $65 billion in roughly 18 months implies a rapidly expanding need for training and inference capacity. Its reported $30 billion commitment to Microsoft Azure powered by Nvidia systems provides a particularly direct link between Anthropic's growth and Nvidia's infrastructure demand. Anthropic is also reportedly committing $45 billion to rent AI computing capacity from Nscale, with that infrastructure expected to use Nvidia's Vera Rubin chips, indicating that the relationship can translate into future-generation hardware demand rather than being limited to Nvidia's existing products.
The investment could also strengthen Nvidia's position as AI workloads shift from model training toward large-scale inference and agentic AI. Nvidia recently said Anthropic is evaluating its Vera CPU for CPU-intensive agentic workloads, while Nvidia has positioned Blackwell Ultra and the Vera Rubin platform around the rapidly expanding inference market. Nvidia has disclosed visibility into more than $1 trillion of ***** ulative Blackwell and Rubin revenue from the beginning of 2025 through 2027, with Anthropic among the model developers contributing to that ecosystem. A successful Anthropic IPO would therefore potentially create a well-capitalized AI customer capable o

27 days ago
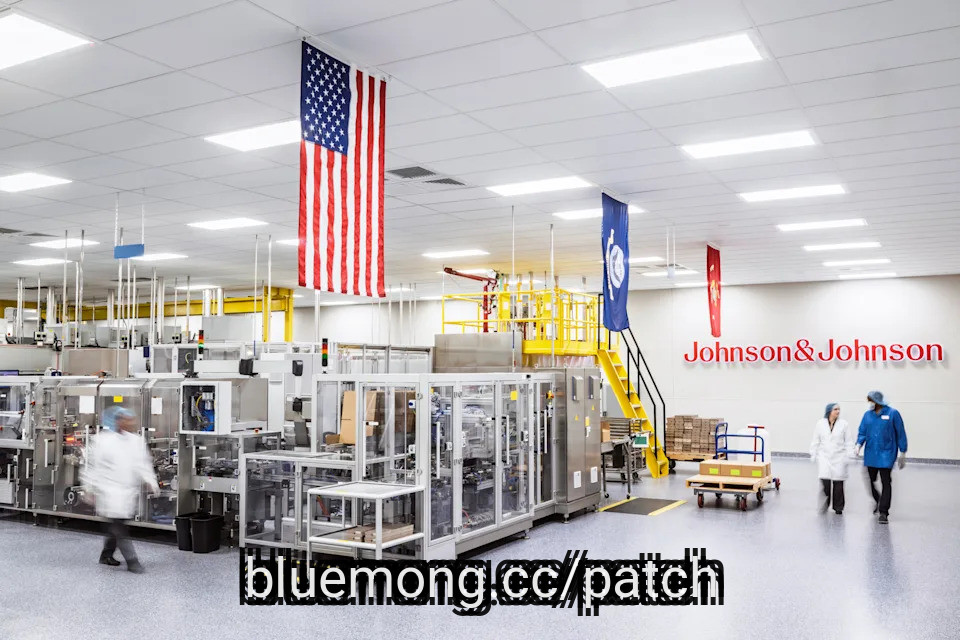
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
27 days ago
GSK plc (NYSE:GSK) plans to close its vaccine manufacturing facility in Dresden, Germany, by summer 2027, putting 641 jobs at risk. The decision reflects declining demand for traditional egg-based flu vaccines, which has left GSK with more manufacturing capacity than it needs. GSK reviewed its Dresden and Ste-Foy, Canada, flu vaccine sites and chose to consolidate production in Canada, which it says can meet anticipated demand more sustainably and competitively.
The closure comes as GSK plc (NYSE:GSK) is shifting its influenza strategy toward newer technology: the company is advancing an mRNA-based seasonal flu vaccine into Phase III after Phase II results showed stronger immune responses than standard-dose vaccines in younger adults and high-dose vaccines in older adults. The broader vaccine environment has also weakened, with Reuters reporting declining sales across flu, RSV, and other vaccines amid lower demand and policy-related pressures, increasing the importance of manufacturing discipline and portfolio selection.
Copyright: kadmy / 123RF Stock Photo
The closure could ultimately strengthen GSK plc (NYSE:GSK)'s margins and cash generation by removing excess capacity from a declining part of the influenza market rather than continuing to carry the fixed costs of an underutilized facility. GSK explicitly said demand for traditional egg-based flu vaccines is falling and that it has more capacity than required, while the Canadian facility can meet anticipated future demand competitively.
This is particularly important because GSK's vaccine business remains a significant earnings contributor but is increasingly being driven by products with better growth prospects: second-quarter 2026 vaccine sales rose 8% to £2.3 billion, with meningitis vaccines up 21% and Arexvy sales increasing by more than 100%, while Shingrix generated £0.9 billion. The Dresden decision therefore looks less like a retreat from vaccines overall and more like a reallocation of manufacturing capacity away from mature egg-based products toward higher-value technologies.
#demand #Manufacturing
27 days ago
Equifax Inc. (EFX) is a global data, **** ytics, and technology company headquartered in Atlanta, Georgia. It operates as one of the "Big Three" credit bureaus, providing consumer and commercial credit reporting, identity and fraud solutions, and decisioning **** ytics to financial institutions, employers, governments, and other enterprises worldwide. The company has a market capitalization of $20.24 billion, which makes it a "big cap" stock.
The stock reached a 52-week low of $150.74 on June 22, but is up 14.3% from that level. Renewed confidence in Equifax's growth initiatives has sent the stock up 5.2% over the past three months. The broader Dow Jones Industrial Average ($DOWI) is up 2.4% over the same period. Therefore, the stock has outperformed the wider index over this period.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Morgan Stanley Doubles Down on Apple Stock as New Offerings Become 'More Exciting'
The EV Bubble Has Burst. How to Play Rivian Stock Now.
#analytics #credit #period #equifax

27 days ago
Colgate-Palmolive Company (NYSE:CL) is reportedly exploring the sale of several mass-market personal care brands, including Softsoap, Irish Spring and Speed Stick, in a portfolio reshaping effort that could generate more than $1 billion. The company is working with Goldman Sachs on the potential divestiture. Personal care accounted for roughly 17% of Colgate-Palmolive's 2025 net sales, or about $3.5 billion, while oral care remains the company's largest business.
The move comes as Colgate faces pressure in its North American business. Although the company recently reported a 4.9% increase in net sales, organic sales in North America declined 3%, highlighting competitive pressure in a mature market. The strategy is also consistent with a broader consumer-goods shift toward simplifying portfolios and concentrating capital on higher-growth categories. Unilever, Nestlé, and other major consumer companies have similarly been selling slower-growing or non-core businesses.
The biggest positive is that Colgate-Palmolive Company (NYSE:CL) could become a more focused and potentially higher-quality business. Selling brands that no longer fit its highest-priority growth areas would allow management to concentrate capital, marketing spending, and management attention on oral care, pet nutrition, and other businesses where Colgate has stronger competitive advantages. The company's decision would therefore be less about abandoning personal care altogether and more about improving the quality of the remaining portfolio.
A sale could also unlock meaningful shareholder value. If the divestitures generate more than $1 billion, Colgate would have additional capital that could be used for debt reduction, share repurchases, acquisitions, or investment behind its strongest brands. In a mature consumer-staples company, disciplined capital allocation can have an outsized impact on earnings growth and shareholder returns. There is also evidence that portfolio simplification is becoming increasingly attractive across the consumer-goods industry. The Wall Street Journal has highlighted how companies such as Unilever and Nestlé are shedding businesses that add complexity without providing sufficient growth. The underlying argument is that the benefits of owning a very broad portfolio have diminished as consumer preferences become more fragmented and smaller brands become better at responding to trends.
Most importantly, the divestiture could improve Colgate-Palmolive Company (NYSE:CL)'s strategic focus at a time when North American competition is challenging. Rather than allocating resources to defend slower-growing personal-care brands, management could direct investment toward categories and geographies with better long-term growth prospects. That could ultimately support margins and organic growth even if the immediate revenue base becomes smaller.
#personal #NYSE #Portfolio
28 days ago
WASHINGTON (AP) — The top Democrat on the House Foreign Affairs Committee said Wednesday that he's going to block a proposed sale of $2.8 billion in heavy weaponry to Israel over concerns that the powerful bombs may not be used in line with U.S. and international law.
Rep. Gregory Meeks of New York said he would withhold approval for the sale because of "grave, unresolved concerns" about how these munitions could be used in densely populated areas of Gaza and Lebanon by Israeli Prime Minister Benjamin Netanyahu's government.
"The Trump administration has not provided sufficient ****** urances that these weapons will be used by the Netanyahu government in accordance with U.S. law and with appropriate protections for civilians," Meeks said in a statement. "I therefore will not clear this sale at this time."
Meeks' objections, however, will not likely affect the sale, which was informally notified to lawmakers on Tuesday. Once it is formally notified to Congress, Secretary of State Marco Rubio can bypass the normal congressional review process by making an emergency determination that the transaction is an urgent national security interest.
Rubio has done so in the past, including bypassing a normal congressional review process to approve a nearly $3 billion sale to Israel last year. The administration then approved a new series of arms sales to Israel totaling $6.67 billion in January.
#used

28 days ago
Citigroup Inc. (NYSE:C)'s CFO Gonzalo Luchetti said the bank expects return on tangible common equity (RoTCE) to come in slightly above 11% in 2026, while also indicating that Citi will increase stock buybacks from the $13 billion repurchased in 2025. The bank plans to accelerate roughly $500 million of investment by year-end, including spending on severance and marketing intended to expand its credit-card and wealth-management businesses. Citi also expects to remove Banamex from its balance sheet in 2027, which will create an estimated $9 billion currency-translation adjustment loss.
The 11%+ target is meaningful because Citi's profitability has already improved materially. In the second quarter, Citi generated $24.8 billion of revenue, up 14% year over year, while net income rose 45% to $5.8 billion. Investment-banking revenue increased 44% to $1.55 billion, and net interest income increased 13%. Citi's SEC filing shows second-quarter RoTCE of 13.0%, versus 8.7% a year earlier, while the first half of 2026 produced a 13.1% RoTCE. The new guidance therefore suggests management believes profitability can remain above the longer-term 11%-13% RoTCE range Citi established for 2027-28, despite additional investment spending.
Kiev.Victor / Shutterstock.com
The bullish argument is that Citigroup Inc. (NYSE:C) appears to be converting its multiyear restructuring into higher returns while simultaneously returning more capital to shareholders. The move from 8.7% RoTCE in the second quarter of 2025 to 13.0% in the second quarter of 2026 represents a substantial improvement in capital efficiency. Citi's efficiency ratio also improved to 57.4% from 62.7%, indicating that revenue growth is increasingly translating into operating leverage rather than being absorbed by expenses. That is particularly relevant because management now intends to spend another roughly $500 million on severance, marketing, and growth initiatives; if these investments produce the intended expansion in cards and wealth management, they could support revenue growth without derailing the profitability trajectory.
Capital returns provide another positive lever. Citi repurchased $13 billion of stock in 2025 and now expects to increase that amount, while its June 2026 CET1 ratio remained 12.78%, comfortably above its 11.6% standardized regulatory requirement. Buybacks can reduce tangible common equity and shares outstanding, potentially supporting both RoTCE and per-share earnings when executed below intrinsic value. Citi's tangible book value per share had already risen 7% year over year to $100.89 by June 30, 2026. The combination of higher operating profitability, shrinking share count, and improving capital efficiency strengthens the case for a valuation re-rating if Citi can sustain returns above 11%.
#year #management
28 days ago
Kimberly-Clark Corporation (NASDAQ:KMB) is preparing ***** et sales to address EU antitrust concerns surrounding its planned $40 billion acquisition of Kenvue, according to Reuters. The company is reportedly seeking to offer remedies that could secure European Commission approval by the September 29 deadline, avoiding a more extensive four-month investigation. Similar regulatory concerns have already emerged in Australia, where the deal received conditional approval after Kimberly-Clark agreed to divest Kenvue's Carefree and Stayfree brands.
The transaction is strategically important because it would create a consumer-health and personal-care company with approximately $32 billion of annual revenue and $7 billion of adjusted EBITDA. Kimberly-Clark Corporation (NASDAQ:KMB) expects about $1.9 billion of annual cost synergies and $500 million of revenue synergies, although it expects to invest roughly $2.5 billion in cash to achieve the cost savings. Therefore, the scale of any EU divestitures will be critical to determining whether Kimberly-Clark can retain the expected economic benefits of the deal.
The strongest bullish argument is that Kimberly-Clark Corporation (NASDAQ:KMB) is actively working toward a regulatory solution rather than allowing the EU review to threaten the transaction. If the company can satisfy regulators through limited ***** et sales, it could preserve the majority of Kenvue's revenue and earnings while moving ahead with the combination. The expected $1.9 billion in annual cost savings represents a substantial earnings opportunity relative to the combined company's roughly $7 billion adjusted EBITDA target, giving Kimberly-Clark significant potential to improve margins and cash generation after integration.
The Australian precedent also suggests that targeted divestitures could be sufficient to resolve competition concerns without materially undermining the broader deal. Securing EU approval by September 29 would be particularly positive because it would remove a major source of uncertainty and allow Kimberly-Clark Corporation (NASDAQ:KMB) to focus on integration and synergy execution. With Kenvue adding major brands across consumer health and personal care, successful completion could also broaden Kimberly-Clark's portfolio and reduce its reliance on its existing product categories.
The biggest risk is that the EU requires more substantial ***** et sales than Kimberly-Clark Corporation (NASDAQ:KMB) currently expects. Giving up attractive Kenvue brands or businesses in Europe could reduce the revenue and EBITDA acquired through the transaction, while Kimberly-Clark would still have to bear much of the financing, transaction, and integration burden. That could make the $40 billion purchase price less attractive on a risk-adjusted basis, particularly if the divested ***** ets are among Kenvue's stronger European businesses.
#revenue


28 days ago
BioNTech SE (NASDAQ:BNTX) reported that its investigational lung-cancer drug gotistobart produced a clinically meaningful overall-survival benefit in the Phase 3 PRESERVE-003 trial in patients with metastatic squamous non-small cell lung cancer whose disease had progressed after prior immunotherapy and chemotherapy. Reuters said gotistobart nearly doubled survival compared with standard-of-care chemotherapy, strengthening the case for the drug as a potential chemotherapy-free treatment in a population with significant unmet need.
The result builds on earlier Stage 1 data, where gotistobart reduced the risk of death by 54% versus docetaxel, with a hazard ratio of 0.46. Median overall survival was not yet reached for gotistobart versus 9.95 months for docetaxel, while the 12-month progression-free survival rate was 25.2% versus 0%. BioNTech is now awaiting the pivotal Stage 2 readout, making the latest result important not only for the drug's approval prospects but also for the credibility of BioNTech's broader transition from a COVID-vaccine company toward a multi-product oncology business.
The strongest bullish argument is that gotistobart now has repeated evidence of a meaningful survival advantage in a difficult-to-treat lung-cancer population. The earlier Stage 1 dataset showed 55.6% of patients alive in the gotistobart arm versus 23.8% with docetaxel, alongside a 54% reduction in the risk of death. The latest Phase 3 update reinforces that signal rather than introducing an entirely new hypothesis. If the pivotal Stage 2 data confirm the benefit, BioNTech SE (NASDAQ:BNTX) could have a differentiated therapy capable of competing on survival rather than simply response rates, potentially supporting meaningful pricing power and a commercially attractive oncology franchise.
The result also strengthens BioNTech's broader oncology strategy because gotistobart is one piece of a much larger pipeline rather than a standalone bet. BioNTech says it has 14 ongoing pivotal trials and more than 10 novel combination programs, while its lung-cancer strategy spans more than 16 ongoing clinical trials and five Phase 3 programs. Gotistobart's success therefore provides validation for the company's immuno-oncology capabilities, while other ***** ets such as pumitamig and antibody-drug conjugates advance toward additional indications. BioNTech has identified 17+ late-stage or pivotal readouts through 2030+, creating the possibility that a successful gotistobart launch becomes the first major commercial proof point in its planned transition to a multi-product oncology company.
#biontech #survival



