3 days ago
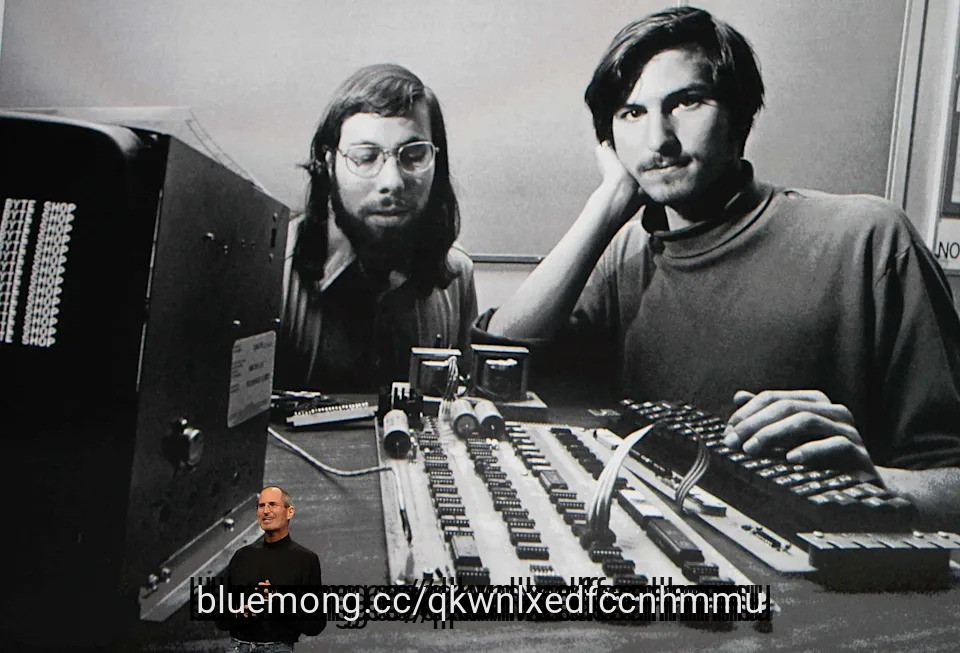
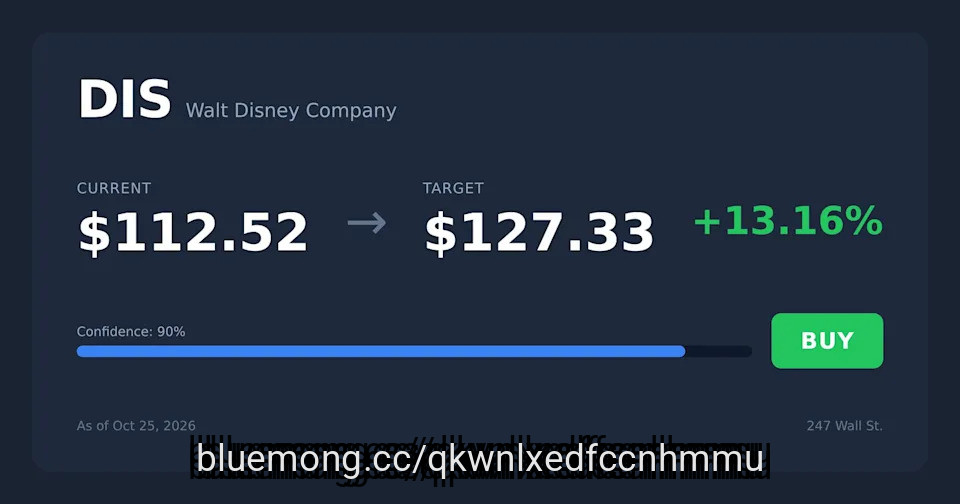
Disney's 2006 all-stock Pixar deal gave Jobs about 138 million DIS shares worth $3.5 billion, outpacing his AAPL stake by more than 4 times.
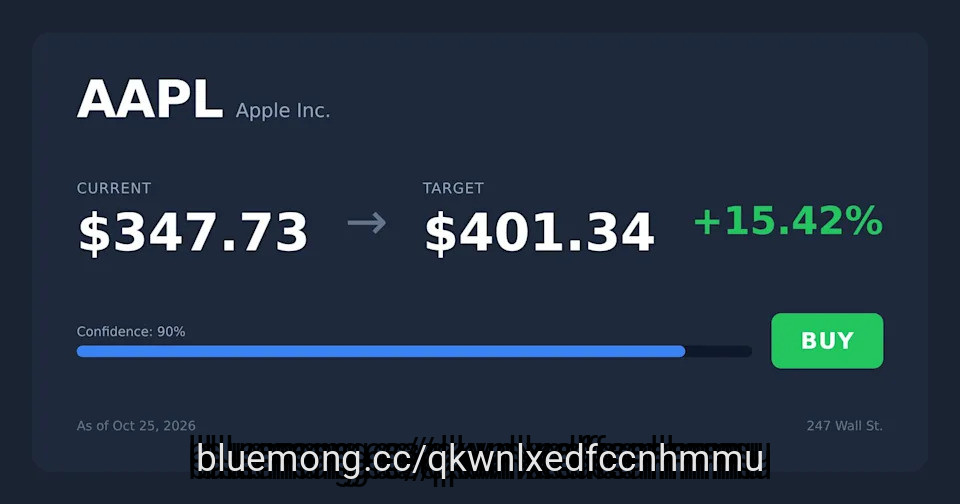
Apple stock rose about 4 times from its 2006 level while Disney gained just 1.23 times, narrowing the gap between Jobs's two largest holdings by 2011.
Read More: Learn 7 ways to generate income with a $1,000,000+ portfolio (sponsor)
Steve Jobs lost his place at Apple (NASDAQ:AAPL) in 1985. What he did next ended up tying his fortune to Disney (NYSE:DIS) as much as to the company he co-founded.
#times #Apple

26 days ago
Kay Dudley tells POEPLE her mother's lupus experience helped her advocate for her own diagnosis after years of being dismissed
The content creator and husband, Tay Dudley, raises awareness through Lupus Foundation of America events and campaigns
Kay relies on pacing herself and accepting Tay's support while parenting their three daughters
Internet personality Kay Dudley has been incredibly open about what life has looked like while navigating her lupus diagnosis.
Speaking with PEOPLE, Kay, who boasts over 18 million followers across the Instagram and TikTok pages she shares with her husband, Tay Dudley, touches on one of the more specific side effects that she has dealt with as a result of learning to navigate the diagnosis — specifically how it shapes the way she shows up for her three daughters daily.
The pair has made it part of their mission online to spread awareness of the disease, a chronic autoimmune condition that can cause inflammation and pain throughout the body. The two frequently partner with the Lupus Foundation of America to help support the organization by promoting donations and leading walks, including this weekend's Walk to End Lupus Now in New York City, which will take place on Oct. 3.
Kay Dudley.
Credit: Bails Shoots
#foundation



1 month ago
Margin debt hit $1.45 trillion in August, up 140% since 2022 and outpacing the S&P 500's 98% gain, which leaves the market carrying far more forced-selling risk.
At roughly 4.5% of GDP, margin debt now exceeds the dot-com bubble's peak, meaning a routine correction could cascade into broker-forced liquidations across the market.
The real danger isn't high leverage itself but the simultaneous forced selling that erupts when overleveraged investors all need cash at once.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
The longer-term comparison is even more striking. Since the end of 2022 -- and the start of the current AI-dominated era -- investor borrowing has increased by $847 billion, or 140%, versus a 98% gain for the S&P 500 over the same period. That means leverage has grown faster than the market value investors have accumulated, presumably as they took on debt to buy into the AI boom.
#market #leverage #investors

1 month ago
GE Vernova Inc (NYSE:GEV) rebounded with Bernstein's backing after an earlier sell-off that followed broader concerns about technology infrastructure spending.
Shares were up 6% at $933.94 during afternoon trading on Wednesday, outpacing the utilities sector's reported 1.24% advance.
GE Vernova also ranked among the three leading stocks by turnover in the utilities sector as its shares recovered from prior-session declines.
Bernstein reaffirmed its "outperform" rating, highlighting electrification demand beyond immediate artificial intelligence data center needs.
The brokerage said utility-driven power grid upgrades, energy security and decarbonization initiatives accounted for the majority of electrification orders.
#backing


1 month ago
Alphabet's (GOOGL) Search revenue grew 17% to $63B and Cloud surged 82% to $25B, even as GOOGL still trades at a market-level P/E of 15.
Alphabet's cloud is outpacing Azure's growth at a cheaper multiple than Microsoft (MSFT), while Meta (META) owns none of Alphabet's cloud, OS, or Waymo ***** ets.
Alphabet's $175B+ CapEx pushed free cash flow negative, but a $460B cloud backlog and 34% operating margin justify the infrastructure bet.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Google made the cut. Enter your email to see the other nine names and why GOOGL earned its spot. The report is free. Enter your email and see the full list.
I keep adding to my position in Alphabet (NASDAQ:GOOGL) because the loudest bear case, that AI would gut Google Search and hollow out the ad engine, keeps getting louder while the numbers keep going the other way. The skeptics said generative AI would strip clicks out of the funnel. Instead, AI is actively boosting the advertising business, and my cost basis has been rising alongside the buy ***** on.
#free


1 month ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual **** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#elastic #vector #company


1 month ago
Coherent jumped 6% and Lumentum climbed 5% with no catalyst, driven by short covering after both stocks fell sharply over the prior month.
SOXX gained only 2% and SPY just 0.3%, making the optics group's surge a positioning-only bounce confined to the sector, not a broad re-rating.
Just released. Our ******* ysts combed the entire stock market and named the ten best stocks to buy right now, and Coherent didn't make the cut. Enter your email to see the names that beat COHR. The report is free. Enter your email and see if any of your stocks made the cut.
Optics stocks are rebounding Wednesday morning without a fresh headline to point to, and the size of the group's move relative to the broader market is the story. The iShares Semiconductor ETF (NASDAQ:SOXX) is at $508.59, up 2%, while the SPDR S&P 500 ETF Trust (NYSEARCA:SPY) is at $759.69, up just 0.3%. The three optics names running today are outpacing both benchmarks by a wide margin.
Coherent Corp. (NYSE:COHR) stock is up 6% to $287.21 in Wednesday morning trading. The bounce arrives after a rough stretch. Coherent shares had fallen 12% over the past month heading into today's session, and that drawdown is the part of the setup that hasn't been undone.
#optics


1 month ago
Anthropic is moving forward with plans for an initial public offering that could value the company at $2 trillion, with signs pointing to the listing remaining on track, according to Bloomberg. Nasdaq has been selected as the venue for the listing, and Nvidia is reportedly weighing a contribution of around $10 billion to the offering.
Bloomberg reports Anthropic's annualized revenue at $65 billion, with the company's margins underpinned by investor confidence in where AI capabilities are headed rather than by today's cash generation.
The IPO comes as Anthropic chief executive officer Dario Amodei has published an essay calling on AI companies to manage the pace of frontier model development. Amodei's essay calls on firms "must slow the pace" of capability improvements, yet frames the goal as "a balanced rate" of progress, with the ****** urance that "progress will still seem fast," Bloomberg notes. When CFO Krishna Rao shared the piece on LinkedIn, his commentary centered on the themes of "pacing" and "common standards."
Anthropic is preparing to tell IPO investors that its potential revenue opportunity exceeds $30 trillion, according to The Wall Street Journal. The company more than doubled its revenue to $11.6 billion in the second quarter and could seek to raise as much as $100 billion in its offering — both figures that would surpass what ****** eX achieved when it went public in June at a $1.77 trillion valuation.
Investors have projected that Anthropic's annualized revenue will reach between $100 billion and $120 billion before year's end, representing more than tenfold growth from the $47 billion annualized revenue the company reported in May, according to the Financial Times as cited in earlier reporting. Morgan Stanley, Goldman Sachs, and JPMorgan are leading the offering. The company filed paperwork with the Securities and Exchange Commission in June.
#billion #bloomberg #trillion #according


1 month ago
On September 11, Elastic (NYSE:ESTC) rolled out Elasticsearch Vector Database, a new serverless offering the company says lets developers ship large-scale vector search and AI applications without stitching together the usual pile of infrastructure themselves. The launch landed less than three weeks after Elastic posted first-quarter fiscal 2027 results on August 27, for the period ended July 31, giving investors a fresh product story to weigh against a quarter that already showed accelerating growth.
The new database automates what used to require manual ***** embly: chunking documents, hosting embedding and reranking models, configuring indexes, and wiring query-time retrieval. Elastic built in expert-tuned defaults, a single field type that handles indexing, embeddings, and chunking together, and hybrid search that combines full-text and vector retrieval in one query. The system scales to hundreds of billions of vectors using Elastic's Better Binary Quantization, which the company says shrinks vector memory by up to 32 times while keeping recall high, and pricing is based on data and search capacity rather than the opaque compute units the company says define most pure-play vector database pricing.
That product push follows a quarter that was already running hot. Total revenue reached $478 million in the first quarter of fiscal 2027, up 15% year over year, while current remaining performance obligations grew 21% and remaining performance obligations grew 27%. Sales-led subscription revenue, which strips out Monthly Elastic Cloud, grew 18% year over year to $399 million, outpacing the company's overall subscription growth.
Elastic added more customers with annual contract value above $100,000 than in any prior quarter, pushing that cohort past 1,800 from over 1,720 in the fourth quarter of fiscal 2026 and over 1,550 a year earlier. Net expansion rate held around 111%, and the company generated $143 million in adjusted free cash flow during the quarter. Guidance for the second quarter of fiscal 2027, ending October 31, calls for revenue of $486 million to $487 million and a swing to positive GAAP operating margin, with full fiscal 2027 non-GAAP operating margin guided to roughly 19.4%, up from 16.2% in the quarter just reported.
Growth came with a reminder that Elastic has not fully crossed into GAAP profitability. The company posted a GAAP operating loss of $24 million in the first quarter of fiscal 2027, a -5% operating margin, and a GAAP net loss per share of $0.16. Non-GAAP figures told a healthier story, with $77 million in non-GAAP operating income and $0.70 in non-GAAP diluted earnings per share, but the gap between the two measures shows how much of Elastic's reported profitability still depends on excluding real costs like stock-based compensation.
#quarter #fiscal #year #operating

1 month ago
Southern Company (SO) and Vistra (VST) both profited from AI power demand, yet VST shares are down 30% over the past year.
U.S. electricity prices climbed 4% over the past year, outpacing headline inflation and directly contradicting Musk's claim that AI data centers lower consumer bills.
The $180 annual savings Musk cited applies to one Georgia utility's contract; new AI-driven generation will land in rate bases all ratepayers fund.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Southern Company didn't make the cut. Enter your email to see the names that beat SO. The report is free. Enter your email and see if any of your stocks made the cut.
At 10:18 a.m. ET on Monday, Elon Musk told his audience that "AI data centers resulting in lower electricity prices for consumers" and pointed to a post claiming Georgia Power's new large-load contracts, overwhelmingly data centers, will save customers nearly a billion dollars, erasing about $180 per year from their bills. The post reached more than 503,000 impressions. Twelve days earlier, West Virginia Governor Patrick Morrisey made the same argument on CNBC, saying net electricity prices will be lower when data centers come in. It is becoming an industry talking point. It is also colliding with the price data Americans actually pay.
#data #centers #company #musk



1 month ago
Cathie Wood, head of Ark Investment Management, often buys her favorite tech stocks when she sees a new opportunity.
That's what she did last week, pouring $27.9 million into Meta Platforms (META) as the company pushes deeper into AI.
Last year, the flagship Ark Innovation ETF gained 35.49%, far outpacing the S&P 500's return of 17.88% in the same period. So far this year, Wood's flagship Ark Innovation ETF (ARKK) is up 8.66% as of writing, while the S&P 500 surged 11.85%, Yahoo Finance data shows.
Wood gained a reputation after the Ark Innovation ETF delivered a rosy 153% return in 2020. But her style also brings painful losses in bearish markets, as seen in 2022, when the ETF tumbled more than 60%.
Those swings have weighed on Wood's long-term gains. As of Sept. 11, her Ark Innovation ETF has delivered a five-year annualized return of -6.89%, while the S&P 500 has an annualized return of 11.42% over the same period, according to data from Morningstar.
#meta #last #period


1 month ago
Leave it to Elon Musk to say, essentially, I've been right all along.
The **** eX (SPCX) and Tesla (TSLA) CEO agreed with Anthropic (ANTH.PVT) CEO Dario Amodei on his essay arguing for pacing AI advances.
The crux of Amodei's argument is that AI using recursive self-improvement "could outrun our ability to understand and control these systems, and so must be pursued very carefully, if at all."
In order to prevent future harms, Amodei said frontier AI companies should commit to embedding third-party evaluators in their organizations that can **** s their AI models and confirm the labs' "adherence to safety practices and commitments, report incidents, and help **** s the alignment of not just completed AI models but training pipelines and processes."
Musk replied on X.com, "Dario is right," but also added later that he's been "sounding the alarm" over AI for some time now, linking back to a post he made back in 2023, when he wrote, "AGI is significantly higher risk than nuclear weapons, in my opinion. Super smart humans have trouble imagining something vastly smarter than themselves."
#assess


1 month ago
Intel's 7% drop and AMD's 6% slide outpace NVIDIA's 3% pullback, an order that is the reverse of AI exposure ranking, suggesting a positioning unwind rather than a demand shift.
SOXX falling 6% against QQQ's 2% drop confirms the sell-off is chip-specific, not a broad Nasdaq retreat.
Amodei explicitly ruled out halting AI training, and Anthropic itself committed to deploying AMD's MI450 GPUs in a disclosed partnership.
Just released. Our **** ysts combed the entire stock market and named the ten best stocks to buy right now, and NVIDIA made the cut. Enter your email to see the other nine names and why NVDA earned its spot. The report is free. Enter your email and see the full list.
Chip stocks are sliding in early Monday trading after an AI pacing appeal over the weekend rippled beyond memory suppliers and into logic and accelerator names. Intel (NASDAQ:INTC) stock is falling 7% to $95.96, AMD (NASDAQ:AMD) stock is down 6% to $486.80, and NVIDIA (NASDAQ:NVDA) stock is declining 3% to $212.50. Intel is falling hardest of the three, NVIDIA is falling the least, and AMD sits in the middle, an ordering that runs opposite to each name's exposure to AI accelerator demand.
#nvda


1 month ago
Dire warnings on AI from the CEOs of Anthropic (ANTH.PVT) and OpenAI (OPAI.PVT) could weigh especially heavily on the business of CoreWeave if the tech is reined in.
"The most exposed name in our coverage is CoreWeave," Bernstein ******* yst Madison Rezaei wrote in a note on Monday. "We estimate that 25% of their existing active U.S. power, with an additional ~74% of their contracted power, is situated in Tier 3 and Tier 4 markets. The backlog is primarily comprised of take-or-pay contracts, so we do not anticipate a threat there, but could see a pullback in demand for the contracted, not-yet-sold rural power if training development slows."
CoreWeave shares fell nearly 7% in premarket trading, one of the worst slides in the AI stock patch on the fresh CEO warnings.
Within the course of two days, AI ******* ans at Anthropic (ANTH.PVT), CEO Dario Amodei, and OpenAI (OPAI.PVT), CEO Sam Altman, have managed to scare the ******* out of the human race with the powerful technology they created and pushed their teams full of pioneering super-coders to supercharge.
"Over the last few months, I have become convinced that fully addressing the risks requires even more prudence — not just investing in risk prevention, but pacing the rate of capabilities advancement so that risk prevention has time to keep up," Amodei stated in a 3,800-word essay on Saturday. "We must slow the pace at which we improve the capabilities of A.I. models. Progress will still seem fast, and we must make wise use of the time we gain."
#power #anth #openai #warnings



2 months ago
On September 3, a caller asked if UnitedHealth Group Incorporated (NYSE:UNH) has enough profitable growth that they should consider adding it to their portfolio. Mad Money host Jim Cramer replied:
Yes, the answer: it does, it does. You know, I've got to tell you, I thought that last quarter was very, very good. The stock market did not like the quarter as much as I thought it would, but the stock's making a stand here. I think that UNH is good to buy.
Cramer's bullish stance rests on the core strength of the company's financial delivery and improving execution. In its second-quarter 2026 report, UnitedHealth Group Incorporated (NYSE:UNH) posted consolidated revenues of $112 billion and operating earnings of $8 billion. Adjusted diluted earnings per share reached $6.38, outpacing Wall Street expectations by $1.48. Driven by strong performance across both the UnitedHealthcare and Optum divisions, management raised its full-year 2026 adjusted EPS guidance to a range of $19.50 to $20. Furthermore, the medical care ratio improved to 86.7% down from 89.4% a year prior, showing that medical cost trends and pricing are aligning effectively.
On the other hand, Wall Street remains cautious about lingering cost pressures across the managed care landscape. Even though the medical care ratio improved compared to last year, patients continuing to utilize medical services at a high rate keeps expenses heavy. At the same time, commercial insurance margins are taking longer to bounce back. Adding in tighter payment adjustments for government-backed plans along with heavy spending on tech infrastructure, cautious investors could have reasons to wait rather than chasing the stock higher.
Insider Monkey's data tracking over 1000 hedge funds shows accumulation by major ****** et managers. 143 hedge funds had positions in UnitedHealth Group Incorporated (NYSE:UNH) in Q2 compared to 130 in Q1. Of those funds, Fisher ****** et Management was the top shareholder with nearly 9.1 million shares. The firm increased its position in the stock by 74% in the quarter. Additionally, short interest remains low, with the short percentage of the float sitting at 1.92%, showing a general lack of aggressive bearish bets against the stock.
#unitedhealth #funds

2 months ago
Apple Inc. (NASDAQ:AAPL) raised the price of Apple TV in the U.S. to $14.99 a month from $12.99 and increased the individual Apple One bundle to $21.95 a month from $19.95, CNBC reported.
Apple TV launched in 2019 at $4.99 a month and has since added significant content, including the film "F1" and a fourth season of "Ted Lasso." The move follows a $1-a-month increase to Apple Music in July, which Apple attributed to licensing costs. Apple reported $30.7 billion in services revenue for its fiscal third quarter, up 12% year over year. The segment's gross margin fell more than a percentage point sequentially, which the company blamed on product mix and foreign exchange headwinds.
The higher price shows a genuinely larger content library, not just a margin grab. Apple TV launched with limited programming at $4.99 a month. It now includes award-winning originals like "Severance" and blockbuster films like "F1" and gives Apple a stronger case that the price increase tracks real value added rather than outpacing what subscribers get.
Apple Inc. (NASDAQ:AAPL) is raising prices in step with the rest of the industry, not standing out as an outlier. Netflix, Hulu, Disney+, and Peacock have all raised their own prices recently, reducing the competitive and reputational risk that price-sensitive subscribers abandon Apple TV specifically for a cheaper alternative.
Services remains a genuine growth engine with real momentum behind it. Revenue in the segment grew 12% to $30.7 billion in the fiscal third quarter, and price increases across Apple TV, Apple Music, and Apple One bundles all flow directly into that high-margin, recurring revenue line, reinforcing one of Apple's most valuable businesses beyond hardware sales.
#Margin #aapl #Services

2 months ago
On August 5, Primerica (NYSE:PRI) reported second-quarter results that read as two different companies bolted together. Net income climbed 13% to $202 million, and earnings per diluted share jumped 19% to $6.45, pushing return on stockholders' equity to 32.1%. Total revenue reached $865 million, up 9% from a year earlier. But those headline figures obscure a split story. The investment arm is sprinting to record highs while the life insurance sales force is quietly getting smaller. Here is what is actually moving the numbers.
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ***** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ***** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ***** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#million #year #rose #sales


2 months ago
On August 13, TSS Inc. (NASDAQ:TSSI) reported second-quarter results that look worse on the top line and better underneath it. Revenue fell 20% year over year to $35.1 million, yet gross profit rose 11% and adjusted EBITDA climbed 12%. The company is deliberately walking away from lower-margin procurement work and leaning into systems integration for AI and HPC infrastructure, a business that grew 46% in the quarter. That trade-off is the whole story right now, and it cuts both ways.
Systems integration revenue reached $13.9 million in the quarter, up 46% from a year earlier, and now makes up 39% of revenue, versus just 22% in last year's second quarter. Facilities management grew even faster, up 84% to $2.7 million. CEO Darryll Dewan said systems integration is expected to keep outpacing the rest of the business given strong demand and the company's track record on complex technology projects.
TSS has started deploying capital toward a planned $17 million investment aimed at the next wave of AI data center technology, a buildout the company expects to start converting into higher systems integration revenue in the third quarter. The company has also put an idle **** et back to work: its former Round Rock integration facility began warehouse operations on May 1, generating $0.3 million in operating lease income during the quarter.
Management is also pointing to stronger months ahead. TSS expects the second half of 2026 to outperform the first half, with accelerated systems integration growth, and it maintained guidance for full-year adjusted EBITDA to land between $20 million and $22 million, at the high end of that band.
The revenue decline is not small. Procurement revenue, still TSS's largest segment by dollars, fell 45% to $18.2 million in the quarter and is down 53% to $58.2 million for the first six months of the year. That drop pulled total revenue down 20% in the quarter and 37% for the year to date, to $90.5 million, even as the higher-margin segments expanded.
#systems #procurement


2 months ago
On August 5, Primerica (NYSE:PRI) reported second-quarter results that read as two different companies bolted together. Net income climbed 13% to $202 million, and earnings per diluted share jumped 19% to $6.45, pushing return on stockholders' equity to 32.1%. Total revenue reached $865 million, up 9% from a year earlier. But those headline figures obscure a split story. The investment arm is sprinting to record highs while the life insurance sales force is quietly getting smaller. Here is what is actually moving the numbers.
Investment and savings product sales hit a record $4.4 billion in the quarter, up 23% from a year ago, while client ****** et values ended the period at an all-time high of $140 billion, up 16%. Net inflows added another $397 million. That growth translated directly into profit. ISP segment revenue rose 21% to $361 million, and pretax income jumped 31% to $104 million, meaning the segment's margin expanded even as it grew. The reason: ****** et-based commission revenue climbed 28%, outpacing the 19% rise in average client ****** ets, thanks to a shift toward higher-margin US managed accounts and Canadian mutual funds.
Primerica also returned $172 million to shareholders in the quarter through $135 million in buybacks and roughly $37 million in dividends, bringing year-to-date capital returns to $352 million. Its effective tax rate improved to 21.7% from 23.9% a year earlier, and its life insurer's statutory risk-based capital ratio stood at approximately 440%, a cushion most insurers would envy.
The company's distribution engine tells a rougher story. The life-licensed sales force fell 3% year over year to 148,612 representatives. Recruiting rose 2% to 82,346 recruits, but far fewer of them actually got licensed: new life-licensed representatives dropped 15% to 11,020. That gap between recruiting and licensing shows up directly in output. The company issued 78,904 life insurance policies, down 12%, with total face amount issued falling 8% to $27.7 billion.
Term Life revenue was roughly flat at $444 million even as adjusted direct premiums rose 3%, and segment pretax income fell 4% to $148 million. Part of that came from cost creep rather than claims: the benefits and claims ratio held steady at 57.9%, but the insurance expense ratio rose to 8.4% from 7.6% a year earlier, eating into a segment that is supposed to be Primerica's stable, predictable cash generator.
#sales

2 months ago
On August 3, UFP Technologies (NASDAQ:UFPT) reported second-quarter net income of $20.9 million, up 21.4% from $17.2 million a year earlier, alongside net sales of $174.0 million, a 15.1% jump from $151.2 million. Both figures, along with adjusted earnings per share of $2.92, marked the best quarter in the company's history. For the six months ended June 30, net income reached $38.3 million on sales of $328.2 million, up from $34.4 million and $299.3 million, respectively, in the same period of 2025. The headline numbers look clean. What sits underneath them is less tidy.
The quarter's strength did not come from one customer or one product line carrying the rest. UFP Technologies' top five customers grew 14.7%, and the remainder of its MedTech business grew even faster, at 19.7%. Organic sales growth, stripping out acquisitions, still ran at 12.4% for the quarter and 6.8% for the first half, which means the base business is expanding on its own rather than relying on deals to pad the numbers. Gross margin climbed to 29.3% from 28.8% a year earlier, and operating income rose 15.5% to $28.1 million, outpacing revenue growth. Adjusted EBITDA followed the same pattern, up 14.3% to $36.4 million for the quarter.
The balance sheet moved in a healthy direction too. Long-term debt, excluding current installments, fell to $104.8 million from $122.9 million at the end of 2025, while total equity grew to $462.4 million from $423.9 million over the same stretch. UFP Technologies also added executives in business development, operations, and legal during the quarter, a sign that management is building out the organization to support the growth it is already seeing rather than reacting to it after the fact.
The same earnings release that touted record results also flagged where the strain is showing. CEO Mitch Rock said the company's ongoing investment in its Dominican Republic operations is "taking longer than anticipated" to pay off and is creating "near-term mix and margin pressure" within the U.S. business. That is a direct admission that the expansion driving future capacity is costing money today. Selling, general and administrative expenses grew 21.8% to $22.8 million, faster than the 15.1% sales growth, pushing SG&A as a percentage of sales up to 13.1% from 12.4%. On an adjusted basis, SG&A crept up to 11.7% of sales from 10.8%.
Not every part of the business is contributing to the growth story either. While MedTech surged, the non-medical segment was flat for the quarter, leaving the entire growth burden on one part of the portfolio. Cash on hand also dropped sharply, falling to $9.0 million from $20.3 million at the end of 2025, even as receivables grew to $113.2 million from $82.9 million and inventories rose to $100.1 million from $86.9 million, a combination that suggests working capital is absorbing more cash than it used to.
#sales

2 months ago
On August 26, HEICO Corporation (NYSE:HEI) delivered a third quarter that management itself struggled to summarize without repeating the word record. Net income jumped 33% to $235.4 million, net sales climbed 23% to $1.4 billion, and the company generated $345.3 million in cash from operations, a figure equal to nearly 150% of net income. For a business that has now compounded earnings for close to four decades, the bigger question is not whether HEICO can grow, but how long it can keep growing this fast.
The headline number is 14% organic growth across the company, but the more telling detail is where that growth showed up. The Electronic Technologies Group posted an all-time quarterly record, with net sales up 36% to $483.5 million and operating income up 55% to $125.6 million, as its operating margin expanded from 22.8% to 26%. The Flight Support Group grew net sales 18% to $947.8 million while its operating income rose 24%, outpacing revenue growth as the segment shifted toward higher-value products rather than volume alone. Co-CEO Victor Mendelson said some missile defense customers have asked for production increases as high as tenfold on specific programs, while industrial technology tied to AI and data center buildouts is now feeding demand inside the electronics segment too.
Management also pointed to the integration of Wencor, with Eric Mendelson calling the combination "an absolute home run for HEICO as well as for Wencor." On the balance sheet, HEICO issued $1.2 billion in senior unsecured notes to pay down its revolver and extended that facility's maturity to June 2031, with room to grow capacity to $3 billion. Net debt to EBITDA improved to 1.57 times. The company also raised its semiannual dividend 8% to $0.13 per share, its 96th consecutive payout since 1979, and closed acquisitions of Cook Defence Systems and CalRamic Technologies during the quarter.
The same demand surge fueling HEICO's growth is straining its supply chain from the other direction. Victor Mendelson warned that lead times for certain raw materials and subcomponents are stretching out and getting more expensive, driven in part by competing demand from the AI and data center markets. Eric Mendelson pointed to a narrower but familiar bottleneck in component repair, noting that a job with 99 parts finished still cannot ship while the company waits on the hundredth. Neither issue derailed this quarter's results, but both suggest the growth machine runs on inputs HEICO does not fully control.
#heico

2 months ago
Sept 02, 2026, 1:45 pm EDT
Palantir Technologies
PLTR
+7.71%
was pacing toward its worst day in seven months on Wednesday in the absence of any appreciable news. It was far from the only software stock taking a beating.
PLTR
+7.71%
Copyright ©2026 Dow Jones & Company, Inc. All Rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8
#jones #company #pacing
2 months ago
MD Sass, a boutique ****** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Flowserve Corporation (NYSE:FLS). Flowserve Corporation (NYSE:FLS) is an industrial company that focuses on industrial flow management equipment. On August 28, 2026, Flowserve Corporation (NYSE:FLS) closed at $80.33 per share. The one-month return of Flowserve Corporation (NYSE:FLS) was 4.95%, and its shares gained 49.70% over the past 52 weeks. Flowserve Corporation (NYSE:FLS) has a market capitalization of $10.21 billion.
MD Sass Concentrated Value Strategy stated the following regarding Flowserve Corporation (NYSE:FLS) in its Q2 2026 investor letter:
"We initiated a position in Flowserve Corporation (NYSE:FLS), a global leader in pumps, valves, seals, and other flow control equipment used across energy, power generation, chemicals, water, and general industrial markets. The company operates through its Pumps and Flow Control divisions and benefits from a large installed base that generates recurring, high-margin aftermarket revenue. Over the past several years, management has materially improved the quality of the business through more selective bidding, portfolio rationalization, and its 80/20 operating framework. Adjusted operating margins reached 14.8% in 2025, up 300 bps from the prior year, and management is targeting approximately 20% by 2030.
While continued margin expansion and aftermarket growth support the investment case, the crux of our thesis is nuclear power. FLS is one of the leading suppliers of highly engineered pumps and valves used in nuclear reactors. These
2 months ago
MD Sass, a boutique ****** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Knight-Swift Transportation Holdings Inc. (NYSE:KNX). Knight-Swift Transportation Holdings Inc. (NYSE:KNX) is a freight transportation services provider that operates through Truckload, Less-than-truckload (LTL), Logistics, and Intermodal segments. On August 28, 2026, Knight-Swift Transportation Holdings Inc. (NYSE:KNX) closed at $67.24 per share, reflecting a market capitalization of $10.94 billion. Knight-Swift Transportation Holdings Inc. (NYSE:KNX) posted a one‑month return of ‑1.04%, while its shares gained 54.24% over the past 52 weeks.
MD Sass Concentrated Value Strategy stated the following regarding Knight-Swift Transportation Holdings Inc. (NYSE:KNX) in its Q2 2026 investor letter:
"Knight-Swift Transportation Holdings Inc. (NYSE:KNX) operates the largest full-truckload fleet in North America and operates approximately 21,000 tractors across its irregular route and dedicated fleets. Excluding fuel surcharges and intersegment transactions, Truckload represents approximately 63% of revenue, less-than-truckload represents 19%, logistics 8%, and intermodal 5%.
Trucking is a cyclical, fragmented, and historically low-margin business, and for those reasons we have avoided it. So why own it now? We believe the industry is entering a rate cycle that is meaningfully different from the demand-driven cycles of the past. This cycle is being manufactured on the supply side through a combination of economic attrition, regulatory enforcement, and increased legal liability. Importantly

2 months ago
MD Sass, a boutique **** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Primo Brands Corporation (NYSE:PRMB) as a notable contributor. Primo Brands Corporation (NYSE:PRMB) operates as a branded beverage company in North America. On August 28, 2026, Primo Brands Corporation (NYSE:PRMB) closed at $23.00 per share. Over the past month, Primo Brands Corporation (NYSE:PRMB) returned 3.00%, while its shares have declined 8.40% in the last 52 weeks. Primo Brands Corporation (NYSE:PRMB) has a market capitalization of $8.32 billion, and its stock has traded within a 52-week range of $14.36 to $26.21.
MD Sass Concentrated Value Strategy stated the following regarding Primo Brands Corporation (NYSE:PRMB) in its Q2 2026 investor letter:
"The largest positive contributors to performance in Q2 were Primo Brands Corporation (NYSE:PRMB), Micron Technology (MU), and Henry Schein (HSIC), which collectively contributed approximately 382 bps. PRMB, a leading North American branded water company with a significant retail and home and office delivery business, declined 23% from its March 3 year-to-date peak amid concerns about commodity inflation following the onset of the conflict in Iran. Prices for plastic resins and other oil-related inputs rose sharply from the end of February through mid-April, raising concerns that PRMB would need to cut guidance given its exposure to PET resin and other packaging costs. The company's May 7 financial results and earnings call provided a big sigh of relief. Management explained that a combination of hedging, forward purchase agreements


2 months ago
MD Sass, a boutique ****** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted ****** og Devices, Inc. (NASDAQ:ADI). ****** og Devices, Inc. (NASDAQ:ADI) is a US-based semiconductor company that engages in the design, manufacture, testing, and marketing of integrated circuits (ICs), software, and subsystem products and was added to the portfolio this quarter. On August 28, 2026, ****** og Devices, Inc. (NASDAQ:ADI) closed at $361.78 per share. Over the past month, ****** og Devices, Inc. (NASDAQ:ADI) returned -0.03%, while its shares have gained 43.96% in the last 52 weeks. ****** og Devices, Inc. (NASDAQ:ADI) has a market capitalization of $175.31 billion, and its stock has traded within a 52-week range of $223.47 to $445.91.
MD Sass Concentrated Value Strategy stated the following regarding ****** og Devices, Inc. (NASDAQ:ADI) in its Q2 2026 investor letter:
"Analog Devices, Inc. (NASDAQ:ADI) is one of the two largest ****** og semiconductor franchises globally. ****** og semiconductors bridge physical and digital systems by sensing, converting, and managing signals and power. The business benefits from long product lives, sticky design wins, a broad customer base, modest capital intensity, and increasing content as systems become more complex and electrified.
Our thesis combines an improving cyclical backdrop with secular growth businesses approaching meaningful inflections. ADI has exposure to data centers, automated test equipment, aerospace and defense, industrial automation, and automobile electrification. While ADI is not a pure play AI company, we


2 months ago
MD Sass, a boutique ****** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted TD SYNNEX Corporation (NYSE:SNX) as a new portfolio holding. TD SYNNEX Corporation (NYSE:SNX) is a leading distributor and solutions aggregator for the information technology (IT) ecosystem. On August 28, 2026, TD SYNNEX Corporation (NYSE:SNX) closed at $253.97 per share. Over the past month, TD SYNNEX Corporation (NYSE:SNX) returned -1.12%, while its shares have declined 69.50% in the last 52 weeks. TD SYNNEX Corporation (NYSE:SNX) has a market capitalization of $20.31 billion.
MD Sass Concentrated Value Strategy stated the following regarding TD SYNNEX Corporation (NYSE:SNX) in its Q2 2026 investor letter:
"During the quarter, we initiated a position in TD SYNNEX Corporation (NYSE:SNX), one of the world's largest IT distributors and a critical intermediary between technology vendors and more than 150,000 customers across over 100 countries. Its core Distribution business aggregates hardware, software, cloud products, and services while providing inventory, financing, configuration, and technical support to resellers and systems integrators. Distribution is a low-margin business, but scale matters, and SNX is increasingly benefiting as major vendors consolidate their channel relationships around a smaller number of global partners.
The crux of our thesis, however, is Hyve Solutions, a hidden growth engine that we believe the market continues to value as part of a traditional IT distributor. Hyve, a wholly owned subsidiary of SNX, designs, manufactures, integrates, and manages th


2 months ago
MD Sass, a boutique **** et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Henry Schein, Inc. (NASDAQ:HSIC) as a notable contributor. Henry Schein, Inc. (NASDAQ:HSIC) is a leading distributor of dental products and services. On August 28, 2026, Henry Schein, Inc. (NASDAQ:HSIC) closed at $89.52 per share. Over the past month, Henry Schein, Inc. (NASDAQ:HSIC) returned 3.48%, while its shares have gained 28.66% in the last 52 weeks. Henry Schein, Inc. (NASDAQ:HSIC) has a market capitalization of $9.98 billion, and its stock has traded within a 52-week range of $61.95 to $92.18.
MD Sass Concentrated Value Strategy stated the following regarding Henry Schein, Inc. (NASDAQ:HSIC) in its Q2 2026 investor letter:
"Henry Schein, Inc. (NASDAQ:HSIC), the world's largest provider of healthcare solutions to office-based dental and medical professionals, appreciated 13% in Q2. Strong earnings results and a positive outlook for the balance of the year created a very favorable setup for the company to exceed its full year guidance. We believe that significant cost reductions, combined with accelerating revenue growth, should lead to material positive earnings revisions as we move into Q4 and 2027. We met with HSIC's new CEO, Fred Lowery, and believe his track record, extensive distribution experience, and "outsider" mentality should translate into improved efficiencies and margins, a more profitable product mix, and market share gains. Our estimates remain well above consensus over the next several years, and we believe the stock remains attractively valued on both an abso

2 months ago
MD Sass, a boutique ******* et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On August 28, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $162.33 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 6.94%, while its shares have declined 8.08% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $91.13 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
MD Sass Concentrated Value Strategy stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"We believe Intercontinental Exchange, Inc.'s (NYSE:ICE) underperformance in Q2 resulted primarily from higher interest rates weighing on enthusiasm for its rate sensitive Mortgage Technology business and heightened concerns about the rise of perpetual futures and their potential impact on ICE's futures exchange business. We decided to exit the position because our thesis on the Mortgage Technology business has not played out as expected. One tenet of our investment thesis was that combining Black Knight with ICE's Mortgage Technology platform would lead to market share gains and significant margin expansion. However, results over several quarters do not suggest that ICE has achieved material share gains, and customer consolidation has produced mixed res

2 months ago
MD Sass, a boutique ******* et management firm, published its second-quarter investor update for its flagship, the "MD Sass Concentrated Value Strategy." The letter can be downloaded here. In the first half of 2026, AI infrastructure stocks led the market, with the Russell 1000 Value increasing by 16.3%, outpacing the S&P 500 (10.2%) and Russell 1000 Growth (5.3%). This growth was fueled by semiconductor, memory, and hardware companies benefiting from AI development, even though they are considered cyclical. These sectors, representing only 7.7% of the Russell 1000 Value at the start of the year, contributed nearly 70% of its returns. The portfolio gained 10.0% in the second quarter, net of fees, compared to 13.9% for the Russell 1000 Value Index. Year-to-date, the strategy returned 6.6%, net of fees, versus 16.3% for the Index. The portfolio faced challenges due to limited exposure to companies with the greatest upside from AI infrastructure investments. It also lacked exposure to the Energy sector, which returned about 20% in the first half amid geopolitical tensions with Iran that increased commodity prices, affecting performance. The firm recognizes the importance of adapting its strategies while maintaining core investment principles as it explores future opportunities in emerging technological themes. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, MD Sass Concentrated Value Strategy highlighted Micron Technology, Inc. (NASDAQ:MU). Micron Technology, Inc. (NASDAQ:MU), a leading semiconductor company manufacturing memory and storage products, contributed to the fund's performance this quarter. On August 28, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $932.86 per share. The one-month return of Micron Technology, Inc. (NASDAQ:MU) was 14.00%, and its shares gained 694.60% over the past 52 weeks. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.05 trillion.
MD Sass Concentrated Value Strategy stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"We owned Micron Technology, Inc. (NASDAQ:MU) for only a portion of the second quarter, but its impact was significant, as the stock appreciated approximately 50% during our holding period. Although MU had already experienced a massive run before we initiated our investment, most of the share price appreciation was driven by positive earnings revisions rather than multiple expansion. In fact, with the stock trading at approximately 6x our earnings estimate for the next 12 months, the market clearly signaled that MU was overearning and that a significant decline in earnings was imminent. We believed this ******* umption, although consistent with previous memory boom and bust cycles, was erroneous. We believed this cycle would remain stronger for much longer for three primary reasons. First, high bandwidth memory ("HBM") is growing rapidly, is less commodity orien