

1 month ago
MACOM Technology Solutions is suddenly giving investors two numbers to think about: its stock has more than doubled over the past year, and its newest optical components push data rates toward another doubling.
asharkyu/Shutterstock.com
MACOM Technology Solutions Holdings, Inc. (NASDAQ:MTSI) announced a 3.2-terabit optical chipset on September 17 built around eight 448-Gbps PAM-4 channels. A day later, BMO Capital upgraded the shares to Outperform with a $335 target, arguing that a 36% decline from the May peak had compressed MACOM's forward valuation to roughly 29 times earnings while data-center fundamentals remained intact.
That puts Coherent Corp. (NYSE:COHR) directly in the conversation because both companies supply the optical connectivity needed to keep larger AI clusters fed with data.
MACOM's new platform combines drivers, photodiodes and transimpedance amplifiers for next-generation optical modules. The company says the components are already available, rather than merely a research roadmap.
#data #macom #holdings #NASDAQ

1 month ago
Affirm Holdings, Inc. (NASDAQ:AFRM) has underperformed the broader market year to date, but the tide is slowly turning. Robust growth in interest-bearing loans, a strategic partnership with Shopify in Australia, and accelerating volumes at Amazon provide multiple avenues for continued growth.
On September 12, Goldman Sachs raised its price target to $115 from $106, citing improving underlying fundamentals. The hike follows the company's impressive fourth-quarter fiscal 2026 results, with revenues surging 33% to $1.2 billion and operating income rising $89 million to $147 million.
The robust revenue growth came as the company continued to attract more business interest-bearing loans. Interest income rose 35% in the fourth quarter, in line with a 33% increase in average net loans held for investment partners. More importantly, 80% of Affirm's direct-to-consumer product loans carried interest at quarter-end, giving the company an increasingly meaningful source of recurring interest income.
The investment bank has also touted the growth opportunity around Affirm Card, which is helping the company expand its relationship with consumers beyond individual BNPL transactions. Active cardholders more than doubled to 5.2 million, resulting in a 124% increase in Card GMV to $2.8 billion.
Management has already hinted at continued upside momentum by estimating a massive increase in GMV to $64 billion in fiscal 2027 and an adjusted operating margin of 30.5%. Against this backdrop, Wolfe Research ****** yst Darrin Peller upgraded the stock to Outperform with a $90 price target. According to the ****** yst, Affirm Holdings is a winner in the point-of-sale financing ****** e.
#interest #billion #company


1 month ago
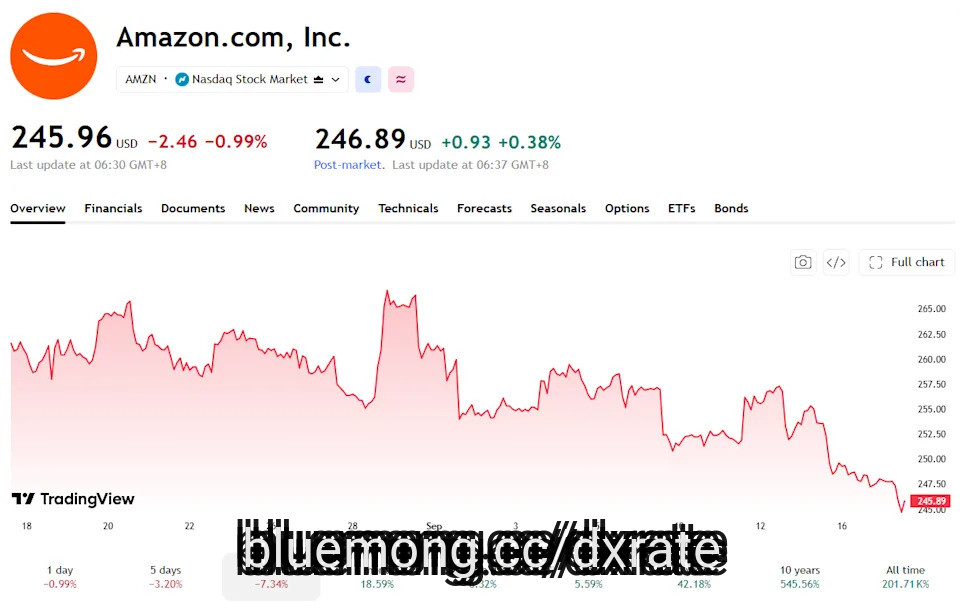
Apollo Global Management warned Wednesday that credit default swaps on hyperscaler debt are pricing in more risk. Chief economist Torsten Slok tied the shift to weakening credit fundamentals rather than routine bond-dealer hedging.
Hyperscalers are the cloud computing giants, including Amazon, Microsoft, Google, and Meta, that run the infrastructure behind the AI boom. They face a credit default swap (CDS) gap against bank debt, widened to about 60 basis points since October 2025.
Slok made the case in a Wednesday note reported by CNBC.
"What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating ****** ets."
Dan Alpert, founding managing partner of Westwood Capital, compared the setup to the run-up to the 2008 mortgage crisis. He said banks have since built far bigger equity buffers and are more diversified than they were then.
#slok

1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#mckesson #alluvium #global


1 month ago
AI data centers are facing growing power constraints, and the issue is becoming increasingly urgent. New utility capacity can take years to develop and bring online, but hyperscalers cannot afford to wait that long to support their growing computing needs. That gap between supply and demand creates an opportunity for Bloom Energy (BE), which is focused on delivering power where and when hyperscalers like Microsoft (MSFT), Amazon (AMZN), and Alphabet (GOOG) (GOOGL) require it. The fundamentals are now starting to provide support for the growing optimism around its opportunity.
Bloom Energy's technology stands out because it can address the AI power challenge on a much shorter timeline. The company's solid-oxide fuel cells are manufactured in factories and can be moved where required. They can also be deployed much faster than traditional power infrastructure. Instead of waiting years for grid upgrades or additional turbine capacity, data center developers can install Bloom Energy's systems and bring power online in a much shorter timeframe. As AI infrastructure expands, that speed has helped the company establish itself as an increasingly important on-site power vendor. All major U.S. hyperscalers are also providing validation of its position.
Why UBS Just Turned Bearish on NuScale Power Stock
Crude Oil Prices Retreat as Supply Fears Ease
Crude Prices Soar as Global Oil Supplies Continue to Tighten
#bloom #crude



1 month ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #remax #NASDAQ #long


1 month ago
Wasatch Global Investors, an ****** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#fund


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On September 15, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $423.04 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.93% over the past month, and its shares are up 5.92% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $91.76 billion.
Conventum – Alluvium Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). HCA Healthcare, Inc. (NYSE:HCA), the hospital operator, fell 17.5%. The share price fell 8.8% immediately following its first quarter results (despite management reaffirming its 2026 guidance). We suspect this is a (over) reaction to poorer than expected respiratory volumes due to a mild flu season. With the shares trading at a discount to our valuation we bought a little more to bring the Fund's position to 6.4%."
HCA Healthcare, Inc. (NYSE:HCA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 75 hedge fund portfolios held HCA Healthcare, Inc. (NYSE:HCA) at the end of the second quarter which was 70 in the previous quarter. While we acknowledge the potential of HCA Healthcare, Inc. (NYSE:HCA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#quarter #fund #alluvium #conventum


1 month ago
Alluvium ******* et Management, an ******* et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted McKesson Corporation (NYSE:MCK). McKesson Corporation (NYSE:MCK) is a leading healthcare services company headquartered in Irving, Texas. On September 15, 2026, McKesson Corporation (NYSE:MCK) closed at $899.56 per share. Over the past month. McKesson Corporation (NYSE:MCK) returned 5.37% and its shares gained 29.95% over the past 52 weeks. McKesson Corporation (NYSE:MCK) has a market capitalization of $106.21 billion, and its stock has traded with a range of $687.68 and $999.00.
Conventum – Alluvium Global Fund stated the following regarding McKesson Corporation (NYSE:MCK) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). McKesson Corporation (NYSE:MCK), the drug distributor (down 12.6%), reported its full year results which were perfectly in-line with our expectations. Management provided strong guidance for its next year's earnings, and reiterated its 13%-16% long term growth expectations. After feeding the numbers through our model, our valuation increased by 18%, and with the share price trading below it, we bought a little more such that it accounts for 6.8% of the Fund."
McKesson Corporation (NYSE:MCK) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 77 hedge fund portfolios held McKesson Corporation (NYSE:MCK) at the end of the second quarter which was 73 in the previous quarter. While we acknowledge the potential of McKesson Corporation (NYSE:MCK) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #fund #conventum #global

1 month ago
Wasatch Global Investors, an ***** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Bloom Energy Corporation (NYSE:BE). Bloom Energy Corporation (NYSE:BE), designs and manufactures solid-oxide fuel cell systems for clean, reliable, on-site power generation. On September 15, 2026, Bloom Energy Corporation closed at $259.35 per share. Over the past month, Bloom Energy Corporation returned 25.51%, and its shares are up 225.53% over the past year. Bloom Energy Corporation has a market capitalization of $76.39 billion, and its stock has traded within a 52-week range of $61.37 to $351.28.
Wasatch Long/Short Alpha Fund stated the following regarding Bloom Energy Corporation (NYSE:BE) in its Q2 2026 investor letter:
"Turning to short positions, detractors from Fund performance were those stocks that rose in price. One of the largest detractors was Bloom Energy Corporation (NYSE:BE). Bloom Energy sells natural, gas-powered fuel cells that help data centers generate power on-site before the centers can connect to the electrical grid. Bloom's stock price has increased significantly in recent months, and we believe it is representative of some of the AI-related exuberance in the small cap market."
Bloom Energy Corporation (NYSE:BE) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 116 hedge fund portfolios held Bloom Energy Corporation (NYSE:BE) at the end of the second quarter, up from 91 in the previous quarter. While we acknowledge the potential of Bloom Energy Corporation (NYSE:BE) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#wasatch


1 month ago
Wasatch Global Investors, an **** et management company, released its "Long/Short Alpha Fund" Q2 2026 investor letter. The letter can be downloaded here. Small- and mid-cap growth stocks posted significant gains in Q2, led primarily by AI-related companies. The Russell 2500 Index rose 20.26%, while the Wasatch Long/Short Alpha Fund—Investor Class increased by 8.29%. However, the fund faced challenges due to the outperformance of lower-quality companies, which negatively impacted its long positions. Despite trailing the benchmark and some losses in short positions, the fund remains confident in its long portfolio's fundamentals, which have not deteriorated. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Wasatch Long/Short Alpha Fund highlighted Real REMAX Group Inc. (NASDAQ:REAX). Real REMAX Group Inc. (NASDAQ:REAX) is a real estate technology company that provides **** le, mortgage, wallet, and franchising and ancillary services. The Real Brokerage, Inc. changed its name to Real REMAX Group Inc. (NASDAQ:REAX) in August 2026. On September 15, 2026, Real REMAX Group Inc. (NASDAQ:REAX) closed at $19.27 per share. Over the past month, Real REMAX Group Inc. (NASDAQ:REAX) declined 30.93%, but its shares are down 61.84% over the past year. Real REMAX Group Inc. (NASDAQ:REAX) has a market capitalization of $422.42 million, and its stock has traded within a 52-week range of $15.50 to $52.50.
Wasatch Long/Short Alpha Fund stated the following regarding Real REMAX Group Inc. (NASDAQ:REAX) in its Q2 2026 investor letter:
"Among shorts, contributors to Fund performance were those stocks that declined in price. One of our largest contributors was REMAX Group Inc. (NASDAQ:REAX). The company operates a cloud-based real estate platform operating across the U.S. and Canada. Real Brokerage's stock was down due to concerns about how AI may disrupt its business model."
Real REMAX Group Inc. (NASDAQ:REAX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 25 hedge fund portfolios held Real REMAX Group Inc. (NASDAQ:REAX) at the end of the second quarter, compared to 21 in the previous quarter. While we acknowledge the potential of Real REMAX Group Inc. (NASDAQ:REAX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#real #reax


1 month ago
Alluvium ****** et Management, an ****** et management company, released its "Conventum – Alluvium Global Fund" second-quarter 2026 investor letter. The letter can be downloaded here. The second quarter reflected a sharp shift from geopolitical uncertainty and oil market volatility to a powerful equity rally led by semiconductor companies. Despite the broader market strength, the Fund declined 1.4% in EUR terms, 2.2% in USD terms, and 3.9% in AUD terms. Portfolio results were mixed, with Alphabet benefiting from strong Cloud growth, while Robert Half, H&R Block, and other holdings posted solid gains. However, cable businesses and several healthcare and consumer holdings weighed on performance. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Conventum – Alluvium Global Fund highlighted HCA Healthcare, Inc. (NYSE:HCA). HCA Healthcare, Inc. (NYSE:HCA) owns and operates hospitals and related healthcare entities. On September 15, 2026, HCA Healthcare, Inc. (NYSE:HCA) closed at $423.04 per share. HCA Healthcare, Inc. (NYSE:HCA) returned 3.93% over the past month, and its shares are up 5.92% over the past year. HCA Healthcare, Inc. (NYSE:HCA) has a market capitalization of $91.76 billion.
Conventum – Alluvium Global Fund stated the following regarding HCA Healthcare, Inc. (NYSE:HCA) in its Q2 2026 investor letter:
"Our two healthcare companies had a poor quarter (in terms of share price performance, not business fundamentals). HCA Healthcare, Inc. (NYSE:HCA), the hospital operator, fell 17.5%. The share price fell 8.8% immediately following its first quarter results (despite management reaffirming its 2026 guidance). We suspect this is a (over) reaction to poorer than expected respiratory volumes due to a mild flu season. With the shares trading at a discount to our valuation we bought a little more to bring the Fund's position to 6.4%."
HCA Healthcare, Inc. (NYSE:HCA) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 75 hedge fund portfolios held HCA Healthcare, Inc. (NYSE:HCA) at the end of the second quarter which was 70 in the previous quarter. While we acknowledge the potential of HCA Healthcare, Inc. (NYSE:HCA) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#healthcare #quarter #letter

2 months ago
Updated Sept. 11, 2026 3:51 pm ET
Listen
(3 min)
1547 ET – U.S. natural gas futures end the week lower as the market enters the shoulder season where summer cooling demand tapers off before early-season heating demand starts to kick in. Last week’s 40 Bcf storage injection was bigger than expected, but smaller than average, leaving inventories 148 Bcf above the five-year average. “Elevated production and falling power demand point to larger injections ahead, leaving firm LNG demand as the main counterweight to the seasonal loosening,” Gelber & ***** ociates says in a note. Nymex front-month gas settles down 0.1% at $2.831/mmBtu for a 4.8% loss on the week.(anthony.harrupwsj.com)
0951 ET – U.S. natural gas futures are giving back yesterday’s small gains and on track for weekly losses as summer ends and cooling demand is set to ease into the autumn. Futures “remain in a sell-the-strength type trade,” Dennis Kissler of BOK Financial says in a note. “While the fundamentals still favor the bears, the market seems to be well supported near the $2.75-$2.70 area.” Nymex natural gas for October delivery is off 0.7% at $2.813/mmBtu.(anthony.harrupwsj.com)
#market #summer #average


2 months ago
Options traders can spend hours searching for the right stock, studying charts, comparing fundamentals and trying to predict the market's next move.
But Barchart expert Rick Orford argues there's another question worth answering before any of that:
Options Flow Alert: Institutional Money Piles Into AMD Stock
Volatility Insurance for Applied Optoelectronics (AAOI) Stock Potentially Inspires a Contrarian Outlook
Unusual Options Activity Points to Big Institutional Bets on These 3 Industries
#options #institutional #money


2 months ago
Pinterest's CFO resignation and slowing Q3 guidance are repricing its 54x P/E multiple, sending PINS down 21% this month while RDDT falls just 2%.
SOCL and SPY are off just 1% and 0.4%, confirming Pinterest's selloff is company-specific rather than a broad social-advertising sector rotation.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Pinterest didn't make the cut. Enter your email to see the names that beat PINS. The report is free. Enter your email and see if any of your stocks made the cut.
Pinterest (NYSE:PINS) stock is sliding again Wednesday afternoon, and the frustrating part for holders is that there's no fresh company headline attached to the move. Pinterest shares are down 8% to $18.59, extending a punishing stretch that has taken the stock down 21% over the past month and pushing it back near the average price where management ran its recent buyback program.
The social peers are softer but nowhere near as weak. Reddit (NYSE:RDDT) stock is down 2% to $147.04, and Snap (NYSE:SNAP) stock is off 1% to $5.36. Both names posted clean Q2 2026 beats earlier this summer, so today's fade for the peer group reflects a sentiment reset across advertising-driven names more than a fundamentals reaction.
#pinterest
SOCL and SPY are off just 1% and 0.4%, confirming Pinterest's selloff is company-specific rather than a broad social-advertising sector rotation.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Pinterest didn't make the cut. Enter your email to see the names that beat PINS. The report is free. Enter your email and see if any of your stocks made the cut.
Pinterest (NYSE:PINS) stock is sliding again Wednesday afternoon, and the frustrating part for holders is that there's no fresh company headline attached to the move. Pinterest shares are down 8% to $18.59, extending a punishing stretch that has taken the stock down 21% over the past month and pushing it back near the average price where management ran its recent buyback program.
The social peers are softer but nowhere near as weak. Reddit (NYSE:RDDT) stock is down 2% to $147.04, and Snap (NYSE:SNAP) stock is off 1% to $5.36. Both names posted clean Q2 2026 beats earlier this summer, so today's fade for the peer group reflects a sentiment reset across advertising-driven names more than a fundamentals reaction.


2 months ago
Every ETF.com fund page follows the same simple pattern: etf.com/[TICKER]. Want the Invesco QQQ Trust? Go to etf.com/QQQ. Want the Vanguard S&P 500 ETF? etf.com/VOO. Each page pulls together the fund's real-time market data, fundamentals, holdings, cost, and **** ysis into one place — so you don't have to hunt across a dozen websites to research a fund. Using QQQ as our example, here's what you'll find.
At the top of every fund page is the live quote — the fund's current price, daily change, and an intraday chart showing how it's moved through the trading day. Alongside it you get the essential trading data: previous close, opening price, volume, the day's range, the 52-week range, and real-time bid/ask prices and sizes. This is the information you need to actually place a trade intelligently — especially the bid/ask spread, which tells you how cheaply you can get in and out.
The Summary Data section gives you the fund's vital statistics in seconds: the issuer (who runs the fund), the inception date (how long it's existed), the expense ratio (what it costs you annually), the AUM (assets under management — a proxy for size and liquidity), the index tracked, the segment, and the fund's legal structure. For QQQ, this is where you'd instantly see it's an Invesco fund tracking the Nasdaq-100. These are the first things any investor should check before buying.
One of the most useful features is the Competing ETFs list. Rather than making you research alternatives on your own, the fund page shows you similar funds side by side — with their AUM and expense ratios — so you can immediately see whether a cheaper or larger competitor exists. On the QQQ page, for example, this is where you'd spot alternatives like QQQM. It turns a single-fund lookup into instant comparison shopping.
Right on the page, the built-in Compare ETFs tool lets you pit the fund against any other ticker — QQQ vs. VOO, QQQ vs. QQQM, whatever you choose — and see the differences in cost, holdings, and performance line by line. It's the fastest way to answer the question every ETF investor eventually asks: "Which of these two should I actually buy?"
#page #invesco #qqqm #real

2 months ago
Oscar Health (OSCR) exhibits strong technical momentum, recently setting a new all-time high.
The stock is up more than 55% over the past year.
OSCR's fundamentals are robust. Revenue is projected to grow 60.17% this year, with earnings estimated to rise 203.58%.
Analyst sentiment is broadly positive, with multiple "Strong Buy" ratings and price targets ranging from $25 to $39.
Valued at $10.2 billion, Oscar Health (OSCR) is a digital health insurance company.
#strong


2 months ago
The Iowa football program has always prided itself on a strong running game led by a tough offensive line and gritty backs. Even though football has evolved into more of a passing sport, Kirk Ferentz hasn't forgotten the fundamentals of what he's built his program on.
That was evident in the Hawkeyes' 2026 season opener on Saturday.
Iowa established the run game early and often in its 40-0 win over Northern Illinois. The Hawkeyes finished the game with 38 carries for 289 yards, averaging 7.6 yards per carry. They also had two rushing touchdowns, which both came in the first quarter courtesy of fourth-year running back Kamari Moulton.
Moulton opened 2026 with a 50-yard score behind pristine blocking from the offensive line. A few minutes later, he added a 37-yard touchdown run to his ledger, once again following some fantastic blocks. By the time the first quarter came to an end, Moulton had already rushed for over 130 yards.
Kamari Moulton has 6 carries for 132 yards and 2 TD’s today. It’s still the first quarter. pic.twitter.com/qJsJGwszdC
#program



2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
Management is prioritizing a return to core fundamentals in the Snacks division, specifically targeting households with kids for Goldfish and launching national brand campaigns for Pepperidge Farm.
The Meals and Beverage segment is leaning into 'semi-scratch' cooking trends, which represent 50% of at-home cooking occasions, by focusing on convenience with 5-ingredient-or-less recipes.
Performance attribution highlights a divergence in the soup portfolio, where cooking-related products (broth and condensed) are performing well while 'eating' soups require further innovation to meet consumer value needs.
The company is implementing a new $500 million enterprise cost-savings program through fiscal 2030, focusing on procurement efficiencies and supply chain network optimization.
#focusing


2 months ago
WestEnd Capital Management, an investment advisor, released its Q2 2026 investor letter. The letter can be downloaded here. WestEnd Capital Management's Core Strategy achieved a 16.3% net return in the quarter, surpassing the S&P 500's 15.0%. This performance stemmed from strong earnings generators and upward earnings revisions, showcasing U.S. companies' efficiency in converting sales into profits. S&P 500 net profit margins reached a decade-high of 14.8% in Q1 and are expected to remain above 14% in Q2 despite challenges like higher interest rates and geopolitical uncertainty. Technology remains a key focus in WestEnd's portfolio, along with investments in infrastructure, demographic shifts, financial innovation, and selective consumer opportunities. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, WestEnd Capital Management highlighted Janus Living, Inc. (NYSE:JAN). Janus Living, Inc. (NYSE:JAN) is the only U.S. publicly traded REIT focused exclusively on the senior housing sector and the only U.S. publicly traded REIT. On September 2, 2026, Janus Living, Inc. (NYSE:JAN) closed at $30.70 per share. Over the past month, Janus Living, Inc. (NYSE:JAN) returned 5.51%, and its shares are up 27.08% over the three months. Janus Living, Inc. (NYSE:JAN) has a market capitalization of $9.45 billion.
WestEnd Capital Management stated the following regarding Janus Living, Inc. (NYSE:JAN) in its Q2 2026 investor letter:
"Janus Living, Inc. (NYSE:JAN) is one of the nation's largest pure-play owners and operators of senior housing communities. Unlike traditional triple-net REITs that collect fixed lease payments, Janus generates operating income directly from resident rents and service fees. That means the company captures the full operational upside as occupancy and rental rates increase, while also ******* uming the operational risks of running its communities. Because residents pay privately rather than through Medicare or Medicaid reimbursement programs, the business is largely insulated from changes in government reimbursement policy.
The industry's long-term fundamentals remain compelling:
#westend


2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7% gain. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted DoorDash, Inc. (NASDAQ:DASH). DoorDash, Inc. (NASDAQ:DASH) is a US-based leading online food ordering and delivery platform. On September 2, 2026, DoorDash, Inc. (NASDAQ:DASH) closed at $226.24 per share. DoorDash, Inc. (NASDAQ:DASH) returned 8.87% over the past month, while its shares lost 9.06% over the past 52 weeks. DoorDash, Inc. (NASDAQ:DASH) has a market capitalization of $98.04 billion.
Sands Capital Select Growth Fund stated the following regarding DoorDash, Inc. (NASDAQ:DASH) in its Q2 2026 investor letter:
"The sales of DoorDash, Inc. (NASDAQ:DASH) and Nu Holdings reflected the high bar for inclusion in a concentrated portfolio of roughly 30 businesses. We continue to view both companies as high-quality businesses and will monitor them closely but believe the portfolio would be better served by reallocating capital toward AI infrastructure beneficiaries and other idiosyncratic growth opportunities."
DoorDash, Inc. (NASDAQ:DASH) is on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 107 hedge fund portfolios held DoorDash, Inc. (NASDAQ:DASH) at the end of the second quarter which was 117 in the previous quarter. While we acknowledge the potential of DoorDash, Inc. (NASDAQ:DASH) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#doordash #dash #letter

2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7% gain. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Micron Technology, Inc. (NASDAQ:MU). Micron Technology, Inc. (NASDAQ:MU) is a leading semiconductor company manufacturing memory and storage products. On September 02, 2026, Micron Technology, Inc. (NASDAQ:MU) closed at $956.08 per share. Over the past month, Micron Technology, Inc. (NASDAQ:MU) returned 8.46%, but its shares are up 669.73% over the past year. Micron Technology, Inc. (NASDAQ:MU) has a market capitalization of $1.08 trillion, and its stock has traded within a 52-week range of $118.52 to $1,255.00.
Sands Capital Select Growth Fund stated the following regarding Micron Technology, Inc. (NASDAQ:MU) in its Q2 2026 investor letter:
"Micron Technology, Inc. (NASDAQ:MU) and SanDisk increased the portfolio's exposure to memory, which has become a critical bottleneck in the AI infrastructure stack. Agentic AI systems require greater context, faster retrieval, and more persistent memory, increasing demand for DRAM, high-bandwidth memory, and NAND. At the same time, advanced memory remains difficult, capital intensive, and time consuming to manufacture. The industry has also become more consolidated and disciplined, which should limit the speed of supply response. We believe this combination of accelerating demand and constrained supply can support stronger pricing, better margins, and a more durable earnings cycle for leading memory providers."
#NASDAQ #fund #sands #investor

2 months ago
Deere & Company (NYSE:DE) seems to have attracted renewed attention from ***** ysts after an impressive rise in its stock so far this year. As of August 31, the stock gained more than 35%. On August 31, Baird upgraded its rating on Deere & Company (NYSE:DE) from Neutral to Outperform and lifted its price target from $640 to $800.
Bull Case
Baird sees a favorable setup for Deere & Company (NYSE:DE) because of its high exposure to North American row-crop equipment demand. The research firm expects the company to be among the first agricultural equipment companies to benefit when investors see a recovery in the agricultural sector.
The firm also noted that commentary on early order programs indicated that orders for planters and sprayers were up by a mid-single-digit percentage compared with last year's completed program. Baird believes that this suggests early order programs could end up higher by completion and this also provides early signs of a possible recovery in production and precision agriculture.
According to Baird, the current early order programs could be significantly underestimating the actual demand potential for production and precision agriculture in 2027 if its ***** sment of corn and soybean fundamentals proves correct. The firm noted that the potential recovery should continue into 2028.
#early
2 months ago
In the world of robotic surgery, one company is both the undisputed leader and the most expensive option, forcing investors to ask if operational excellence is worth the premium.
Intuitive Surgical (ISRG), the pioneer of robotic-assisted surgery, trades around $370, a share after a tough year. The stock has delivered a -21% return over the last twelve months, badly trailing the S&P 500's +19.2% gain. Yet, within its peer group, it commands the highest valuation. Why does the market charge a top-tier price for the company with the group's worst-performing stock?
By the numbers, Intuitive Surgical's operational lead is real, even if Globus Medical sits close behind at 19.7%. The company's revenue grew 21% over the last twelve months, well ahead of diversified rivals like Medtronic, which grew at 8.4%.. Its 31% operating margin also leads the pack, again comfortably ahead of Medtronic's 18.8%. This is a business that executes at a higher level than its competition. The market sees this performance and charges accordingly. Intuitive Surgical trades at 42.5 times earnings, the highest multiple in its group. For comparison, Medtronic trades at a much lower 24.2 times earnings. The mismatch is stark: investors are paying a premium for leading fundamentals, but so far, that premium has not translated into positive returns.
ISRG
MDT
#robotic


2 months ago
Listen
(3 min)
1523 ET – Oil futures rise for a third straight session as strikes between the U.S. and Iran raise concerns about further escalation and oil flows out of the Persian Gulf. The EIA reported a bigger-than-expected 4.5 million barrel draw in U.S. commercial crude oil stocks for last week, while the Department of Energy released another 3.1 million barrels from the Strategic Petroleum Reserve. The withdrawal “keeps attention on the increasingly tight market dynamics,” says David Russell of TradeStation. Diesel stocks are at the lowest on record for the time of year as farmers and truckers enter their high-demand season, he adds. “Supply and demand fundamentals are taking over as government intervention loses effect and the SPR reaches critical levels.” WTI settles up 0.9% at $91.01 a barrel and Brent rises 1% to $95.63. (anthony.harrupwsj.com)
1611 GMT – Oil prices rise in volatile trade, with Brent crude above $95 a barrel after U.S. crude stockpiles saw a larger-than-expected drop last week. Brent is up 0.9% to $95.50 a barrel, while WTI futures rise 0.5% to $90.67 a barrel. Renewed military strikes between the U.S. and Iran are dimming hopes for a near-term resolution of the conflict and reopening of the Strait of Hormuz, keeping the geopolitical risk premium high. Meanwhile, according to the EIA, commercial crude oil stocks excluding the Strategic Petroleum Reserve were down by 4.5 million barrels in the week ended Aug. 28, compared with expectations of a 300,000-barrel fall. “Oil is now more than 30% higher since the conflict began in February, with refined-product markets facing even greater tightness,” says Soojin Kim from MUFG. (giulia.petroniwsj.com)
#crude #week #Iran


2 months ago
On August 11, Kristina Ruggeri from Argus upgraded The Boeing Company (NYSE:BA) from Hold to Buy, based on the company's long-term prospects within the expanding commercial aerospace segment. The ****** yst expects the company's impressive backlog, topline growth and margins to continue expanding after the management made progress in addressing concerns linked with production and profitability. Ruggeri's price target of $265 results in more than 26% upside potential as of August 28 closing. Let's explore the underlying business fundamentals that support this rating upgrade.
Recent financials clearly back the rating upgrade by Argus, as the company reported $24.6 billion in Q2 2026 revenue compared to $22.7 billion during Q2 2025. The 8% topline expansion primarily reflected 171 commercial deliveries during the quarter. Despite a core loss of ($0.76) per share, the company's cash flows turned positive amid improved working capital. In the second quarter, it posted $1.4 billion in operating cash flow and $631 million in free cash flow. Management reiterated its optimistic FCF projections, with a full-year guidance between $1 billion and $3 billion, depending partly on delivery volumes and timing of customer receipts.
The company's demand backlog further strengthens the bullish narrative, as it reported $715 billion in total backlog by the end of second quarter. This included a backlog of $597 billion for commercial airplanes segment, involving more than 6,200 aircraft. It is composed of thousands of orders for 737 MAX, along with elevated demand across its wide-body segment covering 767, 777, and 787 programs. Backlogs for Defense, ****** e & Security, and Global Services segments stood at $85 billion and $33 billion, respectively.
Company President and CEO, Kelly Ortberg, reflected on the remainder of the year, stating:
"While there is more work ahead in the second half of the year, the momentum we are building continues to move Boeing in the right direction."
#second

2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Intercontinental Exchange, Inc. (NYSE:ICE), a US-based financial services company that provides technology, data, and market infrastructure to financial institutions, corporations, and government entities. On September 1, 2026, Intercontinental Exchange, Inc. (NYSE:ICE) closed at $159.60 per share. Over the past month, Intercontinental Exchange, Inc. (NYSE:ICE) returned 4.85%, while its shares have declined 10.30% in the last 52 weeks. Intercontinental Exchange, Inc. (NYSE:ICE) has a market capitalization of $89.6 billion, and its stock has traded within a 52-week range of $121.79 to $177.00.
Sands Capital Select Growth Fund stated the following regarding Intercontinental Exchange, Inc. (NYSE:ICE) in its Q2 2026 investor letter:
"Intercontinental Exchange, Inc. (NYSE:ICE) is one of the world's largest operators of financial exchanges and clearinghouses. Shares declined as investor concerns around AI disruption in ICE's Mortgage business and potential competition from perpetual futures contracts weighed on the stock. Much of the underperformance appears to reflect multiple compression rather than a weakening of fundamentals, which remain solid. In our view, the market is overestimating the risk that AI will displace ICE Mortgage. The business is not simply a workflow solution; it is a platform that connects lenders, data vendors, and other participants required to originate, sell, and service mortgages, while also serving as a system of record for a significant portion of the U.S. mortgage ecosystem. We also believe concerns around perpetual futures competition are overstated, as the structure of these products may limit their use in institutional hedging and risk management, particularly before accounting for liquidity. As such, we believe the recent sell-off more than discounts these risks."
#investor


2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Sphere Entertainment Co. (NYSE:SPHR). Sphere Entertainment Co. (NYSE:SPHR) is a US-based live entertainment and media company. On September 1, 2026, Sphere Entertainment Co. (NYSE:SPHR) closed at $133.30 per share, reflecting a market capitalization of $4.79 billion. Sphere Entertainment Co. (NYSE:SPHR) posted a one-month return of -17.02%, while its shares gained 175.53% over the past 52 weeks.
Sands Capital Select Growth Fund stated the following regarding Sphere Entertainment Co. (NYSE:SPHR) in its Q2 2026 investor letter:
"Sphere Entertainment Co. (NYSE:SPHR) and ****** e Exploration Technologies (SpaceX) were added as more idiosyncratic growth opportunities. Sphere is creating a new category of immersive live entertainment, where we believe premium in-person experiences may become more valuable as digital content becomes increasingly abundant. Its Las Vegas venue combines live events, original content, and proprietary technology, creating the potential for high utilization and attractive venue-level economics. Over time, the investment case depends on Sphere's ability to scale beyond Las Vegas through additional venues, licensing, and high-margin content monetization."
Sphere Entertainment Co. (NYSE:SPHR) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 1 hedge fund portfolios held Sphere Entertainment Co. (NYSE:SPHR) at the end of the second quarter, which was 2 in the previous quarter. While we acknowledge the potential of Sphere Entertainment Co. (NYSE:SPHR) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #s
2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index at 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its Q2 2026 investor letter, Sands Capital Select Growth Fund highlighted Carpenter Technology Corporation (NYSE:CRS), a specialty metals manufacturer serving diversified industries. Carpenter Technology Corporation (NYSE:CRS), held since 2025 with a 4.2% portfolio weight, contributed 1.7% to the Fund's performance this quarter. On September 1, 2026, Carpenter Technology Corporation (NYSE:CRS) closed at $473.06 per share. Over the past month, Carpenter Technology Corporation (NYSE:CRS) declined 17.06%, while its shares are up 100.69% over the past year. Carpenter Technology Corporation (NYSE:CRS) has a market capitalization of $23.44 billion, and its stock has traded within a 52-week range of $228.00 to $625.99.
Sands Capital Select Growth Fund stated the following regarding Carpenter Technology Corporation (NYSE:CRS) in its Q2 2026 investor letter:
"Carpenter Technology Corporation (NYSE:CRS) is a leading supplier of specialty nickel alloys for the aerospace industry. Fiscal third quarter results reinforced our margin thesis as the company demonstrated significant operating leverage as the aerospace equipment cycle continued to recover. Specialty Alloys Operations generated an 86 percent incremental margin in a quarter when volume grew at its strongest rate since the post-COVID aerospace recovery. In our view, the results helped validate that Carpenter's earnings power can continue to expand as the business benefits from improving volume, pricing, and mix. We maintain conviction, supported by Carpenter Technology's specialized materials leadership, pricing power, and exposure to a multiyear aerospace production recovery."
#technology #corporation #capital #select


2 months ago
Sands Capital, an investment management company, released its "Sands Capital Select Growth Fund" Q2 2026 investor letter. The letter can be downloaded here. Select Growth Fund targets U.S. businesses driving significant structural change through disruptive innovation. The fund returned 23.2% in the quarter, outperforming the Russell 1000 Growth Index's 16.7%. U.S. large-cap growth equities rebounded sharply, driven by improving corporate fundamentals and renewed investor confidence in AI, despite geopolitical uncertainties. However, the market's gains were narrow, concentrated among AI beneficiaries. The portfolio's success stemmed from strength in AI infrastructure holdings, especially memory and storage, supported by better pricing and tightening supply. As AI development advances, continuous demand for compute capacity is expected, prompting investments in memory, CPUs, AI chips, and semiconductor manufacturing to address emerging bottlenecks essential for scaling AI. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Sands Capital Select Growth Fund highlighted Lam Research Corporation (NASDAQ:LRCX), a leading semiconductor equipment company that supplies semiconductor processing equipment. Lam Research Corporation (NASDAQ:LRCX), with a 4.7% portfolio weight, contributed 2.2% to the Fund's performance this quarter. On September 1, 2026, Lam Research Corporation (NASDAQ:LRCX) closed at $290.20 per share. Over the past month, Lam Research Corporation (NASDAQ:LRCX) declined 5.60%, but its shares are up 196.91% over the past year. Lam Research Corporation (NASDAQ:LRCX) has a market capitalization of $363.13 billion.
Sands Capital Select Growth Fund stated the following regarding Lam Research Corporation (NASDAQ:LRCX) in its Q2 2026 investor letter:
"Lam Research Corporation (NASDAQ:LRCX) is a leading global provider of semiconductor fabrication equipment. Shares of the business benefited from renewed confidence in semiconductor capital spending and the rising complexity of chip manufacturing. In the first quarter, revenue grew 24 percent and adjusted earnings per share grew 42 percent year over year, while June-quarter guidance exceeded consensus expectations. The company is a critical supplier of etch and deposition equipment, both of which become increasingly important as memory architectures and leading-edge semiconductor manufacturing grow more complex. We believe Lam's exposure to high-bandwidth memory, advanced NAND, and a recovering memory investment cycle gives it a differentiated role within the AI infrastructure supply chain."
#NASDAQ #fund #select



