

2 days ago
The wealthy live in a different reality, and they often flaunt it arrogantly in front of others. Here, we share some absurd situations witnessed by drivers of Reddit, who observed firsthand how affluent individuals behave while being driven around.
Navigating city traffic on a daily basis is no simple task. Drivers encounter all sorts of passengers, each with their own unique stories, expectations, and distinct personalities.
In this instance, drivers share their experiences transporting wealthy individuals, recounting the unexpected situations that can arise when dealing with such extravagant and highly idiosyncratic personalities. Get ready to read some unusual things about wealthy people.
Pinterest
"My father drove one of the comedians from blue collar comedy tour and he said he heard him talking to someone about how much merchandise they sold at the show that he was just performing. I thought that was kinda cool."
#drivers #Share
Navigating city traffic on a daily basis is no simple task. Drivers encounter all sorts of passengers, each with their own unique stories, expectations, and distinct personalities.
In this instance, drivers share their experiences transporting wealthy individuals, recounting the unexpected situations that can arise when dealing with such extravagant and highly idiosyncratic personalities. Get ready to read some unusual things about wealthy people.
"My father drove one of the comedians from blue collar comedy tour and he said he heard him talking to someone about how much merchandise they sold at the show that he was just performing. I thought that was kinda cool."
#drivers #Share

20 days ago
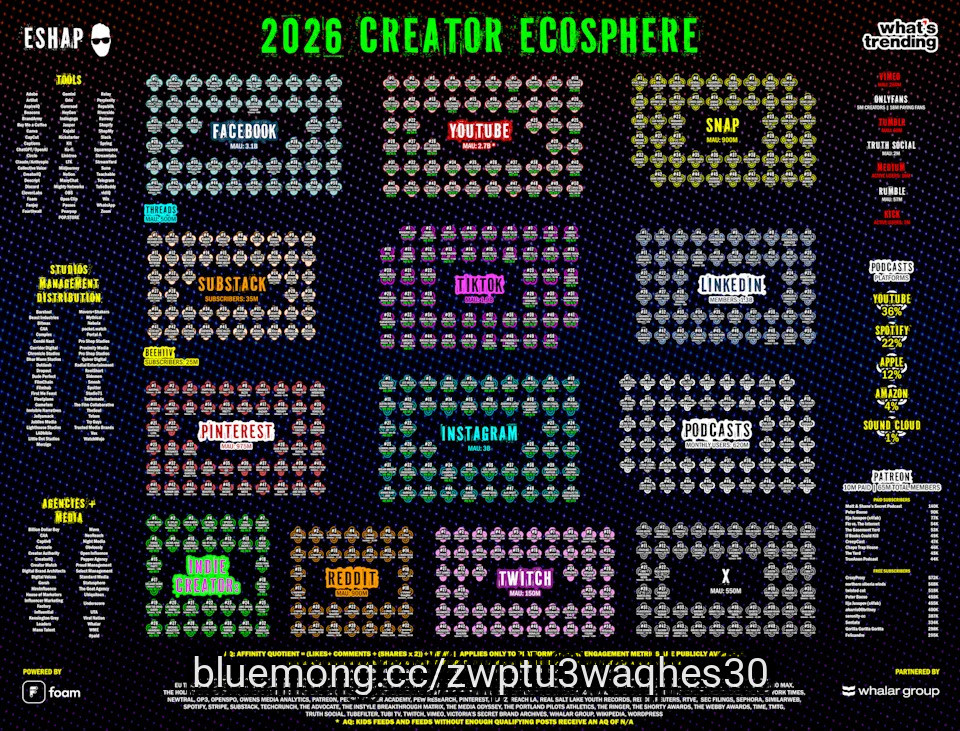
We now have a better idea of exactly who the biggest creators are on social media. ESHAP and What's Trending have partnered to unveil the second annual Creator Map, a guide to the biggest creators by platform. And TheWrap has your first look at their findings.
The Creator Map will be unveiled later today at the first Jupiter Festival Miami, which is sponsored by YouTube. Evan Shapiro, media cartographer and ESHAP founder and CEO; Shira Lazar, What's Trending founder and CEO; and Jon Goss, CEO of the Lighthouse will unveil the project on the main stage of the event.
Described as the "definitive visual guide to the creator ecosphere," the Creator Map offers a data-informed view of the creator economy, an industry that can often feel confusing and chaotic from an outsider perspective. For the first time, the top 200 creators across Instagram, YouTube and TikTok will have both their follower counts and Affinity Quotient scores published on the map. Sponsored by Whalar Group and with data powered by Whalar's creator operating system Foam, the Affinity Quotient measures the depth of audience engagement and places a greater emphasis on active signals such as shares and saves than on passive interactions. That's an important insight as engagement rather than follower count has become the top metric in the creator economy. The Creator Affinity 100 list was first presented at this this year's IBC and identified 100 creators generating the greatest affinity among their audiences.
The map also identifies top creators across Snap, Facebook, LinkedIn, X, Twitch, Pinterest and Rumble, along with the top Substack publishers and podcasters. Additionally, it identifies some of the top agencies, studios, technology tools, payment platforms and other companies powering the creator ecosystem. Check it out below:
ESHAP and What's Trending Creator Map (Photo Credit: ESHAP, What's Trending)
#biggest

26 days ago
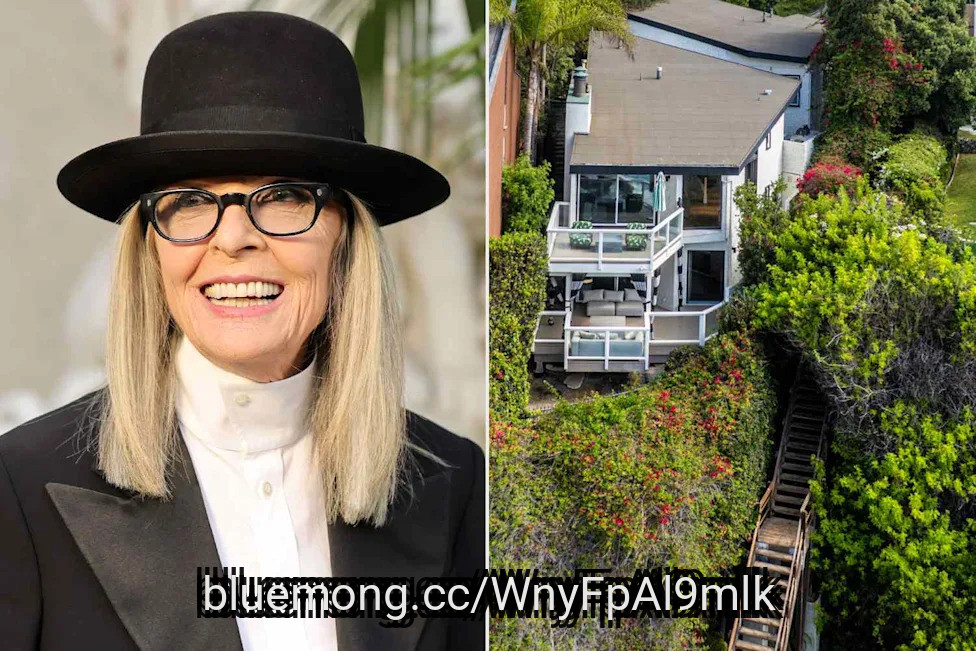
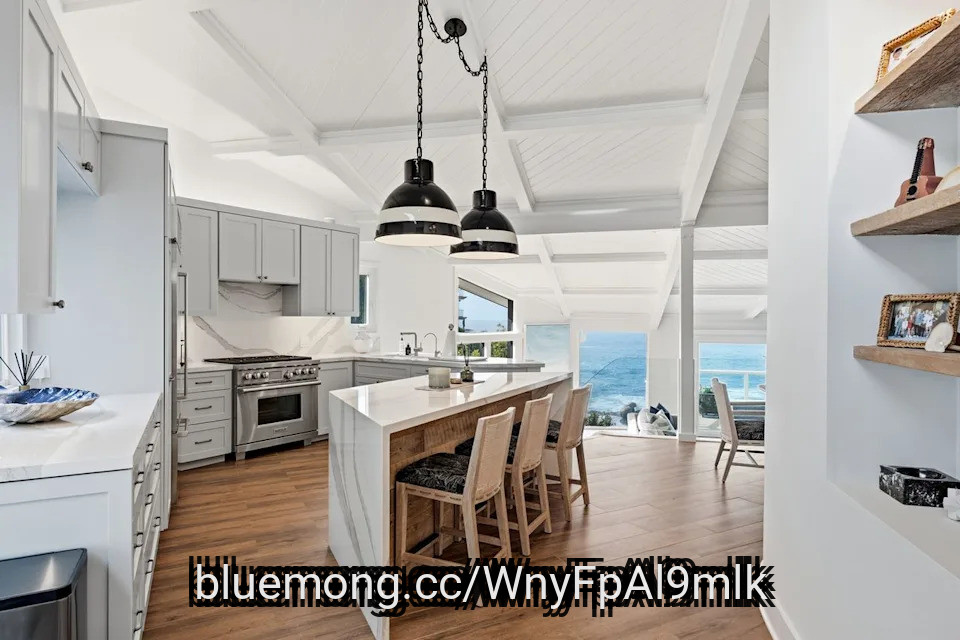
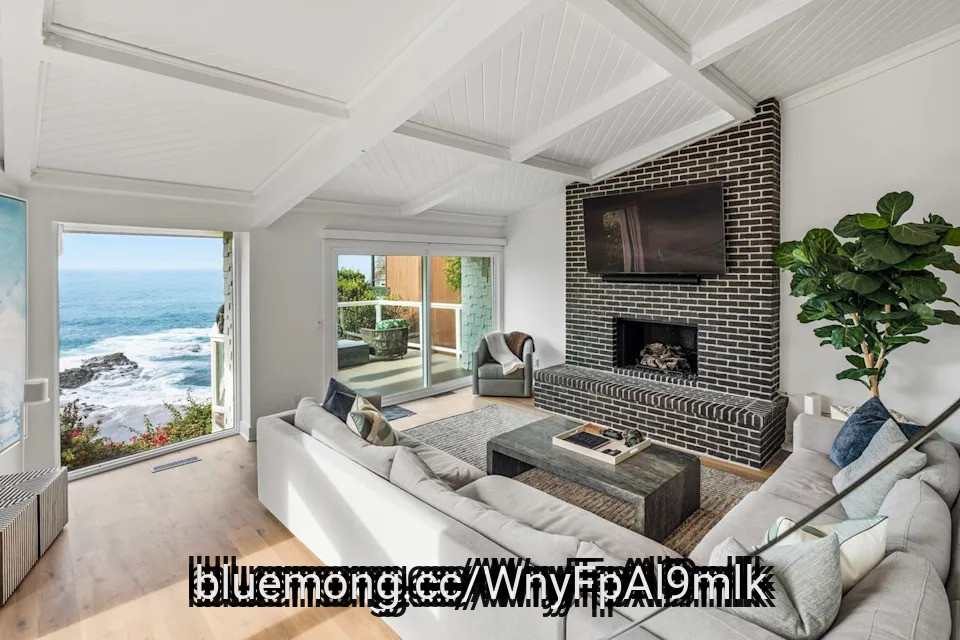
Diane Keaton's former Laguna Beach, Calif., home and "last renovation project" has hit the market for $10.3 million
The current owners preserved most of Keaton's designs and have decided to sell as they need more ***** e for their growing family
Most recently, Keaton's L.A. "Pinterest House" sold for $18 million in August after years of renovations
Diane Keaton's former Laguna Beach, Calif., home has hit the market for $10.3 million nearly one year after her death.
The four-bedroom, three-bathroom property was the star's "last renovation project" before her death at age 79 in October 2025, according to Luxre Realty agent Brooke Wainwright, who holds the listing with partner David Koffs.
#beach #calif #home

26 days ago
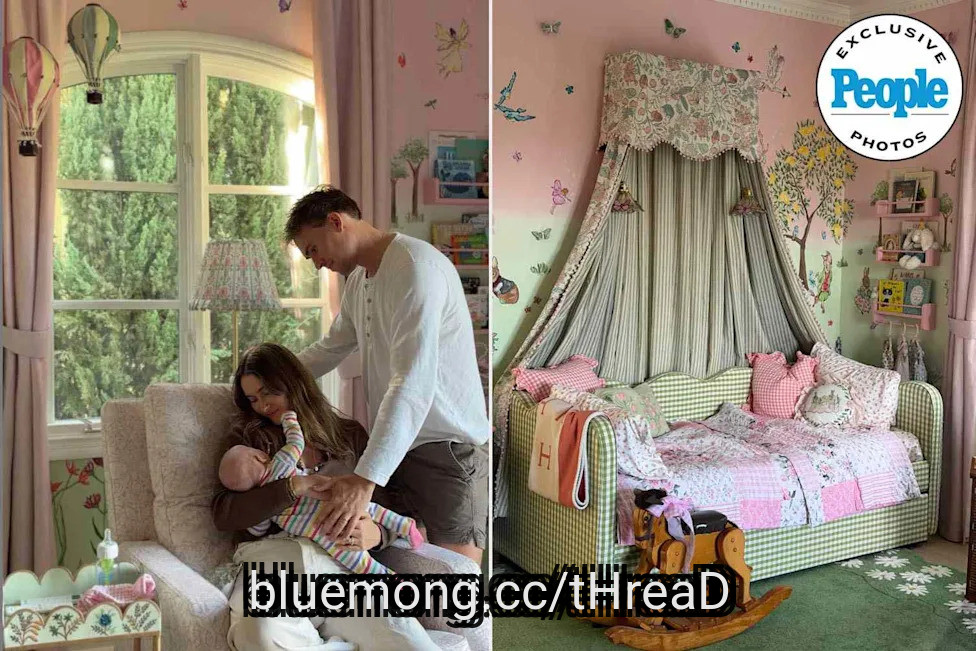
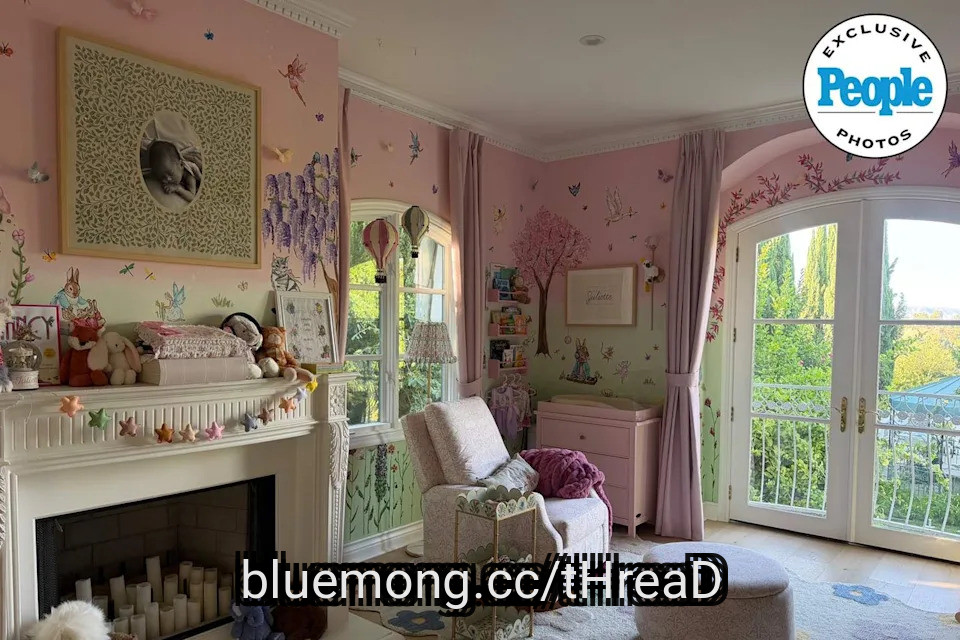
Madeleine White is sharing the design for her daughter Juliette's room after welcoming her early at 33 weeks with husband Andrew Fedyk in June 2026
The hand-painted mural includes family pets, beloved storybook characters and a DJ bunny requested by Fedyk
White partnered with Minted to create the special trundle bed plus storage designed to grow with her daughter
After months of taking her followers through the process of custom-designing her nursery for her daughter, content creator Madeleine White is unveiling the finished product.
Following the arrival of her baby girl, Juliette July, with husband Andrew Fedyk (also known as the DJ Loud Luxury) in June 2026, the popular creator has partnered with Minted to design her baby girl's ***** e. Speaking exclusively with PEOPLE, White shares the behind-the-scenes design process for the newborn's room — which looks straight out of a storybook.
White shares that the nursery's inspiration stemmed from a dream she had had since the moment she found out she was having a little girl. Inspired by a "beautiful woodland animal mural wallpaper" she had stumbled across on Pinterest, the rest of the nursery began to take shape.
White sourced pieces from all over — including her travels, sentimental pieces from her family and more — to curate Juliette's perfect ***** e.
#andrew #june


2 months ago
Pinterest's CFO resignation and slowing Q3 guidance are repricing its 54x P/E multiple, sending PINS down 21% this month while RDDT falls just 2%.
SOCL and SPY are off just 1% and 0.4%, confirming Pinterest's selloff is company-specific rather than a broad social-advertising sector rotation.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Pinterest didn't make the cut. Enter your email to see the names that beat PINS. The report is free. Enter your email and see if any of your stocks made the cut.
Pinterest (NYSE:PINS) stock is sliding again Wednesday afternoon, and the frustrating part for holders is that there's no fresh company headline attached to the move. Pinterest shares are down 8% to $18.59, extending a punishing stretch that has taken the stock down 21% over the past month and pushing it back near the average price where management ran its recent buyback program.
The social peers are softer but nowhere near as weak. Reddit (NYSE:RDDT) stock is down 2% to $147.04, and Snap (NYSE:SNAP) stock is off 1% to $5.36. Both names posted clean Q2 2026 beats earlier this summer, so today's fade for the peer group reflects a sentiment reset across advertising-driven names more than a fundamentals reaction.
#pinterest
SOCL and SPY are off just 1% and 0.4%, confirming Pinterest's selloff is company-specific rather than a broad social-advertising sector rotation.
Just released. Our ***** ysts combed the entire stock market and named the ten best stocks to buy right now, and Pinterest didn't make the cut. Enter your email to see the names that beat PINS. The report is free. Enter your email and see if any of your stocks made the cut.
Pinterest (NYSE:PINS) stock is sliding again Wednesday afternoon, and the frustrating part for holders is that there's no fresh company headline attached to the move. Pinterest shares are down 8% to $18.59, extending a punishing stretch that has taken the stock down 21% over the past month and pushing it back near the average price where management ran its recent buyback program.
The social peers are softer but nowhere near as weak. Reddit (NYSE:RDDT) stock is down 2% to $147.04, and Snap (NYSE:SNAP) stock is off 1% to $5.36. Both names posted clean Q2 2026 beats earlier this summer, so today's fade for the peer group reflects a sentiment reset across advertising-driven names more than a fundamentals reaction.


2 months ago
On August 28, Pinterest (NYSE:PINS) said that the Chief Financial Officer, Julia Donnelly, will leave the company on October 30, kicking off an external search for her replacement. Vikram Naidu, the company's vice president of finance and business operations, will serve as interim principal financial officer in the meantime. Donnelly is departing to join a private, early-stage company after roughly three years in the role, a stretch CEO Bill Ready credited with 11 consecutive quarters of double-digit revenue growth. The timing puts a spotlight on whether Pinterest can keep that momentum going without her.
The financial picture Donnelly leaves behind is a strong one. In the second quarter of 2026, Pinterest generated $1.18 billion in revenue, up 18% year over year and the fourth straight quarter above $1 billion. Global monthly active users climbed to 640 million, an 11% increase and the eleventh consecutive quarter of double-digit user growth, with Gen Z now making up more than half the platform's user base.
The United States and Canada region, Pinterest's most lucrative market, shows the acceleration most clearly. Revenue there grew 18%, a five-point jump from the prior quarter, helped by a restructured sales team and tighter account coverage for mid-market advertisers. Average revenue per user in that region rose 14% to $8.30. Management has also leaned hard into artificial intelligence, rolling its conversational Pinterest ****** istant out to most US users by the end of July and pointing to open-source models that run at less than 8% of the cost of comparable closed systems.
Profitability improved alongside growth. Adjusted EBITDA reached $311 million, a 26% margin that expanded 130 basis points from a year earlier, and free cash flow totaled $1.3 billion over the trailing twelve months. Pinterest used some of that cash to retire nearly 111 million shares this year, spending more than $2 billion on buybacks.
Donnelly's exit adds a layer of uncertainty to a company that just forecast a deceleration. Pinterest's own guidance calls for third-quarter revenue growth of 13% to 15%, down from 18% in the second quarter, a slowdown management attributes to the shift in when Prime Day fell, a smaller currency tailwind, and continued pressure from Asia-based cross-border retailers hit by regulatory actions in Europe. Competition from Meta's Instagram for digital advertising dollars is compounding the squeeze.
#revenue #year #company


2 months ago
Snap (NYSE:SNAP), a camera-first social platform with augmented reality and advertising, closed at $5.42, down 8.53%. Pennsylvania's attorney general sued Snap over Snapchat's design and child-safety claims. Investors are watching follow-up legal risk and product disclosures. Trading volume reached 64.4M shares, coming in about 53% above its three-month average of 42.0M shares. Snap IPO'd in 2017 and has fallen 78% since going public.
S&P 500 (SNPINDEX:^GSPC) closed at 7,675, down 0.04%, while the Nasdaq Composite (NASDAQINDEX:^IXIC) finished at 26,130, down 0.08%. Among internet content and information, digital advertising and social media peers, Meta Platforms (NASDAQ:META) closed at $576.14, up 1.07%, while Pinterest (NYSE:PINS) closed at $23.32, down 1.44%, showing mixed sentiment across ad-supported apps.
Pennsylvania's attorney general sued Snap yesterday, claiming that Snapchat kept "young users compulsively engaged," while lacking necessary safety standards and guardrails for age-appropriate content. This lawsuit was filed less than one day before Meta Platforms agreed to pay a historic $17.1 billion settlement for similar issues with children using its social media platforms.
However, while Meta has been battling this lawsuit for months, Snap's situation is brand new, prompting the market to send its shares down 9% today. A.G. Dave Sunday specifically cited Snap's Snapstreaks (which can be restored with a payment), disappearing messages, infinite scrolling, and "T for teen" rating as some of the many issues in the complaint.
Snap stock remains an unprofitable company -- though it is getting closer to breakeven -- and continues to rely heavily upon stock-based compensation, diluting shareholder value over time. With sales growth slowing over the last three years, yesterday's lawsuit against Snap, and today's ruling against Meta, I'm just not interested in the social media stock today, regardless of its popularity. It may simply be a better app than a company.
#snap #closed #lawsuit


2 months ago
Director Benjamin Silbermann reported a sale of 93,750 shares of Class A Common Stock in Pinterest, Inc. (NYSE:PINS) in an SEC Form 4 filing.
Metric
Value
Transaction value
~$2.2 million
#common
Metric
Value
Transaction value
~$2.2 million
#common


2 months ago
On August 4, Pinterest, Inc. (NYSE:PINS) beat Wall Street's second-quarter targets, then told investors to expect a slower ride ahead. Shares dropped as much as 9% in extended trading anyway. The firm posted adjusted earnings of 43 cents a share, well past the 36 cents **** ysts had expected. Revenue was $1.18 billion against a $1.15 billion estimate. However, the guidance told a different story: third-quarter revenue of $1.19 billion to $1.21 billion implies growth of just 13% to 15%, a real step down from the 18% pace investors had gotten used to.
CEO Bill Ready spent part of the earnings call making a case that stuck with people: He said that any company still ignoring open-source AI models is probably wasting its shareholders' money. Pinterest is leaning into that idea itself, mixing pricier proprietary models with cheaper open-weight ones through what CFO Julia Donnelly called "model routing infrastructure," sending the hard stuff to expensive models and routine tasks to cheap ones. Donnelly also explained why growth is slowing: the ad boost from the World Cup won't repeat next quarter, while European regulators are squeezing the Asian retailers who buy heavily on Pinterest.
Etsy, Inc. (NYSE:ETSY) had its own rough week for a different reason. On August 5, the marketplace beat estimates and raised its full-year sales outlook. The firm then cut 220 jobs, about 12% of its staff, the same day.
Pinterest, Inc. (NYSE:PINS)'s user numbers held up well, with monthly actives up 11% to 640 million, ahead of the 635 million **** ysts wanted. Adjusted EBITDA of $311 million beat both the company's own guidance and Street estimates of $270 million. CEO Ready's push into cheap open-source AI could keep a lid on costs even as usage climbs.
However, growth itself is the problem. Revenue is decelerating from 18% down to a guided 13% to 15%. CFO Donnelly warns that European pressure on Asian advertisers could mean this slowdown will last longer than one quarter.
#billion
2 months ago
Director Benjamin Silbermann reported a sale of 93,750 shares of Class A Common Stock in Pinterest, Inc. (NYSE:PINS) in an SEC Form 4 filing.
Metric
Value
Transaction value
~$2.2 million
#common
Metric
Value
Transaction value
~$2.2 million
#common


2 months ago
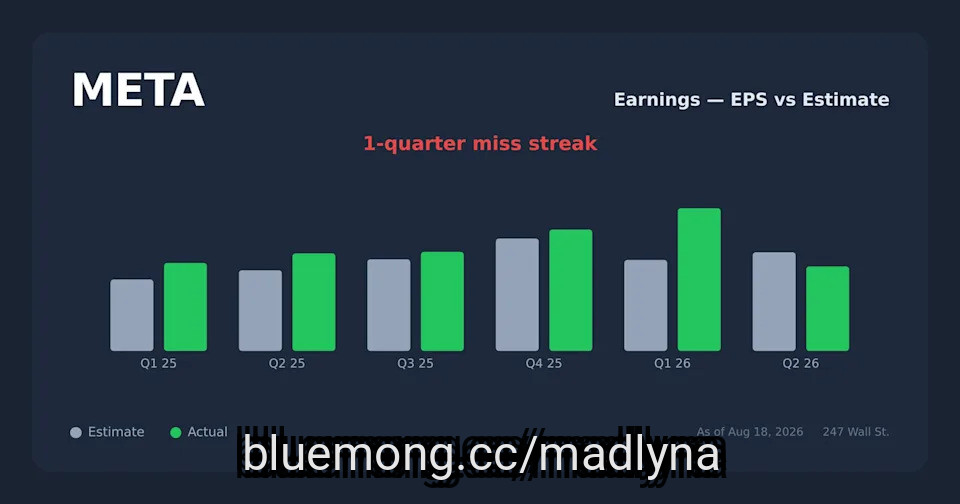
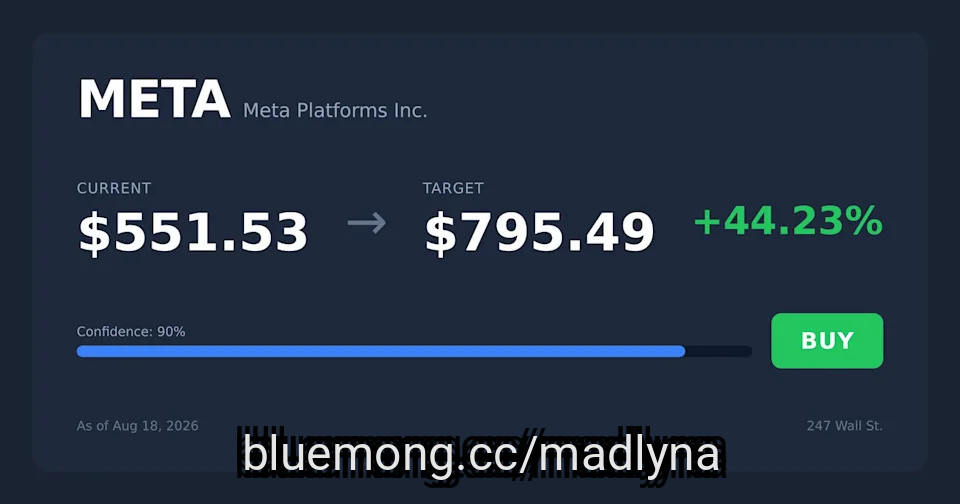
META stock fell 4% as a 29-state youth-harm trial opened in Oakland, with potential damages of $1.4 trillion rivaling its entire market cap.
Pinterest (PINS) rose 3% and Snap (SNAP) gained 2% Tuesday, confirming Meta's selloff reflects company-specific legal and cost problems, not sector weakness.
Meta's Q2 costs surged 55% against 28% revenue growth, cratering free cash flow to just $784 million from $8.55 billion a year earlier.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Meta didn't make the cut. Grab the names FREE today.
Meta Platforms (NASDAQ:META) stock is down 4% to $548.14 in Tuesday morning trading as a 29-state youth-harm trial opens in Oakland. Investors are reassessing a cost base growing far faster than revenue.
#Stock #trial


2 months ago
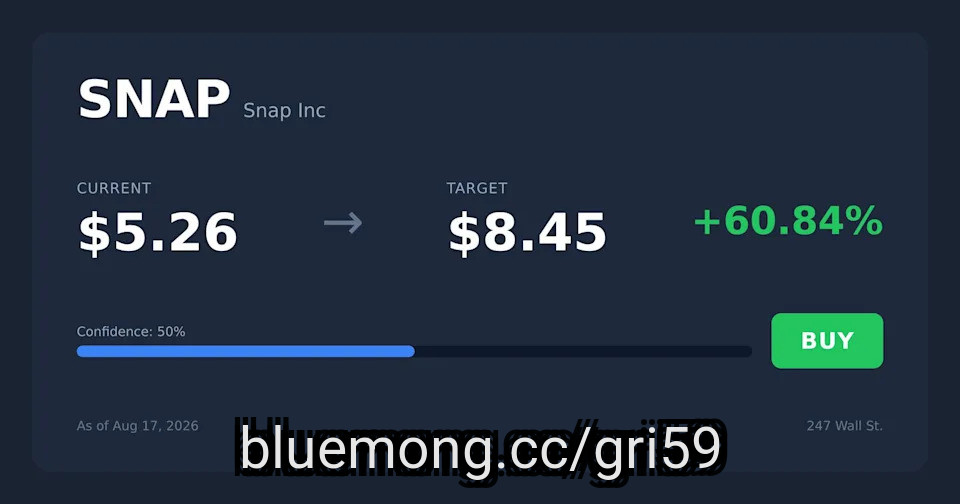
The 9th Circuit stripped Snap's Section 230 immunity, opening 3,000+ lawsuits and sending SNAP shares down 3% after an overnight plunge to $4.74.
Meta and Pinterest fell 3% and 4%, respectively, as the ruling cast an industry-wide liability shadow across social media platforms.
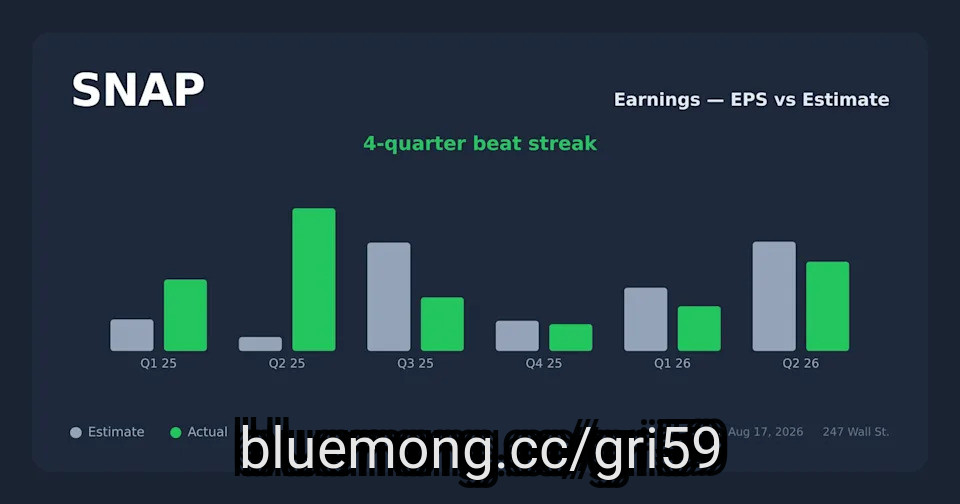
Snap's Q2 revenue beat of $1.6 billion and EBITDA surging to $250 million from $41 million couldn't offset **** yst caution over unquantifiable litigation risk.
Act now: the **** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Snap didn't make the cut. Grab the names FREE today.
Snap (NYSE:SNAP) shares are down 3% to $5.24 Monday midday, giving back part of a sharp overnight decline that saw the stock fall as much as 12% to $4.74 before buyers stepped in. The catalyst is a federal appeals court ruling that pierces a legal shield social platforms have long relied upon.
#snap #down #ruling #analyst

2 months ago
Costco Wholesale Corporation (NASDAQ:COST) is one of Jim Cramer's favorite stocks. The shares are down by 1% over the past year and are up by 12% year-to-date. As he has done with Apple and NVIDIA, Cramer has continued to stick with Costco Wholesale Corporation (NASDAQ:COST) through thick and thin. The CNBC TV host believes that the firm's scale and negotiating power enable it to provide Americans with the lowest prices. As Costco Wholesale Corporation (NASDAQ:COST) reported its July sales data on August 5th, Cramer discussed the firm a day later in his morning appearance:
"But what I want to see today, to see if it's strong or not, is Costco. Cause Costco had very, very good numbers, okay. And I think that should be a good example if, yes that's getting rewarded. There's an example where you had a number that wasn't [inaudible] better than expected that also said good things. A lot of times it was better than expected but we didn't get the good things. We didn't get the forecast ****** p. So if you have a quarter, you reported the quarter, and you gave us a forecast, it's like Pinterest. Pinterest forecast was not as strong as we'd like but the quarter was terrific. A lot of people raised the price tag, but Pinterest went down. And that's been the template, if you don't raise your forecast as much as people were hoping, your stock does not do that well."
Costco Wholesale Corporation (NASDAQ:COST)'s scale and market share allow it to run a major membership program, which is one of its strongest points. Membership renewal rates signal customer loyalty, and as of its fiscal third quarter, Costco Wholesale Corporation (NASDAQ:COST) reported US and Canadian renewal rates of 92.2%. Through its fees, the retailer is also able to offer its customers lower prices than most and create a feedback loop of renewal rates and customer satisfaction. Yet, at the same time, Costco Wholesale Corporation (NASDAQ:COST)'s strengths also create weaknesses. The firm's forward P/E of 42 is higher than Walmart's 38 and significantly higher than Target's 18.6.
As for Pinterest, Inc. (NYSE:PINS), the visual search engine platform's shares closed 8.7% lower on August 5th after the firm had reported its second quarter earnings on the day before. Cramer used the results to point to the impact of forward guidance on a company's shares. While Pinterest, Inc. (NYSE:PINS)'s revenue and EPS of $1.18 billion and $0.43 beat ****** yst estimates of $1.15 billion and $0.36, the firm's midline guidance of $1.20 billion met ****** yst estimates. As is the case with other marketplace companies, such as Booking Holdings, the debate for Pinterest, Inc. (NYSE:PINS) also concerns whether the firm will be able to generate long-term value through its AI initiatives. At the same time, the impact of these initiatives on margins and the business's reliance on cyclical retailers are additional worry points.
#cramer


3 months ago
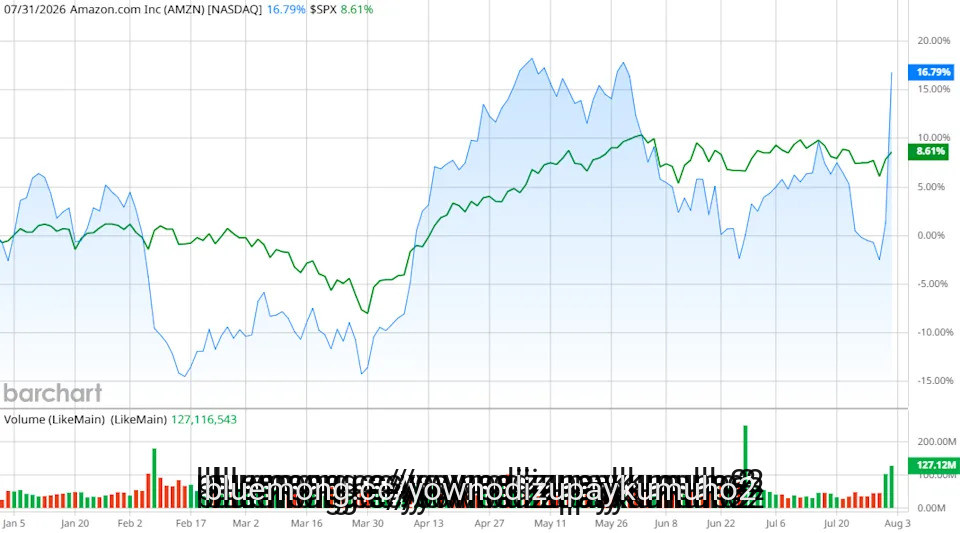
Score one for Andy Jassy and his team at Amazon (AMZN). After months of AMZN stock underperforming the S&P 500 ($SPX) on fears that the company was spending too much, too fast on its artificial intelligence (AI) buildout, the CEO put those fears to rest with the latest earnings report. The release made one thing clear: Amazon's AI strategy is paying off in a big way.
Amazon's second-quarter report recorded the fastest growth in Amazon Web Services (AWS) in 18 quarters, with the segment exceeding an annual run rate of $25 billion in AI revenue thanks to new agreements signed with several big companies, including Warner Bros. Discovery (WBD), Pinterest (PINS), Snowflake (SNOW), and Moody's (MCO). Amazon also recorded a $25 billion annual run rate for its chips business, which includes its custom-built Trainium AI chip. Amazon has commitments from AI startups Anthropic and OpenAI, Uber Technologies (UBER), Pinterest, and numerous smaller startups.
CoreWeave Just Scored a Leidos Partnership. What That Means for CRWV Stock Here.
Palantir Is Set to Deliver Strong Q2. **** ysts See 60% Upside Potential for PLTR Stock.
How to Play Jersey Mike's Subs Stock After the JMKE IPO
#amzn #pinterest
4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted ICON Public Limited Company (NASDAQ:ICLR). ICON Public Limited Company (NASDAQ:ICLR) is a clinical research organization that provides outsourced development and commercialization services to the pharmaceutical, biotechnology, and medical device industries. On July 7, 2026, ICON Public Limited Company (NASDAQ:ICLR) stock closed at $168.72 per share. One-month return of ICON Public Limited Company (NASDAQ:ICLR) was 16.69%, and its shares gained 12.08% over the past 52 weeks. ICON Public Limited Company (NASDAQ:ICLR) has a market capitalization of about $12.92 billion.
Artisan Mid Cap Value Fund stated the following regarding ICON Public Limited Company (NASDAQ:ICLR) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON Public Limited Company (NASDAQ:ICLR), Humana, Gartner and Pinterest, each of which dropped by 30% or more during the quarter. ICON, a leading provider of outsourced clinical development services to pharmaceutical and biotechnology companies, was the largest detractor. The stock fell sharply—nearly 49% in a single day—after the company announced it would delay its financial results due to an internal review of its accounting, specifically related to revenue recognition in recent years. While ICON indicated its cash position remains intact, the situation raises uncertainty around reported earnings and has pressured investor confidence in the near term. This development comes at a challenging time for the broader contract research industry, where funding constraints and cautious spending by biotech and pharmaceutical companies have already weighed on demand. Although the lack of updated financials limits near term visibility, we believe the stock reflects a more attractive valuation based on conservative ****** umptions for free cash fl

4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Gartner, Inc. (NYSE:IT). Established in 1979, Gartner, Inc. (NYSE:IT) is a research and advisory company that provides business and technology insights to help businesses make informed decisions. On July 7, 2026, Gartner, Inc. (NYSE:IT) closed at $140.80 per share. One-month return of Gartner, Inc. (NYSE:IT) was -9.11%, and its shares lost 64.30% over the past 52 weeks. Gartner, Inc. (NYSE:IT) has a market capitalization of $9.43 billion.
Artisan Mid Cap Value Fund stated the following regarding Gartner, Inc. (NYSE:IT) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON, Humana, Gartner, Inc. (NYSE:IT) and Pinterest, each of which dropped by 30% or more during the quarter. Gartner, a technology and business advisory firm, declined following signs of slowing growth and a weaker-than-expected outlook for 2026. Its core research business has been affected by several cyclical headwinds, including US government cost-cutting, uncertainty around trade policy and longer sales cycles. At the same time, some investors have become concerned about the potential long-term impact of artificial intelligence on Gartner's business model. While we take these risks seriously, we believe the company's current challenges are primarily cyclical, and any meaningful disruption from AI is likely to play out over a longer time horizon. Gartner continues to generate strong free cash flow, maintains a solid balance sheet and has been returning capital to shareholders, including approximately $2 billion of share repurchases in 2025. At current levels, we believe the stock appears attractively valued."


4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Pinterest, Inc. (NYSE:PINS). Pinterest, Inc. (NYSE:PINS) is a social media and visual discovery platform that enables users to find ideas, such as recipes, home, and style inspiration. On July 7, 2026, Pinterest, Inc. (NYSE:PINS) closed at $22.42 per share. One-month return of Pinterest, Inc. (NYSE:PINS) was 2.99%, and its shares lost 37.53% over the past 52 weeks. Pinterest, Inc. (NYSE:PINS) has a market capitalization of $12.56 billion.
Artisan Mid Cap Value Fund stated the following regarding Pinterest, Inc. (NYSE:PINS) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON, Humana, Gartner and Pinterest, Inc. (NYSE:PINS), each of which dropped by 30% or more during the quarter. Pinterest's recent results have been impacted by macroeconomic headwinds, particularly tariffs, which have weighed on advertising spending by large retail customers. Compared with larger social media peers, Pinterest is less diversified and more exposed to consumer-driven categories, making it more sensitive to these pressures. While we continue to view digital advertising as a structurally attractive market with growth likely to exceed that of the broader economy, we chose to exit the position in favor of more compelling opportunities. Nearly four years into the current management team's tenure, progress on key priorities, including user growth, engagement, monetization and profitability, has been slower than expected."

4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted ICON Public Limited Company (NASDAQ:ICLR). ICON Public Limited Company (NASDAQ:ICLR) is a clinical research organization that provides outsourced development and commercialization services to the pharmaceutical, biotechnology, and medical device industries. On July 7, 2026, ICON Public Limited Company (NASDAQ:ICLR) stock closed at $168.72 per share. One-month return of ICON Public Limited Company (NASDAQ:ICLR) was 16.69%, and its shares gained 12.08% over the past 52 weeks. ICON Public Limited Company (NASDAQ:ICLR) has a market capitalization of about $12.92 billion.
Artisan Mid Cap Value Fund stated the following regarding ICON Public Limited Company (NASDAQ:ICLR) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON Public Limited Company (NASDAQ:ICLR), Humana, Gartner and Pinterest, each of which dropped by 30% or more during the quarter. ICON, a leading provider of outsourced clinical development services to pharmaceutical and biotechnology companies, was the largest detractor. The stock fell sharply—nearly 49% in a single day—after the company announced it would delay its financial results due to an internal review of its accounting, specifically related to revenue recognition in recent years. While ICON indicated its cash position remains intact, the situation raises uncertainty around reported earnings and has pressured investor confidence in the near term. This development comes at a challenging time for the broader contract research industry, where funding constraints and cautious spending by biotech and pharmaceutical companies have already weighed on demand. Although the lack of updated financials limits near term visibility, we believe the stock reflects a more attractive valuation based on conservative ******* umptions for free cash f

4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Gartner, Inc. (NYSE:IT). Established in 1979, Gartner, Inc. (NYSE:IT) is a research and advisory company that provides business and technology insights to help businesses make informed decisions. On July 7, 2026, Gartner, Inc. (NYSE:IT) closed at $140.80 per share. One-month return of Gartner, Inc. (NYSE:IT) was -9.11%, and its shares lost 64.30% over the past 52 weeks. Gartner, Inc. (NYSE:IT) has a market capitalization of $9.43 billion.
Artisan Mid Cap Value Fund stated the following regarding Gartner, Inc. (NYSE:IT) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON, Humana, Gartner, Inc. (NYSE:IT) and Pinterest, each of which dropped by 30% or more during the quarter. Gartner, a technology and business advisory firm, declined following signs of slowing growth and a weaker-than-expected outlook for 2026. Its core research business has been affected by several cyclical headwinds, including US government cost-cutting, uncertainty around trade policy and longer sales cycles. At the same time, some investors have become concerned about the potential long-term impact of artificial intelligence on Gartner's business model. While we take these risks seriously, we believe the company's current challenges are primarily cyclical, and any meaningful disruption from AI is likely to play out over a longer time horizon. Gartner continues to generate strong free cash flow, maintains a solid balance sheet and has been returning capital to shareholders, including approximately $2 billion of share repurchases in 2025. At current levels, we believe the stock appears attractively valued."


4 months ago
Artisan Partners, an investment management firm, issued its first-quarter 2026 investor letter for the "Artisan Mid Cap Value Fund". A copy of this letter is available for download here. In Q1 2026, the portfolio underperformed the benchmark Russell Midcap Value Index as the market favored momentum-driven stocks over quality factors. Some holdings faced company-specific setbacks and negative sentiment. The Fund's Investor Class: ARTQX returned -4.93%, Advisor Class: APDQX declined by -4.90%, and Institutional Class: APHQX fell by -4.97%, all trailing the Index's 3.68% gain. The equity market in the quarter was mixed, with mid- and small-cap indices showing resilience despite lagging large-cap growth stocks. Volatility increased, initially fueled by interest in AI and private credit, but escalated after the outbreak of war in Iran, leading to rising oil prices. Sector performance varied, with energy leading the gains. The Fund continues to seek companies capable of value growth during market dislocations at attractive entry points. Also, review the Fund's top five holdings to see its best picks for 2026.
In its first-quarter 2026 investor letter, Artisan Mid Cap Value Fund highlighted Pinterest, Inc. (NYSE:PINS). Pinterest, Inc. (NYSE:PINS) is a social media and visual discovery platform that enables users to find ideas, such as recipes, home, and style inspiration. On July 7, 2026, Pinterest, Inc. (NYSE:PINS) closed at $22.42 per share. One-month return of Pinterest, Inc. (NYSE:PINS) was 2.99%, and its shares lost 37.53% over the past 52 weeks. Pinterest, Inc. (NYSE:PINS) has a market capitalization of $12.56 billion.
Artisan Mid Cap Value Fund stated the following regarding Pinterest, Inc. (NYSE:PINS) in its Q1 2026 investor letter:
"Among the biggest decliners were ICON, Humana, Gartner and Pinterest, Inc. (NYSE:PINS), each of which dropped by 30% or more during the quarter. Pinterest's recent results have been impacted by macroeconomic headwinds, particularly tariffs, which have weighed on advertising spending by large retail customers. Compared with larger social media peers, Pinterest is less diversified and more exposed to consumer-driven categories, making it more sensitive to these pressures. While we continue to view digital advertising as a structurally attractive market with growth likely to exceed that of the broader economy, we chose to exit the position in favor of more compelling opportunities. Nearly four years into the current management team's tenure, progress on key priorities, including user growth, engagement, monetization and profitability, has been slower than expected."

4 months ago
RiverPark Advisors, an investment advisory firm and sponsor of the RiverPark family of mutual funds, released its "RiverPark Large Growth Fund" Q1 2026 investor letter. A copy of the letter can be downloaded here. The US stock market declined in the quarter with the S&P 500 index ("S&P") and the Russell 1000 Growth index ("RLG") falling 4.33% and 9.78%, respectively. Markets started the year positively but became volatile mainly due to increased tensions with Iran. The Federal Reserve kept rates unchanged in January and February. Still, rising energy prices and weaker economic data sparked concerns about stagflation, leading investors to rethink the timing and scale of future rate cuts. Investor sentiment shifted from growth and tech stocks amid inflation, interest rate, and supply chain concerns. Opposing AI-driven rotations heavily influenced investor sentiment, affecting growth stocks—enthusiasm grew for semiconductor firms linked to AI infrastructure spending, while enterprise software companies, viewed as vulnerable to AI disruption, faced pessimism. The Fund's software holdings were sold off heavily, while the underweight in semiconductor companies, which benefited most from AI infrastructure spending, affected the performance. Despite challenges, the firm remains confident in the long-term prospects and valuations of its portfolio companies. Please review the Fund's top five holdings to gain insights into their key selections for 2026.
In its first-quarter 2026 investor letter, RiverPark Large Growth Fund highlighted Pinterest, Inc. (NYSE:PINS). Pinterest, Inc. (NYSE:PINS) is a social media and visual discovery platform that enables users to find ideas, such as recipes, home, and style inspiration. On July 2, 2026, Pinterest, Inc. (NYSE:PINS) closed at $22.07 per share. One-month return of Pinterest, Inc. (NYSE:PINS) was 1.77%, and its shares lost 38.90% over the past 52 weeks. Pinterest, Inc. (NYSE:PINS) has a market capitalization of $12.36 billion.
RiverPark Large Growth Fund stated the following regarding Pinterest, Inc. (NYSE:PINS) in its Q1 2026 investor letter:
"Pinterest, Inc. (NYSE:PINS): PINS was a significant detractor for the quarter, declining 40% before we exited the position. Pinterest's Q4 2025 earnings report, released in February, was disappointing: revenue of $1.32 billion grew 14.3% year-over-year but missed the $1.33 billion consensus, adjusted EPS of $0.67 fell short of expectations, and Q1 2026 revenue guidance of $951–$971 million came in well below the $980 million the Street had anticipated. CEO Bill Ready attributed the shortfall to an "exogenous shock" from tariffs that caused the company's largest retail advertiser cohort, particularly in home furnishings and décor, to meaningfully pull back on brand advertising budgets. The company also announced approximately 15% workforce reductions and organizational restructuring, further unsettling investors. Multiple **** ysts downgraded the stock following the report


4 months ago
TimesSquare Capital Management, an equity investment management company, released its "U.S. Mid Cap Growth Strategy" first-quarter 2026 investor letter. A copy of the letter can be downloaded here. The Strategy fell 7.72% (net) in the quarter compared to -6.35% for the Russell Midcap Growth Index. In the first quarter, markets navigated geopolitical tensions and economic resilience alongside temporary global tariffs. High oil prices and supply chain disruptions followed U.S. and Israeli involvement in Iran, prompting a shift to safer **** ets and a reevaluation of supply chains and energy dependencies. Central banks maintained steady policies despite energy-driven inflation. In this environment, the Strategy remains focused on disciplined management teams with durable competitive advantages. Please review the Strategy's top five holdings to gain insights into their key selections for 2026.
In its first-quarter 2026 investor letter, TimesSquare Capital U.S. Mid Cap Growth Strategy highlighted Pinterest, Inc. (NYSE:PINS). Pinterest, Inc. (NYSE:PINS) is a social media and visual discovery platform that enables users to find ideas, such as recipes, home, and style inspiration. On June 30, 2026, Pinterest, Inc. (NYSE:PINS) closed at $21.03 per share. One-month return of Pinterest, Inc. (NYSE:PINS) was 1.74%, and its shares lost 41.16% over the past 52 weeks. Pinterest, Inc. (NYSE:PINS) has a market capitalization of $11.78 billion.
TimesSquare Capital U.S. Mid Cap Growth Strategy stated the following regarding Pinterest, Inc. (NYSE:PINS) in its Q1 2026 investor letter:
"For the Communication Services sector, we prefer to invest in media and services companies that are either well placed from an advertising perspective for their target audience or that provide differentiated services. Pinterest, Inc. (NYSE:PINS) is an image-based social media platform. We exited our position following slower-than-expected fourth-quarter results and cautious guidance, attributed to advertising pullbacks by retailers impacted by tariffs. Its shares were down -44% while held in the quarter. The combination of softer-than-expected results along with lackluster forward guidance led us to liquidate the position."
Pinterest, Inc. (NYSE:PINS) is not on our list of 40 Most Popular Stocks Among Hedge Funds Heading Into 2026. According to our database, 49 hedge fund portfolios held Pinterest, Inc. (NYSE:PINS) at the end of the first quarter, compared to 53 in the previous quarter. In Q1 2026, Pinterest, Inc. (NYSE:PINS) delivered $1 billion in revenue, up 18% year over year. While we acknowledge the potential of Pinterest, Inc. (NYSE:PINS) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.




