3 days ago
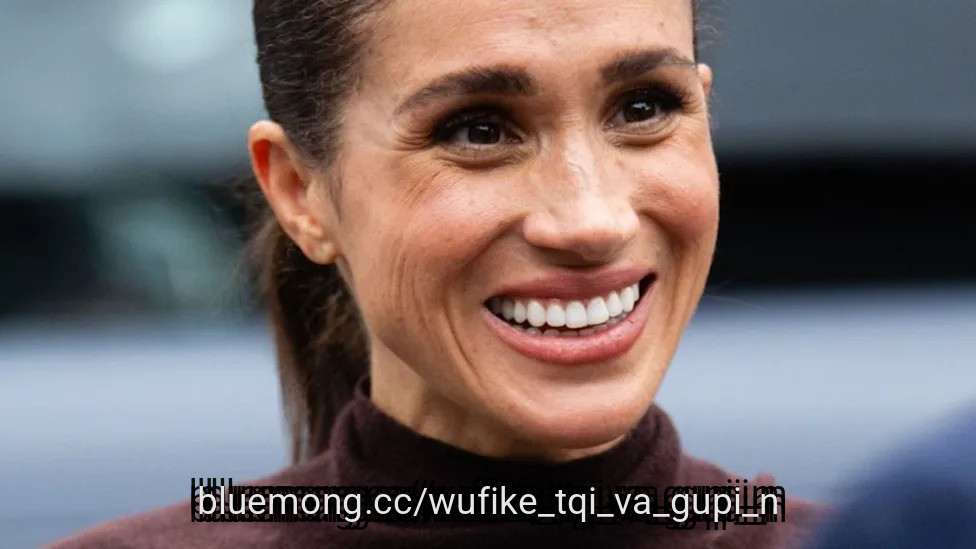
Meghan Markle is facing renewed scrutiny following reports that she is preparing to film in Australia. After the **** ss of Sussex and Prince Harry relocated to the UK at the end of August, reports of an upcoming work stint in Australia have led royal commentators to question how the family will manage the transition.
Meghan Markle is set to appear on Junior MasterChef Australia's upcoming season, which will film in Australia in 2027. However, it has not been confirmed whether Prince Harry, Prince Archie and Princess Lilibet will be joining her. The Sussex children recently changed schools in the UK after their security team raised concerns about their previous commute. The possibility of another move has now prompted questions about how the family's arrangements could work during Meghan's filming commitment.
On The Sun's Royal Exclusive, the **** ss of Sussex was criticized for the possibility of relocating her kids again. "Career-wise for her, it's, you know, it's good news," host Sarah Hewson said. She continued, "What about for the kids who they've just brought over to the UK, got settled in a new school. Is that going to change anything or do we think the kids will be going?" The Sun's royal editor Matt Wilkinson shared his thoughts. "The children thing is a really interesting thing because we know that they've already changed schools once," he said.
Wilkinson added, "They said they were coming back to the UK for the children's schooling. So these are unanswered questions…" The royal editor was unsure whether it would be "an exceptionally long period for Meghan and Harry." He wondered if the Sussexes will take their kids to another school. "Is it going to be another um you know, traffic crisis outside of school in Sydney or Melbourne or something? But yeah, I would really like a little kind of welcome break…," Wilkinson said.
Hewson felt Harry could take the kids for a trip to Australia if it occurs during school days. "[They could] take the kids to go out and see mum while she's working," the royal correspondent explained.
#harry
Meghan Markle is set to appear on Junior MasterChef Australia's upcoming season, which will film in Australia in 2027. However, it has not been confirmed whether Prince Harry, Prince Archie and Princess Lilibet will be joining her. The Sussex children recently changed schools in the UK after their security team raised concerns about their previous commute. The possibility of another move has now prompted questions about how the family's arrangements could work during Meghan's filming commitment.
On The Sun's Royal Exclusive, the **** ss of Sussex was criticized for the possibility of relocating her kids again. "Career-wise for her, it's, you know, it's good news," host Sarah Hewson said. She continued, "What about for the kids who they've just brought over to the UK, got settled in a new school. Is that going to change anything or do we think the kids will be going?" The Sun's royal editor Matt Wilkinson shared his thoughts. "The children thing is a really interesting thing because we know that they've already changed schools once," he said.
Wilkinson added, "They said they were coming back to the UK for the children's schooling. So these are unanswered questions…" The royal editor was unsure whether it would be "an exceptionally long period for Meghan and Harry." He wondered if the Sussexes will take their kids to another school. "Is it going to be another um you know, traffic crisis outside of school in Sydney or Melbourne or something? But yeah, I would really like a little kind of welcome break…," Wilkinson said.
Hewson felt Harry could take the kids for a trip to Australia if it occurs during school days. "[They could] take the kids to go out and see mum while she's working," the royal correspondent explained.
#harry
3 days ago
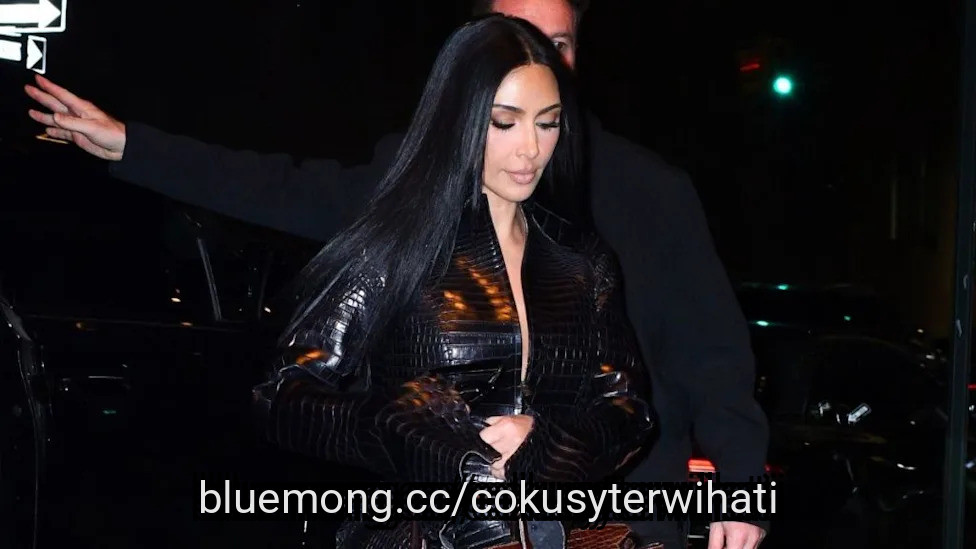
Kim Kardashian knows how to make a statement with her fashion choices, and her latest appearance in Beverly Hills was no exception. The reality star and business mogul stepped out in an all-black ensemble that combined daring details with extravagant luxury. However, it was her exceptionally rare handbag that truly stole the spotlight.
Earlier reported by The Fashion Spot, Kardashian turned heads in a glossy black crocodile-effect jacket that featured a striking, structured silhouette. The fitted piece came with long sleeves, a dramatic collar, and a shiny textured finish that reflected the camera flashes.
The jacket was left partially unzipped at the front, creating a plunging neckline that added a daring touch to the sophisticated outfit.
The jacket also featured a cinched waist that emphasized Kardashian's figure, while its slightly flared hem gave it a more sculptural appearance. She paired the statement piece with opaque black tights.
Kardashian completed her ensemble with pointed-toe black stiletto heels featuring a glossy finish. She styled her signature long, jet-black hair straight with a center part, falling past her shoulders. She opted for her usual glamorous makeup, including defined eyes, sculpted cheeks, and a soft nude lip.
#appearance
Earlier reported by The Fashion Spot, Kardashian turned heads in a glossy black crocodile-effect jacket that featured a striking, structured silhouette. The fitted piece came with long sleeves, a dramatic collar, and a shiny textured finish that reflected the camera flashes.
The jacket was left partially unzipped at the front, creating a plunging neckline that added a daring touch to the sophisticated outfit.
The jacket also featured a cinched waist that emphasized Kardashian's figure, while its slightly flared hem gave it a more sculptural appearance. She paired the statement piece with opaque black tights.
Kardashian completed her ensemble with pointed-toe black stiletto heels featuring a glossy finish. She styled her signature long, jet-black hair straight with a center part, falling past her shoulders. She opted for her usual glamorous makeup, including defined eyes, sculpted cheeks, and a soft nude lip.
#appearance

3 days ago
Over the last four years, the ageless Dow Jones Industrial Average (DJINDICES:^DJI), broad-based S&P 500 (SNPINDEX:^GSPC), and growth-focused Nasdaq Composite (NASDAQINDEX:^IXIC) have been virtually unstoppable. The artificial intelligence (AI) data center build-out has fueled an investing frenzy similar to what was witnessed in the mid-to-late 1990s with the internet.
But the stock market isn't without headwinds. Arguably, the biggest obstacle to the continuity of this bull market rally is persistently elevated inflation. The bad news for investors is that the Federal Reserve's initial inflation forecast for November shows things are getting downright ugly for Wall Street.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Fed Chair Kevin Warsh and his colleagues may need to get more aggressive with rate hikes. Image source: Official Federal Reserve Photo.
Though there's no perfect inflation prediction tool, the Federal Reserve Bank of Cleveland's Inflation Nowcasting tool does an exceptional job of accounting for new economic data and adjusting inflation forecasts in real time.
#inflation #data #market #jones
But the stock market isn't without headwinds. Arguably, the biggest obstacle to the continuity of this bull market rally is persistently elevated inflation. The bad news for investors is that the Federal Reserve's initial inflation forecast for November shows things are getting downright ugly for Wall Street.
Missed AI's "Act 1"? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Fed Chair Kevin Warsh and his colleagues may need to get more aggressive with rate hikes. Image source: Official Federal Reserve Photo.
Though there's no perfect inflation prediction tool, the Federal Reserve Bank of Cleveland's Inflation Nowcasting tool does an exceptional job of accounting for new economic data and adjusting inflation forecasts in real time.
#inflation #data #market #jones
9 days ago
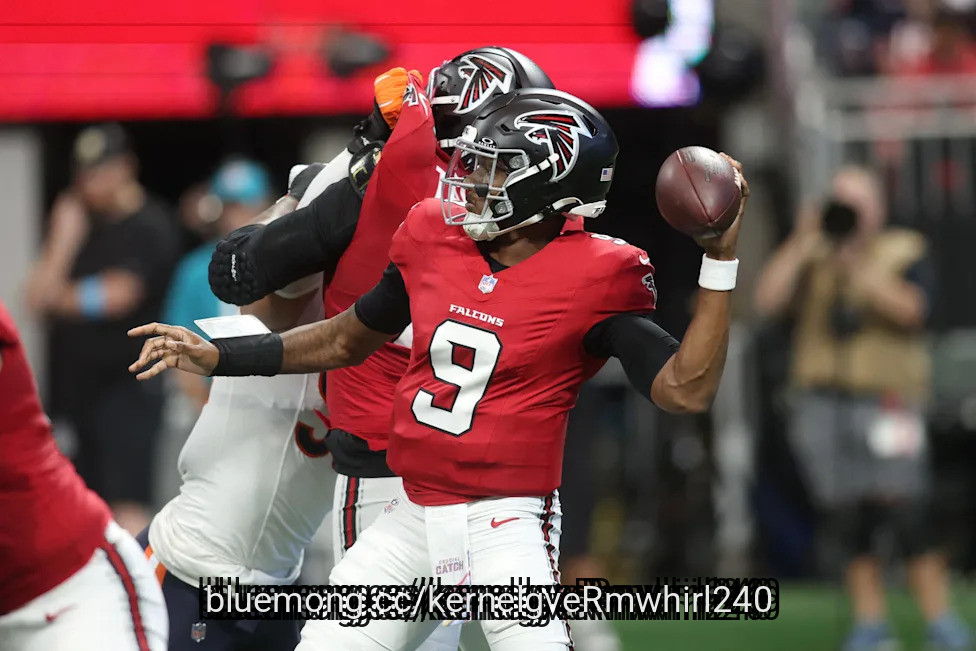
Slowly but surely the secret is coming out that Michael Penix Jr. has officially arrived as a franchise quarterback. The Atlanta Falcons' starter has been exceptional since returning to the lineup in Week 3, racking up nine touchdown passes to go with just one interception.
Penix is fresh off his best game of the season, totaling three scores and no turnovers against a top-five San Francisco 49ers defense.
That should have gotten Penix a huge ****** p in the weekly NFL.com quarterback rankings, but he only saw a modest gain of one spot, coming in at No. 12. That puts him in-between two former league MVPs, one spot below Patrick Mahomes and one above Matt Stafford.
"Michael Penix Jr. looks very comfortable and decisive in Kevin Stefanski's offense, freely spreading the ball among his many talented targets at a rate I haven't seen from him previously in his NFL career. Penix's contributions were especially important in a game in which Bijan Robinson fell short of breaking things open on the ground, and a reason to take the Falcons seriously going forward."
While the small gain is a little disappointing, keep in mind that Penix wasn't even listed in most quarterback rankings going into the season. Instead, it was Tua Tagovailoa representing the Falcons, usually somewhere between Nos. 30 and 32 among projected starters.
#quarterback
Penix is fresh off his best game of the season, totaling three scores and no turnovers against a top-five San Francisco 49ers defense.
That should have gotten Penix a huge ****** p in the weekly NFL.com quarterback rankings, but he only saw a modest gain of one spot, coming in at No. 12. That puts him in-between two former league MVPs, one spot below Patrick Mahomes and one above Matt Stafford.
"Michael Penix Jr. looks very comfortable and decisive in Kevin Stefanski's offense, freely spreading the ball among his many talented targets at a rate I haven't seen from him previously in his NFL career. Penix's contributions were especially important in a game in which Bijan Robinson fell short of breaking things open on the ground, and a reason to take the Falcons seriously going forward."
While the small gain is a little disappointing, keep in mind that Penix wasn't even listed in most quarterback rankings going into the season. Instead, it was Tua Tagovailoa representing the Falcons, usually somewhere between Nos. 30 and 32 among projected starters.
#quarterback



9 days ago
Manchester United are considering an ambitious January move for Leeds United striker Dominic Calvert-Lewin as Michael Carrick searches for solutions to his side's growing attacking concerns.
According to Laurie Whitwell and Beren Cross of The Athletic, United have begun ****** sing potential centre-forward targets ahead of the winter transfer window, with Calvert-Lewin emerging as a player of interest.
The 29-year-old England international has rediscovered his goalscoring touch at Elland Road, making him an intriguing option for a Manchester United side facing an increasingly complicated period without Benjamin Sesko.
However, persuading Leeds to part with their leading striker could prove exceptionally difficult.
Calvert-Lewin's resurgence represents one of the more compelling stories in English football. Having endured several injury-disrupted seasons at Everton, the striker has rebuilt his reputation since joining Leeds on a free transfer in the summer of 2025.
#leeds
According to Laurie Whitwell and Beren Cross of The Athletic, United have begun ****** sing potential centre-forward targets ahead of the winter transfer window, with Calvert-Lewin emerging as a player of interest.
The 29-year-old England international has rediscovered his goalscoring touch at Elland Road, making him an intriguing option for a Manchester United side facing an increasingly complicated period without Benjamin Sesko.
However, persuading Leeds to part with their leading striker could prove exceptionally difficult.
Calvert-Lewin's resurgence represents one of the more compelling stories in English football. Having endured several injury-disrupted seasons at Everton, the striker has rebuilt his reputation since joining Leeds on a free transfer in the summer of 2025.
#leeds



13 days ago
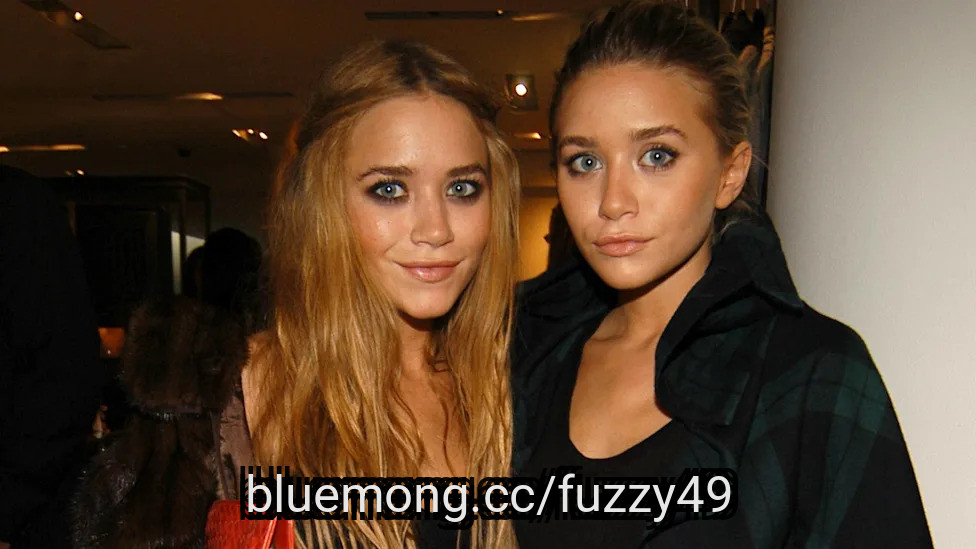
Millennials grew up watching the Olsen twins on Full House and in other family-friendly movies. It Takes Two, Passport to Paris, the list goes on.
Then came their business endeavors after stepping away from showbiz, and this year marks two full decades since Mary-Kate Olsen and Ashley Olsen launched a clothing line with one mission: design the perfect white T-shirt.
They called it The Row, and Women's Wear Daily reports that it remains influential across handbags and other fashion realms — yet never losing sight of its beginnings as an elevated basics brand.
The fashion line remains active on social media, especially this month. Check out The Row's Summer 2027 Womenswear Collection in the recent Instagram carousel below.
"Focusing on exceptional fabrics, impeccable details, and precise tailoring, the house combines a timeless perspective with subtle attitudes which form an irreverent classic signature," per the brand's official website. "The Row's collections also explore the strength of simplistic shapes that speak to discretion and are based on uncompromising quality."
#olsen
Then came their business endeavors after stepping away from showbiz, and this year marks two full decades since Mary-Kate Olsen and Ashley Olsen launched a clothing line with one mission: design the perfect white T-shirt.
They called it The Row, and Women's Wear Daily reports that it remains influential across handbags and other fashion realms — yet never losing sight of its beginnings as an elevated basics brand.
The fashion line remains active on social media, especially this month. Check out The Row's Summer 2027 Womenswear Collection in the recent Instagram carousel below.
"Focusing on exceptional fabrics, impeccable details, and precise tailoring, the house combines a timeless perspective with subtle attitudes which form an irreverent classic signature," per the brand's official website. "The Row's collections also explore the strength of simplistic shapes that speak to discretion and are based on uncompromising quality."
#olsen

20 days ago
A look up and a precise finish with sublime skill: Michael Olise once again demonstrated his exceptional quality in FC Bayern's 5–0 win over Bodø/Glimt. In the 83rd minute of the Champions League encounter, the Frenchman picked up pace down the right flank, cut inside and curled the ball beautifully into the top corner. A goal that was the perfect way to kick off the new Champions League campaign.
The German record champions' fans were thrilled by Olise's goal and chose it as FC Bayern's Goal of the Month for September. With 43.4 per cent of the vote, the forward came out on top against Alphonso Davies, who had also scored a spectacular goal to make it 3–0 during that same 5–0 win. Davies received 20.1 per cent of the vote.
Hot on Davies' heels were Jamal Musiala with his opener against Union Berlin (16.8 per cent) and Momoko Tanikawa, who also received 16.8 per cent of the votes for her winner against SC Freiburg. Fifth place went to Bogdan Olychenko for his opener for the FC Bayern reserves against Eichstätt (2.9 per cent).
It's already Olise's second consecutive fan accolade following his Goal of the Month for August. With his stunning finish against Bodø/Glimt, the Frenchman once again demonstrated that he's set to deliver special moments on a regular basis this season too.
Olise has been shortlisted for the Ballon d'Or alongside Harry Kane, Luis Díaz and Dayot Upamecano:
#champions
The German record champions' fans were thrilled by Olise's goal and chose it as FC Bayern's Goal of the Month for September. With 43.4 per cent of the vote, the forward came out on top against Alphonso Davies, who had also scored a spectacular goal to make it 3–0 during that same 5–0 win. Davies received 20.1 per cent of the vote.
Hot on Davies' heels were Jamal Musiala with his opener against Union Berlin (16.8 per cent) and Momoko Tanikawa, who also received 16.8 per cent of the votes for her winner against SC Freiburg. Fifth place went to Bogdan Olychenko for his opener for the FC Bayern reserves against Eichstätt (2.9 per cent).
It's already Olise's second consecutive fan accolade following his Goal of the Month for August. With his stunning finish against Bodø/Glimt, the Frenchman once again demonstrated that he's set to deliver special moments on a regular basis this season too.
Olise has been shortlisted for the Ballon d'Or alongside Harry Kane, Luis Díaz and Dayot Upamecano:
#champions


20 days ago
As of right now, we're in a bit of trouble.
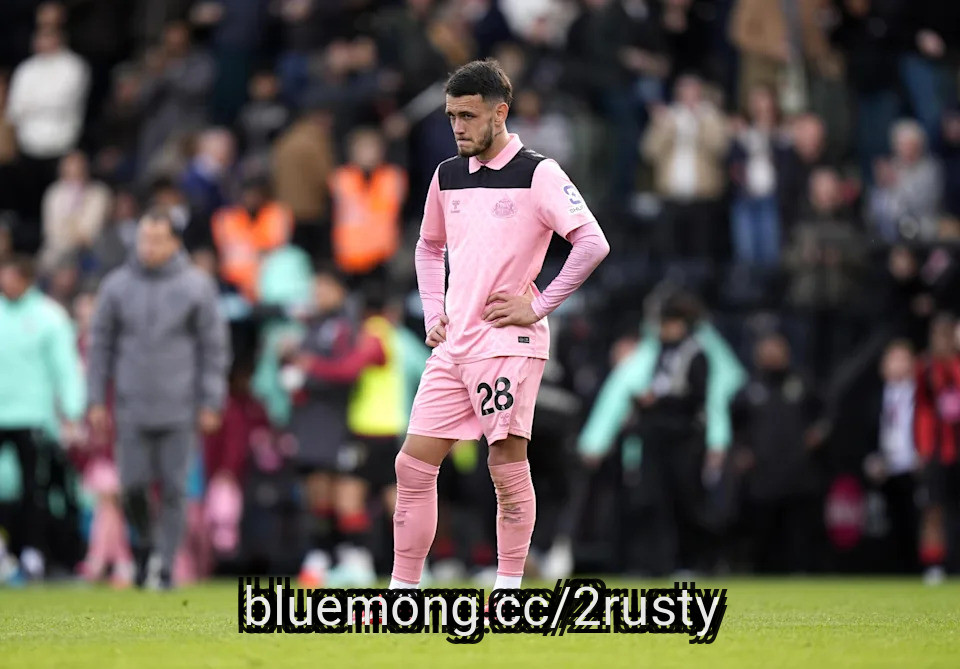
I despise the fact that I've had to type that sentence and I accept that it's still early in the season and with plenty of time for things to change, but the fact is that Sunderland are enduring a terrible opening stanza of their 2026/2027 Premier League season.
Although Thursday night's Europa League victory over Torreense was memorable, this crash-and-burn display against the Cherries was a brutal comedown and featured all the hallmarks of this lethargic, disjointed side in full cry.
From back to front (bar Robin Roefs, who was exceptional), the Lads were dismal on Sunday and even though Régis Le Bris shuffled the starting eleven in an attempt to shore things up and seemingly eke out a 0-1 away win, it backfired spectacularly, leaving the head coach with yet more wreckage to sift through and a group of players for whom the highs of 2025/2026 must seem a lifetime away.
This wasn't inevitable.
#premier
I despise the fact that I've had to type that sentence and I accept that it's still early in the season and with plenty of time for things to change, but the fact is that Sunderland are enduring a terrible opening stanza of their 2026/2027 Premier League season.
Although Thursday night's Europa League victory over Torreense was memorable, this crash-and-burn display against the Cherries was a brutal comedown and featured all the hallmarks of this lethargic, disjointed side in full cry.
From back to front (bar Robin Roefs, who was exceptional), the Lads were dismal on Sunday and even though Régis Le Bris shuffled the starting eleven in an attempt to shore things up and seemingly eke out a 0-1 away win, it backfired spectacularly, leaving the head coach with yet more wreckage to sift through and a group of players for whom the highs of 2025/2026 must seem a lifetime away.
This wasn't inevitable.
#premier



1 month ago
Trillion-dollar conglomerate Berkshire Hathaway (NYSE:BRKA)(NYSE:BRKB) entered 2026 in uncharted territory for the first time in more than half a century. On Dec. 31, Warren Buffett, the company's longtime CEO, who oversaw a greater-than-6,000,000% outperformance of the benchmark S&P 500 since the mid-1960s, retired as CEO. His successor, Greg Abel, is now in charge of Berkshire's $350 billion investment portfolio.
While the Oracle of Omaha had a knack for spotting amazing deals hiding in plain sight, he wasn't infallible. Decisions made in the years leading up to his retirement with No. 1 holding Apple (NASDAQ:AAPL) have cost Berkshire Hathaway up to $112 billion in would-be gains.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
Warren Buffett began building a position in the "Apple" of his eye in the first quarter of 2016. While artificial intelligence is all the rage today, Buffett was more interested in consumers' draw to the brand when he initially invested. Apple has an exceptionally loyal customer base that's shown a willingness to pay premium prices for its physical products (iPhone, iPad, and Mac).
#warren
While the Oracle of Omaha had a knack for spotting amazing deals hiding in plain sight, he wasn't infallible. Decisions made in the years leading up to his retirement with No. 1 holding Apple (NASDAQ:AAPL) have cost Berkshire Hathaway up to $112 billion in would-be gains.
Missed AI's "Act 1"? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ******* ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
Warren Buffett began building a position in the "Apple" of his eye in the first quarter of 2016. While artificial intelligence is all the rage today, Buffett was more interested in consumers' draw to the brand when he initially invested. Apple has an exceptionally loyal customer base that's shown a willingness to pay premium prices for its physical products (iPhone, iPad, and Mac).
#warren



1 month ago
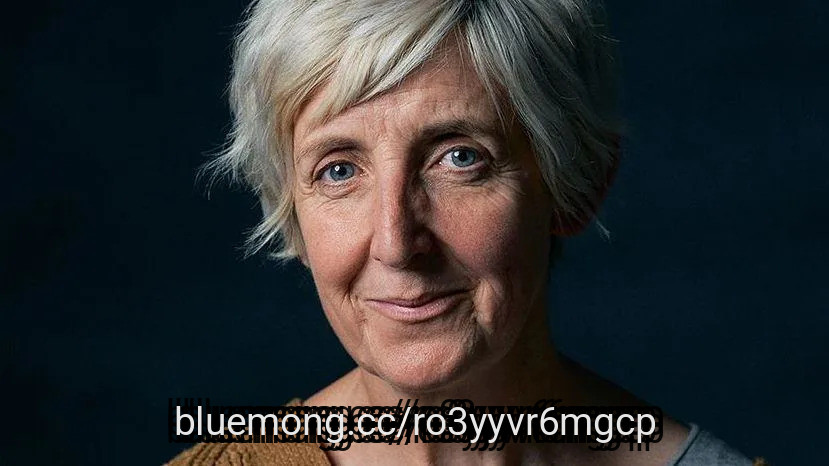
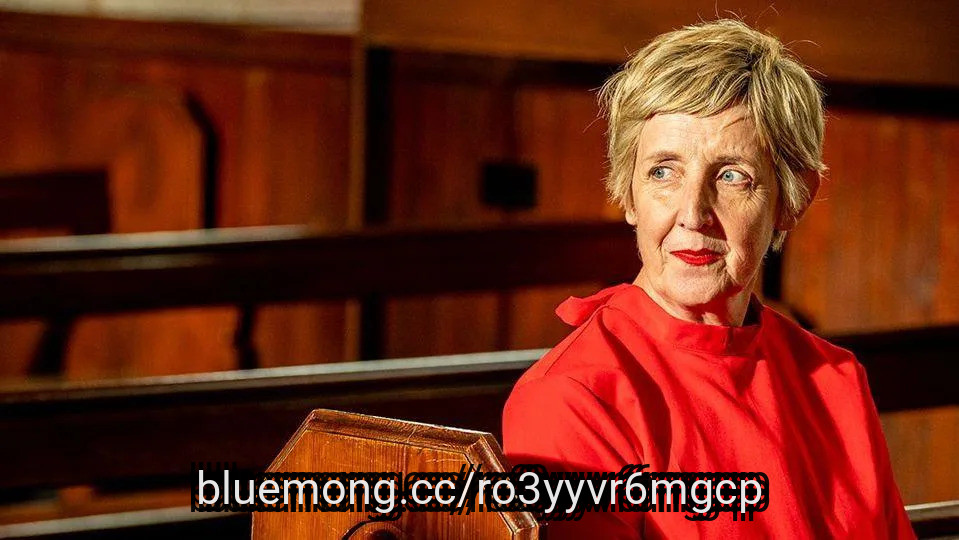
Actress Julie Hesmondhalgh is to become the first winner of The Theatres Trust's lifetime achievement award.
The former Coronation Street star from Accrington, Lancashire, is being recognised for her exceptional performances on stage and screen, as well as her work in championing regional theatres.
Hesmondhalgh, who played Hayley Cropper for more than 15 years, said she was "very honoured" with the accolade which will be presented to her at the inaugural Great British Theatres Awards in London on 2 November.
She is currently starring in BBC One's The Celebrity Traitors. Here's a look at her career and campaigning work.
Julie Hesmondhalgh is currently starring in BBC One's The Celebrity Traitors [BBC/Studio Lambert/Euan Cherry]
#starring
The former Coronation Street star from Accrington, Lancashire, is being recognised for her exceptional performances on stage and screen, as well as her work in championing regional theatres.
Hesmondhalgh, who played Hayley Cropper for more than 15 years, said she was "very honoured" with the accolade which will be presented to her at the inaugural Great British Theatres Awards in London on 2 November.
She is currently starring in BBC One's The Celebrity Traitors. Here's a look at her career and campaigning work.
Julie Hesmondhalgh is currently starring in BBC One's The Celebrity Traitors [BBC/Studio Lambert/Euan Cherry]
#starring

1 month ago
Warren Buffett stepped down from his role as the chief executive officer of Berkshire Hathaway (NYSE: BRKA)(NYSE: BRKB) at the end of 2025. During his 60-year tenure, he grew the company into a $1 trillion conglomerate with multiple wholly owned subsidiaries, a $350 billion stock portfolio, and over $350 billion in cash.
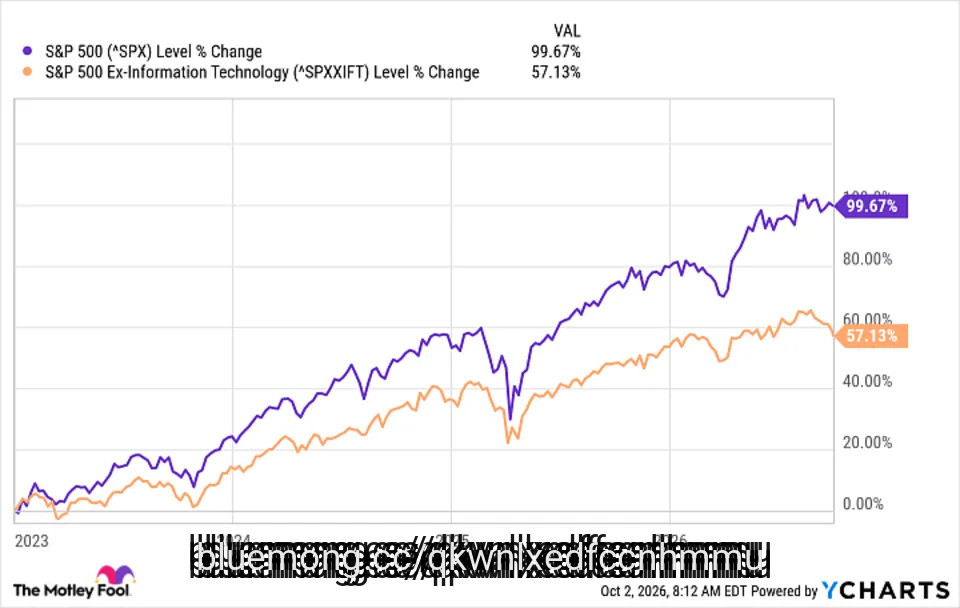
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing
Had an investor purchased $500 worth of Berkshire shares when Buffett took the helm in 1965, thatr person would have been sitting on a whopping $24 million by the time Buffett stepped down. However, Buffett was a full-time professional investor, so he always knew the average person would struggle to replicate his results. That's why he regularly advocated for exchange-traded funds (ETF) that track a diversified index like the S&P 500 (SNPINDEX: ^GSPC).
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
In his 2013 annual letter to shareholders (published in February 2014), Buffett specifically recommended the Vanguard S&P 500 ETF (NYSEMKT: VOO) because of its exceptionally low fees. While young investors in their 20s and 30s can afford to take more risks, those in their 40s who want to achieve financial security heading into retirement might want to heed Buffett's advice. Here's why I'd buy the Vanguard ETF if I were in that age group.
The S&P 500 is made up of 500 American companies from 11 different sectors of the economy. It has a very strict entry criteria, requiring its members to maintain a market capitalization of at least $22.7 billion, and they must also generate positive earnings. But even after meeting those conditions, a special committee still has the final say over which companies make the cut.
#NVIDIA #signal #flashing


1 month ago
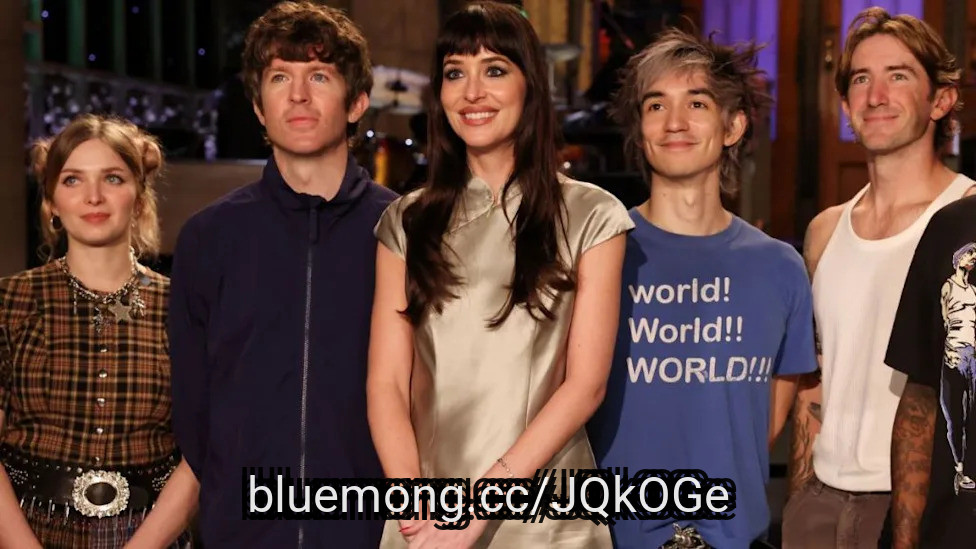
Dakota Johnson was a sight to behold in a Yana Matkivski set as she posed for promo ahead of her "Saturday Night Live" hosting debut. Recently, the actress stepped out in New York City, embodying minimalist glamour as always. Photos and videos of her from the promo shoot have already made the rounds online.
For the outing, Dakota Johnson turned heads in a stunning Yana Matkivski two-piece set. The sage-green satin top featured a structured, high-neck bodice designed with sharp cap sleeves that tapered cleanly into a fitted torso. The fabric converged at the hip into a cropped hem, framing the waistband of the matching skirt beneath it.
Furthermore, the Helen Mini Skirt revealed an exceptionally short hem that sat high on her thighs. Extending from the waistband, the satin fabric skimmed smoothly down her hips, falling softly over her legs as she walked.
The skirt also featured a fitted, straight-cut silhouette with no added volume or pleating. It hugged her hips before ending in a clean, minimalist line above the knee. The pairing blended structured tailoring with soft, fluid satin.
Johnson paired the set with serious sparkle, opting for Marlo Laz's Natasha Diamond Bracelet, a two-tone piece lined with round diamonds, priced at $26,000. On her finger, she added Jessica McCormack's 0.90ct Diamond Golden Snake Ring, valued at $33,500. Meanwhile, her beauty styling leaned into minimalist glamour to complement the muted tones of the set.
#dakota
For the outing, Dakota Johnson turned heads in a stunning Yana Matkivski two-piece set. The sage-green satin top featured a structured, high-neck bodice designed with sharp cap sleeves that tapered cleanly into a fitted torso. The fabric converged at the hip into a cropped hem, framing the waistband of the matching skirt beneath it.
Furthermore, the Helen Mini Skirt revealed an exceptionally short hem that sat high on her thighs. Extending from the waistband, the satin fabric skimmed smoothly down her hips, falling softly over her legs as she walked.
The skirt also featured a fitted, straight-cut silhouette with no added volume or pleating. It hugged her hips before ending in a clean, minimalist line above the knee. The pairing blended structured tailoring with soft, fluid satin.
Johnson paired the set with serious sparkle, opting for Marlo Laz's Natasha Diamond Bracelet, a two-tone piece lined with round diamonds, priced at $26,000. On her finger, she added Jessica McCormack's 0.90ct Diamond Golden Snake Ring, valued at $33,500. Meanwhile, her beauty styling leaned into minimalist glamour to complement the muted tones of the set.
#dakota

1 month ago
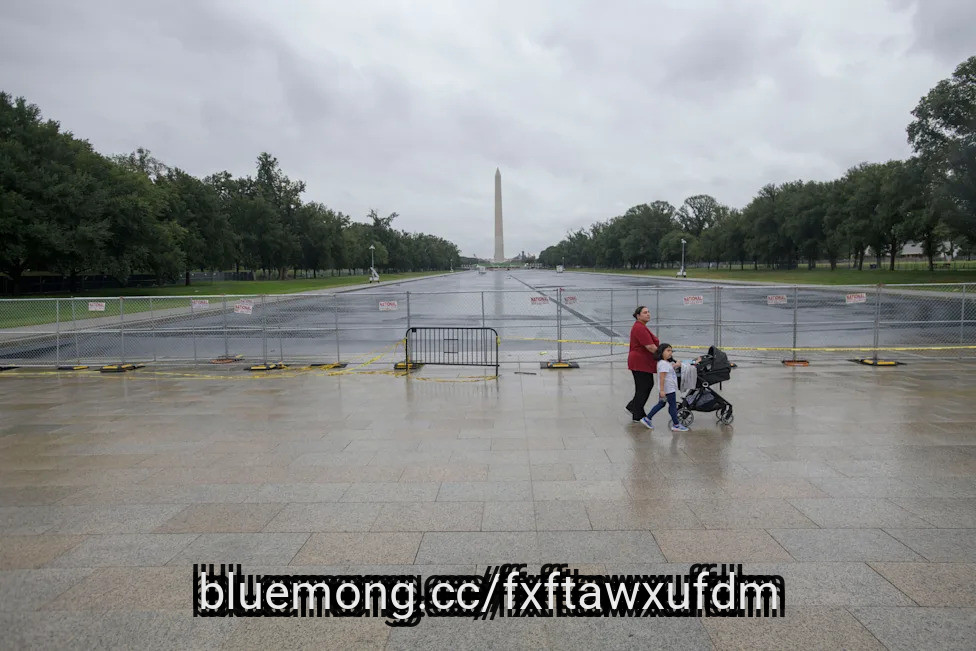
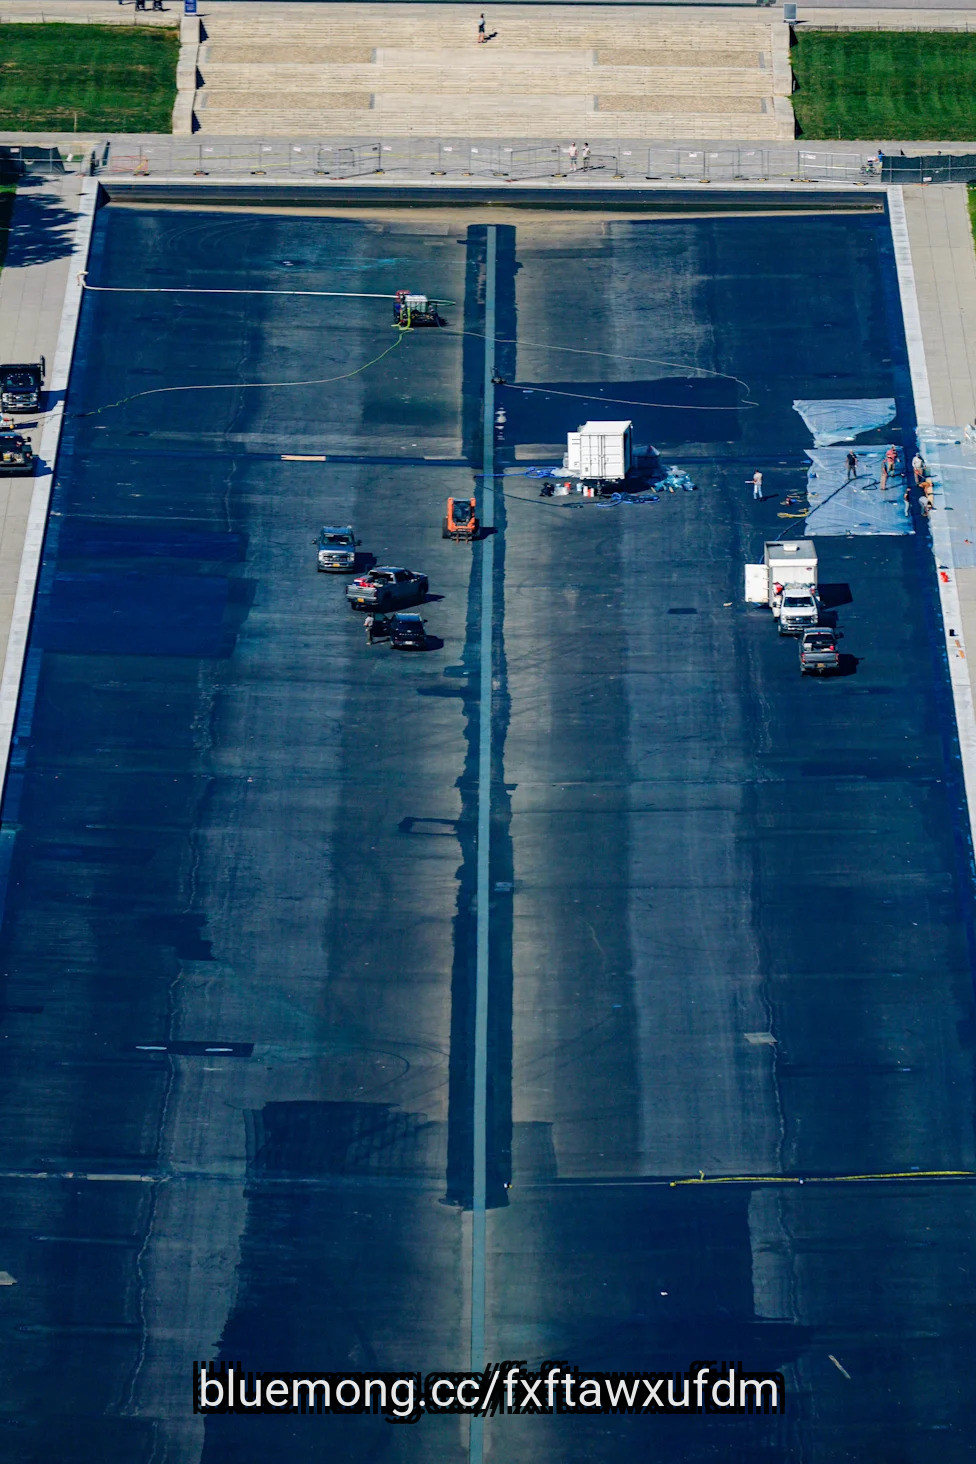
WASHINGTON (AP) — A judge in the nation's capital agreed on Thursday to permanently dismiss a criminal case charging a former Olympian with vandalizing the Lincoln Memorial Reflecting Pool, a move that could prevent federal prosecutors from reviving the case under political pressure from President Donald Trump.
D.C. Superior Court Judge Todd Edelman ordered the dismissal of David Hearn's case with "prejudice," which would block U.S. Attorney Jeanine Pirro's office from refiling the felony charge against him. The judge ruled nearly a month after hearing attorneys' arguments.
Hearn's lawyers say Trump administration officials have continued to falsely accuse the Maryland resident of vandalizing the reflecting pool despite Pirro's decision to drop the case on July 31. Trump responded by saying Pirro "choked" and "folded like an umbrella."
Edelman said the case presents "exceptional circumstances" that warrant dismissing the case permanently. He agreed with defense attorneys that the government "shot first and asked questions later" by charging Hearn in a "a lightning-fast indictment process."
"While the government wishes to hold open the possibility of the development of evidence that would support a future prosecution, its own representations make plain that such a possibility is theoretical at best, and more likely, is simply fanciful," the judge wrote.
#reflecting
D.C. Superior Court Judge Todd Edelman ordered the dismissal of David Hearn's case with "prejudice," which would block U.S. Attorney Jeanine Pirro's office from refiling the felony charge against him. The judge ruled nearly a month after hearing attorneys' arguments.
Hearn's lawyers say Trump administration officials have continued to falsely accuse the Maryland resident of vandalizing the reflecting pool despite Pirro's decision to drop the case on July 31. Trump responded by saying Pirro "choked" and "folded like an umbrella."
Edelman said the case presents "exceptional circumstances" that warrant dismissing the case permanently. He agreed with defense attorneys that the government "shot first and asked questions later" by charging Hearn in a "a lightning-fast indictment process."
"While the government wishes to hold open the possibility of the development of evidence that would support a future prosecution, its own representations make plain that such a possibility is theoretical at best, and more likely, is simply fanciful," the judge wrote.
#reflecting

2 months ago
Volkswagen has dramatically cut its 2026 profit outlook as deteriorating business in China, restructuring costs and a multibillion-euro writedown at Porsche pile pressure on Europe's largest automaker.
The German carmaker now expects an operating margin of no more than 1% this year, down from its previous forecast of at least 4%, according to Bloomberg. Volkswagen shares fell more than 7% following the announcement, dragging other automakers lower.
VW expects around €10 billion ($11.5 billion) in charges this year, including restructuring costs ****** ociated with workforce reductions and writedowns on Chinese ****** ets. The total includes a €6-billion writedown related to Porsche, reflecting revised long-term expectations for the sports-car maker.
Excluding the exceptional charges, Volkswagen said its operating margin would be around 4%.
China represents one of the biggest challenges. Volkswagen CFO Arno Antlitz said the market has contracted by around 20%, with no stabilization currently in sight. Chinese automakers are simultaneously taking domestic market share and expanding into Europe with competitively priced electric vehicles.
#porsche
The German carmaker now expects an operating margin of no more than 1% this year, down from its previous forecast of at least 4%, according to Bloomberg. Volkswagen shares fell more than 7% following the announcement, dragging other automakers lower.
VW expects around €10 billion ($11.5 billion) in charges this year, including restructuring costs ****** ociated with workforce reductions and writedowns on Chinese ****** ets. The total includes a €6-billion writedown related to Porsche, reflecting revised long-term expectations for the sports-car maker.
Excluding the exceptional charges, Volkswagen said its operating margin would be around 4%.
China represents one of the biggest challenges. Volkswagen CFO Arno Antlitz said the market has contracted by around 20%, with no stabilization currently in sight. Chinese automakers are simultaneously taking domestic market share and expanding into Europe with competitively priced electric vehicles.
#porsche


2 months ago
Answering a caller's query about The Procter & Gamble Company (NYSE:PG) during the lightning round of the September 10 episode of Mad Money, Jim Cramer said:
It's a tough stock. It's a tough stock because they don't have the growth that I want. They do have the 3% yield, but that's not enough. So, I'm going to say, you know, we sold it for the club. Don't look back.
The Procter & Gamble Company's (NYSE:PG) upside relies on elite operational execution and pricing power in high-margin categories. Continuous supply chain savings and an aggressive premiumization push toward items like Tide PODS help protect profitability. Combined with strong free cash flow productivity, management returned roughly $15 billion in FY 2026 through dividends and share buybacks, ensuring a steady earnings floor despite slow top-line growth.
The primary headwind is weak top-line momentum, with organic sales flat in the second quarter as challenging consumer trends, particularly in the U.S., weighed on growth. Foreign exchange friction and cost pressures further cap near-term earnings acceleration. Additionally, while the stock offers a reliable 3% dividend yield, that income profile creates a steep opportunity cost when risk-free ******* ets and higher-growth stocks offer attractive returns. We recently discussed what Cramer thinks is the ideal valuation for a good entry point in our article, "Jim Cramer Discusses Procter & Gamble (PG) Valuation and Growth."
According to Insider Monkey's data, 83 hedge funds had a stake in The Procter & Gamble Company (NYSE:PG) in Q2 compared to 78 in the prior quarter. Short percentage of the float is 1.21%, showing its status as a defensive holding rather than a short target. While the company provides exceptional balance sheet stability and reliable cash returns for defensive portfolios, its modest top-line growth trajectory and premium valuation continue to test investor patience, validating Cramer's decision to reallocate capital toward faster-moving opportunities.
#company
It's a tough stock. It's a tough stock because they don't have the growth that I want. They do have the 3% yield, but that's not enough. So, I'm going to say, you know, we sold it for the club. Don't look back.
The Procter & Gamble Company's (NYSE:PG) upside relies on elite operational execution and pricing power in high-margin categories. Continuous supply chain savings and an aggressive premiumization push toward items like Tide PODS help protect profitability. Combined with strong free cash flow productivity, management returned roughly $15 billion in FY 2026 through dividends and share buybacks, ensuring a steady earnings floor despite slow top-line growth.
The primary headwind is weak top-line momentum, with organic sales flat in the second quarter as challenging consumer trends, particularly in the U.S., weighed on growth. Foreign exchange friction and cost pressures further cap near-term earnings acceleration. Additionally, while the stock offers a reliable 3% dividend yield, that income profile creates a steep opportunity cost when risk-free ******* ets and higher-growth stocks offer attractive returns. We recently discussed what Cramer thinks is the ideal valuation for a good entry point in our article, "Jim Cramer Discusses Procter & Gamble (PG) Valuation and Growth."
According to Insider Monkey's data, 83 hedge funds had a stake in The Procter & Gamble Company (NYSE:PG) in Q2 compared to 78 in the prior quarter. Short percentage of the float is 1.21%, showing its status as a defensive holding rather than a short target. While the company provides exceptional balance sheet stability and reliable cash returns for defensive portfolios, its modest top-line growth trajectory and premium valuation continue to test investor patience, validating Cramer's decision to reallocate capital toward faster-moving opportunities.
#company


2 months ago
Walk into a Burlington Stores (NYSE:BURL) location on a Saturday afternoon, and you will see the mechanism of the company's business model in action. It's a literal hunt for value: a customer finds a name-brand jacket at a steep discount, checks the tag, and takes it to the register. Burlington operates as an off-price retailer of apparel, footwear, and home goods. With the stock priced at $228.73 as of Sept. 15, 2026, it has fallen by 15% over the past 12 months, a period marked by significant operational expansion and active navigation of the retail sector.
Our proprietary Hidden Gems scoring system ****** igns Burlington Stores an overall Superscore of 78 out of 100, placing it in the Strong category. The Superscore is an AI-powered metric that evaluates a company's overall strength by combining financial performance, product-market position, technological capabilities, leadership quality, and relative valuation. It represents the unification of all our scores into a single score for public companies, with five rating bands: Exceptional (90-100), Strong (75-89), Above Average (60-74), Average (40-59), and Cautious (0-39).
This 78 Superscore places the company in the Top ~14% of every company we score. This ****** ysis provides a data-driven signal to help you weigh the company's operational strengths against its risks as part of your own due diligence.
Accelerated store growth: Management successfully opened 104 net new stores in fiscal 2025, executing a long-term strategy to reach 2,000 total locations.
Operational efficiency gains: Gross margin reached 46% in Q2 fiscal 2026, driven by improved inventory turnover and a sophisticated supply chain that distributes goods from six regional centers.
#strong
Our proprietary Hidden Gems scoring system ****** igns Burlington Stores an overall Superscore of 78 out of 100, placing it in the Strong category. The Superscore is an AI-powered metric that evaluates a company's overall strength by combining financial performance, product-market position, technological capabilities, leadership quality, and relative valuation. It represents the unification of all our scores into a single score for public companies, with five rating bands: Exceptional (90-100), Strong (75-89), Above Average (60-74), Average (40-59), and Cautious (0-39).
This 78 Superscore places the company in the Top ~14% of every company we score. This ****** ysis provides a data-driven signal to help you weigh the company's operational strengths against its risks as part of your own due diligence.
Accelerated store growth: Management successfully opened 104 net new stores in fiscal 2025, executing a long-term strategy to reach 2,000 total locations.
Operational efficiency gains: Gross margin reached 46% in Q2 fiscal 2026, driven by improved inventory turnover and a sophisticated supply chain that distributes goods from six regional centers.
#strong


2 months ago
Hive Digital Technologies Chief Financial Officer Darcy Daubaras joined Steve Darling from Proactive to discuss the appointment of renowned capital markets executive Hubert Marleau as an Independent Director of HIVE's wholly owned subsidiary, BUZZ High Performance Computing (BUZZ HPC), a move designed to strengthen governance and strategic oversight as the company expands its sovereign AI infrastructure platform across Canada.
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across
Daubaras said Marleau's appointment brings an exceptional level of experience in capital markets, corporate governance and strategic growth at a pivotal time for BUZZ HPC. As demand for artificial intelligence infrastructure continues to accelerate globally, HIVE is positioning BUZZ HPC as a key provider of sovereign AI computing solutions, and management believes Marleau's expertise will help guide the business through its next phase of expansion.
Marleau has spent more than five decades working across North American capital markets and is widely recognized as one of Canada's most experienced investment and governance professionals. His career spans investment banking, ******* et management, corporate finance and public company leadership, giving him a unique perspective on scaling businesses, raising capital and creating shareholder value.
A co-founder of Palos Capital Corp. and Palos Management Inc., Marleau has held influential leadership positions throughout Canada's financial sector. His extensive resume includes serving as a Governor of both the Montreal and Vancouver stock exchanges, Chairman of the Toronto Stock Exchange Listing Committee and a director of the Investment Dealers ******* ociation of Canada, now known as IIROC.
Over the course of his distinguished career, Marleau has served as a current or former director of more than 50 publicly traded companies in Canada and the United States. He has also played a key role in raising both public and private capital for hundreds of issuers and has advised on numerous mergers, acquisitions and financing transactions across a wide range of industries.
#canada #across

2 months ago
On September 10, a caller outlined a detailed financial thesis showing Micron Technology, Inc. (NASDAQ:MU) reaching $1,400 and asked whether the **** ysis held water. In response, Mad Money host Jim Cramer said:
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry
I mean, that's a remarkable **** ysis. It's spot on in every single number. Every single thing you said is true, which is why my Charitable Trust owns it, and why we are buying it aggressively. And by the way, can I just say if you listen to what… [the caller] said, he put some money away. He was fortunate enough to have money, which I know not everybody can have, but he had money. He put it in an individual stock. Now, if he put it in an index fund, he'd make some money, but he got really rich. And part of my job is not just to get you rich, but to hopefully get you really rich.
Micron Technology, Inc. (NASDAQ:MU) stands as one of three primary global manufacturers of dynamic random-access memory (DRAM) and NAND flash memory, positioning it at the center of the ongoing expansion in artificial intelligence infrastructure. Because advanced AI workloads require significantly higher memory bandwidth, demand has surged for Micron's High-Bandwidth Memory (HBM3E) architecture, which is integrated directly into top-tier AI graphics processors and data center accelerators. With memory production capacity for advanced AI chips remaining constrained industry-wide, Micron has secured long-term purchase agreements that cover its HBM output through 2026 and into 2027, providing visibility into top-line revenue growth.
Driven by accelerated AI server adoption and broader pricing recovery across traditional DRAM and NAND markets, it reported extraordinary growth in fiscal Q3. Revenue surged to $41.46 billion, more than quadrupling the $9.30 billion generated in the same period last year and stepping up sharply from $23.86 billion in the prior quarter. The company demonstrated exceptional operating leverage during the period, posting GAAP net income of $28.24 billion ($24.67 per diluted share) and non-GAAP net income of $28.86 billion ($25.11 per diluted share). Operating cash flow also scaled quickly, reaching $25.39 billion compared to $11.90 billion in the prior quarter and $4.61 billion in the prior-year period.
Despite its strong position in the AI supply chain, Micron Technology, Inc. (NASDAQ:MU) operates in a historically cyclical memory industry with some operational and market risks. Memory chip pricing remains sensitive to industry-wide supply-and-demand imbalances, where oversupply can rapidly compress profit margins during broader downturns in consumer electronics demand or corporate IT spending.
#billion #memory #NASDAQ #industry


2 months ago
Auxier ******* et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset
In its second-quarter 2026 investor letter, Auxier ******* et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ******* et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#Growth #asset

2 months ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#billion #year #rather


2 months ago
Auxier ***** et Management, an investment advisory firm, released its second-quarter 2026 investor letter. The letter can be downloaded here. Following a strong rebound from the first-quarter decline, the S&P 500 gained 15.2% as accelerating capital spending toward artificial intelligence infrastructure drove significant gains across technology hardware companies. Semiconductor and data-center-related businesses benefited from supply constraints and strong demand, while enterprise software remained under pressure as investors reassessed AI disruption risks and compressed valuations. In the quarter, Auxier Focus Fund's Investor Class gained 8.82% and 10.70% for the six months ended June 30, 2026. Despite strong earnings growth across the broader market, Auxier highlighted concerns around rising margin debt, increased leverage, and elevated capital flows into high-growth technology areas that could amplify future volatility. The firm continues to focus on identifying enduring businesses with strong competitive advantages, resilient cash flows, and sustainable long-term growth potential. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong
In its second-quarter 2026 investor letter, Auxier ***** et Management highlighted The Kroger Co. (NYSE:KR). The Kroger Co. (NYSE:KR) is a leading supermarket chain that operates combination food and drug stores, multi-department stores, marketplace stores, and price impact warehouses. On September 14, 2026, The Kroger Co. (NYSE:KR) closed at $60.91 per share. Over the past month, The Kroger Co. (NYSE:KR) returned 10.12%, but its shares are down 7.06% over the past year. The Kroger Co. (NYSE:KR) has a market capitalization of $37.32 billion, and its stock has traded within a 52-week range of $54.15 to $76.58.
Auxier ***** et Management stated the following regarding The Kroger Co. (NYSE:KR) in its Q2 2026 investor letter:
"Consumer staples underperformed during the quarter. Elevated inflation, high interest rates and rising gas prices contributed to lower consumer spending, impacting companies like The Kroger Co. (NYSE:KR) and PepsiCo. Although Kroger's stock has been weak, its new CEO Greg Foran brings exceptional leadership that promises positive change. While he was President of Walmart US from 2014-2019, the company achieved 20 consecutive quarters of same-store sales growth and scaled its online grocery pickup. Since joining Kroger he has aggressively reduced prices and boosted the growth in private label and organic offerings. The stock trades at a mere 12 times earnings which is a significant discount to both Costco and Walmart."
#NYSE #quarter #Growth #strong

2 months ago
Bank of America Corporation (NYSE:BAC) expects third-quarter investment banking fees to fall by at least 10% year over year, which highlights a broader normalization across capital markets after an unusually strong first half of 2026. BofA expects investment banking fees of roughly $1.6 billion to $1.8 billion in the third quarter, compared with $2 billion a year earlier. CEO Brian Moynihan said the broader investment banking market is also down around 10%, suggesting that the softer quarter reflects a cooling in industry activity rather than a company-specific breakdown.
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year
The comparison with the second quarter illustrates how sharp the normalization is. BofA's investment banking fees had risen 50% year over year to $2.1 billion in Q2, while sales and trading revenue reached a record $7.1 billion. The current outlook therefore represents a pullback from elevated levels rather than a reversal of the broader recovery in dealmaking. Global M&A activity remained substantial in the first half of 2026, with more than $3 trillion of announced transactions, providing evidence that corporate deal appetite has remained relatively healthy even as quarterly activity fluctuates.
Pixabay/Public Domain
From a longer-term perspective, the normalization does not necessarily undermine Bank of America Corporation (NYSE:BAC)'s capital-markets franchise. Investment banking revenues remain well above the depressed levels seen during the earlier downturn in deal activity, while the bank continues to have a substantial pipeline of potential transactions. Moynihan's comments that the pipeline remains strong suggest that some of the current weakness could reflect the timing of transactions rather than a fundamental loss of corporate demand for M&A, financing or advisory services.
BofA also has a diversified earnings base that makes it less dependent on any single capital-markets cycle. Its second-quarter net interest income increased 9% to $16 billion, while average loans and leases grew 8%. That provides a more stable source of revenue as investment banking normalizes. In this context, the Q3 decline can be viewed as a shift away from exceptionally strong capital-markets contributions rather than evidence that the bank's broader earnings trajectory has deteriorated.
#investment #banking #year

2 months ago
ASML Holding N.V. (NASDAQ:ASML) is examining ways to produce more than 110 EUV lithography systems in 2028, according to JPMorgan ***** ysts following a meeting with CFO Roger Dassen. The company is already nearly sold out for 2027 and expects to produce at least 80 EUV systems that year, meaning output above 110 in 2028 would represent at least a 37.5% increase from the 2027 level. JPMorgan said the main constraint has shifted toward ***** embly speed rather than the availability of critical components, suggesting ASML believes additional capacity can be unlocked through manufacturing and ***** embly improvements.
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company
The potential increase is being driven primarily by AI-related demand. ASML's existing EUV machines, which cost roughly $200 million each, are essential for manufacturing leading-edge AI processors, while customers including TSMC, Samsung, SK Hynix and Intel are expanding advanced-chip capacity. Reuters reported separately that virtually all of ASML's EUV production capacity is booked through 2027, while the company has begun construction of a new Eindhoven facility designed to accelerate tool ***** embly and eventually accommodate up to 20,000 workers.
The strongest bullish implication is that ASML Holding N.V. (NASDAQ:ASML) may be able to convert exceptionally strong demand into higher unit volumes rather than simply relying on price increases. Moving from at least 80 EUV systems in 2027 to more than 110 in 2028 would materially expand the number of high-value systems ASML can monetize. This comes after the company already raised its 2026 revenue outlook to €43 billion–€45 billion, compared with its previous €36 billion–€40 billion range, while targeting a 54%–56% gross margin. Reuters also reported that second-quarter revenue reached €9.3 billion with a 54% gross margin, demonstrating that stronger AI-driven demand is already translating into financial performance.
The longer-term competitive position is particularly favorable because ASML Holding N.V. (NASDAQ:ASML) effectively has no commercial competitor in EUV. JPMorgan estimates that ASML held 94% of the overall lithography market in 2025, while Reuters describes the company as having maintained a monopoly in EUV since the late 2010s. At the same time, customers are committing to ASML's next-generation High-NA technology: the machines cost approximately $400 million, can print features about 40% smaller than existing EUV systems, and TSMC, Samsung, and SK Hynix have all established plans for production adoption. If AI chip demand remains strong enough to support both higher low-NA volumes and eventual High-NA adoption, ASML could see a multi-year increase in system shipments, revenue, and potentially cash generation while strengthening its already exceptional competitive moat.
#company

2 months ago
(NewsNation) — Two days into their first term at a school in the United Kingdom, Prince Archie and Princess Lilibet are already switching schools due to security concerns.
A spokesperson for the Duke and ***** ss of Sussex told People Magazine that the children were being removed from the school in the Cotswolds over security concerns that were unknown until the term began.
Those concerns included heavy traffic in the area, the distance between the school and the family's home, and that the concern was heightened after an incident that, ***** o magazine reports, "made it difficult for their vehicles to stay in convoy."
Meghan to head back to the US in 5 weeks for 'work'
"The parents remain extremely grateful to all the teachers and staff for the love, care and effort they have shown their family," the spokesperson said. "This decision should in no way be interpreted as a reflection on the school or the exceptional care the children have received there."
#security #spokesperson
A spokesperson for the Duke and ***** ss of Sussex told People Magazine that the children were being removed from the school in the Cotswolds over security concerns that were unknown until the term began.
Those concerns included heavy traffic in the area, the distance between the school and the family's home, and that the concern was heightened after an incident that, ***** o magazine reports, "made it difficult for their vehicles to stay in convoy."
Meghan to head back to the US in 5 weeks for 'work'
"The parents remain extremely grateful to all the teachers and staff for the love, care and effort they have shown their family," the spokesperson said. "This decision should in no way be interpreted as a reflection on the school or the exceptional care the children have received there."
#security #spokesperson


2 months ago
Dell Technologies (DELL) stock more than quadrupled over the past year, a 323% gain, against about 18% for the S&P 500, and even Hewlett Packard Enterprise (HPE), up 130.6%, finished far behind. Management had described most of the drivers before the run began: customers sitting on old servers, AI orders that had outrun shipments earlier in the year, and costs falling while sales rose. Those signs could not tell you how far the stock would go.
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
What Was Dell Seeing In Its Customers' Data Centers?
In February 2025, management said customers still ran a very large base of Dell's 13th and 14th generation servers, ready to be replaced. AI demand, already under discussion then, was exceptionally strong by May 2025, with $12.1 billion of AI server orders in fiscal Q1 2026, more than Dell's AI server shipments for all of fiscal 2025.
In August 2025, management said over 70% of its installed base was running on 14th generation servers or older, and that one 17th generation server could replace six or seven old ones. The results were uneven. In fiscal Q2 2026, traditional server revenue rose again and international demand grew, but demand in North America, its most profitable region, was weak.
Why Were Dell's Costs Falling While Its Sales Rose?
#server
2 months ago
On September 8, a caller inquired if Trinity Industries, Inc. (NYSE:TRN) is worth looking at after its recent pullback. Mad Money host Jim Cramer replied:
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
Yes, Railcar, shouldn't be down this much. I like your thinking. You waited for the big hit. Now, it's in a good place. I would pull the trigger.
Trinity Industries, Inc. (NYSE:TRN) has faced a sharp correction, pulling back significantly from its 52-week high of $38.31. Despite this downward pressure, the company's fundamental **** et base remains exceptionally stable. In its second-quarter earnings report, the company posted total revenues of $485 million and diluted earnings per share from continuing operations of $1.25, with earnings benefiting from a $132 million non-cash pre-tax gain tied to the Napier Park railcar partnership transaction.
The leasing and services segment continues to support the business, posting a robust fleet utilization rate of 97.3% and an improved lease renewal success rate of 75%. In addition, the Future Lease Rate Differential improved to +3.5%, showing healthy pricing power on expiring contracts. Management reaffirmed its full-year EPS guidance of $2.20 to $2.40, supported by a solid railcar backlog standing at $1.6 billion.
The primary catalyst for Trinity Industries, Inc.'s (NYSE:TRN) recent sell-off stems from margin compression within the Rail Products manufacturing division. Operating margins in manufacturing faced pressure from an unplanned production interruption at the Longview manufacturing facility and temporary realignment expenses tied to the company's Mexican footprint. These localized execution issues overshadowed a strong quarterly performance in leasing, causing the stock to drift below both its 50-day and 200-day moving average.
#trinity
2 months ago
1900
The White Sox beat the Cleveland Blues, 12-4, in Chicago to clinch the franchise's first pennant. (The American League would not be recognized as an official major league until 1901, however.) Roy Patterson got the win in the game.
The season seemed to set the tone for the franchise, with exceptional pitching and defense — and just enough hitting to win games. Cleveland manager Jimmy McAleer said as much after the Sox clinched against his club: "It's the strangest thing that ever happened. A club with no good batsman to win a flag! Why, such a thing was never heard of before. [Dick] Padden has done most of it. He has been the whole works, and has shown himself a born general. The pitchers did the rest, with special credit to that lad Patterson."
Brett Ballantini devoted an episode of South Side Sox's Flashback to this win, back in 2019.
1908
Ultimately, the White Sox did not prevail for the pennant, but don't say they didn't put up a fight. Arriving at Detroit's Bennett Park for a five-game set against the first-place Tigers and behind by three games, the White Sox won the opener, then played four consecutive extra-inning games to finish out the series, splitting them. On this day, the White Sox got back to just two games out with a 2-1 victory in 10 innings. Frank Smith not only went the distance for his 12th win on the season, he singled in the game-winner in the top of the 10th.
The White Sox continued a three-way fight for the pennant (with Cleveland as well), and the season came down to the last day, hosting Detroit. Had the White Sox not been blown out in the finale, they would have finished tied with (but percentage points ahead of) Cleveland and a half-game in front of the Tigers for the pennant.
#white #season #patterson #league
The White Sox beat the Cleveland Blues, 12-4, in Chicago to clinch the franchise's first pennant. (The American League would not be recognized as an official major league until 1901, however.) Roy Patterson got the win in the game.
The season seemed to set the tone for the franchise, with exceptional pitching and defense — and just enough hitting to win games. Cleveland manager Jimmy McAleer said as much after the Sox clinched against his club: "It's the strangest thing that ever happened. A club with no good batsman to win a flag! Why, such a thing was never heard of before. [Dick] Padden has done most of it. He has been the whole works, and has shown himself a born general. The pitchers did the rest, with special credit to that lad Patterson."
Brett Ballantini devoted an episode of South Side Sox's Flashback to this win, back in 2019.
1908
Ultimately, the White Sox did not prevail for the pennant, but don't say they didn't put up a fight. Arriving at Detroit's Bennett Park for a five-game set against the first-place Tigers and behind by three games, the White Sox won the opener, then played four consecutive extra-inning games to finish out the series, splitting them. On this day, the White Sox got back to just two games out with a 2-1 victory in 10 innings. Frank Smith not only went the distance for his 12th win on the season, he singled in the game-winner in the top of the 10th.
The White Sox continued a three-way fight for the pennant (with Cleveland as well), and the season came down to the last day, hosting Detroit. Had the White Sox not been blown out in the finale, they would have finished tied with (but percentage points ahead of) Cleveland and a half-game in front of the Tigers for the pennant.
#white #season #patterson #league
2 months ago
FC Barcelona will be gunning for their sixth straight victory this season when they take on Levante in La Liga on Sunday.
The Blaugrana came into the matchday as La Liga leaders, after having won each of their four games in the competition so far, scoring 17 and conceding only two goals.
They built on their exceptional start with a 5-1 thrashing of Feyenoord in their UEFA Champions League opener on Wednesday night.
Given their splendid form so far, Barça go into the game as overwhelming favourites. Their opponents, Levante are in the bottom half of the table with five points from four games so far.
They have not lost any of their previous three matches, drawing against Osasuna and Malaga on either side of a 5-2 victory over Real Betis.
#levante #games #Barcelona
The Blaugrana came into the matchday as La Liga leaders, after having won each of their four games in the competition so far, scoring 17 and conceding only two goals.
They built on their exceptional start with a 5-1 thrashing of Feyenoord in their UEFA Champions League opener on Wednesday night.
Given their splendid form so far, Barça go into the game as overwhelming favourites. Their opponents, Levante are in the bottom half of the table with five points from four games so far.
They have not lost any of their previous three matches, drawing against Osasuna and Malaga on either side of a 5-2 victory over Real Betis.
#levante #games #Barcelona


2 months ago
Liverpool head into another Premier League test with momentum building, and Virgil van Dijk has made the message clear. Good performances matter, results matter more, but consistency is what separates serious sides from the rest.
After a comeback win over Atletico Madrid in midweek and a 2-0 league victory against Ipswich Town before that, Liverpool now have the chance to make it three wins on the bounce at Anfield against Fulham. The captain is not interested in noise or sentiment. He is focused on standards.
In his programme notes, Van Dijk said: "After an important and, in my opinion, well-deserved win over Atletico Madrid, it is great to be back at Anfield again this afternoon as we return to Premier League action against Fulham.
"I thought the atmosphere on Wednesday night was exceptional, particularly in the second half as we chased the victory.
"I have said many times that we are at our best when everyone is pushing together, and I hope you can see how hard we are all working to give you a team to be proud of."
#premier #dijk #fulham
After a comeback win over Atletico Madrid in midweek and a 2-0 league victory against Ipswich Town before that, Liverpool now have the chance to make it three wins on the bounce at Anfield against Fulham. The captain is not interested in noise or sentiment. He is focused on standards.
In his programme notes, Van Dijk said: "After an important and, in my opinion, well-deserved win over Atletico Madrid, it is great to be back at Anfield again this afternoon as we return to Premier League action against Fulham.
"I thought the atmosphere on Wednesday night was exceptional, particularly in the second half as we chased the victory.
"I have said many times that we are at our best when everyone is pushing together, and I hope you can see how hard we are all working to give you a team to be proud of."
#premier #dijk #fulham


2 months ago
Arizona Cardinals tight end Trey McBride will play with a refined passion in 2026. With the 2025 season in his rearview mirror and the Los Angeles Chargers ahead, McBride is hoping that his passion and premier pass-catching can spark the beginning of a new chapter for the franchise.
The Chargers lost defensive coordinator Jesse Minter, who moved on to a head coaching position with the Baltimore Ravens. Still, Chargers safety Derwin James Jr. is on the roster and his skillset poses a significant opposition for McBride. Cardinals head coach Mike LaFleur still has plans on making McBride the focus of the team offense and it'll come down to pure will to determine whether or not McBride can muscle up.
The Cardinals seem to have a competent offensive personnel group at the skills positions but time will tell how their offensive line fares in 2026. Play-action and the quick passing game are both strategies where LaFleur and offensive coordinator Nathaniel Hackett are likely to call on McBride's jersey number. McBride is quick and physical, plus his route running makes him a mismatch for most opposing linebackers and safeties.
Ultimately, if the Cardinals are to stand a chance on Sunday, they will rely on their passing attack to propel the offense and that'll mean that McBride must be exceptionally magnificent. The Chargers allowed just 19.8 points per game in 2025, but without the mastermind of Minter, McBride might locate a few breaches that can be exploited.
Get more Cardinals and NFL coverage from Cards Wire's Jess Root and others by listening to the latest on the Rise Up, See Red podcast. Subscribe on Spotify, YouTube or Apple Podcasts.
#play #passion #coordinator
The Chargers lost defensive coordinator Jesse Minter, who moved on to a head coaching position with the Baltimore Ravens. Still, Chargers safety Derwin James Jr. is on the roster and his skillset poses a significant opposition for McBride. Cardinals head coach Mike LaFleur still has plans on making McBride the focus of the team offense and it'll come down to pure will to determine whether or not McBride can muscle up.
The Cardinals seem to have a competent offensive personnel group at the skills positions but time will tell how their offensive line fares in 2026. Play-action and the quick passing game are both strategies where LaFleur and offensive coordinator Nathaniel Hackett are likely to call on McBride's jersey number. McBride is quick and physical, plus his route running makes him a mismatch for most opposing linebackers and safeties.
Ultimately, if the Cardinals are to stand a chance on Sunday, they will rely on their passing attack to propel the offense and that'll mean that McBride must be exceptionally magnificent. The Chargers allowed just 19.8 points per game in 2025, but without the mastermind of Minter, McBride might locate a few breaches that can be exploited.
Get more Cardinals and NFL coverage from Cards Wire's Jess Root and others by listening to the latest on the Rise Up, See Red podcast. Subscribe on Spotify, YouTube or Apple Podcasts.
#play #passion #coordinator