
1 month ago
On September 16, Air Products (NYSE:APD) said it had signed a long-term deal to supply high-purity gases to a leading chipmaker, backed by roughly $250 million of its own money in Arizona. It is the company's second semiconductor supply win, and the two projects together carry more than $900 million of investment. That is a notable turn for a company that has been pulling back from big clean-energy projects.
The Arizona project plays to what Air Products already does. It will build, own, and operate the equipment, from hydrogen generation units and carbon dioxide purification to bulk supply for three gases: helium, hydrogen, and carbon dioxide. That means the customer's gas supply runs through equipment Air Products owns. Supply is targeted to start in phases, so the buildout can move alongside the customer's expansion plans. And this is familiar ground. Air Products has supplied electronics makers for more than 40 years, and its Chandler facility has served the Phoenix chip cluster since 1981, with a pipeline system carrying ultra-high purity nitrogen around the area.
The core business gives the deal a solid floor. In the fiscal third quarter, reported on July 30, adjusted earnings per share rose 12% to $3.47, and management lifted its full-year outlook to an adjusted $13.39 to $13.49 per share. Margins widened as well, so growth is showing up as profit. Chips appear elsewhere in the results too, since the company announced a deal to build four large air separation units to serve a chipmaker's growth in Taiwan.
The cost of the pivot is hard to ignore. On June 30, Air Products announced it would not go ahead with its Louisiana Clean Energy Complex and would discontinue a zero-carbon liquid hydrogen facility in Casa Grande, Arizona, plus other smaller clean energy distribution projects. The exits triggered roughly $2.9 billion in pre-tax charges, which is why the company posted a GAAP loss of $6.47 per share in the third quarter even as its underlying earnings grew. Adjusted results leave that hit out, but the GAAP numbers show what the retreat cost.
Owning the ****** ets also means funding them. Air Products expects about $3.5 billion of capital spending in fiscal 2026, and the Arizona plant alone is a commitment of approximately $250 million, with supply arriving in phases. The release also leaves gaps: it does not name the customer or say how long the contract runs, so the length of the revenue stream is unclear. Elsewhere, Europe's operating income rose only 2% as costs climbed, and management says it is still cautious about the economic backdrop.
#clean #adjusted


1 month ago
NuScale Power Corporation (SMR) stands out as America's leading developer of small modular reactors (SMRs), building light-water nuclear systems designed to deliver reliable, carbon-free baseload power. Its core product, the NuScale Power Module, targets a wide range of applications, from traditional electricity generation to industrial decarbonization, AI data center power supply, and hydrogen production. Notably, NuScale remains the only SMR developer to secure Standard Design Approval from the U.S. Nuclear Regulatory Commission, a regulatory milestone that continues to anchor its competitive positioning in the emerging advanced nuclear industry.
NuScale's stock has been anything but stable. Over the past 52 weeks, shares have traded across an enormous range, from a low of $7.21 to a high of $57.42, before settling closer to $10.81. That volatility stems from a mix of factors: heavy retail investor interest, elevated short interest fueling sharp swings in both directions, and macroeconomic shifts in interest rates that disproportionately affect capital-intensive, pre-revenue growth companies. Compared to the Russell 2000, a benchmark of diversified, largely profitable small-cap stocks, NuScale carries a significantly higher beta and downside risk, reflecting its speculative, early-stage commercialization profile.
Goldman Sachs Expects Fed Chair Kevin Warsh to Raise Rates This Week — But Not Because of Oil Prices.
Crude Prices Soar as Global Oil Supplies Continue to Tighten
Middle East Supply Constraints Lift Crude Oil Prices
#nuclear #crude



1 month ago
Choosing between a clean energy innovator and a traditional oil giant reflects a core tension in today's market. Investors must decide if Bloom Energy (NYSE:BE) or Diamondback Energy (NASDAQ:FANG) is the better buy.
Bloom Energy manufactures solid oxide fuel cells that provide reliable onsite power, targeting the surging demand from artificial intelligence infrastructure. Diamondback Energy focuses on extracting oil and gas from the Permian Basin, prioritizing operational efficiency and shareholder returns. While both operate in the energy **** e, their business models, risk profiles, and valuation metrics differ significantly for 2026 investors.
Bloom Energy serves as a prominent player among renewable energy stocks, focusing on solid oxide technology for onsite electricity and hydrogen production. The company targets large-load customers in the data center, semiconductor, and industrial sectors where power reliability is critical. Key partnerships include an agreement with American Electric Power (NASDAQ:AEP) to provide up to one gigawatt of fuel cells and a financing framework worth nearly $5.0 billion with Brookfield (NYSE:BN).
In FY 2025, Bloom Energy reported revenue of approximately $2.0 billion, which represents a growth rate of roughly 37.3% compared to the prior year. Despite this robust top-line performance, the company reported a net loss of nearly $88.4 million for the same period. This loss widened from a net loss of approximately $29.2 million in FY 2024, although the net margin of negative 4.4% in FY 2025 was a significant improvement over the negative 22.7% margin seen in FY 2023.
As of its December 2025 balance sheet, Bloom Energy holds a debt-to-equity ratio of 3.9x. This ratio measures total debt against shareholder equity, indicating the company relies moderately on borrowed funds to fuel its expansion. The current ratio, which measures a company's ability to cover short-term debts with its short-term **** ets, stands at a strong 6.0x. For FY 2025, free cash flow reached close to $57.2 million, which is the cash remaining after paying for operating costs and equipment investments.
#bloom #million

2 months ago
Bloom Energy (NYSE: BE), a developer of solid oxide fuel cells (SOFCs), has been one of the market's hottest growth stocks. Its shares surged more than 2,500% over the past two years, while its backlog swelled to $20 billion at the end of 2025. That's ten times the $2.0 billion in revenue it generated in 2025. ******* ysts expect its revenue to more than double to $4.1 billion this year, then grow 65% to $6.8 billion in 2027 and 46% to $9.9 billion in 2028.
That growth trajectory is impressive, but the recent introduction of its Power Connect system -- which could reduce its on-site installation time by more than 40% -- could help it exceed those bullish estimates. Let's see why this upgrade could matter more than the size of its backlog.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Bloom's SOFCs can convert natural gas, biogas, propane, and hydrogen into electricity without any combustion. Its systems can also be deployed on-site in less than three months and bypass traditional electrical grids, which can require years to set up new connections.
Those advantages make SOFC systems a popular choice for data centers seeking to quickly expand their cloud and AI infrastructure while maintaining a smaller carbon footprint. Oracle, CoreWeave, Nebius, Equinix, and other data center giants already use its SOFC systems. Brookfield ******* et Management (NYSE: BAM), one of the world's largest ******* et managers, funds Bloom's development and deployment of those SOFC systems via a $25 billion partnership.
#systems #signal #years #sofcs
0.00$ raised of 0.00$ goal
0 donations
0.00$
to go

2 months ago
Bloom Energy (BE) jumped 8% on momentum with no new catalyst, while FuelCell (FCEL) and Plug Power barely moved in the same risk-on session.
HYDR's 3% gain versus SPY's 1% rise largely reflects Bloom Energy's 15.5% fund weighting, masking weak breadth across hydrogen names.
KR Sridhar declared Bloom "the standard for AI onsite power" after Q2 revenue of $1.07 billion beat estimates and full-year guidance hit $4.2 billion.
Just released. Our ****** ysts combed the entire stock market and named the ten best stocks to buy right now. The report is free. Enter your email and see if any of your stocks made the cut.
A risk-on tape is lifting high-beta fuel cell names on Thursday, but the group is splitting sharply on the way up. Bloom Energy (NYSE:BE) stock is up 8% to $233.69 in midday trading. That's a large single-session move against much more muted action from its two closest hydrogen and fuel cell peers.
#risk


2 months ago
Our ****** ysts just identified a stock with the potential to be the next Nvidia. Tell us how you invest and we'll show you why it's our #1 pick. Tap here.
French gases group Air Liquide is getting the activist-investor treatment.
Elliott reportedly built a stake and wants the firm to sharpen margins. Investors liked the idea, sending the shares higher as the market started pricing in a little less patience and a little more pressure.
Elliott's been engaging with the company for months, though the the size of the stake is not known. The message, however, is clear: improve margins and compete harder with the sector's best operators.
Air Liquide is not exactly a wounded minnow. The Paris-based group is worth about €108 billion (about $125 billion) and supplies gases including oxygen, nitrogen and hydrogen to factories, hospitals, semiconductor plants and energy customers. It is one of Europe's major industrial champions. But activists don't usually arrive because everything looks perfect.
#liquide #gases #stake


2 months ago
Nancy Pelosi's household disclosed a Bloom Energy stake valued between $4.25M and $14.5M from late July, pushing BE up 5% and FCEL 4% on sympathy.
The Pelosi filing also included Intel, an established Bloom Energy data center customer, while Plug Power's exclusion from the catalyst keeps HYDR flat.
Bloom Energy's Q2 revenue hit a record $1.07 billion, up 166% year over year, and the company raised its full-year 2026 guidance to a range of $3.9 billion to $4.2 billion.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and Plug Power didn't make the cut. Grab the names FREE today.
Shares of Bloom Energy (NYSE:BE) are up 5% to $214.98 in early Tuesday trading, and FuelCell Energy (NASDAQ:FCEL) stock is up 4% to $19.45. The Global X Hydrogen ETF (NASDAQ:HYDR) sits unchanged at $42.34 while two of its largest U.S. components rally.
#bloom #year #fcel #plug


2 months ago
Sustainable Growth Advisers (SGA), an investment management company, released its second-quarter 2026 investor letter for its "Global Growth Strategy." The letter can be downloaded here. The SGA Global Growth Portfolio returned 7.4% gross and 7.2% net, compared with 14.9% for the MSCI ACWI and 19.8% for the MSCI ACWI Growth Index. Momentum leadership and enthusiasm around AI infrastructure drove markets, with semiconductor, memory, and hardware stocks accounting for much of the gain. Although the portfolio owned AI beneficiaries, broader holdings lagged despite fundamentals, as median revenue and EPS growth reached 12% and 14% and more than 60% of the holdings beat expectations. SGA believes valuation compression reflects sentiment rather than weaker business quality, leaving the portfolio near its widest discount to the market since inception. The firm continues to favor durable compounders and expects 16% revenue growth and 20% earnings growth over three years. Also, please check the Fund's top five holdings to see its best picks for 2026.
In its second-quarter 2026 investor letter, SGA Global Growth Strategy highlighted Canadian Pacific Kansas City Limited (NYSE:CP). Canadian Pacific Kansas City Limited (NYSE:CP) owns and operates a transcontinental freight railway in Canada and internationally. On August 24, 2026, Canadian Pacific Kansas City Limited (NYSE:CP) closed at $94.68 per share. The one-month return of Canadian Pacific Kansas City Limited (NYSE:CP) was 3.25%, and its shares gained 24.17% over the past 52 weeks. Canadian Pacific Kansas City Limited (NYSE:CP) has a market capitalization of $83.25 billion.
SGA Global Growth Strategy stated the following regarding Canadian Pacific Kansas City Limited (NYSE:CP) in its Q2 2026 investor letter:
"We engaged with management of Canadian Pacific Kansas City Limited (NYSE:CP) in advance of the company's annual meeting to discuss its climate strategy and a proposal on climate-related disclosures. A key topic of discussion was the company's decision to defer establishing a Science Based Targets initiative (SBTi)-validated 1.5°C-aligned emissions reduction target. While the ISS Sustainability policy recommended voting against the climate proposal due to the absence of intermediate and long-term emissions targets, management explained that the delay stemmed from the lack of a finalized intensity-based methodology from SBTi appropriate for the freight rail industry, emphasizing that CPKC remains committed to its existing goal of reducing locomotive well-to-wheel emissions intensity by 36.9% by 2030 and continues to work with SBTi as industryspecific frameworks evolve. Management highlighted continued spending on locomotive fleet modernization, including investment in new Tier 4 locomotives, expansion of its hydrogen locomotive program, and trials of renewable fuels. After reviewing the company's disclosures, proxy materials, and feedback from management, we concluded that the company is making goo


2 months ago
Benzinga and Yahoo Finance LLC may earn commission or revenue on some items through the links below.
Owning a rental property is supposed to bring in money. For Oz and his wife, their Tampa, Florida, townhome is doing the opposite. After all the expenses are counted, Oz says they're losing exactly $730 every month.
Oz called "The Ramsey Show" and shared that the couple never actually planned to become landlords. They bought the newly constructed townhome about three years ago, lived there for roughly 10 months and then moved back to Miami when Oz's job called him into the office.
Don't Miss:
This Energy Company Says It Can Turn Coal Into Hydrogen, Diesel And Other Products—Without Burning It.
#finance


2 months ago
Hydrogen stocks have spent years testing investors' patience. Still, August 2026 offers two very different reasons for optimism: one company inching toward profitability after a brutal reset and another already cashing in on the artificial intelligence (AI) power boom. If you believe the sector's turnaround is real, Plug Power (NASDAQ: PLUG) and Bloom Energy (NYSE: BE) are worth a close look.
No stock better represents the boom-and-bust cycle of the hydrogen industry than Plug Power. Finally, though, Plug could be moving in a positive direction for good. In Plug's second quarter, the adjusted loss per share was just $0.07, beating expectations by a penny. Plug also hit $178.3 million in revenue, and gross margins approached breakeven.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Management has been cutting costs while simultaneously pushing growth. Operating expenses fell 50% year over year, while deployed units more than doubled to 1,666, and service revenue exploded 82% in the same time frame.
Plug maintains more than $160 million in cash and equivalents, and that number, combined with growth and lower costs, should give Plug plenty of runway to hit its targets. The turnaround story still has a long way to go, but it looks like the hydrogen fuel cell manufacturer is well on its way.
#power #still #years

2 months ago
On August 10, Plug Power (NASDAQ:PLUG) held its second-quarter earnings call, and the numbers pointed toward a company closing the gap between its long-promised turnaround and reality. Revenue climbed to $178 million, gross margin crept to nearly break-even, and management raised its full-year growth guidance for the second time this year. CEO Jose Luis Crespo framed the quarter as proof the business is executing, and the underlying figures back that up.
Revenue rose about 9% sequentially to $178 million, pushing first-half sales to $342 million, up 11% year-over-year. Management raised full-year revenue growth guidance to 15% to 16%, up from the 13% to 15% range given last quarter, citing visibility into a historically second-half-weighted business. Material handling was the standout. Plug deployed 1,670 GenDrive units in the quarter, more than doubling the 39 units deployed in the second quarter of last year. Service revenue grew 82% year-over-year to $29.8 million with a 27% margin, and two of the company's largest material handling customers are planning to refresh more than 20,000 GenDrive units over the next three years, a multi-year revenue base already locked in.
The electrolyzer segment added fresh wins too, including a 50 MW order tied to a final investment decision at the Hunter Valley Hydrogen Hub in Australia, a 30 MW UK project reaching FID, and selection for a 275 MW feed study in Quebec. Management also pointed to European regulation, including Spain's draft renewable fuels framework, as a potential driver of roughly 10 GW of electrolyzer demand by 2030.
Despite the progress, the business remains unprofitable across every segment. Gross margin was still negative at roughly -0.9%, and the fuel segment, while improved to -48.8% from -91% a year ago, remains deeply unprofitable. GAAP EPS was a loss of $0.14, weighed down by about $104 million in non-cash mark-to-market charges tied to convertible debt and warrants. The reported 50% year-over-year drop in operating expenses to $62 million leaned heavily on a $39.7 million recovery of previously impaired ****** ets, including a $37 million gain from a customer contract dispute settled in June, meaning the underlying cost base improved less than the headline number implies. Cash usage of $61 million for the quarter, while down 58% sequentially, still represents ongoing burn.
The company's liquidity plan depends in part on non-dilutive financing, including a July transaction expected to generate about $80 million from ****** et sales, of which only $47 million had been received as of the call. Positive EBITDA in the fourth quarter remains a target management reiterated rather than a result already delivered.
#year #revenue

3 months ago
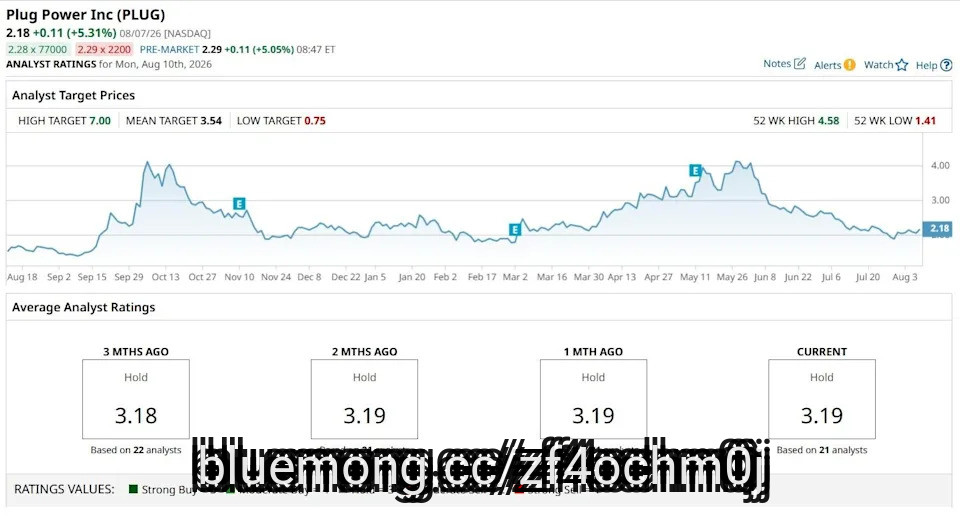
Plug Power (PLUG) shares have inched higher ahead of the company's second-quarter results scheduled for release today, Aug. 10, after market close.
Consensus is for the hydrogen fuel cell specialist to record a loss of $0.08 per share, which would represent about a 50% improvement versus the same quarter last year.
Don't ****** ume Micron Will Share SanDisk's Fate. Here's Why.
The Nvidia-SpaceX Deal Is Sending a Clear Signal on AI Dominance
Rocket Lab Investors Have Plenty to Cheer Ahead of Q2 Earnings Today
#Share


3 months ago
Antipodes Partners published its "Antipodes Global Strategy" second-quarter 2026 investor letter, highlighting the key performance stocks, portfolio changes, and the market outlook. A copy of the letter can be downloaded here. The second quarter of 2026 delivered one of the strongest equity market recoveries in recent history, as global equities gained 14.9% in US dollar terms. Renewed enthusiasm for artificial intelligence, strong corporate earnings, and easing tensions with Iran supported the rebound, while growth stocks outperformed value and emerging markets led gains, particularly Korea and Taiwan. The Antipodes Global Value Strategy underperformed its benchmark during the quarter and over the 12 months to June 30, 2026, as returns became concentrated in a narrow group of semiconductor and hardware stocks. Consumer staples and consumer discretionary holdings supported performance, while information technology, software, and internet exposure detracted. The firm remains cautious on expensive memory companies because pricing and supply remain cyclical despite AI demand. The Strategy continues to favor valued infrastructure, specialty semiconductors, resilient software, and quality businesses. For insights into its key selections for 2026, please review the Strategy's top five holdings.
In its Q2 2026 investor letter, Antipodes Global Strategy highlighted TotalEnergies SE (NYSE:TTE). TotalEnergies SE (NYSE:TTE) is a leading energy company that produces and markets oil and biofuels, natural gas, biogas, and low-carbon hydrogen, renewables, and electricity. On August 7, 2026, TotalEnergies SE (NYSE:TTE) closed at $85.83 per share. The one-month return of TotalEnergies SE (NYSE:TTE) was 7.49%, and its shares gained 43.01% over the past 52 weeks. TotalEnergies SE (NYSE:TTE) has a market capitalization of $190.44 billion.
Antipodes Global Strategy stated the following regarding TotalEnergies SE (NYSE:TTE) in its Q2 2026 investor letter:
"TotalEnergies SE (NYSE:TTE) underperformed as weaker crude oil and natural gas prices reduced earnings expectations and cash-flow forecasts across the integrated energy sector in line with geopolitical tensions easing over the Quarter. Concerns over slowing global economic growth and softer fuel demand also weighed on commodity markets, while increased OPEC+ supply expectations added further pressure to oil prices. Although TotalEnergies continued to benefit from its diversified LNG, power and renewable energy portfolio, these positives were outweighed by declining upstream earnings expectations. A broader rotation away from defensive energy stocks toward higher-growth sectors and profit taking after a stronger period also contributed to weakness."
#strategy #letter #stocks

3 months ago
Plug Power (NASDAQ:PLUG) — a popular hydrogen fuel stock — popped after announcing second-quarter earnings on Aug. 10. Investors and ****** ysts alike were impressed by the company's progress towards profitability. Revenue gains and cost efficiencies helped the company beat estimates for both sales and profits.
Plug Power posted an adjusted second-quarter loss of $0.07 per share. That beat Wall Street's prediction of an $0.08 per share loss, while also handily outpacing last year's result of an $0.18 per share loss.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Narrowed losses were helped by a 15% spike in hydrogen fuel sales, which, in turn, was driven by rising demand among the company's growing installed customer base. Sales overall ticked higher by 2.5% year-over-year to $178.3 million, beating consensus estimates by nearly $10 million.
Analysts were particularly excited by the company's progress towards profitability, as well as boosted sales growth guidance.
#plug #signal #analysts #flashing
3 months ago
WENDOVER, Utah (AP) — The first — and only — person to break the sound barrier in a car hits the track in Utah this week with new wheels and his eye on another record.
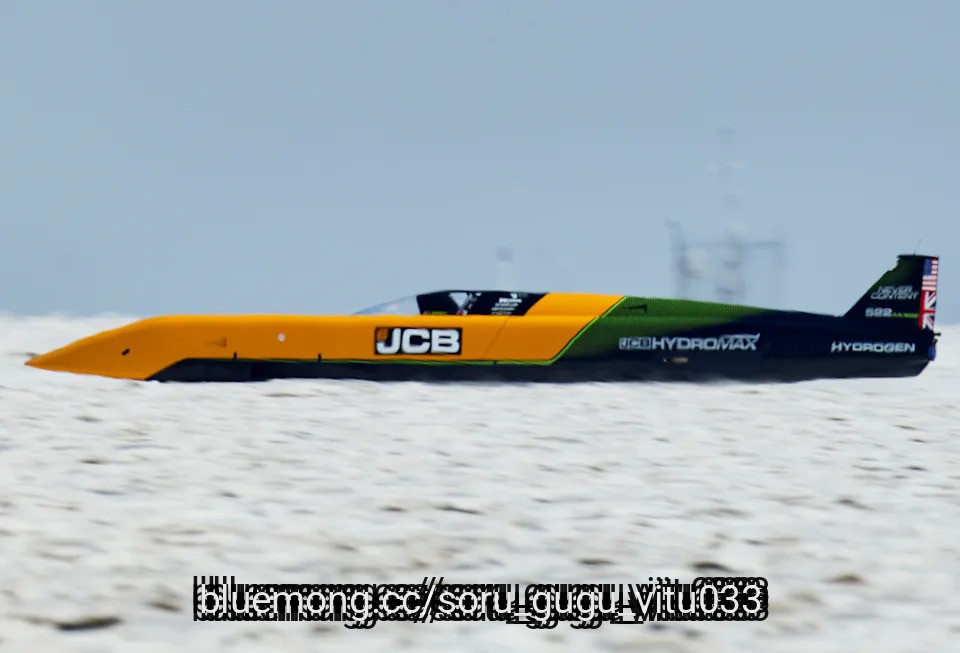
Twenty years ago, British driver Andy Green set the land speed record for a diesel-powered car, reaching 350.092 mph (563.4 kph) at Utah's famous Bonneville Salt Flats. Green will return to the lunarlike landscape Tuesday and try to beat that mark, this time with a hydrogen-powered car.
The retired Royal Air Force fighter pilot aims not only to win another accolade but to showcase the power of hydrogen as a clean-energy alternative. It's the "fuel of the future," Green told The ******* ociated Press in a July interview.
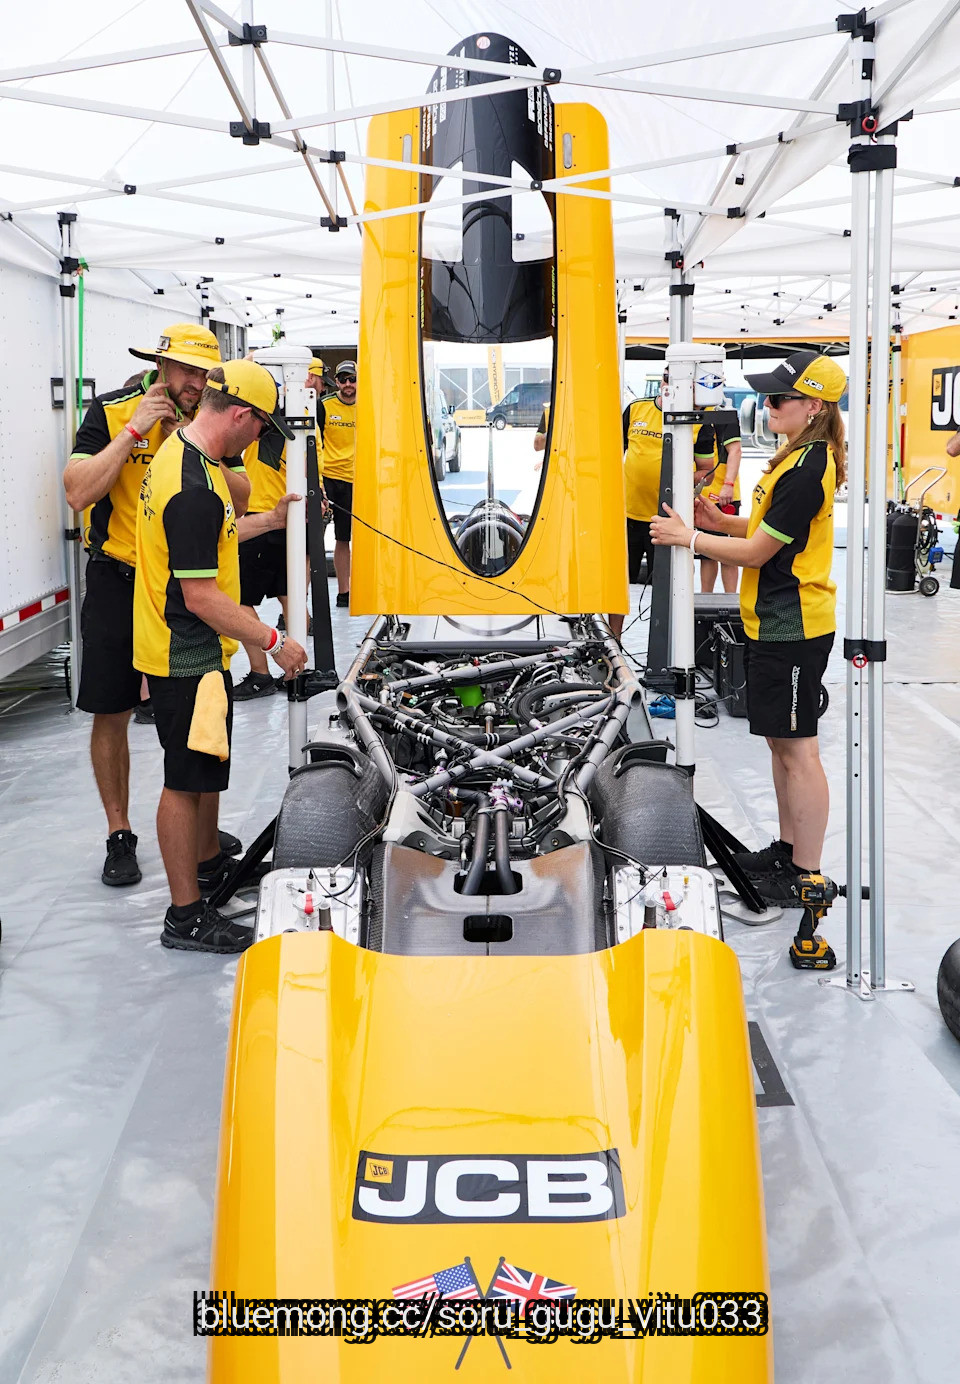
Green will be driving the 32-foot (9.75-meter) JCB Hydromax, the brainchild of British construction equipment manufacturer JCB. The car is bright yellow, long and slim, resembling a pencil. It's powered by two hydrogen internal combustion engines with a combined 1,600 horsepower, which were adapted from engines used in the company's construction machinery. They mix pressurized hydrogen gas with air and ignite it to create bursts of power.
In targeting the diesel-powered record, Green also hopes to easily clear the world land speed records for hydrogen internal combustion engines (185.5 mph/298.5 kph) and electric vehicles (341.3 mph/549.2 kph).
#hydrogen



3 months ago
The massive investment in building AI data centers is one of the biggest storylines this year. It coincides with a similar headline. Power is the biggest bottleneck in developing this crucial AI infrastructure. That's driving robust demand for all forms of power, including gas, nuclear, and battery storage.
However, data centers aren't the only AI infrastructure that requires power. The companies manufacturing the chips, servers, and other equipment vital to these facilities also need energy. That's providing an additional opportunity for Bloom Energy (NYSE: BE) to cash in on the AI power story. The hydrogen fuel cell company recently expanded its partnership with MiTAC Computing Technology, a leader in high-performance, energy-efficient server solutions for AI data centers.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Bloom Energy will deploy fuel cell systems for an islanded microgrid at MiTEC's AI server manufacturing campus in Fremont, California. It's an expansion of its existing partnership with MiTEC. Bloom has also installed a fuel cell microgrid at the company's San Jose manufacturing facility.
Companies like MiTEC are facing the same power constraints as AI data center developers. They need more power quickly, which is an issue given the time required for permitting and grid interconnection. They can't wait for the grid to supply their needs, which is why they're turning to Bloom Energy's rapidly deployable onsite power solutions.
#NVIDIA

3 months ago
Bloom Energy (NYSE: BE) has lost about 37% of its value since hitting an all-time high just a few weeks ago. It was trading at around $345 a share then -- and it's at about $218 now.
Normally, a steep decline of that caliber would tell you something went wrong with Bloom's business. In the case of the hydrogen stock, however, the opposite is the case.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Indeed, the company's most recent earnings report was arguably its strongest yet. Bloom raked in over $1 billion in revenue, marking its first billion-dollar quarter in company history, and both margins and profitability improved significantly. To top it off, management raised 2026 revenue guidance (again) into the range of $3.9 billion to $4.2 billion.
What's more, Wall Street expects Bloom's revenue to more than triple over the next two years, as the artificial intelligence (AI) boom will likely fuel stronger demand for its solid oxide fuel cell systems.
#bloom



3 months ago
The Fastest Man on Earth is slowing down in order to rush us into an enhanced future.
It's all relative, they say, and in this case, you must come to grips with 351 miles per hour registering as "slowing down."
"It's been an interesting journey and I'm hugely enjoying it," Andy Green said by phone midweek from Northwest Utah, where the annual Speed Week is under way at the famed Bonneville Salt Flats.
It was 29 years ago when Green, the former fighter-jet pilot in the UK's Royal Air Force, became the first Earth-bound person to go supersonic, surpassing the speed of sound and reaching 763 mph. Next Wednesday, Aug. 12, the goal is 351 mph, which by comparison sounds like a milk-and-bread run, but it will also be a record because at Bonneville's annual carnival of speed, again, it's all relative.
In this case, it'd be a record for hydrogen-powered machinery.
#down #case #fastest

3 months ago
As energy demand from artificial intelligence surges, investors are weighing the merits of fuel cells versus next-generation nuclear. Choosing between Bloom Energy (NYSE:BE) and Oklo (NYSE:OKLO) requires balancing established revenue against futuristic potential.
Bloom Energy provides solid-oxide fuel cell technology for reliable on-site power, catering to data centers and industrial clients. Oklo is a pre-revenue developer of small modular reactors aiming to revolutionize carbon-free energy. Both companies target the massive power needs of the modern economy, yet they sit at very different stages of commercial maturity.
Bloom Energy sells solid-oxide energy servers providing onsite electricity and hydrogen to customers like SK ecoplant and American Electric Power (NASDAQ:AEP). Customer concentration like this adds a layer of risk to the business since revenue depends heavily on major partnerships. Recently, the company secured a $1.7 billion project with Nebius (NASDAQ:NBIS) and a financing framework with Brookfield ***** et Management (NYSE:BAM).
In FY 2025, revenue reached nearly $2.0 billion, representing growth of approximately 37.3%. This expansion was driven by increasing demand for onsite generation in the electric utility stocks ***** e. Despite the top-line growth, the company reported a net loss of roughly $88.4 million, representing a net margin of negative 4.4%.
As of its December 2025 balance sheet, the debt-to-equity ratio was approximately 3.9x. This ratio measures total debt relative to shareholder equity, suggesting the company uses a significant amount of borrowed money. The current ratio is a healthy 6.0x, while free cash flow, or cash left after capital expenditures, reached roughly $57.2 million.
#energy #oklo


3 months ago
Investors in 2026 face a clear choice between a speculative hydrogen pioneer and a profitable oil giant. Plug Power (NASDAQ:PLUG) and Occidental Petroleum (NYSE:OXY) represent two very different paths in the evolving energy landscape.
Plug Power focuses on the future of green hydrogen and fuel-cell technology, while Occidental Petroleum produces traditional energy while investing in carbon capture. They are compared because they offer different ways to play the energy transition.
Plug Power builds green hydrogen and fuel-cell solutions for global industrial applications. The company focuses on large-scale logistics, providing fuel to the material handling and e-mobility sectors. Walmart is a major customer, representing roughly 24.2% of consolidated revenues as of late 2025, adding a layer of risk to the business.
In FY 2025, revenue reached nearly $709.9 million, reflecting a growth rate of approximately 12.9% over the previous year. Despite this growth, the company reported a net loss of approximately $1.6 billion for the same period. This resulted in a net margin of -229.8%, highlighting the significant costs involved in scaling hydrogen production.
As of its December 2025 balance sheet, the debt-to-equity ratio was 1.0x. This metric, which measures a company's total debt against its shareholder equity, sits at 1.0x, while a current ratio of 2.3x indicates the company has enough short-term **** ets to cover immediate liabilities. However, free cash flow was negative $661.5 million in FY 2025, meaning cash outflows exceeded inflows from operations and capital investments.
#power #fuel


3 months ago
As energy demand from artificial intelligence surges, investors are weighing the merits of fuel cells versus next-generation nuclear. Choosing between Bloom Energy (NYSE:BE) and Oklo (NYSE:OKLO) requires balancing established revenue against futuristic potential.
Bloom Energy provides solid-oxide fuel cell technology for reliable on-site power, catering to data centers and industrial clients. Oklo is a pre-revenue developer of small modular reactors aiming to revolutionize carbon-free energy. Both companies target the massive power needs of the modern economy, yet they sit at very different stages of commercial maturity.
Bloom Energy sells solid-oxide energy servers providing onsite electricity and hydrogen to customers like SK ecoplant and American Electric Power (NASDAQ:AEP). Customer concentration like this adds a layer of risk to the business since revenue depends heavily on major partnerships. Recently, the company secured a $1.7 billion project with Nebius (NASDAQ:NBIS) and a financing framework with Brookfield ****** et Management (NYSE:BAM).
In FY 2025, revenue reached nearly $2.0 billion, representing growth of approximately 37.3%. This expansion was driven by increasing demand for onsite generation in the electric utility stocks ****** e. Despite the top-line growth, the company reported a net loss of roughly $88.4 million, representing a net margin of negative 4.4%.
As of its December 2025 balance sheet, the debt-to-equity ratio was approximately 3.9x. This ratio measures total debt relative to shareholder equity, suggesting the company uses a significant amount of borrowed money. The current ratio is a healthy 6.0x, while free cash flow, or cash left after capital expenditures, reached roughly $57.2 million.
#oklo


3 months ago
Northbrook, Illinois-based CF Industries Holdings, Inc. (CF) manufactures and sells hydrogen and nitrogen products for energy, fertilizer, emissions abatement, and other industrial activities. Valued at $18.7 billion by market cap, the company provides clean energy to feed and fuel the world sustainably. The leading global manufacturer of hydrogen and nitrogen products is expected to announce its fiscal second-quarter earnings for 2026 after the market closes on Wednesday, Aug. 5.
Ahead of the event, ***** ysts expect CF to report a profit of $5.71 per share on a diluted basis, up 140.9% from $2.37 per share in the year-ago quarter. The company has consistently surpassed the consensus estimates in each of the last four quarters.
Alibaba Stock Just Got Apple's Biggest AI Endorsement. This Could Be a Game Changer for BABA.
Elon Musk Says If ***** eX Accomplishes Its Goals, 'It Will Be Worth More Than The Rest of Earth' — Though He's Also Said 'Money Will Stop Being Relevant'
AI Bubble Fears, Earnings and Other Can't Miss Items this Week
#products


3 months ago
Earlier this month, Plug Power (NASDAQ: PLUG) investors received some great news: The company's 50-megawatt (MW) hydrogen electrolyzer project in Australia is expected to move into the execution phase. This essentially clears the way for Plug Power to deliver on its end of the bargain and book the related revenue.
While Plug Power has completed other projects elsewhere in Australia, this electrolyzer project is now that country's largest renewable hydrogen project to reach this level of development. Orica, the customer -- a large mining conglomerate that bills itself as the "world's largest mining-dedicated producer of sodium cyanide, supporting gold processing, silver recovery and other mineral extraction operations" -- operates an existing ammonia production facility on Kooragang Island.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Currently, that facility produces most of its electricity from natural gas. Plug Power's proton exchange membrane (PEM) electrolyzer will use renewable energy sources to produce hydrogen fuel, offsetting around 7.5% of the facility's natural gas usage.
To put this project into perspective, Plug Power has now deployed around 320 MW of its GenEco electrolyzer systems across six continents. For comparison, one of Plug Power's biggest installed systems is a 100-MW Galp project in Portugal. That system is now one of Europe's largest electrolyzer installations. It is expected to be fully online by the end of this year. So while this 50-MW system in Australia is meaningful, it is not a game changer in any large sense.

3 months ago
Earlier this month, Plug Power (NASDAQ: PLUG) investors received some great news: The company's 50-megawatt (MW) hydrogen electrolyzer project in Australia is expected to move into the execution phase. This essentially clears the way for Plug Power to deliver on its end of the bargain and book the related revenue.
While Plug Power has completed other projects elsewhere in Australia, this electrolyzer project is now that country's largest renewable hydrogen project to reach this level of development. Orica, the customer -- a large mining conglomerate that bills itself as the "world's largest mining-dedicated producer of sodium cyanide, supporting gold processing, silver recovery and other mineral extraction operations" -- operates an existing ammonia production facility on Kooragang Island.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Currently, that facility produces most of its electricity from natural gas. Plug Power's proton exchange membrane (PEM) electrolyzer will use renewable energy sources to produce hydrogen fuel, offsetting around 7.5% of the facility's natural gas usage.
To put this project into perspective, Plug Power has now deployed around 320 MW of its GenEco electrolyzer systems across six continents. For comparison, one of Plug Power's biggest installed systems is a 100-MW Galp project in Portugal. That system is now one of Europe's largest electrolyzer installations. It is expected to be fully online by the end of this year. So while this 50-MW system in Australia is meaningful, it is not a game changer in any large sense.
While Plug Power has completed other projects elsewhere in Australia, this electrolyzer project is now that country's largest renewable hydrogen project to reach this level of development. Orica, the customer -- a large mining conglomerate that bills itself as the "world's largest mining-dedicated producer of sodium cyanide, supporting gold processing, silver recovery and other mineral extraction operations" -- operates an existing ammonia production facility on Kooragang Island.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Currently, that facility produces most of its electricity from natural gas. Plug Power's proton exchange membrane (PEM) electrolyzer will use renewable energy sources to produce hydrogen fuel, offsetting around 7.5% of the facility's natural gas usage.
To put this project into perspective, Plug Power has now deployed around 320 MW of its GenEco electrolyzer systems across six continents. For comparison, one of Plug Power's biggest installed systems is a 100-MW Galp project in Portugal. That system is now one of Europe's largest electrolyzer installations. It is expected to be fully online by the end of this year. So while this 50-MW system in Australia is meaningful, it is not a game changer in any large sense.


4 months ago
Baker Hughes Company (NASDAQ:BKR) is one of the best stocks to invest in under $100. On June 23, Baker Hughes announced a significant long-term service agreement with ANOH Gas Processing Company/AGPC for the ANOH Gas Processing Plant in Nigeria. The contract covers lifecycle support, including parts, repair services, and engineering advisory for the facility's critical turbomachinery, specifically its two NovaLT16 gas turbines.
In addition to traditional maintenance, the agreement incorporates iCenter digital services powered by Cordant for remote monitoring and diagnostics. These tools are designed to optimize equipment reliability and operational availability, supporting the plant's role as a vital contributor to Nigeria's domestic gas supply and power generation goals.
This partnership expands on a 2019 collaboration where Baker Hughes originally supplied the plant's power island solution. Work will be managed through the company's service center in Port Harcourt, leveraging local talent to **** ist Nigeria's transition toward lower-carbon fuel sources.
Baker Hughes Company (NASDAQ:BKR) is an energy technology company that develops and delivers technologies for the entire hydrogen value chain. Its main products are hydrogen-enabled turbines, compressors, valves, centrifugal pumps, non-metallic pipes, sensors, and monitoring systems.
While we acknowledge the risk and potential of BKR as an investment, our conviction lies in the belief that some AI stocks hold greater promise for delivering higher returns and doing so within a shorter time frame. If you are looking for an AI stock that is more promising than BKR and that has 10,000% upside potential, check out our report about the cheapest AI stock.


4 months ago
August WTI crude oil (CLQ26) on Thursday closed down -1.44 (-1.96%), and August RBOB gasoline (RBQ26) closed down -0.0647 (-2.00%).
Crude oil and gasoline prices gave up an early advance on Thursday and fell sharply on speculation the escalation of hostilities between the US and Iran will be limited. Crude prices initially moved higher on Thursday after the US attacked Iranian targets for a second day in response to Iranian attacks on shipping in the Strait of Hormuz.
PLUG Stock Alert: Plug Power Just Scored a Major Green Hydrogen Win in Australia
Nat-Gas Erases Early Gains on the Outlook for Larger US Inventories
Beyond the War Premium: How Strategic Reserves Create a New Floor for Oil Prices

4 months ago
August Nymex natural gas (NGQ26) on Thursday closed down -0.200 (-6.23%).
Nat-gas prices tumbled to a 1.5-month low on Thursday and settled sharply lower. Above-average weekly US nat-gas storage levels undercut prices. The EIA reported on Thursday that weekly EIA nat-gas inventories rose by +61 bcf for the week ended July 3, above the five-year average for the week at +51 bcf.
PLUG Stock Alert: Plug Power Just Scored a Major Green Hydrogen Win in Australia
Nat-Gas Erases Early Gains on the Outlook for Larger US Inventories
Beyond the War Premium: How Strategic Reserves Create a New Floor for Oil Prices

4 months ago
Plug Power Inc. (NASDAQ:PLUG) is one of the Best Penny Stocks to Invest In According to Billionaires. Plug Power Inc. (NASDAQ:PLUG) has announced significant developments over the past months, which have resulted in the stock gaining around 10% over the past 6 months.
Firstly, the company posted results for its fiscal Q1 2026 quarter on May 11. During the quarter, the company reported 22% year-over-year revenue growth to $163.5 million. Although still negative, the gross margins improved sharply from -55% to -13%, driven by cost cuts, better service execution, and more efficient fuel sourcing.
More recently, on June 24, Plug Power announced completing a major milestone at the Måde Power-to-X facility in Esbjerg, Denmark, operated by European Energy. Management noted that the project involved installing, testing, and handing over a 5 MW GenEco PEM electrolyzer system.
The company's containerized system design simplified on-site work and sped up the path to production. With this project, Plug Power now has more than 70 GenEco electrolyzer systems running across six continents, giving it a growing base of operating experience to refine design and commissioning.
Plug Power Inc. (NASDAQ:PLUG) is an alternative energy technology firm. It designs, develops, commercializes, and manufactures hydrogen and fuel cell systems for the material handling and stationary power fields.

4 months ago
Palm Valley Capital Management, an investment management firm, has issued the second-quarter 2026 investor letter for the "Palm Valley Capital Fund." A copy of the letter can be downloaded here. In the second quarter, the fund's investor class gained 1.80%, while the S&P SmallCap 600 rose 19.7% and the Morningstar Small Cap Total Return Index returned 14.0%. The Strategy primarily focused on small-cap categories, allocating 75% to cash equivalents. This led to underperformance relative to benchmarks. The Fund is currently seeking more small-cap opportunities that meet its return criteria and will act swiftly if market conditions improve. The Index benefited from strong contributions from data center construction and biotech sectors, while the energy industry lagged. Additionally, reviewing the fund's top five holdings can reveal its best investments in 2026.
In its second-quarter 2026 investor letter, Palm Valley Capital Management highlighted Vontier Corporation (NYSE:VNT) as a newly added position. Vontier Corporation (NYSE:VNT) is a global industrial technology and mobility solutions company that operates through mobility technologies, repair solutions, and environmental and fueling solutions segments. On July 7, 2026, Vontier Corporation (NYSE:VNT) closed at $28.49 per share, reflecting a market capitalization of $4.01 billion. Vontier Corporation (NYSE:VNT) posted a one-month return of 0.60%, while its shares lost 25.56% over the past 52 weeks.
Palm Valley Capital Management stated the following regarding Vontier Corporation (NYSE:VNT) in its Q2 2026 investor letter:
"The Fund acquired three new positions during the second quarter: The Clorox Company (ticker: CLX), Molson Coors Beverage Company (ticker: TAP), and Vontier Corporation (NYSE:VNT). Vontier sells the equipment, software, and recurring services that help convenience stores pump gas and process payments, repair shops diagnose problems, and car washes operate efficiently. It was spun out of Fortive Corporation in 2020, which itself was formerly part of Danaher. Key operations include fueling equipment and payment systems through the brands Invenco and Gilbarco Veeder-Root, vehicle repair and diagnostics tools through Matco Tools, and car wash technology through DRB. The company touches a large portion of the world's fuel transactions, since its equipment is installed at hundreds of thousands of fuel sites globally. Vontier enjoyed a significant temporary tailwind, peaking in 2021, when U.S. gas stations were required to upgrade payment terminals at the pump to support EMV chip card transactions due to shifting fraud liability rules. Some investors have long-term concerns about the company's relevance as the transportation fleet moves away from internal combustion engines. Vontier has become more fuel agnostic in recent years, with its products serving vehicles powered by gasoline, electricity, and hydrogen. The firm owns a leading provider of electric vehicle (EV) charging softw


4 months ago
The market is not only technically overbought at this time, but arguably on shaky fundamental ground. High inflation is slowly chipping away at the economy, and the steep valuations of artificial intelligence (AI) stocks that performed so well when the AI revolution was still young are now being questioned.
Nevertheless, there are compelling growth stocks out there. You just might need to dig a little deeper than you normally would to find them. Here are three suggestions to get your search started.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
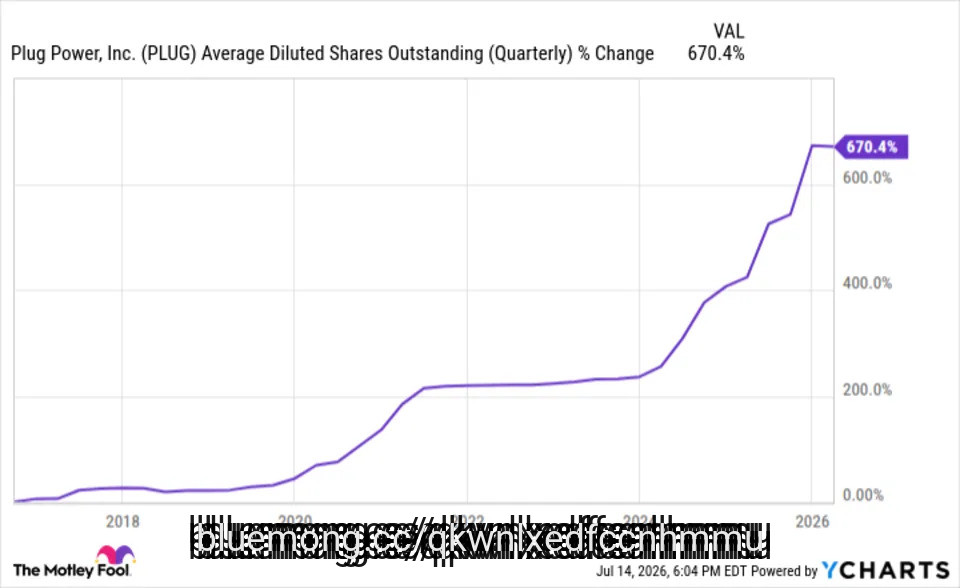
For the entirety of Plug Power's (NASDAQ: PLUG) 29-year existence, it's been unprofitable, and increasingly so. For most of this time, plenty of observers wondered why the hydrogen fuel cell company was so willing to stick with what seemingly looked like a lost cause.
Now we know. This technology is finally moving into the mainstream, offering the company a chance to reach enough scale that profitability is at least possible.





