

22 days ago
Rising interest rates have the US on a collision course with the need to finally deal with its bloated debt pile, Goldman Sachs warns.
"Persistently higher rates would boost interest expense as a share of GDP — a key gauge of the cash outflows needed to service the debt — and push the debt-to-GDP ratio up to 132% by 2035, 10 percentage points above our baseline, raising the odds that deficit reduction becomes necessary sooner to stabilize the debt," Goldman Sachs strategist Pierfrancesco Mei wrote in a new note on Tuesday.
US Treasury yields have climbed aggressively this year, effectively pushing up the country's debt servicing costs. The benchmark 10-year Treasury yield (^TNX) has surged more than 115 basis points, from around 4.10% late last year to a 24-year high of around 5.28% at present.
Read more: How soaring Treasury yields could hit your finances
This sustained sell-off across the bond market has been fueled by inflation brought on by the US war on Iran, which prompted the Federal Reserve to hike interest rates last month. The economy's resilience in the face of pricing pressures has also contributed to the sell-off.
#points #yields



22 days ago
Rising interest rates have the US on a collision course with finally having to deal with its bloated debt pile, warns Goldman Sachs.
"Persistently higher rates would boost interest expense as a share of GDP—a key gauge of the cash outflows needed to service the debt—and push the debt-to-GDP ratio up to 132% by 2035, 10 percentage points above our baseline, raising the odds that deficit reduction becomes necessary sooner to stabilize the debt," said Goldman Sachs strategist Pierfrancesco Mei in a new note on Tuesday.
US Treasury yields have climbed aggressively this year, effectively pushing up the country's debt servicing costs. The benchmark 10-year Treasury yield has surged more than 115 basis points, from around 4.10% late last year to a 24-year high of around 5.28% at present.
This sustained sell-off across the bond market has been fueled by inflation brought on by the US war on Iran, which prompted the Federal Reserve to hike interest rates last month. The economy's resilience in the face of pricing pressures has also contributed to the sell-off.
What's happening in the bond market couldn't come at a worse time for US debt watchers.
#interest



1 month ago
Pharming Group N.V. (NASDAQ:PHAR) announced on September 11 that the U.S. Food and Drug Administration approved Joenja for children aged 4–11 with activated PI3K delta syndrome, or APDS, who weigh at least 27 kilograms. APDS disrupts immune function.
The new 40 mg and 50 mg tablet strengths expand dosing options for Joenja, or leniolisib. The pediatric regimen also includes 70 mg twice daily for children weighing at least 45 kilograms. Pharming Group N.V. (NASDAQ:PHAR) expects the new strengths in October through its existing distribution and patient-support network.
The expansion arrives as the revenue mix shifts. Second-quarter Joenja revenue increased 40% year over year to $17.9 million, while RUCONEST revenue declined 10% to $72.3 million. Total revenue fell 3% to $90.2 million. Joenja's growth is substantial, but the larger franchise still determines much of the overall result.
Pharming Group N.V. (NASDAQ:PHAR) can bring the pediatric doses to market through an established commercial platform. Distribution relationships and patient support are already in place, which could allow additional sales without duplicating the infrastructure required for an entirely new product.
The opportunity is to spread those capabilities across more eligible patients while maintaining support for existing users. Incremental revenue could improve commercial efficiency, although pediatric servicing costs will still matter.
#revenue #NASDAQ #joenja #pediatric


1 month ago
This story was originally published on CRE Daily. Join 70,000+ commercial real estate professionals getting daily news, market insights, and industry ******* ysis delivered straight to their inbox with the free CRE Daily newsletter.
A $420 million CMBS loan backed by the 893,000-square-foot office tower at 51 West 52nd Street will exit special servicing after Harbor Group closed a negotiated extension.
Morningstar reported occupancy fell from 99% to 86% and cash flow dropped 37% below underwritten levels, though a source close to the deal says the building is now fully leased.
Harbor Group bought the Midtown tower from ViacomCBS for $760 million in 2021, the largest investment sale that year, and has since invested $150 million in upgrades.
A $420 million CMBS loan backed by 51 West 52nd Street, a 38-story, 893,000-square-foot Midtown office tower, will exit special servicing after sponsor Harbor Group International closed a negotiated loan extension, according to Commercial Observer. The loan, which backs the single-asset, single-borrower DBGS 2021-W52 deal, was transferred to special servicing ahead of its October 2026 maturity even though it still carried a 12-month extension option, per an alert from Morningstar Credit ******* ytics.
#group #extension

2 months ago
Northern Trust Corporation (NASDAQ:NTRS) announced on September 7 that Warwickshire Pension Fund had appointed it to provide global custody, valuation reporting, capital call execution and performance measurement. The UK public pension fund has approximately £3.6 billion, or $4.8 billion, in ****** ets.
The appointment strengthens the pension-servicing franchise of Northern Trust Corporation (NASDAQ:NTRS). Contract duration and fees were not disclosed in the announcement. The investment question is whether the relationship can generate meaningful recurring revenue and support further wins.
Scale sets the hurdle. Northern Trust Corporation (NASDAQ:NTRS) reported $20.0 trillion of ****** ets under custody or administration at June 30. Warwickshire's ****** ets equal approximately 0.024% of that base. The pension ****** ets represent a servicing opportunity, with revenue depending on the services provided and contractual pricing.
Northern Trust Corporation (NASDAQ:NTRS) won responsibility for several connected functions. Combining custody, valuation reporting, and performance measurement could make the relationship more embedded in the fund's operations. Capital call execution also provides a role in supporting private-market investments.
Warwickshire is one of 18 partner funds in Border to Coast Pensions Partnership. For Northern Trust Corporation (NASDAQ:NTRS), successful delivery could provide a reference for additional pension mandates. The opportunity lies in repeating the service model across clients and expanding relationships as operational needs evolve.
#pension #assets


2 months ago
You can find original article here WealthManagement. Subscribe to our free daily WealthManagement newsletters.
The competitive field to build out the tech infrastructure to ease the use of alternative investments in the wealth channel just got a little more crowded as New York-based fintech Aqua announced a $18.8 million Series A to back what it's calling a turnkey alternative investments platform.
The AI-native platform seeks to be a single solution that brings fund creation, operational workflows, investment lifecycle management, marketplace access, document intelligence and investor servicing into a single environment. In addition to managing off-the-shelf private market funds, advisors using Aqua can build special purpose vehicles, registered funds, fund of funds and feeder funds.
The $15 million Series A, led by Arthur Ventures with participation from Alumni Ventures, follows a 2021 $3.8 million seed round backed by Google's AI Fund, Y Combinator. It plans to use the funding to accelerate business and platform development, expand its engineering and partnership teams, and deepen integrations across custodians and fund sponsors. (The firm started as a team of six, but now has two dozen employees and it plans to continue to staff up as it onboards more advisors and fund managers.)
To be sure, Aqua is far from alone in attempting to streamline the alternative investments process. The **** e continues to be led by well-known players iCapital and CAIS, which service thousands of wealth firms through their marketplaces, and each has continued to add tech to support the lifecycle of alternative investments. Firms including SUBSCRIBE, Canoe, Gridline, Allocate, Alto, Arch, Opto, GLAS Funds, Altigo/SEI and Apex Alts also compete in the area, focusing on streamlining all aspects of the investment process. In addition, traditional TAMPs like InvestCloud, Envestnet, Orion, Addepar and Black Diamond have made enhancements to support private markets.
#Investments #subscribe #series

2 months ago
CNBC reported that The Goodyear Tire & Rubber Company (NASDAQ:GT) has extended the timeline for its "Goodyear Forward" turnaround plan after key financial targets went unmet.
CEO Mark Stewart told CNBC the company is trying to reach a 10% operating margin and generate meaningful cash flow, but debt remained above $7 billion at the end of the second quarter. Goodyear posted a $453 million net loss through the first half of the year against operating income of just $131 million, a 1.6% margin. The business has been hit by tariffs, elevated raw material costs, and expanding competition from cheaper Chinese tire imports. Capital expenditures, which ran roughly $2 billion combined in 2024 and 2025, are expected to fall to $725 million this year as the company prioritizes debt paydown and refinancing.
Copyright: baranq / 123RF Stock Photo
The core business is still generating a positive operating margin even amid a large net loss. Operating income of $131 million over six months shows The Goodyear Tire & Rubber Company (NASDAQ:GT)'s core tire operations are not losing money at the operating level, suggesting the much larger net loss stems mainly from the cost of servicing its debt rather than the core business itself failing.
Management is showing real capital discipline and not just promises since cutting planned capital expenditures to $725 million this year from roughly $1 billion annually in 2024 and 2025 combined is a measurable step toward freeing up cash for debt reduction. Moreover, tangible customer-facing investments, like the new retail concept store Stewart showcased in Detroit.
#goodyear #tire


2 months ago
The federal interest burden has reached a new height, exceeding even the 1991 record, but **** ysts warn the risks **** ociated with servicing the ever-growing national debt today are much higher than they were 35 years ago, **** ysts warn.
A recent **** ysis from investment management firm Doubleline noted that in 2025, the federal net interest payment on the U.S.'s now-$40 trillion national debt reached 18.5% of revenue, surpassing 1991's record 18.4%. That means the U.S. is collecting nearly 19% of all taxes and revenue just to pay off interest on its ballooning debt, equivalent to $1.25 trillion—more than the entire 2026 defense budget.
Growing interest payments create a cycle: the government must borrow more just to cover the interest, leaving it less flexible to spend on infrastructure, education, and other investments that drive growth.
The amount of money needed just to pay the interest on America's debt has swelled over the last decade as interest rates have grown, with interest expense as a percentage of revenue tripling since 2015, according to global market commentator the Kobeissi Letter, citing the Congressional Budget Office, which predicts interest expense levels to climb to 25% by 2036.
"The US debt crisis is in uncharted territory," the Kobeissi Letter wrote on a social media post. "These projections **** ume no major slowdown, recession, or significant rise in Treasury yields over this period."
#interest #kobeissi #letter #record

2 months ago
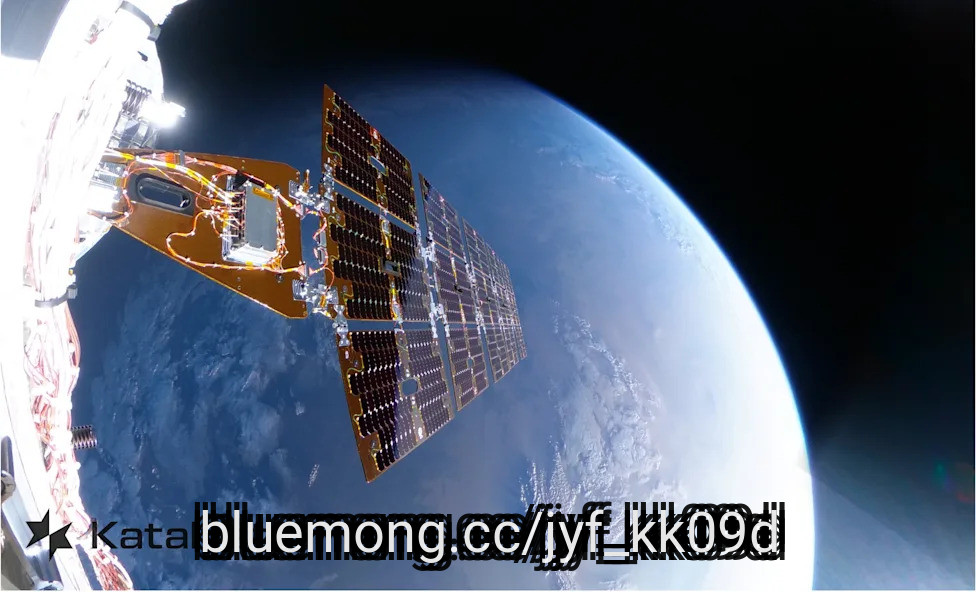
CAPE CANAVERAL, Fla. (AP) — A private **** ecraft that was supposed to provide a lifeline to NASA's Swift Observatory managed to get close to the sinking telescope and even snap photos two weeks after the rescue was abandoned.
But the three-armed robotic salvager had to turn away because it was low on fuel, according to Katalyst **** e Technologies, which attempted the daring operation.
"We got so close, but so far," Katalyst CEO Ghonhee Lee told The **** ociated Press this week.
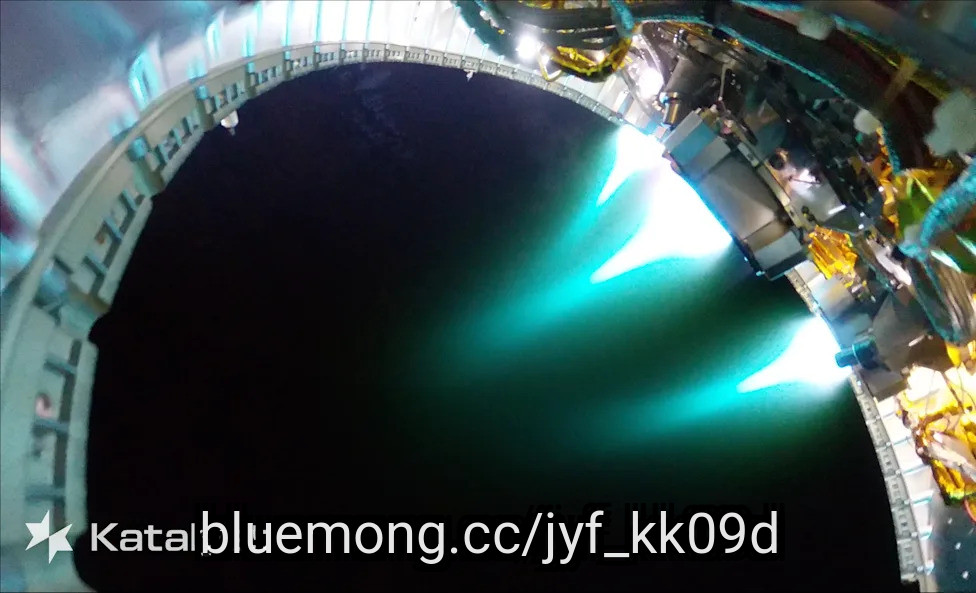
Katalyst's Link **** ecraft got within 15 kilometers (9 miles) of Swift on Tuesday, using its sensors to gather data on the doomed telescope for NASA. The rescue effort had already been called off in August because of Link's own troubles in orbit, but the company wanted the practice for future satellite-servicing missions.
Link went into an uncontrollable spin soon after rocketing to Swift's rescue in July. Flight controllers managed to slow the tumble and stabilize the **** ecraft, using up precious fuel. In the end, there was not enough fuel remaining to boost the aging Swift into a higher, longer-lasting orbit so it could continue observing the cosmos.
#rescue #link #close #telescope


2 months ago
Bernstein expects Bitcoin (COIN:BTCUSD) to reach $300,000 by the end of 2029, with ***** yst Gautam Chhugani identifying the cryptocurrency as a major potential beneficiary of what he describes as the debasement trade.
The forecast ***** umes Bitcoin continues to broadly follow its historical four-year market cycle, with Bernstein also expecting the cryptocurrency to recover to a new record high of $150,000 by the middle of 2027.
"Following our price-to-marginal cost framework, we would expect the next market peak to be $300K by CY2029E and the market recovering to new all-time high of $150,000 by mid-2027E," Chhugani wrote in a note to clients.
Bernstein's longer-term Bitcoin outlook is partly based on its view that the four-decade period of declining interest rates has come to an end.
Governments are consequently facing higher debt-servicing costs at a time when sovereign debt levels have reached unprecedented levels, creating additional pressure on public finances.
#debt #levels

2 months ago
The 10-year Treasury yield hit a 19-month high Monday morning in a challenge to Treasury Secretary Scott Bessent's effort to ****** ert control over long-term government bond yields. Higher long-term bond yields are generally a negative for stock prices and mortgage rates, and place upward pressure on the surging cost of servicing the federal debt.
Treasury announced on Aug. 19 that it would at least double the size of buybacks of government bonds with durations of 10 years up to 30 years. The announcement stirred a brief easing of yields, with the 10-year yield slipping to 5 basis point to 4.65%. But the 10-year yield touched 4.76% on Monday, the highest since January 2025.
The 30-year Treasury yield, at 5.27%, hasn't yet eclipsed the 5.29% level ahead of Bessent's buyback news. That was the highest 30-year yield level since 2007.
The upward pressure on the 10-year Treasury yield has a number of contributors. A big one seems to be a surge in corporate debt issuance by AI hyperscalers like Google, Amazon and Microsoft. Those technology ****** ans are offering higher rates than Treasury, directing some buying power away from government debt and forcing yields higher. Persistent inflation is another factor and the resumption in U.S.-Iran strikes over the weekend won't help.
Then there's the federal budget deficit, which will come in around 6% of GDP this year, extraordinarily high for a period of solid economic growth. The rising burden of interest costs and the expense of Social Security and Medicare for baby boomers suggests that big deficits may be here to stay.
#yield



2 months ago
Klarna Group plc (NYSE:KLAR) reported second-quarter net income of $9 million, reversing a $53 million loss a year earlier and remaining profitable after posting positive net income in the first quarter of 2026. Revenue increased 27% to $1.04 billion, while transaction margin dollars rose 42% to $446 million. Yet the shares closed 22.8% lower as investors focused on weaker expectations for the rest of the year.
Klarna Group plc (NYSE:KLAR) reduced its 2026 gross merchandise volume forecast to $149 billion to $151 billion from more than $155 billion and lowered its revenue outlook to $4.08 billion to $4.16 billion from more than $4.34 billion. Management cited weaker expectations for Germany, its largest market by volume. Currency movements accounted for approximately $600 million of the reduction in full-year GMV guidance.
The reported quarter showed continued growth and improved profitability, but the revised forecasts suggested that momentum in a core European market is slowing. For Klarna Group plc (NYSE:KLAR), the central question is whether better transaction economics can outweigh weaker growth expectations.
U.S. GMV increased 27%, outpacing companywide GMV growth of 18%, while credit loss provisions declined to 0.52% of GMV from 0.56%. Klarna Group plc (NYSE:KLAR) also increased transaction margin dollars to 42.8% of revenue, more than 4.5 percentage points higher than a year earlier.
Klarna Group plc (NYSE:KLAR) raised its full-year transaction-margin-dollar forecast to $1.62 billion to $1.65 billion and expects company-defined non-IFRS adjusted operating income of $280 million to $300 million. Transaction margin dollars, another company-defined non-IFRS measure, equal revenue less processing and servicing costs, credit loss provisions, and funding costs. The expansion indicates that higher volume is producing stronger economics after those direct costs.
#revenue


2 months ago
On August 11, Cardinal Health (NYSE:CAH) reported fourth-quarter fiscal 2026 results that on the surface look almost too good to be true. Non-GAAP diluted EPS jumped 40% year over year to $2.91, and full-year adjusted free cash flow hit $5 billion. But a large piece of that quarterly jump came from a one-time tariff refund, and the company's own guidance for the year ahead points to a much more normal pace of growth. That gap between the headline number and what's actually repeatable is where this story gets interesting.
Cardinal Health's fiscal 2026 was broad, not lucky. Operational growth was broad-based across segments, with fourth-quarter total revenue reaching $63.7 billion (up 6% year over year) driven by solid demand in Pharmaceutical and Specialty Solutions. Non-GAAP earnings per share have more than doubled since fiscal 2022, from $5.07 to $11.26, and adjusted free cash flow grew from $2.3 billion to $5 billion over that same four-year stretch, funding $7 billion returned to shareholders.
Pharmaceutical and Specialty Solutions did the heavy lifting again in the fourth quarter, with revenue up 6% to $58.8 billion and segment profit up 21% to $645 million on strength in both brand and Specialty. BioPharma Solutions landed two additional gene therapy 3PL commercialization agreements, with Cardinal Health now exclusively servicing nearly half the cell and gene therapy market and supporting approximately three-fourths of the total market overall. The smaller growth businesses continue to compound rapidly: Nuclear PET and Theranostics revenue grew 20% and 30% respectively in the fourth quarter, while at-Home Solutions posted a 99% total fill rate with its best quarter ever for on-time departures. The board also just authorized a $5 billion increase to the buyback program, pushing total authorization to $6.4 billion, and locked in a long-term Kroger contract extension along with a renewal of its largest medical products customer.
Look closer at that 40% EPS jump, though, and a chunk of it isn't repeatable. About $0.31 of the $2.91 in quarterly diluted earnings per share, roughly 15 percentage points of the 40% growth, came from a one-time $100 million net benefit tied to IEEPA tariff refunds landing in the Global Medical Products and Distribution segment. Strip that out and GMPD's fourth-quarter profit was just $50 million, and the company says it continues to incur ongoing costs from the tariffs that replaced IEEPA. Reported GMPD revenue actually fell 2% for the quarter.
#quarter #specialty


2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment ******* umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML) provides lithography solutions for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems. On August 18, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,802.98 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was 0.06% and its shares gained 140.56% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $682.12 billion.
Eagle Capital Management stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"Half of our capital here is invested in TSMC and ASML Holding N.V. (NASDAQ:ASML), two of the most dominant businesses in the semiconductor supply chain. The other half is invested across the three major hyperscalers. We ascribe a portion of the value of each of these three companies to their cloud business and the balance to the remainder of the company; i.e., 60% of the value of Amazon is from AWS and 40% is from retail.
TSMC and ASML are two of the best businesses in the semiconductor industry. ASML has a monopoly in extreme ultraviolet lithography ("EUV"), which is required for leading-edge semiconductor manufacturing. Both companies are well positioned over the next 5-10 years to participate in the sector's secular growth while maintaining their competitive positions. That said, they will face pressures when the next downturn comes.
#holding #capital #Growth


2 months ago
Eagle Capital Management, an investment management company, released its second quarter 2026 investor letter. A copy of the letter can be downloaded here. In the quarter, Eagle Capital Management discussed how enthusiasm around AI capital spending has driven strong S&P 500 earnings growth while also increasing risks from elevated valuations, concentrated demand, and aggressive investment **** umptions. Eagle remains a strong believer in AI but prefers constructing a portfolio that can perform across multiple outcomes rather than relying on one forecast. The firm believes current earnings can overstate underlying economics because semiconductor equipment is depreciated over several years, while free cash flow growth remains much weaker. It also expects competition and additional capacity across AI labs, hyperscalers, and semiconductors to eventually create winners and losers. These dynamics are encouraging Eagle to recycle capital toward attractive opportunities outside the most crowded AI trades while maintaining selective exposure to high quality beneficiaries. The portfolio trades at a 20% market discount with faster expected EPS growth. Please review the Strategy's top five holdings for key selections.
In its second-quarter 2026 investor letter, Eagle Capital Management highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML) provides lithography solutions for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems. On August 18, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,802.98 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was 0.06% and its shares gained 140.56% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $682.12 billion.
Eagle Capital Management stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"Half of our capital here is invested in TSMC and ASML Holding N.V. (NASDAQ:ASML), two of the most dominant businesses in the semiconductor supply chain. The other half is invested across the three major hyperscalers. We ascribe a portion of the value of each of these three companies to their cloud business and the balance to the remainder of the company; i.e., 60% of the value of Amazon is from AWS and 40% is from retail.
TSMC and ASML are two of the best businesses in the semiconductor industry. ASML has a monopoly in extreme ultraviolet lithography ("EUV"), which is required for leading-edge semiconductor manufacturing. Both companies are well positioned over the next 5-10 years to participate in the sector's secular growth while maintaining their competitive positions. That said, they will face pressures when the next downturn comes.
#asml #NASDAQ #management #letter

2 months ago
Aristotle Capital Boston, LLC, an investment advisor, released its "Small Cap Equity Fund" Q2 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned 13.69% in the second quarter of 2026, trailing the Russell 2000 Index's 21.49% gain as security selection in information technology and industrials weighed on performance despite positive allocation effects. Top contributors included MACOM Technology Solutions and Mercury Systems, which benefited from strong demand in semiconductor, aerospace, and defense markets, while Alamos Gold and Huron Consulting Group detracted due to operational challenges, weaker gold prices, and investor concerns surrounding artificial intelligence disruption. During the quarter, the fund initiated positions in IPG Photonics and UMB Financial, citing opportunities tied to advanced manufacturing, automation, reshoring trends, and diversified financial services, while exiting Americold Realty Trust, Byline Bancorp, and Verra Mobility. Looking ahead, management remains constructive on U.S. small-cap equities, noting that valuations remain attractive relative to large caps and that earnings growth is expected to accelerate into late 2026 and 2027. Factors such as increased merger and acquisition activity, improving domestic manufacturing due to reshoring and infrastructure investments, and a favorable regulatory environment are expected to support this **** et class in the long term. In addition, please check the Fund's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, Aristotle Small Cap Equity Fund highlighted stocks like UMB Financial Corporation (NYSE:UMBF). UMB Financial Corporation (NYSE:UMBF) operates a diversified banking business serving commercial, institutional, and personal customers across the United States. The one-month return of UMB Financial Corporation (NYSE:UMBF) was 5.14% while its shares traded between $103.38 and $153.32 over the last 52 weeks. On August 19, 2026, UMB Financial Corporation (NYSE:UMBF) stock closed at approximately $146.10 per share, with a market capitalization of about $11.11 billion.
Aristotle Small Cap Equity Fund stated the following regarding UMB Financial Corporation (NYSE:UMBF) in its Q2 2026 investor letter:
UMB Financial Corporation (NYSE:UMBF) is a regional bank with a diversified business model spanning commercial banking, institutional **** et servicing, private wealth management, healthcare payments, and specialty financial services. Unlike many regional banks, UMB generates a meaningful portion of its revenue from fee-based businesses, providing a more stable earnings profile and reducing reliance on net interest income. The company has consistently demonstrated disciplined underwriting, strong credit quality, and a conservative balance sheet, positioning it to perform across economic cycles. We believe UMB is well positioned to benefit from improving loan growth, expanding fee income, and continued

2 months ago
Citi is preparing to add Bitcoin custody alongside traditional ***** ets as the banking giant builds out its digital ***** et infrastructure.
Announced on Tuesday, the service will be part of Custody+, a suite of custody and settlement tools. The bank said clients will be able to access traditional securities and crypto custody through the same framework.
The announcement expands on plans Citi revealed in October to launch institutional Bitcoin custody in 2026.
"Custody+ is the product of a multi-year commitment to building infrastructure that matches the speed of our clients' strategies," Amit Agarwal, Head of Custody at Citi Investor Services, said in a statement. "We have designed each solution to help clients simplify their operating models amid increasing complexities in the operating environment."
Citi said more than 80% of its ***** et-servicing event volume is now processed in real time. Its Citi Token Services platform also allows clients to move tokenized deposits nearly instantly, 24 hours a day, across select markets.
#citi #operating

2 months ago
World Liberty Financial (CRYPTO: $WLFI) has moved closer to bringing its USD1 (CRYPTO: $USD1) stablecoin under a federally supervised banking structure after the Office of the Comptroller of the Currency conditionally approved a national trust bank charter for World Liberty Trust Company.
The approval would allow the Trump family-backed crypto company to issue USD1 directly and custody the U.S. dollar ****** ets backing the stablecoin. Those functions are currently handled through BitGo (NASDAQ: $BTGO).
Unlike a traditional commercial bank charter, the national trust structure generally does not permit deposit-taking or lending. It would instead give World Liberty a single federal framework for custody, ****** et servicing and settlement, areas the company has said are central to its plans for institutional clients such as exchanges and investment firms.
More From Cryptoprowl:
MEXC July TradFi Trading Shifts Toward AI Storage as SNDK Futures Volume Surges More Than 15x Times
#usd1

3 months ago
Strategy sold Bitcoin at roughly $64,000 per coin to fund preferred stock dividends, taking a 15% loss on its $75,000 average cost.
STRC preferred stock has rebounded 35% from its June low to $95, and Saylor wants it at $100 before buying Bitcoin again.
Saylor rebranded Strategy from a bitcoin treasury company to a Digital Credit Framework, shifting priority from accumulating Bitcoin to servicing debt obligations.
Act now: the ****** yst who called NVIDIA in 2010 just named his top 10 AI stocks — and MicroStrategy didn't make the cut. Grab the names FREE today.
Bitcoin treasury companies built their entire investment case on one promise: buy and hold, forever. Strategy (NASDAQ:MSTR) was the company that made that thesis famous -- and lately, the company that's been quietly breaking it.
#company


3 months ago
Emerald Wealth Partners, an independent ***** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML), a lithography solutions provider for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems, contributed 156 bps to the strategy's performance during the quarter. On August 4, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,711.89 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was -3.21% and its shares gained 147.76% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $648.21 billion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"ASML Holding N.V. (NASDAQ:ASML) rose 51.0%, adding 156 bps benefitting from the euphoria surrounding the semiconductor sector. Its monopoly in advanced lithography remains one of the most durable competitive positions we own. Each new generation of its machines allows chipmakers to pack more transistors into less silicon. This steady improvement in efficiency — better performance per watt, easier thermal management, a lower cost per unit of compute — is what underpins further advances in AI, and every other application where efficient chips matter."
#wealth


3 months ago
This story was originally published on Multifamily Dive. To receive daily news and insights, subscribe to our free daily Multifamily Dive newsletter.
The second half of July brought news that several apartment properties moved into special servicing, while others had their values reduced.
Once again, Texas was at the epicenter of these transfers, though one property in Brooklyn, New York, is also facing challenges, according to a flurry of Morningstar reports.
Two Keener Investments properties in League City, Texas — Harbor Walk and The Shore — were transferred to special servicing after the Houston-based owner stated that it "could no longer come out of pocket for debt service and escrow shortages," according to a July 31 Morningstar report.
The properties are still listed on Keener's website. It did not reply to a request for comment from Multifamily Dive.
#july #texas #servicing


3 months ago
Emerald Wealth Partners, an independent ****** et and wealth management firm based in Zurich, released its Q2 2026 investor letter for the "Focused Equity Strategy." A copy of the letter can be downloaded here. The Strategy reported a 0.8% gross return for the second quarter of 2026. Equity markets rallied after the first quarter's Iran shock faded and oil prices reversed their spike, but the advance remained narrow and concentrated in cyclical semiconductor and memory stocks benefiting from supply constraints. The letter warned that investors were treating peak-cycle earnings as durable, while FOMO, IPO demand, and a US cyclically adjusted P/E ratio near 40 pointed to late-cycle market behavior. Long-term fundamentals are currently undervalued by the market, leading to underperformance in the strategy, notably due to the portfolio's avoidance of low-quality momentum-driven semiconductor stocks, which boosted the benchmark this quarter. It remains focused on enterprise infrastructure, digital platforms, custom silicon, and networking businesses that hold customer relationships, workflow data, distribution, and efficiency advantages, which could allow them to monetize AI rather than be displaced by it. Please review the Strategy's top five holdings for its key selections.
In its second-quarter 2026 investor letter, Emerald Wealth Partners Focused Equity Strategy highlighted ASML Holding N.V. (NASDAQ:ASML). ASML Holding N.V. (NASDAQ:ASML), a lithography solutions provider for the development, production, marketing, sales, upgrading, and servicing of advanced semiconductor equipment systems, contributed 156 bps to the strategy's performance during the quarter. On August 4, 2026, ASML Holding N.V. (NASDAQ:ASML) closed at $1,711.89 per share. One-month return of ASML Holding N.V. (NASDAQ:ASML) was -3.21% and its shares gained 147.76% over the past 52 weeks. ASML Holding N.V. (NASDAQ:ASML) has a market capitalization of $648.21 billion.
Emerald Wealth Partners Focused Equity Strategy stated the following regarding ASML Holding N.V. (NASDAQ:ASML) in its Q2 2026 investor letter:
"ASML Holding N.V. (NASDAQ:ASML) rose 51.0%, adding 156 bps benefitting from the euphoria surrounding the semiconductor sector. Its monopoly in advanced lithography remains one of the most durable competitive positions we own. Each new generation of its machines allows chipmakers to pack more transistors into less silicon. This steady improvement in efficiency — better performance per watt, easier thermal management, a lower cost per unit of compute — is what underpins further advances in AI, and every other application where efficient chips matter."
#asml #Equity

3 months ago
Vertiv (NYSE:VRT) primarily generates revenue by designing, manufacturing, and servicing critical power and thermal management systems for data centers and communication networks.
It recently acquired ThermoKey and Strategic Thermal Labs to expand its liquid cooling capabilities, and it reported a 15% net income margin for the quarter ended June 30, 2026.
BWX Technologies (NYSE:BWXT) primarily generates revenue by producing precision naval and critical nuclear components for the United States government and commercial power sectors.
While securing contracts exceeding $1.4 billion from the United States Naval Nuclear Propulsion Program, it recorded an 11% net income margin for the quarter ended March 31, 2026.
Revenue gives investors insight into the total demand for a company's products and services before expenses are deducted. Tracking this figure helps investors understand the scale and top-line growth trajectory of a business.
#revenue #NYSE #naval #critical

3 months ago
Shares of ASML (NASDAQ: ASML) fell after technology publication The Information reported this week that an unnamed Chinese company backed by the Chinese government has begun manufacturing its own chip-making equipment. However, investors shouldn't be worried, as this is unlikely to hurt ASML's fortunes any time soon.
The machines reportedly being made in China are deep ultraviolet (DUV) lithography machines. This is an older technology used to manufacture older chips and the less critical components of advanced chips. DUV machines are also used to manufacture ordinary DRAM and flash memory. While ASML is a top supplier of DUV machines by a wide margin, it is not the only company that makes these machines. ***** anese companies Nikon and Canon also supply them.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
What separates ASML from the pack, though, is that it is the only company in the world with EUV (extreme ultraviolet lithography) technology, which is needed to make advanced logic chips and is also used to make high-bandwidth memory (HBM). These are extremely complex machines, and competitors outside China have largely given up trying to replicate the technology. These are also the machines that drive ASML's growth. EUV machines can cost more than $220 million apiece, while DUV machines can cost as little as $5 million, with higher-end advanced immersion DUV machines running closer to $90 million.
While a loss of DUV sales to China could impact ASML's revenue, the region now accounts for a smaller share of its overall revenue. The company is restricted from selling EUV and advanced DUV machines to China and is only allowed to sell older-technology systems to Chinese companies. As such, only about 14% of its sales came from the country last quarter. Meanwhile, there was already a bill in Congress set to prevent ASML from selling or servicing machines for the first three Chinese companies expected to receive these homegrown DUV machines, so this revenue was likely to be cut off regardless.
#machines #company

3 months ago
Victory Capital, overseeing the RS Large Cap Value Strategy, released its Q2 2026 investor letter. A copy of the letter can be downloaded here. The RS Large Cap Value Strategy underperformed the Russell 1000 Value Index in the second quarter of 2026 as unfavorable stock selection and sector allocation weighed on relative performance. U.S. equities remained resilient despite the Iran conflict, elevated inflation, labor market concerns and uncertainty around Federal Reserve leadership, with the S&P 500 gaining 15% and the Russell 1000 Value returning 13.9%. Market leadership broadened beyond the Magnificent Seven toward semiconductor, memory, power and other AI infrastructure beneficiaries, while investors also moved down the cap spectrum, helping the Russell 2000 Value rise 17.2%. Information Technology returned 80.63%, while Energy fell 13.77%; stock selection in Technology and Industrials and an underweight Technology position were key detractors. Looking ahead, the firm remains focused on risk management, valuation discipline and identifying financially strong, out-of-favor or misunderstood companies with capable management, improving ROIC, attractive reinvestment opportunities and share prices below estimated intrinsic value. In addition, please check the Strategy's top five holdings to know its best picks in 2026.
In its second-quarter 2026 investor letter, RS Large Cap Value Strategy highlighted MarketAxess Holdings Inc. (NASDAQ:MKTX). MarketAxess Holdings Inc. (NASDAQ:MKTX) operates an electronic trading platform for institutional investor and broker-dealer firms. On July 21, 2026, MarketAxess Holdings Inc. (NASDAQ:MKTX) closed at $112.27 per share. One-month return of MarketAxess Holdings Inc. (NASDAQ:MKTX) was -1.05% and its shares gained -47.06% over the past 52 weeks. MarketAxess Holdings Inc. (NASDAQ:MKTX) has a market capitalization of $3.99 billion with a 52-week trading range between $108.75 - $214.98.
RS Large Cap Value Strategy stated the following regarding MarketAxess Holdings Inc. (NASDAQ:MKTX) in its Q2 2026 investor letter:
"MarketAxess Holdings Inc is a leading electronic trading platform for fixed income securities. MKTX connects institutional investors and broker-dealers for trading across corporate and government bonds. Servicing over 2,100 institutional clients, with nearly 20% market share of US corporate investment grade bond trading, the company has established a strong market position. Shares were under pressure during the quarter over concerns of increased competition and margin pressure. Despite the recent underperformance and broader market concerns, we remain positive on the structural change opportunity taking place under the new CEO and continue to hold the position."
#large #trading

3 months ago
Securitize Corp. (NYSE: $SECZ) and Cantor Fitzgerald are taking tokenization into the primary equity market, creating a pathway for public companies to conduct initial public offerings and follow-on offerings onchain.
The agreement combines Cantor's equity capital markets and trading capabilities with Securitize's regulated infrastructure for issuing, distributing and servicing tokenized securities. Securitize Markets, the company's SEC-registered broker-dealer affiliate, will participate in the offering and settlement process.
Public companies using the structure would still operate inside the established framework for traditional offerings. Blockchain infrastructure would sit underneath the issuance process, supporting digital ownership records, greater transparency and access to investors already active across onchain markets.
More From Cryptoprowl:
Stablecoin Market Cap Declines By $10 Billion

3 months ago
UWM Holdings Corp (NYSE:UWMC) is one of the 8 Most Undervalued Growth Stocks to Buy for the Next 10 Years. UWM Holdings Corp (NYSE:UWMC) is one of the most undervalued growth stocks to buy for the next 10 years. On July 7, BTIG ****** yst Douglas Harter reiterated a Buy rating on the stock. He also ****** igned a target price of $4. On the same day, UWMC received another ****** yst's attention. Terry Ma from Barclays maintained a Buy rating on the stock and set a target price of $4.
Earlier on June 2, Two Harbors Investment shareholders voted to approve the sale to CrossCountry Mortgage, meaning UWMC officially lost its bid to acquire TWO. Previously, on December 17 2025, UWM Holdings Corp (NYSE:UWMC) agreed to acquire TWO in a $1.3 billion all-stock deal. The company wanted to strengthen its position in the mortgage industry and expand its access to mortgage servicing rights by acquiring TWO. However, in March, CrossCountry offered an all-cash proposal. As a result, the real estate investment trust terminated its deal with UWMC, stating that CrossCountry's proposal was superior. This setback leaves the company without the strategic and financial benefits it had expected to gain from the acquisition.
UWM Holdings Corporation (NYSE:UWMC) is a wholesale residential mortgage lender. The company is based in Pontiac, Michigan, and was founded in 1986.
While we acknowledge the potential of UWMC as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 10 Best AI Stocks to Watch in July and 12 Best Dow Stocks to Invest In Right Now.

4 months ago
We recently published Bill Miller Portfolio: Top 10 Stock Picks. Financial Holdings, Inc. (NYSE:BFH) is one of the top stock picks.
Bread Financial Holdings, Inc. (NYSE:BFH) is a financial services company that provides credit card, loan servicing, and other ****** ociated services. Its shares are up by 54% over the past year and by 28% year-to-date. Barclays and TD Cowen discussed the firm in July. Barclays ****** ped the share price target to $104 from $70 and the rating to Equalweight from Underweight. TD Cowen also hiked Bread Financial Holdings, Inc. (NYSE:BFH)'s share price target. It raised the price target to $103 from $95 and kept a Hold rating on the stock.
With the year's first half over, Bread Financial Holdings, Inc. (NYSE:BFH) is gearing up to report its fiscal second quarter earnings. The firm has scheduled its earnings release for July 23rd. Miller Value Partners has disclosed the firm's shares in its 13F holdings since 2023. According to Insider Monkey's data, the firm first disclosed 25,725 shares that were worth $807,508 in Q2 2023. The stake peaked to being worth $18.7 million in Q2 2025.
While we acknowledge the potential of BFH as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
READ NEXT: 33 Stocks That Should Double in 3 Years and Cathie Wood 2026 Portfolio: 10 Best Stocks to Buy.


4 months ago
UWM Holdings Corporation (NYSE:UWMC) is one of the Best Penny Stocks to Invest In According to Billionaires. The stock was held by 16 billionaire investors as of Q1 2026, with total holdings around $151.9 billion.
Recently, on June 25, UWM Holdings Corporation (NYSE:UWMC) was upgraded to Outperform from Market Perform at Keefe Bruyette. Despite the upgrade, the firm lowered the price target from $4.5 to $3.75. The firm noted that they expect the mortgage rates to stay elevated around the 6.25% to 6.5% range through 2028. As a result, the firm lowered the price targets across ****** le insurers and mortgage originators broadly.
Despite the cautious outlook, the firm believes that UWM Holdings is attractively priced at current valuations; hence, it upgraded the stock to Outperform. Moreover, the firm also expects the company to cut its dividend. While dividend cuts are often seen negatively, in this case, the ****** yst views it as constructive. He elaborated that reducing the payout would let the company retain more capital, build equity, and strengthen its balance sheet. The firm sees the likely dividend cut as a near-term positive trigger that could support the stock, even as the broader mortgage industry outlook stays challenging.
UWM Holdings Corporation (NYSE:UWMC) is a company specializing in origination, sale, and servicing residential mortgage lending. Founded in 1986, the company originates primarily from conforming and government loans.
While we acknowledge the potential of UWMC as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
4 months ago
Abacus Global Management (NYSE: $ABX) is moving part of the secondary life insurance market onchain, using blockchain infrastructure to track ownership, liens and cash-flow rights across its portfolio.
The company said more than 100 in-force policies have already been tokenized, with its full balance sheet portfolio expected to move onchain by the end of 2026. Future policy originations are also set to enter the same structure.
Abacus is targeting an ****** et class estimated at $224 billion in the secondary market, where policy transfers still require buyers to review ownership records, beneficiary ****** ignments, servicing histories, and other documents before a transaction can close.
More From Cryptoprowl:
Ripple, The Company Behind XRP, Is Valued At $50 Billion



