5 days ago
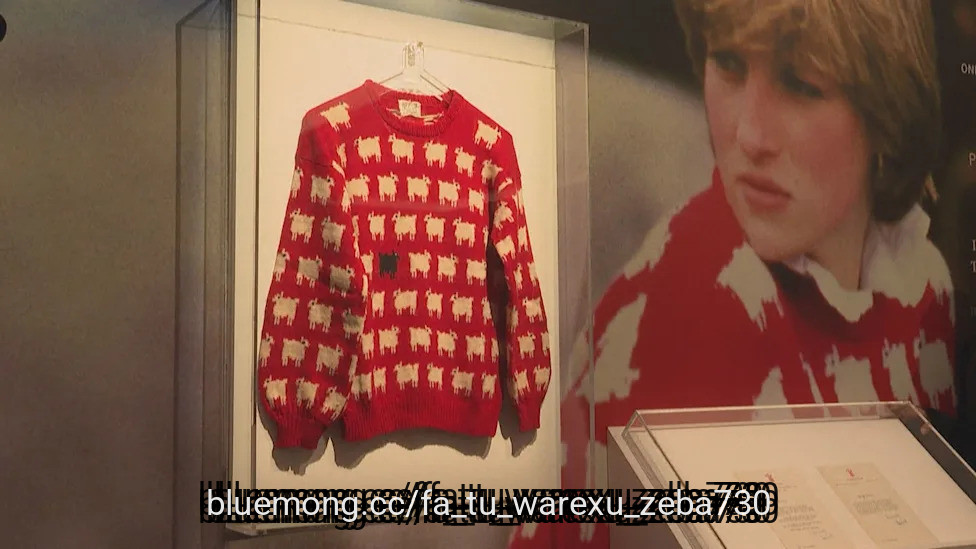
Princess Diana remains one of the most influential royal style figures decades after her death. From glamorous evening gowns to casual sweatshirts, her clothes attracted enormous attention and often carried meanings that went far beyond fashion. Few pieces illustrate that fascination better than her famous red Black Sheep sweater, featuring rows of white sheep and a single black one standing apart from the flock.
Diana first wore the Warm & Wonderful sweater in 1981, shortly after her engagement to Prince Charles. The playful design quickly attracted attention, particularly because the lone black sheep invited interpretations about Diana's own position within royal life. Those interpretations remain speculative, but there is clear evidence that she valued the garment. After the original sweater was damaged, Buckingham Palace contacted the designers seeking a repair or replacement. Diana later appeared publicly in the replacement.
Years later, the original sweater was rediscovered and offered at auction through Sotheby's in 2023. Before the sale, it carried an estimate of $50,000 to $80,000. Its significance came from more than Diana simply having worn it. The accompanying correspondence helped establish its history, while photographs of Diana wearing the distinctive design made it instantly recognizable to collectors and royal fashion enthusiasts.
The final result dramatically exceeded expectations. The sweater sold for $1.143 million, including fees, setting a record at the time for an item of clothing worn by Diana at auction. The price also demonstrated how dramatically demand for objects connected with the princess had grown. Other pieces from her wardrobe had already achieved impressive results, including a purple Victor Edelstein evening gown that sold for more than $600,000 earlier in 2023.
Diana's wardrobe continues to attract this level of interest because her clothing became closely connected with her public identity. Early in her royal life, she embraced romantic dresses and traditional silhouettes. Over time, her wardrobe became increasingly confident, incorporating streamlined tailoring, memorable eveningwear and relaxed casual pieces.
#pieces #princess #evening #casual
Diana first wore the Warm & Wonderful sweater in 1981, shortly after her engagement to Prince Charles. The playful design quickly attracted attention, particularly because the lone black sheep invited interpretations about Diana's own position within royal life. Those interpretations remain speculative, but there is clear evidence that she valued the garment. After the original sweater was damaged, Buckingham Palace contacted the designers seeking a repair or replacement. Diana later appeared publicly in the replacement.
Years later, the original sweater was rediscovered and offered at auction through Sotheby's in 2023. Before the sale, it carried an estimate of $50,000 to $80,000. Its significance came from more than Diana simply having worn it. The accompanying correspondence helped establish its history, while photographs of Diana wearing the distinctive design made it instantly recognizable to collectors and royal fashion enthusiasts.
The final result dramatically exceeded expectations. The sweater sold for $1.143 million, including fees, setting a record at the time for an item of clothing worn by Diana at auction. The price also demonstrated how dramatically demand for objects connected with the princess had grown. Other pieces from her wardrobe had already achieved impressive results, including a purple Victor Edelstein evening gown that sold for more than $600,000 earlier in 2023.
Diana's wardrobe continues to attract this level of interest because her clothing became closely connected with her public identity. Early in her royal life, she embraced romantic dresses and traditional silhouettes. Over time, her wardrobe became increasingly confident, incorporating streamlined tailoring, memorable eveningwear and relaxed casual pieces.
#pieces #princess #evening #casual
12 days ago
The Kansas City Royals made their first big offseason move on Thursday by cutting ties with closer Carlos Estévez. The team declined his $13 million club option, which means he hits the open market. Instead of paying that high price, Kansas City will hand him a $2 million buyout. This decision clears the books but leaves a huge hole in the bullpen after he led the league with 42 saves in 2025.
At the same time, the club exercised a $2.5 million option on right-hander Tony Gonsolin. Per MLB.com Royals, this move keeps a former All-Star under contract for 2027 despite his recent injury struggles. It is a low-cost gamble for a pitcher who once went 16-1 with a 2.14 ERA in 2022. After ending last season with a 5.07 bullpen ERA that ranked 29th in the majors, the Royals must acquire all available pitching help.
Letting Estévez walk feels risky, but the math makes sense for a small-market team. He signed a two-year, $22.2 million deal before 2025 and delivered a 2.45 ERA that year. However, his 2026 season was a disaster filled with injuries and blown saves. He was limited to just one appearance before a comebacker hit his foot and a rotator cuff strain ended his year. According to Yardbarker, his strikeout rate dropped while his walk rate climbed in 2025, showing he was already losing a step.
Paying $13 million for a pitcher who might not even throw a pitch in 2027 is hard to justify. The Royals are better off taking the $2 million buyout and trying to find a cheaper replacement. They need to fix a relief corps that allowed too many runs and lost too many games. The 69-93 record from last year proves the bullpen was a major problem that this move attempts to address.
Bringing back Gonsolin is a different kind of bet, one based on potential rather than recent results. He joined the team on August 13 while recovering from elbow surgery he had in August 2025. In just one major league outing this year against the White Sox, the 32-year-old surrendered five runs across 2 2/3 innings. Per Royals Keep, the $2.5 million price tag is very affordable for a starter with his career stats of 37 wins and 13 losses.
#year #kansas #city
At the same time, the club exercised a $2.5 million option on right-hander Tony Gonsolin. Per MLB.com Royals, this move keeps a former All-Star under contract for 2027 despite his recent injury struggles. It is a low-cost gamble for a pitcher who once went 16-1 with a 2.14 ERA in 2022. After ending last season with a 5.07 bullpen ERA that ranked 29th in the majors, the Royals must acquire all available pitching help.
Letting Estévez walk feels risky, but the math makes sense for a small-market team. He signed a two-year, $22.2 million deal before 2025 and delivered a 2.45 ERA that year. However, his 2026 season was a disaster filled with injuries and blown saves. He was limited to just one appearance before a comebacker hit his foot and a rotator cuff strain ended his year. According to Yardbarker, his strikeout rate dropped while his walk rate climbed in 2025, showing he was already losing a step.
Paying $13 million for a pitcher who might not even throw a pitch in 2027 is hard to justify. The Royals are better off taking the $2 million buyout and trying to find a cheaper replacement. They need to fix a relief corps that allowed too many runs and lost too many games. The 69-93 record from last year proves the bullpen was a major problem that this move attempts to address.
Bringing back Gonsolin is a different kind of bet, one based on potential rather than recent results. He joined the team on August 13 while recovering from elbow surgery he had in August 2025. In just one major league outing this year against the White Sox, the 32-year-old surrendered five runs across 2 2/3 innings. Per Royals Keep, the $2.5 million price tag is very affordable for a starter with his career stats of 37 wins and 13 losses.
#year #kansas #city
12 days ago
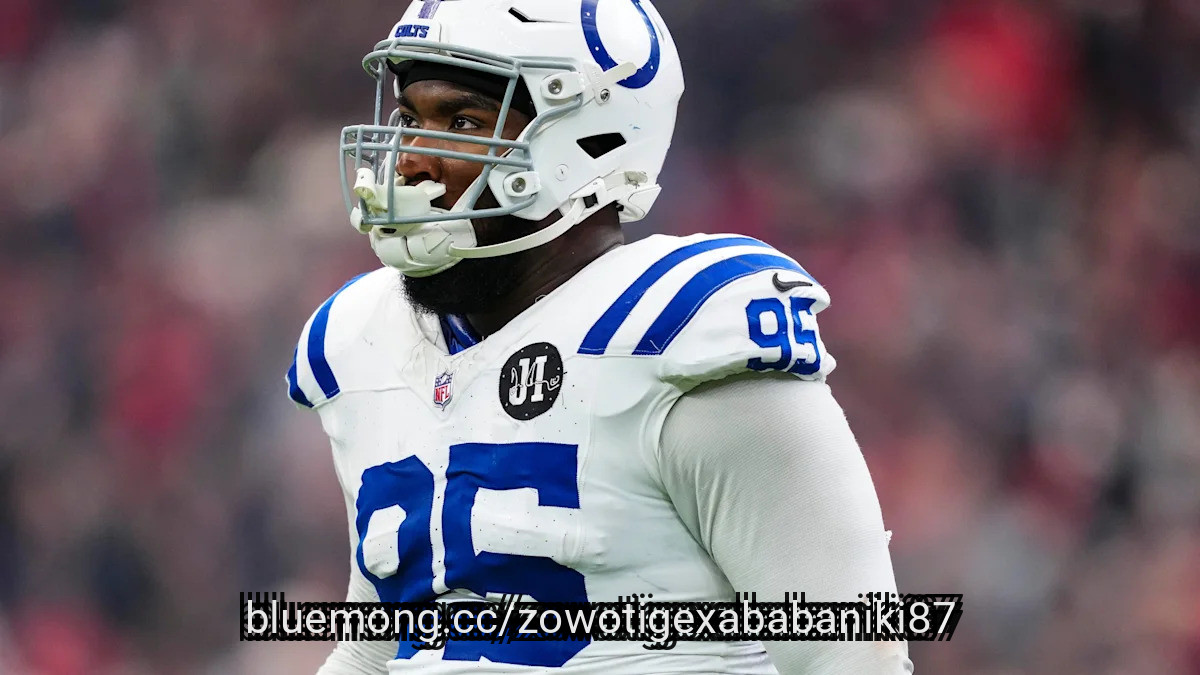
According to NFL Network's Mike Garafolo, despite other team's recent inquiries, the Indianapolis Colts have no intentions of trading breakout defensive tackle Ade Adebawore ahead of the league's trade deadline:
With longtime veteran DeForest Buckner's departure, the 25-year-old Adebawore, who was originally a 2023 4th round pick by Indianapolis, is expected to immediately start full-time as his replacement going forward in 2026.
While those are big shoes to fill at 3T, Adebawore has had a standout campaign in a rotational role, recording 17 tackles (7 solo), a pass defensed, 4.0 sacks, and 15 total QB pressures during 7 games (1 start) this season.
Athletic, fast, twitchy, and featuring a surprisingly strong bull rush for his size at 6,'2", 282 pounds, Adebawore has really been flashing his immense athleticism so far this season and turning it into significant on-the-field production—albeit during rotational reps previously:
As a pending free agent in the last year of his current rookie contract, Adebawore appears to be an ascending young player and potential building block, who the rebuilding Colts would ******* uredly like to keep long-term defensively, with an ample amount of projected 2027 available team salary cap ******* e at $61.9M right now.
#season
With longtime veteran DeForest Buckner's departure, the 25-year-old Adebawore, who was originally a 2023 4th round pick by Indianapolis, is expected to immediately start full-time as his replacement going forward in 2026.
While those are big shoes to fill at 3T, Adebawore has had a standout campaign in a rotational role, recording 17 tackles (7 solo), a pass defensed, 4.0 sacks, and 15 total QB pressures during 7 games (1 start) this season.
Athletic, fast, twitchy, and featuring a surprisingly strong bull rush for his size at 6,'2", 282 pounds, Adebawore has really been flashing his immense athleticism so far this season and turning it into significant on-the-field production—albeit during rotational reps previously:
As a pending free agent in the last year of his current rookie contract, Adebawore appears to be an ascending young player and potential building block, who the rebuilding Colts would ******* uredly like to keep long-term defensively, with an ample amount of projected 2027 available team salary cap ******* e at $61.9M right now.
#season
23 days ago
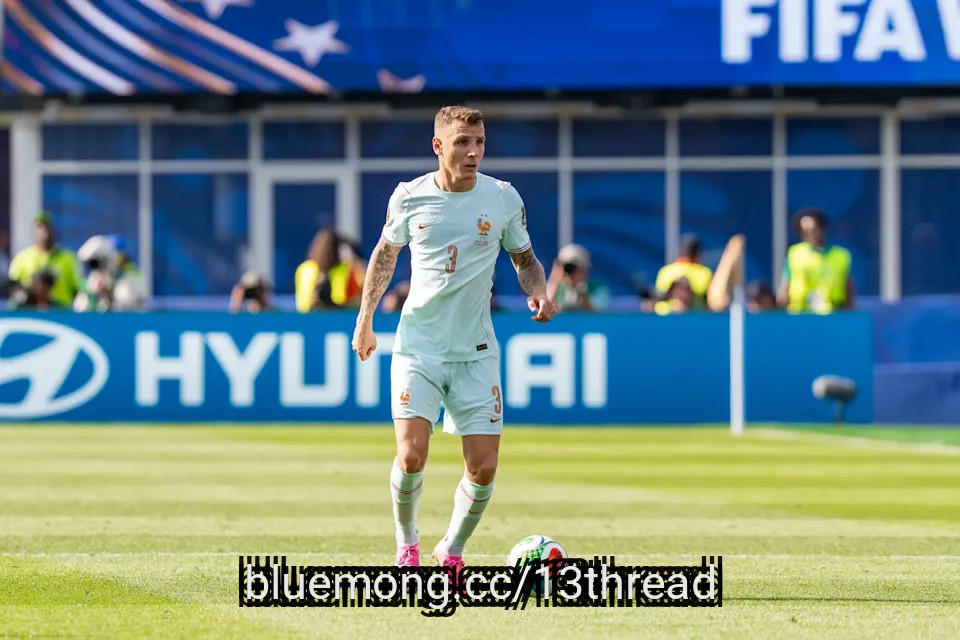
Paris Saint-Germain have a selection problem on the left of defence before their Champions League meeting with Barcelona: Nuno Mendes is injured, and Lucas Digne is the natural alternative against Lamine Yamal. Mundo Deportivo reported the situation on 19 October, describing Mendes as Luis Enrique's preferred answer to the Barcelona winger.
The timing matters for the Catalans, with Yamal in excellent form. His impact in Barcelona's comeback against Galatasaray underlined the threat PSG will need to manage on Tuesday.
Digne's recent outing against Strasbourg did little to strengthen his case. Mundo Deportivo **** sed the Frenchman's display in PSG's 3-1 defeat as laboured and lacking in decisiveness, and reported that Luis Enrique substituted him as he changed course after starting several reserves.
Lucas Digne playing for France. – Photo: Bryan Berlin / CC BY-SA 4.0
That leaves the coach weighing a natural replacement whose latest performance raised questions, rather than simply making a like-for-like switch without concern. Digne is also a former Barcelona player, having spent two seasons at the club from 2016 to 2018.
#mundo #luis
The timing matters for the Catalans, with Yamal in excellent form. His impact in Barcelona's comeback against Galatasaray underlined the threat PSG will need to manage on Tuesday.
Digne's recent outing against Strasbourg did little to strengthen his case. Mundo Deportivo **** sed the Frenchman's display in PSG's 3-1 defeat as laboured and lacking in decisiveness, and reported that Luis Enrique substituted him as he changed course after starting several reserves.
Lucas Digne playing for France. – Photo: Bryan Berlin / CC BY-SA 4.0
That leaves the coach weighing a natural replacement whose latest performance raised questions, rather than simply making a like-for-like switch without concern. Digne is also a former Barcelona player, having spent two seasons at the club from 2016 to 2018.
#mundo #luis

23 days ago
The Los Angeles Rams are facing growing concerns over their special teams after an 18-16 defeat to the Arizona Cardinals left Sean McVay's side with a 2-4 record.
Los Angeles lost kicker Blake Grupe to a knee injury during the game, raising the possibility that the team could need another replacement after releasing Harrison Mevis following his missed kick against the Buffalo Bills.
The latest setback has added to the pressure on a Rams team that entered the season with Super Bowl ambitions but has struggled to find consistency.
According toThe Athletic's Nate Atkins, the Rams are becoming increasingly nervous about their special teams unit as the problems continue to mount.
"The problems are just so widespread that it can be hard to know where to start," Atkins wrote. "The kicking game is chief among them, because the Rams could need a third starting kicker if Grupe's knee injury is serious, after Grupe replaced the waived Harrison Mevis last week."
#grupe #mevis #kicker
Los Angeles lost kicker Blake Grupe to a knee injury during the game, raising the possibility that the team could need another replacement after releasing Harrison Mevis following his missed kick against the Buffalo Bills.
The latest setback has added to the pressure on a Rams team that entered the season with Super Bowl ambitions but has struggled to find consistency.
According toThe Athletic's Nate Atkins, the Rams are becoming increasingly nervous about their special teams unit as the problems continue to mount.
"The problems are just so widespread that it can be hard to know where to start," Atkins wrote. "The kicking game is chief among them, because the Rams could need a third starting kicker if Grupe's knee injury is serious, after Grupe replaced the waived Harrison Mevis last week."
#grupe #mevis #kicker

1 month ago
The United States military has had 81 aircraft destroyed or damaged in the war with Iran, a Congressional Research Service report released this week says.
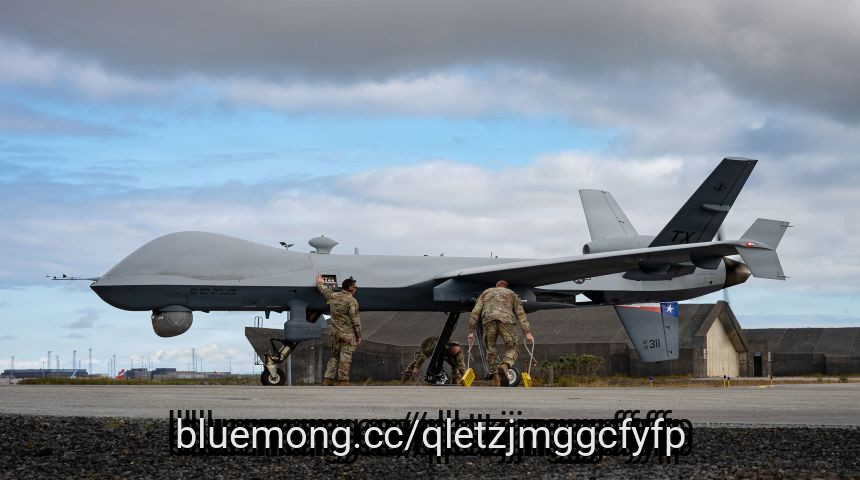
The number includes both airplanes and helicopters as well as drones, with the MQ-9 Reaper drone – used for intelligence, surveillance and reconnaissance, close air support and combat search and rescue – accounting for more than half of the losses.
But also on the list are some of the Pentagon’s most-prized ***** ets, including an F-35A fighter jet and an E-3 Sentry, the four-engine jet with a large radar dome atop the fuselage used for target tracking and airspace management.
The total cost of the aircraft lost is between $1.9 billion and $3.3 billion, depending on the Defense Department’s plans for replacements, the report said, citing figures from the Congressional Budget Office.
The total cost of the war is much higher – at least $45 billion, sources have told CNN. That figure doesn’t include damage to infrastructure at US bases in the region, including those where some of the aircraft losses happened.
#congressional #report #including #total
The number includes both airplanes and helicopters as well as drones, with the MQ-9 Reaper drone – used for intelligence, surveillance and reconnaissance, close air support and combat search and rescue – accounting for more than half of the losses.
But also on the list are some of the Pentagon’s most-prized ***** ets, including an F-35A fighter jet and an E-3 Sentry, the four-engine jet with a large radar dome atop the fuselage used for target tracking and airspace management.
The total cost of the aircraft lost is between $1.9 billion and $3.3 billion, depending on the Defense Department’s plans for replacements, the report said, citing figures from the Congressional Budget Office.
The total cost of the war is much higher – at least $45 billion, sources have told CNN. That figure doesn’t include damage to infrastructure at US bases in the region, including those where some of the aircraft losses happened.
#congressional #report #including #total
1 month ago
When a caller mentioned that they are thinking about adding to their position in Simon Property Group, Inc. (NYSE:SPG) during the October 2 episode of Mad Money, Jim Cramer commented:
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate
I think you're absolutely right... I want you to add to the Simon Property Group... What a great man he (David Simon, previous CEO) was, and he built a fabulous company, and you should buy more of it.
A September 8 question about buying Simon Property Group led Cramer to bring another real estate stock into the conversation.
Simon Property Group, Inc. (NYSE:SPG) reported second-quarter real estate funds from operations of $3.29 per diluted share, up 7.9% year-over-year. Domestic property net operating income increased 8.5%. Occupancy at its U.S. malls and premium outlets remained at 96%, while base minimum rent increased 6.3% to $62.42 per square foot. Management raised its full-year real estate funds from operations outlook to $13.20 - $13.30 per share. These figures show rent and property-income growth without requiring an increase in occupancy. Leasing activity also remained substantial. During the earnings call, management reported signing approximately 1,200 leases covering more than 4.8 million square feet, with new-deal volume increasing more than 20%.
Stable occupancy does not mean every tenant is healthy. Simon Property Group, Inc. (NYSE:SPG) absorbed approximately one million square feet of ****** e returned through retailer bankruptcies during the quarter. Management said it successfully re-leased the ****** e, helping maintain occupancy. That shows leasing strength, but also a reminder of the work required to preserve rental income. Additional retailer failures could bring more vacancies and replacement costs, even when demand for the properties remains sound.
#occupancy #NYSE #management #estate
1 month ago
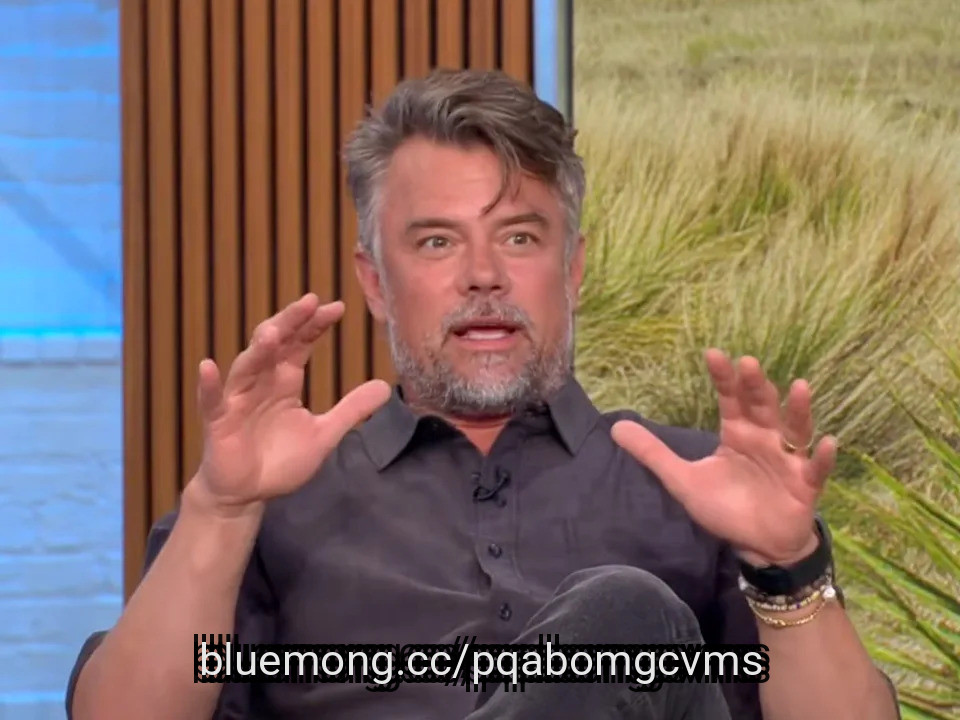
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of Hollywood because his fellow A-listers would "make fun" of him—while opening up about the very different life he has built away from Los Angeles.
The 53-year-old "Ransom Canyon" star recently spoke about his experience with testosterone replacement therapy, revealing that his former representatives had warned him that publicly attaching himself to the treatment could damage his image and career.
Duhamel, who co-founded men's health company Gatlan, said during an appearance on Dave Asprey's "The Human Upgrade" podcast that he initially had reservations about becoming so publicly involved with the company because of the potential response in Hollywood.
"I won't tell you the agency that I'm no longer with, but they said, 'Don't do it. It's bad for your image,'" he recalled. "And I was like, 'All right, watch.'"
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of town in Hollywood—while opening up about the very different life he has built away from Los Angeles. (CBS Mornings)
#duhamel #left
The 53-year-old "Ransom Canyon" star recently spoke about his experience with testosterone replacement therapy, revealing that his former representatives had warned him that publicly attaching himself to the treatment could damage his image and career.
Duhamel, who co-founded men's health company Gatlan, said during an appearance on Dave Asprey's "The Human Upgrade" podcast that he initially had reservations about becoming so publicly involved with the company because of the potential response in Hollywood.
"I won't tell you the agency that I'm no longer with, but they said, 'Don't do it. It's bad for your image,'" he recalled. "And I was like, 'All right, watch.'"
Josh Duhamel has revealed how his decision to enter the testosterone business left him fearing that he could be run out of town in Hollywood—while opening up about the very different life he has built away from Los Angeles. (CBS Mornings)
#duhamel #left


1 month ago
Shares of AutoZone (NYSE: AZO) rose on Tuesday after the automotive replacement parts and accessories distributor reported stronger-than-expected profits.
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AutoZone's net sales grew 5.6% year over year to $6.6 billion in its fiscal 2026 fourth quarter, which ended on Aug. 29.
The auto-parts purveyor opened 175 stores during the quarter and a total of 374 over the trailing 12 months. AutoZone ended the period with 8,031 stores, including 6,863 stores in the U.S., 1,001 in Mexico, and 167 in Brazil.
Additionally, same-store sales, which measure revenue from locations open for at least a year, increased by 2.7%, or 1.5% when excluding foreign currency fluctuations.
#year #autozone #quarter #NYSE
Missed AI's "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our ****** ysts, we're only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
AutoZone's net sales grew 5.6% year over year to $6.6 billion in its fiscal 2026 fourth quarter, which ended on Aug. 29.
The auto-parts purveyor opened 175 stores during the quarter and a total of 374 over the trailing 12 months. AutoZone ended the period with 8,031 stores, including 6,863 stores in the U.S., 1,001 in Mexico, and 167 in Brazil.
Additionally, same-store sales, which measure revenue from locations open for at least a year, increased by 2.7%, or 1.5% when excluding foreign currency fluctuations.
#year #autozone #quarter #NYSE
2 months ago
Veteran ******* yst Jim Cramer sees something in Apple's (AAPL) latest launch that is more than a reason for its customers to buy another replacement phone.
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran
After visiting Apple's Manhattan store, the CNBC host praised the iPhone 18 but reserved his strongest enthusiasm for the foldable Duo. He plans to buy it as a second phone, a distinction that gives his excitement an intriguing business angle.
Apple shares have already gained around 23.6% this year through September 18, raising the stakes for turning product excitement into sales.
For context, Apple unveiled its iPhone 18 Pro lineup and first foldable iPhone on September 9. The Pro models reached stores on September 18; Duo availability follows on October 23.
For Cramer, the bigger opportunity goes beyond better cameras and battery life. His reaction suggests Apple could give loyal customers a fresh reason to spend, even when their existing phones still work perfectly well.
#reason #phone #veteran

2 months ago
Concerned about an AI bubble? Sign up for The Daily Upside for smart and actionable market news, built for investors.
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
There's a lot we can't predict, like the outcome of the midterm elections, who will make it to the Super Bowl or whether Taylor Swift was actually hinting at a new album release in that Emmy's sketch. But when it comes to what our retirement looks like, we can certainly try.
Many retirement plans offer predictive tools that can help savers forecast their future balances, retirement readiness, income replacement rates and more. Participants, however, aren't happy with the options: J.D. Power's recent survey of digital experience satisfaction for retirement plans found that predictive tools were the lowest-performing attribute.
"The technology in the 401(k) is seriously behind what people are used to in their consumer life," said Fred Barstein, CEO of The Retirement Advisor University. When the underlying technology structure is old and **** bersome, it's hard for the tools to be as effective as they could be.
Sign up for The Daily Upside at no cost for premium **** ysis on all your favorite stocks.
#tools #sign #upside #like
2 months ago
On September 4, the U.S. Department of War (DoW) announced a $336,112,000 Navy contract for Huntington Ingalls Industries, Inc. (NYSE:HII) to advance procurement of long-lead materials for the construction of the future USS William J. Clinton (CVN 82).
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries
Work on the program will be executed in Newport News, Virginia, with completion anticipated by March 2039. Shipbuilding and conversion funding from FY 2026 will be obligated at the time of award.
The contract is not just a headline number, but reaffirms the company's status as the sole nuclear carrier builder for the U.S. Navy.
The long lead materials contract has secured Huntington Ingalls Industries, Inc. (NYSE:HII)'s role on the CVN 82 well before construction begins, which has extended revenue visibility to 2039.
According to defense websites, the Navy plans on spending $22.34 billion on its aircraft carrier replacement program over the next five years. This contract can be seen as among the first in a larger sequence, with more awards to come as procurement accelerates.
#navy #contract #ingalls #industries

2 months ago
While he stepped down as CEO of Berkshire Hathaway at the end of last year, Warren Buffett's wealth, and thus his portfolio, is still tied to the conglomerate and its stock portfolio. On that end, Berkshire's top-three positions -- consisting of Apple (NASDAQ: AAPL), American Express (NYSE: AXP), and Alphabet (NASDAQ: GOOG) (NASDAQ: GOOGL) (Nasdaq) -- make up more than half of its equity portfolio.
All three are strong compounding businesses with wide moats, but which looks like the best of the group to buy today? Let's take a look at each.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple is Berkshire's largest holding, making up about 22% of its portfolio. The stock is a Buffett favorite because it has one of the best compounding business models out there.
Apple, of course, is best known for its iPhone and other devices. Smartphones and computers tend to have very predictable replacement cycles, which creates an almost recurring type of revenue stream for the company. However, the beauty of the business stems from its closed-garden ecosystem that helps lock in consumers, from which it then collects high-margin service revenue. This revenue comes from a variety of sources, including a search revenue-sharing deal with Alphabet, commissions on app downloads, Apple Pay, and subscriptions for things like cloud storage.
#NASDAQ #revenue #best #alphabet
All three are strong compounding businesses with wide moats, but which looks like the best of the group to buy today? Let's take a look at each.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Apple is Berkshire's largest holding, making up about 22% of its portfolio. The stock is a Buffett favorite because it has one of the best compounding business models out there.
Apple, of course, is best known for its iPhone and other devices. Smartphones and computers tend to have very predictable replacement cycles, which creates an almost recurring type of revenue stream for the company. However, the beauty of the business stems from its closed-garden ecosystem that helps lock in consumers, from which it then collects high-margin service revenue. This revenue comes from a variety of sources, including a search revenue-sharing deal with Alphabet, commissions on app downloads, Apple Pay, and subscriptions for things like cloud storage.
#NASDAQ #revenue #best #alphabet

2 months ago
Burford Capital Limited (NYSE:BUR) announced on September 14 that its indirect, wholly owned subsidiary, Burford Capital Global Finance LLC, priced $300 million of 8% senior secured notes due 2029. Closing is expected September 17, subject to customary conditions.
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE
Net proceeds and existing cash are intended to redeem the subsidiary's 6.25% unsecured notes due in 2028. The transaction would move this maturity into 2029, with a coupon 175 basis points higher.
The September 14 offering announcement confirmed $400 million of outstanding 2028 notes, making the cash contribution central to the refinancing. Burford Capital Limited (NYSE:BUR) said it expected to issue a conditional notice targeting September 24, 2026, for redemption of all $400 million, subject to successful completion of the $300 million financing.
For Burford Capital Limited (NYSE:BUR), refinancing ahead of maturity creates more room for litigation investments to generate cash. Court proceedings, settlements, and collections follow uncertain schedules. Reducing dependence on a particular realization date could help management preserve investment value.
Redeeming the confirmed $400 million balance with $300 million of replacement notes would reduce gross principal by $100 million. Calculated annual coupons would fall from $25 million to $24 million, before fees and other financing costs.
#capital #september #NYSE
2 months ago
This story was originally published on Bisnow, the newsroom global commercial real estate reads first. To receive daily news and **** ysis, subscribe to Bisnow's free suite of newsletters.
The following article is a collaboration between Bisnow and business tech publication IT Brew.
It was Thanksgiving week in 2022 — a time when most employees are hard to find, let alone critical pieces of data center power infrastructure. And Kurt Bogle needed a transformer.
Bogle, then a senior regional director of critical facilities operations at NTT Global Data Centers, oversaw seven operational buildings around Chicago and Virginia and a staff of about 150 people. After a transformer failed a test, Bogle had to find a replacement and coordinate a swap with the on-site managers — all without disrupting service.
Thankfully, Bogle found a spare, but his experience illustrates the importance of systems thinkers at data centers who know how to acquire the resources necessary to maintain data centers' high uptime expectations. Given supply chain limitations and a steady build-out of data centers, such expertise is more crucial than ever — and there are signs a labor shortage is underway, threatening Big Tech's artificial intelligence ambitions and the reliable operation of mission-critical facilities.
#data #critical
The following article is a collaboration between Bisnow and business tech publication IT Brew.
It was Thanksgiving week in 2022 — a time when most employees are hard to find, let alone critical pieces of data center power infrastructure. And Kurt Bogle needed a transformer.
Bogle, then a senior regional director of critical facilities operations at NTT Global Data Centers, oversaw seven operational buildings around Chicago and Virginia and a staff of about 150 people. After a transformer failed a test, Bogle had to find a replacement and coordinate a swap with the on-site managers — all without disrupting service.
Thankfully, Bogle found a spare, but his experience illustrates the importance of systems thinkers at data centers who know how to acquire the resources necessary to maintain data centers' high uptime expectations. Given supply chain limitations and a steady build-out of data centers, such expertise is more crucial than ever — and there are signs a labor shortage is underway, threatening Big Tech's artificial intelligence ambitions and the reliable operation of mission-critical facilities.
#data #critical


2 months ago
Crane Company (NYSE:CR) announced a definitive agreement on September 14 to acquire Trillium Flow Technologies' U.S. pump business for approximately $240 million. The operations primarily serve municipal water and wastewater customers and are expected to generate approximately $115 million in full-year revenue. Closing is expected in the fourth quarter, subject to regulatory approvals and customary conditions.
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE
The acquisition would add Floway, Wemco, Roto-Jet and WSP to Process Flow Technologies. Their installed equipment base supports service, repair, retrofit and replacement demand, giving the transaction a recurring-revenue rationale.
Crane Company (NYSE:CR) disclosed a price of approximately 14.6 times estimated 2026 adjusted EBITDA. Adjusted EBITDA is a company-defined non-GAAP measure based on earnings before interest, taxes, depreciation, and amortization, with further adjustments. The announcement did not specify the target's adjustments or provide a GAAP reconciliation.
Water and wastewater systems require reliable pumping equipment throughout their operating lives. An established installed base creates opportunities to sell replacement parts, restore equipment, and upgrade performance long after the original sale.
For Crane Company (NYSE:CR), those customer relationships could make revenue less dependent on winning entirely new projects. Service capability and product familiarity may also help retain customers when equipment eventually needs replacement.
#NYSE

2 months ago
The Williams Companies, Inc. (NYSE:WMB) lost a key New Jersey water-quality certification for Northeast Supply Enhancement, or NESE, after a September 8 federal appeals court ruling reported by Reuters on September 9. The Third Circuit vacated the certification and returned the matter to state regulators. The Williams Companies, Inc. (NYSE:WMB) said that, at this time, it did not expect the ruling to adversely affect construction or the anticipated in-service timeline.
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction
The project, which Reuters described as costing approximately $1 billion, expands the existing Transco network through Pennsylvania, New Jersey and New York. The Williams Companies, Inc. (NYSE:WMB) continues to target fourth-quarter 2027 service. The investment question is whether the permit review can be resolved quickly enough to protect both that schedule and the economics of the investment.
The commercial rationale rests on delivering additional gas into a constrained market. The Williams Companies, Inc. (NYSE:WMB) says demand continues to grow in areas including Brooklyn, Queens, Staten Island and Long Island. Planned capacity of approximately 400,000 dekatherms per day would expand the system's ability to serve those markets.
NESE also builds on existing infrastructure. The Williams Companies, Inc. (NYSE:WMB) plans pipeline loops, compressor work, and connections to the Transco system. Those connections give the added capacity access to an established transportation network and regional delivery points, although substantial construction remains necessary.
The remand leaves a route for reconsideration by New Jersey regulators. For The Williams Companies, Inc. (NYSE:WMB), the favorable scenario is a replacement certification that addresses the court's findings without requiring substantial redesign or disrupting the construction sequence.
#williams #NYSE #jersey #construction

2 months ago
Johnson & Johnson (JNJ) has been a rewarding stock to hold, up about 53% over the past year against about 17% for the S&P 500. The change worth noticing over that stretch is quieter than the price. Management said sales still rose 5.6% despite a STELARA drag of about 460 basis points. Management is encouraging investors to evaluate the company's underlying momentum by presenting growth rates that exclude STELARA alongside its reported figures.
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter
A year and a half ago, that drag was the headline. Management's own framing of the first quarter of 2025 noted an approximate 810 basis point headwind on Innovative Medicine sales.
By the second quarter of 2026, that segment-level drag remained heavy at roughly 760 basis points (or about 460 basis points across the total enterprise), yet management's emphasis shifted to highlighting double-digit operational growth excluding STELARA
The exclusion is not a rounding adjustment. STELARA sales fell 55.7% in the second quarter of 2026, and management put that drag at about 460 basis points of the whole company's 5.6% operational sales growth.
Two products show what the replacement looks like. TREMFYA booked $2 billion of sales in the second quarter of 2026, up over 70%, and management says ulcerative colitis and Crohn's disease are the major drivers of that growth. ICOTYDE, a recently launched once-daily pill for psoriasis, is the second, which leadership has highlighted as a key pipeline priority for the immunology business.
#sales #basis #drag #quarter

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#systems #parnassus
2 months ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of ***** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#billion #depuy
2 months ago
Broyhill **** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
In its second-quarter 2026 investor letter, Broyhill **** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill **** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#broyhill #investor
2 months ago
Apollo Global Management, Inc. (NYSE:APO) is reportedly in talks to acquire Johnson & Johnson (NYSE:JNJ) DePuy Synthes orthopedics business in a transaction that could value the unit at close to $20 billion, according to Bloomberg, as reported by Reuters. J&J generated $9.3 billion of revenue from the orthopedics business in 2025, making the potential transaction material for both companies. The discussions could reach an agreement within weeks, although J&J is also considering a public-market spin-off. This is consistent with J&J's October 2025 decision to separate DePuy Synthes within an expected 18-to-24-month timeframe and shift its MedTech portfolio toward higher-growth, higher-margin businesses.
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
For Apollo Global Management, Inc. (NYSE:APO), the attraction is the opportunity to acquire a large, established medical-device franchise with substantial recurring demand from joint-replacement and surgical procedures. A roughly $20 billion valuation against $9.3 billion of 2025 revenue implies a price-to-sales multiple of about 2.2x, giving Apollo room to pursue operational improvements, portfolio rationalization, and margin expansion if the business is acquired at an attractive valuation.
DePuy Synthes also has meaningful scale and leading positions across major orthopedics categories, while J&J has recently invested in technologies that could strengthen the franchise, including an agreement covering Gemtrack tracking technology for robotic and navigation-assisted joint procedures and the acquisition of Expanding Innovations for expandable spine implants. Apollo is also entering the potential deal from a position of considerable financial scale: it had approximately $1.05 trillion of **** ets under management as of June 30, 2026, with $198 billion in equity strategies and $849 billion in credit strategies. Its second-quarter results included $111 billion of gross capital deployment, demonstrating the capacity to execute large transactions.
For Johnson & Johnson (NYSE:JNJ), a sale could accelerate the portfolio transformation that management has already identified as a strategic priority while potentially delivering a sizeable upfront cash inflow. J&J explicitly said its planned orthopedics separation should increase the company's top-line growth and operating margins by allowing it to concentrate on Oncology, Immunology, Neuroscience, Cardiovascular, Surgery and Vision.
The company has also been restructuring orthopedics, with $307 million of restructuring expense in 2025, following $167 million in 2024 and $319 million in 2023, primarily tied to market and product exits. A sale could therefore remove a business that has required restructuring resources while allowing J&J to redeploy capital toward areas it views as higher growth and higher margin.
#NYSE #johnson
2 months ago
Broyhill ***** et Management, a Charlotte-based firm, issued its second-quarter 2026 investor letter, which is available for download here. The Broyhill Equity Composite gained 8.8% in Q2, trailing the MSCI All Country World Index's 15.1% and the MSCI ACWI Value Index's 10.8%. For the first half, the Composite returned 2.3%, versus 11.5% for the Index. The letter highlights that a significant portion of the shortfall occurred in April due to market dynamics and geopolitical events, with tech, particularly semiconductors, driving recent gains. Broyhill notes its lack of direct semiconductor exposure but acknowledges potential interest in the sector if opportunities arise, maintaining its investment philosophy focused on capital protection in fragile market conditions. Also, check the fund's top five holdings to see its best picks in 2026.
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset
In its second-quarter 2026 investor letter, Broyhill ***** et Management highlighted Valvoline Inc. (NYSE:VVV) as a leading performance contributor. Valvoline Inc. (NYSE:VVV) is a US-based automotive preventive maintenance company that offers oil changes, battery, bulb, and wiper replacements; tire rotations; and other maintenance services. On September 14, 2026, Valvoline Inc. (NYSE:VVV) closed at $30.37 per share. Over the past month, Valvoline Inc. (NYSE:VVV) declined 9.69%, and its shares lost 25.33% over the past 52 weeks. Valvoline Inc. (NYSE:VVV) has a market capitalization of $3.87 billion.
Broyhill ***** et Management stated the following regarding Valvoline Inc. (NYSE:VVV) in its Q2 2026 investor letter:
"Valvoline Inc. (NYSE:VVV) gained 18%, having also led the first quarter. Comparable sales grew 8.2% against consensus near 5.4%, adjusted EBITDA grew 28%, and guidance was raised across comparable sales, EBITDA, and earnings. The company added 31 stores and now operates 2,409 stores, with ticket sales driving roughly two-thirds of the gain."
Valvoline Inc. (NYSE:VVV) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. According to our database, 44 hedge fund portfolios held Valvoline Inc. (NYSE:VVV) at the end of the second quarter, compared to 39 in the previous quarter. While we acknowledge the potential of Valvoline Inc. (NYSE:VVV) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#valvoline #asset

2 months ago
Parnassus Investments, an investment management company, released the "Parnassus Growth Equity Fund" second-quarter 2026 investor letter. The letter can be downloaded here. During the quarter, the Fund (Investor Shares) returned 17.49% (net of fees), outperforming the Russell 1000 Growth Index's 16.74%. Holdings in Information Technology and Consumer Discretionary sectors boosted relative returns, while Communication Services and Financials holdings detracted. For the year-to-date period, the Fund returned 6.17% (net of fees), outperforming the Russell 1000 Growth's 5.33%. The firm remains constructively bullish on U.S. equities and continues to be selective, valuation-sensitive, and focused on disruptive growth opportunities through active stock selection. Growth stocks advanced during the second quarter, as the Russell 1000 Growth Index generated strong double-digit returns driven by increased confidence in the durability of the ongoing artificial intelligence (AI) infrastructure build-out. Additionally, reviewing the Fund's top five holdings could help identify its best picks for 2026.
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter
In its second-quarter 2026 investor letter, Parnassus Growth Equity Fund highlighted Comfort Systems USA, Inc. (NYSE:FIX) as a new position. Comfort Systems USA, Inc. (NYSE:FIX) is a leading mechanical and electrical installation, renovation, maintenance, repair, and replacement services provider to commercial, industrial, and institutional customers. On September 15, 2026, Comfort Systems USA, Inc. (NYSE:FIX) closed at $1,576.78 per share. Over the past month, Comfort Systems USA, Inc. (NYSE:FIX) declined 5.15% and its shares gained 110.86% over the past 52 weeks. Comfort Systems USA, Inc. (NYSE:FIX) has a market capitalization of $55.49 billion.
Parnassus Growth Equity Fund stated the following regarding Comfort Systems USA, Inc. (NYSE:FIX) in its Q2 2026 investor letter:
"Other positions added during the quarter included Comfort Systems, a mechanical, electrical and plumbing contractor. Comfort Systems USA, Inc. (NYSE:FIX) is a mechanical, electrical and plumbing contractor that provides the skilled labor that's essential for building increasingly complex data centers, where demand continues to accelerate alongside AI investment."
Comfort Systems USA, Inc. (NYSE:FIX) is not on our list of the 40 Most Popular Stocks Among Hedge Funds. As per our database, 83 hedge fund portfolios held Comfort Systems USA, Inc. (NYSE:FIX) at the end of the second quarter which was 80 in the previous quarter. While we acknowledge the potential of Comfort Systems USA, Inc. (NYSE:FIX) as an investment, we believe certain AI stocks offer greater upside potential and carry less downside risk. If you're looking for an extremely undervalued AI stock that also stands to benefit significantly from Trump-era tariffs and the onshoring trend, see our free report on the best short-term AI stock.
#NYSE #quarter
2 months ago
During the September 10 episode of Mad Money, a caller questioned whether recent vertical integration by industrial competitors and market selloffs warranted a lower valuation for Howmet Aerospace Inc.'s (NYSE:HWM) economic moat, or if demand remained strong enough to make the pullback an overreaction. Jim Cramer replied:
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
Now, look, I'll tell you, here's the problem… It's a fastener company, and it frankly is, most times, very commodity-oriented business, and it happens to sell at 44 times earnings, and we don't want to pay that for commodities even though the business is strong. I think people are saying, "Wait a second, that's too much to pay, and I'm going to wait till it goes lower." And if you look at the chart, it does seem like it is going lower.
Howmet Aerospace Inc. (NYSE:HWM) occupies a sole-source or primary-supplier position across critical narrowbody and widebody aircraft programs, providing single-crystal turbine blades, advanced structural castings, and **** anium fasteners. Approval and qualification requirements, manufacturing complexity, and a limited supplier base can make alternative sources difficult to establish quickly. That gives the company strong pricing power on both new plane parts and higher-margin replacement spares.
The structural advantages of Howmet Aerospace Inc.'s (NYSE:HWM) business model can be seen in its Q2 financial results. Revenue surged over 24% year-over-year (21% organically) to $2.55 billion, driven by a 28% jump in commercial aerospace revenue, a 38% expansion in industrial gas turbines, and an 11% gain in defense aerospace. The core Engine Products division recorded third-party sales of $1.37 billion, up 32% year-over-year, while segment adjusted EBITDA margins expanded by 470 basis points to 37.7%.
Despite its market positioning, Howmet Aerospace Inc. (NYSE:HWM) carries valuation risks that advise a cautious approach. Trading at elevated EV/EBITDA and forward P/E multiples relative to traditional industrial peers, the stock leaves little margin for operational missteps. Capital expenditures are projected to exceed $500 million in 2026 as the company builds out production capacity for next-generation engine components and gas turbines, reducing near-term free cash conversion flexibility.
#lower #ebitda
2 months ago
Duke basketball coach Jon Scheyer addressed the reports linking him to the NBA during the offseason.
The Blue Devils head coach was reportedly linked to Dallas Mavericks through the offseason as a potential replacement for Jason Kidd. The Mavericks ultimately hired former Michigan coach Dusty May.
Scheyer discussed the NBA interest on the Glue Guys Podcast on Monday, Sept. 14.
"If anybody that knows me, I wouldn't be able to live with myself not seeing this thing through, that's just the bottom line," Scheyer said. "I'm at a one-of-one place where (it's) not often you get your dream job when you're 33, and that's what happened to me."
Scheyer took over for Mike Krzyzewski in 2022 after spending nine seasons on his predecessor's staff. A former Duke national champion and two-time team captain, Scheyer is entering his fifth season as the program's head coach. He owns a 124-25 career record, the most wins by any Division I head coach in their first four seasons, and has led the Blue Devils to three ACC Tournament championships, three NCAA Elite Eight appearances and one Final Four.
#duke
The Blue Devils head coach was reportedly linked to Dallas Mavericks through the offseason as a potential replacement for Jason Kidd. The Mavericks ultimately hired former Michigan coach Dusty May.
Scheyer discussed the NBA interest on the Glue Guys Podcast on Monday, Sept. 14.
"If anybody that knows me, I wouldn't be able to live with myself not seeing this thing through, that's just the bottom line," Scheyer said. "I'm at a one-of-one place where (it's) not often you get your dream job when you're 33, and that's what happened to me."
Scheyer took over for Mike Krzyzewski in 2022 after spending nine seasons on his predecessor's staff. A former Duke national champion and two-time team captain, Scheyer is entering his fifth season as the program's head coach. He owns a 124-25 career record, the most wins by any Division I head coach in their first four seasons, and has led the Blue Devils to three ACC Tournament championships, three NCAA Elite Eight appearances and one Final Four.
#duke
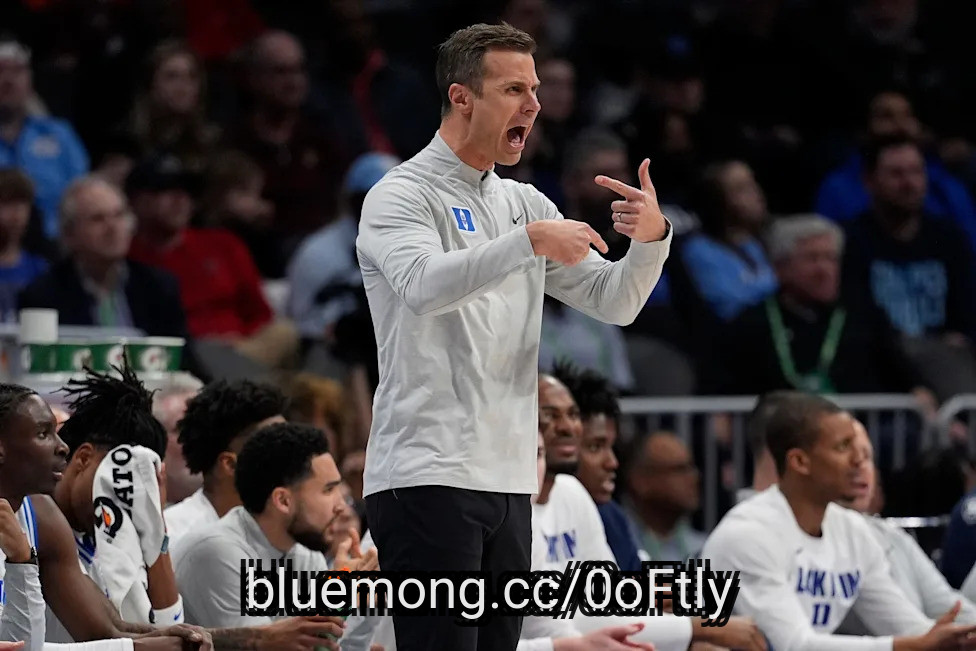
2 months ago
Three and a half years of freight recession did two things to the truck financing market at once. It shredded the credit profiles of the carriers who most needed to borrow. It also pushed a large share of the lenders who would have lent to them out of the sector. Both are now rationing the equipment replacement cycle the industry has spent two years waiting on.
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large
Kirk Mann stayed in. As executive vice president and general manager of the transportation vendor solutions business at Mitsubishi HC Capital America, he financed trucks through the entire downturn and watched a great many of them come back.
"There are a lot of lenders, banks that left, and so we've had the benefit of being one of the lenders actually lending money in this ****** e," Mann said in an interview with FreightWaves. What competition remains is mostly OEM captive finance arms, a couple of large independents and a few bank-led groups, he said.
The carriers that did not survive were overwhelmingly the newest. On average, 85% of motor carriers with fewer than two years of operating experience and their own operating authority failed over a three-year stretch of the downturn, Mann said.
Back in January 2023, Mann sat in Mitsubishi HC Capital's Chicago offices with Wayne Pass, the company's chief credit officer for vendor solutions, since retired. He asked what a Freightliner Cascadia 13-speed with a tall sleeper and fewer than 500,000 miles was worth. Both men wrote down $45,000. Mann then asked what the company was financing those trucks at. About $110,000.
#mitsubishi #back #financing #large

2 months ago
NVIDIA Corporation (NASDAQ:NVDA) has an argument against rapid hardware obsolescence: older accelerators still command rental prices. For CoreWeave, Inc. (NASDAQ:CRWV), which sells access to computing infrastructure, the harder question is how much of that rent becomes a return.
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return
The September 7 settlement of a transaction-based GPU rental benchmark put NVIDIA's H100 SXM at $3.17 per GPU-hour and its older A100 SXM4 at $1.05. Those are market benchmarks, not CoreWeave's realized prices or the economics of its entire fleet.
The distinction matters because a chip can remain useful without every owner earning an attractive return on the equipment purchased around it.
NVIDIA benefits when buyers believe its systems can serve workloads across multiple product generations. A longer revenue-producing life can make the initial purchase easier to justify and reinforce confidence in its computing ecosystem.
That does not guarantee faster replacement demand. Customers able to run suitable tasks on older equipment may defer some upgrades. NVIDIA still needs new systems to offer advantages worth paying for, especially when power and facility capacity constrain deployment.
#NASDAQ #rental #computing #return
2 months ago
India will look to seal the three-match T20I series against Afghanistan when the two teams meet in the second match at the Arun Jaitley Stadium on Tuesday.
India lead the series 1-0 after a convincing seven-wicket win in the first T20I. Afghanistan will need a much better performance to keep the series alive.
Afghanistan were in trouble early in the first T20I after losing five wickets for 43 runs inside the Power-play. Azmatullah Omarzai and Mohammad Nabi then put the innings back on track with an 83-run partnership.
Omarzai remained unbeaten on 64 off 44 **** as Afghanistan finished with 156/8. However, the total was not enough against India's strong batting line-up.
Arshdeep Singh was India's best bowler, taking 3/9. Jasprit **** rah also made an impact on his return to international cricket by picking up an early wicket. Axar Patel and Varun Chakaravarthy also took wickets as Afghanistan struggled to build momentum.
India made the chase look easy thanks to an explosive innings from Abhishek Sharma.
The left-handed opener smashed 82 off just 32 **** , hitting seven fours and seven sixes. Ishan Kishan also made a useful contribution with 42.
India reached 157/3 in only 13.4 overs to take a 1-0 lead in the series.
Afghanistan's biggest concern will be their top order.
Rahmanullah Gurbaz was dismissed for a duck in the first over of the opening T20I. Afghanistan will need their top-order batters to give the team a stronger start and provide a platform for players such as Omarzai, Nabi and Rashid Khan.
The visitors have several match-winners in their squad, including Rashid Khan, Noor Ahmad, Mujeeb Ur Rahman and Naveen-ul-Haq.
Captain Ibrahim Zadran, who is leading Afghanistan in his first series as full-time T20I captain, will hope his team can turn its individual talent into a more disciplined performance.
India also have some selection decisions to make despite their comfortable win in the first T20I.
Abhishek's 82 has strengthened his position at the top of the order, while Sanju Samson scored only 10 runs.
Ishan Kishan also scored 42, giving India another option in the batting line-up. Teenage batter Vaibhav Sooryavanshi could also be in contention after missing the first T20I.
India will also be without Harshit Rana, who has been ruled out after suffering a rectus femoris strain. Yash Thakur has joined the squad as his replacement.
A win on Tuesday will give India an unassailable 2-0 lead in the three-match series. Afghanistan, meanwhile, need a victory to take the series into a decider.
#first #lead #seven #need
India lead the series 1-0 after a convincing seven-wicket win in the first T20I. Afghanistan will need a much better performance to keep the series alive.
Afghanistan were in trouble early in the first T20I after losing five wickets for 43 runs inside the Power-play. Azmatullah Omarzai and Mohammad Nabi then put the innings back on track with an 83-run partnership.
Omarzai remained unbeaten on 64 off 44 **** as Afghanistan finished with 156/8. However, the total was not enough against India's strong batting line-up.
Arshdeep Singh was India's best bowler, taking 3/9. Jasprit **** rah also made an impact on his return to international cricket by picking up an early wicket. Axar Patel and Varun Chakaravarthy also took wickets as Afghanistan struggled to build momentum.
India made the chase look easy thanks to an explosive innings from Abhishek Sharma.
The left-handed opener smashed 82 off just 32 **** , hitting seven fours and seven sixes. Ishan Kishan also made a useful contribution with 42.
India reached 157/3 in only 13.4 overs to take a 1-0 lead in the series.
Afghanistan's biggest concern will be their top order.
Rahmanullah Gurbaz was dismissed for a duck in the first over of the opening T20I. Afghanistan will need their top-order batters to give the team a stronger start and provide a platform for players such as Omarzai, Nabi and Rashid Khan.
The visitors have several match-winners in their squad, including Rashid Khan, Noor Ahmad, Mujeeb Ur Rahman and Naveen-ul-Haq.
Captain Ibrahim Zadran, who is leading Afghanistan in his first series as full-time T20I captain, will hope his team can turn its individual talent into a more disciplined performance.
India also have some selection decisions to make despite their comfortable win in the first T20I.
Abhishek's 82 has strengthened his position at the top of the order, while Sanju Samson scored only 10 runs.
Ishan Kishan also scored 42, giving India another option in the batting line-up. Teenage batter Vaibhav Sooryavanshi could also be in contention after missing the first T20I.
India will also be without Harshit Rana, who has been ruled out after suffering a rectus femoris strain. Yash Thakur has joined the squad as his replacement.
A win on Tuesday will give India an unassailable 2-0 lead in the three-match series. Afghanistan, meanwhile, need a victory to take the series into a decider.
#first #lead #seven #need

2 months ago
A Palestinian fashion designer says she nearly closed down her fashion brand until Olivia Rodrigo stepped in.
In a new interview, designer Yasmeen Mjalli told Vogue Arabia that her brand Nöl Collective, founded in 2020, almost exclusively imported natural fibers to create their clothes. She recalled the numerous challenges and hardships of creating new pieces in the West Bank.
Mjalli told the magazine she once ordered a shipment of naturally dyed handwoven wool for the brand's autumn collection, only for it to have been held and ultimately destroyed by Israeli customs. She said she made an attempt to source replacement fabric in Jerusalem, but her efforts were thwarted due to the army closing down roads out of Ramallah.
"I was genuinely like, maybe we should stop, maybe this is our last effort. I was just so tired," Mjalli said.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#down
In a new interview, designer Yasmeen Mjalli told Vogue Arabia that her brand Nöl Collective, founded in 2020, almost exclusively imported natural fibers to create their clothes. She recalled the numerous challenges and hardships of creating new pieces in the West Bank.
Mjalli told the magazine she once ordered a shipment of naturally dyed handwoven wool for the brand's autumn collection, only for it to have been held and ultimately destroyed by Israeli customs. She said she made an attempt to source replacement fabric in Jerusalem, but her efforts were thwarted due to the army closing down roads out of Ramallah.
"I was genuinely like, maybe we should stop, maybe this is our last effort. I was just so tired," Mjalli said.
COMPLEX SHOP: Shop the brands you love, anytime and anywhere. Uncover what's next. Buy. Collect. Obsess.
#down